

Key Highlights
- High-income families face complex tax regulations that can significantly impact financial outcomes, necessitating executive tax planning.
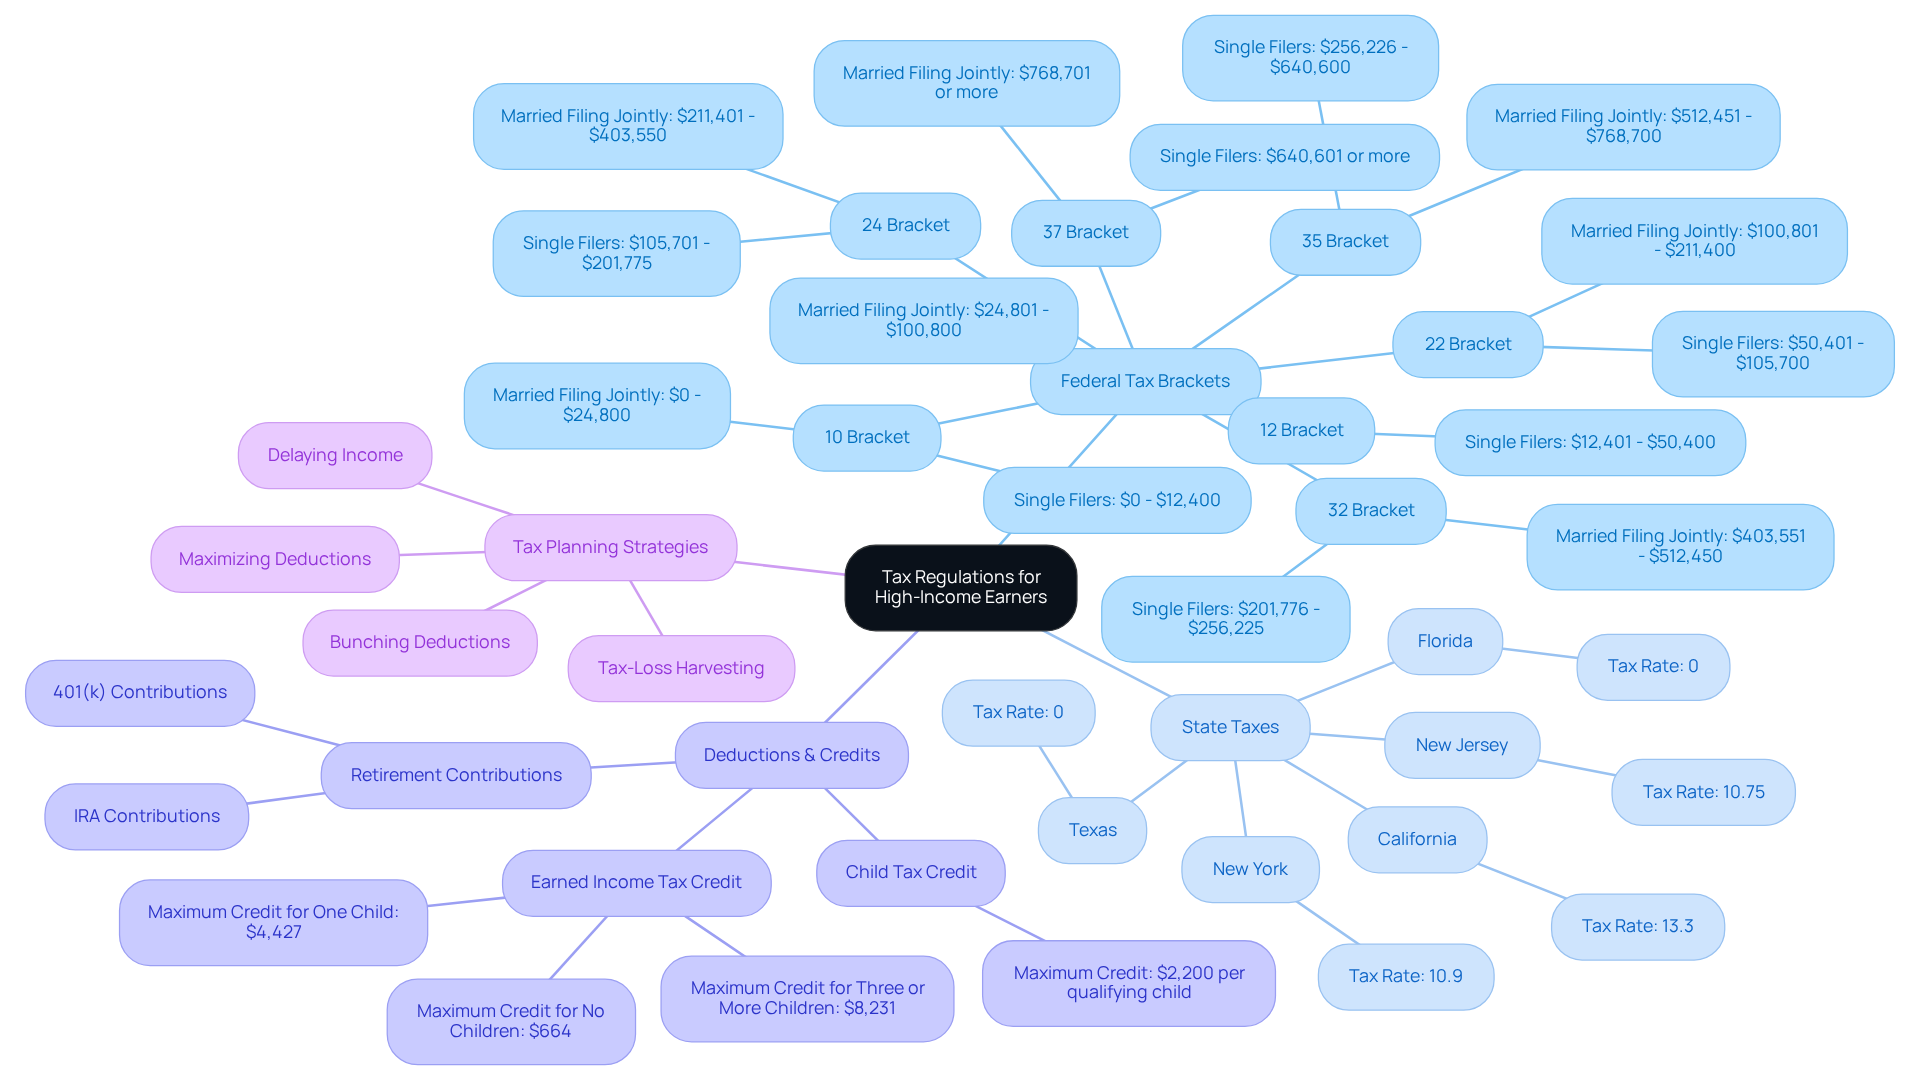
- Federal tax brackets for 2026 range from 10% to 37%, with specific rates for different income levels, such as 24% for single filers earning between $105,701 and $201,775.
- States like California (13.3%), New York (10.9%), and New Jersey (10.75%) impose high state taxes, while relocating to states with no income tax, like Texas or Florida, can alleviate some tax burdens.
- Deductions and credits, such as the Child Tax Credit (CTC) of $2,200 per qualifying child, are crucial for reducing taxable income.
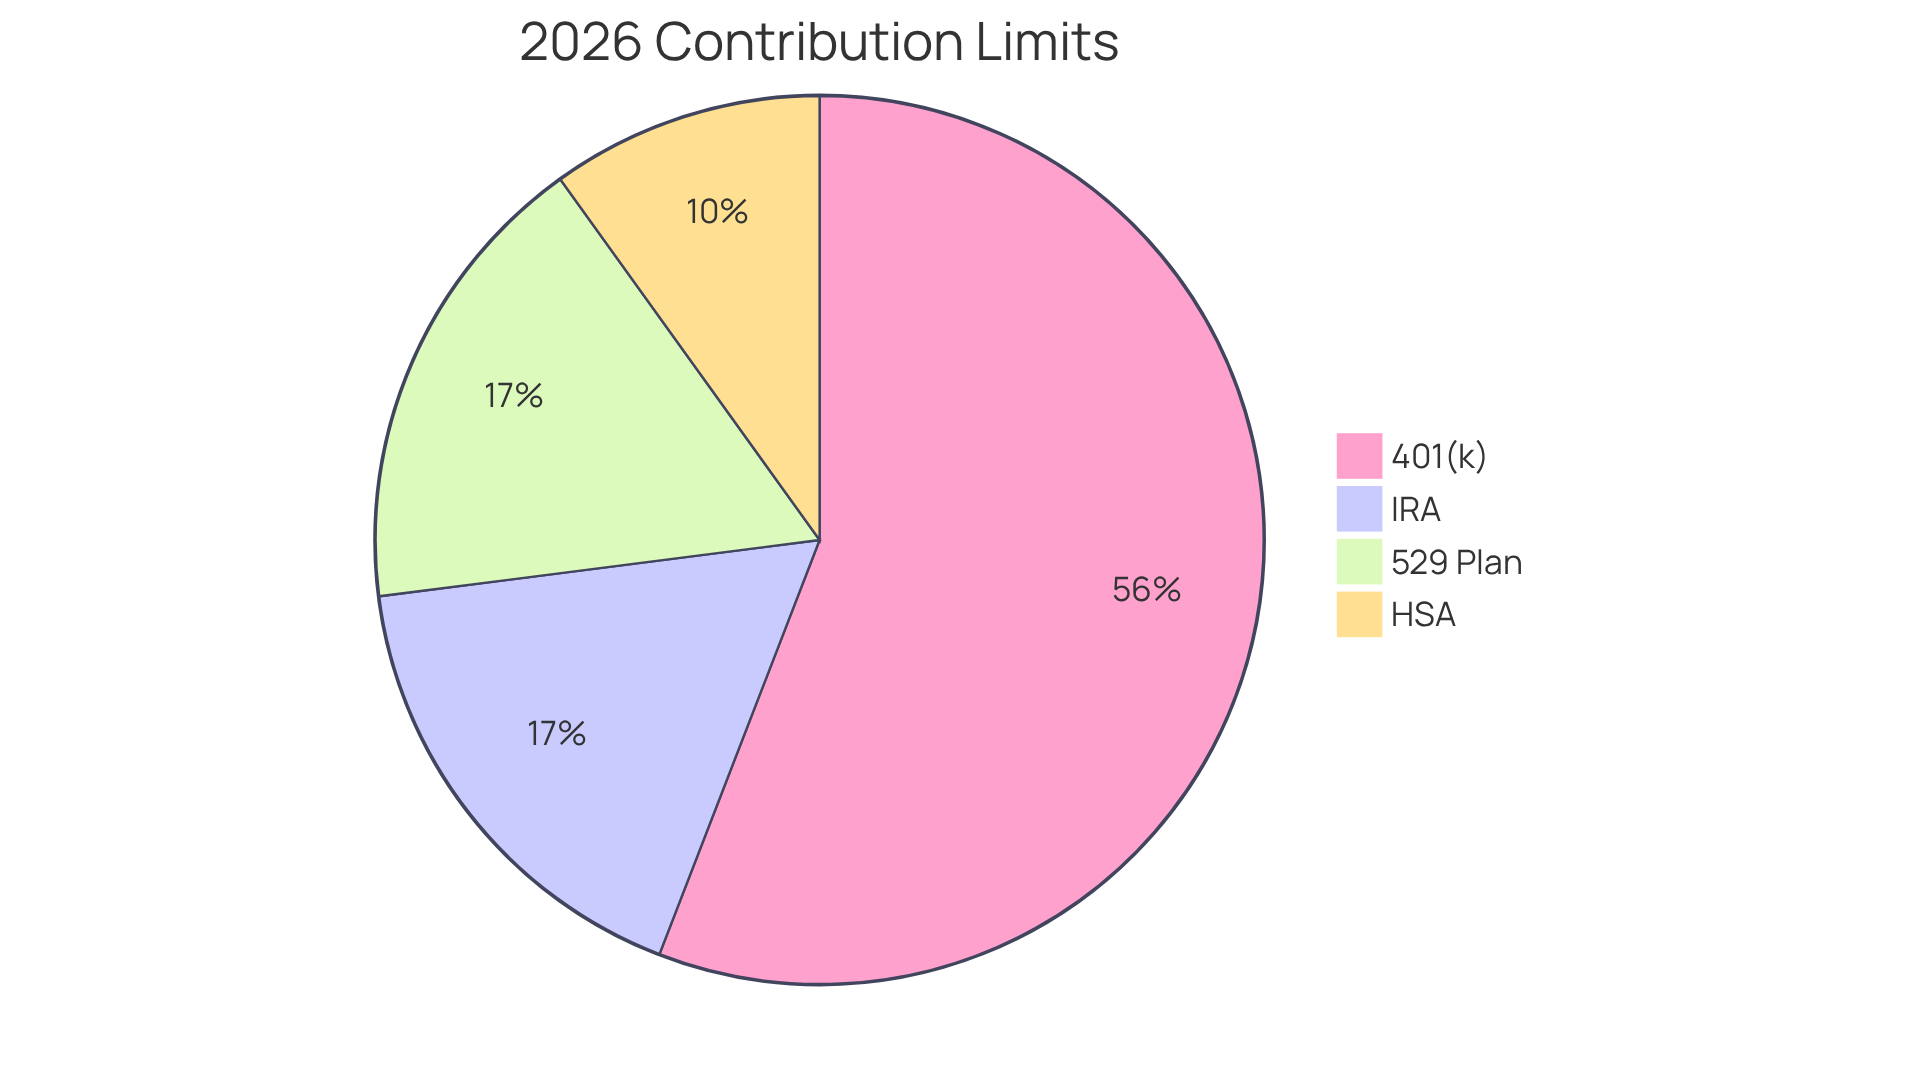
- Maximising contributions to retirement accounts like 401(k)s and IRAs can lower taxable earnings; limits for 2026 are $24,500 for 401(k)s and $7,500 for IRAs.
- Health Savings Accounts (HSAs) offer triple tax advantages, with contribution limits of $4,350 for individuals and $8,750 for households in 2026.
- Tax-loss harvesting allows families to offset gains with losses, potentially reducing capital gains taxes.
- Charitable contributions of appreciated assets can provide tax benefits, including avoiding capital gains taxes and receiving deductions for fair market value.
- Collaborating with a fiduciary advisor, like Bright Advisers, can help families navigate complex tax situations and develop tailored strategies for financial security.
Introduction
Imagine the stress of trying to keep up with tax laws while also planning for your family’s future. Navigating the world of taxes can feel overwhelming, especially for high-income families striving to secure their financial future. Effective tax planning isn’t just about numbers; it’s about securing your family’s future and peace of mind.
It’s important to understand how changing tax laws can impact your family’s financial decisions, and we’re here to help you navigate it all. This article will explore tax planning strategies that not only save you money but also bring peace of mind for your family’s future. Together, we can ensure you’re making informed decisions that align with your family’s values and goals.
Understand Tax Regulations for High-Income Earners
Imagine feeling overwhelmed by the complexities of tax regulations while trying to secure your family’s financial future. High-income families often find themselves navigating a challenging landscape that can significantly impact their financial outcomes, highlighting the importance of executive tax planning for high income earners.
It’s important to understand where your earnings fit within the federal tax brackets for 2026, which range from 10% to 37%. For instance, single filers will face a 24% tax rate on earnings between $105,701 and $201,775, while those making over $640,600 will be taxed at the highest rate of 37%. Knowing this can help you make smarter choices for your family’s financial health.
State taxes can add another layer of complexity. States like California (13.3%), New York (10.9%), and New Jersey (10.75%) impose high state earnings taxes. Imagine if you could alleviate some of this burden by timing your earnings or even relocating to lower-tax states like Texas or Florida.
Deductions and credits are also crucial for high-income earners, highlighting the importance of executive tax planning for high income earners, who often face limitations such as the SALT deduction cap. Understanding which deductions are accessible and how to enhance them is vital for executive tax planning for high income earners to lower taxable earnings. For example, the maximum Child Tax Credit (CTC) remains at $2,200 per qualifying child, providing significant relief for families.
Contributions to retirement accounts can also reduce taxable earnings. For 2026, consider maximizing contributions to 401(k)s and IRAs, especially if you are eligible for catch-up contributions. This approach not only decreases current taxable earnings but also aids in achieving long-term objectives.
By taking the time to understand these regulations, you can unlock opportunities that truly benefit your family’s future. For instance, a case study on tax-loss harvesting shows how selling underperforming investments can counterbalance gains, effectively reducing taxable amounts and potentially moving households into a lower tax bracket. Additionally, being aware of the 2026 Alternative Minimum Tax (AMT) exemption phaseout thresholds-set at $500,000 for unmarried individuals and $1,000,000 for married couples-can further guide your tax planning efforts. Together, we can navigate this journey and ensure your family’s financial well-being.
Maximize Contributions to Tax-Advantaged Accounts
Imagine feeling overwhelmed by financial decisions, unsure of how to maximize your family’s savings and secure their future. By utilizing executive tax planning for high income earners, high-earning households can greatly lower their taxable earnings by increasing contributions to tax-advantaged accounts. Here are some key strategies to consider:
-
401(k) and IRA Contributions: For 2026, the contribution limit for 401(k) plans is $24,500, with an additional $7,500 for those aged 50 and older. The IRA contribution limit is set at $7,500 for individuals under 50, with a catch-up contribution of $1,100 for those aged 50 and older. Families should ensure they are contributing the maximum allowed to fully leverage these tax benefits. Additionally, the combined contribution limit for 401(k) plans, including both employee and employer contributions, is $72,000 in 2026.
-
Health Savings Accounts (HSAs): HSAs provide triple tax advantages: contributions are tax-deductible, growth is tax-deferred, and withdrawals for qualified medical expenses are tax-free. For 2026, the contribution limit is $4,350 for individuals and $8,750 for households. Utilizing HSAs can help cover medical expenses while simultaneously reducing taxable income.
-
529 College Savings Plans: Contributions to 529 plans grow tax-free, and withdrawals for qualified education expenses are also tax-free. Families may consider superfunding their 529 plans to maximize tax benefits and prepare for their children’s education.
Many families, despite their high incomes, often overlook valuable strategies in executive tax planning for high income earners that could significantly impact their financial future. By using these accounts wisely, families can save more and lower their tax bills. For example, households that begin contributing early and fully utilize employer matches can greatly enhance their retirement savings over time. In 2026, individuals aged 60 to 63 can utilize a super catch-up contribution limit of up to $11,250, allowing them to accelerate their retirement savings as they approach retirement age. This method not only aids in creating a strong economic future but also helps ensure that families are well-prepared for their children’s educational requirements.
Consider the situation of Allison and Brian. As high earners, they felt lost when it came to executive tax planning for high income earners. With the guidance of Bright Advisers, they learned to optimize their tax situation, secure their children’s future through education funding, and gain the ability to retire sooner. By integrating tax strategies into their comprehensive monetary plan, they experienced the peace of mind that comes with economic security, allowing them to enjoy more quality time with their loved ones.
If you’re feeling lost in the financial maze, we’re here to help you find your way with personalized solutions that fit your family’s needs. Our services include integrated tax planning and tax-loss harvesting strategies tailored to your unique situation. Join our waitlist today to learn how we can help you achieve your financial goals.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Leverage Investment Strategies and Charitable Giving
Imagine feeling overwhelmed by tax season, unsure of how to make the most of your family’s hard-earned money. High-income families can find relief through executive tax planning for high income earners, along with strategic investment and charitable giving. Here are some effective approaches that can ease your financial burden:
-
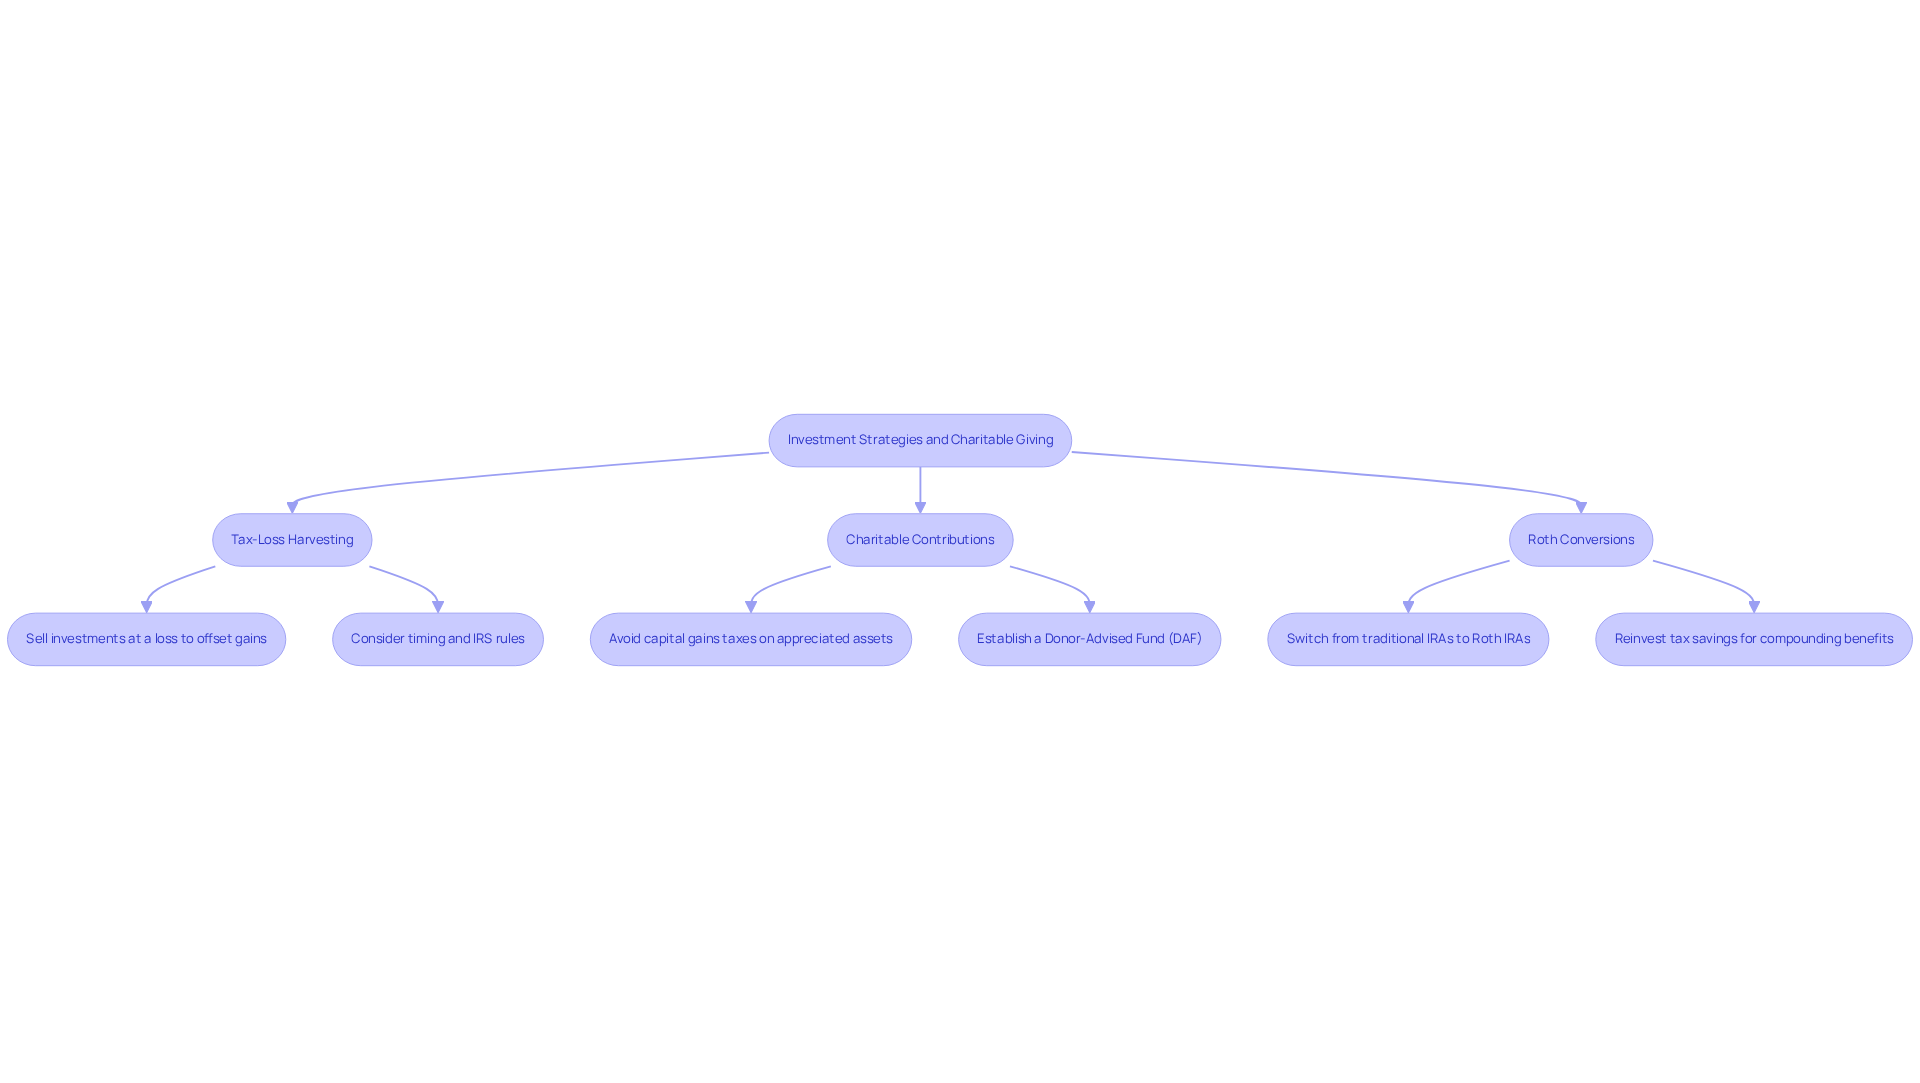
Tax-Loss Harvesting: Consider tax-loss harvesting: a way to turn losses into gains. By selling investments that have lost value, you can offset gains from profitable ones, easing your tax burden during uncertain times. For instance, if your family sells an investment at a $30,000 loss while realizing a $25,000 gain from another, you can offset those gains, leading to no capital gains owed and an estimated total savings of $4,800.
-
Charitable Contributions: Think about charitable contributions: when you donate appreciated assets like stocks, you not only help others but also gain significant tax benefits for your family. You can avoid capital gains taxes on the appreciation while receiving a charitable deduction for the fair market value of the asset. Establishing a Donor-Advised Fund (DAF) can facilitate more strategic giving, allowing your family to manage charitable contributions over time while maximizing tax advantages.
-
Roth Conversions: Have you considered Roth conversions? Switching from traditional IRAs to Roth IRAs can be a smart move, especially in years when your earnings are lower, giving your family a brighter financial future. While taxes are paid on the converted amount, future withdrawals are tax-free, providing long-term benefits.
By integrating these strategies, you can effectively manage your tax obligations through executive tax planning for high income earners while also supporting your philanthropic interests. Understanding the nuances of tax-loss harvesting, including the importance of timing and adherence to IRS rules, is crucial for maximizing benefits and ensuring compliance. By embracing these strategies, you can not only ease your financial burden but also create a lasting legacy for your family.
Collaborate with Financial Advisors for Tailored Tax Strategies
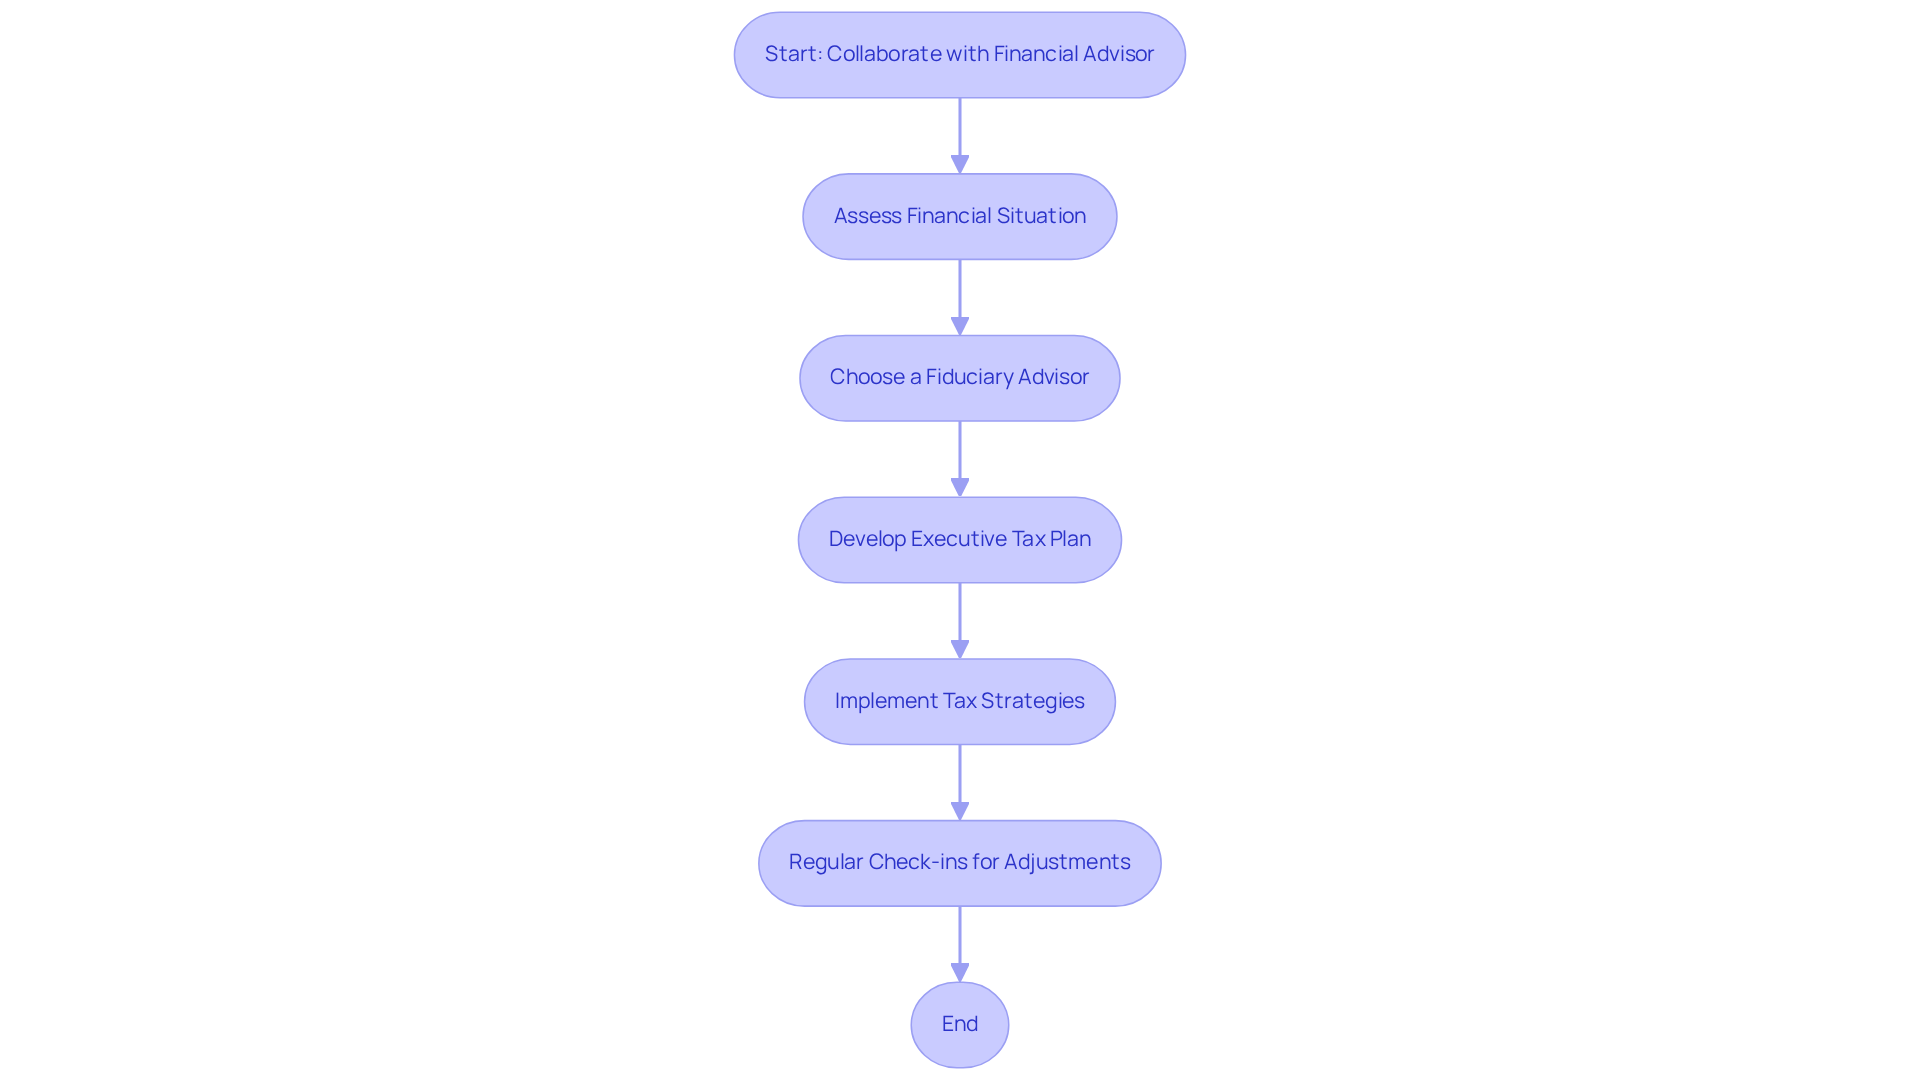
Imagine the stress of navigating tax laws alone, unsure if you’re making the right choices for your family’s future. As a high-income family, have you considered how executive tax planning for high income earners with a fiduciary advisor could assist you in navigating your tax strategies?
Choosing a fiduciary advisor means you have someone who is legally obligated to act in your best interest. It’s important to understand that high-income families often face complex tax situations that necessitate executive tax planning for high income earners. Did you know that many successful families rely on wealth advisors to guide them through their financial journeys?
Imagine how much easier it could be if your wealth management and executive tax planning for high income earners worked hand in hand, ensuring you never miss out on potential savings. For example, households like Jay and Emma, who collaborated with Bright Advisers, effectively combined their financial strategies with executive tax planning for high income earners, resulting in improved tax strategies and a personalized retirement plan that balanced their current obligations with future goals.
Regular check-ins with your advisor can help you adapt to changes, ensuring you’re always on track and avoiding costly mistakes. For instance, families employing tax-smart strategies, such as tax-loss harvesting, have effectively lowered their taxable income and enhanced after-tax returns. Emily and Mark, another Bright Advisers group, gained from regular assessments that assisted them in managing their resources effectively while reaching their objective of economic independence.
With the right support, you can confidently secure your family’s financial future and enjoy peace of mind together. Bright Advisers is committed to helping families make wise wealth decisions and preserve their wealth across generations.
Conclusion
Imagine feeling secure about your family’s financial future, even amidst the complexities of tax planning. Understanding effective executive tax planning is essential for high-income families like yours. Many families feel overwhelmed by the complexities of tax regulations, but proactive planning can lead to peace of mind and financial security.
Key strategies can make a significant difference. Think about:
- Maximizing contributions to your 401(k)
- IRA
- HSA
- 529 plans
These steps not only help optimize your tax outcomes but also align with your family values. Utilizing tax-loss harvesting and charitable giving can further enhance your financial well-being.
It’s important to understand that taking action now can make a world of difference for your family’s future. Collaborating with a fiduciary advisor ensures that your tax strategies are tailored to your unique situation. We’re here for you – working with a fiduciary advisor can help you navigate these complexities with confidence.
Together, we can prioritize your family’s financial well-being and create a legacy that lasts for generations. Taking the first step today could mean a brighter tomorrow for your family. Explore personalized solutions that align with your goals and embrace the opportunity to secure your family’s financial future.
Frequently Asked Questions
What are the federal tax brackets for high-income earners in 2026?
In 2026, federal tax brackets for high-income earners range from 10% to 37%. For example, single filers will face a 24% tax rate on earnings between $105,701 and $201,775, while those earning over $640,600 will be taxed at the highest rate of 37%.
How do state taxes affect high-income earners?
State taxes can significantly impact high-income earners, with states like California (13.3%), New York (10.9%), and New Jersey (10.75%) imposing high state earnings taxes. Timing earnings or relocating to lower-tax states like Texas or Florida can help alleviate some of this tax burden.
What role do deductions and credits play in tax planning for high-income earners?
Deductions and credits are crucial for high-income earners, especially given limitations like the SALT deduction cap. Understanding accessible deductions and how to enhance them is vital for lowering taxable earnings. For instance, the maximum Child Tax Credit (CTC) is $2,200 per qualifying child.
How can contributions to retirement accounts help reduce taxable earnings?
Maximizing contributions to retirement accounts such as 401(k)s and IRAs can reduce taxable earnings. This strategy not only decreases current taxable income but also supports long-term financial goals, especially if eligible for catch-up contributions.
What is tax-loss harvesting and how can it benefit high-income families?
Tax-loss harvesting involves selling underperforming investments to counterbalance gains, effectively reducing taxable amounts. This strategy can potentially move households into a lower tax bracket, providing significant tax relief.
What are the Alternative Minimum Tax (AMT) exemption phaseout thresholds for 2026?
For 2026, the AMT exemption phaseout thresholds are set at $500,000 for unmarried individuals and $1,000,000 for married couples. Being aware of these thresholds can guide tax planning efforts for high-income earners.
List of Sources
- Understand Tax Regulations for High-Income Earners
- Tax inflation adjustments and retirement limits for 2026 (https://ameriprise.com/financial-goals-priorities/taxes/retirement-limits-tax-brackets)
- 2025 and 2026 tax brackets and federal income tax rates | Fidelity (https://fidelity.com/learning-center/personal-finance/tax-brackets)
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- 2026 individual tax brackets, and tips for understanding what you pay (https://principal.com/individuals/learn/individual-tax-brackets-understand-what-you-pay)
- Understanding the 2026 Federal Income Tax Brackets (https://onedigital.com/en-US/articles/understanding-the-2026-federal-income-tax-brackets)
- Maximize Contributions to Tax-Advantaged Accounts
- 401(k) contribution limits 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- IRA contribution limits for 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/ira-contribution-limits)
- 401(k) Contribution Limits 2026: Maximize Savings | Human Interest | Human Interest (https://humaninterest.com/learn/articles/401k-contribution-limits)
- Nationwide Retirement Plans (https://nrsforu.com/rsc-preauth/investing/irs-limits)
- What are 2026 401(k) and individual retirement account max contribution limits? (https://principal.com/individuals/learn/what-are-2026-401k-and-ira-max-contribution-limits)
- Leverage Investment Strategies and Charitable Giving
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Tax Loss Harvesting Rules: What High-Income Investors Need To Know – True Wealth Design (https://truewealthdesign.com/tax-loss-harvesting-rules)
- How large are individual income tax incentives for charitable giving? (https://taxpolicycenter.org/briefing-book/how-large-are-individual-income-tax-incentives-charitable-giving)
- Tax-Loss Harvesting Can Work Year-Round for Investors—Here’s How | Morgan Stanley (https://morganstanley.com/articles/tax-loss-harvesting)
- Charitable contributions: tax strategies (https://fidelitycharitable.org/guidance/charitable-tax-strategies/charitable-contributions.html)
- Collaborate with Financial Advisors for Tailored Tax Strategies
- 4 Reasons Why Wealthy Pre-Retirees Need a Fiduciary – Agemy Financial Strategies (https://agemy.com/blog/4-reasons-why-wealthy-pre-retirees-need-a-fiduciary)
- Why High-Net-Worth Families Should Work with a Fiduciary Advisor (https://epwealth.com/blog/why-high-net-worth-families-should-work-with-a-fiduciary-advisor)
- Financial Planning & Tax Strategy | Why Integration Matters (https://veritaswm.com/the-intersection-of-financial-planning-and-tax-strategy-why-you-need-both)
- Tax Planning Strategies for High-Net-Worth Individuals | Boulay (https://boulaygroup.com/5-tax-planning-strategies-for-high-net-worth-individuals)
- Your Guide to Tax-Efficient Planning | Morgan Stanley (https://morganstanley.com/Themes/tax-efficient-investing-financial-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading