

Key Highlights
- High-income families often face higher federal tax brackets, with rates ranging from 24% to 37% for incomes over $250,000.
- Phaseouts of deductions, such as the Child Tax Credit, can limit financial assistance for families as their income rises.
- Complex investment structures lead to varying effective tax rates for high earners, complicating tax planning.
- Families in high-tax states like California (13.3%) and New York (10.9%) face additional tax burdens, necessitating careful planning.
- Strategies to reduce tax liability include increasing retirement contributions, utilising Health Savings Accounts (HSAs), and tax-loss harvesting.
- Claiming child-related tax credits and making charitable contributions can also provide significant tax benefits.
- Professional tax experts can create customised strategies, keep families updated on tax laws, and help navigate complex tax situations.
- Regularly reviewing financial strategies and diversifying revenue streams are essential for long-term tax efficiency.
- Utilising tax-advantaged accounts, such as 529 plans, can help families save for education while minimising tax liabilities.
- Staying informed about legislative changes allows families to adapt their tax strategies effectively.
Introduction
Imagine feeling overwhelmed by tax obligations while trying to secure your family’s future. High-income families, especially those with young children, often find themselves navigating a complex web of tax responsibilities that can feel daunting. It’s tough to feel secure when tax obligations keep piling up. But with the right strategies, you can turn this stress into a pathway for financial stability.
Let’s explore some effective tax planning strategies that can help your family thrive. This journey will not only help you manage your tax liabilities but also seize opportunities for long-term financial health. How can families transform these challenges into actionable strategies that enhance their financial well-being? Together, we can transform these challenges into opportunities for a brighter financial future.
Understand the Unique Tax Challenges for High-Income Earners
Imagine feeling overwhelmed by tax obligations while trying to provide the best for your family. High-income families, especially young parents, often face several tax challenges that complicate their financial situations, highlighting the importance of high income tax planning for high income earners.
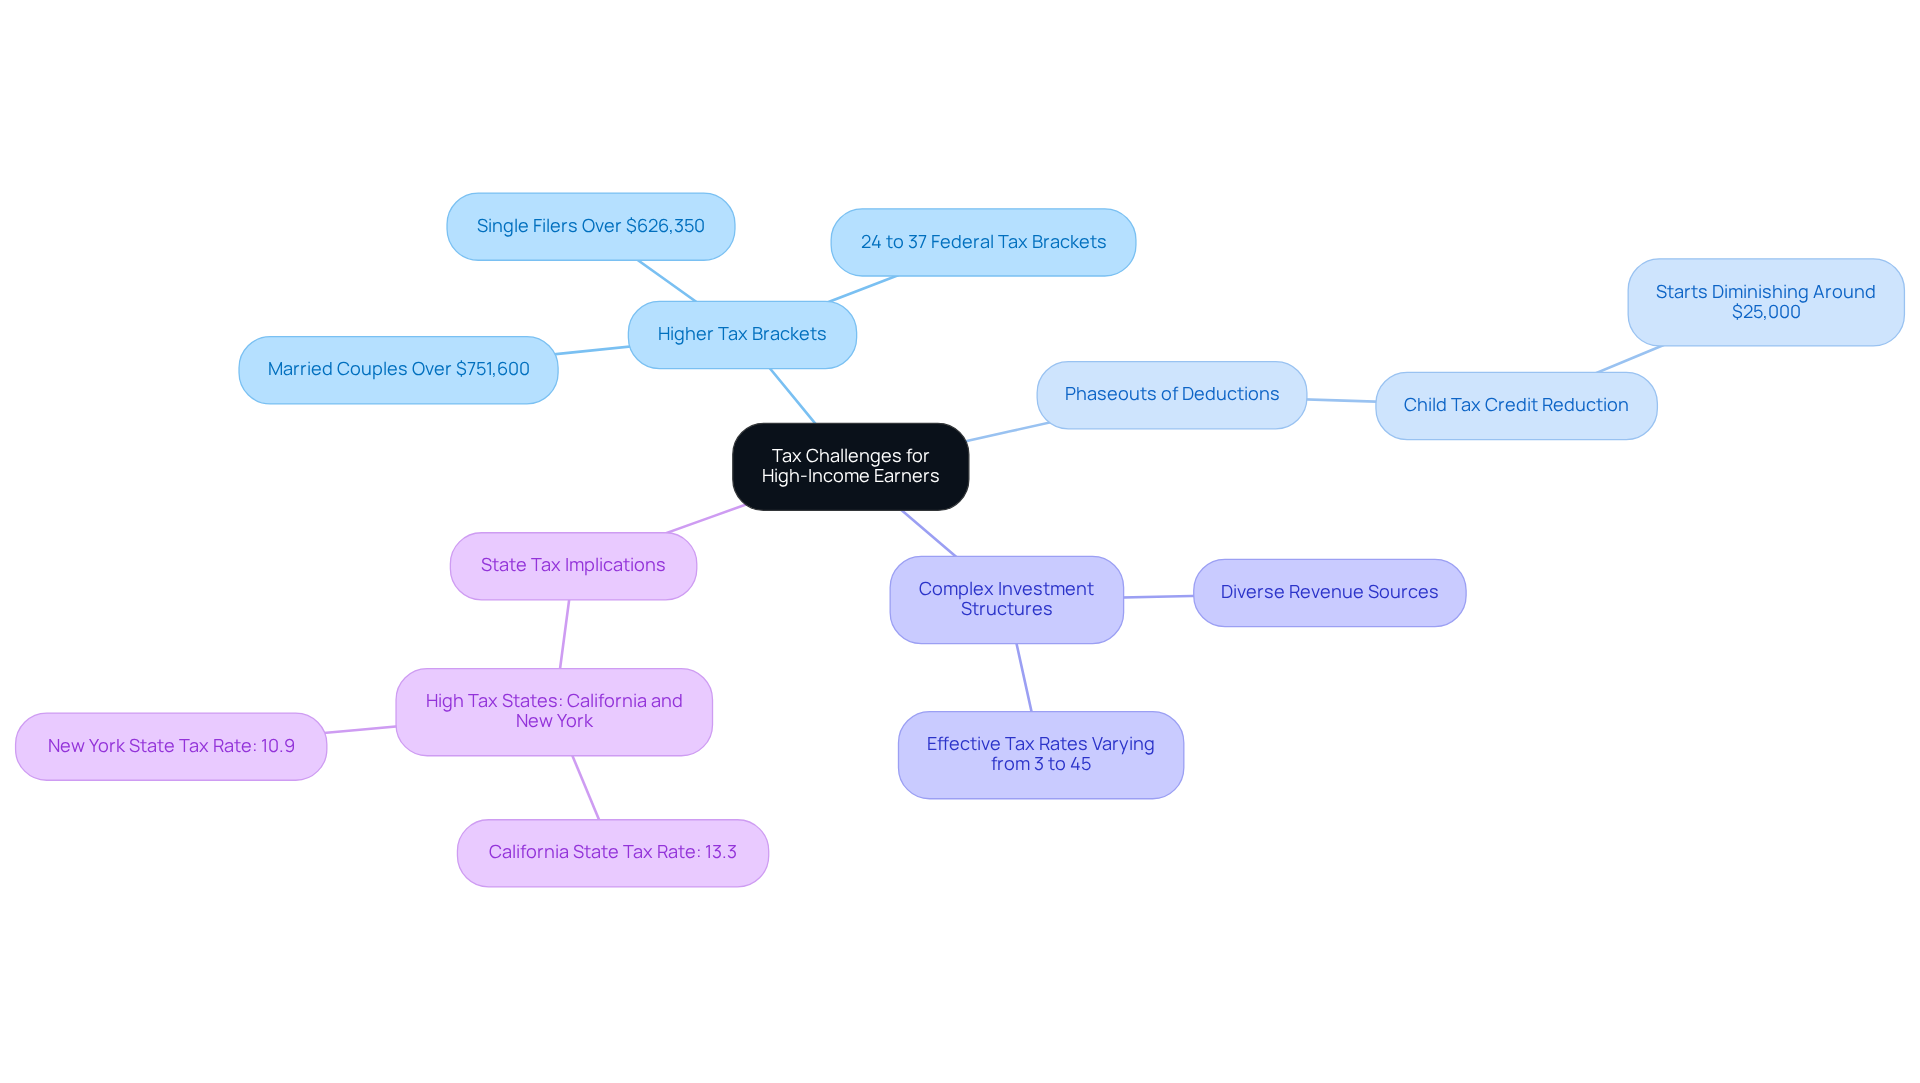
- Higher Tax Brackets: Families earning over $250,000 frequently find themselves in the 24% to 37% federal tax brackets, which can significantly increase their tax liability. For instance, single filers with earnings surpassing $626,350 and married couples making over $751,600 are taxed at the highest rate of 37%. This can feel daunting when you’re focused on your family’s future.
- Phaseouts of Deductions: Many tax advantages, like the Child Tax Credit, which can lower tax obligations by $2,000 for households earning around $25,000, start to diminish as earnings rise. This decrease can restrict the financial assistance available to families as they strive to improve their circumstances.
- Complex Investment Structures: High-earning families often have diverse revenue sources, including investments, leading to complicated tax situations involving capital gains and dividends. For example, some top 1% earners may pay effective tax rates as low as 3% or as high as 45%, depending on their earnings composition. This complexity can be overwhelming, especially when you’re trying to balance family life.
- State Tax Implications: Families living in high-tax states like California and New York face additional burdens, with state income tax rates reaching as high as 13.3% and 10.9%, respectively. This can further complicate their overall tax strategy, making high income tax planning for high income earners even more essential to have a solid plan in place.
Understanding these challenges is the first step toward finding solutions that can lighten the financial load for your family. Consulting with financial professionals can provide valuable insights into navigating these complexities and optimizing tax outcomes. With the right support, you can turn these challenges into opportunities for your family’s financial well-being.
Implement Proven Strategies for Reducing Tax Liability
Imagine feeling the weight of tax season lift off your shoulders with simple strategies that can make a real difference for your family.
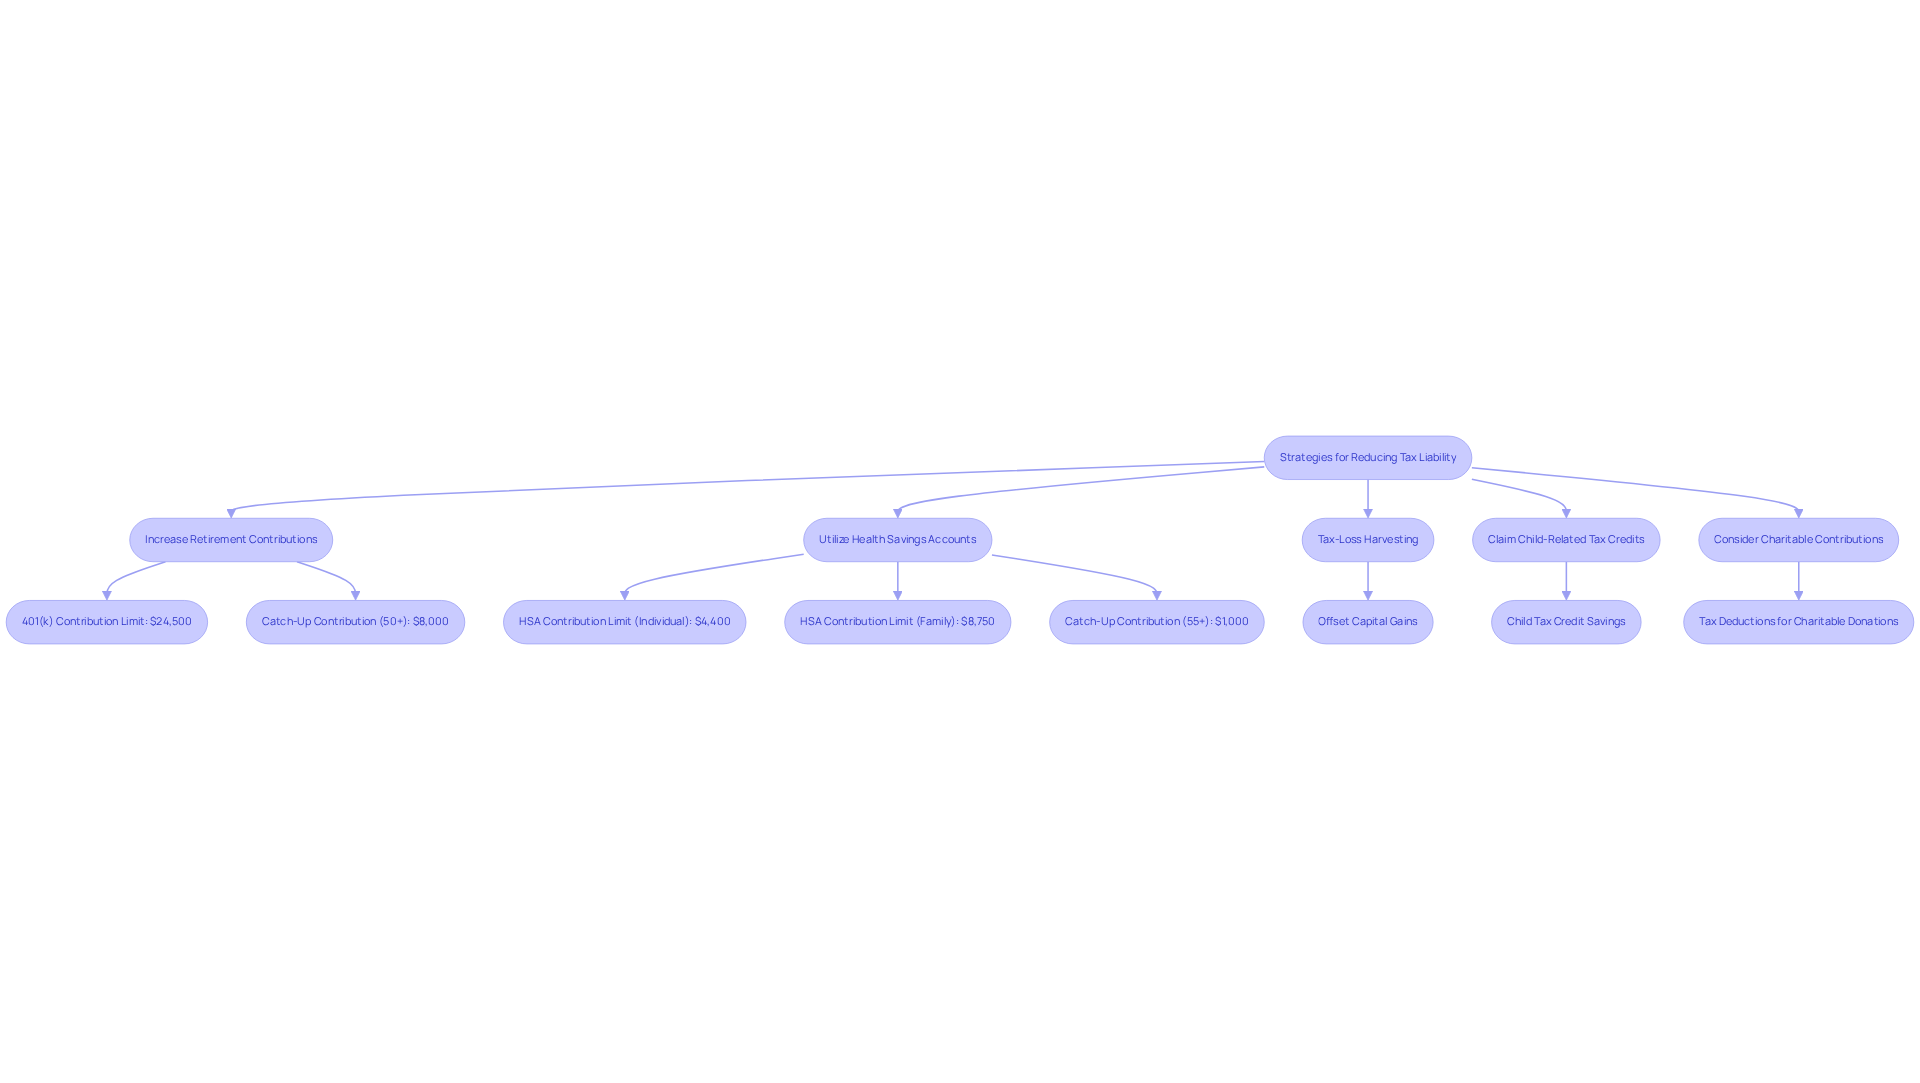
- Increase Retirement Contributions: Contributing to retirement accounts like 401(k)s can help you lower your taxable earnings. For 2026, the contribution limit for 401(k)s is set at $24,500, with an additional catch-up contribution of $8,000 for those aged 50 and older. This way, you can not only save for your future but also ease the burden of taxes today.
- Utilize Health Savings Accounts (HSAs): HSAs offer a tax-efficient way to save for medical expenses. Contributions are tax-deductible, and withdrawals for qualified medical expenses are tax-free. In 2026, individuals can contribute up to $4,400 to their HSAs, while households can contribute up to $8,750. Plus, those aged 55 or older can make an extra catch-up contribution of $1,000.
- Tax-Loss Harvesting: Imagine the stress of trying to balance your investments while keeping your tax bill manageable. Selling some investments at a loss can actually help you with that! This strategy allows you to offset capital gains, making it easier to handle your tax obligations.
- Claim Child-Related Tax Credits: Make sure your family is taking full advantage of available credits, like the Child Tax Credit, which can lead to substantial savings. For 2026, the annual gift exclusion amount is $19,000, allowing you to gift money without incurring tax liabilities.
- Consider Charitable Contributions: Donating to qualified charities can provide tax deductions while supporting causes that matter to your family. This not only helps manage tax burdens but also fosters a sense of community and responsibility.
By using these strategies, you can take control of your taxes and free up resources for what truly matters to your family. For instance, families like Jay & Emma successfully funded their children’s education while planning for retirement with the guidance of Bright Advisers. Similarly, Emily and Mark found the flexibility to make career choices based on their desired work-life balance through thorough financial planning. Additionally, individuals aged 60 to 63 can take advantage of enhanced catch-up contributions, allowing them to contribute a total of $35,750 to their retirement savings in 2026. Taking these steps today can pave the way for a more secure and fulfilling future for your loved ones.
Note: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Leverage Professional Expertise for Optimal Tax Planning
Imagine feeling overwhelmed by tax laws while trying to focus on your family’s needs. Professional expertise in tax planning can be a game-changer. Here are several compelling reasons to consider:
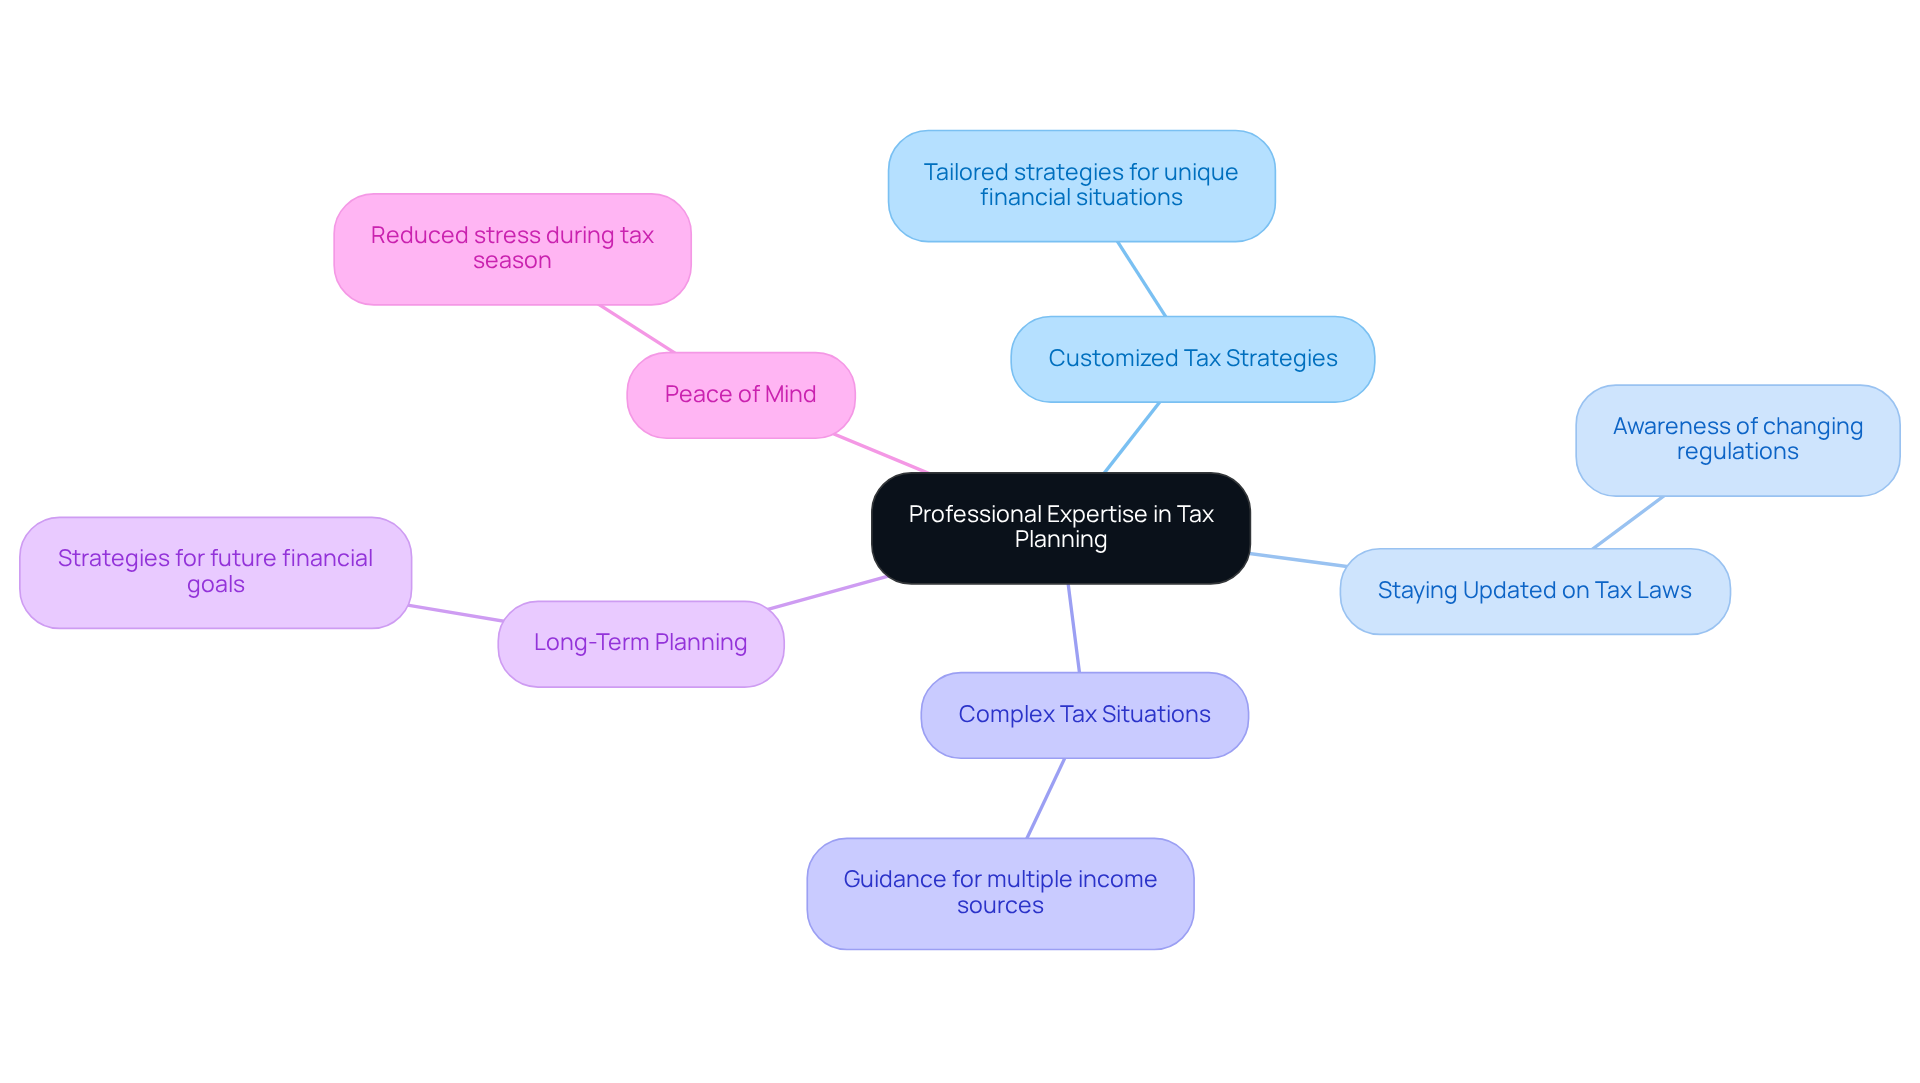
- Customized Tax Strategies: Tax experts can help craft strategies that fit your family’s unique financial picture, ensuring you make the most of every deduction and credit.
- Staying Updated on Tax Laws: With tax laws constantly changing, professionals help families stay informed about new regulations that could impact their financial situation.
- Complex Tax Situations: If your family has multiple income sources or investments, navigating intricate tax scenarios can be challenging. Tax professionals have the specialized knowledge to guide you through it.
- Long-Term Planning: Professionals assist families in developing long-term tax strategies that not only address current obligations but also plan for future goals, like funding education or retirement.
- Peace of Mind: When you partner with a tax expert, you can breathe easier, knowing that your tax worries are in capable hands, allowing you to focus on what truly matters-your family.
By collaborating with tax experts, families can ensure knowledgeable choices that improve their tax results and promote their economic well-being. By seeking professional help, you can turn tax season from a source of stress into an opportunity for financial growth for your family.
Focus on Long-Term Tax Efficiency and Adaptability
Imagine feeling confident about your family’s financial future, knowing you’re making the best choices for your loved ones. For high-income families, high income tax planning for high income earners is crucial for achieving long-term tax efficiency and flexibility, which supports sustainable economic health. Here are some strategies to consider:
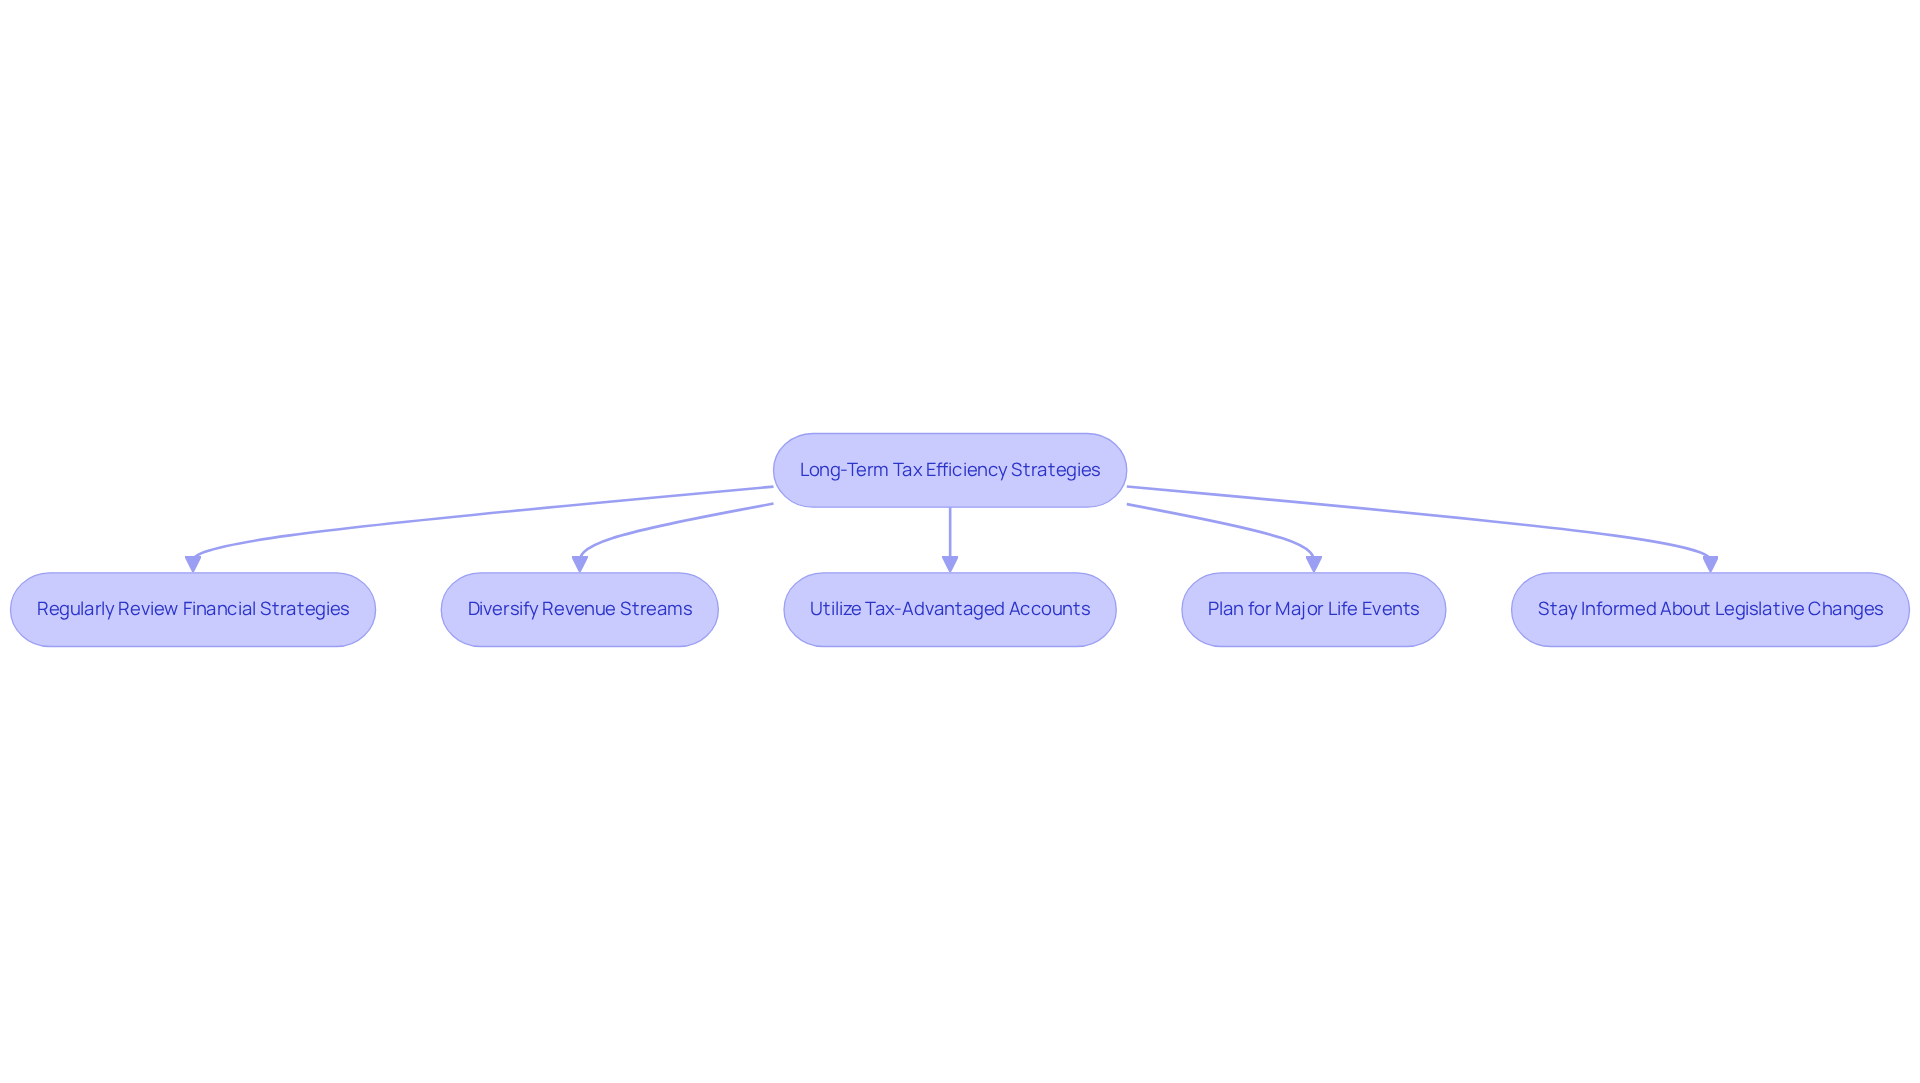
- Regularly Review Financial Strategies: Many families feel overwhelmed by the complexities of tax planning, unsure of where to start. Regularly reviewing your financial strategies can help ease that burden. Families ought to perform yearly evaluations of their plans to examine their tax approaches and make necessary modifications based on alterations in earnings, expenses, or tax regulations. For instance, Allison and Brian, a couple in their late 40s, worked with Bright Advisers to regularly review their financial situation, which helped them identify opportunities for tax optimization.
- Diversify Revenue Streams: By diversifying revenue streams, families can manage their tax liabilities more effectively. This includes balancing earned income with investment income to optimize tax brackets. Allison and Brian learned to balance their significant earnings from their respective careers with strategic investments, enhancing their overall economic position.
- Utilize Tax-Advantaged Accounts: Families should take full advantage of tax-advantaged accounts, such as 529 plans for education savings, which can provide tax-free growth and withdrawals for qualified expenses. Bright Advisers guided Allison and Brian in setting up such accounts, securing their children’s educational future while minimizing tax liabilities.
- Plan for Major Life Events: Anticipating significant life events, such as job changes or the birth of a child, can assist households in adjusting their tax strategies proactively to reduce liabilities. By planning ahead, Allison and Brian were able to navigate their monetary landscape more effectively, ensuring they were prepared for any changes.
- Stay Informed About Legislative Changes: Keeping updated on changes in tax legislation can assist households in adjusting their strategies to maintain tax efficiency. Bright Advisers provided Allison and Brian with insights into relevant tax laws, enabling them to make informed decisions that positively influenced their economic well-being.
By focusing on high income tax planning for high income earners and adaptability, you can create a financial plan that grows with your family’s needs, allowing you to enjoy precious moments together. This approach not only enhances your financial security but also provides the freedom to enjoy quality time with loved ones, knowing your financial future is well-planned.
Conclusion
Navigating tax planning can feel overwhelming, especially when you’re trying to balance family life and financial responsibilities. Many families find themselves facing unique challenges, like higher tax brackets and the stress of managing complex investments, all while trying to provide for their children. When families understand these challenges, they can take proactive steps to ease their financial stress and create a brighter future for their children.
Consider strategies like:
- Boosting retirement contributions
- Using Health Savings Accounts to help ease your financial burden
- Don’t forget about child-related tax credits
- The joy of giving back through charitable contributions, which can lighten your tax load
Having a trusted tax professional by your side can make all the difference, offering personalized strategies and keeping you updated on any changes that could affect your family.
It’s important to focus on long-term tax efficiency, ensuring your family’s financial health remains strong for years to come. By regularly reviewing your financial strategies and planning for life’s big moments, you can feel empowered to make choices that truly reflect your family’s needs. Taking these steps not only helps secure your family’s financial future but also allows you to create precious memories together, knowing you’re ready for whatever comes next.
Frequently Asked Questions
What are the unique tax challenges faced by high-income earners?
High-income earners often face challenges such as higher tax brackets, phaseouts of deductions, complex investment structures, and state tax implications, all of which can complicate their financial situations.
How do higher tax brackets affect high-income families?
Families earning over $250,000 frequently find themselves in the 24% to 37% federal tax brackets, significantly increasing their tax liability. For example, single filers earning over $626,350 and married couples making over $751,600 are taxed at the highest rate of 37%.
What are phaseouts of deductions and how do they impact families?
Phaseouts of deductions occur when tax advantages, such as the Child Tax Credit, begin to diminish as earnings rise. This can limit the financial assistance available to families, making it harder to improve their financial circumstances.
Why are complex investment structures a challenge for high-income families?
High-earning families often have diverse revenue sources, including investments, which can lead to complicated tax situations involving capital gains and dividends. Effective tax rates for top earners can vary widely, from as low as 3% to as high as 45%, depending on their earnings composition.
How do state tax implications affect high-income earners?
Families living in high-tax states like California and New York face additional burdens, with state income tax rates reaching as high as 13.3% and 10.9%, respectively. This complicates their overall tax strategy and emphasizes the need for effective tax planning.
What steps can high-income families take to address these tax challenges?
Understanding these tax challenges is the first step toward finding solutions. Consulting with financial professionals can provide valuable insights into navigating these complexities and optimizing tax outcomes for better financial well-being.
List of Sources
- Understand the Unique Tax Challenges for High-Income Earners
- Who Is Paying Their Fair Share of Taxes? A New Analysis and Interactive Tool (https://budgetlab.yale.edu/research/who-paying-their-fair-share-taxes-new-analysis-and-interactive-tool)
- Tax moves for 2026 | Fidelity (https://fidelity.com/learning-center/personal-finance/tax-moves)
- Tax Bracket Calculator | TaxAct (https://taxact.com/tax-resources/tax-calculators/tax-bracket-calculator)
- 2026 Federal Income Tax Brackets and Interactive Calculator (https://bipartisanpolicy.org/explainer/2026-federal-income-tax-brackets-and-interactive-calculator)
- Understanding the 2026 Federal Income Tax Brackets (https://onedigital.com/en-US/articles/understanding-the-2026-federal-income-tax-brackets)
- Implement Proven Strategies for Reducing Tax Liability
- Potential Long-Term Benefits of Investing Your HSA (https://schwab.com/learn/story/potential-long-term-benefits-investing-your-hsa)
- How Much Can I Contribute to a 401(k) in 2026? (https://epwealth.com/blog/how-much-can-i-contribute-to-a-401k-in-2026)
- Nationwide Retirement Plans (https://nrsforu.com/rsc-preauth/investing/irs-limits)
- 401(k) contribution limits 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- Leverage Professional Expertise for Optimal Tax Planning
- 11 Proven Tax Strategies for High-Income Earners in 2025 — Square Accounting LLC (https://sqaccounting.com/blog/the-new-rules-of-personal-finance-in-wealth-9d86a-fycej-ma2cs-9xz6z)
- High-Income Tax Planning Strategies for 2025 | DHJJ (https://dhjj.com/high-income-tax-planning-strategies-for-2025)
- Tax Planning Strategies for High-Net-Worth Individuals | Boulay (https://boulaygroup.com/5-tax-planning-strategies-for-high-net-worth-individuals)
- Tax Planning for High Income Earners: Strategies to Preserve and Grow Wealth – Towerpoint Wealth (https://towerpointwealth.com/tax-planning-for-high-income-earners-strategies-to-preserve-and-grow-wealth)
- Year-End Tax Planning Strategies for High-Net-Worth Families (https://creativeplanning.com/insights/taxes/year-end-tax-planning-high-net-worth-families)
- Focus on Long-Term Tax Efficiency and Adaptability
- Tax diversification in 3 steps (https://ameriprise.com/financial-goals-priorities/taxes/tax-diversification-retirement)
- SOI Tax Stats – SOI working papers | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-soi-working-papers)
- Office of Tax Analysis (https://home.treasury.gov/policy-issues/tax-policy/office-of-tax-analysis)
- Post-tax Income Inequality Rose From 2009 to 2024 Despite More Equal Household Income After Taxes and Credits (https://census.gov/library/stories/2025/09/post-tax-income.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading