

Overview
This article gently explores the best timing for selling shares acquired through Employee Stock Purchase Plans (ESPPs). It encourages employees to consider selling 80% to 90% of their shares right after acquisition, a thoughtful strategy to reduce stock price risks. Imagine the peace of mind that comes with immediate liquidity, allowing you to better support your family’s needs.
Moreover, the article highlights the potential benefits of holding shares for over a year, which could lead to lower long-term capital gains tax rates. This approach not only maximizes your overall returns but also aligns beautifully with your personal financial goals.
Together, we can navigate this journey toward financial stability, ensuring that your family’s future is secure. We’re here for you every step of the way.
Key Highlights:
- ESPPs allow employees to buy company stock at a discount, typically 5% to 15% below market value.
- Participation rates in ESPPs can exceed 40% when companies use third-party resources.
- Many employees hold ESPP shares for over a year, contrary to the belief that they sell quickly.
- Shorter enrollment windows can enhance engagement in ESPP programs.
- Employees should consider selling 80% to 90% of ESPP shares right after acquisition to mitigate stock price risk.
- Holding shares for over a year may qualify for long-term capital gains tax treatment, offering lower tax rates.
- Immediate sales can lead to regular income tax on discounts, reducing overall returns.
- A structured selling strategy, such as selling quarterly or annually, helps manage investments effectively.
- Consulting with financial and tax advisors is crucial for optimizing ESPP strategies and understanding tax implications.
- Exploring other equity compensation options can provide insights for better financial planning.
Introduction
Navigating the complexities of Employee Stock Purchase Plans (ESPPs) can truly be a game changer for employees eager to enhance their financial portfolios. These employer-sponsored programs offer a wonderful opportunity for individuals to acquire company stock at a discounted rate, which can lead to immediate profit and potential long-term gains. However, as enticing as these plans may seem, it’s important to understand the nuances—from optimal selling strategies to tax implications—to maximize the benefits for you and your family.
Imagine if you could make informed decisions that align with your financial aspirations. With insights from industry experts and recent data, this article gently explores effective strategies for participating in ESPPs, helping you evaluate the best timing for selling shares, and avoiding common pitfalls. Together, we can navigate this journey, ensuring that you feel supported in your financial planning.
Understand Employee Stock Purchase Plans (ESPPs)
Employee Stock Purchase Plans (ESPPs) can be a wonderful opportunity for you to invest in your family’s future. These employer-sponsored programs allow staff members to purchase shares of their company’s stock at a reduced rate, typically between 5% and 15% less than market value. Imagine being able to set aside a part of your salary during an offering period, which may last from six months to two years, helping you build a nest egg for your loved ones.
Participating in an ESPP offers several advantages. You could see immediate profit from the discount, invest in the company you work for, and potentially enjoy long-term capital gains if the stock appreciates. It’s heartening to note that recent data shows companies using broker or third-party administrator resources report participation rates exceeding 40%. This highlights how effective these plans can be in engaging staff. Contrary to the common belief that workers quickly sell their ESPP holdings, two-thirds of companies reveal that participants often hold their stock for an average of one year or longer. This insight showcases a more engaged and long-term approach to stock ownership, challenging the myth that workers undervalue their ESPP shares.
Emily Cervino, head of Industry Relationships and Thought Leadership at Fidelity Stock Plan Services, stresses the importance of staying informed about current trends in equity compensation plan design. Many companies now prefer shorter enrollment windows, with half of those surveyed adopting a brief two-week enrollment period. This can significantly enhance participation and engagement, making it easier for you to take advantage of these plans. Understanding the basics of ESPPs is crucial for anyone looking to optimize their financial benefits, especially regarding espp when to sell. By using these plans wisely, you can strengthen your overall financial strategy and work towards a more secure future for your family.
However, it’s essential to be aware of common pitfalls. Failing to hold shares long enough to realize potential gains or misunderstanding the tax implications of selling shares can hinder your progress in understanding espp when to sell. To leverage ESPPs effectively and understand espp when to sell, consider the following steps:
- Review the offering period and contribution limits.
- Monitor stock performance and market conditions.
- Consult with a money management expert to understand tax implications and develop a selling strategy that addresses espp when to sell.
- Stay informed about company performance and industry trends.
By following these guidelines, you can make informed choices that align with your financial objectives. Remember, we’re here for you—together, we can navigate this journey toward a brighter financial future.

Evaluate Key Factors for Selling ESPP Shares
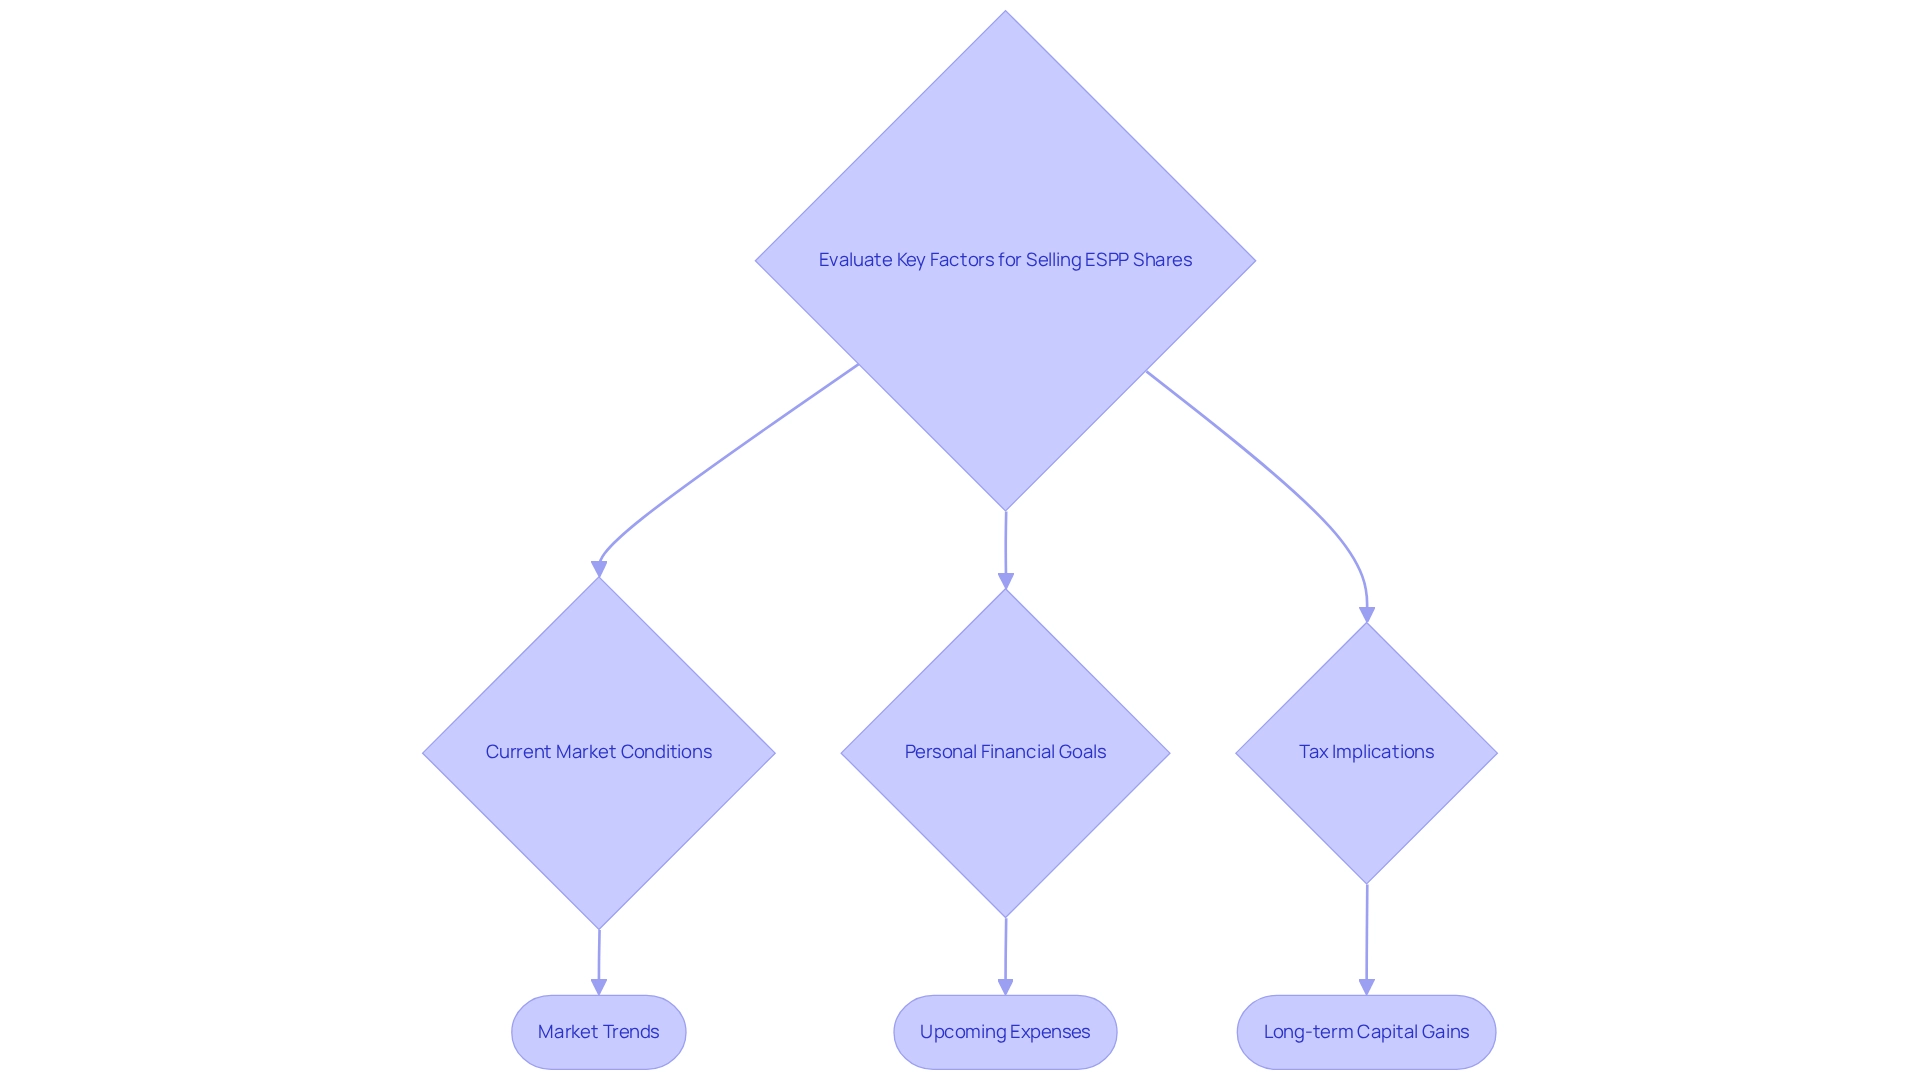
Navigating ESPP when to sell stocks is a journey that requires thoughtful consideration of various factors, such as current market conditions, your personal financial goals, and tax implications. As we look ahead to 2025, market trends suggest that it may be wise for employees to consider selling 80% to 90% of their ESPP holdings right after acquisition. This approach not only allows you to benefit from the inherent discount but also helps mitigate the risks associated with stock price fluctuations.
Imagine holding onto your stocks for over a year. This could be advantageous, as it may qualify you for long-term capital gains tax treatment, which typically offers a lower tax rate compared to regular income. It’s important to assess your current financial needs—like upcoming expenses or investment opportunities—while keeping an eye on market trends that might impact stock prices.
For instance, a recent case study highlighted how market conditions, both bullish and bearish, significantly influence how long people hold onto their ESPP stocks. Understanding these trends can empower you to determine ESPP when to sell, as you weigh the potential for appreciation against the risks of market volatility. We’re here for you, and professional guidance underscores the importance of staying informed about tax regulations and market dynamics. These elements are crucial in making strategic decisions regarding your ESPP assets. By carefully evaluating these factors, you can enhance your profits and align your selling strategies with your family’s financial objectives. Together, we can navigate this journey, ensuring that your financial choices reflect your values and priorities.
Follow a Step-by-Step Process to Time Your Sale
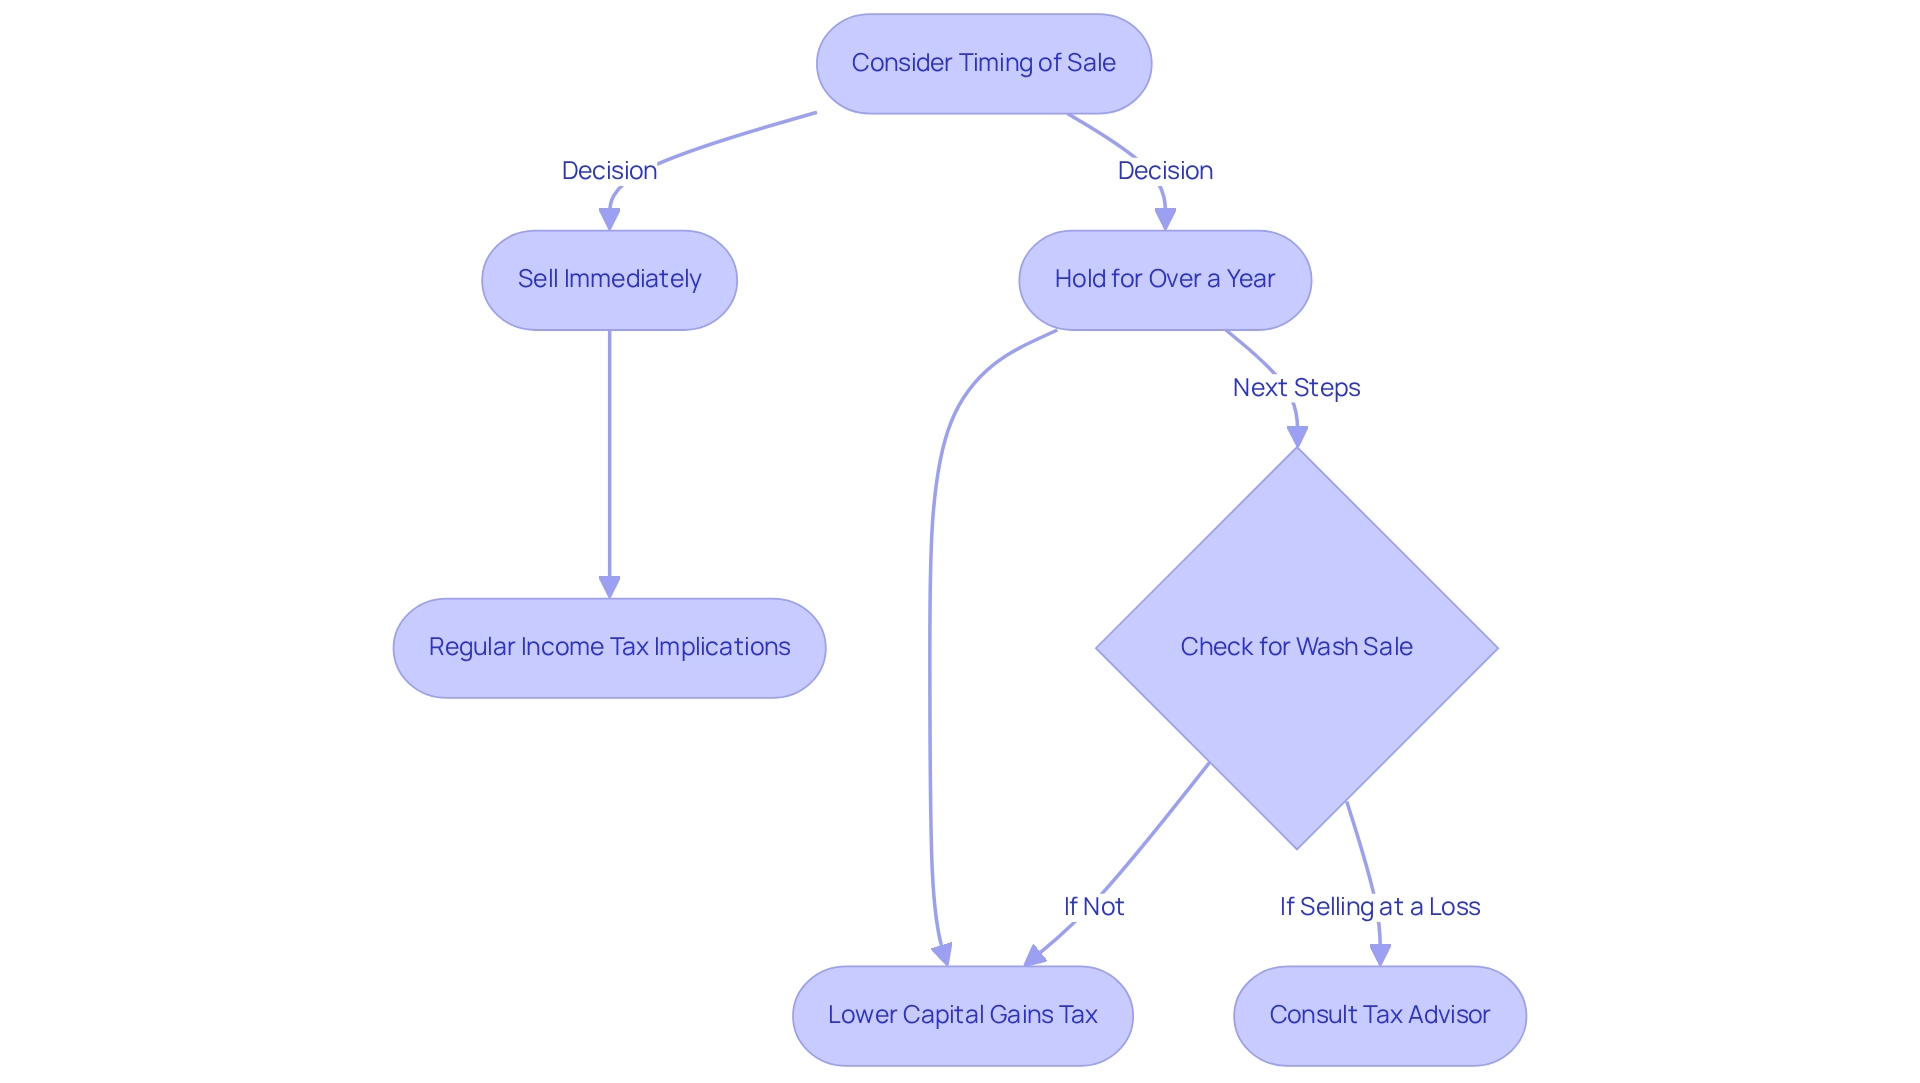
When it comes to espp when to sell stocks, it’s crucial for employees to thoughtfully consider the tax implications involved. Selling stocks immediately after acquisition can lead to the discount being taxed as regular income, which might significantly reduce your overall returns. For instance, a 15% reduction on stocks could translate to a $6.00 tax impact based on the offering date price. However, by holding onto those stocks for over a year, any profits beyond the purchase price can benefit from the more favorable long-term capital gains rate, which is vital for maximizing your returns.
Understanding the holding period requirements for qualifying dispositions is essential, as it can shape your tax strategies. Imagine if you sold shares at a loss; it’s important to be cautious of triggering a wash sale, which could erase potential tax benefits. The case study on tax loss harvesting illustrates that careful management is necessary to avoid pitfalls that could negatively influence your tax outcomes. Utilizing financial applications can simplify the calculation of capital gains taxes by organizing transaction histories and applying the correct rates based on your income and filing status. As Natalie Campisi wisely noted, “For investors juggling multiple accounts or frequent trades, a tax app can help keep things organized, accurate and less likely to trigger an IRS headache.” Preparing for capital gains taxes should be a key part of your comprehensive financial strategy.
Consulting with a tax advisor can provide personalized insights into your specific tax situation, helping you optimize your selling strategies. By being proactive and informed, you can navigate the complexities of ESPP assets and understand espp when to sell to make decisions that align with your family’s financial goals. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future.
Avoid Common Mistakes When Selling ESPP Shares
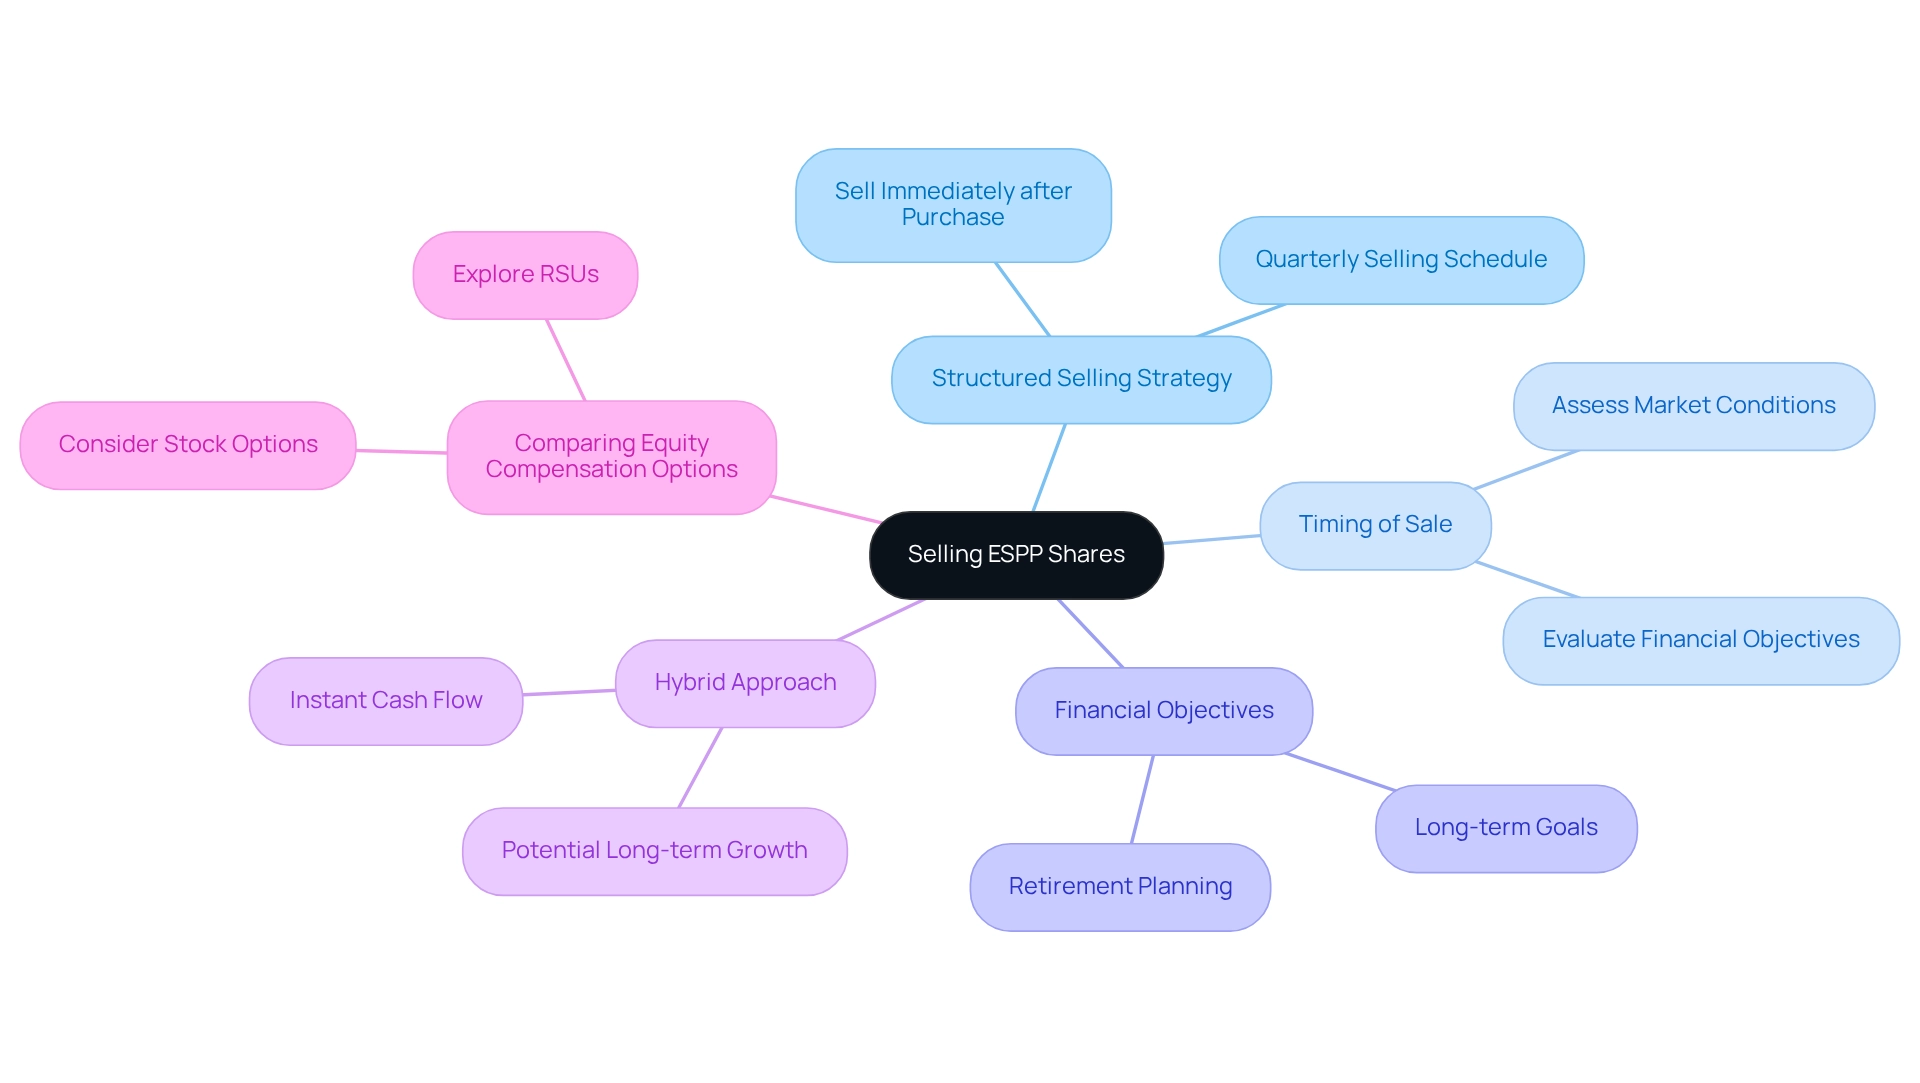
To maximize profits from the Employee Stock Purchase Plan (ESPP), it’s essential for staff to know when to sell and adopt a structured selling strategy that feels manageable and supportive. Imagine selling a portion of your stocks right after acquisition—this can allow you to take advantage of a purchase discount that can be as high as 15%. By doing so, you not only gain prompt liquidity but also keep some shares for potential long-term growth. As Jason Preti wisely notes, “If the stock price goes up after you’ve purchased it through your ESPP, you can sell it at the higher market price and pocket the difference as a profit.” This hybrid approach offers instant cash flow while also enabling you to benefit from future stock appreciation.
It’s important to consistently assess your financial objectives and market conditions to determine when to sell and modify your selling strategy as needed. Establishing a systematic schedule for selling shares—perhaps quarterly or annually—can help mitigate emotional decision-making and clarify when to sell, ensuring a disciplined approach to managing your investments. Statistics reveal that many workers sell their shares right after purchase, underscoring the importance of understanding the implications of such decisions for your family’s financial future.
In addition to these strategies, exploring other forms of equity compensation, like stock options and restricted stock units (RSUs), can provide valuable insights for your financial planning. The case study titled “Exploring Other Forms of Equity Compensation” compares ESPPs with other equity compensation options, highlighting their unique characteristics. Understanding these differences can empower you to make informed decisions that align with your long-term financial objectives. Financial experts emphasize that a well-rounded approach to equity compensation, including hybrid selling strategies, can significantly enhance overall investment outcomes.
Furthermore, we encourage you to explore the broader landscape of equity compensation beyond ESPPs. Together, we can navigate this journey and fully understand your options, ensuring that your family’s financial goals are met with care and support.
Conclusion
Participating in Employee Stock Purchase Plans (ESPPs) offers a wonderful chance for employees to strengthen their financial portfolios through discounted company stock. It’s essential to understand the structure, benefits, and potential pitfalls of these plans to maximize financial gains. By grasping key concepts like contribution limits, market conditions, and tax implications, you can make informed decisions that align with your family’s financial aspirations.
Imagine the impact of timing when selling ESPP shares—it’s pivotal for realizing profits. By evaluating market trends and personal financial goals, alongside strategic selling practices, you can significantly enhance your overall returns. Consider a hybrid approach: selling a portion of shares immediately while holding others for long-term appreciation. This strategy can help mitigate risks associated with stock price volatility while taking advantage of favorable tax treatment.
Ultimately, having a proactive, informed strategy is vital for navigating the complexities of ESPPs. We encourage you to consult with financial and tax advisors who can help tailor your approach to fit your specific circumstances. Together, we can ensure you make the most of your participation in these beneficial programs. Embracing the available resources and insights can empower you to secure a more stable financial future through effective management of your ESPP investments. Remember, we’re here for you every step of the way.
Frequently Asked Questions
What is an Employee Stock Purchase Plan (ESPP)?
An Employee Stock Purchase Plan (ESPP) allows employees to buy shares of their company’s stock at a reduced rate, typically between 5% to 15% below market value, during a structured offering period that can last from six months to two years.
What are the benefits of participating in an ESPP?
Benefits of participating in an ESPP include immediate profits from the stock discount, the opportunity to invest in the company you work for, and potential long-term capital gains if the stock appreciates.
How do participation rates in ESPPs compare among companies?
Companies utilizing broker or third-party administrator resources report participation rates exceeding 40%, indicating that these plans effectively engage employees.
Do employees typically sell their ESPP shares quickly?
Contrary to common belief, many employees do not sell their ESPP shares quickly. Two-thirds of companies indicate that participants tend to hold their stock for an average of one year or longer, reflecting a long-term commitment to stock ownership.
What should parents consider when participating in an ESPP?
Parents should understand the basics of ESPPs to optimize their financial benefits, be mindful of common pitfalls like not holding shares long enough to realize potential gains, and be aware of the tax implications of selling shares.
How can employees make informed decisions about their ESPP?
Employees can make informed decisions by monitoring stock performance and market conditions, consulting with a monetary advisor to understand tax implications, and staying informed about company performance and industry trends.
List of Sources
- Understand Employee Stock Purchase Plans (ESPPs)
- Trends in ESPP Policies and Participation (https://naspp.com/blog/espp-policies-and-participation)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Employee Stock Purchase Plan (ESPPs) Trends (https://stockopter.com/employee-stock-purchase-plan-espps-trends)
- Employee stock purchase plan – ESPP (https://globalshares.com/insights/employee-stock-purchase-plan-espp)
- Evaluate Key Factors for Selling ESPP Shares
- Strategies for Selling ESPP Shares: A Comprehensive Guide for Employees (https://upstock.io/post/strategies-for-selling-espp-shares-a-comprehensive-guide-for-employees)
- When Should You Sell ESPP Shares? — EquityFTW (https://equityftw.com/articles/when-should-you-sell-espp-shares)
- Holding Period: The Holding Period: Timing Your ESPP Sales for Maximum Gain – FasterCapital (https://fastercapital.com/content/Holding-Period–The-Holding-Period–Timing-Your-ESPP-Sales-for-Maximum-Gain.html)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/s/blog/espp-tax-rules-what-you-need-to-know-MC7NEMNJHGRBD3NPLYMZUQQ23MAQ)
- 2025 Market Outlook | First Command (https://firstcommand.com/coaching-center/insights/2025-market-outlook)
- More Muted Gains for Stocks in 2025 | Morgan Stanley (https://morganstanley.com/insights/articles/stock-market-outlook-2025)
- When Employees Thrive, Companies More Than Triple Their Stock Market Performance (https://greatplacetowork.com/resources/blog/when-employees-thrive-companies-triple-their-stock-market-performance)
- Follow a Step-by-Step Process to Time Your Sale
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/s/blog/espp-tax-rules-what-you-need-to-know-MC7NEMNJHGRBD3NPLYMZUQQ23MAQ)
- Capital Gains Tax Rates For 2024 And 2025 (https://forbes.com/advisor/taxes/capital-gains-tax)
- Capital Gains Tax Rates and Potential Changes in 2025 (https://investopedia.com/taxes/capital-gains-tax-101)
- ESPP Shares: To Sell or Not to Sell? (https://plancorp.com/blog/espp-selling-strategies)
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- ESPP Tax: The Complete Guide to Maximizing Your Benefits (https://simplicitywm.com/espp-tax-complete-guide)
- Avoid Common Mistakes When Selling ESPP Shares
- Everything You Need to Know Before Selling Your ESPP Shares – Benny (https://blog.heybenny.com/selling-espp-shares-post)
- When Should You Sell ESPP Shares? — EquityFTW (https://equityftw.com/articles/when-should-you-sell-espp-shares)
- Strategies for Selling ESPP Shares: A Comprehensive Guide for Employees (https://upstock.io/post/strategies-for-selling-espp-shares-a-comprehensive-guide-for-employees)
- Employee Stock Purchase Plan Explained: Discounts, Tax Treatment, and Divesting Strategies (https://unleashedfinancial.com/blogs/employee-stock-purchase-plan-explained–discounts–tax-treatment–and-divesting-strategies)
- When to Sell ESPP Shares: Timing Tips for Taxes and Gains (https://blog.myrawealth.com/insights/when-to-sell-espp-shares)
- 3 Common ESPP Mistakes That Cost You Money (and How to Avoid Them) (https://juliemerrill.me/blog/espss-3-common-mistakes)
- Employee Stock Purchase Plans 101 | Plancorp (https://plancorp.com/employee-stock-purchase-plans-101)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading