

Key Highlights
- Restricted Stock Units (RSUs) are shares awarded to employees that vest over time, providing shares delivered at vesting without initial cost.
- Stock Options allow employees to purchase shares at a predetermined price, requiring an initial investment and presenting financial risks.
- RSUs are taxed as ordinary income upon vesting, while Stock Options are taxed at exercise, which can complicate tax planning.
- Families should understand the tax implications of their equity compensation to avoid unexpected tax bills, especially in high-tax states like California.
- Evaluating financial goals and risk tolerance is crucial for choosing between RSUs and Stock Options, aligning compensation with family objectives.
- Bright Advisers offers personalised wealth management solutions to help families navigate equity compensation complexities and achieve financial security.
Introduction
Imagine feeling overwhelmed by financial choices while trying to secure your family’s future. Navigating the world of equity compensation can be challenging for young parents like you. With options such as Restricted Stock Units (RSUs) and stock options available, understanding the nuances of each can truly unlock significant benefits for your family.
Many parents feel overwhelmed by the choices they face, unsure of how to navigate the financial landscape. Questions about risk, tax implications, and long-term financial goals can cloud the decision-making process. How can you find clarity in these options to make the best choice for your family’s unique needs?
Define RSUs and Stock Options
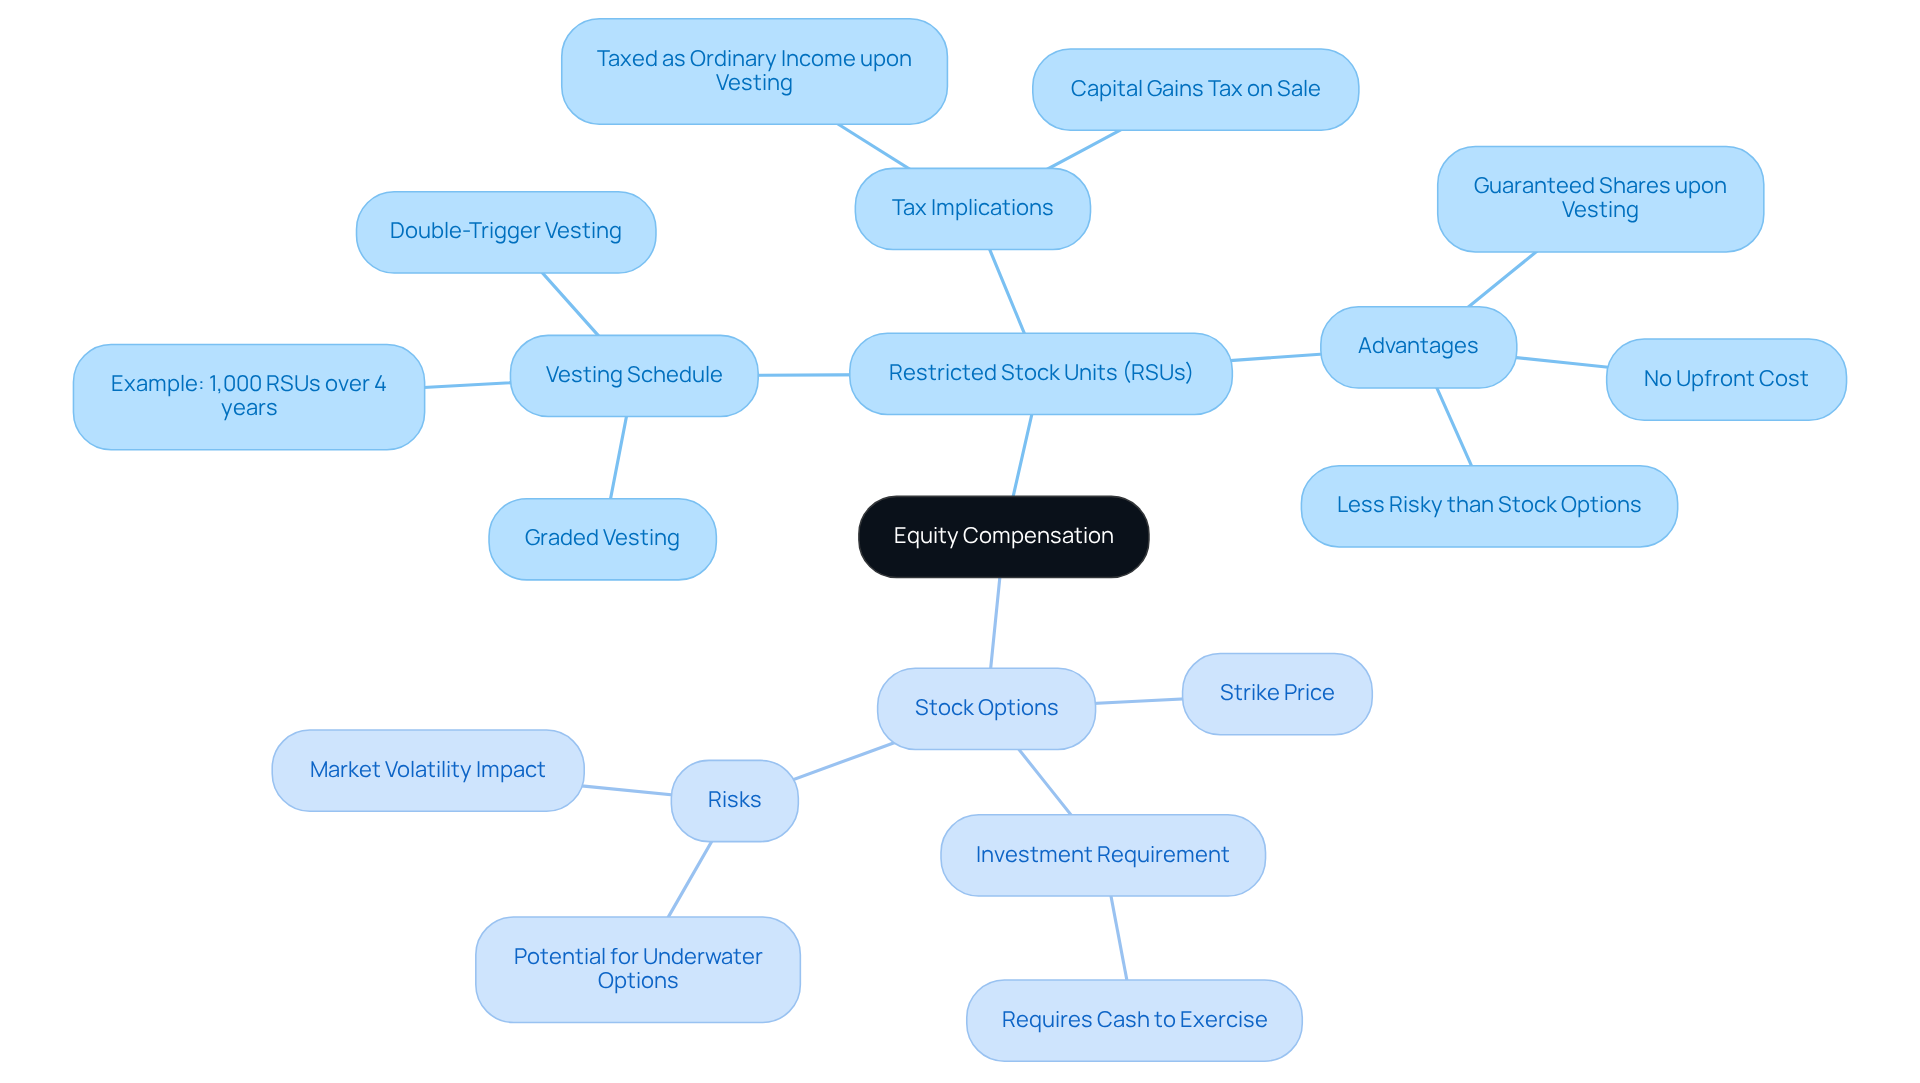
Imagine receiving shares as part of your compensation, but feeling uncertain about how to make the most of them for your family’s future. Restricted Stock Units (RSUs) are shares awarded to employees based on fulfilling certain criteria, usually including a vesting period. For instance, you might be awarded 1,000 RSUs with a four-year vesting schedule, earning 250 shares each year. Once these units vest, you gain full ownership of the shares, providing a straightforward form of equity compensation. The best part? RSUs are typically awarded at no cost to you, making them an appealing choice for those seeking stability in their pay.
Many employees, like Allison and Brian, feel overwhelmed by the complexities of their compensation packages, unsure of how to make the most of them for their family’s future. It’s important to understand that restricted stock units are taxed as regular income when they vest, based on their fair market value at that time. This lack of understanding can lead to missed opportunities for financial growth and stability for their families. That’s why reaching out for expert guidance can help families navigate these complexities and make the most of their resources.
Stock Options grant employees the right to purchase shares at a predetermined price, known as the strike price, within a specified timeframe. Unlike RSUs, stock options require an initial investment to exercise, which can present a financial risk if the stock price does not surpass the strike price.
Key Characteristics:
- RSUs are generally simpler and offer shares delivered at vesting, making them appealing for employees seeking stability. As Munchow observes, restricted stock units offer a more direct, assured type of remuneration that is appreciated by workers who might favor lower risk and more consistent returns.
- Stock options may present higher potential rewards but come with inherent risks, particularly if the stock price fails to rise above the strike price.
Tip: Understanding the terms and conditions of your equity compensation, especially when considering equity grant vs RSU, is crucial for maximizing its benefits in long-term financial planning. Additionally, be aware of the tax implications related to restricted stock units, as they are taxed as ordinary income upon vesting based on the fair market value at that time. By understanding your equity compensation, you can take confident steps toward securing your family’s financial future.
Identify Key Differences Between RSUs and Stock Options
Navigating the world of stock options and restricted stock units can feel overwhelming, especially when you’re trying to secure your family’s future.
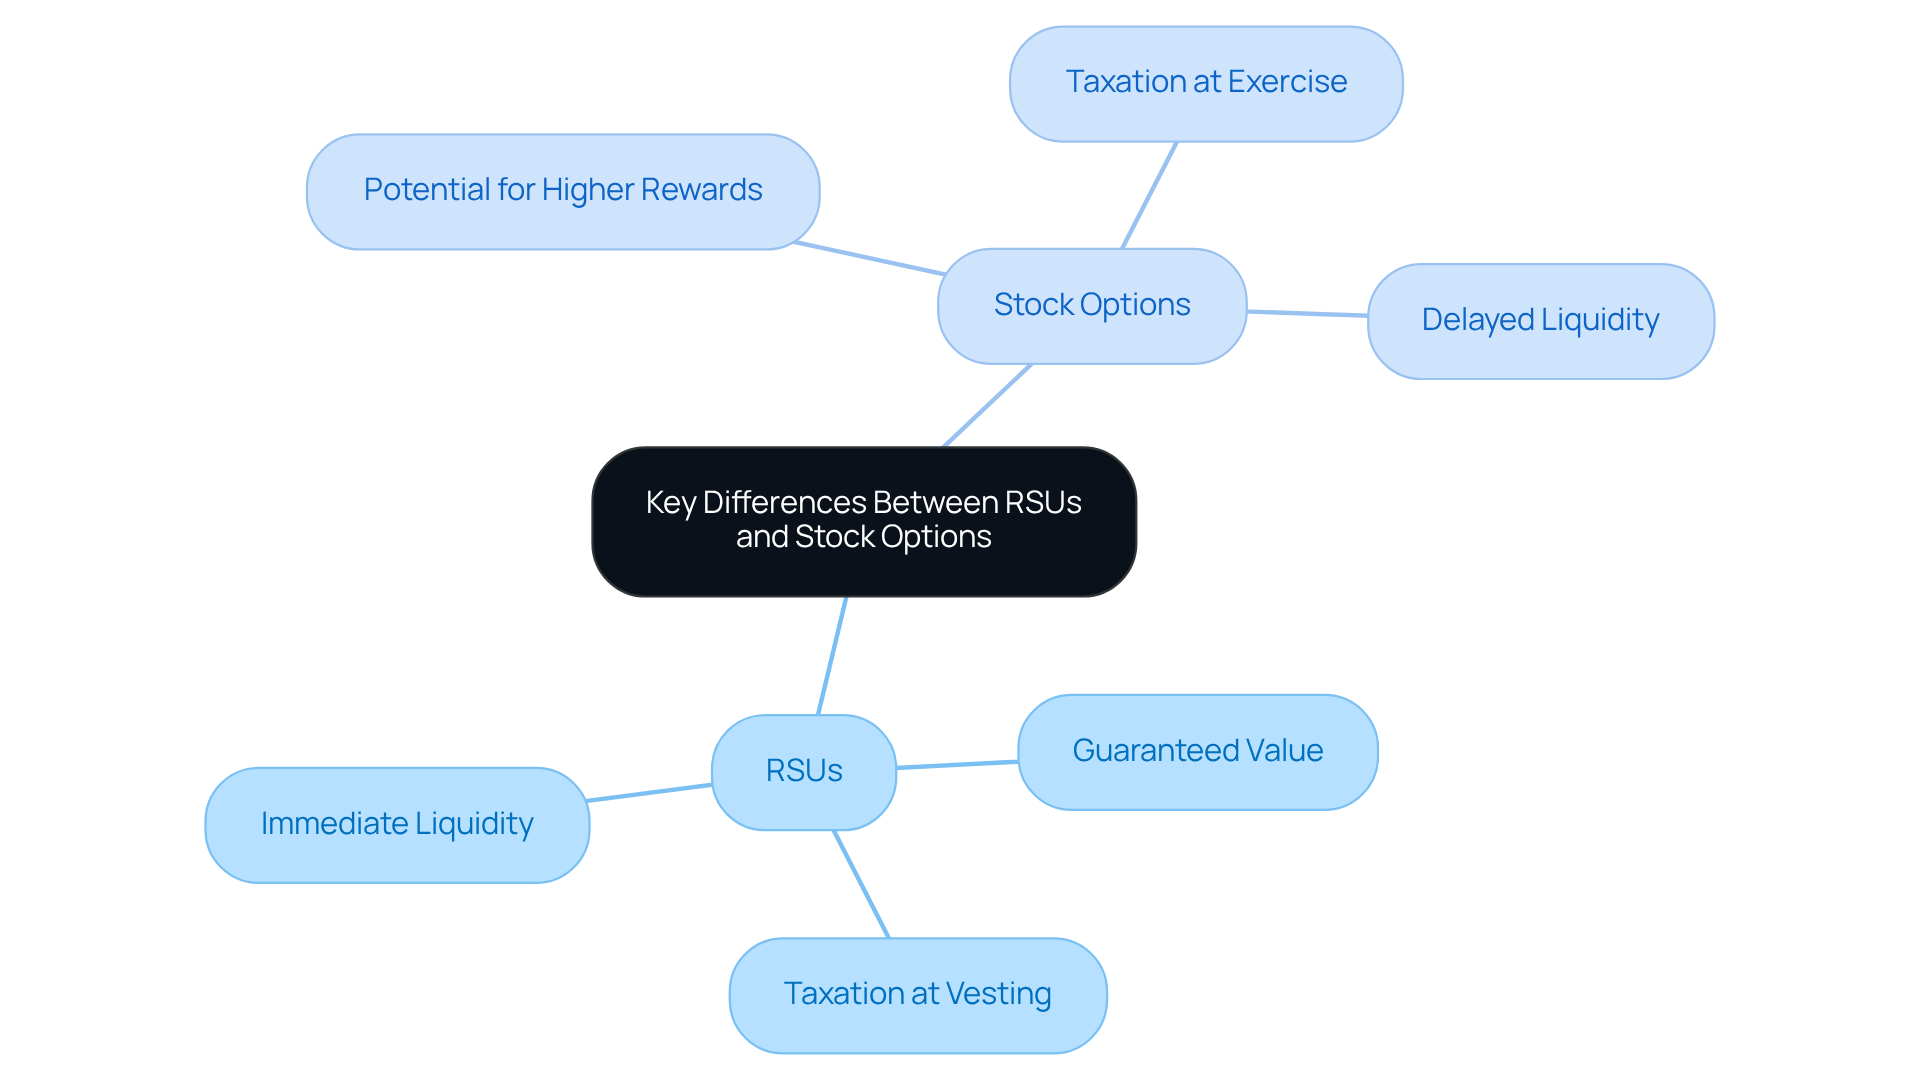
Imagine receiving shares that are yours once they vest, like a gift for your hard work, versus needing to buy shares at a set price with stock options. When it comes to taxes, RSUs are taxed as soon as they vest, while stock options are taxed when you decide to use them, which can feel a bit complicated.
With RSUs, you have a known share count, which can feel safer for your family. Stock options might offer bigger rewards, but they come with more uncertainty, depending on how the stock performs. You can sell RSUs right after they vest, giving you quick access to funds, while stock options might require some patience before you can cash in.
Take a moment to think about your family’s current financial situation and future needs to see which option feels right for you. At Bright Advisers, we understand that young households like Jay & Emma, Emily & Mark, and Allison & Brian face unique financial challenges. Our customized wealth management solutions empower families to achieve financial security and educational preparedness through personalized planning and tax optimization.
By collaborating with us, you can manage the intricacies of equity grant vs RSU, ensuring that your financial choices align with your family’s goals. As you evaluate your options, remember that our thorough onboarding process is designed to create a tailored plan that meets your specific needs. Join our waitlist today to discover how Bright Advisers can assist you in making informed choices regarding stock options, ultimately resulting in a more secure economic future for your loved ones.
Evaluate Tax Implications of RSUs and Stock Options
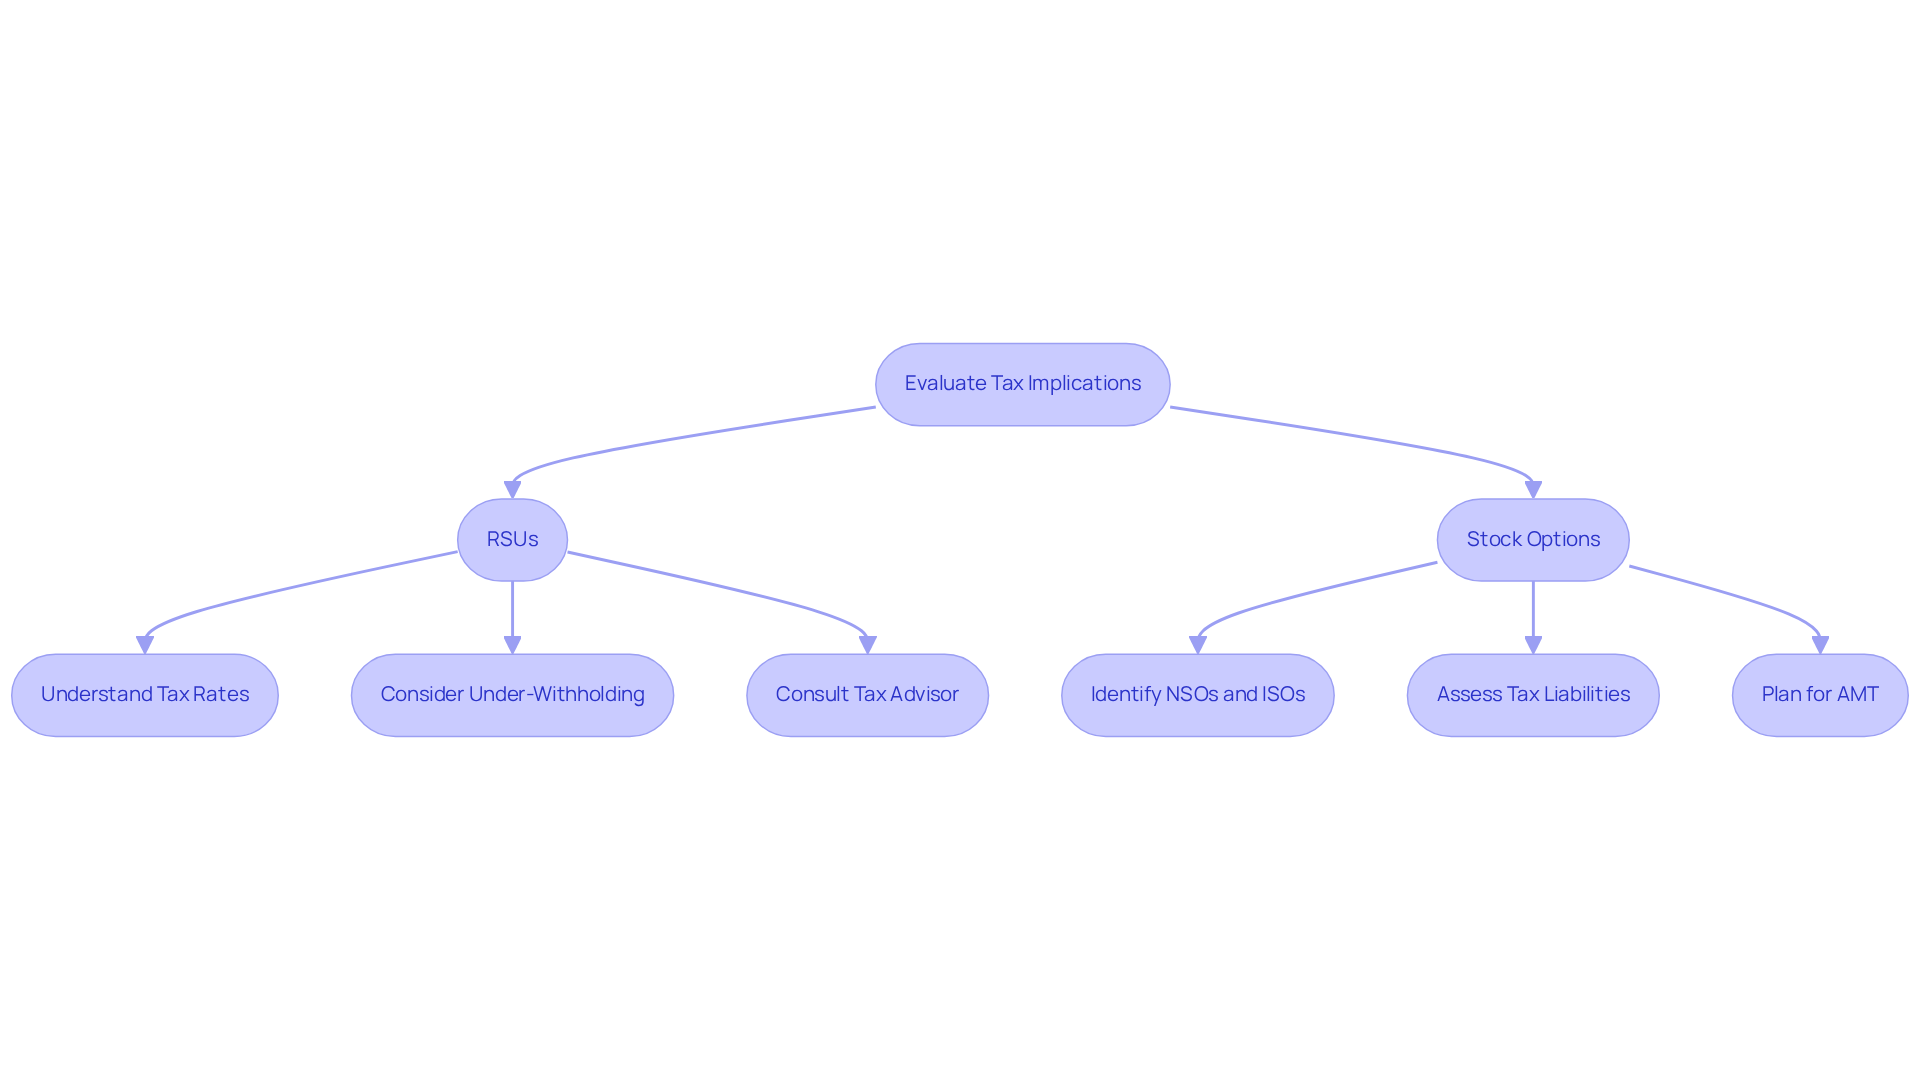
Imagine the worry of receiving an unexpected tax bill just when you thought you were on top of your finances. Taxed as ordinary income at the time of vesting, RSUs can be taxed at rates as high as 50.3% in California due to federal and state taxes! Employers usually withhold shares to cover tax liabilities. However, this can lead to under-withholding for high earners, causing unexpected tax bills. That’s where Bright Advisers steps in. Just like Jay and Emma, you can find guidance to ease your financial worries and make the most of your resources. By establishing a comprehensive budget and selecting investment strategies focused on diversification, they balanced growth potential and risk management, ensuring they were prepared for tax implications.
Now, let’s talk about Stock Options. Non-Qualified Stock Options (NSOs) are taxed at exercise based on the difference between the market price and the strike price, which can create significant tax liabilities if not planned for properly. Incentive Stock Options (ISOs) may provide advantageous tax treatment if specific conditions are satisfied, but they can activate Alternative Minimum Tax (AMT), complicating tax situations for households. Emily and Mark, for example, collaborated with Bright Advisers to navigate these complexities, gaining a clearer understanding of their monetary situation and developing a comprehensive plan that aligned with their goals.
Planning Tip: Consulting a tax advisor is crucial to understand how equity compensation impacts your tax situation and to explore strategies for minimizing tax liabilities effectively, such as maximizing retirement contributions and adjusting W-4 forms. Bright Advisers incorporates tax planning and preparation into their services, ensuring households are equipped to handle these challenges.
Action Item: Regularly track your vesting schedules and potential tax implications, including the risk of under-withholding, to avoid surprises during tax season, especially considering the complexities introduced by California’s tax landscape. By collaborating with Bright Advisers, families can focus on what truly matters-their loved ones-without the burden of financial uncertainty.
Assess Your Financial Goals and Risk Tolerance
Imagine feeling confident about your family’s financial future, knowing you have a clear plan in place.
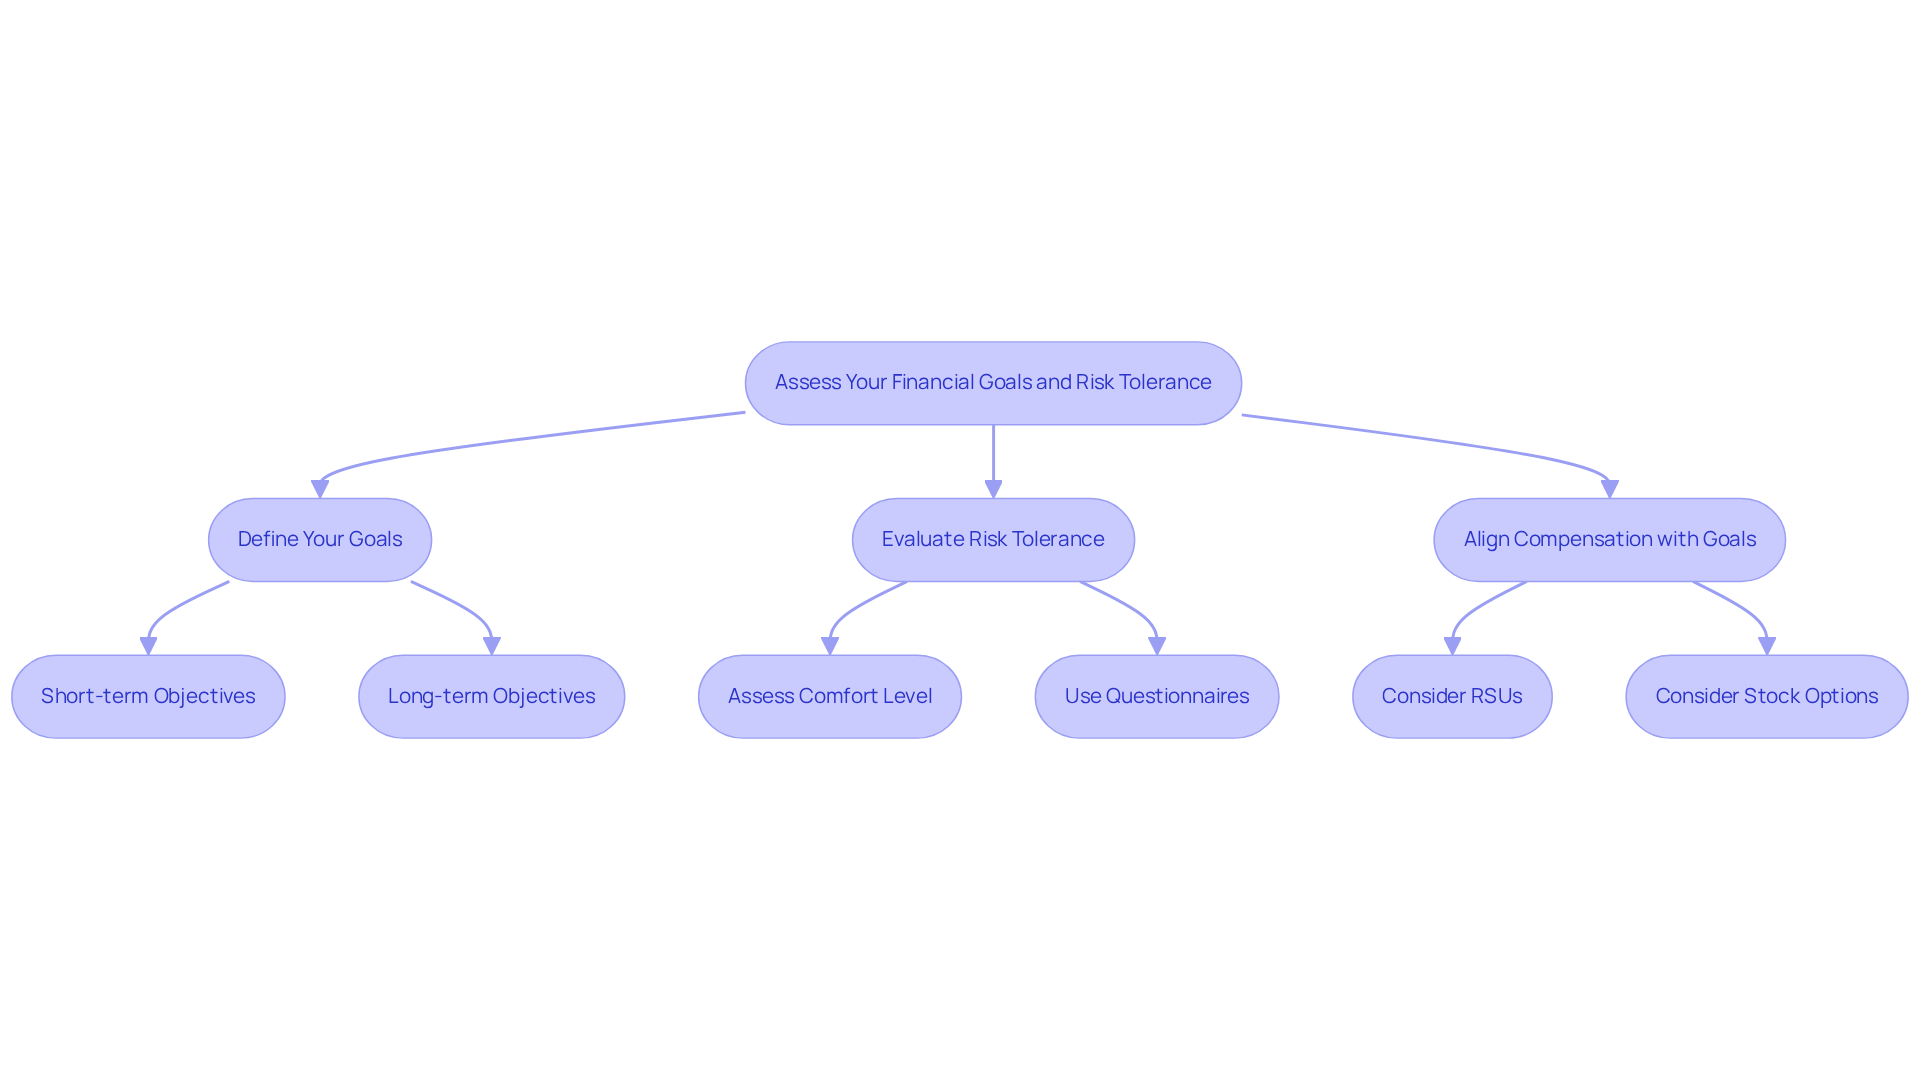
Define Your Goals: Identify your household’s short-term and long-term monetary objectives, like saving for education, purchasing a home, or planning for retirement. When you have clarity, it guides your financial decisions and aligns with your family’s values and vision for the future. We believe in starting with what truly matters to your family. Please note that we are currently at capacity and invite you to join our waitlist for future availability.
Evaluate Risk Tolerance:
- Assess your comfort level with potential investment losses. Understanding your risk tolerance is crucial for making informed investment choices.
- Utilize online risk tolerance questionnaires to help gauge your comfort level and align your investment strategy accordingly.
Align Compensation with Goals:
- If your family prioritizes stability, consider Restricted Stock Units (RSUs) for their predictable value.
- If you are open to taking risks for potentially higher rewards, stock options may be a suitable choice.
Checklist: Document your monetary goals and engage in discussions with your partner to ensure both of you are aligned in your planning efforts. This collaborative approach can improve your monetary strategy and foster a shared commitment to achieving your objectives. As you embark on this journey, our comprehensive onboarding process at Bright Advisers will guide you through defining your family strategy, developing a sound financial plan, and building a customized investment strategy focused on achieving your unique family and financial goals. The onboarding process includes:
- Getting started
- Data gathering
- Strategy session
- Financial planning
- Investment strategy
With the right guidance, you can turn your financial dreams into reality, ensuring a brighter future for your family.
Conclusion
Navigating the world of equity compensation can feel overwhelming for young families, but understanding the differences between Restricted Stock Units (RSUs) and stock options is a vital step toward securing your financial future. Taking a moment to evaluate your equity compensation options can empower your family to make choices that truly reflect your financial goals and comfort levels.
Think of RSUs as a simpler, more secure choice for your family, while stock options might offer exciting potential but come with their own set of risks. It’s important to consider how each option impacts your family’s financial landscape, especially when it comes to taxes and long-term goals.
Remember, every step you take toward understanding these options is a step closer to a secure future for your family. Engaging with a fiduciary advisor like Bright Advisers can provide the necessary guidance to navigate these complexities. With the right support, you can confidently make choices that protect your family’s future and nurture your shared dreams.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are shares awarded to employees based on fulfilling certain criteria, typically including a vesting period. Once the units vest, employees gain full ownership of the shares, which are usually awarded at no cost.
How do RSUs work in terms of vesting?
RSUs typically have a vesting schedule, such as a four-year plan where an employee earns a certain number of shares each year. For example, if awarded 1,000 RSUs with a four-year vesting schedule, the employee would receive 250 shares each year.
How are RSUs taxed?
RSUs are taxed as regular income when they vest, based on their fair market value at that time.
What are stock options?
Stock options grant employees the right to purchase shares at a predetermined price, known as the strike price, within a specified timeframe. Unlike RSUs, stock options require an initial investment to exercise.
What are the key differences between RSUs and stock options?
RSUs are generally simpler and provide shares delivered at vesting, making them appealing for employees seeking stability. In contrast, stock options may offer higher potential rewards but come with risks, especially if the stock price does not exceed the strike price.
Why is it important to understand equity compensation?
Understanding the terms and conditions of equity compensation, including the tax implications of RSUs, is crucial for maximizing benefits and making informed long-term financial planning decisions for families.
How can families navigate the complexities of their compensation packages?
Seeking expert guidance can help families understand their compensation packages better and make the most of their resources for financial growth and stability.
List of Sources
- Define RSUs and Stock Options
- All you need to know about RSUs (https://beqom.com/blog/restricted-stock-units-all-you-need-to-know-about-rsus)
- What are restricted stock units (RSUs)? A complete guide – Qapita (https://qapita.com/blog/restricted-stock-units)
- RSU vs. Stock Options: Navigating Equity Compensation (https://tgcsearch.com/business-insights/rsu-vs-stock-options-navigating-equity-compensation)
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- What is an RSU? Restricted Stock Guide for Executives (https://jnba.com/insights/what-is-an-rsu)
- Identify Key Differences Between RSUs and Stock Options
- Employee Ownership by the Numbers (https://nceo.org/research/employee-ownership-by-the-numbers)
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)
- RSU vs Stock Options: Key Differences To Know | Citrine Capital (https://citrinecapitaladvisors.com/blog/rsu-vs-stock-options)
- ESOP vs RSU vs ESPP: Key Differences, Meaning & Tax Benefits (https://vestedfinance.com/blog/us-stocks/differences-between-esops-rsus-and-espps)
- RSU vs. Stock Options: Navigating Equity Compensation (https://tgcsearch.com/business-insights/rsu-vs-stock-options-navigating-equity-compensation)
- Evaluate Tax Implications of RSUs and Stock Options
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- Stock Options vs Restricted Stock Units (RSUs): A guide (https://jpmorganworkplacesolutions.com/insights/rsus-vs-stock-options)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Assess Your Financial Goals and Risk Tolerance
- Gen Z turns to parents as Americans reshape financial goals, Wells Fargo study finds (https://investmentnews.com/wirehouses/gen-z-turns-to-parents-as-americans-reshape-financial-goals-wells-fargo-study-finds/265911)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- The Influence of Risk, Financial Literacy, and Trust on Financial Advice-seeking Behavior in a Cross-racial Examination (https://financialplanningassociation.org/learning/publications/journal/FEB23-influence-risk-financial-literacy-and-trust-financial-advice-seeking-behavior-cross-racial-OPEN)
- Wells Fargo 2026 Money Study Reveals Americans Redefining the American Dream; Gen Z leaning on Parents for Financial Support (https://newsroom.wf.com/news-releases/news-details/2026/Wells-Fargo-2026-Money-Study-Reveals-Americans-Redefining-the-American-Dream-Gen-Z-leaning-on-Parents-for-Financial-Support/default.aspx)
- BofA Study Finds Fewer Gen Z Rely on Family for Financial Assistance, Even With 42% Living Paycheck to Paycheck (https://newsroom.bankofamerica.com/content/newsroom/press-releases/2026/05/bofa-study-finds-fewer-gen-z-rely-on-family-for-financial-assist.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading