

Key Highlights:
- Verify relevant certifications such as CFP, CPWA, or CWS to ensure the advisor has the necessary expertise.
- Review the advisor’s educational background and professional experience to build confidence in their ability to meet your family’s needs.
- Cheque for any disciplinary actions or complaints through regulatory bodies like FINRA or SEC to confirm their reputation.
- Assess the advisor’s success in managing portfolios for ultra high net worth clients to gauge their capability.
- Ensure the advisor is committed to ongoing education to stay updated on economic trends and regulations.
- Inquire about asset protection strategies including trusts, insurance policies, and legal structures tailored to your financial situation.
- Request case studies from the advisor to understand the effectiveness of their asset protection strategies.
- Clarify the fee structures, including management fees and performance fees, to understand the total costs involved.
- Discuss the advisor’s accountability measures and performance benchmarks for transparency and trust.
- Seek references or testimonials from clients with similar backgrounds to assess the advisor’s effectiveness with ultra high net worth individuals.
Introduction
Choosing the right financial advisor is a pivotal decision that can shape the financial future of ultra high net worth families. Imagine if you could find someone who not only understands the complexities of wealth management but also truly cares about your family’s unique challenges. This essential checklist serves as your guide to navigating the process of selecting an advisor who possesses the right qualifications and shares your values.
With so many options available, it’s important to ask: how can you ensure that the advisor you choose aligns with your family’s specific financial needs? Together, we can explore this journey, ensuring that your family’s priorities are at the forefront of every decision. We’re here for you, ready to support you in making this crucial choice.
Verify Advisor Qualifications and Experience
When choosing a , it’s essential to consider a few key factors that can make a world of difference for your family’s future.
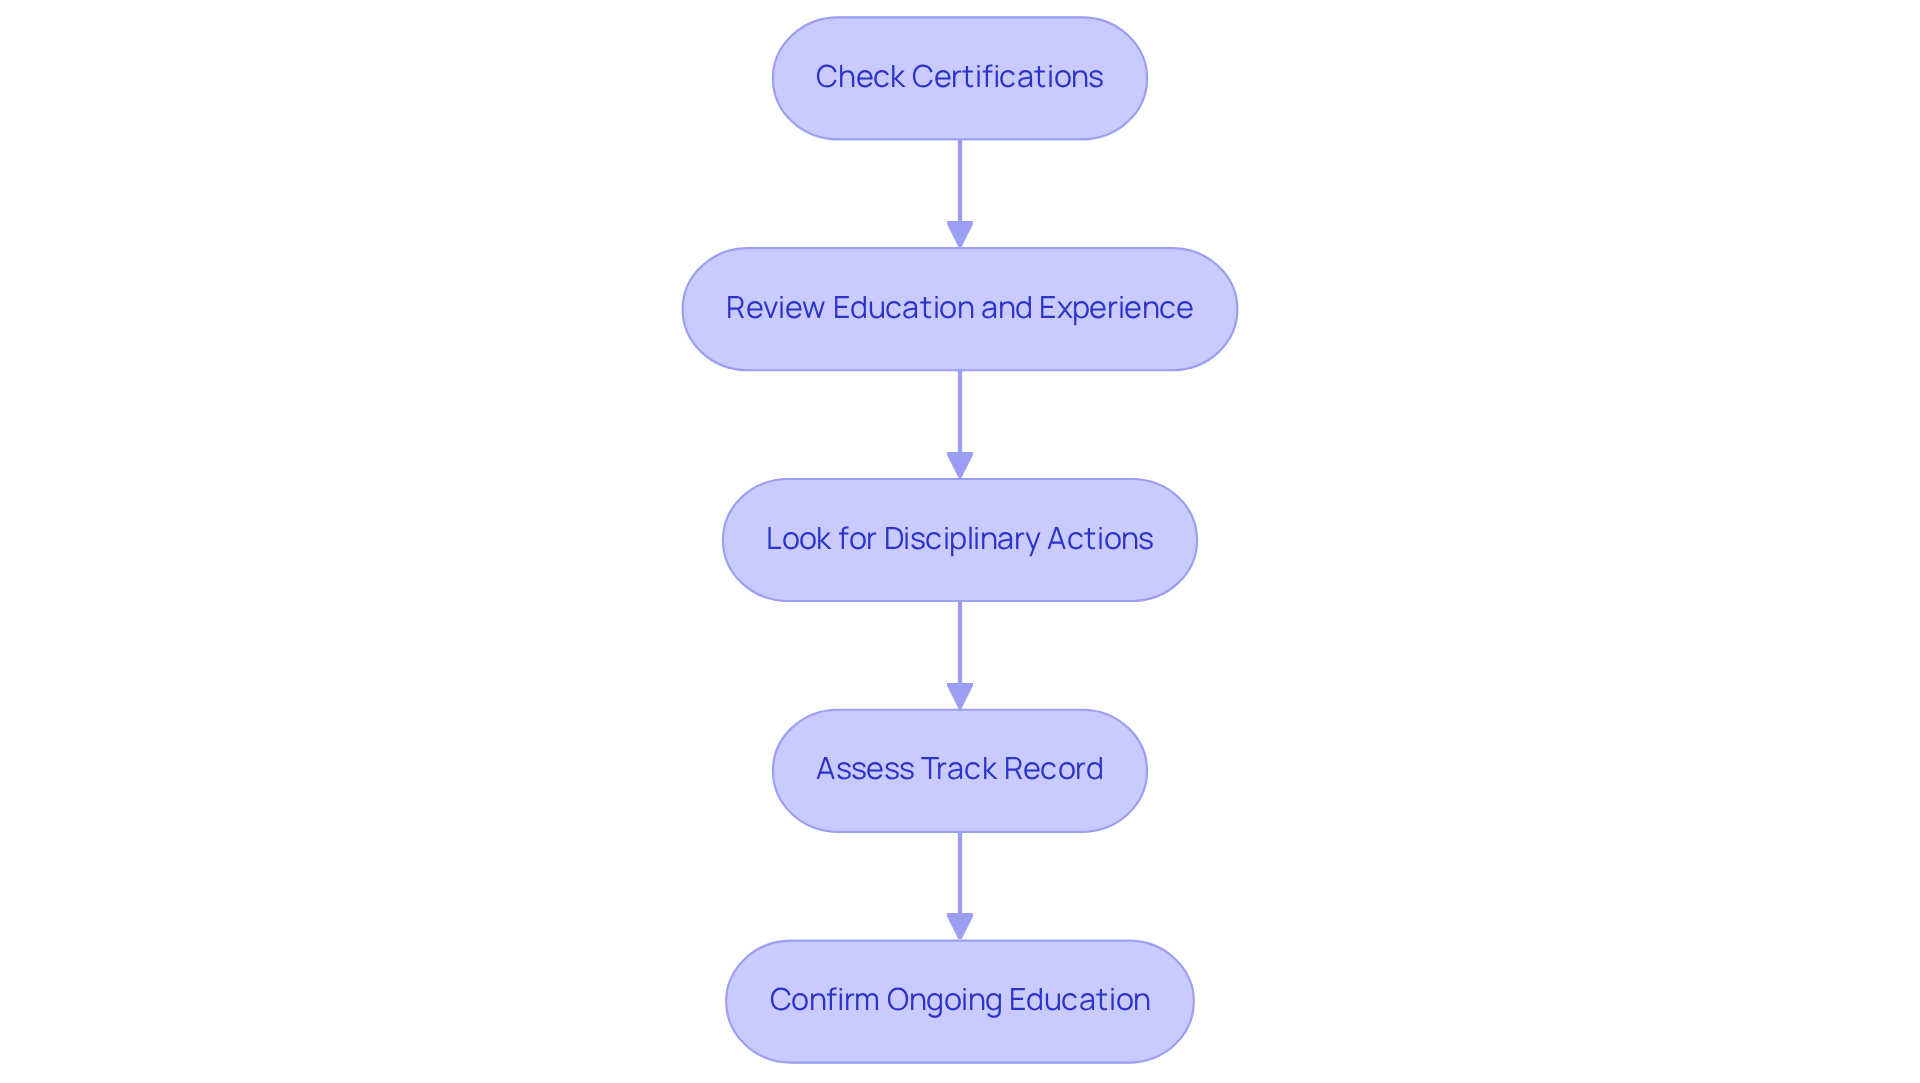
- First, check for relevant certifications like CFP, CPWA, or CWS. These credentials show that the advisor has the expertise needed to guide you through your financial journey.
- Next, take a moment to review their educational background and professional experience. Understanding their qualifications can help you feel more confident in their ability to support your family’s unique needs.
- It’s also important to look for any disciplinary actions or complaints through regulatory bodies such as FINRA or the SEC. This step ensures that you’re working with someone who has a solid reputation and is committed to ethical practices.
- Assessing the track record of an ultra high net worth financial advisor with clients is crucial too. Focus on the success of the ultra high net worth financial advisor in managing portfolios similar to yours, as this can provide insight into how they might handle your family’s wealth.
- Lastly, confirm their ongoing education and commitment to staying updated on economic trends and regulations. A dedicated advisor will always strive to enhance their knowledge, ensuring they can offer you the best advice possible.
Remember, we’re here for you every step of the way. Together, we can navigate this journey and secure a brighter financial future for your family.
Inquire About Asset Protection Strategies
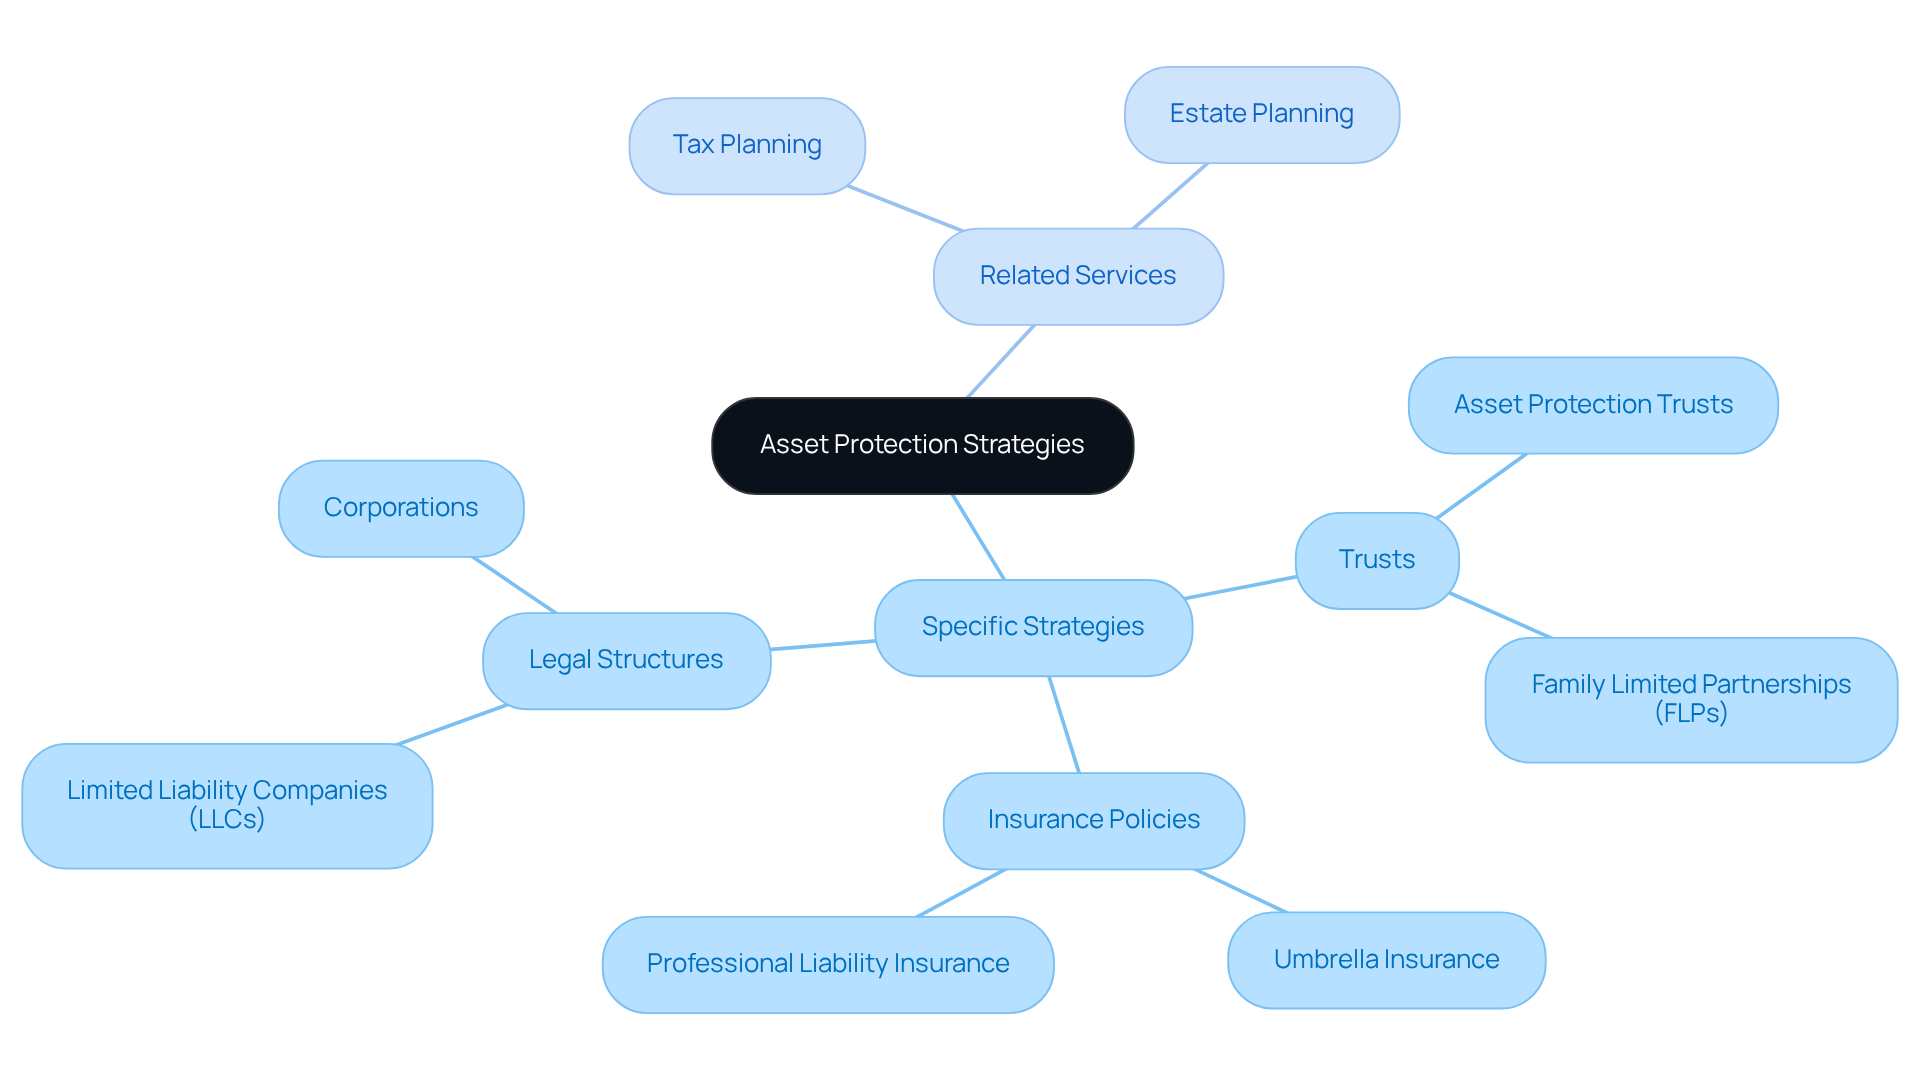
When you think about , it’s essential to have a clear understanding of the strategies available. Ask your advisor to share their approach to asset protection and risk management, ensuring they provide a tailored plan that fits your unique financial situation.
Consider discussing specific strategies like:
- Trusts
- Insurance policies
- Legal structures
These are designed to safeguard your family’s wealth. It’s important to assess their experience with individuals who have similar financial profiles, confirming their knowledge of current laws and regulations that impact asset protection.
Imagine if you could see real-life examples of successful asset protection strategies. Request case studies from your advisor; these can offer valuable insights into how effective these strategies can be for your family’s needs.
Also, think about how these asset protection strategies can work alongside other services offered by Bright Advisers, such as:
This comprehensive approach ensures that your wealth management aligns with your family’s values and priorities.
Remember, we’re here for you. Together, we can navigate this journey toward securing your family’s future.
Clarify Fee Structures and Accountability
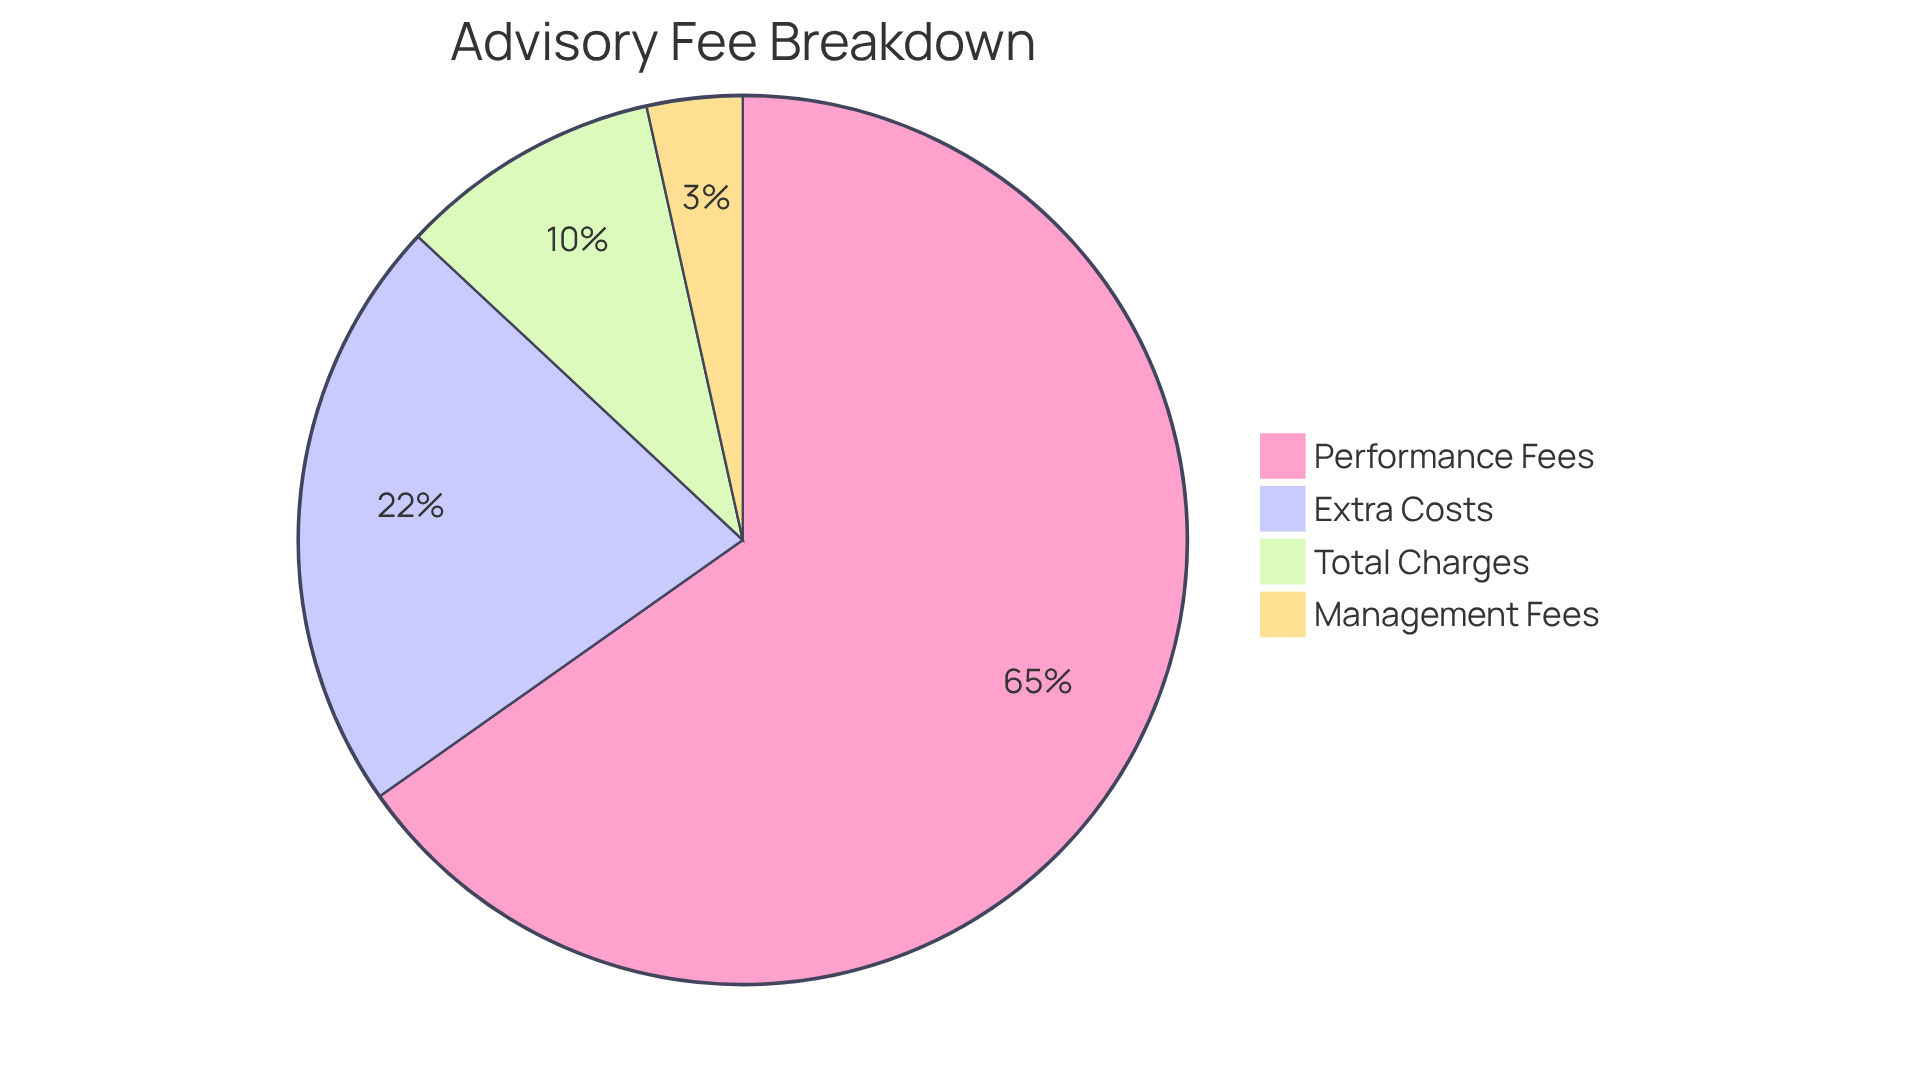
When it comes to managing your family’s wealth, understanding the costs involved is essential. Imagine sitting down with an ultra high net worth financial advisor and feeling confident about every charge related to their services. For example, Bright Advisers offers a standard [investment management fee](https://brightadvisers.com/?p=12761) of 0.80%, which is billed monthly in advance based on your account’s market value. Knowing the full range of fees – like management fees, performance fees, and any extra costs – helps you evaluate the overall expense of financial advice.
It’s important to ask whether your advisor, particularly an ultra high net worth financial advisor, works on a fee-only, commission-based, or hybrid model. Bright Advisers typically charges a flat fee or a percentage of assets under management, ensuring their compensation aligns with your best interests. Understanding how fees are calculated and when they’re charged – whether monthly, quarterly, or annually – can make a big difference in your financial planning.
Consider discussing the advisor’s accountability measures, such as performance benchmarks and how often they report back to you. A trustworthy consultant should have clear criteria for success and provide regular updates on performance, helping you stay aligned with your family’s financial goals. Bright Advisers is committed to transparency, offering clients regular updates on costs and performance, which fosters trust and empowers you to make informed decisions about your investments.
As a gentle reminder, be cautious if total charges exceed 2.0% annually when combining consultant and investment fees; this could indicate excessive costs. With many financial consultants, particularly ultra high net worth financial advisors, operating under a , it’s crucial to keep this trend in mind when evaluating potential advisors. Open communication about fees is vital, as many investors feel uncertain about compensation without proper guidance. By discussing service costs openly, you can build trust and strengthen your relationship with your advisor, attracting those who are ready to invest in quality advice for their family’s future.
Ask About Experience with Similar Clients
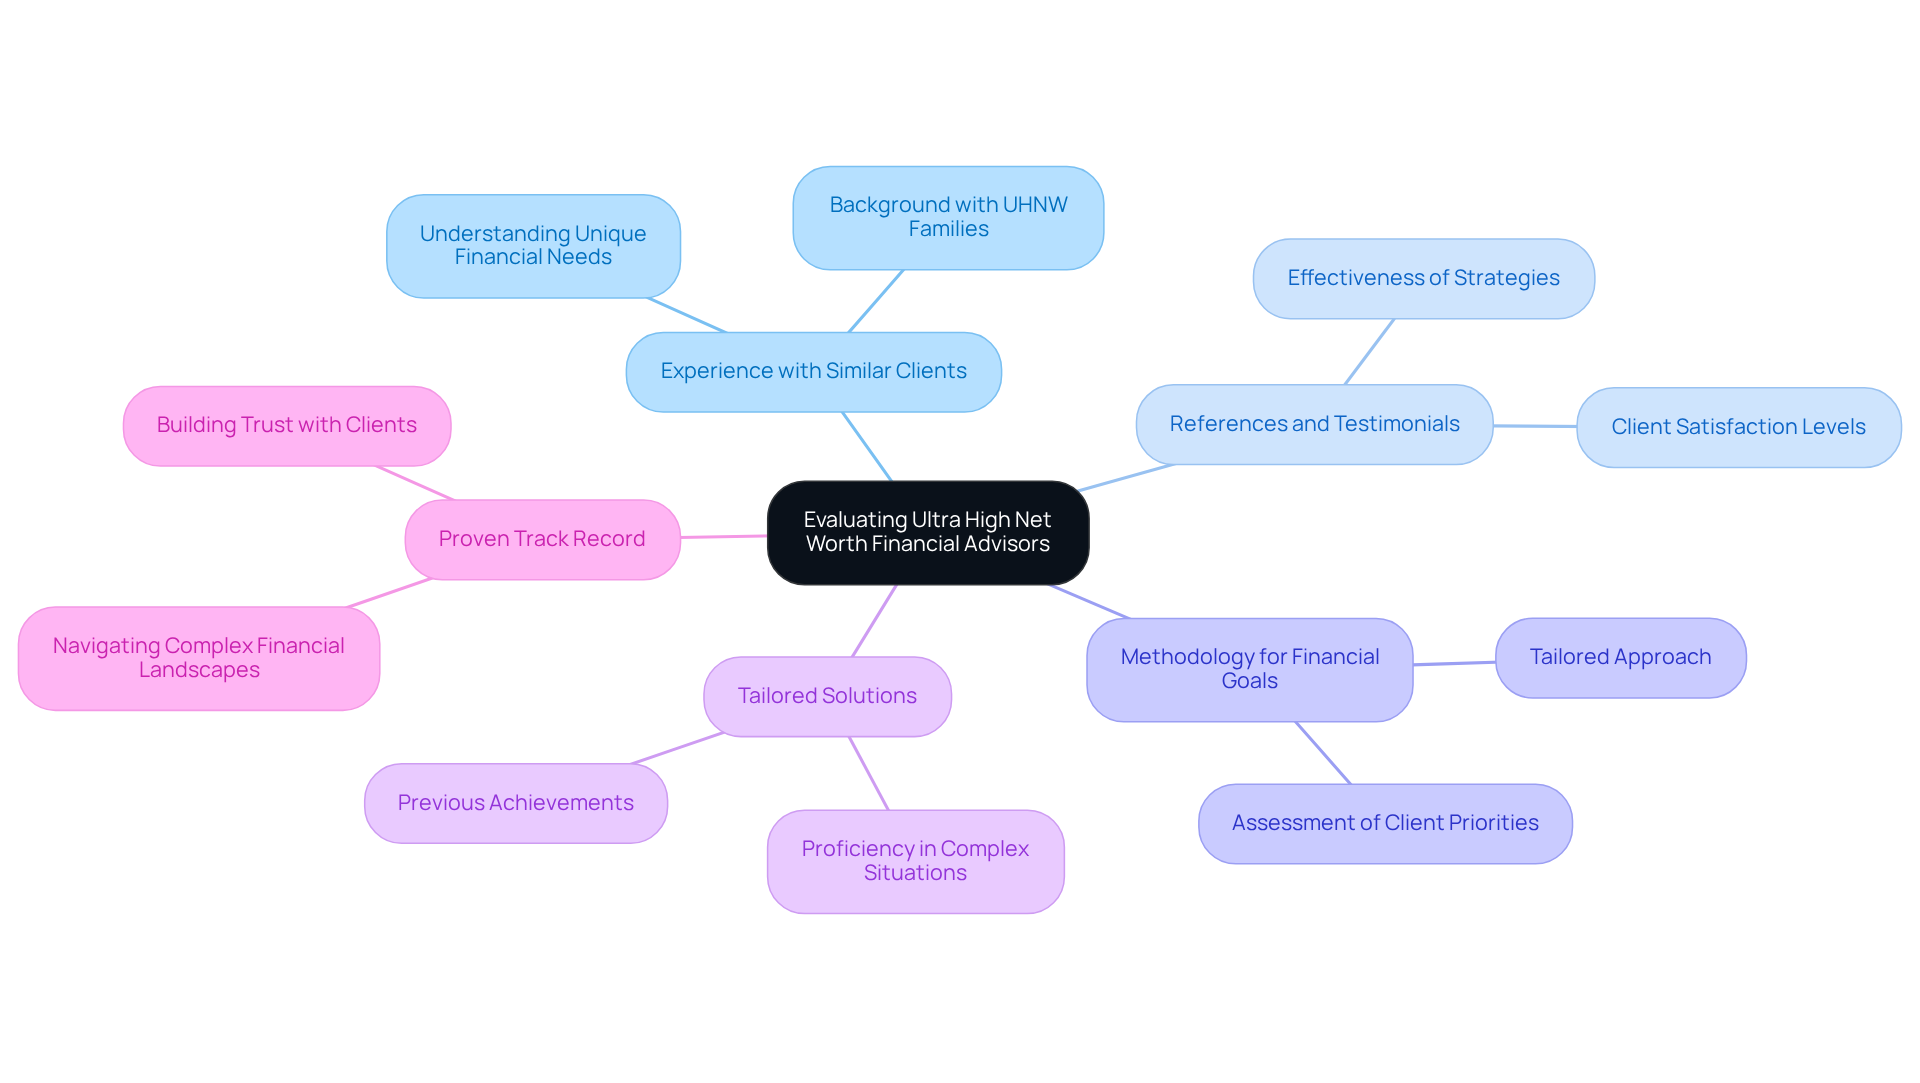
When considering an , it’s vital to ask about their experience with ultra-high-net-worth families or individuals. This background is crucial for understanding the unique financial needs that come with significant wealth. Imagine having someone who truly gets the intricacies of your monetary concerns.
Don’t hesitate to request references or testimonials from clients with similar backgrounds. This can give you insight into their satisfaction levels and the effectiveness of the consultant’s strategies. It’s important to know that others have walked this path and found success.
Discuss the methodology of the ultra high net worth financial advisor for identifying and addressing the specific financial goals of clients. This ensures they can tailor their approach to fit your family’s unique situation. After all, your family’s priorities deserve personalized attention.
Assess their ability to provide tailored solutions. Look for previous achievements that demonstrate their proficiency in handling complex financial situations. Knowing they have successfully navigated similar challenges can instill confidence in their capabilities.
Finally, confirm their proven track record in navigating complex financial landscapes. This is essential for building trust in their ability to manage significant wealth. Remember, you’re not just looking for a consultant; you’re seeking a partner who understands your family’s journey. Together, we can navigate this path with confidence.
Conclusion
Choosing the right ultra high net worth financial advisor is a significant step that can profoundly impact your family’s financial well-being and legacy. It’s essential to ensure that your advisor has the right qualifications, experience, and ethical standards. This journey involves:
- Checking certifications
- Understanding their approach to asset protection
- Clarifying fee structures
- Assessing their experience with clients who share similar financial profiles
Imagine if you could navigate this complex selection process with confidence. Key steps include:
- Verifying qualifications and certifications
- Asking about personalized asset protection strategies
- Ensuring transparency in fee structures
It’s also crucial to evaluate the advisor’s experience with ultra high net worth clients, as this directly influences their ability to tackle unique financial challenges effectively.
Ultimately, finding the right financial advisor isn’t just about managing wealth; it’s about building a partnership that resonates with your family’s values and financial aspirations. By following this checklist, you can make informed decisions that protect your assets and enhance your financial future. Remember, taking the time to ask the right questions and seeking an advisor who understands the nuances of wealth management will lead to a more secure and prosperous financial journey. Together, we can navigate this path with care and confidence.
Frequently Asked Questions
What certifications should I look for in a financial advisor?
You should look for relevant certifications such as CFP (Certified Financial Planner), CPWA (Certified Private Wealth Advisor), or CWS (Certified Wealth Strategist), as these indicate the advisor’s expertise.
Why is it important to review a financial advisor’s educational background and professional experience?
Reviewing their educational background and professional experience helps you assess their qualifications and can increase your confidence in their ability to meet your family’s unique financial needs.
How can I check if a financial advisor has a good reputation?
You can check for any disciplinary actions or complaints against the advisor through regulatory bodies like FINRA (Financial Industry Regulatory Authority) or the SEC (Securities and Exchange Commission) to ensure they have a solid reputation and adhere to ethical practices.
Why is it important to assess a financial advisor’s track record?
Assessing the track record of an ultra high net worth financial advisor is crucial as it provides insight into their success in managing portfolios similar to yours, which can indicate how they might handle your family’s wealth.
What should I confirm regarding a financial advisor’s ongoing education?
You should confirm that the advisor is committed to ongoing education and staying updated on economic trends and regulations, as this ensures they can offer you the best advice possible.
List of Sources
- Verify Advisor Qualifications and Experience
- Has My Stockbroker or Investment Advisor Been Disciplined? (https://finraarbitrationattorney.com/has-my-stockbroker-investment-advisor-been-trouble-disciplined)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- 2024 FINRA Sanctions Study (https://eversheds-sutherland.com/en/united-states/insights/2024-finra-sanctions-study)
- Key Statistics (https://finra.org/media-center/statistics)
- Inquire About Asset Protection Strategies
- The Future of Asset Protection: Trends to Watch (https://jamesburnslaw.com/the-future-of-asset-protection-trends-to-watch)
- Asset Protection Planning Facts (https://assetprotectionplanners.com/planning/facts)
- Elevate Your Financial Security: Mastering Asset Protection Strategies – Like Law Group Bloomington, Indiana (https://likelawgroup.com/2025/06/09/elevate-your-financial-security-mastering-asset-protection-strategies)
- 7 Asset Protection Strategies for High-Net-Worth Individuals | Apt Wealth Partners (https://aptwealth.com.au/news/asset-protection-strategies)
- Essential Asset Protection Strategies for High Net Worth Individuals (https://investopedia.com/articles/personal-finance/060515/asset-protection-high-net-worth-individuals.asp)
- Clarify Fee Structures and Accountability
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Nearly 78% of Advisors to Shift Toward Fee-Based Services by 2026 (https://connectmoney.com/stories/nearly-78-of-advisors-to-shift-toward-fee-based-services-by-2026)
- More than three-quarters of advisors to embrace fee models by 2026, Cerulli says (https://investmentnews.com/practice-management/more-than-three-quarters-of-advisors-to-embrace-fee-models-by-2026-cerulli-says/259740)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- Ask About Experience with Similar Clients
- Why advisors need to up their service game for high-net-worth and UHNW clients (https://investmentnews.com/practice-management/why-advisors-need-to-up-their-service-game-for-high-net-worth-and-uhnw-clients/261889)
- Institute-Certified Advisors Attract Wealthier Clients (https://investmentsandwealth.org/advisor-publications/blog/how-institute-certified-advisors-attract-wealthier-clients-a-look-at-the-data)
- How UHNW Families Manage Wealth: Survey Results & Resources (https://pbig.ml.com/articles/uhnw-family-wealth.html)
- As the high-net-worth seek out new wealth managers, how do you retain clients and capture money-in-motion? (https://pwc.com/us/en/industries/financial-services/asset-wealth-management/high-net-worth-investor.html)
- Understanding ultra-high-net-worth individuals (https://clearingcustody.fidelity.com/insights/spotlights/understanding-ultra-high-net-worth-individuals)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading