

Key Highlights
- Employees may experience financial benefits from an IPO but must navigate complex tax implications related to their equity compensation.
- Equity compensation types include Incentive Stock Options (ISOs), Non-Qualified Stock Options (NQSOs), and Restricted Stock Units (RSUs), each with distinct tax treatments.
- ISOs can qualify for long-term capital gains tax rates if held for specific periods, while NQSOs are taxed as ordinary income upon exercise.
- RSUs are taxed as ordinary income when they vest, potentially leading to significant tax liabilities.
- Proactive tax planning strategies, such as exercising stock options early and increasing retirement contributions, can help minimise tax liabilities.
- The Net Investment Income Tax (NIIT) may increase effective tax rates on capital gains, particularly in states like California where capital gains are taxed as ordinary income.
- Understanding the lock-up period after an IPO is crucial for managing tax obligations and investment strategies.
- Professional guidance in IPO tax planning can help families make informed financial decisions and secure their financial future.
Introduction
Imagine the excitement of your company going public, but also the worry about how it might affect your family’s finances. Navigating the complexities of an initial public offering (IPO) can feel overwhelming for many startup employees. Let’s explore some caring strategies that can help you navigate the tax implications of an IPO, ensuring your family’s financial future remains bright.
As you think about the different types of equity and their tax treatments, consider how you can prepare for the financial impact of an IPO and make choices that support your family’s dreams. Without proper planning, employees risk facing unexpected tax burdens that could impact their family’s financial stability. With the right strategies, you can turn the challenges of an IPO into opportunities for your family’s future.
Understand the Implications of an IPO for Employees
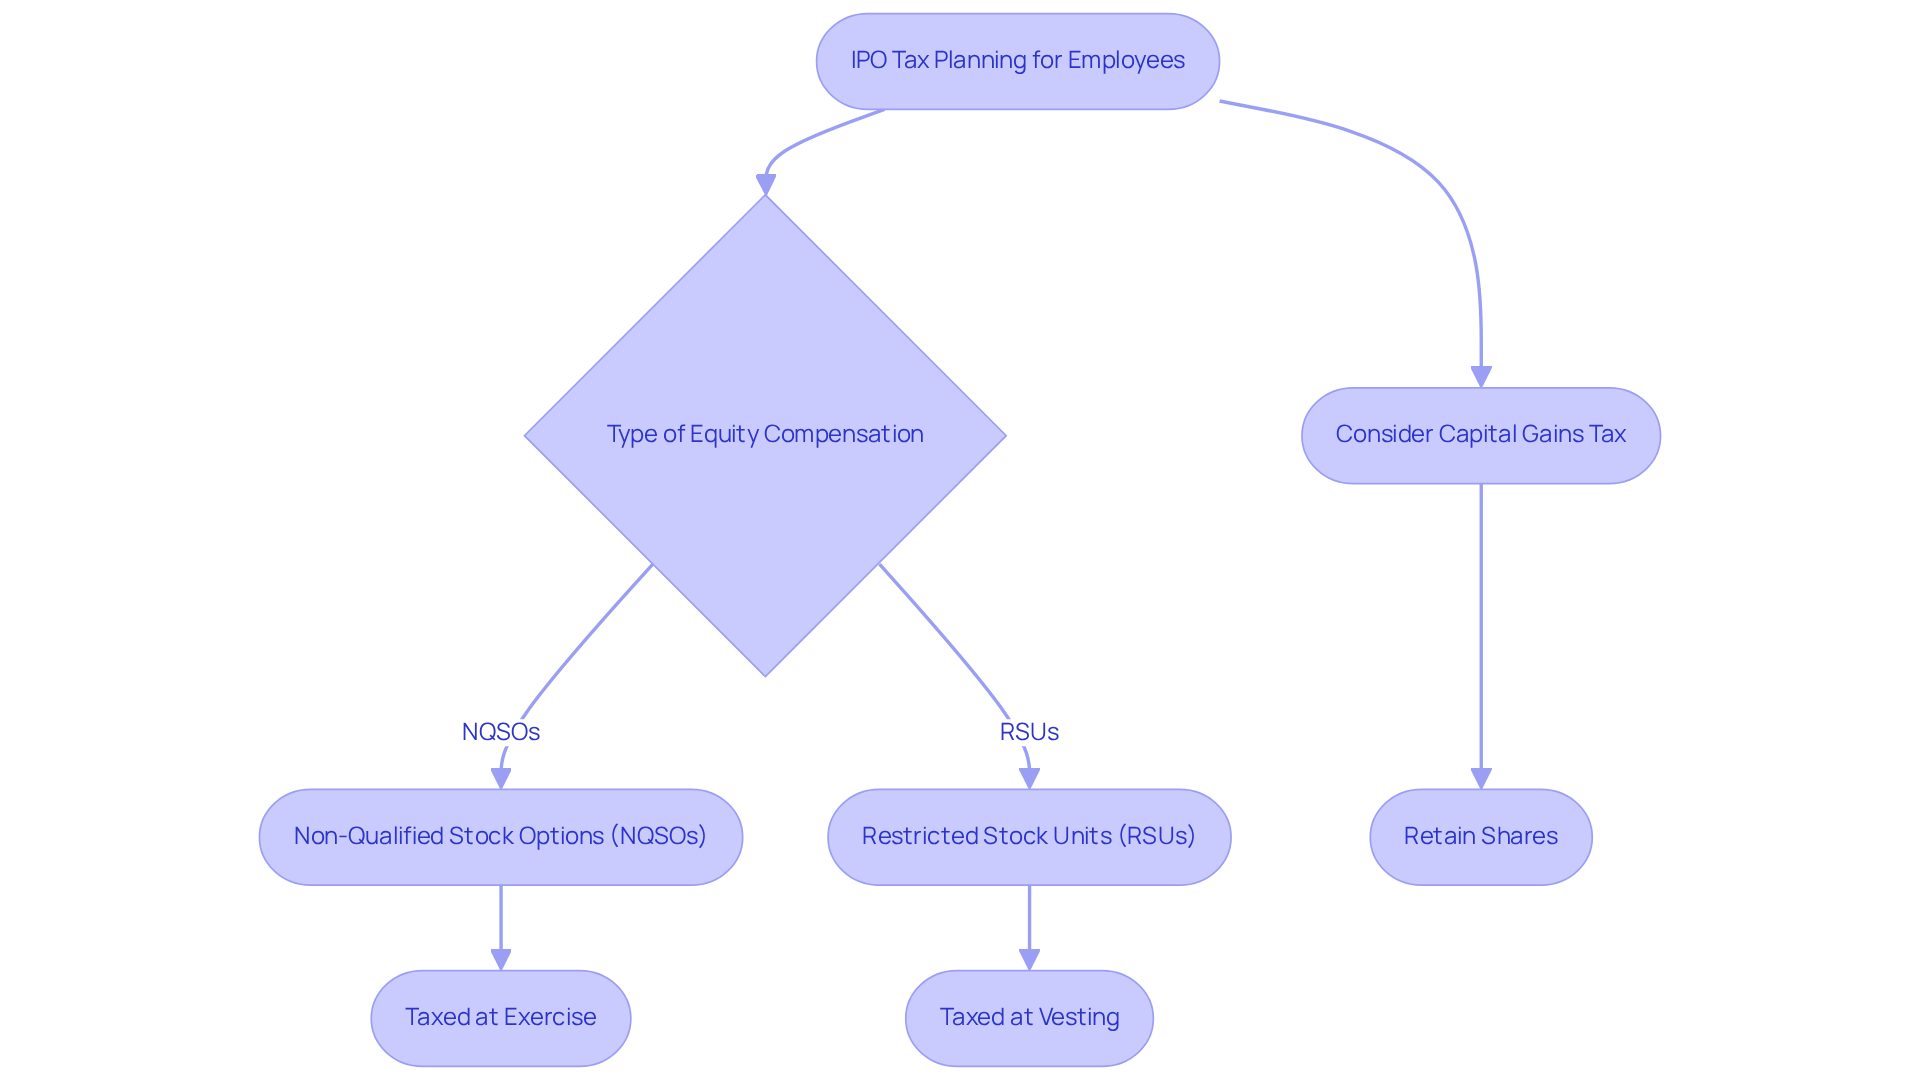
Imagine receiving a financial boost from your company going public, only to feel overwhelmed by the need for IPO tax planning for startup employees that follows. Many employees feel anxious about navigating the tax landscape after receiving their equity compensation, especially in relation to IPO tax planning for startup employees. However, this financial boost brings a wave of tax considerations, particularly IPO tax planning for startup employees, that can feel daunting. Employees must understand that the value of their equity compensation will be subject to ordinary income tax upon vesting or exercise, which is crucial for effective IPO tax planning for startup employees, depending on the type of equity they hold. For instance, IPO tax planning for startup employees indicates that non-qualified stock options (NQSOs) are taxed at exercise, while RSUs are taxed as income when they vest. Furthermore, staff should be mindful of the possibility of capital profits tax when considering IPO tax planning for startup employees if they retain their shares and sell them later. It’s important to grasp these tax implications, especially for families who want to consider IPO tax planning for startup employees to set aside funds for their children’s education and other needs.
As we look ahead to 2026, it’s crucial to consider how the Net Investment Income Tax (NIIT) might affect your returns. For example, the highest federal tax rate on long-term capital profits is 20%, but with the NIIT, the effective rate can increase to 23.8%. Furthermore, staff must navigate the complexities of state taxes, particularly in California, where capital gains are taxed as ordinary income.
At Bright Advisers, we emphasize the importance of proactive tax planning strategies, such as IPO tax planning for startup employees, tailored for families. Collaborating with advisors who specialize in IPO tax planning for startup employees can assist individuals in creating strategies to effectively manage their tax obligations. Our clear fee structure guarantees no concealed charges, enabling families to concentrate on their monetary objectives. By understanding these tax implications and leveraging our personalized financial planning services, individuals can make informed decisions that align with their financial goals and family needs. By taking proactive steps today, you can ensure that your family’s financial future is secure and bright. Join our waitlist today to learn more about how we can assist you in navigating these complexities.
Implement Pre-IPO Tax Strategies to Minimize Liabilities
Imagine feeling the weight of tax obligations as your company prepares for an IPO, and contemplating IPO tax planning for startup employees to secure your family’s financial future amidst the complexities. To navigate this journey, there are several strategies you can consider.
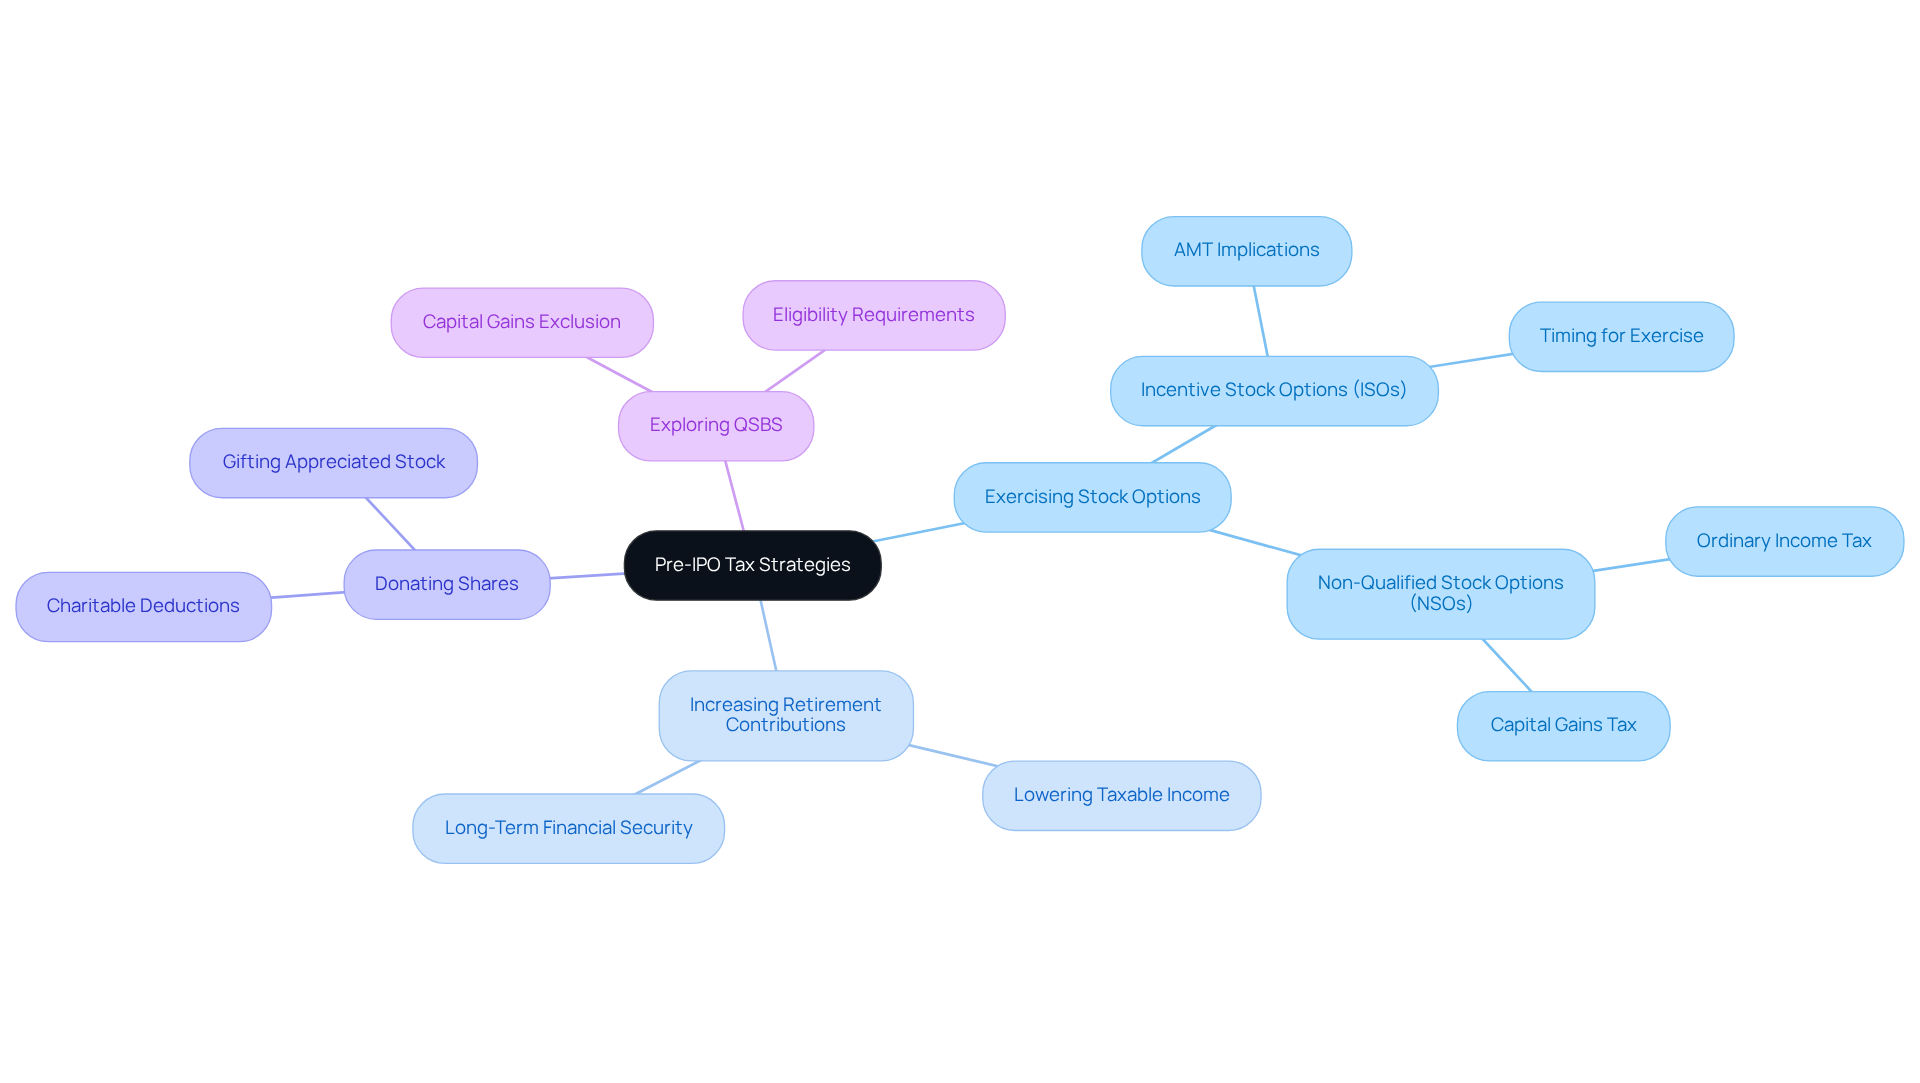
You might be wondering about exercising stock options early. This can help reduce the amount subject to the Alternative Minimum Tax (AMT), which can feel overwhelming. Let’s break it down together. If you exercise Incentive Stock Options (ISOs) in the year of or before the IPO, you may incur AMT on the bargain element. This is taxed at rates between 26% and 28%. It’s important to understand that the AMT due date is April 15 of the following year. Knowing this can help you plan better for your family’s needs.
Consider how increasing your contributions to retirement accounts can lower your taxable income. It’s a step towards securing your family’s future. Have you thought about donating appreciated shares to charity? It’s a generous way to give back while also benefiting from a charitable deduction.
Exploring the benefits of Qualified Small Business Stock (QSBS) can be worthwhile. It might allow you to exclude significant capital gains, which can be a relief for your family’s finances. With these strategies in place, you can feel more secure about your family’s financial future as the IPO approaches, knowing that IPO tax planning for startup employees is helping you take steps to save on taxes.
Navigating tax planning can be complex, but remember, families like yours can find comfort in professional guidance to help you through these challenges together.
Navigate the Lock-Up Period: Tax Considerations and Strategies
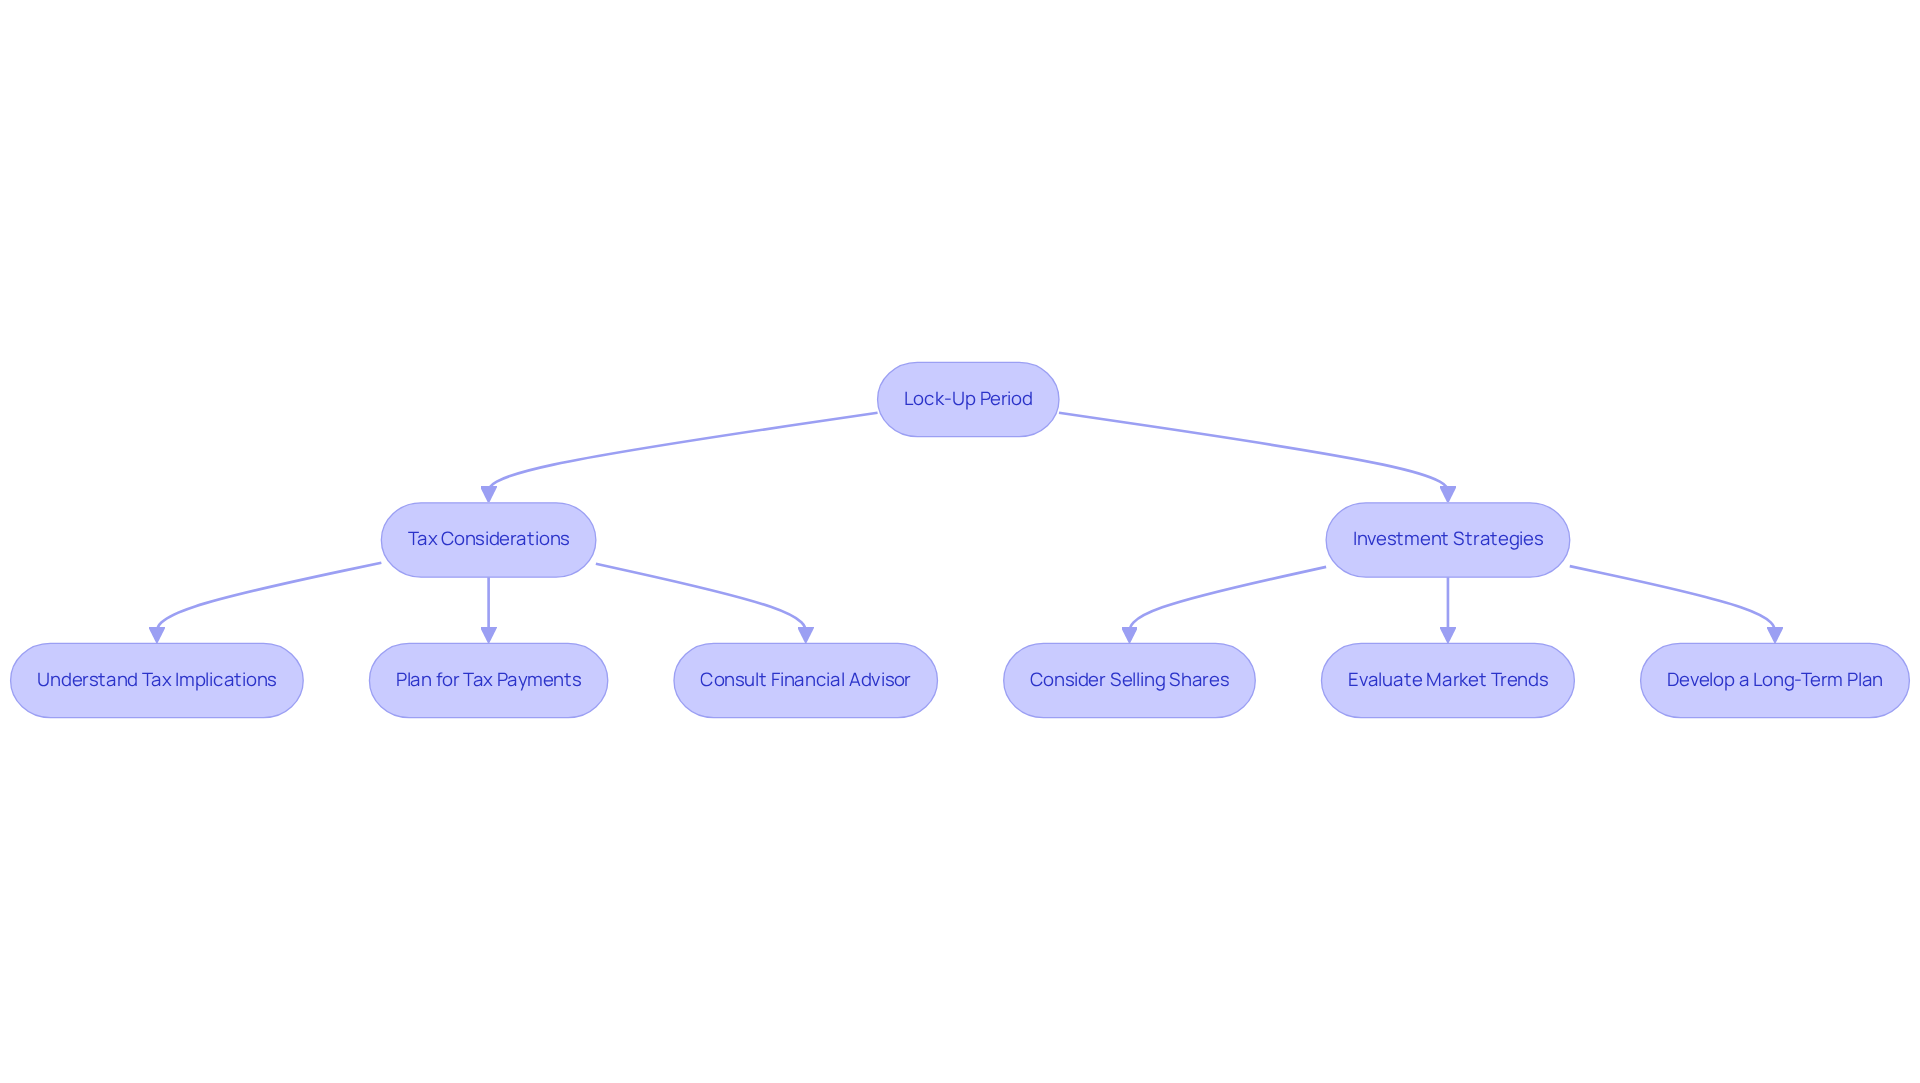
Imagine feeling anxious about your finances while waiting for your shares to unlock after an IPO, particularly in the context of ipo tax planning for startup employees. During this time, you can’t sell your shares, which can feel overwhelming. This waiting period can lead to stress, especially when unexpected tax bills come due, making ipo tax planning for startup employees crucial to alleviate worries about how to cover them. But don’t worry; there are ways to manage these challenges and ensure you’re prepared for what’s ahead.
Thinking about selling some shares right after the lock-up can help you meet those tax payments and reduce risk in your investments. Keep in mind that selling shares right after the lock-up can lead to higher taxes, which can feel frustrating. That’s why it’s so important to have a plan in place for ipo tax planning for startup employees during this time.
You might notice that new public companies sometimes don’t perform as well as expected, which can be disheartening. Understanding these trends can help you feel more confident in your financial decisions. Real-life stories show how important it is to grasp the ins and outs of your equity compensation.
Talking to a financial advisor can make a big difference in navigating your options and ensuring you don’t miss out on opportunities. Getting involved in planning your stock options can really help you make the best choices for your family’s future.
Differentiate Between Equity Types: Tax Treatments and Implications
Navigating the world of equity compensation can feel overwhelming, especially when you’re trying to secure your family’s financial future. Employees often receive various types of equity compensation, including:
- Incentive Stock Options (ISOs)
- Non-Qualified Stock Options (NQSOs)
- Restricted Stock Units (RSUs)
Each type of equity compensation comes with its own tax implications, which can really impact your family’s finances.
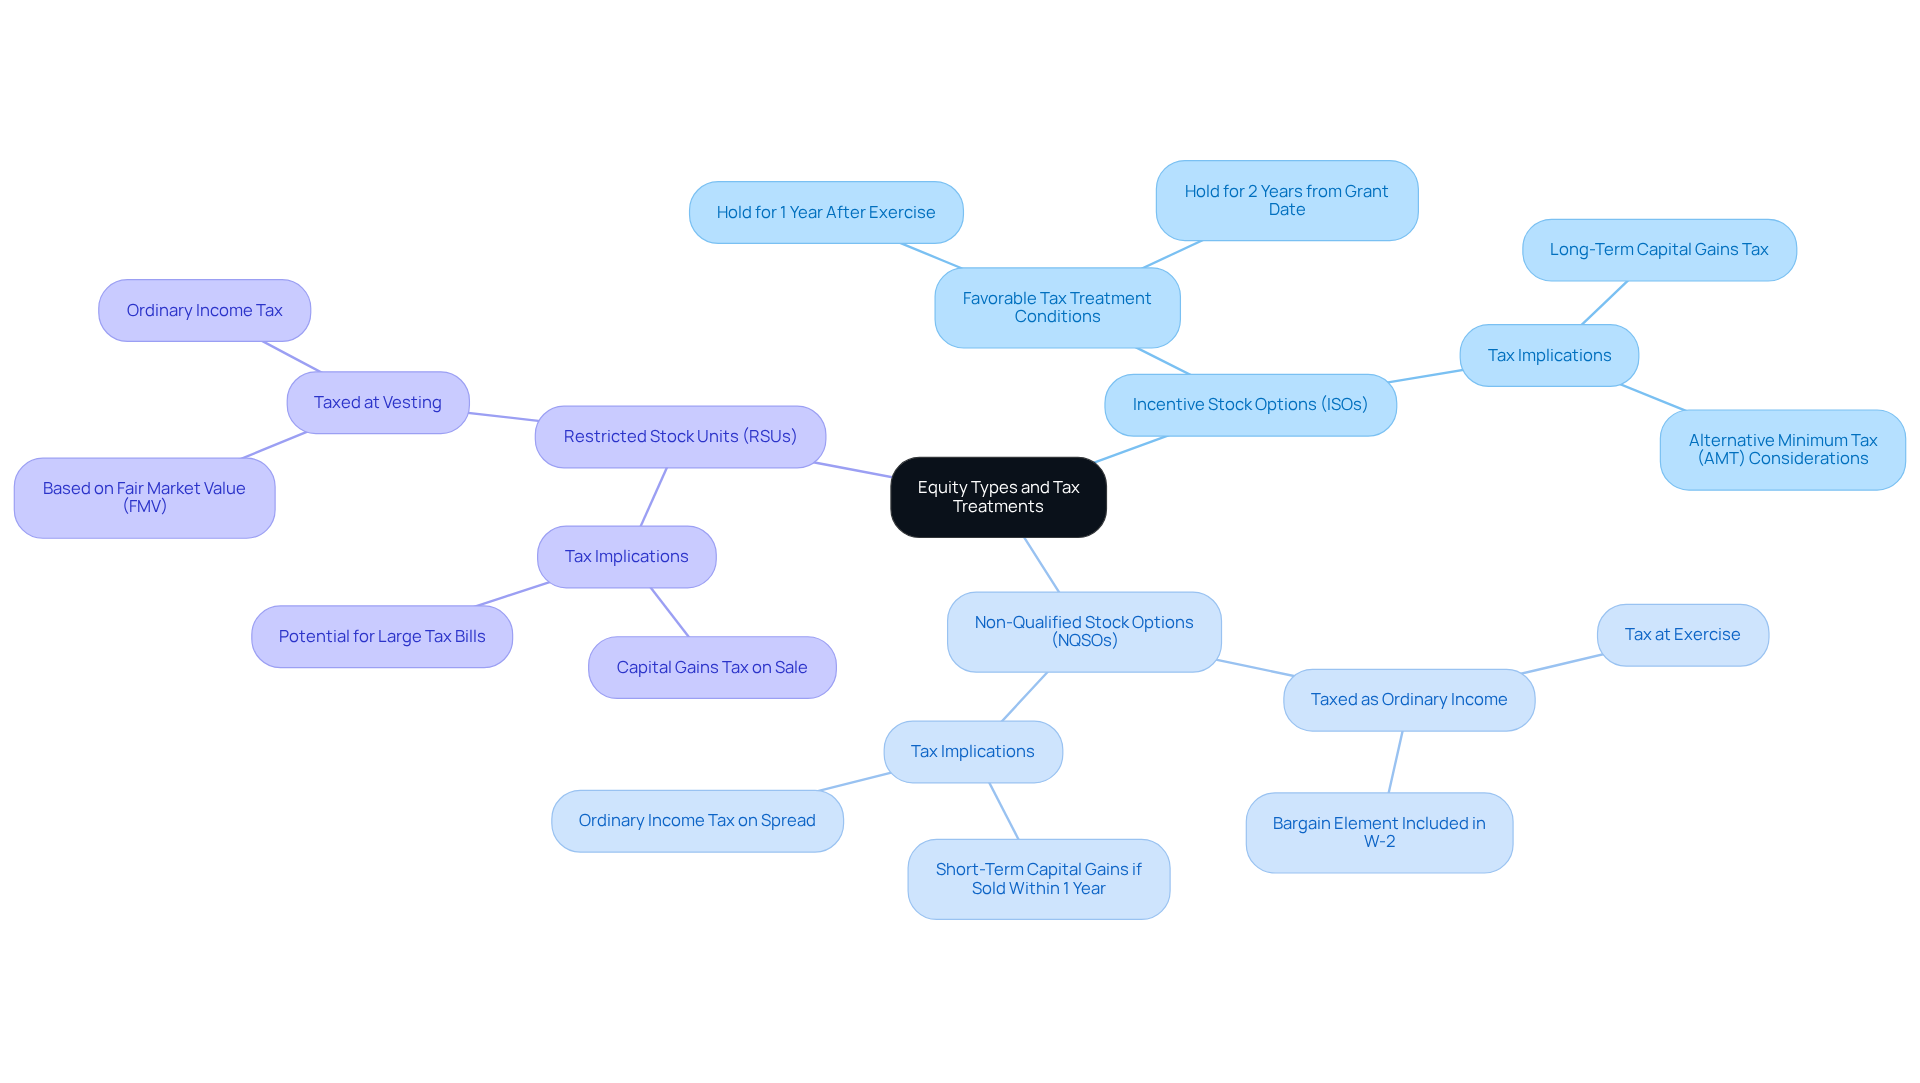
ISOs can provide favorable tax treatment if certain conditions are met. If you hold the shares for at least one year after exercising and two years from the grant date, you may qualify for long-term capital gains tax rates, which are generally lower than ordinary income tax rates. On the other hand, NQSOs are taxed as ordinary income upon exercise. This means the difference between the exercise price and the fair market value (FMV) at the time of exercise is included in your taxable income.
RSUs are taxed as ordinary income when they vest, based on the FMV of the shares at that time. This can lead to significant tax liabilities, especially if a large number of RSUs vest in a single year. Picture the worry of facing unexpected tax bills while you’re focused on your family’s future. It’s important to prepare for the income recognized at vesting to avoid surprises.
Understanding these differences is crucial for you to develop smart IPO tax planning for startup employees that meets your family’s needs. By distinguishing between these equity types, you can better align your financial strategies with your long-term goals, particularly in planning for your children’s future.
Case studies illustrate the importance of accurate reporting and tax planning. For instance, you must ensure that the cost basis reported for RSUs matches the FMV at vesting to avoid double taxation when shares are sold. Additionally, the timing of exercising stock options can have a substantial impact on tax liabilities, which underscores the importance of IPO tax planning for startup employees in managing equity compensation. Understanding these nuances can empower you to make informed decisions that protect your family’s financial well-being.
Conclusion
Navigating the world of IPO tax planning can feel daunting, especially when you’re trying to secure your family’s future. But with these opportunities come challenges that can feel overwhelming for families. Understanding how equity compensation works can help you make choices that support your family’s financial dreams.
Consider strategies like:
- Exercising stock options early
- Boosting your retirement contributions to ease your tax burden
Staying proactive during the lock-up period and knowing the tax impacts of your equity can make a big difference.
Working with trusted advisors can help you navigate these challenges and feel more prepared for what lies ahead. Remember, taking charge of your tax planning is key to reducing stress and focusing on your family’s future.
When you understand the implications of an IPO and take proactive steps, you can ease financial worries and focus on what truly matters: your loved ones. We’re here to help you make smart financial choices that protect your family’s future for generations to come.
Frequently Asked Questions
What should employees understand about the tax implications of an IPO?
Employees should be aware that the value of their equity compensation will be subject to ordinary income tax upon vesting or exercise, which is essential for effective IPO tax planning.
How are different types of equity compensation taxed during an IPO?
Non-qualified stock options (NQSOs) are taxed at the time of exercise, while restricted stock units (RSUs) are taxed as income when they vest.
What additional tax considerations should employees keep in mind after an IPO?
Employees should consider the possibility of capital gains tax if they retain their shares and sell them later, as well as the impact of the Net Investment Income Tax (NIIT) on their returns.
How does the Net Investment Income Tax (NIIT) affect capital gains?
The highest federal tax rate on long-term capital gains is 20%, but with the NIIT, the effective rate can increase to 23.8%.
Are there state tax implications for employees in California regarding IPOs?
Yes, in California, capital gains are taxed as ordinary income, which adds complexity to tax planning for employees.
What proactive strategies can employees use for IPO tax planning?
Employees can collaborate with advisors who specialize in IPO tax planning to create strategies that effectively manage their tax obligations.
How does Bright Advisers support families with IPO tax planning?
Bright Advisers emphasizes proactive tax planning strategies tailored for families and offers a clear fee structure with no hidden charges, helping families focus on their financial goals.
What is the importance of understanding tax implications for families?
Understanding these tax implications is crucial for families who want to set aside funds for their children’s education and other needs, ensuring their financial future is secure.
List of Sources
- Understand the Implications of an IPO for Employees
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)
- 2026–2027 Tech IPO Equity Tax Guide | Evolution Tax & Legal (https://evolutiontaxlegal.com/tech-ipo-wave-employee-equity-taxes)
- IPO Process: A Roadmap for Founders Going Public | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/preparing-for-an-ipo)
- What Does an IPO Mean for Stock Options? What Happens to Employees When a Company Goes Public | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/what-does-an-ipo-mean-for-employees)
- Implement Pre-IPO Tax Strategies to Minimize Liabilities
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Pre-IPO Tax Planning: Don’t Let Taxes Derail Your Life After Work – Burton Enright Welch (https://bewinvest.com/insights/pre-ipo-tax-planning-dont-let-taxes-derail-your-life-after-work)
- Pre-IPO Employee Tax Planning | Capital Tax (https://capitaltax.com/pre-ipo-tax-planning)
- IPO Planning for Employees: Tax Strategies, Risks, and What to Do Before You Sell (https://missionwealth.com/ipo-planning-for-employees)
- 2026–2027 Tech IPO Equity Tax Guide | Evolution Tax & Legal (https://evolutiontaxlegal.com/tech-ipo-wave-employee-equity-taxes)
- Navigate the Lock-Up Period: Tax Considerations and Strategies
- Selling Shares When the Lockup Ends: Managing Equity and Liquidity Post-IPO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/should-you-sell-stock-options-after-the-ipo-lockup-period)
- IPO Planning for Employees: Tax Strategies, Risks, and What to Do Before You Sell (https://missionwealth.com/ipo-planning-for-employees)
- How Long Is an IPO Lock-Up Period, and What Should You Do While You Wait? – NerdWallet (https://nerdwallet.com/investing/learn/what-to-do-during-lock-up-period)
- Differentiate Between Equity Types: Tax Treatments and Implications
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- ISOs vs. NSOs: Equity Tax Strategies | Dark Horse CPAs (https://darkhorse.cpa/blog/incentive-stock-options-vs-nonqualified-stock-options)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading