

Key Highlights
- Develop a comprehensive IPO tax strategy by assessing equity compensation structures, including stock options and RSUs.
- Understand the implications of exercising Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NQSOs) to avoid unexpected tax liabilities.
- Plan for Alternative Minimum Tax (AMT) by calculating potential liabilities and considering exercising options in lower-income years.
- Utilise Qualified Small Business Stock (QSBS) for potential capital gains tax exclusions if held for over five years.
- Set aside cash for taxes related to equity compensation to avoid financial strain when tax obligations arise.
- Consult with a tax advisor experienced in IPOs to navigate complexities and optimise tax planning.
- Review tax withholding to reflect increased income from vested RSUs and stock sales to avoid penalties.
- Diversify investments to reduce concentration risk and align with long-term financial goals.
- Maximise contributions to tax-advantaged accounts like 401(k)s and IRAs to lower taxable income.
- Consider gifting appreciated shares to reduce taxable estate and provide tax benefits.
- Engage in ongoing tax planning with professionals to adjust strategies as financial situations evolve.
Introduction
Imagine facing the excitement of an IPO while juggling family responsibilities – it’s a lot to handle, isn’t it? Getting a grip on tax planning is crucial to make the most of your equity compensation, like stock options and RSUs. As you and your family look forward to the possibilities an IPO can bring, you might wonder: how can you plan wisely to keep more of what you earn and build a secure future? In this article, we’ll explore key IPO tax planning strategies designed just for tech employees, helping your family make smart choices during this important moment.
Establish a Pre-IPO Tax Strategy
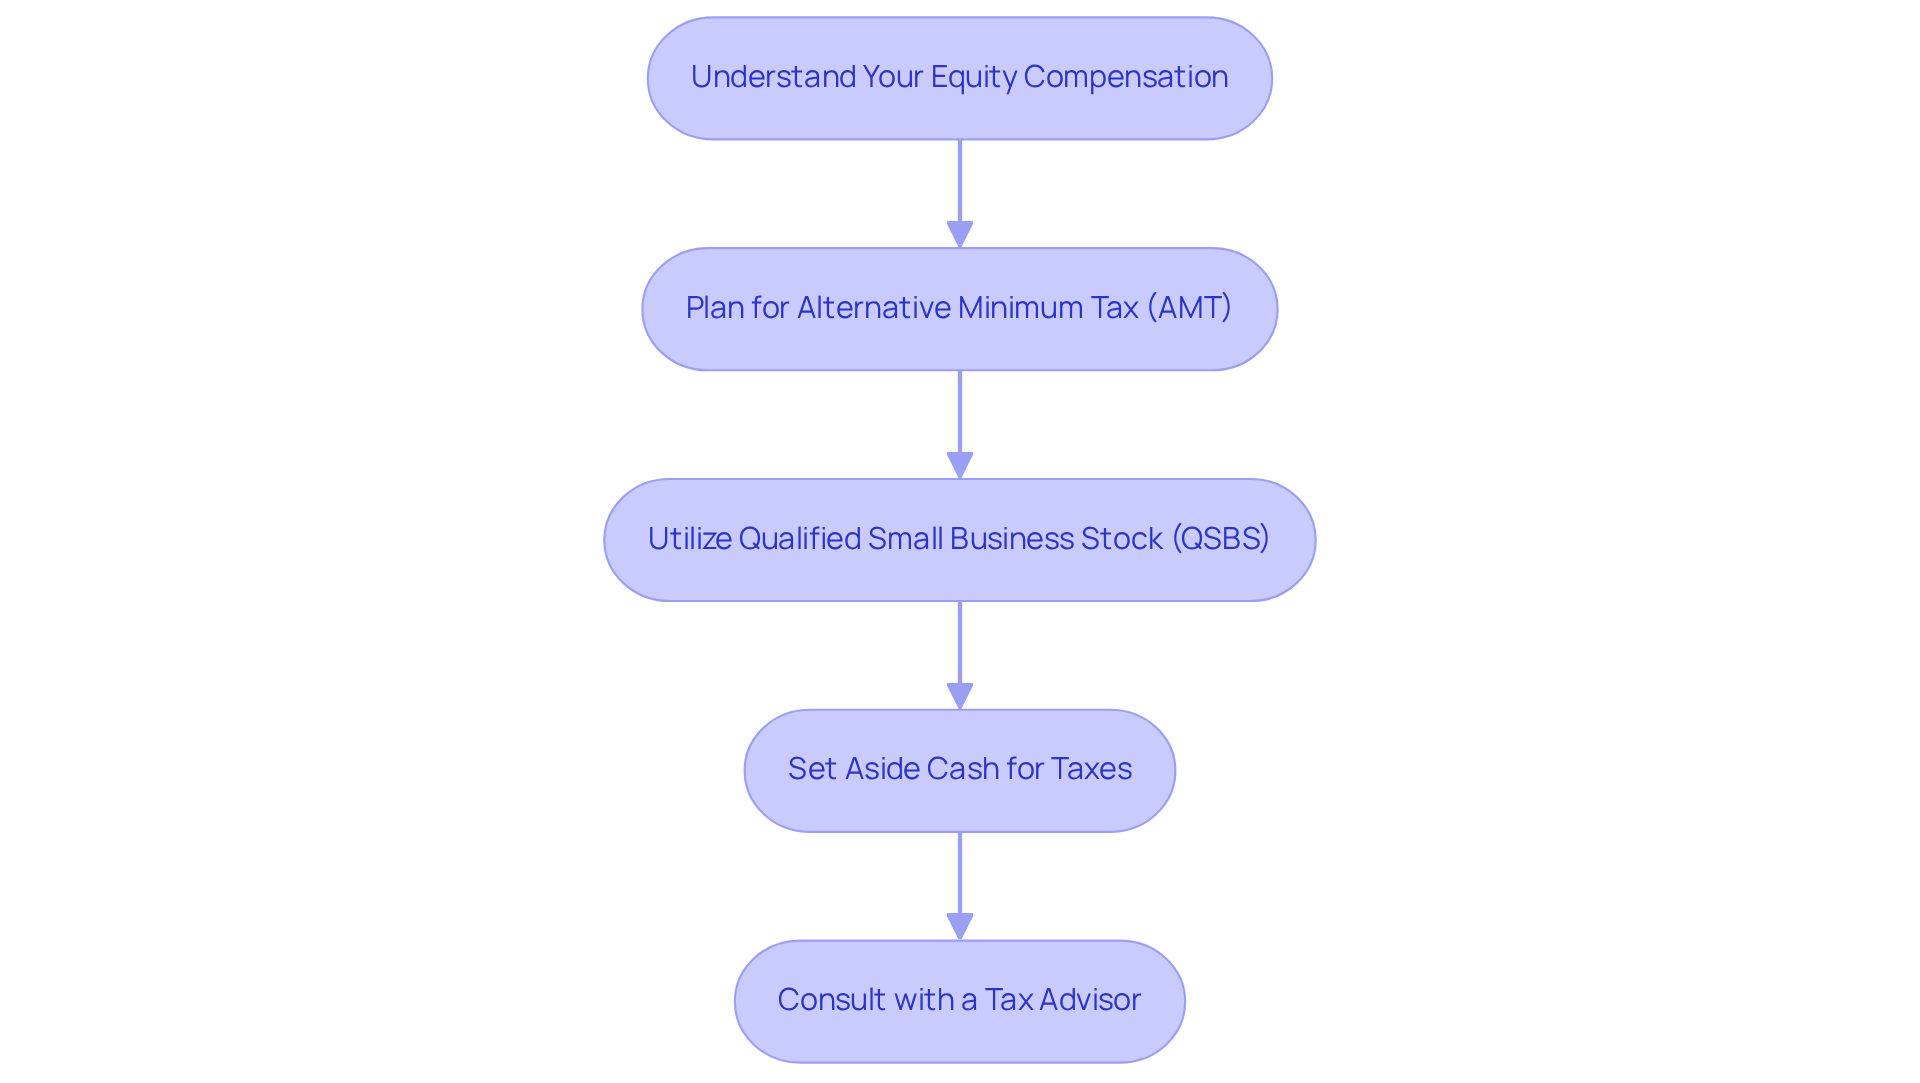
Before your company goes public, the weight of financial planning can feel overwhelming, especially when you have a family to think about. Developing a comprehensive strategy for IPO tax planning for tech employees is crucial. Start by assessing your equity compensation structure, including stock options and restricted stock units (RSUs).
-
Understand Your Equity Compensation: If you have ISOs, exercising them might lead to AMT, which can be a surprise. Familiarize yourself with the types of equity you hold, such as Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NQSOs). Each category has distinct financial implications, particularly concerning when obligations are triggered.
-
Plan for Alternative Minimum Tax (AMT): If you hold ISOs, exercising them can trigger AMT. Calculate your potential AMT liability and consider exercising options in a year when your income is lower to minimize the impact. Starting in 2026, the AMT exemption phaseout begins at $500,000 for single filers and $1,000,000 for married joint filers, making strategic planning essential.
-
Utilize Qualified Small Business Stock (QSBS): If your company qualifies, holding QSBS can provide significant tax benefits, including potential exclusion from capital gains tax if held for more than five years. The QSBS cap increases to the greater of $15 million or 10 times your adjusted basis, effective from 2027.
-
Set Aside Cash for Taxes: Anticipate the tax liabilities that will arise from your equity compensation and set aside cash to cover these expenses. This proactive approach can prevent monetary strain when taxes are due, especially since the difference between the exercise price and the stock’s fair market value is treated as ordinary income.
-
Consult with a Tax Advisor: It’s a good idea to talk to a tax professional who understands IPOs and can help you find the best path for your family. Consulting with knowledgeable advisors can assist in navigating the complexities of equity compensation and enhancing your approaches to IPO tax planning for tech employees.
Alongside these measures, consider incorporating comprehensive management strategies offered by Bright Advisers, such as budgeting, asset and liability tracking, cash flow projections, and education funding. These services can assist you in navigating the complexities of tax planning while ensuring your family’s economic future is secure. Remember, past performance does not guarantee future results, and all investments carry risks. By taking these steps, you can ensure that your family’s future remains bright, even amidst the complexities of financial planning.
Understand Equity Compensation and Tax Implications
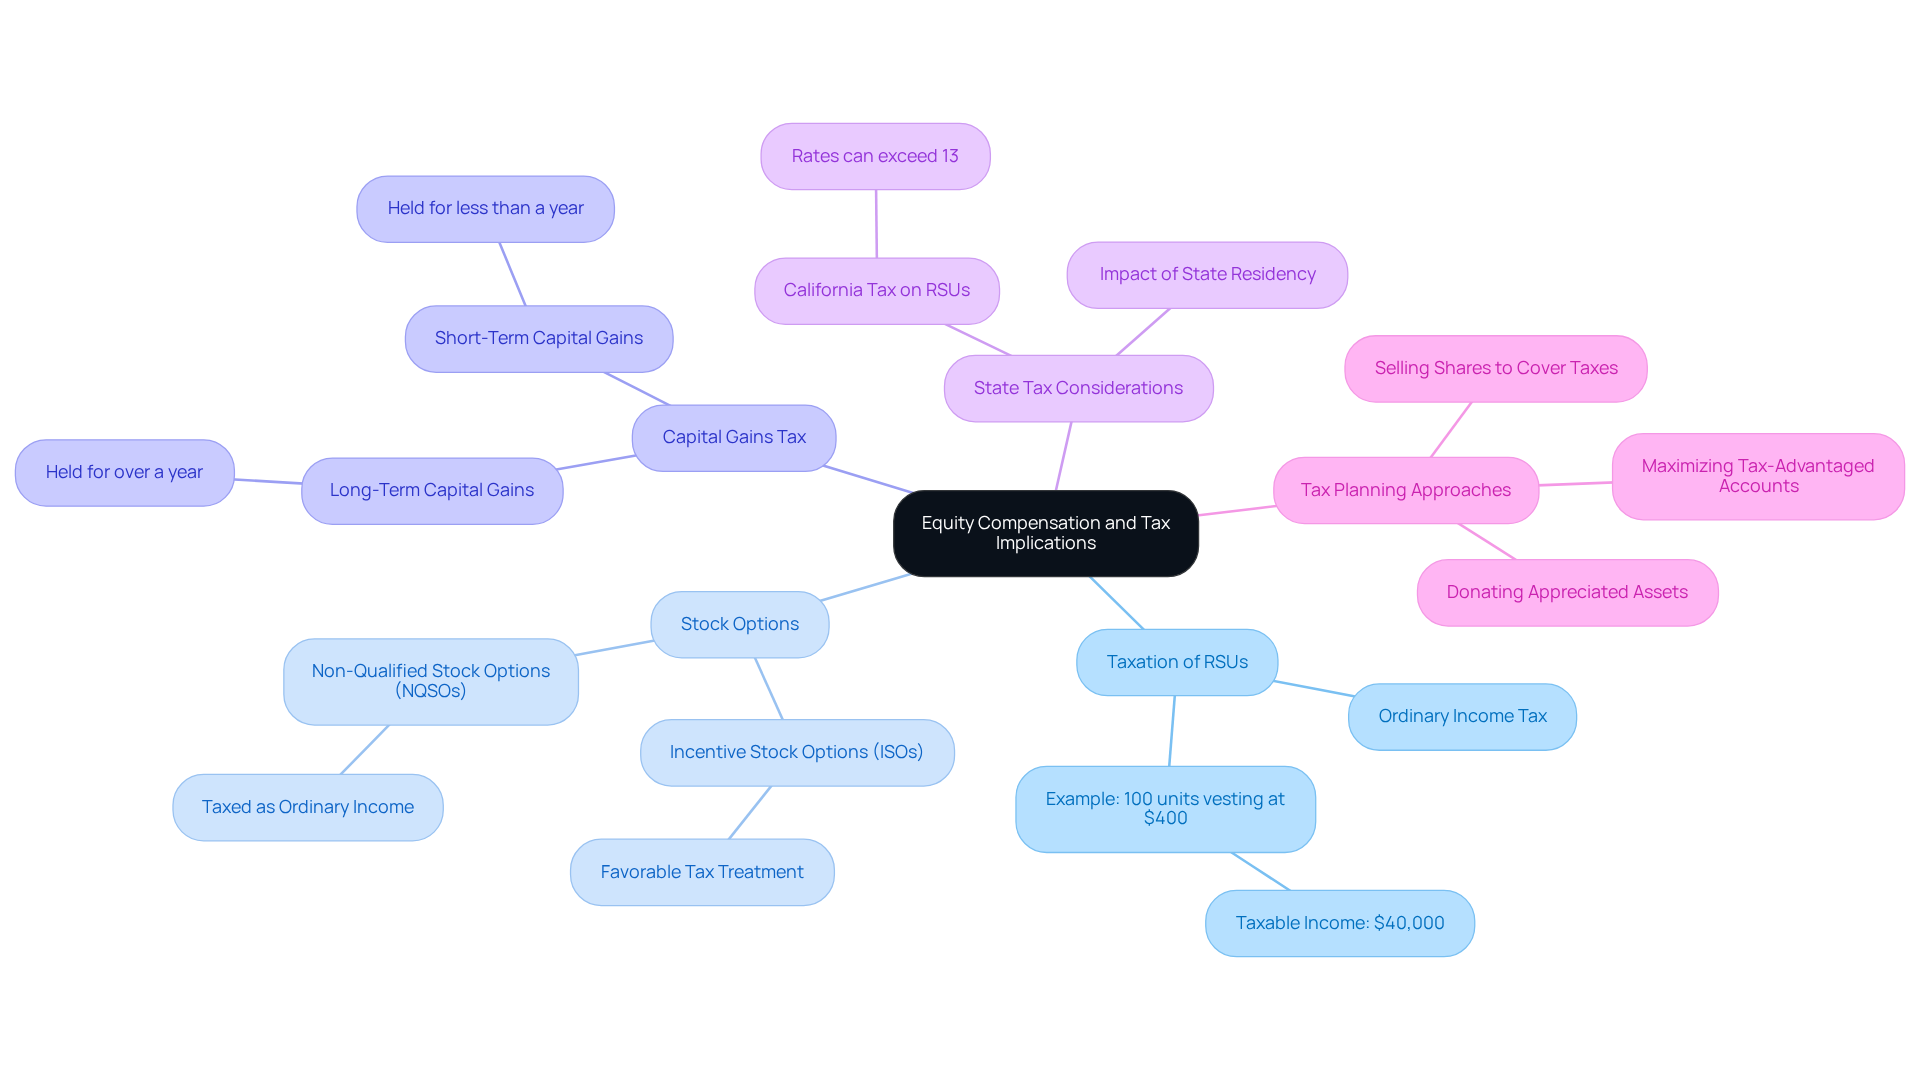
Imagine facing a tax bill that could change your family’s financial future – this is the reality for many when it comes to IPO tax planning for tech employees and dealing with equity compensation. Here are some key points to consider:
-
Taxation of RSUs: When Restricted Stock Units (RSUs) vest, they’re taxed as ordinary income. This means the fair market value at vesting gets added to your taxable income, which might push you into a higher tax bracket. For example, if 100 units vest at a stock price of $400, that’s $40,000 of taxable income.
-
Stock Options: It’s important to understand the difference between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NQSOs). ISOs can qualify for favorable tax treatment if certain conditions are met, while NQSOs are taxed as ordinary income when exercised.
-
Capital Gains Tax: If you hold stocks for over a year after they vest, any profits from selling those stocks may be subject to long-term capital gains tax, which is usually lower than ordinary income tax rates. This can lead to significant tax savings if the assets appreciate in value.
-
State Tax Considerations: Be mindful of how your state taxes equity compensation. For instance, California residents must pay state tax on all RSU income, regardless of where they work, with rates that can exceed 13%. This can greatly impact your overall tax liability.
-
Tax Planning Approaches: Consider strategies like selling a portion of your holdings to cover tax obligations or donating appreciated assets to charity to offset taxable income. These methods can help you manage your tax exposure effectively and align your financial goals with your equity compensation.
We’re here to help you navigate these complexities and find the best path for your family’s financial future. By understanding these tax implications, particularly through IPO tax planning for tech employees, you can take control of your financial journey and secure a brighter future for your family.
Plan for the Lock-Up Period and Its Financial Impact
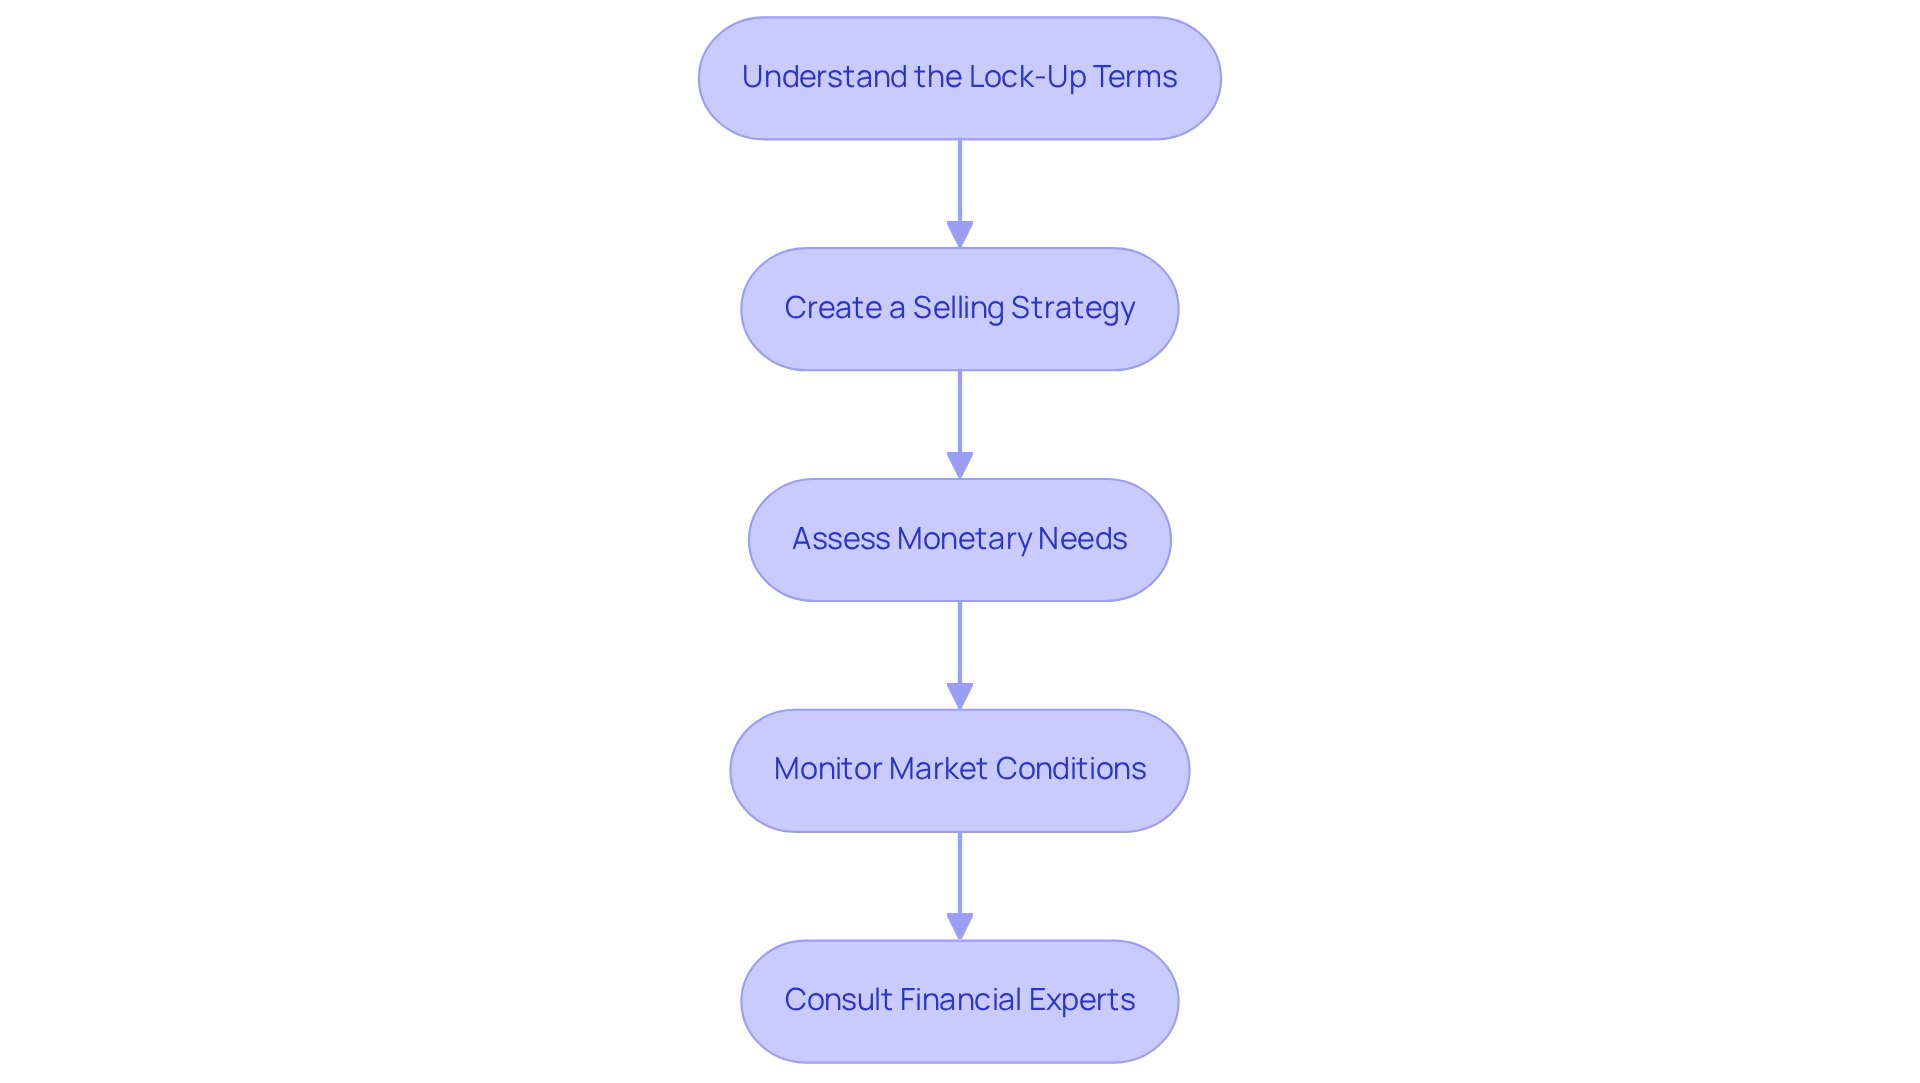
Navigating the lock-up period after an IPO can be a daunting task for many families. Here’s how to approach this critical time effectively:
-
Understand the Lock-Up Terms: Familiarize yourself with your company’s specific lock-up agreement. Knowing when you can sell your assets is crucial for planning your liquidity needs.
-
Create a Selling Strategy: Develop a clear plan for how and when to liquidate your holdings once the lock-up period ends. Consider staggering your sales to manage tax implications and avoid flooding the market, which could lower stock prices. A staggered approach to selling your shares can give you more flexibility and help with your financial planning.
-
Assess Monetary Needs: Take a moment to evaluate your immediate financial obligations, like tax payments or other expenses, and plan your share sales accordingly. This way, you can ensure you have the liquidity to cover these costs without relying solely on your salary.
-
Monitor Market Conditions: Keep an eye on market trends and your company’s stock performance. Timing your sales based on market conditions can help you maximize your returns and reduce risks associated with volatility.
-
Don’t hesitate to reach out to financial experts who can help you align your selling strategy with your family’s goals. This ensures that your decisions support your family’s long-term wealth management objectives.
Case Studies: For instance, Allison and Brian, a couple with significant incomes, initially faced challenges with tax planning and wealth management. Through their collaboration with Bright Advisers, they not only optimized their tax situation but also secured their children’s future through education funding and gained the ability to retire sooner. Similarly, Jay and Emma successfully navigated funding their children’s education while planning for retirement, achieving a balance between their present responsibilities and long-term aspirations. These examples highlight the importance of a well-organized financial plan during crucial times, such as IPO tax planning for tech employees.
By understanding the complexities of the lock-up period and applying these strategies, families can more effectively navigate the economic landscape after an IPO. Remember, understanding these strategies can empower your family to make informed financial decisions during this pivotal time.
Implement Post-IPO Tax Management Strategies
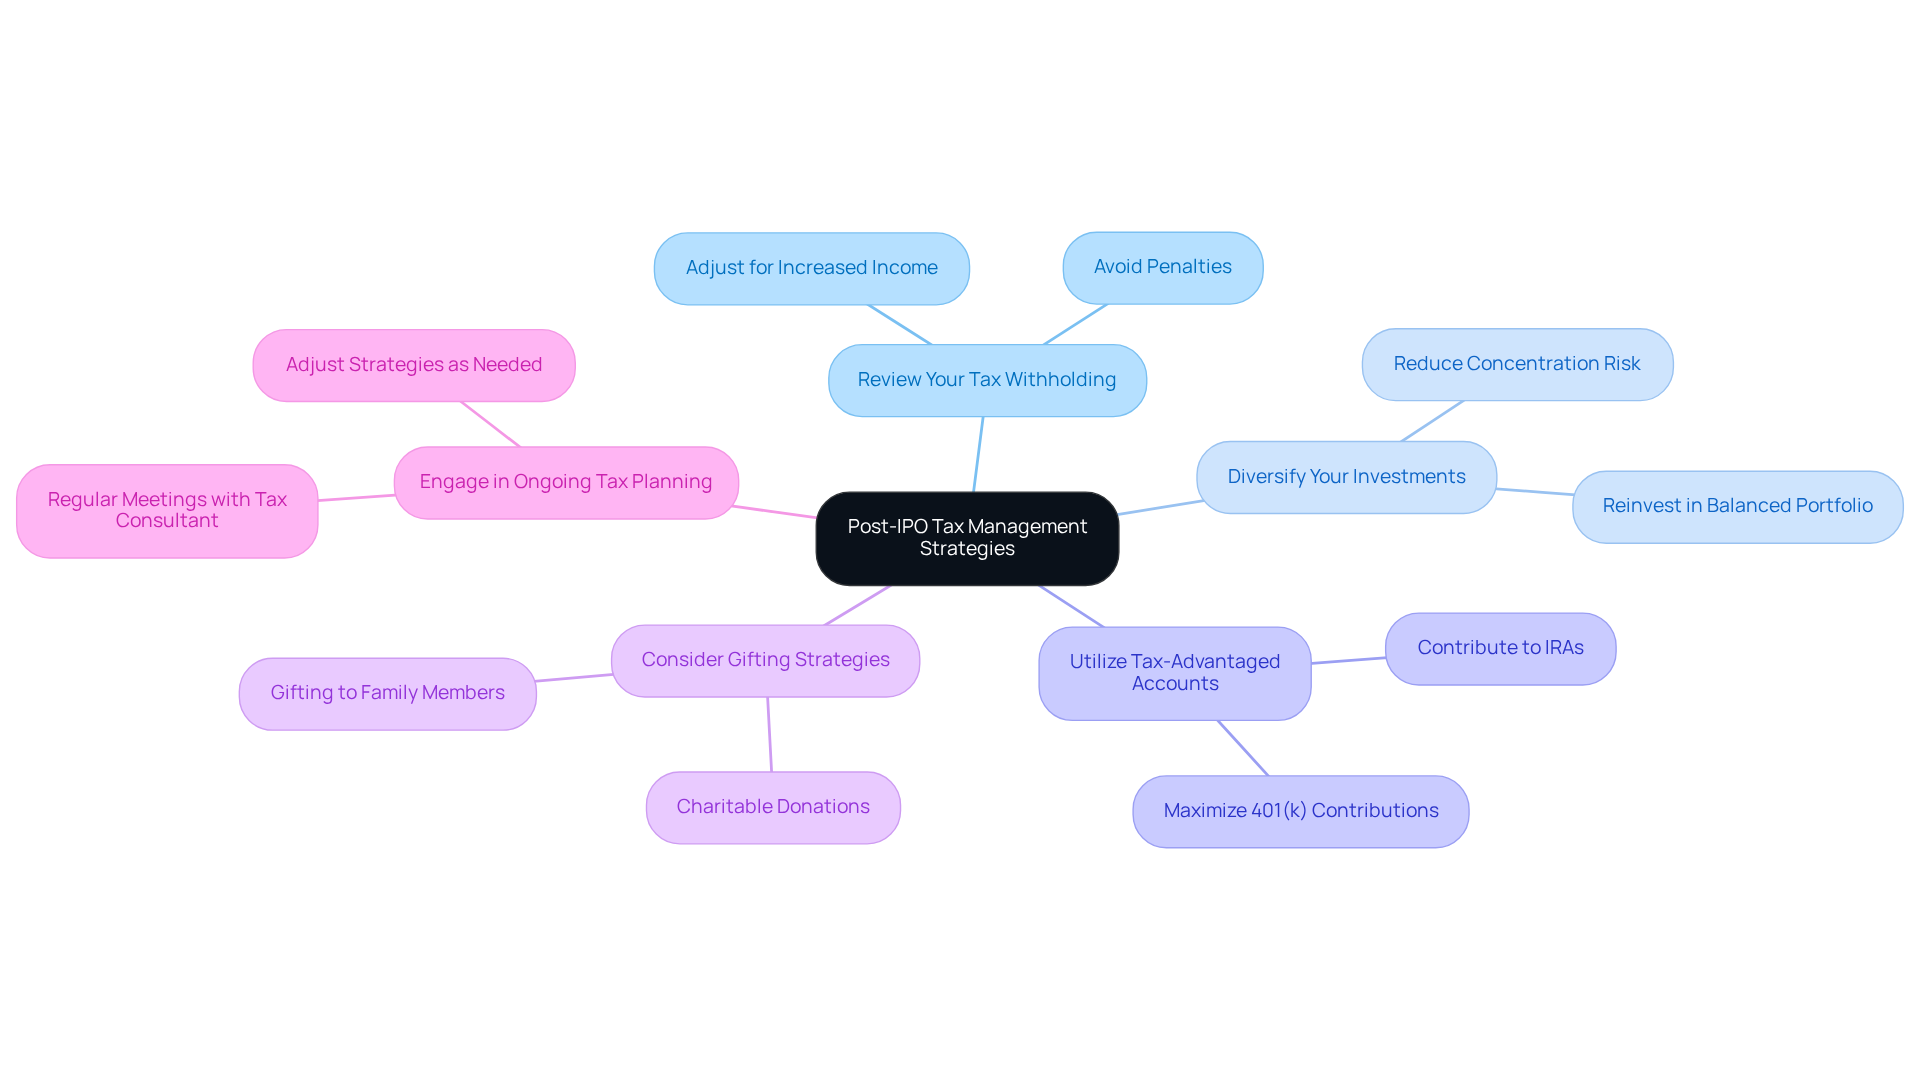
Imagine the relief of confidently managing your tax situation with IPO tax planning for tech employees after your company goes public, ensuring your family’s financial future is secure. Here are some key strategies to consider:
-
Review Your Tax Withholding: Adjust your tax withholding to reflect the increased income from vested RSUs and stock sales. This way, you can avoid penalties and make sure enough is withheld to cover your taxes.
-
Diversify Your Investments: To reduce concentration risk, think about diversifying your investment portfolio. Selling a portion of your shares can allow you to reinvest in a more balanced portfolio that aligns with your long-term financial goals. At Bright Advisers, we’re here to help families build strong, balanced portfolios that stand the test of time.
-
Utilize Tax-Advantaged Accounts: Maximize contributions to tax-advantaged accounts like 401(k)s and IRAs. This approach can help lower your taxable income while preparing for retirement. Participating in ongoing tax planning with Bright Advisers can further enhance your tax strategies, ensuring you’re ready for future financial needs.
-
Consider Gifting Strategies: If you have significant gains, gifting appreciated shares to family members or charities can reduce your taxable estate and provide tax benefits. This can be especially helpful for high-income families.
-
Engage in Ongoing Tax Planning: Regular meetings with a tax consultant are essential to assess your financial situation and adjust your tax strategies as needed. If you don’t take action, you might face unexpected tax burdens that could put a strain on your family’s finances. Bright Advisers is committed to helping families navigate these complexities with transparent, all-inclusive fee structures and no hidden costs.
By taking these steps, you can safeguard your family’s financial well-being and embrace the future with confidence. For families interested in personalized financial planning, Bright Advisers offers comprehensive wealth management solutions tailored to your unique needs. All advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
It can feel overwhelming to think about how an IPO might affect your family’s financial future. Planning ahead for your family’s financial future before your company goes public can make a big difference. Understanding your equity compensation and working with trusted advisors can help your family feel more prepared for what lies ahead.
Key strategies to consider include:
- Assessing your equity compensation structure
- Planning for alternative minimum tax (AMT)
- Exploring Qualified Small Business Stock (QSBS) for potential tax benefits
- Grasping the tax implications of stock options and Restricted Stock Units (RSUs)
- Developing a clear plan for the lock-up period
- Implementing post-IPO tax management strategies
With the right guidance, you can turn these challenges into opportunities for your family’s financial growth.
Taking these steps can empower your family to navigate the IPO journey with confidence and clarity. Engaging with Bright Advisers can provide the necessary support and expertise to ensure a well-structured financial plan, allowing your family to thrive even amidst the challenges of an IPO. For those ready to take control of their financial future, exploring personalized wealth management solutions is a vital next step.
Frequently Asked Questions
Why is it important to establish a pre-IPO tax strategy?
Establishing a pre-IPO tax strategy is crucial for tech employees to manage the financial implications of equity compensation and ensure their family’s economic future is secure.
What should I assess when developing a pre-IPO tax strategy?
You should assess your equity compensation structure, including stock options and restricted stock units (RSUs), to understand their financial implications.
What are the different types of equity compensation I should be aware of?
The main types of equity compensation include Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NQSOs), each with distinct financial implications.
How can exercising ISOs affect my taxes?
Exercising ISOs can trigger the Alternative Minimum Tax (AMT), which may lead to unexpected tax liabilities. It’s important to calculate your potential AMT liability and consider exercising options in a year with lower income to minimize the impact.
What is the AMT exemption phaseout, and when does it begin?
The AMT exemption phaseout begins in 2026, starting at $500,000 for single filers and $1,000,000 for married joint filers, making strategic planning essential.
What are the benefits of holding Qualified Small Business Stock (QSBS)?
Holding QSBS can provide significant tax benefits, including potential exclusion from capital gains tax if held for more than five years. The QSBS cap increases to the greater of $15 million or 10 times your adjusted basis, effective from 2027.
How should I prepare for tax liabilities from equity compensation?
You should anticipate tax liabilities arising from your equity compensation and set aside cash to cover these expenses, preventing monetary strain when taxes are due.
Why is it advisable to consult with a tax advisor regarding IPO tax planning?
Consulting with a tax professional who understands IPOs can help you navigate the complexities of equity compensation and find the best tax strategies for your family.
What additional management strategies can assist with tax planning?
Comprehensive management strategies offered by Bright Advisers, such as budgeting, asset and liability tracking, cash flow projections, and education funding, can help navigate tax planning complexities.
What important disclaimers should I keep in mind regarding investments and tax strategies?
Remember that past performance does not guarantee future results, and all investments carry risks.
List of Sources
- Establish a Pre-IPO Tax Strategy
- Equity Tax Planning: What to Know | Citrine Capital (https://citrinecapitaladvisors.com/blog/equity-tax-planning)
- 5 Steps to Solve Your IPO Tax Issues: IPO and Taxes (https://kbfinancialadvisors.com/5-steps-to-solve-your-ipo-tax-issues)
- How to Prepare for an IPO: Financial & Tax Planning Guide — Brooklyn Fi (https://brooklynfi.com/blog/how-to-prepare-for-an-ipo-2026)
- IPO Tax Planning for Employees Before Going Public | BPM (https://bpm.com/insights/ipo-tax-planning-for-employees)
- 4 Tax Management Strategies To Consider for Your Equity Compensation | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/equity-comp-optimize-taxes)
- Understand Equity Compensation and Tax Implications
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSUs at Big Tech: How They Work, When You’re Taxed, and What to Do When They Vest (https://raymondjames.com/invictuswealthadvisory/invictus-insights/2026/05/26/rsus-at-big-tech-how-they-work-when-youre-taxed-and-what-to-do-when-they-vest)
- RSU Tax Planning for Tech Executives: How to Avoid Costly Surprises – Hapanowicz (https://hapfinancial.com/blog/rsu-tax-planning-tech-executives)
- RSU Tax Strategies: A Complete Guide for Tech Employees (https://helmterminal.dev/blog/rsu-tax-strategies)
- Tax Impacts of Equity Compensation (https://wsadvisors.com/tax-impacts-of-equity-compensation)
- Plan for the Lock-Up Period and Its Financial Impact
- IPO Basics: What to Know Before Investing (https://schwab.com/learn/story/ipo-basics-what-to-know-before-investing)
- SpaceX’s Staggered Lockup Means Six Selling Decisions, Not One: How Employees Should Think About Each Window (https://savantwealth.com/savant-views-news/article/spacexs-staggered-lockup-means-six-selling-decisions-not-one-how-employees-should-think-about-each-window)
- Early Lock-Up Releases: Overview and Trends (https://capx.cooley.com/2025/01/20/early-lock-up-releases-overview-and-trends)
- SEC.gov | Initial Public Offerings (IPOs) (https://sec.gov/data-research/statistics-data-visualizations/initial-public-offerings-ipos)
- July 2026 Economic and Market Update: The Mega-IPO Era Arrives – Crestwood Advisors (https://crestwoodadvisors.com/july-2026-economic-and-market-update-the-mega-ipo-era-arrives)
- Implement Post-IPO Tax Management Strategies
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- RSU Vesting at IPO (https://kbfinancialadvisors.com/rsu-vesting-at-ipo-tax-withholding)
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)
- CPA for Tech Employees | RSU & Stock Option Tax Planning | Taxstra (https://taxstra.com/services/cpa-for-tech-employees)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading