

Key Highlights
- IPO tax planning is crucial for families to understand the financial impact of a company’s public offering.
- Stock options and RSUs may be taxed as ordinary income upon vesting, potentially increasing tax brackets.
- The Kiddie Tax affects how children’s unearned income is taxed, adding complexity to family finances.
- Families should develop a comprehensive financial strategy pre-IPO, assessing stock options and RSUs.
- Tax-loss harvesting can offset gains, and families should set aside funds for potential tax liabilities.
- Understanding equity compensation types, like stock options and RSUs, is essential for informed financial decisions.
- Long-term capital gains tax rates can be beneficial if shares are held for over a year.
- Ongoing tax planning after an IPO is necessary to navigate new financial responsibilities and optimise tax situations.
- Exercising Incentive Stock Options (ISOs) may trigger Alternative Minimum Tax (AMT), affecting cash liquidity.
- Charitable giving strategies, such as donating appreciated securities, can provide tax benefits.
Introduction
Imagine the excitement of an IPO, but also the worries that come with it for families like yours. As companies go public, it’s easy to feel overwhelmed by how this affects your family’s finances and taxes. That’s why having a solid IPO tax plan is so important.
Let’s explore some key strategies that can help your family navigate the tax implications of an IPO, so you can feel secure about your financial future. Together, we can turn the challenges of an IPO into opportunities for lasting wealth while keeping your children’s future safe.
Understand IPO Tax Implications for Families
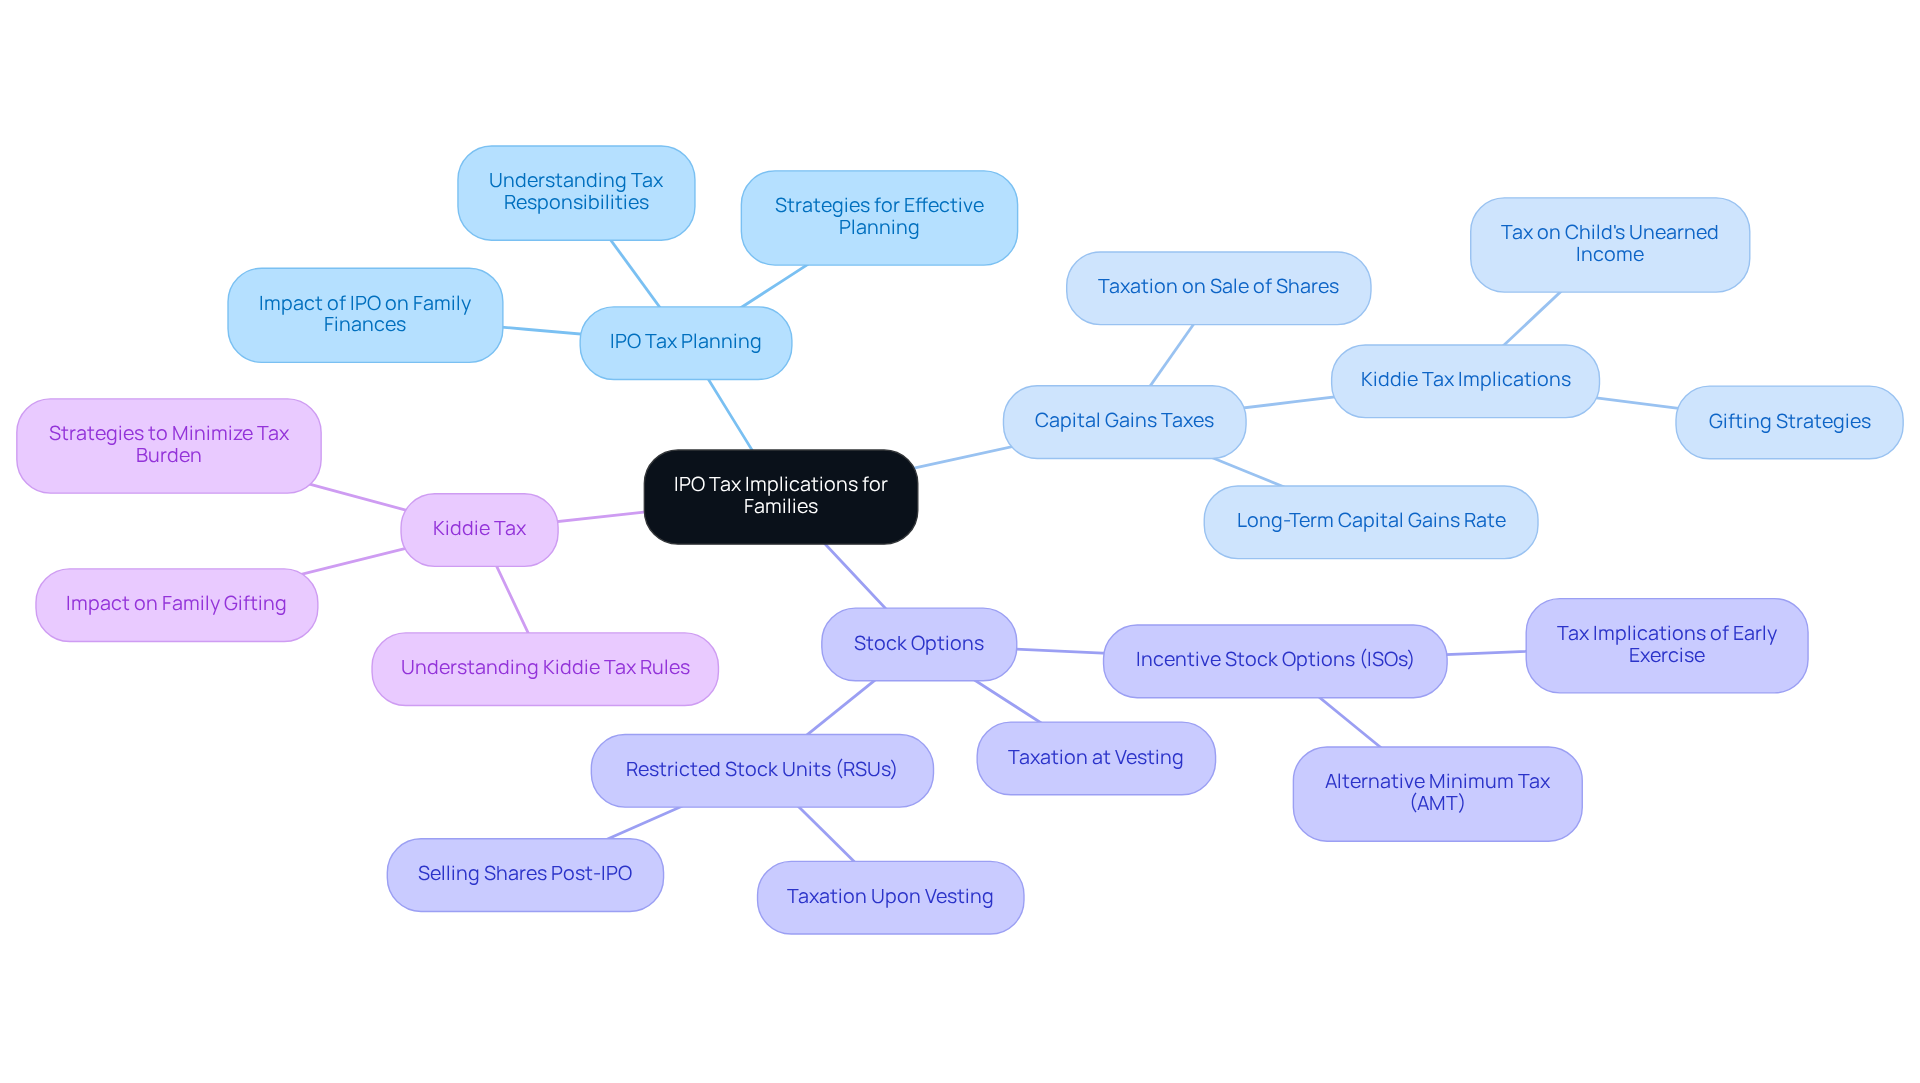
Imagine the excitement of a company going public, but also the importance of IPO tax planning to understand how it impacts your family’s finances. It’s important to recognize how IPO tax planning, along with capital gains taxes, stock options, and estate taxes, can influence your family’s financial journey.
For example, if you receive stock options or RSUs as part of your job, they might be taxed like regular income when they vest, which could push your family into a higher tax bracket. Understanding the Kiddie Tax is also important, as it affects how your child’s unearned income is taxed, adding another layer to your family’s financial picture.
By grasping these concepts, you can prepare your family for the responsibilities that come with an IPO, including important considerations for IPO tax planning to nurture your children’s future. Together, we can navigate these complexities and ensure a brighter financial path for your family.
Develop a Comprehensive Financial Strategy Pre-IPO
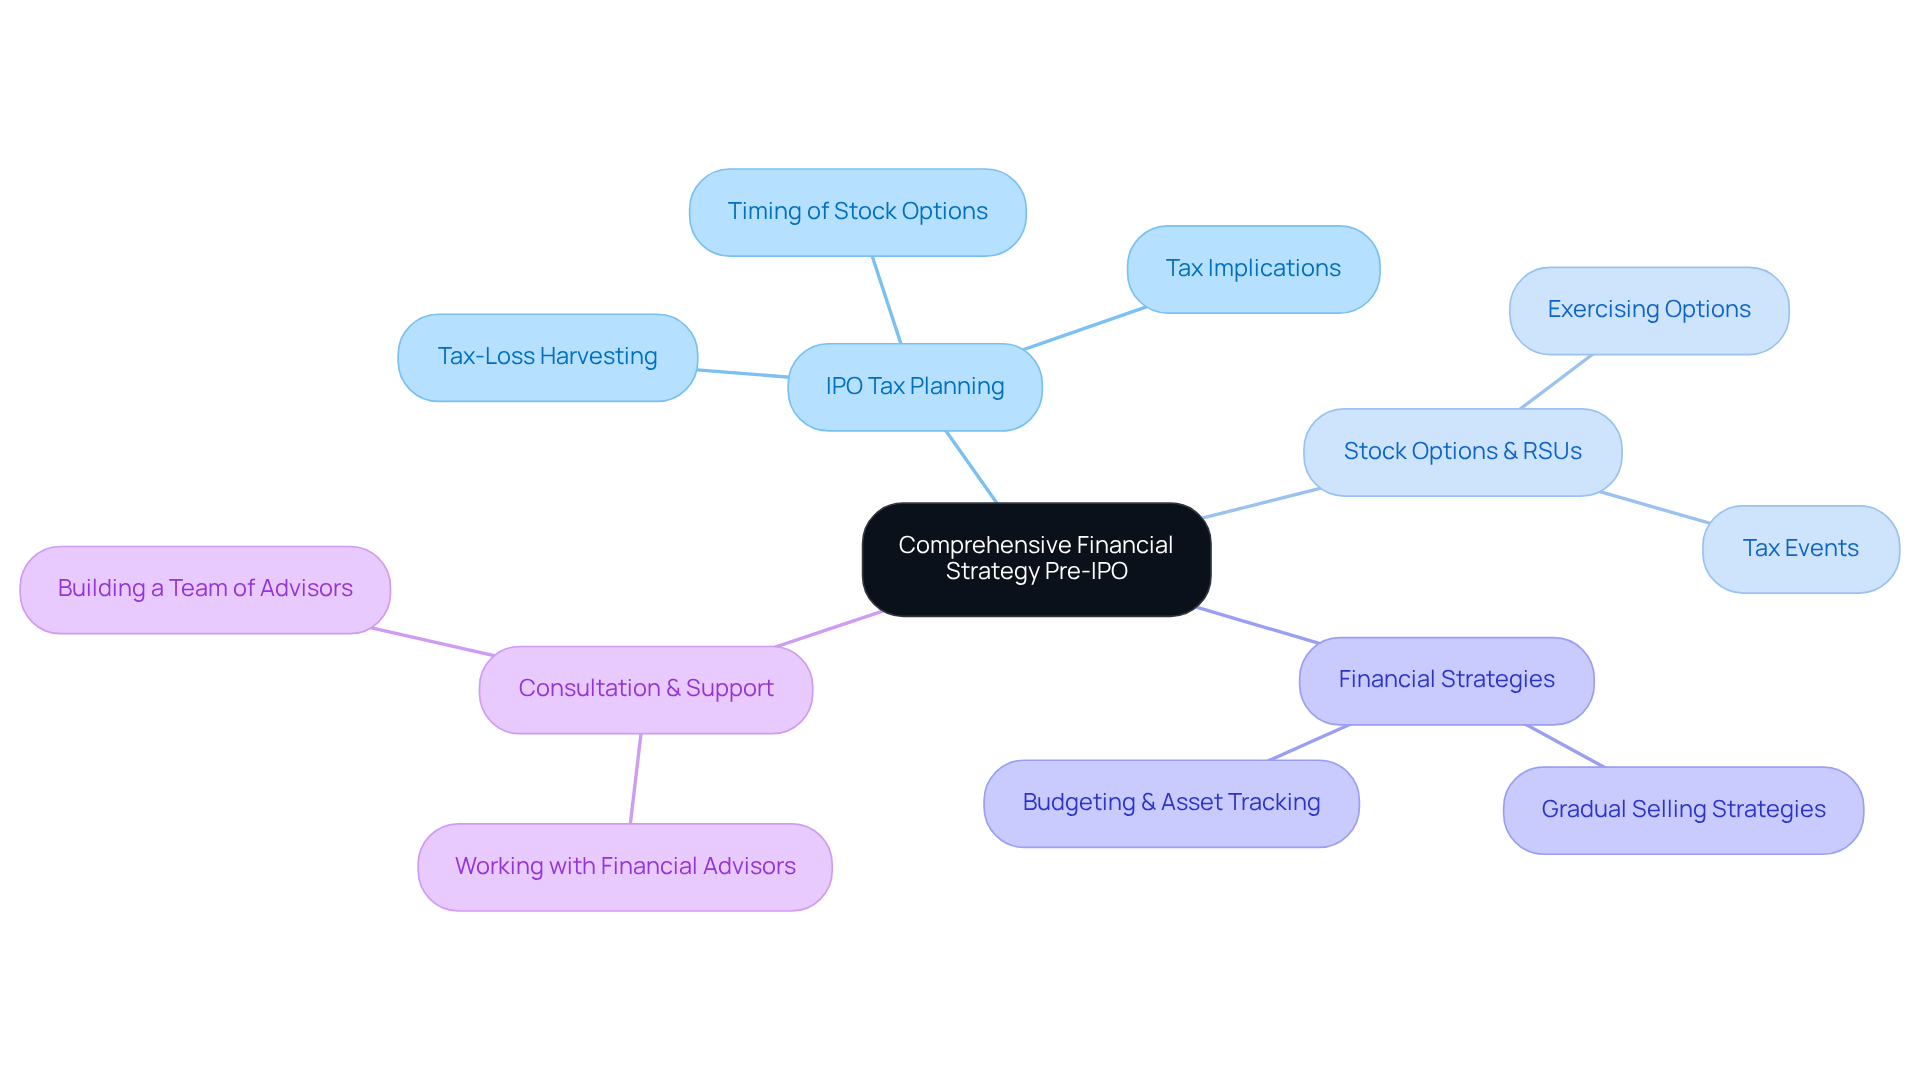
Imagine facing the complexities of an IPO while trying to secure your family’s financial future. Before an IPO, it’s essential for households to focus on IPO tax planning by creating a thorough monetary strategy that assesses their current economic condition. This means looking at how much your stock options and Restricted Stock Units (RSUs) might be worth, figuring out the best time to exercise them, and understanding the implications of IPO tax planning when selling shares after the IPO.
For instance, RSUs are typically taxed as ordinary income when they vest, often coinciding with the IPO, which can create significant tax events. Many families feel overwhelmed by the financial intricacies of an IPO, unsure of how to navigate the potential tax implications and the role of IPO tax planning in the timing of stock options. Families should also explore IPO tax planning strategies, including tax-loss harvesting, to offset gains and consider setting aside funds to cover potential tax liabilities.
By taking proactive steps, families can transform uncertainty into confidence, ensuring a brighter financial future for their children. Working with a consultant who understands IPO tax planning can provide you with tailored advice that feels just right for your family’s needs. By integrating budgeting and asset tracking into your strategy, you can further enhance your planning efforts.
Case studies illustrate the importance of strategic timing for exercising stock options and the benefits of gradual selling strategies post-IPO, such as dollar-cost averaging, which helps manage taxes and reduce financial risk. With thoughtful planning, you can turn the challenges of an IPO into opportunities for lasting wealth for your family.
Navigate Equity Compensation Types and Their Tax Effects
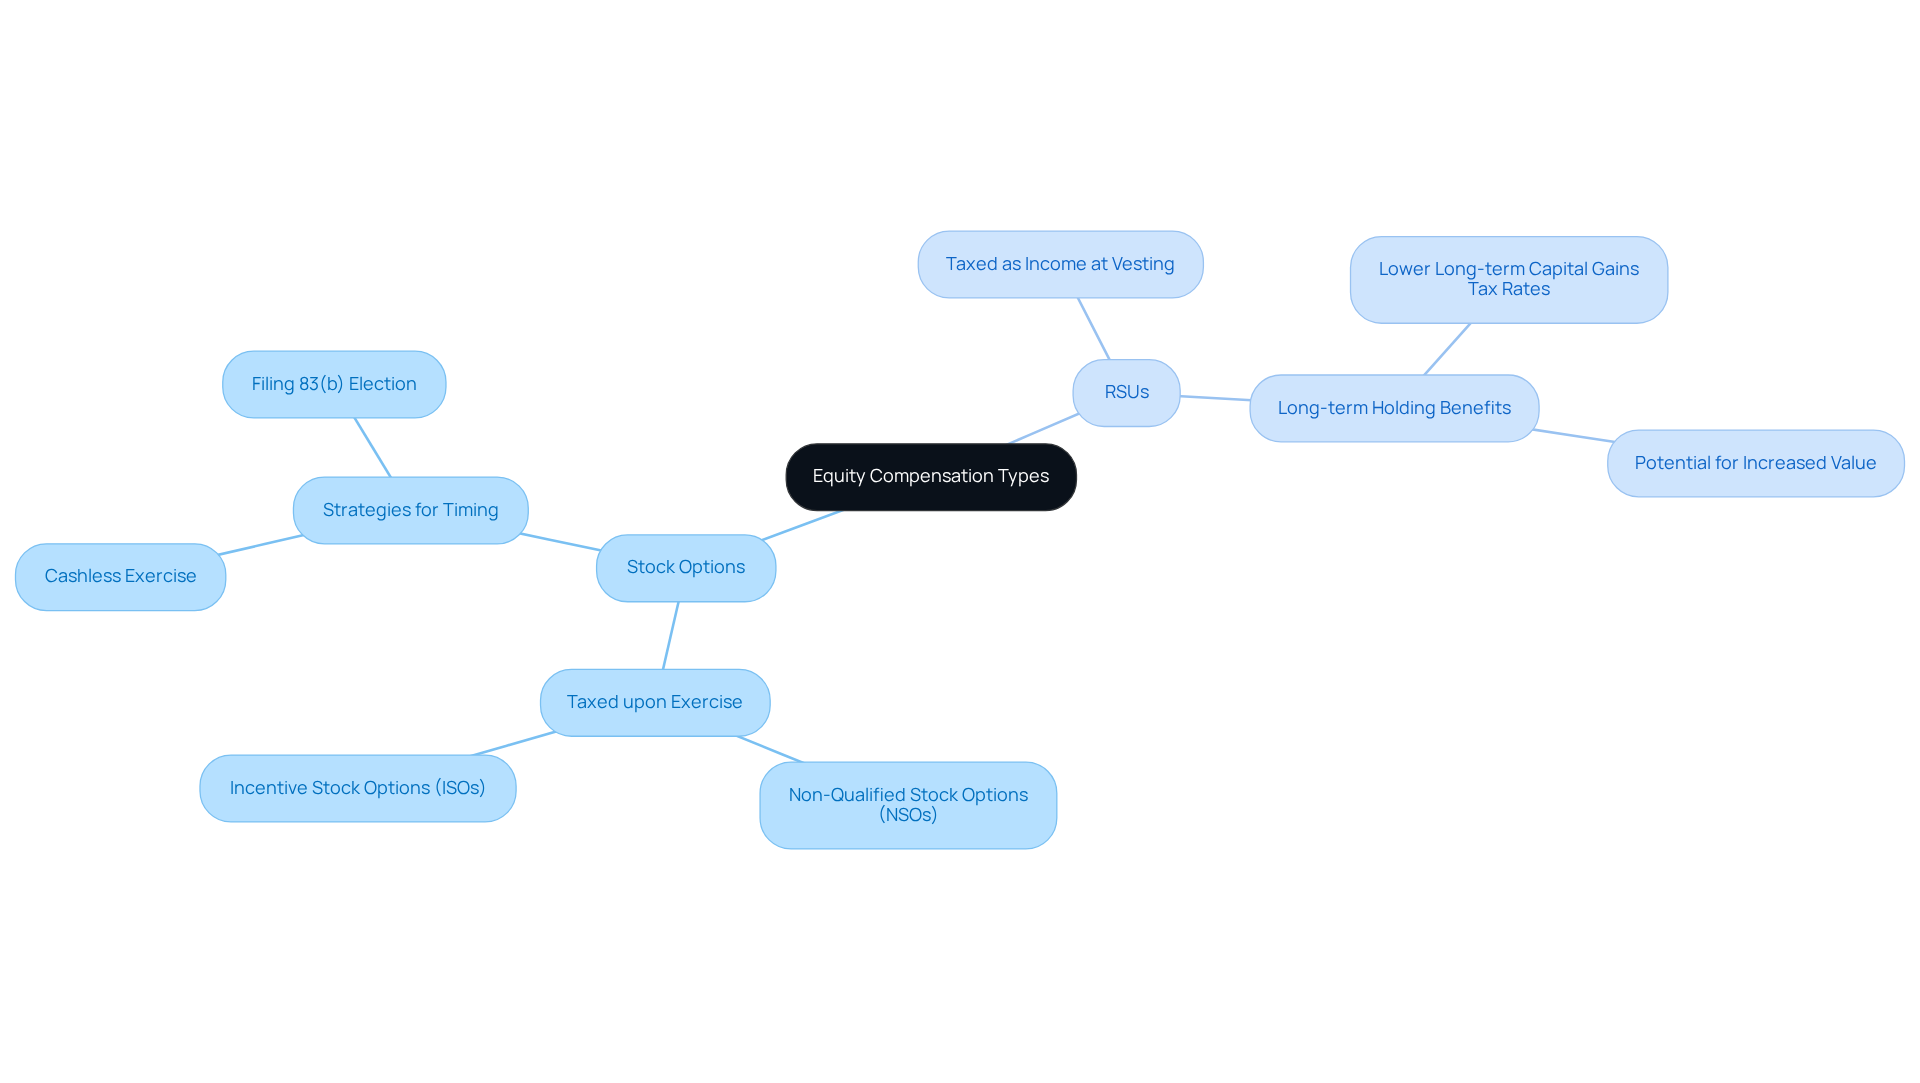
Imagine feeling overwhelmed by the different types of equity compensation your job offers, like stock options and RSUs, each with its own tax implications that can be confusing. For instance, stock options can be taxed when you exercise them, while RSUs are taxed as regular income when they vest, which can be tricky to navigate. It’s important to understand these differences so you can make the best choices for your family’s financial future.
Many families, like Allison and Brian, may not realize the financial opportunities they could be missing out on because of tax planning challenges. They worry about their family’s financial well-being and are eager to improve their situation. Working with Bright Advisers, they discovered how the timing of exercising options or selling shares can make a big difference in their tax situation.
Plus, families can take advantage of strategies like holding onto shares for over a year to benefit from lower long-term capital gains tax rates. With the right understanding and expert guidance, families can make informed choices that align with their financial goals, ensuring they don’t miss out on valuable opportunities. Together, we can navigate this journey and secure a brighter financial future for your family.
Implement Ongoing Tax Planning After the IPO
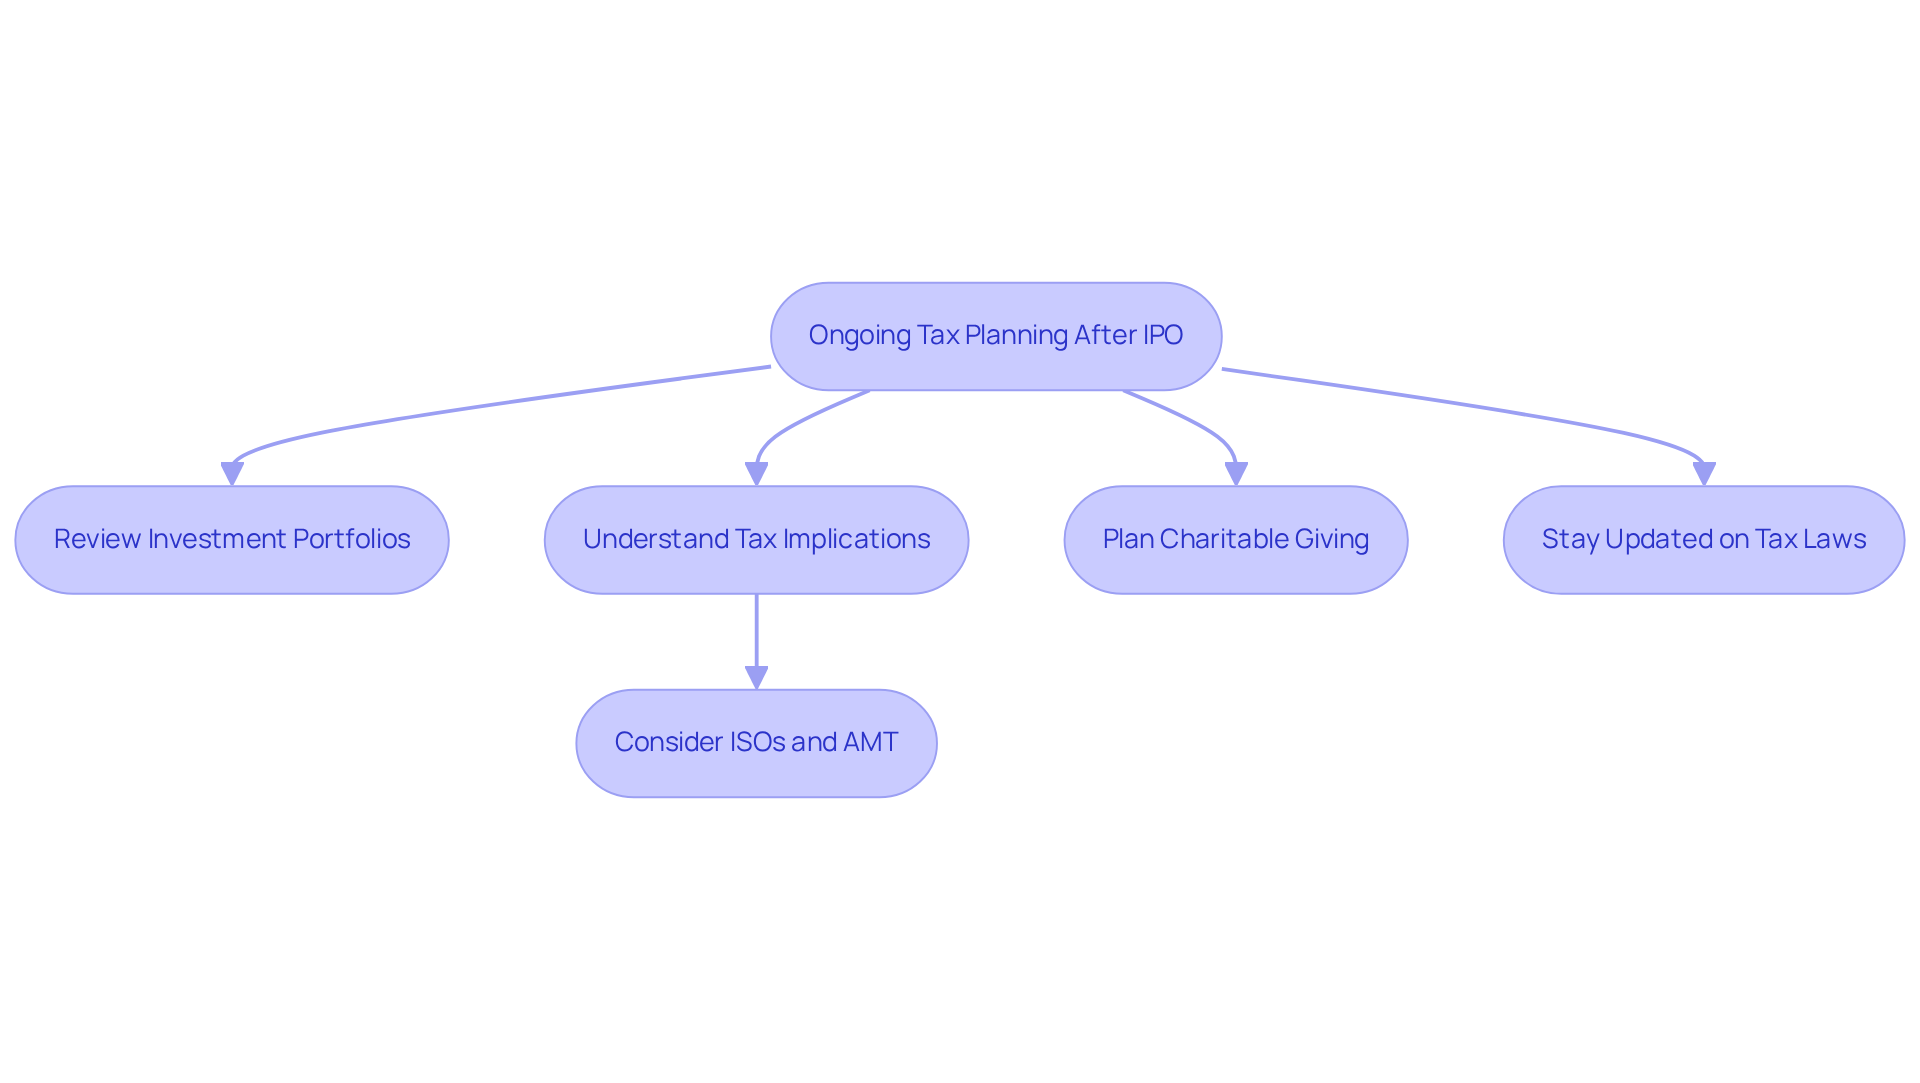
Imagine the confusion and worry that can arise when faced with new financial responsibilities after an IPO. It’s important to understand that after an IPO, families may feel overwhelmed by the need for ongoing IPO tax planning to navigate their new financial landscape. Regularly reviewing investment portfolios and understanding the tax implications of equity holdings is crucial. For instance, families should be aware that exercising Incentive Stock Options (ISOs) can trigger Alternative Minimum Tax (AMT), which may create a discrepancy between reported earnings and actual cash liquidity.
We’re here for families like Allison and Brian, who initially felt lost in the complexities of tax planning. Through their collaboration with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This shows how thoughtful IPO tax planning can help families turn IPO proceeds into lasting wealth, allowing them to focus on their long-term goals and independence.
Charitable giving can also be strategically planned to capture tax benefits while supporting meaningful causes. For example, donating appreciated securities instead of cash can avoid capital gains taxes and qualify for a full market value deduction. Staying updated on changes in tax laws is essential, as these can greatly affect monetary situations. The lifetime gift and estate tax exemption is currently $13.99 million per individual, allowing households to transfer wealth efficiently.
By taking these steps, families can find peace of mind, knowing they are securing a brighter future for their children. Effective IPO tax planning can transform IPO proceeds into lasting wealth, thereby supporting long-term goals and financial independence.
Conclusion
Imagine the relief of understanding how an IPO can shape your family’s financial future, especially when young children are involved. Recognizing the various tax responsibilities associated with stock options, RSUs, and capital gains can feel overwhelming, but it’s essential for preparing for the financial changes that come with a public offering. Many families feel overwhelmed by the complexities of tax responsibilities that come with an IPO. By taking these steps, families can transform uncertainty into confidence about their financial future.
Throughout this article, we’ve highlighted key strategies, like developing a comprehensive financial plan before an IPO and navigating the complexities of equity compensation. It’s important to consider the timing of exercising stock options, explore tax-loss harvesting, and stay informed about tax law changes to optimize your financial outcomes. Collaborating with experts like Bright Advisers can provide tailored guidance to help families make informed decisions that align with their long-term goals.
Ultimately, effective IPO tax planning is not just about managing immediate tax liabilities; it’s about transforming potential financial windfalls into lasting wealth for future generations. Taking these steps today can empower your family to build a legacy that lasts for generations, ensuring your children thrive in a secure financial environment. Engaging with a knowledgeable advisor can make all the difference in achieving these objectives, paving the way for a brighter financial future.
Frequently Asked Questions
What is the significance of IPO tax planning for families?
IPO tax planning is crucial for families as it helps them understand how a company’s public offering can impact their finances, including capital gains taxes, stock options, and estate taxes.
How are stock options and RSUs taxed?
Stock options and Restricted Stock Units (RSUs) are typically taxed as regular income when they vest, which may result in the family being pushed into a higher tax bracket.
What is the Kiddie Tax and why is it important?
The Kiddie Tax affects how a child’s unearned income is taxed, which adds complexity to a family’s financial situation and planning.
How can understanding these tax implications benefit families?
By grasping the tax implications of IPOs, families can better prepare for the financial responsibilities that come with an IPO and make informed decisions to secure their children’s future.
List of Sources
- Understand IPO Tax Implications for Families
- What is an IPO? Initial Public Offerings Explained (https://schwab.com/learn/story/what-is-an-ipo)
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)
- 3 Tax Things to Beware of After IPO – Page (https://kbfinancialadvisors.com/3-tax-things-to-beware-of-after-ipo)
- Tax implications of gifting appreciated stock or crypto to a minor child vs UGMA/UTMA (https://community.freetaxusa.com/discussion/1483/tax-implications-of-gifting-appreciated-stock-or-crypto-to-a-minor-child-vs-ugma-utma)
- Pre-IPO Tax Planning: Don’t Let Taxes Derail Your Life After Work – Burton Enright Welch (https://bewinvest.com/insights/pre-ipo-tax-planning-dont-let-taxes-derail-your-life-after-work)
- Develop a Comprehensive Financial Strategy Pre-IPO
- IPO Planning for Employees: Tax Strategies, Risks, and What to Do Before You Sell (https://missionwealth.com/resources/insights/ipo-planning-for-employees)
- Thoughtful IPO Planning: Protect & Grow Your Wealth (https://aspiriant.com/fathom/ipo-planning-guide)
- Financial Planning with Equity Compensation (https://schwab.com/learn/story/financial-planning-with-equity-compensation)
- 4 Tax Management Strategies To Consider for Your Equity Compensation | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/equity-comp-optimize-taxes)
- Navigate Equity Compensation Types and Their Tax Effects
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/blog/espp-tax-rules-what-you-need-to-know)
- RSUs vs. Options: Tax Implications of Equity Compensation (https://brightonjones.com/blog/rsus-vs-options)
- Implement Ongoing Tax Planning After the IPO
- Tax Planning Strategies to Grow and Protect Family Wealth – BCR Wealth Strategies (https://bcrwealth.com/tax-planning/tax-planning-strategies-to-grow-and-protect-family-wealth)
- Tax Tips And Warnings For IPO Company Employees And Their Advisors (https://forbes.com/sites/brucebrumberg/2026/06/23/tax-tips-and-warnings-for-ipo-company-employees-and-their-advisors)
- Pre-IPO Tax Planning: Don’t Let Taxes Derail Your Life After Work – Burton Enright Welch (https://bewinvest.com/insights/pre-ipo-tax-planning-dont-let-taxes-derail-your-life-after-work)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading