

Key Highlights
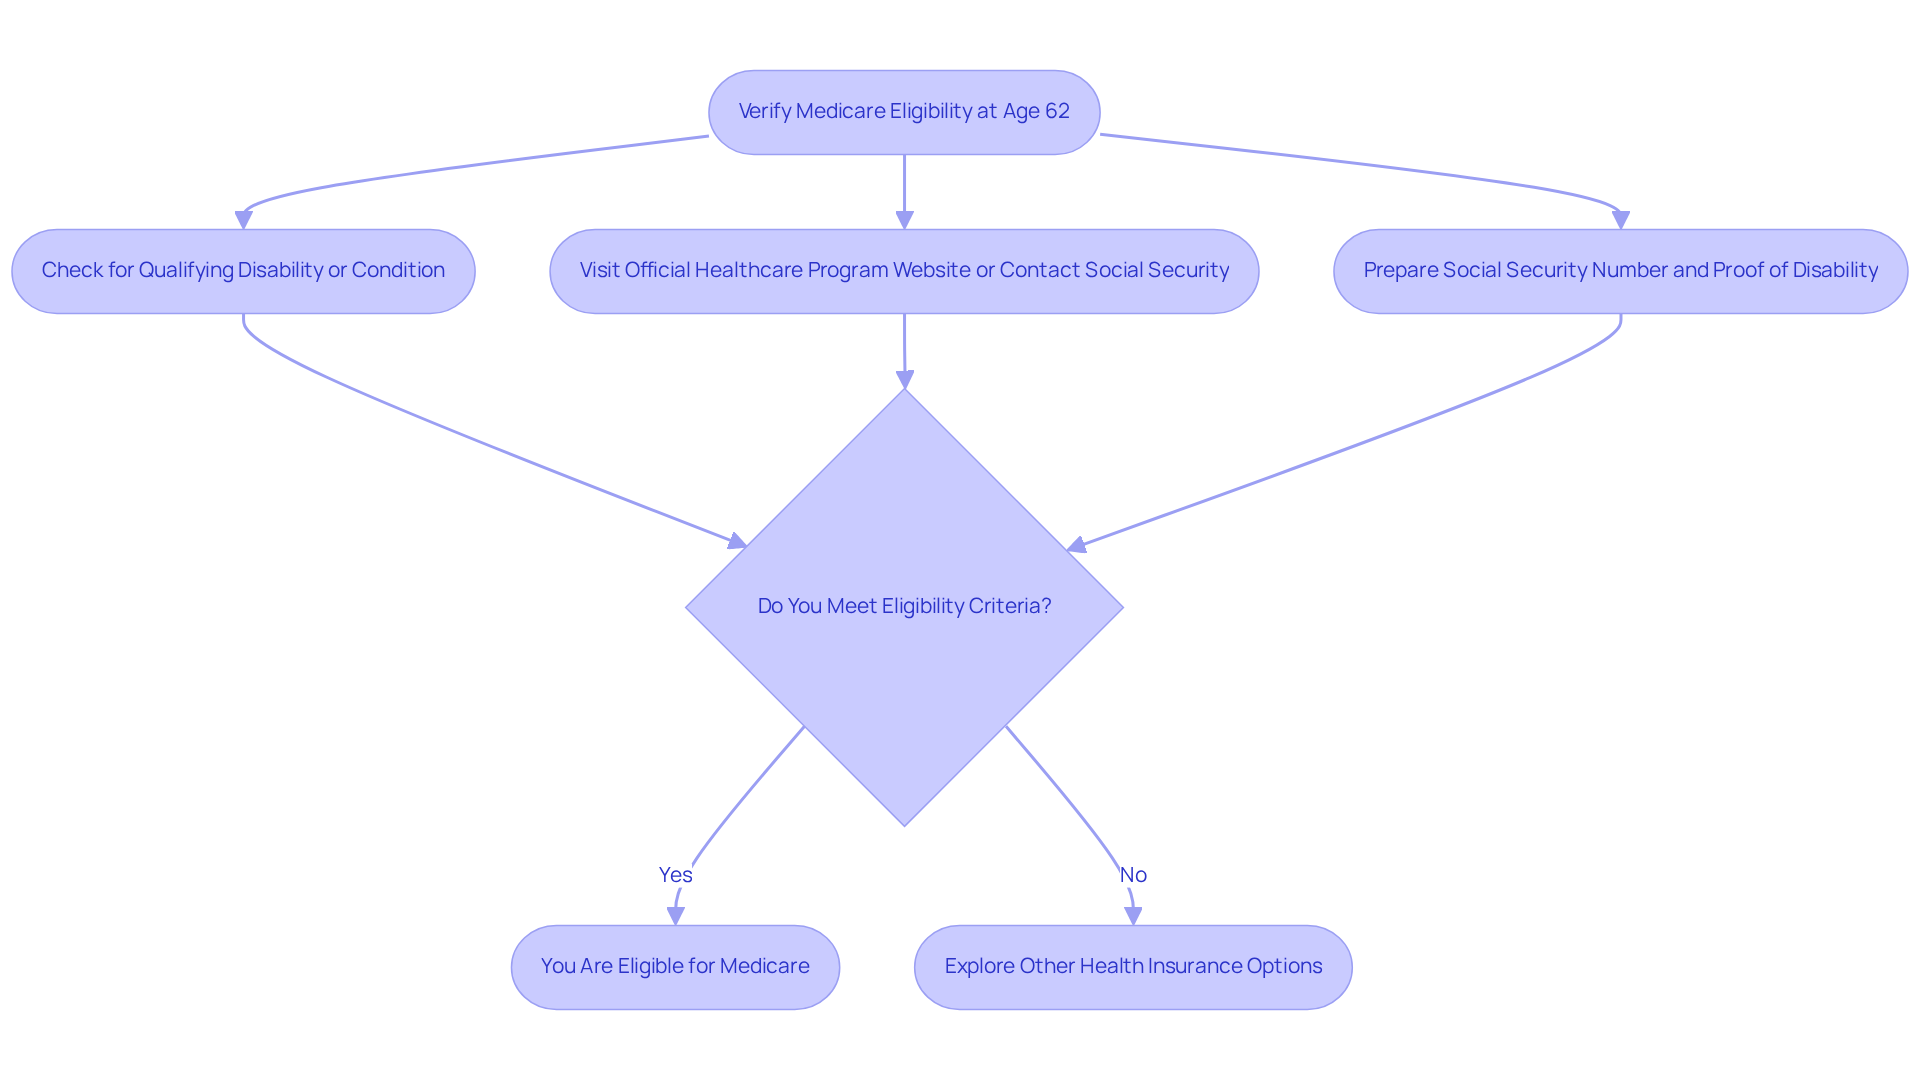
- Cheque for early Medicare eligibility if you have a qualifying disability or condition; visit the official healthcare programme website or contact Social Security.
- Have your Social Security number and proof of disability ready to confirm eligibility status.
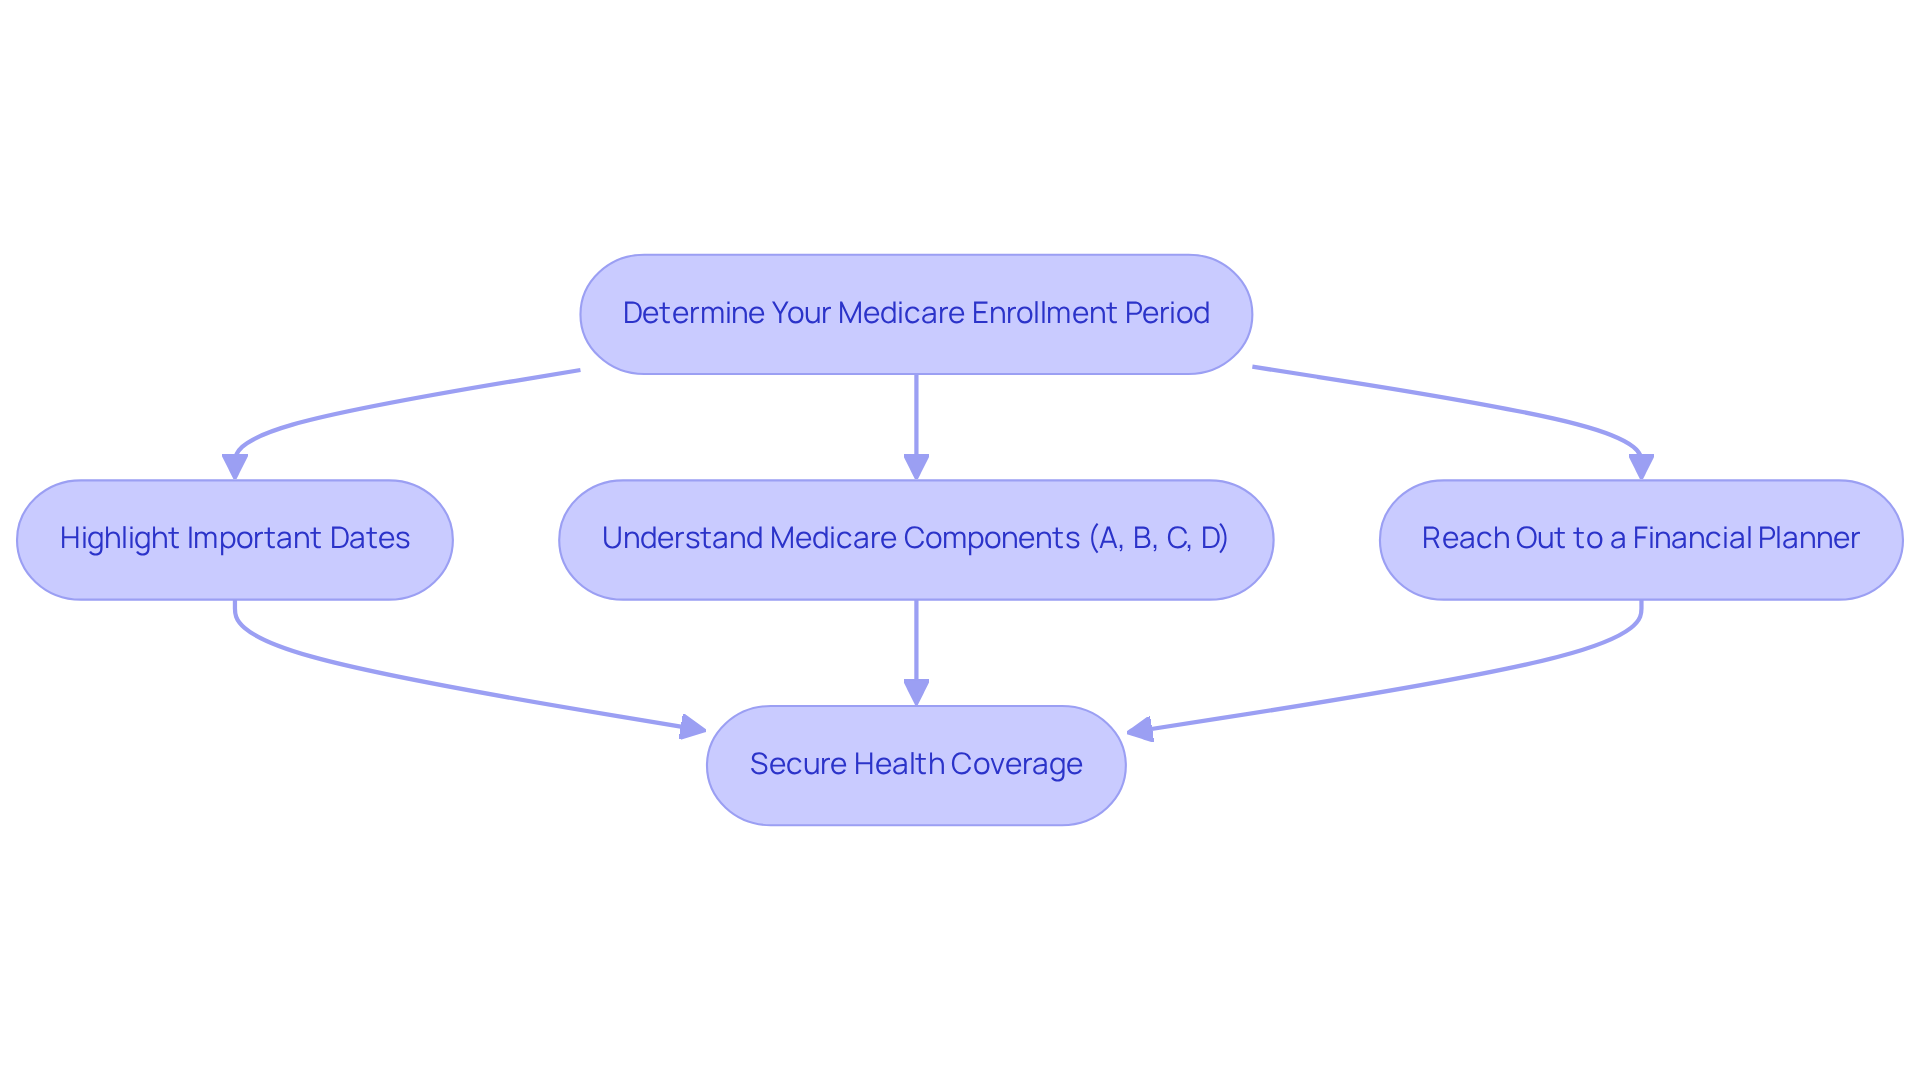
- Mark important Medicare enrolment dates on your calendar to avoid missing the registration window.
- Understand the components of Medicare (A, B, C, D) to choose the best coverage for your family.
- Consult with a financial planner at Bright Advisers to integrate Medicare into your family’s retirement plan.
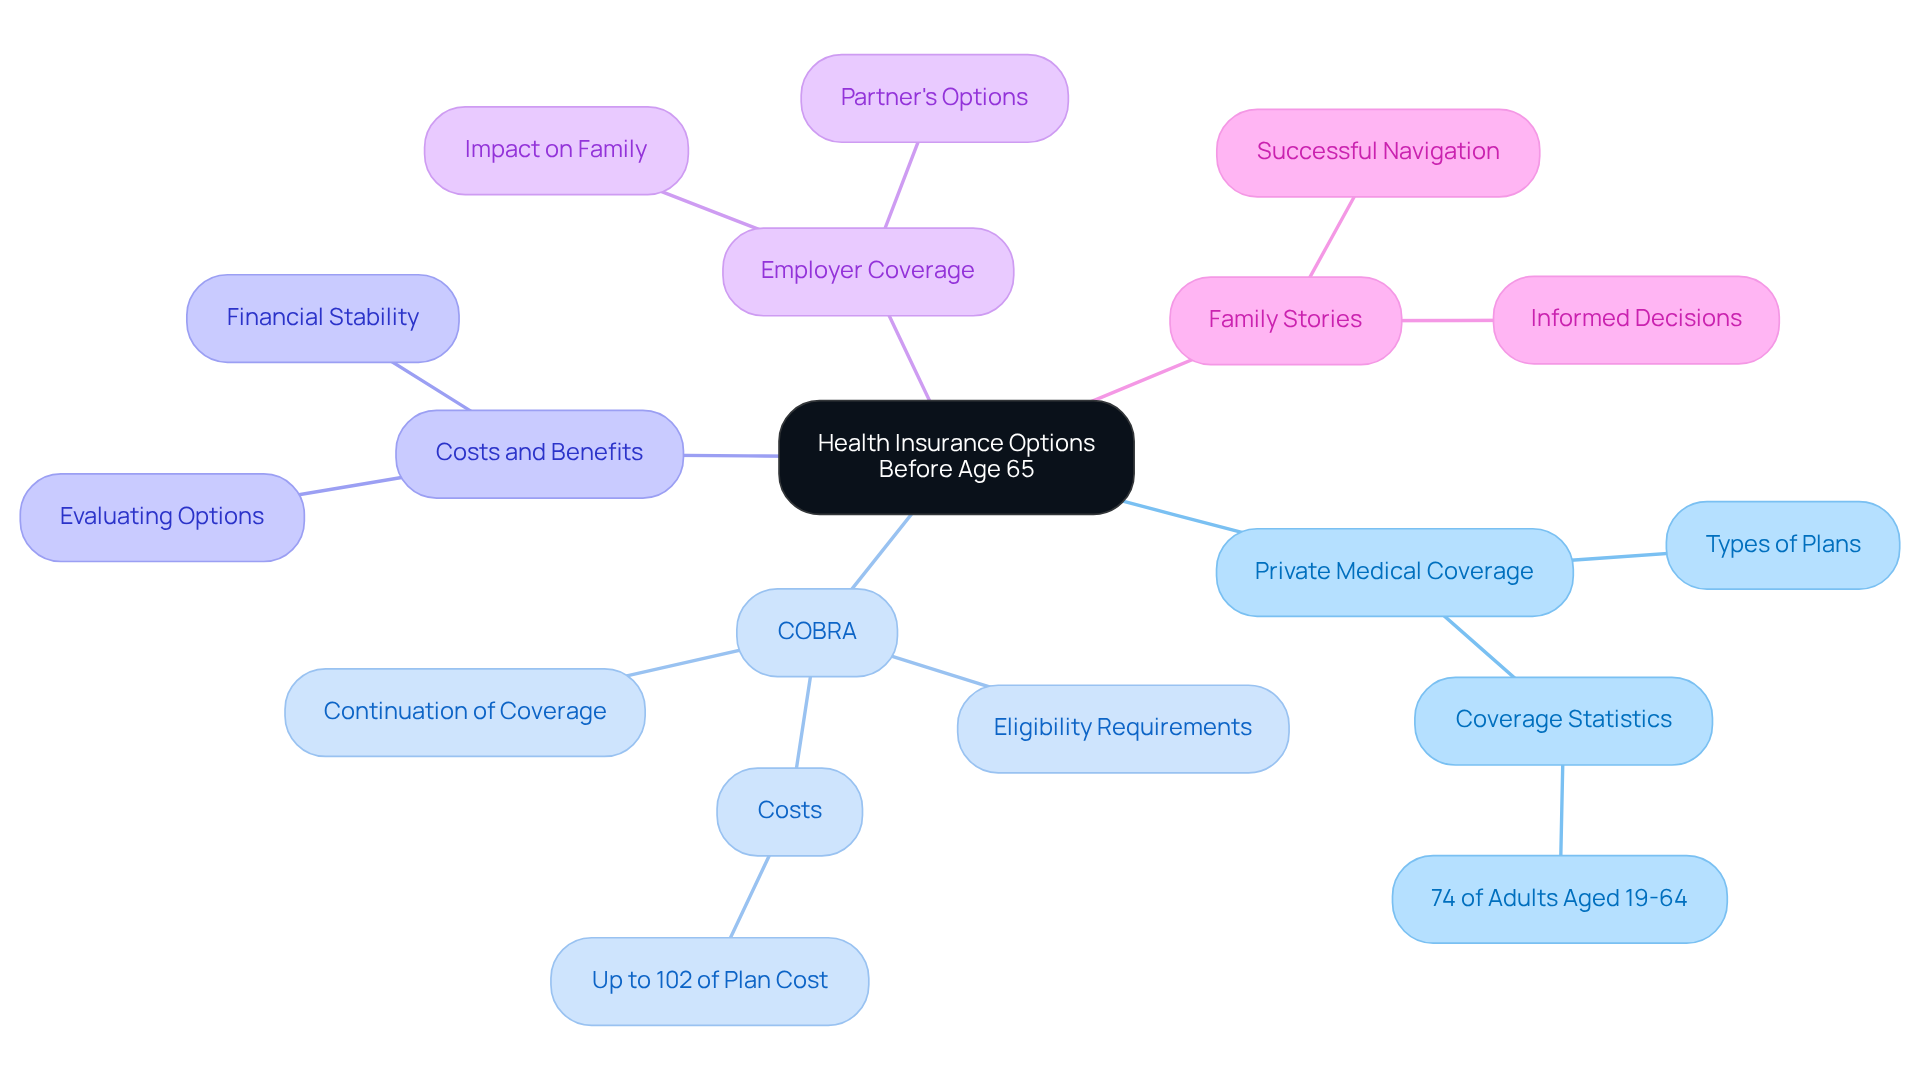
- Explore private medical coverage options through the Health Coverage Marketplace if leaving a job with medical benefits.
- Consider COBRA to maintain group medical benefits temporarily after job loss.
- Discuss employer medical coverage options with your partner for additional financial stability.
- Assess how retirement plans may affect spousal Medicare benefits and consider delaying enrolment to avoid penalties.
- Engage a financial advisor to navigate healthcare choices and ensure informed decisions for your family’s future.
Introduction
Imagine standing at the crossroads of health care decisions as you approach Medicare at age 62. As you and your family prepare for this important milestone, knowing the essential steps for enrollment can help ensure you have the coverage you need.
What challenges might you face along the way, and how can you tackle them to ensure the best health outcomes for your loved ones? Together, we’ll explore the key actions you can take to navigate Medicare enrollment, empowering your family to make informed decisions for a healthier future.
Verify Your Medicare Eligibility at Age 62
Navigating health insurance can feel overwhelming, especially when you’re trying to ensure your family is protected.
Check if you have a qualifying disability or condition that permits early eligibility for health insurance. It can be frustrating to find out that many won’t qualify for federal health coverage until they are turning 62 and Medicare. To confirm your eligibility status, visit the official healthcare program website or contact Social Security.
Make sure to have your Social Security number and any proof of disability ready, as these documents will help in your journey. If you don’t meet the criteria for government health coverage at this age, don’t worry. There are other options available to ensure you and your family are covered. Explore different health insurance choices that can fit your needs.
Determine Your Medicare Enrollment Period
Navigating Medicare can feel overwhelming, especially when you’re focused on your family’s future. It’s a good idea to highlight these important dates on your calendar, so you can feel secure knowing you won’t miss this crucial enrollment window. If you’re receiving Social Security benefits, you may find that you’re automatically registered in the health insurance program.
Understanding the various components of Medicare – A, B, C, and D – can help you determine what coverage is best for your family. By grasping these components, you can ensure your family is well-protected and financially secure.
Reaching out to a caring financial planner, like those at Bright Advisers, can help you see how Medicare can seamlessly fit into your family’s retirement plan. This is especially important for young families like Jay and Emma, who are looking to reduce financial anxiety while effectively allocating resources for their future and their children’s education.
With the right guidance, you can confidently secure the health coverage your family deserves.
Explore Health Insurance Options Before Age 65
Imagine facing a sudden job loss and the uncertainty of your family’s health coverage – it’s a daunting situation many families find themselves in. Let’s take a moment to explore the private medical coverage plans available through the Health Coverage Marketplace. These plans can be tailored to meet your family’s unique needs.
If you’re leaving a job that offered medical coverage, think about COBRA. It can help you keep your group medical benefits for a while, giving you some peace of mind during a tough transition. Remember, navigating health coverage can feel overwhelming, especially during times of change. It’s normal to feel uncertain about the best choices for your family.
Take a close look at the costs and benefits of each option. Did you know that in 2024, 74% of adults aged 19 to 64 had private coverage? Understanding these choices can help meet your family’s specific needs. Talk with your partner about their employer’s medical coverage options, which may include you, offering extra financial stability for your family.
Look at stories from families who have successfully navigated their health insurance choices before turning 65. Their experiences show just how important it is to make informed decisions for your family’s health coverage. By exploring your options and making informed decisions, you can ensure your family stays protected during life’s unexpected turns.
Assess Impact of Retirement on Spousal Medicare Benefits
Imagine sitting down with your spouse to discuss how your retirement plans can shape your family’s healthcare choices. It’s important to know that:
- If one of you qualifies for the federal health program, the other might not be eligible until turning 62 and Medicare, which is a concern to consider together.
- Take a moment to look at your financial picture together; this can help you decide if extra health insurance is something to think about for the spouse who isn’t on Medicare yet.
- You might also want to explore options for delaying Medicare enrollment for the spouse who is not yet eligible, particularly when turning 62 and Medicare, to ensure you avoid any penalties.
Together, let’s explore how a financial advisor can help you navigate these important decisions for your family’s future.
Conclusion
Imagine feeling overwhelmed as you approach Medicare at age 62, wondering how to ensure your family’s health needs are met. Getting to know the ins and outs of eligibility and enrollment can help families feel more in control of their health coverage.
It’s vital to check your Medicare eligibility and know the enrollment timelines to avoid any surprises later on. Don’t forget to think about how retirement might affect spousal benefits, as it’s a key part of your planning journey.
This journey isn’t just about checking boxes; it’s about creating a safety net for your family’s health and peace of mind. Engaging with a knowledgeable financial advisor, like those at Bright Advisers, can provide personalized guidance tailored to your unique situation.
As you embark on this journey, remember that with the right support, you can turn uncertainty into a brighter, healthier future for your family.
Frequently Asked Questions
What is the main focus of the article regarding Medicare eligibility?
The article focuses on verifying Medicare eligibility at age 62, particularly for individuals with qualifying disabilities or conditions.
How can I check my Medicare eligibility?
You can check your Medicare eligibility by visiting the official healthcare program website or by contacting Social Security.
What documents should I have ready to confirm my eligibility?
You should have your Social Security number and any proof of disability ready to assist in confirming your eligibility status.
What if I do not qualify for Medicare at age 62?
If you do not meet the criteria for government health coverage at age 62, there are other health insurance options available to ensure you and your family are covered.
Why is it important to verify Medicare eligibility?
Verifying Medicare eligibility is important to ensure that you and your family have the necessary health insurance coverage as you approach age 62.
List of Sources
- Verify Your Medicare Eligibility at Age 62
- Medicare for People Under 65 – Center for Medicare Advocacy (https://medicareadvocacy.org/under-65-project)
- State Scorecard on Medicare Beneficiary Experiences (https://commonwealthfund.org/publications/scorecard/2025/oct/state-scorecard-medicare-performance)
- Medicare Statistics And Facts (https://forbes.com/advisor/health-insurance/medicare/medicare-statistics)
- Determine Your Medicare Enrollment Period
- Medicare Initial Enrollment Period (IEP) | UnitedHealthcare (https://uhc.com/medicare/medicare-education/medicare-initial-enrollment-period.html)
- Medicare Advantage in 2026: Enrollment Update and Key Trends | KFF (https://kff.org/medicare/medicare-advantage-in-2026-enrollment-update-and-key-trends)
- 2024 Medicare Statistics and Fast Facts | MedicareAdvantage.com (https://medicareadvantage.com/resources/medicare-statistics)
- Medicare Enrollment Numbers – Center for Medicare Advocacy (https://medicareadvocacy.org/medicare-enrollment-numbers)
- Explore Health Insurance Options Before Age 65
- State of Health Insurance in California (SHIC) (https://healthpolicy.ucla.edu/our-work/state-health-insurance-california-shic)
- Health Care Coverage for Retirees (https://healthcare.gov/retirees)
- Continuation of Health Coverage (COBRA) (https://dol.gov/general/topic/health-plans/cobra)
- Health Insurance Coverage in the United States: 2024 (https://census.gov/library/publications/2025/demo/p60-288.html)
- FastStats (https://cdc.gov/nchs/fastats/health-insurance.htm)
- Assess Impact of Retirement on Spousal Medicare Benefits
- Medicare coverage for non-working spouses (https://uhc.com/news-articles/medicare-articles/medicare-coverage-for-non-working-spouses)
- Avoid late enrollment penalties (https://medicare.gov/basics/costs/medicare-costs/avoid-penalties)
- The Medicare Enrollment Mistake Costing Seniors $8,000 in Lifetime Penalties (https://finance.yahoo.com/sectors/healthcare/articles/medicare-enrollment-mistake-costing-seniors-132004946.html)
- A Guide to Medicare Benefits for Spouses | Wellcare (https://wellcare.com/en/resources/medicare-benefits-for-spouses)
- What Is the Penalty for Late Enrollment in Medicare? (https://ncoa.org/article/understanding-medicares-late-enrollment-penalties)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading