

Key Highlights
- Fee-based advisory models charge clients directly through flat fees, hourly rates, or a percentage of investments, promoting transparency.
- Commission-based advisors earn income from product sales, which can create conflicts of interest and affect the quality of advice.
- 86% of advisory firms primarily use AUM fees, indicating a trend towards fee-based models that support sustainable revenue.
- Fee-based advisors prioritise client needs and often provide holistic services, including tax and estate planning.
- Commission-based models may lead to a lack of ongoing support and guidance, focusing instead on transactions.
- Over half of families prefer clear, predictable fee structures, highlighting a shift towards fee-based advisory services.
- Understanding these models is crucial for families to make informed financial decisions that align with their long-term goals.
- Bright Advisers emphasises fiduciary duty, ensuring no hidden fees or conflicts of interest, and focuses on personalised wealth management.
Introduction
Imagine feeling secure about your family’s financial future, but unsure which path to take in financial advisory services. You might be wondering whether to choose fee-based or commission-based advisory services. Each option has its own set of benefits and challenges, and it’s important to find one that aligns with your family’s values and long-term goals.
As you consider these options, you may ask yourself: which model truly supports your family’s needs and fosters a relationship built on trust and clarity? This article invites you to explore the key differences between these advisory approaches together, empowering you to make informed decisions that resonate with your aspirations. Understanding these differences can empower you to choose a path that truly supports your family’s dreams and values.
Define Fee-Based and Commission-Based Advisory Models
Navigating financial advice can feel overwhelming, especially when you’re trying to secure a bright future for your family. Imagine having a financial partner who operates on fee-based advisory models, charging you directly through flat fees, hourly rates, or a percentage of your investments.
On the other hand, commission-based advisors make their money from the products they sell, which can sometimes create a conflict of interest that might not serve your family’s best needs. Understanding this difference is vital for families like yours, as it can greatly affect the quality and trustworthiness of the financial guidance you receive.
Recent trends show that:
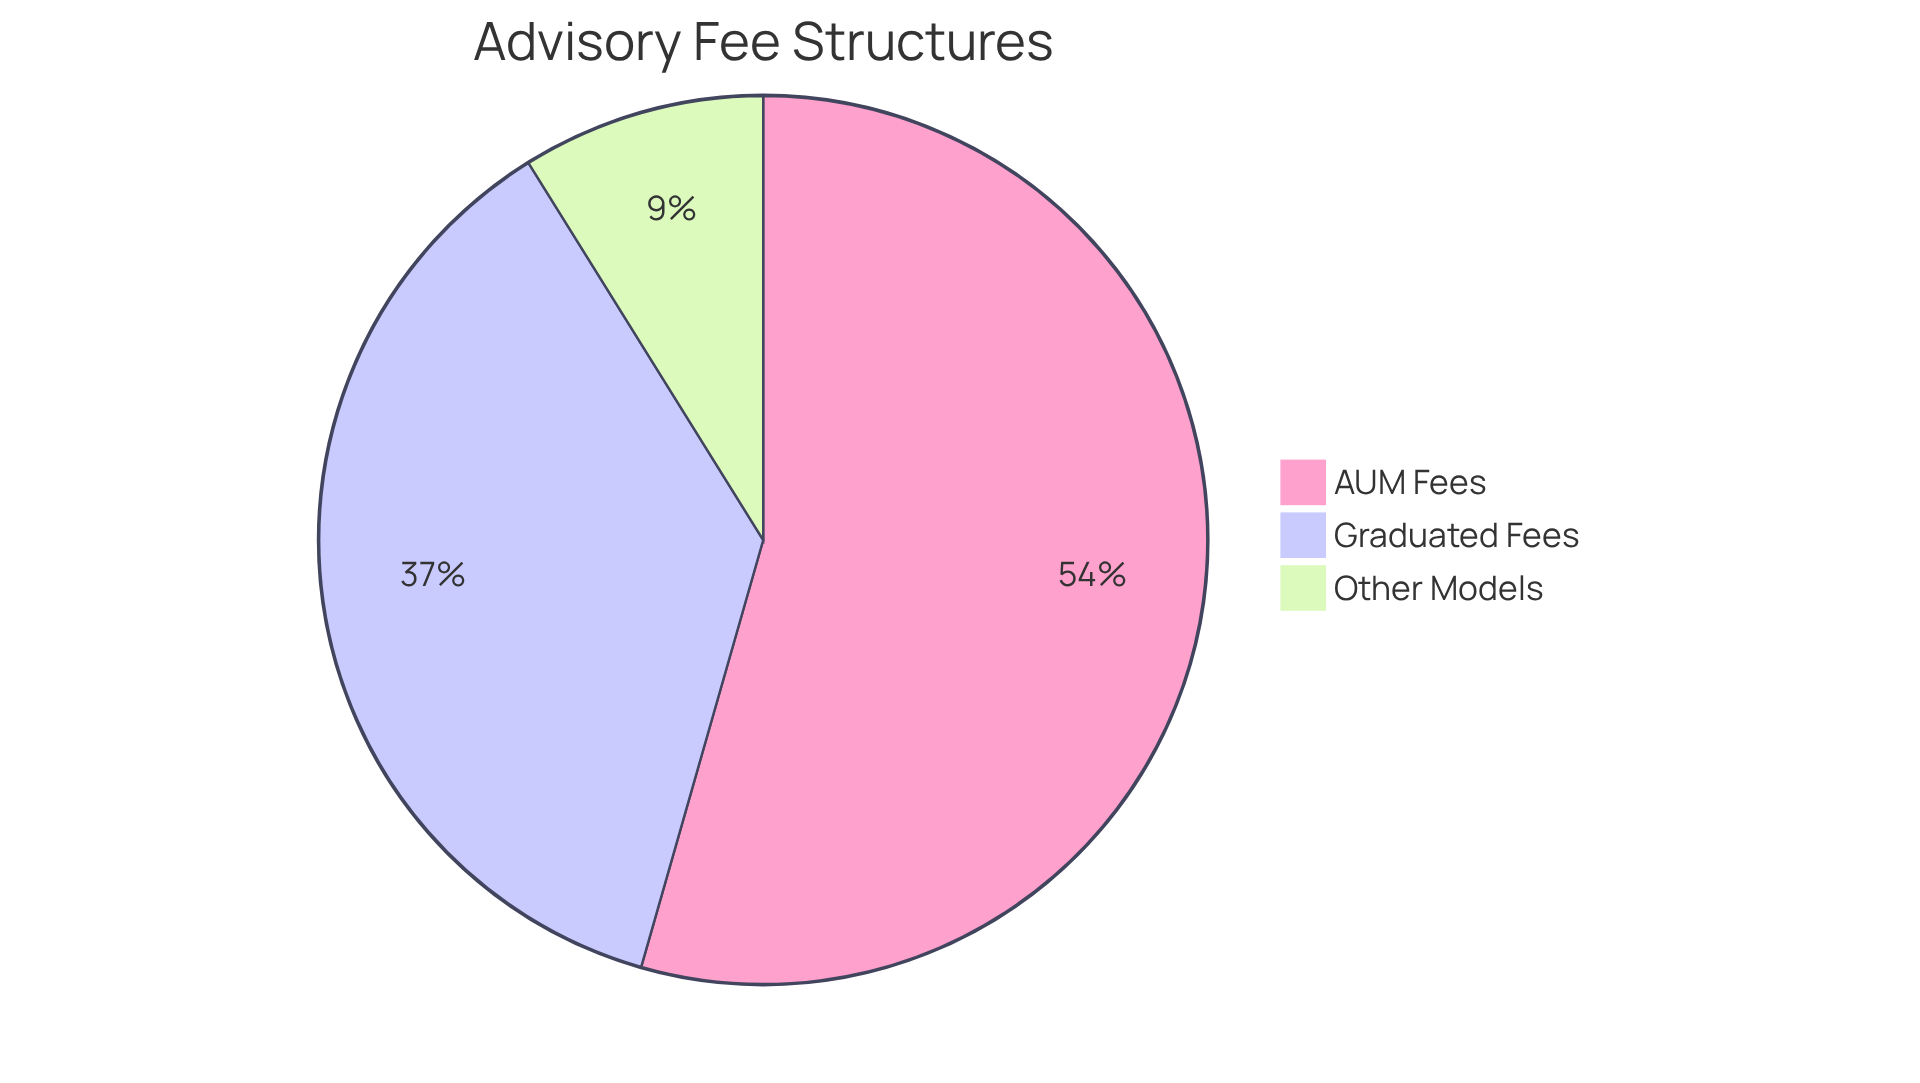
- 86% of advisory firms primarily rely on AUM fees, reflecting a shift towards fee-based advisory models that support predictable and sustainable revenue.
- 58% of advisory firms employ graduated fee structures, which can provide more competitive pricing across various customer segments.
- In 2023, the average expense ratio for U.S. open-end mutual funds was 0.36%, a decrease from prior years, further emphasizing the trend towards reduced investment costs that advantage investors.
Case studies illustrate the effectiveness of fee-based advisory models. For example, companies that have implemented unbundled pricing models often discover that overall charges for bundled and unbundled services are almost the same, indicating that unbundling can improve accessibility for customers with smaller portfolios. Additionally, as portfolio sizes increase, many advisors tend to decrease their AUM fees, countering the perception that larger portfolios equate to higher fees. This trend reflects a nuanced understanding of client needs and the complexity of managing larger portfolios.
Grasping these models is essential for families charting their financial futures, as it shapes the guidance you receive and the overall experience of planning together. Bright Advisers is committed to empowering young households through personalized planning and strategic resource allocation, ensuring that financial security and educational readiness are within reach.
Explore Benefits of Fee-Based Advisory for Young Families
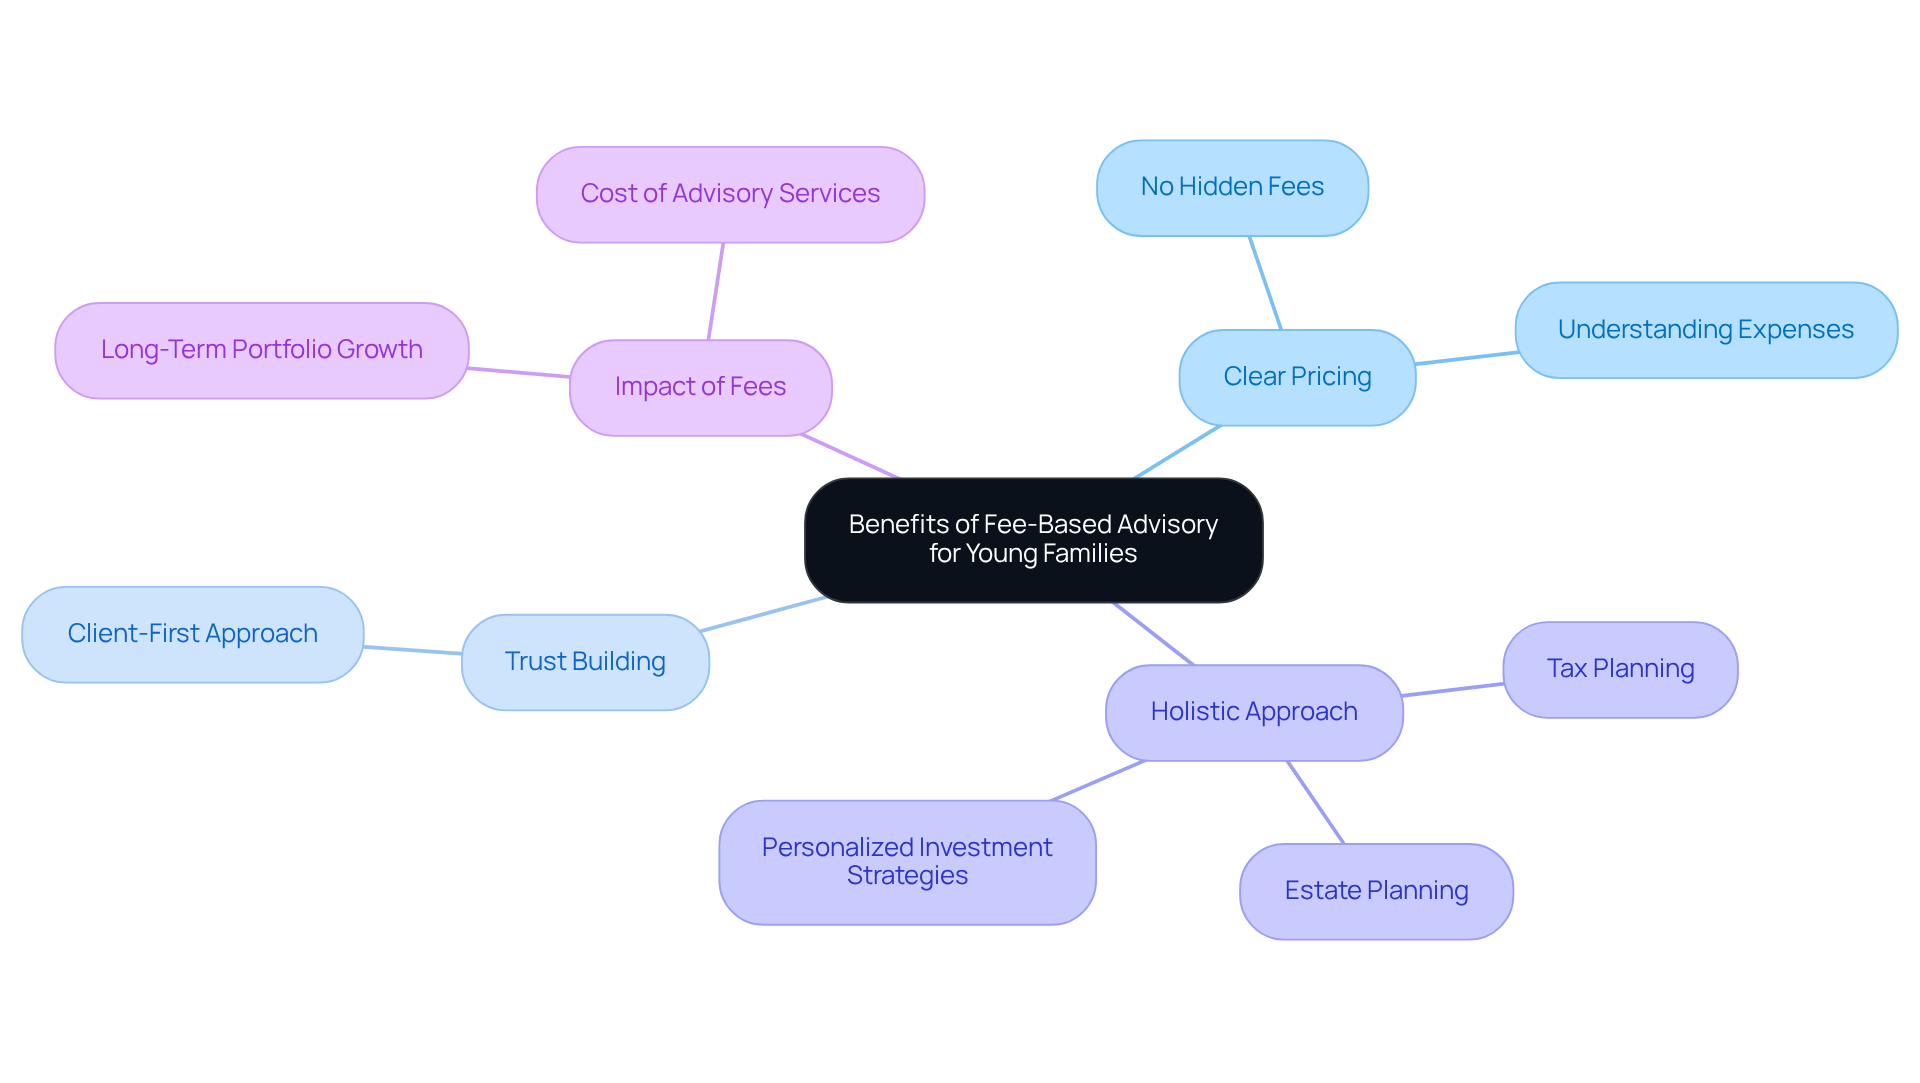
Imagine feeling confident about your family’s financial future without the worry of hidden fees or unclear costs. Fee-based advisory models provide numerous benefits tailored for young households. One big plus is the clear pricing, helping families understand their expenses without worrying about hidden fees. This openness builds trust between families and their advisors, which is so important for smart financial planning. Plus, fee-based advisors are required to put their clients’ needs first, which is a big deal for families seeking to align their economic strategies with long-term goals.
Additionally, fee-based advisors often take a holistic approach to managing finances, integrating essential services like tax planning, estate planning, and personalized investment strategies. Bright Advisers, for example, uses in-house technology to create hyper-personalized portfolios, steering clear of costly mutual funds and ETFs. This all-in-one service makes managing your finances easier and can lead to better results for your family. Families like Emily and Mark, who worked with Bright Advisers, found customized services that helped them navigate the complexities of financial planning. By thoroughly evaluating their situation, they crafted a strategy that improved their financial well-being and gave them the freedom to choose whether to keep working.
More and more families-over half now-are choosing holistic advice to guide their financial decisions, showing how much this approach is valued. Furthermore, an investment consultant charging a 1% fee on a $500,000 portfolio could cost households $5,000 each year, highlighting the importance of understanding fee structures. Significantly, a 1% charge could diminish a portfolio’s worth by almost 28% over 30 years, assuming a consistent 7% yearly return. By choosing fee-based advisory services, families can navigate the complexities of wealth management with greater confidence and clarity, ultimately securing their futures and alleviating financial anxiety. Together, we can navigate this journey.
Analyze Drawbacks of Commission-Based Models
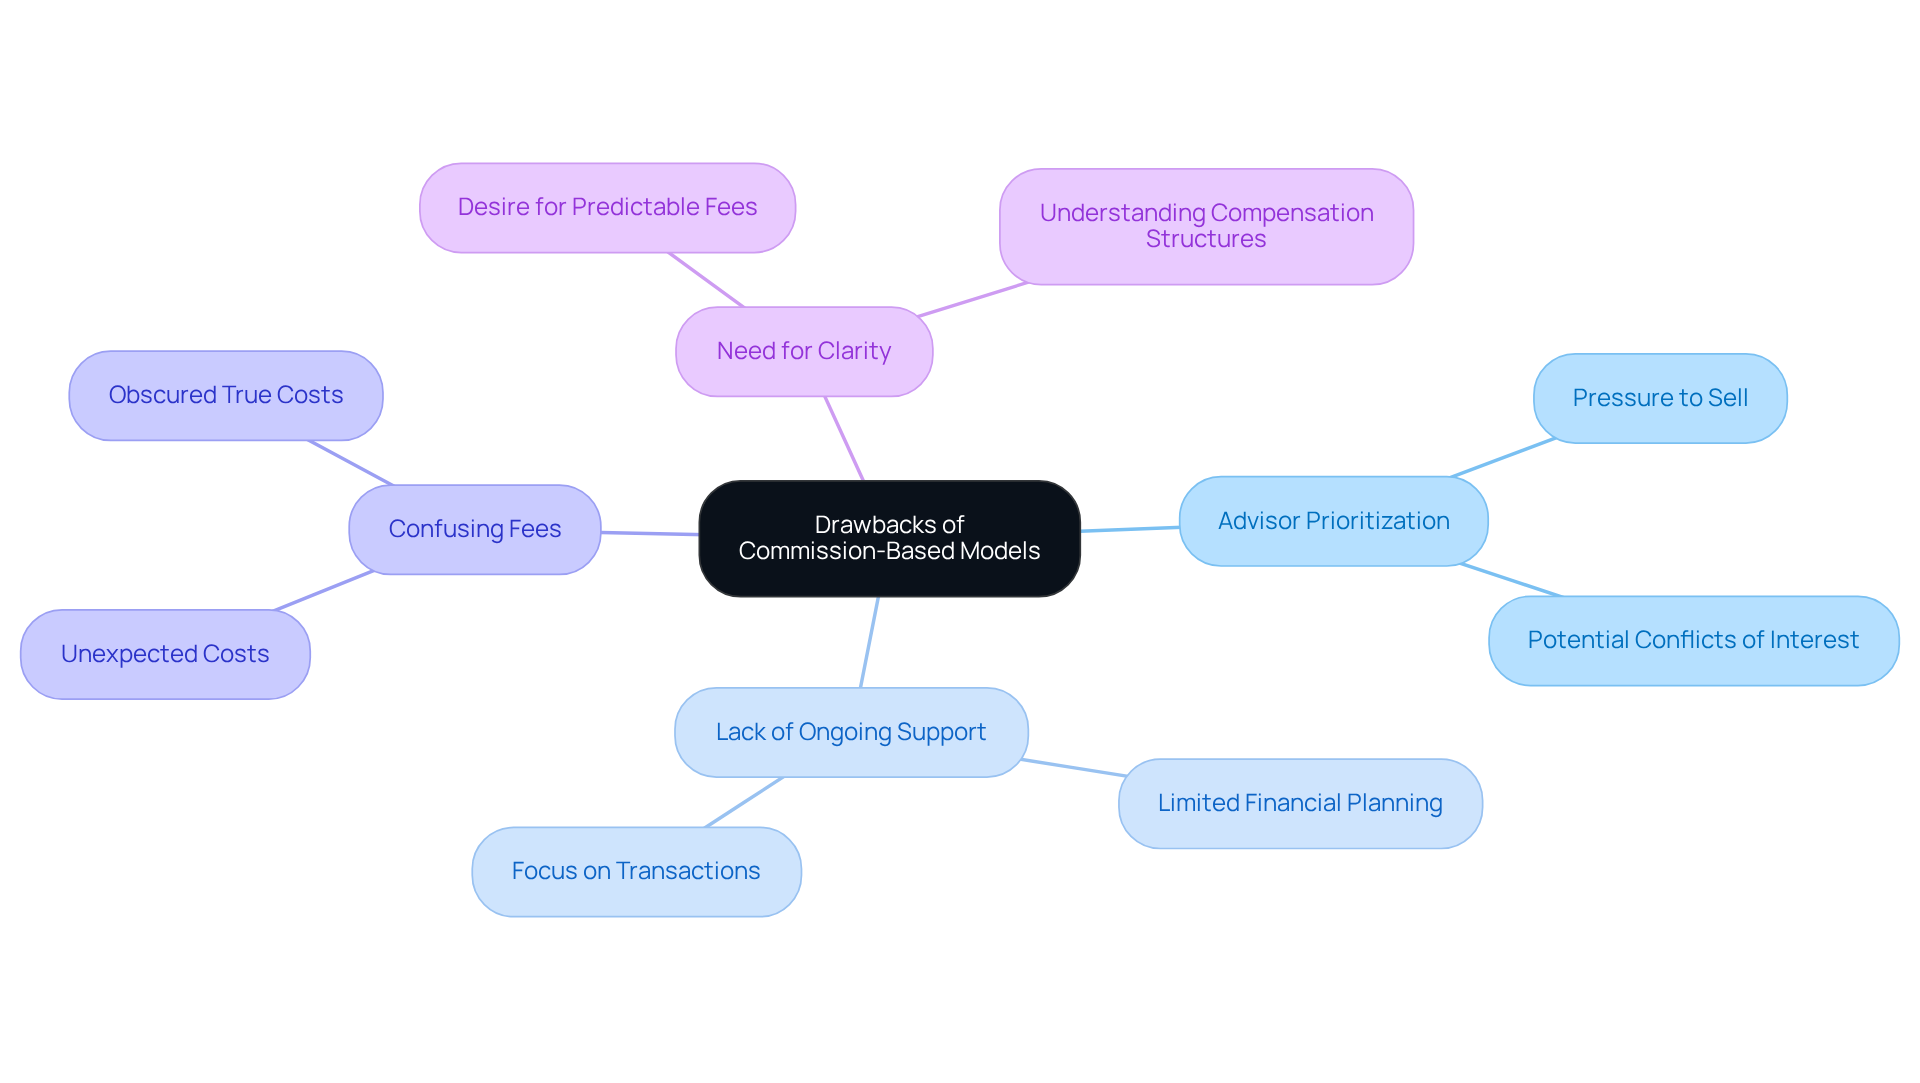
Imagine feeling uncertain about your financial choices while trying to secure a bright future for your family. Commission-based advisory models can bring some challenges that young households should be aware of. It’s concerning to think that some advisors might prioritize their commissions over what’s best for your family. This pressure can lead to choices that don’t truly serve your family’s needs.
Many commission-based advisors focus on quick transactions rather than building lasting relationships that support your family’s financial journey. This approach can leave families without the comprehensive support they need, especially when navigating complex financial decisions that affect generations.
It’s also important to talk about how confusing fees can be for families. The way commissions are structured can obscure the true costs of the advice you receive, leading to unexpected financial burdens. This uncertainty can make it harder for families to feel confident about their financial future.
Many families, about 61%, are looking for clearer, more predictable ways to pay for financial advice, such as through fee based advisory. Case studies show that commission-based advisors often don’t provide ongoing guidance or planning services, as their income mainly comes from product sales rather than continuous client interaction. These challenges can make it tough for families to feel secure about their financial future, so it’s crucial to find a fee based advisory that aligns with your family’s goals. Together, we can navigate this journey and ensure your family’s financial well-being.
Compare Fee-Based and Commission-Based Models: A Side-by-Side Analysis
Navigating the world of financial advice can feel overwhelming, especially when you’re trying to secure a bright future for your family. Understanding the differences between fee-based advisory models and commission-based advisory models is crucial for making informed decisions that align with your family’s values.
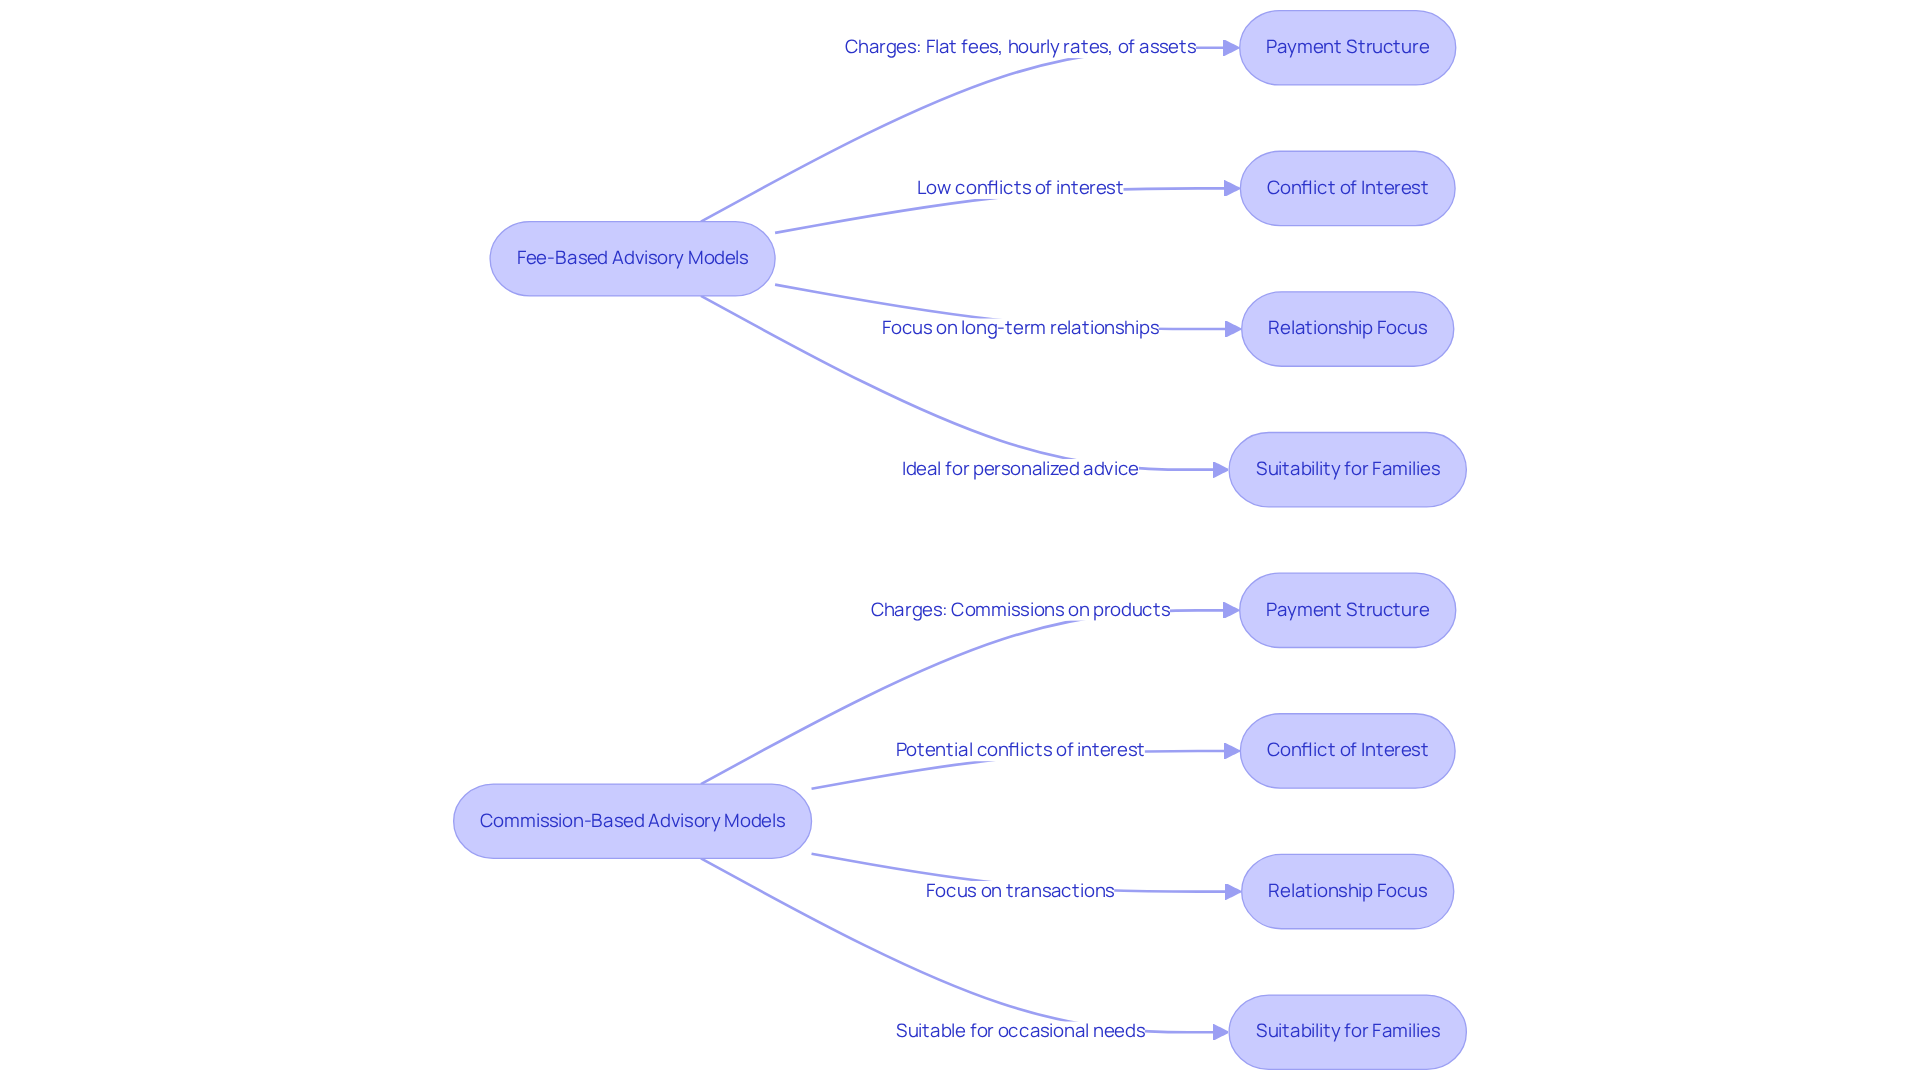
Imagine knowing exactly what you’re paying for; fee-based advisory services charge you directly through flat fees, hourly rates, or a percentage of your assets, ensuring clarity in your financial journey. On the other hand, commission-based advisors earn their income from the products they sell, which can sometimes create conflicts of interest that might not align with your family’s best needs.
Fee-based advisory services are committed to your family’s well-being, legally bound to act in your best interest and provide recommendations that truly support your financial goals. In contrast, commission-based advisors often focus on transactions, which might leave your family’s broader financial picture overlooked.
Fee-based advisors prioritize building lasting relationships, ensuring you feel supported and understood throughout your financial journey. Sometimes, commission-based advisors might focus more on sales than on your family’s unique needs, which can affect the trust in your relationship.
Fee-based advisory is ideal for families like yours who seek personalized advice and long-term strategies that adapt to your changing needs. Commission-based advisory might suit families with occasional financial needs, as costs arise only when transactions occur, but it may not provide the comprehensive support you deserve.
This side-by-side analysis highlights the key differences between fee-based advisory models and commission-based advisory models, enabling families to evaluate which model aligns best with their financial goals and values. Choosing the right advisory model can be the first step towards a secure financial future for your family, and we’re here to help you every step of the way.
Conclusion
Let’s take a moment to understand the differences between fee-based and commission-based advisory models, as this is crucial for families like yours who want to secure a bright financial future. Choosing between these two models can greatly affect the quality of guidance you receive. It influences not just your immediate decisions but also your long-term financial strategies. When families choose a fee-based advisory approach, they enjoy transparency and personalized service. This commitment to their best interests helps build a trusting relationship with their financial advisors.
Throughout this article, we’ve highlighted key insights, including the advantages of fee-based models, such as clear pricing structures and a holistic approach to financial planning. We’ve also examined the drawbacks of commission-based models, including potential conflicts of interest and a lack of ongoing support. Real-life stories and statistical trends illustrate how fee-based advisory services can lead to better financial outcomes for families, emphasizing the importance of aligning financial strategies with family goals.
Choosing the right advisory model can transform your family’s financial future, ensuring you make informed decisions that align with your values. By prioritizing transparency and a fiduciary duty, you can navigate your financial journey with confidence. Engaging with a fee-based advisor like Bright Advisers can empower your family to make informed decisions that not only secure your financial well-being today but also preserve wealth for future generations. For personalized guidance tailored to your family’s financial aspirations, consider reaching out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967. By choosing a fee-based advisor, you’re not just making a decision for today; you’re investing in your family’s future and peace of mind.
Frequently Asked Questions
What are the main differences between fee-based and commission-based advisory models?
Fee-based advisory models charge clients directly through flat fees, hourly rates, or a percentage of investments, while commission-based advisors earn money from the products they sell, which can create potential conflicts of interest.
Why is it important to understand the difference between these advisory models?
Understanding the difference is vital as it can significantly affect the quality and trustworthiness of the financial guidance families receive, impacting their financial future.
What recent trends are observed in advisory firms regarding fee structures?
Recent trends show that 86% of advisory firms primarily rely on AUM (Assets Under Management) fees, and 58% employ graduated fee structures, which can offer more competitive pricing for various customer segments.
How have investment costs changed recently?
In 2023, the average expense ratio for U.S. open-end mutual funds was 0.36%, a decrease from previous years, indicating a trend towards reduced investment costs that benefit investors.
What do case studies reveal about fee-based advisory models?
Case studies show that companies using unbundled pricing models often find that overall charges for bundled and unbundled services are similar, suggesting that unbundling can enhance accessibility for clients with smaller portfolios.
How do advisory fees change with portfolio sizes?
Many advisors tend to decrease their AUM fees as portfolio sizes increase, countering the notion that larger portfolios always incur higher fees, reflecting a better understanding of client needs.
What is the mission of Bright Advisers?
Bright Advisers aims to empower young households through personalized planning and strategic resource allocation, ensuring financial security and educational readiness for families.
List of Sources
- Define Fee-Based and Commission-Based Advisory Models
- Why and how financial advisors move to fee-based ꟾ BlackRock (https://blackrock.com/us/financial-professionals/insights/why-financial-advisors-move-to-fee-based-from-brokerage)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Fee-Based Models Rise as Advisers Adapt to Client Needs | PLANADVISER (https://planadviser.com/fee-based-models-dominate-advisers-respond-shifting-client-expectations)
- Fee-Only vs. Fee-Based Financial Advisors (https://smartasset.com/financial-advisor/fee-based-vs-fee-only-financial-advisor)
- Explore Benefits of Fee-Based Advisory for Young Families
- Understanding Financial Advisor Percentage Fees for Young Families – Bright Advisers (https://brightadvisers.com/understanding-financial-advisor-percentage-fees-for-young-families)
- The looming advisor shortage in US wealth management (https://mckinsey.com/industries/financial-services/our-insights/the-looming-advisor-shortage-in-us-wealth-management)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- What to Know About Financial Advisor Fees and Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)
- Analyze Drawbacks of Commission-Based Models
- Commission vs. Fee-Based Financial Advisor (https://wsj.com/buyside/personal-finance/financial-advisors/commission-vs-fee-based-financial-advisor)
- Commission-Based Advisor | Meaning, Pros, Cons, & Evaluation (https://financestrategists.com/financial-advisor/advisor-types/commission-based-advisor)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Fee Only Vs Commission Based A Comprehensive Guide To Financial Advisor Compensation Structures (https://raymondjames.com/talentfinancialservices/our-perspective/2024/03/01/fee-only-vs-commission-based-a-comprehensive-guide-to-financial-advisor-compensation-structures)
- Fee-Only Financial Advisors: Are they really better than commission-based models? (https://assetbook.com/fee-only-financial-advisors-are-they-really-better-than-commission-based-models)
- Compare Fee-Based and Commission-Based Models: A Side-by-Side Analysis
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- Fee Only Vs Commission Based A Comprehensive Guide To Financial Advisor Compensation Structures (https://raymondjames.com/talentfinancialservices/our-perspective/2024/03/01/fee-only-vs-commission-based-a-comprehensive-guide-to-financial-advisor-compensation-structures)
- Fee-Based and Commission-Based Financial Advisor Compensation Models (https://assetmark.com/resources/blog/fee-based-vs-commission-based-financial-advisor-compensation-models)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- Fee-Based vs. Commission-Based Financial Advisors (https://smartasset.com/financial-advisor/fee-based-vs-commission-financial-advisor)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading