

Key Highlights
- FERS includes three main components: Basic Benefit Plan, Social Security, and Thrift Savings Plan (TSP), providing a reliable income stream for federal workers.
- Retiring at age 62 or later with 20 years of service grants a pension multiplier of 1.1%, with pensions adjusted for inflation through Cost of Living Adjustments (COLAs).
- The TSP had approximately $840 billion in assets in 2023, with various fund options allowing federal employees to grow their retirement savings effectively.
- Eligibility for FERS requires at least five years of service and reaching the Minimum Retirement Age (MRA), while SSDI requires 40 work credits and proof of severe disability.
- SSDI payments can be more generous than FERS benefits, but there is a five-month waiting period for SSDI support, which can strain families financially.
- The average SSDI benefit is projected to reach about $1,811.02 by December 2025, while the average federal retirement annuity is around $2,126.
- Strategic planning is essential for families to navigate retirement benefits, with case studies showing that many FERS participants may need to work longer due to insufficient savings.
- Long-term planning should include budgeting for healthcare costs and exploring supplemental insurance options to enhance economic security for families relying on SSDI.
- Customised financial strategies, such as those provided by Bright Advisers, can help families optimise their financial potential and secure their children’s future.
Introduction
Imagine feeling overwhelmed by the complexities of securing your family’s financial future. Navigating the intricacies of retirement and disability benefits can be daunting for young parents. It’s important to understand how FERS and SSDI can fit into your family’s financial plan. As you weigh your options, knowing the eligibility requirements and financial implications of both FERS and SSDI becomes crucial. How can you weave these benefits into a plan that brings peace of mind for your family?
Understand FERS Regular Retirement and SSDI
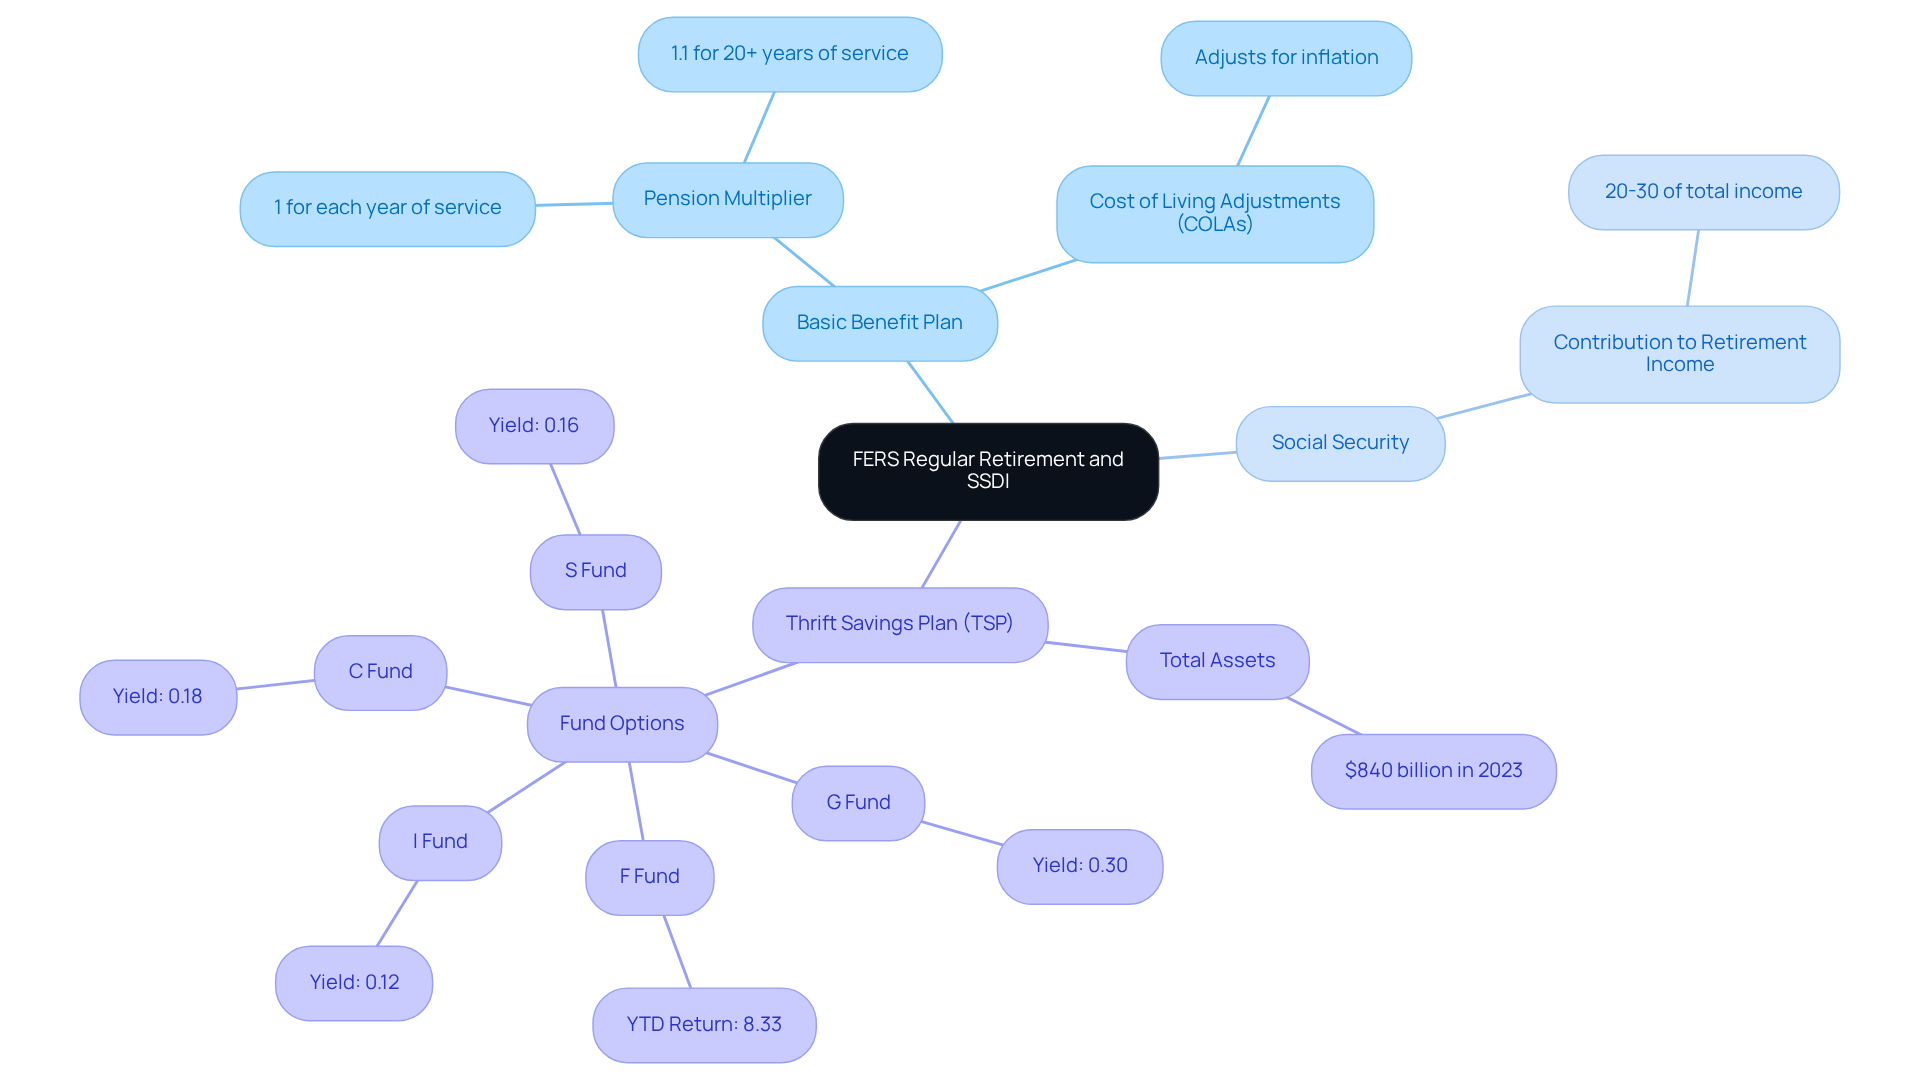
Imagine feeling secure about your family’s future, knowing you have a solid retirement plan in place. The Federal Employees Retirement System, which includes FERS regular retirement and SSDI, offers a comprehensive retirement plan for federal workers, helping you secure your family’s future through three key sources:
- Basic Benefit Plan
- Social Security
- Thrift Savings Plan (TSP)
This structure is designed to provide a reliable income stream throughout retirement, which is essential for families aiming for long-term financial stability.
In 2026, families will find that FERS regular retirement and SSDI benefits can truly make a difference in their financial journey. Employees who retire at age 62 or later with at least 20 years of service receive a pension multiplier of 1.1%, enhancing their retirement income. Plus, federal employee retirement system pensions are adjusted for inflation through Cost of Living Adjustments (COLAs), ensuring that retirees maintain their purchasing power over time.
The TSP, an essential part of the retirement system, had total assets of approximately $840 billion in 2023, with various fund options yielding different returns. For instance, the TSP G Fund yielded 0.30%, while the F Fund had a year-to-date return of 8.33%. These investment options allow federal employees to grow their retirement savings effectively.
Understanding FERS regular retirement and SSDI is vital for young parents, as it significantly contributes to ensuring your family’s financial security and peace of mind. For example, efficient estate planning can safeguard a spouse’s inheritance from estate tax, allowing families to manage their wealth according to their desires. Additionally, the ability to choose survivor benefits for partners married after retirement offers extra economic stability, which is essential for families navigating the complexities of retirement planning.
By understanding these benefits, you can build a strong financial foundation for your family, ensuring a brighter future together.
Compare Eligibility Requirements for FERS and SSDI
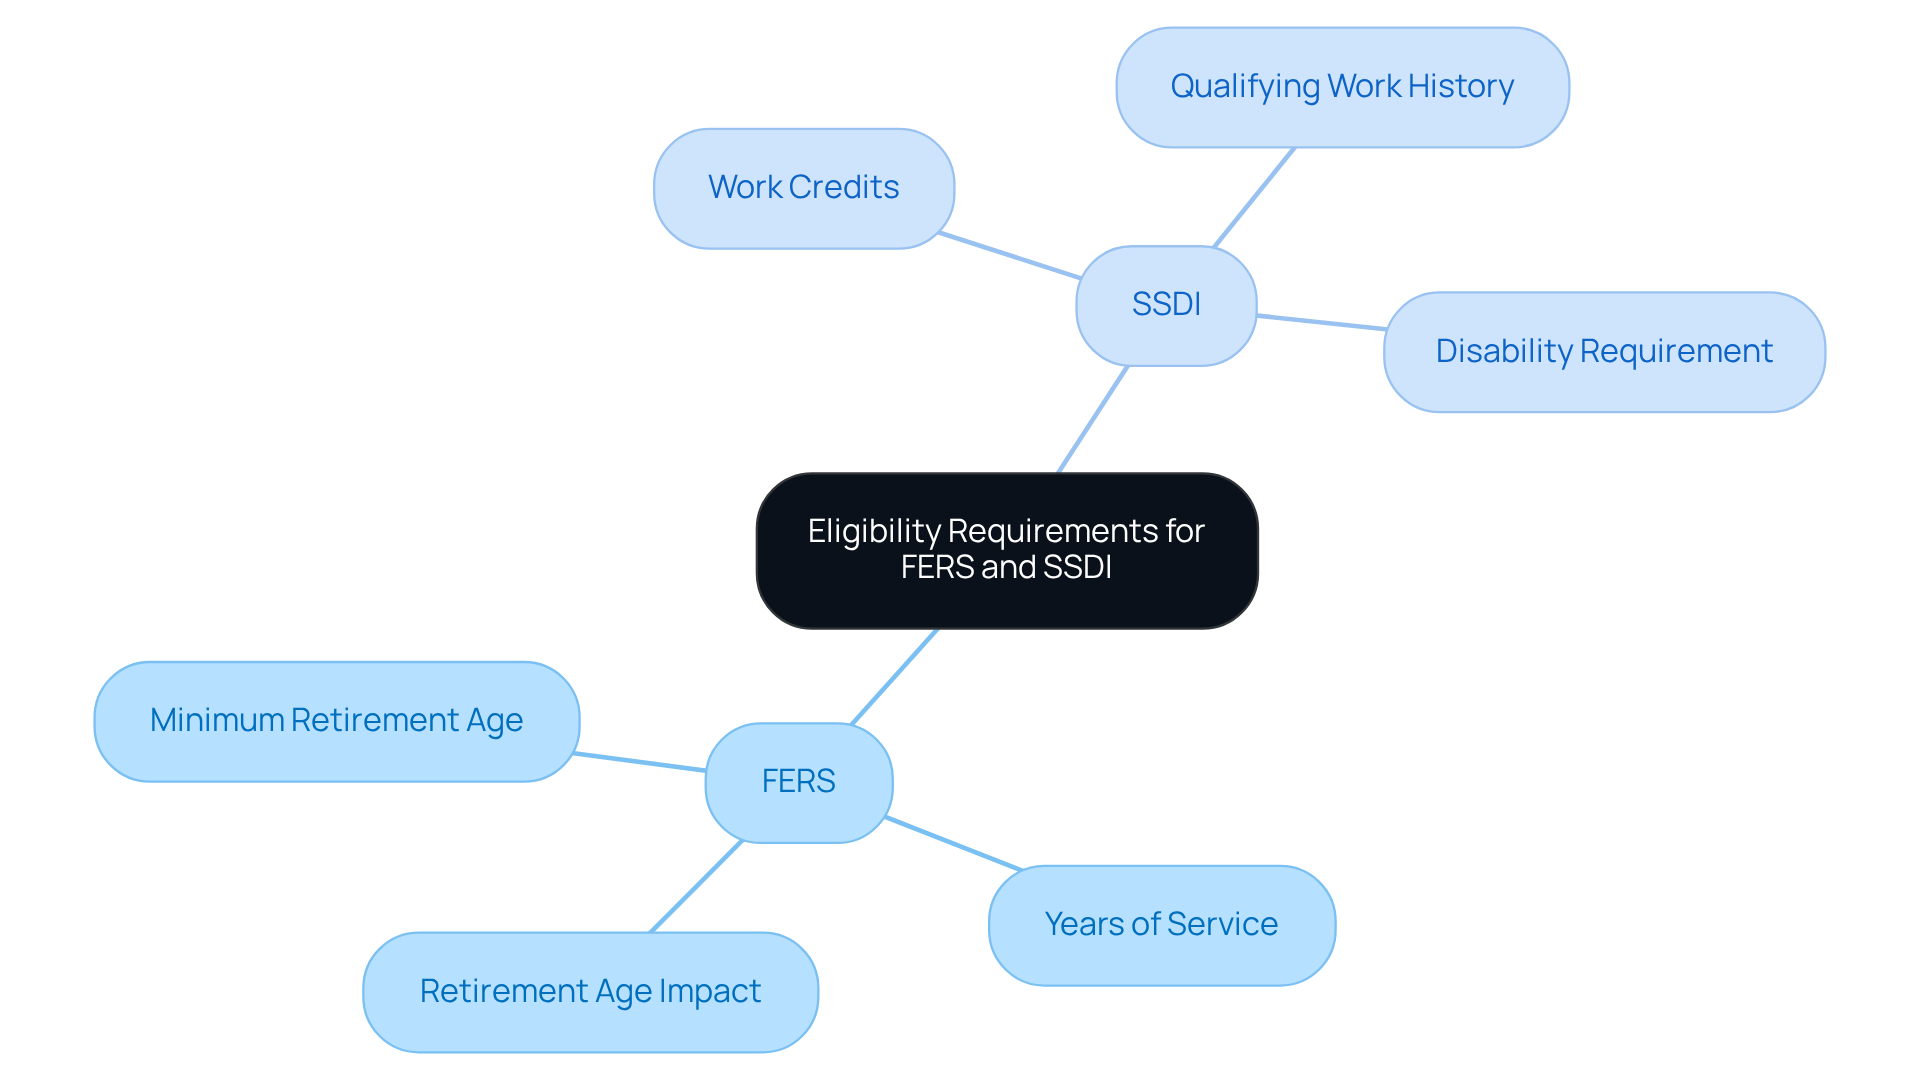
Imagine trying to plan for your family’s future while juggling the complexities of FERS regular retirement and SSDI benefits. To qualify for FERS, you usually need at least five years of service and must reach the Minimum Retirement Age (MRA) to enjoy full benefits. For instance, if a federal worker retires at the MRA with at least 10 years of service, they can access entitlements, though these may be reduced if they retire before age 62. Picture this: in FY2022, most federal employees were retiring at around 62 years old, after dedicating over 25 years to their careers. This paints a typical picture of retirees under this system.
On the other hand, eligibility for Social Security Disability Insurance (SSDI) requires a qualifying work history, typically needing 40 work credits, with 20 earned in the last 10 years. Applicants must also show they have a severe disability that prevents them from working. As of April 2024, about 7.3 million individuals received SSDI assistance, highlighting how crucial this program is for those unable to work due to health issues.
It’s important for young parents to understand these eligibility criteria, as it directly impacts their access to benefits and guides their planning strategies. Navigating the maze of FERS regular retirement and SSDI benefits can feel overwhelming, especially when you’re trying to secure your family’s future. Not knowing this could mean missing out on vital support that can lighten your family’s financial load. Understanding these benefits can be the key to unlocking a more secure future for your family.
Evaluate Financial Benefits and Drawbacks of Each Option
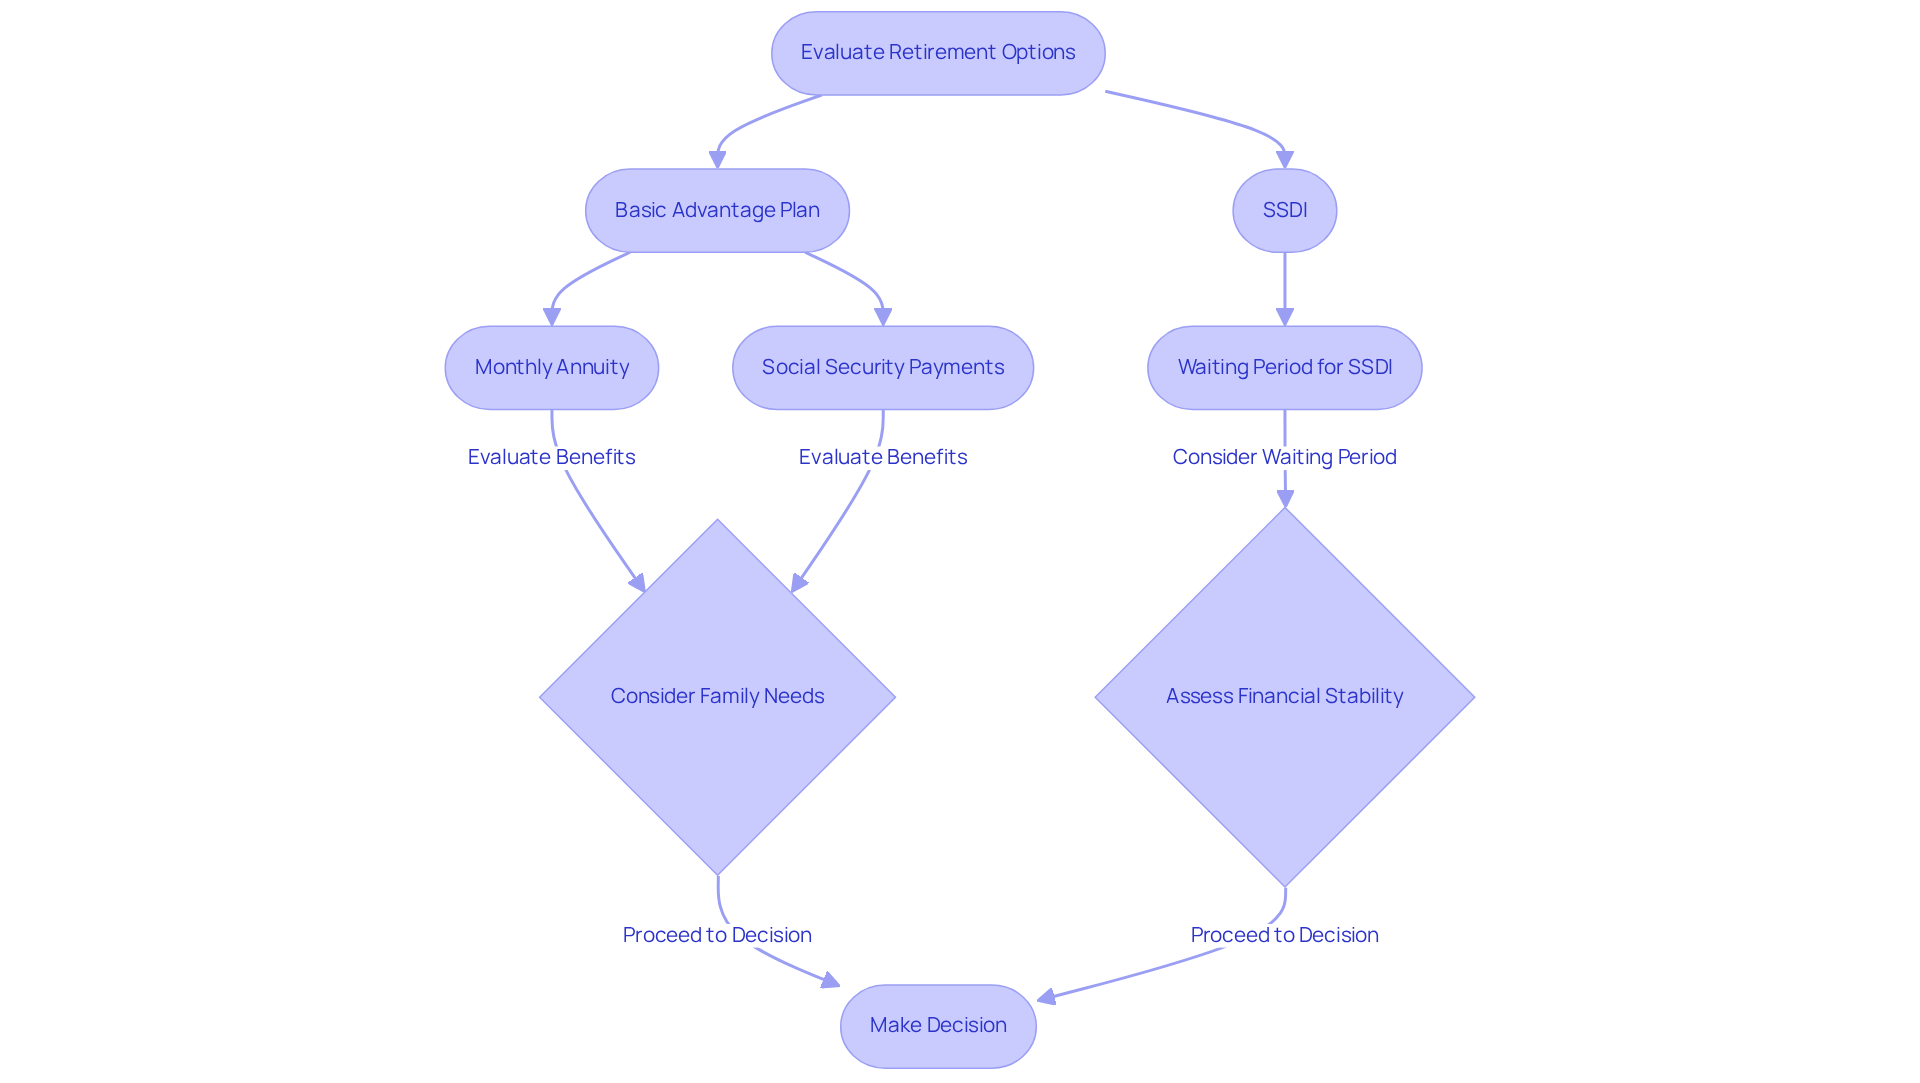
Imagine navigating the complexities of retirement planning while trying to secure a stable future for your family. The retirement system can be a reliable source of income, especially for families like yours who are striving for financial stability. The Basic Advantage Plan offers a monthly annuity based on your salary and years of service, which can be boosted by Social Security payments and the Thrift Savings Plan (TSP). Many families may find themselves confused about which option truly meets their needs, as the advantages of FERS regular retirement and SSDI may not equal the greater payments accessible through Social Security Disability Insurance for individuals with substantial disabilities.
On the other hand, SSDI payments can be quite generous, sometimes even more than what you’d get from FERS regular retirement and SSDI. These payments are based on your average lifetime earnings, making them beneficial for households with a strong income history. But SSDI does have a five-month waiting period before support kicks in, which can put financial strain on families needing help right away.
Understanding these financial options is key for parents like you to make choices that fit your family’s goals. For instance, the average monthly benefit from SSDI has shown a consistent increase, reaching approximately $1,811.02 by December 2025, reflecting adjustments for inflation and economic conditions. In comparison, the average monthly annuity for federal retirees stands at about $2,126, highlighting the need for families to assess their specific circumstances when selecting between these options.
Without careful planning, families might face unexpected challenges that could impact their financial future. Case studies indicate that approximately 30-35% of FERS participants are on track to replace 75% of their income at age 62, while many others may need to work longer or accept reduced income due to insufficient savings. This underscores the importance of strategic planning in managing the complexities of retirement benefits and ensuring economic security for future generations.
For households like Allison and Brian, who sought guidance from Bright Advisers, optimizing their tax situation was essential in maximizing their economic potential. By incorporating tax optimization strategies, such as effective resource allocation and education funding, they secured their children’s future and gained the ability to retire sooner. This success narrative illustrates how customized wealth management approaches can enable households to attain economic stability and independence, allowing them to enjoy more quality time with their loved ones. As you consider your options, remember that support is available to help you make the best choices for your family’s future.
Assess Long-Term Planning Strategies for FERS and SSDI
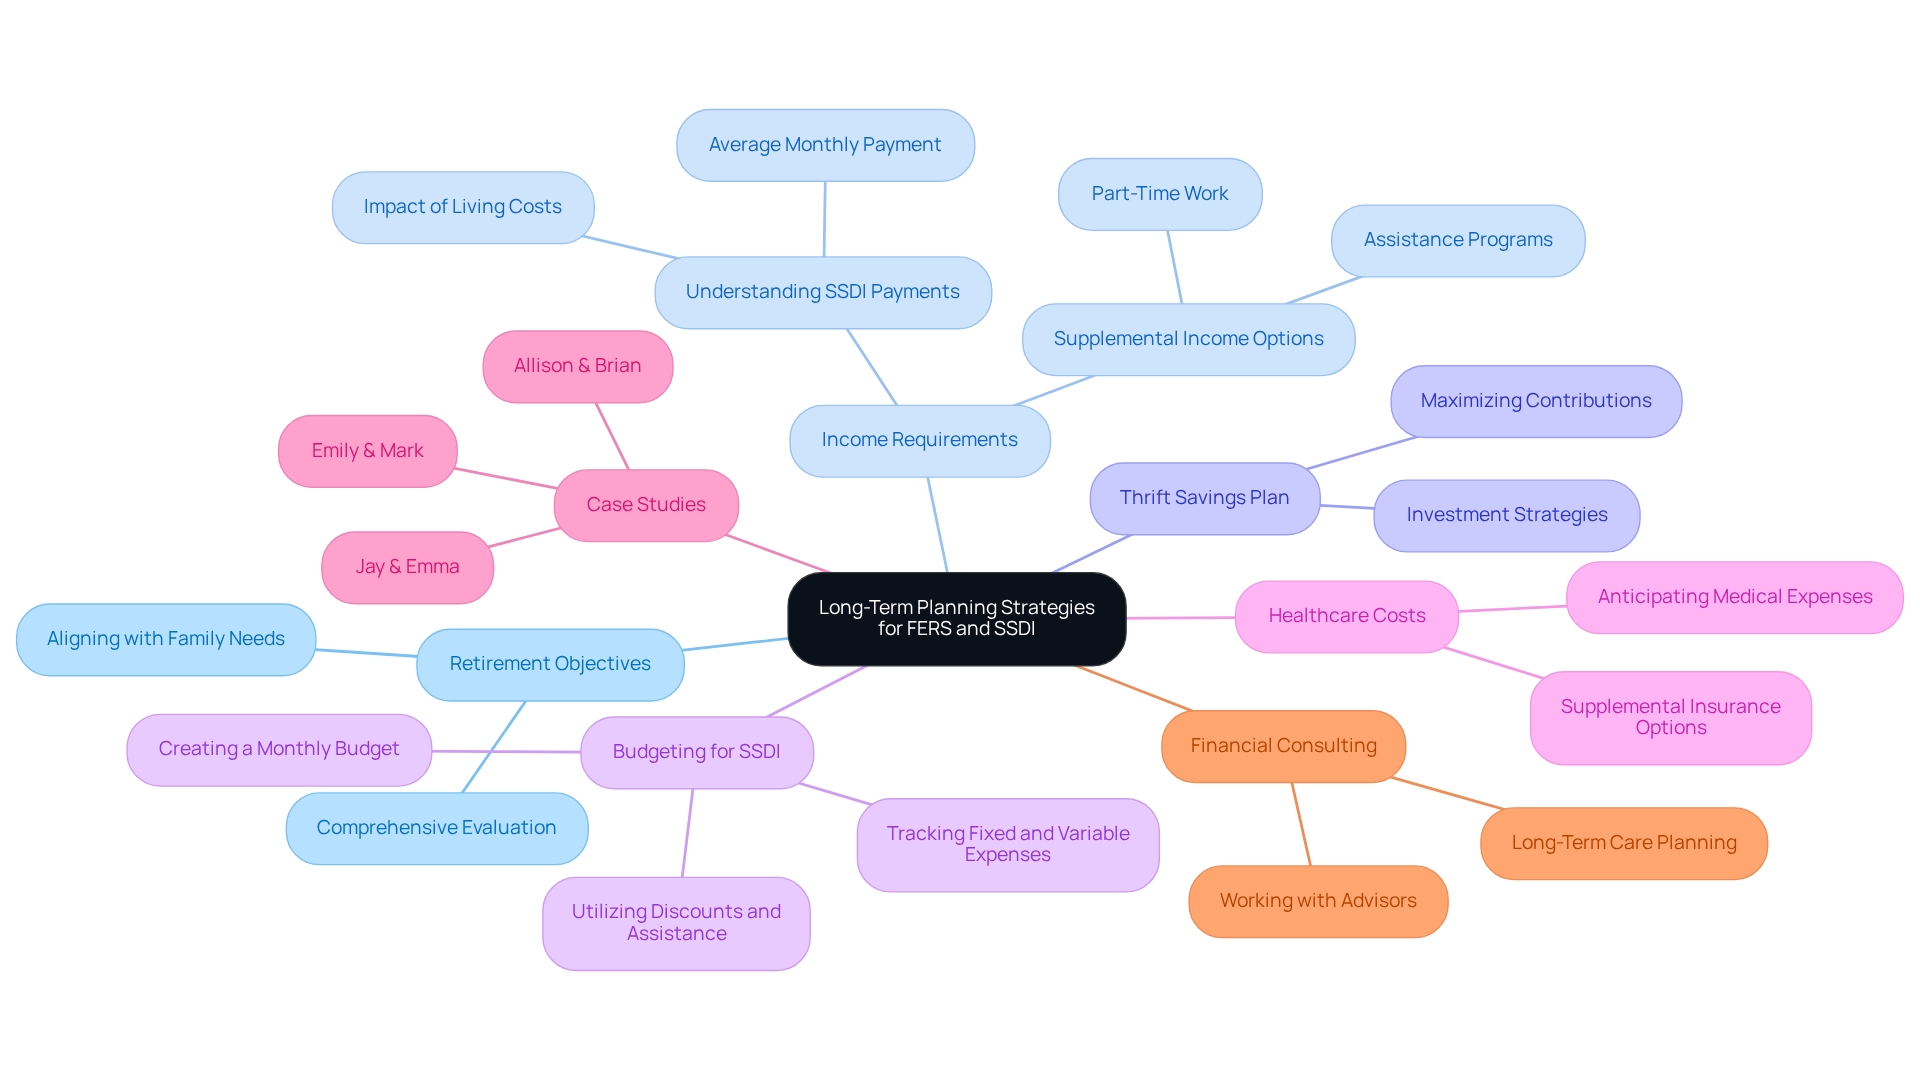
Imagine feeling secure about your family’s financial future, even amidst the uncertainties of retirement and disability benefits, knowing that the plan fers regular retirement and ssdi. For households evaluating the Federal Employees Retirement System, long-term planning should gently include a comprehensive evaluation of retirement objectives, possible income requirements, and approaches to enhance advantages from the Thrift Savings Plan. Partnering with a caring financial consultant can help you craft a retirement plan that truly reflects your family’s needs and dreams, giving you peace of mind for the future.
If your family relies on Social Security Disability Insurance (SSDI), it’s essential to focus on budgeting and managing resources to adapt to the changing nature of benefits. Planning for the long-term implications of disability is crucial, including anticipating healthcare costs and potential shifts in family dynamics. Exploring supplemental insurance options and additional resources can further enhance your economic security. By understanding how to efficiently combine fers regular retirement and ssdi into your long-term planning, you can create a more secure economic base for your children.
Case studies demonstrate the significance of these strategies: families in regions with lower living expenses, such as Mississippi and Arkansas, often find that SSDI assistance can meet basic needs more efficiently than in high-cost locations like California and New York, where extra support is often required. Moreover, families using FERS can benefit from organized financial planning, which has been shown to significantly decrease consumer debt, enabling a more secure retirement. For example, Allison and Brian, a couple in their late forties, sought guidance from Bright Advisers to maximize their financial potential through strategic tax planning. Despite their substantial incomes, they were unaware of the financial opportunities they were missing due to inadequate tax planning. With Bright Advisers’ support, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. Other families, such as Jay & Emma and Emily & Mark, have also thrived with customized financial strategies that align with their unique goals. By adopting these long-term planning strategies, families can navigate the complexities of financial management with greater confidence.
With the right guidance, you can build a financial foundation that not only supports your family today but also paves the way for a brighter tomorrow.
Conclusion
Imagine trying to secure your family’s future while navigating the complexities of FERS and SSDI. Understanding the differences between these two options can feel overwhelming, especially when each has its own set of rules and benefits. Both FERS and SSDI offer unique advantages that can significantly impact your long-term planning. When families understand these differences, they can confidently choose the path that best supports their loved ones.
Throughout this article, we’ve explored the eligibility criteria for both FERS and SSDI, emphasizing how each program works. FERS provides a structured retirement plan with benefits that can be enhanced through the Thrift Savings Plan, while SSDI offers critical support for those unable to work due to disabilities. It’s essential to consider the financial implications of each option, as careful planning can help maximize benefits and avoid potential pitfalls.
Navigating the world of FERS and SSDI can feel like a daunting journey for families. Working with a caring financial advisor can help families craft personalized strategies that meet their immediate needs and build a brighter future together. By prioritizing informed decision-making and proactive planning, you can ensure your family is well-equipped to face the challenges ahead and enjoy a fulfilling life together. With the right guidance, you can turn these challenges into stepping stones for a brighter future for your family.
Frequently Asked Questions
What is the Federal Employees Retirement System (FERS)?
The Federal Employees Retirement System (FERS) is a comprehensive retirement plan for federal workers that includes three key sources: the Basic Benefit Plan, Social Security, and the Thrift Savings Plan (TSP).
How does FERS regular retirement benefit federal employees?
FERS regular retirement provides a reliable income stream throughout retirement, which is essential for families aiming for long-term financial stability. Employees who retire at age 62 or later with at least 20 years of service receive a pension multiplier of 1.1%, enhancing their retirement income.
What are Cost of Living Adjustments (COLAs) in relation to FERS pensions?
Cost of Living Adjustments (COLAs) are adjustments made to federal employee retirement system pensions to account for inflation, ensuring that retirees maintain their purchasing power over time.
What is the Thrift Savings Plan (TSP) and its significance?
The Thrift Savings Plan (TSP) is an essential part of the retirement system with total assets of approximately $840 billion in 2023. It offers various fund options with different returns, allowing federal employees to grow their retirement savings effectively.
What were the returns of the TSP funds in 2023?
In 2023, the TSP G Fund yielded 0.30%, while the F Fund had a year-to-date return of 8.33%.
Why is understanding FERS regular retirement and SSDI important for young parents?
Understanding FERS regular retirement and SSDI is vital for young parents as it significantly contributes to ensuring their family’s financial security and peace of mind, allowing for effective estate planning and management of wealth.
How can estate planning benefit families under FERS?
Efficient estate planning can safeguard a spouse’s inheritance from estate tax, allowing families to manage their wealth according to their desires and ensuring economic stability.
What options are available for survivor benefits in FERS?
FERS allows for the choice of survivor benefits for partners married after retirement, providing extra economic stability for families navigating retirement planning complexities.
List of Sources
- Understand FERS Regular Retirement and SSDI
- Factors that Affect Your FERS Pension the Most (https://fedweek.com/retirement-financial-planning/factors-that-affect-your-fers-pension-the-most)
- State of Federal Retirement Readiness 2026: 50 Data Points (https://fedtools.com/blog/state-of-federal-retirement-readiness-2026)
- Report: FERS Now Covers 98 Percent of Federal Workforce, Half of Retirees (https://fedweek.com/retirement-financial-planning/report-fers-now-covers-98-percent-of-federal-workforce-half-of-retirees)
- Retirement Statistics (https://opm.gov/retirement-center/retirement-statistics)
- Famous Quotes on Financial Stability and Well-Being – Center for the Advancement of Well-Being (https://wellbeing.gmu.edu/famous-quotes-on-financial-stability-and-well-being)
- Compare Eligibility Requirements for FERS and SSDI
- Understanding the Statistics of Who Receives SSDI: A Comprehensive Overview | Preszler & Bunch (https://preszlerandbunch.com/blog/understanding-the-statistics-of-who-receives-ssdi-a-comprehensive-overview)
- Social Security Disability Insurance (https://cbpp.org/research/social-security/social-security-disability-insurance-0)
- Annual Statistical Report on the Social Security Disability Insurance Program, 2024 (https://ssa.gov/policy/docs/statcomps/di_asr)
- Federal Employees’ Retirement System: Summary of Recent Trends (https://congress.gov/crs-product/98-972)
- Disabled-worker statistics (https://ssa.gov/oact/STATS/dibStat.html)
- Evaluate Financial Benefits and Drawbacks of Each Option
- Q&A – Federal Disability Retirement vs. Social Security Disability | Harris (https://federaldisability.com/qa-federal-disability-retirement-vs-social-security-disability)
- State of Federal Retirement Readiness 2026: 50 Data Points (https://fedtools.com/blog/state-of-federal-retirement-readiness-2026)
- Top Ten Facts about Social Security (https://cbpp.org/research/social-security/top-ten-facts-about-social-security)
- Disabled-worker statistics (https://ssa.gov/oact/STATS/dib-g3.html)
- What Federal Employees With a FERS Pension Are Getting Wrong About Their TSP (https://finance.yahoo.com/markets/options/articles/federal-employees-fers-pension-getting-192740742.html)
- Assess Long-Term Planning Strategies for FERS and SSDI
- Money Management Tips When on SSDI – Disability Support Services (https://dssmd.com/money-management-tips-when-on-ssdi)
- Can You Survive on SSDI Alone? | Disability Advice (https://disabilityadvice.org/guide/can-you-survive-on-ssdi-alone)
- Financial Planning For People With Disabilities: Key Advice (https://farther.com/foundations/financial-planning-for-people-with-disabilities-key-advice)
- The Effect of Government Pensions on Financial Well-Being | Institute (https://tiaa.org/public/institute/publication/2019/effect-government-pensions-financial-well-being)
- Financial Planning Tips For Individuals On SSDI And SSI: Maximizing Benefits & Budgeting Strategies – Trajector Disability (https://trajectordisability.com/financial-planning-tips-for-individuals-on-ssdi-and-ssi-maximizing-benefits-budgeting-strategies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading