

Key Highlights
- W2 executives are employees with fixed salaries, leading to limited control over tax withholdings and benefits.
- Business owners can choose structures like LLCs or S Corporations, allowing for broader tax deductions and savings.
- In 2026, single filers can qualify for a full 20% Qualified Business Income deduction if earnings are below $203,000.
- W2 executives can benefit from employer-sponsored retirement plans, while business owners can deduct a wider range of expenses.
- Tax strategies for W2 executives include maximising contributions to retirement plans and utilising Health Savings Accounts (HSAs).
- Business owners can leverage deductions for operational costs and retirement plans like SEP IRAs or Solo 401(k)s.
- W2 executives face higher tax rates and limited deductions compared to business owners, who enjoy more tax flexibility.
- Understanding these differences is crucial for families to make informed financial decisions and optimise tax planning.
Introduction
Imagine feeling overwhelmed by tax planning, especially when you’re trying to provide the best for your family. Understanding the nuances of tax planning can be daunting, particularly for high-income families balancing W2 income and business ownership. W2 executives often find themselves at the mercy of their employers’ tax strategies, facing limited deductions and higher tax rates. On the other hand, business owners enjoy the flexibility to leverage various structures and deductions to optimize their tax liabilities.
Let’s explore how each group can navigate their unique tax situations, focusing on the distinct tax implications that could significantly impact financial outcomes for high-income families. With the right strategies, families can optimize their tax liabilities and secure a brighter financial future.
Distinguishing W2 Executives from Business Owners in Tax Context
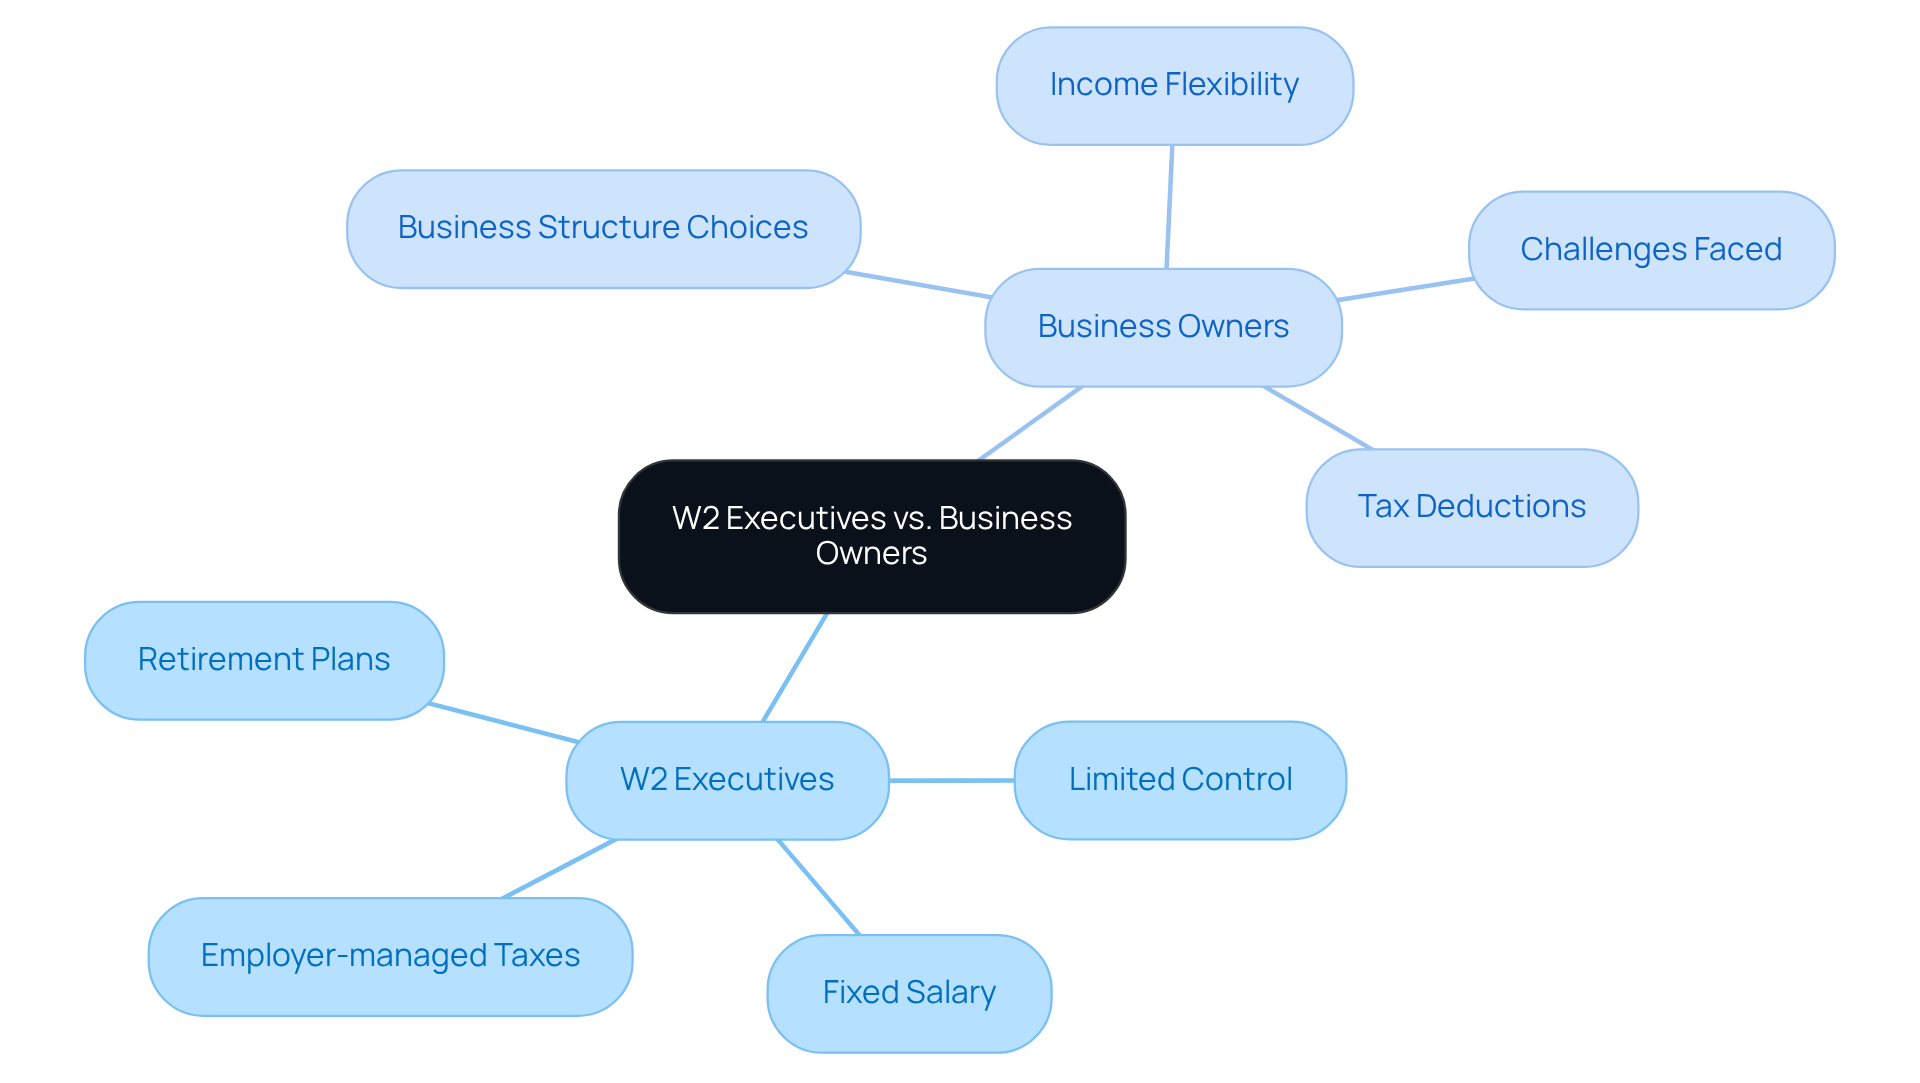
Imagine feeling like your financial future is out of your hands while others have the freedom to shape theirs. W2 executives are employees of corporations who receive a fixed salary and benefits, which highlights the importance of high income W2 tax planning for executives, as their income is subject to standard payroll taxes. Their tax situation is largely managed by their employers, which affects their high income W2 tax planning for executives, leaving them with limited control over tax withholdings and benefits.
On the other hand, entrepreneurs have the freedom to run their own businesses, allowing them to choose structures like LLCs or S Corporations that can help lower their taxes. This difference can really impact how much you can save on taxes, which is important for your family’s financial health. For instance, while W2 executives may benefit from employer-sponsored retirement plans, business owners can deduct a broader range of business expenses, including health insurance premiums and retirement contributions.
In 2026, single filers can qualify for a full 20% Qualified Business Income deduction if their earnings are below $203,000, while married couples filing jointly can qualify if their earnings are below $406,000. But keep in mind, some income types, like W-2 wages and capital gains, don’t qualify for QBI, which can limit high income W2 tax planning for executives’ benefits.
Plus, the average small business owner makes about $69,647 a year, which shows the financial landscape they navigate. This flexibility can mean big tax savings for business owners, but it also comes with its own set of challenges that can feel overwhelming. In fact, 70% of small business owners have made sacrifices for their business, underscoring the complexities they face in managing their finances.
Understanding these differences can help you make informed decisions that support your family’s financial well-being.
Tax Strategies for W2 Executives: Maximizing Deductions and Benefits
Navigating the world of taxes can feel overwhelming, especially for families trying to secure their financial future. As a busy parent, you might wonder how to make the most of your tax situation while juggling family responsibilities.
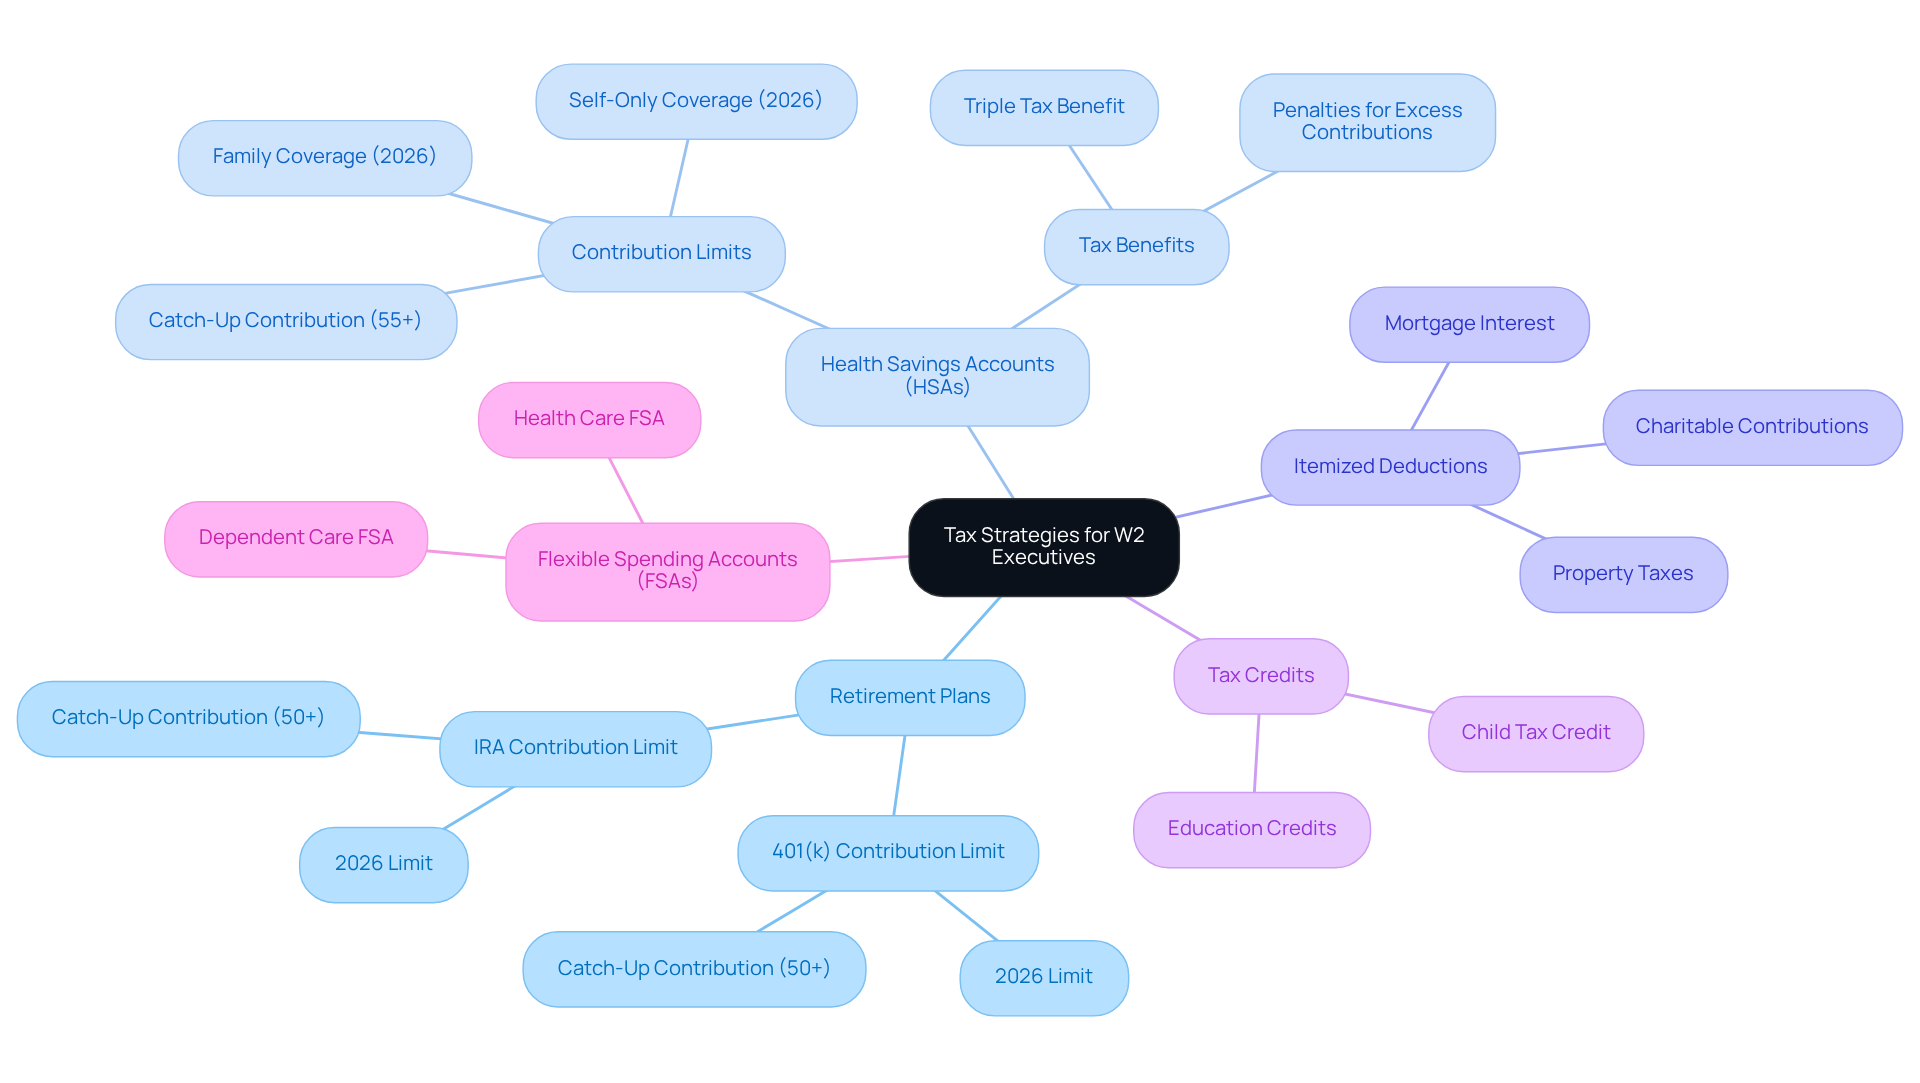
Imagine being able to secure your family’s future while also reducing your taxable income. Contributing to employer-sponsored retirement plans, like 401(k)s, is a great way to do just that. For 2026, the contribution limit is set at $24,500, with an additional catch-up contribution of $8,000 available for those aged 50 and older.
Have you heard about Health Savings Accounts (HSAs)? They’re a fantastic way to save for medical expenses while enjoying tax benefits that can help your family budget better. For 2026, the contribution limits are $4,400 for self-only coverage and $8,750 for family coverage, with an additional $1,000 catch-up contribution for individuals aged 55 and older. Just be mindful of potential penalties for excess contributions, which can incur a 6% excise tax if not corrected before the tax filing deadline.
It’s also worth considering itemizing deductions for mortgage interest, property taxes, and charitable contributions, especially if these exceed the standard deduction. This approach can lead to substantial tax savings, giving you more resources for your family.
Exploring available tax credits, like the Child Tax Credit or education credits, can further reduce your tax liabilities. These credits directly lower the amount of tax owed, making them valuable tools for tax planning.
Utilizing Flexible Spending Accounts (FSAs) for dependent care or medical expenses can provide additional tax savings. FSAs enable you to set aside pre-tax funds for eligible expenses, effectively lowering your taxable amounts.
By embracing these strategies, you can feel more confident in your financial decisions, knowing you’re doing what’s best for your family. For instance, a case study showed that an executive who maximized their 401(k) contributions and utilized an HSA saved over $10,000 in taxes over a three-year period, illustrating the significant impact of high income w2 tax planning for executives. Understanding these options is crucial for families aiming to navigate the complexities of tax obligations while securing their financial future.
Tax Strategies for Business Owners: Leveraging Business Structures for Savings
Imagine feeling confident about your business finances while ensuring your family’s future is secure. Business owners can implement various tax strategies to achieve significant savings, including:
-
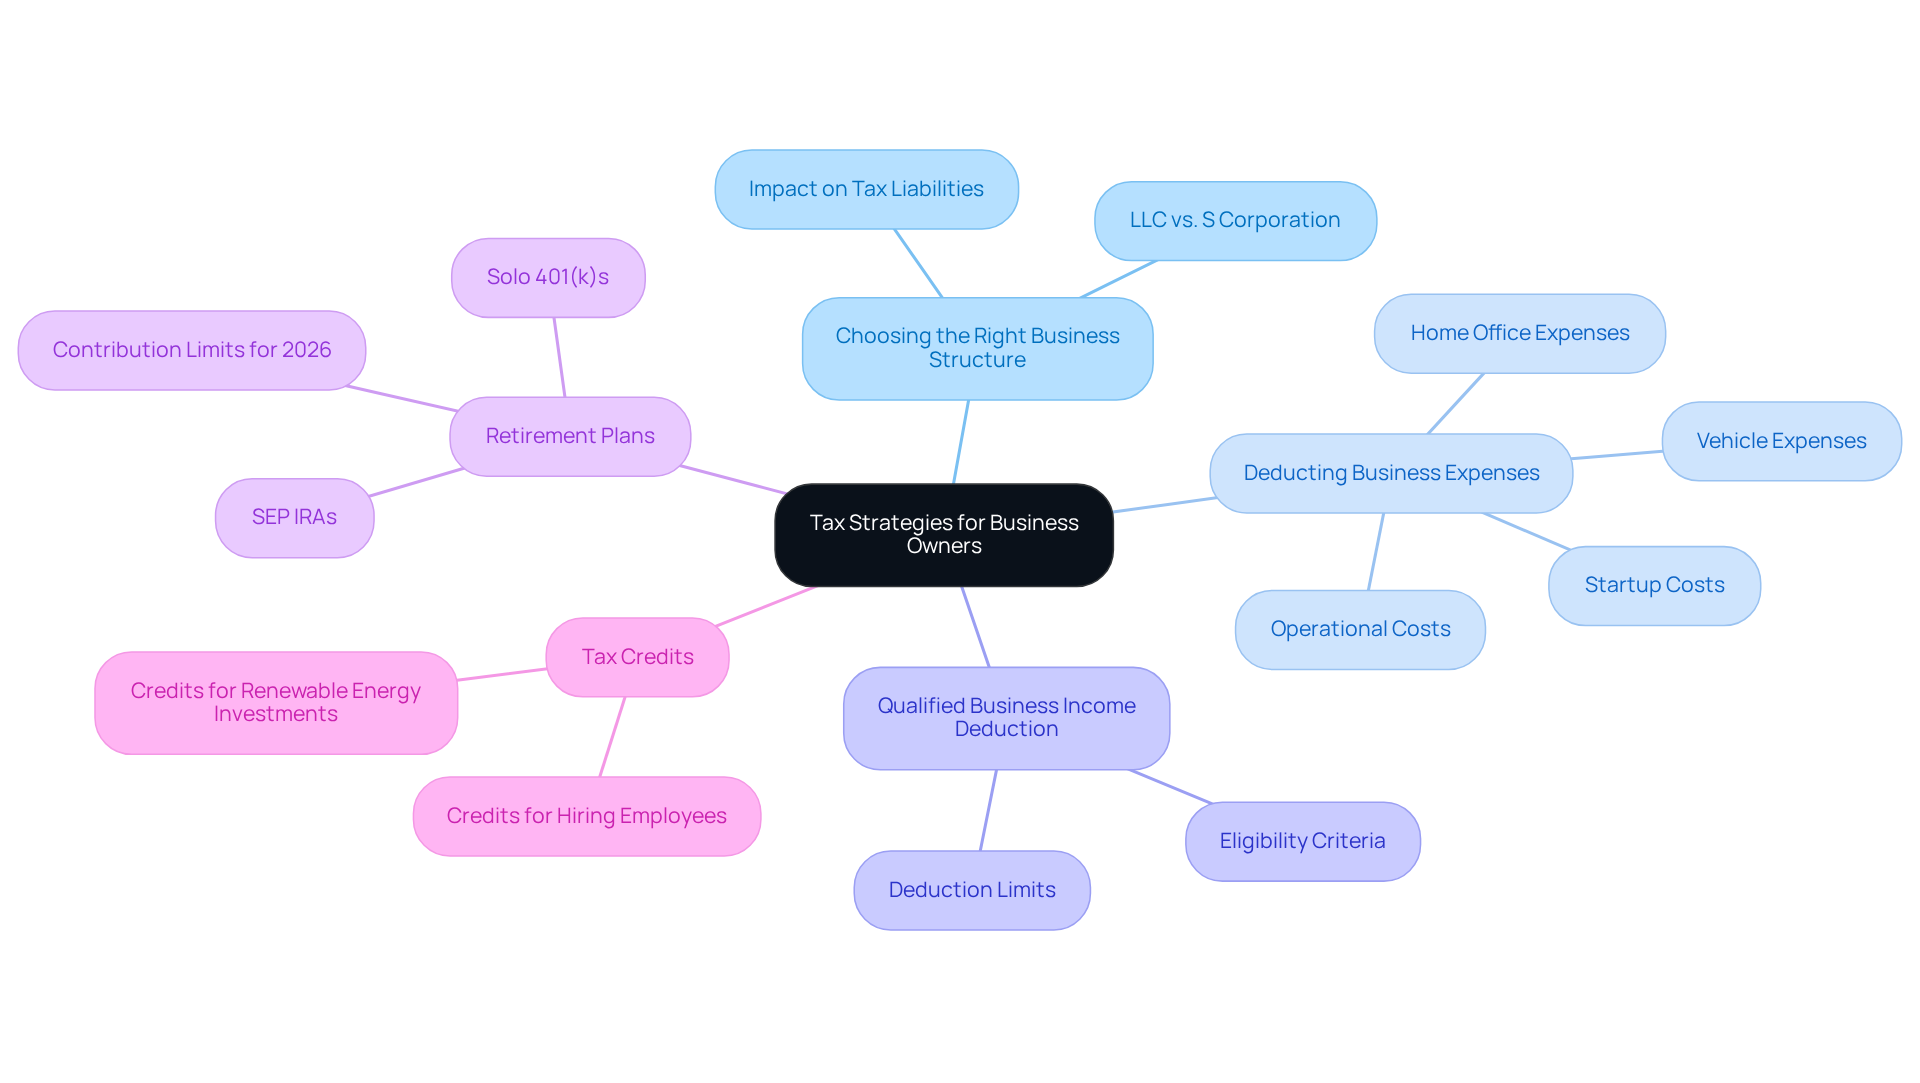
Choosing the Right Business Structure: Selecting an appropriate business structure, like an LLC or S Corporation, can greatly influence your tax liabilities. For instance, S Corporations allow you to pay yourself a reasonable salary while taking additional profits as distributions, which are taxed at a lower rate.
-
Deducting Business Expenses: You can deduct a wide range of expenses, including operational costs, home office expenses, and vehicle expenses. This can lead to a substantial reduction in your taxable income. For example, companies can deduct up to 100% of expenses associated with goods sold, including raw materials and direct labor. Plus, if you incurred less than $50,000 in startup and organizational expenses, you can deduct up to $10,000 right away, which is especially helpful for new entrepreneurs.
-
Qualified Business Income Deduction: If you’re eligible, you can take advantage of a 20% deduction on qualified earnings, further reducing your tax liability. In 2026, you can deduct this amount if you earn less than $201,751 in taxable income, making it essential to understand your eligibility.
-
Retirement Plans: Creating retirement plans like SEP IRAs or Solo 401(k)s allows you to contribute significantly more than conventional employee plans, boosting your long-term savings while offering immediate tax advantages. In 2026, you can contribute up to $24,500 to a 401(k) and $17,000 to a SIMPLE IRA, which can greatly enhance your financial planning.
-
Tax Credits: Exploring available tax credits, such as those for hiring employees or investing in renewable energy, can yield additional savings. For example, organizations can receive tax credits for offering paid family and medical leave, which not only decreases tax obligations but also promotes employee well-being.
Navigating tax laws can feel daunting, especially for new business owners. But by utilizing these strategies, you can manage your taxes better, allowing you to keep more of what you earn for your family’s needs. It’s crucial to keep track of your deductions; it protects you from audits and helps you stay compliant with IRS regulations. High-income families like Allison and Brian can benefit from high income W2 tax planning for executives through Bright Advisers to navigate these complexities and optimize their financial resources. Together, we can ensure you’re not missing out on valuable opportunities for wealth accumulation. Bright Advisers offers transparent, all-inclusive fee structures with no hidden fees, commissions, or trade fees, ensuring you can make informed decisions about your financial future. With the right strategies, you can not only protect your business but also create a brighter future for your loved ones.
Comparative Analysis: Tax Planning Pros and Cons for Executives vs. Business Owners
Navigating the world of taxes can feel overwhelming, especially when you’re trying to secure your family’s financial future. Let’s explore the differences between high income W2 tax planning for executives and business owners, so you can make informed choices that benefit your loved ones.
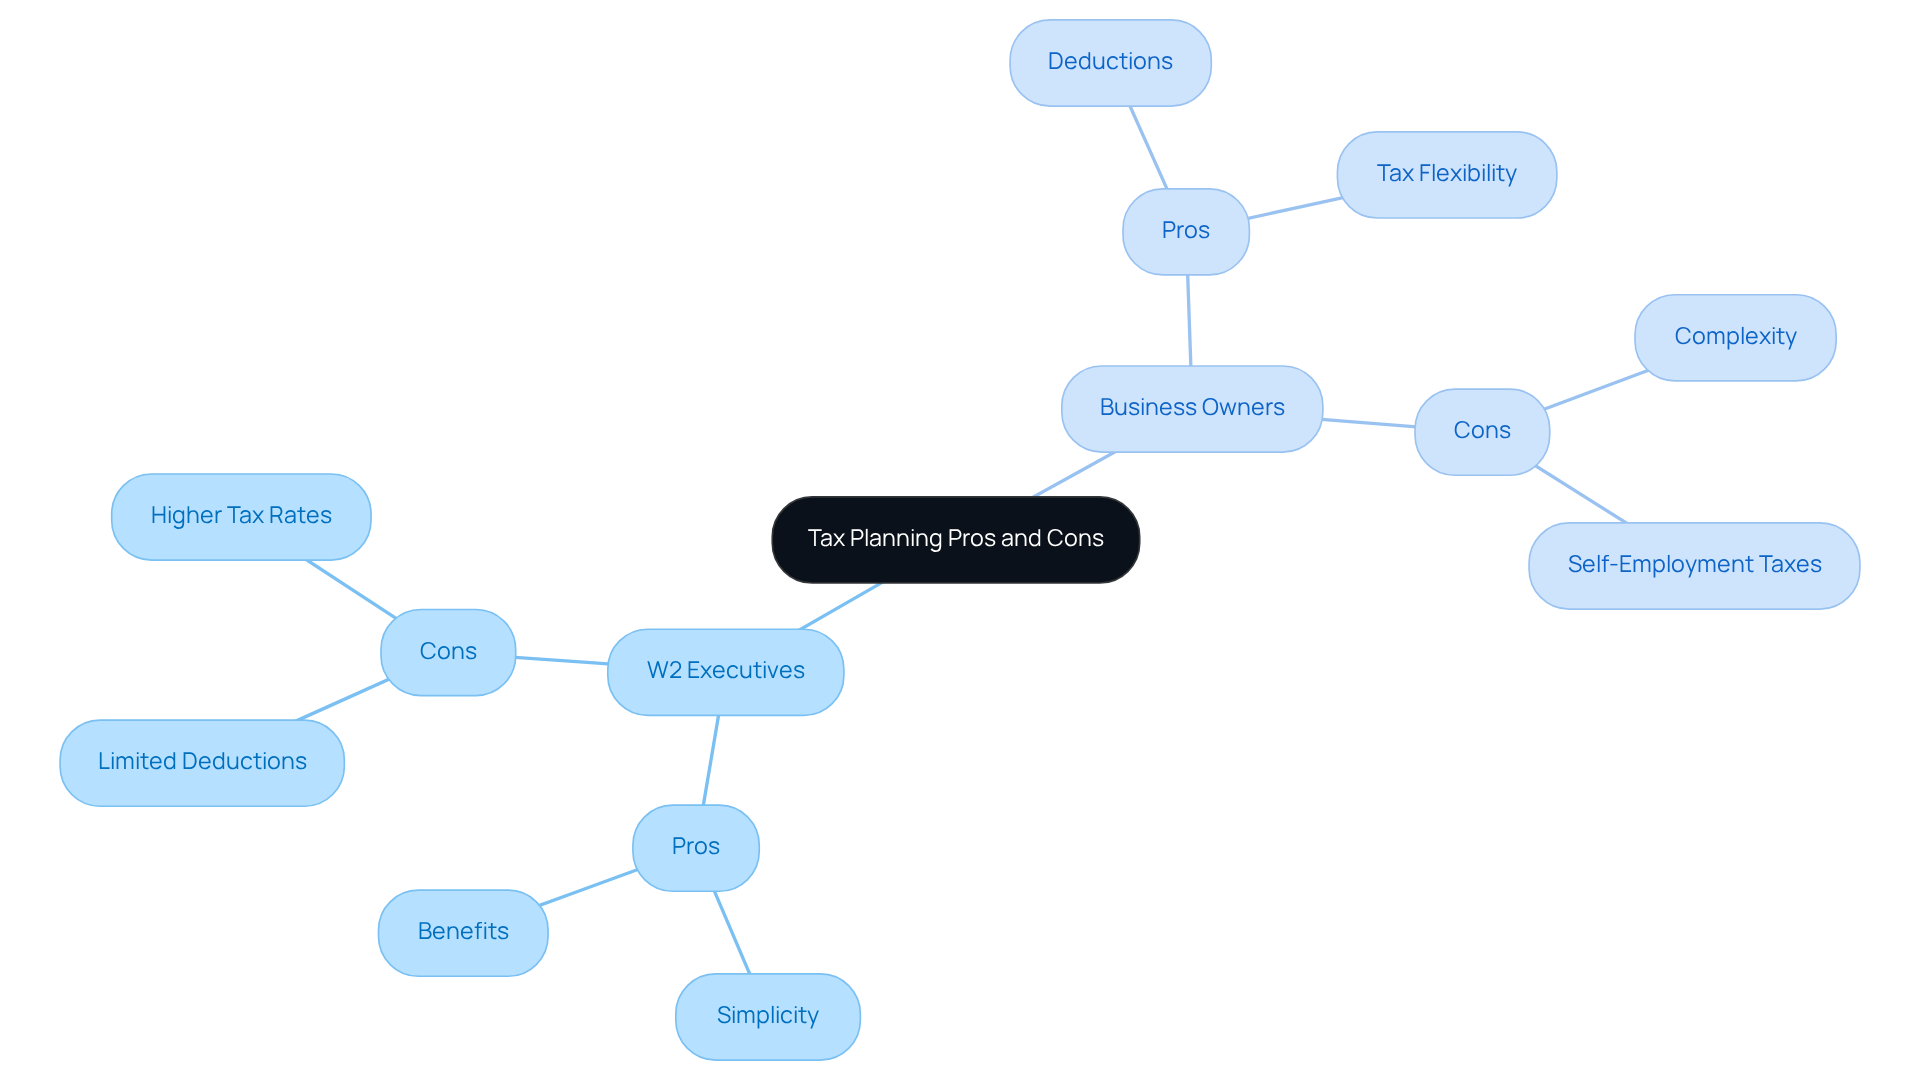
W2 Executives
Pros:
- Simplicity: With tax withholding managed by your employer, the tax filing process becomes much easier.
- Benefits: Access to employer-sponsored benefits, like retirement plans and health insurance, can offer significant tax advantages that support your family’s needs.
Cons:
- Limited Deductions: Unfortunately, W2 executives have fewer opportunities for deductions compared to business owners, as many personal expenses aren’t deductible.
- Higher Tax Rates: Income is taxed at standard rates, which can be higher than the capital gains rates that entrepreneurs enjoy. For instance, the 2026 tax bracket for single filers at 35% applies to earnings exceeding $640,600.
Business Owners
Pros:
- Deductions: Business owners can deduct a wider range of expenses, including costs directly related to their business, which can significantly lower taxable income and free up funds for family priorities.
- Tax Flexibility: You have greater control over your income and deductions, allowing for more strategic tax planning that aligns with your family’s goals.
Cons:
- Complexity: It’s important to understand that managing your business taxes can feel like a juggling act, with the need for careful record-keeping and compliance with various rules. Additionally, self-employment tax includes 12.4% for Social Security on the first $184,500 of net earnings, which adds to your overall tax burden.
- Self-Employment Taxes: As a business owner, you must pay self-employment taxes, which can increase your overall tax burden.
In summary, while W2 executives enjoy the ease of employer-managed taxes, high income W2 tax planning for executives allows business owners to embrace the freedom to make choices that lead to potential savings and a brighter future for their families. The standard deduction for single filers in 2026 is $16,100, and for married couples filing jointly, it is $32,200. By understanding these differences, you can make informed decisions that truly benefit your family’s financial well-being. Remember, keeping tax returns and supporting documents for at least seven years is essential for compliance and effective planning.
Conclusion
Imagine navigating the complex world of taxes as a busy parent, where every decision impacts your family’s future. W2 executives often find their tax situation feels simpler, with employers handling withholdings, but this simplicity can hide missed opportunities. Yet, this straightforwardness can mean fewer deductions and higher rates, which can be frustrating for families trying to save. On the other hand, business owners have more options for tax savings, but it can feel overwhelming to manage all those responsibilities.
It’s essential to know how to make the most of the tax strategies available to you. Each group faces its own challenges, but together, we can find ways to secure a brighter future for our families. Understanding these differences is key to creating a personalized plan that fits your family’s unique needs. We’re here to help you explore personalized tax planning solutions that make sense for your family. With the right guidance, you can turn tax planning into a powerful tool for securing your family’s dreams.
Frequently Asked Questions
What is the primary difference between W2 executives and business owners in a tax context?
W2 executives are employees of corporations with fixed salaries and benefits, leading to limited control over tax withholdings and benefits. In contrast, business owners have the freedom to run their own businesses and choose structures like LLCs or S Corporations, which can help lower their taxes.
How does high income W2 tax planning differ for executives compared to business owners?
High income W2 tax planning for executives is largely managed by their employers, which limits their control over tax strategies. Business owners can deduct a broader range of business expenses, including health insurance premiums and retirement contributions, allowing for potentially greater tax savings.
What tax benefits can business owners access that W2 executives cannot?
Business owners can deduct various business expenses and may qualify for a 20% Qualified Business Income deduction if their earnings are below certain thresholds. W2 executives, however, are subject to standard payroll taxes and have fewer options for tax deductions.
What are the income thresholds for the Qualified Business Income deduction in 2026?
In 2026, single filers can qualify for a full 20% Qualified Business Income deduction if their earnings are below $203,000, while married couples filing jointly can qualify if their earnings are below $406,000.
What challenges do small business owners face compared to W2 executives?
Small business owners navigate a complex financial landscape and often make sacrifices for their business, with 70% reporting such sacrifices. This complexity can lead to overwhelming challenges in managing their finances, despite the potential for tax savings.
Why is understanding the differences between W2 executives and business owners important for financial planning?
Understanding these differences can help individuals make informed decisions that support their family’s financial well-being, allowing them to better navigate tax planning and financial strategies.
List of Sources
- Distinguishing W2 Executives from Business Owners in Tax Context
- 2026 Small Business Revenue Statistics + Tips To Boost Yours – Vena (https://venasolutions.com/blog/small-business-revenue-statistics)
- SOI tax stats: What’s new | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-whats-new)
- 21 tax deductions (write offs) for small businesses in 2026 (https://brex.com/spend-trends/expense-management/small-business-tax-deductions-and-write-offs)
- Tax Deductions LLC Owners Should Know for 2026 | Insureon (https://insureon.com/blog/llc-tax-deductions)
- Business Tax Rates Explained: Structures, Brackets & Real Costs (https://lnbaccounting.com/understanding-business-tax-rates)
- Tax Strategies for W2 Executives: Maximizing Deductions and Benefits
- How Much Can I Contribute to a 401(k) in 2026? (https://epwealth.com/blog/how-much-can-i-contribute-to-a-401k-in-2026)
- HSA contribution limits 2026 and 2027 | Fidelity (https://fidelity.com/learning-center/smart-money/hsa-contribution-limits)
- Maximize Your HSA and Retirement Contributions in 2026 (https://kahnlitwin.com/blogs/tax-blog/maximize-your-hsa-and-retirement-contributions-in-2026)
- 2026 Health Savings Account (https://dartmouth.edu/hr/benefits_compensation/benefits/2026_benefits/hsa.php)
- 401(k) Catch-Up Contributions: Final SECURE 2.0 Rules for Employers (https://employeefiduciary.com/blog/401k-catch-up-contributions)
- Tax Strategies for Business Owners: Leveraging Business Structures for Savings
- 21 tax deductions (write offs) for small businesses in 2026 (https://brex.com/spend-trends/expense-management/small-business-tax-deductions-and-write-offs)
- Small Business Tax Planning: 15 Ways To Save in 2026 (https://paychex.com/articles/payroll-taxes/tax-saving-tips-at-year-end)
- 24 Small-Business Tax Deductions to Know in 2026 – NerdWallet (https://nerdwallet.com/business/taxes/learn/small-business-tax-deductions-guide)
- Small Business Taxes 2026: Complete Guide to Tax Types, Rates & Structures (https://forafinancial.com/blog/small-business/what-taxes-do-small-businesses-pay)
- Business Taxes: How OBBBA Will Impact Business Owners (https://financialplanningassociation.org/learning/publications/journal/NOV25-business-taxes-how-obbba-will-impact-business-owners-OPEN)
- Comparative Analysis: Tax Planning Pros and Cons for Executives vs. Business Owners
- Understanding the 2026 Federal Income Tax Brackets (https://onedigital.com/en-US/articles/understanding-the-2026-federal-income-tax-brackets)
- Business Tax Rates Explained: Structures, Brackets & Real Costs (https://lnbaccounting.com/understanding-business-tax-rates)
- SOI tax stats: What’s new | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-whats-new)
- Tax Strategies To Reduce Taxable Income For High-Income W-2 Earners (https://wcginc.com/blog/tax-strategies-for-high-income-w-2-earners-smart-ways-to-reduce-taxable-income)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading