

Overview
RSUs (Restricted Stock Units) can feel overwhelming, especially when it comes to taxes. When these units vest, they are taxed as ordinary income based on their fair market value. This can significantly impact your overall tax liability, which is something every parent should consider.
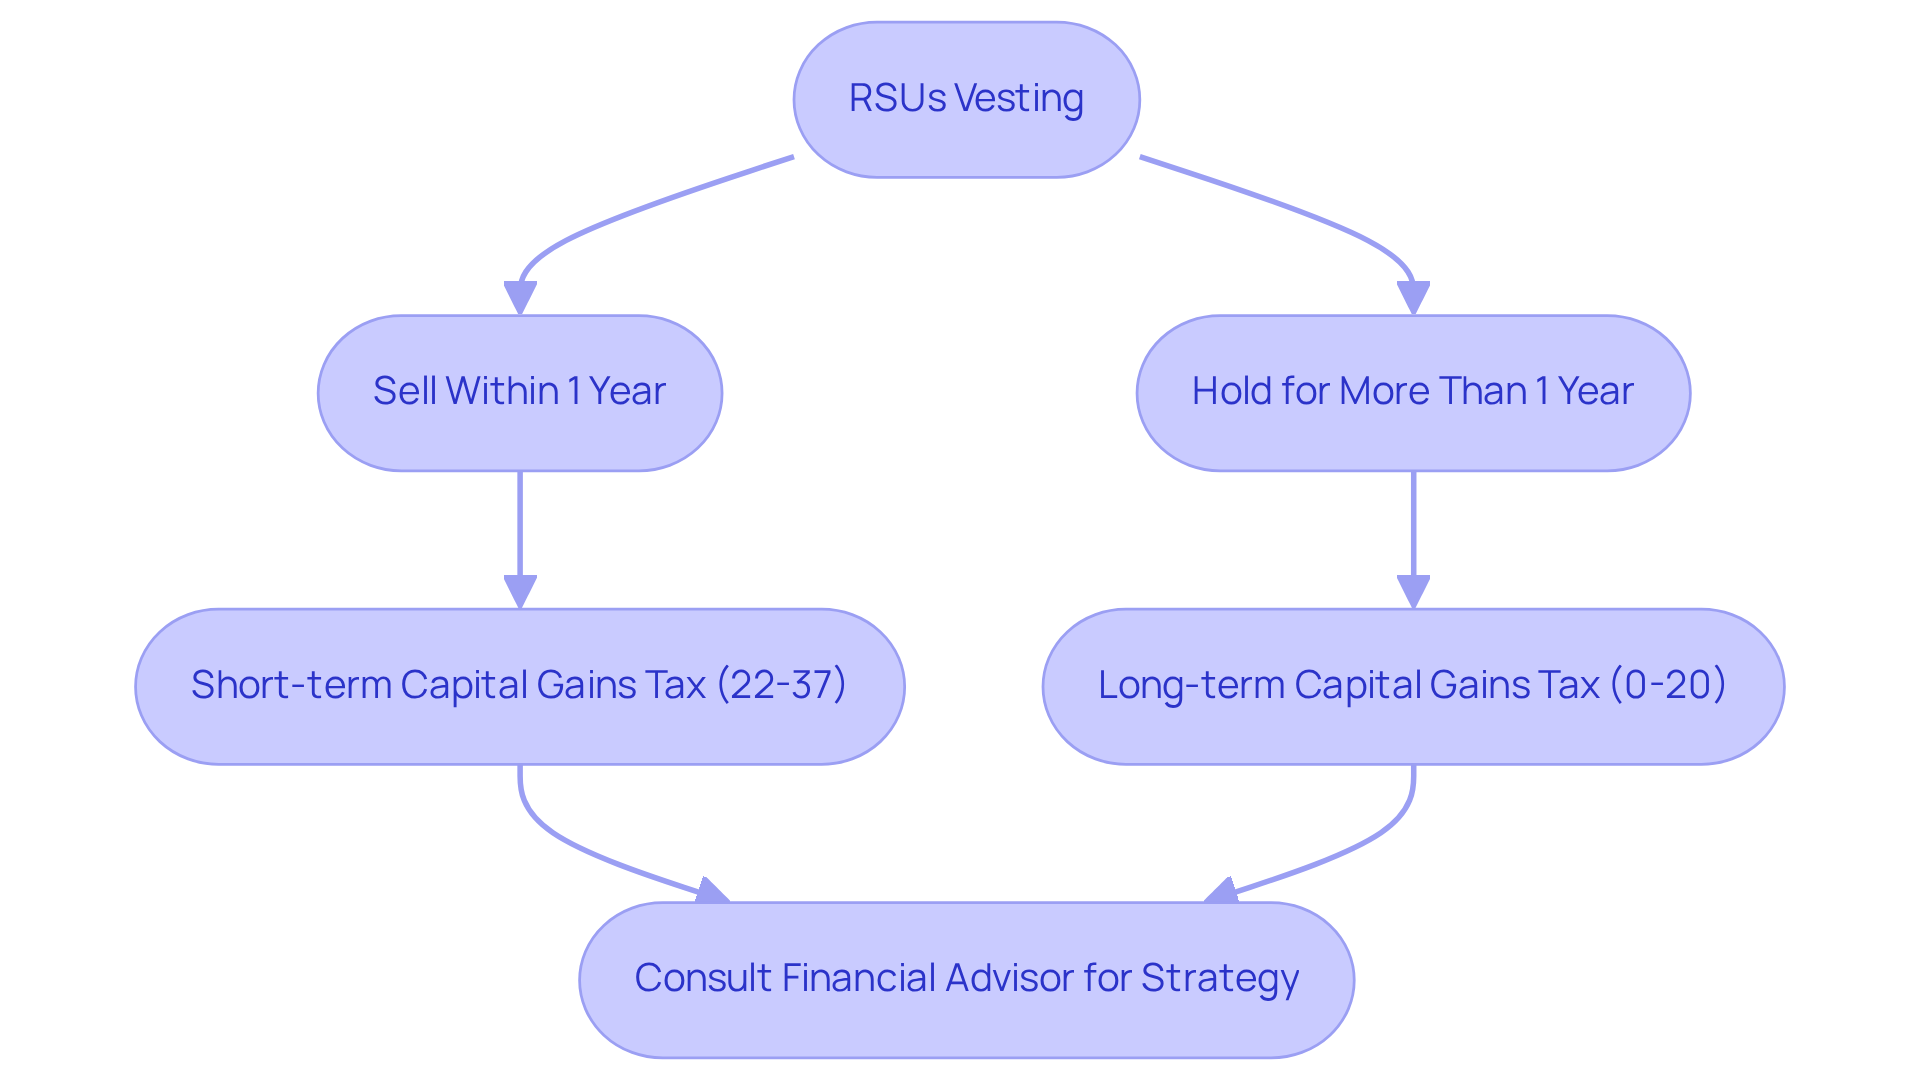
Imagine if you sold your RSUs within a year of vesting. You would incur short-term capital gains tax, which is taxed at ordinary income rates. However, if you hold onto them for over a year, any gains you realize will be subject to a lower long-term capital gains tax. This distinction is crucial and emphasizes the importance of strategic planning to optimize your tax outcomes.
Together, we can navigate this journey of financial planning. By understanding these nuances, you can make informed decisions that align with your family values. Remember, we’re here for you, ready to support you in achieving your financial goals.
Key Highlights:
- RSUs are a form of equity compensation promising shares contingent on meeting criteria, often with a vesting schedule.
- Nearly 40% of employees in tech are expected to receive RSUs by 2025, making them significant for financial planning.
- Upon vesting, RSUs are taxed as ordinary income based on their fair market value, impacting overall tax liability.
- Short-term capital gains tax applies if RSUs are sold within one year post-vesting, while long-term capital gains tax applies otherwise.
- Strategies to optimise RSU tax outcomes include timing sales, adjusting tax withholding, diversification, and utilising tax-advantaged accounts.
- Common mistakes in RSU tax reporting include double-counting income, incorrect cost basis reporting, missing sale reporting, and ignoring state taxes.
- Consulting a financial advisor can help navigate RSU complexities and align strategies with financial goals.
Introduction
Understanding the intricacies of Restricted Stock Units (RSUs) is essential for employees, especially for parents navigating the complexities of family finances. Imagine the peace of mind that comes with grasping these valuable equity compensations, particularly as they become increasingly common in the tech sector. However, it’s important to understand that the implications of their taxation can significantly impact budgeting and long-term financial planning.
How are RSUs taxed when sold? What strategies can families employ to optimize their tax outcomes? These are crucial questions that, when unraveled, can help prevent unexpected tax burdens. Together, we can navigate this journey and empower you to make informed decisions that secure your family’s financial future. Remember, you’re not alone in this; we’re here for you every step of the way.
Define Restricted Stock Units (RSUs)
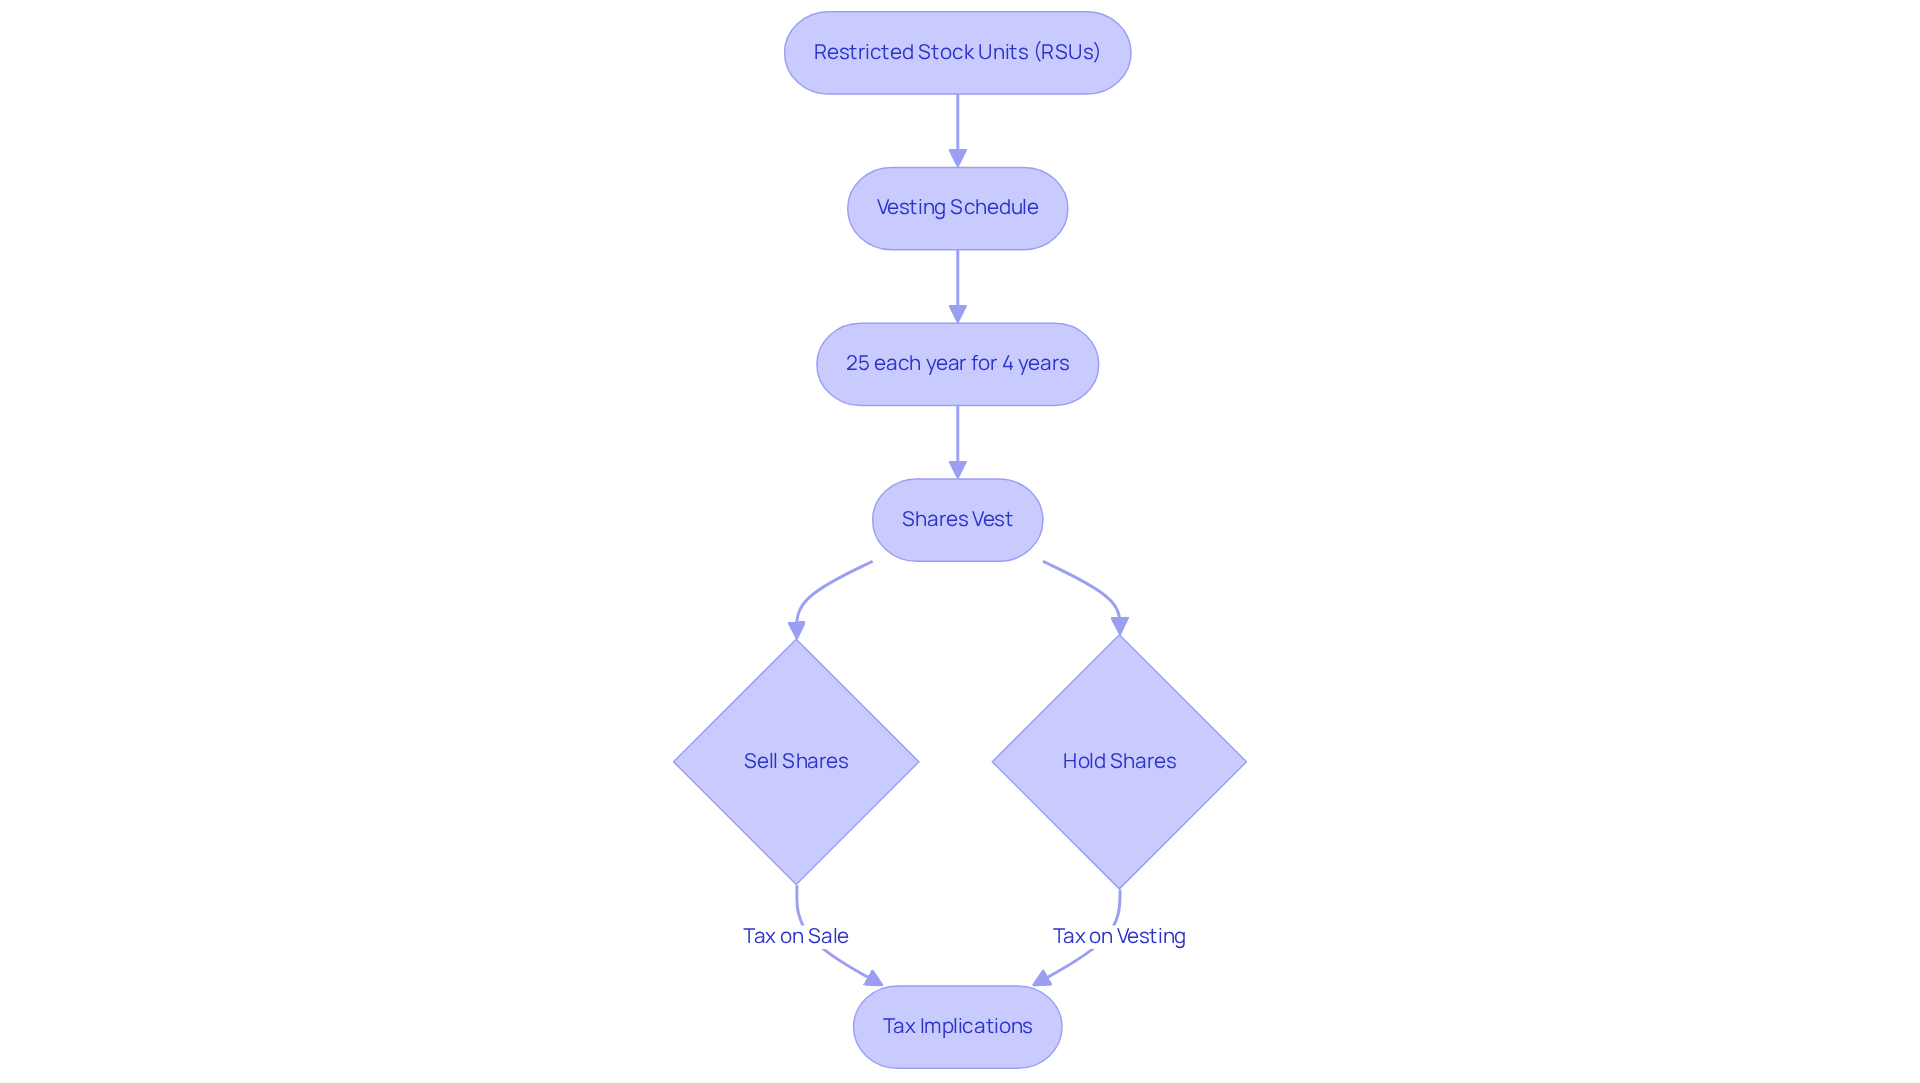
Restricted Stock Units (RSUs) are a valuable form of equity compensation that many employers, particularly in the technology sector, offer. Unlike traditional stock options, RSUs give employees the promise of shares at a future date, contingent upon meeting specific criteria, like waiting periods. Imagine a common vesting schedule where 25% of the shares become available each year over a four-year period. Once these units vest, employees receive actual shares, allowing them the choice to sell or hold on to them, directly linking their value to the company’s stock price.
This connection can make RSUs a crucial part of an employee’s overall compensation, especially as nearly 40% of employees in tech and corporate sectors are expected to receive them by 2025. Understanding how RSUs work is essential for parents, as they can significantly impact budgeting and tax responsibilities. When these shares vest, the fair market value is treated as ordinary income for tax purposes, leading to considerations about how are RSUs taxed when sold, which may affect an employee’s tax bracket.
Being informed about RSUs not only helps in maximizing their benefits but also supports parents in managing the complexities of financial obligations while raising a family. It’s important to consider seeking advice from a financial consultant who can help create a strategy that incorporates RSUs into your overall financial plan. This way, you can be prepared for the tax implications and understand how are RSUs taxed when sold, allowing you to make informed decisions about selling or retaining your shares. Together, we can navigate this journey and ensure your family’s financial future is secure.
Understand Tax Implications When Selling RSUs
When Restricted Stock Units vest, they are taxed as regular income based on their fair market value at that moment. This means the value of the shares is added to your taxable income for the year, which can significantly impact your overall tax liability. Imagine if you obtain 300 RSUs priced at $10 each when they become available; this would contribute $3,000 to your taxable income, possibly moving you into a higher tax bracket.
If you decide to sell the shares after they vest, you should consider how RSUs are taxed when sold, as any profit made from the sale is subject to capital gains tax. It’s important to understand that the rate at which you are taxed depends on how long you hold the shares after vesting:
- Short-term capital gains apply if you sell the shares within one year of vesting, taxed at your ordinary income rate, which can range from 22% to 37% depending on your total income.
- Long-term capital gains apply if you hold the shares for more than one year, typically taxed at a lower rate, often between 0% and 20%, depending on your income level.
Comprehending these tax consequences is essential for parents, as it aids in preventing unforeseen tax charges and enables improved budget planning. For instance, families like Jay and Emma, who sought advice from Bright Advisers, benefited from strategic selling of restricted stock units. They were advised to time their sales wisely, reducing tax obligations while aligning with their broader monetary objectives.
As one investment consultant observes, “Selecting a regulated adviser who is clear about their fees can assist you in avoiding unnecessary charges and ensuring you obtain impartial, effective advice for your stock options and retirement planning.” Consulting with a financial advisor can provide tailored insights into optimizing the timing of sales and understanding the nuances of capital gains tax. Together, we can navigate this journey, ultimately supporting a more secure financial future for your children.
Implement Strategies to Optimize RSU Tax Outcomes
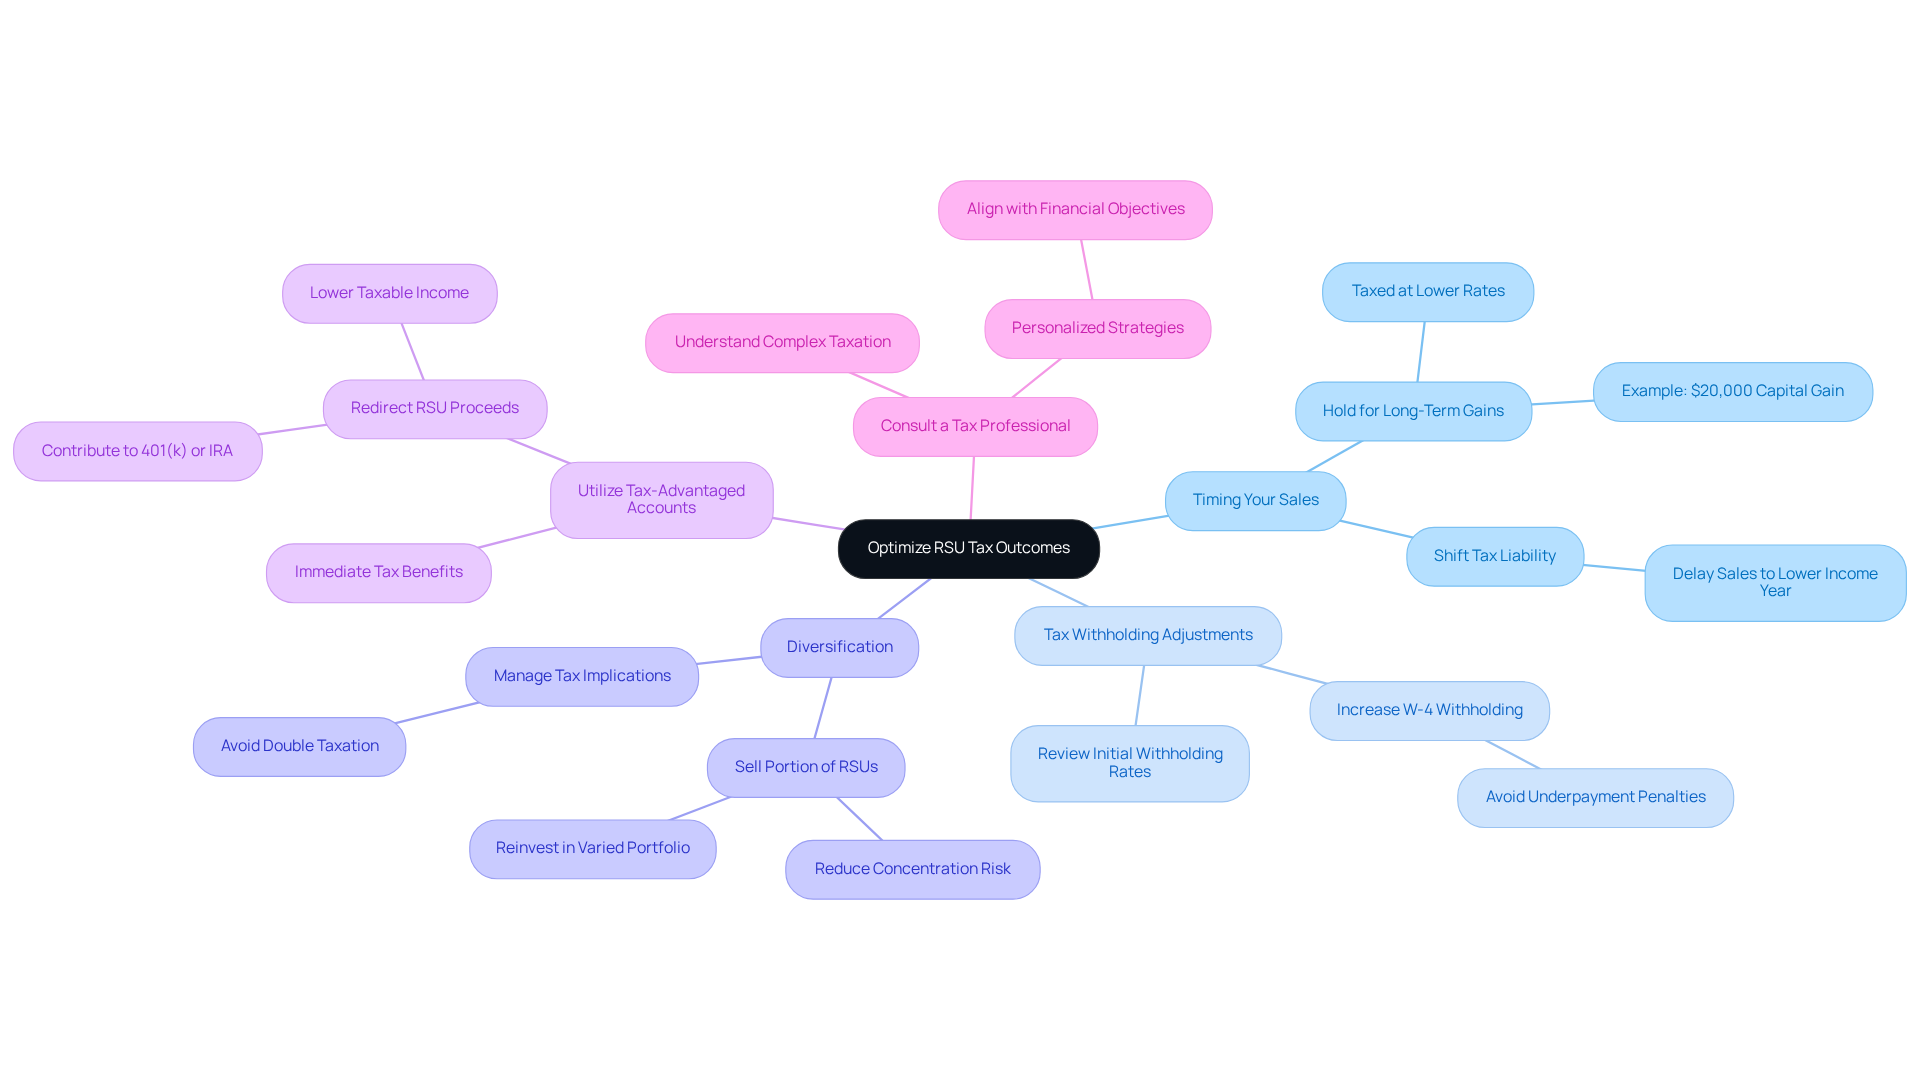
To optimize tax outcomes related to RSUs, consider these thoughtful strategies that can make a difference for your family’s financial future:
-
Timing Your Sales: Imagine holding onto your RSUs for more than one year after they vest. This simple act can significantly lighten your tax burden, as gains will be taxed at lower long-term capital gains rates—sometimes as low as 15% for many families. This approach aligns beautifully with the careful planning strategies used by families like Emily and Mark, who sought to enhance their economic well-being.
-
Tax Withholding Adjustments: It’s important to ensure your employer withholds enough taxes at vesting to avoid underpayment penalties. Adjusting your W-4 to increase withholding can effectively manage this risk, as many employees discover that their initial withholding rates fall short of covering their tax liabilities.
-
Diversification: To reduce monetary risk, consider selling a portion of your RSUs and reinvesting in a varied portfolio. This strategy not only alleviates concentration in your employer’s stock but also helps manage potential tax implications, specifically how are RSUs taxed when sold, associated with large gains. As George Dimov, President & Managing Owner, insightfully states, “One of the biggest challenges RSU holders face is avoiding double taxation.”
-
Utilize Tax-Advantaged Accounts: Redirecting proceeds from RSU sales into tax-advantaged accounts like a 401(k) or an IRA can lower your taxable income, providing immediate tax benefits while securing your family’s economic future. Families like Emily and Mark have successfully employed this strategy to improve their economic security.
-
Consult a tax professional to learn how RSUs are taxed when sold; given the complexities surrounding RSU taxation, seeking advice from a tax advisor can yield personalized strategies that align with your family’s monetary objectives. As one expert wisely noted, “Timing your sales can shift tax liability by an entire year, making it essential to plan accordingly.” Furthermore, families such as Emily and Mark have effectively navigated their restricted stock units by employing strategies that enhanced their tax advantages while aligning with their long-term financial goals.
Remember, we’re here for you as you navigate this journey together, making informed decisions that support your family’s values and aspirations.
Identify Common Mistakes in RSU Tax Reporting
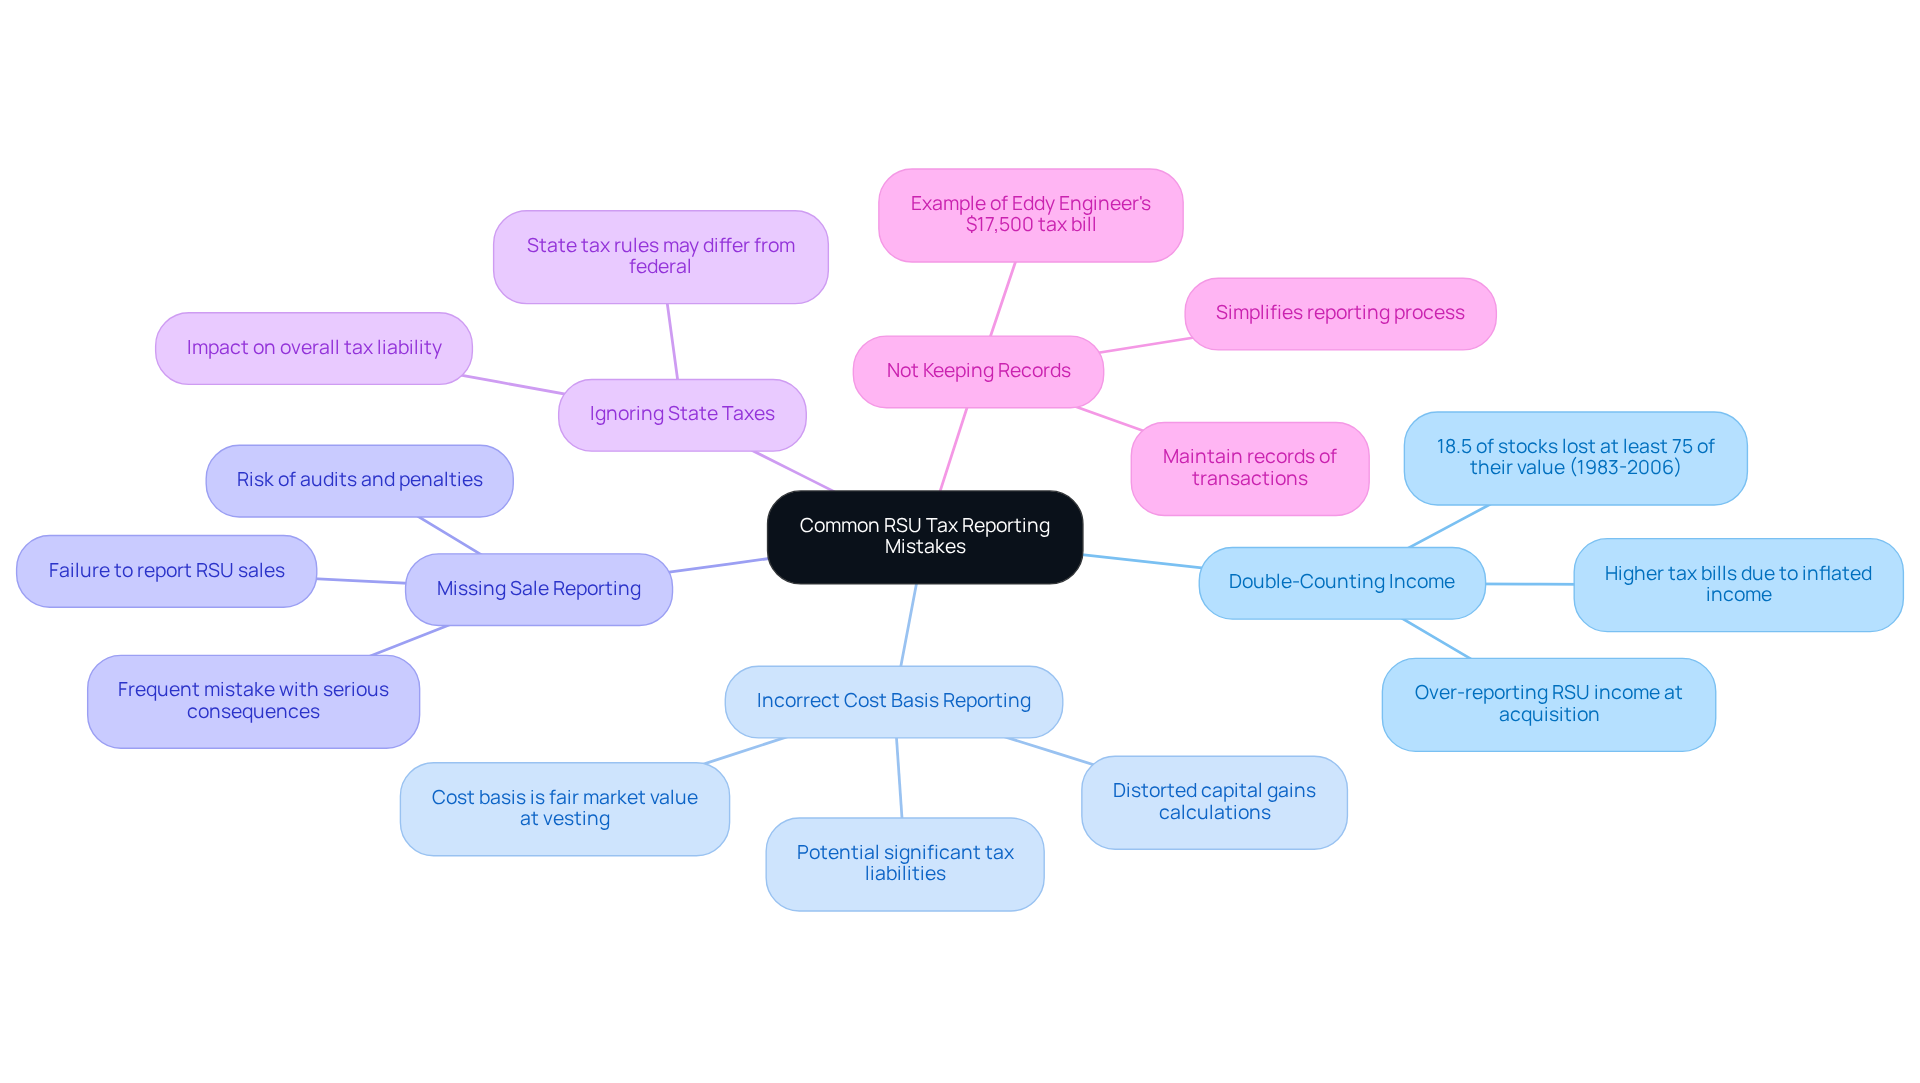
When considering how RSUs are taxed when sold on your tax return, it’s essential to navigate the process carefully to avoid pitfalls that could lead to penalties and unexpected tax burdens.
-
Double-Counting Income: Imagine the stress of over-reporting your income! It’s crucial to avoid reporting RSU income at acquisition and to understand how RSUs are taxed when sold. This common oversight can inflate your income, resulting in higher tax bills. Remember, approximately 18.5% of stocks lost at least 75% of their value from 1983-2006, illustrating the risks of misreporting.
-
Incorrect Cost Basis Reporting: It’s important to ensure that you accurately report the cost basis of your restricted stock units when selling them. Typically, the cost basis is the fair market value at the time of vesting. Misreporting this can distort your capital gains calculations, potentially leading to significant tax liabilities. As the WJA Tax Department emphasizes, it’s crucial to understand how RSUs are taxed when sold to ensure they are correctly reported on your tax return and to avoid double taxation.
-
Missing Sale Reporting: Always remember to report how RSUs are taxed when sold on your tax return. Overlooking this can lead to audits and penalties, complicating your financial situation. The misreporting of RSU sales is a frequent mistake that can have serious economic consequences.
-
Ignoring State Taxes: Be mindful of state tax implications, as some states have specific rules regarding RSU taxation that may differ from federal regulations. This can significantly impact your overall tax liability.
-
Not Keeping Records: Maintaining thorough records of your RSU transactions, including vesting dates, sale dates, and amounts, is a wise practice. It simplifies the reporting process and ensures accuracy, helping you avoid costly mistakes. For instance, Eddy Engineer faced a staggering tax bill of $17,500 due to misreporting his RSU income, highlighting the financial impact of these errors.
Consulting with a tax professional can provide you with the clarity and support needed to navigate these complexities effectively. We’re here for you, ready to help you manage your financial journey with confidence.
Conclusion
Understanding the taxation of Restricted Stock Units (RSUs) is crucial for parents navigating their financial futures. This guide has illuminated the intricacies of how RSUs are taxed when sold, helping you grasp the importance of timing, reporting, and strategic planning. By recognizing the tax implications associated with RSUs, families can make informed decisions that align with their broader financial goals.
Key insights discussed include:
- The distinction between ordinary income tax at vesting and capital gains tax upon sale.
- The benefits of long-term holding strategies.
- The potential pitfalls of misreporting RSU transactions.
It’s important to understand that consulting with financial and tax professionals can optimize your outcomes. These experts can provide tailored advice that helps families avoid common mistakes, such as double-counting income or misreporting capital gains.
Ultimately, the effective management of RSUs can lead to significant financial advantages for families. By applying the strategies outlined in this guide, such as timing sales and utilizing tax-advantaged accounts, you can enhance your economic security and ensure a brighter future for your children. Together, we can navigate this journey by taking proactive steps in understanding and managing RSU taxation. This empowerment will enable families to approach their financial journeys with confidence and clarity.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation that employers, especially in the technology sector, offer to employees. They promise shares at a future date, contingent upon meeting specific criteria, such as waiting periods.
How do RSUs differ from traditional stock options?
Unlike traditional stock options, which give employees the right to purchase shares at a set price, RSUs provide employees with actual shares after certain conditions, like vesting schedules, are met.
What is a common vesting schedule for RSUs?
A common vesting schedule for RSUs is where 25% of the shares become available each year over a four-year period.
What happens when RSUs vest?
When RSUs vest, employees receive actual shares, allowing them the choice to sell or hold onto them, and their value is linked to the company’s stock price.
How prevalent are RSUs in the workforce?
Nearly 40% of employees in the tech and corporate sectors are expected to receive RSUs by 2025.
How are RSUs taxed when they vest?
When RSUs vest, the fair market value of the shares is treated as ordinary income for tax purposes, which can impact an employee’s tax bracket.
Why is it important for parents to understand RSUs?
Understanding RSUs is essential for parents as they can significantly impact budgeting and tax responsibilities, helping them manage the complexities of financial obligations while raising a family.
Should employees seek financial advice regarding RSUs?
Yes, it is advisable for employees to seek advice from a financial consultant to create a strategy that incorporates RSUs into their overall financial plan and to prepare for the tax implications.
List of Sources
- Define Restricted Stock Units (RSUs)
- The Psychological Impact of RSUs as Compensation: Understanding Employee Perspectives and Motivations – CIGMA Accounting (https://cigmaaccounting.co.uk/the-psychological-impact-of-rsus-as-compensation)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- Future Trends in Equity Compensation: The Evolution of Stock Options and RSUs (https://linkedin.com/pulse/future-trends-equity-compensation-evolution-stock-options-rsus-bxnpc)
- Understand Tax Implications When Selling RSUs
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- RSU Tax Implications: What To Do When RSUs Vest + Tax Strategy (https://skwealth.com/blog/rsu-tax-implications-and-strategy)
- Restricted Stock Units (RSUs): What You Need to Know About Taxes, Selling Shares and Long-Term Strategies (https://aspiriant.com/fathom/rsus-taxes-selling-and-more)
- How RSUs Impact Your Retirement Planning: Insights from a Financial Adviser – CIGMA Accounting (https://cigmaaccounting.co.uk/how-rsus-impact-your-retirement-planning)
- Ask an Advisor: How Are RSUs Taxed? – NerdWallet (https://nerdwallet.com/article/investing/how-are-rsus-taxed)
- Implement Strategies to Optimize RSU Tax Outcomes
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Understanding Restricted Stock Units Definition for Young Parents – Bright Advisers (https://brightadvisers.com/understanding-restricted-stock-units-definition-for-young-parents)
- How are RSUs Taxed: A Complete Guide for 2025 (https://dimovtax.com/how-are-rsus-taxed-guide)
- RSU Guide + Strategy After Vesting (https://safelandingfinancial.com/rsus)
- Identify Common Mistakes in RSU Tax Reporting
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Restricted Stock Units – RSU Tax Tips: Avoid Double Taxation (https://juliemerrill.me/blog/rsu-tax-tips-avoid-double-taxation)
- The Most Common RSU Mistakes — And How to Avoid Them (https://plancorp.com/blog/restricted-stock-unit-rsu-mistakes)
- How to Avoid Double Taxation on Restricted Stock Units (RSUs) (https://insights.wjohnsonassociates.com/blog/how-to-avoid-paying-double-tax-for-restricted-stock-units-rsus)
- How to Avoid Common RSU Tax Mistakes (https://solidaritywealth.com/how-to-avoid-common-rsu-tax-mistakes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading