

Key Highlights
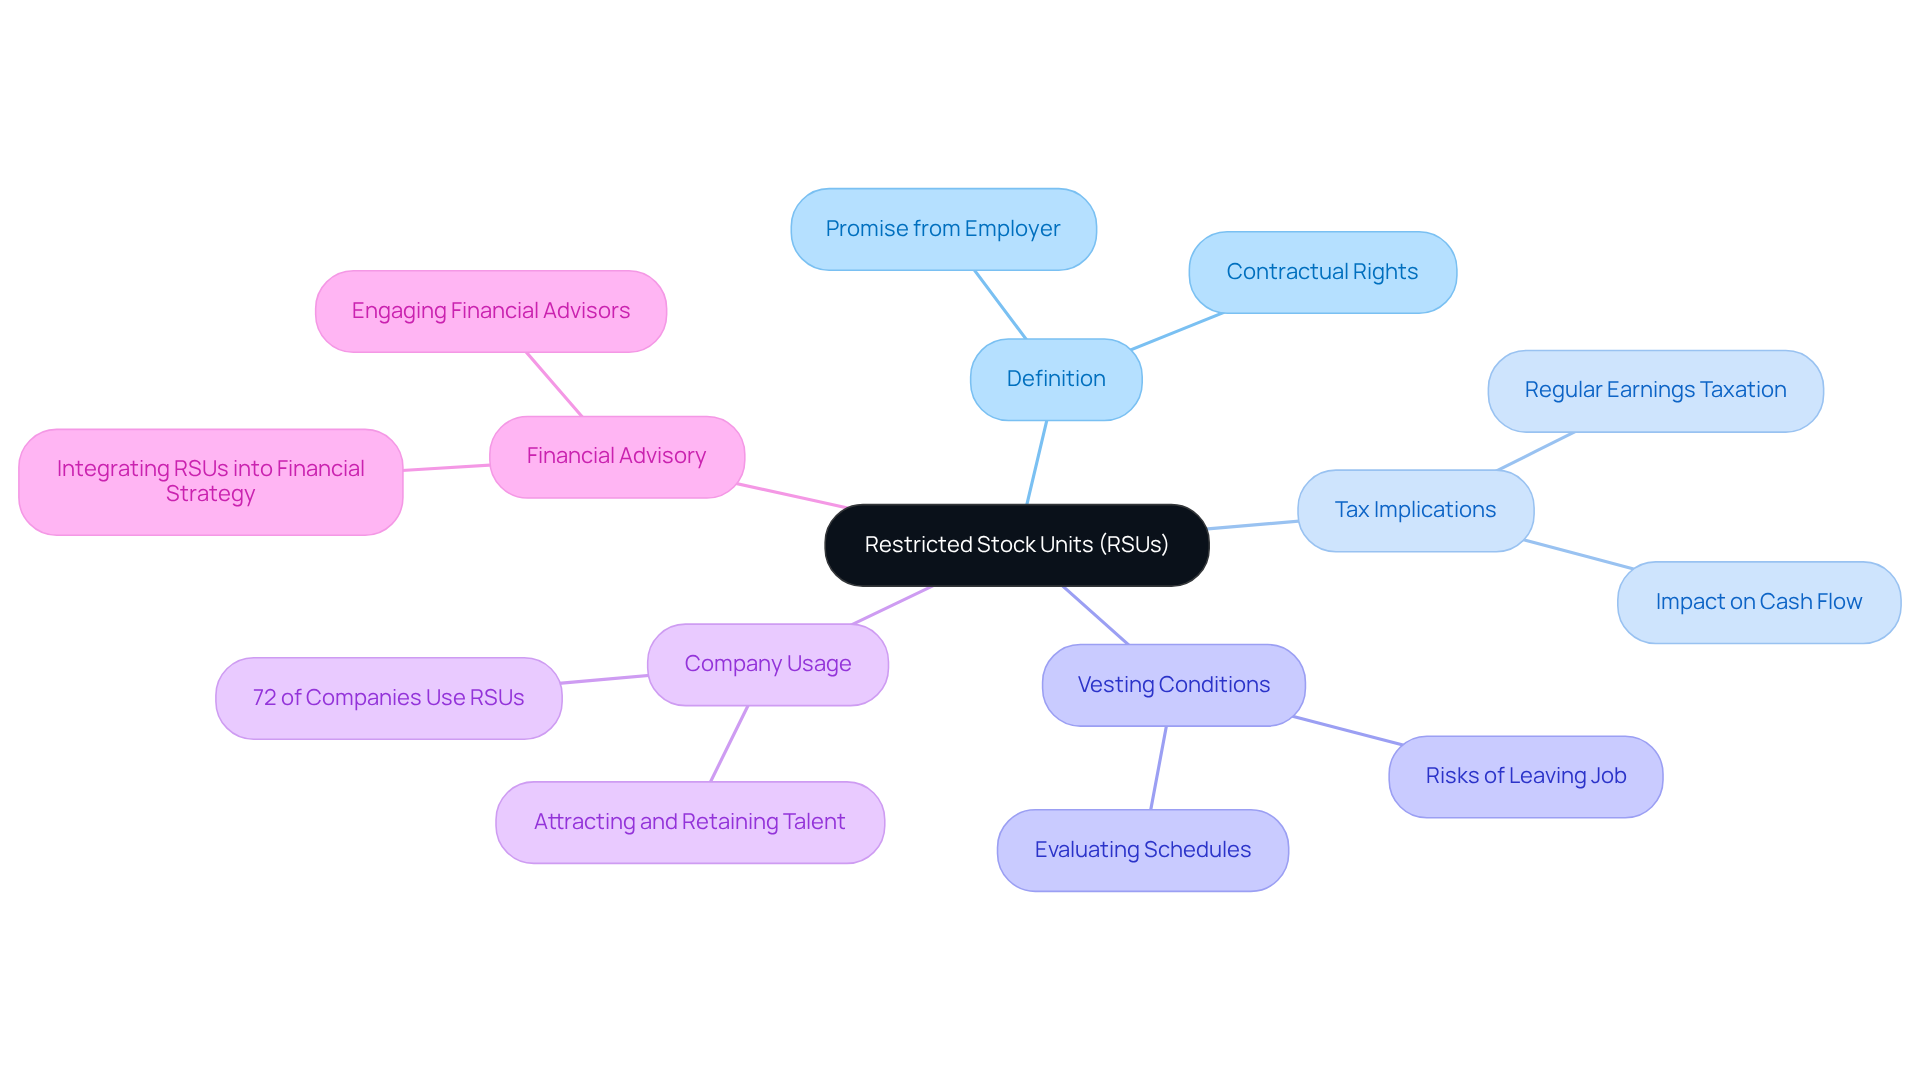
- Restricted Stock Units (RSUs) are promises from employers to deliver shares or cash in the future, contingent on meeting specific conditions.
- RSUs are increasingly used by companies, with 72% adopting them to support employees.
- When RSUs vest, their fair market value is taxed as regular income, complicating cash flow and tax responsibilities for families.
- Families must be aware of the potential tax implications, including federal and state tax rates, which can be as high as 13.3% in California.
- Capital gains tax applies when selling RSU shares, with rates varying based on how long the shares are held after vesting.
- Reporting RSUs on tax returns involves including vested earnings on Form 1040 and detailing any sales on Schedule D and Form 8949.
- Common misconceptions include the belief that RSUs are taxed twice; they are taxed as ordinary income at vesting and as capital gains upon sale.
- Understanding RSU taxation is crucial for effective financial planning, especially for families aiming to avoid unexpected tax liabilities.
Introduction
Imagine navigating the world of Restricted Stock Units (RSUs) while juggling the demands of family life – it’s a challenge many parents face. As these units become a popular form of compensation, understanding how they are taxed is crucial for managing your household budget. Together, we’ll explore how RSUs are taxed, helping your family avoid pitfalls and discover opportunities for financial growth. Let’s uncover how you can make informed decisions about RSUs and steer clear of misconceptions that might surprise you at tax time.
Define Restricted Stock Units (RSUs)
Imagine the stress of managing your family’s finances while trying to understand complicated stock options. Restricted Stock Units (RSUs) can be a valuable part of your compensation, but they come with their own set of rules and conditions. These units signify a promise from your employer to deliver shares of stock or cash at a later date, but you’ll need to meet specific requirements, like staying with the company or hitting performance targets, before they become yours.
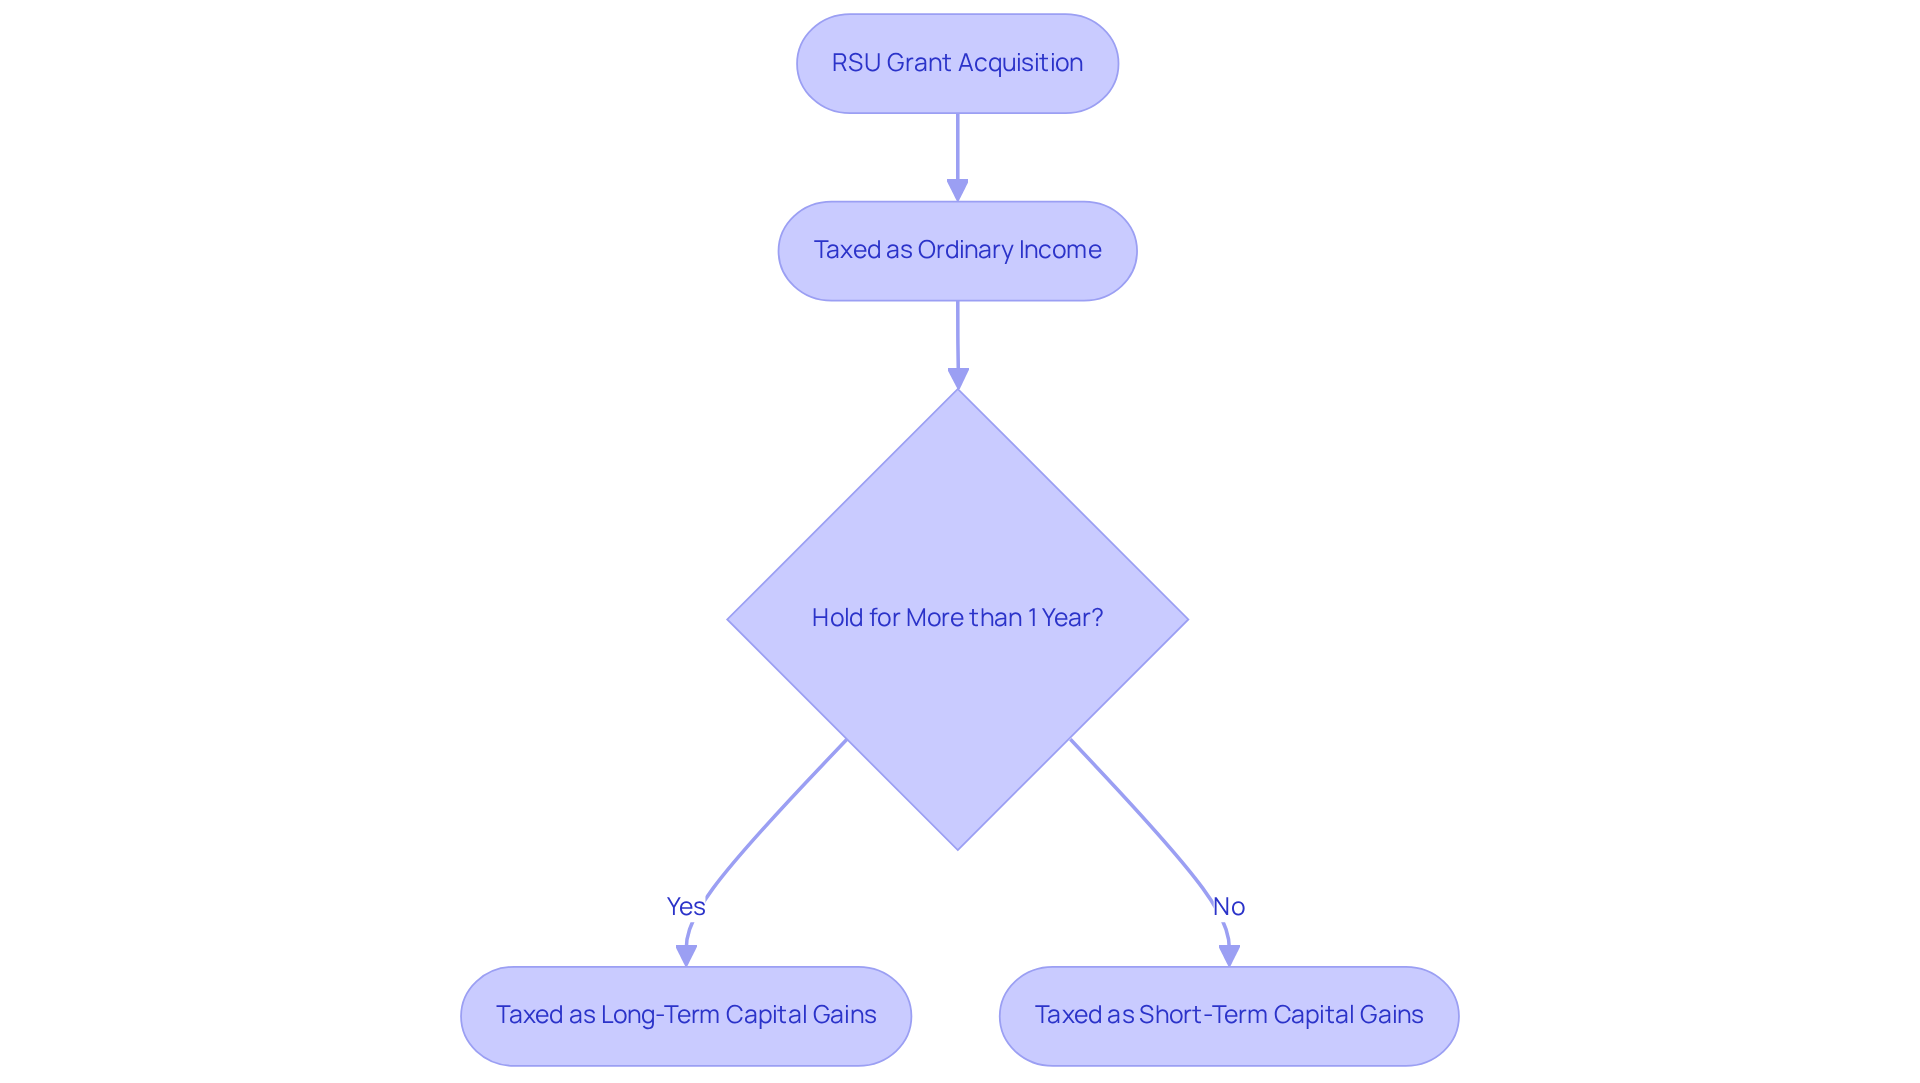
It’s important for parents to understand how RSU grants are taxed and how they can impact their family’s financial journey. When RSUs vest, it raises the question of how RSU grants are taxed, as the fair market value of the shares is taxed as regular earnings, which can complicate your cash flow and tax responsibilities. This is especially true for families with varying income levels, where unexpected tax bills can add to the stress.
Did you know that 72% of companies are now using restricted stock units to support their employees? This shows just how vital they are in today’s job market. However, while RSUs can offer great opportunities, they also come with risks. For instance, if you leave your job before your RSUs vest, you might lose them altogether. This makes it crucial to evaluate vesting schedules carefully and understand how they can affect your family’s wealth.
As you navigate the complexities of restricted stock units, remember that you don’t have to do it alone. Engaging with a financial advisor can provide you with valuable insights into how to integrate these assets into your broader financial strategy. With the right guidance, you can turn these challenges into opportunities for your family’s financial growth.
Explain RSU Taxation Process
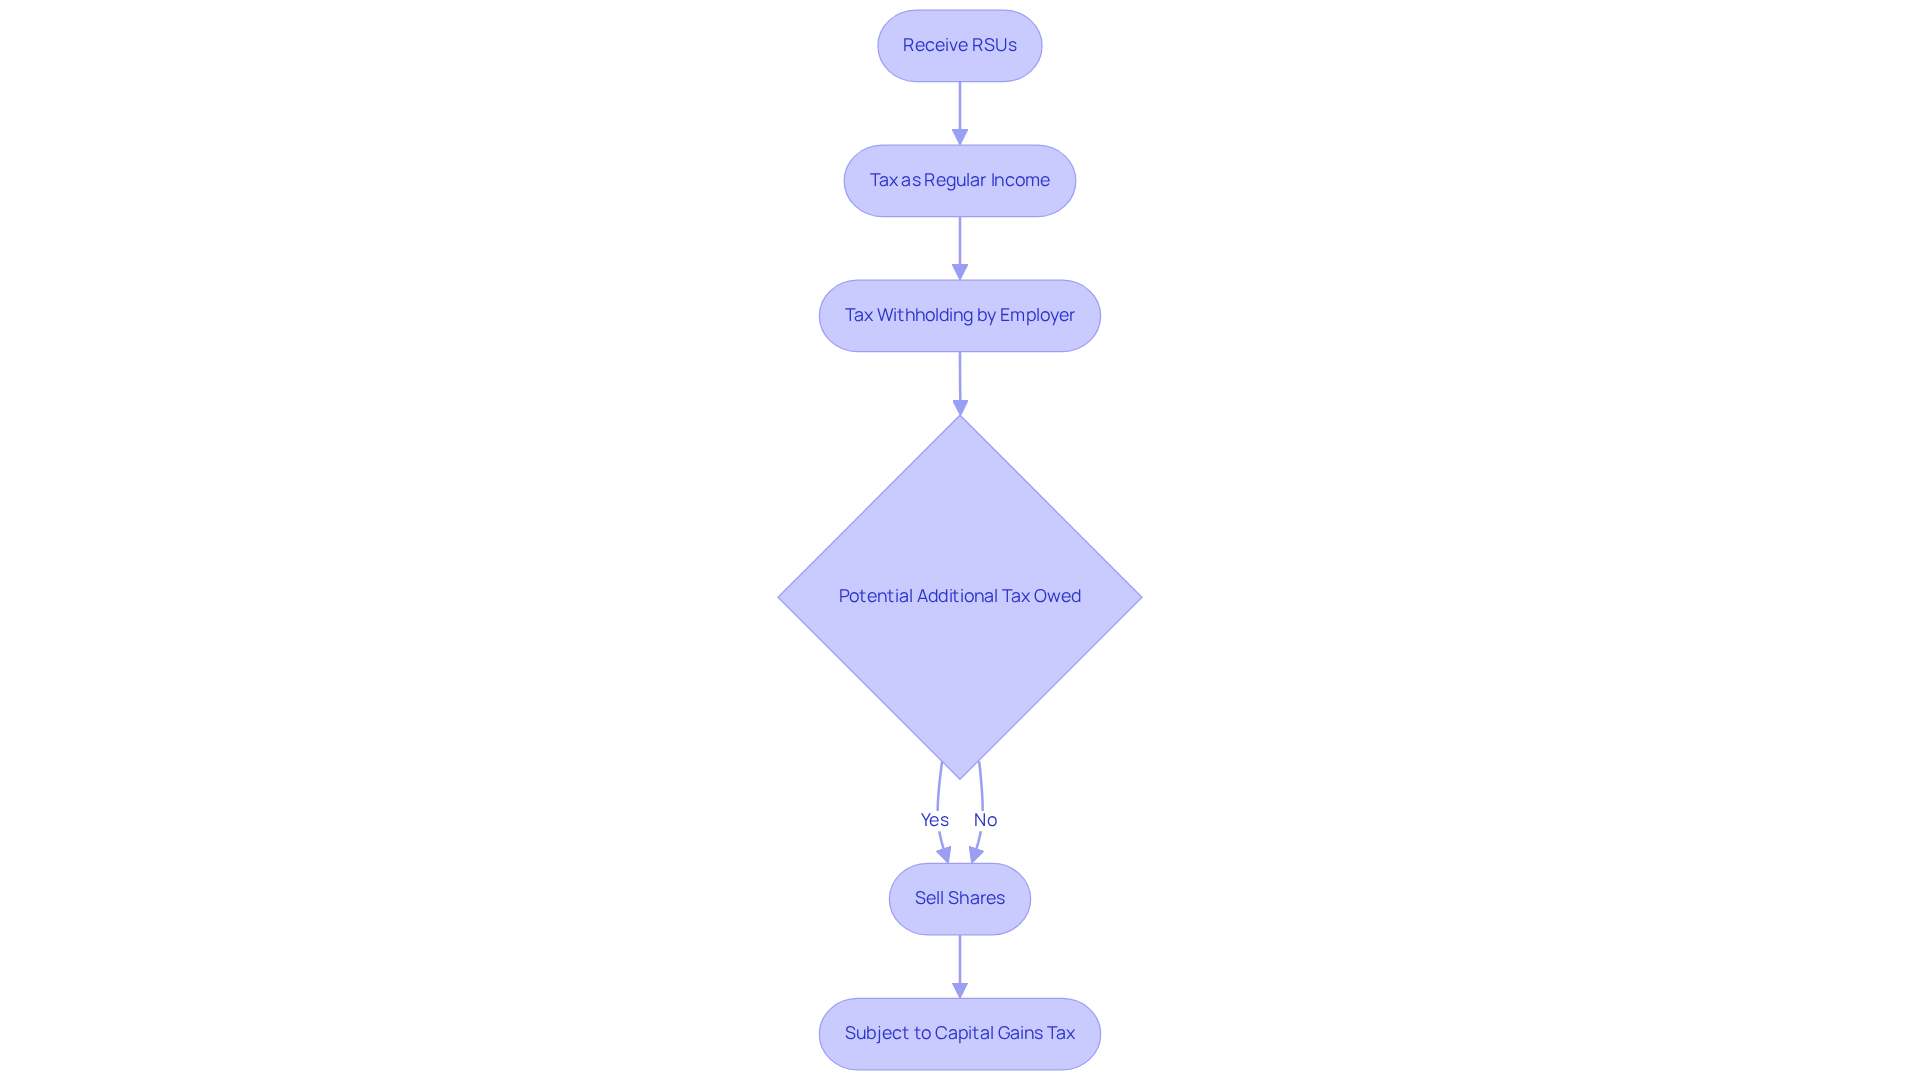
Imagine the surprise of receiving Restricted Stock Units, only to find out how RSU grants are taxed and how this could affect your family’s finances. When you receive your RSUs, the fair market value is treated as regular income, leading to inquiries about how RSU grants are taxed at the federal, state, and payroll levels. This can feel daunting, especially when you’re focused on your family’s needs. Your employer usually takes care of some of the tax withholding, but it’s good to be aware of how RSU grants are taxed, as you might still owe more depending on your total earnings. We understand how this can add to your worries.
Once you sell your shares, it is important to understand how RSU grants are taxed on any profit you make, as it will be subject to capital gains tax. This can feel like another hurdle, but knowing what to expect can help you plan better for your family’s future. Understanding how RSU grants are taxed can empower you to make informed decisions that support your family’s financial well-being.
Detail RSU Tax Rates and Implications
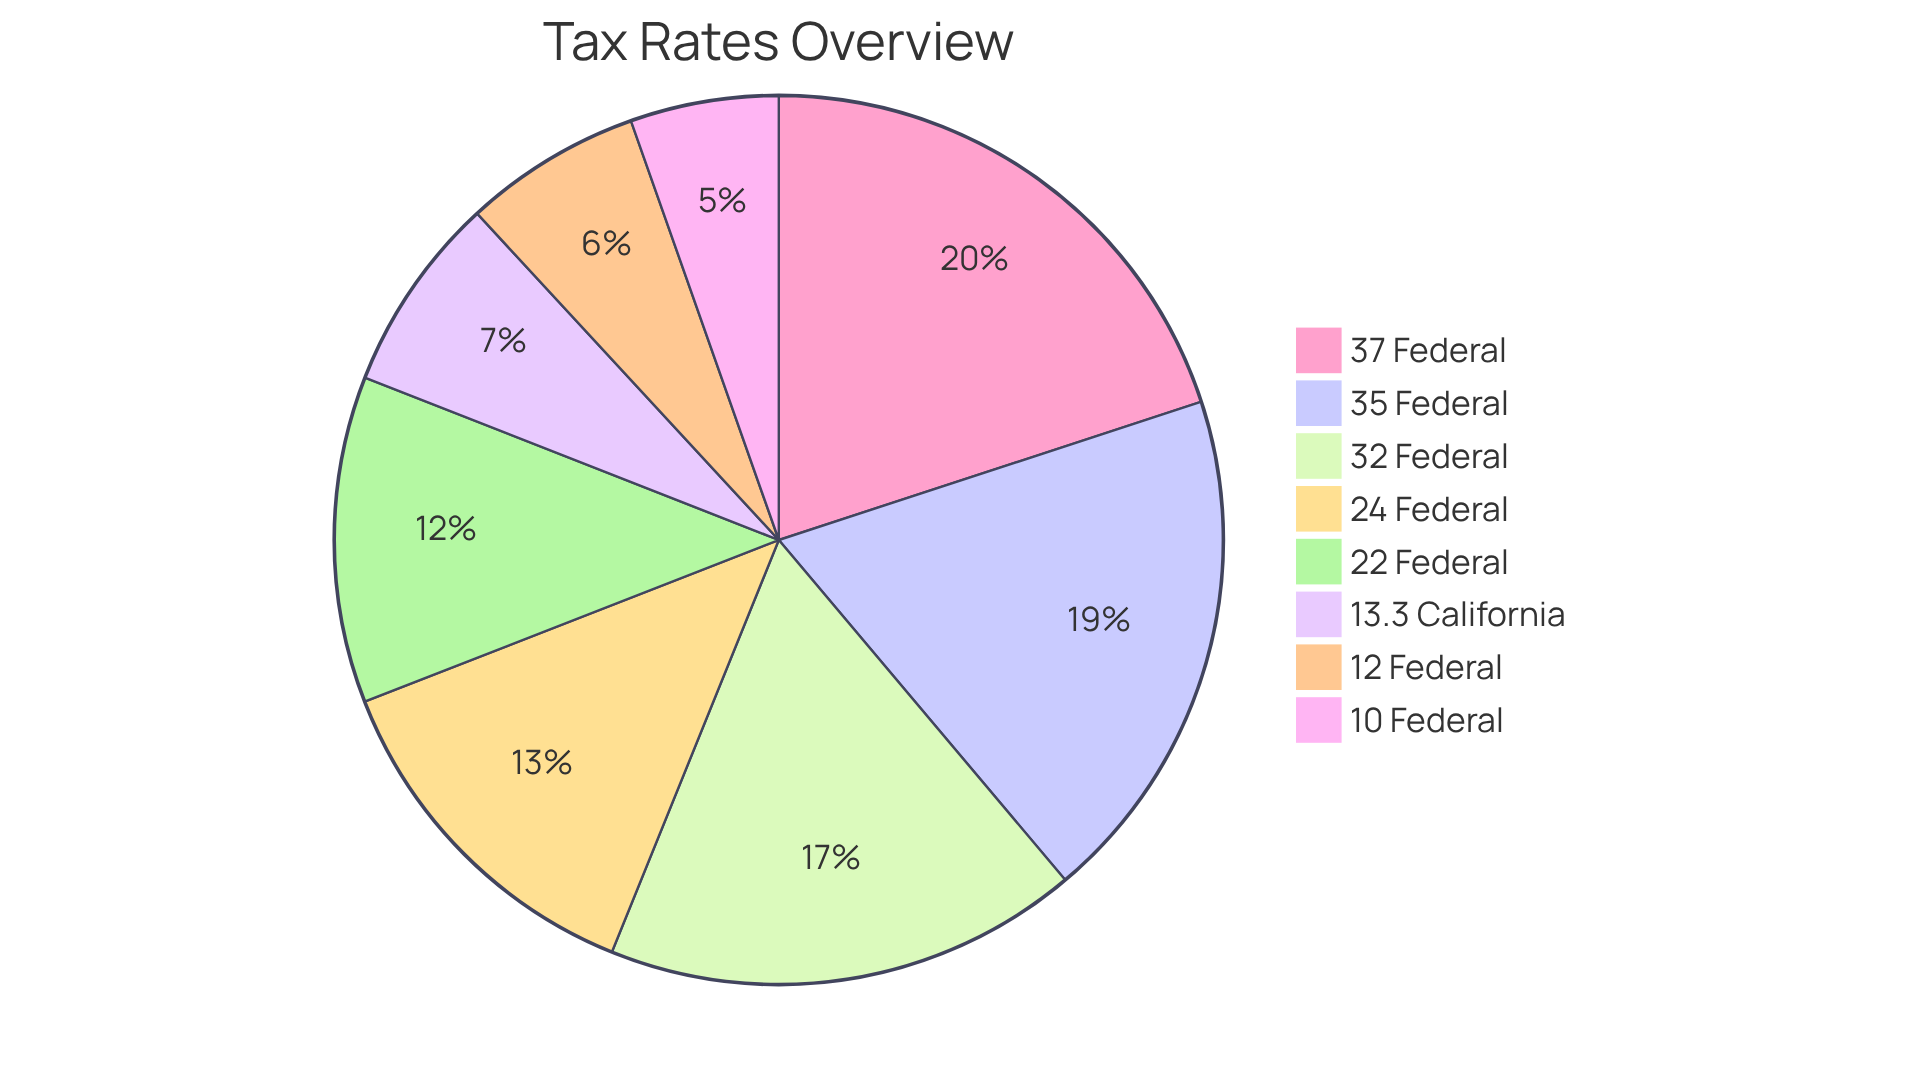
Imagine the relief of understanding how your Restricted Stock Units can work for your family’s financial future. When your Restricted Stock Units vest, it’s important to know they’ll be taxed like your regular earnings, which can feel daunting. Depending on your total earnings, this tax can range from 10% to 37%. For instance, if you find yourself in the 24% tax bracket, you’ll incur a 24% tax on the value of the RSUs that vest.
In California, navigating state taxes can feel like an added challenge for families, with rates reaching up to 13.3% for high earners. Once you sell those shares, it’s crucial to understand that any gains will be subject to capital gains tax, which can impact your family’s finances. These gains are categorized as either short-term or long-term, depending on how long you hold the shares after they vest. Short-term capital gains are taxed at standard rates, while long-term capital gains benefit from lower rates, making it beneficial to hold shares for over a year.
By 2026, the federal long-term capital gains tax rates for single filers will be set at:
- 0% for earnings up to $49,450
- 15% for earnings between $49,451 and $545,500
- 20% for earnings surpassing $545,500
By strategically managing how your RSU grants are taxed, you can make a real difference in your family’s financial planning, especially in California, where tax rates are among the highest in the nation. Remember, you’re not alone in this journey; we’re here to help you navigate these complexities and secure your family’s future.
Guide on Reporting RSUs on Tax Returns
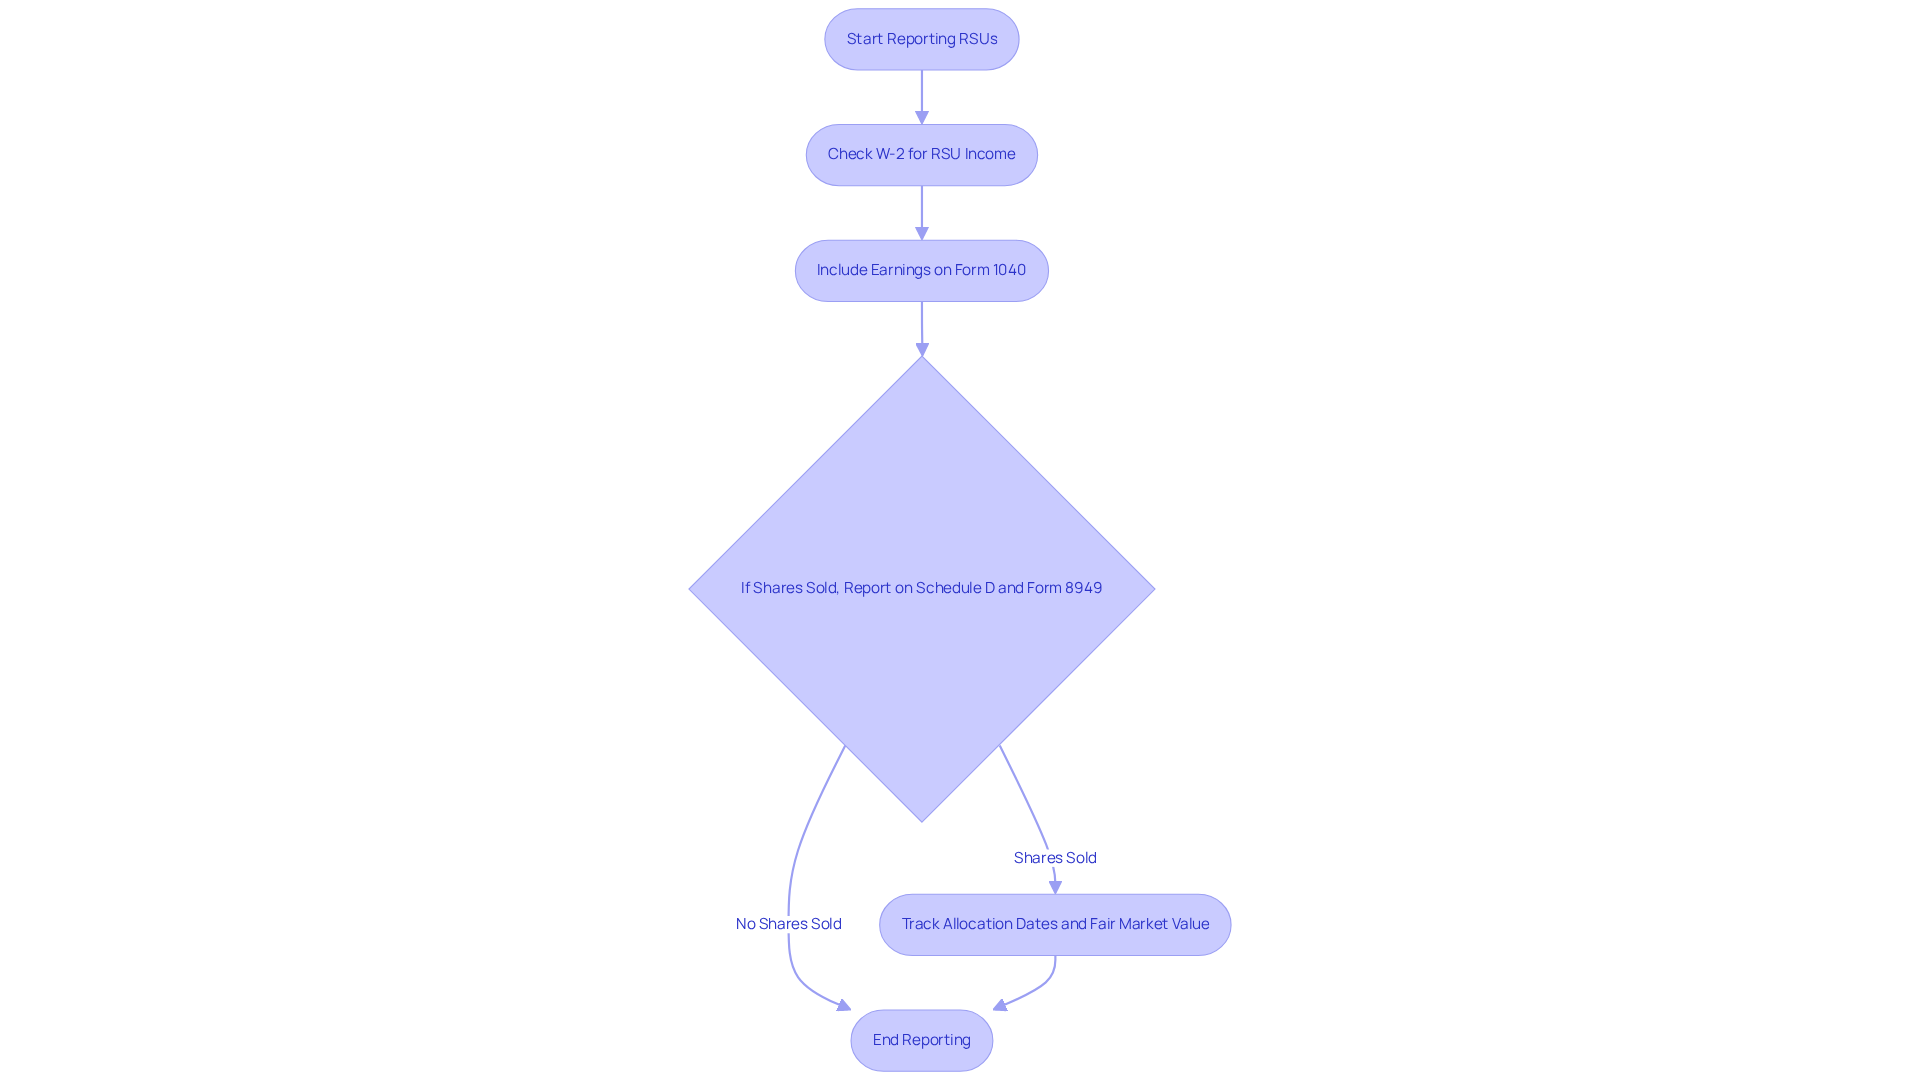
Imagine the relief of knowing how RSU grants are taxed correctly, which eases your tax worries. You’ll want to include the earnings from your vested RSUs on your Form 1040 to understand how RSU grants are taxed. Typically, this income shows up on your W-2, but it’s a good idea to double-check how RSU grants are taxed to ensure the amount matches your records. If you’ve sold any shares, you’ll also need to report the sale on Schedule D and Form 8949, detailing the sale price and the cost basis – the value at acquisition.
Keeping track of your allocation dates and the fair market value can help you avoid any surprises down the road. If you have multiple RSUs maturing at different times, don’t worry – keeping an eye on each one can make your reporting much smoother. Remember, we’re here for you, guiding you through these financial details so you can focus on what truly matters – your family.
Address Common RSU Tax Misconceptions
Imagine the confusion and worry that can arise when it comes to understanding how RSU grants are taxed and their implications. Many people worry about how RSU grants are taxed, as they are taxed twice – first when they become available and again when sold. In reality, how RSU grants are taxed happens only once at the time of acquisition, where the value is treated as regular earnings. Any gains from selling the shares are taxed as capital gains.
It’s important to understand how RSU grants are taxed, as retaining restricted stock units for a year after vesting doesn’t guarantee reduced tax rates. While long-term capital gains are indeed taxed at a lower rate, it raises the question of how RSU grants are taxed, since the initial allocation still incurs ordinary income tax. This can lead to unexpected liabilities if not managed properly. Imagine the stress of facing unexpected tax bills when you thought you were prepared. For instance, an employee who has RSUs valued at $100,000 upon becoming fully owned may face significant tax consequences if they assume the value will remain constant.
Many employees, just like you, might think their employer’s withholding at vesting takes care of their entire tax bill, but it’s important to know how RSU grants are taxed to avoid unwelcome surprises. Understanding these nuances can really help you and your family plan better, especially when aiming to avoid costly surprises during tax season. By grasping these nuances, you can protect your family’s financial future and avoid those unexpected surprises come tax season.
Conclusion
Many parents feel overwhelmed by the complexities of Restricted Stock Units (RSUs) and their tax implications. These units can significantly impact your income and tax obligations, making it crucial to understand how they work and what they mean for your family. By demystifying the RSU taxation process, you can better prepare for the financial responsibilities that come with these valuable assets.
Throughout this guide, we’ve shared key insights about RSUs, including how they are treated as regular income upon vesting and the varying tax rates based on income levels. It’s important to understand the significance of accurate reporting on tax returns. We’ve also addressed common misconceptions about RSU taxation, highlighting the need for careful planning to avoid unexpected tax liabilities. When families understand RSUs, they can confidently plan for their financial future.
But remember, you’re not alone in this journey. With the right support, families can confidently embrace their financial journey and secure a brighter future together. Seeking guidance from a fiduciary advisor like Bright Advisers can help you navigate the complexities of RSU taxation with ease. This proactive approach not only helps in maximizing financial opportunities but also ensures that your family is well-prepared for what lies ahead. Embracing this knowledge can lead to a more intentional and secure financial path for generations to come.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation from an employer that promises to deliver shares of stock or cash at a later date, contingent upon meeting specific requirements such as staying with the company or achieving performance targets.
How are RSUs taxed?
When RSUs vest, the fair market value of the shares is taxed as regular income at the federal, state, and payroll levels. This can complicate cash flow and tax responsibilities, especially for families with varying income levels.
What happens if I leave my job before my RSUs vest?
If you leave your job before your RSUs vest, you may lose the RSUs altogether, making it essential to evaluate vesting schedules carefully.
How can RSUs impact my family’s financial situation?
RSUs can provide valuable compensation but also come with risks and tax implications that can affect your family’s financial journey, including unexpected tax bills when they vest.
What should I consider when managing RSUs?
It’s important to understand the vesting schedules, tax implications, and how to integrate RSUs into your broader financial strategy. Engaging with a financial advisor can provide valuable insights.
What tax considerations should I be aware of when selling RSU shares?
When you sell your RSU shares, any profit made will be subject to capital gains tax, which is another important factor to consider for your family’s financial planning.
List of Sources
- Define Restricted Stock Units (RSUs)
- This job perk is like a ‘cash bonus’ — but you need a long-term strategy, experts say (https://cnbc.com/2024/04/25/here-are-the-key-things-to-know-about-your-restricted-stock-units.html)
- What is an RSU? Restricted Stock Guide for Executives (https://jnba.com/insights/what-is-an-rsu)
- Equity Compensation and the Rise of Restricted Stock Units (https://natlawreview.com/article/equity-compensation-and-rise-restricted-stock-units)
- Understanding Restricted Stock Units (RSUs) | Modera Wealth Management (https://moderawealth.com/understanding-restricted-stock-units-rsus)
- Explain RSU Taxation Process
- RSU Tax Treatment — Complete 2026 Guide | Uncle Kam (https://unclekam.com/tax-write-offs/deductions/restricted-stock-units-tax)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU Tax in California: What Married Founders Need to Know in 2026 | Neptune Blog (https://meetneptune.com/blog/rsu-tax-in-california)
- Your Guide to California’s RSU Tax Rate | Consilio Wealth Advisors (https://consiliowealth.com/insights/your-guide-to-californias-rsu-tax-rate)
- Detail RSU Tax Rates and Implications
- California’s Long-term Capital Gains Tax (https://edelmanfinancialengines.com/education/tax/capital-gains-tax-california)
- California Tax Brackets 2026: See Your Exact Tax Rate by Income (https://paycheckcalculatorcalifornia.com/california-tax-brackets-2026)
- California State Taxes: What You’ll Pay in 2026 (https://aarp.org/states/california/state-tax-guide)
- State-by-State Capital Gains Tax Rates for 2026 (https://theentrustgroup.com/blog/state-capital-gains-tax?hs_amp=true)
- California State Income Tax Rates & Brackets (2025-2026) – NerdWallet (https://nerdwallet.com/taxes/learn/california-state-tax)
- Guide on Reporting RSUs on Tax Returns
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- How to Report RSUs or Stock Grants on Your Tax Return (https://turbotax.intuit.com/tax-tips/investments-and-taxes/how-to-report-rsus-or-stock-grants-on-your-tax-return/L55yZieu0)
- 6 Common RSU Tax Mistakes (and How to Avoid Them) – Summitry (https://summitry.com/blog/common-rsu-tax-mistakes)
- Restricted Stock And RSU Tax Returns: 10 Mistakes To Avoid (https://mystockoptions.com/articles/restricted-stock-rsus-10-mistakes-to-avoid-on-your-tax-return)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- Address Common RSU Tax Misconceptions
- Avoid an RSU Double Tax — EquityFTW (https://equityftw.com/articles/avoid-an-rsu-double-tax)
- Are RSUs Taxed Twice? What You Need to Know | Consilio Wealth Advisors (https://consiliowealth.com/insights/are-rsus-taxed-twice-what-you-need-to-know)
- Common RSU Misconceptions — Brooklyn Fi (https://brooklynfi.com/blog/rsu-misconceptions)
- RSU Taxes Explained and 4 Tax Strategies for 2023 (https://ceritypartners.com/insights/rsu-taxes-explained-and-4-tax-strategies-for-2023)
- RSU Recipients Face $45,000 Tax Surprises: Why the 22% Withholding Rate Isn’t Enough (https://247wallst.com/personal-finance/2026/04/22/rsu-recipients-face-45000-tax-surprises-why-the-22-withholding-rate-isnt-enough)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading