

Key Highlights
- Restricted Stock Units (RSUs) are employer-provided benefits that can enhance family financial security once certain conditions are met.
- RSUs follow a granting timeline based on time or performance metrics, impacting financial planning for families.
- The value of RSUs is tied to the company’s stock price, which can fluctuate, affecting overall compensation.
- RSUs are taxed as ordinary income upon vesting, and their fair market value (FMV) is reported on W-2 forms.
- Families should identify the acquisition date and calculate FMV to understand tax liabilities associated with RSUs.
- Employers typically withhold taxes on RSU income, but this may not cover the total tax owed, especially for higher earners.
- Common reporting pitfalls include double-counting income, ignoring withholding shortfalls, and misunderstanding cost basis.
- Maintaining thorough records of RSUs is crucial for accurate tax reporting and compliance.
- Consulting a financial advisor can help families navigate RSU-related tax implications and optimise financial strategies.
Introduction
Imagine the relief of understanding how Restricted Stock Units (RSUs) can secure your family’s financial future. As these units transition into tangible shares, they can significantly impact your total compensation and, in turn, your financial planning strategies. Many families find themselves confused and anxious about how to report RSUs correctly.
It’s important to understand that navigating the tax implications can be tricky. Together, we can explore the steps your family can take to report RSUs accurately and steer clear of costly mistakes.
Understand Restricted Stock Units (RSUs)
Imagine feeling confident about your family’s financial future, even amidst the complexities of compensation packages. Restricted Stock Units (RSUs) can be a valuable gift from your employer, helping to secure your family’s future without the need for any purchase. Once certain conditions are met, these units transform into real shares that you can choose to sell or keep. For families, understanding how RSUs are reported on W2 is essential, as this knowledge can represent a significant part of an employee’s total compensation package, greatly influencing financial planning strategies, especially when considering future educational costs for children or retirement savings.
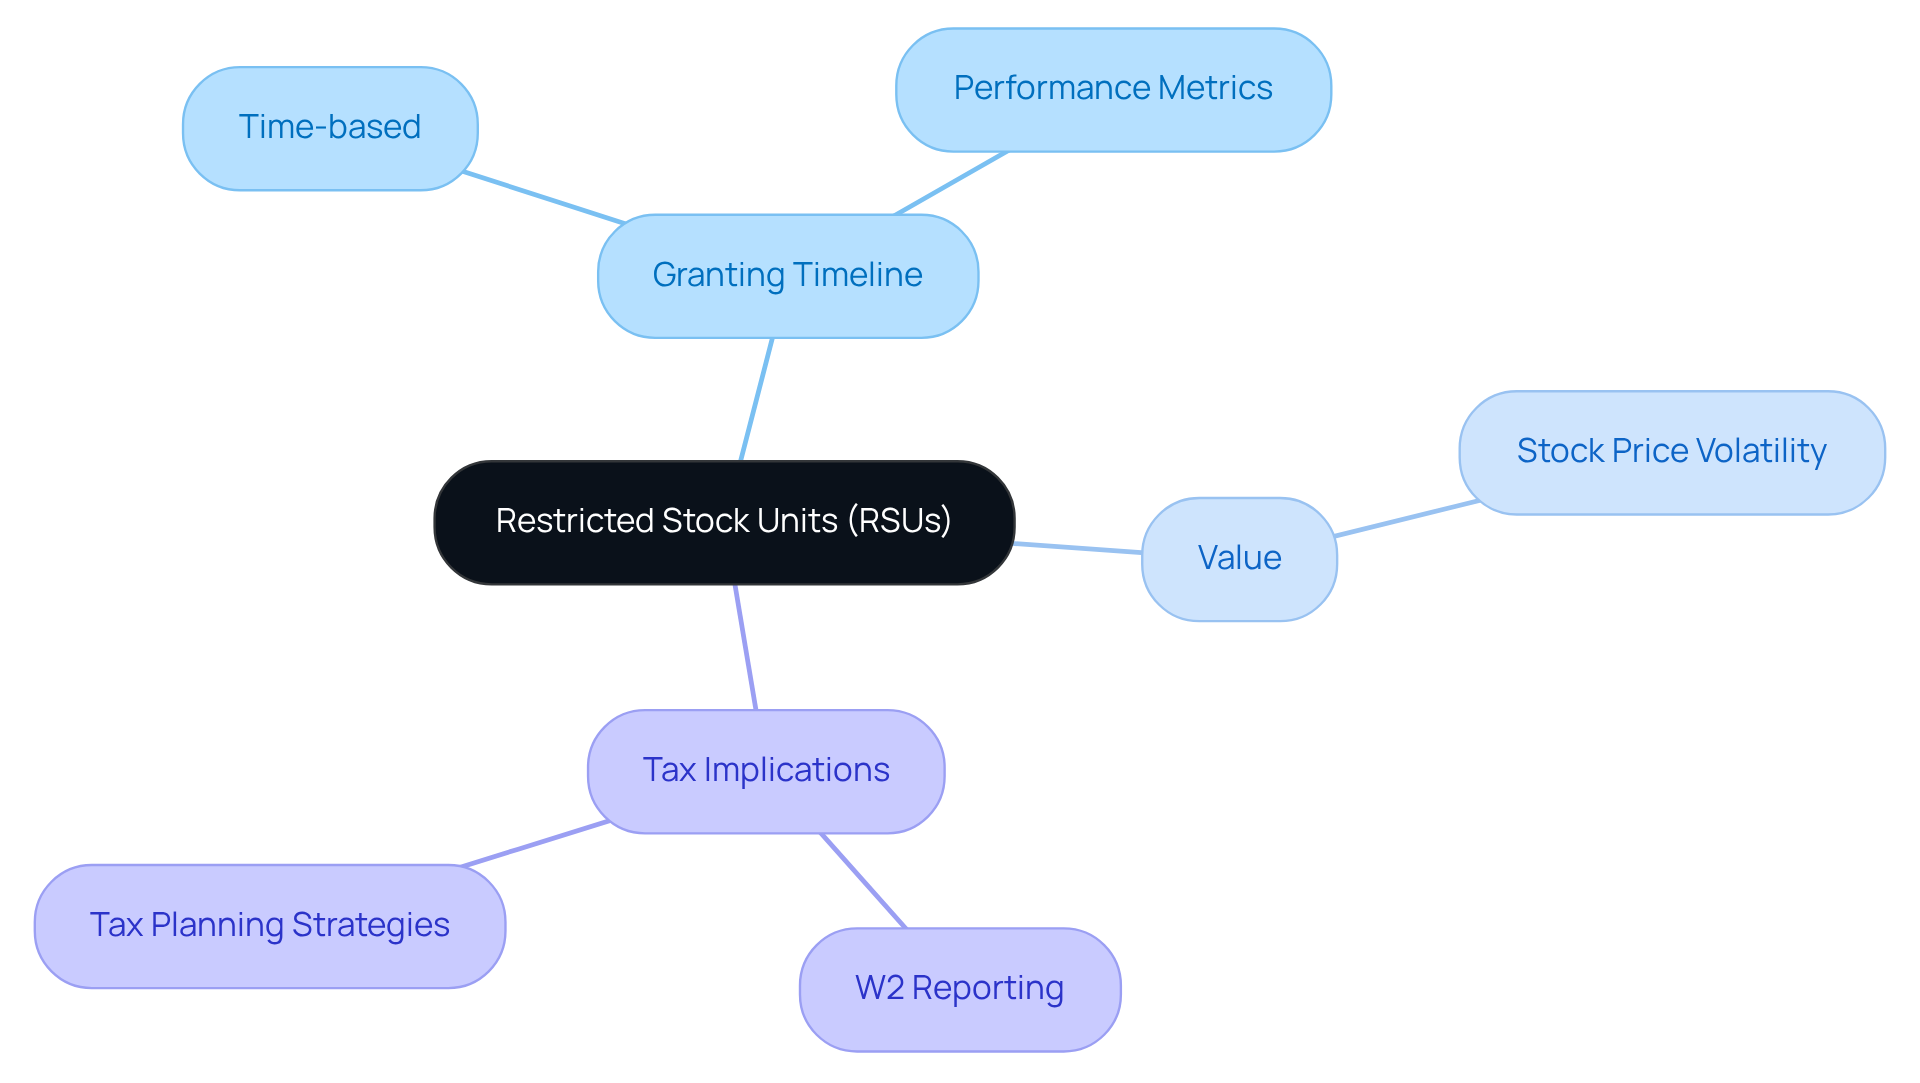
- Granting Timeline: It’s important to know that RSUs typically follow a granting timeline, which specifies when you gain the right to the shares. This schedule may be based on time-like after a set number of years-or performance metrics. Being aware of these timelines can help you plan better for your family’s needs.
- Value: The value of RSUs is directly tied to the company’s stock price, which can change significantly. This volatility can impact your overall compensation, making it crucial to consider in your financial planning.
Understanding how RSUs are taxed is vital, especially regarding how they are RSU reported on W2, as they are classified as income once they vest. This classification can affect your household’s tax planning, highlighting the importance of proactive strategies to manage potential tax liabilities.
When you understand these key aspects of restricted stock units, you can navigate your family’s financial landscape with confidence and clarity. With the right knowledge, you can turn these financial tools into stepping stones for your family’s dreams.
Determine Tax Implications at Vesting
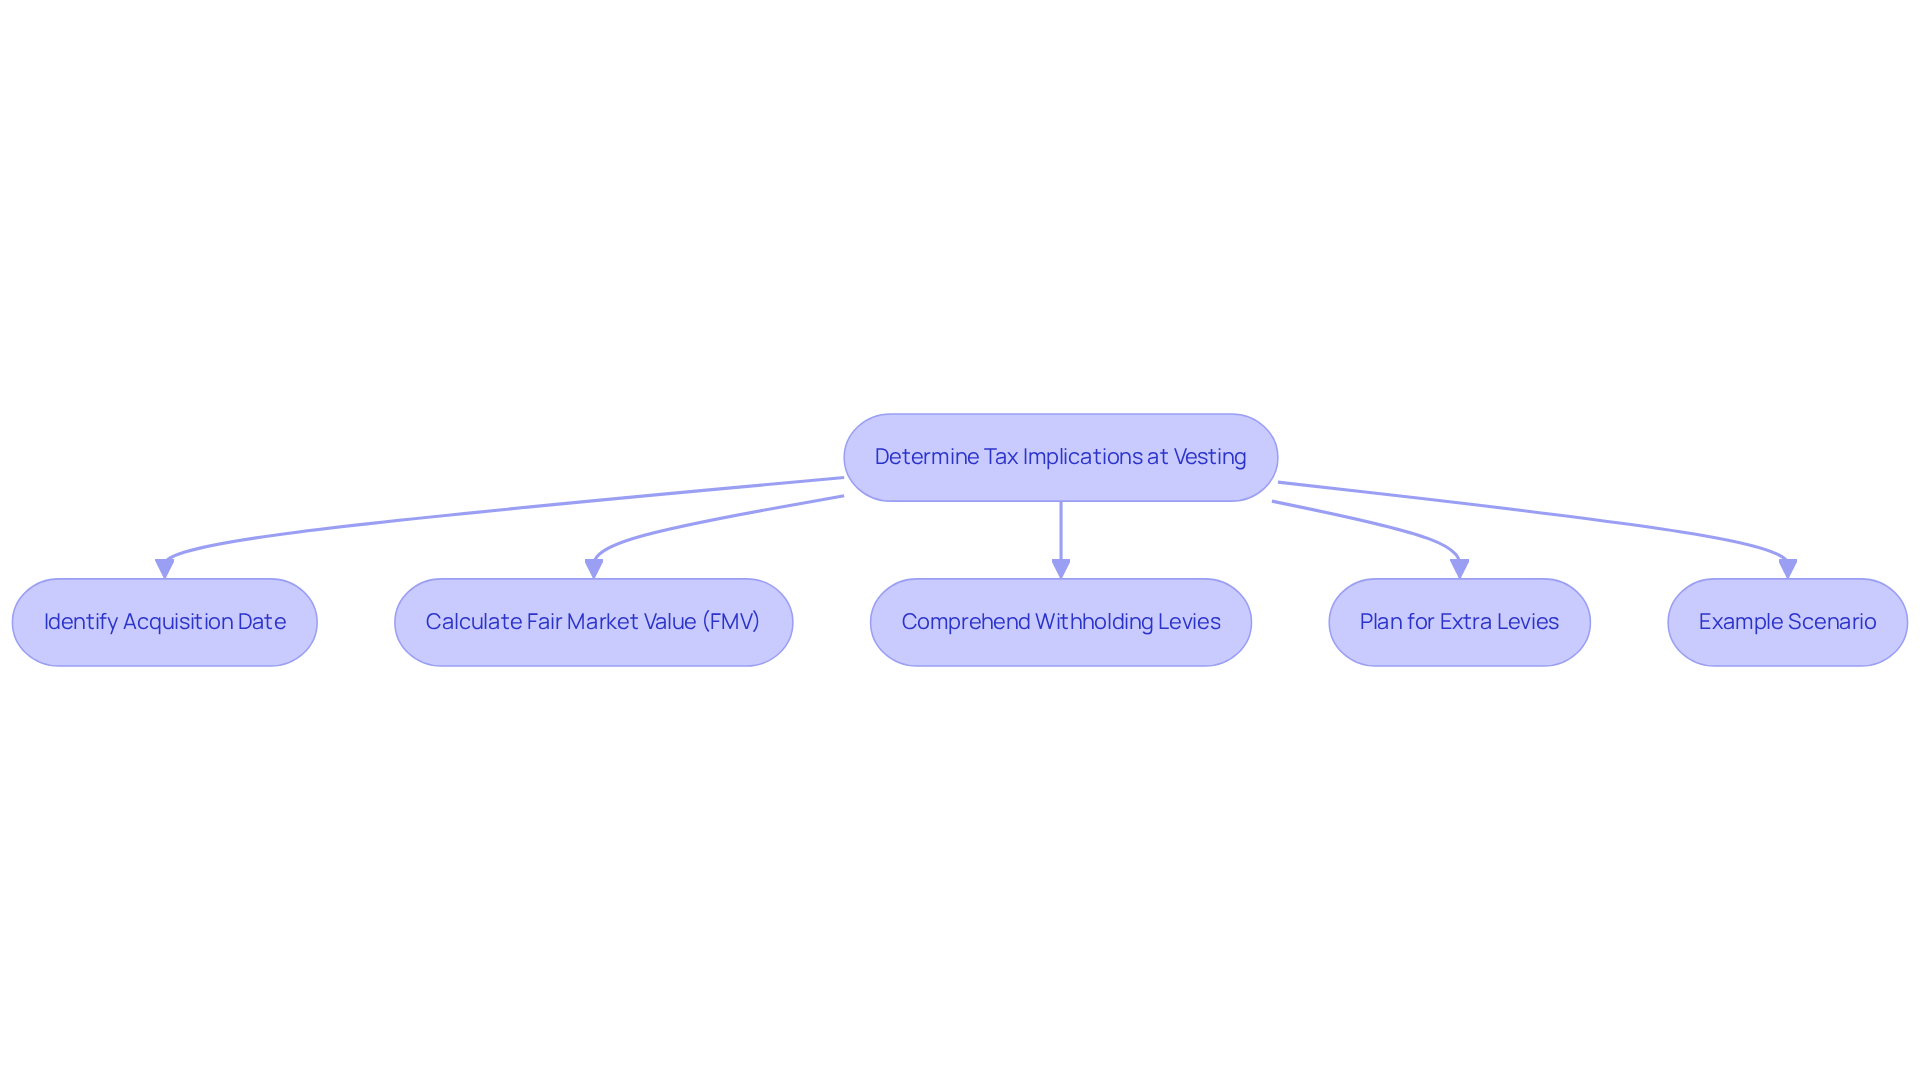
Navigating the world of RSUs can feel overwhelming, especially when it comes to understanding their tax implications for your family. When RSUs become available, they’re categorized as ordinary income, and their fair market value (FMV) at that moment is included in your taxable income. It’s important to grasp how taxes can impact your family’s financial planning, so you can navigate this journey with confidence. Here’s how to approach this process:
- Identify the Acquisition Date: This date is crucial as it marks when your tax liability begins.
- Calculate the Fair Market Value (FMV): Determine the FMV of the shares on the acquisition date, as this amount will be reported as income on your W-2, where RSUs are reported on W-2.
- Comprehend Withholding Levies: Employers typically withhold taxes on the earnings from restricted stock units at vesting. However, this withholding may not cover your total tax liability, especially if you’re in a higher tax bracket. For example, California residents earning above $500,000 may face a combined federal and state tax rate ranging from 45% to over 52% on RSU income.
- Plan for Extra Levies: Many families find it helpful to set aside extra funds for any surprises that might come up when tax season arrives. Setting aside funds to cover any shortfall in withholding is advisable.
Example Scenario:
Imagine your RSUs vest with an FMV of $10,000. This amount is how RSUs are reported on W-2 as income. If your employer withheld $2,500 in taxes but your total tax liability is $3,000, you’ll need to pay the additional $500 when you file your taxes. This understanding is crucial for households to budget effectively for tax season, as insufficient planning can result in unexpected tax bills.
Take, for instance, the inspiring journey of Allison and Brian, who turned their tax challenges into a success story. As a medical device sales representative and a restaurant owner, they initially faced hurdles due to inadequate tax planning. By collaborating with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This empowered them to enjoy more quality time with their loved ones, showcasing how tailored wealth management solutions can enhance financial security and freedom for families.
Note: Past performance does not guarantee future results, and securities investments are subject to risk. Bright Advisers provides advisory services through Lifeworks Advisors, a registered investment adviser.
Report RSUs on Your W-2
Imagine the relief of knowing exactly how to report your RSUs without the stress of unexpected tax surprises.
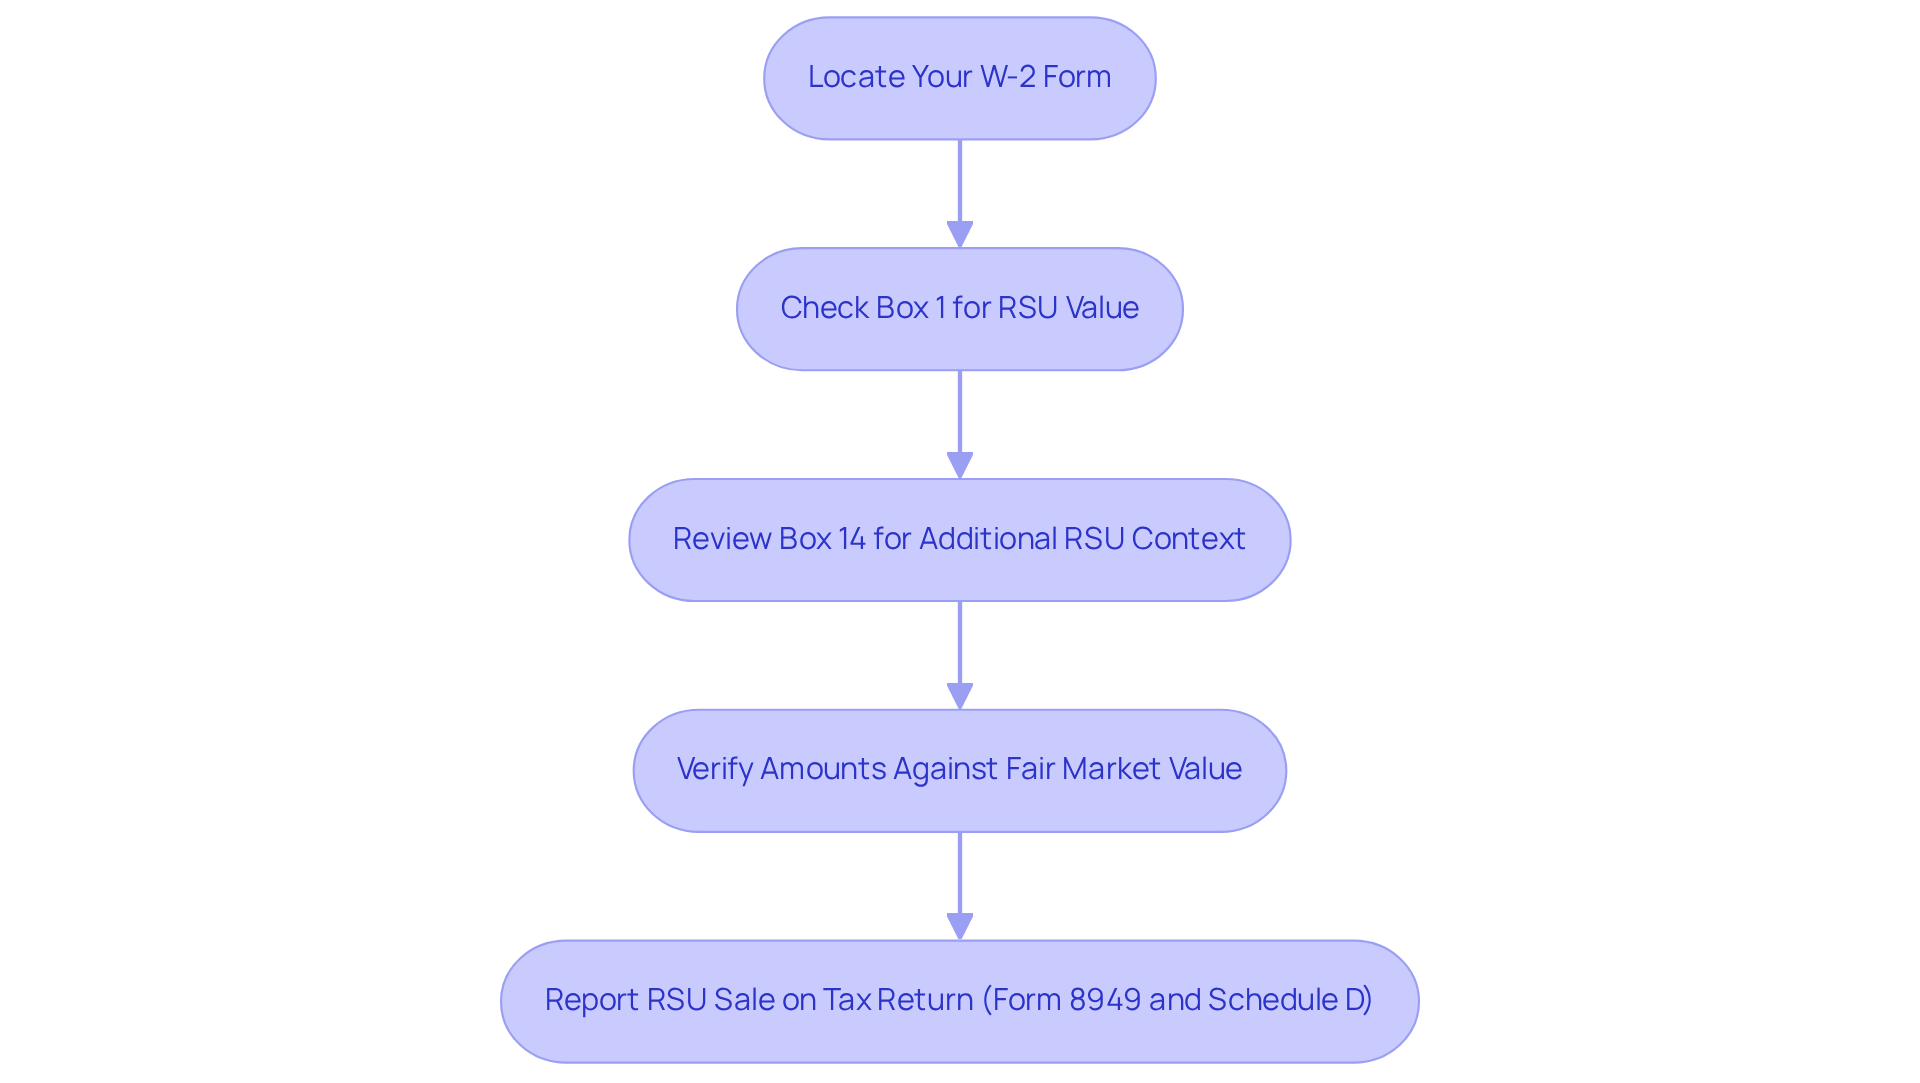
When it comes to reporting, it is important to understand how RSUs are reported on W-2. First, locate your W-2 form. Your employer provides this document, summarizing your earnings and tax withholdings for the year. It’s crucial for accurate reporting.
Next, check Box 1. The value of your vested restricted stock units is typically included here, representing your total taxable income. This figure includes your RSUs, so it’s important to pay attention.
You might also want to review Box 14. Some employers report RSU values in this box, offering additional context for your income. However, it’s not mandatory, so verify its presence.
Make sure the amounts match what you expected based on the fair market value of your RSUs when they vested. If you notice any discrepancies, don’t hesitate to reach out to your employer for clarification. We understand that navigating tax implications can feel overwhelming, especially with family responsibilities on your plate.
If you sell your RSU shares after they vest, remember to report that sale on your tax return. Use Form 8949 and Schedule D to track any capital gains or losses. This step is vital for families aiming to manage their investments effectively and avoid double taxation.
Consider these case studies:
- Reporting RSU Income on W-2: Income from RSUs is reported on the W-2 form, with taxes withheld by employers. However, withholding may not cover the full tax owed, leading to potential estimated tax payments if insufficient withholding occurs.
- Understanding W-2 and Restricted Stock Units: Tech professionals can leverage their understanding of restricted stock units to enhance their financial strategies, ensuring they maximize their compensation effectively.
Consulting a financial advisor can provide tailored strategies for managing RSU-related tax implications. By understanding these steps, you can take control of your financial future and ensure your family’s stability.
Avoid Common Reporting Pitfalls
Navigating the world of RSUs can feel overwhelming, especially when it comes to taxes that could impact your family’s financial future. Families should be vigilant about common pitfalls that can lead to significant tax issues:
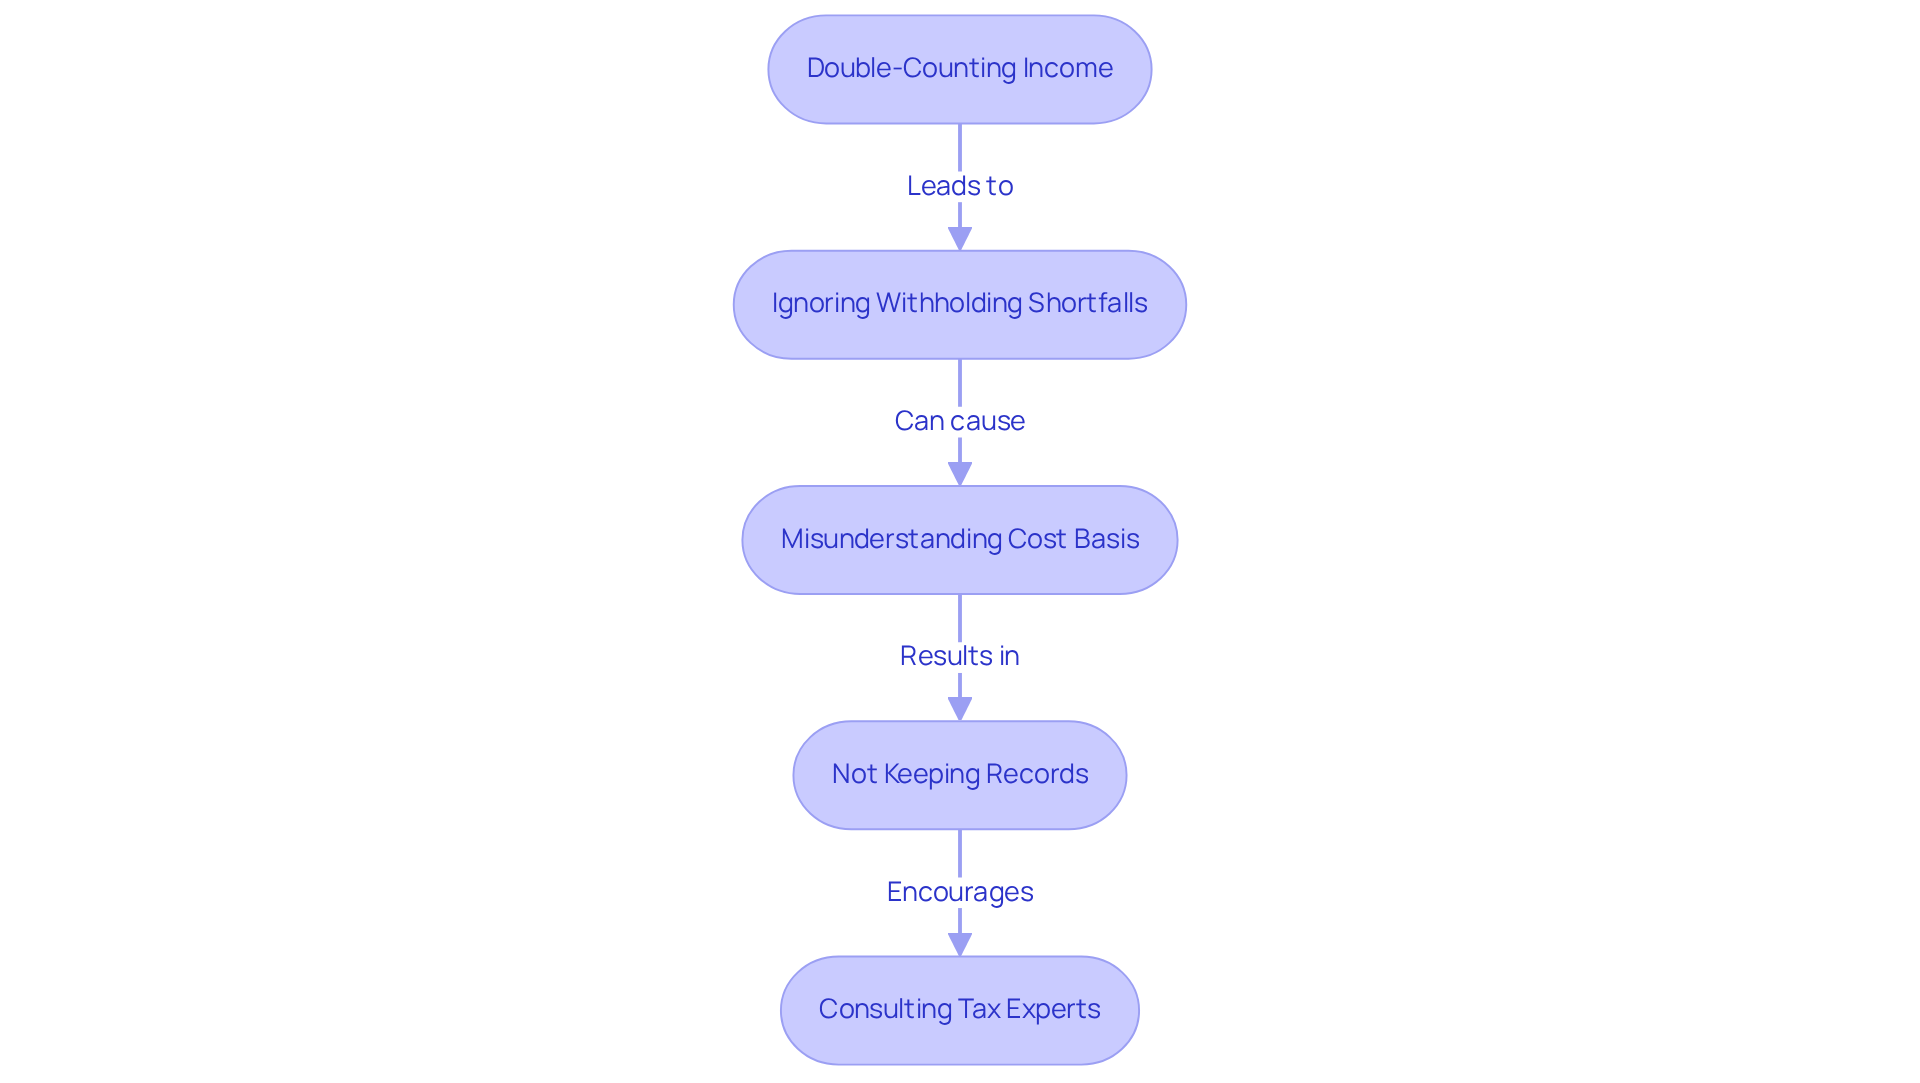
- Double-Counting Income: Imagine the stress of receiving an unexpected tax bill because of a simple mistake. It’s crucial to ensure that the income from RSUs are reported on W-2 and isn’t duplicated on your tax return. This can lead to overreporting your income, which might result in penalties from the IRS.
- Ignoring Withholding Shortfalls: Employers typically withhold 22% for federal taxes on restricted stock units, but this may not cover the actual tax owed. If you suspect your withholding is insufficient, plan for additional tax payments. Failing to do so can lead to underpayment penalties, adding more stress to your financial situation.
- Misunderstanding Cost Basis: When selling RSU shares, accurately reporting the cost basis is essential. This basis should reflect the amount already taxed at the time of acquisition. Incorrect reporting can lead to double taxation on gains, complicating your tax obligations further.
- Not Keeping Records: Maintaining thorough records of RSUs, including vesting dates and the fair market value (FMV) at vesting, is vital. This documentation supports accurate reporting and can help resolve discrepancies with the IRS, preventing unexpected tax liabilities.
- Consulting Tax Experts: If RSU taxation feels complicated, remember, you’re not alone – consider reaching out to a tax expert who can guide you through the intricacies of RSU reporting and clarify how RSUs are reported on W-2 to ensure compliance with tax obligations.
By staying informed and seeking support, you can confidently manage your RSUs and protect your family’s financial well-being.
Conclusion
Navigating the world of Restricted Stock Units (RSUs) can feel overwhelming for families, but understanding their impact on your financial future is essential. When you understand how RSUs work – like their vesting and tax implications – you can make choices that truly benefit your family. With this knowledge, you can feel more confident in managing your compensation and preparing for any tax responsibilities that come your way.
We’ve shared important insights, like knowing the fair market value of RSUs when they vest and how to report them accurately on your W-2. It’s wise for families to be aware of potential tax responsibilities and to reach out for help when needed. By understanding these elements, you can effectively manage your wealth and plan for future expenses, such as education and retirement.
Ultimately, managing RSUs is about building a strong financial future for your family. By taking these steps, you’re not just managing your finances; you’re investing in a brighter future for your family. For personalized assistance in navigating these complexities, consider reaching out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967. Embrace the opportunity to turn financial knowledge into actionable strategies that benefit your family for generations to come.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation from an employer that can convert into real shares of stock once certain conditions are met, helping to secure a family’s financial future.
How do RSUs impact financial planning for families?
Understanding RSUs is essential as they can represent a significant part of an employee’s total compensation package, influencing financial planning strategies for future educational costs or retirement savings.
What is the granting timeline for RSUs?
RSUs typically follow a granting timeline that specifies when you gain the right to the shares, which may be based on time (e.g., after a set number of years) or performance metrics.
How is the value of RSUs determined?
The value of RSUs is directly tied to the company’s stock price, which can fluctuate significantly, impacting overall compensation and financial planning.
How are RSUs taxed?
RSUs are classified as income once they vest, which affects how they are reported on W2 forms and can influence household tax planning.
Why is it important to understand how RSUs are reported on W2?
Knowing how RSUs are reported on W2 is crucial for managing potential tax liabilities and for effective financial planning related to overall compensation.
List of Sources
- Understand Restricted Stock Units (RSUs)
- Financial Planning With Restricted Stock Units: 3 Key Questions | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/restricted-stock-units-and-financial-planning)
- RSUs: Balancing Opportunity and Risk in Modern Compensation (https://resilientplanning.com/blog/rsus-balancing-opportunity-and-risk-in-modern-compensation)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Master RSU Tax Withheld: Essential Strategies for Young Families – Bright Advisers (https://brightadvisers.com/master-rsu-tax-withheld-essential-strategies-for-young-families)
- Determine Tax Implications at Vesting
- California RSU Tax Guide 2026: Withholding Rate, SDI, and the $1M Trap (https://countrytaxcalc.com/tax-guides/california-rsu-tax-guide-2026)
- The Hidden Tax Time Bomb in Your RSU Grants: California Edition – Mission Street Wealth (https://missionstreetwealth.com/california-rsu-taxation-the-hidden-tax-time-bomb)
- RSU Tax in California: What Married Founders Need to Know in 2026 | Neptune Blog (https://meetneptune.com/blog/rsu-tax-in-california)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- Report RSUs on Your W-2
- Restricted Stock Unit (RSU) Tax Guide: Vesting, Selling & Reporting (https://summitry.com/blog/how-are-rsus-taxed)
- How to Report RSUs or Stock Grants on Your Tax Return (https://turbotax.intuit.com/tax-tips/investments-and-taxes/how-to-report-rsus-or-stock-grants-on-your-tax-return/amp/L55yZieu0)
- Are RSUs Included in Your W-2? A Step-by-Step Guide for Parents – Bright Advisers (https://brightadvisers.com/are-rs-us-included-in-your-w-2-a-step-by-step-guide-for-parents)
- How To Report RSUs On My Tax Return (https://schmidtfm.com/blog/how-to-report-rsus-on-my-tax-return)
- How to Report RSUs or Stock Grants on Your Tax Return (https://turbotax.intuit.com/tax-tips/investments-and-taxes/how-to-report-rsus-or-stock-grants-on-your-tax-return/L55yZieu0)
- Avoid Common Reporting Pitfalls
- 6 Common RSU Tax Mistakes (and How to Avoid Them) – Summitry (https://summitry.com/blog/common-rsu-tax-mistakes)
- RSU Cost Basis: How to Calculate It and Avoid the Double-Tax Mistake (https://kbfinancialadvisors.com/rsu-cost-basis-tech-employees-guide)
- Equity Compensation and Retirement Planning (https://executivewealthplanning.com/blog/what-should-i-consider-before-financing-an-early-stock-option-exercise)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading