

Key Highlights
- Life insurance payouts, or death benefits, provide essential financial support for families, especially in times of loss.
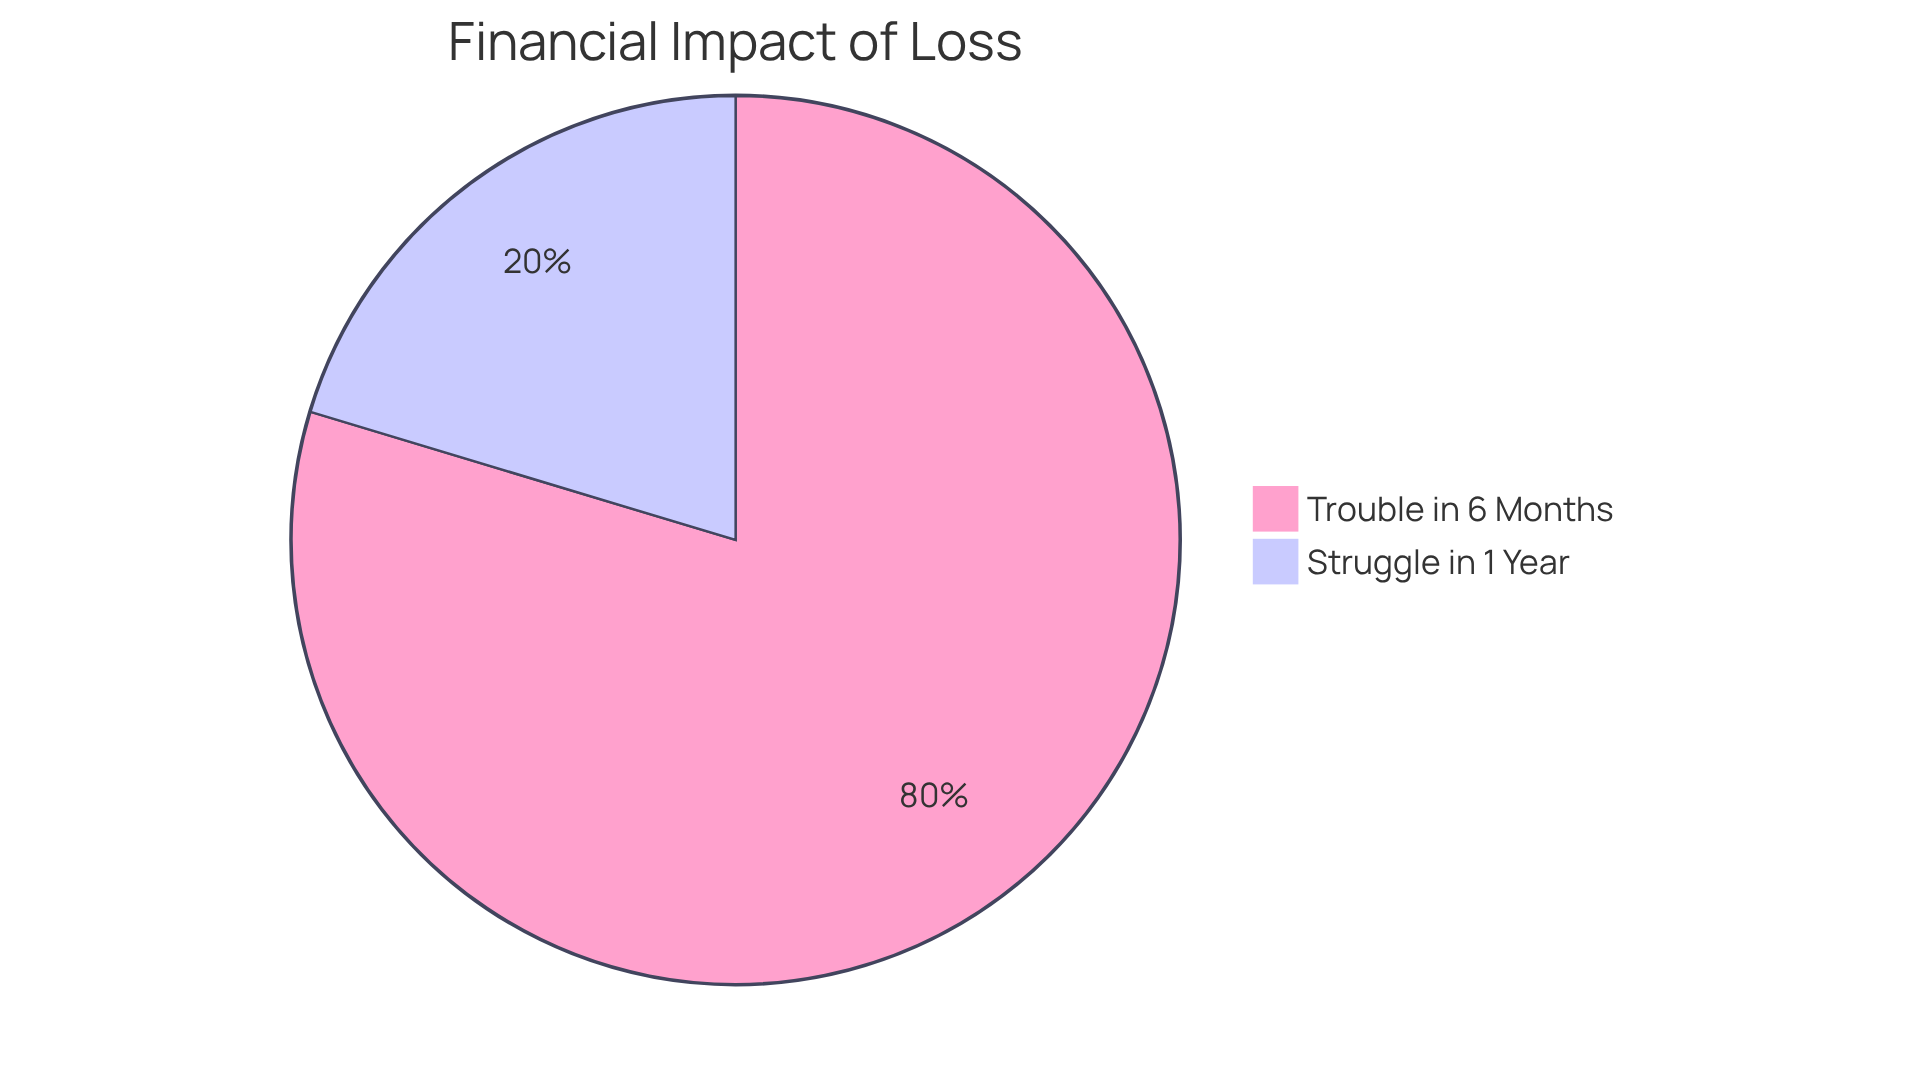
- 12% of families would face financial struggles within a year if the primary earner passes away, underscoring the need for adequate coverage.
- Types of life insurance payouts include lump-sum payments for immediate expenses and instalment payments for ongoing financial stability.
- In 2020, individual policies provided $66.3 billion in death benefits, highlighting the significant impact of life insurance.
- The claims process requires important documents like a certified death certificate and can take 7-60 days depending on complexity.
- Factors influencing life insurance payouts include policy type, the insured’s age and health, and any additional benefits added.
- 56% of households earning below $50,000 express a need for life insurance, indicating a gap in coverage for economically challenged families.
- Working with fiduciary advisors like Bright Advisers can help families create tailored financial strategies to ensure long-term security.
Introduction
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even in the toughest times. Understanding life insurance payouts is crucial for young parents like you, striving to protect your loved ones. These payouts, often called death benefits, can offer vital support during challenging moments, covering everything from daily expenses to long-term educational needs. Yet, many parents feel overwhelmed by the complexities of life insurance, unsure of how to navigate the payout process.
How can you make sure you pick the right policy and smoothly navigate the claims process to keep your loved ones safe?
Define Life Insurance Payouts and Their Importance
Imagine the peace of mind that comes from knowing your family is protected, even in the face of the unexpected. Understanding how do life insurance payouts work is crucial, as these payouts, or death benefits, provide essential support for families when they need it most. For young families, these payouts can be a lifeline, helping cover essential costs like your mortgage, childcare, and education. This coverage can lighten the load, allowing your loved ones to maintain their quality of life during tough times.
Did you know that 12% of families would struggle financially within just a year if the main earner were to pass away? This highlights how vital it is to have enough coverage. In fact, 47% of families would find themselves in financial trouble within six months of losing their primary earner, showing just how important it is to plan ahead.
Real-life stories show the impact of having personal coverage. Many families don’t realize that the support a stay-at-home parent provides can be worth over $50,000 a year. Without this support, families can face unexpected financial pressures, making it crucial to have coverage that considers every family role. Understanding how do life insurance payouts work is crucial for parents to prepare for the unexpected, ensuring their children’s financial security and peace of mind. By prioritizing life coverage, you’re not just planning for the future; you’re ensuring your family’s dreams and stability remain intact, no matter what happens.
Explore Types of Life Insurance Payouts
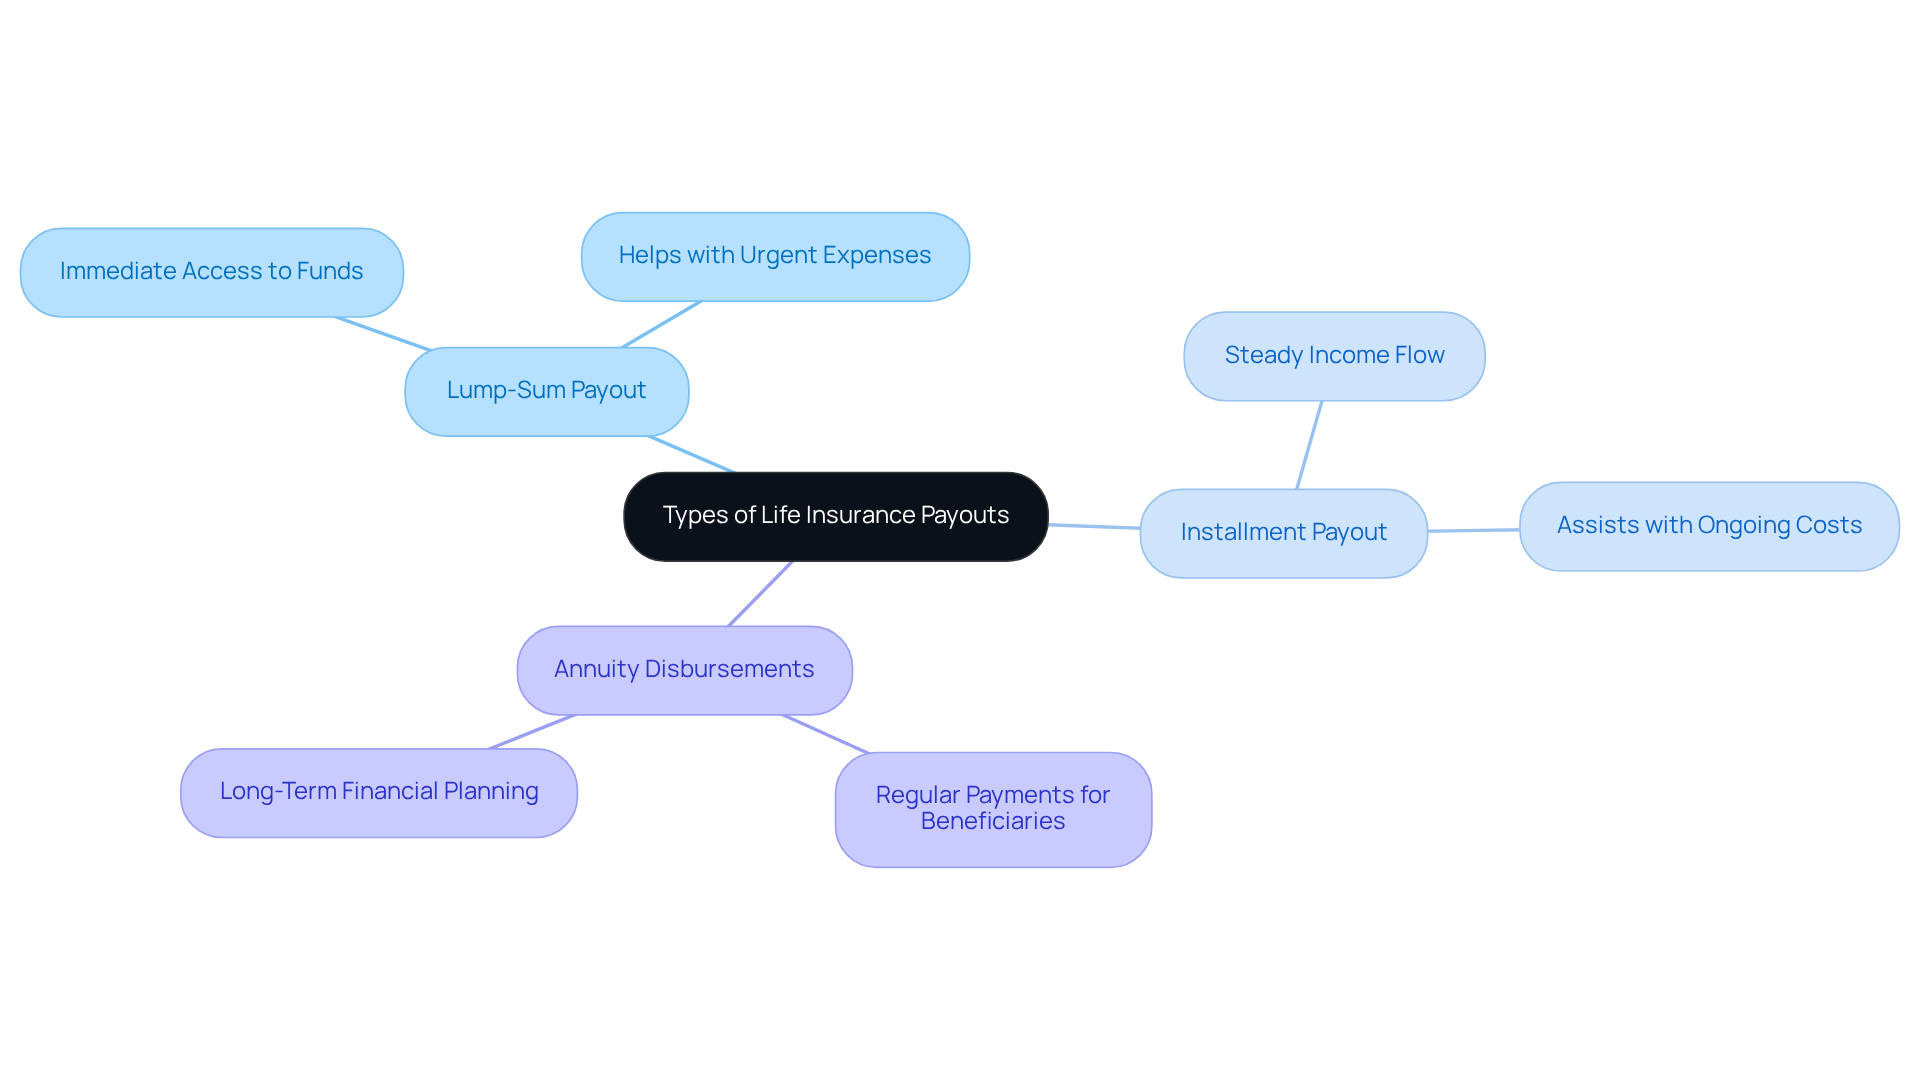
Imagine the peace of mind that comes from knowing your family is financially protected, even in the toughest times. To understand how do life insurance payouts work, it’s important to know that they can be classified into various types, each designed to address specific monetary needs. The most prevalent option is the lump-sum payout, where beneficiaries receive the entire death benefit in one payment. This simple option helps families quickly address urgent expenses like mortgage payments or school fees.
Alternatively, the installment payout allocates the death benefit over a designated timeframe, offering a steady income flow that can assist families in managing ongoing costs. Some policies even provide annuity disbursements, turning the death benefit into regular payments for beneficiaries, which can be especially helpful for long-term financial planning.
Did you know that individual policies provided $66.3 billion in death benefits? That’s a significant amount that can make a real difference for families. Case studies show that many households prefer the lump-sum payment for its promptness, while others opt for installment payments to ensure financial stability over time.
It’s crucial for parents to grasp how do life insurance payouts work so they can choose a policy that truly fits their family’s financial needs. By choosing the right payout option, you can secure your family’s future and ease financial burdens. Choosing the right life insurance payout can be the difference between financial stability and uncertainty for your loved ones.
Understand the Life Insurance Claims Process
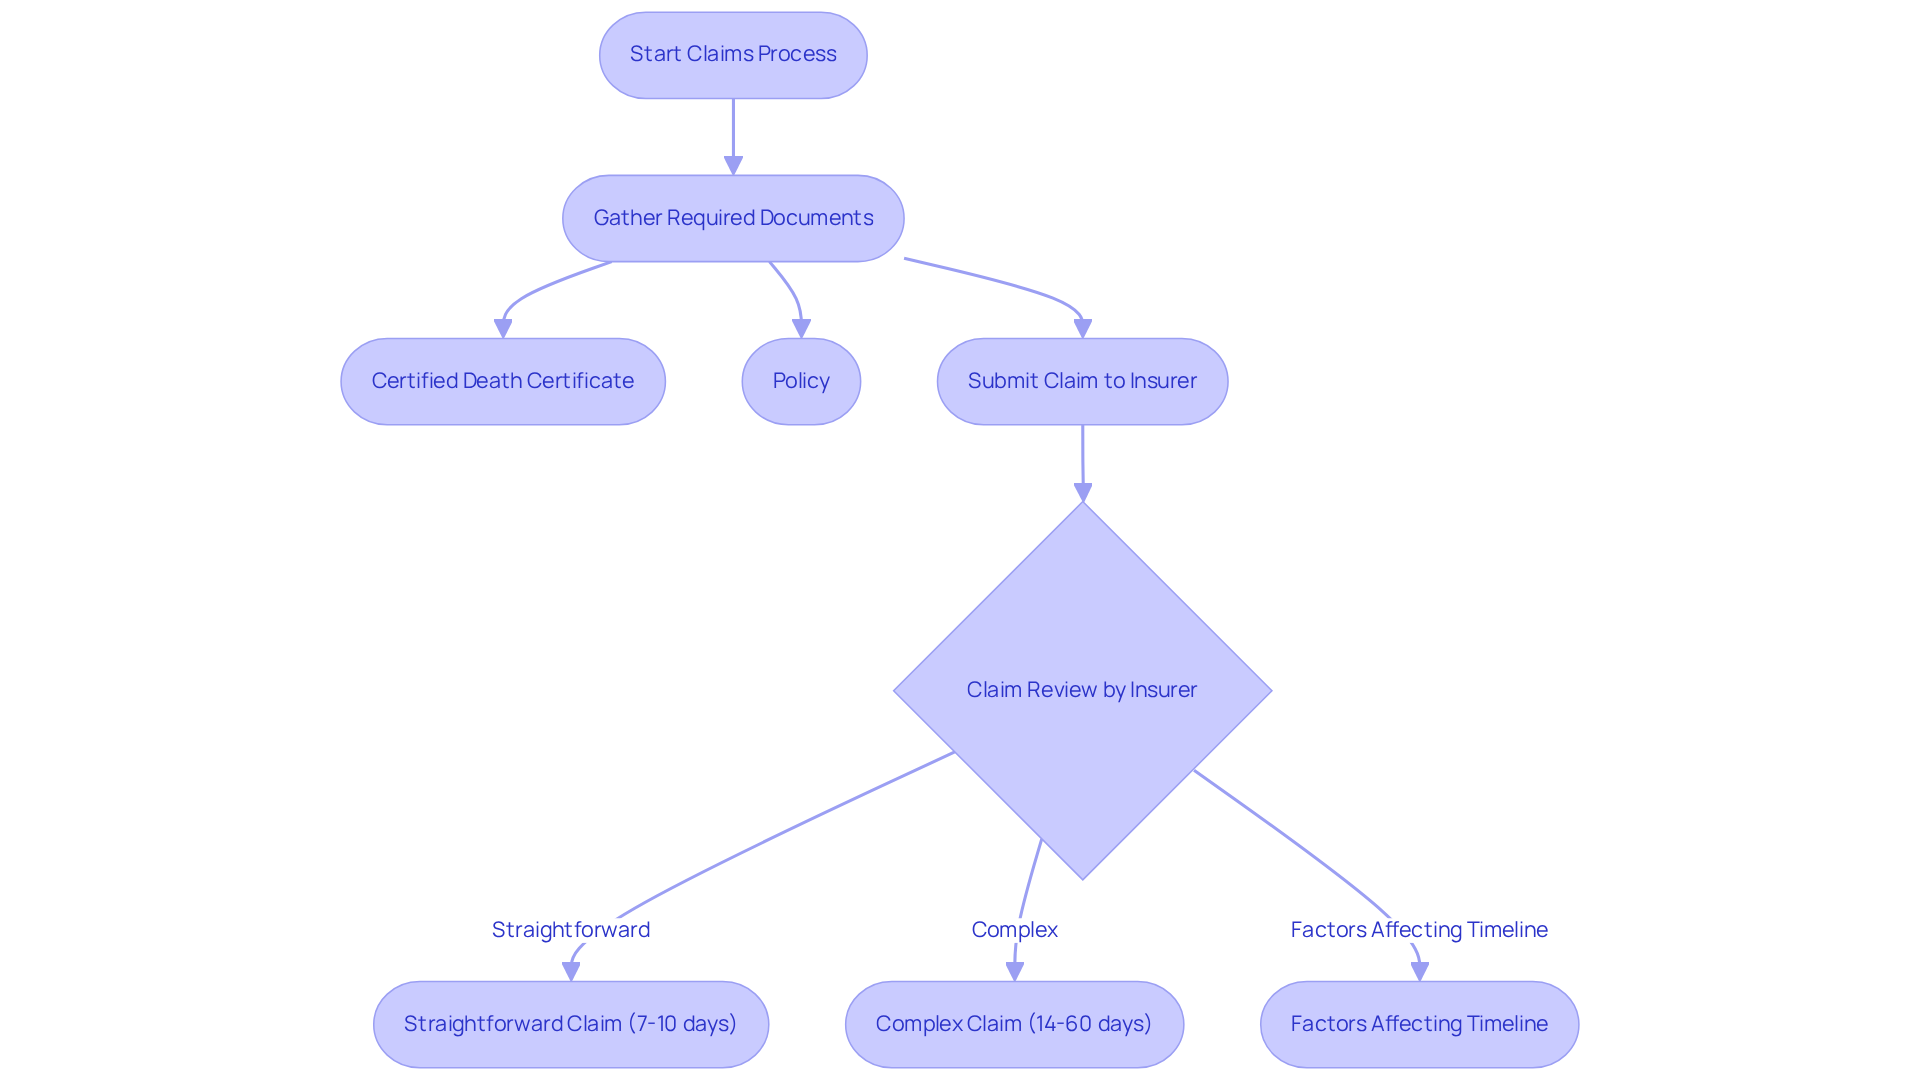
Navigating the claims process after losing a loved one can feel overwhelming, especially when you’re trying to manage everything else on your plate. You’ll need to gather a few important documents, like a certified death certificate and the policy itself, to get started. Insurers will review your claim to ensure it aligns with the policy’s terms and conditions.
It’s important to know that the time it takes to process claims can vary, and understanding this can help ease some of the stress during such a tough time. For straightforward claims, it might take as little as 7-10 business days, while more complex situations could stretch to 14-60 days. Factors like the insurer’s verification requirements and the completeness of your documentation can influence this timeline.
For young parents, understanding how life insurance payouts work can help alleviate some of the financial stress during a time of loss, ensuring timely access to funds when they are needed most. Remember, claims filed during the contestability period may undergo more scrutiny, potentially extending the processing time. By understanding this process, you can focus on what truly matters – your family – during a time of grief.
Identify Factors Influencing Life Insurance Payouts
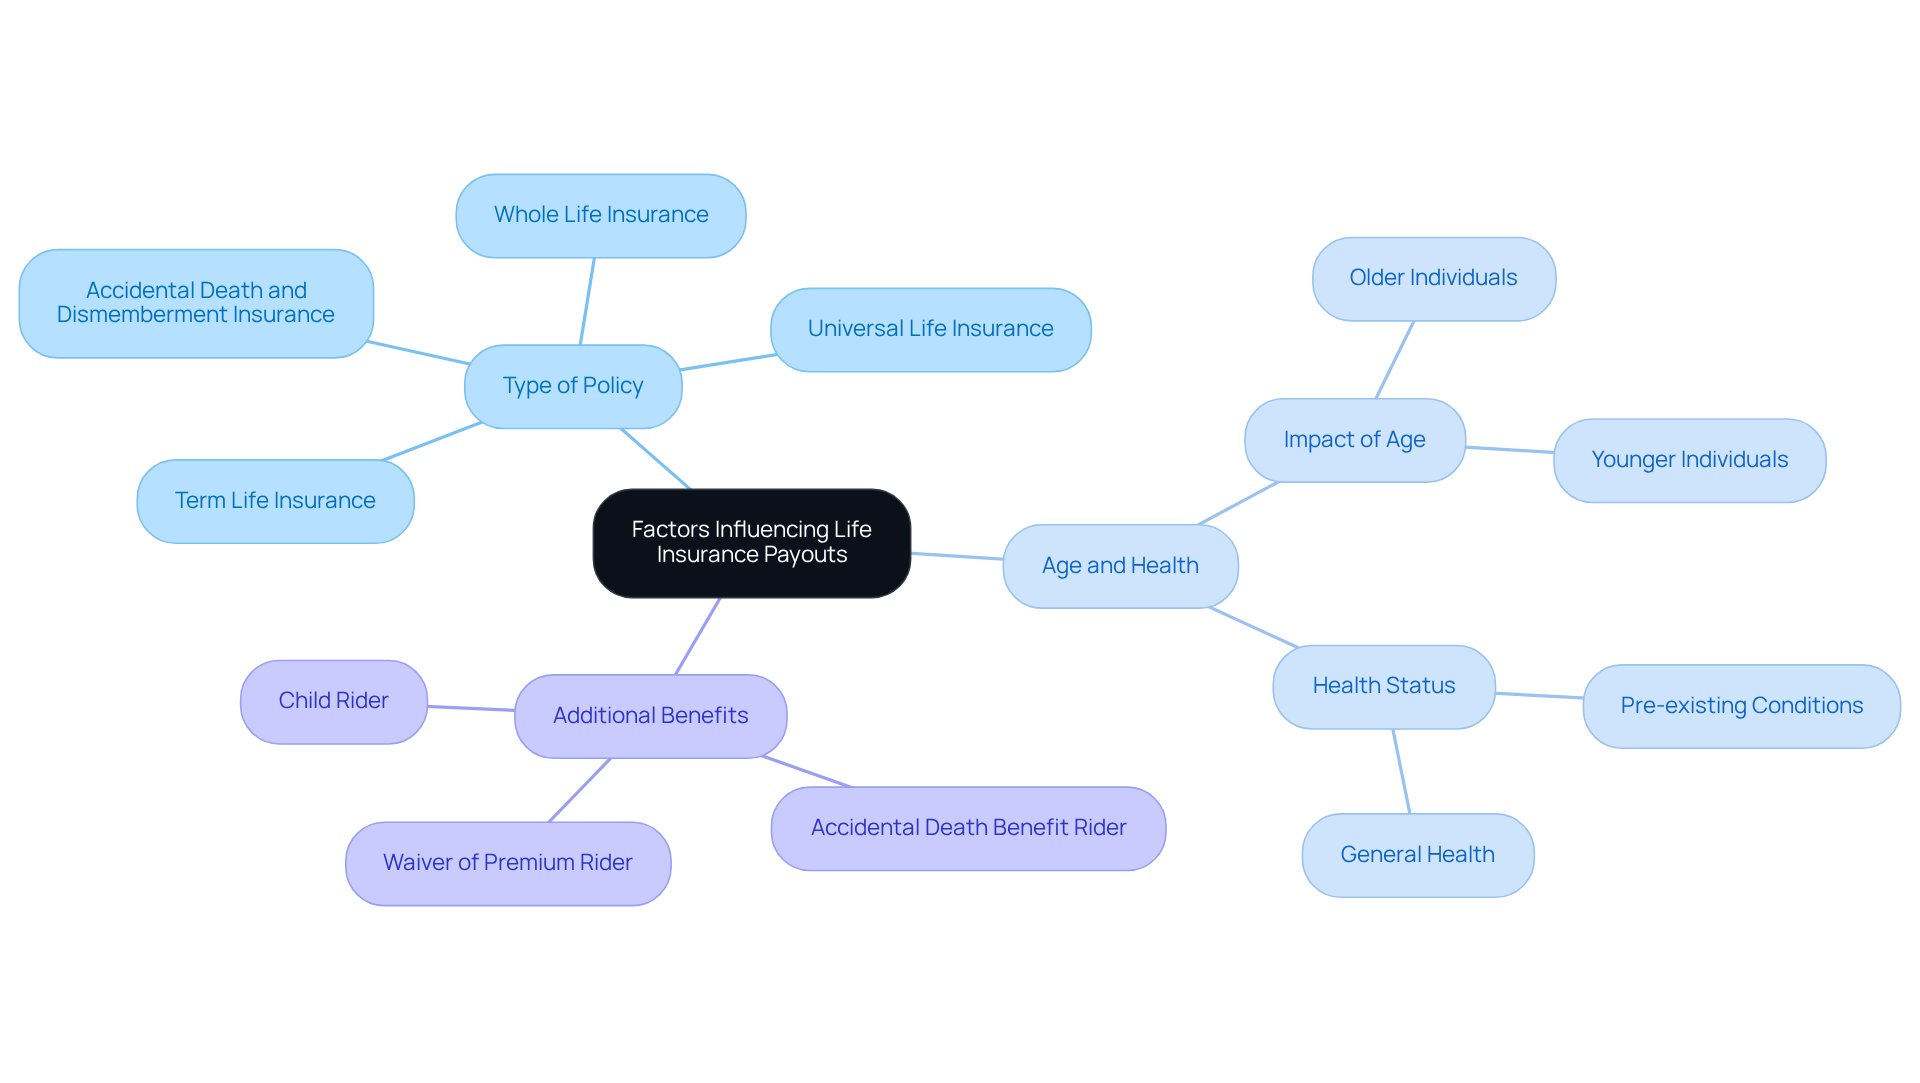
Imagine the peace of mind that comes from knowing your loved ones are protected, even in uncertain times. Several important factors can influence how do life insurance payouts work and how much your loved ones will receive from a policy. These include:
- The type of policy you choose
- Your age and health when you apply
- Any additional benefits you might add
For example, if you include an accidental death benefit rider, your family could receive a higher payout if something unexpected happens. The insurer’s underwriting process is crucial in understanding how do life insurance payouts work, as it assesses the risk of insuring you, which can directly affect the payout amount.
Many families, like yours, rely on life insurance to help replace lost income and maintain their lifestyle during tough times. Yet, a significant number of people feel they don’t have enough coverage. In fact, 56% of households earning below $50,000 annually express a need for life insurance, highlighting the importance for families facing economic challenges. For young families, understanding these factors is key to selecting a policy that meets your current needs and adapts as your life changes.
Consider Jay and Emma, a couple with two kids who turned to Bright Advisers for help. They wanted to ease their financial stress and make the most of their resources. Together, they crafted a comprehensive financial strategy that included tax planning and education savings options, giving them reassurance about their family’s future.
Similarly, Emily and Mark, both busy professionals, worked with Bright Advisers to create a financial plan that allowed them the freedom to choose whether to continue working. Their collaboration led to a clearer understanding of their financial situation and a strategy that aligned with their personal and financial goals.
By taking these steps, you can ensure your family’s future is secure, no matter what life throws your way. With the support of Bright Advisers, families can navigate the complexities of financial planning and create tailored solutions that empower their financial security and educational readiness. It’s essential to maintain active coverage to protect your loved ones when it matters most.
Conclusion
Imagine the worry that creeps in when you think about your family’s future without you. Understanding how life insurance payouts work is essential for young parents seeking to secure their family’s financial future. These payouts, often called death benefits, act as a comforting safety net, helping your loved ones keep their lives on track during tough times. When you embrace life insurance, you’re taking a step to shield your family from unexpected challenges, so you can focus on what truly matters – your children’s happiness and future.
Throughout this article, we’ve explored the different types of life insurance payouts available, including lump-sum and installment options, each designed to meet various financial needs. We also discussed the claims process, highlighting the importance of being prepared with necessary documentation to ensure timely access to funds. Additionally, we touched on the factors that influence payout amounts, emphasizing the significance of choosing the right policy and understanding underwriting processes.
Ultimately, the importance of life insurance for young families cannot be overstated. It’s not just a financial product; it’s a vital part of a comprehensive financial strategy that brings peace of mind and stability. Families are encouraged to engage with fiduciary advisors like Bright Advisers, who can provide personalized guidance and support in navigating these critical decisions. By taking proactive steps today, you can embrace the joy of parenting, knowing your family’s future is secure, no matter what life throws your way.
Frequently Asked Questions
What are life insurance payouts?
Life insurance payouts, also known as death benefits, are the funds provided to beneficiaries upon the death of the insured individual. These payouts offer essential financial support to families during difficult times.
Why are life insurance payouts important?
Life insurance payouts are important because they help cover essential costs such as mortgages, childcare, and education, providing financial stability for families when they need it most.
How quickly can families face financial difficulties without life insurance?
According to statistics, 12% of families would struggle financially within just a year if the main earner were to pass away, and 47% would find themselves in financial trouble within six months.
What is the financial value of a stay-at-home parent’s support?
The support provided by a stay-at-home parent can be worth over $50,000 a year, highlighting the importance of having adequate life insurance coverage that considers all family roles.
How can life insurance help families prepare for the unexpected?
Life insurance helps families prepare for the unexpected by ensuring financial security and peace of mind, allowing them to maintain their quality of life and pursue their dreams, regardless of unforeseen circumstances.
List of Sources
- Define Life Insurance Payouts and Their Importance
- Life Insurance Statistics, Facts, And Industry Trends For 2026 (https://choicemutual.com/original-research/life-insurance-statistics)
- Facts + Statistics: Life insurance | III (https://iii.org/fact-statistic/facts-statistics-life-insurance)
- How Long Could Your Family Survive Without Your Income? New Data Shows Most Households Need More Life Insurance Than They Think (https://everlylife.com/blog/data-shows-when-families-feel-financial-impact)
- The Value of Life Insurance for Young Families – WoodmenLife (https://blog.woodmenlife.org/the-value-of-life-insurance-for-young-families)
- Updated: Life Insurance for Families: Protecting Your Loved Ones | LifePlanify Blog (https://lifeplanify.co/blog/life-insurance-for-families)
- Explore Types of Life Insurance Payouts
- Top Life Insurance Statistics of 2026 (https://moneygeek.com/insurance/life/life-insurance-statistics)
- Life Insurance Statistics, Data and Industry Trends (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Life Insurance Statistics (https://thezebra.com/resources/research/life-insurance-statistics)
- Benefits and Claims (https://iii.org/publications/triple-i-insurance-facts/life-annuity-financial-data/benefits-and-claims)
- Understand the Life Insurance Claims Process
- How Long Do Life Insurance Claims Take? | Daly & Black, P.C. (https://dalyblack.com/how-long-do-life-insurance-claims-take)
- How long does life insurance take to pay out? (https://protective.com/learn/how-quickly-are-life-insurance-claims-paid)
- Aflac Supplemental Insurance (https://aflac.com/resources/life-insurance/how-long-does-life-insurance-take-to-pay-out.aspx)
- How Long Does It Take To Get Life Insurance Payout? (https://coventrydirect.com/blog/how-long-does-it-take-for-life-insurance-payout)
- Identify Factors Influencing Life Insurance Payouts
- Life Insurance Statistics, Data and Industry Trends (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Life Insurance Statistics (https://thezebra.com/resources/research/life-insurance-statistics)
- Understanding the Factors that Impact Life Insurance Payouts: What Your Family Should Know (https://linkedin.com/pulse/understanding-factors-impact-life-insurance-payouts-what-konkwo-xpfsc)
- What are the Key Factors that Determine A Life Settlement Payout | Lighthouse Life (https://lighthouselife.com/news/key-factors-that-determine-life-settlement-payout)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading