

Overview
The formation of an LLC can significantly impact personal taxes for young families, primarily through the benefits of pass-through taxation. This allows business income to be reported directly on the owners’ personal tax returns, simplifying the tax process and providing peace of mind. Imagine the relief of knowing that your hard-earned income is being handled in a way that feels straightforward and manageable.
It’s important to understand that LLCs can open doors to substantial tax deductions, such as the Qualified Business Income deduction. This potential for savings can enhance your financial planning, making it easier to prioritize what truly matters for your family. Together, we can navigate this journey toward greater tax efficiency and financial security.
By considering the formation of an LLC, you are taking a proactive step in your financial management. We’re here for you, ready to support you as you explore these options and make informed decisions that align with your family’s values and goals.
Key Highlights:
- An LLC combines benefits of corporations and partnerships, offering personal liability protection for owners.
- Forming an LLC is strategic for young households, providing asset protection and tailored financial planning.
- LLCs can be structured for pass-through taxation, simplifying tax processes for owners.
- The formation of LLCs among young households has increased by over 20% recently, indicating growing recognition of their benefits.
- Key steps to form an LLC include selecting a business name, appointing a registered agent, and filing necessary documents.
- LLCs are categorized as pass-through entities, meaning income flows directly to owners’ personal tax returns.
- Single-member LLCs report income on Schedule C of Form 1040, while multi-member LLCs file Form 1065 and provide Schedule K-1 to members.
- Eligible LLC owners may qualify for the Qualified Business Income deduction, potentially allowing a 20% business income deduction.
- Filing taxes as an LLC involves determining tax classification, gathering financial records, completing appropriate forms, and claiming deductions.
- Utilizing resources like IRS guidelines, tax software, and professional consultants can optimize LLC tax outcomes.
Introduction
In today’s increasingly complex financial landscape, young families are discovering the empowering potential of Limited Liability Companies (LLCs) as a strategic tool for securing their financial future. Imagine a solution that combines the protective features of corporations with the flexibility of partnerships. LLCs not only offer personal liability protection but also simplify tax processes and pave the way for entrepreneurial success.
As families navigate the intricacies of business ownership and investment, it’s important to understand the formation, tax implications, and filing requirements of an LLC. This article gently delves into the myriad benefits of LLCs, providing insights and practical guidance tailored for families eager to safeguard their assets while pursuing their dreams. Together, we can navigate this journey toward financial security.
Define an LLC and Its Purpose
A Limited Liability Company (LLC) is a versatile business structure that beautifully combines the advantages of both corporations and partnerships. One of its primary benefits is personal liability protection for owners, ensuring that personal assets are shielded from business debts and legal claims. This feature makes limited liability companies especially appealing to small business proprietors and entrepreneurs. For young households, forming an LLC can be a strategic choice for managing household-owned enterprises or investments, providing a layer of protection for personal resources while aligning with the tailored monetary planning offered by Bright Advisers.
Limited liability companies also offer flexibility in management and taxation. They can be structured to facilitate pass-through taxation, leading to the inquiry of how does LLC affect personal taxes since profits and losses are reported directly on the owners’ personal tax returns. This simplifies the tax process, making it easier for households to navigate their financial responsibilities and understand how does llc affect personal taxes. Recent statistics show that the formation of LLCs among young households has increased by over 20% in the past few years, highlighting their growing recognition of the benefits associated with this business structure.
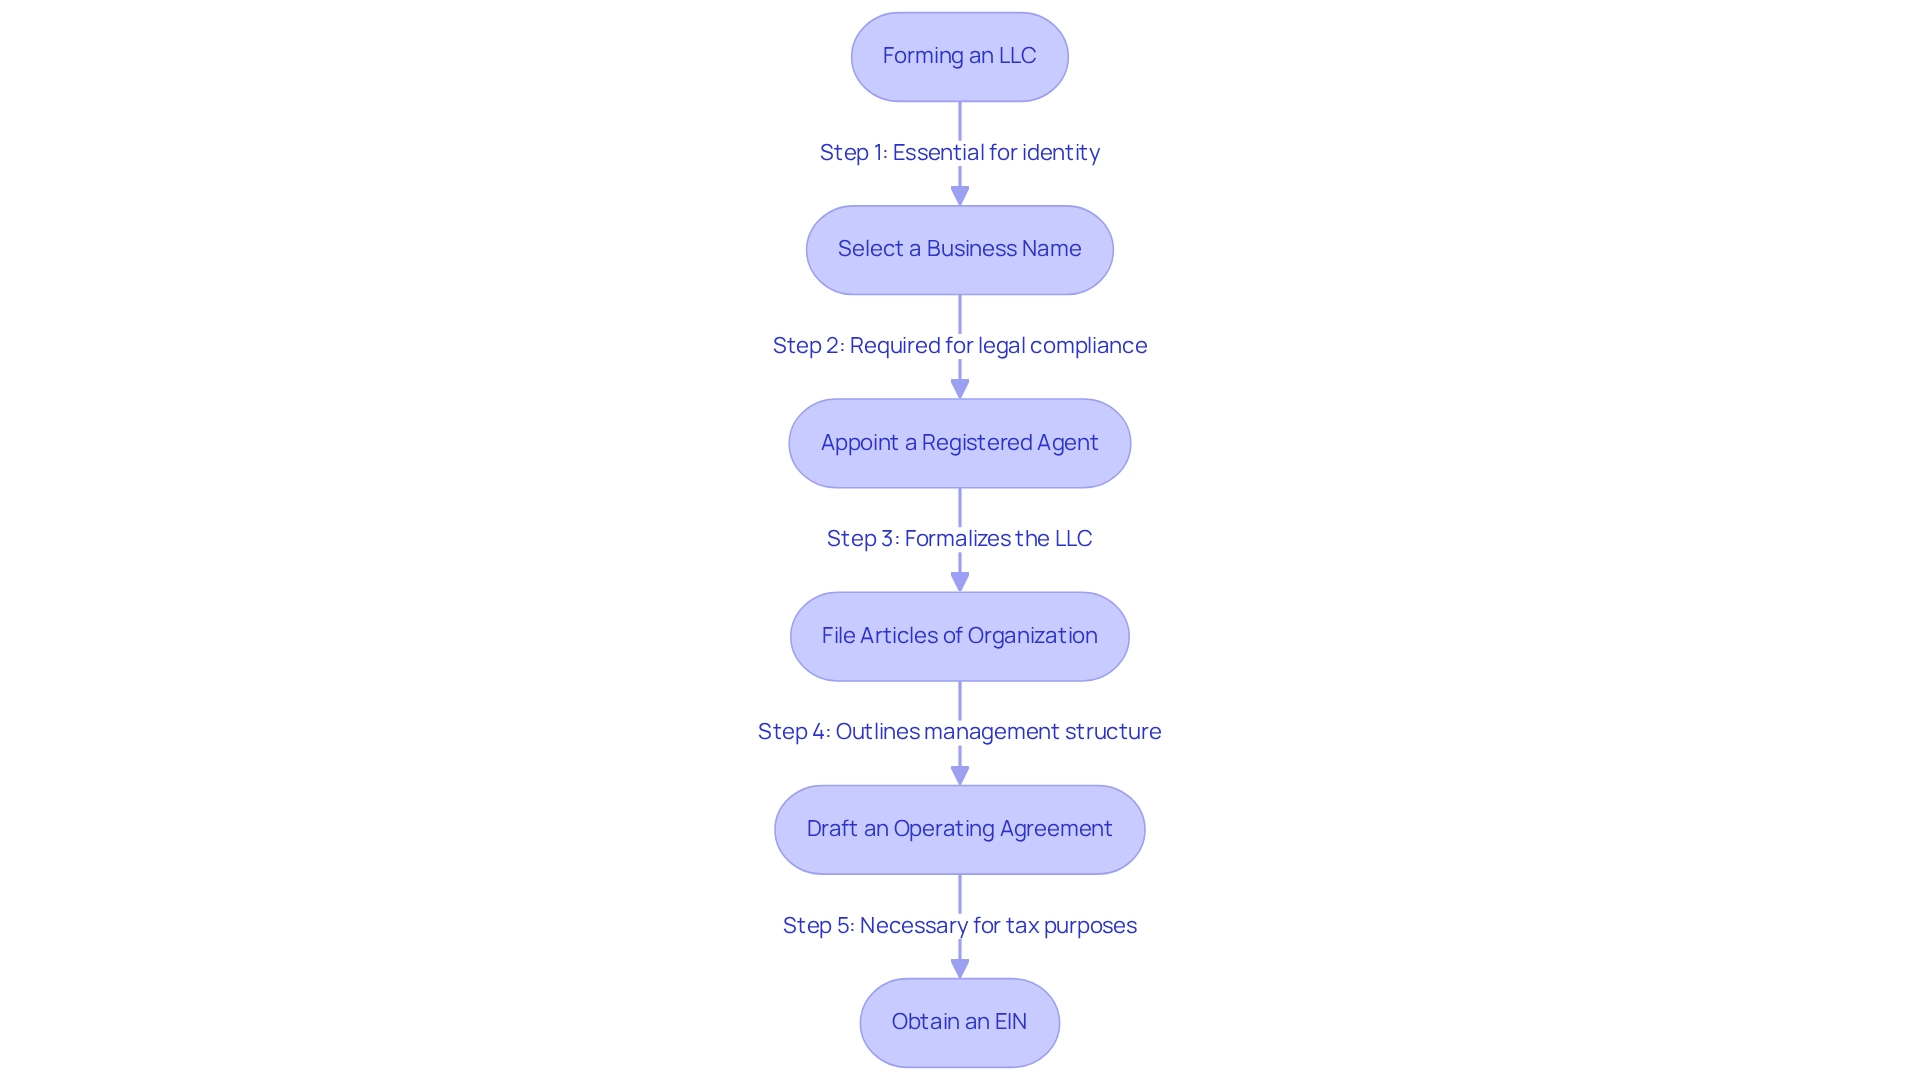
To form an LLC, families typically need to:
- Select a business name
- Appoint a registered agent
- File the articles of organization
- Draft an operating agreement
- Obtain an EIN
These steps are essential for ensuring compliance with IRS terms and conditions, and they can be effectively managed with the guidance of a wealth management partner like Bright Advisers, whose innovative platform connects financial planning with investment strategies.
Real-world examples illustrate how LLCs can effectively protect personal assets. Imagine a family-owned bakery operating as an LLC; it can safeguard the owners’ home and personal savings from any potential lawsuits or debts incurred by the business. This protective measure is crucial for households aiming to build and sustain wealth over generations, aligning perfectly with Bright Advisers’ mission to empower individuals through customized wealth management solutions.
As Jeff Dobyns, Founder & President of SageSpring, shares, “You choose a partner who champions your dreams, celebrates your victories, and walks beside you on the path to achieving your unique goals.” In this context, an LLC can act as that partner, offering a foundational tool for economic security and strategic planning, backed by the innovative wealth management platform of Bright Advisers.
In summary, the purpose of an LLC for young households extends beyond simple business operations; it serves as a foundational tool for economic security and strategic planning. By leveraging the benefits of an LLC, families can ensure their personal assets remain protected while pursuing their entrepreneurial goals and learn how does llc affect personal taxes, all while receiving the personalized support they need from Bright Advisers. To learn more about how Bright Advisers can assist you in your financial journey, consider joining our waitlist today.
Explore the Tax Implications of an LLC
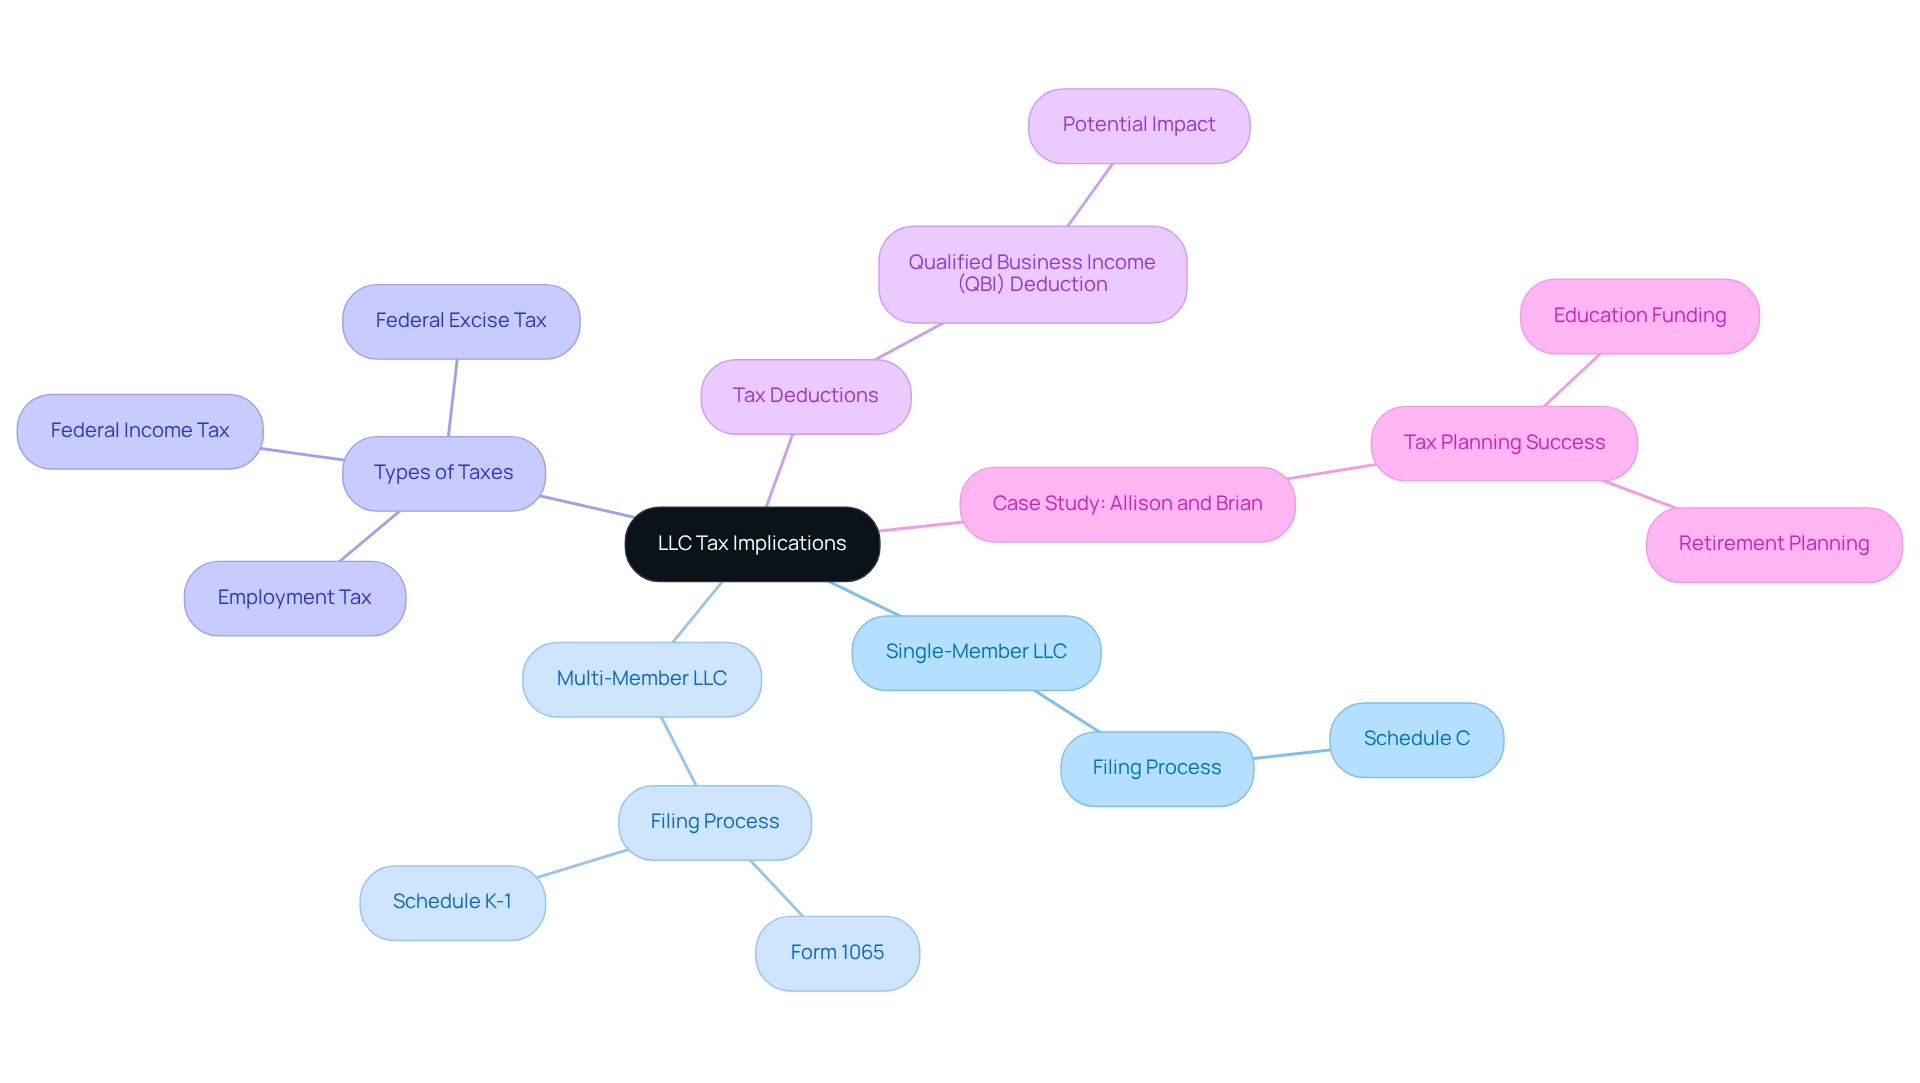
Limited liability companies (LLCs) can be a valuable tool for families, and understanding how does LLC affect personal taxes is important since they are often categorized as pass-through entities for tax purposes. This means that the income they generate isn’t subject to corporate taxation; instead, it raises the question of how does LLC affect personal taxes by flowing directly to the owners’ personal tax returns. For single-member LLCs, this process is quite simple—the owner reports income and expenses on Schedule C of their Form 1040. However, for multi-member LLCs, the process involves filing Form 1065, with each member receiving a Schedule K-1 that details their share of profits or losses.
As you navigate your financial journey, it’s essential to be aware of the common federal taxes associated with LLCs, including federal income taxes, employment taxes, and federal excise tax. Understanding this structure can lead to significant tax savings, especially for those LLCs that qualify for the Qualified Business Income (QBI) deduction, prompting the inquiry of how does LLC affect personal taxes. Eligible owners can deduct up to 20% of their business income, which can greatly reduce their taxable income. Looking ahead to 2025, many LLCs are expected to qualify for this deduction, making it a crucial consideration for young families eager to optimize their financial resources while understanding how does LLC affect personal taxes. By leveraging the benefits of pass-through taxation, families can enhance their financial planning, highlighting the importance of understanding how does LLC affect personal taxes. Imagine being able to manage your income strategically to maximize deductions and minimize tax liabilities.
Take Allison and Brian, for example; as a dedicated medical device sales representative and a passionate restaurant owner, they initially struggled with tax planning. However, by partnering with Bright Advisers, they transformed their tax situation, secured their children’s future through education funding, and gained the freedom to retire sooner. Bright Advisers provided tailored services, including education savings options and retirement planning strategies, empowering them to achieve economic security and independence.
By grasping the nuances of LLC taxation, young families can make informed decisions that bolster their financial stability and growth. Remember, we’re here for you—together, we can navigate this journey toward a brighter financial future.
Guide to Filing Taxes as an LLC
Filing taxes as an LLC can feel overwhelming, especially for young families. However, by following these essential steps, you can navigate the complexities of your tax obligations with confidence:
-
Determine Your Tax Classification: It’s crucial to decide how your LLC will be taxed—whether as a sole proprietorship, partnership, or corporation. This choice significantly influences the question of how does LLC affect personal taxes and can affect your financial outcomes. For example, if you select a partnership structure, be mindful that your deductible loss may be limited. Consider the case of Thomas, who holds a 30% membership interest in his LLC, which restricts his deductible loss to $2,000 from a $10,000 net loss.
-
Gather Financial Records: Take the time to compile all your income and expense documentation for the tax year. This includes invoices, receipts, and bank statements, ensuring that you can report accurately.
-
Complete the Appropriate Forms:
- If you have a single-member LLC, you’ll need to file Schedule C alongside your Form 1040.
- For multi-member LLCs, submit Form 1065 and provide each member with a Schedule K-1 to report their share of income.
-
Claim Deductions: Identify and claim eligible deductions such as business expenses, home office deductions, and the Qualified Business Income (QBI) deduction. These can significantly reduce your taxable income. Working with a monetary consultant from Bright Advisers can help you discover further tax enhancement tactics tailored to your family’s unique circumstances, including budgeting, cash flow forecasts, and asset monitoring. File on Time: Remember to adhere to filing deadlines—typically April 15 for individual returns and March 15 for partnerships. If needed, consider filing for an extension to avoid penalties.
-
Consult a Tax Professional: Engaging a tax advisor can provide clarity and ensure compliance, optimizing your tax situation and helping you avoid common filing errors. Bright Advisers offers comprehensive household fiscal strategies that align your values, vision, and goals with effective tax planning, empowering you to secure your economic future.
It’s important to recognize that households often spend an average of 13 hours preparing their LLC tax returns. This highlights the significance of organization and understanding the filing process. Additionally, statistics indicate that LLCs experience a higher rate of tax filing errors, making it essential to follow these steps carefully. By implementing effective tax filing strategies and leveraging the expertise of Bright Advisers, you can navigate the complexities of how does LLC affect personal taxes while enhancing your financial security. Furthermore, with the minimal audit rate for large partnerships in recent years, it’s vital to stay informed about potential changes that could influence your choice of entity and filing strategies.

Utilize Resources for Tax Optimization
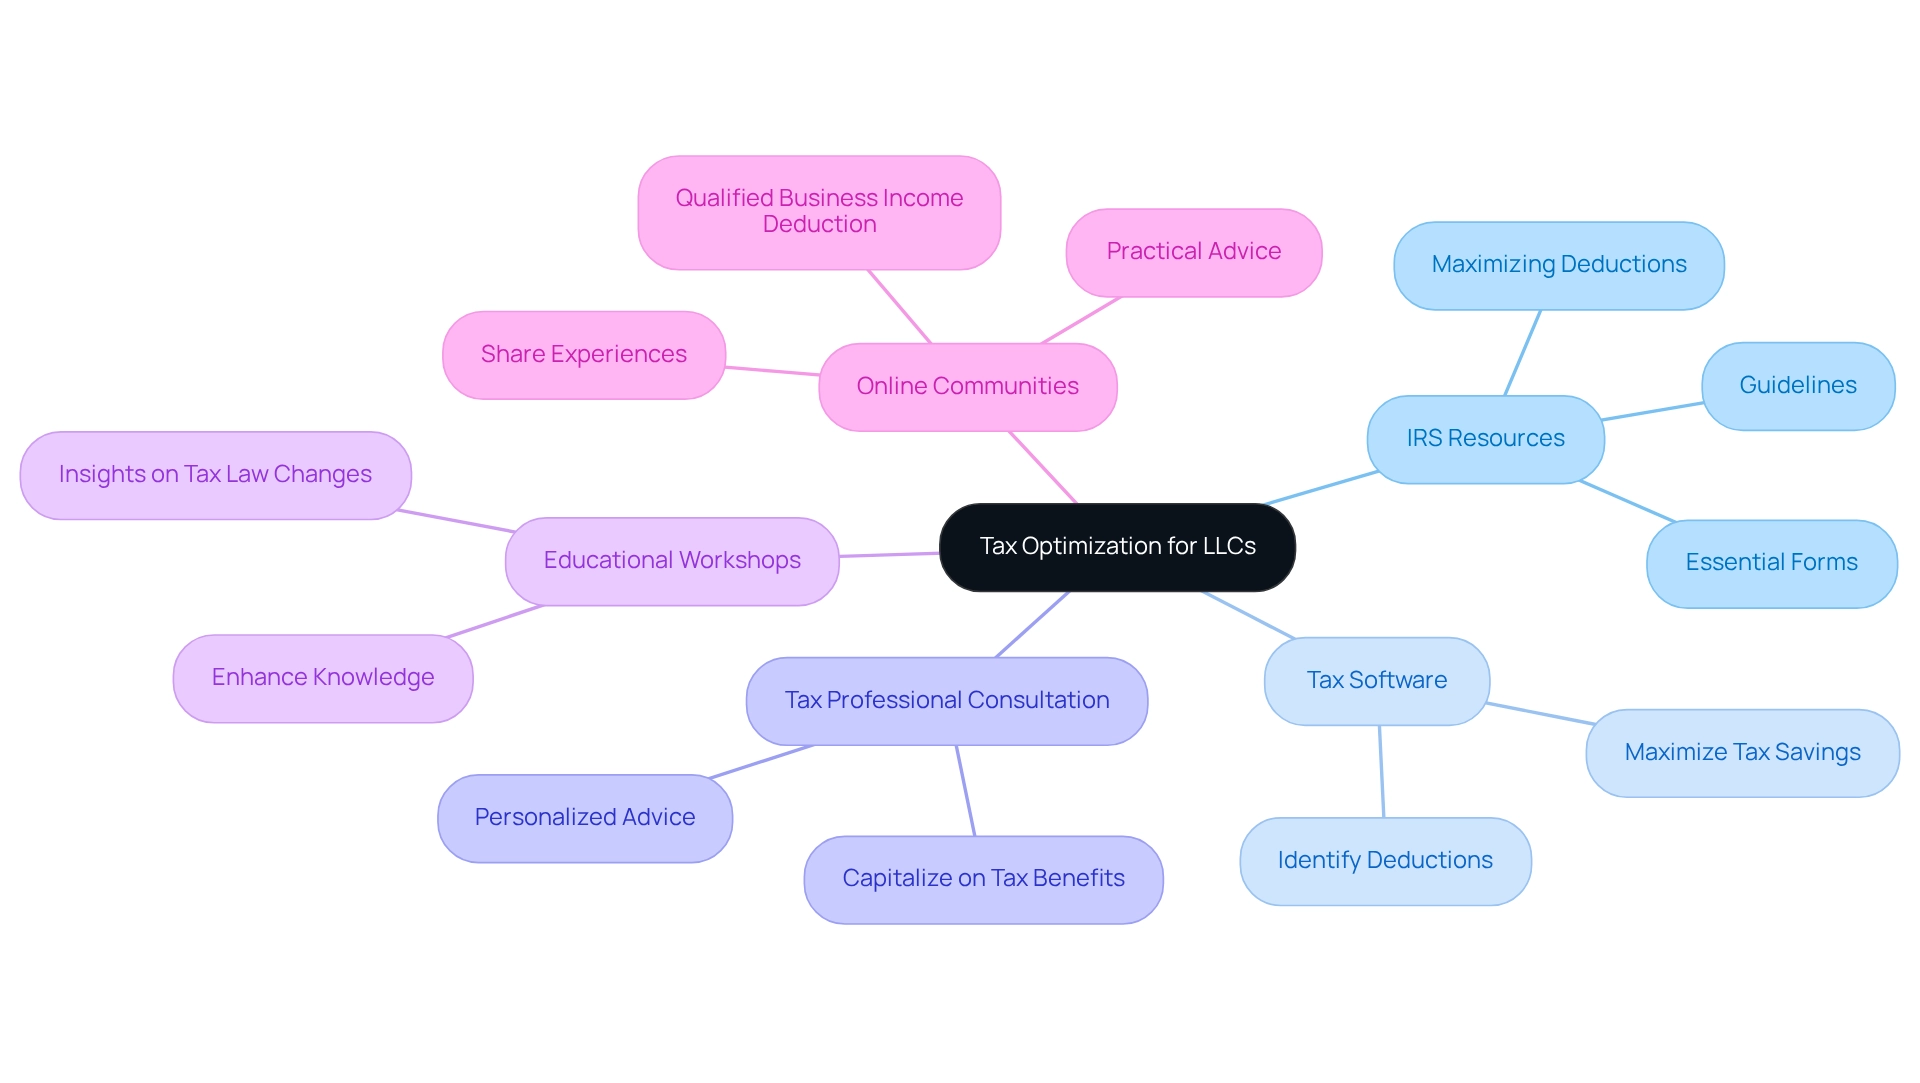
To optimize your taxes as an LLC, it’s important to understand how does LLC affect personal taxes and consider leveraging the following resources that can truly make a difference in your financial journey:
-
IRS Resources: The IRS website is a treasure trove of information on LLC taxation, including essential forms and guidelines. Familiarizing yourself with these resources can help you understand how does LLC affect personal taxes and your obligations and benefits more clearly. Careful planning and documentation are crucial for maximizing deductions, particularly in understanding how does LLC affect personal taxes, making the effective utilization of these resources essential.
-
Tax Software: Imagine having a trusted guide by your side as you navigate the filing process. Tax preparation software is designed to do just that, helping you identify potential deductions and maximizing your tax savings.
-
Consulting a tax professional can help you understand how does LLC affect personal taxes, providing personalized advice tailored to your family’s financial situation. This ensures you capitalize on all available tax benefits. As Jack Nicholaisen wisely noted, ‘Many successful companies started as small limited liability companies,’ underscoring the importance of effective tax strategies.
-
Educational Workshops: Engaging in workshops or webinars focused on understanding how does LLC affect personal taxes can be incredibly beneficial for small enterprises. These sessions offer valuable insights and updates on tax law changes, enhancing your knowledge and preparedness.
-
Online Communities: Connecting with online forums or social media groups where small business owners share their experiences and tips related to LLC taxation can provide practical advice and support. Learning from others in similar situations can be both reassuring and enlightening, particularly in understanding how does LLC affect personal taxes, as smaller limited liability companies may be eligible for certain tax deductions and credits, such as the Qualified Business Income deduction, which can significantly improve economic viability. For instance, the case study titled ‘Tax Benefits for Smaller LLCs’ illustrates how these tax advantages can enhance the economic outlook for entrepreneurs.
Furthermore, businesses operating in multiple states face challenges in keeping up with State and Local Tax (SALT) compliance, especially during a SALT audit. Utilizing IRS resources effectively can lead to better tax outcomes, particularly for families looking to optimize their financial strategies in 2025. Remember, we’re here for you, and together, we can navigate this journey toward financial well-being.
Conclusion
The conversation about Limited Liability Companies (LLCs) highlights their many benefits for young families eager to secure their financial futures. Imagine having personal liability protection that safeguards your family’s assets while offering a flexible structure for managing your business and taxes. With an LLC, families can confidently navigate the complexities of business ownership, knowing they have a supportive framework that aligns with their financial aspirations.
It’s essential to understand the tax implications of LLCs to optimize your financial resources. The pass-through taxation model allows families to sidestep corporate taxes, leading to significant savings. With opportunities like the Qualified Business Income deduction, families can enhance their financial strategies and ensure their hard-earned income is used wisely. Engaging with financial advisors can deepen your understanding and help you implement these valuable tax benefits.
Filing taxes as an LLC might seem overwhelming, but by following structured steps and utilizing available resources, the process can be simplified. Families can take advantage of IRS resources, tax software, and professional advisors to ensure compliance and optimize their tax situations. By being proactive, families can minimize errors and bolster their financial stability.
Ultimately, LLCs are a vital tool for young families aiming to build and protect their wealth. With the right knowledge and support, families can navigate their path to financial security while pursuing their entrepreneurial dreams. Embracing the potential of LLCs not only fosters personal and business growth but also empowers families to create a legacy of financial health for future generations. Remember, we’re here for you—together, we can navigate this journey.
Frequently Asked Questions
What is a Limited Liability Company (LLC)?
An LLC is a versatile business structure that combines the advantages of both corporations and partnerships, providing personal liability protection for owners and safeguarding their personal assets from business debts and legal claims.
What are the benefits of forming an LLC for small business owners and entrepreneurs?
The primary benefits include personal liability protection, flexibility in management and taxation, and the ability to facilitate pass-through taxation, which simplifies the tax process for owners.
How does forming an LLC affect personal taxes?
LLCs can be structured for pass-through taxation, meaning profits and losses are reported directly on the owners’ personal tax returns, making it easier for households to manage their financial responsibilities.
What steps are involved in forming an LLC?
The steps to form an LLC typically include selecting a business name, appointing a registered agent, filing the articles of organization, drafting an operating agreement, and obtaining an EIN.
Why is it important to follow the steps for forming an LLC?
Following these steps ensures compliance with IRS terms and conditions and helps protect personal assets while establishing the business legally.
Can you provide an example of how an LLC protects personal assets?
For instance, a family-owned bakery operating as an LLC can protect the owners’ home and personal savings from potential lawsuits or debts incurred by the business.
How has the formation of LLCs among young households changed recently?
The formation of LLCs among young households has increased by over 20% in recent years, indicating a growing recognition of their benefits.
How can Bright Advisers assist in the formation of an LLC?
Bright Advisers provides guidance and support in managing the steps required to form an LLC, connecting financial planning with investment strategies for families.
List of Sources
- Define an LLC and Its Purpose
- Why Create an LLC? Top Reasons and Benefits Explained (https://marshmallowchallenge.com/blog/why-create-an-llc-top-reasons-and-benefits-explained)
- Is There a Financial Benefit to Forming an LLC? | SageSpring Wealth Partners (https://sagespring.com/is-there-a-financial-benefit-to-forming-an-llc)
- Family LLC vs. Trust | Estate Plan Guide (https://wyomingllcattorney.com/Blog/Family-LLC-vs-Trust)
- Pros and Cons of a Limited Liability Company (LLC) (https://investopedia.com/articles/investing/091014/basics-forming-limited-liability-company-llc.asp)
- Explore the Tax Implications of an LLC
- LLC Pass Through Taxation Explained (How Does It Work?) (https://venturesmarter.com/llc-pass-through-taxation)
- To S-Corp or Not To S-Corp: Evaluating the Tax Implications for Your LLC (https://waverly-advisors.com/insights/to-s-corp-or-not-to-s-corp-evaluating-the-tax-implications-for-your-llc)
- QBI deduction: A tax savings for self-employed and small business owners (https://finance.yahoo.com/personal-finance/taxes/article/qbi-deduction-200545738.html)
- How LLC Members Are Taxed (https://nolo.com/legal-encyclopedia/how-llcs-are-taxed-29675.html)
- Guide to Filing Taxes as an LLC
- LLC Taxes: How are LLCs taxed and what are your options? (https://blockadvisors.com/resource-center/small-business-tax-prep/how-an-llc-is-taxed)
- What IRS Statistics Tell Us About Partnerships and LLCs – Barbara Weltman (https://bigideasforsmallbusiness.com/what-irs-statistics-tell-us-about-partnerships-and-llcs)
- Utilize Resources for Tax Optimization
- Inspirational Tax Planning Quotes to Motivate Your Financial Growth (https://enrichest.com/en/blog/inspirational-tax-planning-quotes-to-motivate-financial-growth)
- 27 Insightful Statistics You Need to Know About LLC Size, Operations, Profitability, & Growth (https://businessinitiative.org/statistics/llc/size)
- 250+ Motivational Quotes For Tax Professionals | TaxConnections (https://taxconnections.com/inspiration-for-tax-professionals-today)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin