

Overview
Living on $2 million requires thoughtful financial planning, and we understand how important this is for you and your family. It’s essential to consider the retirement lifestyle you desire, estimate your expenses, and determine sustainable withdrawal rates. Imagine if you could tailor your withdrawal strategies to fit your unique circumstances and the ever-changing market conditions. It’s crucial to account for inflation and unexpected expenses to ensure your family’s long-term financial stability. Remember, we’re here for you, guiding you through this journey with compassion and support.
Key Highlights:
- Envision your ideal retirement lifestyle to influence financial planning.
- Determine desired retirement age to understand how long savings must last.
- Lifestyle choices impact future expenses; plan accordingly for activities and desires.
- Consider family financial support needs, such as education or elder care.
- Anticipate healthcare expenses as they can significantly affect retirement budgets.
- List fixed expenses (mortgage, utilities) for a stable budget foundation.
- Track variable expenses (groceries, healthcare) for a clearer understanding of financial needs.
- Include discretionary spending (hobbies, travel) while balancing financial goals.
- Identify potential income sources in retirement, including Social Security and investments.
- Understand the 4% rule for sustainable withdrawals from retirement savings.
- Tailor withdrawal strategies to personal circumstances and market conditions.
- Consider a dynamic income strategy with guardrails for reliable income flow.
- Use online withdrawal calculators to simulate different financial scenarios.
- Account for inflation by adjusting long-term budgets and costs.
- Create an emergency fund to cover unexpected expenses, aiming for 6-12 months of living costs.
- Regularly review and adjust financial plans to stay aligned with changing needs.
- Evaluate insurance options to mitigate unexpected costs, enhancing financial stability.
Introduction
Understanding how to stretch a retirement nest egg of $2 million can feel overwhelming for many families. With rising costs and unpredictable expenses, you might be asking yourself: how long can this amount truly support a comfortable lifestyle for you and your loved ones?
In this guide, we’ll gently explore the essential steps for crafting a personalized financial strategy. We’ll cover everything from:
- Calculating your monthly expenses
- Determining sustainable withdrawal rates that align with your family’s needs
As you navigate the complexities of retirement planning, remember that it’s perfectly normal to wonder: what adjustments are necessary to ensure financial security in an ever-changing economic landscape? Together, we can navigate this journey and find the best path forward for you and your family.
Understand Your Retirement Needs and Goals
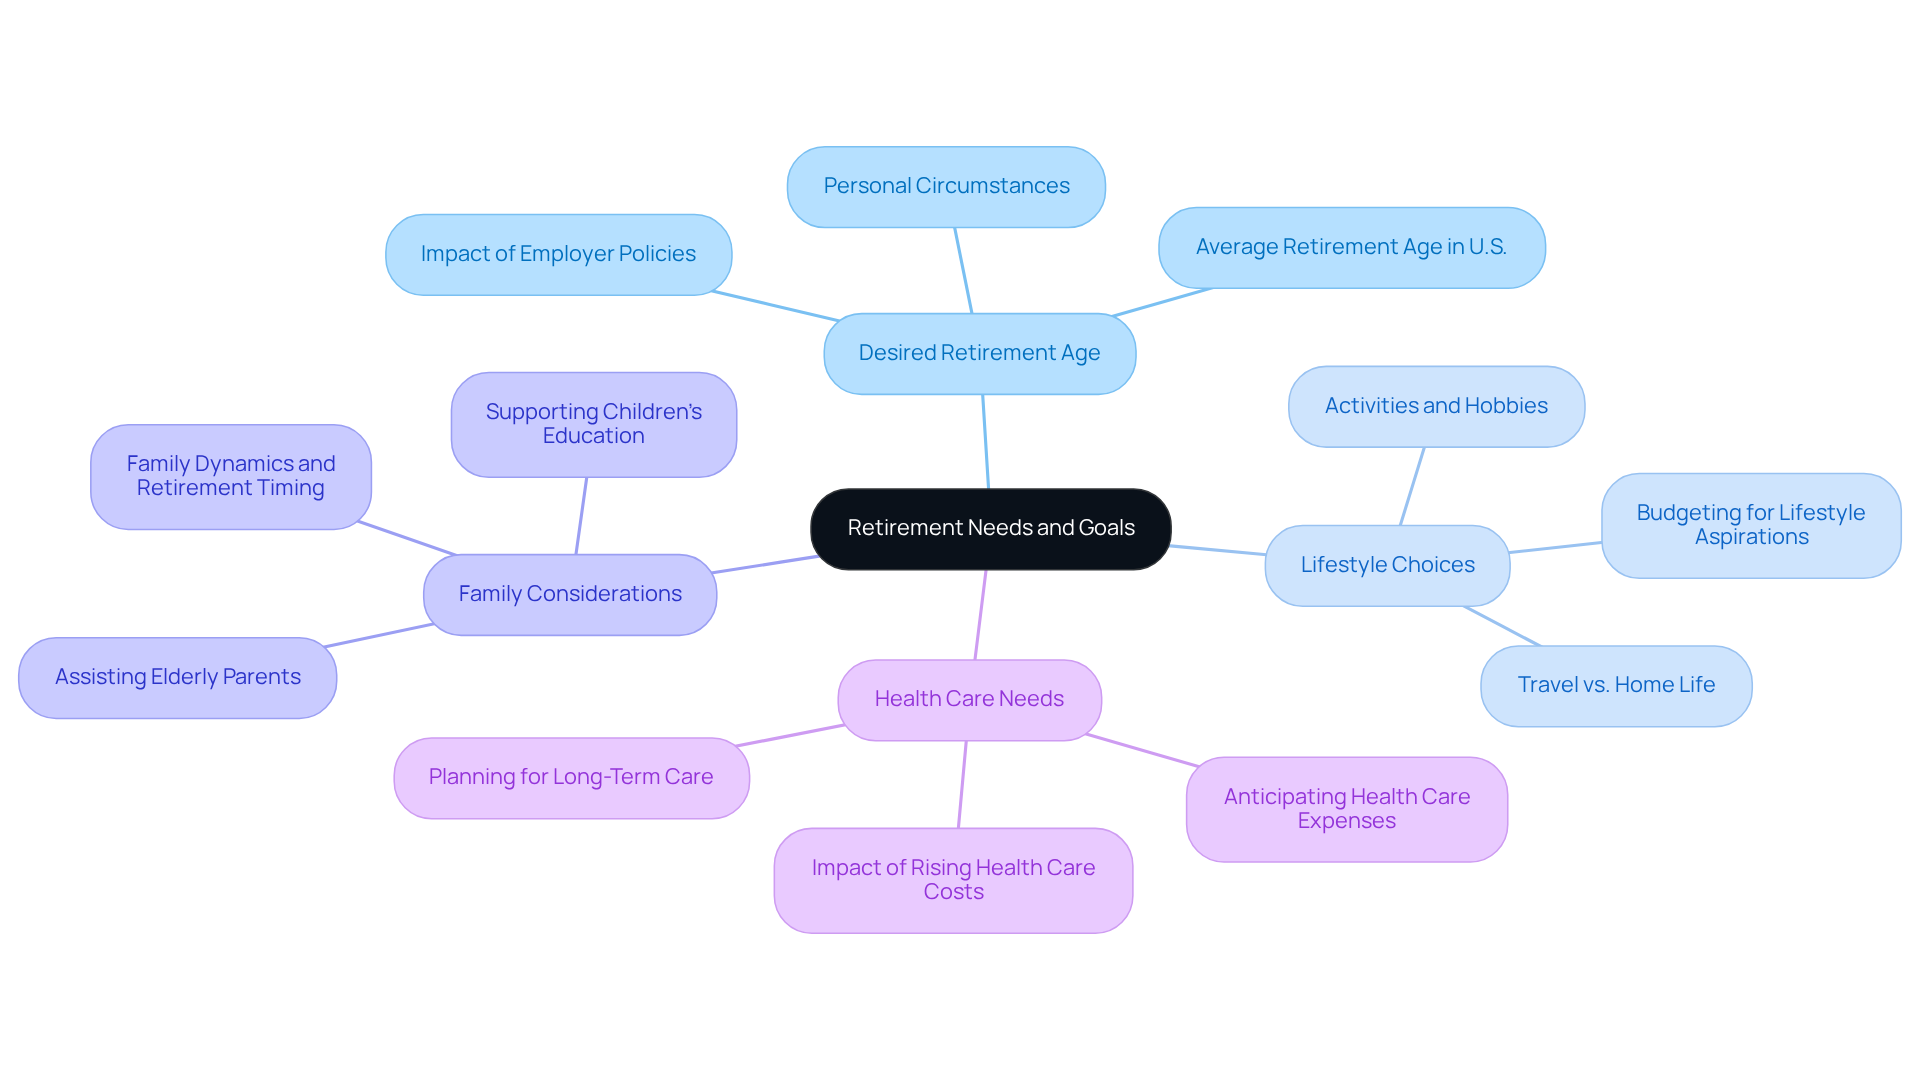
Begin by envisioning your ideal lifestyle in your later years, as this vision will significantly influence your financial planning. Consider these important factors:
- Desired Retirement Age: Reflect on when you hope to retire, as this decision will determine how long your savings need to last. While the average retirement age in the U.S. hovers around 64, personal circumstances may lead you to choose an earlier or later age, and that’s perfectly okay.
- Lifestyle Choices: Picture the activities you wish to engage in. Do you dream of traveling extensively, or do you prefer a more tranquil life at home? Understanding your lifestyle aspirations is key to estimating your future expenses and ensuring you can enjoy the life you envision.
- Family Considerations: Contemplate any family members you may wish to support financially. This could involve funding your children’s education or assisting elderly parents, which can increase your economic responsibilities. Family dynamics can significantly influence your retirement timing and financial planning. At Bright Advisers, we emphasize the importance of crafting a comprehensive family financial strategy that aligns with your values and vision, ensuring your financial decisions support your family’s long-term goals.
- Health Care Needs: Anticipate potential health care expenses, as these can have a profound impact on your budget in your later years. With health care costs on the rise, planning for these needs is essential.
As you navigate this journey, remember that effective retirement strategies often require a delicate balance between personal desires and financial realities, paving the way for a fulfilling and secure future for your family. Consulting with a financial expert at Bright Advisers can provide you with tailored advice that addresses your unique situation, helping you make informed choices about your savings and investments. Take the time to document your objectives and prioritize them to guide your budgeting process effectively.
Calculate Your Monthly Expenses and Income Sources
To ensure financial security for your family and effectively calculate your monthly expenses, let’s take a thoughtful approach together:
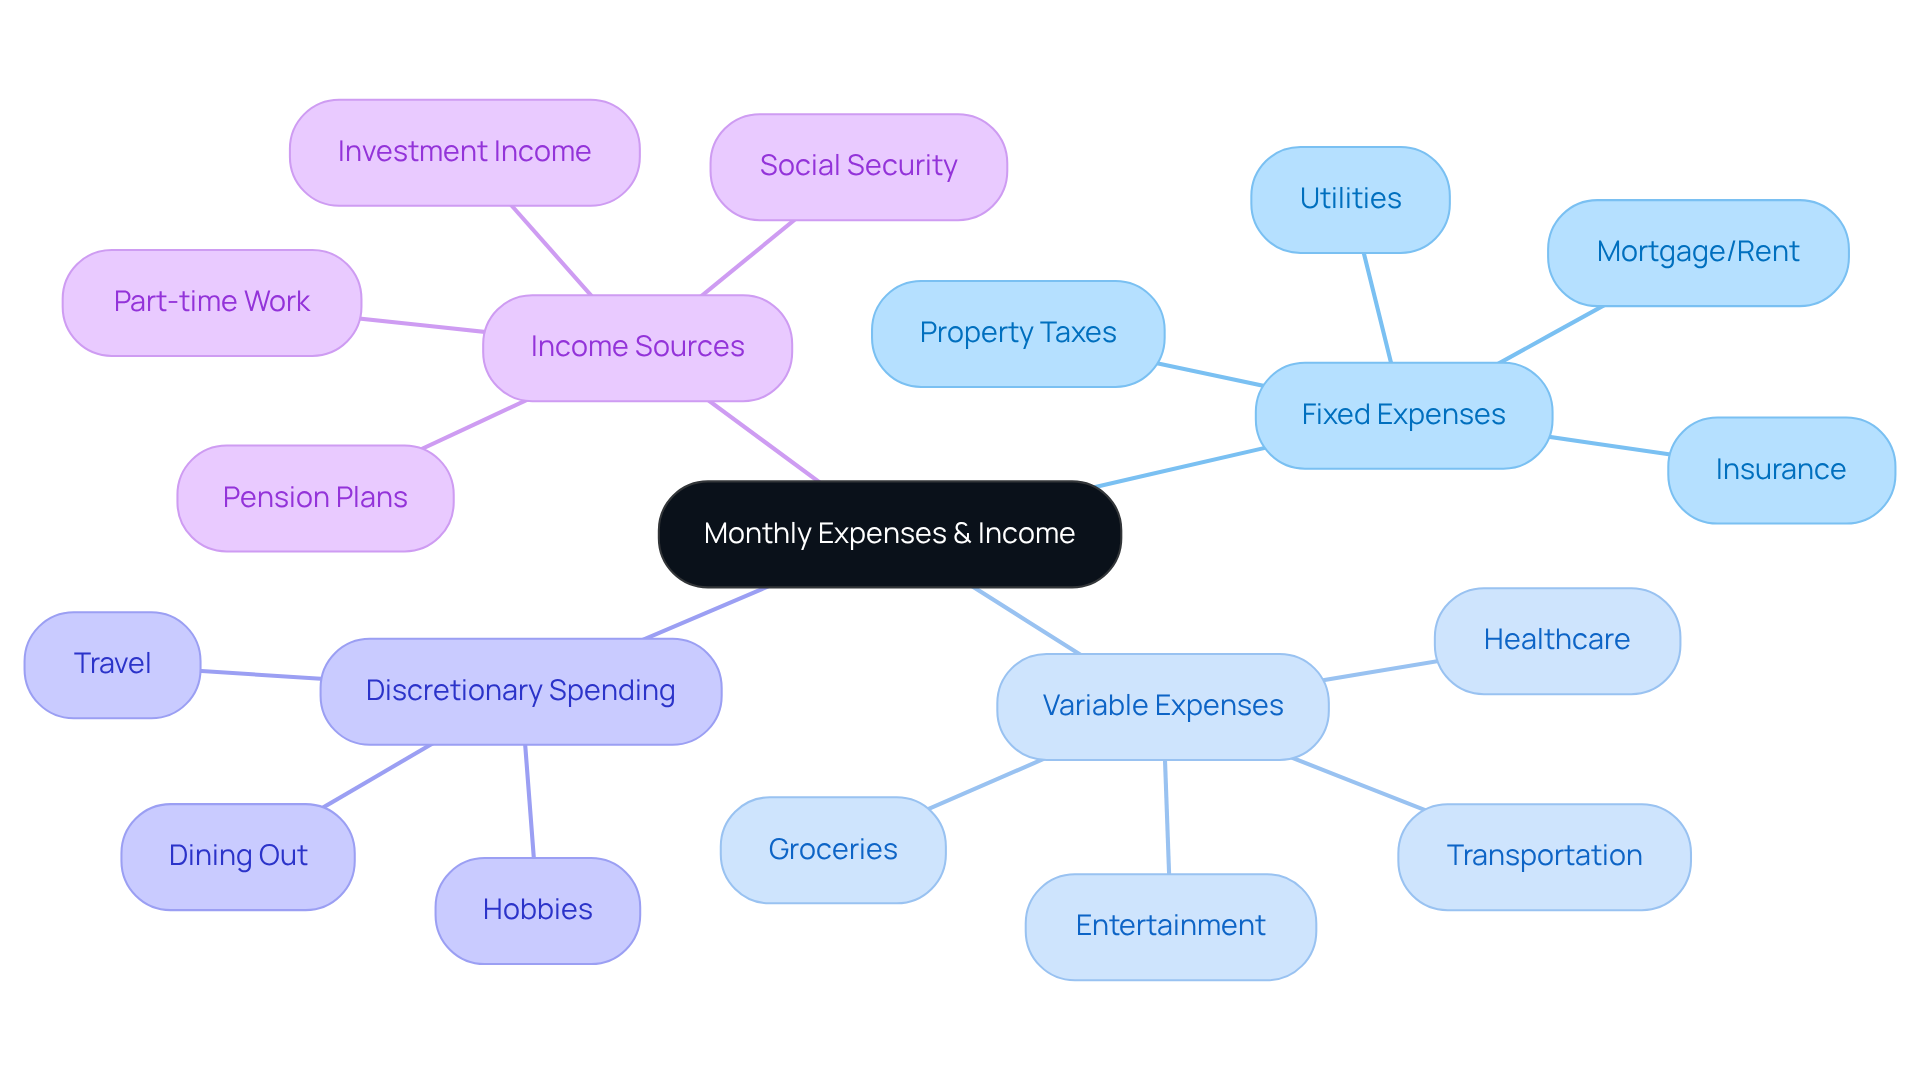
Start with Fixed Expenses: Begin by listing essential costs like your mortgage or rent, utilities, insurance, and property taxes. These predictable expenses are the foundation of your budget, providing stability for your loved ones.
Consider Variable Expenses: Next, think about fluctuating costs such as groceries, transportation, entertainment, and healthcare. Since these can change month to month, tracking them over time will give you a clearer understanding of your family’s needs.
Account for Discretionary Spending: Don’t forget to include non-essential costs like hobbies, dining out, and travel. While these activities bring joy, balancing them with your financial goals is key to maintaining your family’s economic well-being.
Identify Income Sources: Compile potential income sources you might rely on during retirement, which may include:
- Social Security benefits
- Pension plans
- Investment income (dividends, interest)
- Part-time work or side gigs
After creating this comprehensive list, total your monthly expenses and income. This analysis will illuminate your financial needs and help you determine how long you can live on 2 million dollars while sustainably withdrawing from your savings. By understanding both fixed and variable expenses, you can make informed choices that align with your family’s monetary goals. Remember, together, we can navigate this journey toward a secure financial future.
Determine Sustainable Withdrawal Rates
To determine a sustainable withdrawal rate:
-
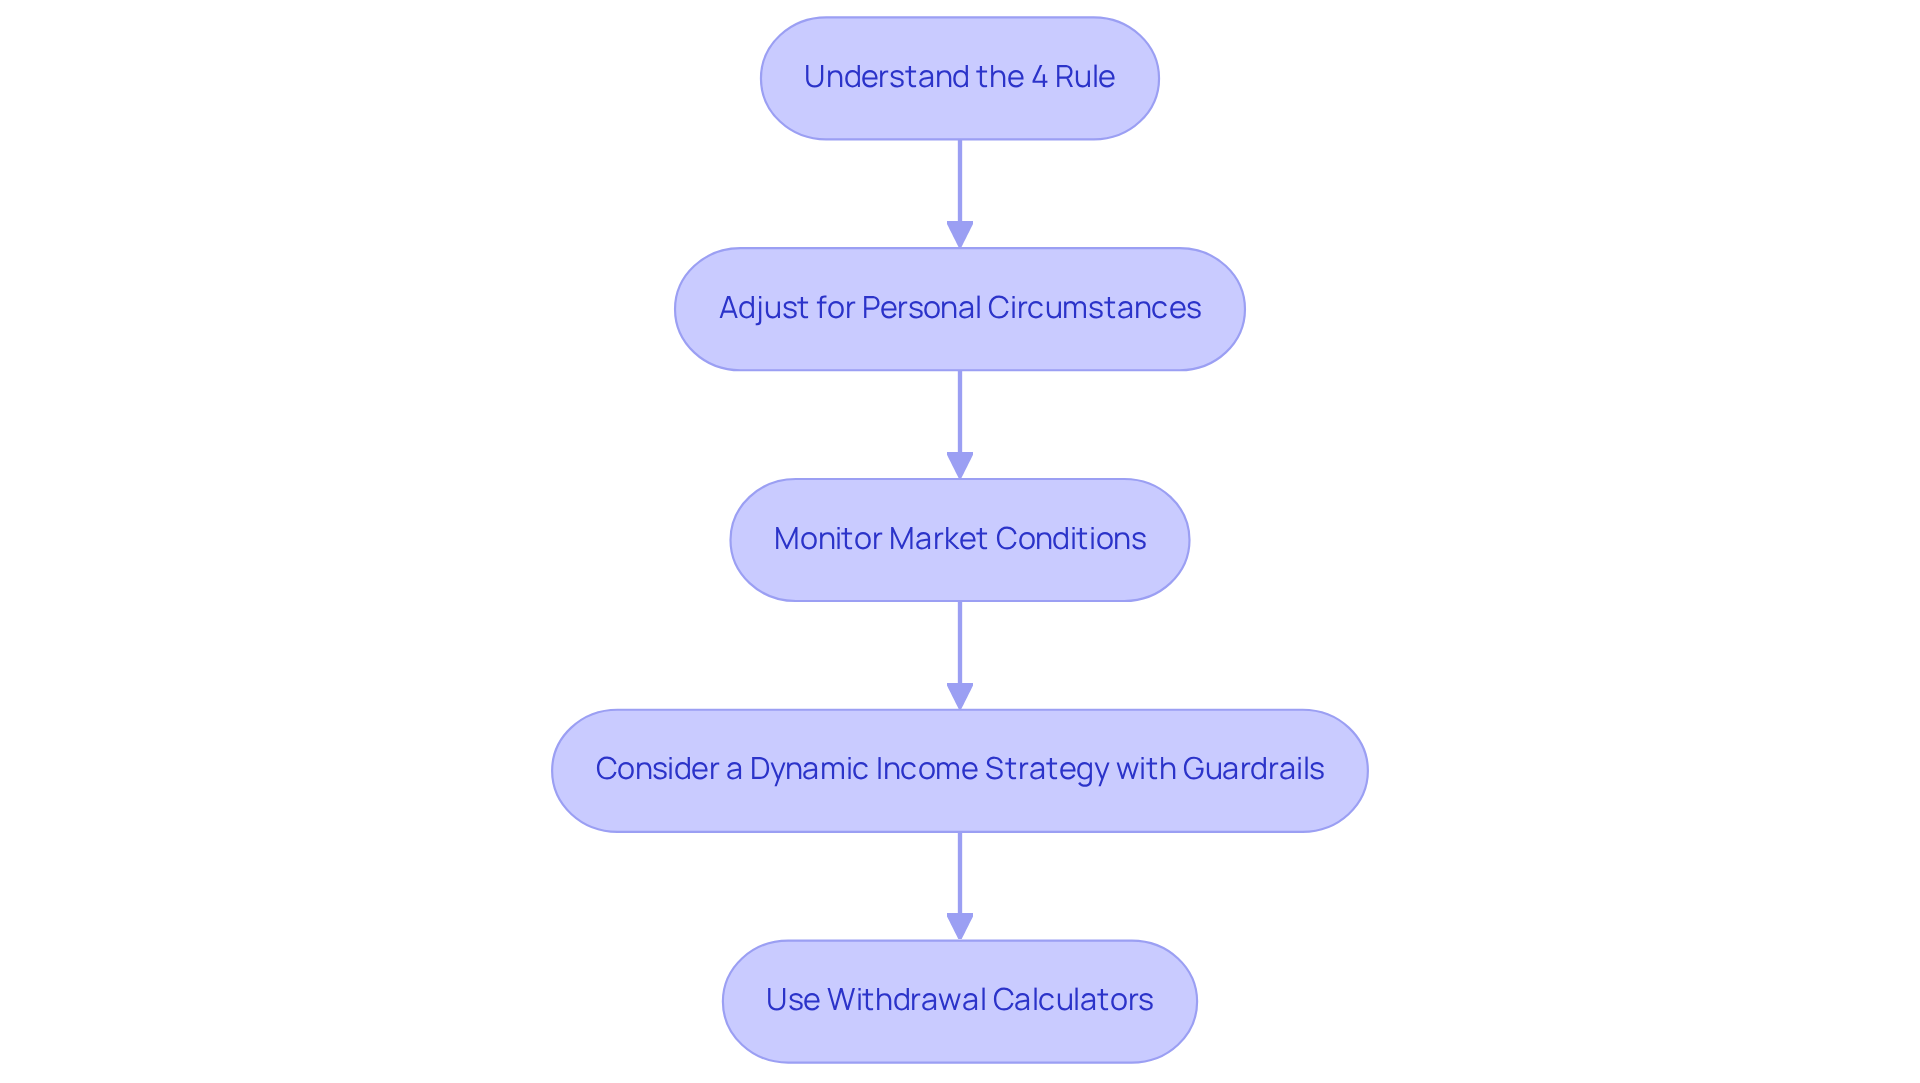
Understand the 4% Rule: Imagine if you could confidently withdraw 4% of your retirement savings each year. This widely recognized guideline suggests that retirees can withdraw this amount annually. With a portfolio of $2 million, one might wonder how long can I live on 2 million dollars if I make an initial withdrawal of $80,000 in the first year. However, it’s important to understand that this rule has limitations, especially in today’s complex economic landscape, where market conditions and personal circumstances can vary significantly.
-
Adjust for Personal Circumstances: It’s crucial to tailor your withdrawal strategy to your unique situation. If you anticipate higher expenses, like healthcare costs, or have specific financial goals, consider withdrawing less than the usual rate. This adaptability is essential for maintaining financial stability during your later years. Bright Advisers highlights the importance of hyper-personalized financial planning, which can help you customize your withdrawal approach to meet your individual needs.
-
Monitor Market Conditions: Picture this: the performance of your investments plays a vital role in the sustainability of your portfolio. During market downturns, it may be necessary to reduce your withdrawal rate to protect your savings. Conversely, in strong market years, you might find opportunities to increase your withdrawals, enhancing your quality of life. As Danny Gudorf observes, the 4% rule faces considerable constraints in today’s intricate financial landscape, underscoring the need for flexible approaches supported by sophisticated investment techniques.
-
Consider a Dynamic Income Strategy with Guardrails: This approach allows you to set an initial income level backed by your portfolio while establishing guardrails that dictate when to increase or decrease spending based on portfolio performance. This strategy can provide a more reliable income flow during your later years. For instance, Michael and Jan modified their withdrawal plan to better suit their needs, demonstrating the effectiveness of this approach. Bright Advisers’ innovative technology can assist you in executing such plans successfully.
-
Use Withdrawal Calculators: Have you tried using online calculators? They can simulate different withdrawal scenarios based on your portfolio size and expected lifespan. This tool can help you visualize how long you can live on 2 million dollars under various circumstances, empowering you to make informed decisions about your future income plan.
By grasping the nuances of the 4% guideline, adjusting your withdrawal approach based on personal situations and market conditions, and considering a flexible income plan, you can create a more sustainable financial strategy that supports your lifestyle in your later years. Utilizing the advanced technology and tailored strategies offered by Bright Advisers, such as their Diversified Premia and Tactical Portfolio strategies, can further enhance your planning process. Remember, we’re here for you, and together, we can navigate this journey.
Account for Inflation and Unexpected Expenses
To effectively account for inflation and unexpected expenses in retirement, consider these nurturing strategies:
-
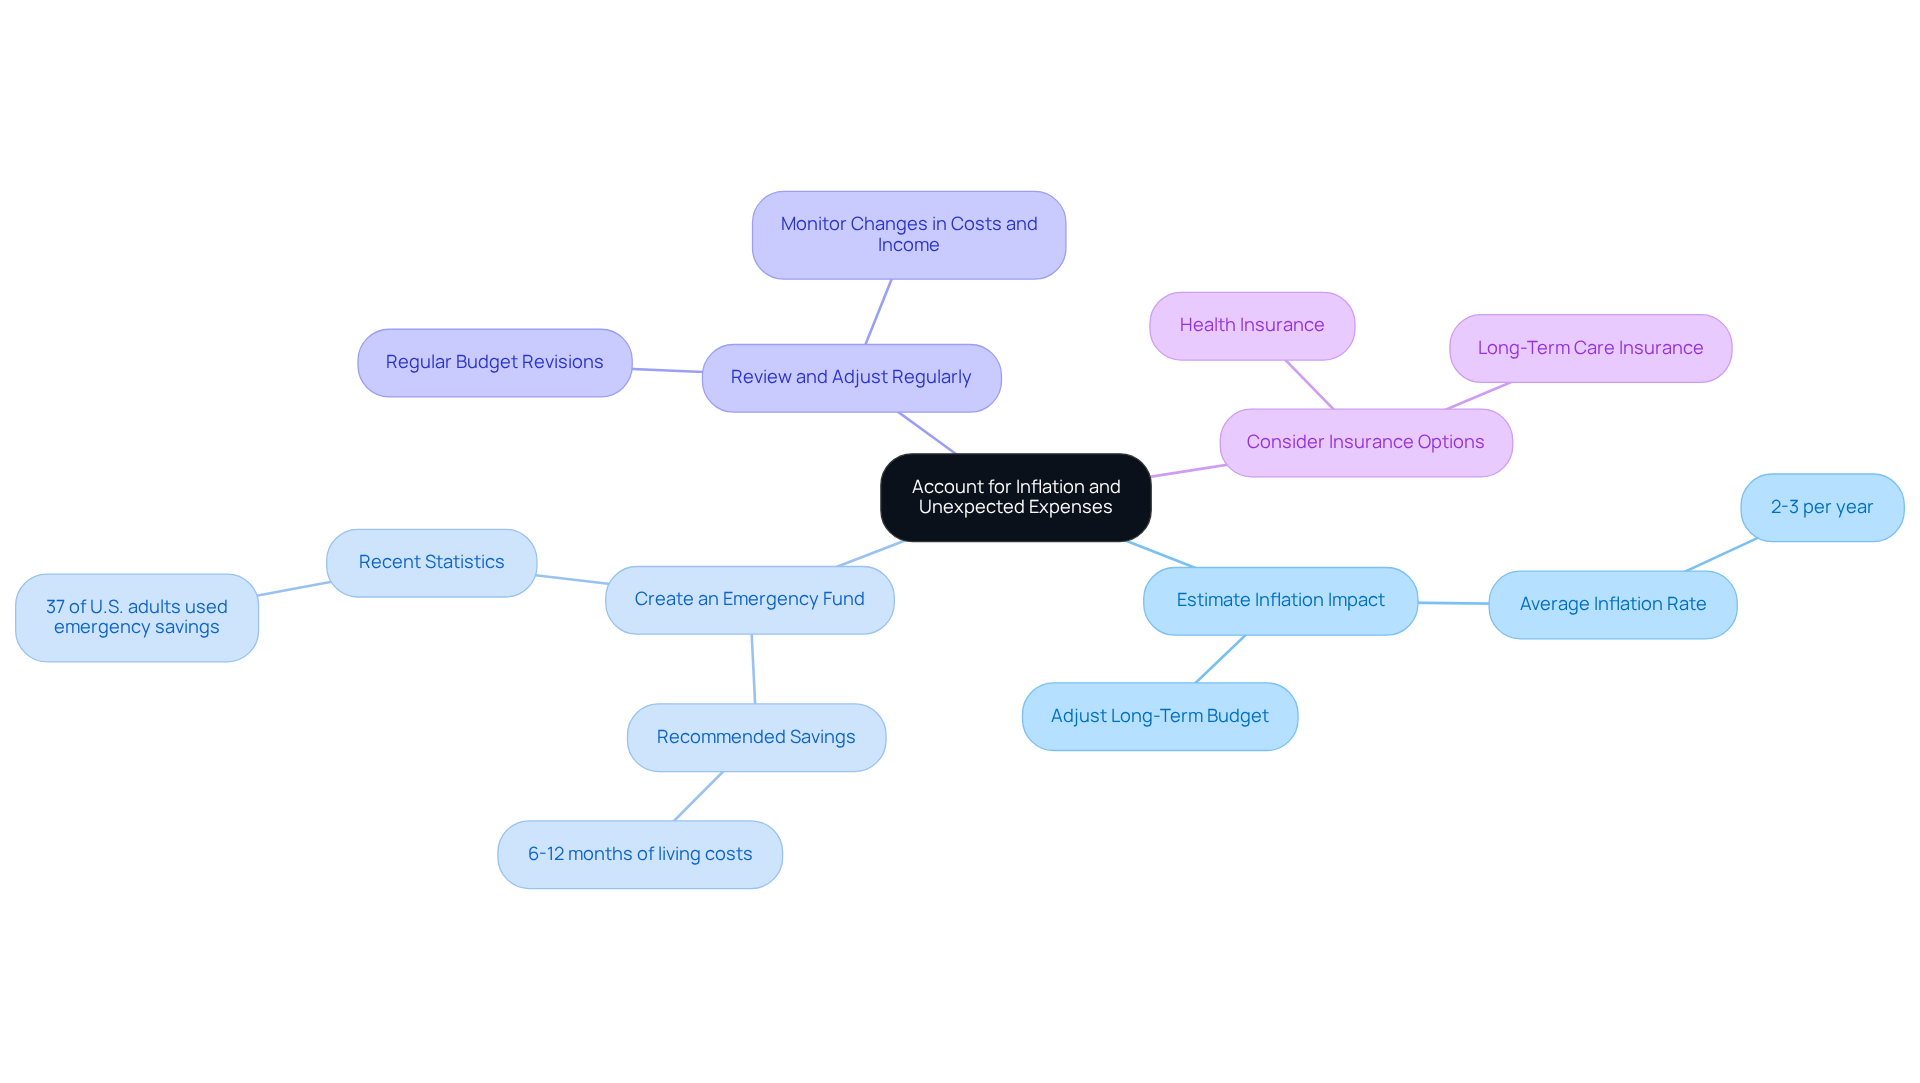
Estimate Inflation Impact: Imagine if inflation averages around 2-3% per year. By integrating this into your long-term budget and adjusting your anticipated costs, you can ensure your financial plan remains practical over time, providing a sense of security for your family.
-
Create an Emergency Fund: It’s important to establish a dedicated emergency fund to cover unforeseen costs, such as home repairs or medical crises. Aim for at least 6-12 months’ worth of living costs. This proactive measure can offer peace of mind and economic stability during unexpected situations. Notably, 37% of U.S. adults tapped into their emergency savings in the past year, highlighting the importance of having these funds readily available.
-
Review and Adjust Regularly: Regularly revisit your budget and monetary plan to account for changes in costs, income, and inflation rates. This ongoing evaluation will assist you in remaining aligned with your monetary objectives and adapting to any shifts in your economic environment.
-
Consider Insurance Options: Evaluate insurance policies that can help mitigate unexpected costs, such as health insurance or long-term care insurance. Having the appropriate coverage can greatly lessen the monetary strain of unforeseen medical expenses.
By preparing for inflation and unforeseen costs, families can improve their financial stability and ensure that their savings endure, prompting them to consider how long can I live on 2 million dollars. Experts recommend saving three to six months of expenses for emergencies, and 63% of people say they would need at least six months of expenses in emergency savings to feel comfortable. As Warren Buffett wisely noted, “Do not save what is left after spending, but spend what is left after saving.” Together, we can navigate the complexities of retirement planning with confidence, knowing that we are here for you every step of the way.
Conclusion
Understanding how to effectively manage $2 million in retirement is a journey that requires a comprehensive approach, one that embraces your personal goals, financial planning, and adaptability. Imagine taking the time to assess your retirement needs, calculating your monthly expenses, and determining sustainable withdrawal rates. This thoughtful process allows you to create a financial strategy that aligns with the lifestyle you desire while ensuring long-term security for you and your family.
In this article, we emphasize several key components:
- Envisioning your retirement goals
- Accurately calculating both fixed and variable expenses
- Recognizing the importance of a dynamic withdrawal strategy
It’s essential to account for inflation and unexpected costs to maintain financial stability. By utilizing resources like withdrawal calculators and consulting financial experts, you can make informed decisions that enhance your quality of life.
Ultimately, the journey toward a secure retirement is not just about the numbers; it’s about crafting a fulfilling life that resonates with your personal aspirations and family needs. Embracing proactive financial planning and remaining adaptable to changing circumstances will empower you to navigate your retirement years with confidence and peace of mind. Taking that first step toward understanding and implementing these strategies can lead to a brighter financial future, ensuring that the question of how long you can live on $2 million is met with assurance and clarity. Together, we can navigate this journey, and we’re here for you every step of the way.
Frequently Asked Questions
What should I consider when envisioning my retirement lifestyle?
You should consider your desired retirement age, lifestyle choices, family considerations, and health care needs. These factors will significantly influence your financial planning.
How does my desired retirement age affect my financial planning?
Your desired retirement age determines how long your savings need to last. While the average retirement age in the U.S. is around 64, personal circumstances may lead you to choose an earlier or later age.
Why are lifestyle choices important in retirement planning?
Understanding your lifestyle aspirations, such as whether you want to travel extensively or prefer a tranquil life at home, is key to estimating future expenses and ensuring you can enjoy the life you envision.
How can family considerations impact my retirement planning?
Family dynamics, such as supporting children’s education or assisting elderly parents, can increase your economic responsibilities and influence your retirement timing and financial strategy.
What should I anticipate regarding health care needs in retirement?
You should anticipate potential health care expenses, as these can significantly impact your budget in later years. Planning for these needs is essential due to rising health care costs.
How can I balance personal desires and financial realities in retirement planning?
Effective retirement strategies require a delicate balance between what you want to achieve and your financial situation. Consulting with a financial expert can help you make informed choices about savings and investments.
What role does consulting with a financial expert play in retirement planning?
Consulting with a financial expert can provide tailored advice that addresses your unique situation, helping you document your objectives, prioritize them, and guide your budgeting process effectively.
List of Sources
- Understand Your Retirement Needs and Goals
- What is the Average Retirement Age in the US? | Guardian (https://guardianlife.com/retirement/average-age)
- The Best Quotes About Retirement (https://retirable.com/advice/lifestyle/best-retirement-quotes)
- 50+ Essential Retirement Statistics for 2025: Demographics (https://annuity.org/retirement/retirement-statistics)
- Calculate Your Monthly Expenses and Income Sources
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- 35 Retirement Quotes for a Happy, Healthy, and Wealthy Life (https://ruleoneinvesting.com/blog/personal-development/retirement-quotes)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 11 More of the Best Quotes on Retirement (https://peabodywealthadvisors.com/blog/11-more-of-the-best-quotes-on-retirement)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Determine Sustainable Withdrawal Rates
- Why You Shouldn’t Use the 4% Rule In Retirement (And a Better Strategy) – % (https://daytonestateplanninglaw.com/episodes/why-you-shouldnt-use-the-4-rule-in-retirement-and-a-better-strategy)
- The 4% Rule: How Much Can You Spend in Retirement? (https://schwab.com/learn/story/beyond-4-rule-how-much-can-you-spend-retirement)
- Account for Inflation and Unexpected Expenses
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- Schwab Study: Retirement Confidence Dips Amid Inflation Concerns; Savers Respond by Cutting Personal Spending While Maintaining 401(k) Contributions (https://pressroom.aboutschwab.com/press-releases/press-release/2025/Schwab-Study-Retirement-Confidence-Dips-Amid-Inflation-Concerns-Savers-Respond-by-Cutting-Personal-Spending-While-Maintaining-401k-Contributions/default.aspx)
- 9 Inspiring Budgeting Quotes (and How You Can Use Them to Take Action NOW) – Atypical Finance (https://atypicalfinance.com/9-inspiring-budgeting-quotes-and-how-you-can-use-them-to-take-action-now)
- Bankrate’s 2025 Emergency Savings Report | Bankrate (https://bankrate.com/banking/savings/emergency-savings-report)
- 10 Best Quotes About Saving Money | Lightheart, Sanders and Associates (https://lsa.cpa/2022/07/26/10-best-quotes-about-saving-money)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading