

Overview
Navigating the world of financial planning can feel overwhelming, especially for young parents. Fee-only financial planners are here to help by offering various fee structures that cater to your unique needs. They typically charge clients through:
- Hourly fees ranging from $120 to $400
- Flat fees between $1,000 and $5,000
- A percentage of managed assets, which can be as low as 0.5% to 1.5% annually
Your total costs will depend on factors like the advisor’s experience and the complexity of the services provided.
Imagine if you could work with someone who truly prioritizes your family’s needs. This is where fee-only planners shine. Their fee structure fosters transparency, ensuring you know exactly what you’re paying for. They operate under a fiduciary standard, which means their advice is unbiased and focused solely on your best interests. This commitment to your financial well-being is not just a service; it’s a partnership.
As you consider your family’s future, it’s important to understand that the right financial guidance can make all the difference. Together, we can navigate this journey, ensuring your family’s values and goals are at the forefront of every decision. Remember, we’re here for you—ready to support you every step of the way.
Key Highlights:
- Fee-only financial planners charge clients directly, minimizing conflicts of interest and ensuring unbiased advice.
- They operate under a fiduciary standard, legally prioritizing clients’ financial needs.
- Common fee structures include hourly fees ($120-$400), flat fees ($1,000-$5,000), Assets Under Management (0.5%-1.5% annually), and retainer fees ($2,000-$7,500 per year).
- The rise of robo-advisors indicates a shift towards technology-driven asset management, with assets reaching $1.37 trillion in 2023.
- Factors influencing advisor costs include advisor experience, service complexity, geographic location, and the scope of services offered.
- Families should assess their specific financial needs, interview candidates, and ensure the planner adheres to fiduciary duty.
- Transparency in fee structures is essential for building trust and avoiding unexpected costs.
Introduction
Navigating the world of financial planning can often feel overwhelming, especially for families striving to secure their financial futures. Imagine if you had a trusted ally by your side, someone who truly understands your concerns and aspirations. As the landscape shifts towards more transparent and client-focused services, fee-only financial planners have emerged as those allies. These compassionate professionals operate under a model that prioritizes your best interests, free from the conflicts of interest that can arise in commission-based arrangements.
With a commitment to ethical practices and personalized strategies, fee-only planners are redefining how families like yours approach their financial goals. This article delves into the role of fee-only financial planners, explores common fee structures, identifies factors influencing costs, and offers guidance on selecting the right planner to meet your specific needs.
By understanding these elements, you can empower yourself to make informed financial decisions and pave the way for a secure future. Together, we can navigate this journey towards financial well-being.
Define Fee-Only Financial Planners and Their Role
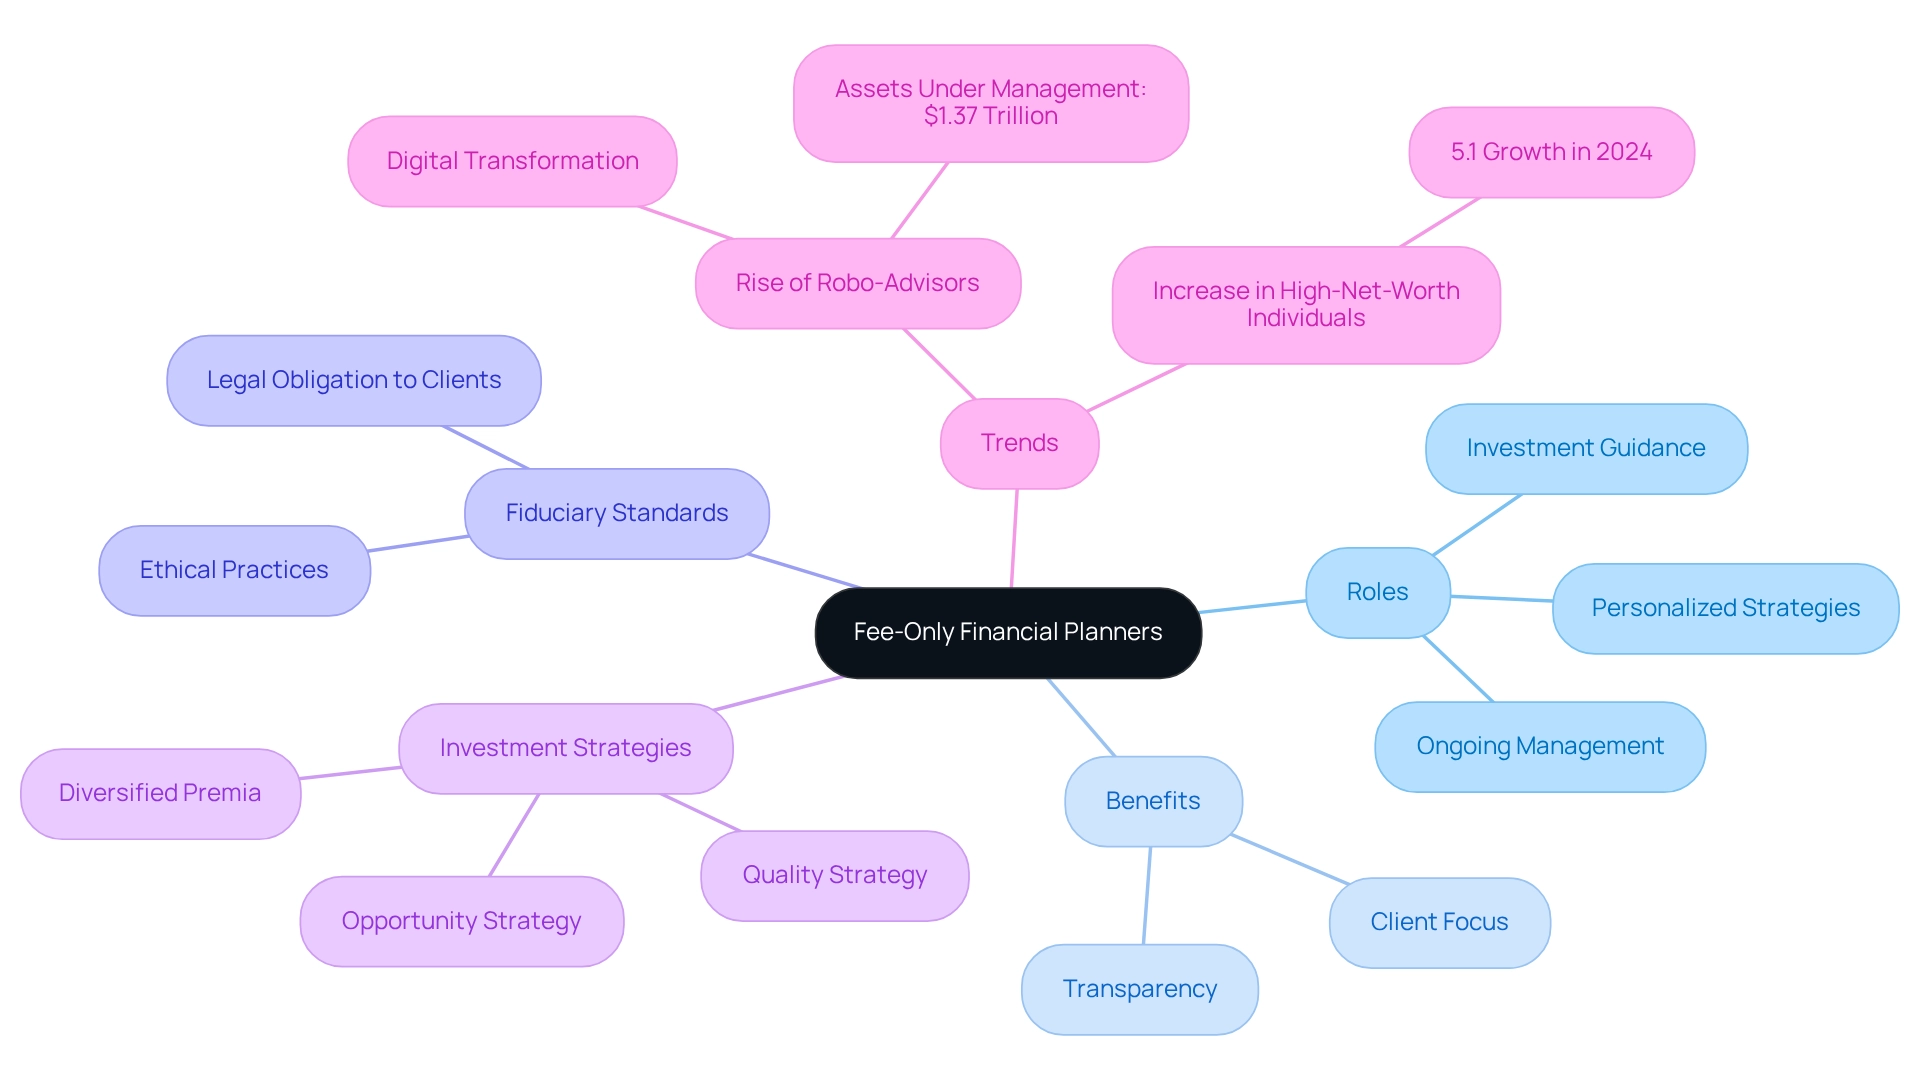
Fee-only advisers are dedicated experts who charge individuals directly for their services, eliminating potential conflicts of interest that can arise from commission-based payment. This model ensures that their recommendations are unbiased and focused solely on the client’s best interests, which is particularly valuable for families seeking trustworthy financial guidance. Operating under a fiduciary standard, these planners are legally bound to prioritize their clients’ needs, empowering families with young children to make informed decisions about their financial futures.
Imagine a partnership where your family’s values and aspirations are at the forefront of financial planning. Bright Advisers exemplifies this approach, working closely with families to develop comprehensive plans that resonate with their unique goals. As Investopedia notes, ‘Fee-only advisors offer transparency and fewer possible conflicts of interest, but it’s important to consider how much are fee only financial planners, as they may cost more upfront and have certain limitations in their service offerings.’
Their roles encompass crafting personalized financial strategies, offering investment guidance, and providing ongoing fiscal management. This structure fosters a transparent relationship, allowing parents to focus on their children’s futures without the distraction of potential conflicts. It’s important to understand that as of 2025, approximately 70% of money advisors adhere to fiduciary standards, reflecting a growing commitment to ethical practices in the industry.
The rise of fee-only planners has been remarkable, leading many to wonder how much are fee only financial planners, as assets managed by robo-advisors reached $1.37 trillion in 2023, signaling a shift towards technology-driven asset management. Bright Advisers embraces innovative in-house technology to enhance their offerings, rendering traditional investment products less relevant. This trend is further supported by the increase in high-net-worth individuals, which may create opportunities for advisory growth, particularly among families seeking personalized services.
Particular investment approaches, like the Diversified Premia, Opportunity Strategy, and Quality Strategy, are utilized to optimize financial outcomes for clients. Case studies, such as that of Emily and Mark, illustrate how much are fee-only financial planners valued for the increased trust and transparency they bring to families, resulting in better financial results. Specialist perspectives emphasize that this model not only strengthens relationships with clients but also equips families to navigate planning challenges effectively. Moreover, the digital transformation in investment advisory practices allows firms like Bright Advisers to expand operations while delivering tailored experiences for clients, highlighting a shift towards innovative wealth management strategies.
Together, we can navigate this journey and ensure your family’s financial future is bright and secure.
Explore Common Fee Structures for Financial Planning
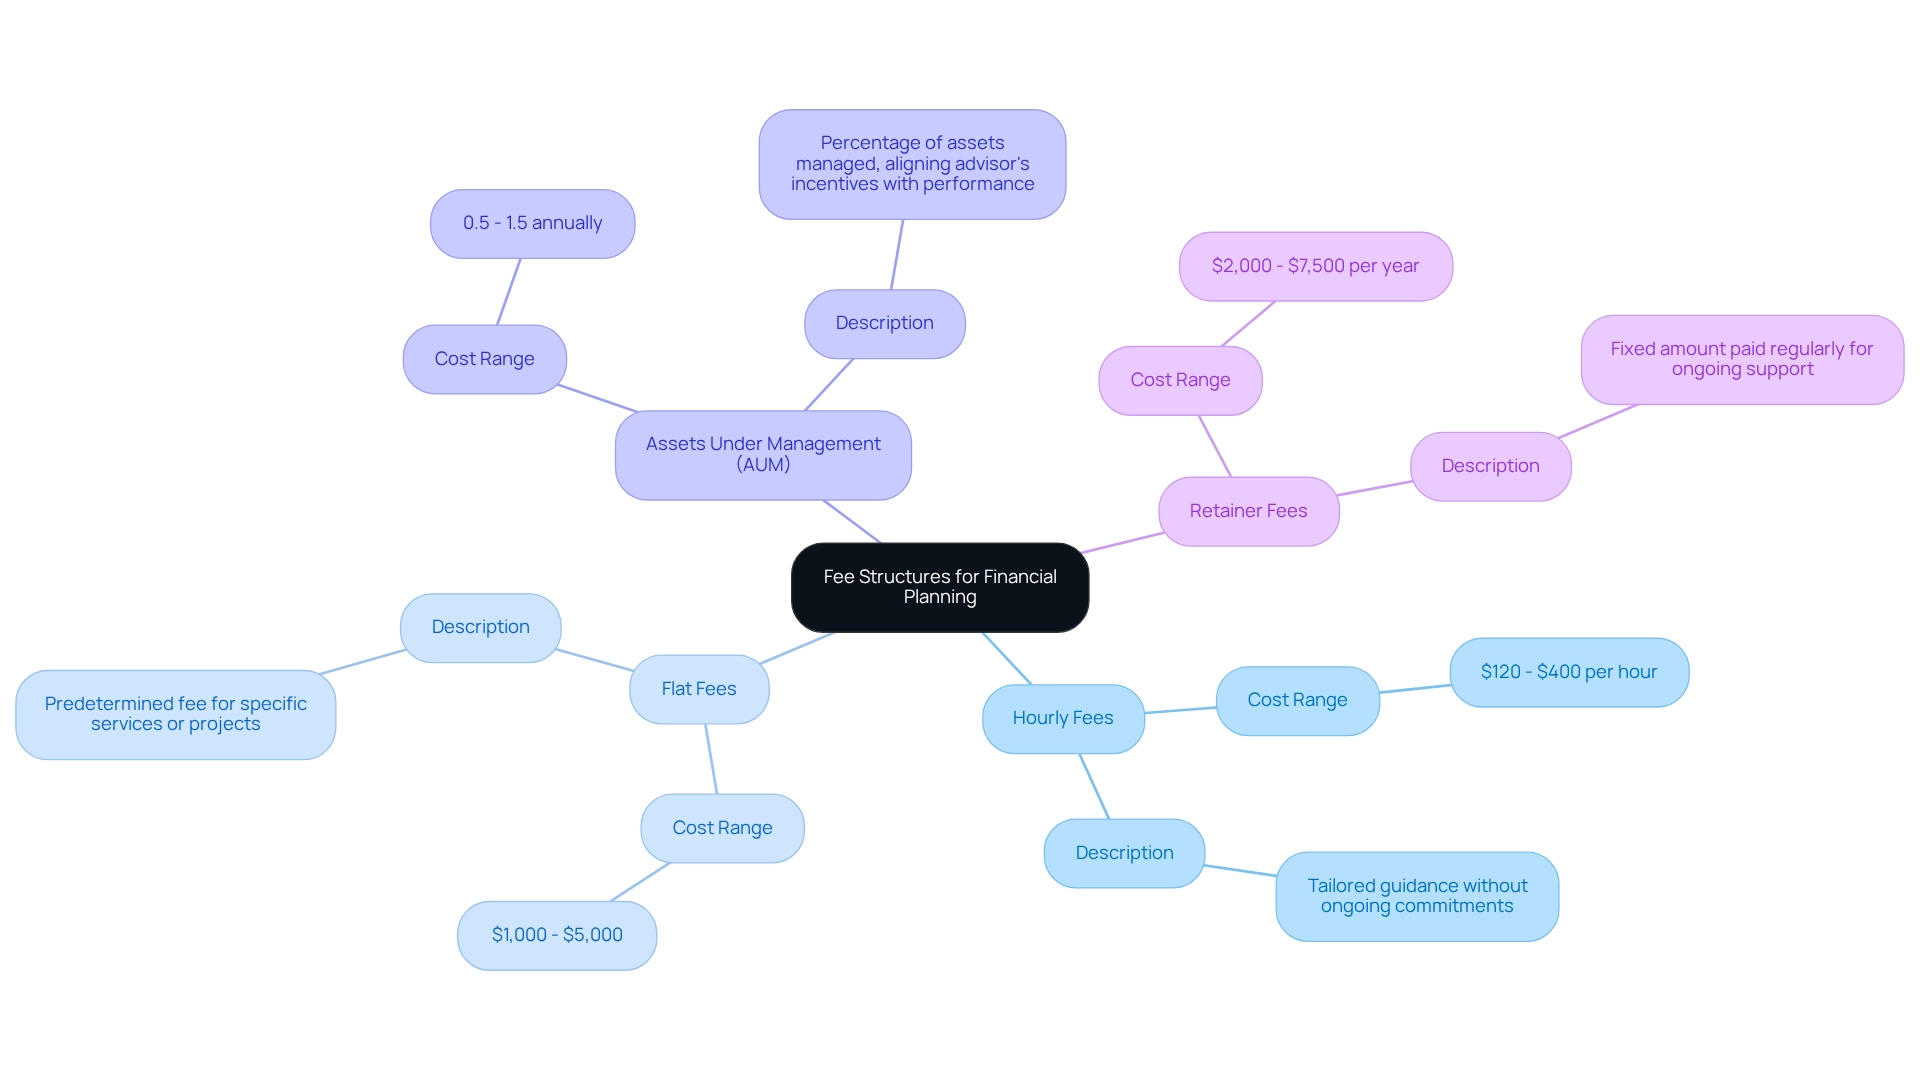
For families navigating monetary complexities, understanding how much are fee only financial planners and the various fee structures for financial planning is essential. Each model caters to different needs, ensuring that you can find the right fit for your unique circumstances.
- Hourly Fees: Imagine needing tailored guidance without the pressure of ongoing commitments. Advisors typically charge between $120 and $400 per hour, allowing you the flexibility to seek help as needed.
- Flat Fees: If you’re looking for clarity and predictability in your financial planning, a flat fee structure might be ideal. This involves a predetermined fee for specific services or projects, generally ranging from $1,000 to $5,000, perfect for comprehensive monetary plans or one-time consultations.
- Assets Under Management (AUM): With this model, advisors charge a percentage of the assets they manage, usually between 0.5% and 1.5% annually. As Andrea Coombes notes, “The cost usually isn’t linked to how much you have available to invest, but you may pay more if your situation is complex.” This approach aligns your advisor’s incentives with your investment performance, fostering a partnership in achieving your financial goals.
- Retainer Fees: For those who desire ongoing support, retainer fees offer a fixed amount paid regularly, either monthly or annually, ranging from $2,000 to $7,500 per year. This ensures you have consistent access to your advisor’s expertise.
At Bright Advisers, we are committed to minimizing fund fees, enhancing accessibility for families. For instance, one family with a modest income benefited from an hourly fee arrangement, receiving customized guidance on specific monetary challenges without the burden of a long-term agreement. Another family, facing significant decisions regarding education and retirement, found value in a flat fee model for a comprehensive plan, which provided them with a clear roadmap for their economic future.
As we look ahead to 2025, trends indicate a growing preference for knowing how much are fee only financial planners in transparent fee structures. Many clients are prioritizing clarity over traditional commission-based models, where mutual fund sales loads typically range from 3% to 6% of investments. This shift underscores the importance of being well-prepared and clear about your monetary needs, which can facilitate better negotiations with advisors.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your values.
Identify Factors Affecting the Cost of Financial Advisors
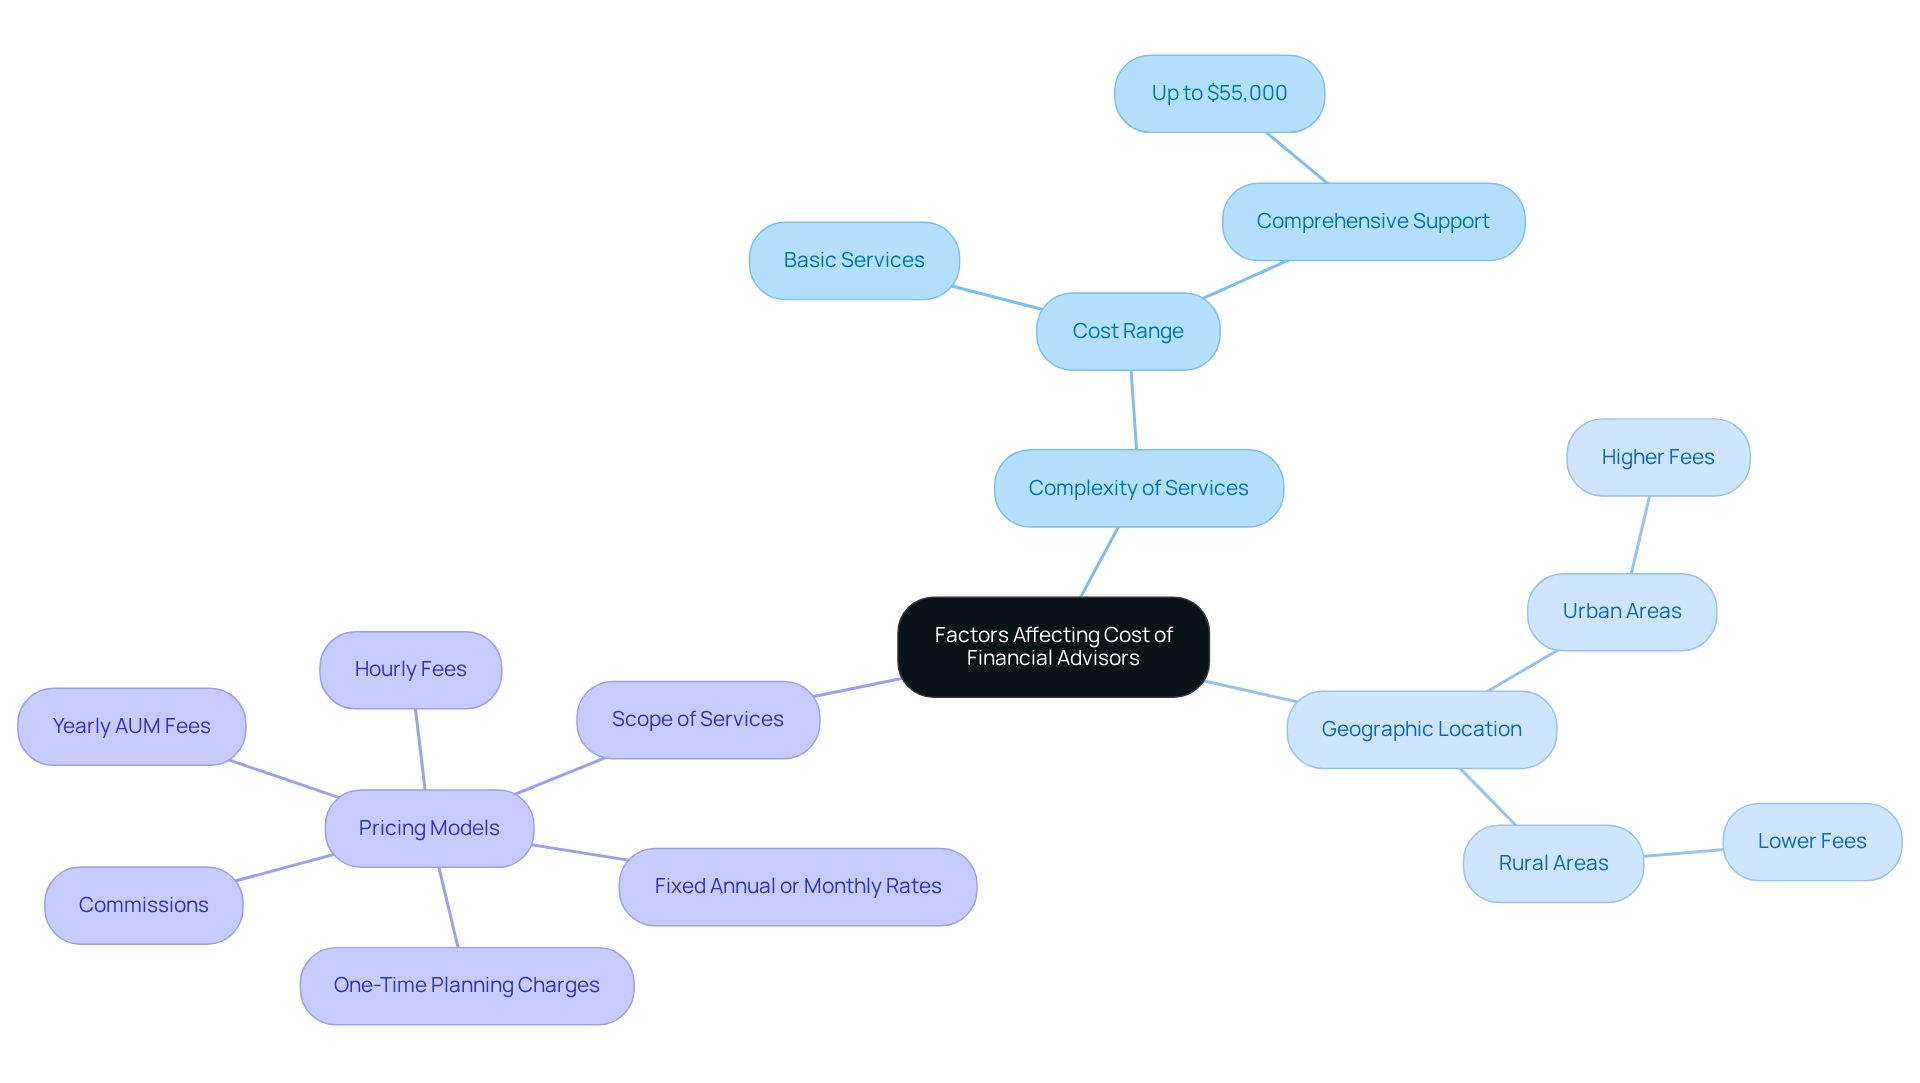
Navigating the world of financial consulting can feel overwhelming, especially for young parents. Understanding how much fee-only financial planners cost and the various factors that influence these fees is crucial in making informed decisions that align with your family’s needs. Advisors with significant experience or advanced certifications, like Certified Financial Planner (CFP) or Chartered Financial Analyst (CFA), often charge higher fees. Their expertise allows them to skillfully navigate complex financial landscapes, ensuring you receive personalized guidance tailored to your family’s goals.
-
Complexity of Services: If you find yourself managing multiple income streams, substantial investments, or intricate tax matters, it’s important to recognize that these complexities can lead to higher costs. The time and knowledge required to address these issues can range from a few thousand dollars to as much as $55,000 for comprehensive support. When considering hiring fee-only advisors, it’s important to understand how much fee-only financial planners charge, as they are paid solely by their clients without commissions from investment products, offering a conflict-free relationship and unbiased advice focused on your best interests. For instance, Lifeworks offers personalized investment consulting with a standard advisory fee of 0.80%, billed monthly based on your account’s market value.
-
Geographic Location: Your location can also impact the cost of advisory services. Advisors in urban areas, where living expenses are higher, may charge more than those in rural settings. Additionally, local demand and competition can further affect pricing. For instance, families in urban regions might find that fees are significantly higher due to increased demand for financial services.
-
Scope of Services: The breadth of services an advisor offers can greatly influence costs. Comprehensive financial planning, which includes investment management, tax planning, and estate planning, generally comes at a higher price than basic advice. Lifeworks, for example, provides a wrap fee program where clients pay a single asset-based fee that covers various brokerage and administrative expenses. This can lead to varying overall costs depending on the level of trading in a given year. Families seeking a holistic approach to their financial well-being should anticipate a premium for these integrated services. As Andrea Coombes notes, money advisors may present various pricing models, including yearly AUM fees, fixed annual or monthly rates, hourly fees, one-time planning charges, or even commissions for certain advisors.
By grasping these elements, you can make informed choices when selecting a financial advisor, ensuring you receive the quality of support that aligns with your family’s financial objectives and complexities. Remember, we’re here for you, and together, we can navigate this journey towards financial security.
Select the Right Fee-Only Financial Planner for Your Needs
Selecting the right fee-only financial planner is a journey that can significantly shape how much are fee-only financial planners in your family’s financial future.
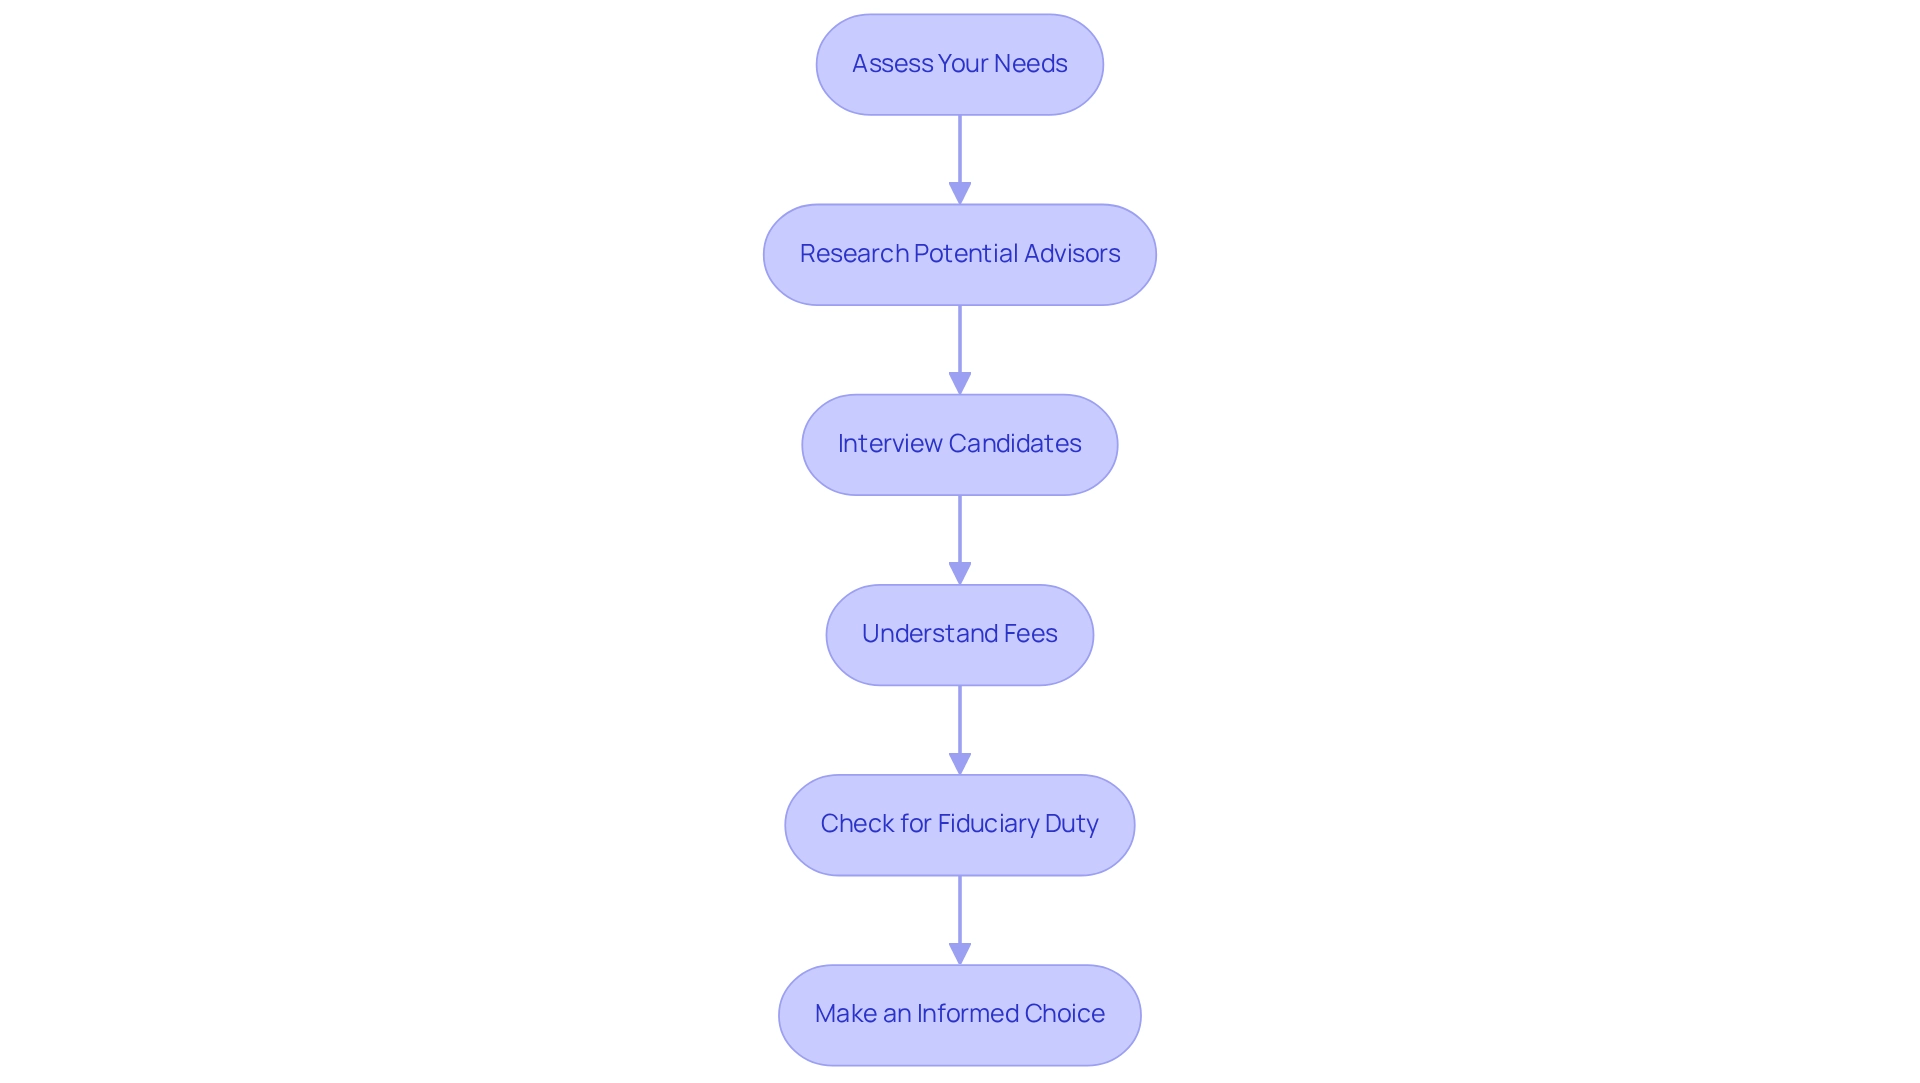
- Assess Your Needs: Imagine starting by identifying the specific services you require, such as retirement planning, investment management, or tax advice. This clarity will help you narrow down your options effectively. It’s essential to recognize that 84% of millennials are underinsured, highlighting the necessity for thorough planning that includes adequate insurance coverage.
- When researching potential advisors, consider how much are fee-only financial planners and seek out those who operate on this basis. Review their credentials, experience, and client testimonials. Utilizing resources like NAPFA can assist you in finding qualified advisors who meet your criteria. For instance, families like Emily and Mark have benefited from Bright Advisers’ customized support, which was created to address their specific needs and objectives.
- Interview Candidates: Arrange consultations with potential planners to discuss your monetary goals. Inquire about how much are fee-only financial planners, as well as their services offered and investment philosophies. This interaction allows you to evaluate their communication style and overall compatibility with your family. As Kris Borghesan observes, “When we examine all of these figures holistically, it’s clear that they all affect one another and influence other important aspects of your economic life,” emphasizing the significance of a thorough approach. Bright Advisers illustrates this by assisting clients through a series of strategy sessions to create a tailored monetary plan.
- It’s important to gain a comprehensive understanding of how much are fee-only financial planners charge for their services. Request a detailed breakdown of all potential costs to avoid any unexpected expenses down the line. Bright Advisers ensures transparency in their fee structures, which is crucial for building trust.
- Check for Fiduciary Duty: Ensure that the planner adheres to a fiduciary standard, which legally obligates them to act in your best interest. This is essential for establishing trust and ensuring that your monetary needs are prioritized.
By following these steps, young families can make informed choices when selecting a planner, ultimately leading to improved monetary results and peace of mind. The case study of Emily and Mark demonstrates how Bright Advisers assisted them in attaining economic independence through customized wealth management tactics, showcasing the transformative effect of personalized monetary planning.
- Join our waitlist: Thank you for considering Bright Advisers for your planning needs. We are currently at capacity and encourage you to join our waitlist. Our team will reach out as soon as we have availability to discuss how we can help you achieve your financial goals.
Conclusion
Fee-only financial planners represent a significant shift in financial advisory services, focusing on what truly matters—your family’s best interests. By eliminating the conflicts of interest found in commission-based models and adhering to a fiduciary standard, these professionals empower families like yours to make informed decisions about their financial futures. Understanding the various fee structures available—whether hourly, flat fees, or assets under management—is crucial. This knowledge helps you select the most suitable arrangement tailored to your unique needs.
Several factors play a crucial role in determining the costs of hiring a financial advisor. Experience, the complexity of services, geographic location, and the scope of services offered are all important considerations. By recognizing these elements, you can make informed choices when seeking guidance, ensuring that the level of service aligns with your family’s financial goals.
Ultimately, choosing the right fee-only financial planner involves a thoughtful process of assessing your needs, researching potential advisors, and understanding fee structures. By following these steps, you can cultivate a trustworthy relationship with your financial planner, paving the way for a secure and prosperous financial future. Remember, the journey towards financial well-being is a collaborative effort. With the right guidance, your family can navigate your financial landscape with confidence and clarity. Together, we can navigate this journey towards a brighter financial future.
Frequently Asked Questions
What is a fee-only adviser?
A fee-only adviser is a financial expert who charges individuals directly for their services, eliminating potential conflicts of interest associated with commission-based payment models. This ensures that their recommendations are unbiased and focused solely on the client’s best interests.
How does the fee-only model benefit families?
The fee-only model is particularly valuable for families seeking trustworthy financial guidance, as it operates under a fiduciary standard, legally binding advisers to prioritize their clients’ needs and empowering families to make informed financial decisions.
What services do fee-only advisers provide?
Fee-only advisers craft personalized financial strategies, offer investment guidance, and provide ongoing fiscal management, fostering a transparent relationship that allows parents to focus on their children’s futures without potential conflicts.
What percentage of money advisers are expected to adhere to fiduciary standards by 2025?
Approximately 70% of money advisers are expected to adhere to fiduciary standards by 2025, reflecting a growing commitment to ethical practices in the financial advisory industry.
How has the rise of fee-only planners impacted the financial advisory landscape?
The rise of fee-only planners has led to significant growth in assets managed by robo-advisors, reaching $1.37 trillion in 2023, indicating a shift toward technology-driven asset management and personalized advisory services.
What investment strategies do fee-only advisers typically utilize?
Fee-only advisers may utilize various investment approaches, including the Diversified Premia, Opportunity Strategy, and Quality Strategy, to optimize financial outcomes for their clients.
How do case studies illustrate the value of fee-only financial planners?
Case studies, such as that of Emily and Mark, demonstrate how fee-only planners are valued for the increased trust and transparency they bring to families, resulting in better financial results.
How is technology influencing the services provided by fee-only advisers?
The digital transformation in investment advisory practices allows firms like Bright Advisers to expand operations and deliver tailored experiences for clients, highlighting a shift towards innovative wealth management strategies.
List of Sources
- Define Fee-Only Financial Planners and Their Role
- Financial advisor industry statistics: key data and trends (https://unbiased.com/pro/discover/trends-insight/financial-advisor-industry-statistics)
- What You Need To Know About Fee-Only Financial Advisors (https://investopedia.com/articles/investing/102014/feeonly-financial-advisers-what-you-need-know.asp)
- Explore Common Fee Structures for Financial Planning
- How Much Does a Financial Advisor Cost? (Updated for 2025) (https://harness.co/articles/average-fees-for-financial-advisors)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost (2025 Insights) (https://jccastleaccounting.com/how-much-does-a-financial-advisor-cost-2025-insights)
- Identify Factors Affecting the Cost of Financial Advisors
- How Much Does a Financial Advisor Cost (2025 Insights) (https://jccastleaccounting.com/how-much-does-a-financial-advisor-cost-2025-insights)
- How Much Does a Financial Advisor Cost? (Updated for 2025) (https://harness.co/articles/average-fees-for-financial-advisors)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- Select the Right Fee-Only Financial Planner for Your Needs
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading