

Overview
Navigating the world of financial advisor fee structures can feel overwhelming, especially for young parents striving to secure their family’s future. This article delves into the various fee types you might encounter:
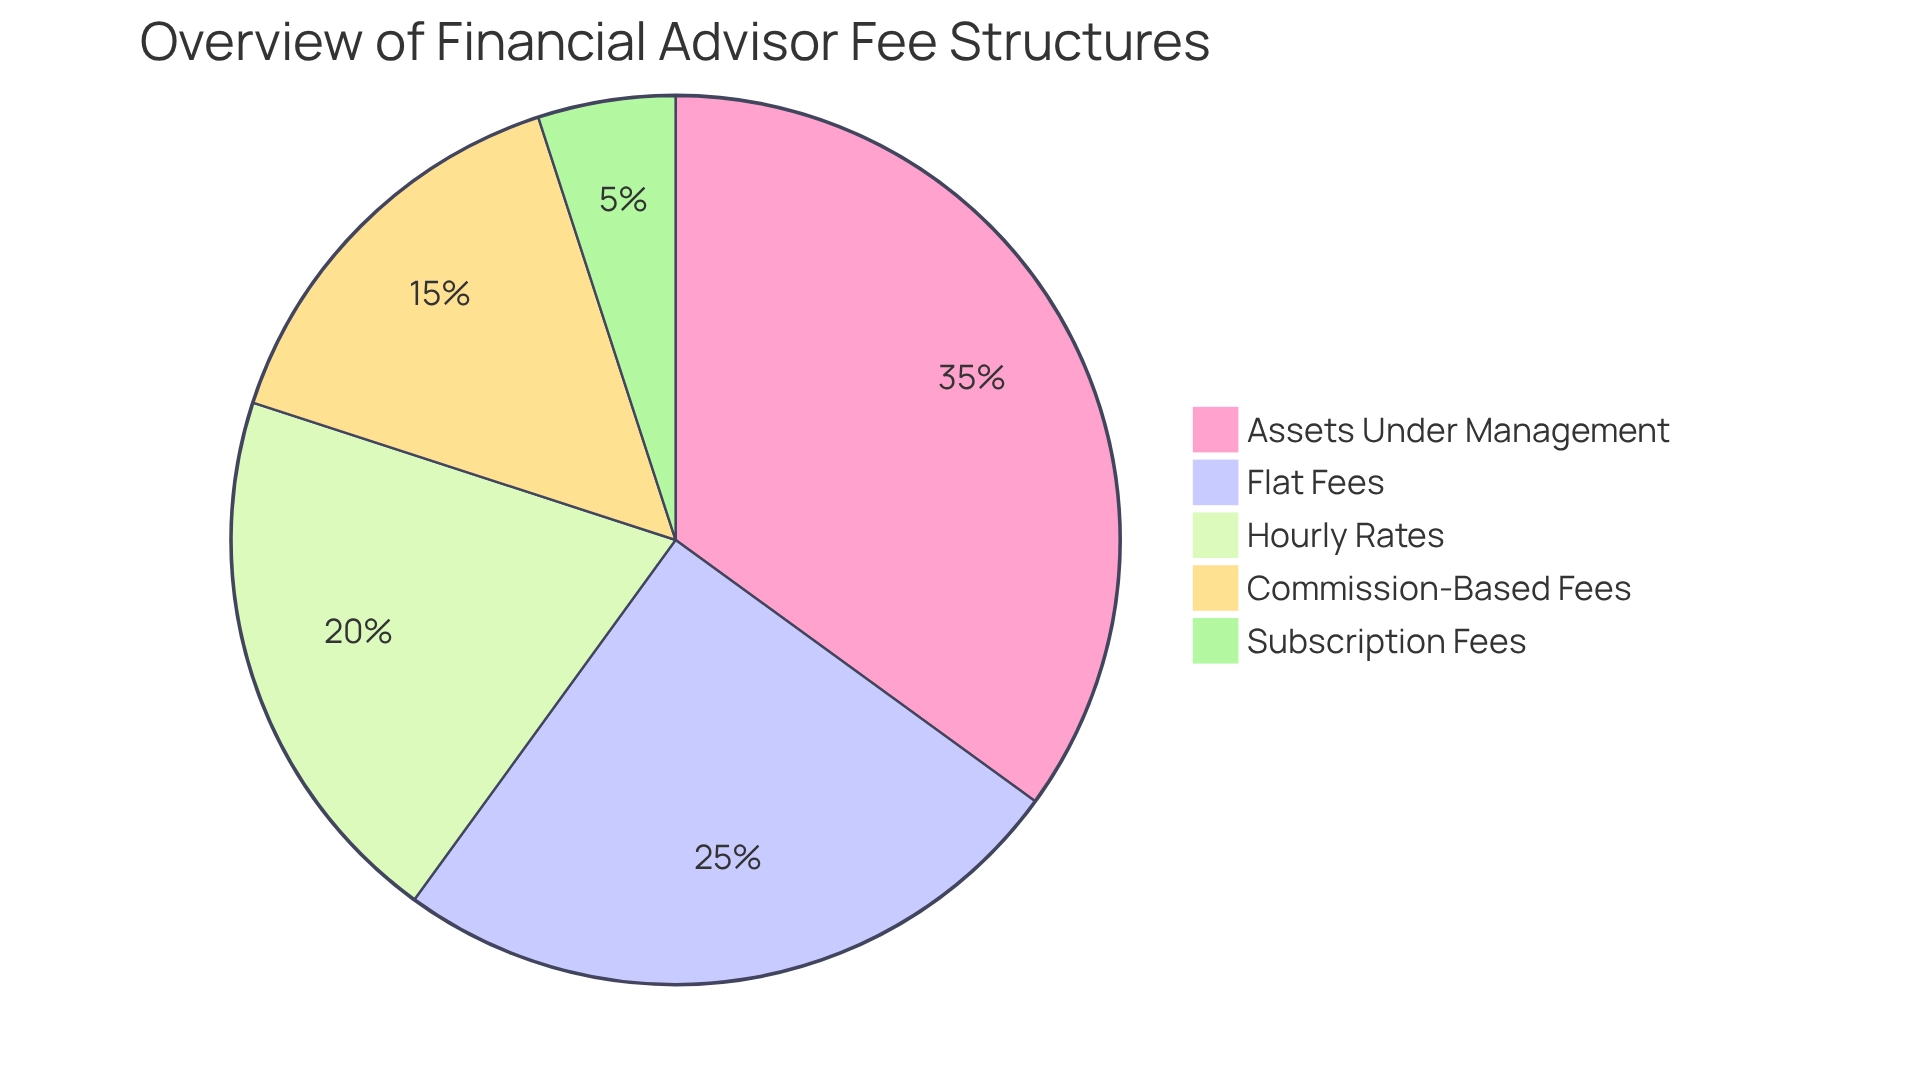
- Assets Under Management (AUM) fees
- Flat fees
- Hourly rates
- Commission-based fees
- Subscription fees
Understanding these fees is crucial for making informed decisions that align with your family’s financial health.
Imagine if you could confidently evaluate and compare these fees to ensure transparency in your financial journey. It’s essential to know the typical ranges and implications of each fee structure, as this knowledge empowers you to negotiate effectively. By doing so, you can prioritize your family’s needs and make choices that truly reflect your values.
We’re here for you, guiding you through strategies that not only clarify these fee structures but also help you feel secure in your financial decisions. Together, we can navigate this journey, ensuring that you have the support you need to achieve your family’s financial goals. Remember, understanding these fees is not just about numbers; it’s about creating a stable future for your loved ones.
Key Highlights:
- Understanding financial advisor fees is crucial for family financial health.
- Assets Under Management (AUM) fees typically range from 0.25% to 2% annually, decreasing as the portfolio grows.
- Flat fees are fixed charges for specific services, usually between $1,000 and $5,000.
- Hourly rates range from $120 to $400, allowing payment only for the time needed.
- Commission-based fees can lead to conflicts of interest, as advisors earn from the products sold.
- Subscription fees provide ongoing services for a predictable monthly or annual cost.
- Families should maintain an emergency fund, with recommendations to cover three to six months of living expenses.
- When evaluating fees, gather information, create comparison charts, assess services, check for hidden fees, consider consultant experience, and read reviews.
- Negotiating fees can lead to savings; research market rates, be open about budget, and request written agreements.
- Bright Advisers aims to keep fund fees low and focuses on transparency and tailored services for families.
Introduction
Navigating the world of financial advisory services can feel overwhelming, especially when faced with a variety of fee structures that could impact your family’s long-term financial well-being. Imagine trying to make sense of asset-based fees, flat rates, and commissions—it’s essential to understand how these costs work as you seek effective wealth management for your loved ones. As financial landscapes evolve, so do the preferences of families like yours, who increasingly value transparency and clarity in financial planning.
This article explores the different fee structures employed by financial advisors, offering insights to help you evaluate, compare, and negotiate fees. By equipping yourself with this knowledge, you can ensure that you receive the best value for your investments. Together, we can navigate this journey, empowering you to make informed decisions that align with your financial goals and secure a prosperous future for your family. Remember, we’re here for you every step of the way.
Understand Financial Advisor Fee Structures
Understanding how much financial advisor fees are and the various fee structures that financial advisors use can feel overwhelming, but it’s crucial for your family’s financial health. Let’s explore these options together, so you can find the best fit for your needs.
-
Assets Under Management (AUM) is a common model where advisors charge a percentage of the assets they manage, typically ranging from 0.25% to 2% annually. As your portfolio grows, this percentage often decreases, making it a more cost-effective choice for larger investments.
-
Flat Fees are another option. Here, advisors may charge a fixed amount for specific services, like creating a comprehensive financial plan. These fees can vary widely, usually falling between $1,000 and $5,000, depending on the complexity of the services you require.
-
Some advisors charge Hourly Rates, typically between $120 and $400. This model allows you to pay only for the time you need, which can be perfect for consultations or specific projects.
-
In a Commission-Based Fee structure, advisors earn commissions from the financial products they sell. While this can lead to lower initial costs, it may create conflicts of interest, as some advisors might lean towards products that yield higher commissions instead of those that best meet your family’s needs.
-
An emerging trend is Subscription Fees, where some advisors offer ongoing services for a monthly or annual fee. This model provides a predictable cost structure, making financial planning more accessible for families.
At Bright Advisers, we prioritize keeping our fund fees low across most of our models. We believe that families should have access to wealth management services without facing excessive costs. However, it’s important to be aware that some clients may still hold legacy fee-bearing mutual funds and ETFs, which can affect their overall fee structure. Understanding how much financial advisor fees are is vital for you to identify which model aligns best with your financial goals. Recently, many families have shown a preference for transparent and flat fee arrangements, seeking clarity in their planning expenses.
In addition to fee structures, it’s essential to maintain an emergency fund. Warren Buffett recommends keeping three to six months’ worth of living expenses in a savings or money market account as a safety net. This strategy helps prevent forced sales at a loss and provides economic security for your family.
As Buffett wisely noted, “An investor should act as though he had a lifetime decision card with just twenty punches on it.” This highlights the importance of thoughtful financial planning and decision-making, especially for families navigating their financial futures. By considering your options and surrounding yourself with knowledgeable guides, you can make informed decisions that support your long-term economic well-being. Remember, we’re here for you, and together, we can navigate this journey.
Explore Different Types of Financial Advisor Fees
When evaluating financial advisor fees, it’s essential to understand the different types available to you and your family:
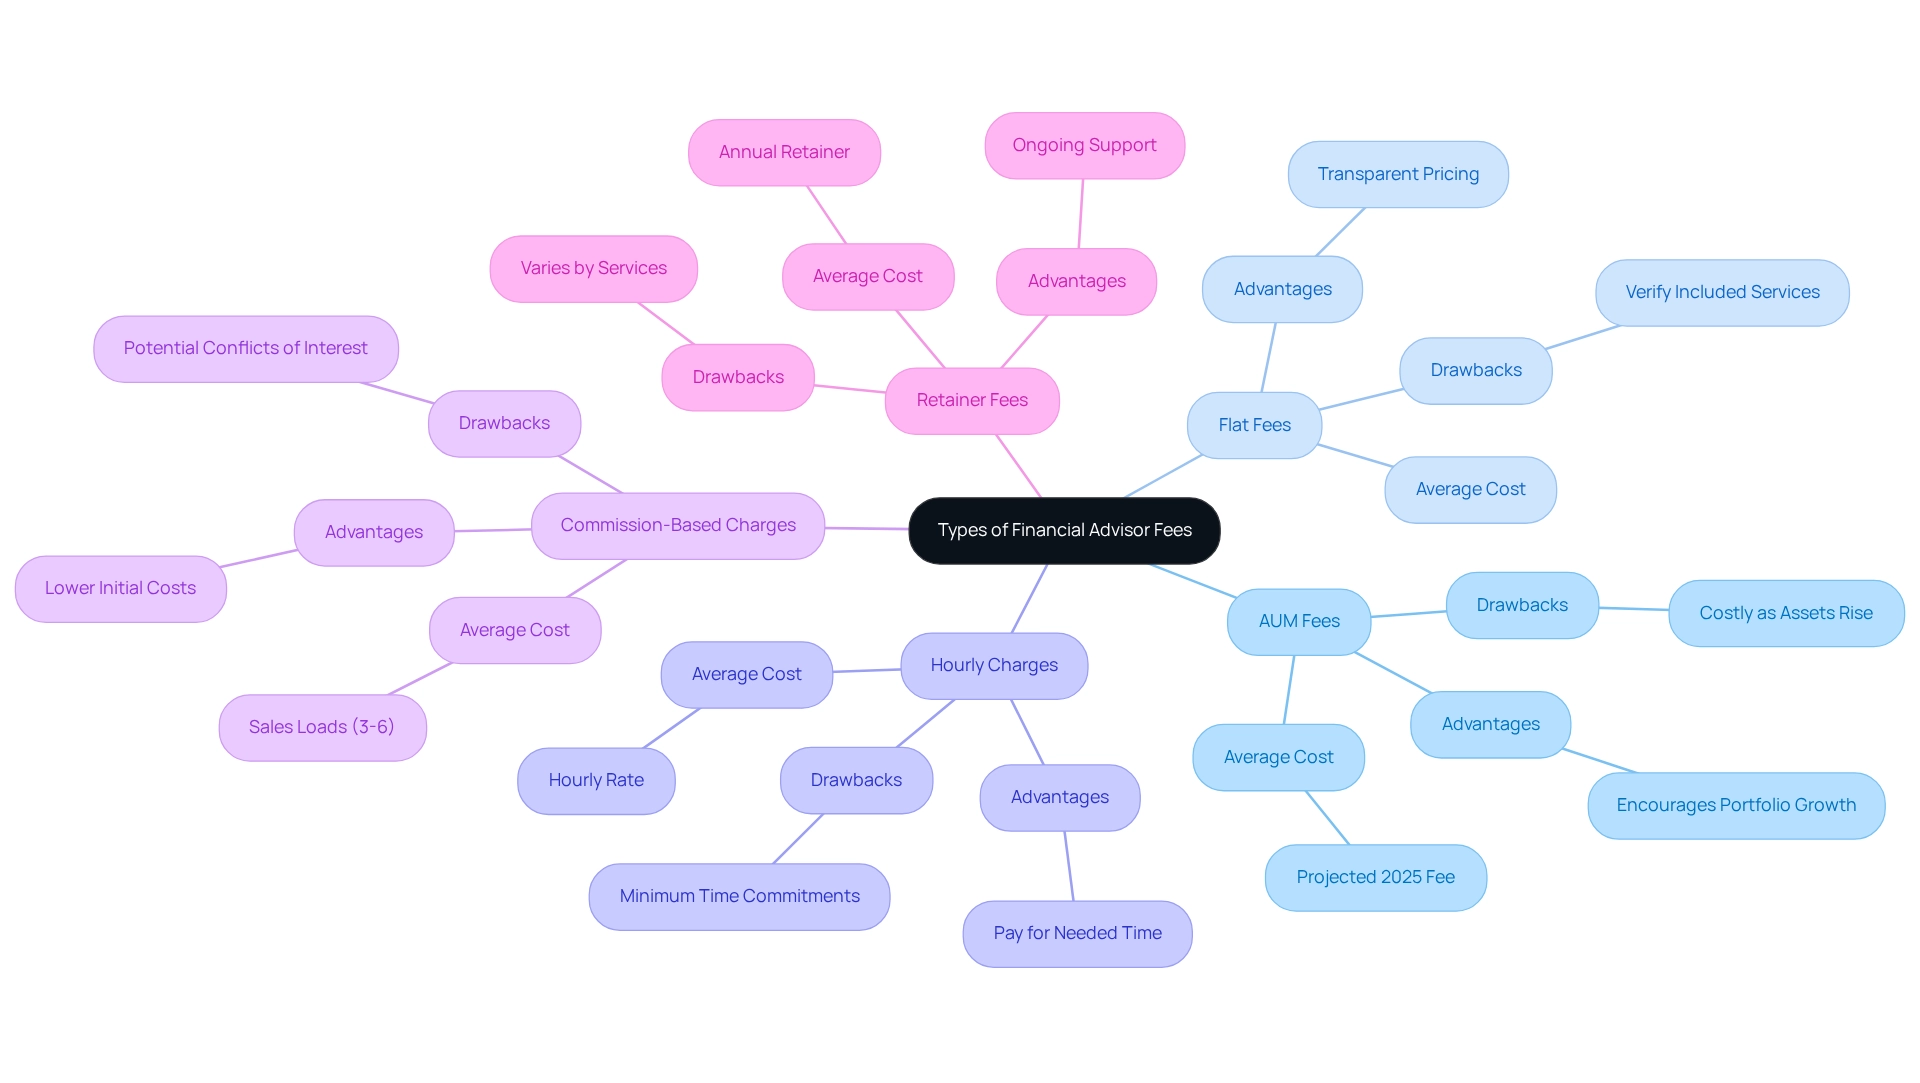
- AUM Fees: These fees are based on a percentage of the total assets managed. For instance, imagine if a consultant manages $1,000,000 and charges a 1% fee; the yearly expense would be $10,000. While this model encourages consultants to expand your portfolio, it can become costly as your assets rise. In 2025, the average AUM fee for investment advisors is projected to be around 1.05%, reflecting a common industry standard.
- Flat Fees: This structure is ideal for families who prefer a transparent, upfront cost. Fixed charges can include extensive financial strategy or particular services, such as retirement planning. It’s important for you to verify that the flat fee includes all required services to prevent unanticipated costs.
- Hourly Charges: Best suited for those seeking occasional advice rather than ongoing management, hourly charges allow you to pay only for the time you require. Be sure to inquire about the advisor’s hourly rate and any minimum time commitments.
- Commission-Based Charges: Although these charges may seem lower at first, they can result in greater long-term expenses due to commissions on products sold, which typically range from 3% to 6% of your investment. It’s crucial to be vigilant about potential conflicts of interest and seek clarity on how these fees are structured. As Andrea Coombes notes, “You carry out the plan on your own and there is no ongoing oversight from the provider unless you request and pay for additional time.”
- Retainer Fees: Some consultants charge a retainer for ongoing services, offering peace of mind for families who need continuous support. This fee structure can vary significantly based on the advisor’s services and expertise.
For families aiming to budget effectively for financial planning services, it is vital to understand how much are financial advisor fees. At Bright Advisers, we are dedicated to low fund charges, ensuring that families can access wealth management without undue expenses. This commitment pertains to the vast majority of our models, although some customers may possess legacy fee-bearing mutual funds and ETFs, which can affect overall expenses. According to the 2024 State of Financial Planning and Charges study, average yearly retainer costs are approximately $4,484, while hourly rates are around $268. This information enables you to assess typical costs and choose services that match your family’s monetary needs. Together, we can navigate this journey with confidence.
Evaluate and Compare Financial Advisor Fees
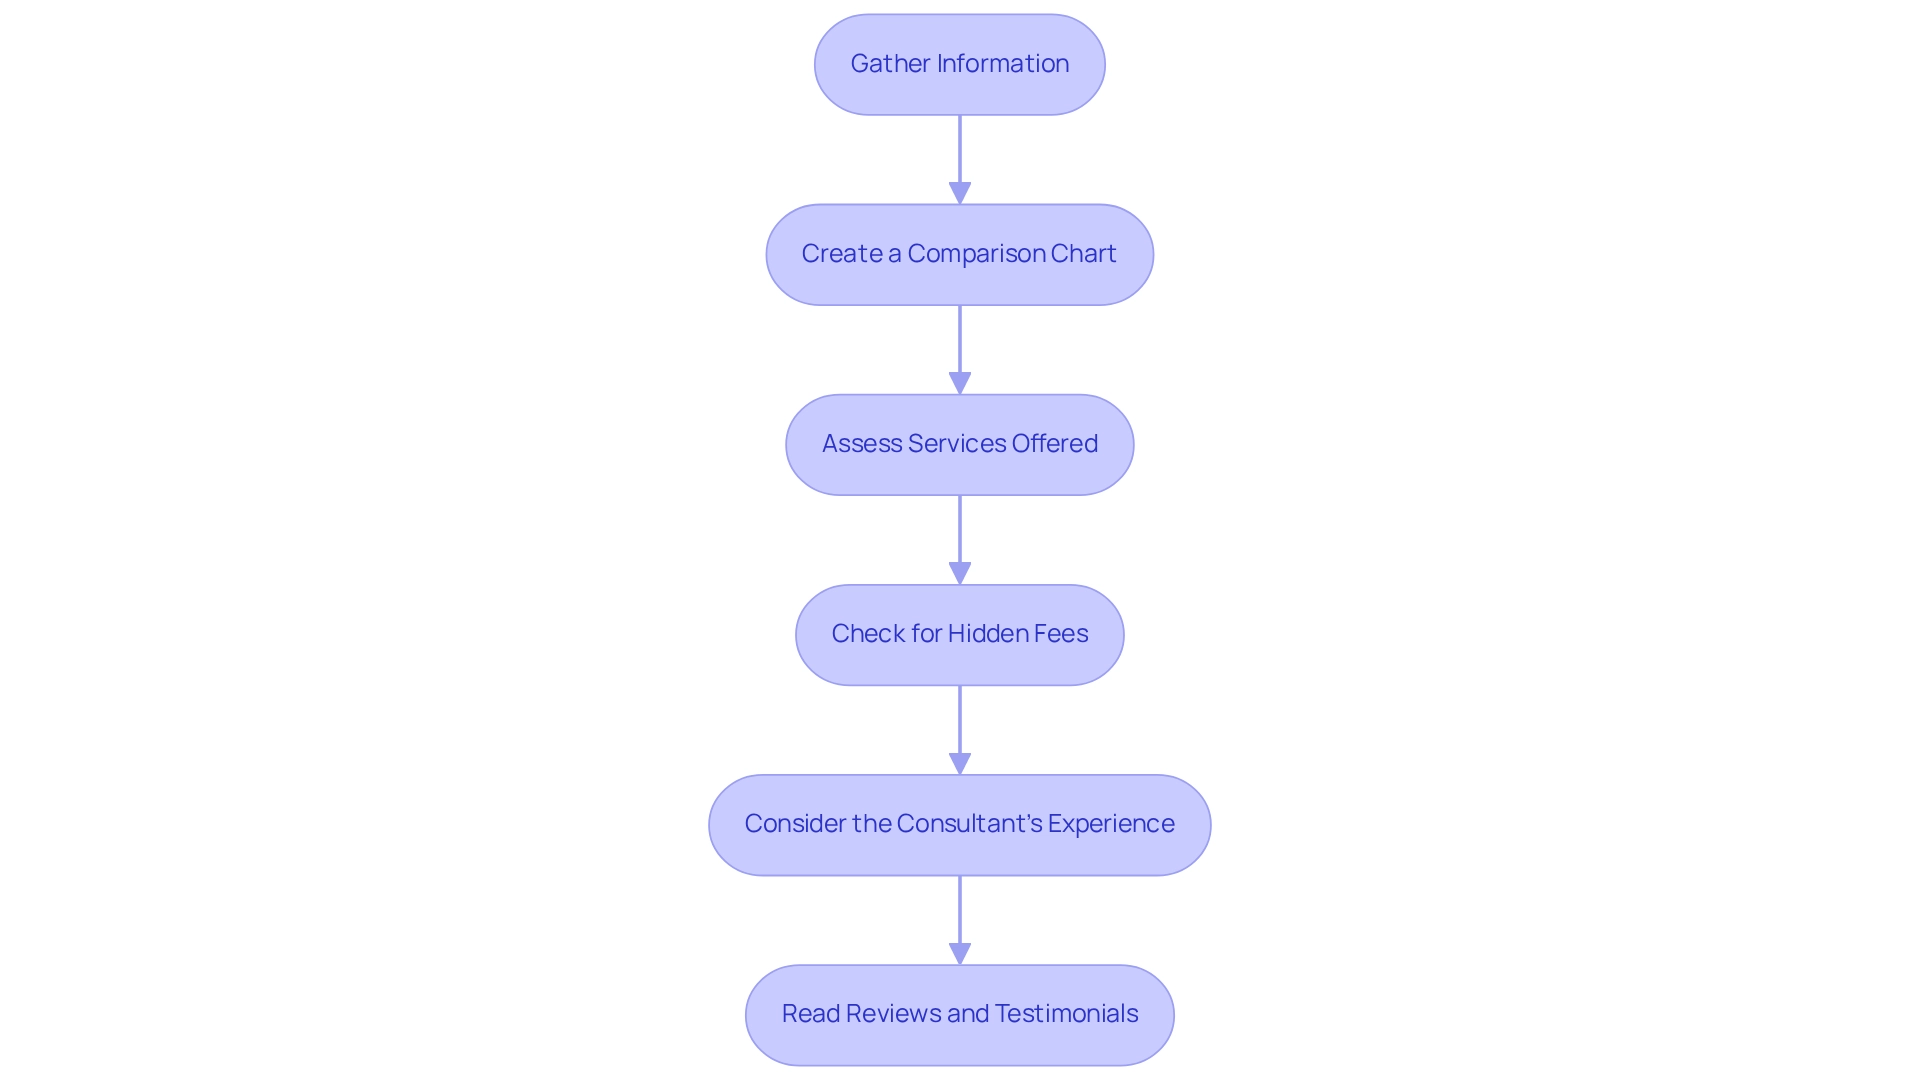
To effectively assess and contrast how much financial advisor fees are, consider these important steps:
- Gather Information: Start by collecting detailed fee structures from multiple advisors. Request a comprehensive summary that includes all potential expenses, ensuring you understand what you might be billed beyond the standard charges. At Bright Advisers, we focus on reducing fund charges, making wealth management more accessible for families like yours. Remember, some clients may hold legacy fee-bearing mutual funds and ETFs, which could influence overall costs.
- Create a Comparison Chart: Organize the information you’ve gathered into a comparison chart. This should include various charge types such as assets under management (AUM) costs, flat rates, hourly charges, and any commissions. For example, an investor with £500,000 invested would incur £2,000 in platform charges at a rate of 0.4% annually. This visual representation will help you easily spot the differences and make informed choices.
- Assess Services Offered: Take a moment to review the services included in the charges. A lower fee might not be beneficial if it comes with limited services or less personalized attention. Ensure that the consultant’s offerings align with your family’s financial needs.
- Check for Hidden Fees: It’s essential to inquire about any hidden fees that may not be immediately visible, such as trading fees or costs linked to specific investment products. Transparency is key in understanding the total cost of advisory services, and at Bright Advisers, we strive to provide clear information about all potential fees.
- Consider the Consultant’s Experience: Evaluate the qualifications and background of the consultant. Sometimes, opting for a slightly higher charge for a more experienced consultant can lead to better long-term financial outcomes.
- Read Reviews and Testimonials: Seek feedback and testimonials to gauge the consultant’s reputation. Understanding how other clients perceive the value they receive in relation to how much financial advisor fees are can offer valuable insights.
Ultimately, it’s important for you to determine if the charges imposed by advisers are justified by the value they provide. By following these steps, families can make informed decisions about hiring a financial consultant, ensuring that the charges incurred are warranted by the value offered. Our goal is to help you find a consultant who not only meets your financial needs but also resonates with your family’s values and long-term aspirations. Together, we can navigate this journey.
Negotiate and Ensure Transparency in Fees
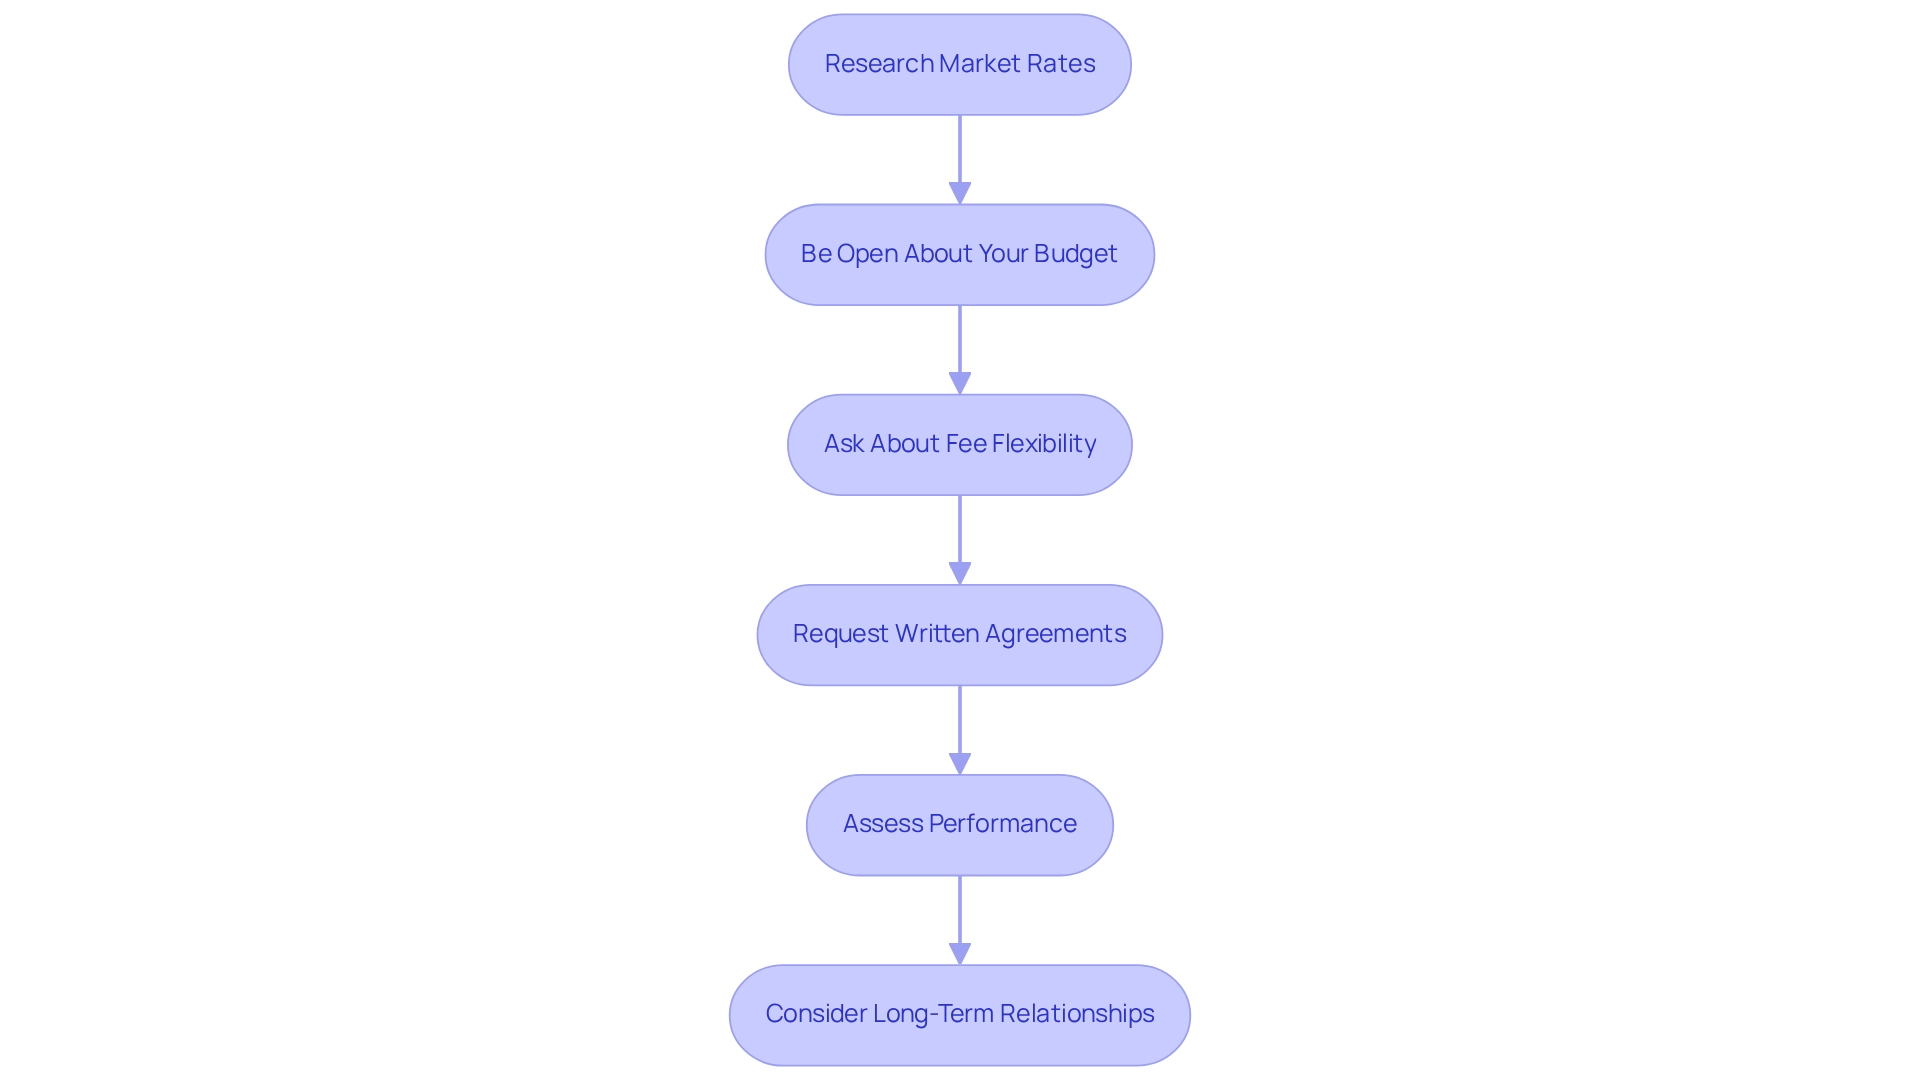
Negotiating financial consultant charges can lead to significant savings and foster a more beneficial financial relationship. Here are some effective strategies to ensure transparency and negotiate successfully:
- Research Market Rates: Start by exploring standard charges for similar services in your area. For example, Charles Schwab’s highest charges for transactions of $500,000 or more are a $255 flat rate plus 0.09 percent of the principal. Understanding how much financial advisor fees are can empower you during negotiations, helping you set reasonable expectations.
- Be Open About Your Budget: Share your budget limitations with the consultant. Many financial experts are willing to adjust their charges when they understand your financial situation and goals.
- Ask About Fee Flexibility: Inquire if the consultant can modify their fee structure based on your specific needs. They might offer a reduced asset under management (AUM) fee for larger portfolios, leading to substantial savings.
- Request Written Agreements: Make sure that all charges and services are documented in writing. This transparency is crucial for avoiding misunderstandings and ensuring both parties are aligned on expectations.
- Assess Performance: If you feel the consultant’s performance does not justify their charges, don’t hesitate to bring this up. A trustworthy consultant will value your feedback and may be willing to adjust their fees to reflect the value they provide.
- Consider Long-Term Relationships: If you’ve been with an advisor for a while, use your loyalty in negotiations. Advisors often appreciate long-term clients and may offer better terms to keep your business.
Bright Advisers is committed to minimizing fund fees, making wealth management more accessible for families. By thoroughly assessing clients like Emily and Mark—looking at their income, expenses, assets, and liabilities—Bright Advisers tailors its services to meet specific needs. This collaborative approach empowers families to unite around shared values and goals, ultimately guiding them toward financial freedom through personalized wealth management strategies.
Conclusion
Understanding the various fee structures of financial advisors is crucial for families seeking effective wealth management. Imagine navigating the complexities of asset-based fees, flat rates, hourly charges, and commission-based structures. Each model presents unique implications for you and your loved ones. By recognizing how these fees work, you can make informed decisions that align with your financial goals and ensure you receive optimal value for your investments.
It’s important to understand that transparency in financial advisory services is essential. Families like yours are increasingly prioritizing clarity regarding costs, highlighting the need for open communication and a thorough evaluation of all potential fees. By gathering detailed information, comparing options, and negotiating effectively, you can navigate the complexities of financial planning with confidence.
Ultimately, securing a trusted financial advisor who values transparency and offers a fee structure that fits within your budget can lead to a stronger financial future for your family. By taking the time to understand and compare these fee structures, you can avoid unnecessary costs and build a lasting partnership with an advisor dedicated to your long-term success and financial well-being. Together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What are the common fee structures used by financial advisors?
Financial advisors commonly use several fee structures, including Assets Under Management (AUM), flat fees, hourly rates, commission-based fees, and subscription fees.
How does the Assets Under Management (AUM) fee structure work?
In the AUM model, advisors charge a percentage of the assets they manage, typically ranging from 0.25% to 2% annually. This percentage often decreases as your portfolio grows.
What are flat fees in financial advisory services?
Flat fees are fixed amounts charged for specific services, such as creating a comprehensive financial plan. These fees usually range from $1,000 to $5,000, depending on the complexity of the services required.
What are hourly rates charged by financial advisors?
Some advisors charge hourly rates, which typically range from $120 to $400. This model allows clients to pay only for the time they need, suitable for consultations or specific projects.
What is a commission-based fee structure?
In a commission-based fee structure, advisors earn commissions from the financial products they sell. While this may lead to lower initial costs, it can create conflicts of interest as advisors might favor products that yield higher commissions.
What are subscription fees in financial advisory services?
Subscription fees are a model where advisors offer ongoing services for a monthly or annual fee, providing a predictable cost structure that can make financial planning more accessible for families.
How does Bright Advisers approach financial advisor fees?
Bright Advisers prioritizes keeping fund fees low across most models, believing that families should have access to wealth management services without excessive costs. However, clients may still hold legacy fee-bearing mutual funds and ETFs that can affect their overall fee structure.
Why is it important to understand financial advisor fees?
Understanding financial advisor fees is vital to identify which fee model aligns best with your financial goals and to ensure clarity in planning expenses.
What does Warren Buffett recommend regarding emergency funds?
Warren Buffett recommends keeping three to six months’ worth of living expenses in a savings or money market account as a safety net to prevent forced sales at a loss and provide economic security.
What is the significance of thoughtful financial planning according to Warren Buffett?
Buffett emphasizes the importance of thoughtful financial planning and decision-making, suggesting that investors should act as though they have a limited number of significant investment decisions to make throughout their lifetime.
List of Sources
- Understand Financial Advisor Fee Structures
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Explore Different Types of Financial Advisor Fees
- Financial Advisor Fee Structures: Comparing Flat Fee and AUM (https://advisorhub.com/resources/financial-advisor-fee-structures-comparing-flat-fee-and-aum)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Evaluate and Compare Financial Advisor Fees
- Independent Financial Advisor Fee Comparison: All-In Costs (https://kitces.com/blog/independent-financial-advisor-fees-comparison-typical-aum-wealth-management-fee)
- How much does financial advice cost? Updated for 2025 (https://pyrfordfp.com/post/how-much-does-financial-advice-cost-updated-for-2025)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Negotiate and Ensure Transparency in Fees
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- How Much Does a Financial Advisor Cost? (2025) (https://talo.com/costs/financial-advisor-cost)
- What to Know About Financial Advisor Fees & Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading