

Key Highlights
- Pension plans serve as a safety net for families, ensuring steady income during retirement.
- Two main types of pension systems are Defined Benefit Plans, which offer predictable income, and Defined Contribution Plans, which depend on contributions and investment performance.
- As of 2023, there were 93.4 million participants in Defined Contribution Plans, indicating their growing popularity.
- Defined Benefit Plans provide a reliable monthly income, while Defined Contribution Plans require active management and understanding of investments.
- Cash Balance Plans combine features of both types, offering guaranteed payouts with individual accounts.
- The median annual benefit from private pensions in 2026 was around $11,440, highlighting the need for additional income sources for retirees.
- Factors influencing pension plan suitability include age, career stage, financial goals, risk tolerance, and employment stability.
- Bright Advisers assists families in navigating pension options and creating personalised financial plans, emphasising fiduciary duty and transparency.
Introduction
Imagine navigating the maze of pension plans, feeling uncertain about which choice will truly secure your family’s future. There are different paths to consider, like Defined Benefit Plans and Defined Contribution Plans. Each has its own benefits and challenges that can shape your family’s retirement income. Families like Jay and Emma often find themselves asking: which plan will truly support our dreams for the future? In this article, we’ll explore the potential of different pension plans, offering insights to help your family make choices that align with your dreams and values.
Understand Pension Plans: Definitions and Types
Imagine the peace of mind that comes from knowing your family’s financial future is secure, thanks to thoughtful pension planning. Pension schemes are like a safety net for your family, helping ensure you have a steady income when you retire. There are two main types of pension systems: Defined Benefit Plans and Defined Contribution Plans.
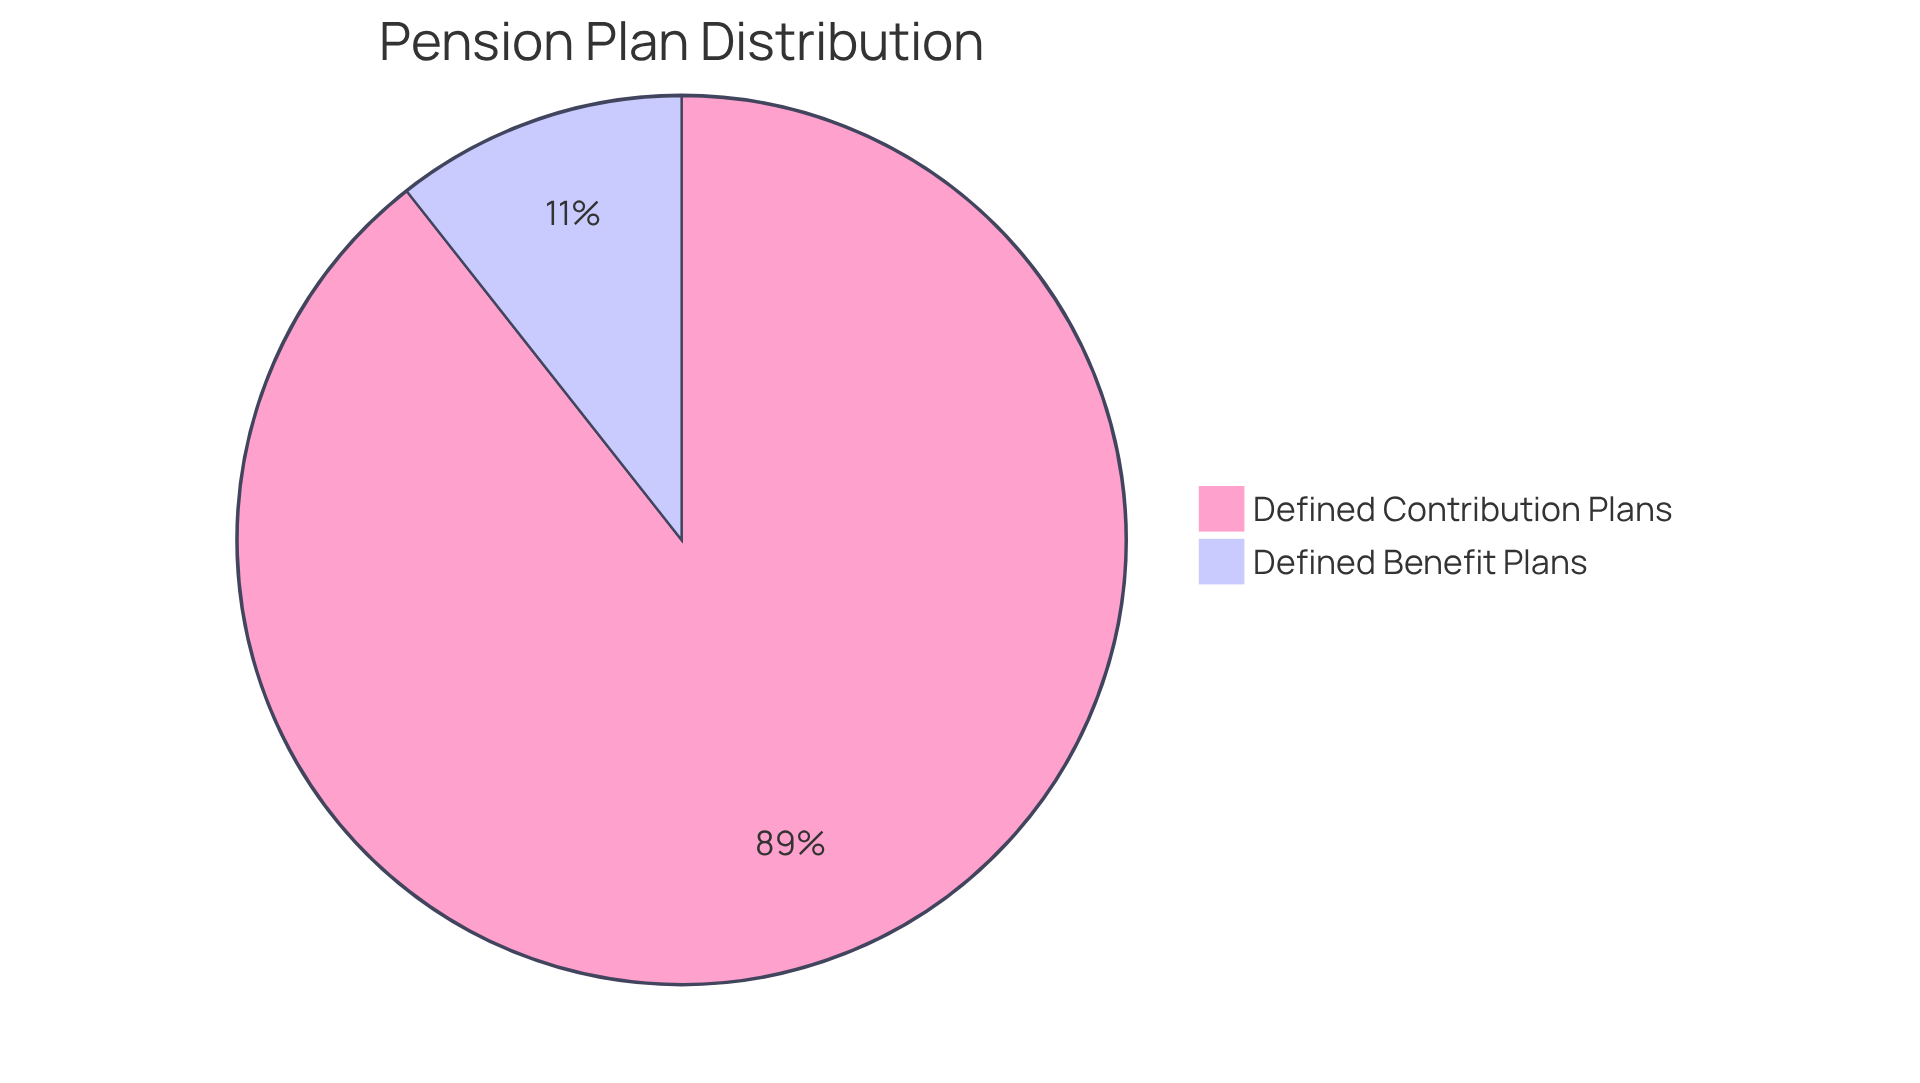
With Defined Benefit Plans, you can count on a reliable income based on your career, giving you peace of mind as you plan for retirement. These plans provide predictability and security, making them attractive for families who prioritize stable income during their later years. For instance, traditional benefit schemes usually offer a monthly annuity that remains consistent, ensuring a dependable income source. Yet, many families are moving towards contribution schemes, with only 11.1 million still in defined benefit plans, showing a shift in how we think about saving for the future.
On the other hand, Defined Contribution Plans, like 401(k)s, don’t guarantee a specific amount when you stop working. Instead, your retirement income depends on how much you contribute and how those investments perform. This approach requires more active management and understanding of investment options, which can be challenging for families who may not feel financially savvy. In 2023, there were 93.4 million participants in defined contribution schemes, highlighting their growing popularity.
Understanding these options is the first step for families to find the right fit for their financial goals and dreams. For families like Jay and Emma, who want to ease financial stress while managing resources for the future and addressing their children’s educational needs, working with a knowledgeable advisor can provide clarity and guidance. By evaluating the stability of traditional benefit schemes against the flexibility of contribution schemes, families can make informed choices about their retirement savings strategies.
At Bright Advisers, we’re here to help families navigate these complexities and create personalized financial plans that truly reflect your unique goals. Our services include integrated tax planning strategies and investment approaches designed to optimize your retirement savings. Join our waitlist today to discover more about how we can assist you in securing your household’s financial future. Please note that all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk. With the right guidance, you can transform uncertainty into confidence for your family’s future.
Explore Different Types of Pension Plans and Their Features
Navigating pension plans can feel overwhelming, especially when you’re trying to secure your family’s future. Here are some key features to consider:
-
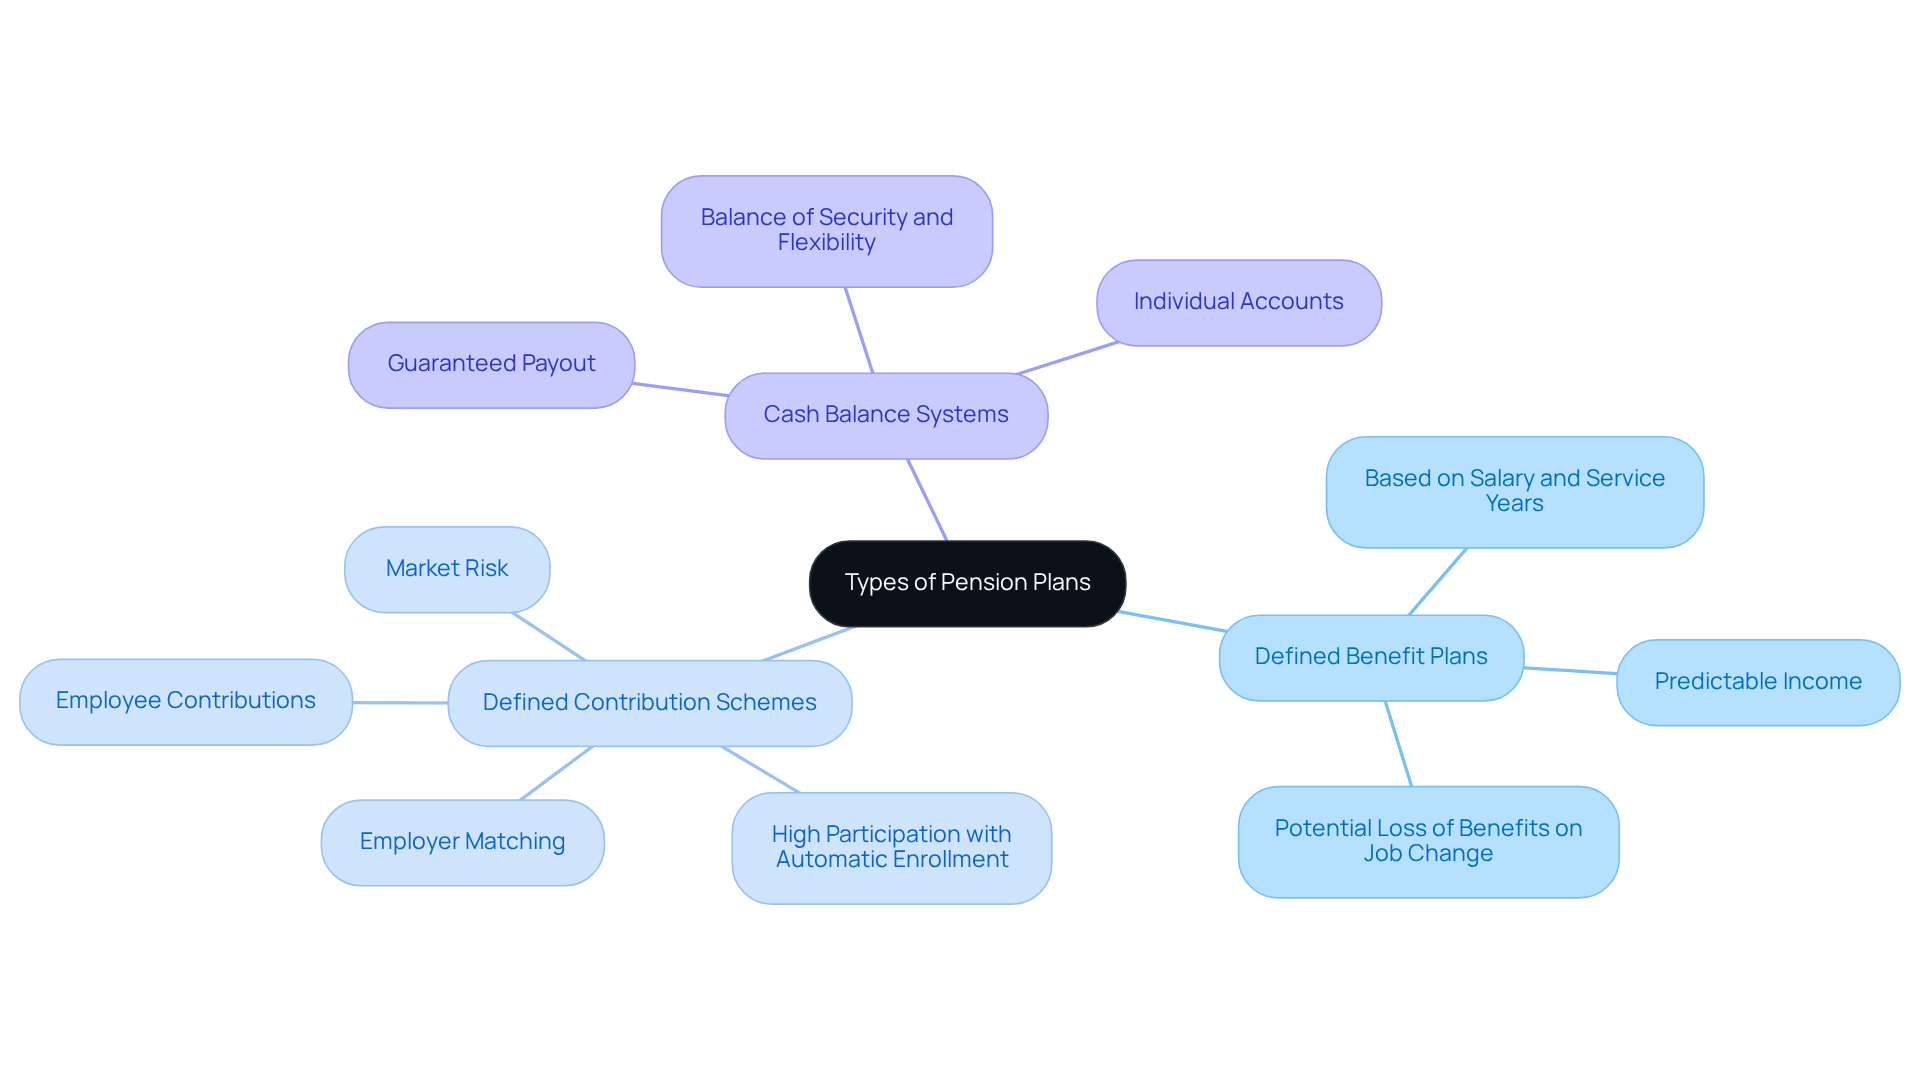
Defined Benefit Plans: These plans typically offer a predictable monthly income based on a formula that includes years of service and salary. This structure provides peace of mind, as retirees know exactly what to expect. But if you change jobs, you might worry about losing some of those benefits, which can be stressful.
-
Defined Contribution Schemes: These arrangements enable employees to contribute a portion of their salary, often with employer matching. Did you know that when companies automatically enroll employees in contribution schemes, nearly 90% participate? That’s a big difference compared to just 70% when they don’t! While these plans offer more flexibility and control over investments, they also come with risks, as market fluctuations can impact the final payout. This means you’ll need to stay informed and proactive about your investments.
-
Cash Balance Systems: A hybrid of the two, cash balance systems provide a guaranteed payout like defined benefit systems but allow for individual accounts like defined contribution systems. This can be attractive for households seeking a balance of security and flexibility.
Understanding these features can help your family weigh the pros and cons of each option. While pension systems are improving, with an average funded status of 85%, there’s still a significant shortfall of $1.13 trillion. This shows just how crucial it is to make informed financial choices for your family’s future. Remember, you’re not alone in this journey; we’re here for you every step of the way.
Compare Earnings Potential: Financial Benefits of Each Pension Plan
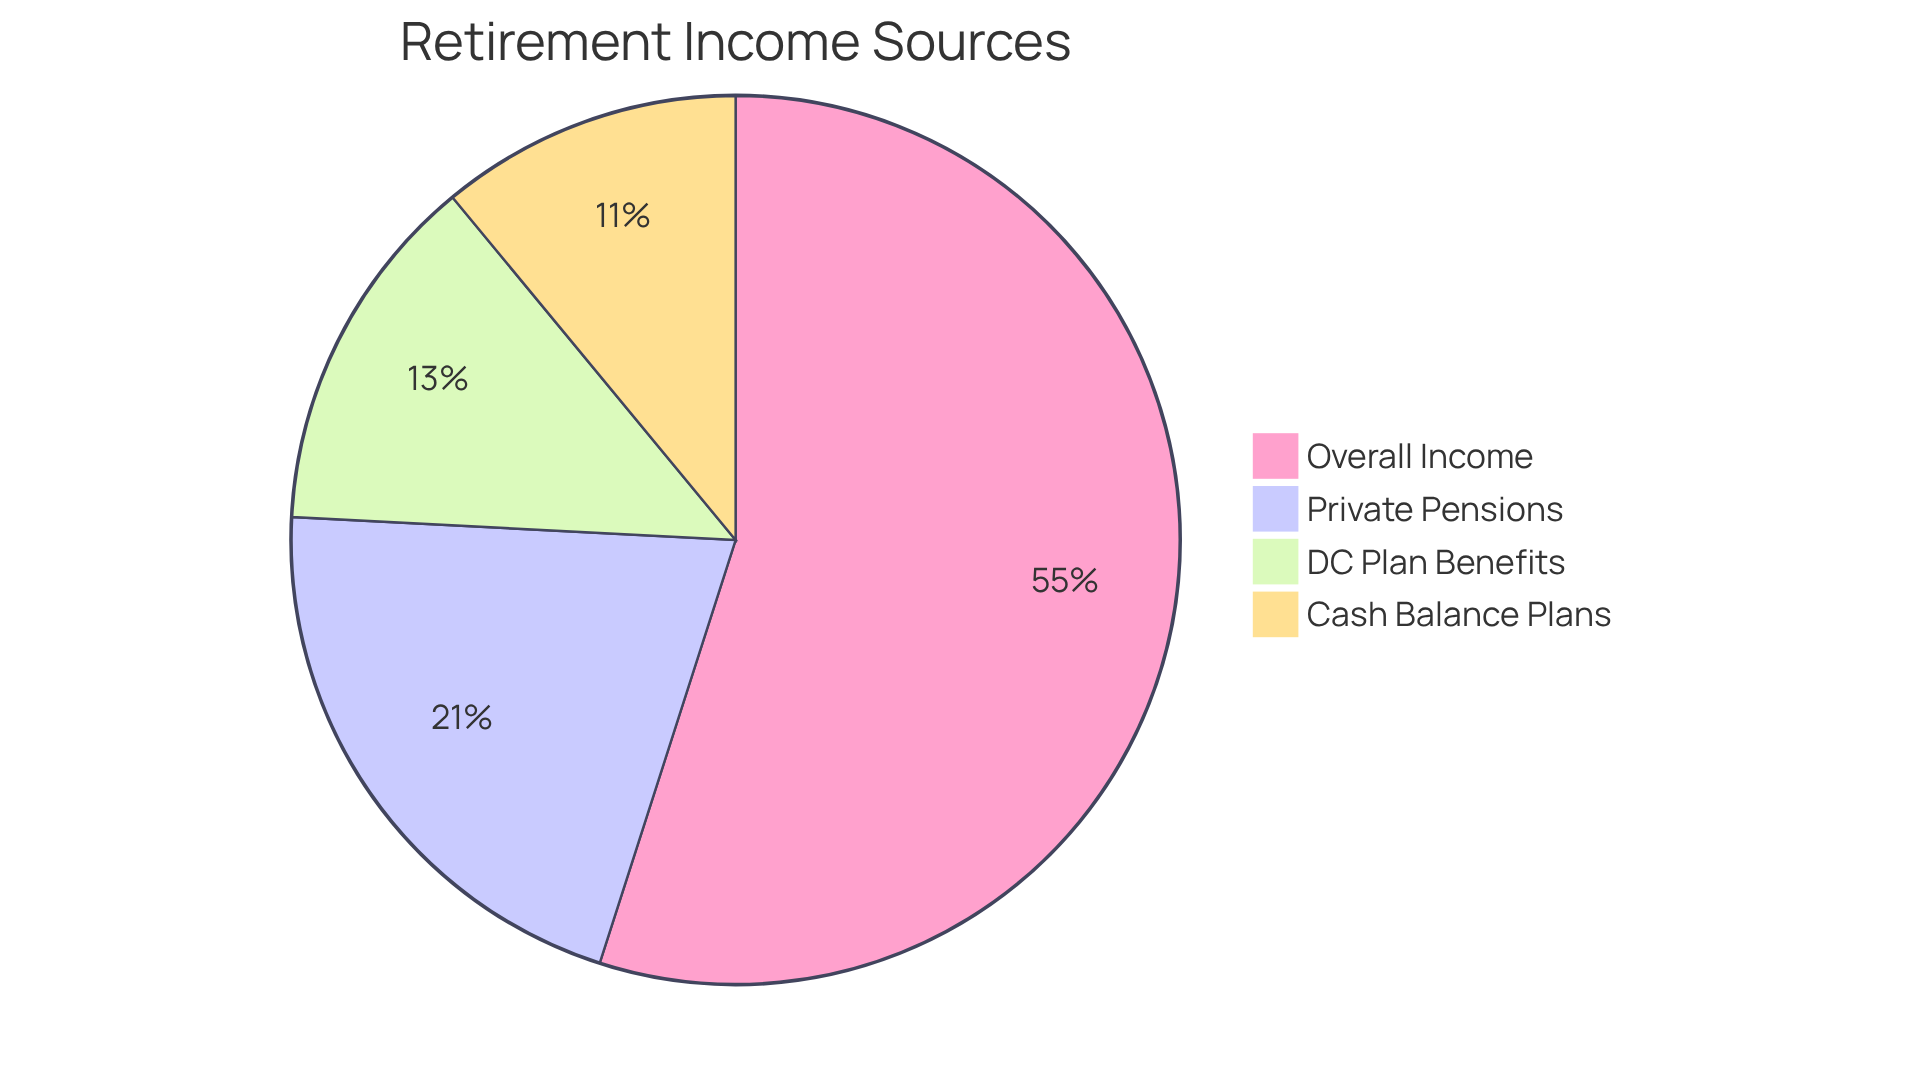
Imagine facing retirement with uncertainty about your financial future – it’s a reality many families grapple with today. The way pension plans are set up can significantly affect how much pensioners can earn. For many, the median annual benefit from private pensions in 2026 was around $11,440 – enough to provide some stability, but is it really enough for your family’s needs? While this amount can help, it’s essential to remember that the median income from all sources for individuals aged 65 and older was $29,740 in 2022. This broader context emphasizes the importance of considering various income sources when planning for the future.
Now, let’s talk about defined contribution schemes. These can be a bit unpredictable. For instance, households contributing regularly to a 401(k) with employer matching may build a retirement fund that replaces about 40% of their pre-retirement income. But keep in mind, this percentage can change based on how the market performs and how much you contribute – it’s a bit of a rollercoaster ride! In fact, in 2019, the annual benefit from a defined contribution arrangement was just 24% of what a defined benefit plan provided.
Then there are cash balance plans. These plans typically offer a guaranteed return on contributions, appealing to families seeking a balance of security and growth. While specific earnings can differ, they usually provide a fixed interest rate, making them a reliable choice for financial planning.
It’s concerning to know that nearly half of adults under 65 feel unsure about having enough resources for their later years – you’re not alone in this worry. By evaluating these earning potentials, households can gain clearer insight into how much pensioners can earn and how each option might assist their financial requirements in retirement. Moreover, case studies show that retirees with traditional benefit systems often achieve improved financial results, as these systems offer assured payouts that help cover necessary expenses. Understanding these options can empower you to make informed decisions that secure your family’s future, ensuring peace of mind as you navigate this journey together.
Assess Suitability: Which Pension Plans Fit Your Needs?
Choosing the right pension plan for your family can feel like a daunting task, but it doesn’t have to be. Here are some important factors to consider:
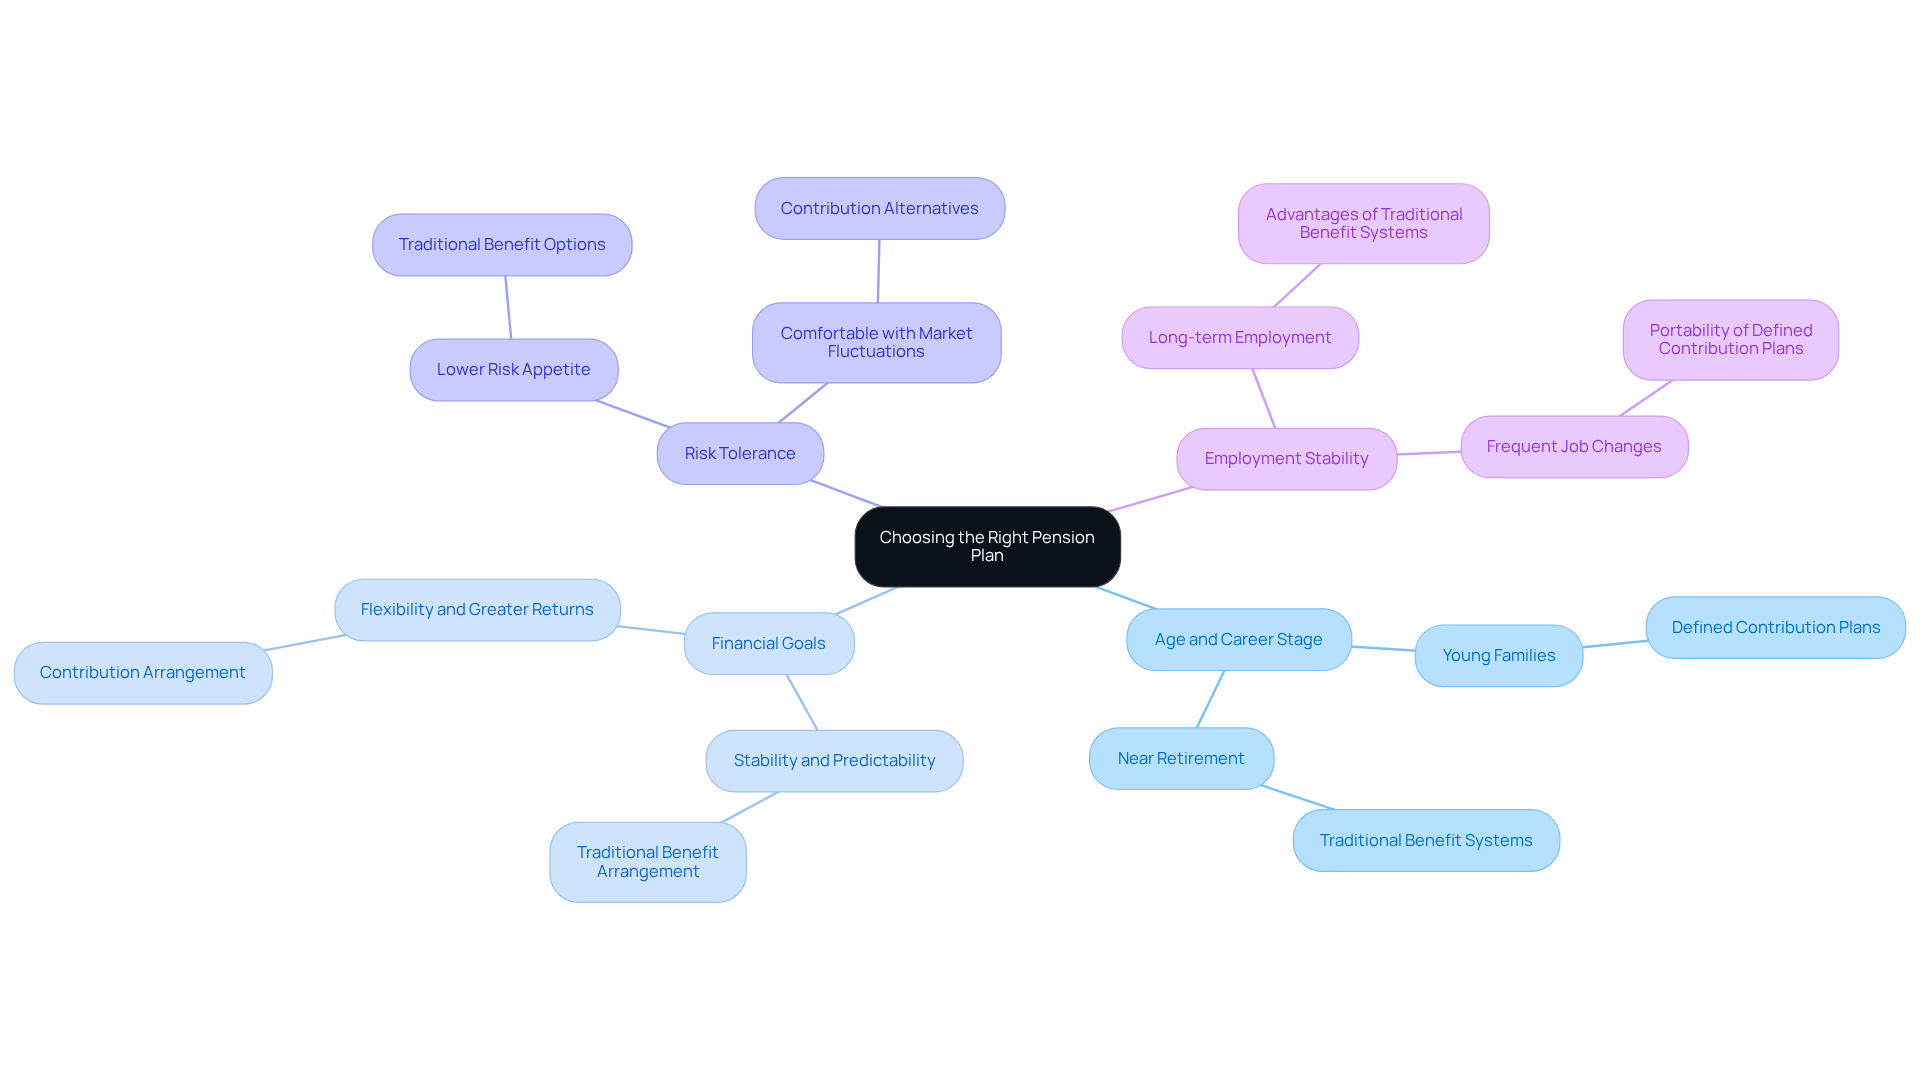
- Age and Career Stage: Imagine you’re a young family just starting out. You might find that defined contribution plans are a great fit for your growing needs. On the other hand, if you’re nearing the end of your career, traditional benefit systems could provide the assured income you desire.
- Financial Goals: If your family cherishes stability and predictability in retirement income, you might find that a traditional benefit arrangement feels like the right choice. However, if you appreciate flexibility and the possibility of greater returns, a contribution arrangement could be the superior option.
- Risk Tolerance: Families with a lower risk appetite may lean towards traditional benefit options, while those comfortable with market fluctuations might prefer contribution alternatives for their growth potential.
- Employment Stability: If you expect to remain with your employer for the long term, a traditional benefit system can offer considerable advantages. Conversely, if you expect to change jobs frequently, a defined contribution plan may offer more portability.
At Bright Advisers, we focus on keeping fund fees low, making wealth management more accessible for families. This approach enables you to invest in your future without the burden of high costs associated with traditional mutual funds and ETFs. By thoroughly assessing these elements and considering Bright Advisers’ clear fee structure, you can choose a pension plan that fits your financial circumstances and future goals. With the right guidance, you can confidently secure your family’s financial future and enjoy peace of mind.
Conclusion
Imagine feeling secure about your family’s financial future, knowing you’ve made the right choices for your retirement. We’ve taken a closer look at two key types of pension plans that can shape your family’s future:
- Defined Benefit Plans
- Defined Contribution Plans
Each has its unique features and implications for your retirement income.
By understanding these options, you can feel empowered to choose what best fits your family’s dreams and needs. Defined Benefit Plans offer predictability, providing a stable income based on your career earnings. On the other hand, Defined Contribution Plans give you flexibility, with retirement income depending on your contributions and market performance.
It’s important to assess your personal circumstances, such as your age, financial goals, and risk tolerance, when selecting the most suitable pension plan. Choosing the right pension plan can be a game-changer for your family’s financial peace of mind in retirement.
With the right support, you can turn uncertainty into confidence, paving the way for a brighter future for your loved ones. Together, we can navigate this journey and ensure your family’s financial well-being for generations to come.
Frequently Asked Questions
What are the two main types of pension plans?
The two main types of pension plans are Defined Benefit Plans and Defined Contribution Plans.
How do Defined Benefit Plans work?
Defined Benefit Plans provide a reliable income based on your career, typically offering a consistent monthly annuity that ensures a dependable income source during retirement.
What is the current trend regarding Defined Benefit Plans?
Many families are moving towards Defined Contribution Plans, with only 11.1 million still participating in Defined Benefit Plans, indicating a shift in how people save for retirement.
How do Defined Contribution Plans differ from Defined Benefit Plans?
Defined Contribution Plans, such as 401(k)s, do not guarantee a specific retirement income. Instead, the income depends on contributions made and the performance of investments, requiring more active management.
What is the current participation rate in Defined Contribution Plans?
In 2023, there were 93.4 million participants in Defined Contribution Plans, highlighting their growing popularity.
Why is it important for families to understand pension options?
Understanding pension options is crucial for families to find the right fit for their financial goals and to make informed choices about their retirement savings strategies.
How can families benefit from working with a financial advisor regarding pension planning?
A knowledgeable advisor can provide clarity and guidance, helping families evaluate the stability of traditional benefit schemes against the flexibility of contribution schemes.
What services does Bright Advisers offer to families?
Bright Advisers offers integrated tax planning strategies and investment approaches designed to optimize retirement savings, helping families create personalized financial plans.
What important disclaimers should be noted regarding advisory services?
All advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
List of Sources
- Understand Pension Plans: Definitions and Types
- A Visual Depiction of the Shift from Defined Benefit (DB) to Defined Contribution (DC) Pension Plans in the Private Sector (https://congress.gov/crs-product/IF12007)
- U.S. Bureau of Labor Statistics (https://bls.gov/ebs/factsheets/defined-benefit-frozen-plans.htm)
- Understanding Defined Benefit and Defined Contribution Plans (https://wolterskluwer.com/en/expert-insights/understanding-defined-benefit-and-defined-contribution-plans)
- How are pensions and 401(k)s different? | Pension Benefit Guaranty Corporation (https://pbgc.gov/about/advocate/resources/pensions)
- Types of Retirement Plans (https://dol.gov/general/topic/retirement/typesofplans)
- Explore Different Types of Pension Plans and Their Features
- State of Pensions 2026 (https://equable.org/report/state-of-pensions-2026)
- New Stats on Employer Retirement Plans – Spotlight on Benefits (https://spotlightonbenefits.com/2022/new-stats-on-employer-retirement-plans)
- National Data | Public Plans Data (https://publicplansdata.org/quick-facts/national)
- Compare Earnings Potential: Financial Benefits of Each Pension Plan
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- Average Retirement Income 2026: How Do You Compare? (https://retirable.com/advice/lifestyle/average-retirement-income-how-do-you-compare)
- The Top 10 Advantages of Maintaining Defined Benefit Pension Plans – National Conference on Public Employee Retirement Systems (https://ncpers.org/top-10-advantages-of-defined-benefit-pension-plans)
- Mastering Defined Contribution Plans: Path to a Secure Retirement (https://dietrichannuity.com/understanding-defined-contribution-income-a-guide-to-retirement-planning)
- Assess Suitability: Which Pension Plans Fit Your Needs?
- Average retirement savings by age (https://empower.com/the-currency/money/average-retirement-savings-by-age)
- 56 Important Retirement Plan Statistics For 2026 – Carry (https://carry.com/learn/retirement-plan-statistics)
- 50+ Essential Retirement Statistics for 2026: Demographics & More (https://annuity.org/retirement/retirement-statistics)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- Has Pension Participation in the Private Sector Improved? – Center for Retirement Research (https://crr.bc.edu/has-pension-participation-in-the-private-sector-improved)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading