

Overview
Understanding the fees associated with money management is crucial for your family’s financial well-being. Money managers typically charge fees that range from 0.25% to 2% of assets under management (AUM). Additionally, there are various other costs to consider, such as:
- Flat charges
- Hourly fees
- Performance-based fees
These can significantly impact your investment returns, making it essential to be aware of them.
Imagine if you could navigate these complexities with confidence. The article details these fee structures and emphasizes the importance of understanding them to make informed decisions. Factors like portfolio size, service complexity, and advisor experience can all influence your overall management costs. By grasping these elements, you can better align your financial strategy with your family’s priorities.
We’re here for you, guiding you through this journey. Together, we can ensure that your financial decisions support your family’s values and goals. Your peace of mind is our priority, and understanding these fees is a vital step towards achieving that.
Key Highlights:
- Money managers charge various fees that can significantly impact financial returns.
- Asset Under Management (AUM) fees range from 0.25% to 2% annually based on total assets managed.
- Flat charges for specific services vary from $1,000 to $55,000 depending on complexity.
- Hourly fees for consultations typically range from $120 to $300 per hour.
- Performance-based fees are common in hedge funds, ranging from 0.15% to 0.75% of AUM.
- Transaction fees arise from buying or selling investments, which can accumulate quickly.
- Custodial charges vary based on the custodian’s services and portfolio size.
- Portfolio size, service complexity, investment strategy, and advisor experience all influence management costs.
- Families should evaluate fee structures and advisor credentials to make informed decisions.
- Typical fees for financial consultants in 2025 range from 0.59% to 1.18% of assets.
Introduction
Understanding the costs associated with hiring a money manager is crucial for families striving to secure their financial futures. Imagine the weight of making the right choices for your family’s financial well-being. With a variety of fee structures ranging from asset management percentages to flat charges, the landscape can feel daunting.
This article gently delves into the intricacies of money management fees, revealing how these costs can significantly influence investment returns. It’s important to understand what hidden factors might be affecting these fees. Together, we can ensure that families are making informed decisions that align with their financial goals, paving the way for a brighter future.
Understand Money Management Fees
Understanding how much do money managers charge can feel overwhelming, especially for young families navigating their financial futures. It’s essential to know how much do money managers charge, as these costs can vary significantly based on the services you choose and how your advisor is compensated. Here’s a gentle breakdown of the common fee structures you might encounter:
- Asset Under Management (AUM) Fees: These fees are typically charged as a percentage of the total assets managed, usually ranging from 0.25% to 2% annually. This model can help you understand how your advisor is invested in your success.
- Flat Charges: If you prefer predictable expenses, flat charges might be appealing. These are set sums billed for specific services, varying from $1,000 to $55,000 depending on the complexity of your financial plan.
- Hourly Fees: For targeted consultations, advisors may charge based on the time spent, with rates typically between $120 and $300 per hour. This approach is often used for specific needs, such as retirement planning or tax strategies.
- Compensation for Performance: Some advisors charge based on the investment returns they achieve, a model often seen in hedge funds. Performance charges can vary from 0.15% to 0.75% of AUM, aligning your advisor’s interests with your financial success.
At Bright Advisers, we are dedicated to keeping fund fees minimal, making wealth management more accessible for families like yours. Additionally, some money consultants offer household reductions, helping to lower your total expenses. Understanding how much do money managers charge is crucial as you plan your budget and evaluate the value of the guidance you receive. By being aware of the costs associated with different financial services, you can make informed decisions that align with your family’s financial goals. Remember, we’re here for you every step of the way, ready to support you in navigating this journey together.

Explore Types of Money Manager Fees
For families looking to secure their financial future, it is crucial to understand how much do money managers charge in fees associated with money management. When considering family investment portfolios, it’s important to understand how much do money managers charge, as they typically charge several common types of fees that can significantly impact returns.
Imagine if you had a trusted partner managing your investments. Management Fees are one of the ongoing costs you might encounter. These fees are charged for managing your investments and are usually expressed as a percentage of assets under management (AUM). For example, a manager charging 1% on a $1 million portfolio would incur an annual fee of $10,000. In 2025, how much do money managers charge typically varies from 0.5% to 2% of AUM, depending on the services provided and the complexity of your portfolio.
It’s important to consider Transaction Fees as well. These costs arise when you buy or sell investments and can accumulate quickly, especially if frequent trading is involved. In 2025, transaction costs can differ significantly. Some advisors may apply a fixed charge per trade, while others might charge a percentage of the transaction value. Families should be mindful that high transaction volumes can erode investment returns over time.
Another consideration is Custodial Charges. These are imposed by the organization that maintains your investments and may be separate from administrative costs. The charges can vary based on the services offered by the custodian and the size of your portfolio.
Additionally, Advisory Charges can be structured as fixed amounts or hourly rates for planning services, separate from investment oversight costs. In 2025, hourly charges for financial guidance typically range from $130 to $300, while flat rates for comprehensive financial plans can vary from $1,000 to $3,000.
Comprehending these fee categories is essential for families assessing how much do money managers charge as part of the overall expense of money management. By evaluating the different costs imposed by various advisors, families can make informed choices that align with their financial objectives and ensure they are not overpaying for services. As Becca Stanek points out, ‘Understanding how charges are organized—and what they include and exclude—can simplify the process of comparing options and figuring out what is most suitable for your circumstances.’ Together, we can navigate this journey towards financial clarity and security.

Identify Factors Affecting Money Manager Costs
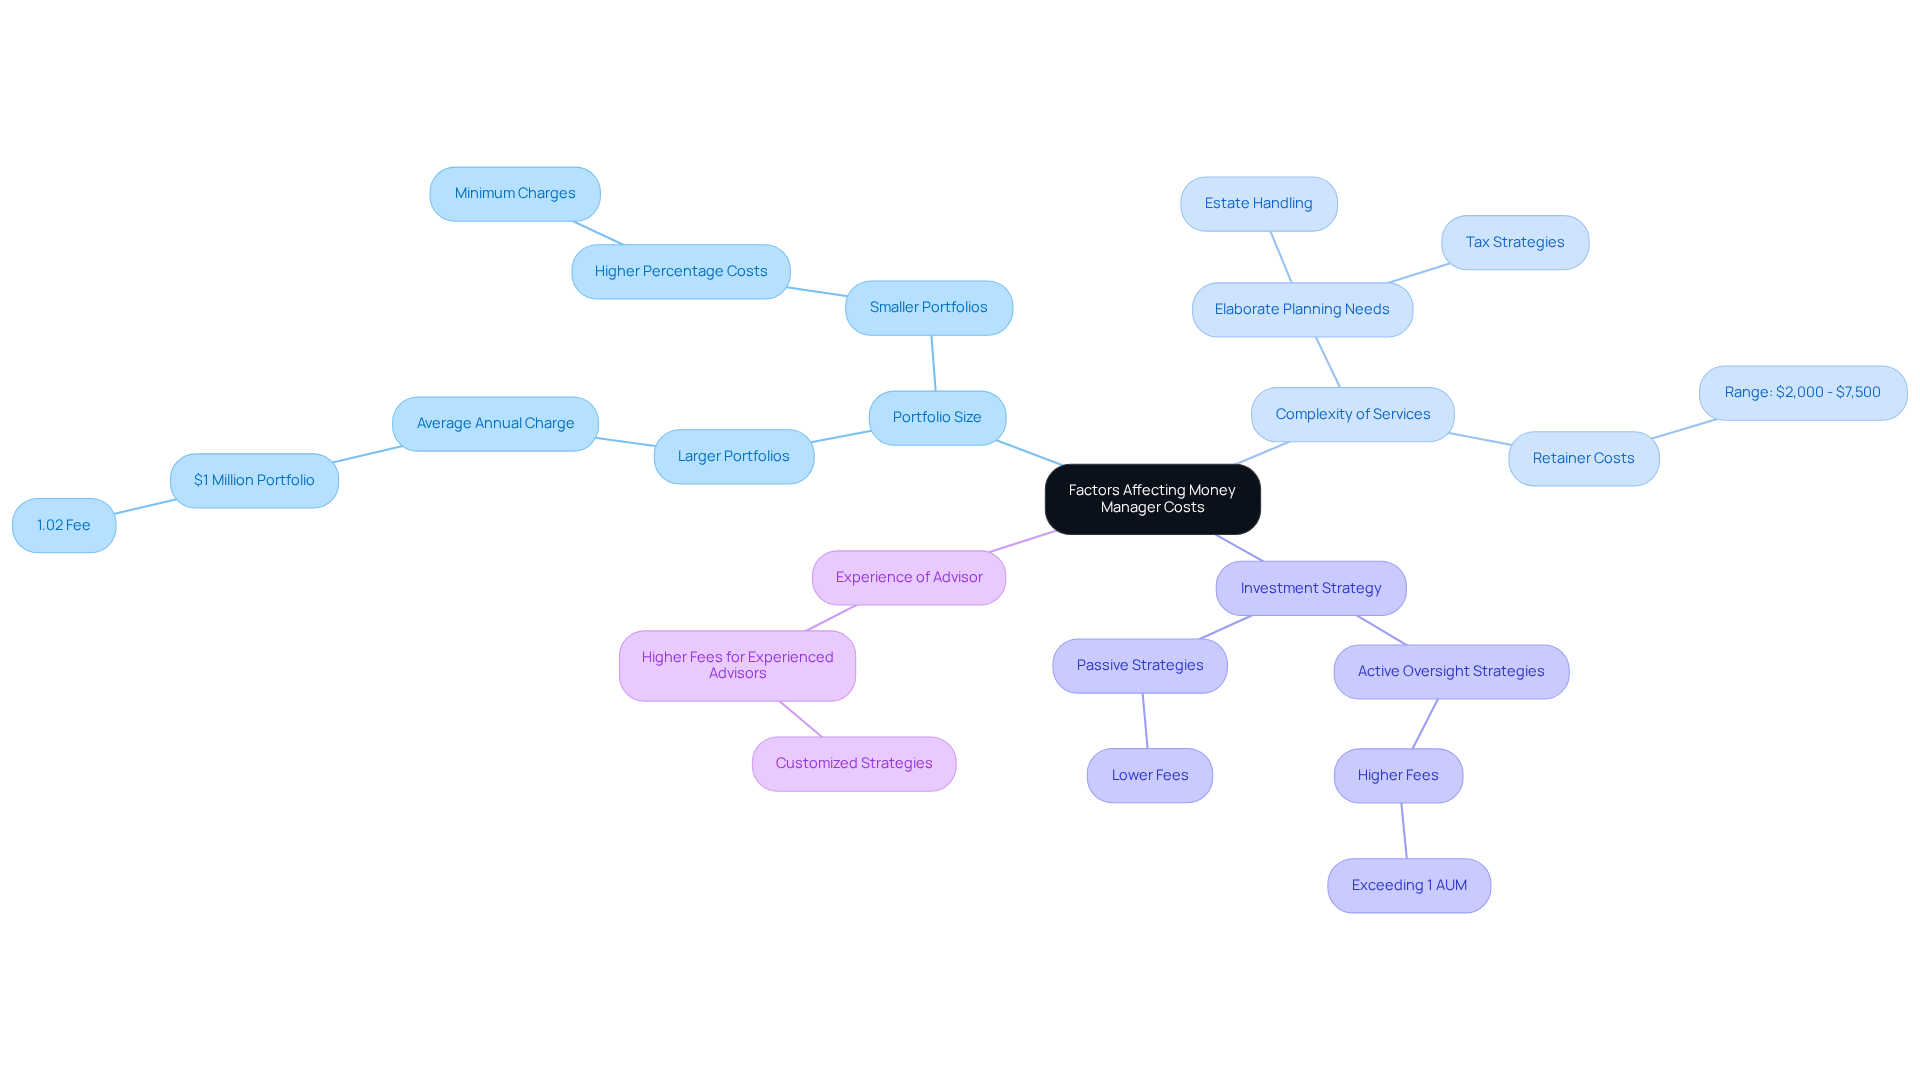
Several factors significantly influence the costs associated with hiring a money manager, and understanding these can help families make informed decisions:
- Portfolio Size: Imagine if your investments could work harder for you. Larger portfolios typically benefit from lower percentage fees due to economies of scale. For instance, a client holding a $1 million portfolio might incur an average annual charge of approximately 1.02%. In contrast, those with smaller portfolios may encounter higher percentage costs, as traditional advisors frequently impose a minimum charge that can disproportionately impact smaller accounts. At Bright Advisers, we are dedicated to minimal fund charges, ensuring that families can access wealth services without excessive costs.
- Complexity of Services: It’s important to understand that financial circumstances requiring elaborate planning, such as estate handling or tax strategies, may demand more intensive supervision, leading to increased costs. For example, retainer costs for conventional advisors can vary from $2,000 to $7,500 each year, based on the intricacy of the services needed. Bright Advisers provides customized wealth strategies that empower families through personalized planning and tax optimization, assisting in navigating these complexities effectively.
- Investment Strategy: Consider how your investment approach can impact your financial future. Active oversight strategies typically involve higher fees compared to passive strategies. This is due to the increased level of oversight and frequent trading involved in active management, which can lead to costs that may exceed 1% of assets under management (AUM). At Bright Advisers, we focus on offering affordable investment strategies that align with your monetary objectives.
- Experience and Credentials of the Advisor: When seeking guidance, remember that advisors with extensive experience and proven track records often command higher fees. Their expertise can validate the expenses, particularly when they offer customized strategies that align with your family’s monetary objectives.
Comprehending these factors enables families to assess the worth of the services they obtain and make informed choices regarding their resource management. As we look ahead to 2025, the typical charges for financial consultants vary from 0.59% to 1.18% of assets, emphasizing the significance of evaluating portfolio size and service complexity when choosing a money manager. Together, we can navigate this journey, ensuring your family’s financial future is secure.
Evaluate and Compare Money Managers
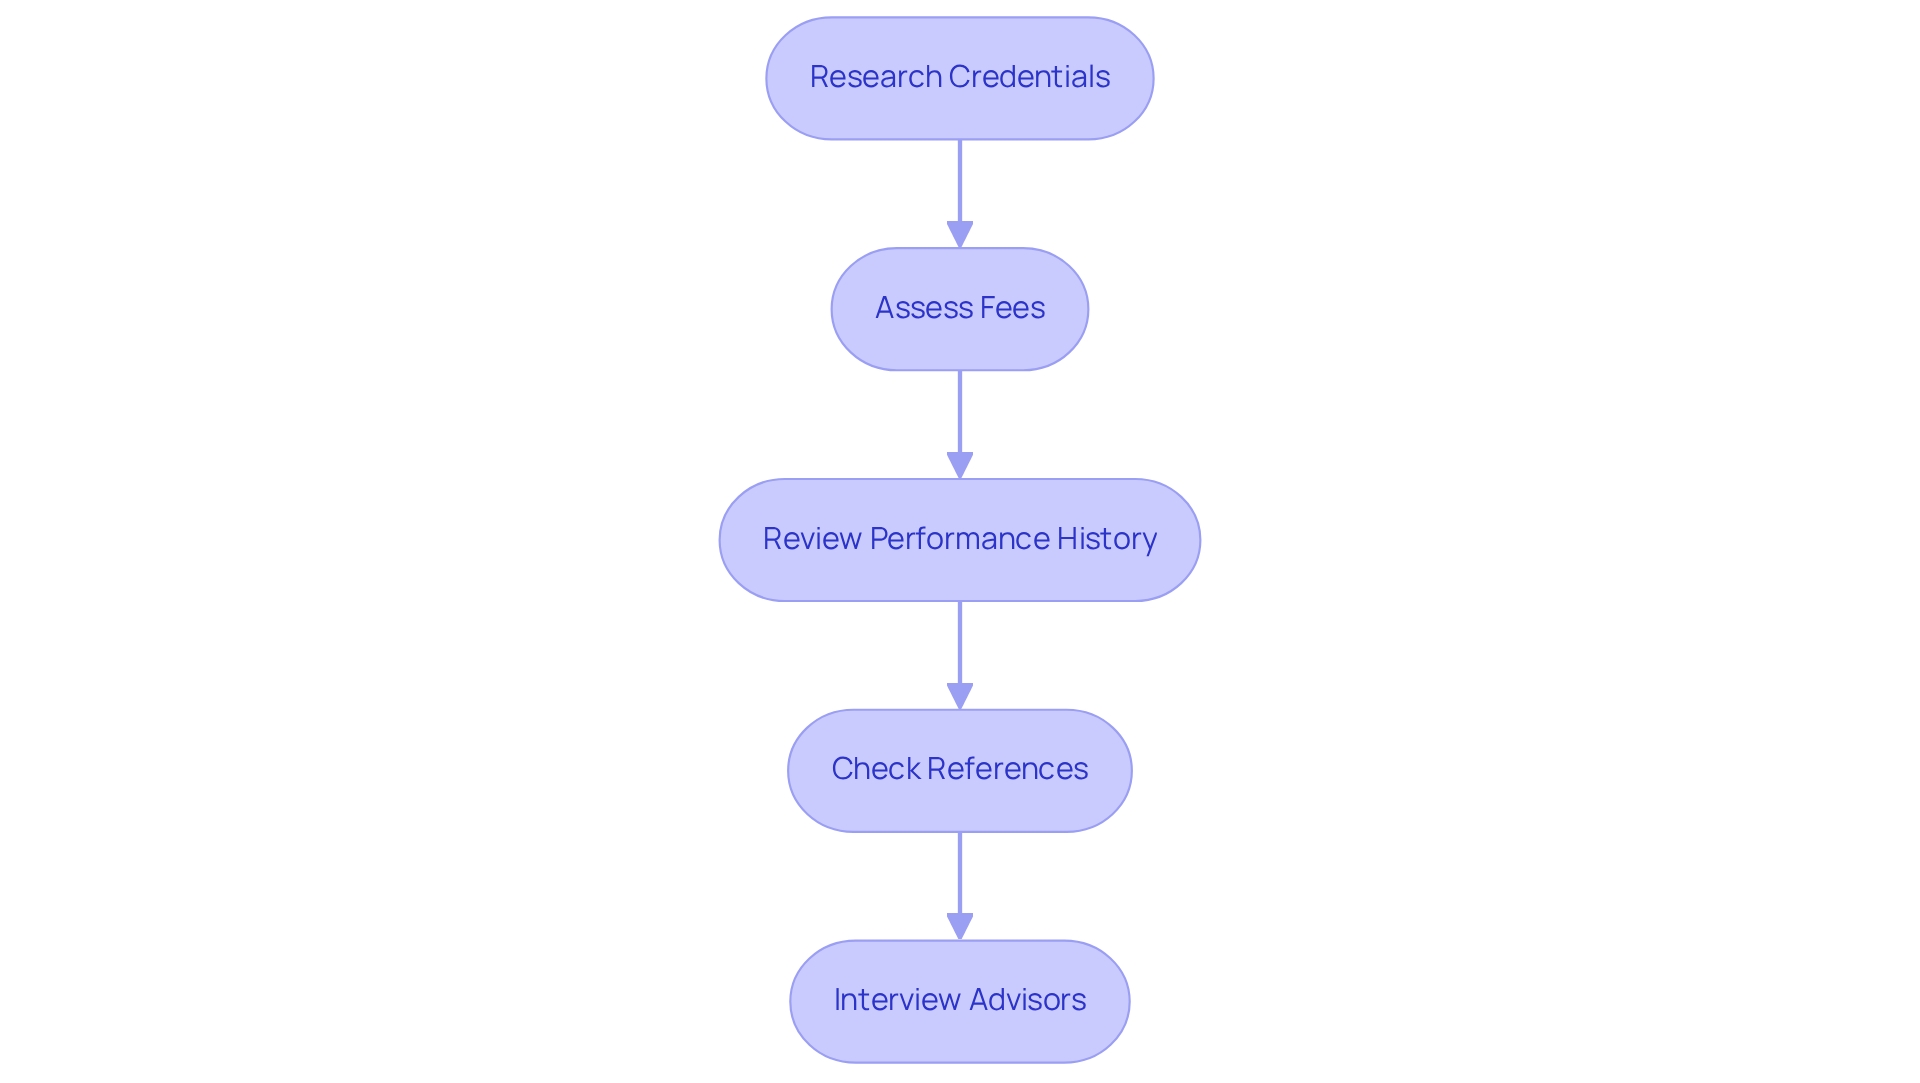
To effectively evaluate and compare money managers, consider these nurturing steps:
-
Research Credentials: Look for certifications such as Certified Financial Planner (CFP) or Chartered Financial Analyst (CFA). These credentials signify that the consultant has undergone rigorous training and adheres to strict ethical standards, ensuring they prioritize your best interests.
-
Assess the fee structures of various consultants to understand how much do money managers charge. When considering how much do money managers charge, typical fees can range from 0.25% to 2% of assets under management, with many charging around 1% for multi-million-dollar portfolios. Understanding these costs is crucial, as even small differences can significantly impact your portfolio’s growth over time.
-
Review Performance History: Imagine if you could analyze the individual’s past performance. While previous results do not ensure future performance, look for consistency and alignment with your monetary objectives.
-
Check References and Reviews: Seek testimonials from current or former clients to gauge the advisor’s reliability and service quality. A strong reputation can indicate a commitment to client satisfaction.
-
Interview Potential Advisors: Arrange meetings to discuss your monetary objectives and inquire about their investment philosophy and approach to client service. This interaction can provide insight into their compatibility with your needs.
By following these steps, families can make informed decisions when selecting a money manager that best fits their needs, ensuring a strong financial foundation for the future. Together, we can navigate this journey, knowing that support and assistance are always available.
Conclusion
Understanding the fees associated with hiring a money manager is essential for families aiming to secure their financial futures. Imagine if you could demystify the various fee structures—asset under management fees, flat charges, and hourly rates. Gaining clarity on how these costs impact your overall investment strategy empowers you to make informed decisions that align with your financial goals, ensuring you are not overpaying for services.
Throughout this guide, we’ve shared key insights regarding the different types of fees, factors influencing costs, and methods for evaluating potential money managers. It’s important to consider aspects such as portfolio size, service complexity, and the advisor’s experience when assessing the value of financial guidance. By understanding these elements, you can confidently navigate the landscape of money management and choose the best options for your unique needs.
Ultimately, your journey to financial security is enhanced by being well-informed about the costs associated with money management. We encourage you to take proactive steps in researching, comparing, and selecting a money manager that best fits your financial objectives. Together, we can ensure a brighter financial future and maximize your investment potential.
Frequently Asked Questions
What are the common fee structures for money managers?
The common fee structures include Asset Under Management (AUM) fees, flat charges, hourly fees, and performance-based compensation.
What are Asset Under Management (AUM) fees?
AUM fees are typically charged as a percentage of the total assets managed, usually ranging from 0.25% to 2% annually.
What are flat charges in money management?
Flat charges are set sums billed for specific services, varying from $1,000 to $55,000 depending on the complexity of your financial plan.
How do hourly fees work for financial consultations?
Advisors may charge hourly fees for targeted consultations, with rates typically between $120 and $300 per hour, often used for specific needs like retirement planning or tax strategies.
What does performance-based compensation mean?
Performance-based compensation means some advisors charge based on the investment returns they achieve, typically ranging from 0.15% to 0.75% of AUM, aligning their interests with your financial success.
How does Bright Advisers approach fund fees?
Bright Advisers is dedicated to keeping fund fees minimal to make wealth management more accessible for families.
Why is it important to understand how much money managers charge?
Understanding the costs associated with different financial services is crucial for planning your budget and evaluating the value of the guidance you receive, helping you make informed decisions aligned with your financial goals.
List of Sources
- Understand Money Management Fees
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- How Much Does a Financial Advisor Cost? (Updated for 2025) (https://harness.co/articles/average-fees-for-financial-advisors)
- How Much Does A Financial Advisor Cost? (https://magnifymoney.com/investing/financial-advisor-cost)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Explore Types of Money Manager Fees
- How Much Does a Financial Advisor Cost? (Updated for 2025) (https://harness.co/articles/average-fees-for-financial-advisors)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost (2025 Insights) (https://jccastleaccounting.com/how-much-does-a-financial-advisor-cost-2025-insights)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- Identify Factors Affecting Money Manager Costs
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost (2025 Insights) (https://jccastleaccounting.com/how-much-does-a-financial-advisor-cost-2025-insights)
- How Much Does a Financial Advisor Cost? (Updated for 2025) (https://harness.co/articles/average-fees-for-financial-advisors)
- What to Know About Financial Advisor Fees & Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- Evaluate and Compare Money Managers
- 20+ Financial Advisor Statistics You Must Know in ([currentyear]) (https://upmetrics.co/blog/financial-advisor-statistics)
- Financial Advisor Statistics: Reports 2025 (https://wifitalents.com/financial-advisor-statistics)
- How Much Does a Financial Advisor Cost? (Updated for 2025) (https://harness.co/articles/average-fees-for-financial-advisors)
- Is My 1% Fee Too High for a $2 Million Portfolio Managed by an Advisor? (https://finance.yahoo.com/news/2-million-invested-financial-advisor-120000821.html)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading