

Overview
Understanding the costs associated with mutual funds is crucial for parents looking to optimize their investment returns. Typically, a mutual fund averages around 0.75% in expense ratios. However, this can vary significantly based on management style and additional fees. Imagine if even small differences in fees could greatly impact your family’s long-term wealth accumulation. It’s important to understand these costs, as selecting lower-cost funds can enhance financial growth for your family.
By being mindful of these fees, you can make informed decisions that resonate with your family’s values. Investing wisely today can lead to a brighter financial future for your children. We’re here for you in this journey, offering support and guidance as you navigate the world of financial planning. Together, we can ensure that your family’s financial goals are met with care and understanding.
Key Highlights:
- Understanding mutual fund costs is crucial for optimising investment returns.
- The average expense ratio for mutual funds is approximately 0.75% as of 2025, but this can vary significantly.
- High fees can substantially impact long-term wealth growth; lower costs are preferable.
- Key components of mutual fund costs include cost ratios (0.25% to 1.5%), management fees (0.60% for active, 0.11% for passive), 12b-1 fees (0.25% to 1%), and sales loads.
- Calculating total costs involves identifying the expense ratio, investment amount, and any additional fees.
- Even small differences in fees can lead to significant variations in returns over time.
- Using tools like the FINRA Fund Analyzer can help visualise the long-term impact of fees on investments.
- Investors are increasingly favouring lower-cost funds, with a nearly $1.2 trillion gap in flows between low-cost and high-cost funds.
Introduction
Understanding the costs associated with mutual funds is a vital step for families eager to optimize their investment returns. Imagine navigating the complexities of management, administrative, and marketing expenses that can impact your long-term wealth growth. As parents, it’s essential to ensure that you’re not sacrificing your financial future due to overlooked fees. This guide delves into the intricacies of mutual fund expenses, providing you with the tools needed to make strategic investment decisions that align with your family’s financial goals. Together, we can navigate this journey toward a brighter financial future.
Understand Mutual Fund Costs
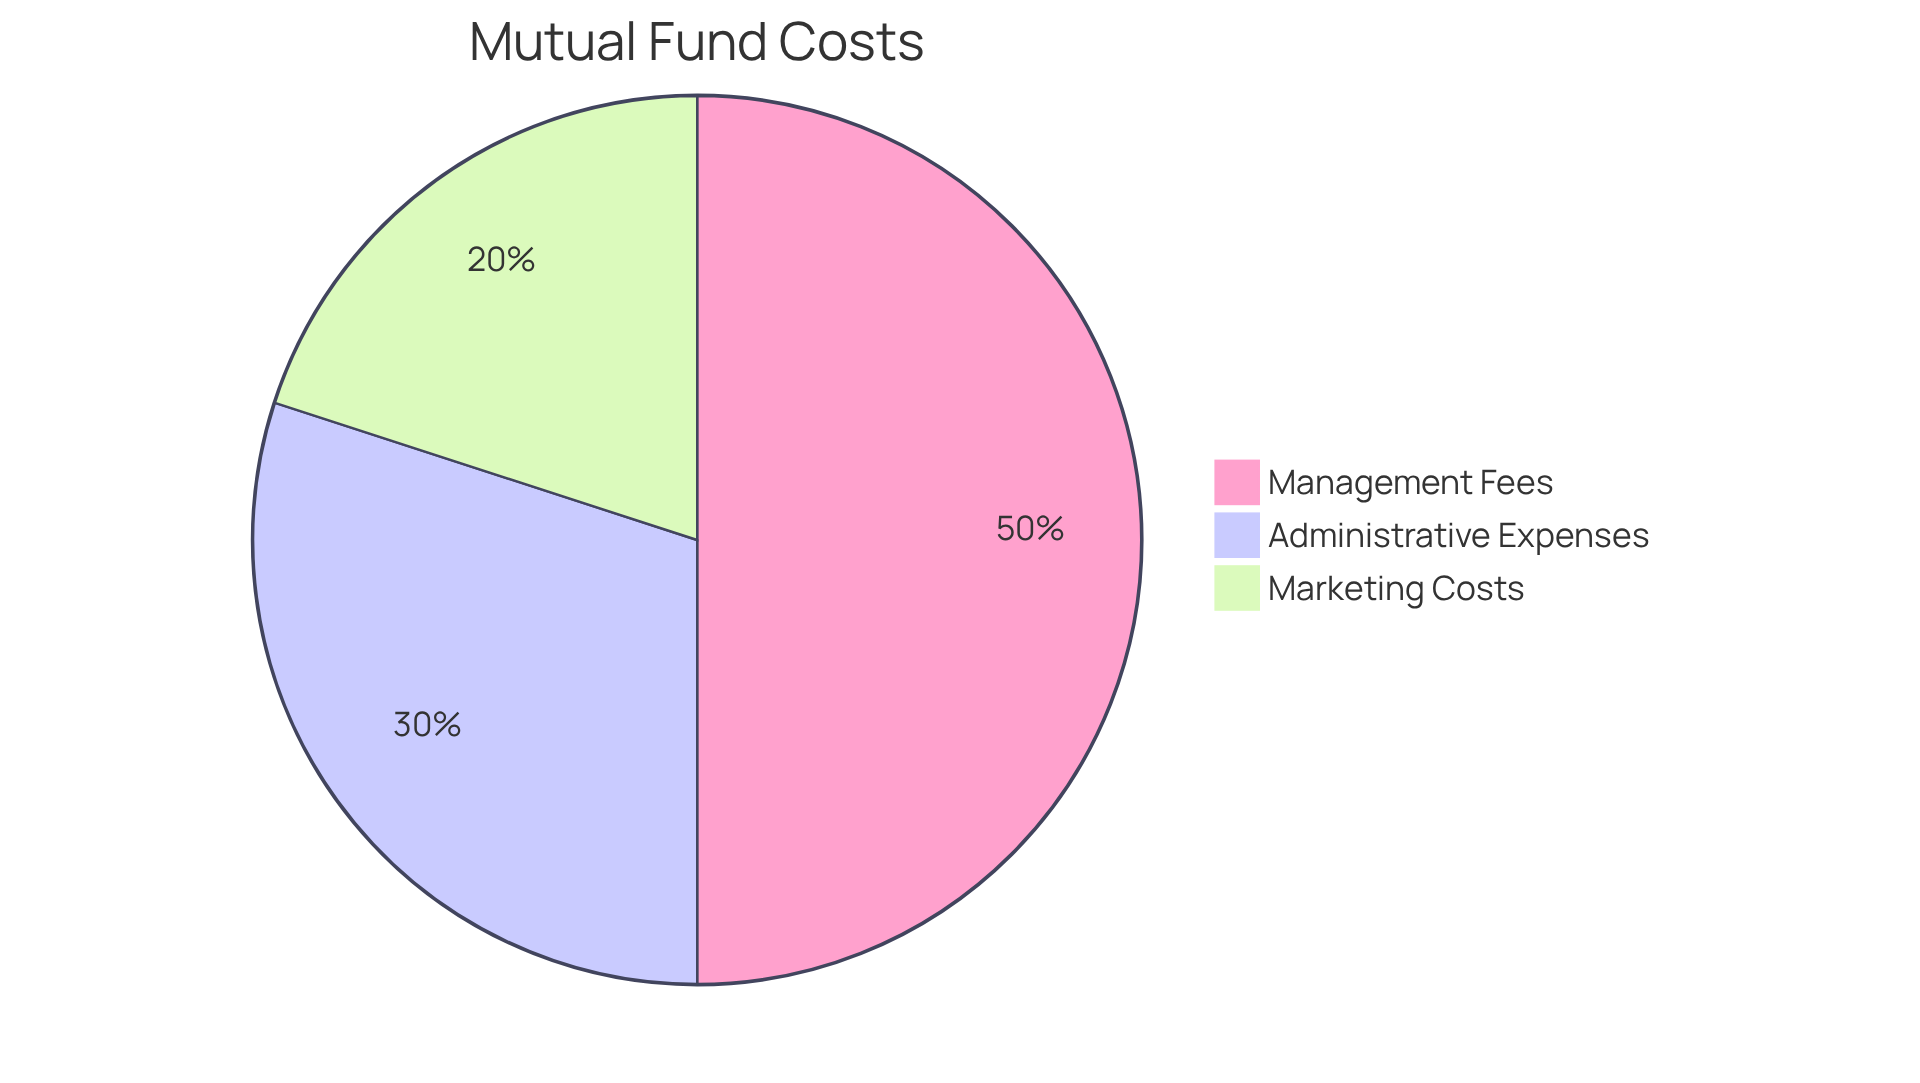
Understanding how much does a mutual fund cost is essential for optimizing your returns. These resources typically incur various charges to cover operational costs, leading to inquiries about how much does a mutual fund cost, including management, administrative, and marketing expenses. These costs are expressed as a portion of the portfolio’s assets, known as the cost percentage. As of 2025, when considering how much does a mutual fund cost, the average expense ratio for mutual investment vehicles is approximately 0.75%, though this can vary significantly based on the type and management style.
At Bright Advisers, we are committed to keeping investment fees low, which applies to the vast majority of our models. This dedication enhances wealth management accessibility for families, ensuring that high fees do not diminish your investment returns over time. For families, understanding how much does a mutual fund cost is crucial. Elevated charges can greatly impact long-term wealth growth, making it vital to consider how much does a mutual fund cost when choosing investments with lower costs that align with your financial goals. Imagine a family investing $10,000 in a mutual fund and considering how much does a mutual fund cost, as they might lose around $100 each year to fees with a 1% expense ratio compared to only $75 with a 0.75% ratio. Over the years, this difference can accumulate significantly, especially when considering how much does a mutual fund cost.
Real-world examples show how families can benefit from understanding mutual investment fees. Picture a household that carefully researches and selects investments with lower fees. By doing this, they not only improve their investment returns but also foster financial literacy in their children, preparing them for future financial responsibilities. As financial consultants often emphasize, being aware of how much does a mutual fund cost is a vital step in making wise investment choices that support your family’s financial future. We’re here for you, ready to help you navigate this journey together.
Identify Key Cost Components
When considering mutual fund costs, it’s important to focus on a few key components that can impact your family’s financial future:
-
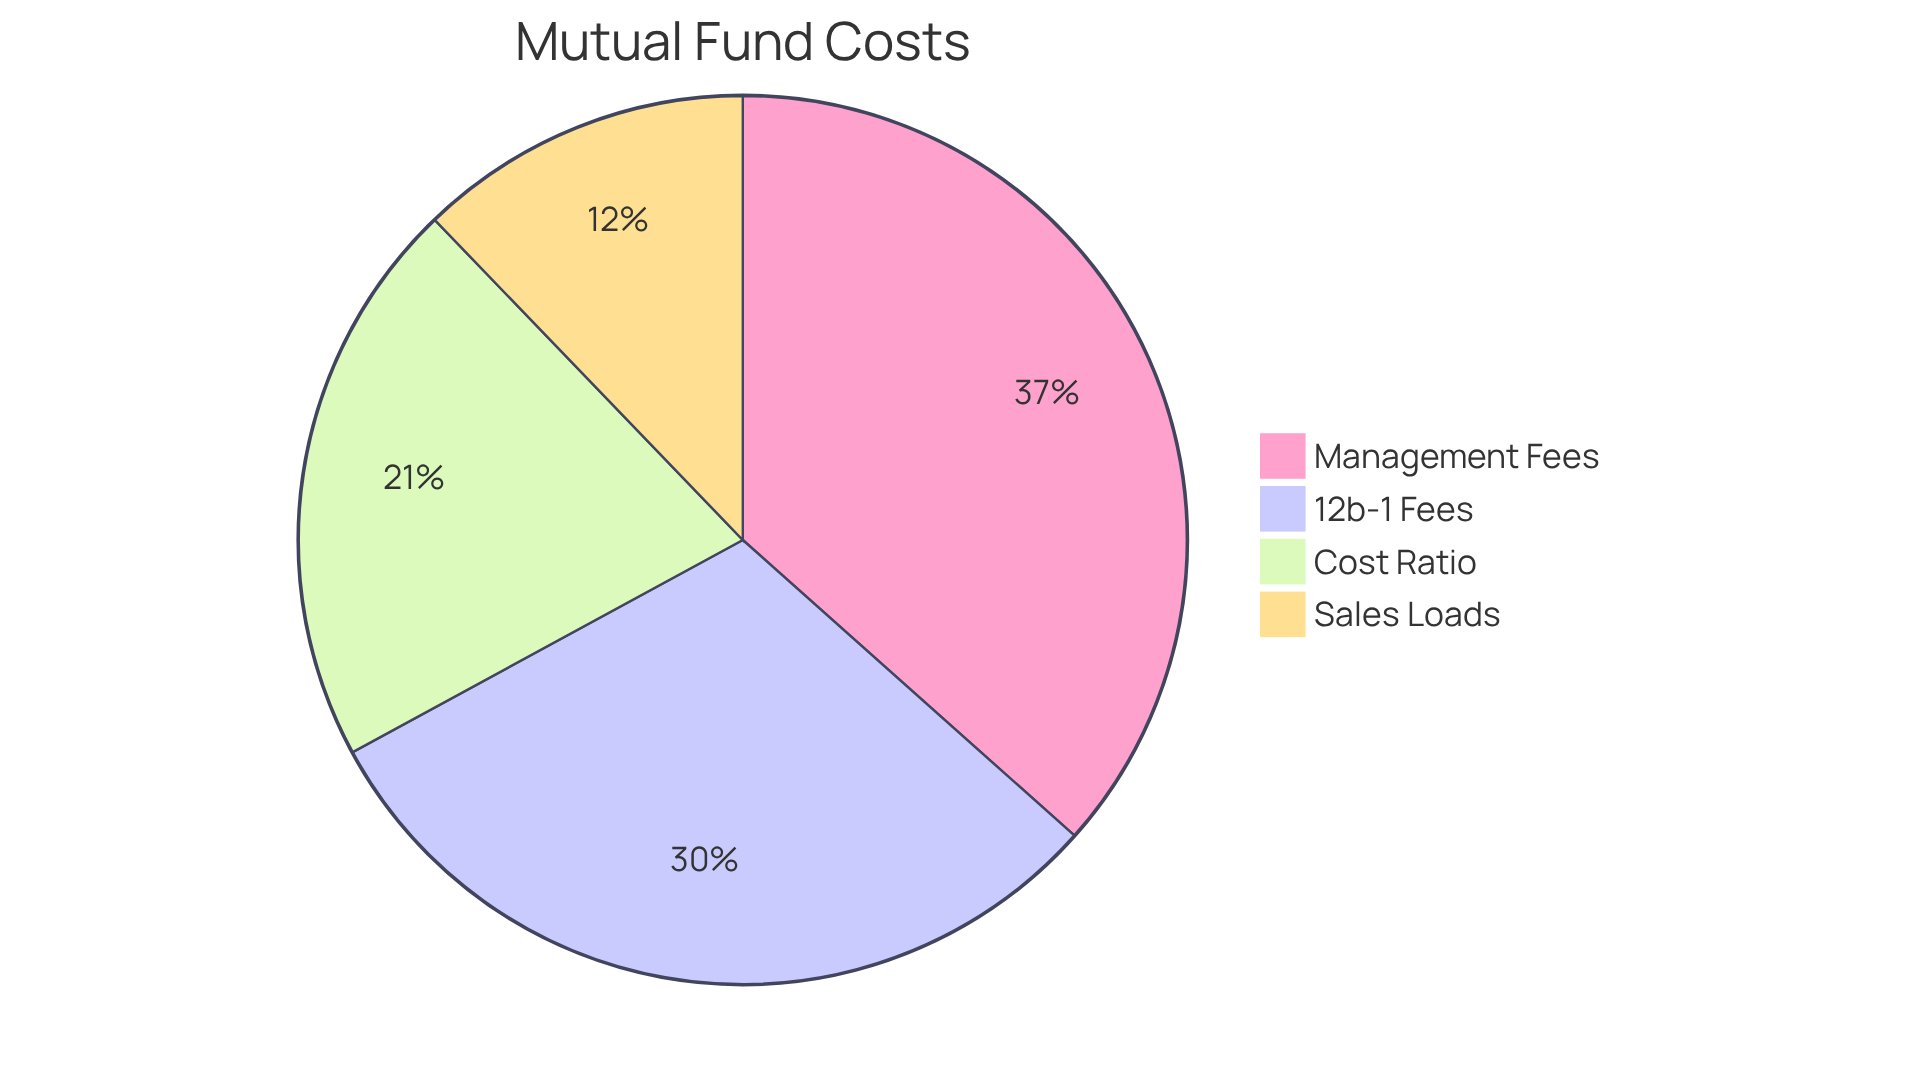
Cost Ratio: This figure reflects the total yearly operating costs of the portfolio divided by its average net assets, typically ranging from 0.25% to 1.5%. In 2024, the asset-weighted average cost percentage for all U.S. mutual vehicles and ETFs decreased to 0.34%, signaling a positive trend toward lower fees for investors like you.
-
Management Fees: These fees compensate the manager for their expertise in investments. In 2024, the average management fee for active U.S. equity investments was 0.60%, while passive options offered a more affordable average of just 0.11%.
-
12b-1 Fees: These are marketing and distribution fees that can be charged annually, often included in the expense ratio. They typically range from 0.25% to 1%, affecting the overall cost of your investment.
-
Sales Loads: Certain investment vehicles may impose fees when you buy (front-end load) or sell (back-end load) shares. Understanding these charges is crucial, as they can significantly impact your investment returns over time.
By carefully evaluating these elements, families can gain a clearer understanding of how much does a mutual fund cost in relation to the actual costs associated with investing. This knowledge empowers you to make informed choices that align with your financial goals. Remember, we’re here for you, and together, we can navigate this journey towards a secure financial future.
Calculate Total Costs Step-by-Step
Calculating the total costs of your mutual fund investment can feel overwhelming, but we’re here to help you navigate this journey. Let’s break it down into manageable steps that can make a difference for your family’s future.
-
Identify the Expense Ratio: Begin by checking the prospectus of your investment or a trusted financial website to discover the expense ratio. This figure represents the annual operating expenses as a percentage of your investment, and understanding it is crucial.
-
Next, decide how much you plan to invest in the mutual portfolio. Did you know that the typical investment sum in collective investment schemes in 2025 is estimated to be around $25,000? Knowing this can help you comprehend the related expenses.
-
Calculate Yearly Costs: Now, let’s calculate your yearly costs. Multiply your investment amount by the cost percentage. For instance, if you invest $10,000 in a portfolio with a 1% management fee, your yearly charge would be $100. Remember, even a small difference in fees can lead to significant variations in returns over time, so it’s important to stay aware of these calculations.
-
Consider Additional Fees: If applicable, don’t forget to include any sales loads or 12b-1 fees in your yearly expenses. For example, a fund with a 12b-1 fee capped at 1% will incur extra costs that should be factored into your overall expenditures. This thorough approach provides a clearer picture of your investment’s total expenses.
Imagine a family planning their investment sums and expenses effectively. For instance, if a family intends to invest $25,000 in a mutual fund with a 1.5% charge, they would face yearly fees of $375. This highlights the importance of understanding these charges before making investment decisions. Financial planners emphasize that knowing your investment amount and expense ratio calculations is vital for maximizing returns and achieving long-term financial goals. As one financial planner wisely noted, “You should never invest in anything until you understand how it works.”
Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.

Evaluate Cost Impact on Returns
To evaluate how much does a mutual fund cost and how it impacts your returns, it’s essential to understand a few key concepts that can shape your family’s financial future.
-
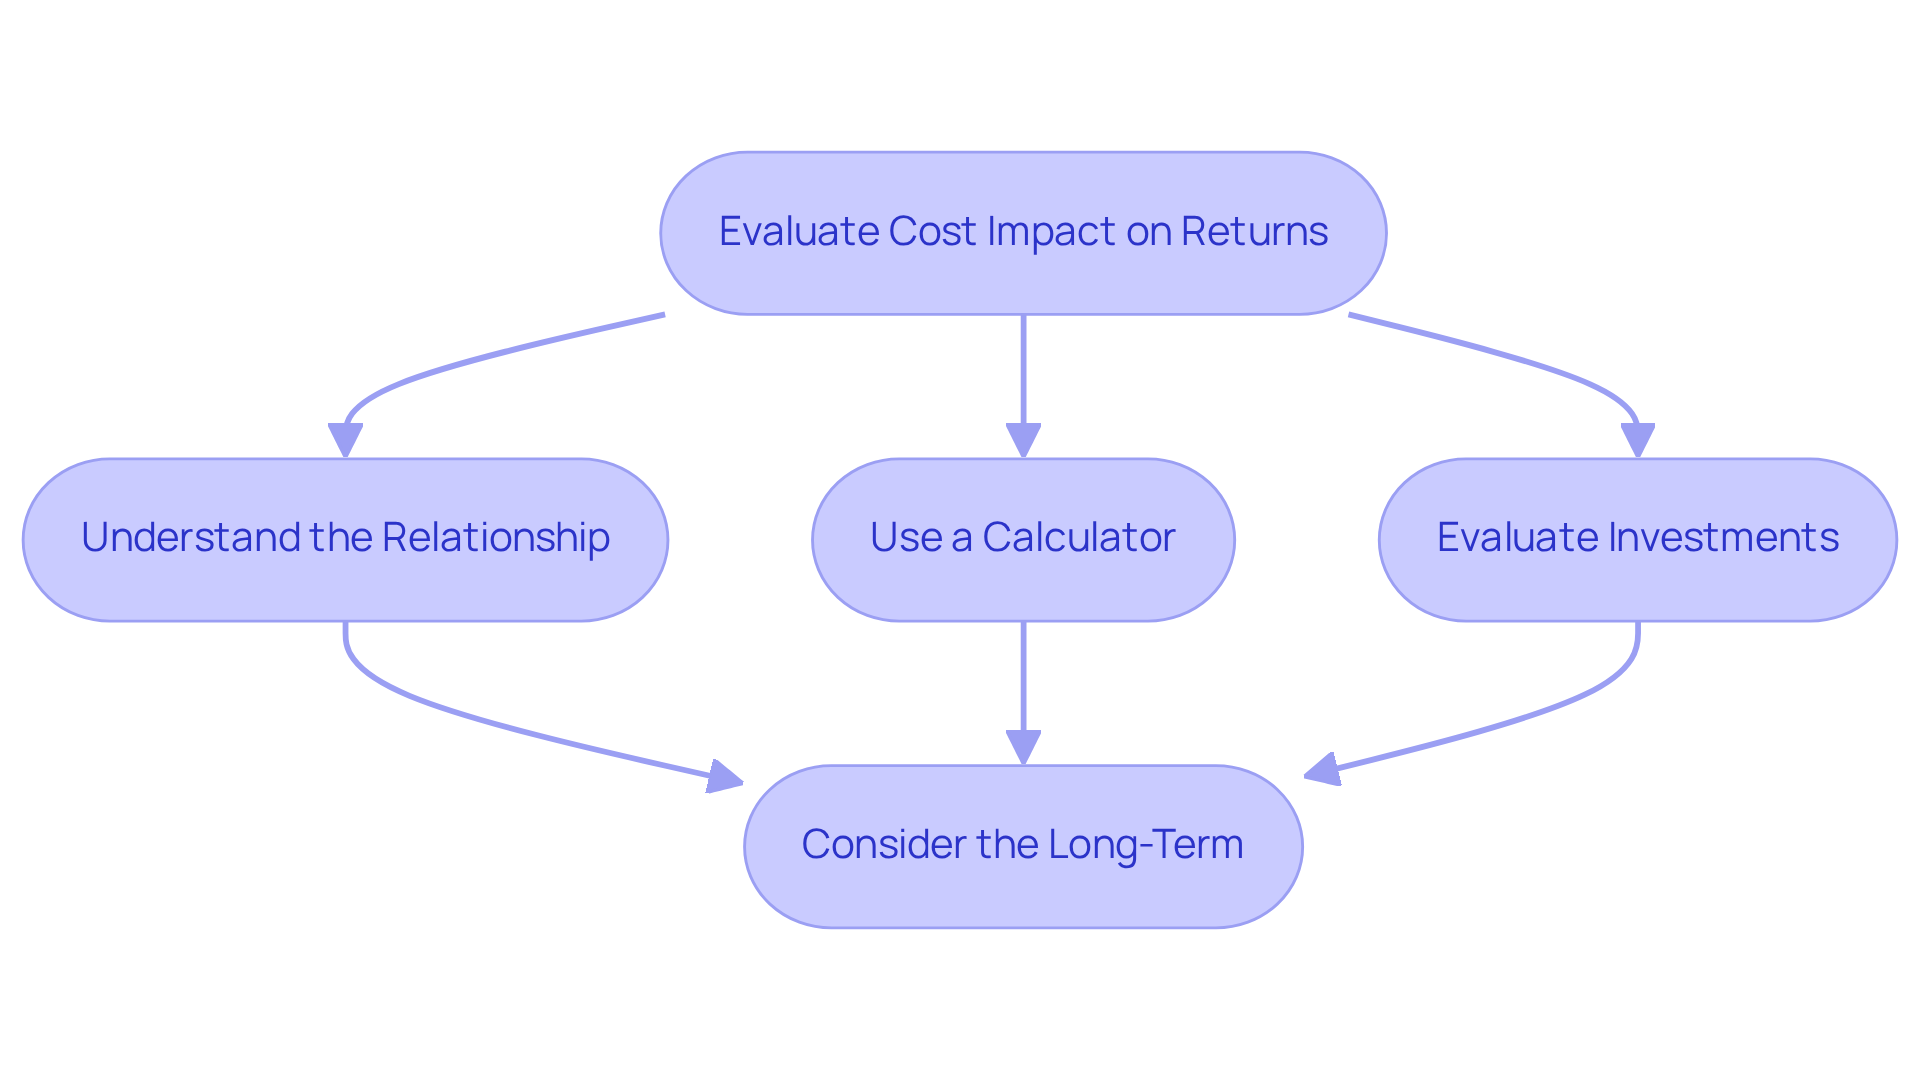
Understand the Relationship: Imagine if a fund produces a 5% return but has a 1% cost. Your actual return would be only 4%. This scenario highlights the critical importance of understanding how much does a mutual fund cost, as fees can erode your investment gains and affect the financial well-being of your loved ones.
-
Use a Calculator: It’s important to utilize online tools, like the FINRA Fund Analyzer, to see how various cost structures influence your investment over time. By entering your investment amount, anticipated return, and cost percentage, you can visualize the long-term effect of fees on your portfolio, helping you make informed decisions.
-
Evaluate Investments: When choosing investments, consider their cost percentages alongside past performance. An investment with a lower cost percentage might outperform a more expensive option over the long run, even if the latter shows better short-term returns. This trend is backed by the reality that the typical spending measure for equity mutual investment vehicles has dropped considerably, suggesting a shift towards more affordable choices that align with family values.
-
Consider the Long-Term: Remember, even small differences in fees can compound significantly over time, impacting your family’s financial future. For example, an investment with a 0.5% expense ratio can lead to substantial savings over 20 years compared to a portfolio with a 1% expense ratio. To maximize your investment growth, it’s important to consider how much does a mutual fund cost when choosing funds with competitive costs. The gap in flows between low-cost and high-cost funds has reached nearly $1.2 trillion, reflecting a strong preference for lower fees among investors. Together, we can navigate this journey towards a more secure financial future for your family.
Conclusion
Understanding the costs associated with mutual funds is crucial for families eager to optimize their investment returns. By grasping the various fees involved—like management fees, expense ratios, and sales loads—investors can make informed decisions that significantly impact their financial futures. This knowledge empowers families to choose mutual funds that align with their financial goals while minimizing unnecessary expenses.
Throughout this article, we shared key insights regarding mutual fund costs, highlighting the importance of evaluating the expense ratio and understanding how different fees affect overall returns. Imagine if selecting lower-cost options could lead to better long-term wealth growth! Real-world examples illustrated this potential, while calculations demonstrated the tangible effects of fees on investment outcomes. By being proactive in researching and understanding these costs, families can enhance their financial literacy and secure a more prosperous future.
Ultimately, the significance of being aware of mutual fund costs cannot be overstated. As families navigate their investment journeys, prioritizing low-cost mutual funds will not only maximize returns but also instill valuable financial habits in the next generation. Together, we can embrace this knowledge as a crucial step toward achieving long-term financial success, ensuring that every dollar invested works harder for your family’s future.
Frequently Asked Questions
Why is it important to understand mutual fund costs?
Understanding mutual fund costs is essential for optimizing your returns, as various charges cover operational expenses and can significantly impact long-term wealth growth.
What types of costs are associated with mutual funds?
Mutual funds typically incur management, administrative, and marketing expenses, which are expressed as a portion of the portfolio’s assets known as the cost percentage.
What is the average expense ratio for mutual funds as of 2025?
As of 2025, the average expense ratio for mutual investment vehicles is approximately 0.75%, although this can vary based on the type and management style of the fund.
How can high mutual fund costs affect a family’s investment returns?
Elevated costs can greatly impact long-term wealth growth. For example, a family investing $10,000 could lose around $100 each year to fees with a 1% expense ratio compared to $75 with a 0.75% ratio, leading to significant differences over time.
How can families benefit from selecting investments with lower fees?
By researching and selecting investments with lower fees, families can improve their investment returns and foster financial literacy in their children, preparing them for future financial responsibilities.
What role do financial consultants play in understanding mutual fund costs?
Financial consultants emphasize the importance of being aware of mutual fund costs as a vital step in making wise investment choices that support a family’s financial future.
List of Sources
- Understand Mutual Fund Costs
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Quotes by Author: Warren Buffett (https://ifa.com/quotes/warren_buffett)
- Identify Key Cost Components
- How Fund Fees are Evolving in the US (https://morningstar.com/business/insights/blog/funds/us-fund-fee-study)
- Costs of U.S. mutual fund investors by type 2024| Statista (https://statista.com/statistics/331680/expenses-incurred-by-mutual-fund-investors-usa-by-fund-type)
- Pay Attention to Your Fund’s Expense Ratio (https://investopedia.com/articles/personal-finance/092613/pay-attention-your-funds-expense-ratio.asp)
- 4 Fund Fee Trends to Watch in 2025 (https://morningstar.com/funds/4-fund-fee-trends-watch-2025)
- Making sense of mutual fund fees and the value behind the costs (https://scotiafunds.com/en/home/news-insights/article.mutual-fund-fees.html)
- Calculate Total Costs Step-by-Step
- Mutual Fund Calculator: Growth and Fees – NerdWallet (https://nerdwallet.com/article/investing/mutual-fund-calculator)
- 7 Leading Private Placement Life Insurance Companies for Families – Bright Advisers (https://brightadvisers.com/7-leading-private-placement-life-insurance-companies-for-families)
- Idaho Power EV Information (https://idahopower.chooseev.com/commercial/case_studies)
- Everything You Need to Know About Investment Fees (https://ramseysolutions.com/retirement/investing-fees-how-much-too-much?srsltid=AfmBOorBCE_qfWGlCuTXl6iaRls4GyIbTXWHFTijHbuao-YGvr9AN5y-)
- The SEC Mutual Fund Cost Calculator (https://sec.gov/investor/tools/mfcc/mfcc-intsec.htm)
- Evaluate Cost Impact on Returns
- Pay Attention to Your Fund’s Expense Ratio (https://investopedia.com/articles/personal-finance/092613/pay-attention-your-funds-expense-ratio.asp)
- US Equity Fund Fees Continue to Decline Amid Rising Investor Demand for Lower-Cost Options (https://ici.org/news-release/25-news-fund-fees-decline)
- 4 Fund Fee Trends to Watch in 2025 (https://morningstar.com/funds/4-fund-fee-trends-watch-2025)
- Mutual Fund and ETF Fees and Expenses – Investor Bulletin | Investor.gov (https://investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/mutual-fund-and-etf-fees-and-expenses-investor-bulletin)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading