

Key Highlights
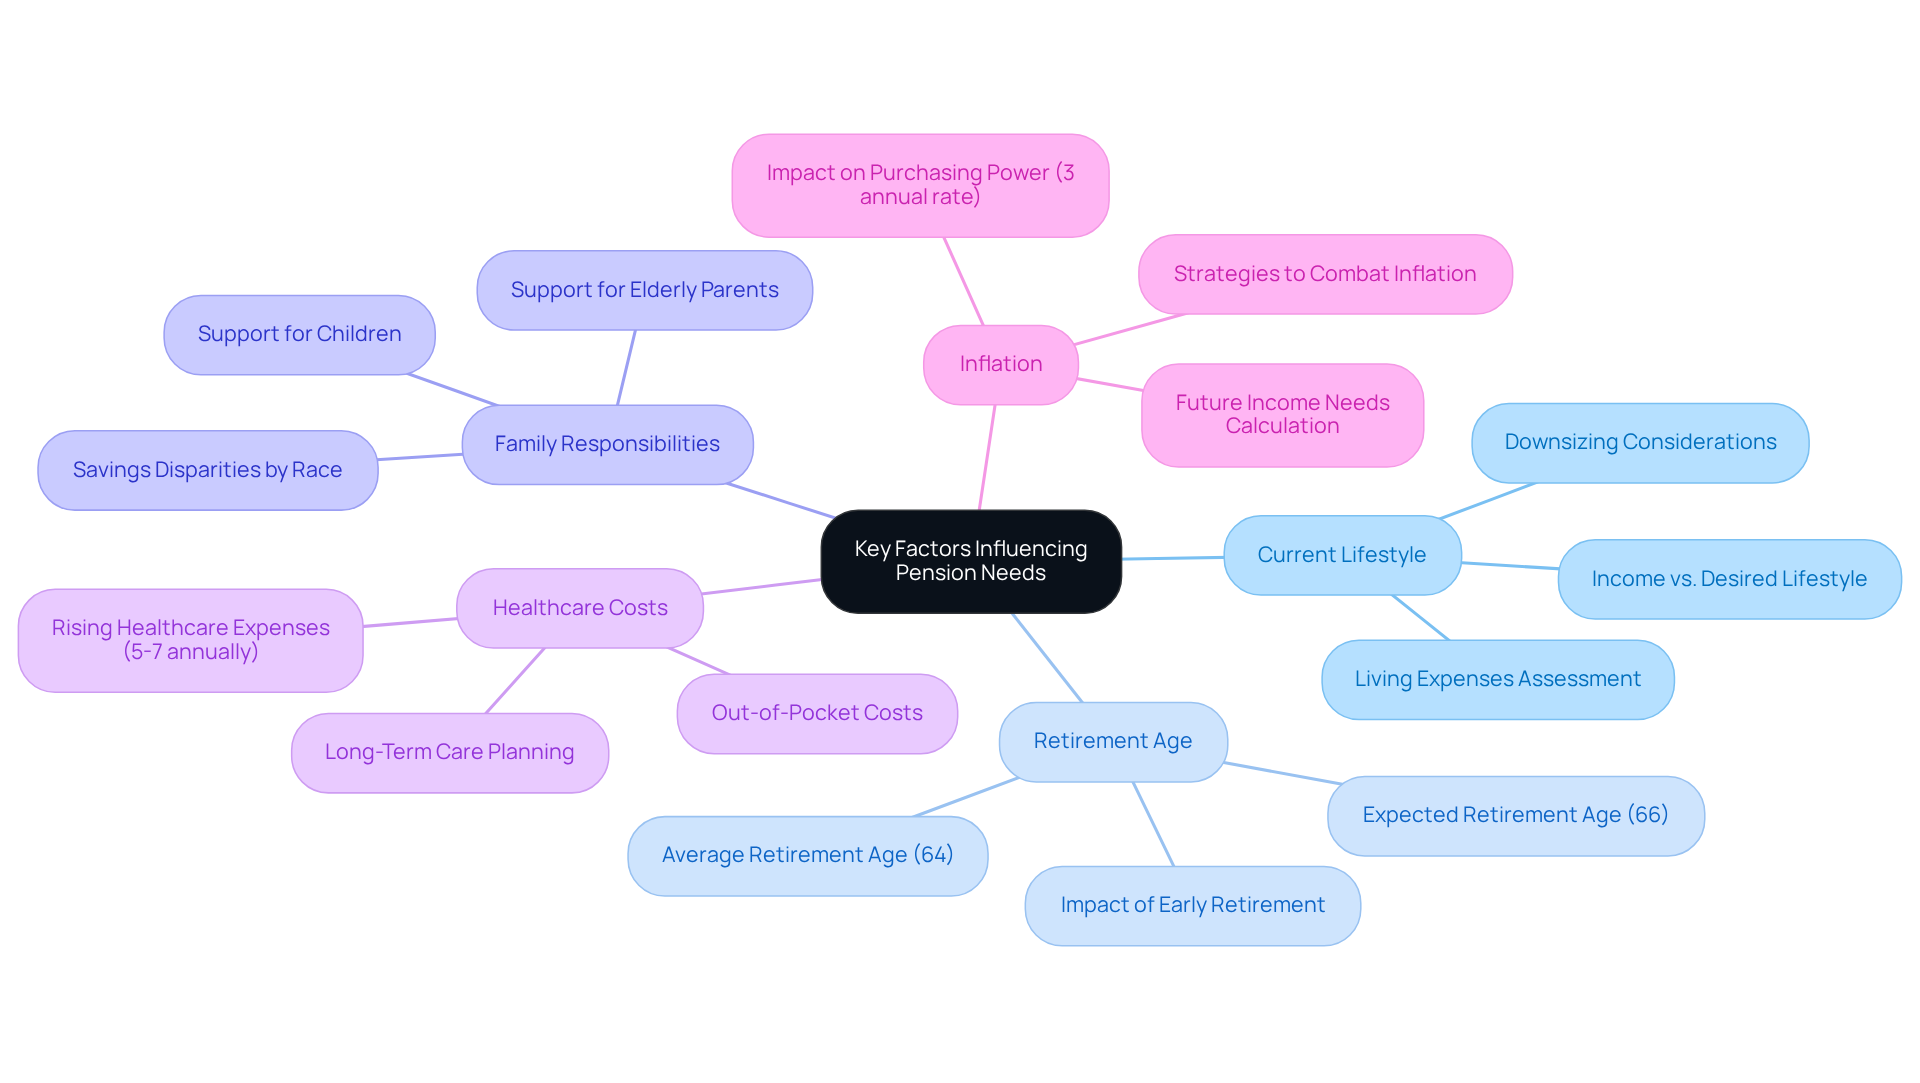
- Current lifestyle choices significantly impact retirement income needs; assess living expenses and potential changes.
- Retirement age affects how long funds must last; average retirement age in the U.S. is 64, with many planning for 66.
- Family responsibilities, such as supporting children or elderly parents, can limit savings potential.
- Healthcare costs are projected to rise by 5-7% annually, necessitating careful planning for these expenses.
- Inflation erodes purchasing power; a 3% annual inflation rate means $50,000 today will require about $67,195 in ten years.
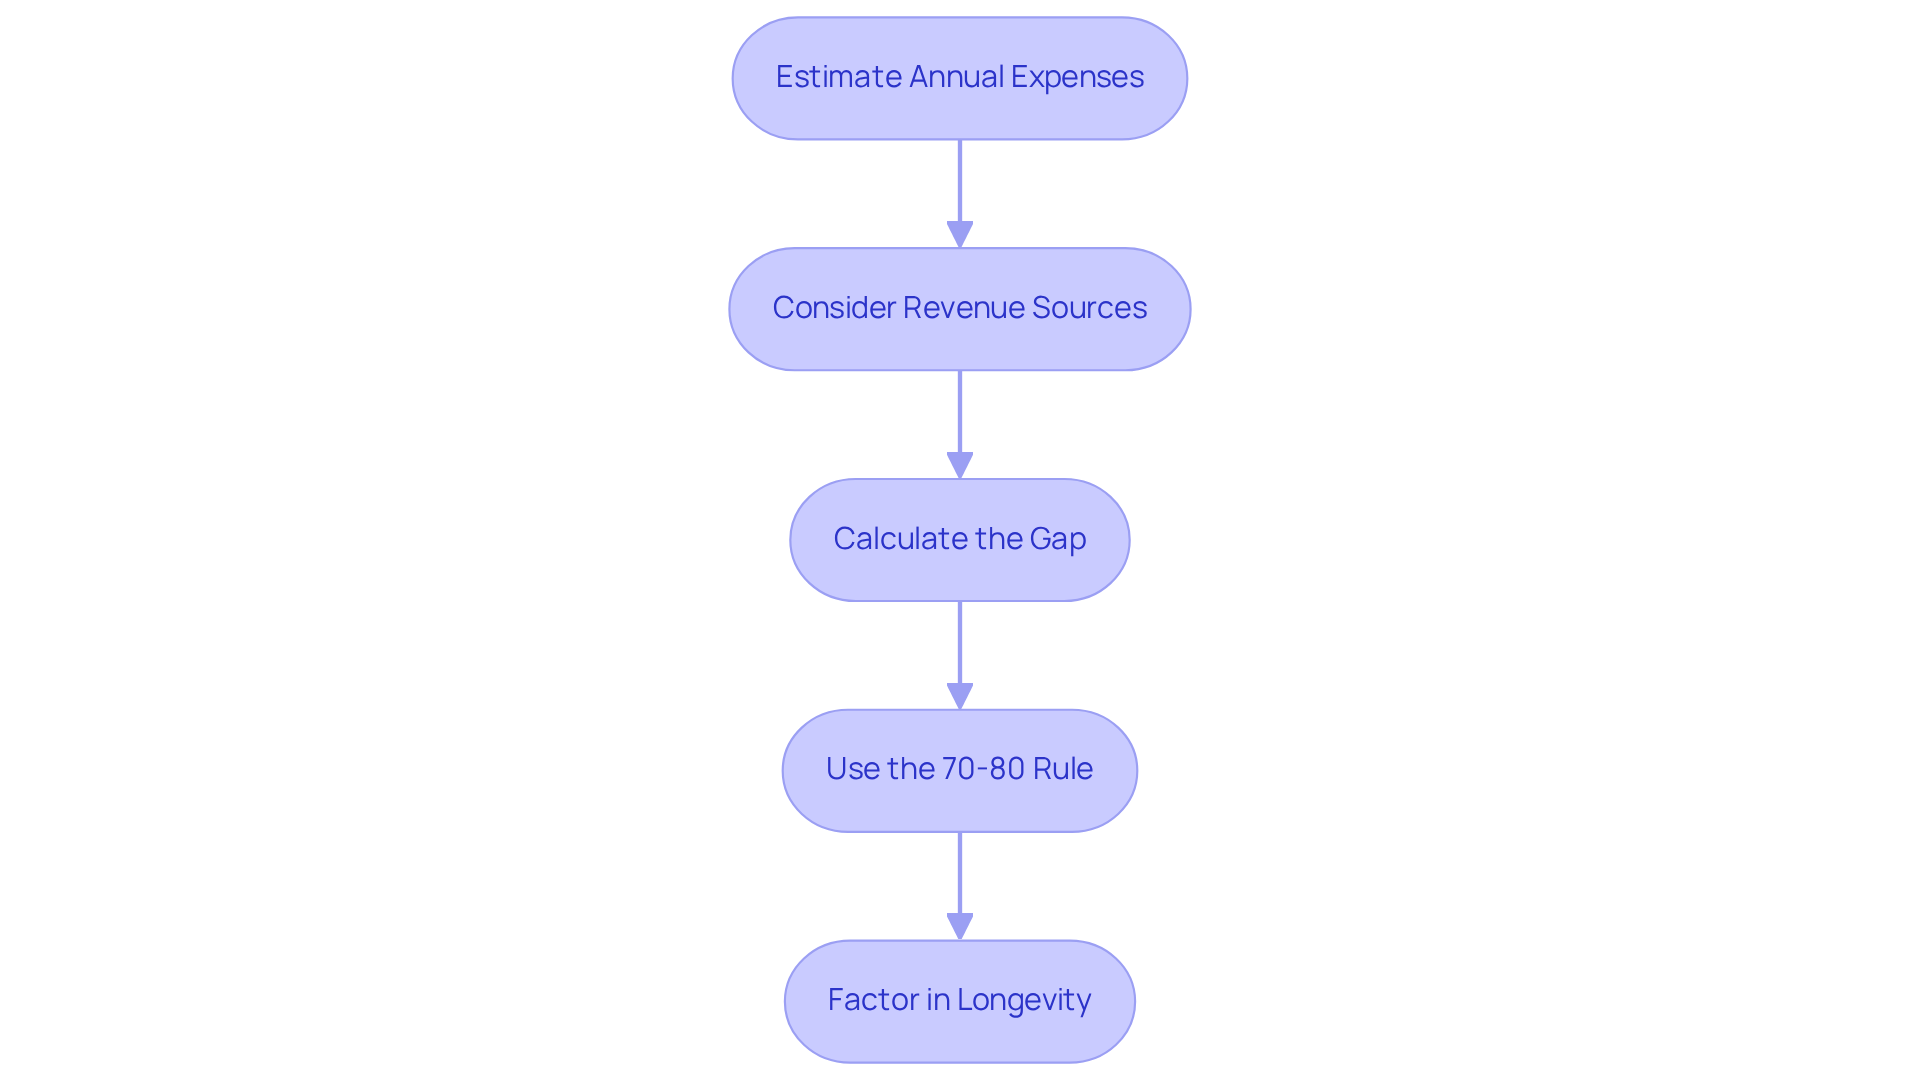
- To calculate desired retirement income, estimate annual expenses, identify revenue sources, and calculate the gap between income and expenses.
- The 70-80% rule suggests aiming for 70-80% of pre-retirement earnings to maintain living standards.
- Consider longevity in retirement planning; healthcare costs for a retired couple may reach around $330,000.
- Regularly assess savings and investment strategies, aiming for a contribution rate of at least 15% of gross income.
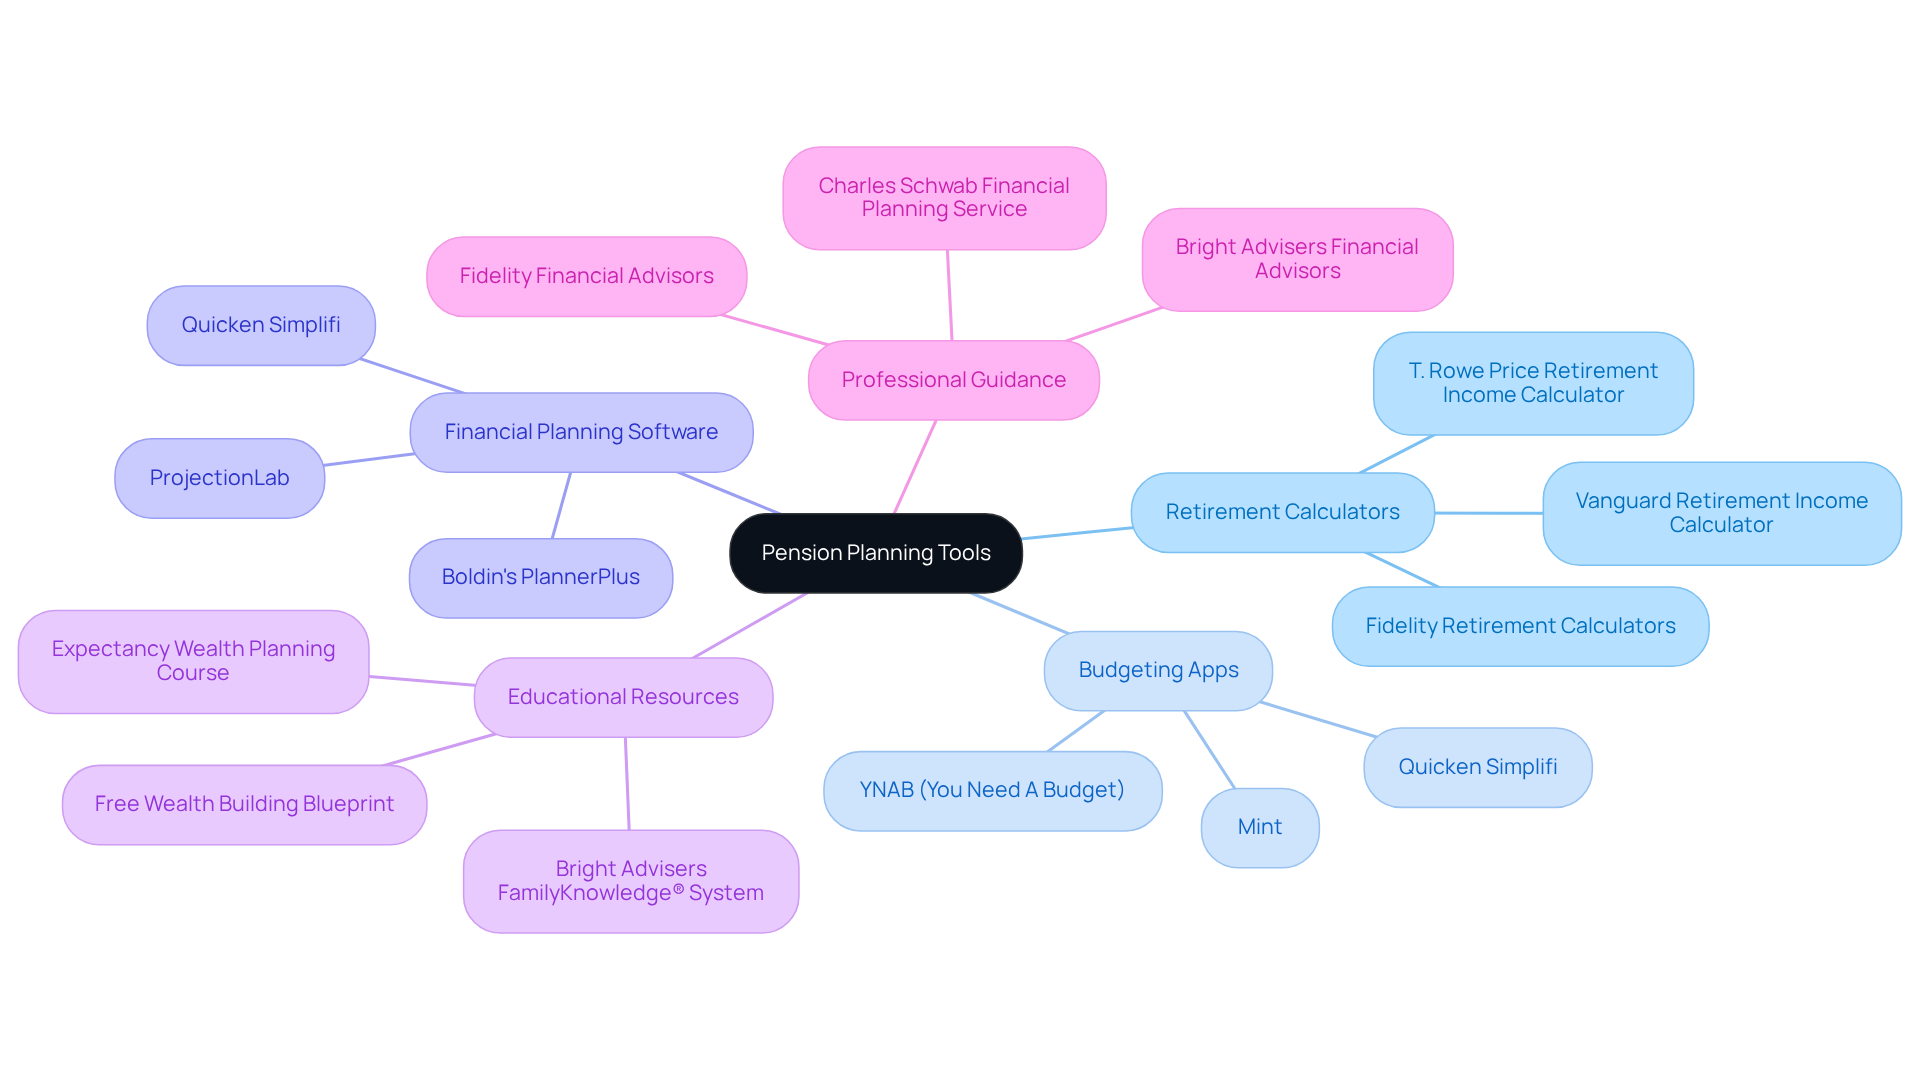
- Utilise retirement calculators, budgeting apps, financial planning software, educational resources, and professional guidance for effective pension planning.
Introduction
Many parents worry about how to secure their family’s future, especially when it comes to retirement. In this guide, we’ll explore the steps you can take to calculate a pension that fits your family’s needs. By understanding key factors like:
- Lifestyle choices
- Family responsibilities
- Healthcare costs
you can gain clarity on what you need for a secure financial future. So, how can you figure out what you need to secure a bright future for your loved ones?
Identify Key Factors Influencing Pension Needs
Imagine facing retirement with uncertainty about your financial future – it’s a concern many parents share. Let’s explore some important factors together that can help you assess your pension requirements and ensure your family is taken care of.
-
Current Lifestyle: Understanding your lifestyle choices is crucial. Many retirees find that their income may not stretch far enough to cover their desired lifestyle, leading to tough choices. Will you maintain the same lifestyle, or do you plan to downsize? Assessing your current living expenses and how they might change in retirement is essential.
-
Retirement Age: When do you plan to retire? The average retirement age in the U.S. is currently 64 years old, but many workers expect to retire at 66. The sooner you retire, the longer your funds must sustain you, which affects how much you need to set aside.
-
Family Responsibilities: Think about your ongoing family responsibilities, like supporting children or elderly parents, which can impact how much you’re able to save. For instance, 42% of individuals of color have set aside savings accounts for the future compared to 68% of non-Hispanic white individuals, highlighting the need for tailored financial strategies that consider individual circumstances.
-
Healthcare Costs: It’s important to anticipate healthcare expenses, as they can weigh heavily on your financial plans in later years. Healthcare costs are expected to rise by 5-7% each year, so planning for these expenses is crucial.
-
Inflation: Don’t forget to factor in inflation, which can erode your purchasing power over time. A common rule of thumb is to assume a 3% annual inflation rate. For example, at a 3% inflation rate, $50,000 required for future income today will need approximately $67,195 in ten years to preserve the same purchasing power.
By understanding these factors, you can take confident steps toward a secure retirement, ensuring your family’s needs are met.
Calculate Your Desired Retirement Income
Imagine a future where your family’s financial needs are met, allowing you to enjoy your retirement without worry. To secure that future, let’s explore how you can calculate your desired retirement income.
-
Estimate Annual Expenses: Think about what you’ll need for housing, food, healthcare, travel, and fun activities. For instance, retirees in the U.S. spent an average of $61,432 annually in 2024, which represents a 2.2% increase from the previous year, with housing alone accounting for approximately 36% of this total.
-
Consider Revenue Sources: Identify potential revenue streams during retirement, such as Social Security, pensions, and returns from assets. The average monthly Social Security benefit in 2026 is about $2,071, which translates to roughly $24,852 annually. Estimate how much you expect to receive from each source.
-
Calculate the Gap: Subtract your anticipated earnings from your estimated expenses to determine the gap. This gap signifies the amount you need to bridge through reserves and investments. For example, if your projected expenses are $60,000 and your anticipated earnings are $30,000, you will need to bridge a $30,000 gap through your savings.
-
Use the 70-80% Rule: A common guideline is to aim for 70-80% of your pre-retirement earnings to maintain your standard of living. Adjust this percentage based on your specific circumstances. For example, if your pre-retirement earnings are $50,000, plan to spend between $35,000 and $40,000 each year after you stop working. If you earn less than $50,000, you may need to replace up to 80% of your pre-retirement income.
-
Factor in Longevity: Consider your life expectancy and plan for a phase that could last 20-30 years or more. This will assist in making sure your funds endure throughout your later years. It’s crucial to recognize that healthcare expenses can be substantial, with estimates indicating a retired couple may require around $330,000 set aside for healthcare costs throughout their later years, which is anticipated to represent approximately 15% of overall expenses.
Without a clear plan, you may find it challenging to maintain your family’s lifestyle. By taking these steps, you’re not just planning for retirement; you’re securing a brighter future for your loved ones.
Assess Current Savings and Investment Strategies
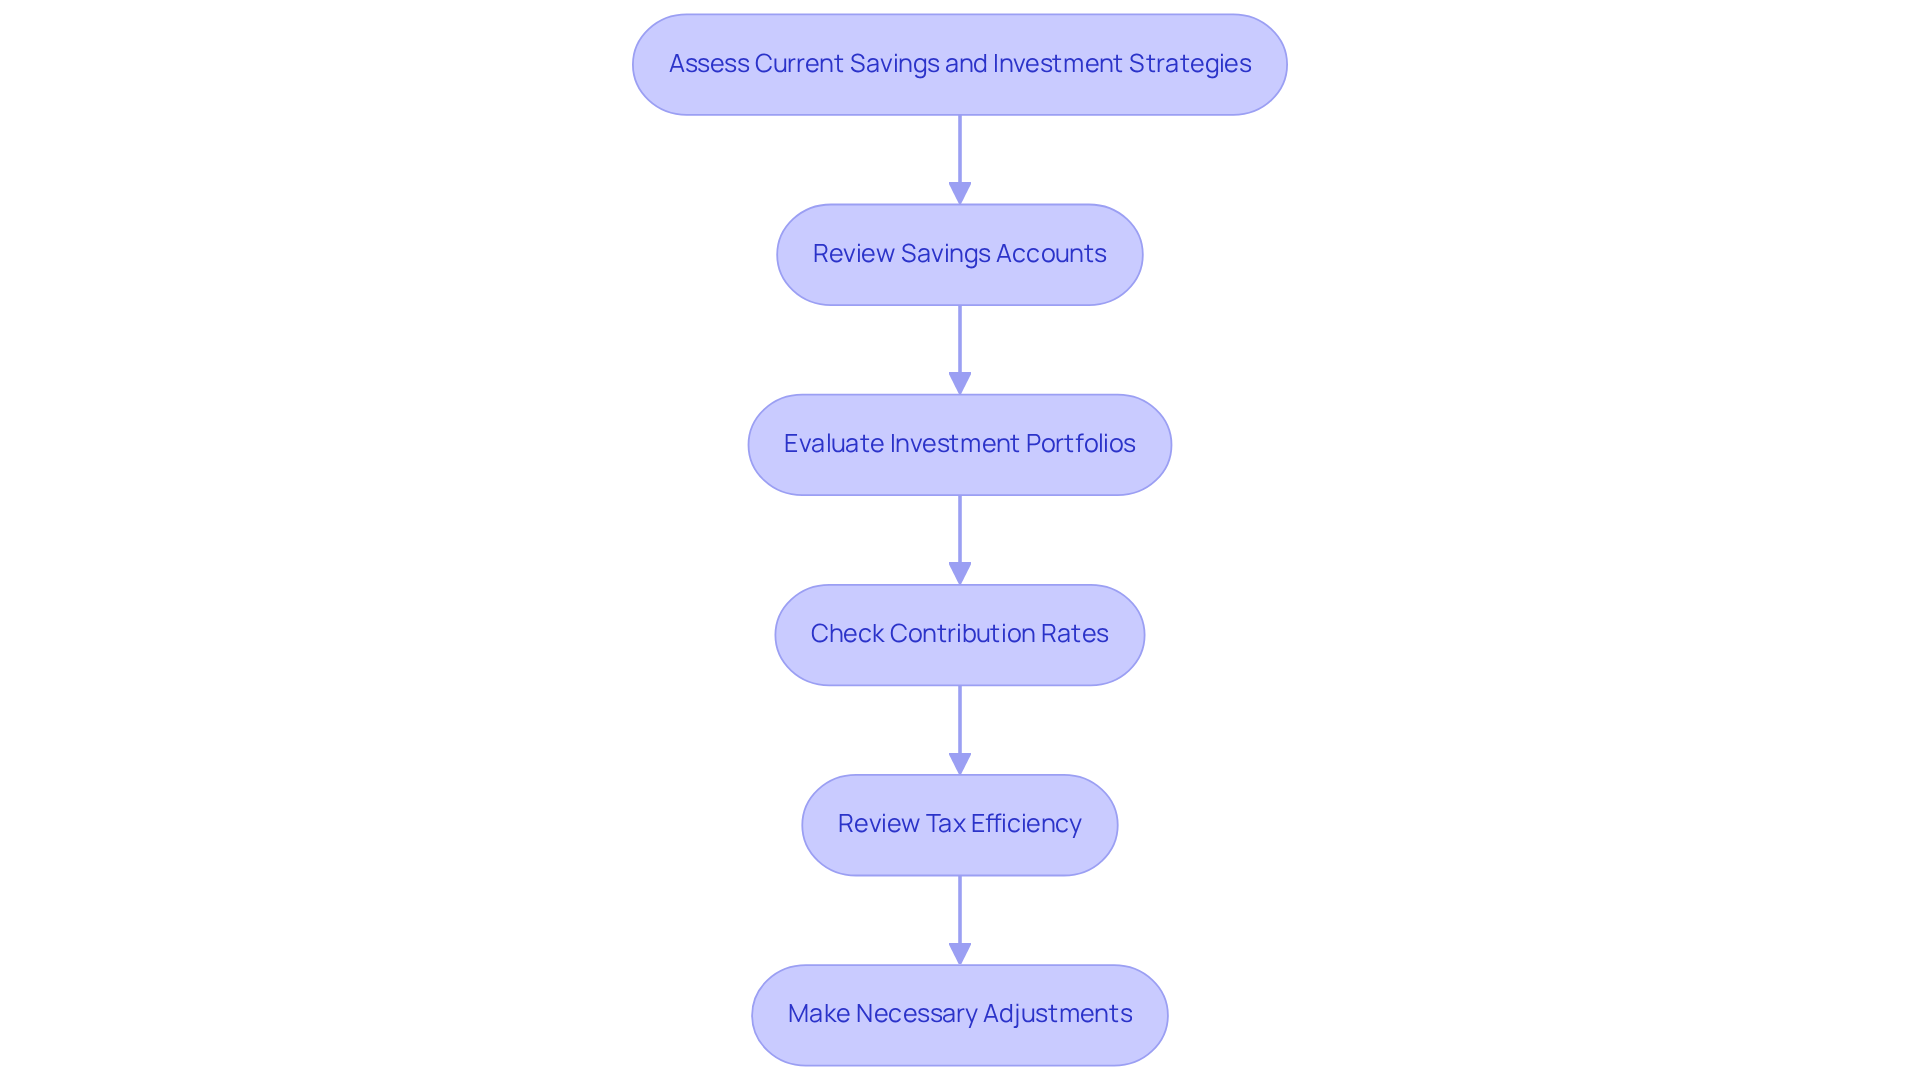
Imagine the peace of mind that comes from knowing your family is financially secure. To effectively assess your current savings and investment strategies, let’s start by taking a gentle look at your savings accounts, ensuring you have enough to cover those unexpected moments. It’s important to have emergency reserves and pension plans in place, particularly when evaluating how much is a decent pension, especially since only 64% of U.S. adults can manage a $400 emergency. Imagine the stress of facing an unexpected expense without a safety net.
Next, consider your investment portfolios. At Bright Advisers, we focus on personalized strategies that fit your family’s unique needs, helping you grow your investments with care. A varied combination of assets is crucial for long-term growth, particularly as funds for the future typically reach their highest point in your 60s.
Now, let’s check your contribution rates. Are you contributing adequately to your savings accounts, like 401(k)s or IRAs? Aiming for a contribution rate of at least 15% of your gross income can significantly influence how much is a decent pension for your retirement outcomes.
It’s also essential to review your financial strategies for tax efficiency. Bright Advisers offers helpful strategies, such as tax-loss harvesting, to reduce tax obligations and improve your overall financial resources. Utilizing tax-advantaged accounts is crucial for optimizing your wealth accumulation. Plus, we maintain a clear fee structure with no hidden charges, commissions, or trading fees, ensuring transparency in your costs.
Finally, based on your assessment, make any necessary adjustments to your savings and financial strategies. This might involve increasing contributions, reallocating resources, or consulting a financial professional for personalized advice. Bright Advisers’ innovative in-house technology can assist you in avoiding costly mutual funds and ETFs, leading to more efficient portfolio management. We also have a no minimum account size policy, making our services accessible to all families.
Regularly checking in on your financial plans can help ensure you’re on the right path for your family’s future. Remember, past performance does not guarantee future results, and all investments carry risks. Taking these steps today can pave the way for a brighter financial future for your family.
Utilize Tools and Resources for Pension Planning
Many parents worry about whether they’re saving enough for their family’s future, and that’s completely understandable. To help ease those concerns, consider utilizing some helpful tools and resources to determine how much is a decent pension for your planning.
-
Retirement Calculators: Imagine having an online tool that estimates how much you need to set aside for the future based on your desired income and current funds. Vanguard and T. Rowe Price offer user-friendly calculators that help you assess your retirement readiness. For instance, T. Rowe Price’s Retirement Income Calculator uses the 4% rule, adjusted for inflation, to give you a clear understanding of your financial needs.
-
Budgeting Apps: Think about using budgeting apps like Mint or YNAB (You Need A Budget) to track your expenses and savings. These tools automatically categorize transactions, making it easier to spot spending patterns and stay on top of your financial goals. A clean and intuitive design in these apps is crucial for keeping you engaged with your budgeting efforts.
-
Financial Planning Software: Imagine using a financial planning tool that helps you visualize different paths for your family’s future. Tools like Quicken Simplifi integrate planning for the future with daily finances, offering features for investment tracking and cash flow projections. This thorough method helps you understand how your current financial habits influence your future savings.
-
Educational Resources: Leverage educational resources from reputable financial institutions or organizations. Bright Advisers offers valuable insights and strategies designed for families, helping you navigate the complexities of planning for the future. Their FamilyKnowledge® System provides interactive lessons that teach your children how to manage their own money and make smart financial decisions as they grow older. This education is crucial for maintaining multi-generational wealth.
-
Professional Guidance: If you feel overwhelmed, seeking professional guidance from a financial advisor who specializes in working with families can be a great step. Bright Advisers offers personalized financial planning and investment management services, including integrated tax planning and tax-loss harvesting strategies. Their dedicated team of advisors can help you create a comprehensive retirement plan that aligns with your family’s unique financial situation.
With the right tools and support, you can confidently navigate your family’s financial journey together, including understanding how much is a decent pension.
Conclusion
It can feel daunting to think about retirement when you’re busy raising a family, but understanding your pension needs is crucial for your peace of mind. By considering your family’s lifestyle, responsibilities, and future needs, you can start to see what your pension should look like. This understanding helps you make choices that will truly support your family in the years to come.
Let’s break down how to figure out what you’ll need for retirement, focusing on your expenses, income sources, and savings strategies. Using tools like retirement calculators and budgeting apps can make planning easier and more effective. Getting help from Bright Advisers can give you personalized strategies that fit your family’s needs perfectly.
Planning for your pension isn’t just about the numbers; it’s about finding peace of mind for your family’s future. Taking these steps helps you build a strong foundation for retirement, so you can focus on what really matters – spending time with your kids and enjoying life. Take the first step towards securing your family’s financial future today. Reach out to Bright Advisers for the support you need on this journey.
Frequently Asked Questions
What are the key factors influencing pension needs?
The key factors influencing pension needs include current lifestyle, retirement age, family responsibilities, healthcare costs, and inflation.
How does current lifestyle affect pension requirements?
Understanding your current lifestyle is crucial, as many retirees find their income may not cover their desired lifestyle. Assessing living expenses and potential changes in retirement is essential for planning.
What is the average retirement age in the U.S.?
The average retirement age in the U.S. is currently 64 years old, with many workers expecting to retire at 66. The earlier you retire, the longer your funds must last, impacting how much you need to save.
How do family responsibilities impact pension savings?
Ongoing family responsibilities, such as supporting children or elderly parents, can affect how much you are able to save for retirement. For example, 42% of individuals of color have set aside savings for the future compared to 68% of non-Hispanic white individuals, indicating the need for tailored financial strategies.
Why is it important to plan for healthcare costs in retirement?
Anticipating healthcare expenses is crucial, as these costs are expected to rise by 5-7% each year, significantly impacting financial plans in later years.
How does inflation affect retirement planning?
Inflation can erode purchasing power over time. A common rule of thumb is to assume a 3% annual inflation rate, meaning that $50,000 needed today will require approximately $67,195 in ten years to maintain the same purchasing power.
What steps can I take to ensure a secure retirement for my family?
By understanding the factors influencing your pension needs, you can take informed steps toward a secure retirement, ensuring that your family’s needs are met.
List of Sources
- Identify Key Factors Influencing Pension Needs
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- 50+ Essential Retirement Statistics for 2026: Demographics & More (https://annuity.org/retirement/retirement-statistics)
- The 10 most important stats for planning your retirement (https://planmember.com/members/retirement-planning-stats)
- 5 Common Factors Affecting Retirement Income | Global Credit Union (https://globalcu.org/financial-planning/learn-investing/retirement-income)
- Calculate Your Desired Retirement Income
- Retirement Cost of Living Guide: Insights & Considerations (https://westernsouthern.com/retirement/retirement-cost-of-living)
- What are the Average Retirement Expenses? | 4 Typical Expenses (https://actsretirement.org/resources-advice/finance-saving-money/saving-money-after-retirement/retirement-expenses)
- How much will you spend in retirement? | Fidelity (https://fidelity.com/viewpoints/retirement/spending-in-retirement)
- Average Retirement Income 2026: By Age, State & Source (https://randallwealthgroup.com/average-retirement-income)
- Monthly Costs for Retirees: What Americans 65 and Older Spend on Housing, Food, Transportation, and Healthcare (https://investopedia.com/monthly-costs-for-retirees-what-americans-65-and-older-spend-on-housing-food-transportation-and-healthcare-12004334)
- Assess Current Savings and Investment Strategies
- Average Retirement Savings By Age In 2026 And How To Catch Up | July Edition (https://forbes.com/sites/investor-hub/article/average-retirement-savings-age-how-to-catch-up)
- Average retirement savings by age (https://empower.com/the-currency/money/average-retirement-savings-by-age)
- Average Savings by Age: 2026 Statistics (https://journeyadvisory.group/blog/average-savings-by-age-2026-statistics)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- 14 Must-Know Retirement Stats For 2026 – Carry (https://carry.com/learn/retirement-stats)
- Utilize Tools and Resources for Pension Planning
- 4 Best Retirement Calculators (Free & Paid) – ROB BERGER (https://robberger.com/best-retirement-calculators)
- Best Retirement Calculator (https://financialmentor.com/calculator/best-retirement-calculator)
- Why Budgeting Apps Are Gaining Popularity | Blog | Academy Bank (https://academybank.com/article/why-budgeting-apps-are-gaining-popularity-in-personal-finance)
- Top Retirement Planning Software with Savings and Retirement Calculators 2026 (https://quicken.com/blog/top-retirement-planning-software-with-savings-and-retirement-calculators-2026?srsltid=AfmBOooKRwWSPyphMhcq9tFQlkujlNjQK4xIbMF5UsbIzi25_YihBw7y)
- How Using Budgeting Apps Can Help with Managing Your Personal Finances (https://pubs.ext.vt.edu/FCS/FCS-166.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading