

Key Highlights
- Define your ideal lifestyle for retirement by considering where to live and activities to engage in.
- Set specific retirement goals, such as travel plans and maintaining a standard of living.
- Anticipate healthcare costs, with an average expected expenditure of $185,500 for a 65-year-old in later years.
- Involve family in retirement discussions to align expectations and financial support needs.
- Visualise your future through vision boards or detailed descriptions to guide financial planning.
- Assess current income, expenses, savings, and debt obligations to understand your financial standing.
- Estimate annual post-employment expenses, aiming for 70-80% of pre-retirement income.
- Determine retirement duration based on life expectancy, planning for at least 20 years of expenses.
- Utilise future planning calculators to estimate monthly savings needed to reach retirement goals.
- Factor in expected income from Social Security and pensions in retirement calculations.
- Adjust savings goals for inflation to maintain purchasing power over time.
- Consult qualified professionals for tailored advice on tax, legal, and investment matters.
- Establish a routine for reviewing and adjusting your retirement plan at least annually.
- Stay informed about changes in tax laws and economic conditions that may affect retirement planning.
Introduction
Imagine standing at the edge of a maze, unsure of how to find your way to a secure and fulfilling retirement. It can be overwhelming to think about all the uncertainties that come with planning for the future. It’s not just about the numbers; it’s about dreaming of a future that fits your family’s hopes and dreams.
This guide will gently walk you through:
- Assessing your family’s financial readiness
- Calculating what you need to save
- Adjusting your plans as life unfolds
What if life takes an unexpected turn, or your dreams evolve? Having a solid plan can bring peace of mind, knowing you’re prepared for whatever life throws your way. By exploring these questions, you can find clarity and confidence in your journey toward a secure retirement for your family.
Define Your Retirement Goals and Lifestyle
Have you ever wondered what your life will look like at age 72? Planning for the future can feel overwhelming, but it’s essential to define your vision first. Let’s explore some gentle steps you can take to envision your future together:
-
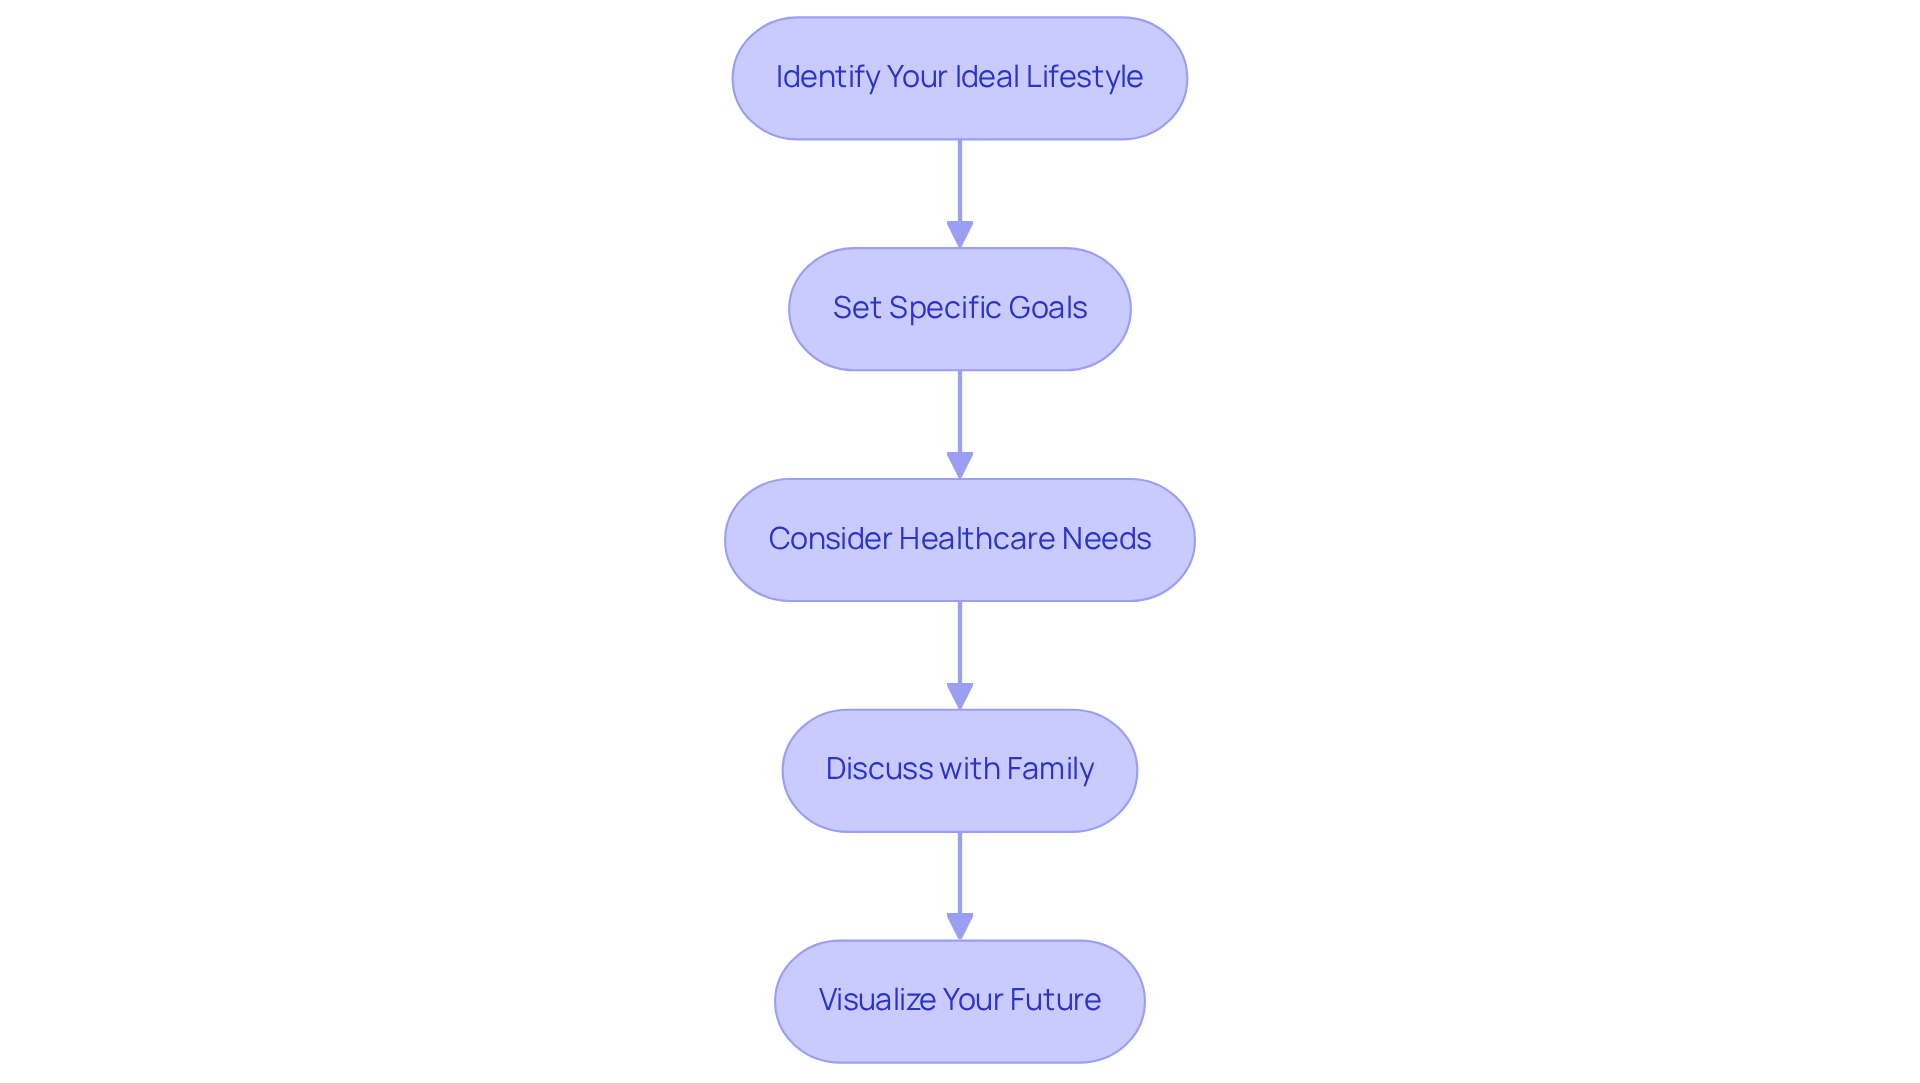
Identify Your Ideal Lifestyle: Reflect on where you want to live, the activities you wish to engage in, and how you want to spend your time. Do you see yourself traveling, volunteering, or enjoying more family time? Understanding how much money do I need to retire at 72 is crucial for assessing how location affects your income in later years. For instance, when considering how much money do I need to retire at 72, living in high-expense areas like California may require significantly more funds than in lower-expense states.
-
Set Specific Goals: Document your goals clearly. For example, you might aim to travel internationally once a year, maintain a certain standard of living, or contribute to your children’s education. In 2026, the average income after leaving the workforce for Americans aged 65 and older is projected to be $58,680 per year. This can serve as a helpful benchmark for determining how much money do I need to retire at 72 during this phase.
-
Consider Healthcare Needs: Anticipate potential healthcare costs, which can be substantial in later life. In 2026, a 65-year-old can expect to spend an average of $185,500 on healthcare during their later years. This highlights the importance of researching average healthcare expenses in your state and planning accordingly. Imagine facing unexpected healthcare expenses that could affect how much money do I need to retire at 72.
-
Discuss with Family: Involve your family in these discussions to ensure your plans for the future align with their expectations and needs, especially if you intend to provide financial support. Approximately 32% of individuals aged 60-64 and 19% of those aged 65-69 continue working part-time to enhance their income after leaving the workforce, which may also affect your planning. Failing to communicate with your family might lead to misunderstandings and unmet expectations in your financial journey.
-
Visualize Your Future: Create a vision board or a detailed description of your ideal phase of life after work. This visual representation can serve as motivation and a guide for your financial planning.
By taking these steps, you’re not just planning financially; you’re creating a future that reflects your family’s dreams and values. This method not only prepares you for the financial aspects of your later years but also ensures that your lifestyle choices resonate with your values and desires.
Assess Key Financial Factors for Retirement
Imagine the peace of mind that comes with knowing your family’s future is secure, even as you navigate the challenges of today. To help you on this journey, let’s explore some key financial factors that will influence your retirement planning:
-
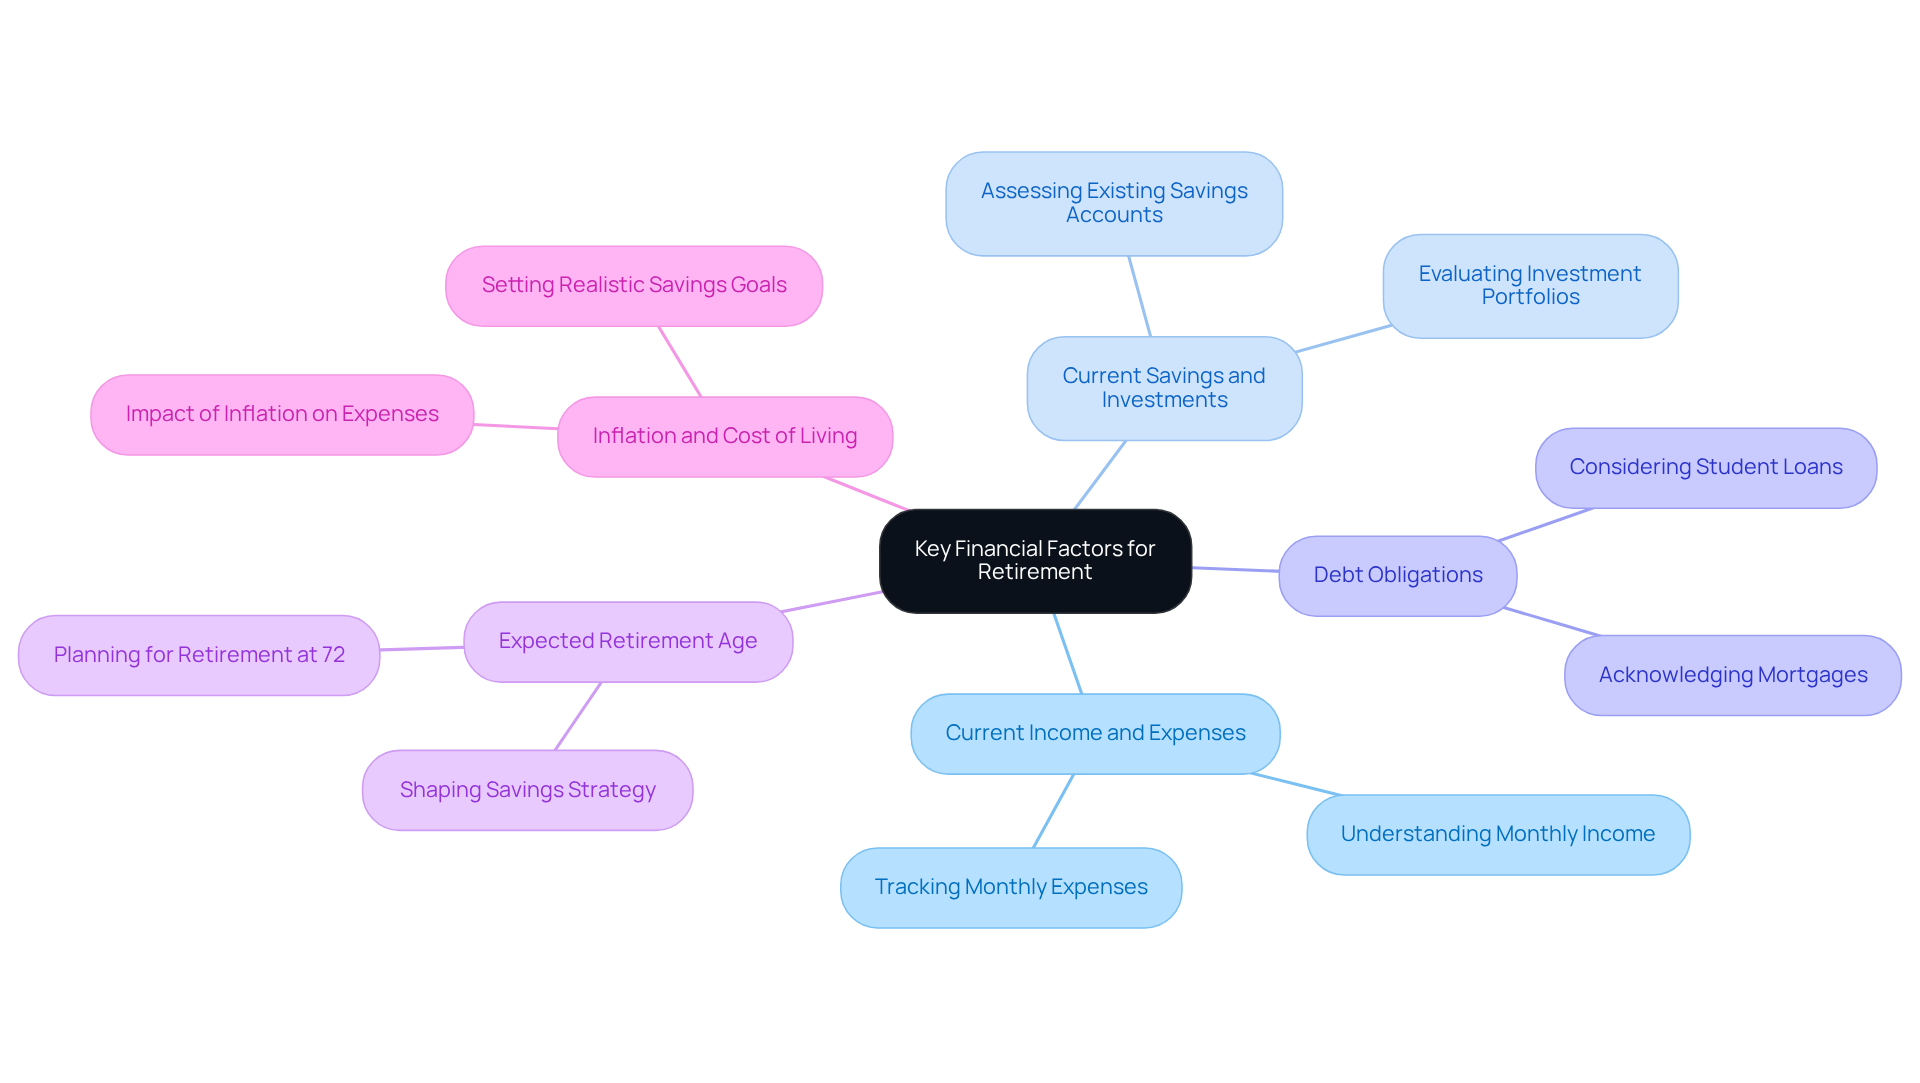
Current Income and Expenses: Let’s start by taking a moment to understand your current income and monthly expenses together. This will help you see how much you can realistically save each month.
-
Current Savings and Investments: Think about your existing savings accounts and investments; knowing where you stand is the first step toward a brighter future.
-
Debt Obligations: It’s important to acknowledge any debts you may have, like mortgages or student loans, as they play a role in your financial journey. Understanding your obligations will assist you in determining how much to save for retirement.
-
Expected Retirement Age: Think about when you envision retiring; this will shape your savings strategy and future plans. Understanding how much money do I need to retire at 72 is crucial for effective planning.
-
Inflation and Cost of Living: Consider how inflation might impact your expenses in the future; this understanding will help you set realistic savings goals.
By thoroughly evaluating these financial factors, you can create a more precise and effective plan for your future. Taking these steps today can pave the way for a more secure and fulfilling retirement for you and your loved ones.
Calculate Your Required Retirement Savings
Imagine facing retirement without a clear understanding of your financial needs – it’s a daunting thought for many families. To determine how much money you need for a comfortable retirement, follow these steps:
-
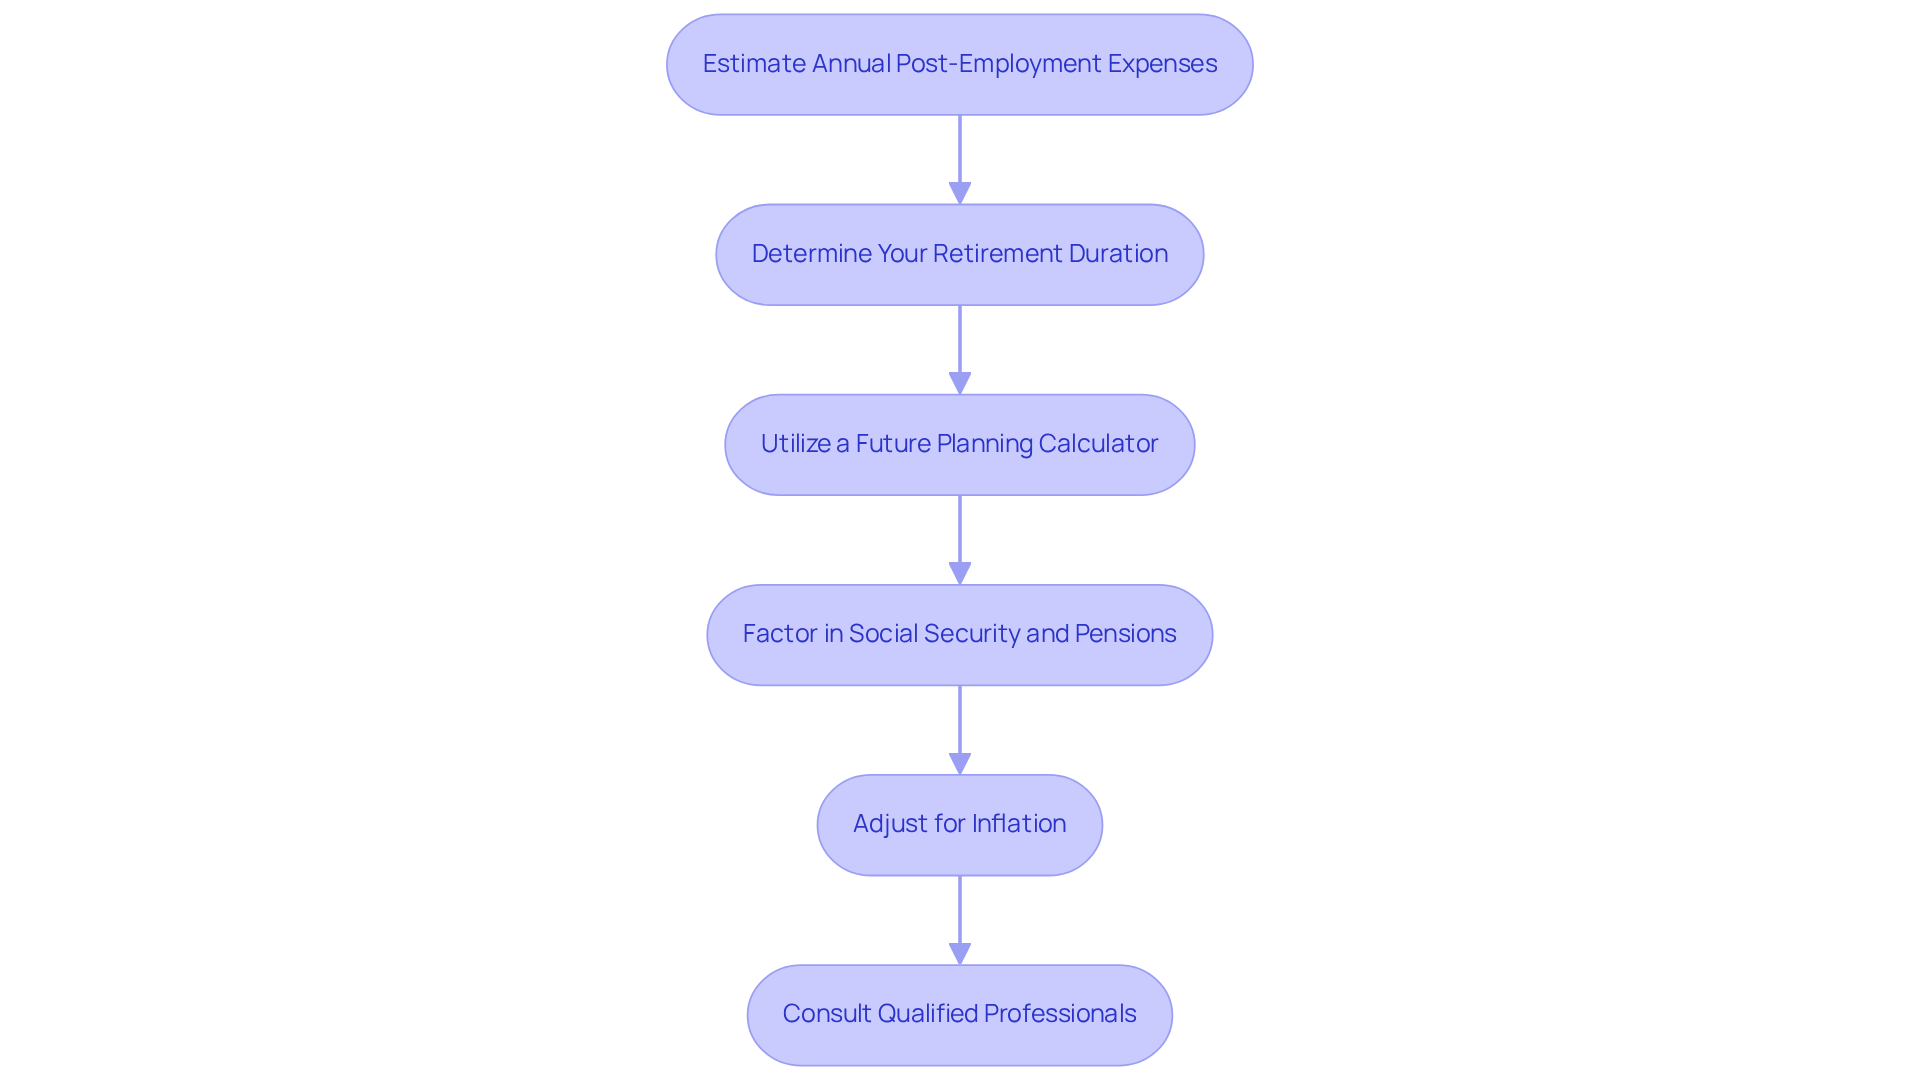
Estimate Annual Post-Employment Expenses: If you earn $100,000 before retirement, aim for $70,000 to $80,000 each year afterward. It’s important to consider your desired lifestyle when estimating your annual expenses after leaving the workforce. Many families worry about how rising costs could affect their retirement plans, and it’s a valid concern. For families like Jay and Emma, who are managing future financial goals alongside educational expenses for their children, understanding these costs is crucial to alleviating financial stress.
-
Determine Your Retirement Duration: Think about your life expectancy to estimate how long your funds must last. For instance, a 65-year-old man may live another 17.5 years, while a woman may live about 20.1 years. It is wise to plan for at least 20 years of expenses after leaving the workforce, considering how much money do I need to retire at 72.
-
Utilize a Future Planning Calculator: Online future planning calculators can help you enter your current funds, anticipated contributions, and projected returns. This tool will show how much you need to save each month to achieve your financial goals. If your goal is to accumulate $1 million by the time you stop working, the calculator can help you figure out the monthly contributions needed based on your current age and anticipated age of leaving the workforce. We’re here to help families navigate these calculations to ensure they are on track to meet their goals.
-
Factor in Social Security and Pensions: Include any expected income from Social Security or pensions in your calculations. For many retirees, Social Security accounts for a significant portion of their income, with 90% relying on it for more than half of their income. Furthermore, 94% of retired individuals with financial plans indicate that they have sufficient resources to live comfortably, emphasizing the significance of having a financial plan. For young families, this planning is crucial to balance present requirements with future security.
-
Adjust for Inflation: It’s crucial to adjust your calculations for inflation, as the purchasing power of your savings will decrease over time. For example, if inflation is anticipated at 2% each year, a financial goal of $1 million today may need to be revised to around $1.5 million in 20 years to preserve the same purchasing power.
-
Consult Qualified Professionals: It’s advisable to consult with qualified professionals regarding specific tax, legal, accounting, and investment situations. This can offer customized advice to ensure your planning for the future is thorough and effective. We provide customized wealth management solutions that assist families like Jay and Emma in navigating these complexities, ensuring they can allocate resources effectively for both future planning and their children’s education.
By taking these steps, you can pave the way for a secure future, ensuring your family thrives even in retirement.
Review and Adjust Your Retirement Plan Regularly
Imagine the peace of mind that comes from knowing your family’s financial future is secure. Establishing a routine for reviewing and adjusting your retirement plan is crucial for staying on track toward your financial goals.
-
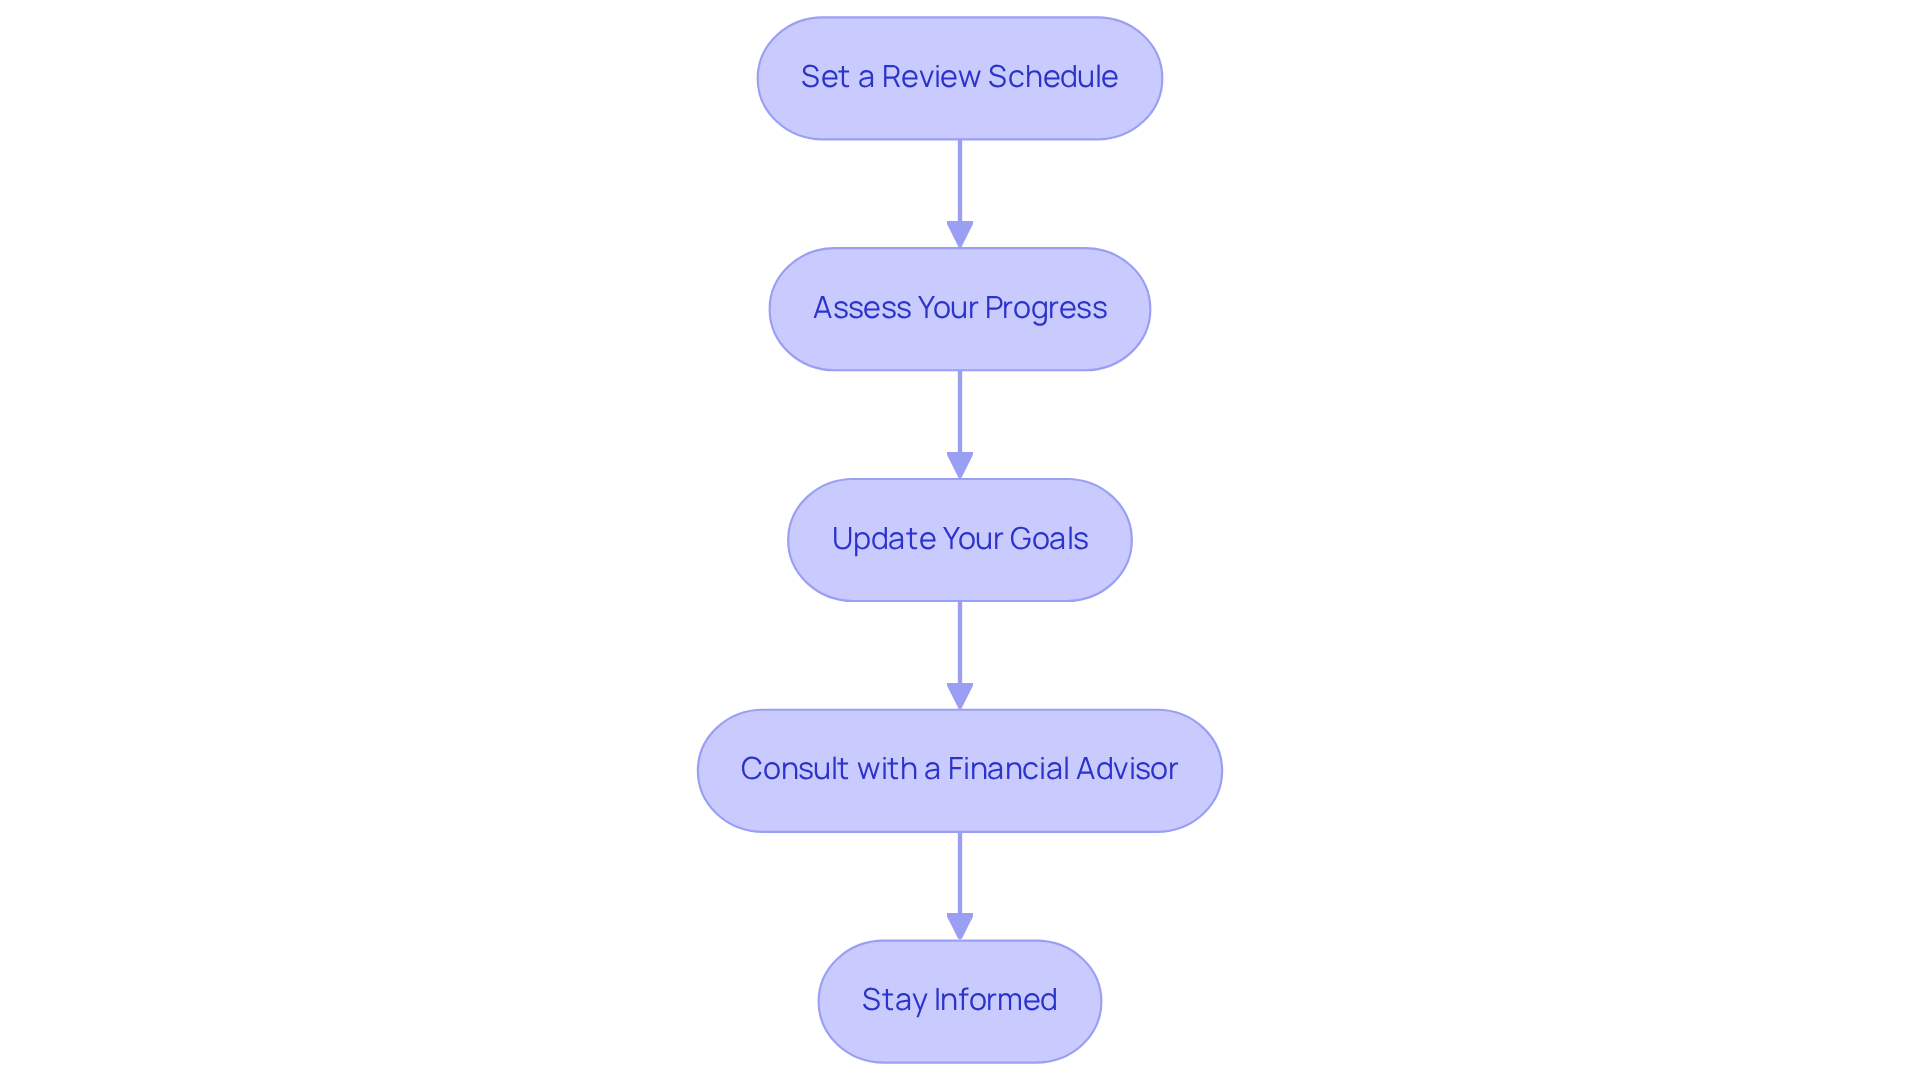
Set a Review Schedule: Aim to review your financial plan at least annually. If significant life changes occur, such as a job change or the birth of a child, consider more frequent reviews.
-
Assess Your Progress: Regularly checking in on your savings plan helps you stay on track and adapt to life’s changes. Compare your current funds and investments against your future objectives. If you find you’re not on track, it’s important to identify the reasons and adjust your savings rate or investment strategy. Bright Advisers’ commitment to minimal fund fees ensures that more of your money is working for you, enhancing your ability to reach your financial goals.
-
Update Your Goals: Life circumstances can change, impacting your future objectives. Be flexible and willing to adjust your retirement vision based on new priorities or financial realities.
-
Consult with a Financial Advisor: Talking to a financial advisor can really help you find the right path for your family’s unique situation. Advisors can assist families in navigating intricate financial environments and ensure that their strategies remain aligned with their objectives. Bright Advisers offers personalized planning and tax optimization strategies to support families in achieving financial security and freedom.
-
Stay Informed: Keep abreast of changes in tax laws, investment opportunities, and economic conditions that may influence your planning for the future. This knowledge empowers you to make informed decisions.
Many parents worry about whether their savings will truly support their family’s future. If you don’t take the time to review your plan, you might miss out on the chance to secure your family’s dreams. A study on engaging financial preparation emphasizes that individuals who strategize for an active lifestyle filled with social activities tend to experience greater fulfillment and connection, reinforcing the significance of proactive preparation. Additionally, statistics show that only 35% of non-retirees believe their retirement savings plan is on track, underscoring the need for regular assessments to avoid falling behind. Taking these steps today can pave the way for a future where your family thrives, not just survives.
Conclusion
Imagine stepping into your retirement years with a clear vision of the life you want to lead, rather than feeling overwhelmed by the numbers. Planning for retirement at age 72 is about more than just crunching numbers; it’s about envisioning the lifestyle you desire. By defining your retirement goals and assessing your financial readiness, you can create a roadmap that aligns with your family’s values and aspirations.
It’s important to understand your unique needs and how the financial landscape can support your dreams. Key insights from this guide highlight the necessity of:
- Setting specific retirement goals
- Evaluating your current financial situation
- Regularly reviewing your plans to adapt to life changes
Many families feel lost when it comes to planning for retirement, unsure of where to start or what steps to take. Consider factors such as healthcare costs, inflation, and potential income sources like Social Security.
Utilizing tools like retirement savings calculators can provide clarity on how much money you need to maintain your desired lifestyle. Consulting with professionals can offer tailored advice to navigate complex financial decisions. By taking these steps, families can transform uncertainty into confidence, paving the way for a joyful retirement.
Ultimately, taking charge of your retirement planning today can open doors to a future filled with cherished moments and peace of mind. By assessing and adjusting your financial strategies, you can ensure that your retirement not only meets your needs but also reflects your dreams and values. Engaging in this process today can lead to a more secure and fulfilling future, allowing your family to enjoy time together without financial stress.
Frequently Asked Questions
Why is it important to define retirement goals and lifestyle?
Defining retirement goals and lifestyle is essential as it helps you envision your future, understand your financial needs, and create a plan that aligns with your values and desires.
What should I consider when identifying my ideal lifestyle for retirement?
Consider where you want to live, the activities you wish to engage in, and how you want to spend your time, such as traveling, volunteering, or enjoying family time.
How does location affect retirement income needs?
Living in high-expense areas, like California, may require significantly more funds for retirement compared to lower-expense states, impacting how much money you need to retire at 72.
What specific goals should I set for my retirement?
Set clear goals such as traveling internationally once a year, maintaining a certain standard of living, or contributing to your children’s education to guide your financial planning.
What are the projected average incomes for retirees?
In 2026, the average income after leaving the workforce for Americans aged 65 and older is projected to be $58,680 per year, which can help you determine your retirement income needs.
How should I plan for healthcare costs in retirement?
Anticipate potential healthcare costs, which can be substantial. In 2026, a 65-year-old can expect to spend an average of $185,500 on healthcare during their later years, so researching average healthcare expenses in your state is crucial.
Why is it important to discuss retirement plans with family?
Involving your family in discussions ensures that your plans align with their expectations and needs, especially if you intend to provide financial support, preventing misunderstandings and unmet expectations.
What is a helpful tool for visualizing my retirement future?
Creating a vision board or a detailed description of your ideal post-work life can serve as motivation and a guide for your financial planning.
How do these steps contribute to my overall retirement planning?
These steps not only prepare you for the financial aspects of retirement but also ensure that your lifestyle choices resonate with your family’s dreams and values.
List of Sources
- Define Your Retirement Goals and Lifestyle
- Fidelity says 2026 retirees may spend $185,500 on healthcare. One category may push those costs higher (https://cnbc.com/2026/07/22/retirement-health-costs-fidelity.html)
- Fidelity estimates retirees will spend $185,500 on healthcare and medical expenses in retirement (https://foxbusiness.com/economy/fidelity-estimates-retirees-spend-185500-healthcare-medical-expenses-retirement)
- Average Retirement Income 2026: By Age, State & Source (https://randallwealthgroup.com/average-retirement-income)
- Retirement Cost of Living Guide: Insights & Considerations (https://westernsouthern.com/retirement/retirement-cost-of-living)
- 2026 retirees could expect to spend $185,000 on healthcare, report finds (https://ktla.com/news/nationworld/2026-retirees-could-expect-to-spend-185000-on-healthcare-report-finds)
- Assess Key Financial Factors for Retirement
- Median Household Income and Cost of Living – San Bernardino County Community Indicators (https://indicators.sbcounty.gov/income/median-household-income-and-cost-of-living)
- Cost of Living in California (https://sofi.com/cost-of-living-in-california)
- What Will It Cost To Live “Comfortably” in Every State in 2026? (https://finance.yahoo.com/news/cost-live-comfortably-every-state-102204972.html)
- California Income Statistics | Current Census Data for California Zip Codes (https://incomebyzipcode.com/california)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/resources/financial-education/detail/money-talk-10-great-quotes-about-personal-finance)
- Calculate Your Required Retirement Savings
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- 14 Must-Know Retirement Stats For 2026 – Carry (https://carry.com/learn/retirement-stats)
- 2026 Retirement Statistics: Average Savings Fall $500,000 Short of What Retirees Say They Need | Clever Real Estate (https://listwithclever.com/research/retirement-statistics)
- Californians need more than $2M in savings to retire comfortably: study (https://ktvu.com/news/californians-need-more-than-2m-savings-retire-comfortably-20-years-study)
- How much do you (really) need to save for retirement? (https://merrilledge.com/article/how-much-do-you-really-need-to-save-for-retirement)
- Review and Adjust Your Retirement Plan Regularly
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- 56 Important Retirement Plan Statistics For 2026 – Carry (https://carry.com/learn/retirement-plan-statistics)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 50+ Essential Retirement Statistics for 2026: Demographics & More (https://annuity.org/retirement/retirement-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading