

Key Highlights
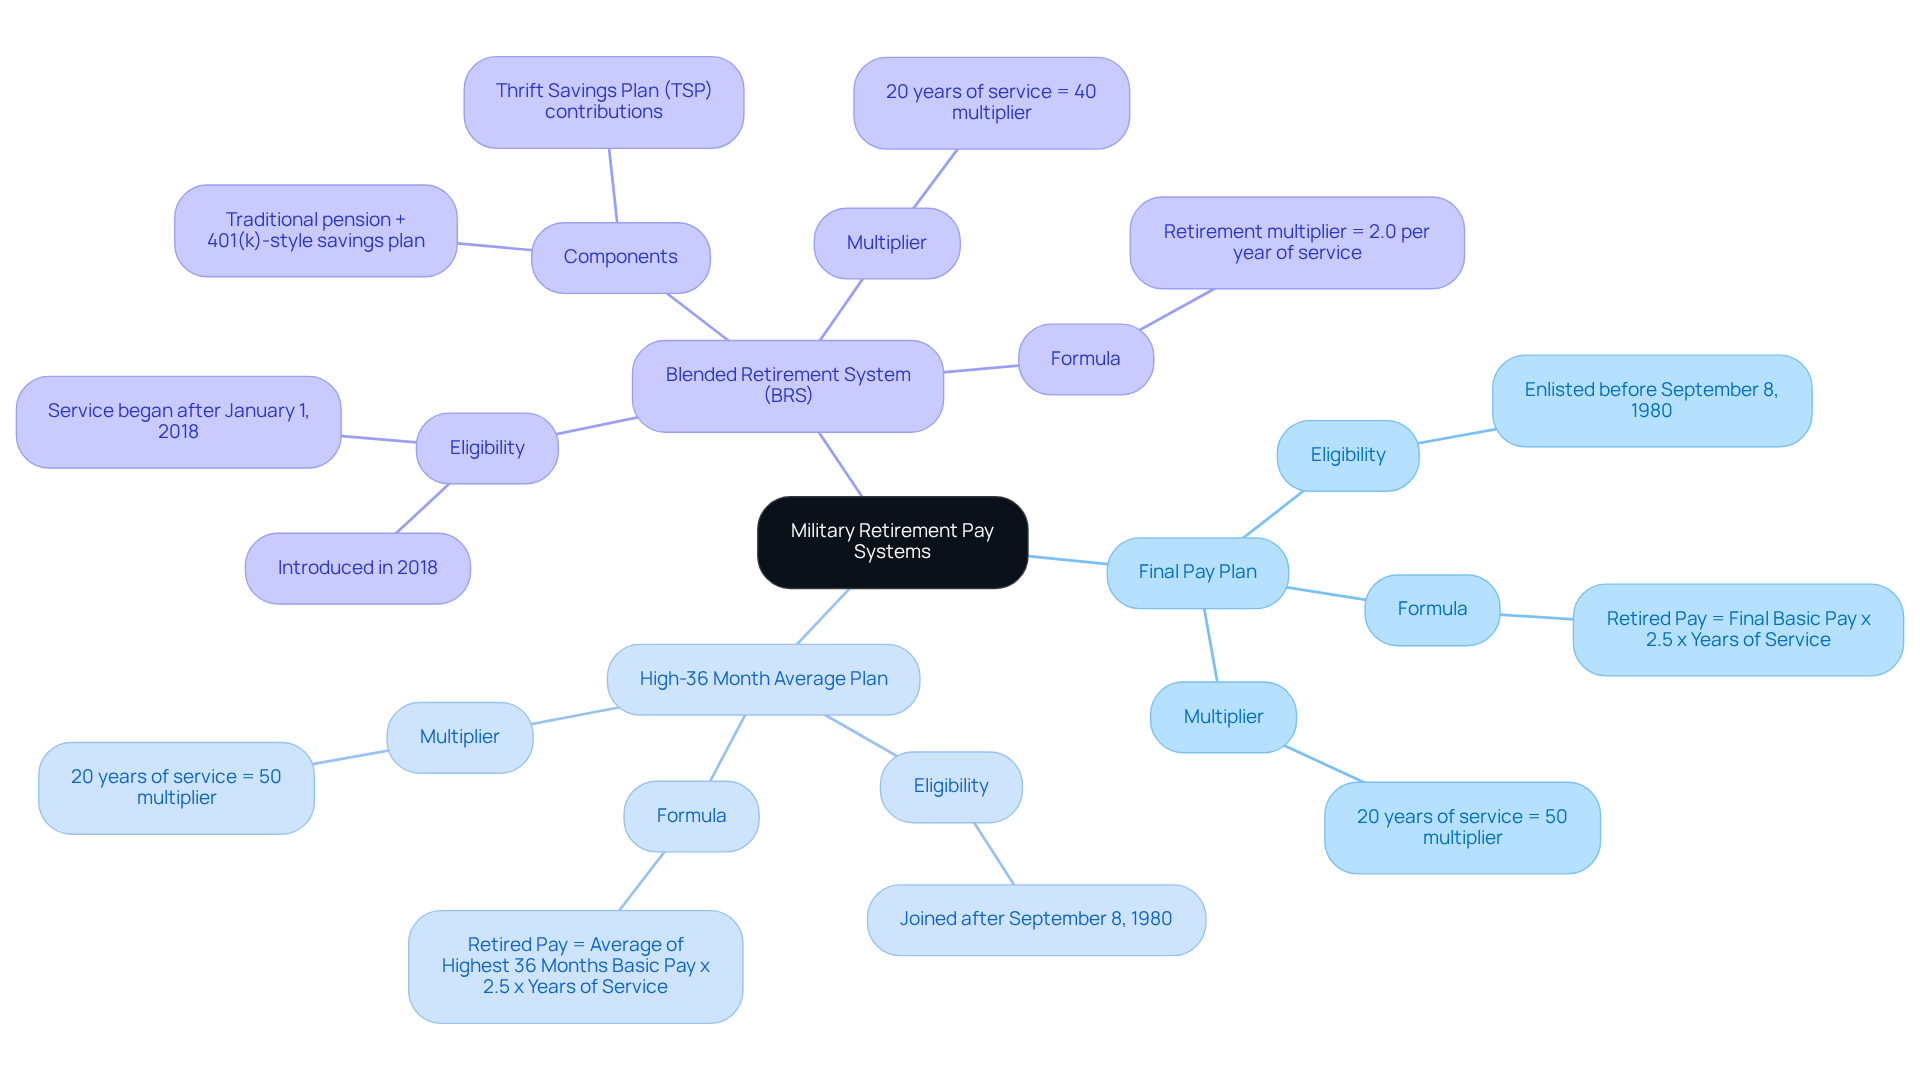
- Military retirement pay systems include the Final Pay Plan, High-36 Month Average Plan, and Blended Retirement System (BRS).
- Final Pay Plan is for those enlisted before September 8, 1980, calculating pay based on final basic salary.
- High-36 Month Average Plan is for those who joined after September 8, 1980, using the average of the highest 36 months of pay.
- BRS combines traditional pension elements with a 401(k)-style savings plan, offering matching contributions from the military.
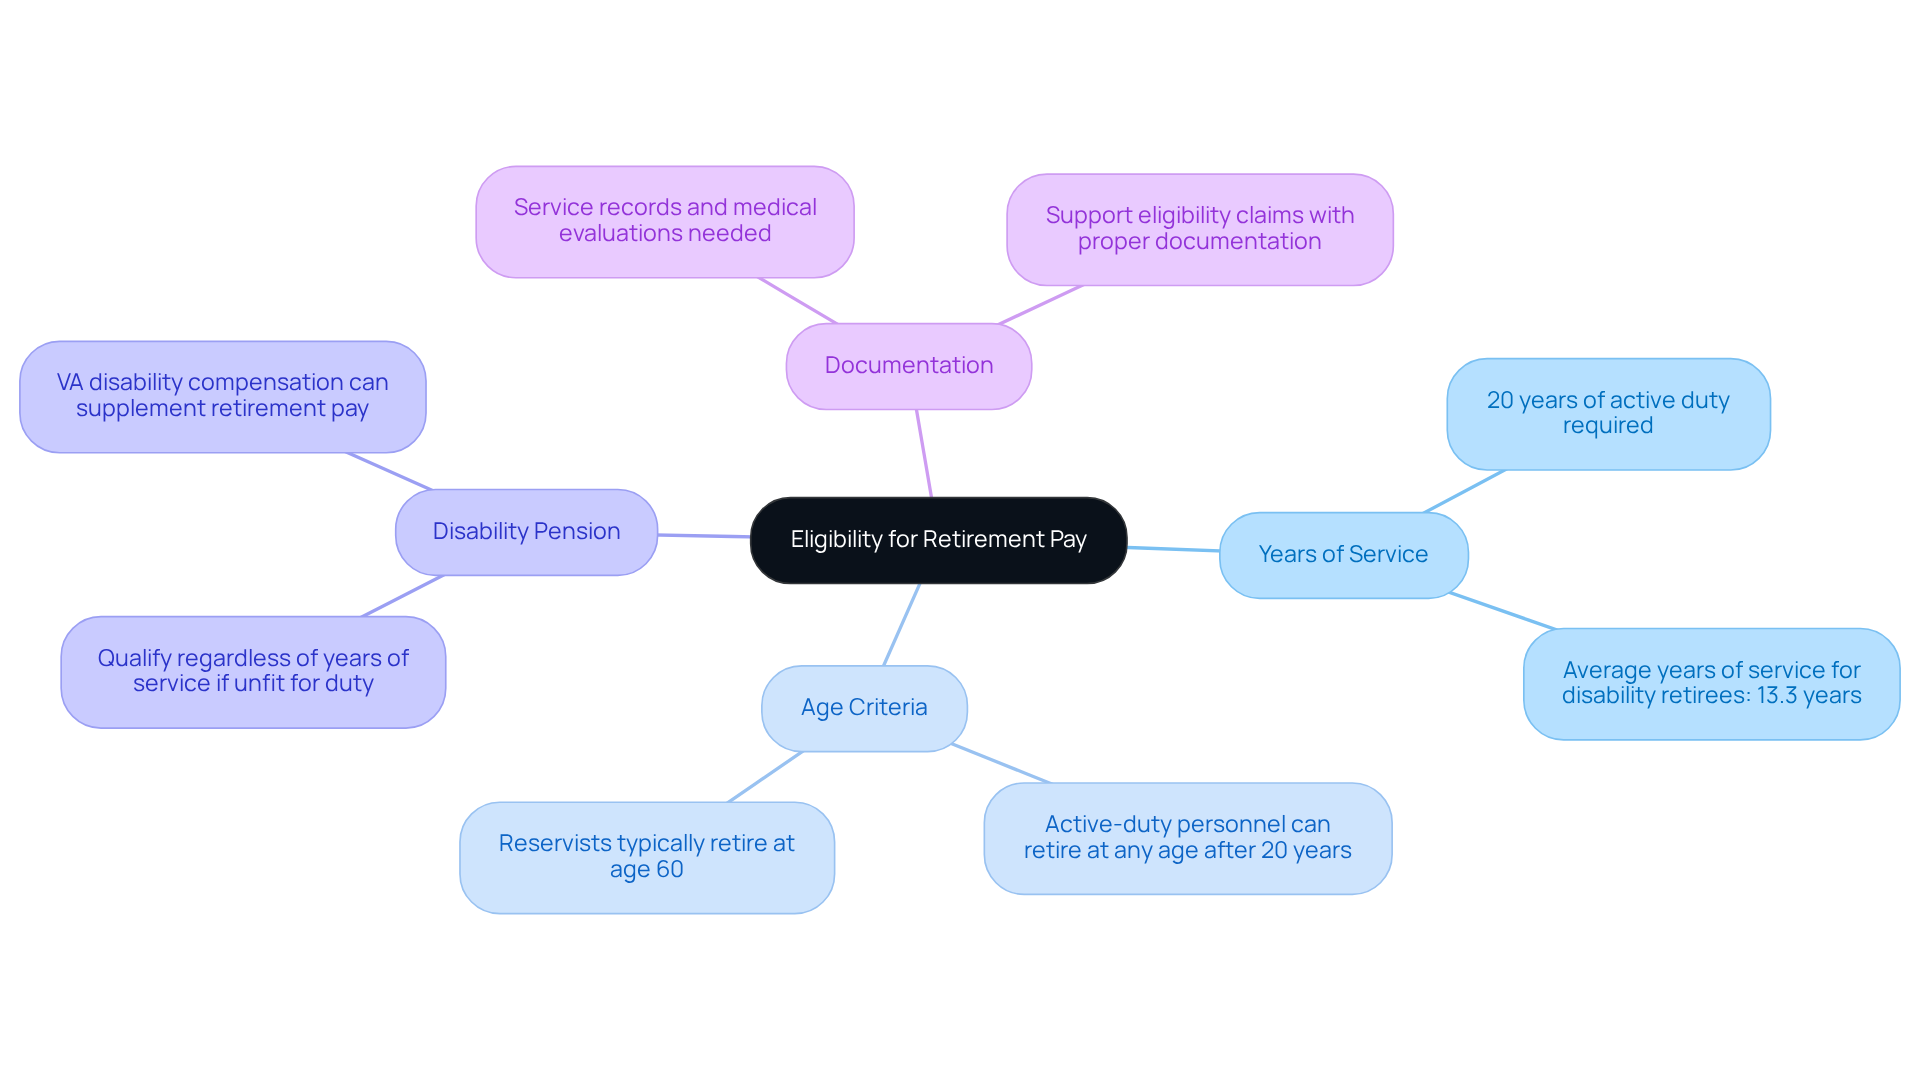
- Eligibility for retirement pay generally requires at least 20 years of active duty service.
- Active-duty personnel can retire at any age after 20 years, while reservists typically retire at age 60.
- Disability pensions are available for service-related disabilities, regardless of years of service.
- Key documents for eligibility claims include service records and medical evaluations.
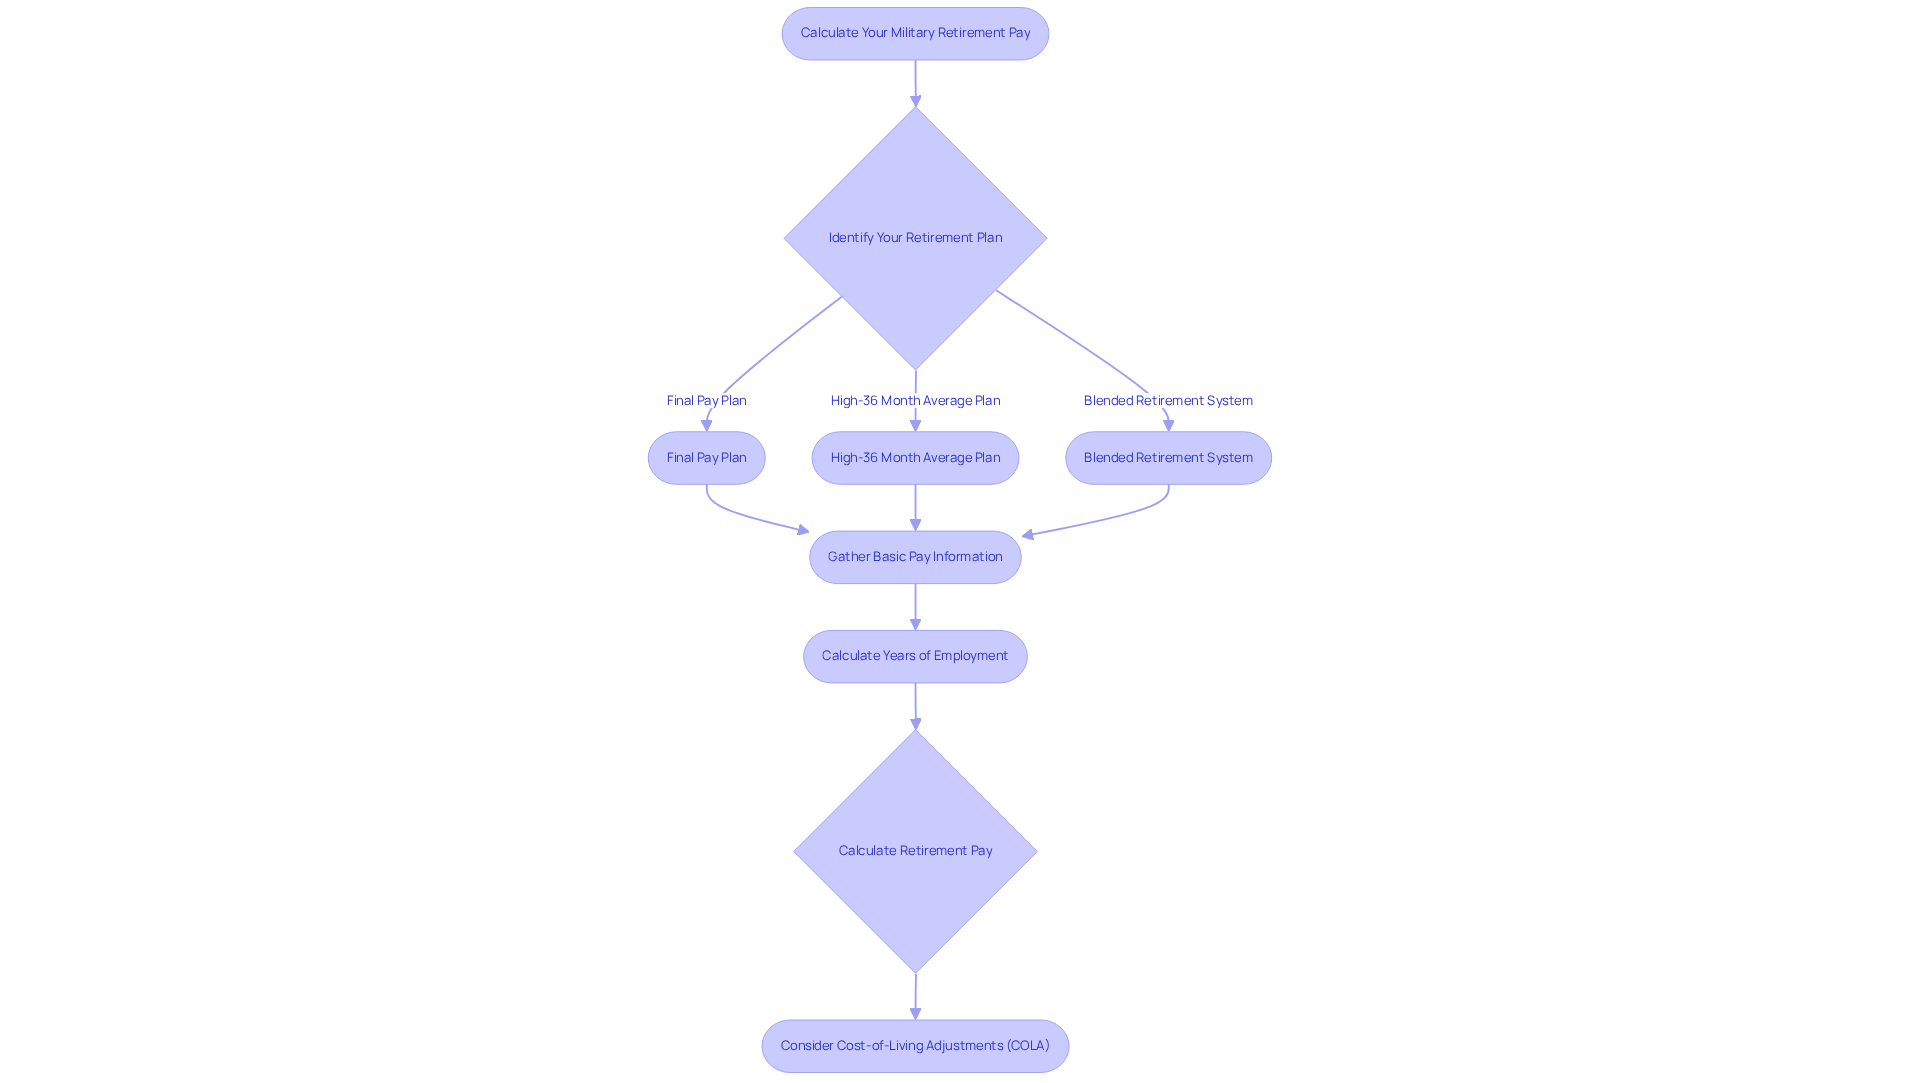
- Calculating retirement pay involves identifying the retirement plan, gathering basic pay information, and applying the appropriate formula.
- Cost-of-living adjustments (COLA) can impact retirement pay, ensuring it keeps pace with inflation.
- Factors affecting retirement pay include years of service, final basic pay, COLA, disability ratings, and tax implications.
Introduction
Imagine transitioning from military life to civilian life, only to feel lost in the complexities of retirement pay. Navigating the maze of military retirement pay can feel overwhelming for many families. Each system offers unique benefits and calculations that can be hard to grasp. This guide is here to help you understand military retirement pay, offering insights into:
- Eligibility
- Calculation methods
- Factors that can influence your family’s financial well-being
Together, we can explore how families can maximize their benefits and secure a brighter financial future amidst these complexities.
Understand Military Retirement Pay Systems
Imagine the peace of mind that comes with understanding your military pension options as you plan for your family’s future. Navigating the complexities of military pensions can feel overwhelming, especially when you’re trying to secure your family’s future. Let’s break it down into three key systems that can help: the Final Pay Plan, the High-36 Month Average Plan, and the Blended Retirement System (BRS).
-
Final Pay Plan: If you enlisted before September 8, 1980, this plan determines your retired compensation based on your final basic salary at the end of your service. The formula is simple:
- Retired Pay = Final Basic Pay x 2.5% x Years of Service
-
High-36 Month Average Plan: For those who joined after September 8, 1980, this plan calculates your pension pay based on the average of your highest 36 months of basic pay. The formula is:
- Retired Pay = Average of Highest 36 Months Basic Pay x 2.5% x Years of Service
-
Blended Retirement System (BRS): Introduced in 2018, this system combines traditional pension elements with a 401(k)-style savings plan. You contribute to a Thrift Savings Plan (TSP) and receive matching contributions from the military. Under the BRS, the pension multiplier is 2.0% per year of service, meaning that after 20 years, you could see a 40% multiplier.
Grasping these systems is crucial for ensuring your family’s financial security as you transition from military service to civilian life. In FY 2023, the Department of Defense processed an impressive 1.3 million retired pay payments each month, showcasing the robust support available for military families like yours. The average time to process pension pay applications was about 30 days, with a remarkable 99.9% success rate for direct deposit payments. These figures highlight the dependable nature of the military pension pay system, providing reassurance for you and your family as you navigate your financial future together. By grasping these pension systems, you can take confident steps toward securing your family’s financial well-being.
Determine Eligibility for Retirement Pay
Navigating military retirement can feel overwhelming, especially when it comes to understanding eligibility for benefits that support your family’s future. Here are some key points to consider:
- Years of Service: Think about the years you’ve dedicated to serving your country – generally, you need at least 20 years of active duty to qualify for retirement pay. This includes your time in the Army, Navy, Air Force, Marine Corps, or Coast Guard.
- Age Criteria: While reservists typically leave the workforce at age 60, active-duty personnel can step down at any age after completing 20 years of service. This flexibility can be a relief as you plan for your family’s future.
- Disability Pension: If you’re deemed unfit for duty due to a service-related disability, you might still qualify for pension pay, regardless of your years of service. This is an important safety net for you and your loved ones.
- Documentation: Gathering the right documents is key – make sure you have your service records and any medical evaluations handy to support your eligibility claim. We’re here to help you through this process.
Understanding these eligibility criteria is essential for military members and their families, as it directly affects how much money do retired military make in terms of financial planning and future strategy. By grasping these criteria, you can take confident steps toward securing your family’s financial future, knowing that support is available every step of the way.
Calculate Your Military Retirement Pay
Imagine the peace of mind that comes with knowing exactly what your military retirement pay will be, especially when planning for your family’s future. Let’s explore how you can confidently calculate your military retirement pay, ensuring your family’s future is secure.
First, let’s identify your retirement plan. Are you under the Final Pay Plan, the High-36 Month Average Plan, or the Blended Retirement System (BRS)? Understanding this is the first step toward securing your family’s financial future.
Next, gather your basic pay information. This means collecting either your final basic pay or the average of your highest 36 months of basic pay, depending on your pension plan. It’s important to have this information at hand for your family’s financial planning.
Now, let’s calculate your years of employment. Think about the total years of active work you’ve dedicated to serving your country. This is a crucial part of your retirement pay calculation.
Now, let’s use the appropriate formula to determine your retirement pay. This step is vital for understanding what you can expect in your post-service life:
- For Final Pay Plan:
Retired Pay = Final Basic Pay x 2.5% x Years of Service - For High-36 Month Average Plan:
Retired Pay = Average of Highest 36 Months Basic Pay x 2.5% x Years of Service - For Blended Retirement System:
Calculate your pension using the same formula as the High-36 Plan, and add any Thrift Savings Plan (TSP) contributions and matching funds.
Finally, consider the cost-of-living adjustments (COLA). It’s essential to remember that your pension pay may be adjusted annually based on inflation, impacting your family’s overall income. Staying informed about these adjustments can help you plan better for your loved ones.
By taking these steps, you’re not just calculating numbers; you’re laying the foundation for your family’s financial well-being.
Consider Factors Affecting Retirement Pay
Imagine the peace of mind that comes with knowing your family’s financial future is secure, even after military service. Understanding how much money do retired military make and how your military retirement pay is determined can feel overwhelming, but it’s essential for your family’s future.
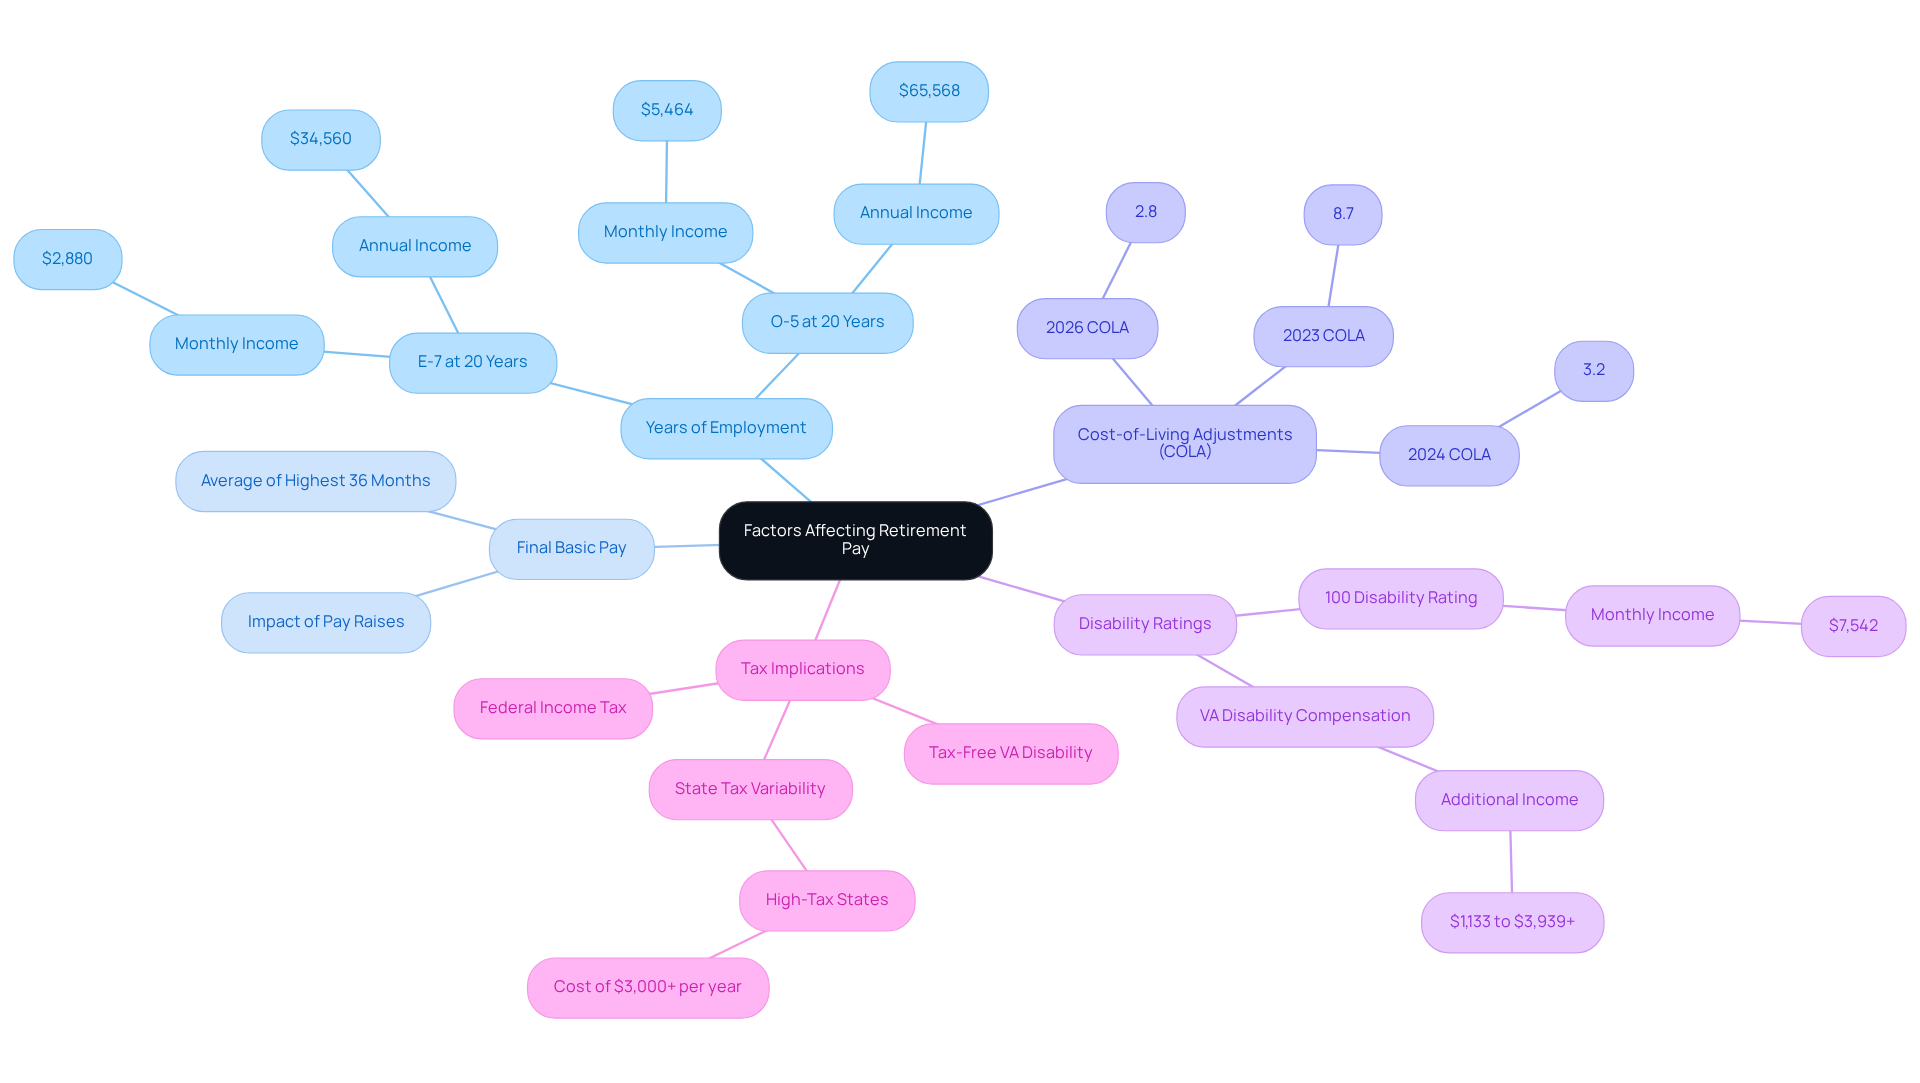
- Years of Employment: Think about the years you’ve dedicated to serving your country. Each year of service not only builds your experience but also directly affects how much money do retired military make in terms of pension compensation. For instance, an E-7 with 20 years of service earns approximately $2,880 per month, leading to the question of how much money do retired military make, which totals $34,560 annually.
- Final Basic Pay: Your retirement pay is linked to your final basic pay or the average of your highest 36 months of pay. Imagine the difference a few pay raises in your final years can make, especially when considering how much money do retired military make, significantly enhancing your income after leaving work.
- Cost-of-Living Adjustments (COLA): Imagine the relief of knowing that your retirement pay will adjust with the cost of living, helping you maintain your family’s lifestyle even as prices rise. For 2026, a 2.8% COLA has been announced, ensuring that benefits keep pace with rising costs.
- Disability Ratings: If you have service-connected disabilities, these can lead to adjustments in your pension pay based on your disability ratings. For instance, veterans with a 100% disability rating can experience a substantial increase in their total monthly income, leading to questions about how much money do retired military make, with some E-9 retirees attaining up to $7,542 per month when merging pension pay and VA disability compensation.
- Tax Implications: Understanding the tax treatment of your pension pay is crucial for effective financial planning. While military pension pay is subject to federal income tax, the tax consequences can differ by state, potentially costing retirees thousands each year based on their location. This is where the expertise of Bright Advisers becomes invaluable. By incorporating integrated tax planning strategies, families like Allison and Brian have successfully optimized their financial situations, ensuring they maximize their income during their later years while minimizing tax liabilities.
Together, by considering these factors and seeking expert advice, you can take meaningful steps toward securing a brighter financial future for your family, ensuring their needs are met with care and confidence.
Conclusion
Navigating military retirement pay can feel overwhelming, but it’s crucial for securing your family’s financial future. By familiarizing yourself with the various retirement pay systems, eligibility criteria, and calculation methods, you can make informed decisions that directly impact your financial well-being. This knowledge empowers you to navigate the complexities of military pensions with confidence, leading to a more stable and intentional approach to wealth management.
Key insights discussed include the three primary military retirement pay systems:
- The Final Pay Plan
- The High-36 Month Average Plan
- The Blended Retirement System (BRS)
Each of these systems has its own way of calculating benefits, and understanding them can really impact how much retirement pay you’ll receive. Additionally, factors such as years of service, final basic pay, cost-of-living adjustments, and disability ratings play crucial roles in determining your overall retirement income. By understanding these elements, you can better prepare for your financial future.
As you embark on this journey, it’s vital to seek guidance from trusted advisors who prioritize fiduciary duty and transparency, like Bright Advisers. By leveraging expert advice and personalized financial strategies, you can optimize your retirement benefits and ensure your financial needs are met for generations to come. By taking these steps, you’re not just planning for retirement; you’re investing in your family’s future happiness and security.
Frequently Asked Questions
What are the main military retirement pay systems?
The three key military retirement pay systems are the Final Pay Plan, the High-36 Month Average Plan, and the Blended Retirement System (BRS).
How does the Final Pay Plan work?
The Final Pay Plan applies to those who enlisted before September 8, 1980, and determines retired compensation based on the final basic salary at the end of service. The formula is: Retired Pay = Final Basic Pay x 2.5% x Years of Service.
What is the High-36 Month Average Plan?
The High-36 Month Average Plan is for those who joined after September 8, 1980. It calculates pension pay based on the average of the highest 36 months of basic pay using the formula: Retired Pay = Average of Highest 36 Months Basic Pay x 2.5% x Years of Service.
What is the Blended Retirement System (BRS)?
The Blended Retirement System, introduced in 2018, combines traditional pension elements with a 401(k)-style savings plan. It includes contributions to a Thrift Savings Plan (TSP) with matching contributions from the military. The pension multiplier under BRS is 2.0% per year of service.
Why is understanding these military retirement systems important?
Understanding these systems is crucial for ensuring financial security as you transition from military service to civilian life, helping you make informed decisions for your family’s future.
What is the processing time for military pension pay applications?
The average time to process pension pay applications is about 30 days, with a 99.9% success rate for direct deposit payments.
How many retired pay payments does the Department of Defense process monthly?
In FY 2023, the Department of Defense processed approximately 1.3 million retired pay payments each month.
List of Sources
- Understand Military Retirement Pay Systems
- Retirement (https://militarypay.defense.gov/pay/retirement)
- Military Retirement: 2026 Verified Stats & Trends (https://gitnux.org/military-retirement-statistics)
- Military Retirement Pay | Military.com (https://military.com/benefits/military-pay/retired-pay)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- Determine Eligibility for Retirement Pay
- Business News (https://m.economictimes.com/news/international/us/military-retirement-pay-increase-2026-how-much-military-retirement-pay-will-increase-in-2026-as-new-2-8-cola-takes-effect/amp_articleshow/125937511.cms)
- Military Retirement: Background and Recent Developments (https://congress.gov/crs-product/RL34751)
- Military Retirement: 2026 Verified Stats & Trends (https://gitnux.org/military-retirement-statistics)
- 2026 Military Retiree COLA Increase | First Command (https://firstcommand.com/coaching-center/financial-resources/military-retiree-cola)
- 2026 Military Retirement Pay Chart by Rank (3.8% Raise) (https://militaryretirementcalc.com/blog/2026-military-retirement-pay-chart)
- Calculate Your Military Retirement Pay
- Military Retirement Pay | Military.com (https://military.com/benefits/military-pay/retired-pay)
- How to Calculate Military Retirement Pay (2026 Formula) (https://militaryretirementcalc.com/blog/how-to-calculate-military-retirement-pay-2026)
- Military Retirement Calculator, Pay, Pension | Military OneSource (https://militaryonesource.mil/financial-legal/personal-finance/military-retirement-calculators)
- Military Retirement Pay Calculator – Veteran.com (https://veteran.com/military-retirement-calculators)
- Consider Factors Affecting Retirement Pay
- 2026 Military Retiree COLA Increase | First Command (https://firstcommand.com/coaching-center/financial-resources/military-retiree-cola)
- 2026 Military Retirement Pay Chart by Rank (3.8% Raise) (https://militaryretirementcalc.com/blog/2026-military-retirement-pay-chart)
- 2026 Military Retirement & VA Disability Rates: 3.8% & 2.8% Increases (https://militaryretirementcalc.com/blog/2026-military-retirement-va-disability-rates)
- Retirees, Veterans to Get 2.8% COLA in 2026 (https://ngaus.org/newsroom/retirees-veterans-get-28-cola-2026)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading