

Key Highlights
- Define retirement goals by visualising desired lifestyle, activities, and living arrangements.
- Assess current lifestyle expenses to determine how much should be saved for retirement.
- Set specific retirement goals, including retirement age and major purchases.
- Consider children’s future needs, such as education, when planning retirement savings.
- Engage in open discussions with partners about financial goals for alignment.
- Estimate monthly retirement expenses, accounting for inflation and potential changes.
- Identify diverse income sources for retirement, including Social Security and pensions.
- Calculate the gap between expected income and expenses to determine necessary savings.
- Establish a savings plan with a target amount for monthly pension contributions.
- Automate contributions and take advantage of employer matching to enhance savings.
- Regularly review and adjust the pension strategy to reflect changes in life circumstances.
- Consult with financial professionals for personalised advice and strategy adjustments.
Introduction
Imagine trying to figure out how much to save for your family’s future – it’s a daunting task, isn’t it? Together, we’ll explore how to define your retirement goals, assess what your family truly needs, and create a savings plan that fits your dreams. But with so many choices out there, how can you feel sure that you’re making the right decisions for your family’s future? Let’s dive into some essential strategies that can help you take charge of your pension planning, ensuring a secure and happy retirement for your family.
Define Your Retirement Goals and Lifestyle Needs
Imagine a future where your family thrives, free from financial worries in retirement. To begin planning for your pension, start by determining how much should I aim to have in my pension, along with defining your retirement goals and lifestyle needs. At Bright Advisers, we understand that every family is unique, and we’re here to help you create a financial plan that truly reflects your dreams and values. Consider the following steps:
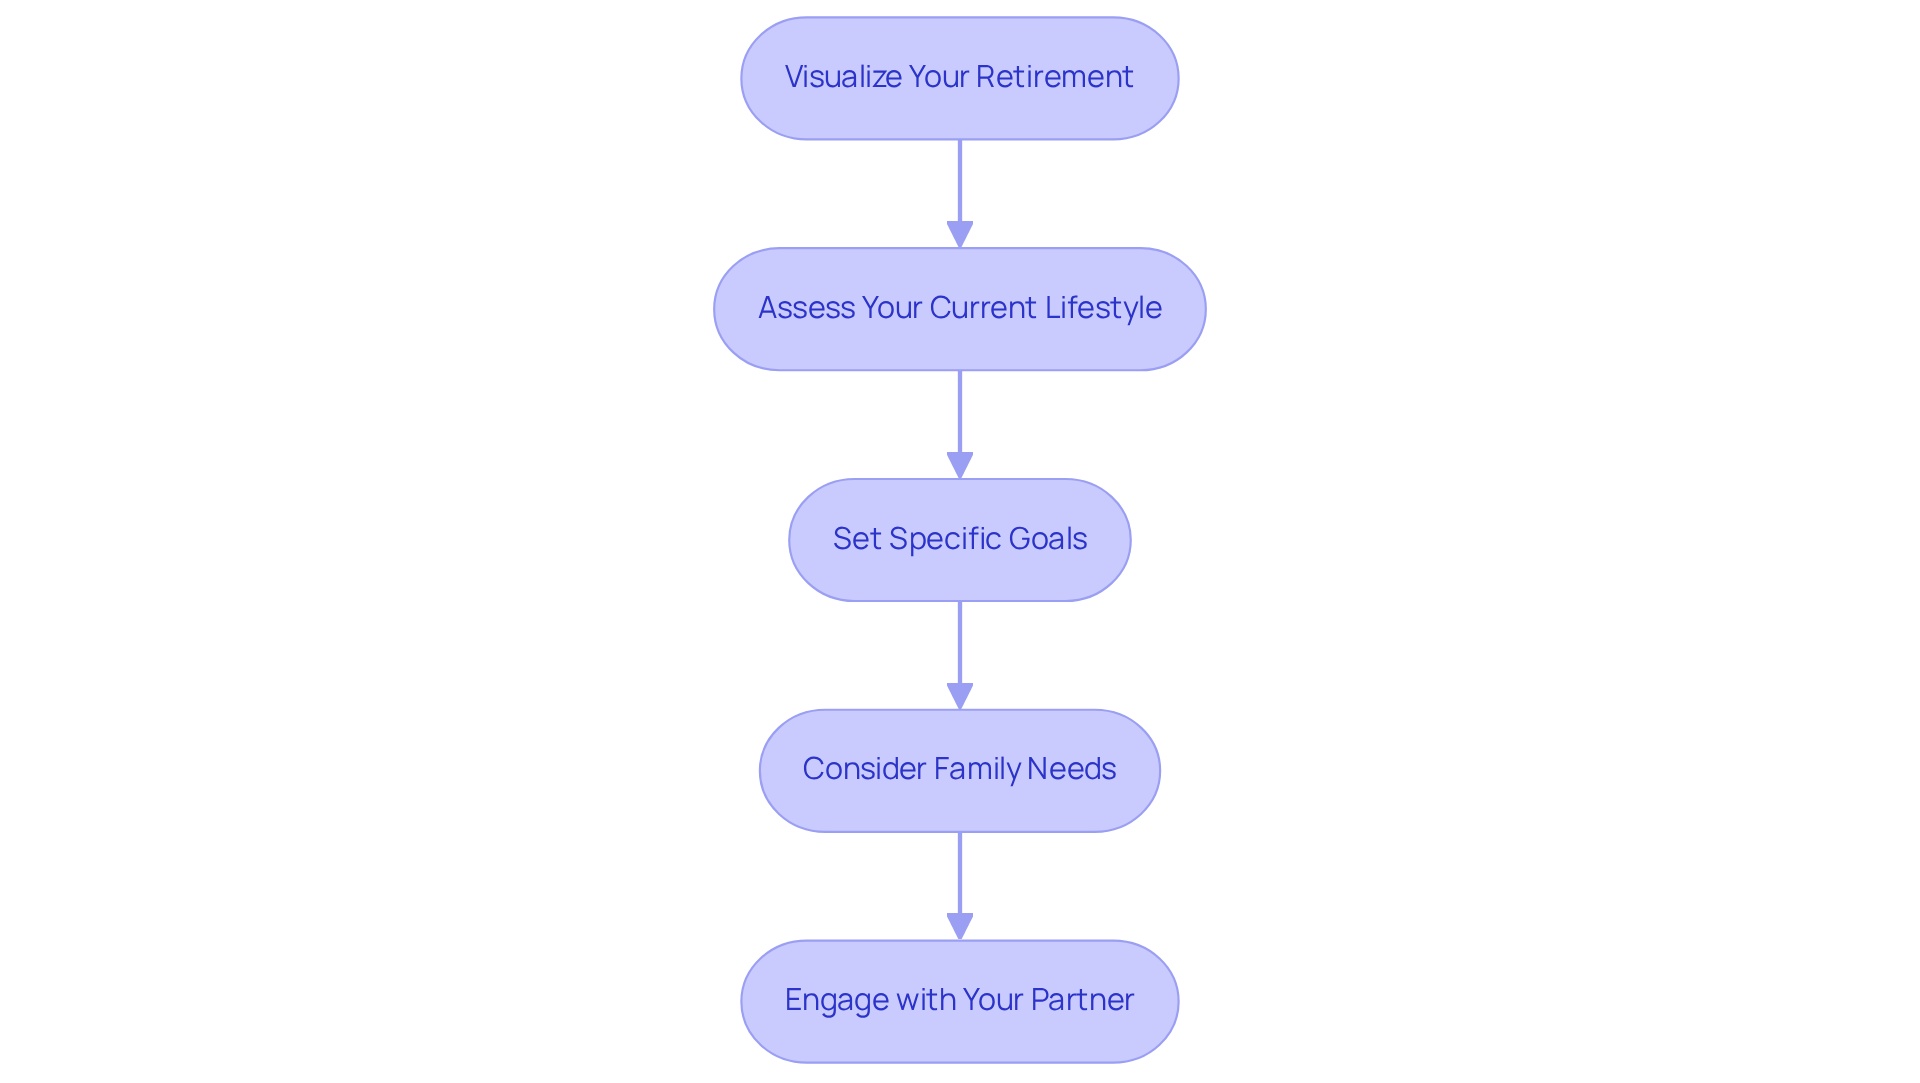
- Visualize Your Retirement: Think about where you want to live, what activities you want to pursue, and how you envision your daily life. This could include traveling, spending time with loved ones, or engaging in hobbies.
- Assess Your Current Lifestyle: Evaluate your current expenses and lifestyle. This will assist you in understanding how much should I aim to have in my pension to sustain your desired lifestyle after you stop working. We use innovative tools to tailor your financial plan, ensuring it’s cost-effective and aligned with your family’s needs.
- Set Specific Goals: Write down specific goals, such as the age you wish to retire, the type of home you want, and any major purchases you plan to make (like a vacation home). Many families find themselves surprised by the costs of retirement, which is why it’s crucial to determine how much should I aim to have in my pension for your peace of mind.
- Consider Family Needs: If you have children, think about their future needs, such as education or support during their early adult years. This can influence how much should I aim to have in my pension. We can help you create a comprehensive family financial strategy that includes budgeting, asset tracking, and tax planning to meet these needs. Additionally, our transparent fee structure ensures there are no hidden fees, commissions, or trade fees, allowing you to focus on your savings.
- Engage with Your Partner: If relevant, have an open conversation with your partner about your future financial goals to ensure alignment and shared understanding.
By clearly defining your retirement goals, you can create a more focused and effective savings strategy. By taking these steps, you’re not just planning for retirement; you’re investing in your family’s peace of mind for years to come. Bright Advisers is here to support you with innovative wealth management solutions designed for households with young children. Join our waitlist today to learn more about how we can help you secure your family’s financial future.
Disclaimer: All advisory services are provided through Lifeworks Advisors, a registered financial adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
Calculate Your Expected Retirement Expenses and Income Sources
Imagine planning for a future where your family’s needs are met without financial worry. To effectively calculate your expected retirement expenses and income sources, follow these steps:
-
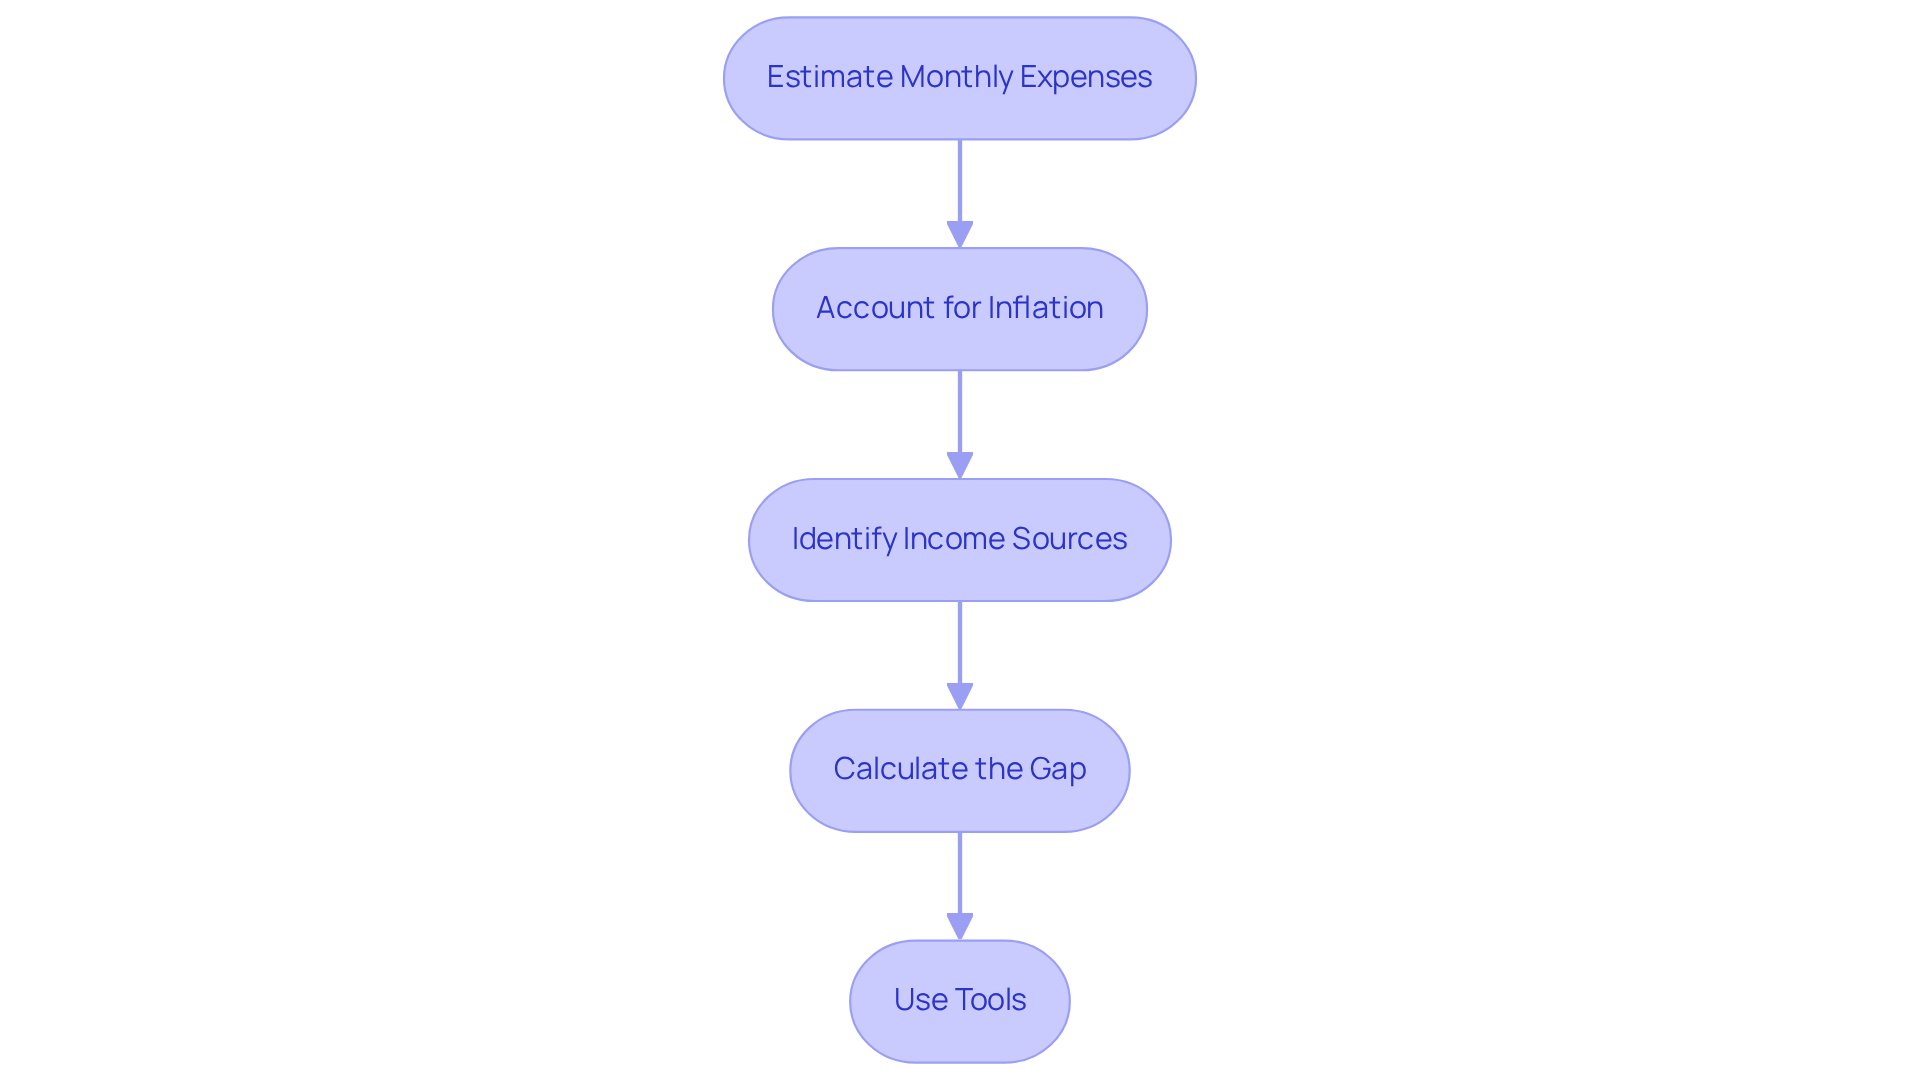
Estimate Monthly Expenses: Start by thinking about the monthly costs you might face in your later years. Consider including essentials like housing, healthcare, food, transportation, and even some fun activities. Use your current expenses as a baseline, adjusting for any changes you foresee. This is especially significant for young families like Jay and Emma, who want to ensure they can meet their children’s educational needs while also saving for the future.
-
Account for Inflation: It’s important to remember that costs will likely rise over time. Plan for an average inflation rate of 2.5-3% per year when estimating your expenses. For instance, a fixed $50,000 annual pension could decline to about $37,000 in purchasing power after just ten years of 3% inflation.
-
Identify Income Sources: Think about the different ways you might bring in income as you grow older. This encompasses Social Security, pensions, savings accounts (like 401(k)s and IRAs), and any other investments or rental income. In 2026, the average income for Americans aged 65 and older is projected to be $58,680 per year, highlighting the importance of diverse income streams. Understanding these sources can help reduce monetary anxiety by offering a clearer view of your future economic situation.
-
Calculate the Gap: Subtract your total expected income from your estimated expenses. This calculation will provide a clear picture of how much you need to save to cover any shortfall. For many families, finding extra income can be crucial to comfortably cover the average annual expenses of around $62,000. This step is essential in balancing immediate educational expenses with long-term financial objectives.
-
Use Tools: Consider utilizing online financial calculators to visualize your situation and adjust your estimates as needed. These tools can assist you in modeling various scenarios and better prepare for your future.
By carefully considering your expected expenses and income, you can gain a clearer picture of how much you need to save for a future where your family feels secure and comfortable. Bright Advisers provides customized wealth management solutions to assist families in navigating these complexities, ensuring that both future financial needs and children’s education are sufficiently funded. Please note that all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
Establish a Savings Plan and Contribute Regularly to Your Pension
Imagine the peace of mind that comes with knowing your family’s future is secure through careful financial planning. To ensure you are on track for retirement, establish a savings plan and commit to regular contributions:
-
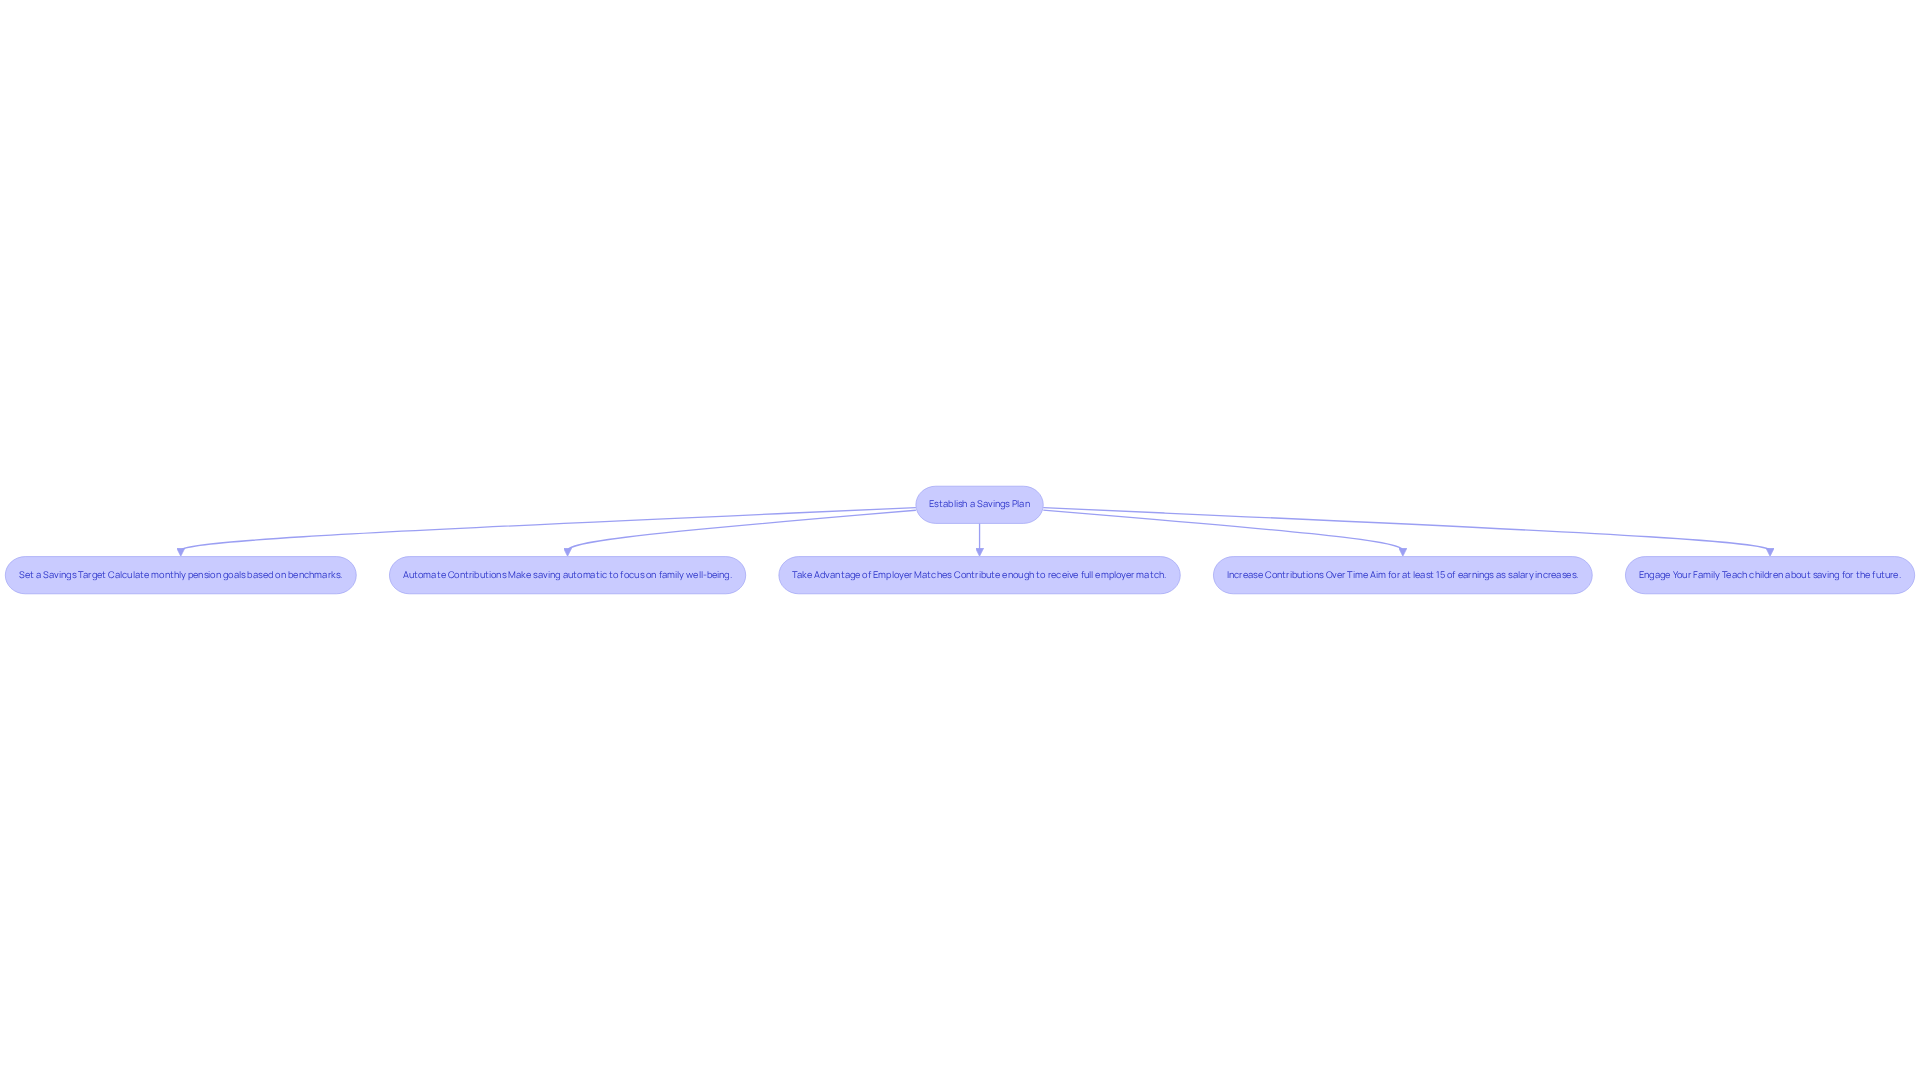
Set a savings target by calculating how much should I aim to have in my pension each month to achieve your financial goals. For context, the median savings for individuals aged 35-44 is approximately $39,958, while the average is $103,552. For those aged 45-54, the median is $115,000, and the average is $188,643. Knowing these benchmarks can help you set realistic targets.
-
Automate Contributions: By making saving automatic, you can focus on what truly matters-your family’s well-being-while effortlessly building your future.
-
Take Advantage of Employer Matches: If your employer offers a matching contribution to your pension plan, contribute enough to take full advantage of this benefit. This can greatly improve your savings, as employer matches can provide extra funds to your savings accounts.
-
Increase Contributions Over Time: As your salary increases or you receive bonuses, consider increasing your contributions. Experts suggest targeting at least 15% of your earnings if feasible, as this can contribute to a more stable future. Case studies indicate that individuals who maintain consistent contributions and diversify their accounts tend to achieve better outcomes.
-
Engage Your Family: Teach your children about the significance of saving for the future. This can instill good money habits early on and help them understand the value of long-term planning.
Many parents find it challenging to juggle daily expenses while also trying to save for their family’s future. By establishing a solid savings plan and contributing regularly, you can build a robust pension, which raises the question of how much should I aim to have in my pension to support your desired retirement lifestyle. Without a solid savings plan, you might face uncertainty when it comes to your family’s future needs. At Bright Advisers, we’re here to help you navigate the complexities of wealth management, ensuring your family has access to the best resources for a secure future. Our transparent fee structure means no hidden costs, allowing you to focus on what truly matters: securing your family’s future. Additionally, we employ strategies such as factor investing and smart beta to enhance your portfolio while avoiding costly mutual funds and ETFs. Please be aware that past performance does not ensure future outcomes, and all financial activities involve risks. For more information on our services, which are provided through Lifeworks Advisors, a registered investment adviser, please reach out. By taking these steps, you’re not just saving; you’re investing in your family’s dreams and aspirations for the future.
Review and Adjust Your Pension Strategy Regularly
Imagine feeling secure about your family’s financial future, knowing how much you should aim to have in your pension strategy is on track.
Make it a habit to regularly review and adjust how much should I aim to have in my pension strategy. Here are some gentle steps to guide you:
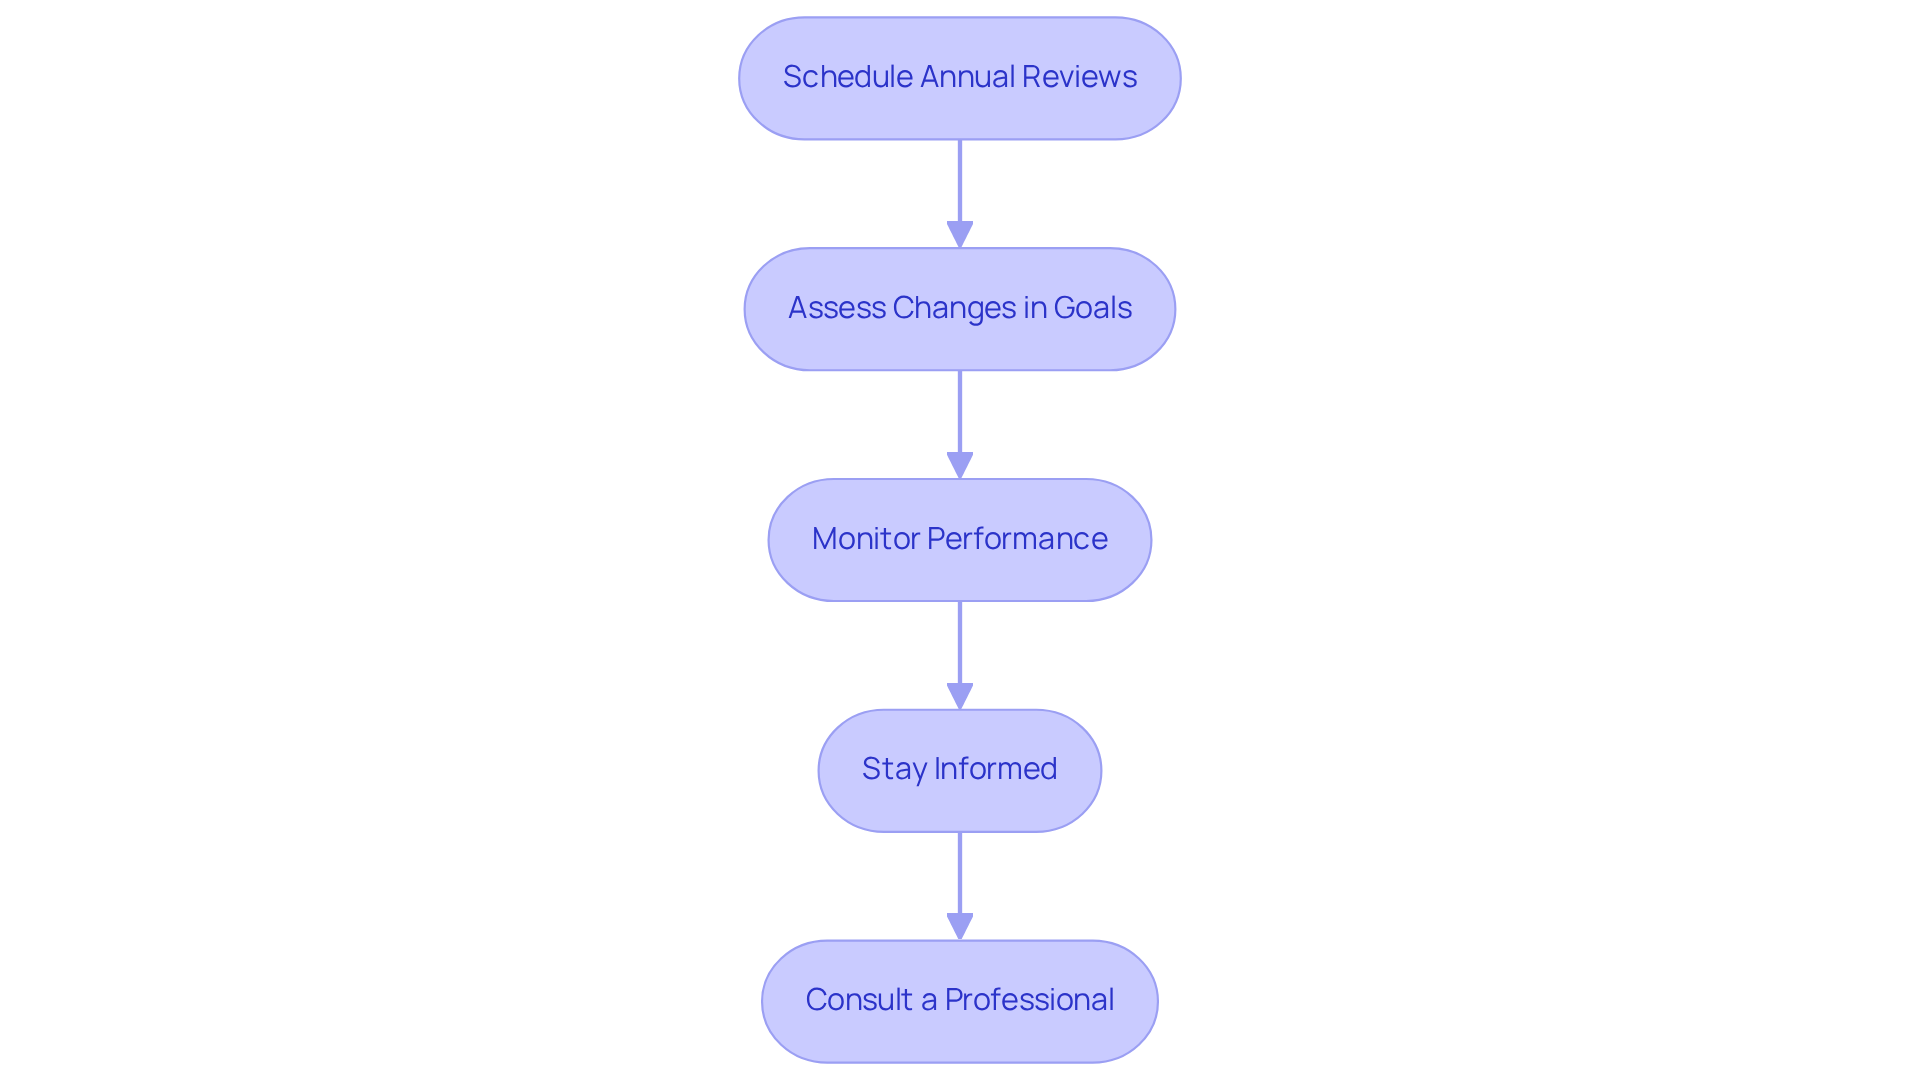
- Schedule Annual Reviews: Designate a specific time each year to assess your pension plan. Align it with your budget calendar or a significant date, like your birthday.
- Assess Changes in Goals: Life can change quickly-new jobs, growing families, or shifting financial priorities. Adjust your pension strategy to reflect these changes. For instance, Jay and Emma, a couple with two children, worked with Bright Advisers to create a financial strategy that helped them navigate their evolving goals while planning for their children’s education and their retirement.
- Monitor Performance: Regularly check how your assets are performing. If some of your investments aren’t doing well, think about moving your money to better options. Emily and Mark, both busy professionals, found that regular evaluations helped them maintain a clear understanding of their financial situation, enabling them to make informed choices about their investments.
- Stay Informed: Keep up with changes in pension regulations, tax laws, and market conditions that may impact your retirement savings. This knowledge empowers you to make informed decisions.
- Consult a Professional: If you’re uncertain about your pension strategy or need personalized advice, consider seeking guidance from a planner. At Bright Advisers, we’re here to help families like yours find the right path to financial stability and prepare for your children’s education.
Statistics show that 58% of private sector employees engaged in savings plans in 2022, a slight rise from earlier years. This highlights the importance of being proactive in financial planning. Families who consistently assess how much they should aim to have in their pension strategies are better equipped to adjust to financial shifts and reach their goals for the future. By regularly reviewing and adjusting your pension strategy, you can confidently navigate your family’s financial journey, ensuring a brighter future for your loved ones.
Disclaimer: Past performance does not guarantee future results. Securities holdings are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Imagine a future where your family’s dreams are secure and your financial worries are behind you. By understanding how much to aim for in your pension, families can create a solid foundation for a secure financial future. This guide emphasizes the importance of:
- Defining retirement goals
- Calculating expected expenses
- Establishing a savings plan
- Regularly reviewing pension strategies
Each step is designed to empower families to make informed decisions that align with their unique needs and aspirations.
Many families struggle to understand how to effectively plan for retirement. Key insights include:
- The necessity of visualizing retirement
- Estimating future expenses while accounting for inflation
- Identifying diverse income sources
Automating contributions and taking advantage of employer matches can significantly enhance savings. Regular reviews of your pension strategy ensure that families remain adaptable to life changes and market conditions, ultimately leading to a more stable financial outlook.
Planning for retirement is more than just crunching numbers; it’s about nurturing your family’s dreams and well-being. By taking proactive steps today, families can navigate the complexities of wealth management with confidence. We’re here to support you every step of the way, helping your family reach those important financial goals. Start planning now to ensure a prosperous future for your loved ones.
Frequently Asked Questions
What should I consider when defining my retirement goals?
You should visualize your retirement by thinking about where you want to live, the activities you want to pursue, and how you envision your daily life. This includes considering travel, spending time with loved ones, and engaging in hobbies.
How can I assess my current lifestyle for retirement planning?
Evaluate your current expenses and lifestyle to understand how much you should aim to have in your pension to sustain your desired lifestyle after you stop working. This assessment helps tailor your financial plan to be cost-effective and aligned with your family’s needs.
Why is it important to set specific retirement goals?
Setting specific goals, such as your desired retirement age, the type of home you want, and major purchases, is crucial because many families are surprised by retirement costs. Clearly defined goals help determine how much you should aim to have in your pension for peace of mind.
How do family needs influence retirement planning?
If you have children, consider their future needs, such as education or support during their early adult years. These factors can influence how much you should aim to have in your pension. A comprehensive family financial strategy can help address these needs.
Should I discuss retirement goals with my partner?
Yes, it is important to have an open conversation with your partner about your future financial goals to ensure alignment and shared understanding.
How can Bright Advisers assist with retirement planning?
Bright Advisers offers innovative wealth management solutions designed for households with young children, helping you create a financial plan that reflects your dreams and values. They provide tools for budgeting, asset tracking, and tax planning.
What is the fee structure for services provided by Bright Advisers?
Bright Advisers has a transparent fee structure with no hidden fees, commissions, or trade fees, allowing you to focus on your savings.
What disclaimer should I be aware of regarding advisory services?
All advisory services are provided through Lifeworks Advisors, a registered financial adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
List of Sources
- Define Your Retirement Goals and Lifestyle Needs
- How much will you spend in retirement? | Fidelity (https://fidelity.com/viewpoints/retirement/spending-in-retirement)
- Average Retirement Savings by Age | Guardian (https://guardianlife.com/retirement/savings-by-age)
- 50+ Essential Retirement Statistics for 2026: Demographics & More (https://annuity.org/retirement/retirement-statistics)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- 106 Revealing Retirement Statistics – Curio Wealth (https://curiowealth.com/106-revealing-retirement-statistics)
- Calculate Your Expected Retirement Expenses and Income Sources
- Monthly Costs for Retirees: What Americans 65 and Older Spend on Housing, Food, Transportation, and Healthcare (https://investopedia.com/monthly-costs-for-retirees-what-americans-65-and-older-spend-on-housing-food-transportation-and-healthcare-12004334)
- How Inflation Impacts Your 2026 Financial Plan and What to Adjust | Brogan Financial (https://broganfinancial.com/inflation-impact-2026-financial-plan)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- Retirement Cost Trends 2026 | SafeMoney.com (https://safemoney.com/retirement-statistics/retirement-cost-trends-2026)
- Average Retirement Income 2026: By Age, State & Source (https://randallwealthgroup.com/average-retirement-income)
- Establish a Savings Plan and Contribute Regularly to Your Pension
- Average Retirement Savings By Age In 2026 And How To Catch Up | July Edition (https://forbes.com/sites/investor-hub/article/average-retirement-savings-age-how-to-catch-up)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- Median Retirement Savings by Age (https://synchrony.com/blog/bank/median-retirement-savings-by-age)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- Average retirement savings by age (https://empower.com/the-currency/money/average-retirement-savings-by-age)
- Review and Adjust Your Pension Strategy Regularly
- Has Pension Participation in the Private Sector Improved? – Center for Retirement Research (https://crr.bc.edu/has-pension-participation-in-the-private-sector-improved)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- Annual Survey of Public Pensions (ASPP) (https://census.gov/programs-surveys/aspp.html)
- National Data | Public Plans Data (https://publicplansdata.org/quick-facts/national)
- 106 Revealing Retirement Statistics – Curio Wealth (https://curiowealth.com/106-revealing-retirement-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading