

Key Highlights
- Pension drawdown allows access to retirement savings starting at age 55, increasing to 57 in 2028.
- Up to 25% of the retirement fund can be withdrawn tax-free, with the remaining 75% subject to income tax.
- Withdrawal strategies enable investment growth, unlike fixed annuities, potentially increasing retirement income.
- Families should assess monthly expenses, future costs, and set monetary goals to determine drawdown amounts.
- Understanding the type of retirement plan (defined contribution vs. defined benefit) is crucial for making informed decisions.
- The 4% rule suggests withdrawing about 4% of savings annually to sustain income over time.
- Tax implications should be considered when withdrawing funds to avoid higher tax brackets.
- Regularly reviewing financial situations and adjusting withdrawals based on market performance is essential for sustainability.
- Engaging with a fiduciary advisor like Bright Advisers can provide personalised guidance and ensure transparency in fees.
- Families are encouraged to stay informed about tax changes and maintain communication with their financial advisor for optimal planning.
Introduction
Imagine feeling secure about your family’s financial future as you approach retirement. Understanding how to draw down from a pension effectively can be a crucial part of that journey, especially for families like yours who want to ensure a stable financial future. This guide gently explores essential strategies and considerations for determining the right withdrawal amounts. We want to help you maintain your desired lifestyle while allowing your investments to grow.
It’s important to understand that with market fluctuations and personal goals, navigating pension drawdown can feel overwhelming. But together, we can find a way to ensure your family’s long-term security. By addressing these complexities, you can make informed decisions that align with your family’s values and aspirations.
Understand Pension Drawdown Basics
Imagine the relief of knowing you can access your retirement savings when you need them most, while still allowing your investments to grow. Let’s explore some key points that can help you navigate this important decision:
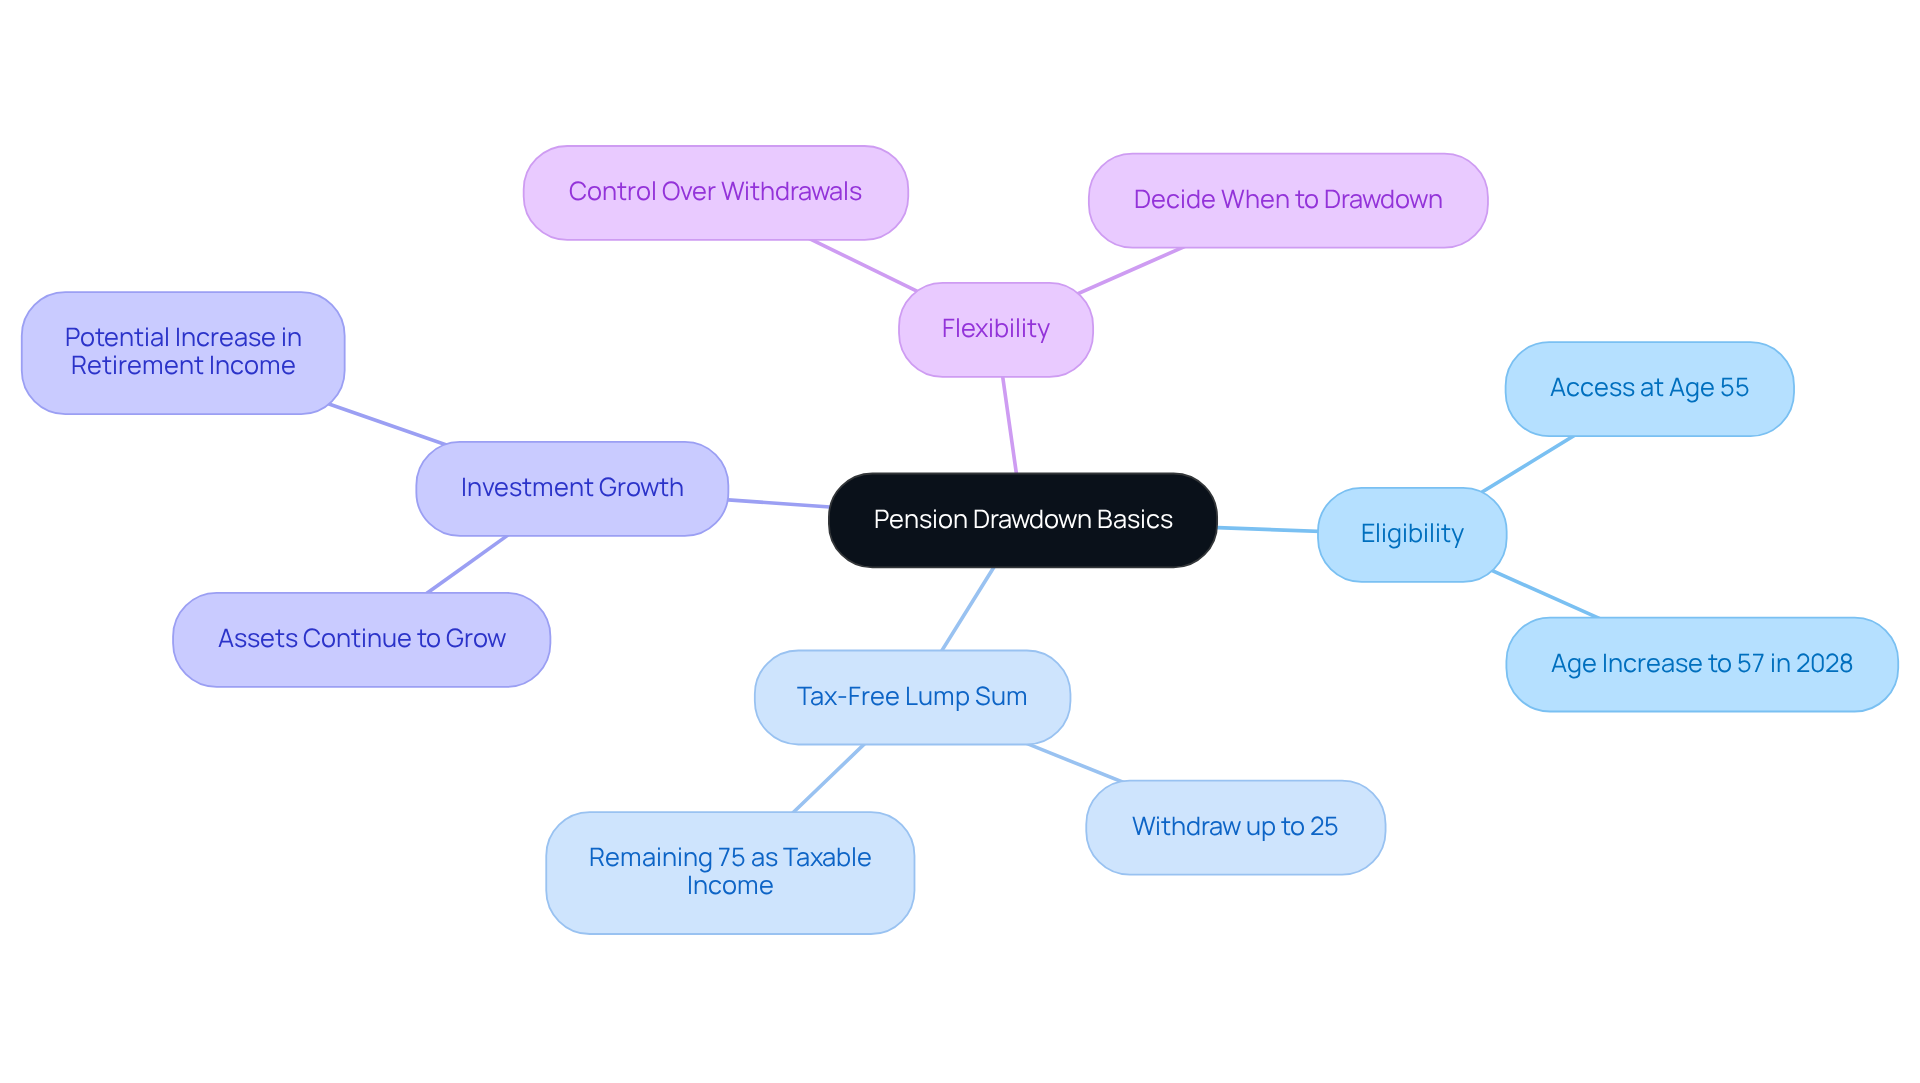
- Eligibility: Generally, you can access your pension through drawdown once you reach 55 years old, with the age increasing to 57 starting in 2028.
- Tax-Free Lump Sum: Typically, you can withdraw up to 25% of your retirement fund as a tax-free lump sum. The remaining 75% can be drawn down as income, which will be subject to income tax.
- Investment Growth: Unlike annuities, where you exchange your retirement fund for a fixed income, withdrawal enables your remaining assets to keep growing, potentially increasing your retirement income over time.
- Flexibility: Flexibility gives you the ability to decide how much should you drawdown from your pension and when, providing you with greater control over your retirement finances.
With this knowledge, you can approach your retirement planning with confidence, knowing support is available every step of the way.
Assess Your Financial Needs and Goals
Imagine the peace of mind that comes from knowing your family’s financial future is secure. Before deciding how much should I drawdown from my pension, it’s important to evaluate your monetary needs and goals. Here’s a gentle approach to guide you:
-
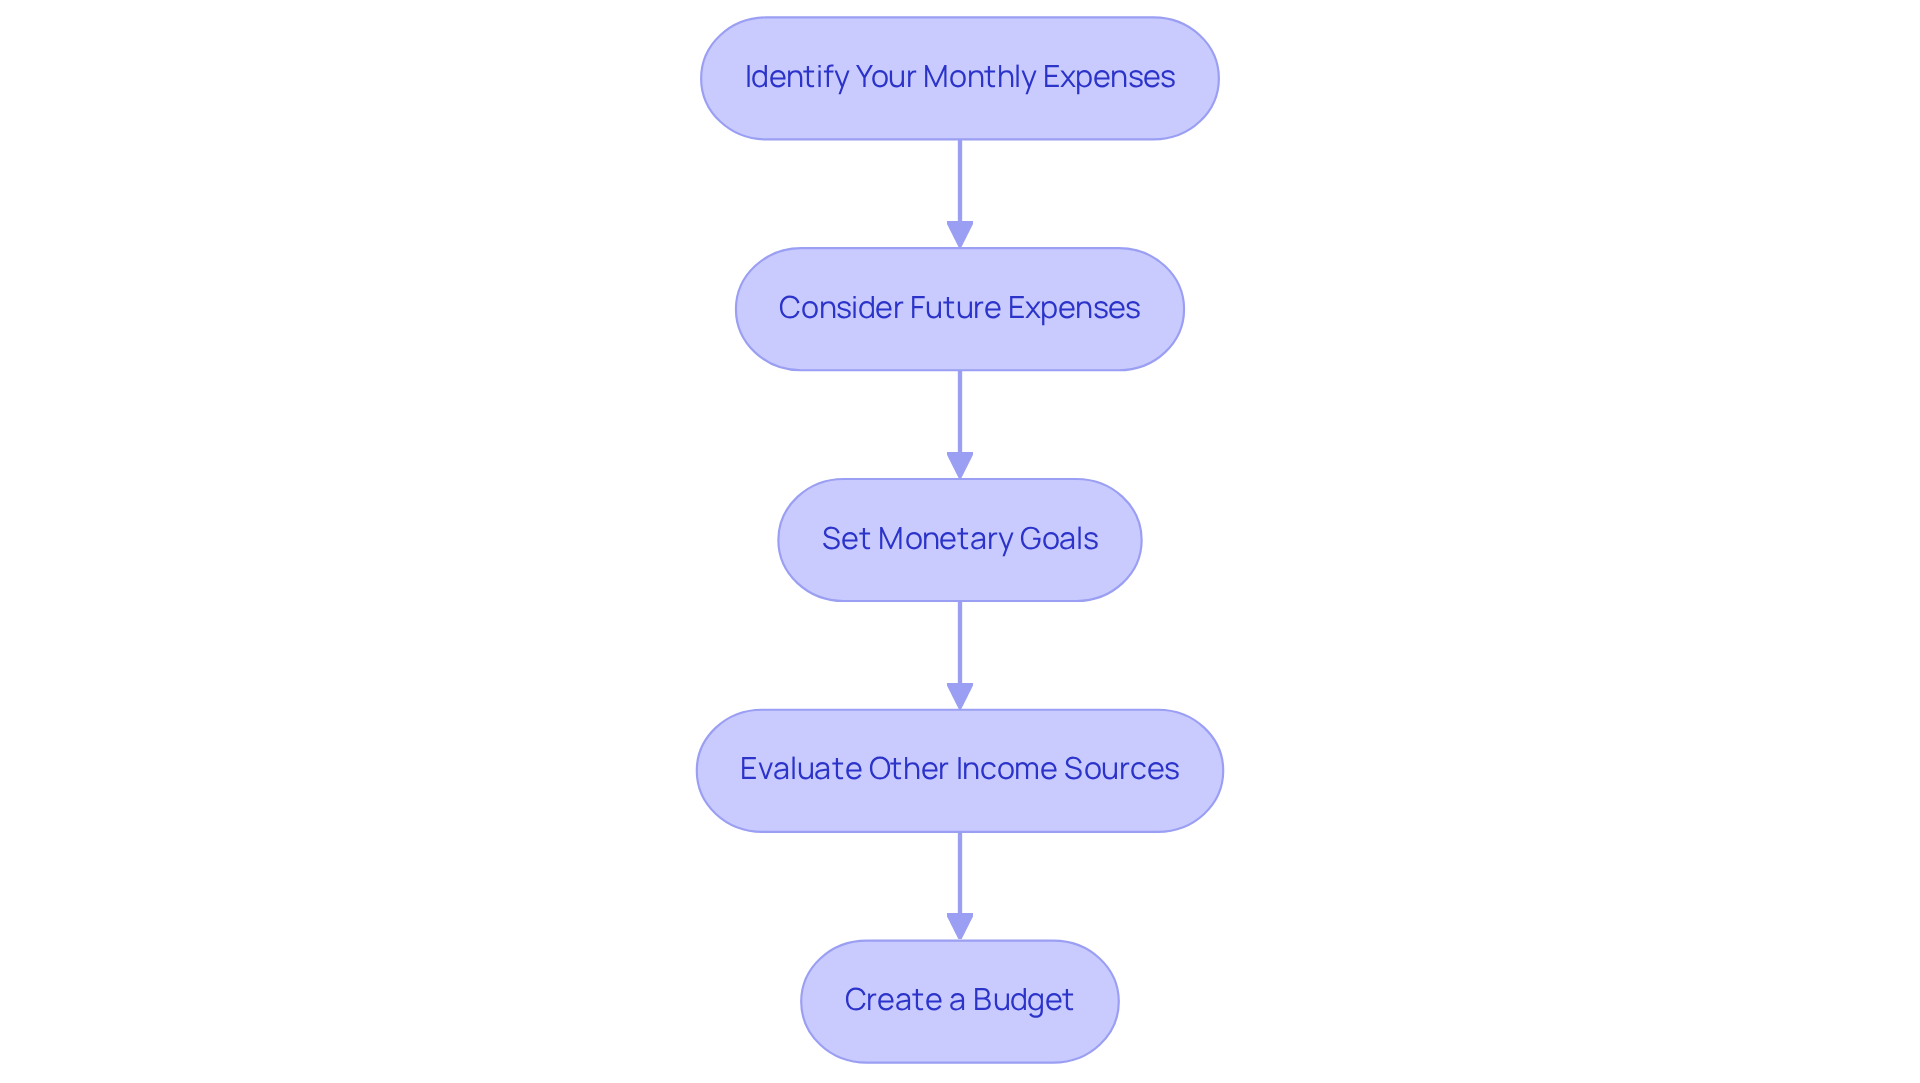
Identify Your Monthly Expenses: Start by calculating your essential monthly expenses, which include housing, utilities, groceries, and healthcare. In Southern California, families typically face average monthly expenses of around $5,630, which serves as a helpful baseline for your income needs.
-
Consider Future Expenses: Think about upcoming costs like your children’s education or family vacations. These future expenses should be part of your budgeting to ensure you’re well-prepared.
-
Set Monetary Goals: Clearly define your short-term and long-term monetary objectives. Whether you dream of traveling, saving for your children’s education, or leaving a legacy, understanding your goals will help you determine the necessary withdrawal amounts.
-
Evaluate Other Income Sources: Take a moment to assess any additional income streams you may have, such as Social Security, rental income, or part-time work. This assessment will clarify how much should I drawdown from my pension.
-
Create a Budget: Develop a budget that aligns with your monetary goals and needs. This budget will act as a guide for your withdrawal plan, ensuring you maintain economic stability during retirement.
With careful planning, you can ensure your family’s dreams are within reach, allowing you to focus on what truly matters – your loved ones.
Evaluate Your Pension Options and Strategies
Navigating your retirement options can feel overwhelming, but understanding your choices is the first step toward securing your family’s future. Here’s how to approach it:
-
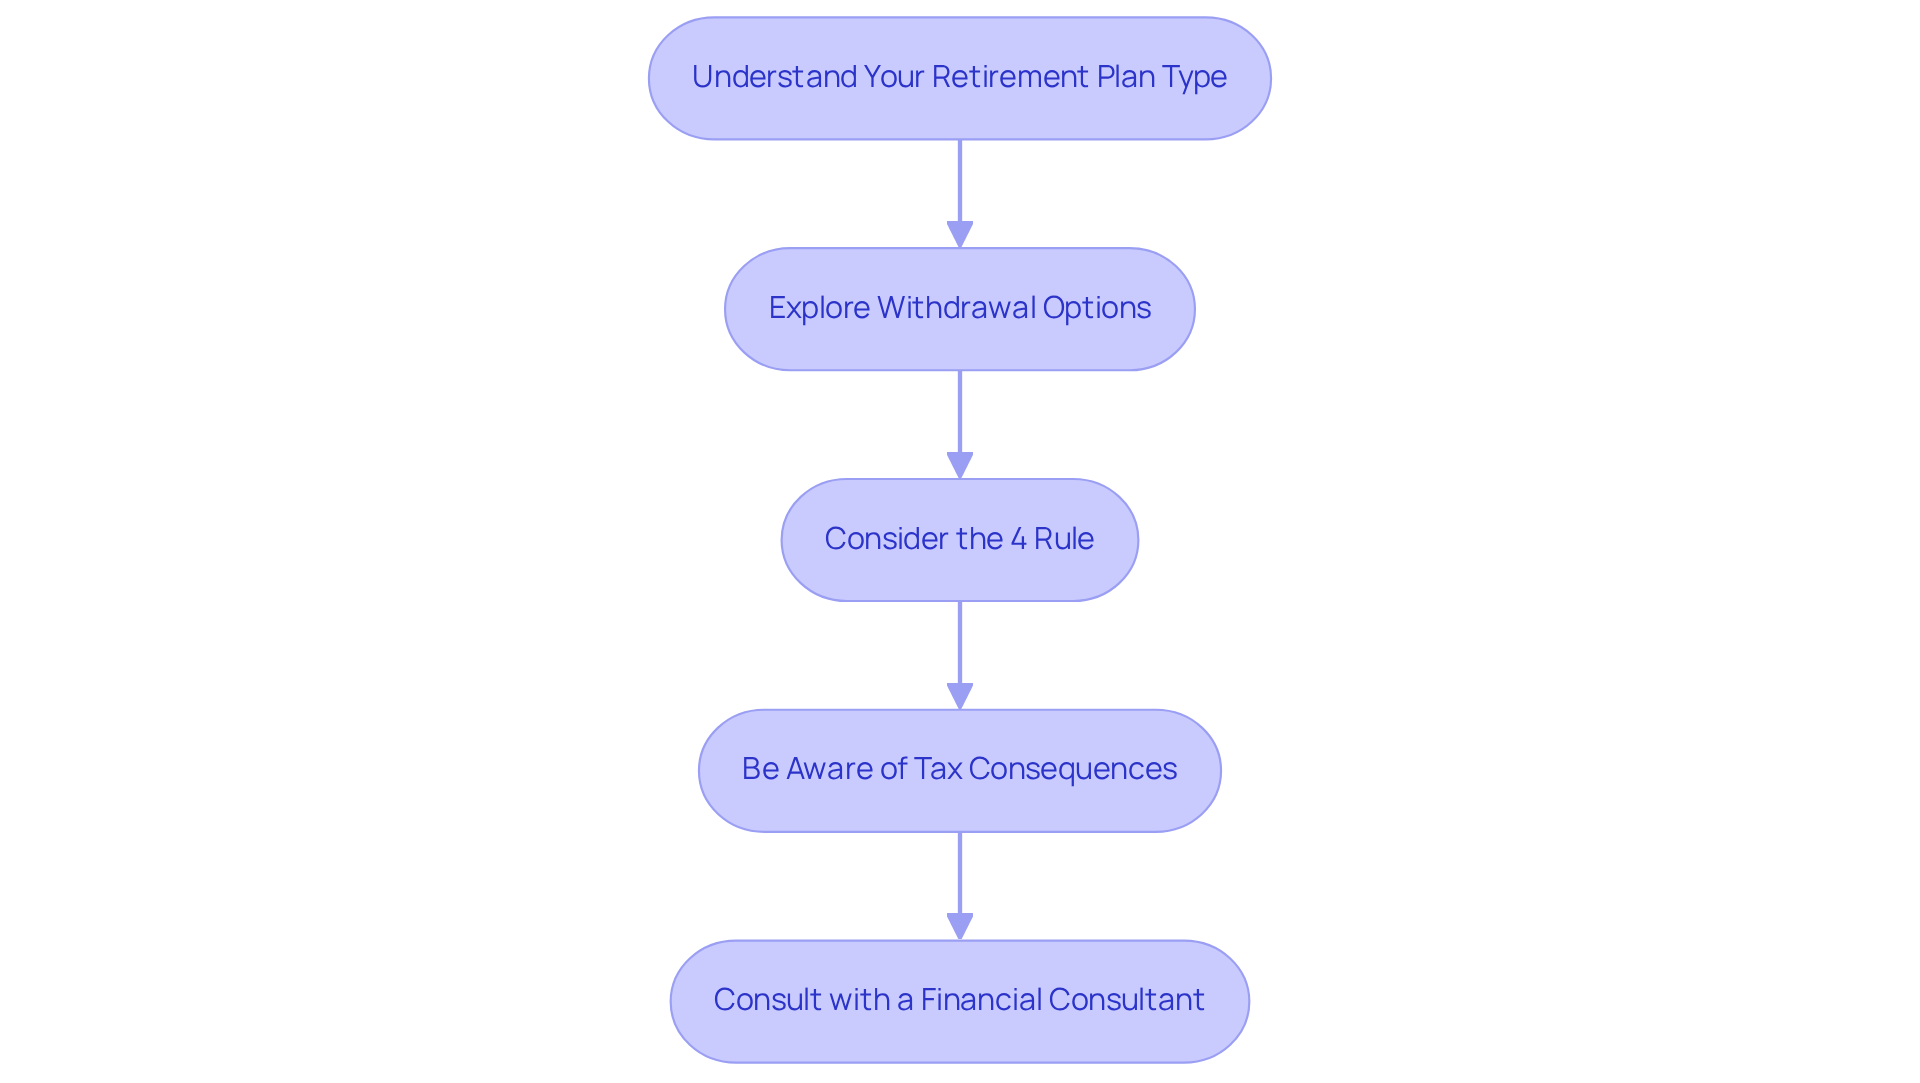
Understand Your Retirement Plan Type: Knowing whether you have a defined contribution (DC) or defined benefit (DB) plan is crucial. Understanding this difference can really help you make the best choices for your family’s future. DB plans guarantee a specific payout based on salary and tenure, while DC plans depend on your contributions and how well your investments perform.
-
Explore Withdrawal Options: Take some time to look into the different withdrawal options your pension provider offers. Some plans might let you withdraw funds as you need them, while others may have rules about when and how much you should draw down from your pension to access your money.
-
Consider the 4% Rule: One helpful guideline is the 4% rule, which means you can withdraw about 4% of your savings each year to help your money last longer. This approach aims to balance your income needs with the longevity of your savings, addressing the question of how much you should draw down from your pension to give you peace of mind.
-
It’s important to be aware of the tax consequences when considering how much you should draw down from your pension. Taking out a large amount in one year could push you into a higher tax bracket. Think about taking smaller amounts over a few years to keep your taxes lower and make things easier on your family. Bright Advisers combines tax planning techniques to help families like Jay and Emma optimize their tax situations while preparing for their children’s education and their retirement.
-
Consult with a Financial Consultant: Working with a fiduciary consultant can provide personalized insights tailored to your family’s unique financial situation. The advisors at Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, focus on transparency and charge simple, customizable monthly fees with no hidden costs. They can guide you through complex choices and help you align your pension income with your retirement goals. For instance, Emily and Mark collaborated with Bright Advisers to create a thorough financial plan that not only concentrated on their retirement but also offered them the freedom to decide whether or not to keep working.
Evaluating your options carefully will empower you to make informed decisions that support your financial well-being. With the right guidance, you can confidently shape a retirement plan that supports your family’s dreams and aspirations.
Monitor and Adjust Your Drawdown Strategy
Imagine feeling secure about your retirement income, knowing you’ve made the right choices for your family’s future. After implementing your drawdown strategy, it’s essential to actively monitor and adjust how much you should drawdown from your pension to ensure sustainability. Here’s how to effectively manage your pension drawdown:
-
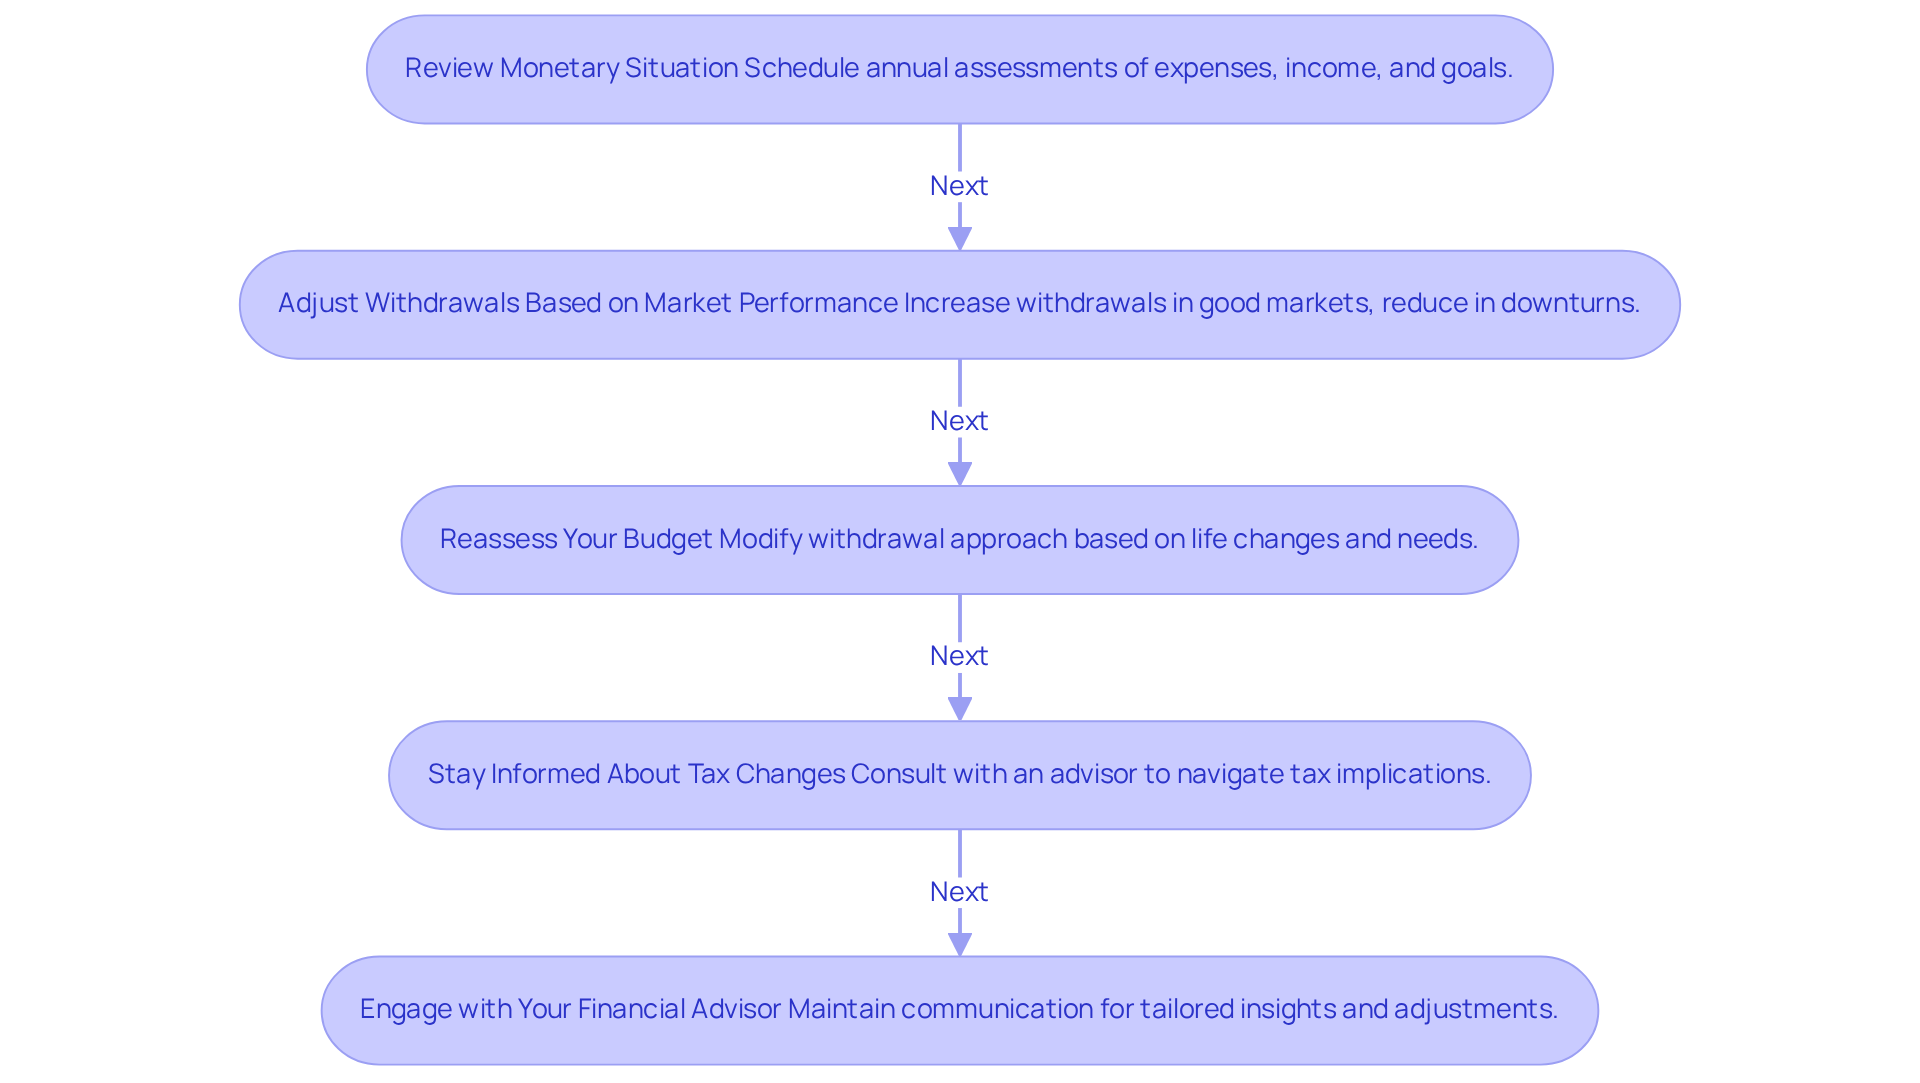
Regularly Review Your Monetary Situation: Schedule annual assessments of your economic status, focusing on expenses, income, and any shifts in your monetary goals. This way, you can adapt to what your family truly needs as life changes. For example, families such as Jay and Emma have gained from regular evaluations, enabling them to enhance their economic plans and lessen stress.
-
Adjust Withdrawals Based on Market Performance: But what happens when the market takes a downturn? It can be tough to know how much should I drawdown from my pension without feeling anxious about your future. If your investments perform well, you might consider increasing your withdrawals. Conversely, during market downturns, reducing withdrawals can help preserve your capital and maintain your financial stability. It’s important to understand how much should I drawdown from my pension, as withdrawing too much during tough times can force you to sell investments at a loss, which can be stressful for your family.
-
Reassess Your Budget: Life changes, such as children growing up or employment shifts, necessitate a reassessment of your budget. Modify your withdrawal approach to incorporate how much should I drawdown from my pension, ensuring it remains relevant to your current circumstances. Remember, 63.1% of participants report stress related to budgeting, so staying proactive can alleviate some of that pressure. Emily and Mark, for example, worked with Bright Advisers to create a budget that accommodates their career ambitions and family needs.
-
Stay Informed About Tax Changes: Ignoring tax changes could mean missing out on opportunities to keep more of your hard-earned money for your family. Tax laws can affect your drawdown approach significantly. Stay informed about any changes that may impact your withdrawals, and consult with an advisor to navigate these complexities effectively. Bright Advisers incorporates tax planning into its offerings, assisting families such as Allison and Brian in maximizing their financial potential through efficient tax approaches.
-
Engage with Your Financial Advisor: Maintain regular communication with your advisor at Bright Advisers. They can offer customized insights and modifications based on market conditions and your individual circumstances, ensuring your approach aligns with your long-term objectives. Additionally, understanding the importance of guaranteed income sources, such as Social Security, can significantly impact your retirement planning.
By taking these steps, you’re not just planning for retirement; you’re ensuring a brighter future for your loved ones. Keep in mind that the sustainable withdrawal rate for 2026 is estimated at 3.9%, which can serve as a helpful benchmark as you plan your withdrawals. Remember, Bright Advisers is dedicated to offering clear, all-encompassing fee structures with no concealed charges, ensuring that families can access the wealth management services they require to secure their economic future.
Conclusion
It can feel overwhelming to figure out how much to take from your pension, especially when you think about your family’s future. By understanding the basics of pension drawdown and keeping an eye on your family’s needs, you can make choices that feel right for your future.
It’s important to know what you’re eligible for and how taxes can affect your choices, so you can feel confident in your decisions. Take a moment to think about your monthly expenses and what your family might need in the future; setting clear goals can help guide you. Learning about different pension plans and how to withdraw funds wisely can help your savings last longer.
This journey is about more than just finances; it’s about ensuring your loved ones are taken care of and finding peace in your choices. Working with a caring advisor like Bright Advisers can give you the support you need to navigate these important decisions. When you have clear and personalized strategies, you can feel more confident about your retirement planning and the future you’re building for your family.
If you need help, don’t hesitate to reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967. We’re here for you and ready to help secure your family’s financial future.
Frequently Asked Questions
What is pension drawdown?
Pension drawdown is a method that allows you to access your retirement savings while still allowing your investments to grow.
When can I access my pension through drawdown?
Generally, you can access your pension through drawdown once you reach 55 years old, but this age will increase to 57 starting in 2028.
How much of my retirement fund can I withdraw tax-free?
You can typically withdraw up to 25% of your retirement fund as a tax-free lump sum.
What happens to the remaining 75% of my retirement fund?
The remaining 75% can be drawn down as income, which will be subject to income tax.
How does pension drawdown differ from annuities?
Unlike annuities, where you exchange your retirement fund for a fixed income, drawdown allows your remaining assets to keep growing, potentially increasing your retirement income over time.
What flexibility does pension drawdown offer?
Pension drawdown provides you with the flexibility to decide how much to withdraw from your pension and when, giving you greater control over your retirement finances.
List of Sources
- Understand Pension Drawdown Basics
- UK Retirement Stats 2024 (https://equityreleasewarehouse.com/data/uk-retirement-stats)
- 10 Powerful Quotes from Financial Gurus on the Importance of Saving for Retirement (https://linkedin.com/pulse/10-powerful-quotes-from-financial-gurus-importance-saving-majmudar)
- Analysis of Future Pension Incomes 2025 (https://gov.uk/government/statistics/analysis-of-future-pension-incomes-2025/analysis-of-future-pension-incomes-2025)
- Living Well in Retirement (https://oprah.com/money/suze-ormans-advice-on-saving-for-retirement)
- Assess Your Financial Needs and Goals
- Cost of Living in California (https://sofi.com/cost-of-living-in-california)
- Average Monthly Expenses by Category – NerdWallet (https://nerdwallet.com/finance/learn/monthly-expenses-single-person-family)
- Cost of Living in Los Angeles 2026: Complete Expense Guide (https://randallwealthgroup.com/cost-of-living-in-la)
- The 2026 Average Cost of Living by State, and Why Ignoring it Could Sink Your Business (https://patriotsoftware.com/blog/accounting/average-cost-living-by-state)
- California Housing Affordability Tracker (1st Quarter 2026) [EconTax Blog] (https://lao.ca.gov/LAOEconTax/Article/Detail/793)
- Evaluate Your Pension Options and Strategies
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- Individuals’ challenges managing pensions through retirement | Institute for Fiscal Studies (https://ifs.org.uk/publications/individuals-challenges-managing-pensions-through-retirement)
- Are Pensions Dead? Comparing Defined Benefit Plans to Defined Contribution Plans (https://wealthtender.com/insights/defined-benefit-vs-defined-contribution)
- Pensions and California Public Schools, 2026 | Getting Down to Facts (https://gettingdowntofacts.com/reports/pensions-and-california-public-schools-2026)
- Monitor and Adjust Your Drawdown Strategy
- Building a retirement drawdown strategy: Key considerations (https://home.saxo/learn/guides/personal-finance/building-a-retirement-drawdown-strategy-key-considerations)
- Retirement Market Outlook | T. Rowe Price (https://troweprice.com/en/us/insights/retirement-market-outlook)
- What Market Volatility in 2026 Means for Retirement Income Planning (https://hffinancial.com/market-volatility-2026-retirement-income-planning)
- Reach your financial goals with the experts in wealthcare (https://ellevest.com/magazine/questions-money-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading