

Overview
Understanding how much to pay in investment fees is essential for your family’s financial well-being. These charges can greatly affect your overall returns. Traditional advisors typically charge between 0.75% and 1.5% of assets under management. In contrast, index funds offer lower fees, ranging from 0.05% to 0.25%. Imagine if even small differences in fees could lead to substantial losses over time. For instance, a portfolio with a 1.5% expense ratio might yield over $73,000 less than one with a 0.1% ratio after 20 years.
It’s important to understand that these fees can add up, impacting your family’s future. By being aware of the costs involved, you can make informed decisions that align with your family’s financial goals. We’re here for you, ready to help you navigate this journey and ensure that your investments work hard for you and your loved ones. Together, we can build a brighter financial future.
Key Highlights:
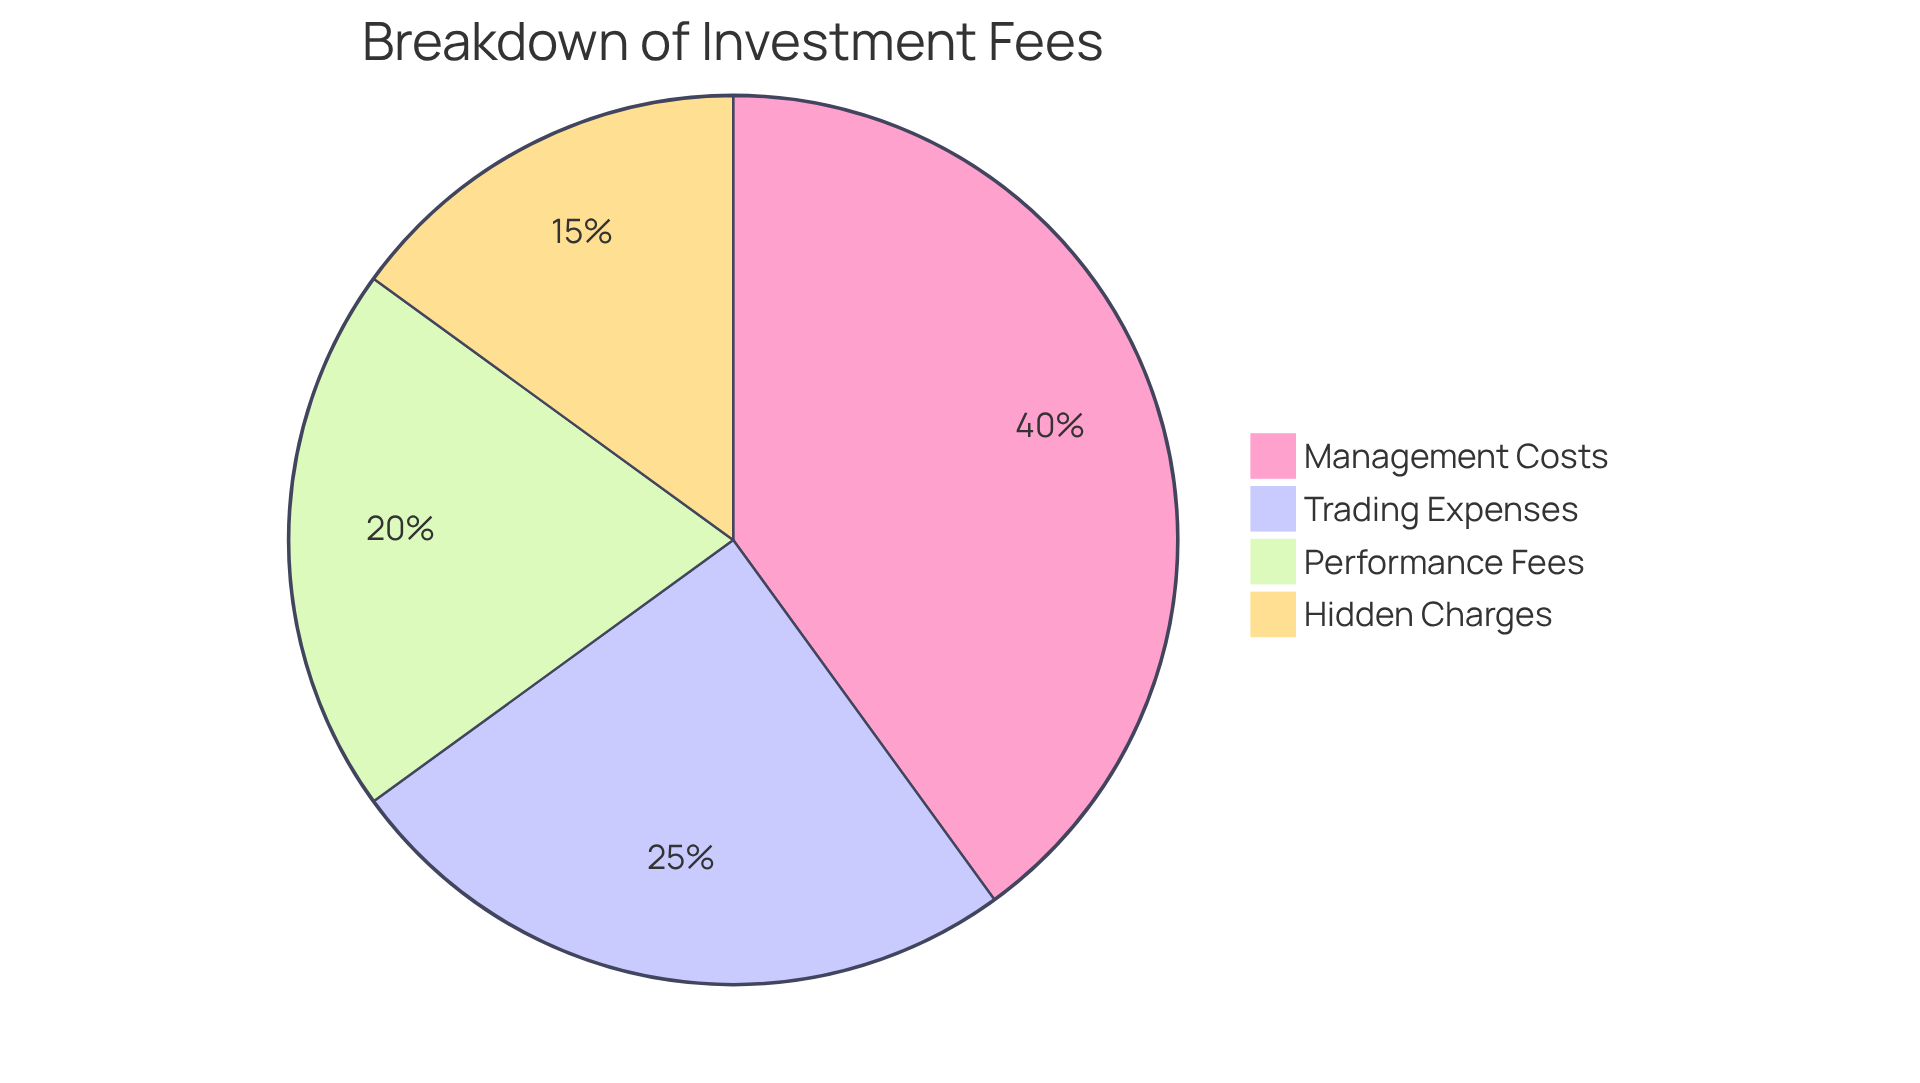
- Investment fees encompass management costs, trading expenses, and performance fees, significantly affecting overall returns.
- Traditional financial advisors charge between 0.75% and 1.5% of assets under management, while index funds have lower expense ratios of 0.05% to 0.25%.
- A portfolio with a 1.5% expense ratio can yield over $73,000 less than one with a 0.1% ratio after 20 years.
- Hidden charges like custodial fees and inactivity charges can further reduce investment returns.
- Management fees for investment funds typically exceed 1%, with actively managed funds averaging 0.42% and passive funds at 0.05%.
- Trading charges can accumulate quickly, particularly for frequent investors, ranging from $1 to $5 per trade.
- Expense ratios reflect annual operational costs; the median for mutual funds in 401(k) plans was 1.27% in 2010.
- Families may lose significant amounts to fees over their lifetimes, with median-income households potentially forfeiting nearly $155,000.
- To evaluate financial situations, individuals should assess existing holdings, total investment costs, and align fees with personal financial goals.
- Negotiating fees with financial advisors can lead to substantial savings; typical advisor fees range from 0.59% to 1.18% of assets under management.
Introduction
Understanding investment fees is crucial for safeguarding your family’s financial future. Yet, many investors, especially young parents, find themselves in the dark about how these costs can erode their returns. Imagine if you could break down the various types of fees—ranging from management and trading expenses to hidden charges. By doing so, you can take charge of your investments and maximize your family’s wealth.
It’s important to understand that with so many options and potential pitfalls, navigating this complex landscape can feel overwhelming. How can you ensure you’re not overpaying and are making the most of your hard-earned money? Together, we can explore these concerns and find the best path forward for your family.
Understand Investment Fees and Their Importance
Investment charges encompass various expenses linked to managing your investments, and understanding how much you should pay in investment fees is vital for your family’s financial health. Understanding how much should I pay in investment fees is essential, as these charges can significantly impact your overall returns and inform your monetary decisions. Common types of charges include:
- Management costs
- Trading expenses
- Performance fees
Imagine if you could keep more of your hard-earned money. When considering traditional financial advisors, it’s important to ask how much should I pay in investment fees, as they often charge between 0.75% and 1.5% of assets under management, while index funds typically have much lower expense ratios, ranging from 0.05% to 0.25%. Even seemingly small charges can accumulate over time, leading to substantial losses in your portfolio. For instance, research shows that a portfolio with a 1.5% expense ratio could yield over $73,000 less than one with a 0.1% ratio after 20 years. This highlights the importance of understanding how much I should pay in investment fees effectively.
It’s also crucial to be aware of hidden charges, such as custodial fees and inactivity charges, which can further diminish your returns. Staying attentive to all expenses related to your holdings can make a significant difference. Remember, Warren Buffett emphasizes that understanding how much should I pay in investment fees and their long-term effects is key to successful investing.
So, what can you do? Being proactive about these expenses, including performing yearly fee assessments, is the first step in enhancing your financial strategy. Households that actively oversee and manage their charges often experience improved returns. Together, we can navigate this journey, ensuring that you keep more of what you’ve earned for your family’s future.
Identify Common Types of Investment Fees
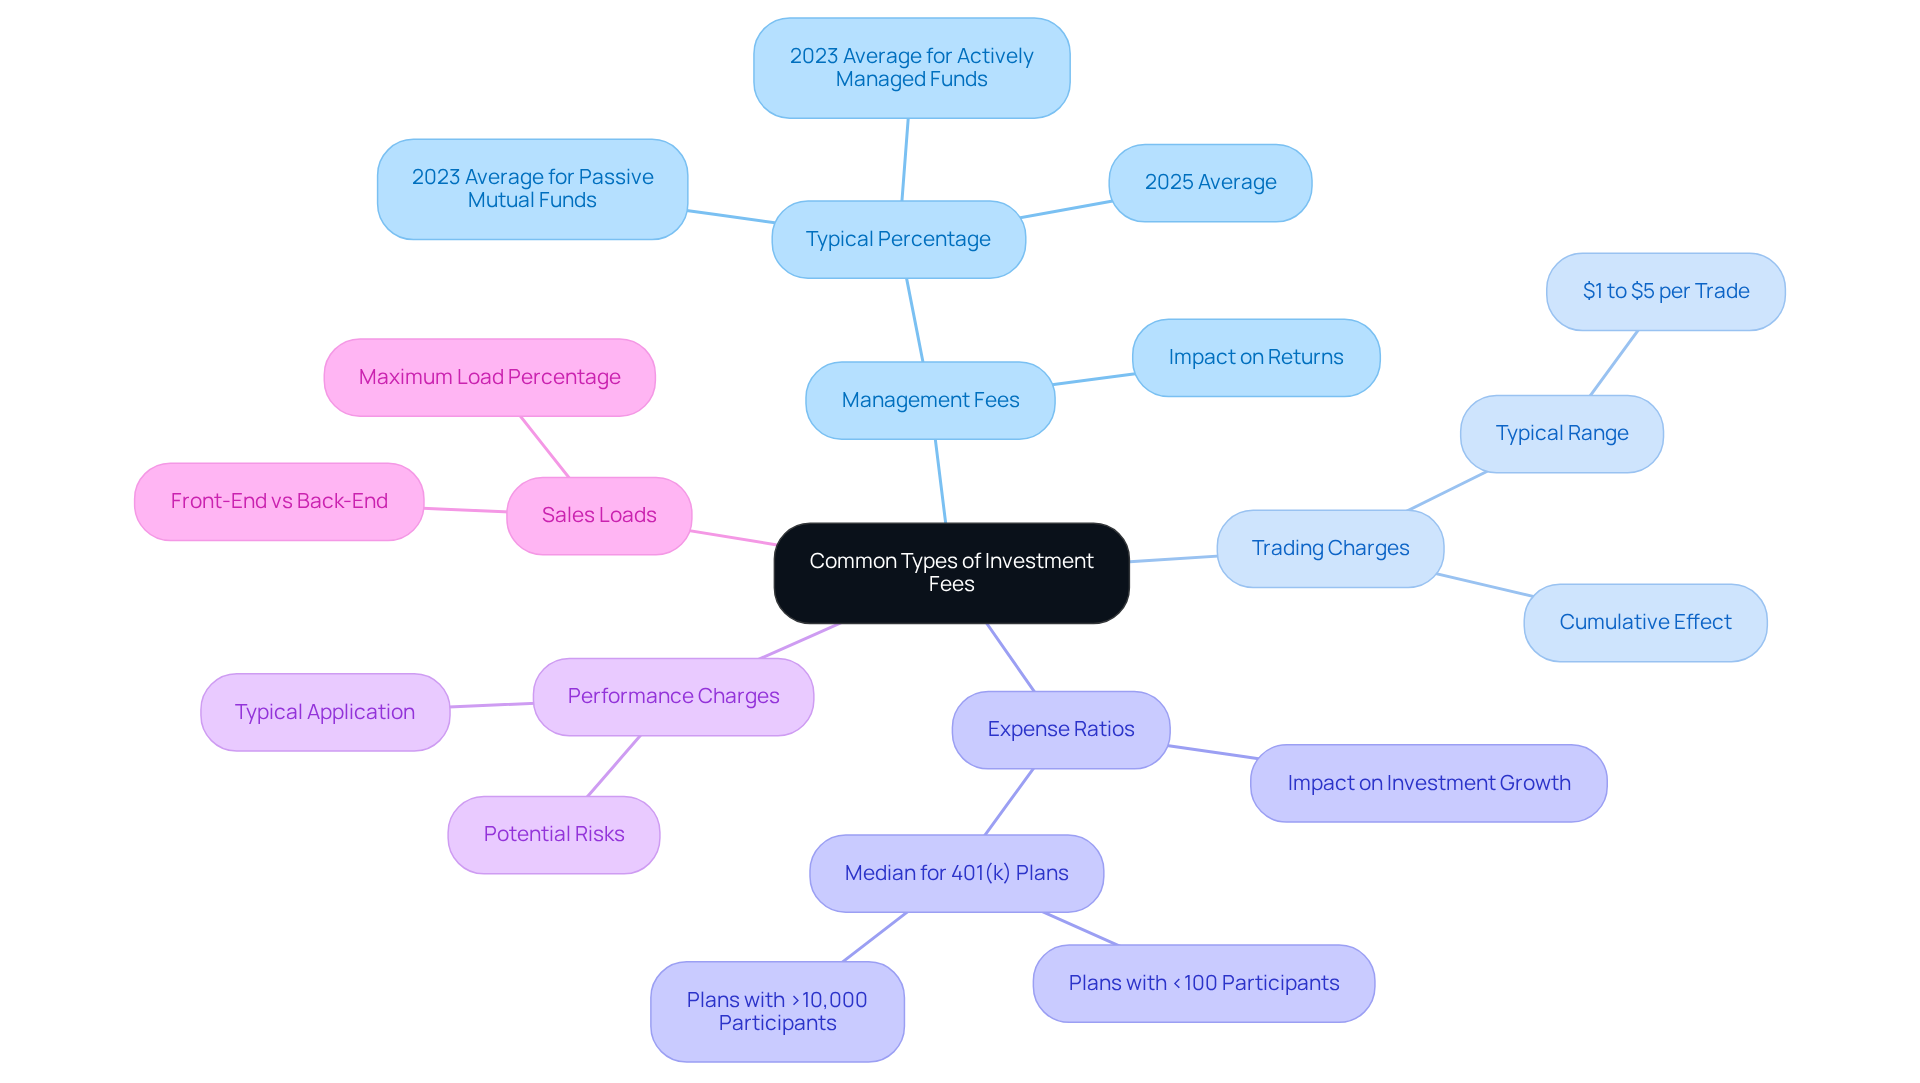
Understanding how much you should pay in investment fees is crucial for your family’s financial future. Grasping the different categories of fees can help you determine how much should I pay in investment fees, empowering you to make well-informed choices that align with your family’s goals. Let’s explore some common types of investment fees that can impact your returns:
- Management Fees: These fees are charged by investment managers for overseeing your portfolio and are typically expressed as a percentage of assets under management (AUM). In 2025, typical management charges for investment funds surpass 1%. It’s worth noting that the average fee for actively managed funds in 2023 was 0.42%, while passive mutual funds had a mere 0.05%. Choosing lower-cost options like index funds can help determine how much should I pay in investment fees, which can significantly benefit your family’s financial health.
- Trading Charges: When you buy or sell securities, you incur trading charges, which can include commissions or spreads. These charges usually range from $1 to $5 per trade. While they may seem small, they can accumulate quickly, especially for families who invest frequently.
- Expense Ratios: This annual charge, represented as a percentage of the fund’s assets, covers operational expenses. For instance, the median expense ratio for mutual funds in 401(k) plans was 1.27% in 2010, and smaller plans often have even higher ratios, averaging 1.29% for those with fewer than 100 participants. Understanding these ratios can help you determine how much you should pay in investment fees related to your overall costs.
- Performance Charges: Some funds, particularly hedge funds, impose fees based on the returns generated. While these charges can motivate managers to perform well, they may also lead to higher overall expenses for your family.
- Sales Loads: When purchasing mutual funds, you may encounter sales loads, which can be front-end (paid upfront) or back-end (paid upon selling). These loads can consume up to 5.75% of your investment, further impacting your returns.
Recognizing these charges is vital for evaluating the total expense of your assets. For families, understanding how much should I pay in investment fees and how these fees can accumulate over time is essential for building and preserving wealth. Imagine a median-income dual-earner household potentially forfeiting nearly $155,000 to fees over their working lifetime—almost one-third of their investment profits. In contrast, a higher-income dual-earner household might spend as much as $277,969 in costs throughout their lifetime. By identifying and managing these expenses, families can make informed choices that reflect their economic aspirations.
Moreover, considering low-cost index funds can be a strategic way to reduce expenses and enhance long-term growth. Together, we can navigate this journey toward financial security, ensuring a brighter future for your family.
Evaluate Your Financial Situation and Fee Structure
Navigating your financial landscape can feel overwhelming, but with a thoughtful approach, you can take control. Here’s how to evaluate your financial situation and fee structure effectively:
-
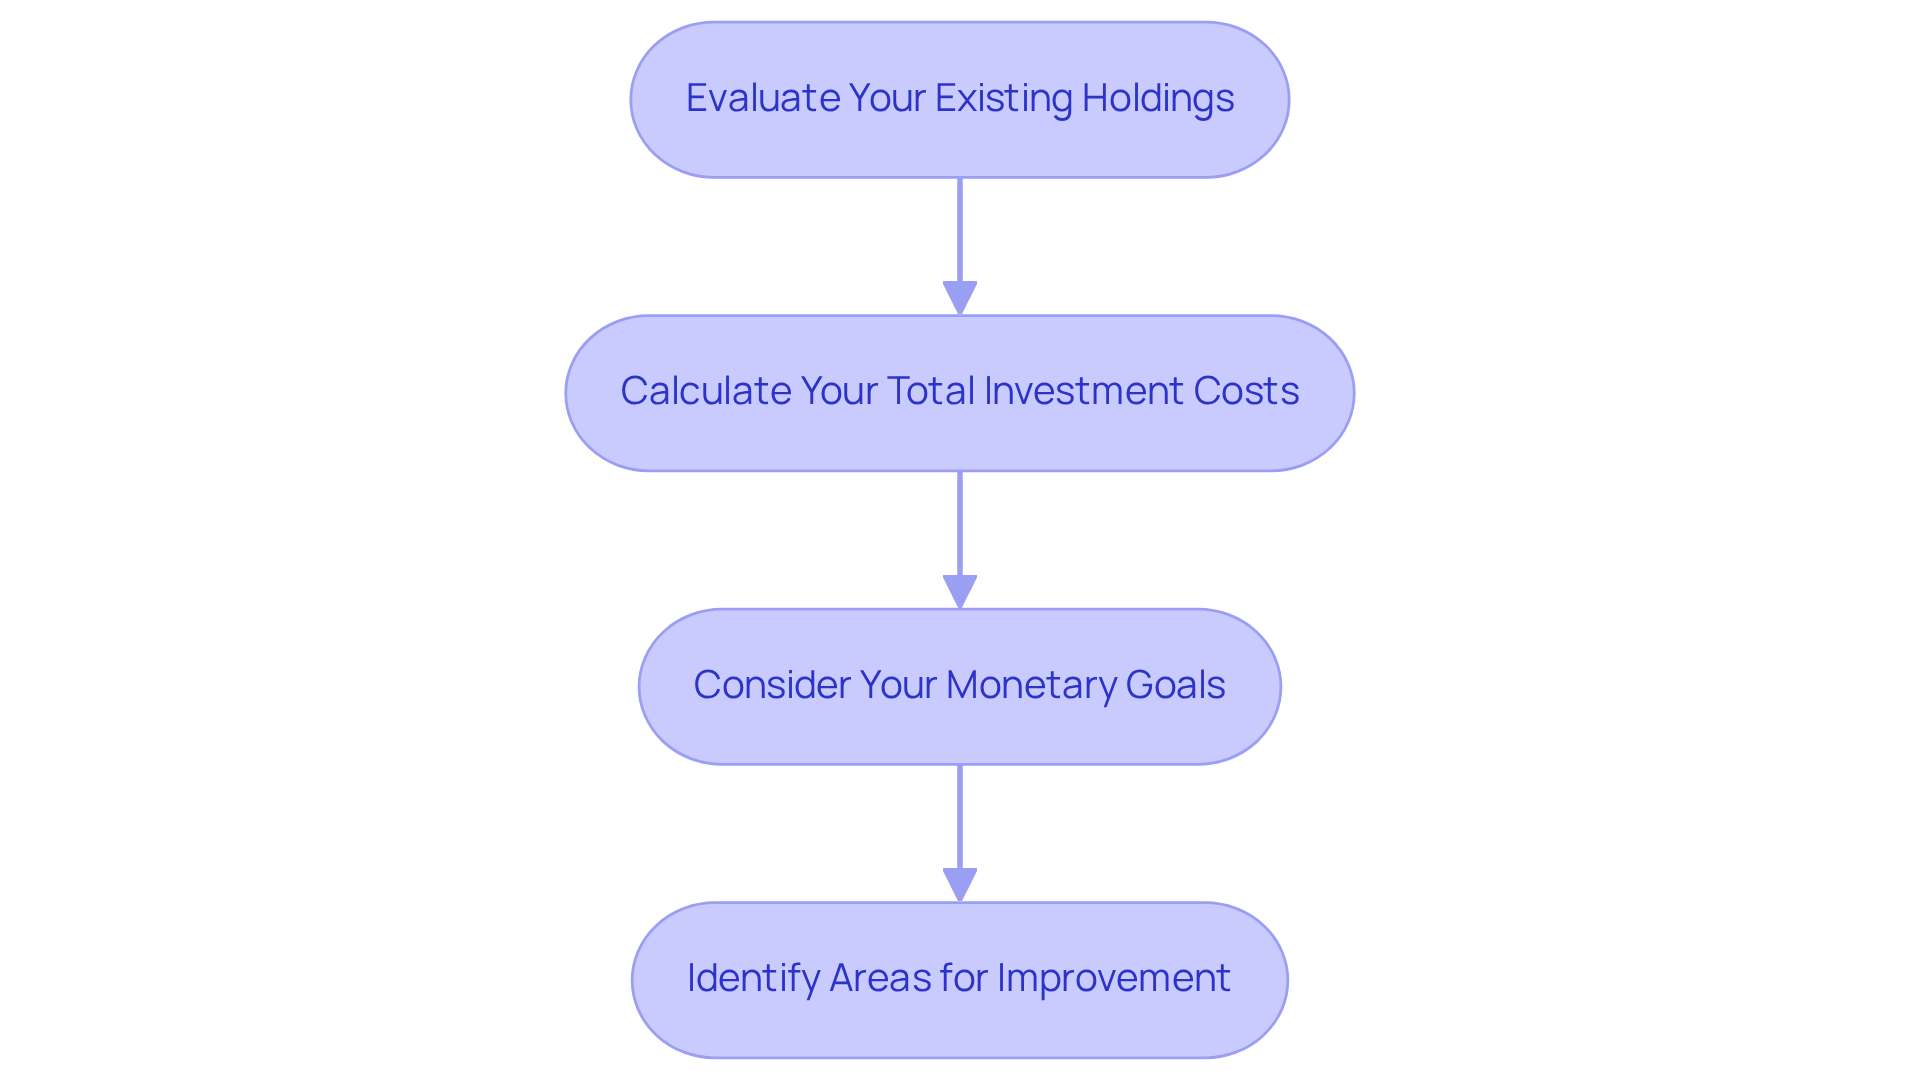
Evaluate Your Existing Holdings: Begin by taking a close look at your financial accounts. Recognize all related charges, paying special attention to how much should I pay in investment fees, trading expenses, and any additional costs that may arise. This step is crucial in understanding where your money is going.
-
Calculate Your Total Investment Costs: Next, sum all identified fees. Understanding the total cost of your investments provides a clearer picture of how much should I pay in investment fees that are being deducted from your returns. This insight will empower you to plan your budget more effectively.
-
Consider Your Monetary Goals: Reflect on your short-term and long-term financial objectives. Are your current assets in line with these goals? Assess how much should I pay in investment fees to determine if they are reasonable given the services you receive. Remember, statistics show that nearly 70% of Americans lack long-term financial planning strategies, highlighting the importance of aligning your resources with your personal goals.
-
Identify Areas for Improvement: Look for opportunities to reduce fees. This could mean switching to lower-cost options or negotiating charges with your advisor. Many families have successfully adjusted their financial strategies by calculating total expenses and making informed changes.
By thoroughly evaluating your financial situation and fee structure, you can make informed decisions that align with your financial goals. Together, we can navigate this journey, enhancing your family’s financial well-being and ensuring a brighter future.
Compare Fees Across Investment Options
To effectively compare fees across various investment options, follow these essential steps:
-
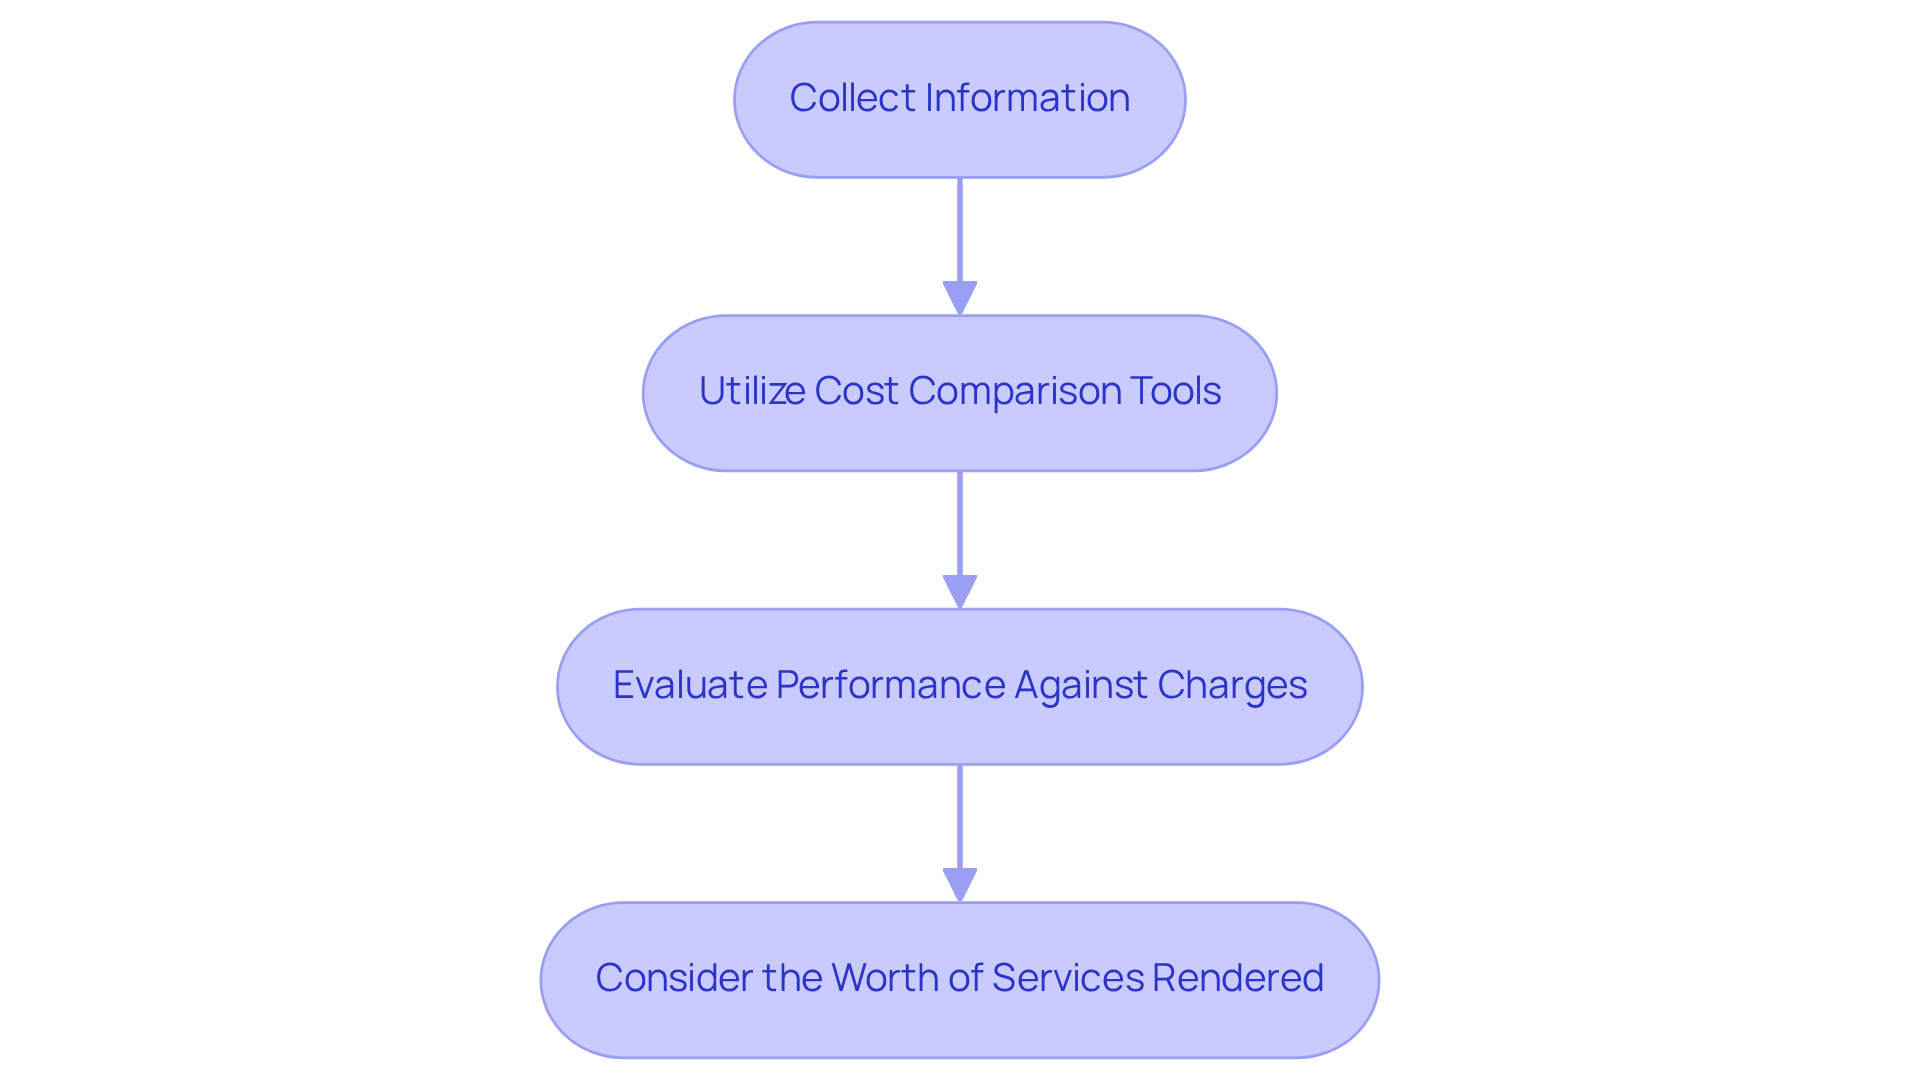
Collect Information: Begin by gathering comprehensive data on the costs related to various financial products, such as mutual funds, ETFs, and managed accounts. Understanding how much you should pay in investment fees is crucial for making informed decisions that align with your family’s financial goals.
-
Utilize Cost Comparison Tools: Imagine if you could easily see how different charges impact your potential returns. Leverage online calculators and comparison resources to analyze these variations. Trustworthy sources can illustrate these distinctions, helping you understand the long-term effects of fees on your family’s financial future. Websites like Schwab MoneyWise and Vanguard offer valuable resources for this purpose.
-
Evaluate Performance Against Charges: It’s important to understand the historical performance of investment options in relation to their costs. For instance, the S&P 500 returned an average of 11.97% per year between 2010 and the end of 2022. Remember, a higher fee does not always guarantee better performance; sometimes, lower-cost options can yield superior returns over time. As Warren Buffett wisely stated, “A higher fee does not always equate to better performance.”
-
Consider the Worth of Services Rendered: Evaluate whether the charges applied are warranted by the services provided. In certain situations, a greater charge might be justified if it encompasses tailored guidance or improved management services that correspond with your monetary objectives.
By methodically assessing how much should I pay in investment fees among various opportunities, families can make better-informed choices that not only align with their monetary goals but also help in reducing avoidable expenses. For example, a family foundation overseeing more than $2 billion successfully navigated fee comparisons to enhance their investment strategies, demonstrating the practical impact of this approach. Together, we can navigate this journey toward financial well-being.
Negotiate Fees with Financial Advisors
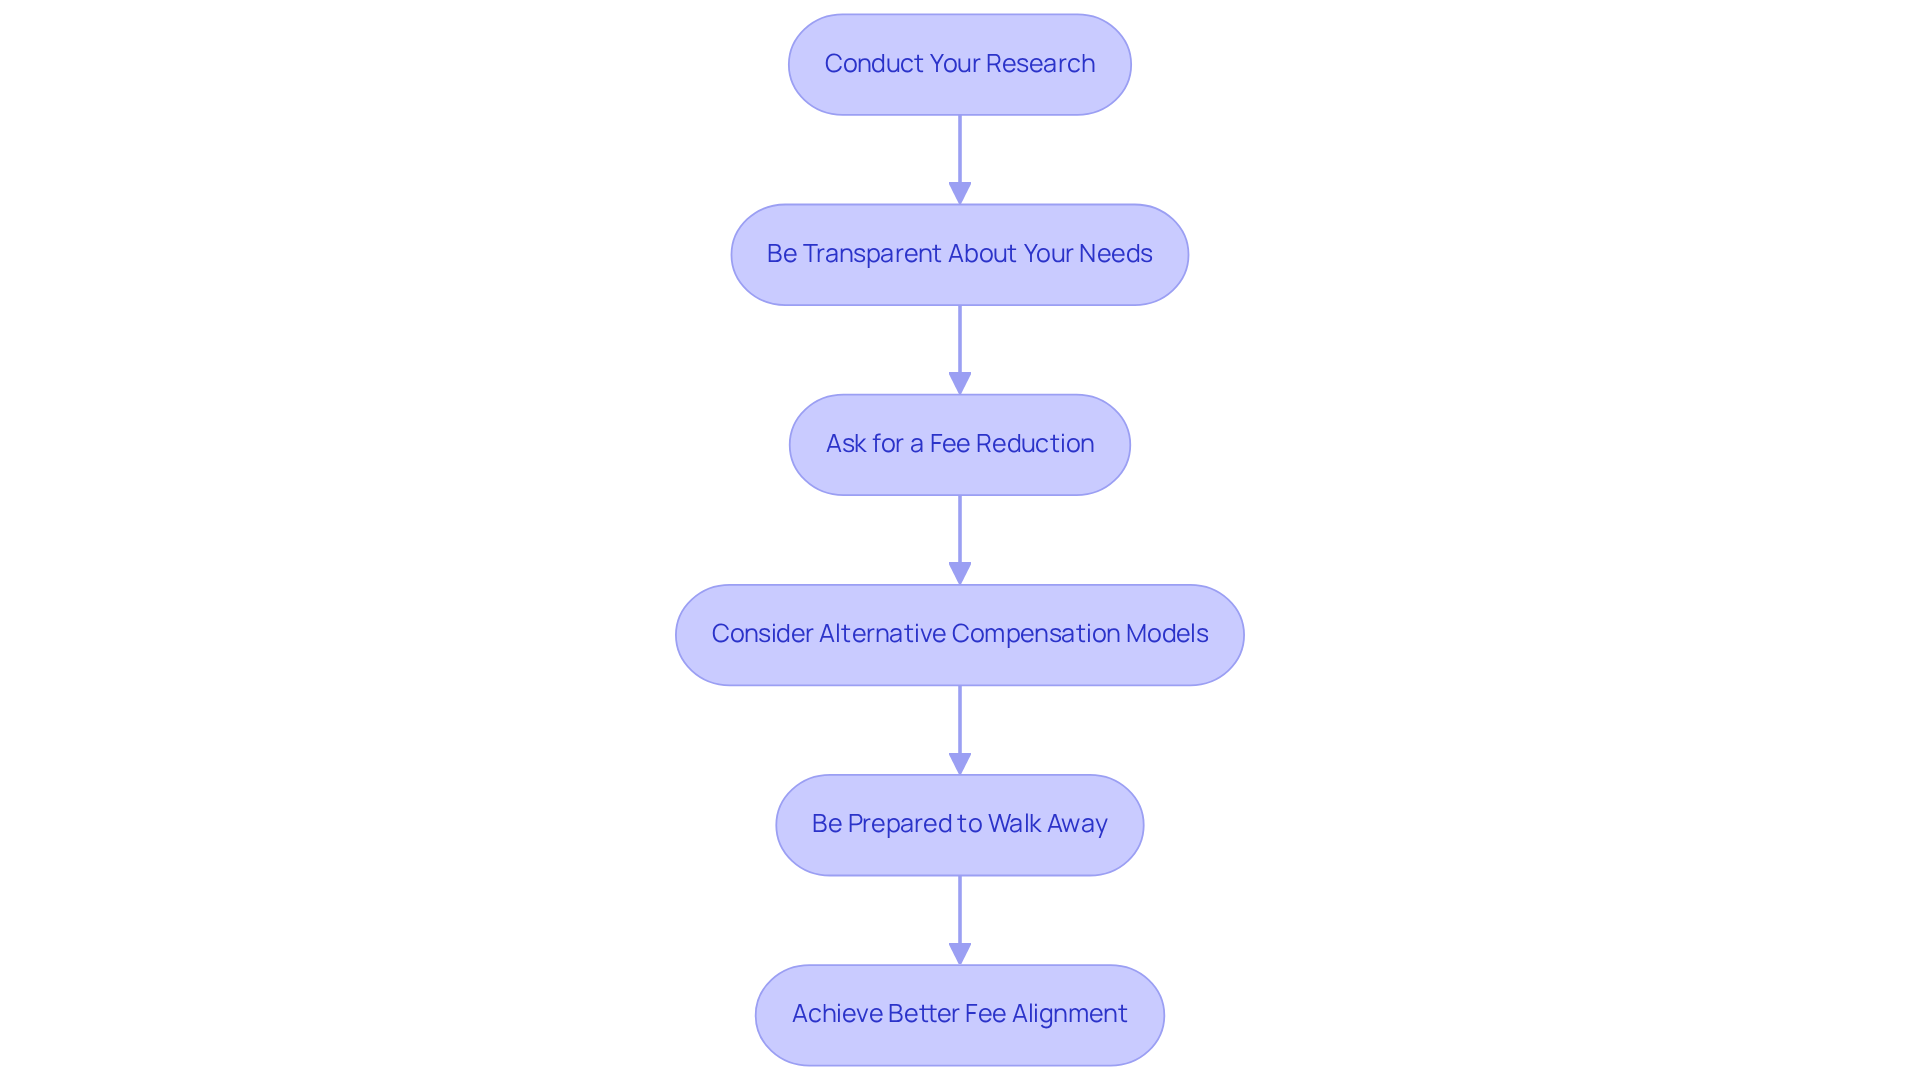
Discussing costs with your money advisor can lead to significant savings and a better alignment with your financial goals. Here’s how to approach this important conversation effectively:
-
Conduct Your Research: Familiarize yourself with how much you should pay in investment fees, as the typical fees charged by advisors in your area usually range from 0.59% to 1.18% of assets under management. Knowing these benchmarks empowers you during negotiations, giving you confidence.
-
Be Transparent About Your Needs: Clearly express your financial objectives and expectations. This openness allows your advisor to tailor their services to your specific needs, fostering a collaborative relationship that benefits your family.
-
Ask for a Fee Reduction: Don’t hesitate to request a lower fee, especially if you’ve been a loyal client or if your portfolio has grown significantly. Many advisors appreciate negotiation, particularly when they value your continued partnership. It’s worth noting that clients who engage in fee discussions can save substantial amounts over time; for instance, $160,000 in costs could accumulate over a long investment period with a wealth advisor.
-
Consider Alternative Compensation Models: Explore different payment structures, such as flat fees or performance-based payments, which might better suit your financial situation. Fixed fees for one-time planning services typically range from $2,000 to $7,500, helping you budget effectively and providing transparency on costs.
-
Be Prepared to Walk Away: If your advisor is unwilling to negotiate, be ready to explore other options. The financial advisory landscape is competitive, and many advisors offer more favorable rates and services.
By actively negotiating fees, you can figure out how much should I pay in investment fees to ensure you receive the best value for your investment management services, potentially saving thousands over time. Additionally, partnering with a financial advisor can add about 3% in net returns through various value-added services, making fee negotiation a worthwhile endeavor. Remember, together, we can navigate this journey toward financial security for your family.
Conclusion
Understanding investment fees is essential for protecting your family’s financial future. These fees, which can significantly diminish your returns, come in various forms, such as management fees, trading expenses, and performance charges. By being aware of how much should be paid in investment fees, families can make informed decisions that align with their financial goals, ultimately keeping more of their hard-earned money.
Throughout this article, we’ve shared key insights on the different types of investment fees and their potential impact on returns. It’s important to understand that even seemingly small charges can accumulate over time, leading to significant financial losses. We’ve outlined practical steps for evaluating your current fee structure, comparing costs across various investment options, and negotiating fees with financial advisors. Each of these actions empowers families to take control of their investments and enhance their overall financial well-being.
Ultimately, the journey toward financial security begins with awareness and proactive management of investment fees. Families are encouraged to regularly assess their financial situation, utilize available resources for fee comparison, and engage in open discussions with their advisors. By prioritizing fee transparency and actively seeking lower-cost investment options, individuals can pave the way for a brighter financial future, ensuring that they maximize their investment returns and achieve their long-term financial aspirations. Together, we can navigate this journey toward financial health, supporting one another every step of the way.
Frequently Asked Questions
What are investment fees and why are they important?
Investment fees are expenses associated with managing your investments, and understanding them is crucial for your family’s financial health, as they can significantly impact overall returns and inform monetary decisions.
What are the common types of investment fees?
Common types of investment fees include management costs, trading expenses, performance fees, expense ratios, and sales loads.
How much do traditional financial advisors typically charge in investment fees?
Traditional financial advisors usually charge between 0.75% and 1.5% of assets under management.
How do the fees of index funds compare to traditional financial advisors?
Index funds typically have much lower expense ratios, ranging from 0.05% to 0.25%.
What is the impact of even small investment fees over time?
Even seemingly small charges can accumulate over time, leading to substantial losses. For example, a portfolio with a 1.5% expense ratio could yield over $73,000 less than one with a 0.1% ratio after 20 years.
What are some hidden charges investors should be aware of?
Investors should be aware of hidden charges such as custodial fees and inactivity charges, which can further diminish returns.
How can families manage their investment fees effectively?
Families can manage investment fees by performing yearly fee assessments and actively overseeing and managing their charges to improve returns.
What are management fees?
Management fees are charged by investment managers for overseeing your portfolio and are typically expressed as a percentage of assets under management (AUM).
What are trading charges?
Trading charges are incurred when buying or selling securities and usually range from $1 to $5 per trade.
What are expense ratios?
Expense ratios are annual charges represented as a percentage of the fund’s assets that cover operational expenses. For instance, the median expense ratio for mutual funds in 401(k) plans was 1.27% in 2010.
What are performance charges?
Performance charges are fees based on the returns generated by some funds, particularly hedge funds, which can lead to higher overall expenses.
What are sales loads?
Sales loads are fees encountered when purchasing mutual funds, which can be front-end (paid upfront) or back-end (paid upon selling), consuming up to 5.75% of your investment.
How can understanding investment fees benefit families?
By understanding and managing investment fees, families can make informed choices that reflect their economic aspirations and potentially save significant amounts over their working lifetime.
List of Sources
- Understand Investment Fees and Their Importance
- 102 Warren Buffett Quotes on Life, Success, & More (https://ruleoneinvesting.com/blog/how-to-invest/warren-buffett-quotes-on-investing-success)
- What is the true impact of hidden fees on investment returns? (https://home.saxo/learn/guides/pricing/what-is-the-true-impact-of-hidden-fees-on-investment-returns)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Recent Research Shows How Fees Can Erode Retirement Savings – Georgetown Center for Retirement Initiatives (https://cri.georgetown.edu/recent-research-shows-how-fees-can-erode-retirement-savings)
- Quotes on Fees • Novel Investor (https://novelinvestor.com/quote-category/fees)
- Identify Common Types of Investment Fees
- 102 Warren Buffett Quotes on Life, Success, & More (https://ruleoneinvesting.com/blog/how-to-invest/warren-buffett-quotes-on-investing-success)
- The Costs of Investing That You May Be Overlooking (https://investopedia.com/investing/costs-investing)
- The Retirement Savings Drain: Hidden & Excessive Costs of 401(k)s | Demos (https://demos.org/research/retirement-savings-drain-hidden-excessive-costs-401ks)
- Investment fees: Why they are critical for your long-term wealth (https://home.saxo/learn/guides/financial-literacy/investment-fees-why-they-are-critical-for-your-long-term-wealth)
- What Is the Average Investment Management Fee? (https://smartasset.com/investing/what-is-the-average-investment-management-fee)
- Evaluate Your Financial Situation and Fee Structure
- Discussing Fees And The Value Of Financial Planning (https://kitces.com/blog/fees-value-financial-advice-client-communication-cost-anchoring)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Key Financial Literacy Statistics in 2023 (https://annuity.org/financial-literacy/financial-literacy-statistics)
- Two-Thirds of Americans Say Their Financial Planning Needs Improvement (https://news.northwesternmutual.com/2023-07-24-Two-Thirds-of-Americans-Say-Their-Financial-Planning-Needs-Improvement)
- Compare Fees Across Investment Options
- Financial – Planning – Case – Studies 2023 | PDF | Investment Fund | Exchange Traded Fund (https://scribd.com/document/695749725/Financial-Planning-Case-Studies-2023)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Negotiate Fees with Financial Advisors
- Financial Advisor Fee Calculator | Evaluate Cost vs. Benefit (https://advisorfinder.com/resources-for-clients/calculators/aum-fee-comparison)
- Is It Worth Paying a Financial Advisor 1%? (https://smartasset.com/financial-advisor/is-it-worth-paying-a-financial-advisor)
- Negotiation Quotes — 25 Legendary Quotes Full of Wisdom (https://procurementtactics.com/negotiation-quotes)
- How Much Does A Financial Advisor Cost? (https://magnifymoney.com/investing/financial-advisor-cost)
- Financial Advisor Statistics for 2025 – TealePen and Pixel (https://tealepenandpixel.com/insights/54-global-financial-advisor-statistics-for-2025)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading