

Key Highlights
- Identify your vision for retirement by visualising your ideal lifestyle and documenting your aspirations.
- Evaluate your current lifestyle and anticipate changes that may affect future expenses, such as downsizing or increased travel.
- Set specific, measurable retirement goals, including estimated costs for travel and living in a new area.
- Consider family needs, including children’s education and support, to determine additional savings requirements.
- Document your goals to maintain focus and clarity in your financial planning efforts.
- Assess potential income sources for retirement, including pensions, Social Security, and retirement accounts.
- Estimate monthly expenses, factoring in both fixed and variable costs, and consider healthcare expenses.
- Account for inflation when estimating future expenses to ensure adequate savings.
- Determine a safe withdrawal rate by dividing desired annual income by total retirement savings, adjusting for market conditions.
- Utilise financial tools and professional guidance to enhance retirement planning, including calculators and personalised advice from Bright Advisers.
Introduction
Imagine feeling lost in the maze of retirement planning, especially when you have little ones to care for. As a parent, you might find it tough to set retirement goals while juggling the needs of your growing family. This guide will gently walk you through:
- Understanding your income
- Estimating your expenses
- Finding a safe way to withdraw funds
All while highlighting the support available to you. Let’s explore how you can harmonize your dreams for retirement with the practical steps needed to achieve them.
Define Your Retirement Goals and Lifestyle Needs
-
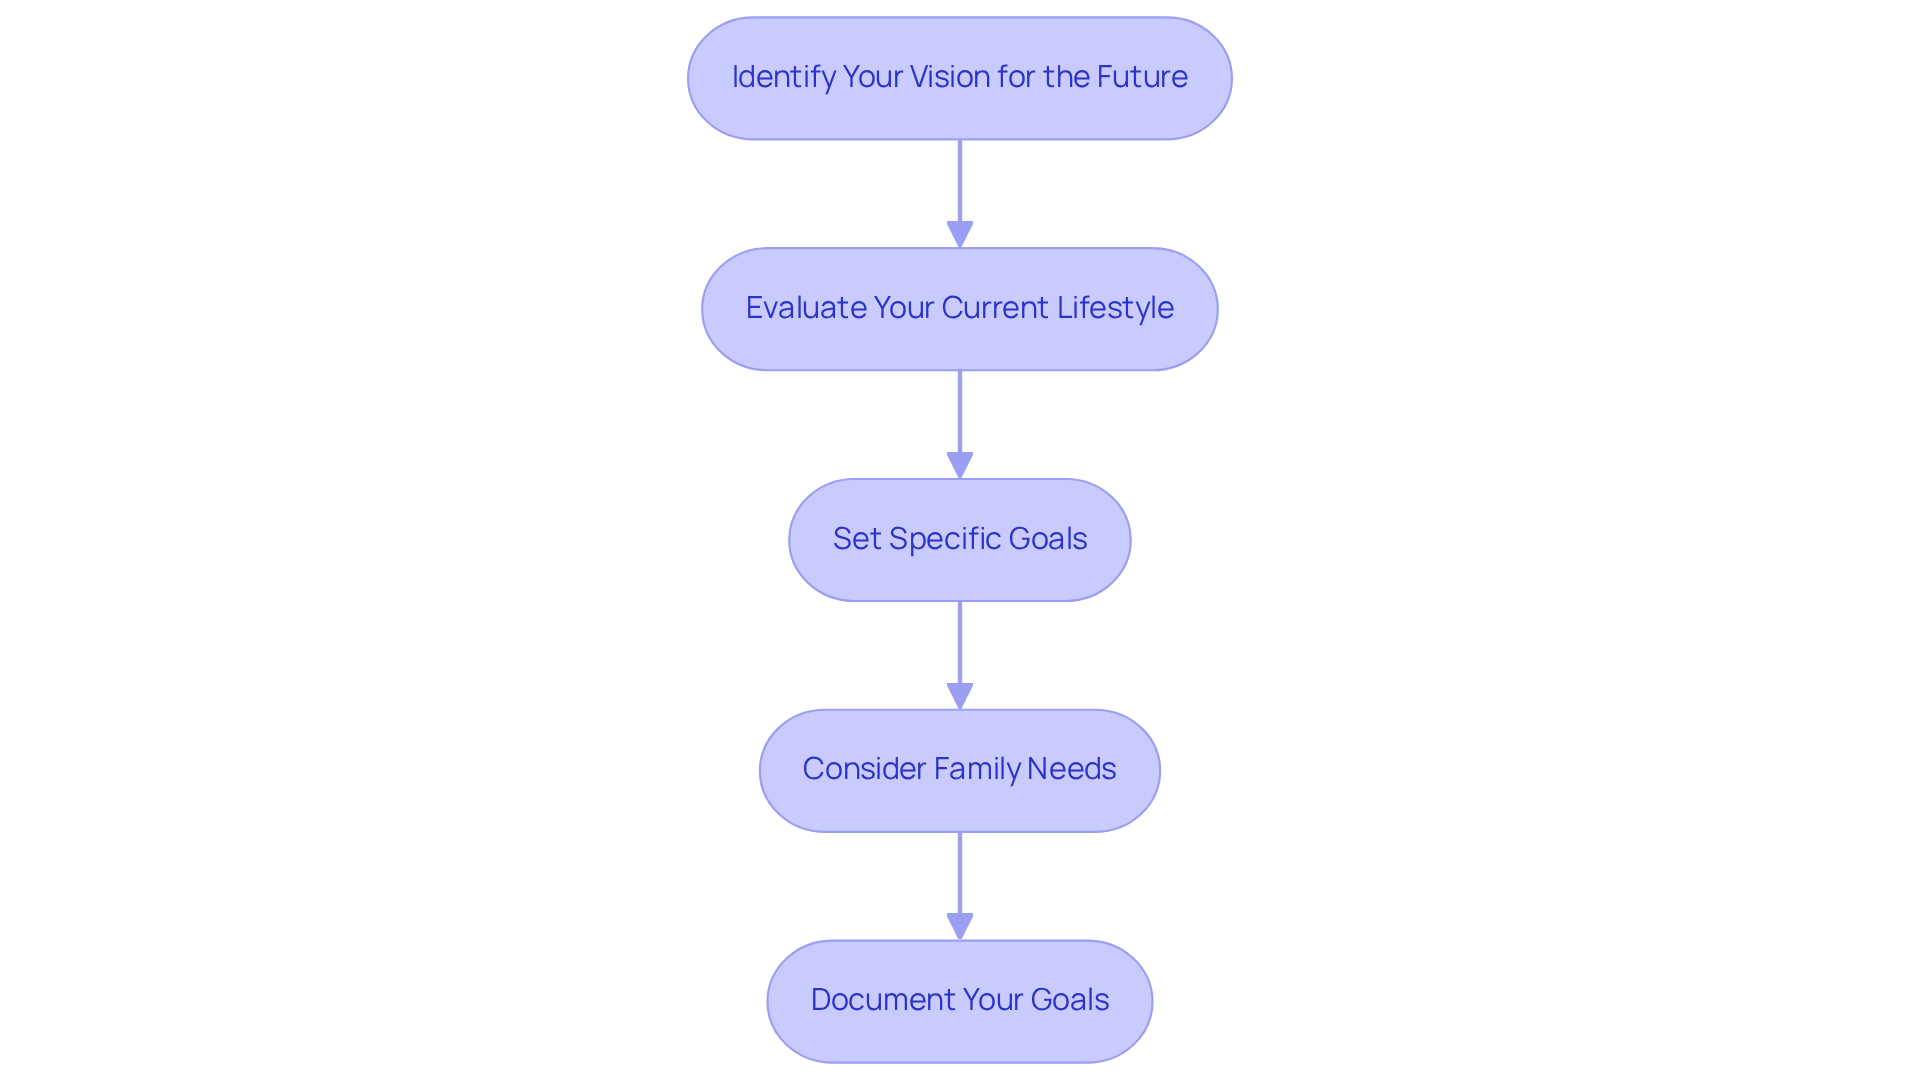
Identify Your Vision for the Future: Imagine a future where your family thrives, free from financial worries. Begin by visualizing your ideal phase of life after work. Consider where you want to live, the activities you wish to engage in, and how you envision spending your time. Recording these aspirations will help you form a clear vision of your future goals.
-
Evaluate Your Current Lifestyle: It’s important to think about how your current way of living may change in the future. Will you downsize your home? Travel more frequently? Pursue new hobbies? Understanding these potential changes is essential for estimating future expenses.
-
Set Specific Goals: Establish clear, measurable goals. For instance, if extensive travel is part of your retirement plan, estimate the associated costs. If moving, investigate the cost of living in your chosen area to ensure your budget aligns with your objectives. We’re here to help you create a personalized strategy that fits your family’s needs, incorporating integrated tax planning and investment approaches designed for families with young children.
-
Consider Family Needs: If you have children, factor in their future needs, such as education or support during their early adult years. This consideration will assist you in determining additional savings needs to secure their economic futures. Bright Advisers highlights the significance of planning for these future expenses to ensure your family’s economic security.
-
Document Your Goals: Create a written document outlining your future objectives and lifestyle needs. This will act as a reference point as you advance with your planning, ensuring that your goals remain at the forefront of your approach. Did you know that only 15% of women have a written plan for their financial future? This highlights how important it is to document your goals. Bright Advisers encourages families to maintain clear documentation to support their financial planning efforts.
Assess Income Sources and Estimate Retirement Expenses
Imagine facing your golden years with confidence, knowing you’ve planned for every financial need.
-
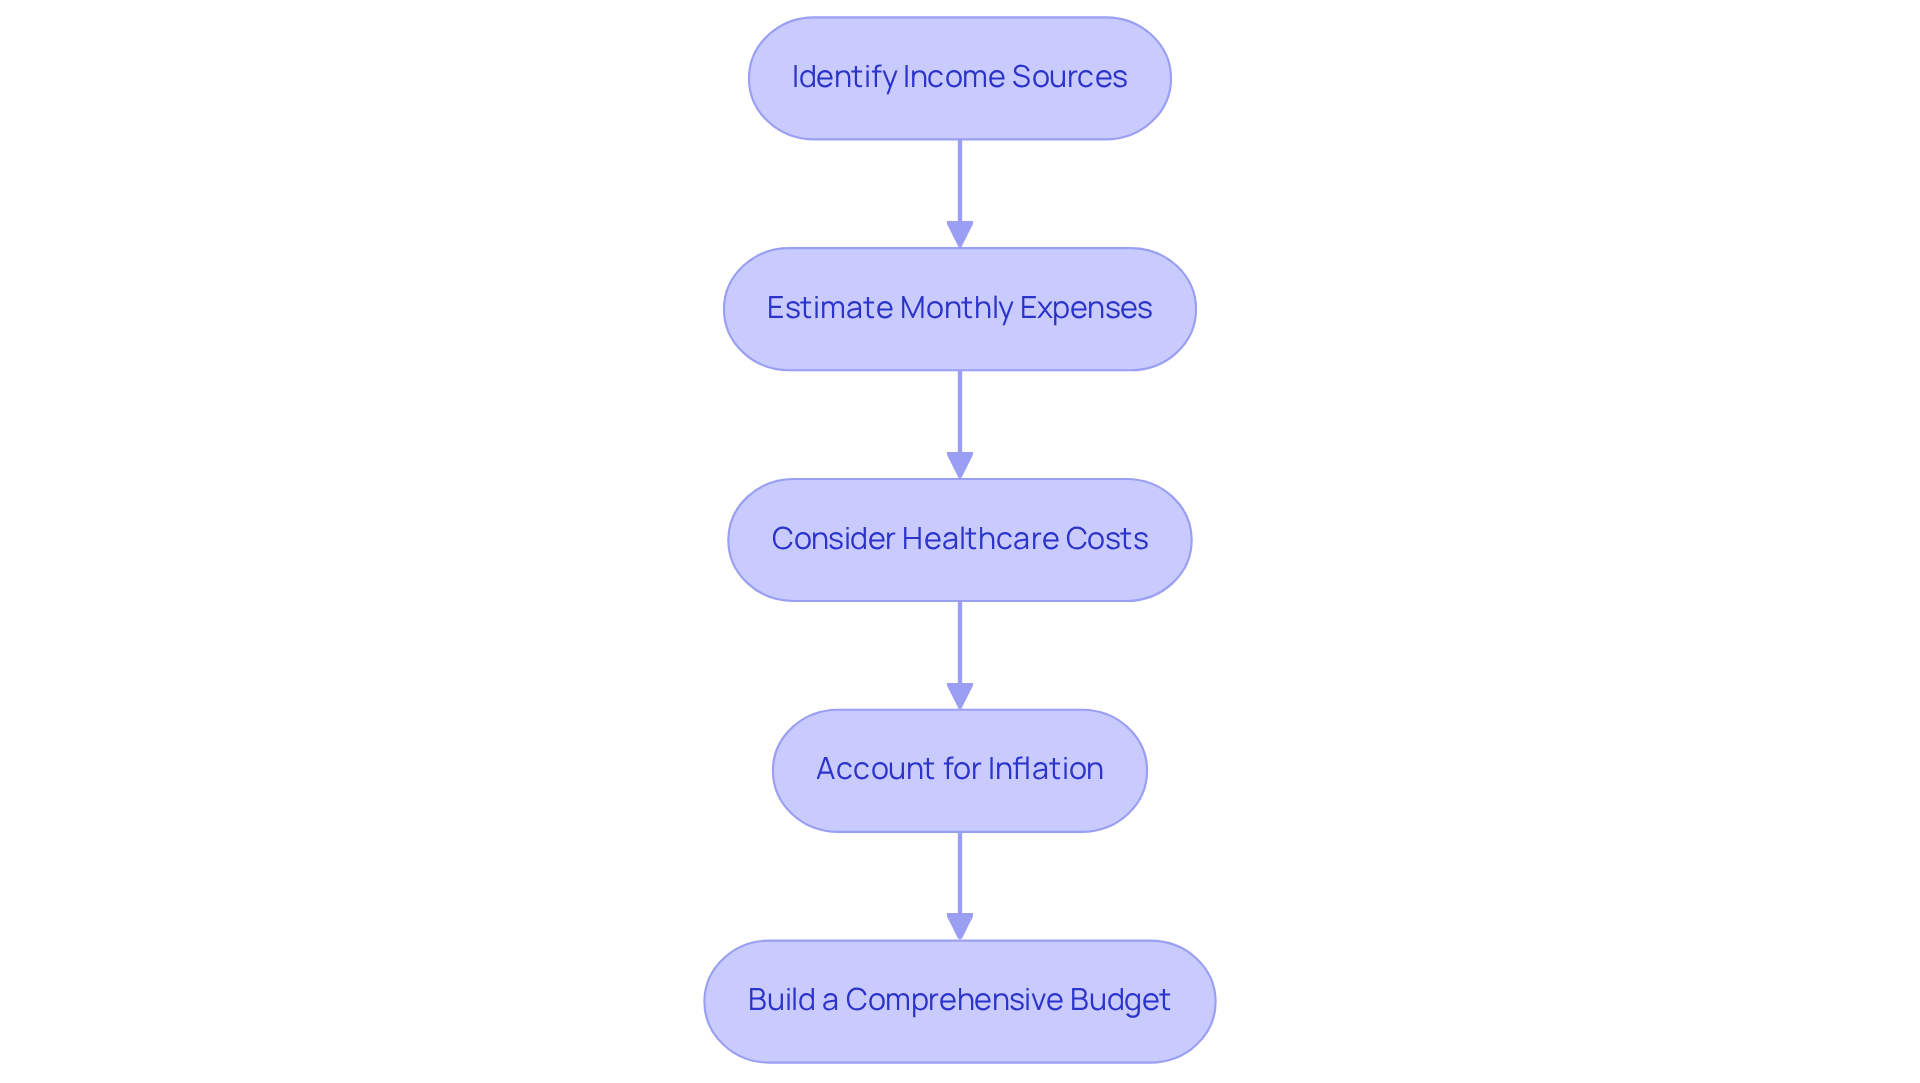
Identify Income Sources: Let’s explore all the potential income sources you might have in your later life. This includes pensions, Social Security, retirement accounts like 401(k) and IRA, and any other investments. For instance, if you have a pension, it’s worth researching how much to save for retirement with pension and how it will contribute to your overall income.
-
Estimate Monthly Expenses: Now, let’s take a moment to think about your monthly costs as you envision your later years. Include fixed costs like housing, utilities, and insurance, along with variable costs such as groceries, entertainment, and travel. You can use your current budget as a starting point, adjusting for any anticipated changes.
-
Consider Healthcare Costs: Healthcare can be a significant expense in later life. It’s important to research potential costs for health insurance, long-term care, and out-of-pocket medical expenses. This preparation will help you face these inevitable costs with confidence.
-
Account for Inflation: Remember, costs will likely rise over time due to inflation. It’s wise to consider an annual increase in expenses when estimating your savings plan for later years.
-
Together, Let’s Build a Comprehensive Budget: Now, let’s build a comprehensive budget that reflects your hopes and dreams for the future. Combine your income sources and estimated expenses into a thorough financial plan. This will help you determine if your income will cover your expenses and identify any gaps that need to be addressed.
With careful planning, you can embrace the future, knowing you’re prepared for whatever comes your way.
Determine a Safe Withdrawal Rate for Your Savings
Imagine facing retirement with uncertainty about how to manage your savings effectively. Understanding withdrawal rate basics can help ease those worries. The 4% rule is a guideline that suggests retirees can withdraw 4% of their funds annually without depleting their resources. However, individual circumstances can lead to variations in this rate.
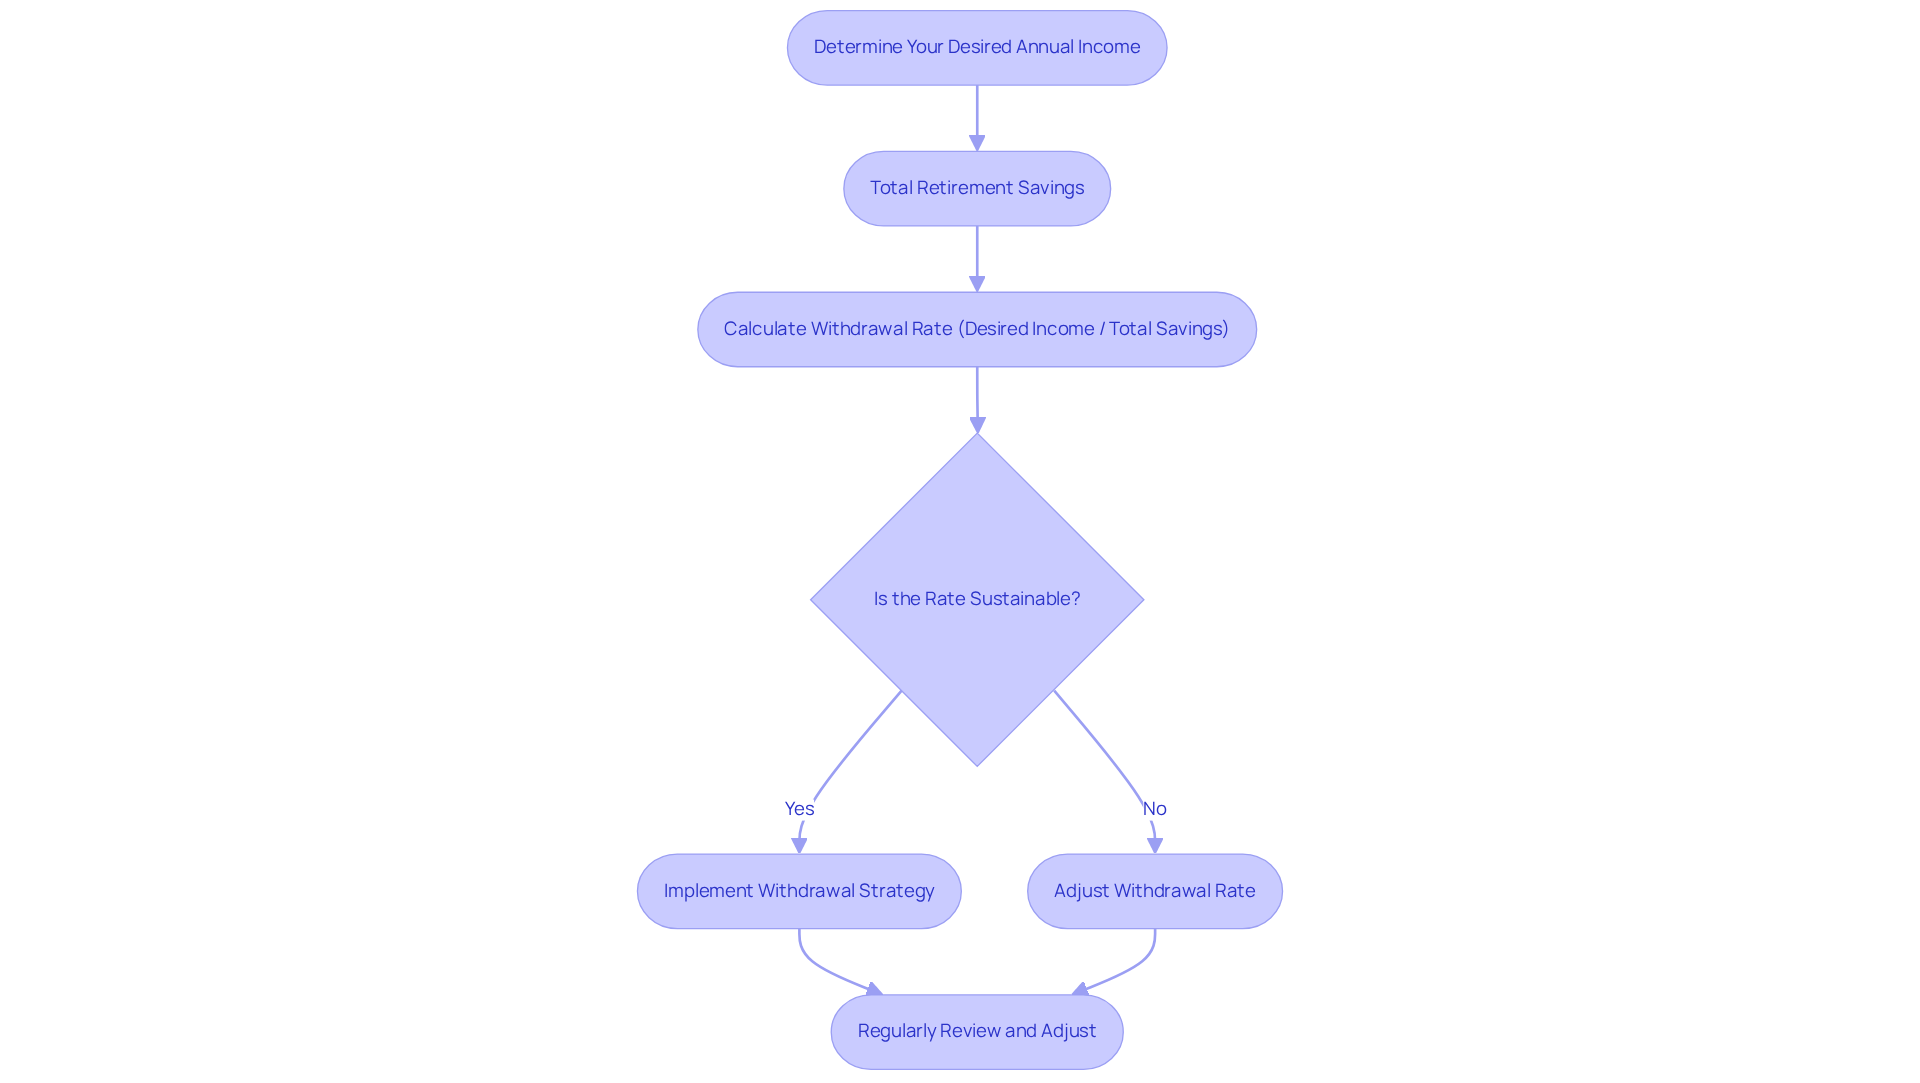
Let’s figure out your safe withdrawal rate together: simply divide your desired annual income by your total retirement savings. For instance, if you need $40,000 per year and have $1,000,000 saved, your withdrawal rate would be 4%. This method aligns with the idea that retirees should strive for a withdrawal rate that balances their income needs with the longevity of their funds.
It’s important to think about how current market conditions and your investment choices can impact your withdrawal rate. A more aggressive portfolio may allow for a higher withdrawal percentage, but this comes with increased risk. Research shows that retirees who adjust their spending based on market trends can improve the chances that their funds will last throughout their later years.
As you set your withdrawal rate, consider how long you might need your savings to last. If you expect a longer retirement, you may need to withdraw less each year to ensure your savings endure. The first decade of retirement is particularly critical; maintaining at least 50-60% of your initial portfolio value during this period is vital for long-term sustainability.
Think of your withdrawal strategy as something that needs to grow and change with you. Regularly assess your financial situation and adjust your withdrawal rate as needed, especially after major life events or shifts in market conditions. By staying proactive and informed, you can ensure your financial future remains secure for your family.
Utilize Financial Tools and Professional Guidance
Imagine feeling confident about your family’s financial future, knowing you have the right tools and support to guide you along the way.
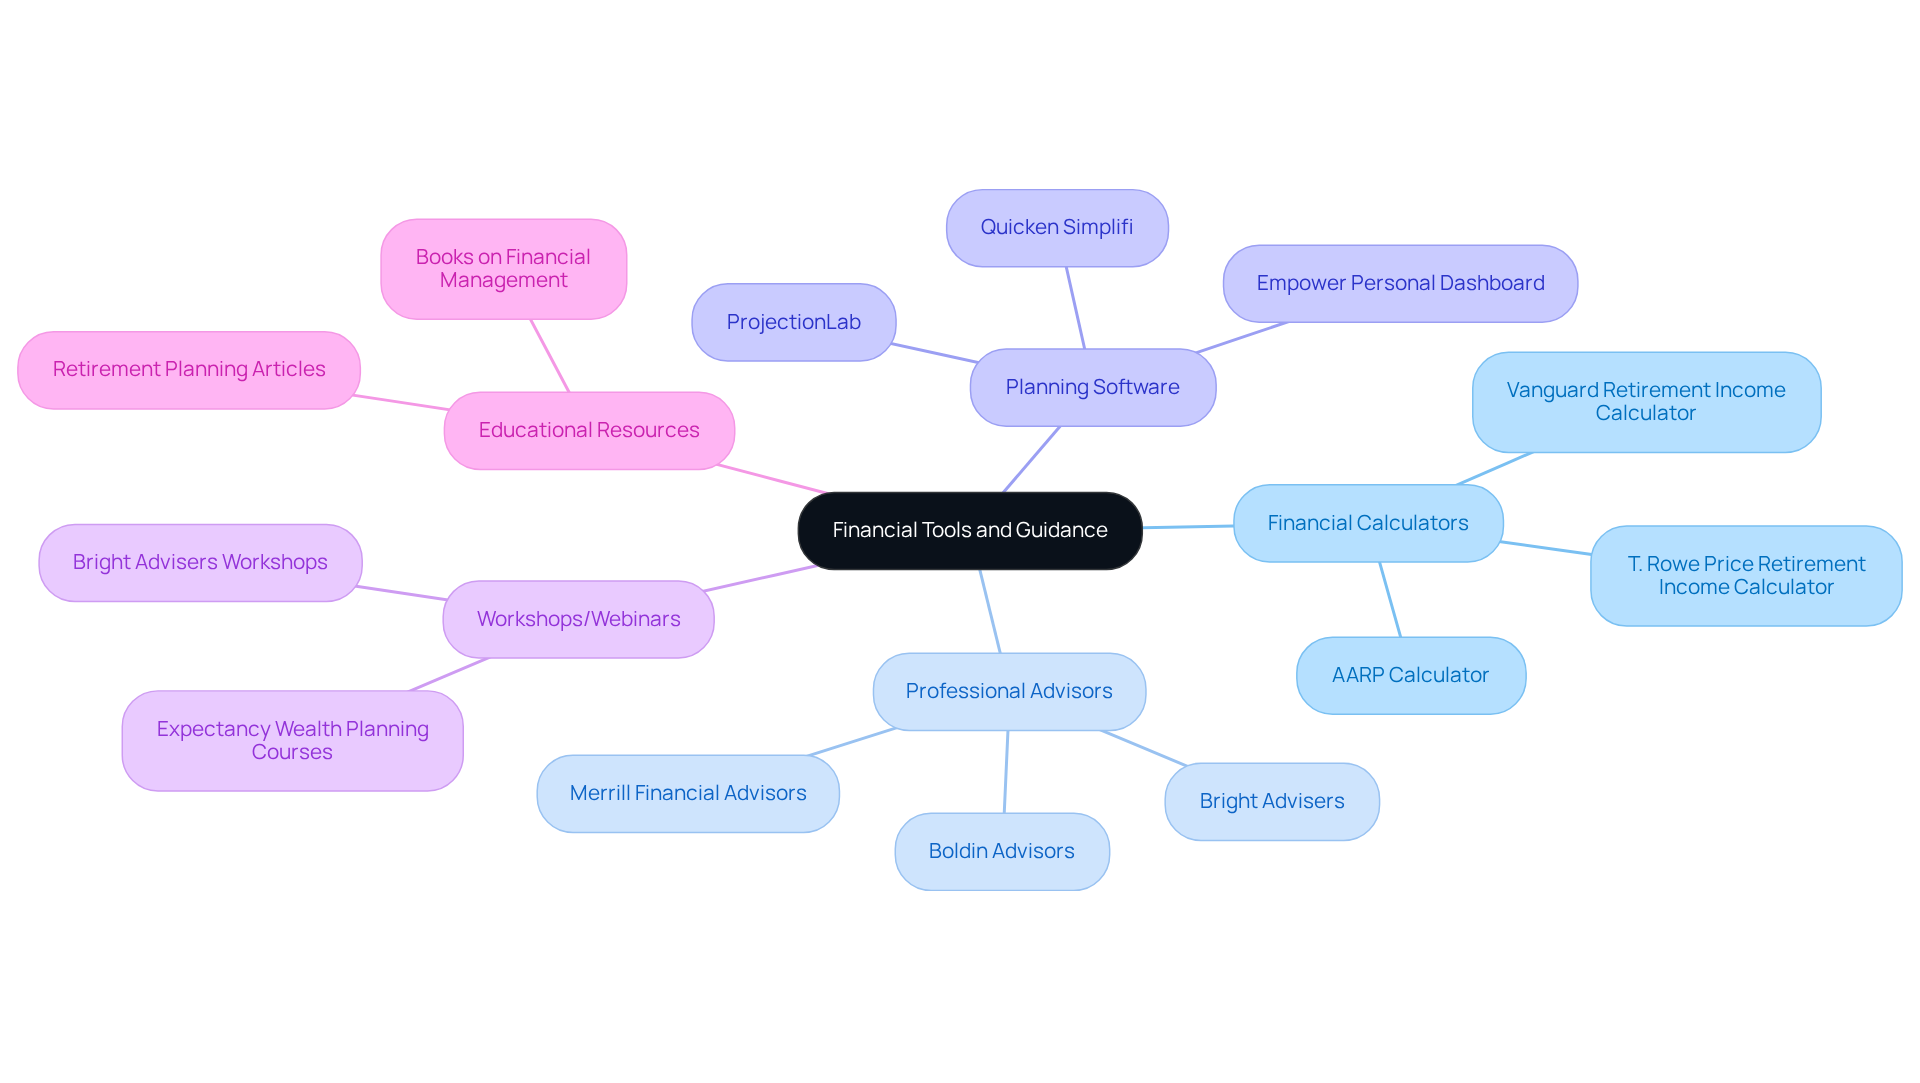
Let’s explore some financial calculators together. These online tools can help you estimate your needs and potential income as you look toward the future. Tools from trustworthy sources like Vanguard offer user-friendly interfaces that make it easier to visualize your economic journey. For instance, the AARP Calculator for Future Planning allows you to adjust your retirement age and see how different saving strategies can impact your future, emphasizing the importance of starting early.
Thinking about professional financial guidance? A money advisor, like those at Bright Advisers, can offer personalized insights tailored to your family’s unique needs. Our team specializes in planning for the future and has extensive experience working with families just like yours. We prioritize transparency, ensuring you understand our fee structures with no hidden costs.
Consider using planning software for the future. Imagine having a tool that simulates various scenarios, showing you how changes in savings, spending, and investment strategies can affect your outcomes. At Bright Advisers, we use cutting-edge technology to create hyper-personalized portfolios, avoiding costly mutual funds and ETFs while maximizing tax-loss harvesting opportunities to enhance your investment approach.
Participate in workshops or webinars focused on planning for the future. These events not only provide valuable information but also connect you with other families facing similar challenges. Bright Advisers offers resources to help families navigate their economic futures effectively, covering essential topics like budgeting and investment strategies.
Stay informed. Regularly reading articles, books, and resources on retirement planning can empower you to make informed financial decisions. If you’re interested in personalized financial planning, consider joining our waitlist at Bright Advisers. Together, we can build a strong financial foundation for your family’s future.
Disclaimer: All advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and securities investments are subject to risk.
By taking these steps, you’re not just planning for tomorrow; you’re investing in a brighter future for your family, one where you can thrive together.
Conclusion
Imagine feeling confident about your family’s financial future as you approach retirement, knowing you have a solid plan in place. By setting clear retirement goals and understanding what your family needs, you can create a plan that truly reflects your dreams. This means looking at where you are now, figuring out what you’ll need in the future, and keeping track of your goals along the way.
It’s essential to understand where your income will come from, what your expenses might be, and how to withdraw funds safely for your family’s needs. By identifying all potential income streams, including pensions and Social Security, you can gain a clearer picture of your financial landscape. Estimating monthly expenses and accounting for healthcare costs are crucial steps in building a budget that supports the retirement lifestyle you envision.
Taking the time to plan for retirement can make all the difference for your family’s future. Engaging with financial advisors like Bright Advisers can provide tailored support, helping you make informed decisions that align with your unique circumstances. Together, we can ensure your family’s financial well-being is prioritized, allowing you to embrace retirement with peace of mind.
Frequently Asked Questions
What should I consider when defining my retirement goals?
Begin by visualizing your ideal future after work, including where you want to live, activities you wish to engage in, and how you envision spending your time. This helps form a clear vision of your future goals.
How can I evaluate my current lifestyle in relation to my retirement?
Think about how your current way of living may change in the future. Consider potential changes such as downsizing your home, traveling more, or pursuing new hobbies, as these will help estimate future expenses.
Why is it important to set specific retirement goals?
Establishing clear, measurable goals allows you to estimate costs associated with your retirement plans, such as travel or moving. This ensures your budget aligns with your objectives and helps create a personalized strategy for your family’s needs.
How should I factor in my family’s needs when planning for retirement?
If you have children, consider their future needs, such as education or support during their early adult years. This will help determine additional savings needed to secure their economic futures.
Why is documenting my retirement goals important?
Creating a written document outlining your future objectives and lifestyle needs serves as a reference point for your planning. It ensures that your goals remain at the forefront of your approach. Notably, only 15% of women have a written plan for their financial future, highlighting the importance of documentation.
How can Bright Advisers assist in my retirement planning?
Bright Advisers helps families create personalized strategies that incorporate integrated tax planning and investment approaches designed for families with young children, ensuring your retirement goals align with your family’s needs.
List of Sources
- Define Your Retirement Goals and Lifestyle Needs
- 106 Revealing Retirement Statistics – Curio Wealth (https://curiowealth.com/106-revealing-retirement-statistics)
- How much will you spend in retirement? | Fidelity (https://fidelity.com/viewpoints/retirement/spending-in-retirement)
- Retirement Cost of Living Guide: Insights & Considerations (https://westernsouthern.com/retirement/retirement-cost-of-living)
- 50+ Essential Retirement Statistics for 2026: Demographics & More (https://annuity.org/retirement/retirement-statistics)
- Average Retirement Savings by Age | Guardian (https://guardianlife.com/retirement/savings-by-age)
- Assess Income Sources and Estimate Retirement Expenses
- Average Retirement Income 2026: By Age, State & Source (https://randallwealthgroup.com/average-retirement-income)
- Retirement Statistics And Income Planning: How Much You Need (https://harborlifesettlements.com/retirement-statistics)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- 2026 Retirement Statistics: Average Savings Fall $500,000 Short of What Retirees Say They Need | Clever Real Estate (https://listwithclever.com/research/retirement-statistics)
- Average Retirement Income (and How to Figure Out Your Own Gap) (https://annuity.org/retirement/planning/average-retirement-income)
- Determine a Safe Withdrawal Rate for Your Savings
- What’s a Safe Retirement Withdrawal Rate for 2026? (https://morningstar.com/retirement/whats-safe-retirement-withdrawal-rate-2026)
- The 4% Rule: How Much Can You Spend in Retirement? (https://schwab.com/learn/story/beyond-4-rule-how-much-can-you-spend-retirement)
- Safe Withdrawal Rate for Early Retirees (https://madfientist.com/safe-withdrawal-rate)
- How long will my savings last? | Fidelity (https://fidelity.com/viewpoints/retirement/how-long-will-savings-last)
- What Is a Safe Withdrawal Rate in Retirement? | Alaska Wealth Advisors (https://akwealthadvisors.com/what-is-a-safe-withdrawal-rate-in-retirement)
- Utilize Financial Tools and Professional Guidance
- Best Retirement Calculator (https://financialmentor.com/calculator/best-retirement-calculator)
- Top Retirement Planning Software with Savings and Retirement Calculators 2026 (https://quicken.com/blog/top-retirement-planning-software-with-savings-and-retirement-calculators-2026?srsltid=AfmBOooN5_kTucnRvDVPjcduE8cvUJZHHptsTl4fl4-0ZW2qklvH7-p4)
- Financial Planning Tools, Calculators, and Resources (https://ml.com/personal-retirement-calculator.html)
- AARP Retirement Calculator (https://aarp.org/money/retirement/retirement-calculator)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading