

Overview
As a young parent, understanding your financial responsibilities can feel overwhelming. If you find yourself earning $100,000, it’s important to know that your total tax liability may be around $22,400. This figure includes federal, state, and possibly local taxes. Imagine the relief of knowing that this estimate is based on a thoughtful breakdown of federal tax brackets and relevant deductions, like the standard deduction, which can significantly ease your taxable income and overall tax burden.
We understand that navigating these financial waters can be challenging. Each step you take towards understanding your taxes is a step towards greater financial security for your family. By familiarizing yourself with these figures and how they impact your budget, you can make informed decisions that align with your family values.
Remember, you’re not alone in this journey. Together, we can explore the options that best suit your needs and help you manage your financial responsibilities with confidence. We’re here for you, ready to support you every step of the way.
Key Highlights:
- Individuals with a $100,000 income face federal income tax, state income tax, and possibly local taxes.
- Federal tax brackets for 2025 include 10%, 12%, 22%, and 24% rates based on income levels.
- The standard deduction for single filers in 2025 is $15,750, reducing taxable income.
- Total federal tax for a $100,000 income is calculated as $17,400, with an example state tax of $5,000 leading to a total tax liability of $22,400.
- Tax credits like the Earned Income Tax Credit and Child Tax Credit can significantly reduce tax bills.
- Exploring deductions such as the standard exemption and itemised expenses can lower tax obligations.
- Retirement contributions to accounts like 401(k)s can also decrease taxable income.
- The effective tax rate for a $100,000 income with a total tax of $22,400 is 22.4%.
- Regular evaluation of tax payments and effective tax rates is crucial for informed financial decision-making.
Introduction
Navigating tax obligations can often feel like wandering through a complex maze, especially for those earning $100,000 a year. This income level brings with it a variety of federal, state, and possibly local taxes, each carrying its own rules and rates. Imagine if you could delve into the intricacies of tax brackets, deductions, and credits to uncover opportunities to lessen your overall tax liability. It’s important to understand that with so many variables at play, there are effective strategies to minimize tax payments while maximizing your take-home income. Together, we can navigate this journey.
Understand Your Tax Obligations on $100,000 Income
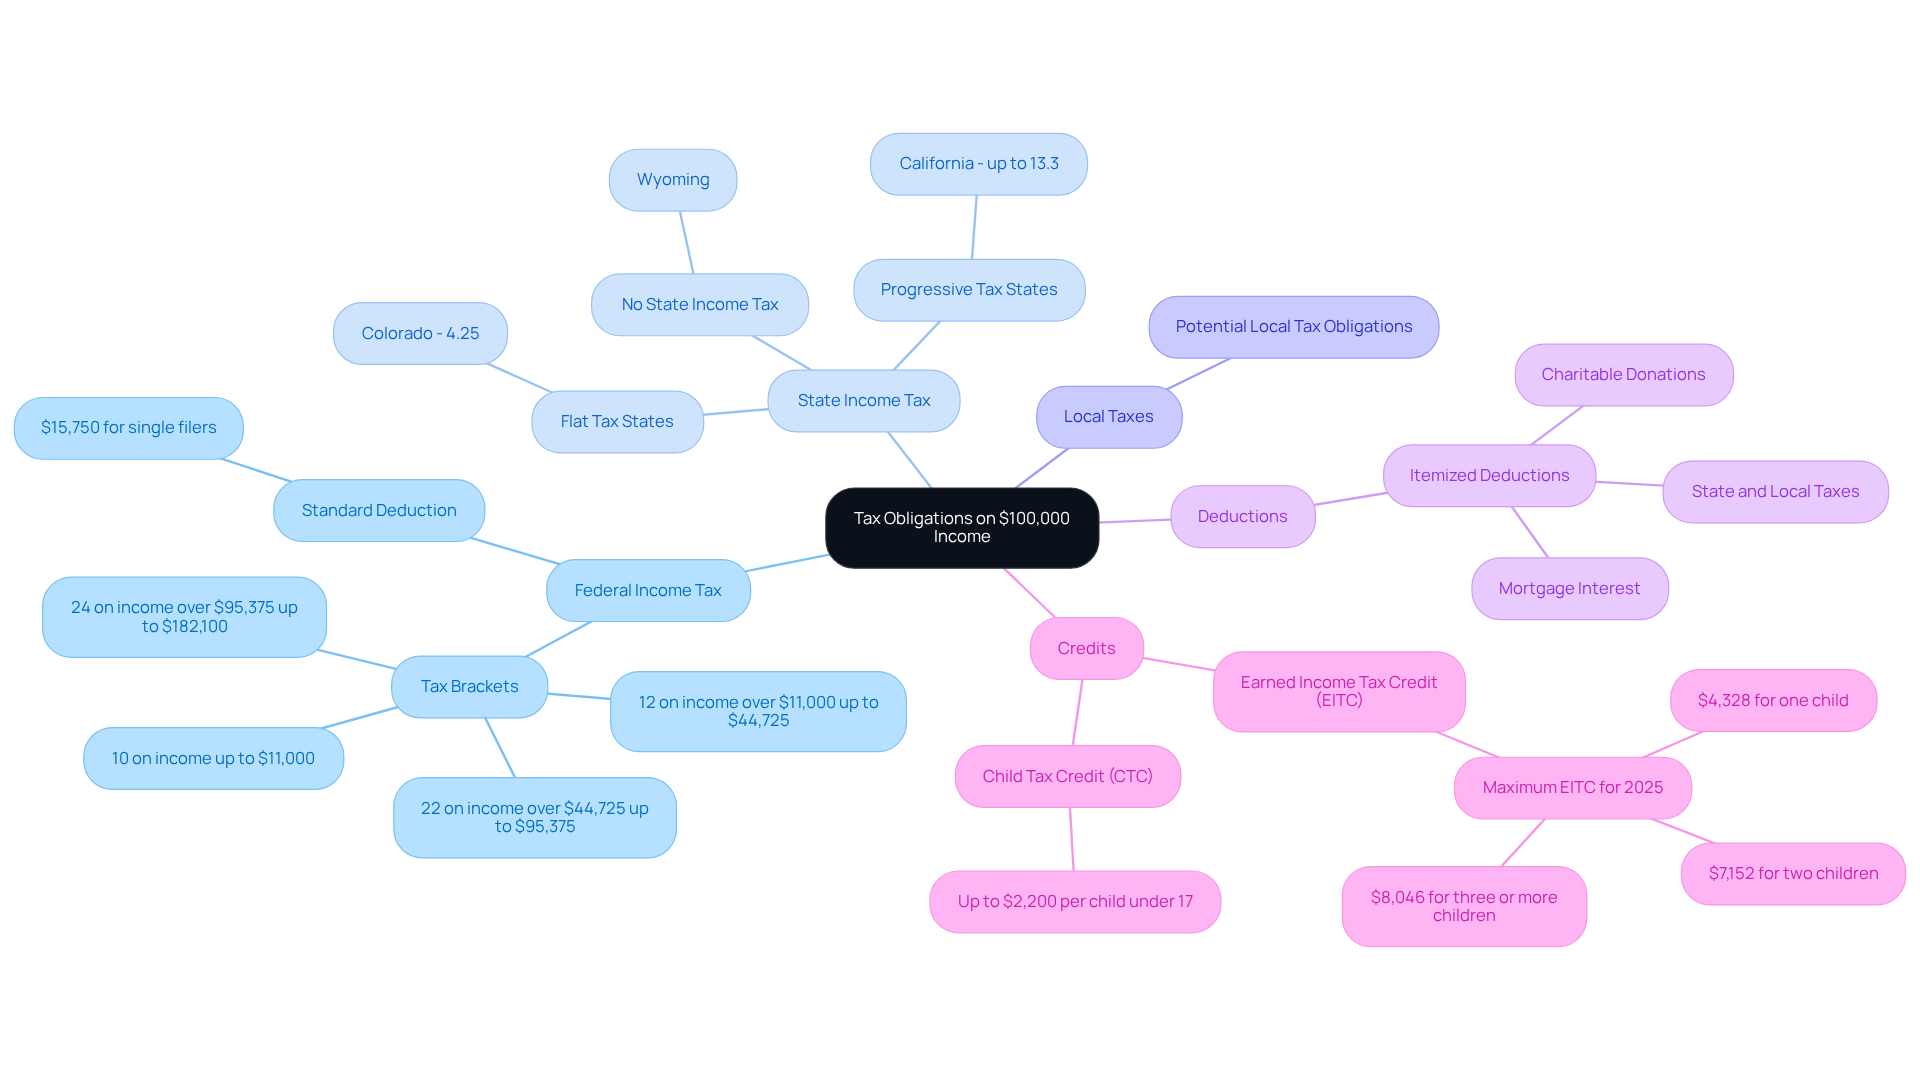
To start, it’s important to understand the different taxes that affect your income. In the United States, individuals often find themselves asking how much do I have to pay in taxes if I make 100k a year, as they encounter federal income tax, state income tax (which varies by state), and possibly local taxes. Federal income tax operates on a progressive system, where rates increase with income. For 2025, the federal tax brackets for a single filer are as follows:
- 10% on income up to $11,000
- 12% on income over $11,000 up to $44,725
- 22% on income over $44,725 up to $95,375
- 24% on income over $95,375 up to $182,100
Additionally, the standard deduction for single filers in 2025 is $15,750. This deduction reduces your taxable income and can significantly influence your overall tax liability.
Understanding these brackets is essential for estimating how much do I have to pay in taxes if I make 100k a year accurately. State tax rates can vary widely; some states impose a flat tax, while others use a progressive system similar to the federal one. For example, states like Colorado have a flat tax rate of 4.25%, while others, like California, have multiple brackets that can reach as high as 13.3% for high earners. Local taxes may also apply based on your location, adding another layer to your tax obligations.
Moreover, tax credits such as the Earned Income Tax Credit (EITC) and the Child Tax Credit (CTC) can further lower your tax bill. It’s essential to explore all available options. As tax expert Bella Avila points out, “Tax credits can reduce your tax bill on a dollar-for-dollar basis; they don’t affect what bracket you’re in.” Knowing your obligations is the first step toward managing your tax responsibilities effectively.
Imagine if you could maximize your deductions and credits. Consulting a tax professional can provide personalized guidance tailored to your unique situation. Together, we can navigate this journey, ensuring you receive the support you need to make informed financial decisions for your family.
Calculate Federal and State Taxes for $100,000 Income
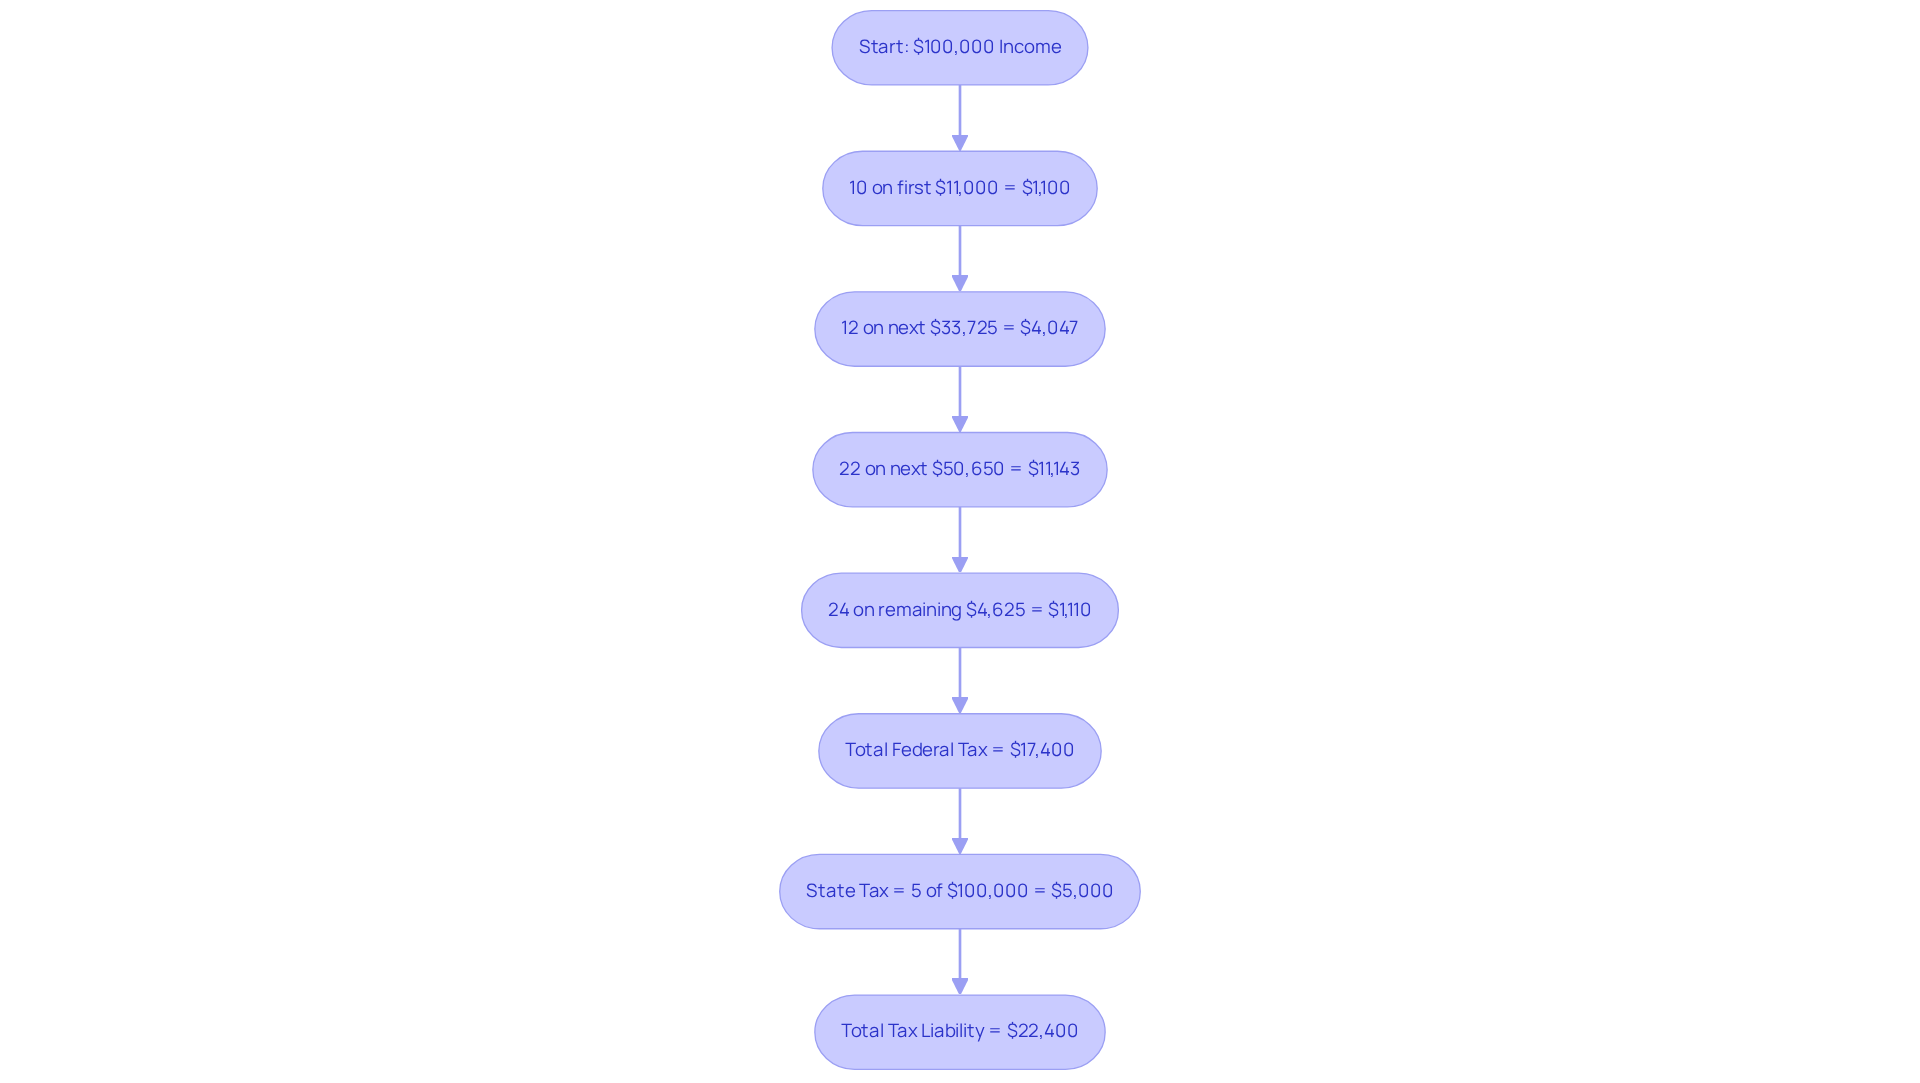
To determine your federal tax, it’s essential to apply the tax brackets to your earnings. For a $100,000 income, let’s break it down together:
-
Calculate the tax for each bracket:
- 10% on the first $11,000 = $1,100
- 12% on the next $33,725 ($44,725 – $11,000) = $4,047
- 22% on the next $50,650 ($95,375 – $44,725) = $11,143
- 24% on the remaining $4,625 ($100,000 – $95,375) = $1,110
-
Add these amounts together:
- Total federal tax = $1,100 + $4,047 + $11,143 + $1,110 = $17,400
Next, let’s consider your state tax. For instance, if you live in a state with a 5% income tax:
- State tax = 5% of $100,000 = $5,000
- Total tax liability:
- Federal tax + State tax = $17,400 + $5,000 = $22,400. This total helps you understand how much do I have to pay in taxes if I make 100k a year.
Understanding these calculations is crucial for young families like Jay and Emma, who are striving to reduce financial anxiety and optimize their resources. Imagine if families like Allison and Brian, who may be unaware of the financial opportunities they are missing due to inadequate tax planning, could benefit significantly from professional guidance. By partnering with experts like Bright Advisers, families can navigate the complexities of tax planning together, ensuring they maximize their wealth accumulation potential while securing their financial future. We’re here for you, guiding you every step of the way.
Identify Deductions and Credits to Reduce Tax Liability
To effectively reduce your tax liability and enhance your financial well-being, especially as a young parent, consider exploring available deductions and credits with the guidance of a professional.
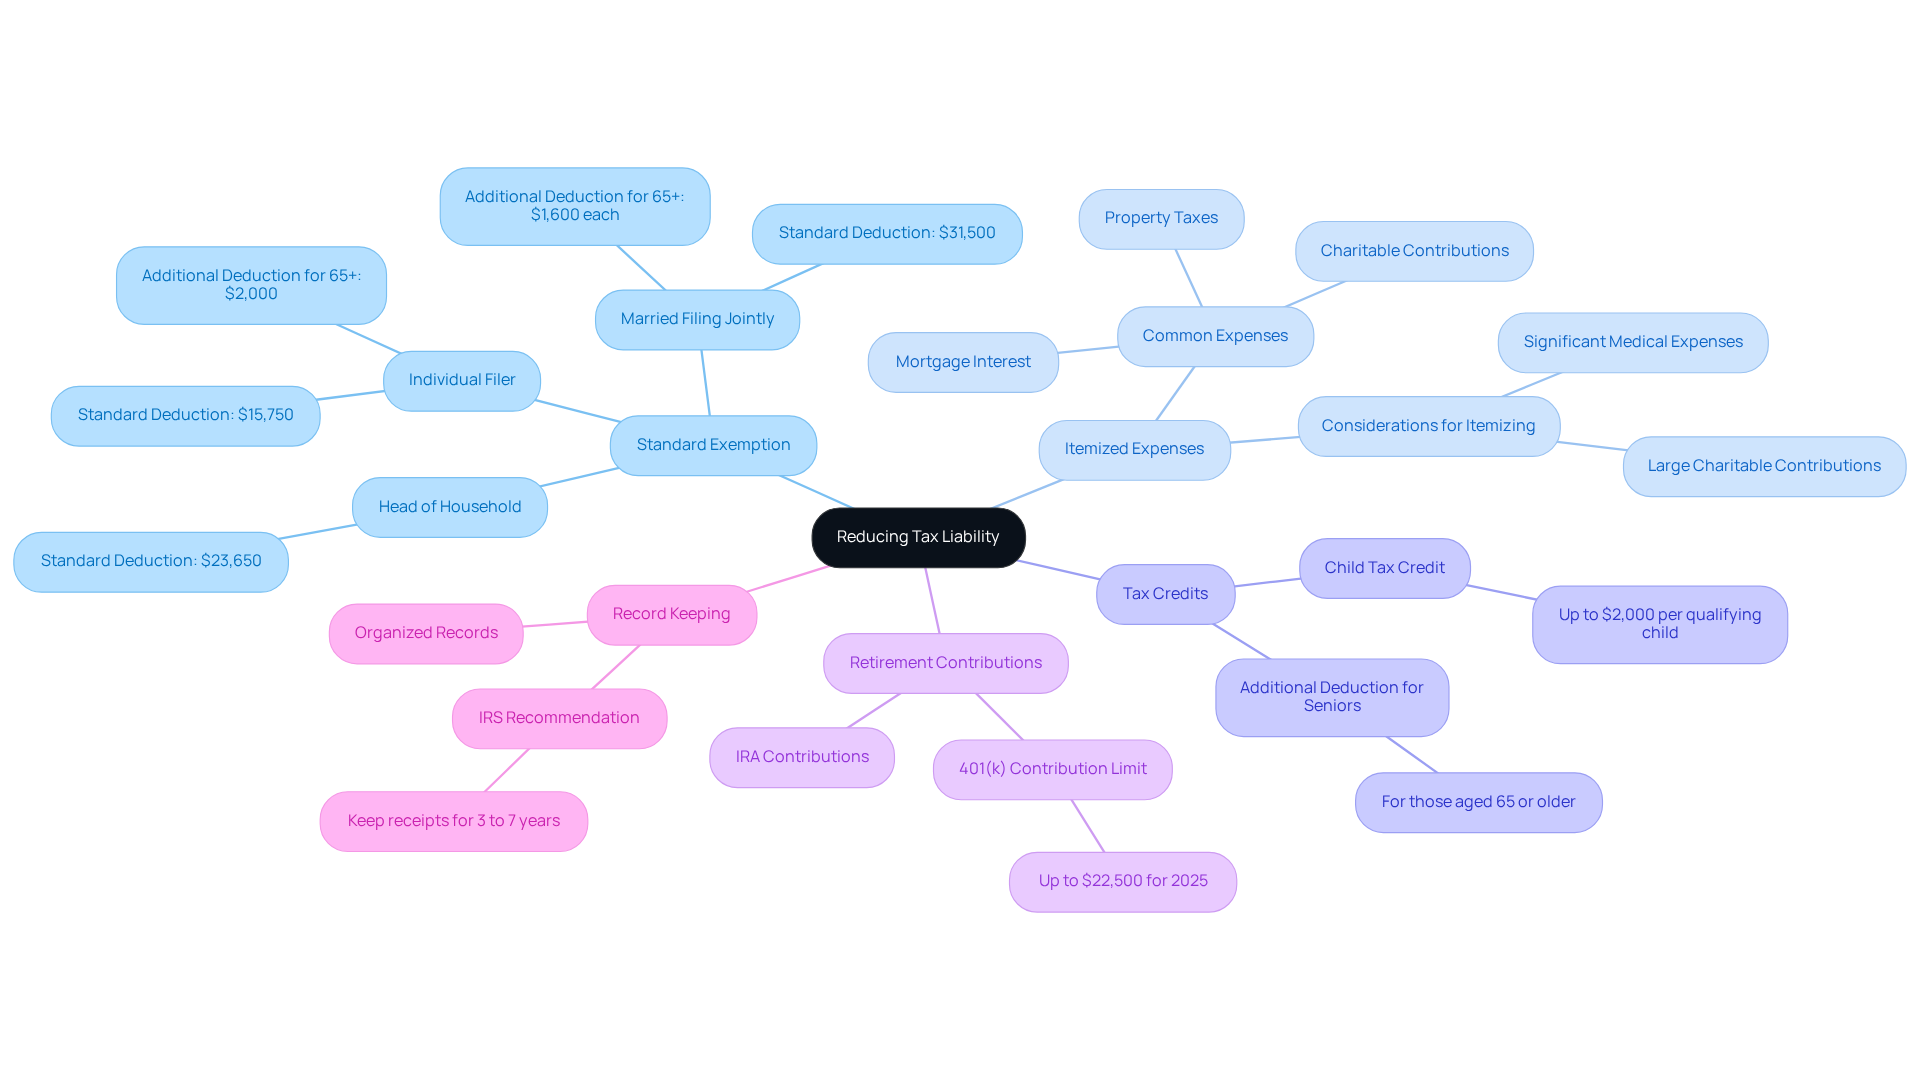
Standard Exemption: Imagine feeling a little lighter during tax season. For 2025, the standard exemption for an individual filer is $15,750. This amount can be subtracted from your taxable income, significantly lowering it. For married couples filing jointly, this allowance rises to $31,500, offering substantial tax relief. Additionally, if you or your spouse are aged 65 or older, you can claim an extra allowance of $2,000, further enhancing your tax relief.
Itemized Expenses: Now, think about your unique situation. If your itemized expenses surpass the standard allowance, it may be worthwhile to itemize. Common itemized expenses include:
- Mortgage interest
- Property taxes
- Charitable contributions
Evaluating these expenses annually can help you determine the best option for maximizing your tax benefits. It’s also important to understand that taxpayers with significant medical expenses or large charitable contributions may find itemizing more beneficial.
Tax Credits: Look for applicable tax credits that can make a real difference. For instance, the Child Tax Credit offers up to $2,000 per qualifying child, directly reducing your tax bill. Moreover, if you or your spouse are aged 65 or older, you can claim an additional deduction, enhancing your tax relief.
Retirement Contributions: Consider your future as well. Contributions to retirement accounts, like a 401(k) or IRA, can also reduce your taxable earnings. For 2025, you can contribute up to $22,500 to a 401(k), effectively lowering your taxable income dollar-for-dollar.
Record Keeping: It’s essential to stay organized. The IRS recommends keeping receipts for 3 to 7 years, especially if you plan to itemize expenses. Maintaining orderly records can be advantageous if you choose to alternate between the standard and itemized tax benefits in upcoming years.
By recognizing and applying these reductions and credits, you can significantly decrease your tax obligation, leading to the question of how much do I have to pay in taxes if I make 100k a year, ensuring more of your hard-earned money remains with you. As Mark Steber, Senior Vice President and Chief Tax Officer for Jackson Hewitt, wisely notes, “By taking advantage of the standard deduction, you can simplify the process, reduce the amount you owe the IRS, and keep more of your hard-earned money in your pocket.” Remember, seeking professional assistance can further enhance your ability to navigate these complexities and optimize your wealth accumulation potential. Together, we can navigate this journey.
Evaluate Total Tax Payments and Effective Tax Rate
To assess your overall tax contributions and effective tax percentage, consider the journeys of clients like Allison and Brian. They partnered with Bright Advisers to enhance their financial prospects through strategic tax planning, and their story could inspire you.
-
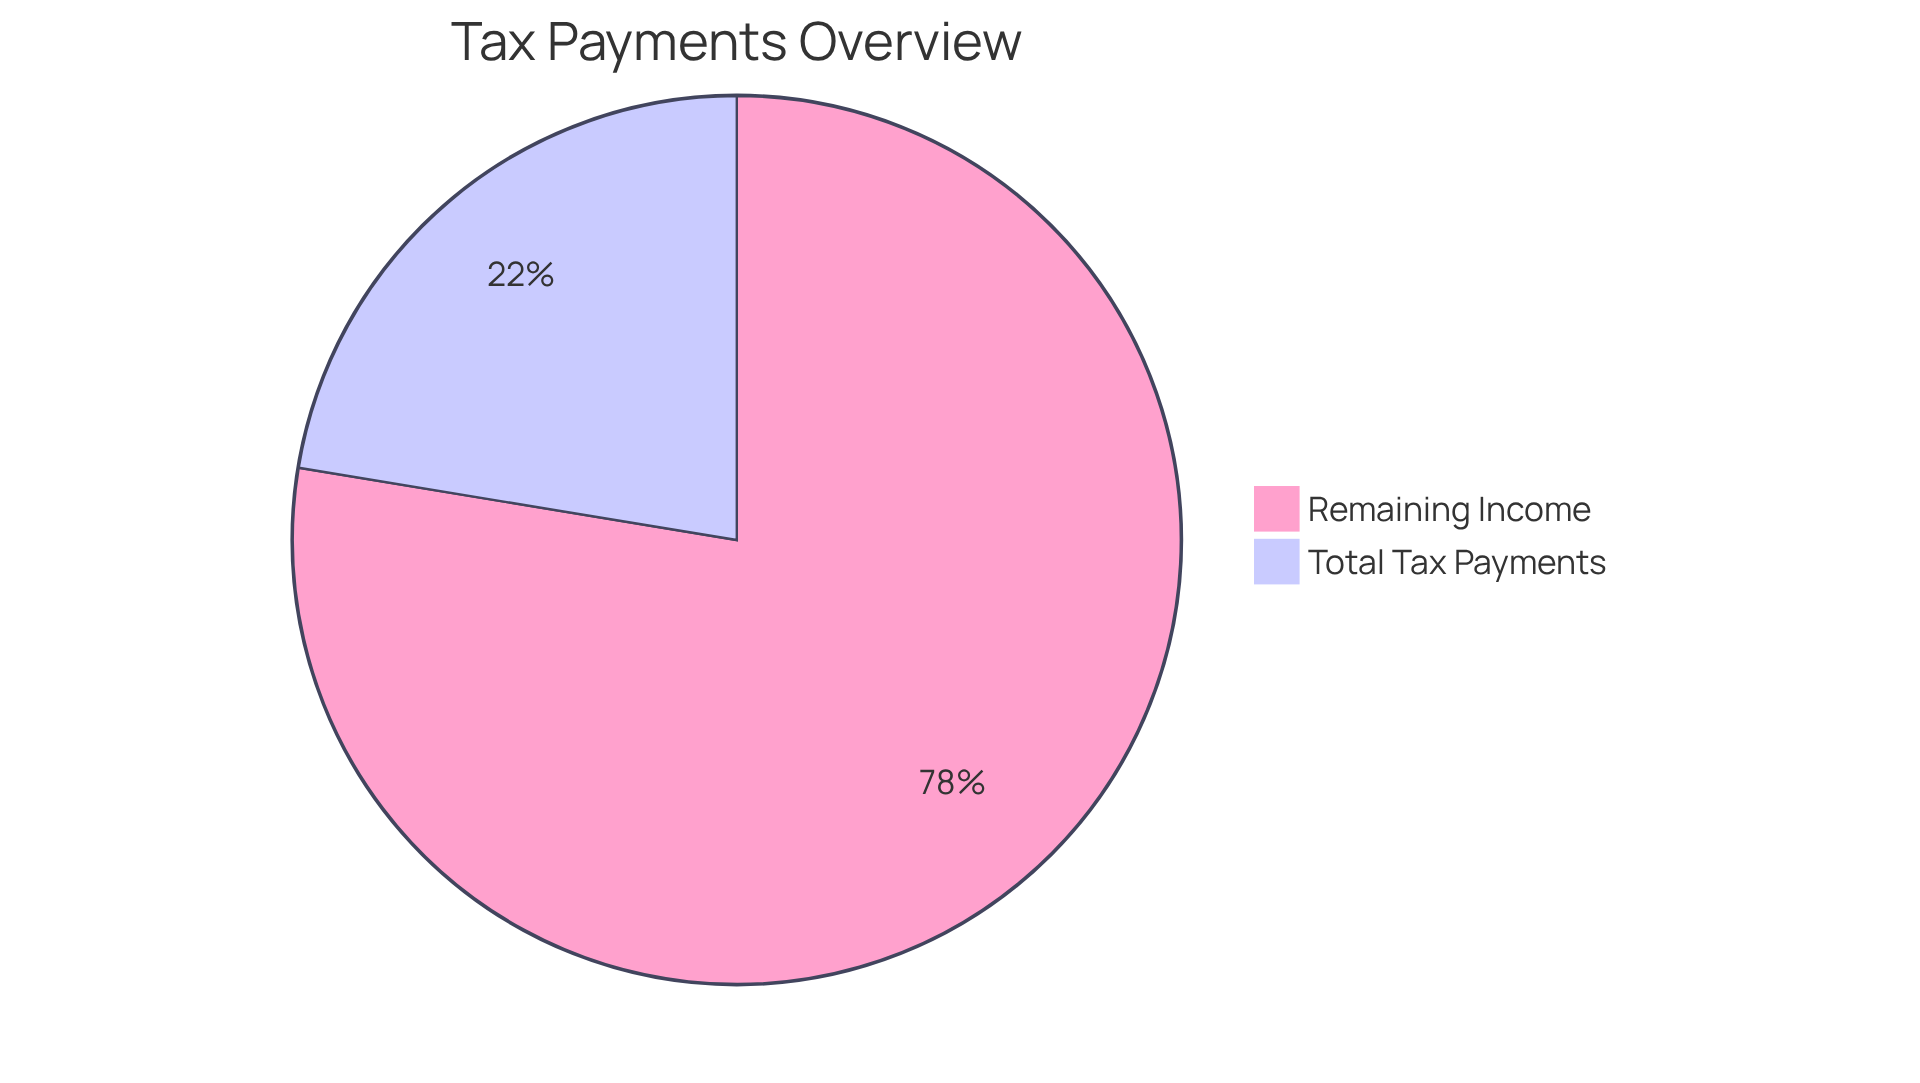
Total Tax Payments: From previous calculations, your total tax liability stands at $22,400.
-
Effective Tax Rate Calculation: The effective tax rate is determined by dividing your total tax payments by your total income:
- Effective Tax Rate = Total Tax Payments / Total Income = $22,400 / $100,000 = 0.224 or 22.4%.
- For context, if your taxable earnings were $100,000 and you want to know how much do I have to pay in taxes if I make 100k a year while paying $20,000 in levies, your effective levy percentage would be 20%.
-
Understanding Your Effective Tax Proportion: This figure reflects the average percentage at which your earnings are taxed. Understanding this percentage is crucial for your future financial strategy, as it helps you see how much of your earnings go to taxes. This insight can guide your decisions regarding investments, savings, and spending.
Allison and Brian were initially unaware of the financial opportunities they were missing due to inadequate tax planning. By collaborating with Bright Advisers, they optimized their tax situation, minimizing their tax liabilities while securing their children’s future through education funding, allowing them to retire sooner.
It’s also important to recognize how much do I have to pay in taxes if I make 100k a year, given the progressive nature of the U.S. tax system, where higher earnings lead to increased tax charges. For example, a married couple filing jointly with a taxable income of $120,000 would owe a total tax of $16,228, illustrating how effective tax amounts are computed in real-life situations.
By regularly evaluating your tax payments and effective tax rate, and considering the impact of tax deductions and credits, you can make informed decisions that align with your financial goals, just as Allison and Brian did. This ultimately empowers your family through strategic tax planning. Remember, we’re here to support you on this journey.
Conclusion
Understanding your tax obligations on a $100,000 income is essential for effective financial planning. This guide has shed light on the various taxes that apply, including federal, state, and local taxes, as well as the importance of deductions and credits that can significantly reduce your taxable income. By breaking down the federal tax brackets and illustrating how to calculate total tax liabilities, it becomes clear that being informed empowers you to navigate your financial responsibilities more effectively.
Key insights from this article highlight the necessity of recognizing tax brackets, utilizing deductions such as the standard exemption, and leveraging tax credits to minimize liabilities. Imagine if you could lower your tax burden and keep more of your hard-earned money for your family. The discussion on effective tax rates emphasizes evaluating your overall tax contributions in relation to your income. Engaging with tax professionals can provide tailored strategies that enhance your financial well-being, helping families like Jay and Emma or Allison and Brian make informed decisions that optimize their financial futures.
Ultimately, proactive tax planning is not just about understanding how much you owe; it’s about making strategic choices that preserve your income for what matters most. By staying informed and seeking guidance, you can navigate the complexities of the tax system, ensuring that you maximize your wealth accumulation potential. Together, we can embrace the resources available to you and take charge of your financial journey, ensuring that more of your income stays in your pocket for future investments and family needs.
Frequently Asked Questions
What taxes do I need to consider if I have an income of $100,000?
You need to consider federal income tax, state income tax, and possibly local taxes. Federal income tax operates on a progressive system, and state tax rates can vary widely depending on your location.
What are the federal income tax brackets for a single filer in 2025?
For 2025, the federal tax brackets for a single filer are:
- 10% on income up to $11,000
- 12% on income over $11,000 up to $44,725
- 22% on income over $44,725 up to $95,375
- 24% on income over $95,375 up to $182,100
How does the standard deduction affect my taxable income?
The standard deduction for single filers in 2025 is $15,750. This deduction reduces your taxable income, which can significantly influence your overall tax liability.
How do state income taxes vary?
State tax rates can vary widely; some states impose a flat tax while others use a progressive system. For example, Colorado has a flat tax rate of 4.25%, while California has multiple brackets that can reach as high as 13.3% for high earners.
What are tax credits, and how can they affect my tax bill?
Tax credits, such as the Earned Income Tax Credit (EITC) and the Child Tax Credit (CTC), can lower your tax bill on a dollar-for-dollar basis. They do not affect which tax bracket you fall into.
Should I consult a tax professional for my tax obligations?
Yes, consulting a tax professional can provide personalized guidance tailored to your unique situation, helping you maximize your deductions and credits effectively.
List of Sources
- Understand Your Tax Obligations on $100,000 Income
- 2024-2025 Federal Tax Brackets & Income Rates – NerdWallet (https://nerdwallet.com/article/taxes/federal-income-tax-brackets)
- Tax Brackets 2025: 2025 Federal Income Tax Rates (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/tax-brackets-2025)
- 2025 Tax Brackets (https://taxfoundation.org/data/all/federal/2025-tax-brackets)
- Tax Laws and Tax Brackets 2025 | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/tax-brackets.html)
- 2025 Federal Income Tax Brackets and Other 2025 Tax Rules | Bipartisan Policy Center (https://bipartisanpolicy.org/explainer/2025-federal-income-tax-brackets-and-other-2025-tax-rules)
- Identify Deductions and Credits to Reduce Tax Liability
- Standard deduction 2025: What it is and how it works | Fidelity (https://fidelity.com/learning-center/smart-money/standard-deduction)
- Standard Deduction 2024-2025: Amounts, How It Works – NerdWallet (https://nerdwallet.com/article/taxes/standard-deduction)
- 2025 Tax Brackets (https://taxfoundation.org/data/all/federal/2025-tax-brackets)
- Tax Year 2025 Standard Deduction (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/2025-standard-deduction)
- Evaluate Total Tax Payments and Effective Tax Rate
- Effective Tax Rate: How It’s Calculated and How It Works (https://investopedia.com/terms/e/effectivetaxrate.asp)
- Marginal vs. Effective Tax Rate: What’s The Difference? | Bankrate (https://bankrate.com/taxes/marginal-vs-effective-tax-rate)
- 2024-2025 Federal Tax Brackets & Income Rates – NerdWallet (https://nerdwallet.com/article/taxes/federal-income-tax-brackets)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading