

Overview
Navigating the world of Employee Stock Purchase Plans (ESPPs) can feel overwhelming, especially when it comes to avoiding double taxation.
It’s important to understand that:
- The discount you receive is treated as ordinary income.
- Holding onto your shares for the necessary periods can help you qualify for lower capital gains tax rates.
Imagine if you could maximize your financial benefits while caring for your family’s future.
Keeping detailed records and consulting with tax professionals can make a significant difference in your journey.
Utilizing tax-advantaged accounts is another way to help your family thrive amidst the complexities of ESPP taxation.
Remember, you’re not alone in this; we’re here for you, ready to support you as you navigate these financial decisions.
Key Highlights:
- Employee Stock Purchase Plans (ESPPs) allow employees to buy company stock at a discount, often up to 15%.
- Understanding the specific conditions and rules of an ESPP is crucial for maximising benefits and minimising tax liabilities.
- The discount received on stock purchases is taxed as ordinary income, and profits from sales incur capital gains tax.
- Holding shares for over one year from purchase and two years from the grant date can qualify for lower long-term capital gains tax rates.
- Keeping detailed records of purchases and sales is essential for accurate tax reporting.
- Consulting a tax professional can provide personalised guidance on maximising deductions and credits related to ESPPs.
- Utilising tax-advantaged accounts for holding ESPP shares can defer taxes and enhance financial flexibility.
- Resources such as tax preparation software, specialised consultants, and online calculators can aid in managing ESPPs effectively.
Introduction
Navigating the intricate world of Employee Stock Purchase Plans (ESPPs) can feel like both an exciting opportunity and a daunting challenge, especially for parents striving to secure their family’s financial future. These plans offer a unique chance to acquire company stock at a discounted rate, yet they also come with complex tax implications that can lead to double taxation if not managed carefully.
Imagine if you could maximize the benefits of ESPPs while minimizing your tax burdens. This guide provides essential strategies and insights to help you effectively manage your ESPPs and avoid the pitfalls of double taxation, ensuring a brighter financial outlook for your loved ones.
We’re here for you as you embark on this journey together.
Understand Employee Stock Purchase Plans (ESPPs)
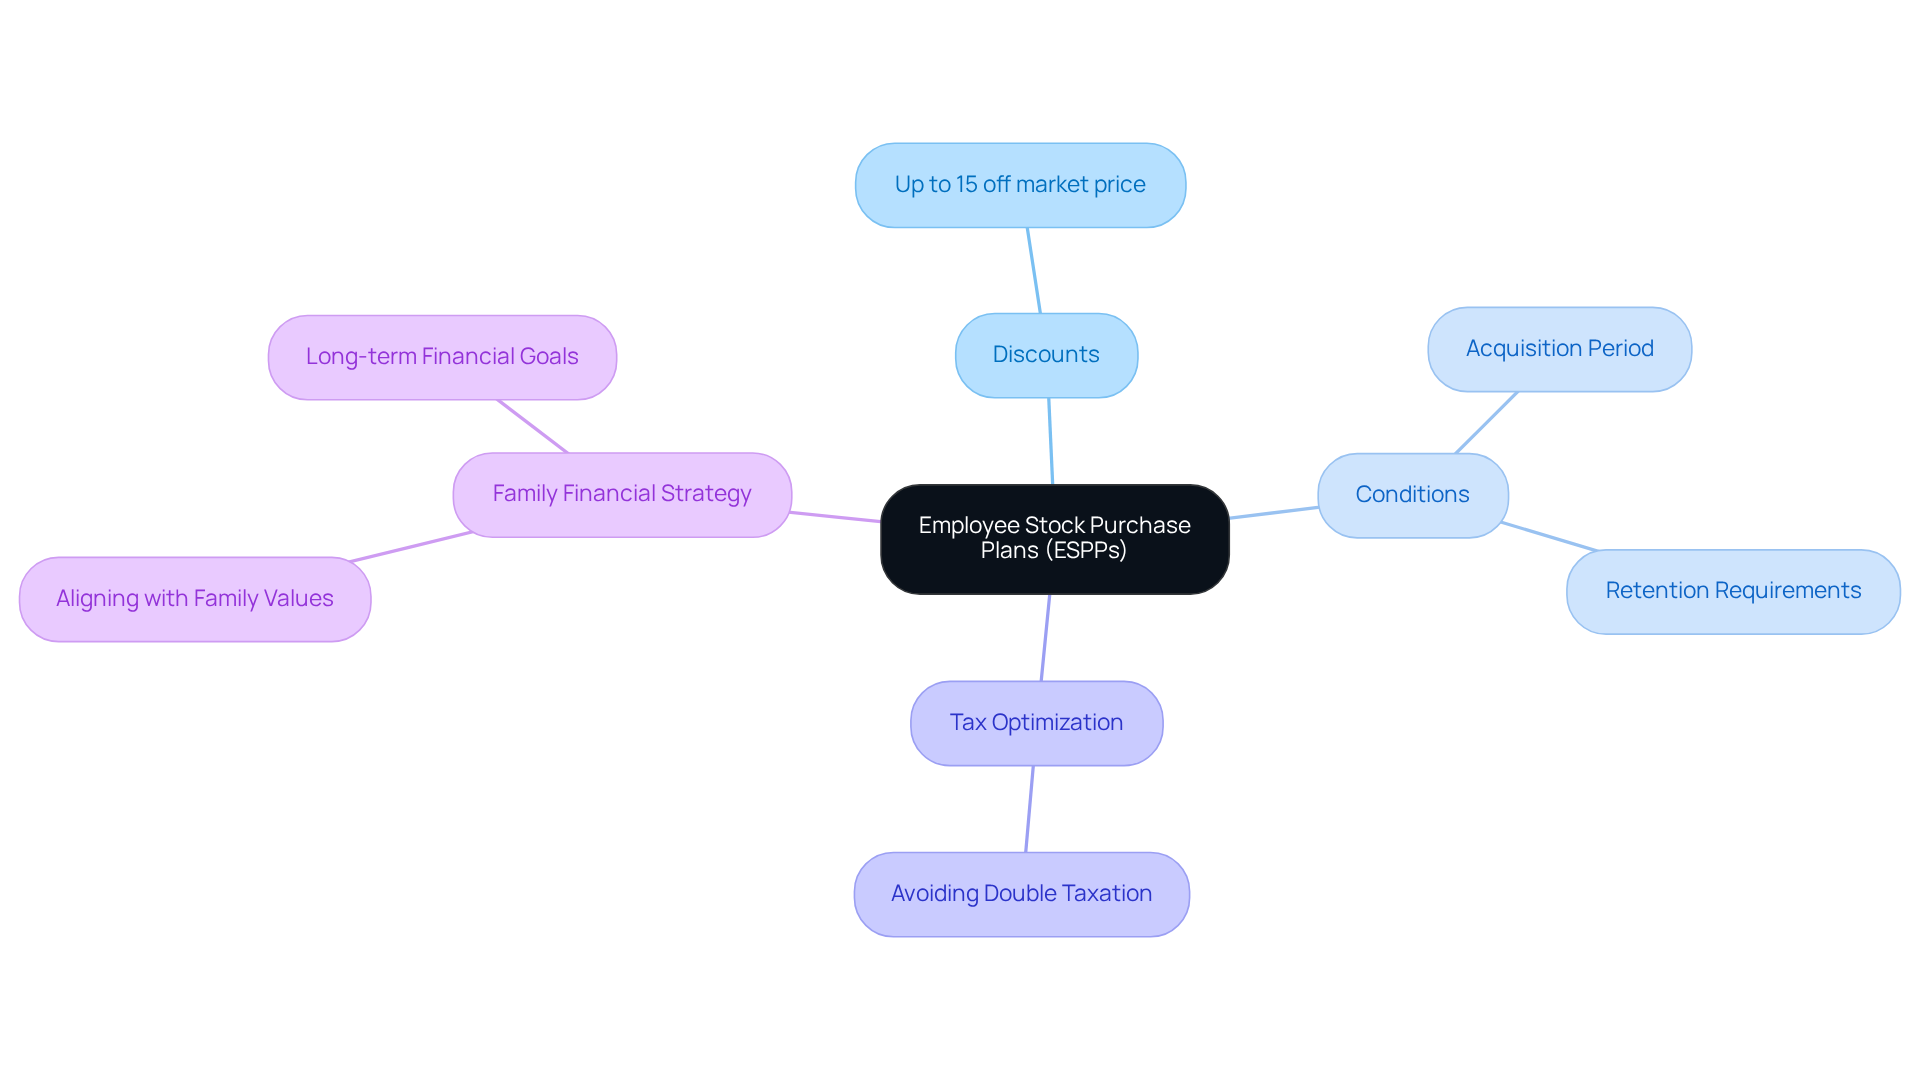
An Employee Stock Purchase Program offers a wonderful opportunity for you and your family to acquire shares of your company’s stock at a reduced price, often through convenient payroll deductions. Imagine being able to buy shares at a discount of up to 15% off the market price! These programs are designed to promote employee ownership, which can play a significant role in your family’s financial strategy.
It’s important to understand the specific conditions of your employee stock purchase plan, such as the acquisition period and any retention requirements. This knowledge can help you optimize the advantages while minimizing tax consequences, particularly in understanding how do I avoid double tax on espp. Familiarizing yourself with the plan’s rules is crucial, as they can vary significantly between companies.
Remember, we’re here for you as you navigate these financial decisions. Together, we can explore how these opportunities align with your family’s values and goals, ensuring a brighter financial future for you and your loved ones.
Explore Tax Implications of ESPPs
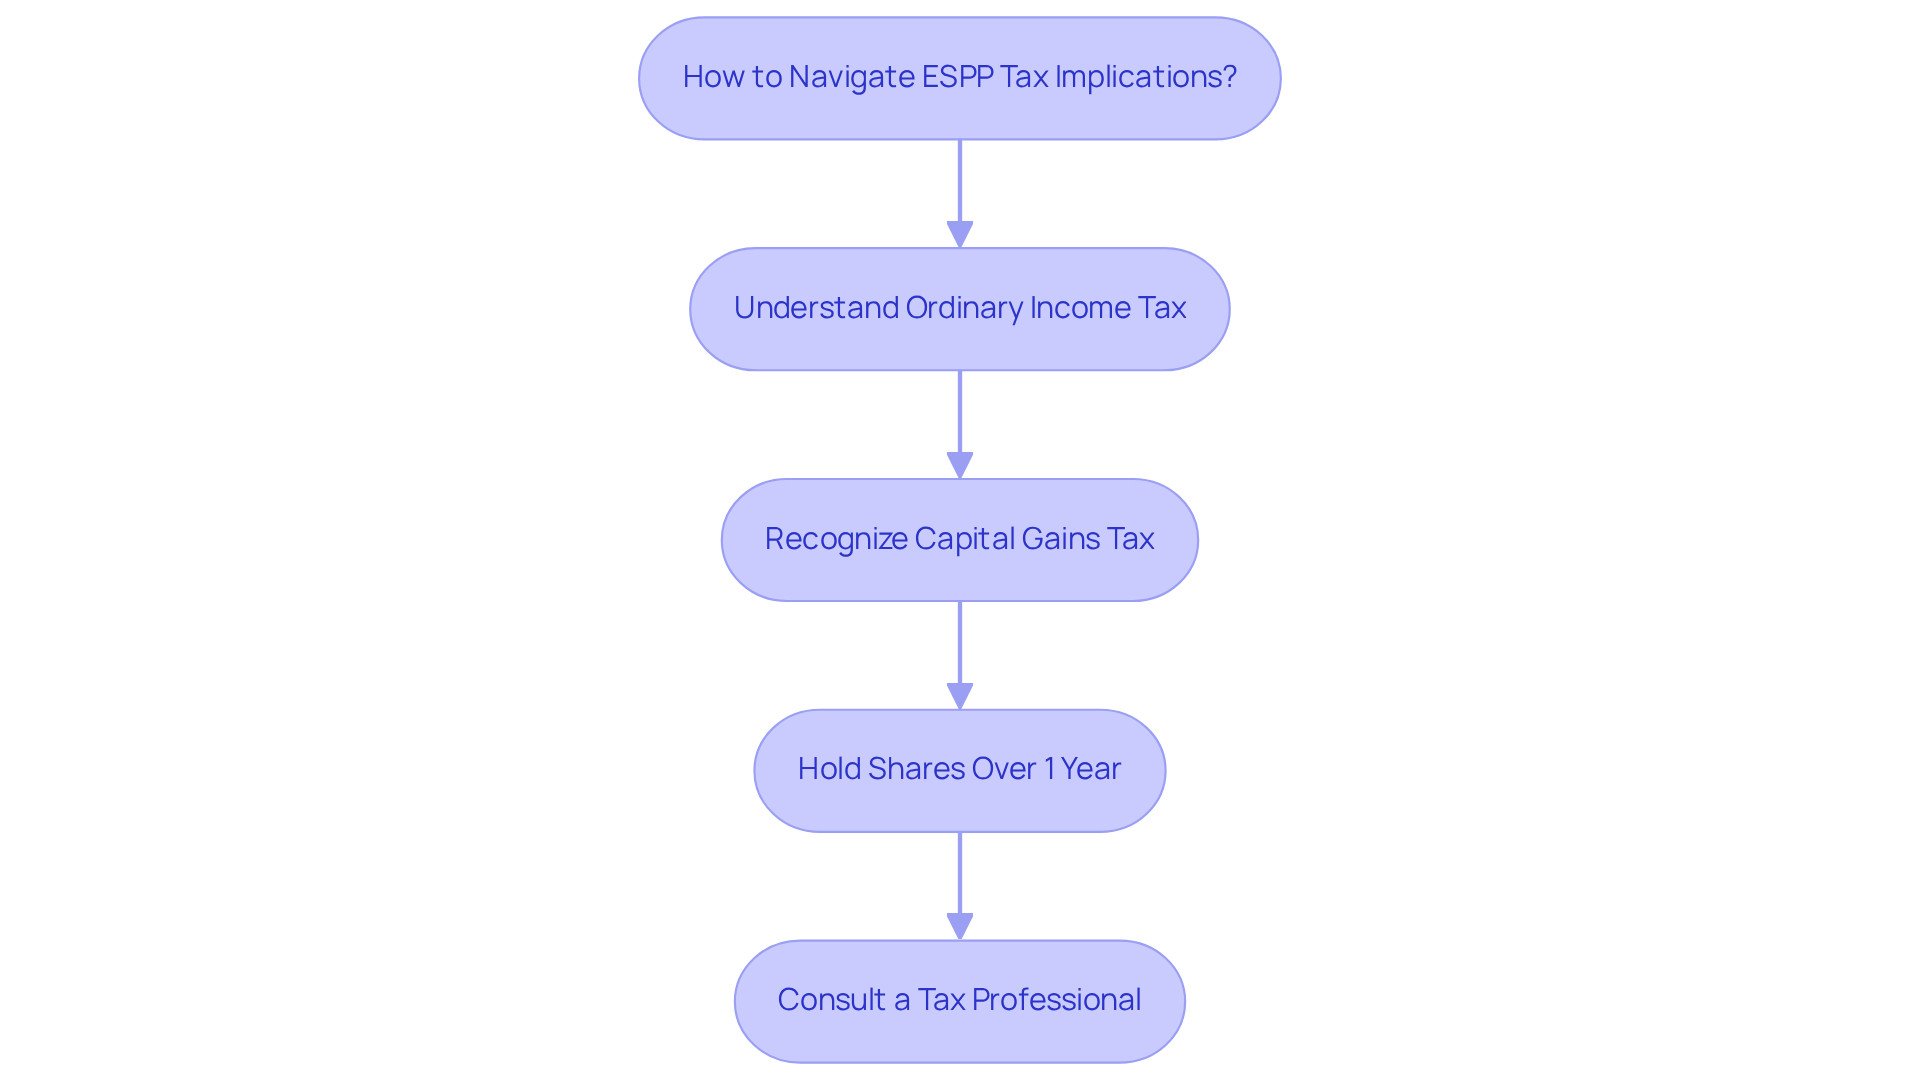
Navigating the complexities of an Employee Stock Purchase Plan (ESPP) can feel overwhelming, particularly for young parents striving to secure their family’s financial future. It’s essential to understand that the discount you receive on stock purchases is considered ordinary income, subject to your standard income tax rate when you sell those assets. For instance, if you acquire stocks at an $8 discount each, that amount is taxed as regular income. Additionally, any profits from selling the stock will incur capital gains tax. If you sell your stocks within a year of buying them, those profits will be taxed as short-term capital gains, which often come with higher rates than long-term capital gains. This intricate web of taxation can lead to double taxation, raising the issue of how do I avoid double tax on espp, where you may find yourself paying taxes on the same income multiple times.
Imagine Sarah, who sold her employee stock plan holdings for $81 after purchasing them for $45, realizing a long-term capital gain of $28 each. However, she faced the reality that the $8 discount she received was taxed as ordinary income. To learn how do I avoid double tax on espp, it’s crucial to hold shares for more than one year from the purchase date and more than two years from the grant date to qualify for favorable tax treatment. Seeking guidance from a tax consultant can provide personalized support, helping young parents make informed decisions about their participation in employee stock purchase plans and their tax obligations.
Statistics reveal that around 25 to 30% of households live paycheck-to-paycheck, as estimated by Bank of America. This reality can influence their willingness to engage in ESPPs, adding another layer of complexity to family financial planning. Moreover, applying the correct cost basis for your employee stock purchase plan holdings is vital to prevent overpayment of taxes on sales. Remember to keep essential documents for tax reporting, such as:
- Form W-2
- Form 3922
- Form 1099-B
These documents will help ensure accurate tax submission and reporting of earnings from your stock shares.
By understanding these tax implications and seeking professional guidance, young families can enhance their financial security and alleviate anxiety surrounding investment decisions. Together, we can navigate this journey toward a more secure financial future for you and your loved ones.
Implement Strategies to Avoid Double Taxation
To help you navigate the complexities of double taxation on your ESPP, here are some thoughtful strategies to consider:
-
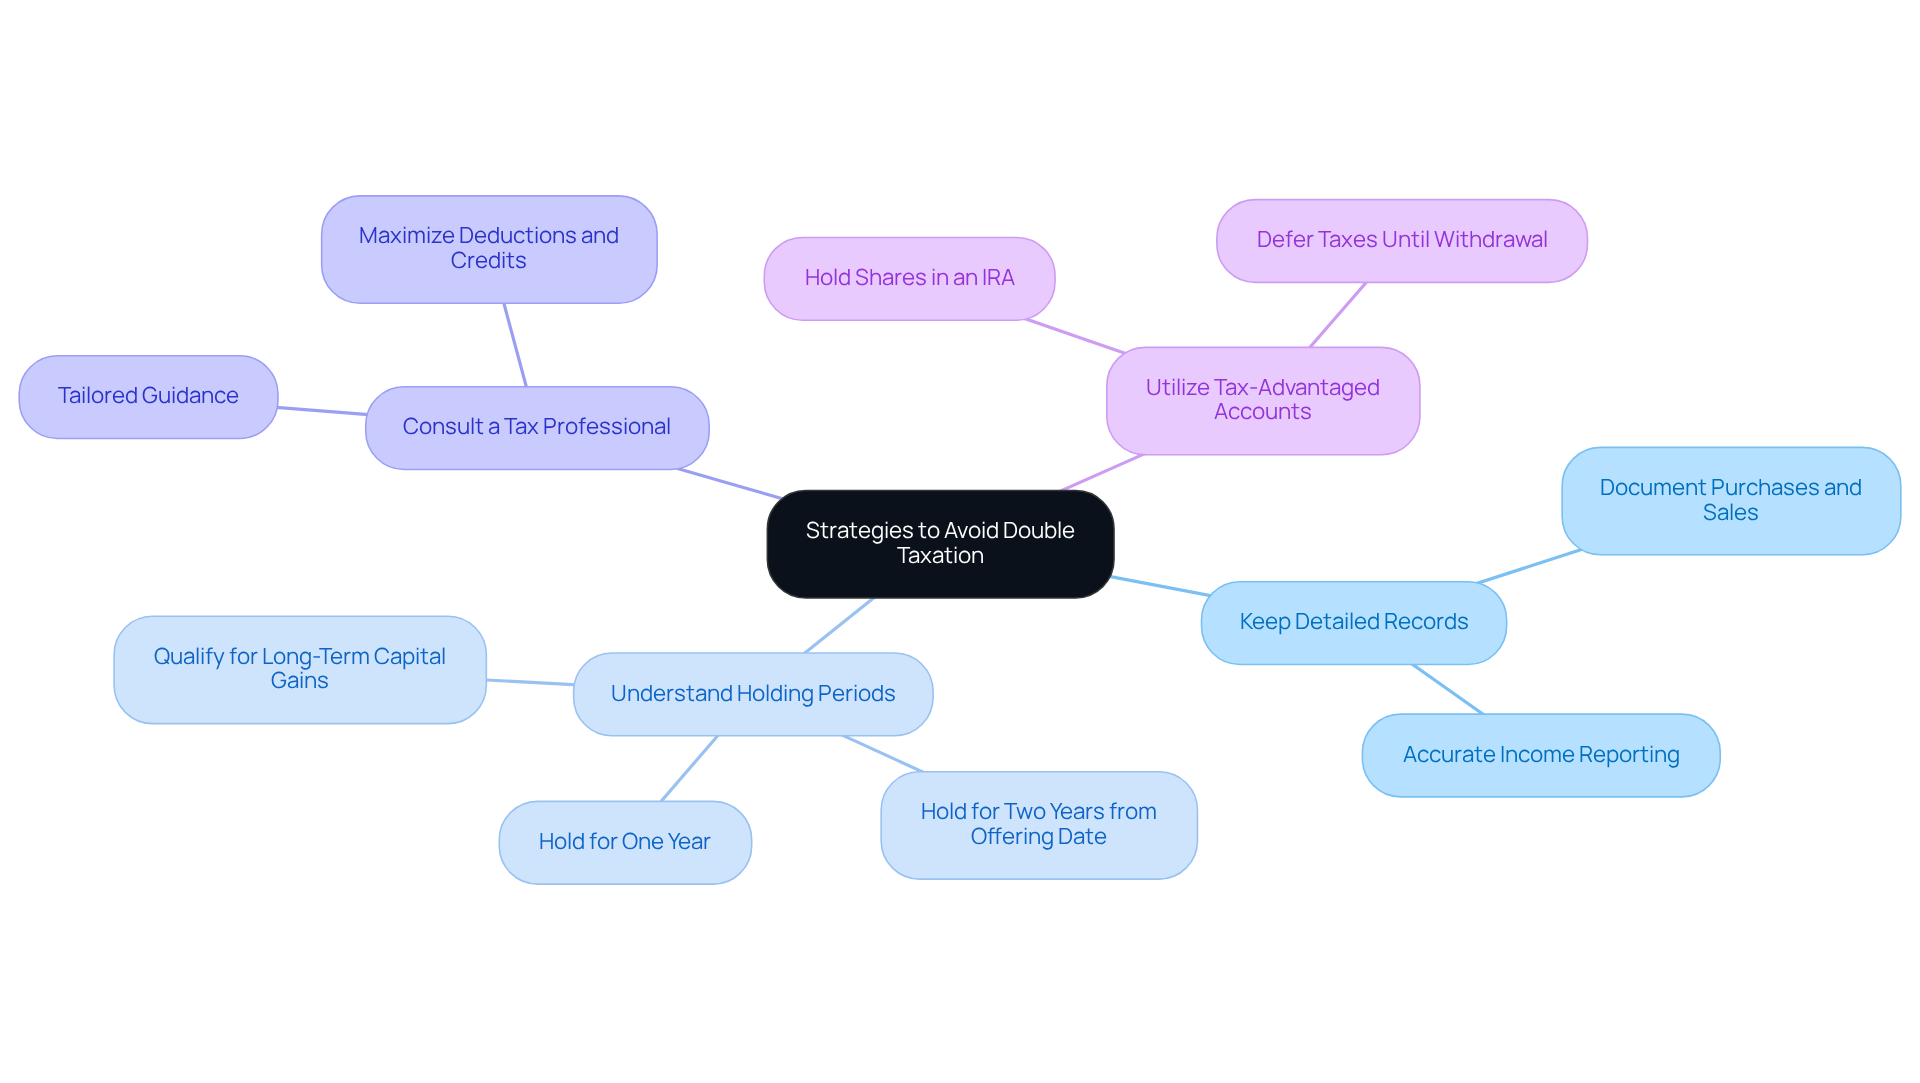
Keep Detailed Records: Imagine having all your purchases, sales, and asset prices neatly documented. This not only simplifies your life but ensures you can report your income accurately on your tax return, giving you peace of mind.
-
Understand Holding Periods: It’s important to understand that if you hold onto your stocks for at least one year after acquiring them and two years from the offering date, you may qualify for long-term capital gains tax rates. These rates are typically lower than standard income tax rates, which could mean more savings for your family.
-
Consult a Tax Professional: Navigating tax laws can feel overwhelming. Consulting with a tax advisor can provide you with tailored guidance, helping you make the most of available deductions and credits, so you can focus on what truly matters—your family.
-
Utilize Tax-Advantaged Accounts: If it’s feasible for you, consider holding your employee stock purchase plan shares in a tax-advantaged account like an IRA. This allows you to defer taxes until withdrawal, providing you with more flexibility in your financial planning.
By embracing these strategies, you can significantly reduce your tax burden and understand how do I avoid double tax on espp, thereby enhancing the benefits of your employee stock purchase plan. Remember, we’re here for you, supporting you every step of the way as you prioritize your family’s financial future.
Utilize Resources for Effective ESPP Management
To effectively manage your ESPP, you may wonder how do I avoid double tax on ESPP, and consider some valuable resources inspired by the success story of Allison and Brian, who transformed their financial future with Bright Advisers.
-
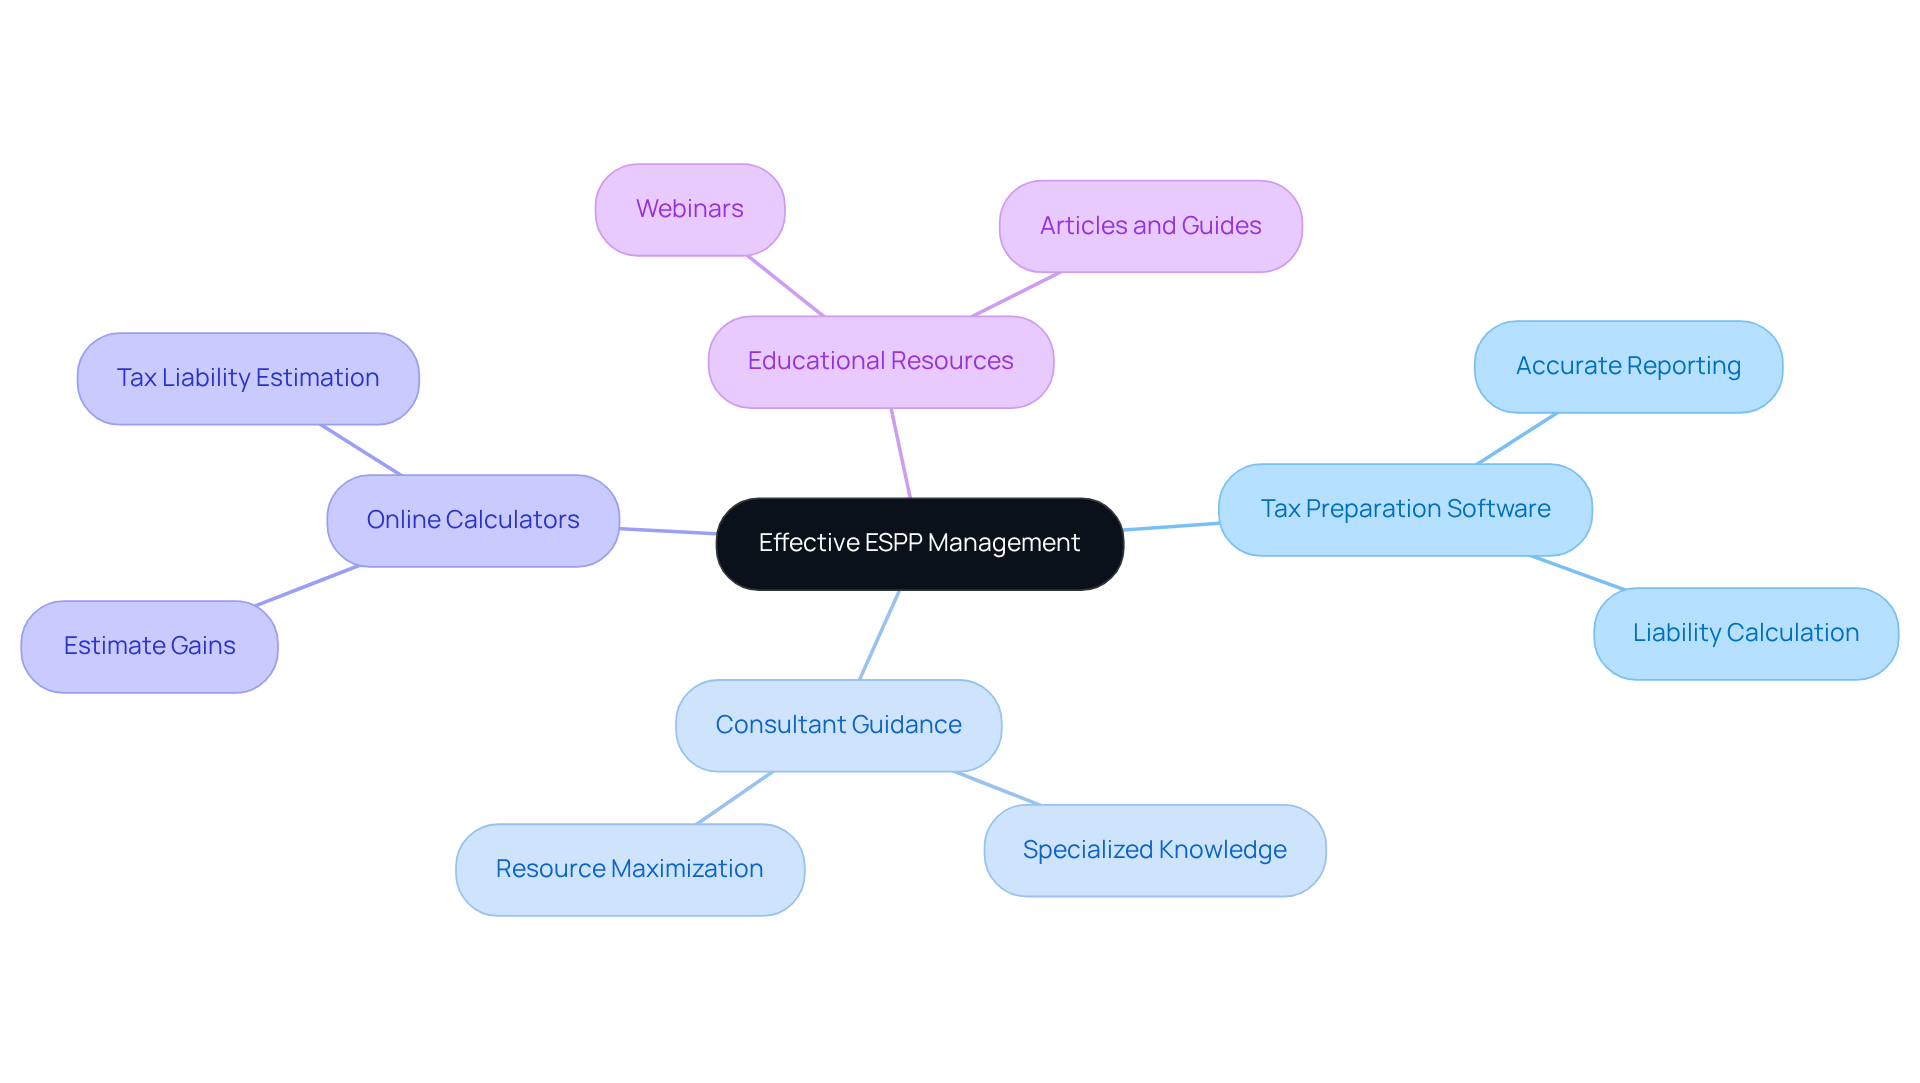
Imagine if you could simplify your tax process. Tax preparation software can be your ally, helping you accurately report your ESPP transactions and calculate your tax liabilities. This way, you can optimize your tax situation and focus on what truly matters—your family.
-
Think about the guidance you deserve. Engaging with a consultant who specializes in employee benefits and tax planning can be transformative. Bright Advisers guided Allison and Brian through the complexities of their monetary landscape, ensuring they maximized their resources and secured their children’s future.
-
What if you could visualize your financial journey? Online calculators are a great tool to estimate your potential gains and tax liabilities from your employee stock purchase plan. This method assisted Allison and Brian in making informed choices regarding their economic future, helping them retire earlier and enjoy precious moments with their loved ones.
-
Knowledge is power. Take advantage of educational resources like webinars, articles, and guides that explain ESPP tax implications and strategies for maximizing benefits. Websites such as TurboTax and Investopedia offer valuable insights that complement the guidance provided by professionals.
By leveraging these resources, you can enhance your understanding of ESPPs and make informed decisions that align with your family’s financial goals, just as Allison and Brian did with the help of Bright Advisers. Remember, together, we can navigate this journey toward a secure future for your family.
Conclusion
Navigating the complexities of Employee Stock Purchase Plans (ESPPs) is crucial for parents who wish to secure their family’s financial future. By understanding the nuances of these plans, including tax implications and strategies to avoid double taxation, families can make informed decisions that enhance their financial well-being.
Imagine keeping detailed records and understanding holding periods—these key insights empower families to maximize the benefits of their ESPP while minimizing the tax burden. Consulting with tax professionals can also provide invaluable support. Additionally, utilizing resources such as tax preparation software and educational materials can further simplify managing ESPPs.
Ultimately, taking proactive steps to understand and manage ESPPs is essential for families aiming to build a secure financial future. By leveraging available tools and professional guidance, parents can transform the complexities of ESPPs into opportunities for growth and stability. Together, we can navigate this journey, alleviating financial anxiety and paving the way for a brighter tomorrow for your loved ones.
Frequently Asked Questions
What is an Employee Stock Purchase Plan (ESPP)?
An Employee Stock Purchase Plan (ESPP) is a program that allows employees to acquire shares of their company’s stock at a reduced price, often through payroll deductions.
How much of a discount can employees receive through an ESPP?
Employees can buy shares at a discount of up to 15% off the market price through an ESPP.
What are the benefits of participating in an ESPP?
Participating in an ESPP promotes employee ownership, which can significantly contribute to a family’s financial strategy.
What should employees understand about their specific ESPP?
Employees should understand the specific conditions of their ESPP, including the acquisition period and any retention requirements, to optimize benefits and minimize tax consequences.
How can employees avoid double taxation on ESPP shares?
Familiarizing oneself with the rules of the ESPP is essential, as understanding these rules can help employees avoid double taxation on shares acquired through the plan.
Why is it important to know the rules of an ESPP?
The rules of an ESPP can vary significantly between companies, so knowing them is crucial for making the most of the plan’s advantages.
List of Sources
- Explore Tax Implications of ESPPs
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading