

Overview
This article serves as a heartfelt guide for families looking to understand the value of Restricted Stock Units (RSUs). It gently emphasizes the importance of grasping vesting schedules, fair market value, and tax implications. Imagine if you could navigate these complexities with confidence!
By outlining a step-by-step process for calculating RSU value, the article invites you to take charge of your financial future. It highlights the necessity of proactive financial planning and encourages you to monitor stock performance, ensuring that your family’s wealth is managed effectively.
Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Key Highlights:
- RSUs are a form of equity compensation that guarantees stock units to employees upon meeting specific vesting conditions.
- A vesting schedule dictates when employees gain access to their RSUs, typically with a one-year cliff and gradual annual vesting.
- The value of RSUs is tied to the company’s stock price, with their worth assessed at the fair market value (FMV) upon vesting.
- Once vested, RSUs are taxed as ordinary income based on their FMV, with a federal withholding rate of 22% for amounts up to $1 million.
- State taxes may also apply, and capital gains tax is incurred on any increase in value if the shares are sold after vesting.
- Families should develop a comprehensive financial plan that incorporates RSUs, monitor stock performance, and diversify their investment portfolios.
- Proactive tax planning and education about RSUs can help families manage their financial responsibilities and optimise their overall wealth.
Introduction
Understanding the value of Restricted Stock Units (RSUs) is essential for families who wish to optimize their financial strategies in today’s complex economic landscape. Imagine if you could turn the intricacies of your compensation package into a tool for securing your family’s future.
As more companies incorporate RSUs into their offerings, knowing how to accurately calculate their worth can significantly impact your financial planning and security. However, the complexities of vesting schedules, fair market value assessments, and tax implications can feel overwhelming.
It’s important to understand that you are not alone in this journey. How can families effectively navigate these challenges to ensure they maximize their RSU benefits and secure a brighter financial future together?
We’re here for you, ready to support you in making informed decisions that align with your family’s values and goals.
Understand Restricted Stock Units (RSUs)
Restricted Stock Units (RSUs) represent a meaningful form of equity compensation that employers offer to their employees. Unlike traditional stock options, RSUs guarantee units of stock to be received at a future date, contingent upon meeting specific conditions, typically outlined in a vesting schedule. Understanding how to calculate RSU value is essential for families aiming to navigate their financial landscape effectively. This is particularly true for individuals like Jay and Emma, who are eager to reduce financial stress and allocate their resources wisely.
- Vesting Schedule: RSUs typically follow a clear vesting timeline that dictates when employees gain access to their shares. For instance, if an employee receives 1,000 RSUs with a four-year vesting period, they would earn 25% of the units each year, culminating in full ownership after four years. It’s important to note that employees must first reach a ‘vesting cliff’ of one year before any shares are distributed. This mechanism not only encourages retention but also teaches employees how to calculate RSU value, aligning their interests with the company’s success. At Bright Advisers, we help clients understand how this affects their financial planning and assist them in strategizing effectively.
- Fair Market Value (FMV): The worth of RSUs is directly tied to the company’s stock price. When the units vest, understanding how to calculate RSU value is essential, as their value is assessed based on the fair market value at that time, allowing employees to benefit from any appreciation in the stock price. This aspect is crucial for families, as seen in the case of Allison and Brian, who are focused on maximizing their financial potential through thoughtful planning.
- Financial Consequences: Once RSUs vest, they are subject to ordinary income tax, meaning employees must pay taxes based on the fair market value of the shares at the time they receive them. Employers are obligated to withhold 22% for federal income taxes on the first $1 million in supplemental income, which can significantly influence financial planning, especially for families juggling multiple income sources. Bright Advisers offers personalized tax optimization strategies to help clients navigate these challenges effectively. Additionally, it’s worth noting that RSUs do not pay dividends until they vest, an important consideration for families assessing the cash flow implications of their equity compensation.
As of 2025, approximately 60% of companies include RSUs in their employee compensation packages, highlighting their growing popularity as a retention strategy. Investment advisors emphasize the importance of knowing how to calculate RSU value, as it can play a vital role in a family’s long-term financial strategy. By grasping these key components, families can make informed decisions about their investments and overall financial health, empowering them to achieve financial security and freedom. Together, we can navigate this journey.

Calculate RSU Value Step-by-Step
Calculating the value of your Restricted Stock Units (RSUs) can feel daunting, but we’re here to guide you on how to calculate RSU value step by step.
-
Identify Your RSUs: Start by determining how many restricted stock units you have been granted and how many have vested. For instance, if you have 100 RSUs and 25 have vested, let’s focus on how to calculate RSU value for those 25 vested RSUs.
-
Find the Fair Market Value (FMV): Next, check the current stock price of your company. You can usually find this information on financial news websites or your company’s investor relations page. For example, in 2025, if the FMV is $50 per share, this number will be crucial for your calculations.
-
Calculate the Total Value: Multiply the number of vested RSUs by the FMV. Using our previous example, if 25 RSUs have vested and the FMV is $50, the calculation would be:
25 RSUs x $50 = $1,250
This means the total value of your vested RSUs is $1,250.
- Consider Future Vesting: If you have unvested RSUs, you can estimate their future value using the same FMV. Just remember, this value depends on those shares vesting in the future.
Understanding how to calculate RSU value in relation to the current stock price trends for RSUs in 2025 is essential, as fluctuations can significantly impact your financial planning. Financial specialists recommend regularly assessing your company’s stock performance to make informed decisions about your equity compensation.
For example, Jane Yoo, a certified money advisor, highlights the importance of understanding the tax implications at both vesting and sale. She notes that the typical tax withholding rate on vested RSUs is 22%. This means that while your vested RSUs might have a gross value of $1,250, the net amount you receive after taxes could be much lower.
Real-life stories from families navigating how to calculate RSU value can provide valuable insights into how these calculations affect overall financial planning. Remember, you’re not alone in this journey; together, we can navigate these complexities and ensure your family’s financial future is secure.

Consider Tax Implications of RSUs
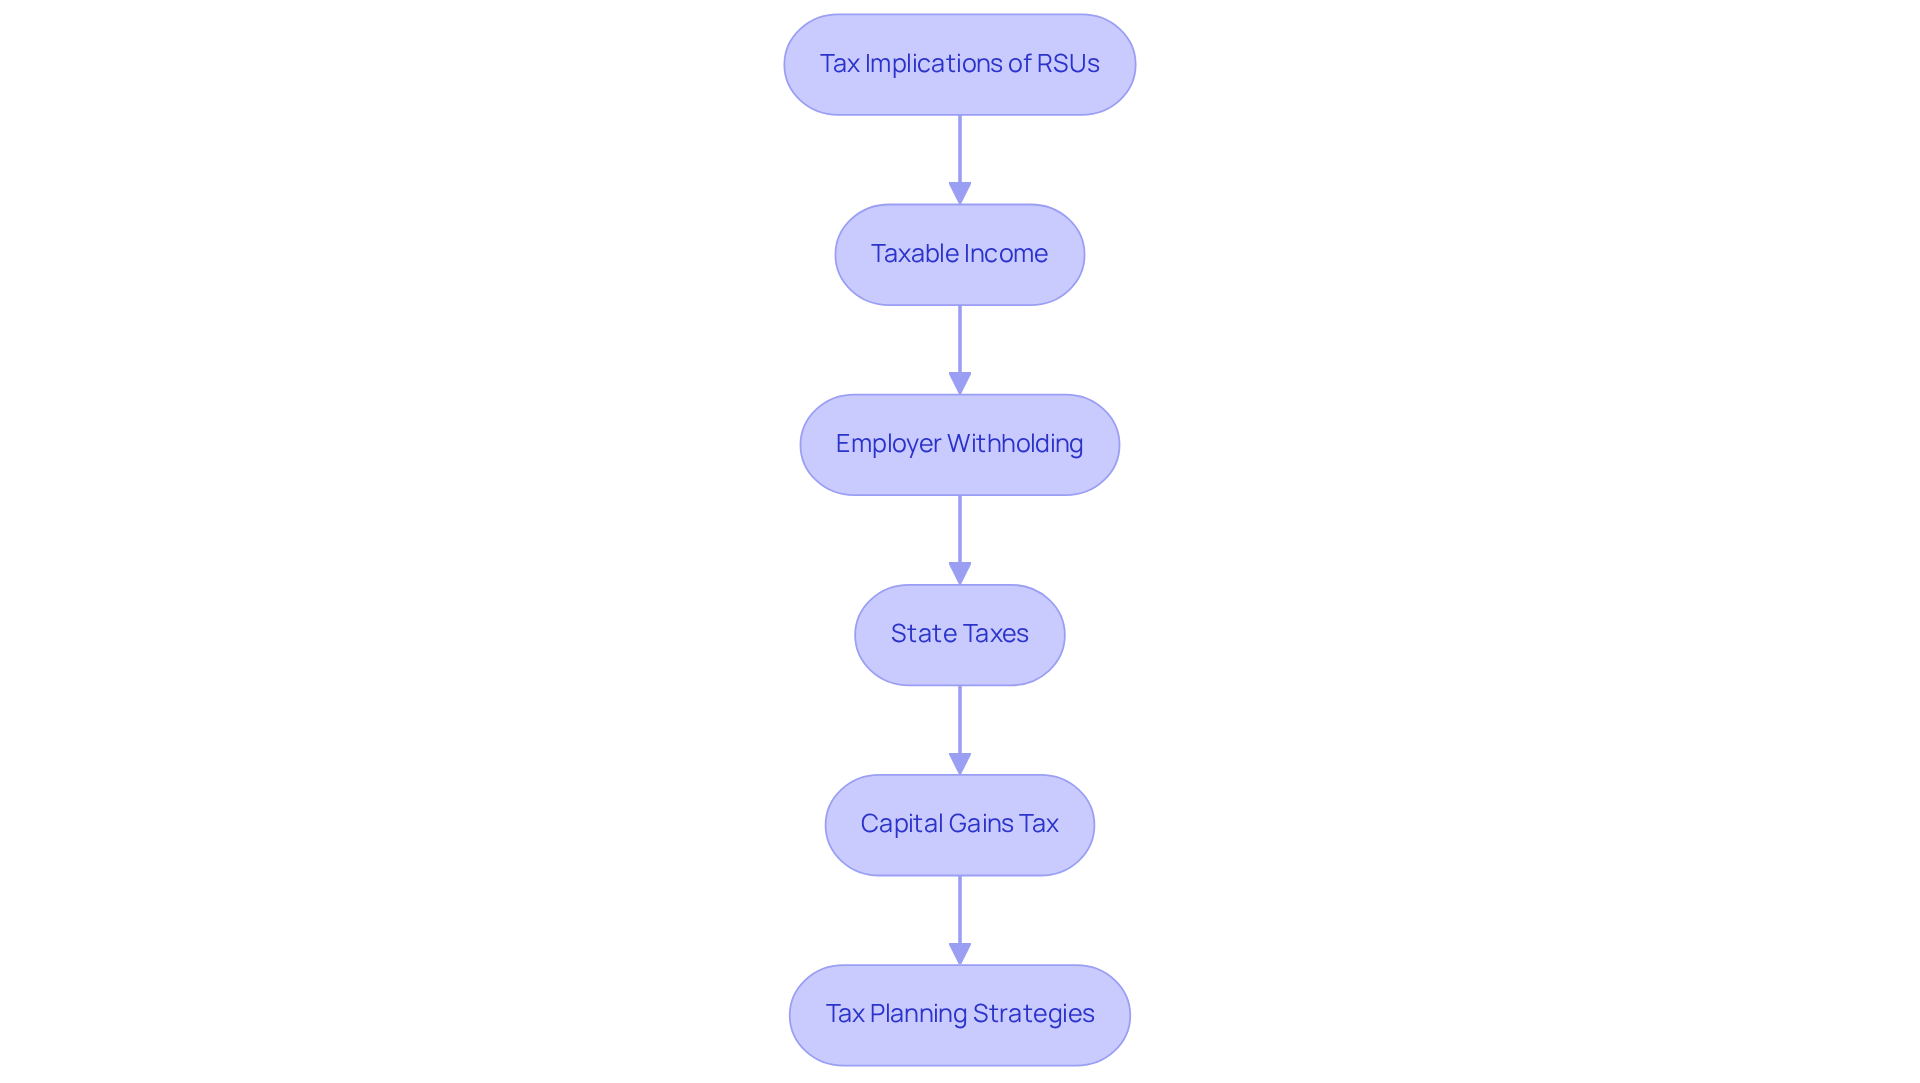
When restricted stock units vest, they are considered income and are subject to taxation. Navigating these tax implications can feel overwhelming, but we’re here to help you understand the process:
- Taxable Income: Understanding how to calculate RSU value involves recognizing that the fair market value (FMV) of your vested restricted stock units is included in your taxable income for the year. For example, if your vested RSUs are valued at $1,250, this amount will be taxed at your ordinary income tax rate. This can be significant, depending on your overall income level. Families like Jay and Emma learned to allocate their resources effectively with the guidance of Bright Advisers, easing their financial anxiety.
- Employers often retain a portion of the stocks to cover taxes. In 2025, the federal withholding rate for RSUs is generally set at 22% for amounts up to $1 million, increasing to 37% for amounts above that threshold. This means you would receive roughly 78% of the shares after deductions for amounts up to $1 million. However, high-income earners may find this rate inadequate, potentially leading to additional payments at tax time. Understanding these implications empowers families to make informed decisions about their financial futures, a service Bright Advisers provides.
- State Taxes: State income taxes may also apply to the value of your restricted stock units. For instance, California imposes a flat supplemental withholding rate of 10.23% for RSUs as of 2025. It’s crucial to check your state’s tax regulations to fully understand your obligations, especially if you earned RSUs while living in a different state. Families like Emily and Mark navigated their financial complexities with tailored strategies from Bright Advisers, ensuring they were well-prepared.
- Capital Gains Tax: If you sell the stocks after they vest, any increase in value from the time of vesting to the time of sale will be subject to capital gains tax. For holdings maintained for over a year, long-term capital gains tax rates apply, which are typically lower than standard income tax rates. Keeping track of how to calculate RSU value at the time of vesting is essential for accurate reporting, much like how Allison and Brian optimized their financial potential through effective tax planning with Bright Advisers.
- Tax Planning Strategies: To minimize your tax burden, consider consulting with a tax advisor to develop effective strategies. This may involve timing the sale of stocks to align with your overall income for the year or utilizing tax-advantaged accounts to offset some of the tax liabilities. Additionally, employing a ‘sell-to-cover’ strategy can help manage immediate tax obligations while retaining some shares for potential future gains. By collaborating with experts such as Bright Advisers, families can develop customized strategies that enable them to attain economic security and independence. Together, we can navigate this journey toward a more secure financial future.
Manage RSUs for Financial Success
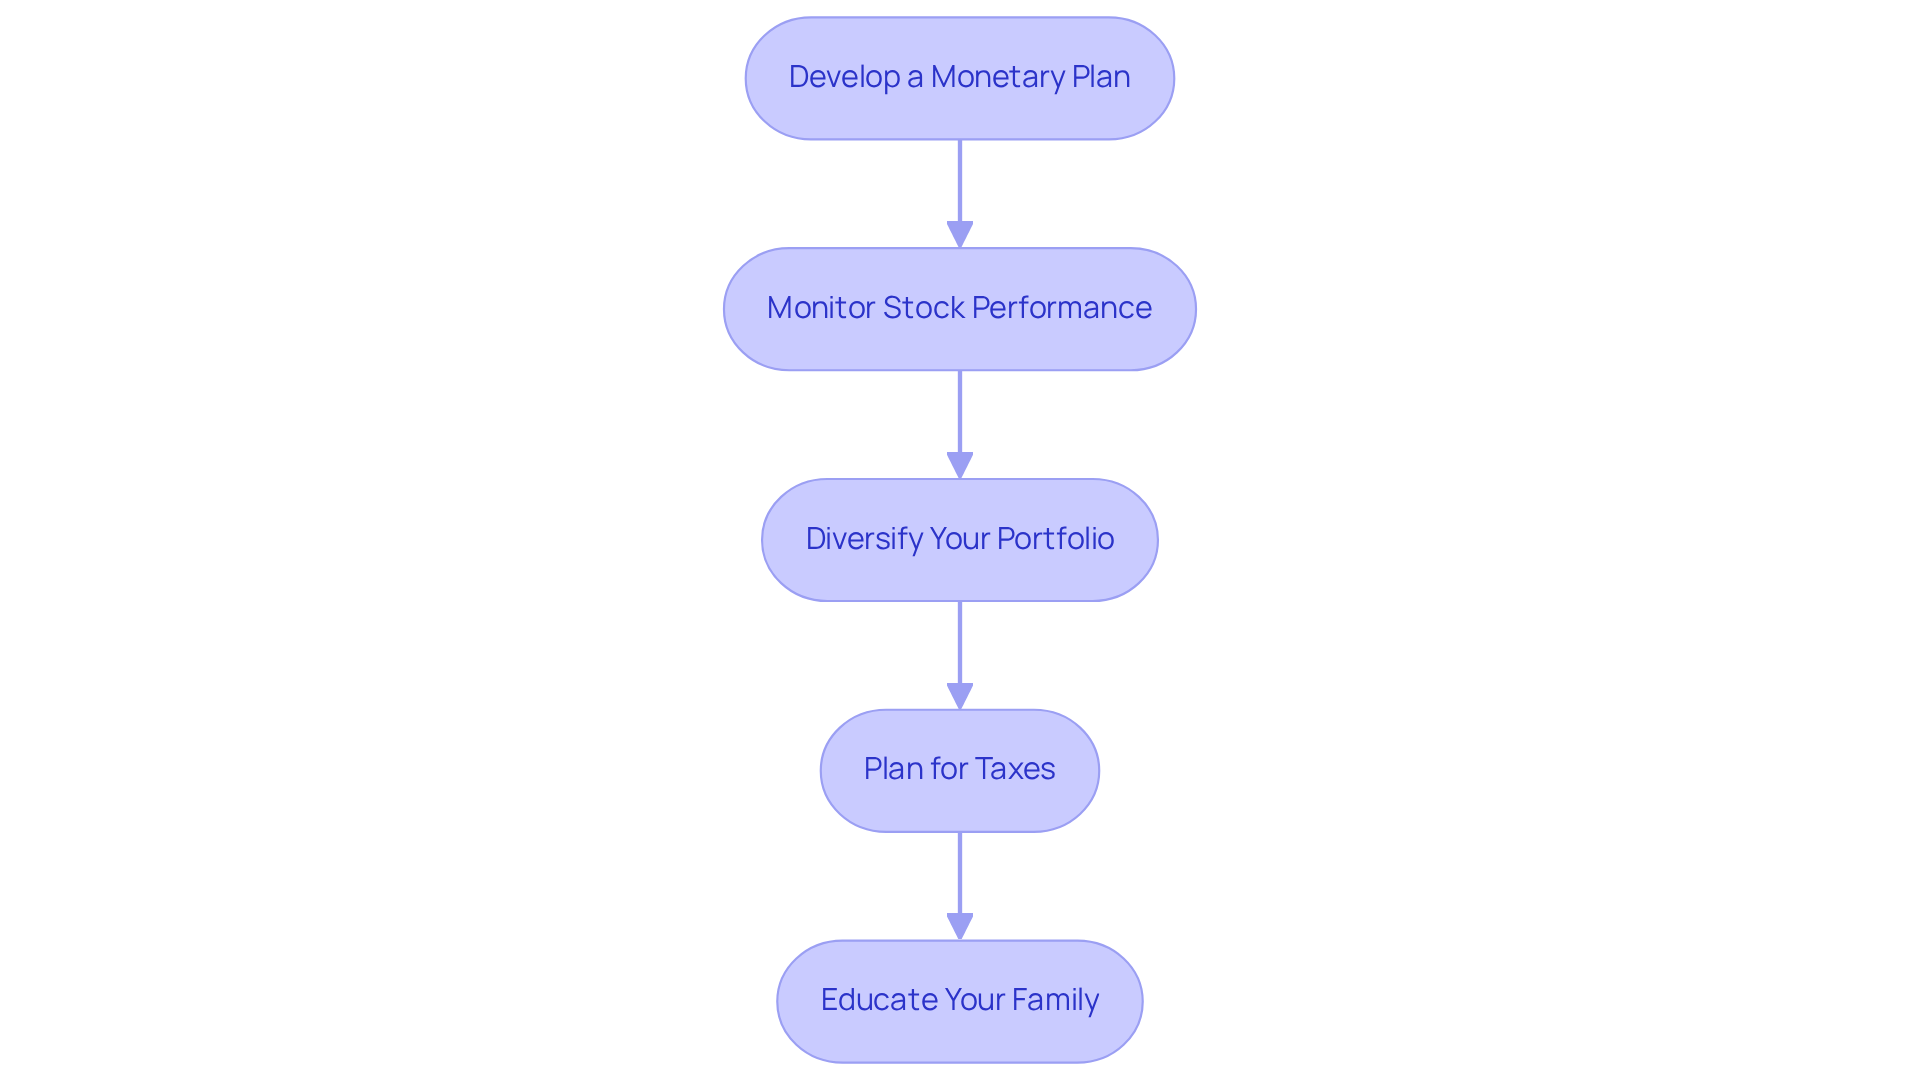
To effectively manage your RSUs and leverage them for financial success, consider these nurturing strategies:
-
Develop a Monetary Plan: Imagine incorporating your restricted stock units into a comprehensive monetary strategy that aligns with your long-term goals—like funding your children’s education or planning for retirement. A well-organized financial strategy, similar to the one created for Allison and Brian with Bright Advisers, can help you navigate the intricacies of how to calculate rsu value while ensuring they enhance your financial future. Through their collaboration, Allison and Brian not only optimized their tax situation but also secured their children’s future through education funding.
-
Monitor Stock Performance: It’s important to regularly track your company’s stock performance. If the stock price is rising, holding onto your shares longer may maximize your gains. Conversely, if the stock price is falling, selling a portion of your restricted stock units could help lessen potential losses and safeguard your investment. Given the fluctuations many companies experience post-IPO, particularly in 2025, this monitoring is crucial for informed decision-making.
-
Diversify Your Portfolio: To prevent over-concentration in your employer’s stock, consider selling a part of your vested restricted stock units. Diversifying your investments can lower risk and improve potential returns, especially since restricted stock units can significantly influence your total net worth. This strategy is particularly vital in 2025, as many companies experience fluctuations in stock performance post-IPO.
-
Plan for Taxes: Be proactive about understanding how to calculate rsu value and the tax implications related to your restricted stock units. The federal tax rate for RSUs is 22%, so setting aside funds to cover tax obligations upon vesting is essential. Seeking advice from a tax expert, like Allison and Brian did, can enhance your tax plan, ensuring you’re ready for any responsibilities that arise from your restricted stock units. This planning is crucial for effective resource management and can greatly improve your wealth accumulation potential, enabling earlier retirement.
-
Educate Your Family: Use your experience with restricted stock units as a teaching opportunity for your children. Discuss the significance of monetary literacy and how RSUs fit into broader wealth management discussions. This not only prepares them for future financial responsibilities but also fosters a culture of informed financial decision-making within your family.
Together, we can navigate this journey, ensuring that your financial decisions pave the way for a secure future for you and your loved ones.
Conclusion
Understanding how to calculate the value of Restricted Stock Units (RSUs) is essential for families striving to enhance their financial well-being. By grasping the nuances of vesting schedules, fair market value, and tax implications, families can transform these complex compensation packages into valuable assets that support their long-term financial goals.
This guide has illuminated the essential steps involved in calculating RSU value, from identifying the number of units granted to understanding the impact of taxes on vested shares. It’s crucial to recognize the importance of fair market value at vesting, the tax obligations that arise, and the strategic management of RSUs to optimize financial outcomes. Imagine how families have successfully navigated these challenges with expert guidance, reinforcing the idea that informed decision-making can lead to greater financial security.
Ultimately, managing RSUs should be viewed as an opportunity for families to build a solid financial foundation. By proactively educating themselves about RSUs and engaging with financial advisors, families can not only maximize the benefits of their equity compensation but also foster a culture of financial literacy that prepares future generations for success. Together, we can secure your financial future and achieve your dreams as a family.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
RSUs are a form of equity compensation that employers offer to employees, guaranteeing units of stock to be received at a future date, contingent upon meeting specific conditions, typically outlined in a vesting schedule.
How does the vesting schedule for RSUs work?
RSUs typically follow a vesting timeline where employees earn access to their shares over time. For example, if an employee receives 1,000 RSUs with a four-year vesting period, they would earn 25% of the units each year, with full ownership after four years. Employees must also reach a ‘vesting cliff’ of one year before any shares are distributed.
What is the Fair Market Value (FMV) of RSUs?
The FMV of RSUs is directly tied to the company’s stock price. When the units vest, their value is assessed based on the fair market value at that time, allowing employees to benefit from any appreciation in the stock price.
What are the tax implications of RSUs once they vest?
Once RSUs vest, they are subject to ordinary income tax based on the fair market value of the shares at the time of receipt. Employers must withhold 22% for federal income taxes on the first $1 million in supplemental income.
Do RSUs pay dividends?
No, RSUs do not pay dividends until they vest.
How common are RSUs in employee compensation packages?
As of 2025, approximately 60% of companies include RSUs in their employee compensation packages, indicating their growing popularity as a retention strategy.
Why is it important to understand how to calculate RSU value?
Understanding how to calculate RSU value is essential for effective financial planning, as it can significantly influence a family’s long-term financial strategy and overall financial health.
List of Sources
- Understand Restricted Stock Units (RSUs)
- RSUs Explained: How Restricted Stock Units Work & Are Taxed (https://vestedfinance.com/blog/us-stocks/rsus-a-comprehensive-guide-to-restricted-stock-units)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- All about RSUs (https://beqom.com/blog/restricted-stock-units-all-you-need-to-know-about-rsus)
- Restricted Stock Units (2023): Detailed Guide, Taxes, More (https://tokenist.com/investing/restricted-stock-units)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Calculate RSU Value Step-by-Step
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- RSUs Explained: How Restricted Stock Units Work & Are Taxed (https://vestedfinance.com/blog/us-stocks/rsus-a-comprehensive-guide-to-restricted-stock-units)
- Restricted Stock Units – RSU Taxation, Vesting, Calculator & More (https://janefinancial.com/restricted-stock-units)
- Restricted Stock Units (RSUs) Comprehensive Guide | TAN Wealth Management | Certified Financial Planner (CFP®) San Francisco | Advisor (https://tanphan.com/blog/restricted-stock-units-rsu-comprehensive-guide)
- RSU Taxes: How Are Restricted Stock Units (RSUs) Taxed? | Facet (https://facet.com/equity/rsu-taxes-calculations-reporting-strategies)
- Consider Tax Implications of RSUs
- Understanding RSU Tax Rates: Comprehensive Guide with Calculator (https://advisorfinder.com/resources-for-clients/tax/rsu-tax-rate)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- RSU Supplemental Withholding 101 — DiversiFi Capital (https://diversificapital.com/blog/rsu-supplemental-withholding)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Manage RSUs for Financial Success
- As the high-net-worth seek out new wealth managers, how do you retain clients and capture money-in-motion? (https://pwc.com/us/en/industries/financial-services/asset-wealth-management/high-net-worth-investor.html)
- Ultra High Net Worth Tax Planning Strategies to Manage Restricted Stock Units – CCMI Creative Capital Management Investments (https://myccmi.com/2023/11/ultra-high-net-worth-tax-planning-strategies-to-manage-restricted-stock-units)
- RSU Tax Calculator (https://advisorfinder.com/resources-for-clients/calculators/rsu-taxes)
- RSU Strategy: When to Sell or Hold Your Vested Shares | Equity Comp Academy (https://3040wealth.com/academy/rsu-planning-strategy)
- Use Restricted Stock Units to Fund Financial Planning Goals (https://zajacgrp.com/insights/restricted-stock-units-to-fund-financial-planning-goals)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading