

Key Highlights:
- K-1 forms are essential for partners in businesses and beneficiaries of estates or trusts for accurate income reporting on tax returns.
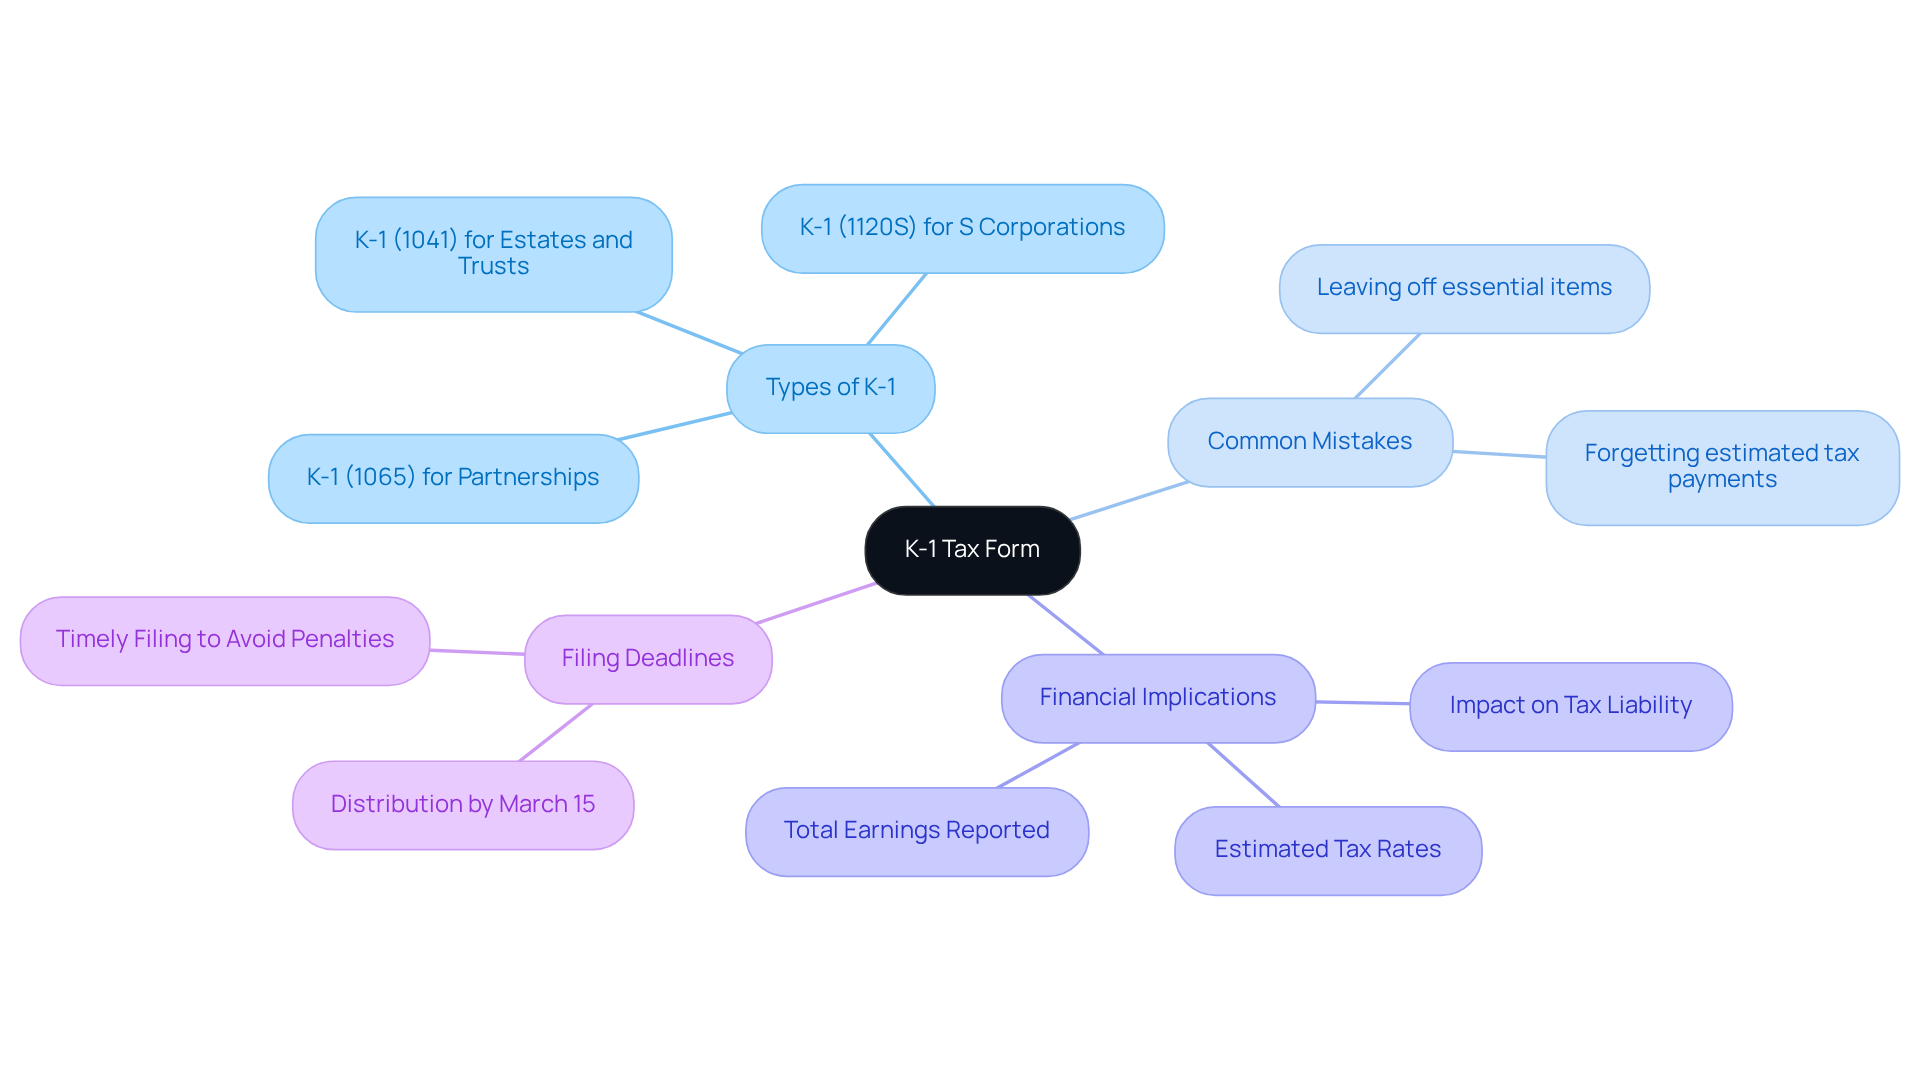
- There are three types of K-1 forms: K-1 (1065) for partnerships, K-1 (1120S) for S corporations, and K-1 (1041) for estates and trusts.
- In 2021, approximately 4.5 million partnership returns reported $3.89 trillion in net earnings, emphasising the significance of K-1 forms.
- Common mistakes in filing K-1 include omitting essential items, which can lead to costly errors.
- Around 30% of families are expected to receive K-1 earnings by 2025, highlighting their relevance in financial planning.
- K-1 forms must be provided by partnerships and S corporations by March 15, with extensions available until September 15.
- Filing K-1 should be done accurately to avoid IRS penalties, which can complicate financial planning.
- The K-1 filing process involves gathering information, identifying the K-1 type, reporting income and deductions, and reviewing for accuracy.
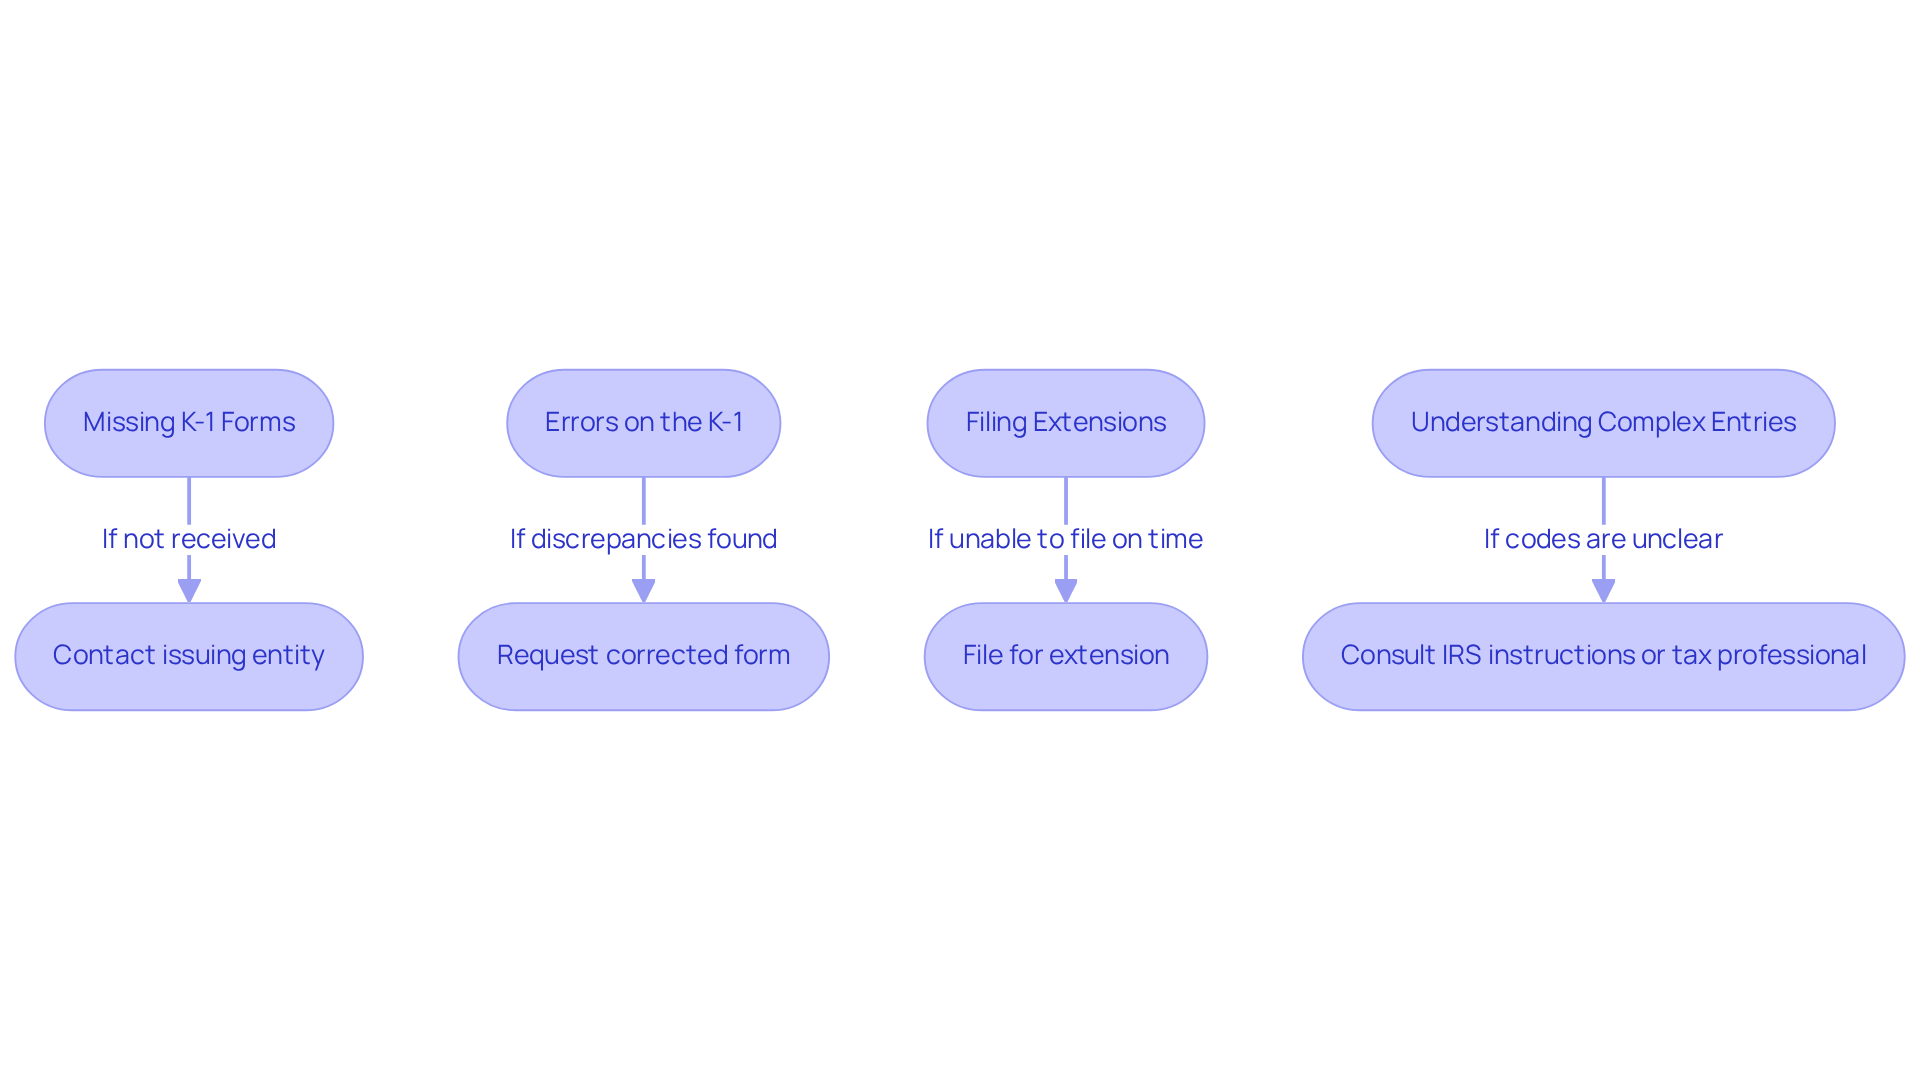
- Common issues include missing K-1 forms, errors on K-1, and understanding complex entries, all of which require proactive management.
Introduction
Understanding the K-1 tax form can feel overwhelming, especially for young parents trying to navigate the complexities of partnership and trust income. But don’t worry-this guide is here to help you master K-1 filings, ensuring you can accurately report your financial obligations and make the most of your tax situation.
Imagine the peace of mind that comes with knowing you’re on top of your family’s finances. With deadlines approaching and potential pitfalls lurking, it’s crucial to avoid common mistakes that could impact your family’s financial future. We’re here for you, guiding you through each step of the process.
It’s important to understand that you’re not alone in this journey. Many parents face similar challenges, and together, we can navigate these waters. By taking the time to learn about the K-1 form, you’re investing in your family’s financial well-being.
Let’s explore how mastering this form can lead to better financial outcomes for your family. With the right knowledge, you can optimize your tax situation and secure a brighter future for your loved ones. Together, we can make this journey a little easier.
Understand the K-1 Tax Form
Understanding how to file K-1, or Schedule K-1, is essential for families involved in partnerships, S corporations, estates, or trusts. If you’re a partner in a business or a beneficiary of an estate or trust, understanding how to file K-1 is crucial for accurate income reporting on your personal tax returns. This understanding can significantly impact your tax liability. In fact, many individuals in the U.S. receive K-1 documents, underscoring their importance in the tax landscape.
Let’s explore the different types of K-1 documents:
- K-1 (1065) for partnerships
- K-1 (1120S) for S corporations
- K-1 (1041) for estates and trusts
Each type provides detailed insights into a partner’s share of the entity’s income, losses, and other tax-related items. For instance, in 2021, approximately 4.5 million partnership returns reported a staggering $3.89 trillion in net earnings. This highlights just how significant K-1 forms are in managing your family’s finances.
Tax professionals often stress the importance of knowing how to file K-1 to avoid costly mistakes in tax filings. Kemberley Washington, a tax analyst, points out that when learning how to file K-1, leaving off essential items is the biggest common mistake people make. Understanding the different types of K-1 income-like ordinary business earnings, rental income, and capital gains-is vital for families to navigate their tax obligations effectively. Imagine a couple like Jay and Emma, who sought guidance from Bright Advisers to ease their financial worries. By mastering the K-1 document, they made informed choices that aligned with their broader financial strategies, ultimately enhancing their overall monetary planning.
Additionally, being aware of the 50% AGI limitation for deductions related to contributions and the fact that around 40% of K-1 partners forget to make estimated tax payments can empower families in proactive financial planning. Remember, knowing how to file K-1 is essential because K-1 documents need to be distributed to partners by March 15 of the following year for timely filing. Together, we can navigate this journey and ensure your family’s financial future is secure.
Identify Who Needs to File a K-1
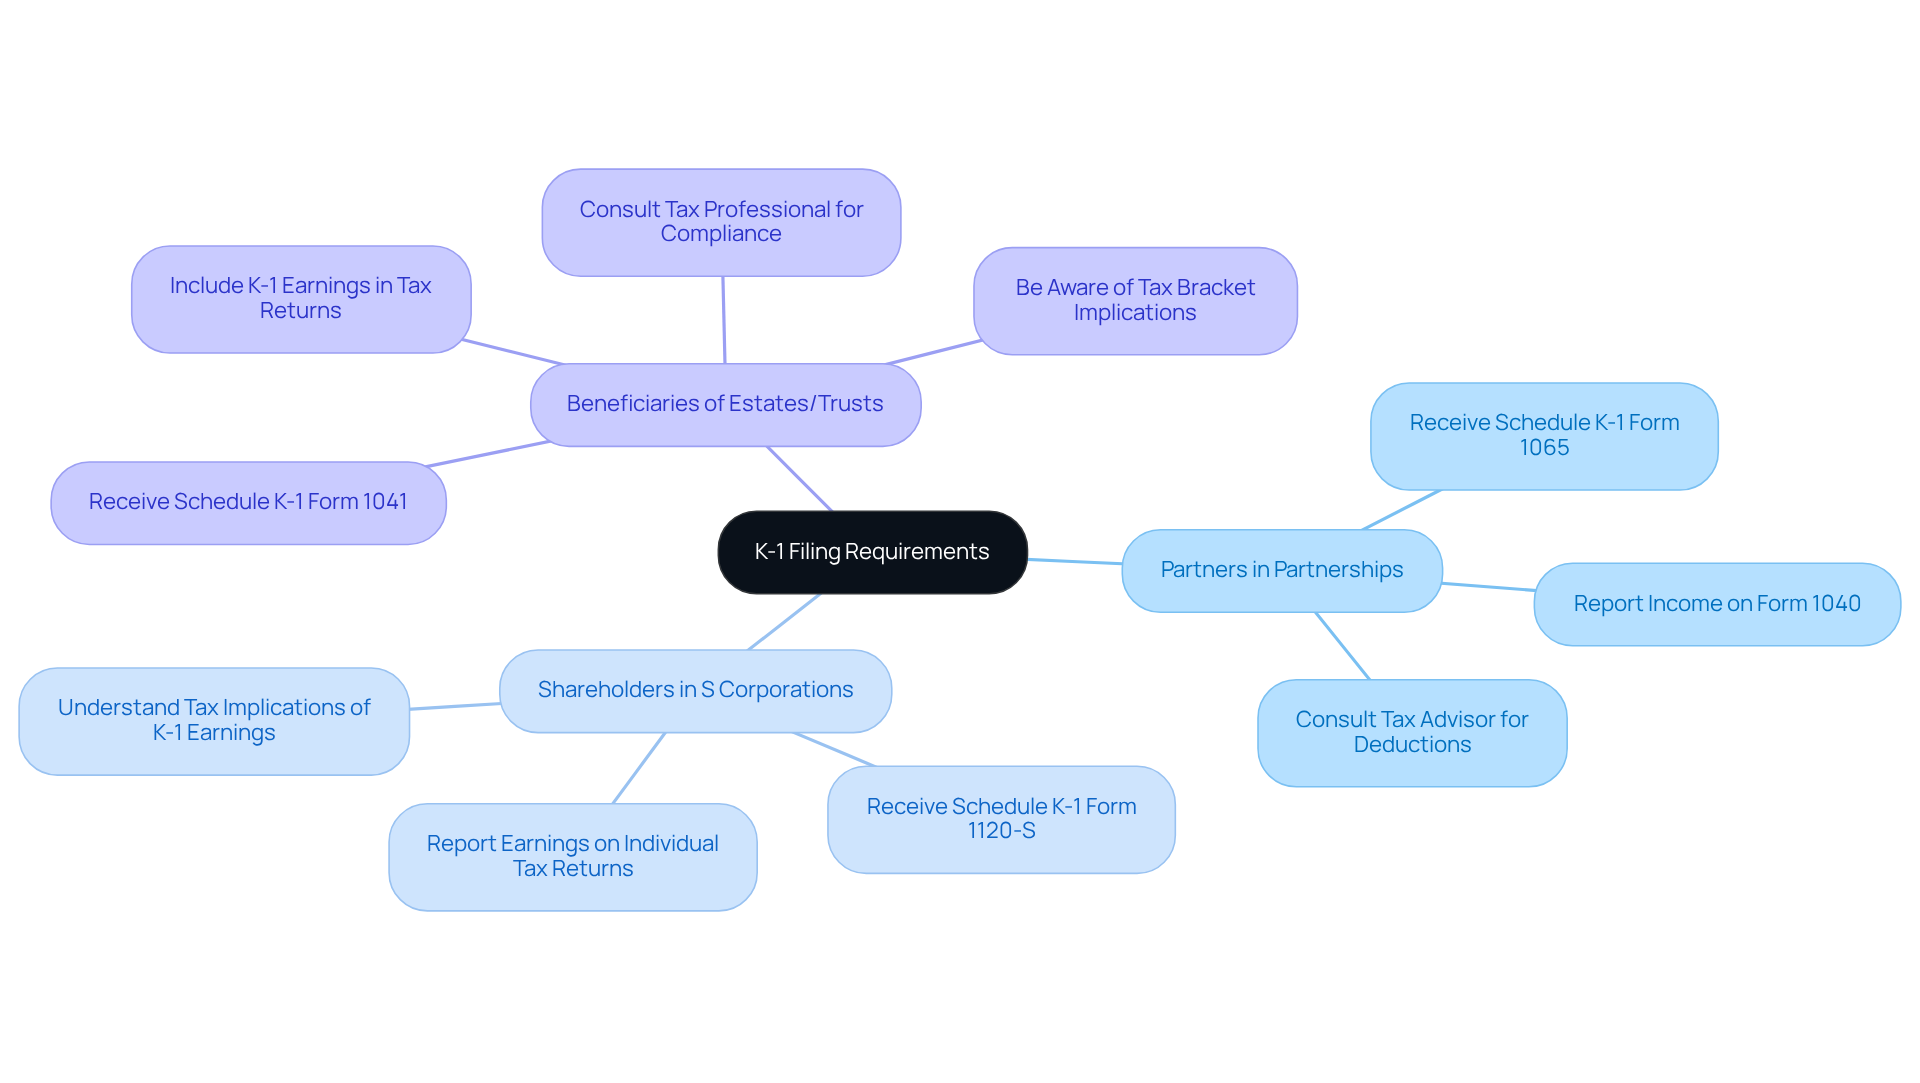
If you’re a partner in a partnership, a shareholder in an S corporation, or a beneficiary of an estate or trust, you’ll likely receive a K-1 document that will guide you on how to file K-1. Understanding this document is essential for your financial well-being. Imagine if you could navigate your tax responsibilities with confidence! Consulting with your tax advisor or the entity that issued the K-1 can help clarify how to file K-1 and your specific filing requirements.
In 2025, around 30% of families are expected to receive K-1 earnings. This statistic highlights how significant these earnings can be for your family’s tax situation. If your children are beneficiaries of a trust or estate, they may also receive a K-1, which needs to be accurately reported on their tax returns. It’s important to understand how this affects your family’s finances.
As one tax advisor wisely noted, “Understanding K-1 earnings is vital for beneficiaries, as it can increase their taxable amount and potentially push them into a higher tax bracket.” This insight underscores the importance of being proactive about your tax filings.
Together, we can navigate this journey. Knowing how to file K-1 documents correctly is crucial for maintaining compliance and optimizing your tax outcomes. Remember, you’re not alone in this process; we’re here for you every step of the way.
Know the Filing Deadlines for K-1 Forms
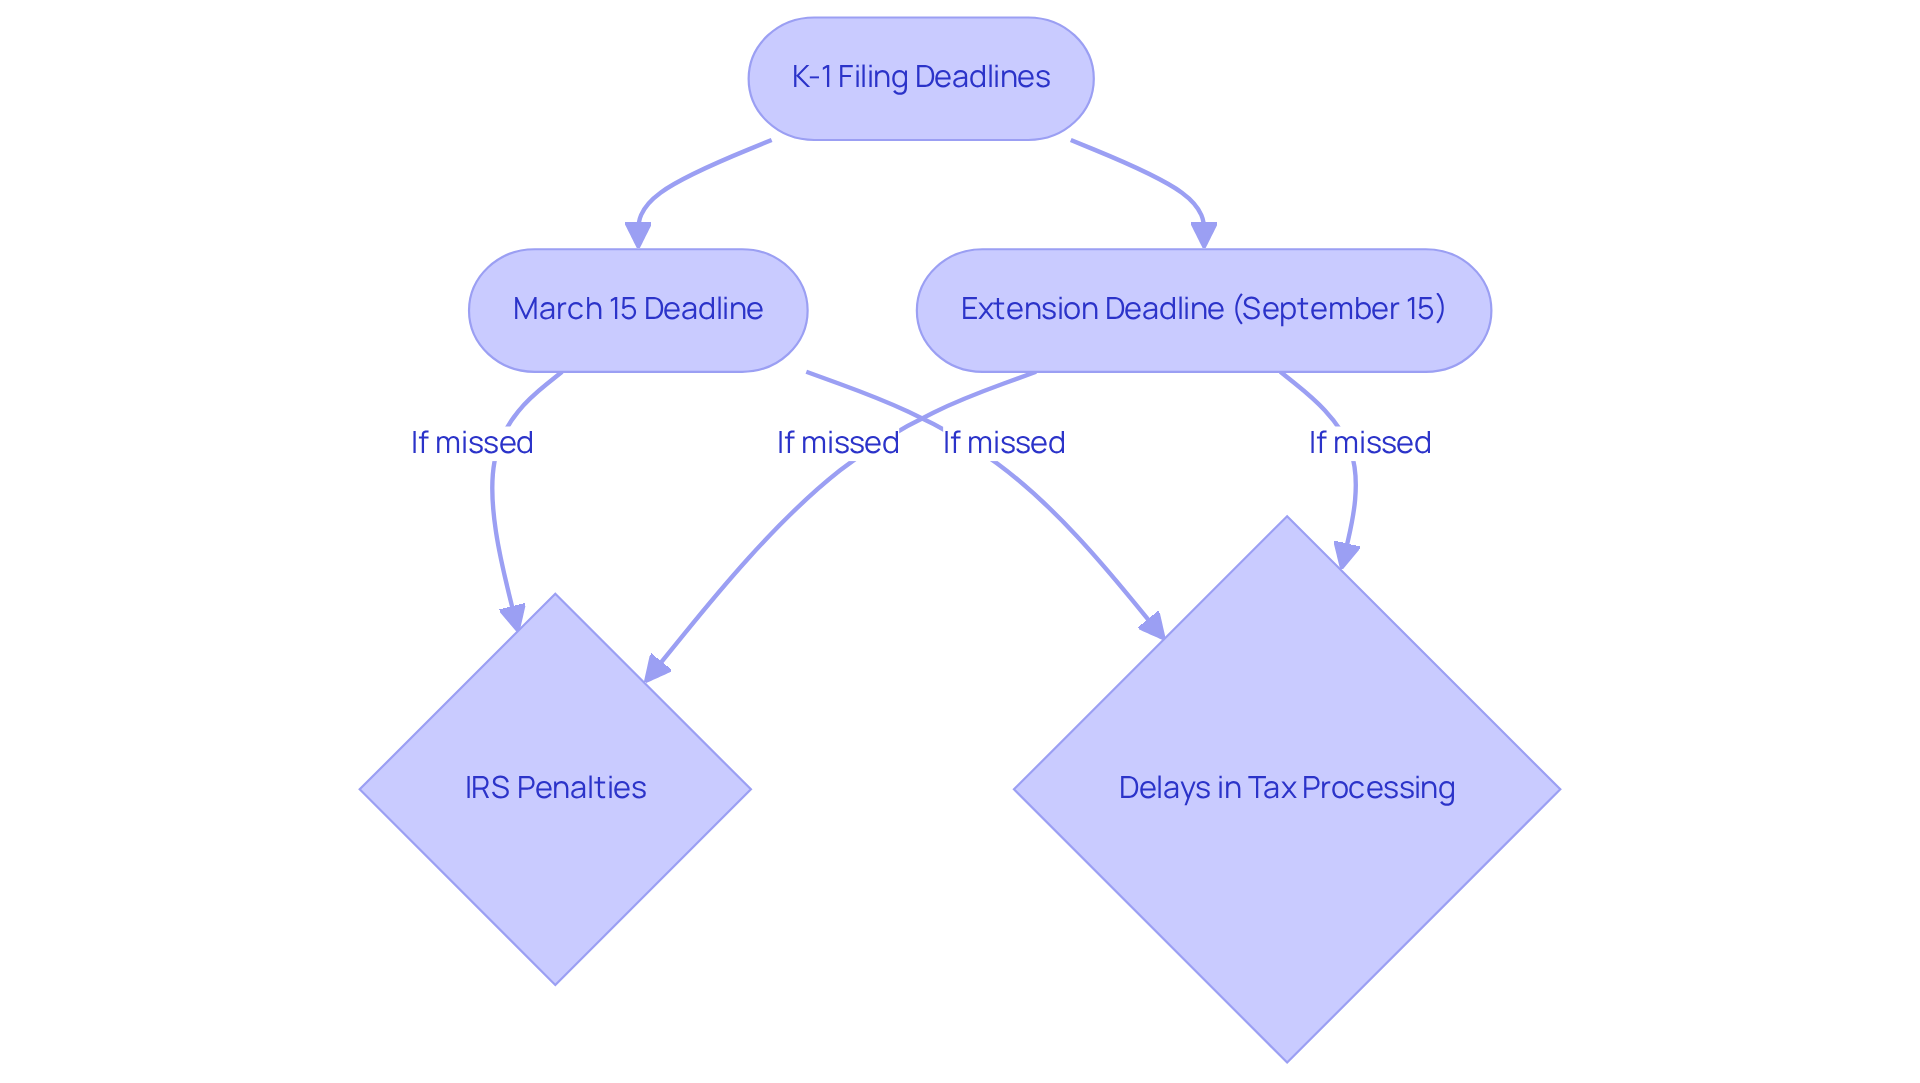
Deadlines for how to file K-1 forms can feel overwhelming, especially for young families trying to manage their finances. Generally, partnerships and S corporations need to provide K-1s to their partners and shareholders by March 15 of the following year. If you file for an extension, this deadline can stretch to September 15.
It’s crucial to keep these dates in mind. Missing them can lead to significant IRS penalties, which might include fines or delays in processing tax returns. Imagine the stress for families who don’t submit on time – penalties can complicate budgeting and financial planning. This is particularly significant for young families like Jay and Emma, who are working with Bright Advisers to ease their worries and optimize their resources through thoughtful strategies like tax planning and budget management.
Additionally, remember how to file K-1 documents, as they must be included in individual tax returns due by April 15. Always verify the specific deadlines with the IRS or your tax advisor to ensure compliance. Did you know that about 30% of investors choose to file for extensions for their K-1 documents? By staying on top of these deadlines, families can better manage their financial strategies and work towards achieving their long-term goals.
Together, we can navigate this journey and ensure that your family’s financial future is secure.
Complete the K-1 Form Step-by-Step
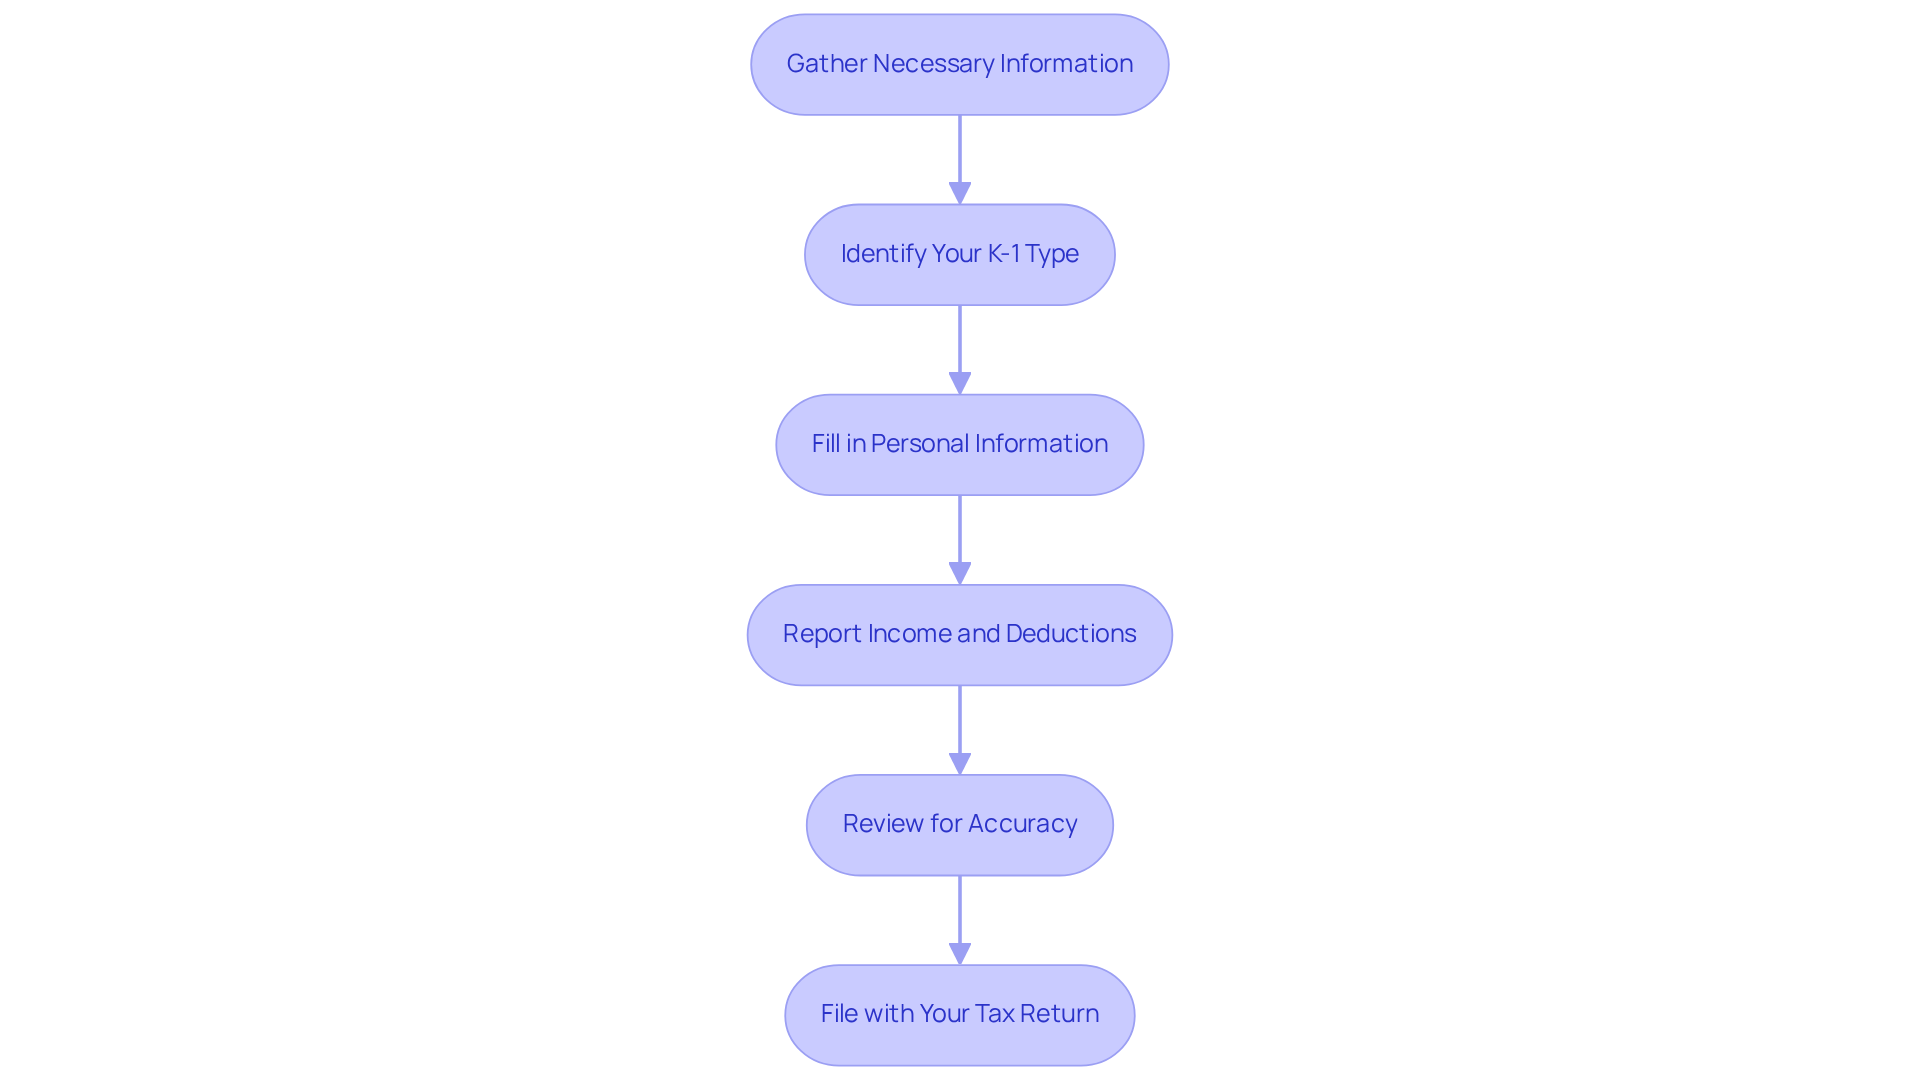
Completing the K-1 form can feel overwhelming, but we’re here to help you learn how to file k1. Just take it step by step, and you’ll gain confidence in managing your finances, including how to file k1.
-
Gather Necessary Information: Start by collecting all the important documents you’ll need. This includes your partnership agreement, previous tax returns, and any financial statements. Having everything in one place can make the process smoother.
-
Identify Your K-1 Type: Next, figure out whether you’re filling out a K-1 for a partnership, S corporation, or estate/trust. Understanding how to file k1 will guide you in the right direction.
-
Fill in Personal Information: Now, it’s time to enter your details. Make sure to include your name, address, and taxpayer identification number (TIN) in the right sections. Accuracy here is key.
-
Report Income and Deductions: Carefully input your share of the entity’s income, deductions, and credits as reported on the K-1. It’s important to ensure everything is accurate when figuring out how to file k1 to avoid any discrepancies later on.
-
Review for Accuracy: Take a moment to double-check all your entries. Errors can lead to complications with the IRS, and we want to help you avoid that stress.
-
File with Your Tax Return: Finally, include the K-1 with your personal tax return (Form 1040). Just remember, you don’t need to submit the K-1 itself to the IRS; keep it for your records when considering how to file k1.
Imagine how much easier tax season can be when you have everything organized! Remember, you’re not alone in this journey. Together, we can navigate these financial responsibilities with ease.
Troubleshoot Common K-1 Filing Issues
Filing K-1 forms can feel overwhelming, especially when you are trying to understand how to file K1, but you’re not alone in this journey. Here are some common issues you might encounter:
-
Missing K-1 Forms: Imagine waiting for your K-1 only to find it hasn’t arrived by the filing deadline. If that happens, don’t hesitate to reach out to the issuing entity right away to request a copy. It’s important to stay proactive.
-
Errors on the K-1: Have you ever noticed discrepancies in the reported income or deductions? If so, it’s crucial to contact the partnership or corporation for guidance on how to file k1 with a corrected form. Getting this right can make a big difference for your family’s finances.
-
Filing Extensions: Life can get busy, and if you can’t file your tax return on time due to a late K-1, remember that you can file for an extension using Form 4868. This simple step can guide you on how to file k1, helping you avoid penalties and giving you peace of mind.
-
Understanding Complex Entries: If you come across unfamiliar codes or terms on the K-1, it’s important to understand what they mean. Consulting the IRS instructions or a tax professional can provide clarity on how to file k1 accurately and ensure proper reporting. We’re here for you, helping you navigate these complexities.
By addressing these common issues, you can take control of your financial situation and focus on what truly matters – your family. Together, we can navigate this journey.
Conclusion
Understanding how to file the K-1 tax form is essential for young parents navigating the complexities of their financial responsibilities. This guide offers crucial insights into the various types of K-1 documents, the importance of accurate reporting, and the specific filing deadlines that must be adhered to. Mastering the K-1 process can significantly impact a family’s overall financial health and tax obligations.
Imagine if you could navigate this process with confidence. Throughout the article, we highlighted key points, including the different types of K-1 forms – partnerships, S corporations, and estates or trusts – as well as common pitfalls to avoid during the filing process. It’s important to understand that timely submissions and proactive management of K-1 income play a vital role in ensuring compliance and optimizing tax outcomes for families.
Ultimately, the journey of filing K-1 forms should not feel daunting. By staying informed and organized, young parents can take control of their financial futures. Embracing these strategies not only alleviates stress but also fosters a more secure financial environment for families. Together, we can navigate this journey, empowering families to make informed decisions that pave the way for financial stability and growth.
Frequently Asked Questions
What is a K-1 tax form?
A K-1 tax form, or Schedule K-1, is a document used to report income, losses, and other tax-related items from partnerships, S corporations, estates, or trusts. It is essential for accurate income reporting on personal tax returns.
Who needs to file a K-1?
Individuals who are partners in a partnership, shareholders in an S corporation, or beneficiaries of an estate or trust will likely receive a K-1 document that guides them on how to file.
What are the different types of K-1 forms?
There are three main types of K-1 forms: K-1 (1065) for partnerships, K-1 (1120S) for S corporations, and K-1 (1041) for estates and trusts.
Why is understanding how to file a K-1 important?
Understanding how to file a K-1 is crucial because it impacts tax liability and ensures accurate reporting of income. Mistakes in filing can lead to costly errors.
What common mistakes do people make when filing K-1 forms?
A common mistake is leaving off essential items from the K-1, which can lead to inaccuracies in tax filings.
What types of income are reported on a K-1?
K-1 forms report various types of income, including ordinary business earnings, rental income, and capital gains.
When must K-1 documents be distributed to partners?
K-1 documents must be distributed to partners by March 15 of the following year to ensure timely filing.
What is the significance of estimated tax payments related to K-1?
Around 40% of K-1 partners forget to make estimated tax payments, which can lead to underpayment penalties and financial issues.
How can K-1 earnings affect a family’s tax situation?
K-1 earnings can increase a family’s taxable amount and potentially push beneficiaries into a higher tax bracket, making it essential to understand and report these earnings accurately.
What should individuals do if they have questions about their K-1?
Individuals should consult with their tax advisor or the entity that issued the K-1 for clarification on filing requirements and to ensure compliance.
List of Sources
- Understand the K-1 Tax Form
- 10 Essential Insights for Every K1 Partner to Navigate Finances – Bright Advisers (https://brightadvisers.com/10-essential-insights-for-every-k-1-partner-to-navigate-finances)
- Understanding the Tax Rate on K1 Income for New Investors – Bright Advisers (https://brightadvisers.com/understanding-the-tax-rate-on-k-1-income-for-new-investors)
- SOI tax stats – Partnership statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-partnership-statistics)
- Identify Who Needs to File a K-1
- 10 Essential Insights on K-1 Tax Form Inheritance for Beneficiaries – Bright Advisers (https://brightadvisers.com/10-essential-insights-on-k-1-tax-form-inheritance-for-beneficiaries)
- SOI tax stats – S corporation statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-s-corporation-statistics)
- Schedule K-1 Tax Form Explained: What Is it & How It Affects You (https://farther.com/resources/foundations/schedule-k-1-tax-form-explained-what-is-it-how-it-affects-you)
- SOI tax stats – Partnership statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-partnership-statistics)
- An Overview of Pass-through Businesses in the United States (https://taxfoundation.org/research/all/federal/overview-pass-through-businesses-united-states)
- Know the Filing Deadlines for K-1 Forms
- 7 Key Dates: When is K1 Due for Investors? – Bright Advisers (https://brightadvisers.com/7-key-dates-when-is-k-1-due-for-investors)
- K-1 Tax Form: How & When to File a Schedule K-1 (https://carta.com/learn/startups/tax-planning/schedule-k-1-tax-form)
- Understanding Tax Form K-1: Reporting, Deadlines & Challenges (https://tax1099.com/glossary/k-1-reporting-rules)
- Filing season statistics for week ending April 25, 2025 | Internal Revenue Service (https://irs.gov/newsroom/filing-season-statistics-for-week-ending-april-25-2025)
- Troubleshoot Common K-1 Filing Issues
- Schedule K-1: What It Is and What to Do in 2025 – NerdWallet (https://nerdwallet.com/investing/learn/schedule-k-1)
- Understanding Tax Form K-1: Reporting, Deadlines & Challenges (https://tax1099.com/glossary/k-1-reporting-rules)
- 10 Essential Insights for Every K1 Partner to Navigate Finances – Bright Advisers (https://brightadvisers.com/10-essential-insights-for-every-k-1-partner-to-navigate-finances)
- 7 Key Conditions on Do Corporations Issue K-1 Forms? – Bright Advisers (https://brightadvisers.com/7-key-conditions-on-do-corporations-issue-k-1-forms)
- Schedule K-1 Tax Form: Essential Filing Tips for Taxpayers | Eqvista (https://eqvista.com/documents/schedule-k-1-tax-form)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading