

Overview
Navigating the world of taxes can feel overwhelming, especially for young parents managing rental properties. This article offers a caring, step-by-step guide to help you file your taxes with confidence. It’s essential to accurately report your rental income and claim allowable deductions, ensuring you maximize your benefits while staying compliant with tax regulations.
Imagine if you could simplify this process! We’ll walk you through the necessary IRS forms, like Form 1040 and Schedule E, while highlighting common deductions such as mortgage interest and repairs. By understanding these elements, you can better prepare for tax season and alleviate some of the stress that comes with it.
Remember, thorough documentation is key. Keeping organized records not only optimizes your tax benefits but also provides peace of mind. You’re not alone in this journey; we’re here for you, ready to support you every step of the way. Together, we can navigate this financial landscape, ensuring your family’s needs are met while you focus on what truly matters.
Key Highlights:
- Rental income is taxable and must be reported on tax returns, including advance rent and security deposits.
- Landlords should differentiate between gross and net rental income, with net income accounting for permissible costs like depreciation.
- Important IRS forms for reporting rental income include Form 1040 and Schedule E.
- Accurate reporting is crucial to avoid audits and penalties from the IRS.
- The Augusta Rule allows homeowners to rent their property tax-free for up to 14 days annually.
- Essential documents for filing taxes include lease agreements, revenue records, expense documentation, and depreciation records.
- Schedule E requires listing assets, reporting revenue, deducting expenses, and calculating net profit.
- Common rental tax deductions include mortgage interest, real estate taxes, repairs, depreciation, utilities, insurance, and professional services.
- Proper documentation and seeking professional guidance can optimise tax benefits and ensure compliance.
Introduction
Navigating the complexities of rental property taxation can feel overwhelming, especially for busy parents trying to balance family and financial responsibilities. Yet, understanding how to file taxes for rental property is not just about compliance with IRS regulations; it can also unlock significant financial benefits through deductions and strategic reporting. Imagine if you could ease some of that financial burden while ensuring your family’s future is secure.
With the rising number of households renting their homes, the stakes have never been higher. How can you, as a landlord, effectively navigate this intricate landscape without falling prey to common pitfalls? This guide offers a step-by-step approach to mastering rental property tax filing, empowering you to optimize your financial outcomes while minimizing risk. Together, we can navigate this journey, ensuring you feel supported every step of the way.
Understand Rental Property Tax Basics
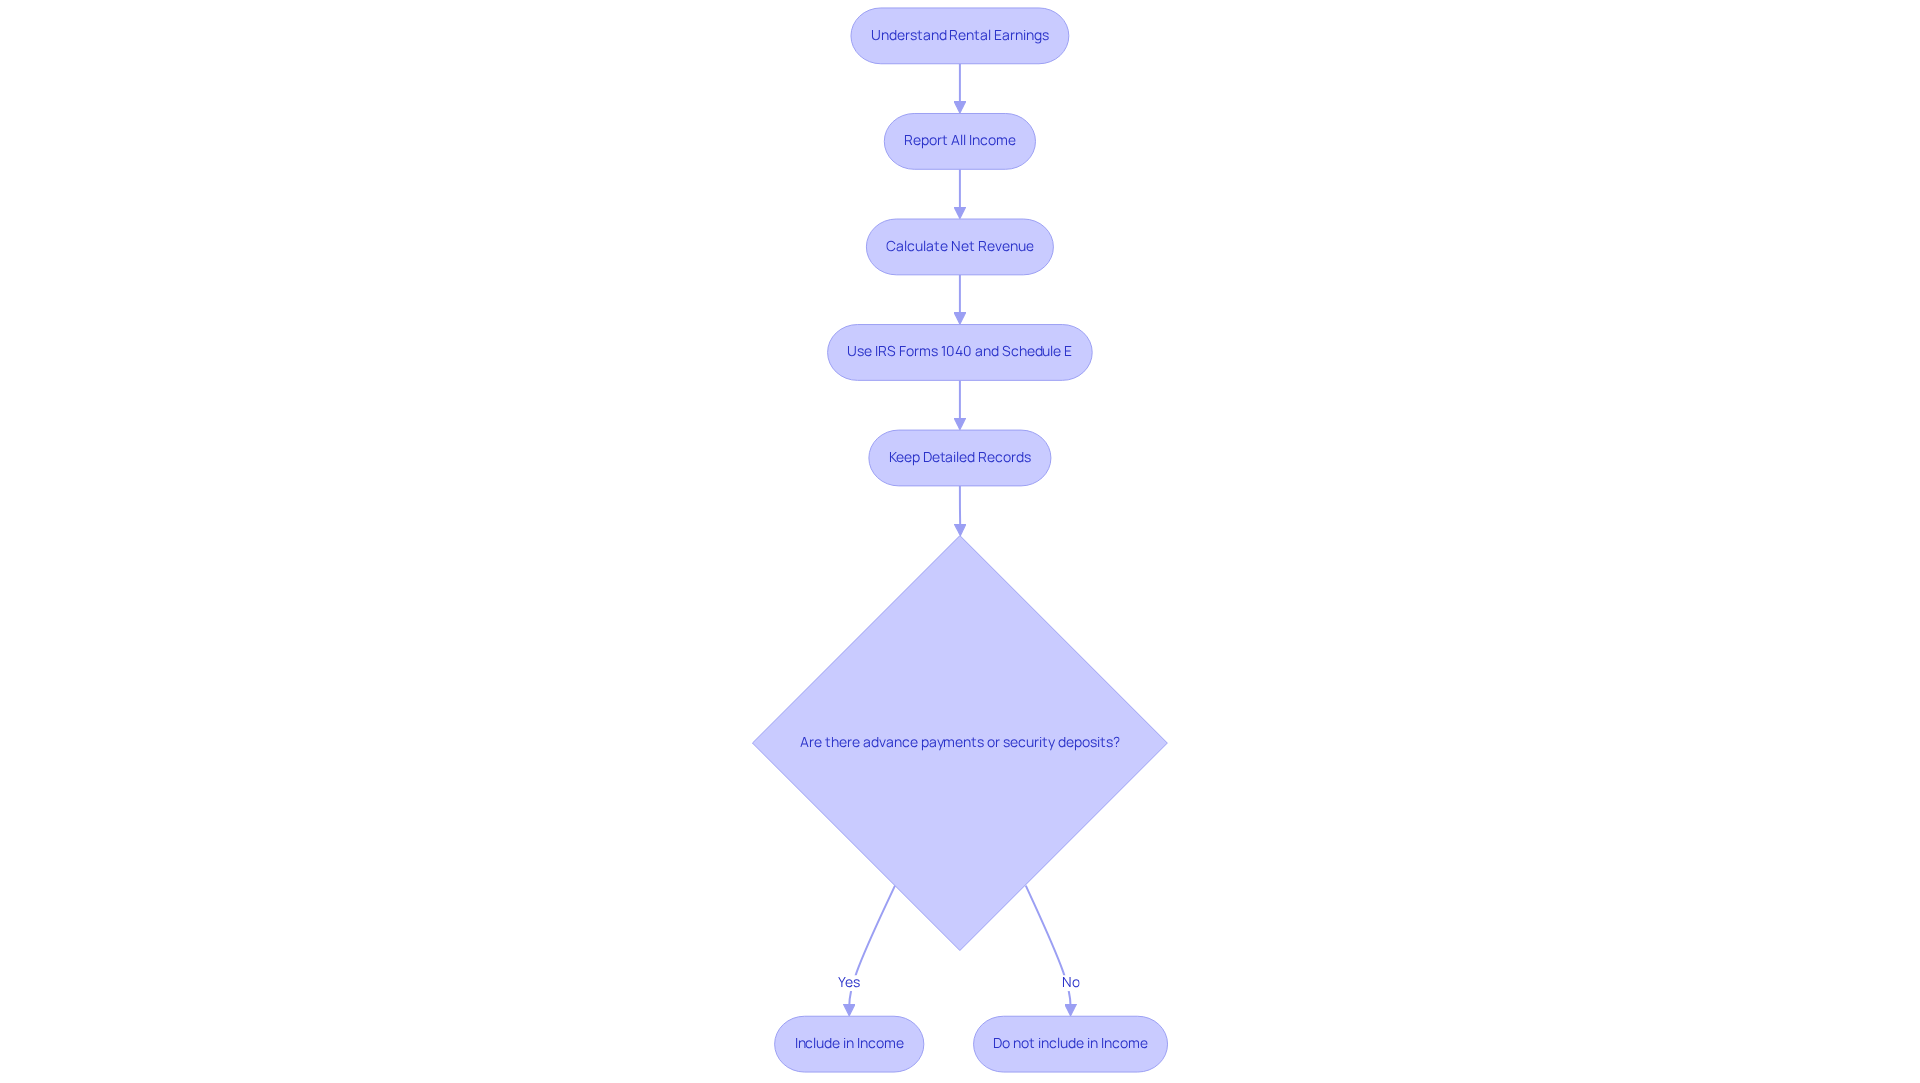
Understanding rental earnings is crucial for your financial well-being. As a landlord, it’s important to understand how to file taxes for rental property, since these earnings are considered taxable revenue and must be declared on your tax return. The IRS requires landlords to disclose all income from leases, including advance rent and security deposits.
Imagine if you could easily differentiate between gross revenue from leasing and net revenue. Net proceeds are calculated after subtracting permissible costs, such as depreciation, which can be filed using Form 4562. Understanding how to file taxes for rental property requires familiarity with IRS Form 1040 and Schedule E, as these documents are used to report your property earnings and related expenses.
By grasping these fundamentals on how to file taxes for rental property, you can avoid common pitfalls and ensure compliance with tax regulations. Precise reporting is vital; unreported earnings might lead to IRS audits and penalties. For instance, if you retain a security deposit due to lease breaches, remember that it must be counted as earnings for that year.
It’s also important to understand how to file taxes for rental property, as all amounts received as rent, including advance payments, must be reported to the IRS, no matter the accounting method you use. Fortunately, the Augusta Rule offers a unique opportunity for tax benefits, allowing homeowners to rent their property tax-free for up to 14 days each year.
By keeping detailed records and following IRS regulations, including understanding the timelines for issuing 1099 forms, you can navigate the intricacies of property earnings taxation effectively. Together, we can manage this journey and ensure your family’s financial future is secure.
Gather Essential Documents and Information
To file your taxes accurately and optimize your financial well-being as a young family, it’s essential to gather some important documents that will make this process smoother:
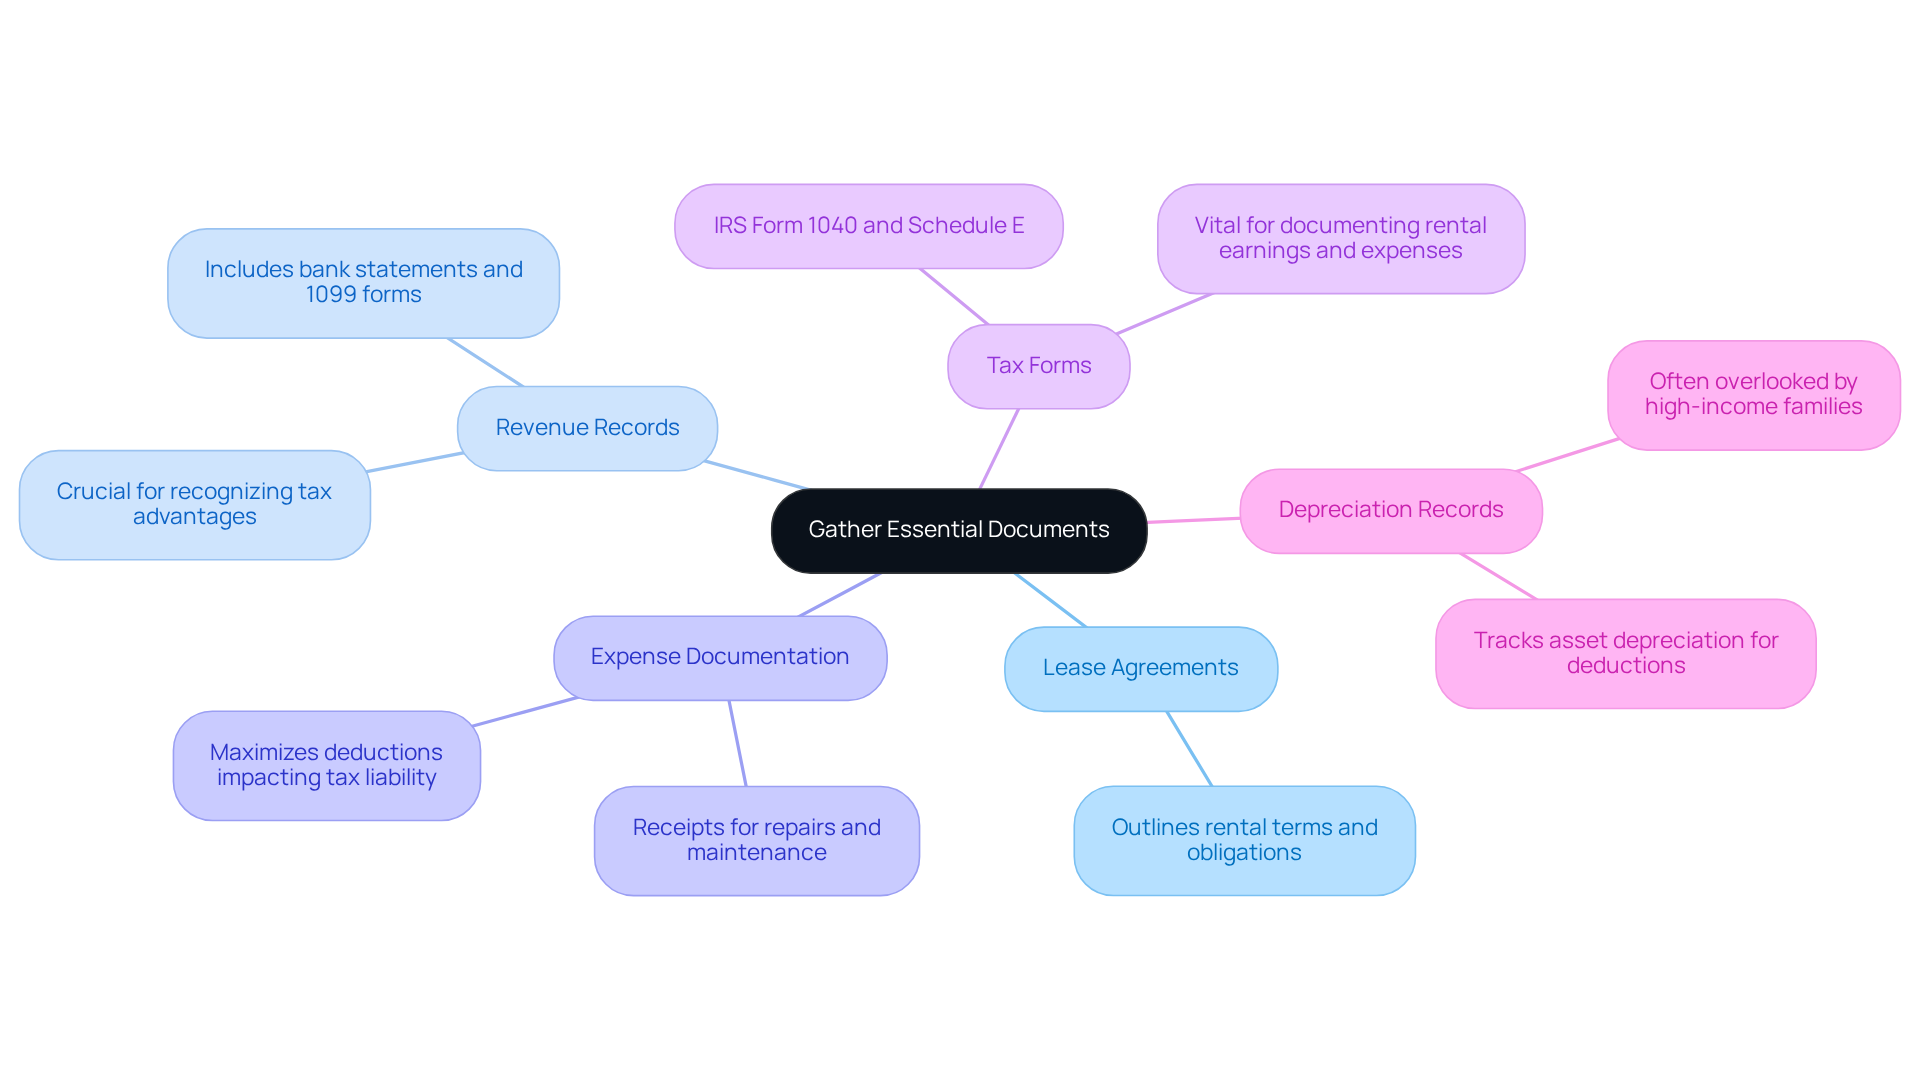
- Lease Agreements: These outline the terms of your rental arrangement, ensuring you understand your obligations and rights. Knowing this can prevent costly mistakes down the road.
- Revenue Records: Include bank statements, receipts, and any 1099 forms received for rental earnings. Having precise financial records is crucial for recognizing potential tax advantages and ensuring you report all your earnings.
- Expense Documentation: Don’t forget to gather receipts for all expenditures related to your estate, such as repairs, maintenance, and management fees. Proper documentation can help you maximize deductions, which can directly impact your overall tax liability.
- Tax Forms: Make sure you have IRS Form 1040 and Schedule E ready for understanding how to file taxes for rental property. These forms are vital for accurately documenting how to file taxes for rental property, including your leasing earnings and expenses.
- Depreciation Records: If applicable, keep track of the depreciation of your asset. This can be a significant deduction that many high-income families often overlook.
By organizing these documents, you’ll streamline the filing process and ensure you claim all eligible deductions. Imagine the peace of mind that comes from knowing you’re making the most of your financial resources! Additionally, consider seeking professional guidance to navigate the complexities of tax planning. Together, we can uncover financial opportunities that may otherwise be missed, ensuring you maximize your wealth accumulation potential. Remember, we’re here for you every step of the way.
Report Rental Income and Expenses Accurately
To accurately document your leasing earnings and learn how to file taxes for rental property, it’s important to utilize Schedule E (Form 1040). Let’s walk through this together, step by step:
-
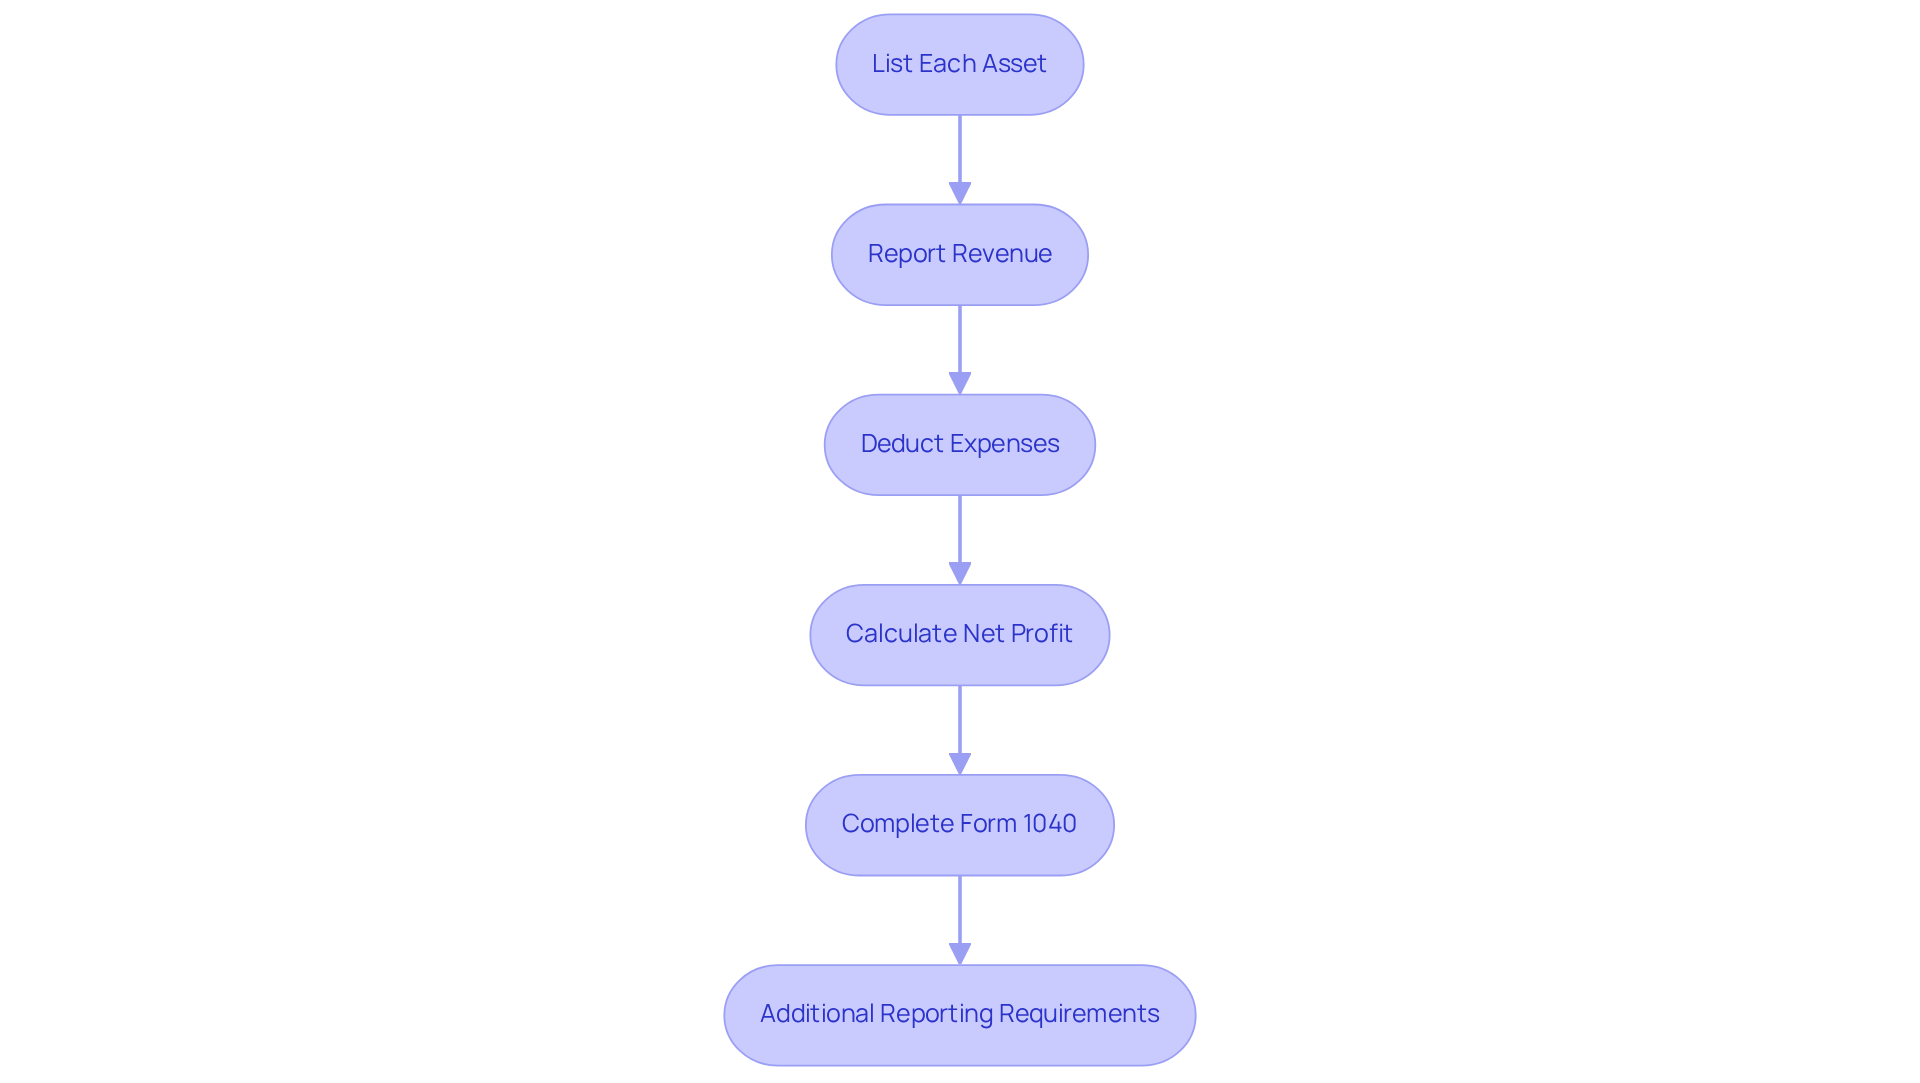
List Each Asset: If you have multiple leased assets, it’s essential to document each one individually on Schedule E. This not only helps in monitoring your revenue but also makes it easier to track expenditures for each asset.
-
Report Revenue: Enter the total rental earnings received for each asset. Remember, this includes not just rent payments but also any extra earnings linked to the asset, like late fees or service charges.
-
Deduct Expenses: In the designated sections, deduct all eligible expenses. Common deductions include mortgage interest, property taxes, repairs, management fees, and utilities. Keeping detailed documentation of these costs is crucial, as they can significantly reduce your taxable earnings from leasing.
-
Calculate Net Profit: Subtract your total expenses from your total earnings to find your net return. This figure is vital for your overall tax reporting.
-
Complete Form 1040: Finally, transfer the net earnings calculated from Schedule E to your Form 1040. This step is key to understanding how to file taxes for rental property, ensuring your leasing earnings are accurately represented in your total tax return.
-
Additional Reporting Requirements: Don’t forget to report the number of lease days and days utilized for personal use, as this is a requirement for Schedule E compliance.
Take a moment to double-check all entries for accuracy to avoid potential issues with the IRS. Mistakes in Schedule E reporting can lead to examinations, so it is essential to understand how to file taxes for rental property and maintain organized records for compliance with the regulations on earnings and deductions.
Remember, 36.6% of U.S. households are renting their homes—the highest rate in 50 years—making accurate reporting even more critical. Additionally, with 74.4% of leased units owned by individual investors, it’s vital to ensure you’re following the proper procedures to prevent any fines. Together, we can navigate this journey and make your financial planning a little easier.
Identify and Claim Rental Tax Deductions
As a rental asset owner, understanding how to file taxes for rental property allows you to significantly reduce your taxable income by claiming various deductions, which can greatly enhance your financial situation. Imagine the relief of knowing you can save money while providing for your family. Here are some common deductions to consider:
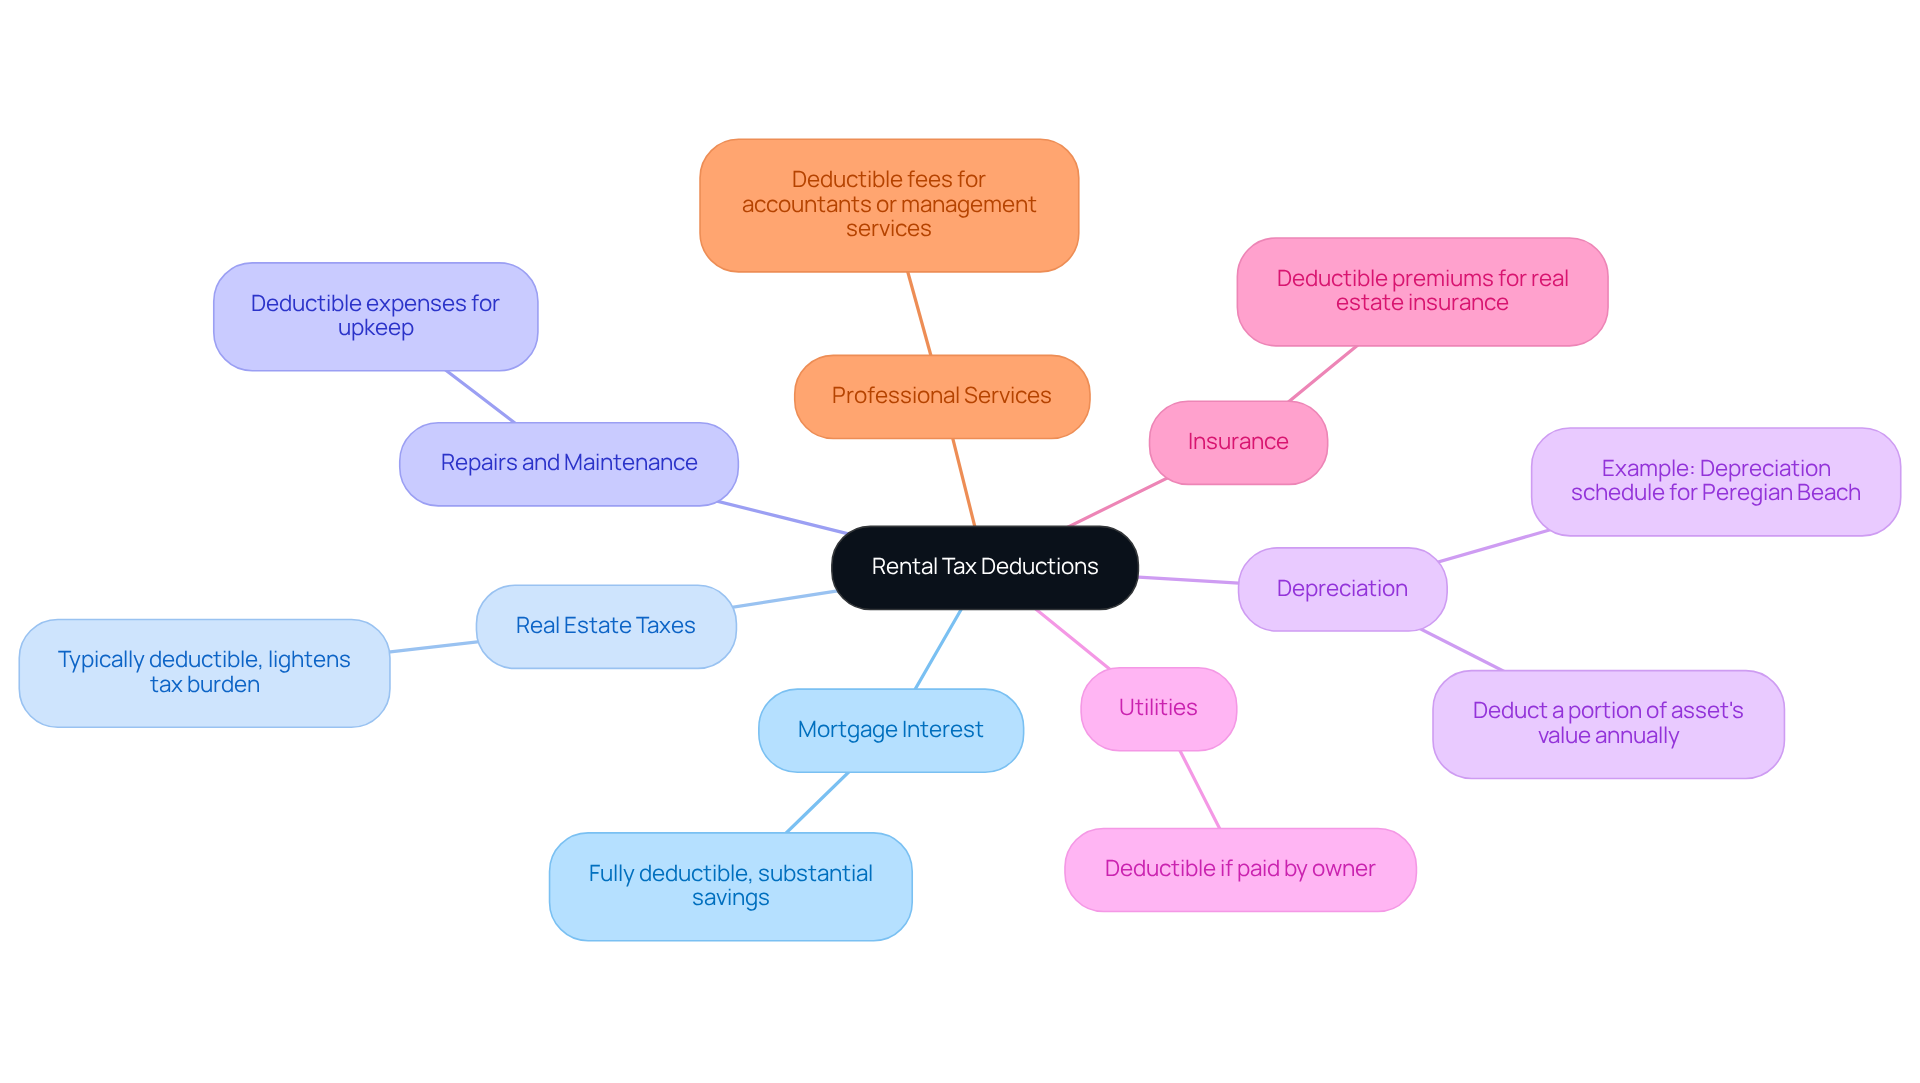
- Mortgage Interest: The interest paid on your mortgage is fully deductible, offering you substantial savings that can be redirected towards your family’s needs.
- Real Estate Taxes: Typically, real estate taxes are deductible, further lightening your tax burden so you can focus on what truly matters.
- Repairs and Maintenance: Expenses related to repairs and upkeep of your rental property can be deducted, ensuring your investment remains in good condition and supports your family’s future.
- Depreciation: You can deduct a portion of the asset’s value each year, leading to considerable tax savings over time. For instance, a leased asset at Peregian Beach was examined to create a depreciation schedule, providing the owner with valuable financial insights.
- Utilities: If you cover utility costs, these expenses are also deductible, helping you manage your budget more effectively.
- Insurance: Premiums for leased real estate insurance can be deducted, safeguarding your investment and providing peace of mind.
- Professional Services: Fees paid to accountants or real estate management services are deductible, allowing you to manage your assets more effectively and focus on your family’s priorities.
To understand how to file taxes for rental property and claim these deductions, it’s important to maintain proper documentation and report them on Schedule E, as utilizing these deductions can lead to significant tax savings, making your rental property a more profitable investment for your family. Remember, seeking professional assistance can further enhance your ability to navigate these complexities. Together, we can navigate this journey and maximize your wealth accumulation potential.
Conclusion
Understanding how to file taxes for rental property is essential for landlords seeking to optimize their financial outcomes. Imagine the peace of mind that comes from familiarizing yourself with the tax implications, necessary forms, and potential deductions. This knowledge not only safeguards against IRS penalties but also empowers you to make informed decisions regarding your investments, ensuring you’re on a path toward financial stability.
Throughout this guide, we’ve highlighted key points that matter to you, including:
- The importance of accurately reporting rental income and expenses
- Gathering essential documentation
- Identifying various deductions available to landlords
It’s important to understand the nuances of Schedule E and recognize the advantages of the Augusta Rule. Each step plays a crucial role in effective tax management, allowing you to navigate these complexities with confidence.
Ultimately, taking proactive steps in understanding and managing rental property taxes can lead to significant financial advantages for your family. We encourage you to embrace the knowledge shared in this guide, ensuring you not only comply with tax regulations but also leverage available benefits to enhance your financial health. Remember, the journey of property ownership is not just about managing assets; it’s about securing a brighter financial future for your loved ones. Together, we can navigate this journey, supporting each other along the way.
Frequently Asked Questions
Why is it important to understand rental property tax basics?
Understanding rental property tax basics is crucial for financial well-being, as rental earnings are considered taxable revenue that must be declared on your tax return.
What income must landlords report to the IRS?
Landlords must report all income from leases, including advance rent and security deposits, to the IRS.
How do you differentiate between gross revenue and net revenue from rental properties?
Gross revenue is the total income from leasing, while net revenue is calculated after subtracting permissible costs, such as depreciation.
Which forms are necessary for filing taxes on rental property?
To file taxes for rental property, landlords need to use IRS Form 1040 and Schedule E to report property earnings and related expenses.
What are the consequences of not accurately reporting rental income?
Failing to report rental income can lead to IRS audits and penalties, as unreported earnings are a significant compliance issue.
How should security deposits be treated for tax purposes?
Security deposits must be counted as earnings for the year if retained due to lease breaches.
What does the Augusta Rule offer for homeowners?
The Augusta Rule allows homeowners to rent their property tax-free for up to 14 days each year, providing a unique opportunity for tax benefits.
What practices can help landlords navigate rental property taxation effectively?
Keeping detailed records and understanding IRS regulations, including the timelines for issuing 1099 forms, can help landlords manage property earnings taxation effectively.
List of Sources
- Understand Rental Property Tax Basics
- Topic no. 414, Rental income and expenses | Internal Revenue Service (https://irs.gov/taxtopics/tc414)
- About The 1099 Requirements For Rental Income – Landlord Studio (https://landlordstudio.com/blog/1099-requirements-for-rental-income)
- IRS Rules for Rental Property: Landlord Tax Guide for 2025 (https://turbotenant.com/accounting/irs-rules-for-rental-property)
- Tips on rental real estate income, deductions and recordkeeping | Internal Revenue Service (https://irs.gov/businesses/small-businesses-self-employed/tips-on-rental-real-estate-income-deductions-and-recordkeeping)
- Report Rental Income and Expenses Accurately
- Reporting Rental Finances: Schedule E (https://bradyware.com/reporting-rental-finances-schedule-e)
- 8 Rental Statistics Every Landlord Needs to Know Today (https://mysmartmove.com/blog/6-rental-statistics-landlords-need-know)
- Landlord Statistics by Category, Income, Unit, & More (https://doorloop.com/blog/landlord-statistics-by-category-income-unit-more)
- Schedule E: How to use this tax form to report rental income and losses (https://finance.yahoo.com/news/schedule-e-tax-form-report-015936764.html)
- About Schedule E (Form 1040), Supplemental Income and Loss | Internal Revenue Service (https://irs.gov/forms-pubs/about-schedule-e-form-1040)
- Identify and Claim Rental Tax Deductions
- How NBTax has helped their clients with property investments (https://nbtax.com.au/case_studies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading