

Overview
Navigating a whole life insurance policy can feel overwhelming, especially for young parents. It’s essential to take a moment to reflect on your reasons for considering cancellation. Start by reviewing your agreement and reaching out to your insurer, as these steps can provide clarity. Remember, understanding the financial implications of losing coverage and cash value is crucial for your family’s future.
Imagine if you could secure your family’s financial well-being while exploring new opportunities. This article offers a structured approach to help you make informed decisions about your insurance and financial future. By understanding your personal financial needs and potential investment options after cancellation, you can take charge of your family’s financial journey.
We’re here for you every step of the way, ensuring that you feel supported as you navigate these important decisions. Together, we can explore the best options that align with your family’s values and goals, helping you create a brighter financial future.
Key Highlights:
- Whole life insurance offers lifelong coverage and builds cash value, unlike term policies.
- Policies require regular premium payments to maintain coverage and cash value growth.
- Higher premiums for whole life insurance reflect its lifelong protection and potential dividends.
- Reasons to consider cancelling a whole life policy include financial strain, changing needs, and better investment alternatives.
- Steps to cancel a whole life insurance policy include reviewing the agreement, contacting the insurer, and confirming cancellation.
- Post-cancellation, individuals should assess the loss of coverage, cash value impact, tax implications, and future insurance needs.
- Redirecting cash from a cancelled policy into other investments can enhance financial stability.
Introduction
Navigating the complexities of whole life insurance can feel overwhelming, especially when contemplating the decision to exit a policy that promises lifelong protection. Imagine a safety net that not only supports your family but also accumulates cash value—this is what whole life insurance offers, making it a vital component of many financial strategies. Yet, as life evolves and personal circumstances shift, the choice to cancel a whole life policy can bring forth significant questions about your financial security and future needs.
It’s important to understand the implications of letting go of such a meaningful investment. How can you ensure that this choice aligns with your long-term financial goals? Remember, we’re here for you as you navigate this journey together.
Understand Whole Life Insurance Basics
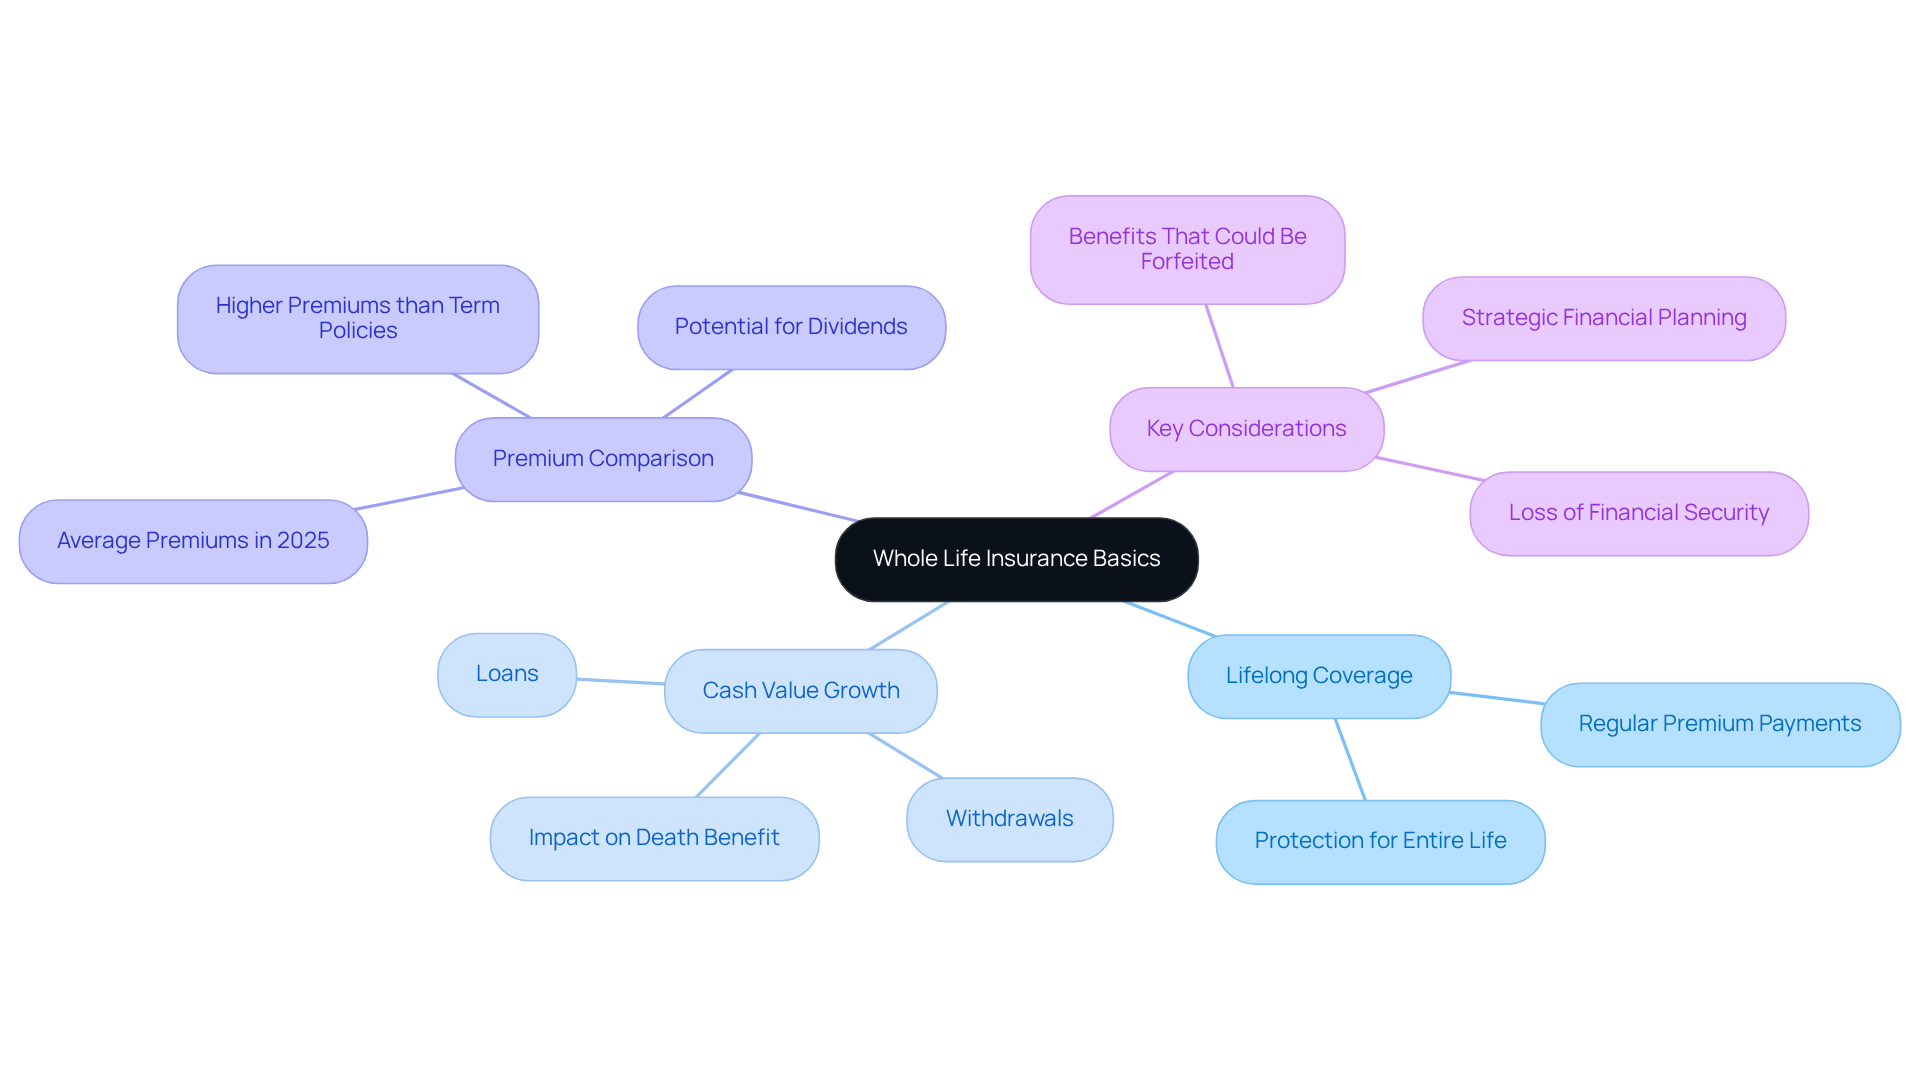
Whole life coverage offers a lasting safety net, providing protection for your entire life, as long as premiums are regularly paid. Imagine knowing that your loved ones are secure no matter what. Unlike term coverage, which lasts only for a set time, whole life policies build cash value over the years. This cash value can be accessed through loans or withdrawals, giving you flexibility, although it’s important to remember that any loans taken will reduce the death benefit.
While whole life plans often come with higher premiums than term policies, they provide lifelong protection and the potential for dividends based on the insurer’s performance. In 2025, the average premium for whole life coverage is expected to be significantly higher than that of term coverage, reflecting the added benefits of lifelong security and cash value growth.
Before deciding how to get out of a whole life insurance policy, it is crucial to understand these key elements:
- Recognize the potential loss of financial security.
- Understand the benefits that could be forfeited.
Financial consultants emphasize that whole life coverage is more than just a safety net; it’s a strategic part of financial planning that helps families manage risks and secure their futures.
By incorporating whole life coverage into a comprehensive financial strategy, families can navigate their financial planning challenges more effectively. At Bright Advisers, we are committed to minimizing fund fees and employing innovative investment strategies, ensuring that families are equipped to secure their futures and alleviate worries about unexpected events.
Real-life stories illustrate how families have successfully utilized whole life policies to enhance their financial stability, making it a vital consideration for those looking to protect their loved ones. Together, we can navigate this journey, ensuring that your family’s future is safeguarded with care and compassion.
Identify Reasons to Exit Your Policy
Before you make the decision to cancel your whole life insurance policy, take a moment to reflect on some important reasons that might influence this choice:
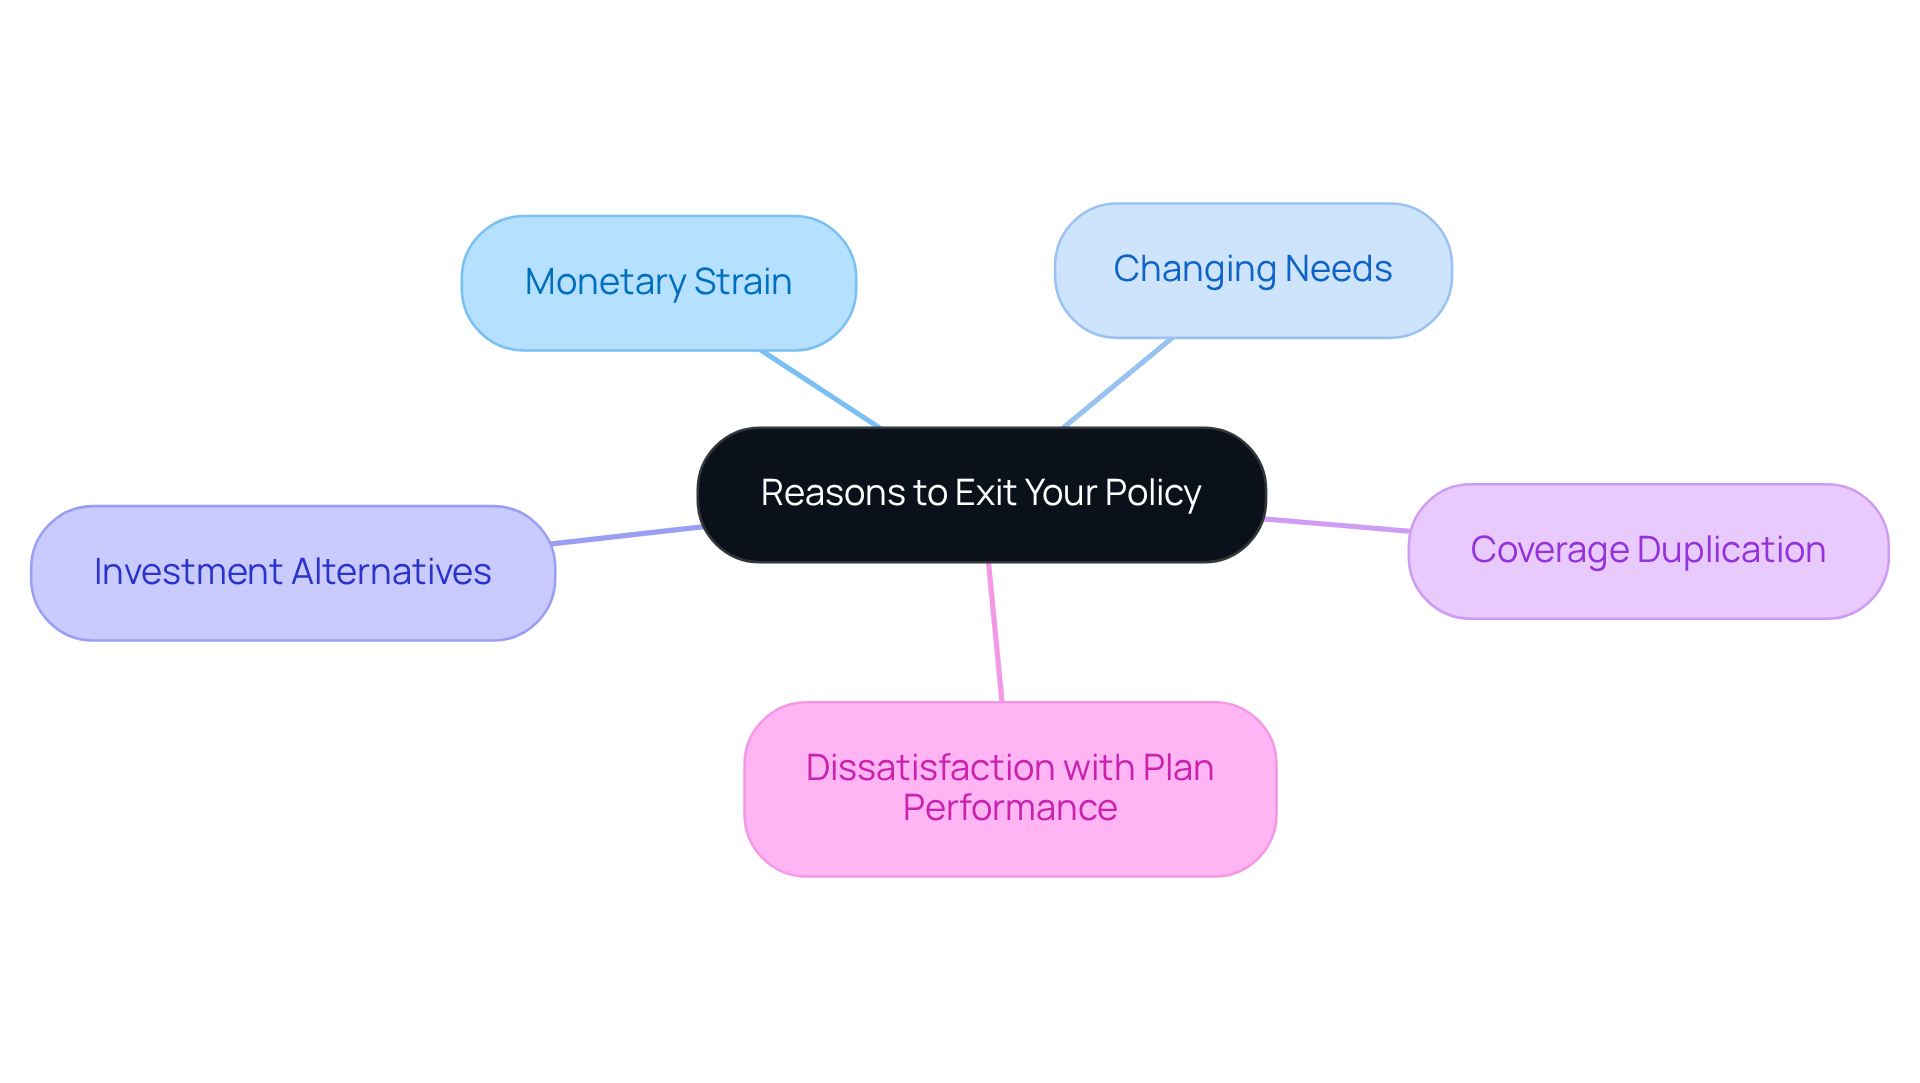
- Monetary Strain: If you find that the premiums are placing a burden on your budget, it could be time to reassess your financial commitments.
- Changing Needs: As your family grows or your financial situation evolves, you may realize that your coverage needs have changed.
- Investment Alternatives: You might discover that there are other investment opportunities that offer better returns than the cash value growth of your whole life insurance plan.
- Coverage Duplication: If you have other life insurance policies or sufficient savings, you may not need the protection that your whole life policy provides.
- Dissatisfaction with Plan Performance: If your plan hasn’t met your expectations, it may be worth considering cancellation.
Taking the time to reflect on these reasons can help you understand how to get out of a whole life insurance policy and determine whether canceling your coverage is the right step for your family’s financial future. Remember, we’re here for you as you navigate these important decisions together.
Follow Steps to Cancel Your Whole Life Insurance Policy
Navigating how to get out of a whole life insurance policy can feel overwhelming, but we’re here to help you through the process. Follow these steps to ensure a smooth process:
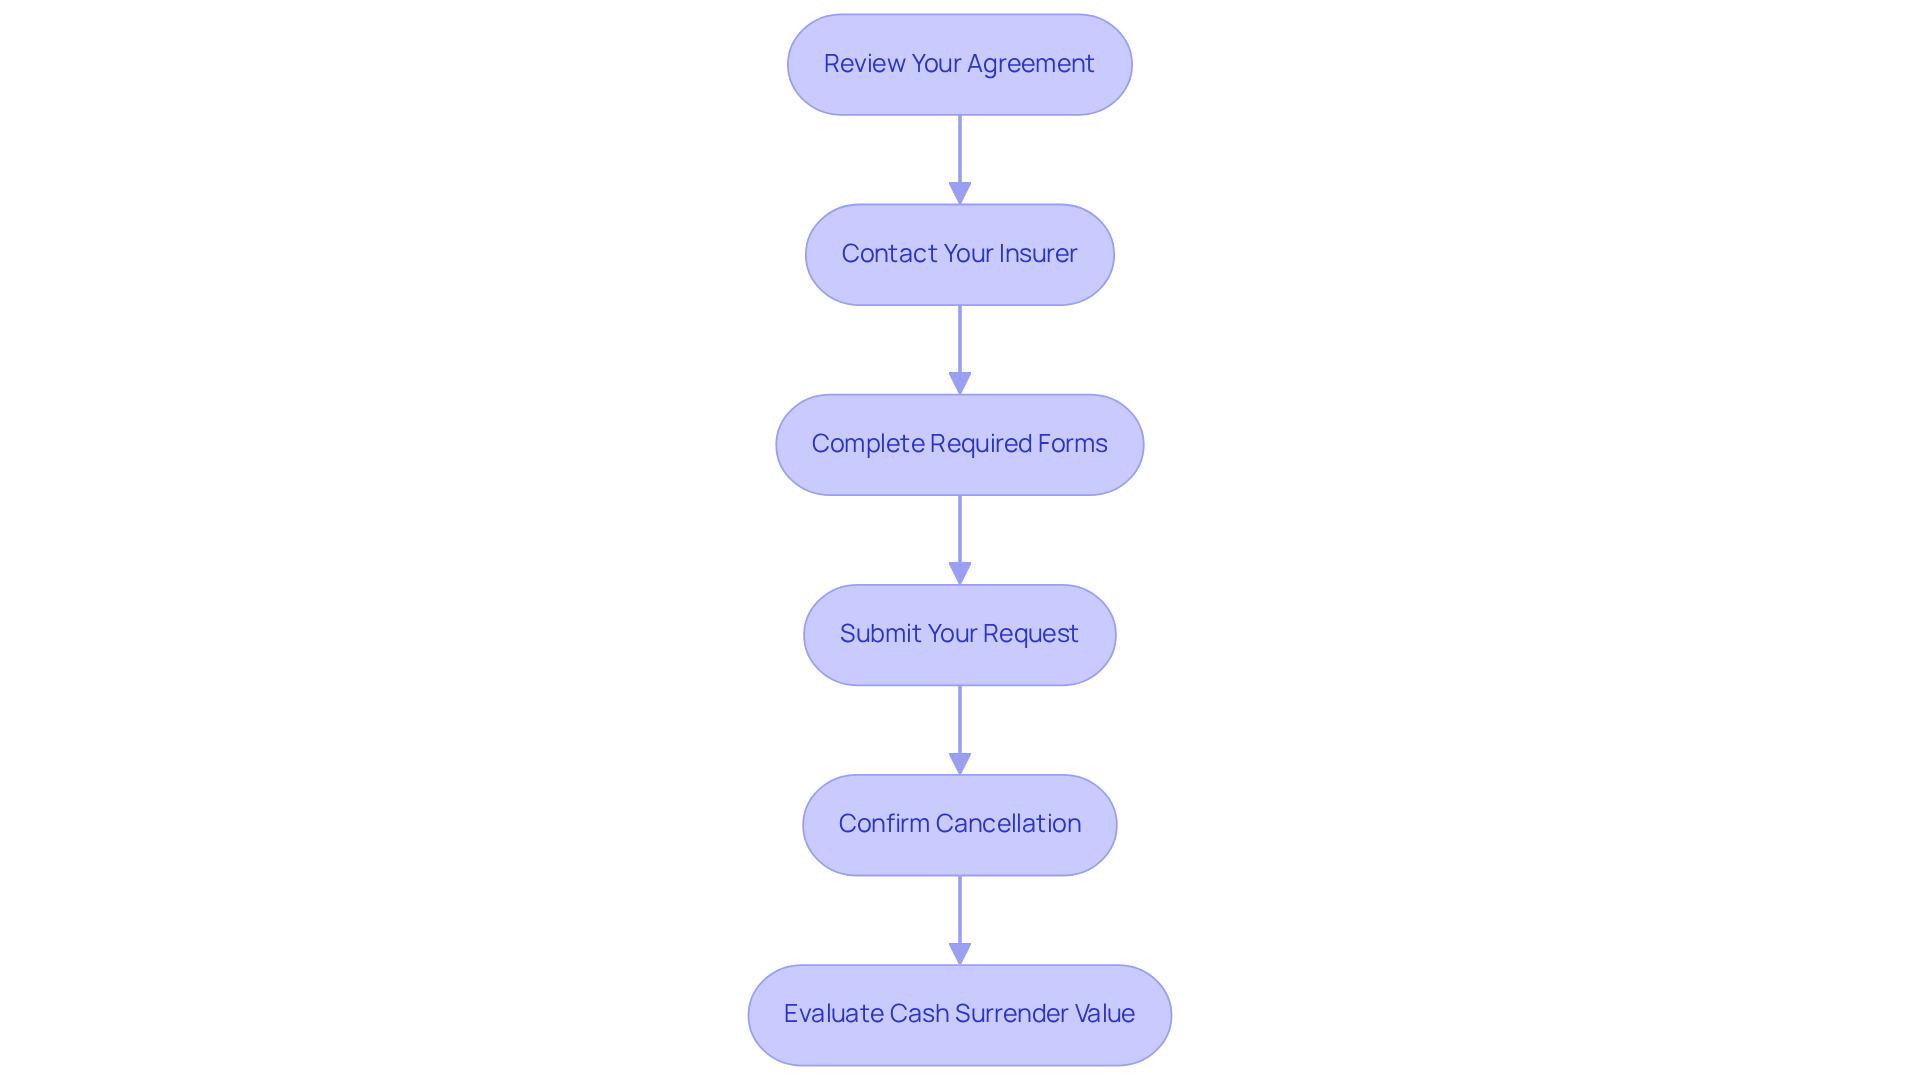
- Review Your Agreement: Begin by taking a moment to examine your documents. Understanding the terms and conditions related to cancellation is crucial, especially regarding any potential penalties or fees that may apply.
- Contact Your Insurer: Reach out to your insurance company via phone, email, or their website. Inquire about the cancellation process and any specific forms you may need to complete. Remember, your insurer is there to assist you.
- Complete Required Forms: Fill out the cancellation forms provided by your insurer, making sure to include all necessary information. This attention to detail can help prevent any delays in processing your request.
- Submit Your Request: Send your cancellation request along with any required documentation. Be sure to retain a copy for your records—having proof of your request is important.
- Confirm Cancellation: After submitting your request, follow up with your insurer to ensure that your coverage has been canceled. This step is vital to understanding any final actions regarding cash value or outstanding loans.
- Evaluate Cash Surrender Value: If applicable, ask about the cash surrender value of your plan and the procedure for its disbursement. This knowledge can empower you in your financial decisions.
The time it takes to terminate a whole life policy can vary, but many families report completing the process within a few weeks. It’s essential to recognize that around 14% of whole life insurance policies result in a payout, highlighting the financial implications of cancellation. Many families have successfully transitioned from whole life coverage by understanding how to get out of a whole life insurance policy, highlighting the importance of knowing the cancellation process. As one coverage agent wisely noted, “Navigating the cancellation process can be complex, but being informed is key to making the right decision for your family’s future.” By following these steps and considering the broader context of cancellation rates, you can navigate this journey with confidence, making informed choices for your family’s financial well-being.
Evaluate Financial Implications Post-Cancellation
After canceling your whole life insurance policy, it’s essential to consider how to get out of a whole life insurance policy and the financial implications that may arise.
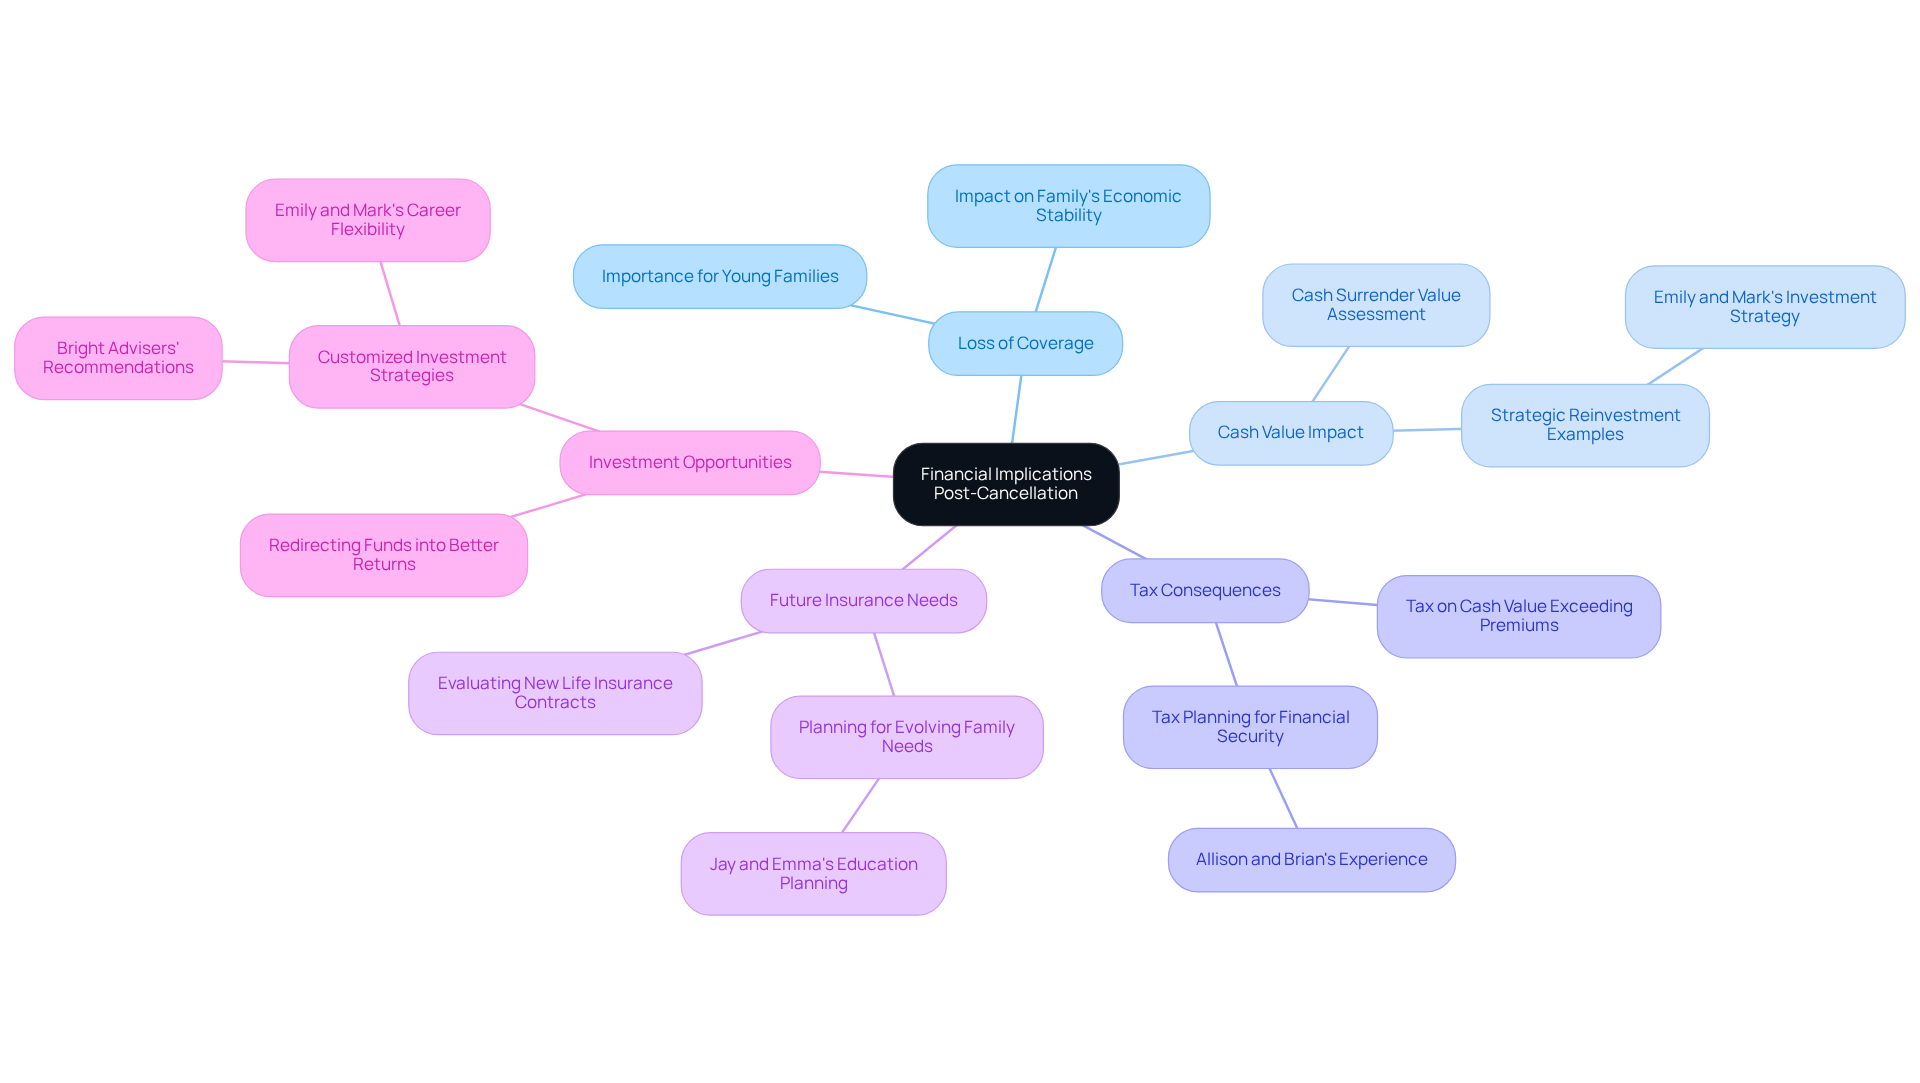
Loss of Coverage: Imagine the impact of no longer having life insurance coverage. This change could significantly affect your family’s economic stability in the event of your passing. For young families, like Jay and Emma, this coverage is crucial to protect their loved ones and alleviate monetary stress.
Cash Value Impact: If you received a cash surrender value, take a moment to assess how this amount relates to how to get out of a whole life insurance policy within your overall monetary strategy. For instance, Emily and Mark redirected their cash value into investments that aligned with their long-term goals, showcasing the importance of strategic reinvestment.
It’s important to understand any tax consequences associated with cashing out your plan when learning how to get out of a whole life insurance policy. If the cash value exceeds the total premiums paid, you may owe taxes on the difference. Just like Allison and Brian, who learned that proper tax planning could minimize these liabilities and enhance their financial security, you too can benefit from careful consideration regarding how to get out of a whole life insurance policy.
Future Insurance Needs: As you reflect on your situation, evaluate whether you will need to acquire a new life insurance contract in the future and how that might influence your budget. Young families should think about their evolving needs, much like how Jay and Emma planned for their children’s education while ensuring they had adequate coverage.
Investment Opportunities: Consider how the funds from the canceled policy can be redirected into other investment opportunities that may offer better returns. Bright Advisers advocates for customized investment strategies, as seen with Emily and Mark, who gained the flexibility to make career decisions based on their desired work-life balance.
By thoughtfully evaluating these implications, you can make informed decisions that align with your family’s financial goals. Remember, we’re here for you, supporting you in ensuring a secure and prosperous future.
Conclusion
Navigating the complexities of whole life insurance can feel overwhelming, especially when faced with the choice to cancel a policy. This guide has illuminated the essential aspects of whole life insurance, from its benefits and cash value growth to the potential financial implications of cancellation. Understanding these elements is crucial for making informed choices that resonate with your personal and family financial goals.
Key insights covered include:
- Recognizing the reasons for exiting a policy
- The step-by-step cancellation process
- Evaluating the financial repercussions post-cancellation
Factors such as changing family needs, financial strain, and alternative investment opportunities play a significant role in this decision. It’s important to understand the cash surrender value and potential tax implications, as these can significantly impact your future financial stability.
Ultimately, the decision to exit a whole life insurance policy deserves careful thought. It requires you to consider both your current circumstances and your long-term financial objectives. Families are encouraged to reflect on their unique situations and seek professional guidance if needed. By doing so, you can ensure that your financial strategies remain robust, secure, and well-suited to your evolving needs. Remember, together, we can navigate this journey, ensuring your family’s financial well-being is prioritized.
Frequently Asked Questions
What is whole life insurance?
Whole life insurance provides lifelong coverage as long as premiums are paid. It offers a safety net for your loved ones, unlike term insurance which only lasts for a specified period.
How does whole life insurance differ from term life insurance?
Whole life insurance lasts for your entire life and builds cash value over time, while term life insurance provides coverage for a limited period without accumulating cash value.
What is the cash value in a whole life insurance policy?
The cash value is a savings component that accumulates over the years in a whole life policy. It can be accessed through loans or withdrawals, but any loans taken will reduce the death benefit.
Are the premiums for whole life insurance higher than those for term policies?
Yes, whole life insurance premiums are generally higher than term policy premiums, reflecting the lifelong protection and cash value growth it offers.
What should I consider before canceling a whole life insurance policy?
Before canceling, it’s important to recognize the potential loss of financial security and understand the benefits that could be forfeited.
How can whole life insurance be part of a financial strategy?
Whole life insurance is considered a strategic part of financial planning, helping families manage risks and secure their futures effectively.
What role do financial consultants play in whole life insurance?
Financial consultants emphasize the importance of whole life coverage in financial planning and help families minimize fees and implement innovative investment strategies.
Can you provide examples of how families have benefited from whole life insurance?
Real-life stories show that families have successfully used whole life policies to enhance their financial stability, making it a significant consideration for protecting loved ones.
List of Sources
- Understand Whole Life Insurance Basics
- What Can Insurance Protect You From: Key Coverage Insights – Bright Advisers (https://brightadvisers.com/what-can-insurance-protect-you-from-key-coverage-insights)
- Case Study: Retirees – Mariaca Wealth Management (https://mariacawealth.com/case_studies/retirees)
- Follow Steps to Cancel Your Whole Life Insurance Policy
- Do 80% of Whole Life Policyholders Cancel their Policies? • The Insurance Pro Blog (https://theinsuranceproblog.com/no-80-of-whole-life-policyholder-dont-cancel-their-policies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading