

Key Highlights
- UTMA accounts allow parents to transfer assets to minors without setting up a formal trust, managed by a custodian until the child reaches adulthood.
- Investment growth in UTMA accounts can benefit from lower tax rates on earnings, enhancing savings potential for children.
- Custodianship can extend until age 25 in some states, providing ongoing support for significant life events like college.
- Bright Advisers offers personalised investment strategies for families, emphasising fiduciary duty and transparency with no hidden fees.
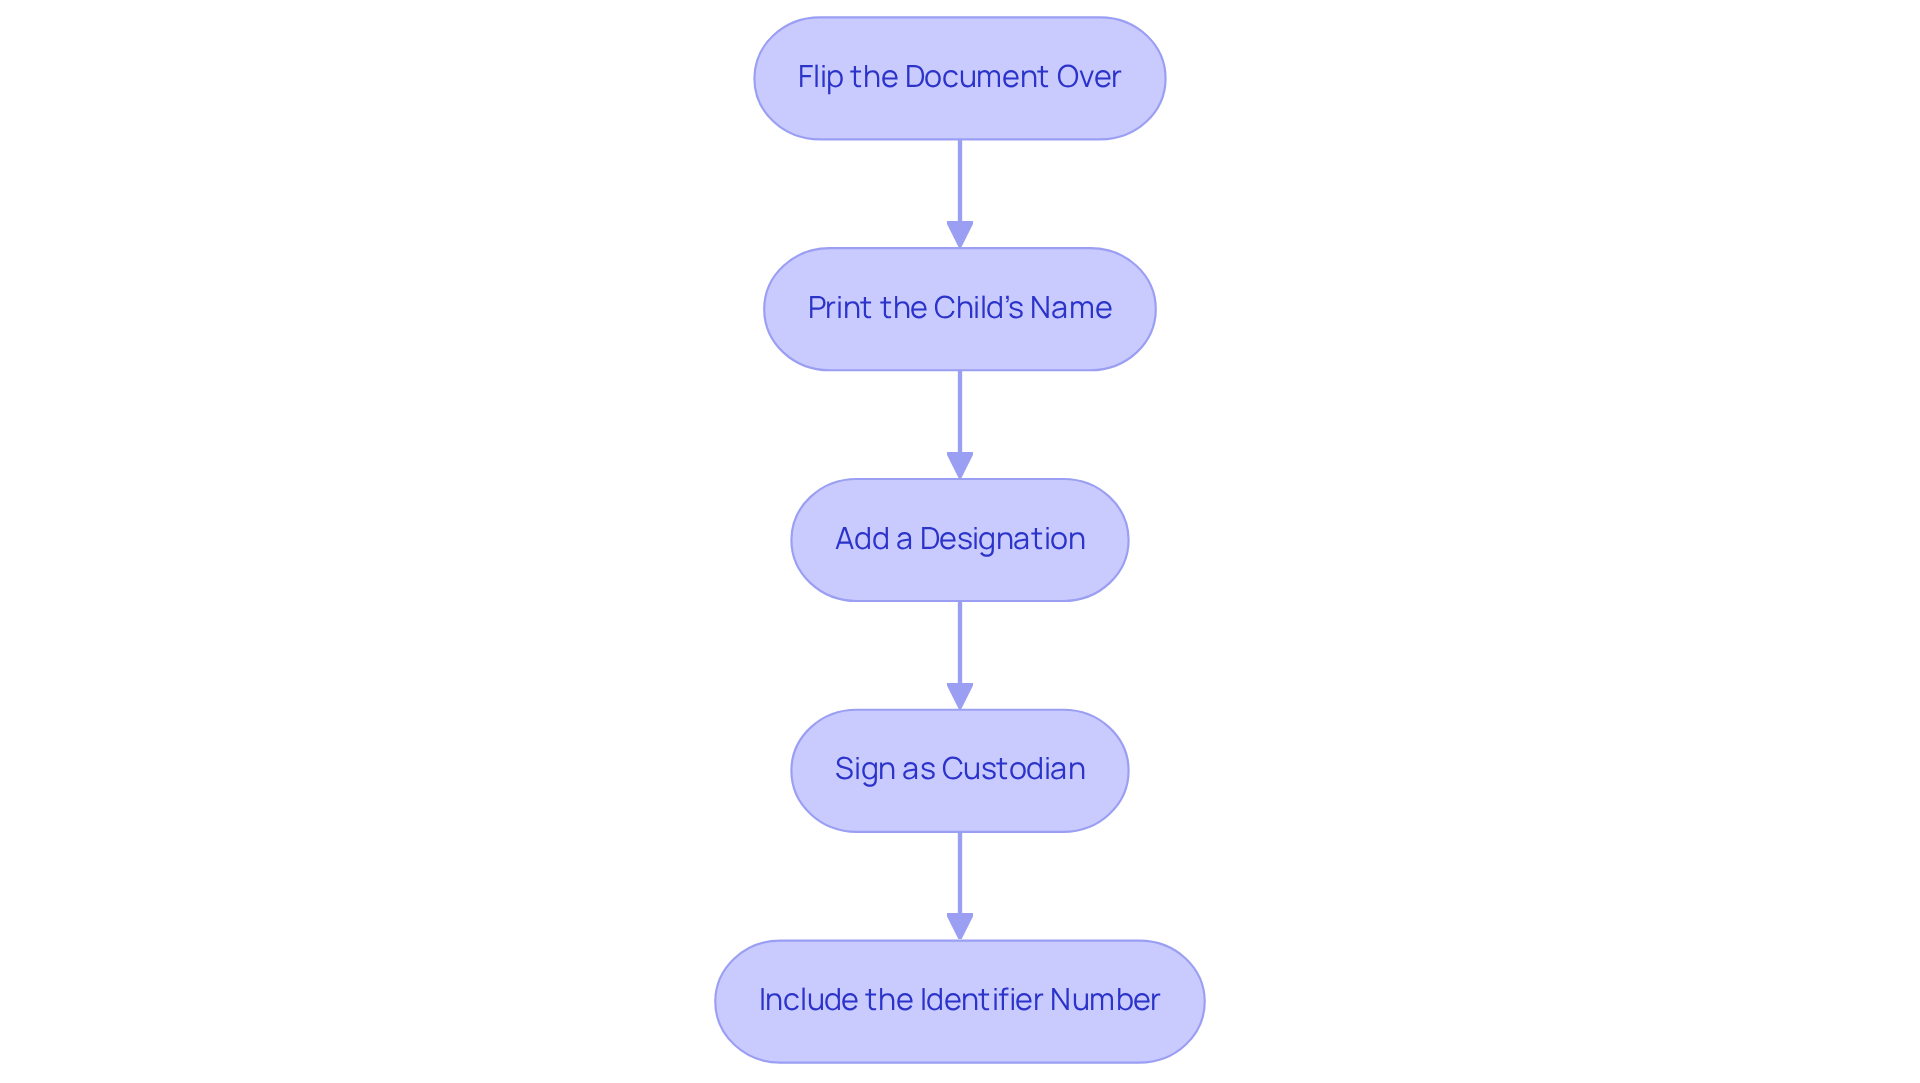
- To endorse a UTMA cheque, write the child’s name, add ‘- minor’, sign as custodian, and optionally include the custodial account number.
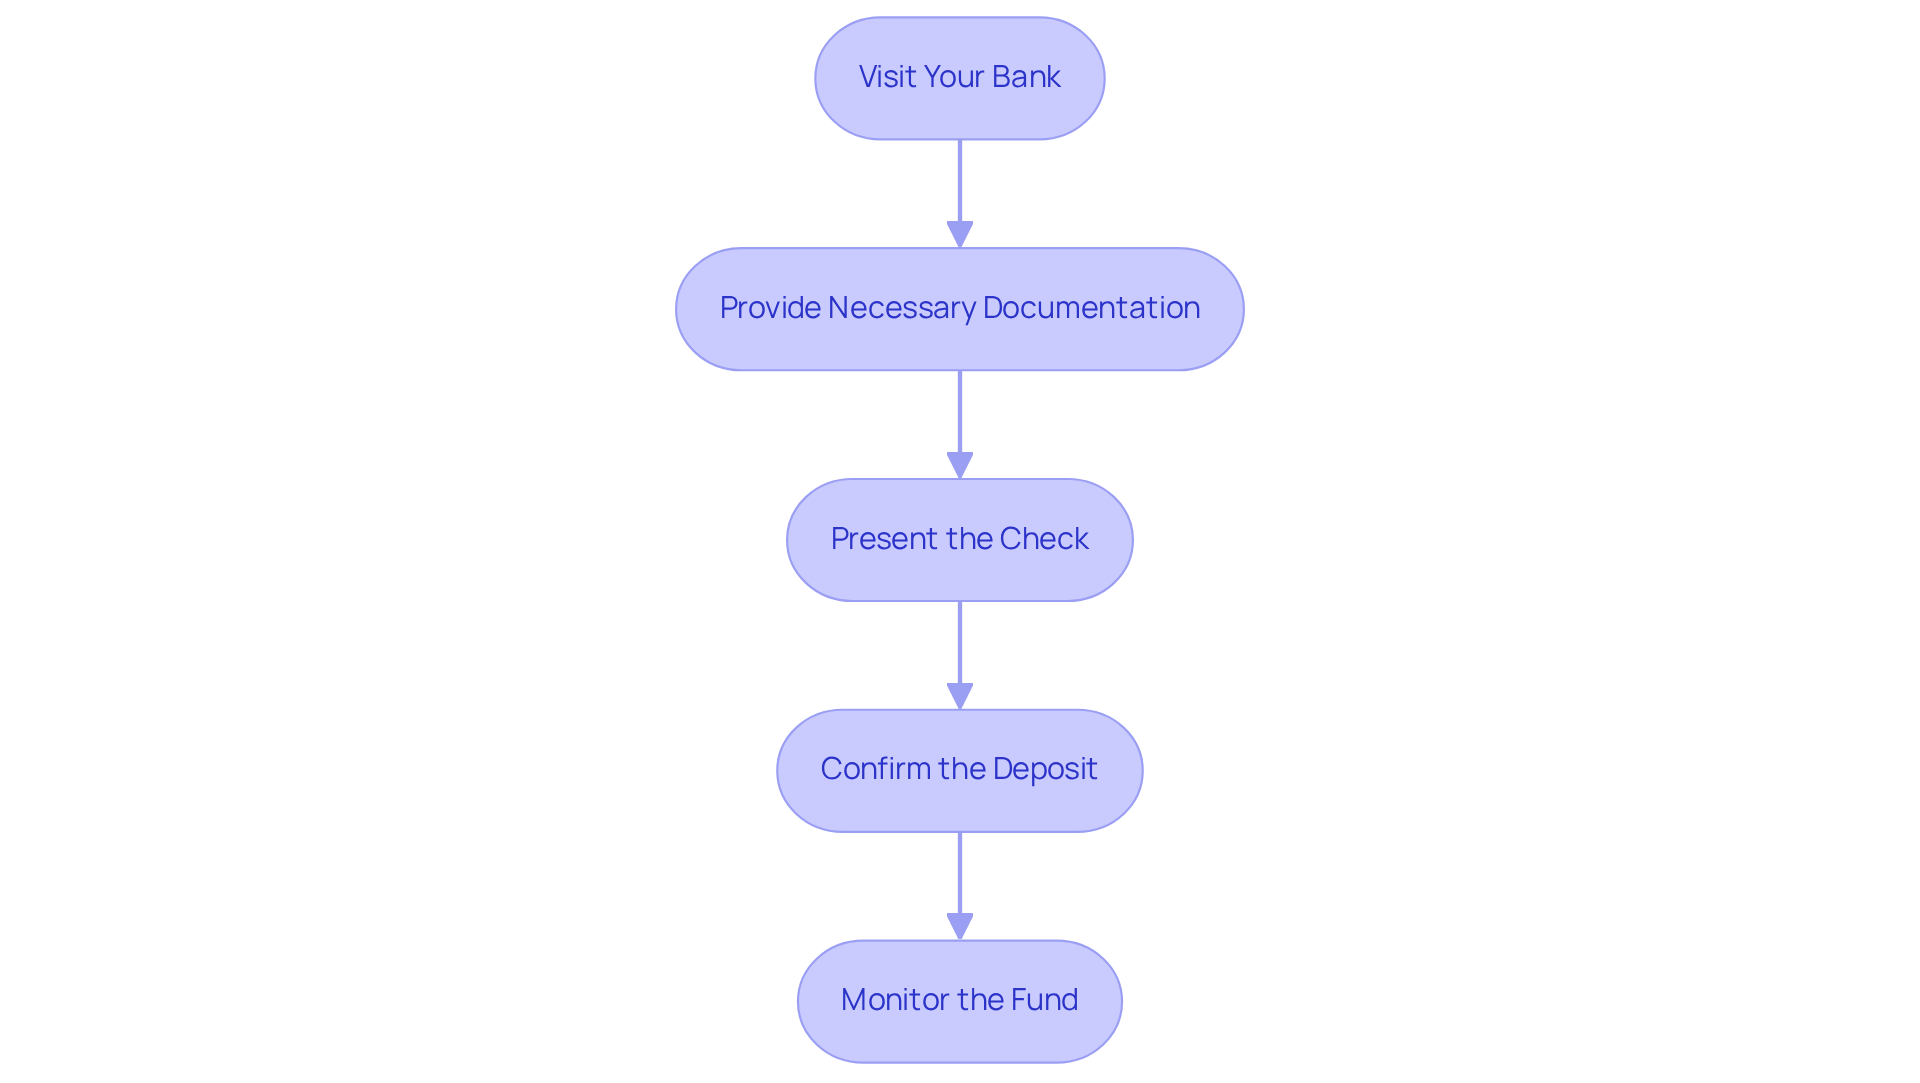
- Depositing a UTMA cheque involves providing documentation, presenting the endorsed cheque to a bank teller, and confirming the deposit.
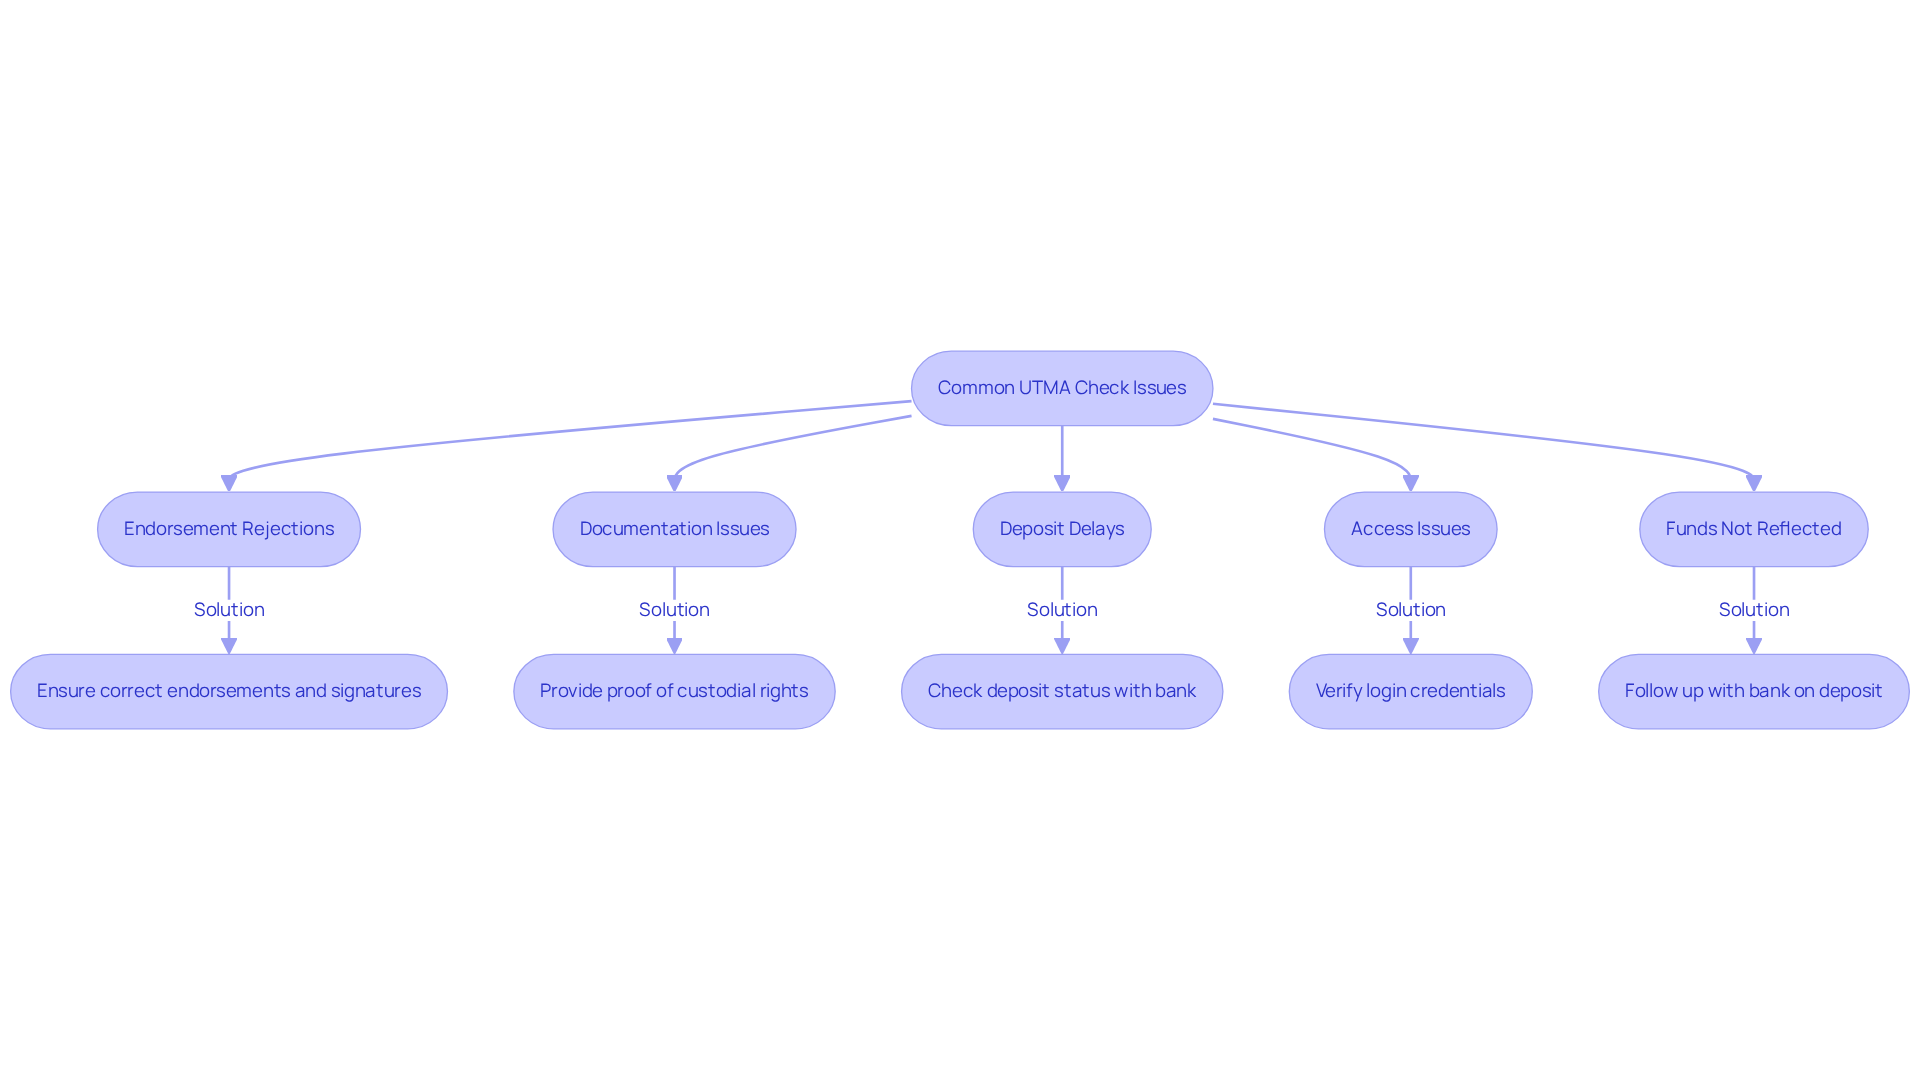
- Common issues include endorsement rejections, documentation requests, deposit delays, access problems, and unreflected funds; solutions involve proper preparation and communication with the bank.
- Families can take advantage of tax-free income up to $2,600 annually for children in 2024, highlighting the importance of effective UTMA account management.
- Investments are subject to risk, and past performance does not guarantee future results; families should consider these factors when planning.
Introduction
Many parents find themselves overwhelmed by the complexities of managing a UTMA (Uniform Transfers to Minors Act) account, but you’re not alone in this journey. These custodial accounts offer a unique opportunity to secure your child’s financial future through tax-advantaged savings. However, many parents feel lost when it comes to handling checks for their child’s account. How can you ensure a smooth endorsement and deposit process while avoiding common pitfalls?
Let’s explore the essential steps together to make managing UTMA accounts easier for you. With the right guidance, you can turn confusion into confidence, ensuring a brighter financial future for your child.
Understand UTMA Accounts and Their Purpose
Imagine a future where your child’s financial dreams are within reach, thanks to smart planning today. UTMA (Uniform Transfers to Minors Act) funds are a wonderful way to start saving for your child’s future, offering tax benefits that can really make a difference. These custodial arrangements allow you to transfer assets like cash, stocks, or securities to your child without the hassle of setting up a formal trust. A custodian oversees these funds until your child reaches adulthood, typically between 18 and 21, depending on where you live.
With a custodian guiding the investments, your child can benefit from a mix of stocks, bonds, and mutual funds, setting them up for a brighter future. This investment growth can be a significant advantage when they finally take control of the funds. Plus, earnings in custodial accounts are usually taxed at your child’s lower tax rate, which can enhance their overall savings potential.
Understanding the purpose and benefits of custodial funds is crucial for parents who want to secure their children’s financial futures. These arrangements not only provide flexibility in managing assets but also offer a straightforward way to gift funds to minors, ensuring that the money is used for their benefit. In some states, custodianship can even extend until your child turns 25, providing continued support during important life stages like college.
In Southern California, more families are turning to custodial savings plans as effective wealth management solutions. Bright Advisers offers innovative strategies that enhance the benefits of custodial funds through personalized investment portfolios. By leveraging advanced technology, Bright Advisers creates tailored financial plans that align with your family’s unique goals, incorporating strategies that maximize financial outcomes and ease your worries.
With a minimum investment of just $1,000 for both UGMA and custodial funds, these options are accessible and valuable tools for parents looking to invest in their children’s futures while navigating financial planning complexities. Bright Advisers prioritizes fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest, which is essential for families making significant financial decisions.
Don’t let the complexities of financial planning hold you back from securing your child’s future; take the first step with us today. If you’re curious about how Bright Advisers can assist you in managing custodial funds and other wealth management strategies, consider joining our client waitlist.
Endorse the Check Correctly
Navigating the endorsement process for a UTMA account can feel overwhelming, but it doesn’t have to be. Follow these simple steps to ensure everything goes smoothly.
- Flip the Document Over: Start by turning the document over to access the endorsement area on the back.
- Print the Child’s Name: Clearly write the child’s full name as it appears on the front of the payment. For example, if the payment is made out to ‘John Doe’, write ‘John Doe’.
- Add a Designation: After the child’s name, include a hyphen followed by the term ‘minor’ to specify that the check is intended for a child’s account. It should state: ‘John Doe – minor’.
- Sign as Custodian: Below the minor’s name, sign your name as the custodian. For example, if you are the custodian, write ‘Jane Doe, Custodian’.
- Include the Identifier Number: Optionally, write the custodial account number beneath your signature to ensure the funds are deposited into the correct place.
Following these steps will help you endorse the document correctly, ensuring it is ready for deposit into the account with a check payable to custodian utma. Under UCC Section 3-307, banks cannot cash instruments payable to individuals under the age of majority for guardians, emphasizing the importance of proper endorsement. Imagine the frustration of having a payment denied simply because the child’s name wasn’t clearly indicated. Proper endorsement not only facilitates smooth transactions but also serves as an educational opportunity for children about banking and financial literacy. For instance, a case study highlighted that improper endorsements can result in administrative delays and potential disputes over funds, underscoring the importance of adhering to these guidelines. When you follow these endorsement practices, you’re not just protecting your child’s financial interests; you’re also fostering their understanding of money management.
Deposit the Check into the UTMA Account
Imagine the peace of mind that comes from knowing you’re securing your child’s financial future. To deposit a check payable to a custodian for a UTMA account, follow these gentle steps:
- When you visit your bank: It’s helpful to choose a branch where you feel comfortable, especially if you have an established relationship there. This can make the process smoother.
- Provide necessary documentation: Bring along any essential paperwork that confirms your custodial rights, like the statement of funds or your identification. This helps ensure everything goes smoothly.
- Present the check: Hand the endorsed check and your documentation to the bank teller. Clearly state your intention to deposit the check payable to custodian UTMA into the custodial fund, ensuring they understand your needs.
- Confirm the deposit: After the teller processes the deposit, don’t forget to request a receipt. This is crucial for your records and gives you peace of mind.
- Monitor the fund: Keep an eye on the custodial fund to ensure that the deposit is accurately reflected. If you notice any discrepancies, reach out to the bank right away.
Depositing funds into UTMA accounts is similar to regular payments, making it easier to understand. Typically, the first $275 of a deposit should be accessible by the next business day, while the rest may take one to five business days to process, depending on factors like the amount deposited and the bank’s policies. By following these steps, you’re not just making a deposit; you’re laying the groundwork for a secure future for your child. At Bright Advisers, we understand how important these financial strategies are in empowering families like Jay & Emma, Emily & Mark, and Allison & Brian to achieve their long-term goals. Our tailored wealth management solutions focus on personalized planning and tax optimization, ensuring that your family’s financial security and educational readiness are prioritized. With each deposit, you’re building a brighter tomorrow for your child, and we’re here to support you every step of the way.
Troubleshoot Common Issues with UTMA Checks
Navigating the world of UTMA transactions can feel overwhelming for parents, especially when unexpected challenges arise. Here are some effective solutions to help you troubleshoot these common issues:
- Check Endorsement Rejections: Imagine the frustration of having a check rejected because of a simple mistake in endorsement. Make sure the minor’s name is printed correctly and that you’ve signed as the custodian. Using blue or black ink can enhance clarity.
- Documentation Issues: If the bank asks for more paperwork, it can feel daunting. Be prepared to provide proof of your custodial rights, like a statement or ID that confirms your role. Keeping clear records can make transactions smoother.
- Deposit Delays: When deposits take longer than expected, it can be stressful. Reach out to the bank to check on the status. Larger checks might need extra verification, which can extend processing times. Typically, banks wait 7 to 10 days for checks to clear before allowing withdrawals.
- Access Issues: If you find yourself struggling to access your UTMA account online, double-check your login credentials. If problems persist, don’t hesitate to contact customer service for help.
- Funds Not Reflected: If you’re worried because your deposited funds haven’t shown up yet, follow up with the bank to ensure the deposit was processed correctly. It’s wise to keep the paper receipt until the transaction clears to avoid complications.
By recognizing these challenges and knowing how to tackle them, you can navigate the process of handling a check payable to custodian UTMA more effectively, ensuring your child’s financial future remains secure. In 2024, you can take advantage of tax-free income up to $2,600 each year for your child, making it even more important to manage these accounts wisely.
Conclusion
Managing checks for your child’s UTMA account can feel overwhelming, but it’s a crucial step in securing their financial future. When you know how to endorse and deposit these checks, you can manage your child’s investments with confidence. Learning these steps not only helps you but also teaches your kids about money management.
Let’s break down the key points:
- Endorse checks correctly
- Gather the right documents
- Know how to troubleshoot any issues that come up
Every little step, like flipping the check and showing ID, helps make banking easier for you and your child. Following these tips can help you avoid delays and feel more confident in managing your child’s account.
For families in Southern California, knowing how to manage UTMA accounts is becoming more important than ever. By adopting these practices, you’re not just securing a better future for your kids; you’re teaching them important lessons about money. If you want to improve your financial strategies, Bright Advisers is here to help with personalized solutions that put your family first.
Frequently Asked Questions
What is a UTMA account?
A UTMA (Uniform Transfers to Minors Act) account is a custodial arrangement that allows parents to transfer assets like cash, stocks, or securities to their child without setting up a formal trust. A custodian manages these funds until the child reaches adulthood, typically between 18 and 21 years old, depending on the state.
What are the benefits of UTMA accounts?
UTMA accounts offer tax benefits, as earnings are usually taxed at the child’s lower tax rate, enhancing overall savings potential. They provide flexibility in managing assets and a straightforward way to gift funds to minors, ensuring the money is used for their benefit.
How long does custodianship last for UTMA accounts?
Custodianship for UTMA accounts typically lasts until the child reaches adulthood, which is usually between 18 and 21 years old. In some states, custodianship can extend until the child turns 25.
What types of investments can be included in a UTMA account?
A UTMA account can include a mix of investments such as stocks, bonds, and mutual funds, allowing for potential investment growth that benefits the child when they take control of the funds.
What is the minimum investment required for UTMA accounts?
The minimum investment required for both UGMA and custodial funds is just $1,000, making these options accessible for parents looking to invest in their children’s futures.
How does Bright Advisers assist with UTMA accounts?
Bright Advisers offers innovative strategies to enhance the benefits of custodial funds through personalized investment portfolios. They leverage advanced technology to create tailored financial plans that align with families’ unique goals.
What is Bright Advisers’ approach to fiduciary duty and transparency?
Bright Advisers prioritizes fiduciary duty and transparency by ensuring there are no hidden fees or conflicts of interest, which is essential for families making significant financial decisions.
How can I get started with Bright Advisers for managing custodial funds?
Interested individuals can take the first step by joining the client waitlist to learn more about how Bright Advisers can assist in managing custodial funds and other wealth management strategies.
List of Sources
- Understand UTMA Accounts and Their Purpose
- Custodial Accounts | T. Rowe Price (https://troweprice.com/personal-investing/accounts/general-investing/ugma-utma.html)
- Are UTMA Accounts a Good Idea for your Minor Children? (https://vjrussolaw.com/are-utma-accounts-a-good-idea-for-your-minor-children)
- Understanding UTMA Accounts: A Guide for Parents and Guardians | Ruth Cantu, CPA (https://linkedin.com/pulse/understanding-utma-accounts-guide-parents-guardians-ruth-1ytpc)
- Endorse the Check Correctly
- justanswer.com (https://justanswer.com/family-law/3g373-redemtion-checks-kids-utma-account-payable.html)
- Endorsing a check for a minor — Grokipedia (https://grokipedia.com/page/Endorsing_a_check_for_a_minor)
- Guide to Endorsing a Check for a Minor | SoFi (https://sofi.com/learn/content/how-to-endorse-a-check-for-a-minor)
- Deposit the Check into the UTMA Account
- I deposited a check. When will my funds be available? (https://helpwithmybank.gov/help-topics/bank-accounts/funds-availability/funds-availability-check.html)
- How long does it take a check to deposit? (https://creditkarma.com/money/i/how-long-does-it-take-check-deposit)
- How Long Does It Take for a Check to Clear? What You Need to Know (https://mybanktracker.com/news/long-takes-check-clear-top-10-banks)
- Why It Can Take Up to Five Days for a Check to Clear (https://usnews.com/banking/articles/how-long-does-it-take-a-check-to-clear)
- Troubleshoot Common Issues with UTMA Checks
- justanswer.com (https://justanswer.com/family-law/3g373-redemtion-checks-kids-utma-account-payable.html)
- UTMAs – The Benefits & Challenges of Child Custodial Accounts | Gelt Guide | Helping Frum Families Live $marter (https://geltguide.com/utmas-the-benefits-challenges-of-child-custodial-accounts)
- How to Endorse a Check for Mobile Deposit | Step-by-Step Guide (https://axosbank.com/personal/insights/finance/digital-banking/what-to-write-on-back-of-check-for-mobile-deposit)
- UTMA Accounts Could Cause Problems for SSI Beneficiaries (https://specialneedsanswers.com/utma-accounts-could-cause-problems-for-ssi-beneficiaries-13989)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading