

Key Highlights
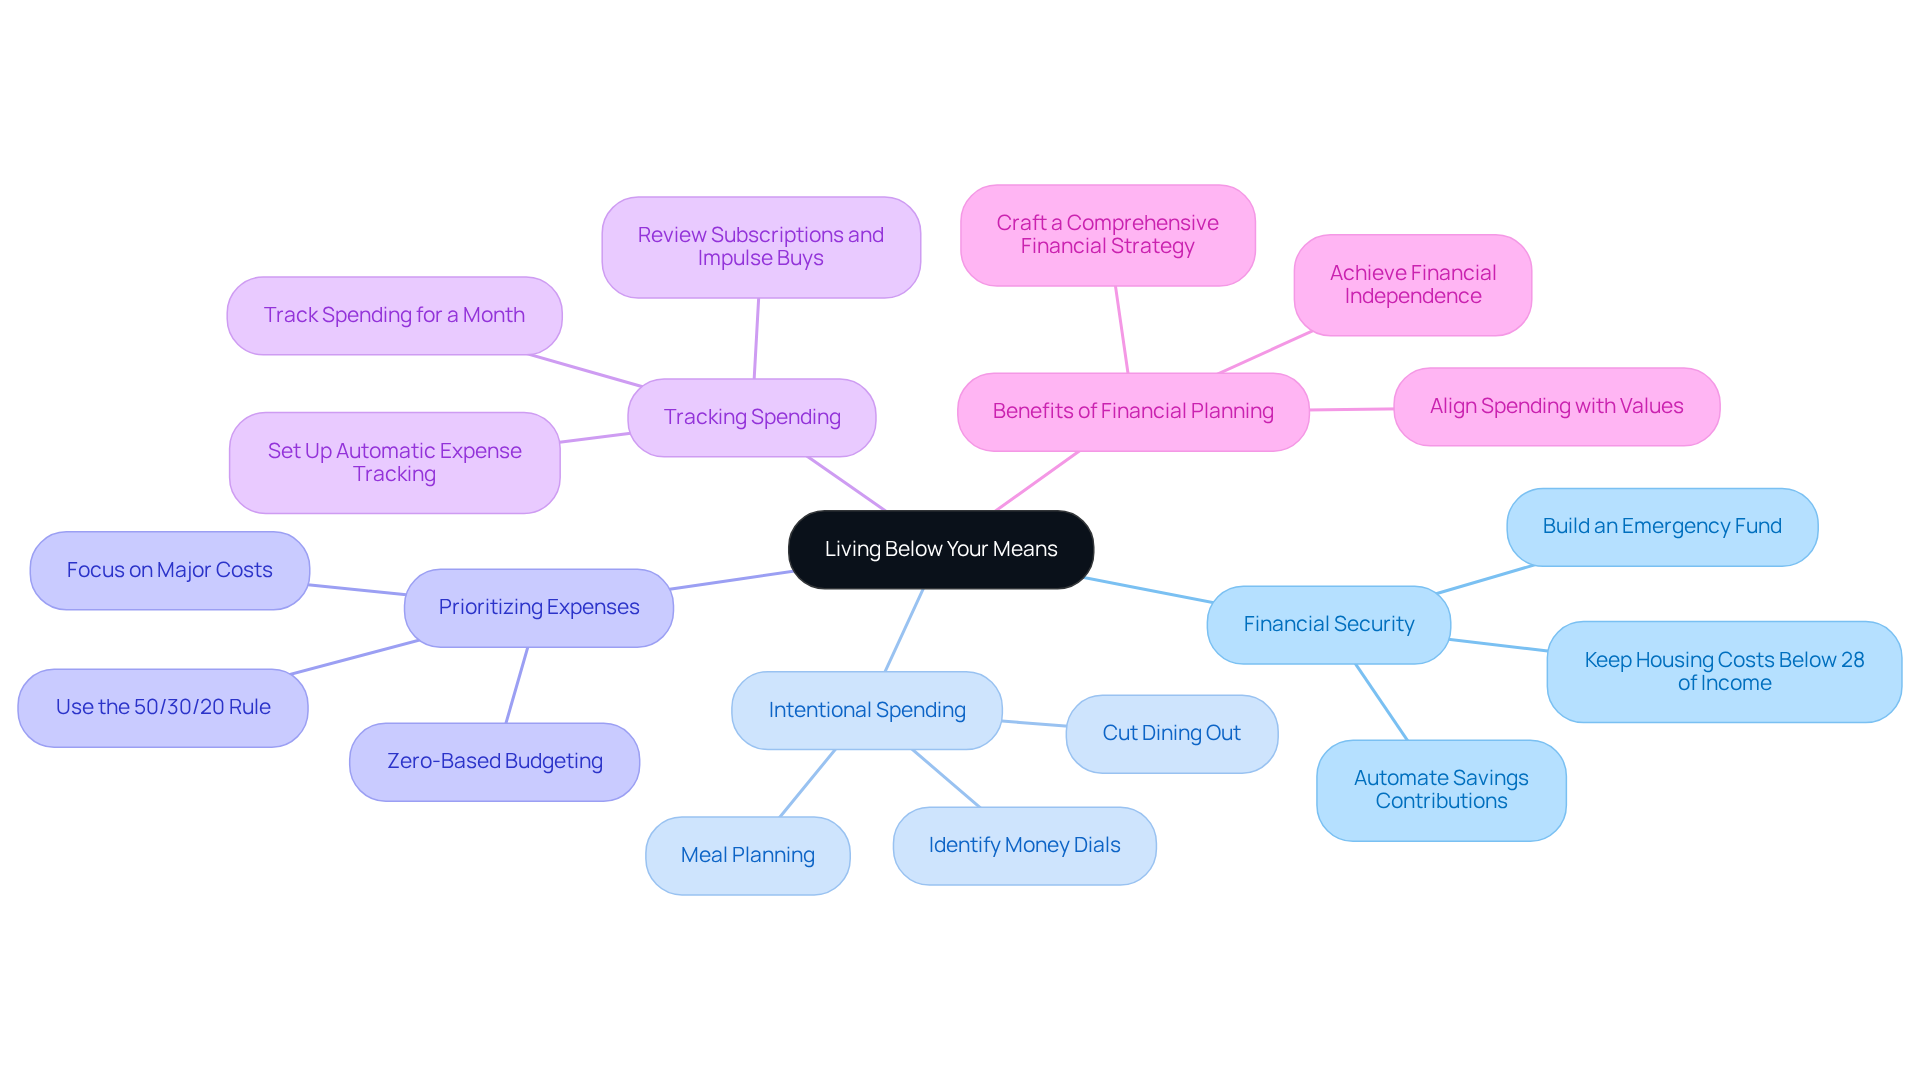
- Living below your means involves consistently spending less than you earn, prioritising essential expenses to create a financial safety net.
- This approach is crucial for young families, helping them save for future needs like education and emergencies.
- Simple changes, such as reducing dining out or meal planning, can lead to significant savings over time.
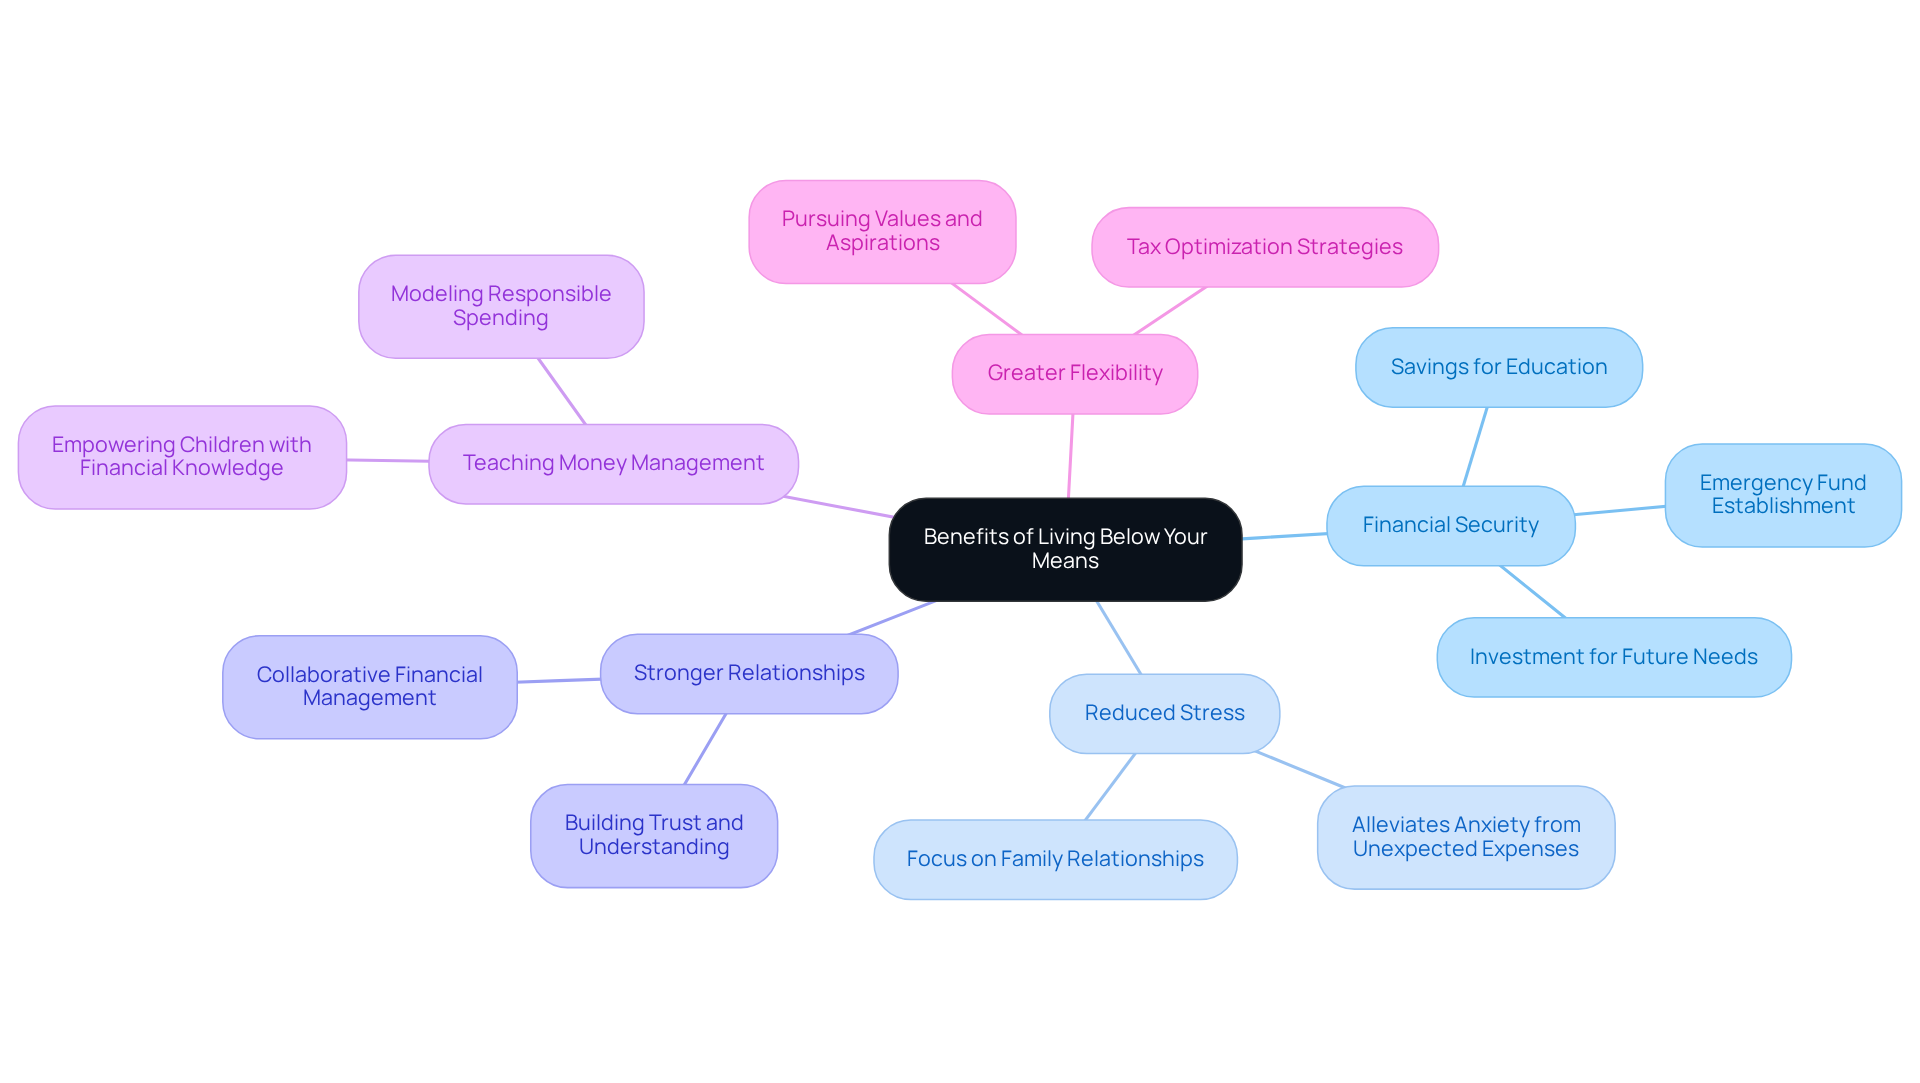
- Benefits of living below your means include financial security, reduced stress, stronger relationships, teaching money management to children, and greater flexibility in financial choices.
- Practical strategies to implement this lifestyle include creating a family budget, prioritising needs over wants, automating savings, involving the family in financial discussions, reducing unnecessary costs, and shopping smart.
- Challenges such as social pressure, impulse spending, and lifestyle inflation can be overcome by focusing on personal financial goals and maintaining a balanced approach to enjoyment and frugality.
- Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, offers personalised financial strategies to help families achieve their financial goals.
Introduction
Imagine a world where financial worries fade away, allowing young families to focus on what truly matters. Living beneath your means isn’t just about budgeting; it’s a way to help your family focus on what truly matters and build a strong financial foundation. Many families find it tough to navigate the pressures of spending and saving. How can you, as a young parent, embrace this lifestyle and create a brighter financial future for your little ones?
Define Living Below Your Means
Imagine feeling secure in your finances, knowing you’re making choices that support your family’s future. Living within your means means consistently spending less than you earn, which helps you save and feel more secure. For young households, this idea is crucial. It’s about prioritizing essential expenses while making thoughtful choices about what you spend on extras. It’s not just about being frugal; it’s about creating a safety net for future needs, like education and emergencies. By embracing this mindset, families can open doors to financial independence and peace of mind.
Many families have found that simple changes, like cutting back on dining out or planning meals, can lead to big savings over time. As money expert Ramit Sethi points out, understanding how to live beneath your means involves spending intentionally to align with your values, allowing for both enjoyment and security. Understanding and applying the principles of living within your means empowers families to make informed choices that support their financial goals, ultimately leading to a more secure future.
We know how challenging it can be for young families to navigate financial pressures, and we’re here to help. Take Jay and Emma, for example. They came to us feeling overwhelmed with two kids and financial stress. With our support, they crafted a comprehensive financial strategy that included smart tax planning and personalized advice, helping them balance their current needs with their long-term dreams.
To understand how to live beneath your means, consider tracking your spending for a month. This can help you spot areas for improvement, like cutting unnecessary expenses or prioritizing savings. This proactive approach can foster a more secure future for your loved ones. Together with Bright Advisers, families like Emily and Mark have gained the freedom to make career choices that fit their desired work-life balance, while Allison and Brian have maximized their financial potential through effective tax planning. With our support, you can create a financial plan that not only meets your needs today but also nurtures your family’s dreams for tomorrow.
Explore the Benefits of Living Below Your Means
Imagine the relief of knowing your family’s financial future is secure, even when life throws unexpected challenges your way. Living below your means presents a multitude of advantages, particularly for young families:
- Financial Security: Did you know that families with an adult over 65 typically need about $108,500 to feel financially secure? This shows just how important budgeting can be. Spending less than you earn enables the establishment of an emergency fund, savings for your children’s education, and investments for future needs. Bright Advisers provides comprehensive tax planning and investment strategies to assist households like Emily and Mark in establishing a strong economic base.
- Reduced Stress: Imagine the stress of unexpected bills piling up, leaving you worried about your family’s future. Having a monetary buffer alleviates anxiety related to unexpected expenses, allowing households to concentrate on nurturing relationships and enjoying quality time together. Jay and Emma experienced this firsthand as they navigated funding their children’s education while planning for retirement, achieving a balance between present responsibilities and long-term aspirations. This peace of mind allows you to focus on what truly matters-your family.
- Stronger Relationships: When couples work together on their finances, it’s not just about numbers; it’s about building trust and understanding each other’s dreams. Collaborating as a couple to manage finances enhances teamwork and communication, which can fortify family bonds. This collaborative method promotes a mutual comprehension of monetary objectives and duties, as demonstrated in the partnership between Emily and Mark with Bright Advisers.
- Teaching Money Management: By modeling responsible spending habits, parents can instill valuable lessons in their children, promoting their future money literacy. Engaging with Bright Advisers empowers households to make informed decisions that they can pass on to their children, ensuring a legacy of financial wisdom.
- Greater Flexibility: Reduced costs offer households the freedom to pursue options that align with their values and aspirations, such as travel or extracurricular activities. The strategies executed by Bright Advisers, including tax optimization and tailored retirement planning, offer households the flexibility to prioritize what matters most to them.
With the right support, you can create a legacy of financial wisdom for your children, ensuring they thrive in their future. By learning how to live beneath your means, young families can attain economic well-being and the liberty to make work optional, just as Emily, Mark, Jay, and Emma accomplished with the support of Bright Advisers, established by Kevin Luu and Kathleen Chou in 2010.
Implement Practical Strategies to Live Below Your Means
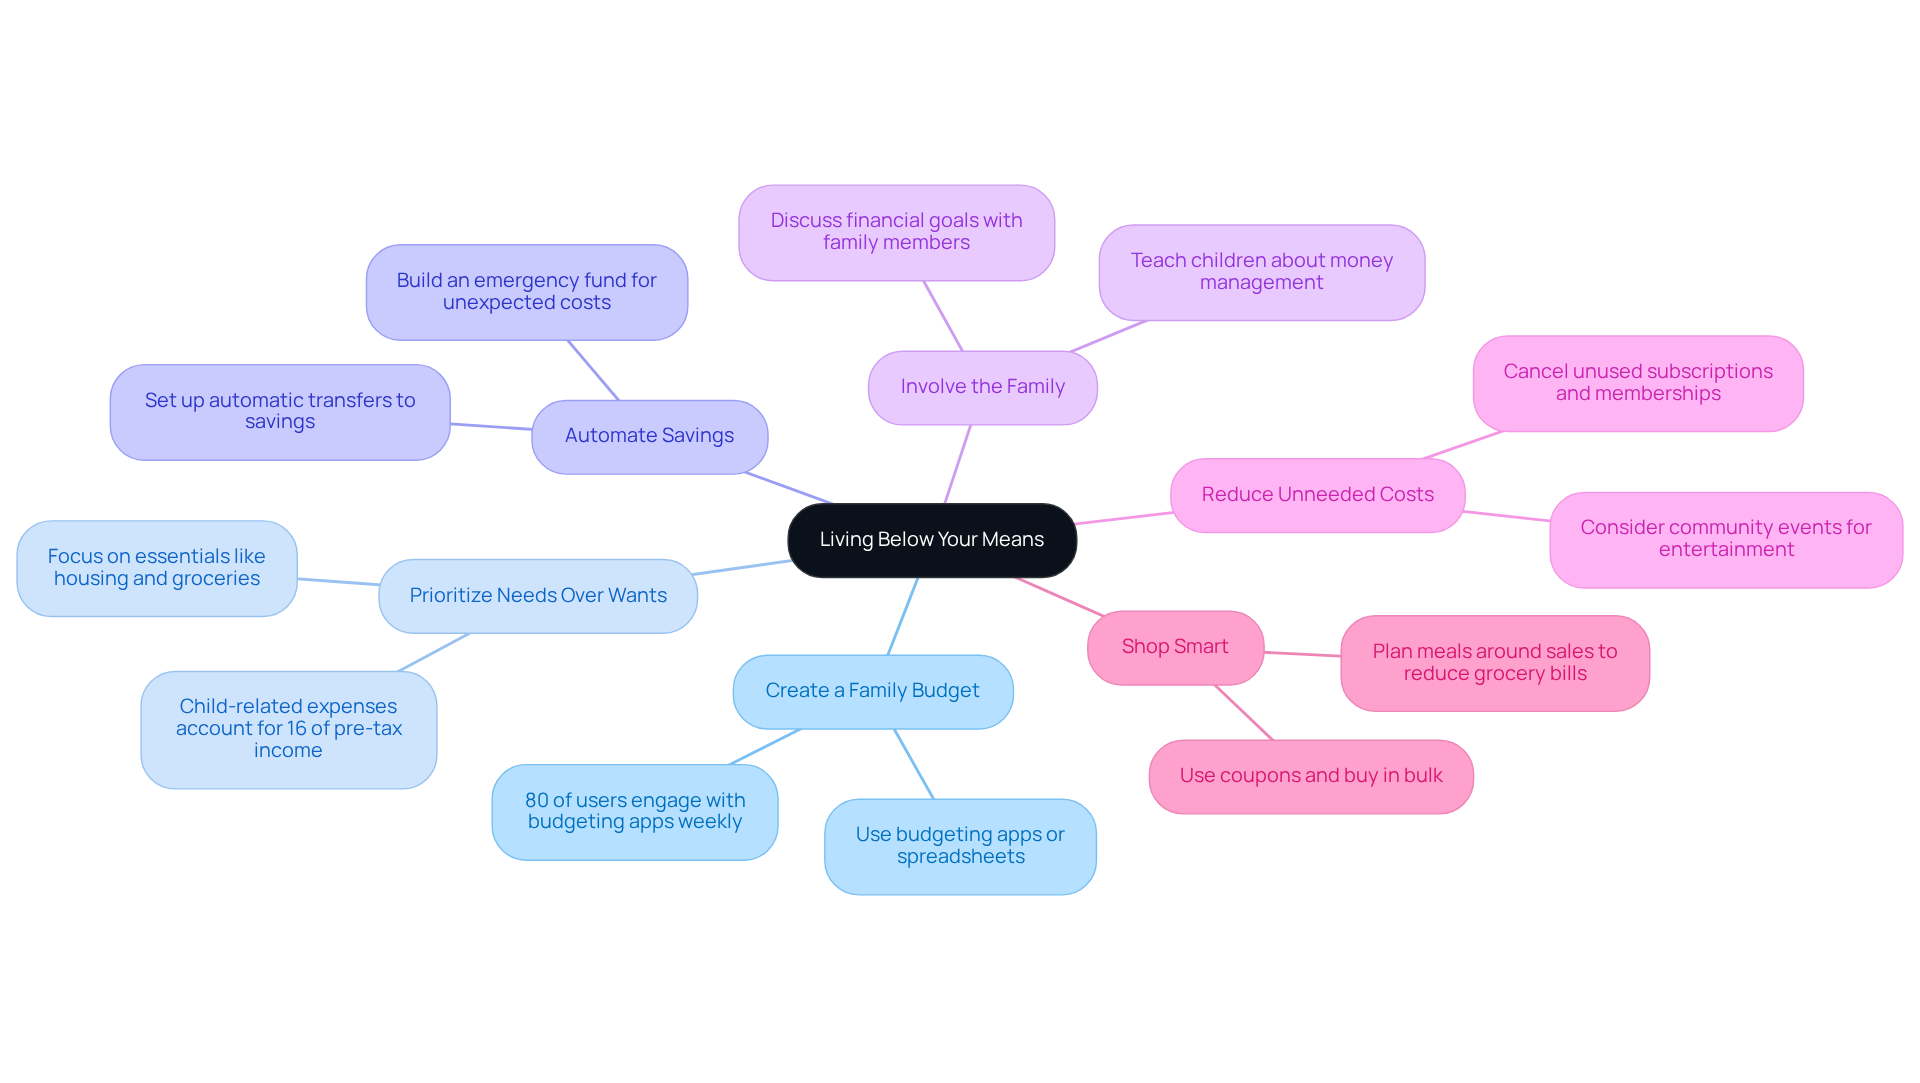
Imagine the relief of knowing your family is financially secure, even in uncertain times. To successfully live below your means, consider these practical strategies:
- Create a Family Budget: Using budgeting apps or even a simple spreadsheet can really help you see where your money is going each month. Nearly 80% of users engage with budgeting apps weekly, making them a valuable tool for financial management.
- Prioritize Needs Over Wants: It’s essential to differentiate between what you need – like housing and groceries – and what you want, such as dining out or entertainment. Focus on meeting your family’s needs first, especially since child-related expenses can take up about 16% of a middle-income household’s pre-tax income.
- Automate Savings: Set up automatic transfers to your savings account each month; think of it as paying yourself first. This approach can help you build an emergency fund, which is so important for those unexpected costs, like job loss or medical bills.
- Involve the Family: Talk about your financial goals with your partner and even your kids; it’s a great way to teach them about money. Involving them in budgeting decisions fosters a sense of responsibility and teamwork, which can be beneficial as they grow.
- Reduce Unneeded Costs: Take a close look at your subscriptions and memberships. Cancel those that don’t enhance your household’s life. Instead, consider community events for entertainment, which can provide enjoyable experiences without the associated costs.
- Shop Smart: Use coupons, buy in bulk, and take advantage of sales. Planning meals around sales can significantly reduce grocery bills, as food accounts for 18% of total child-rearing costs for middle-income families. Additionally, shopping at local markets or using bulk food purchases can help lower costs even further.
Managing finances can feel overwhelming, but these strategies can help you take control. By learning how to live beneath your means, you can create a stable financial future for your family, allowing you to focus on what truly matters – your loved ones.
Overcome Challenges in Living Below Your Means
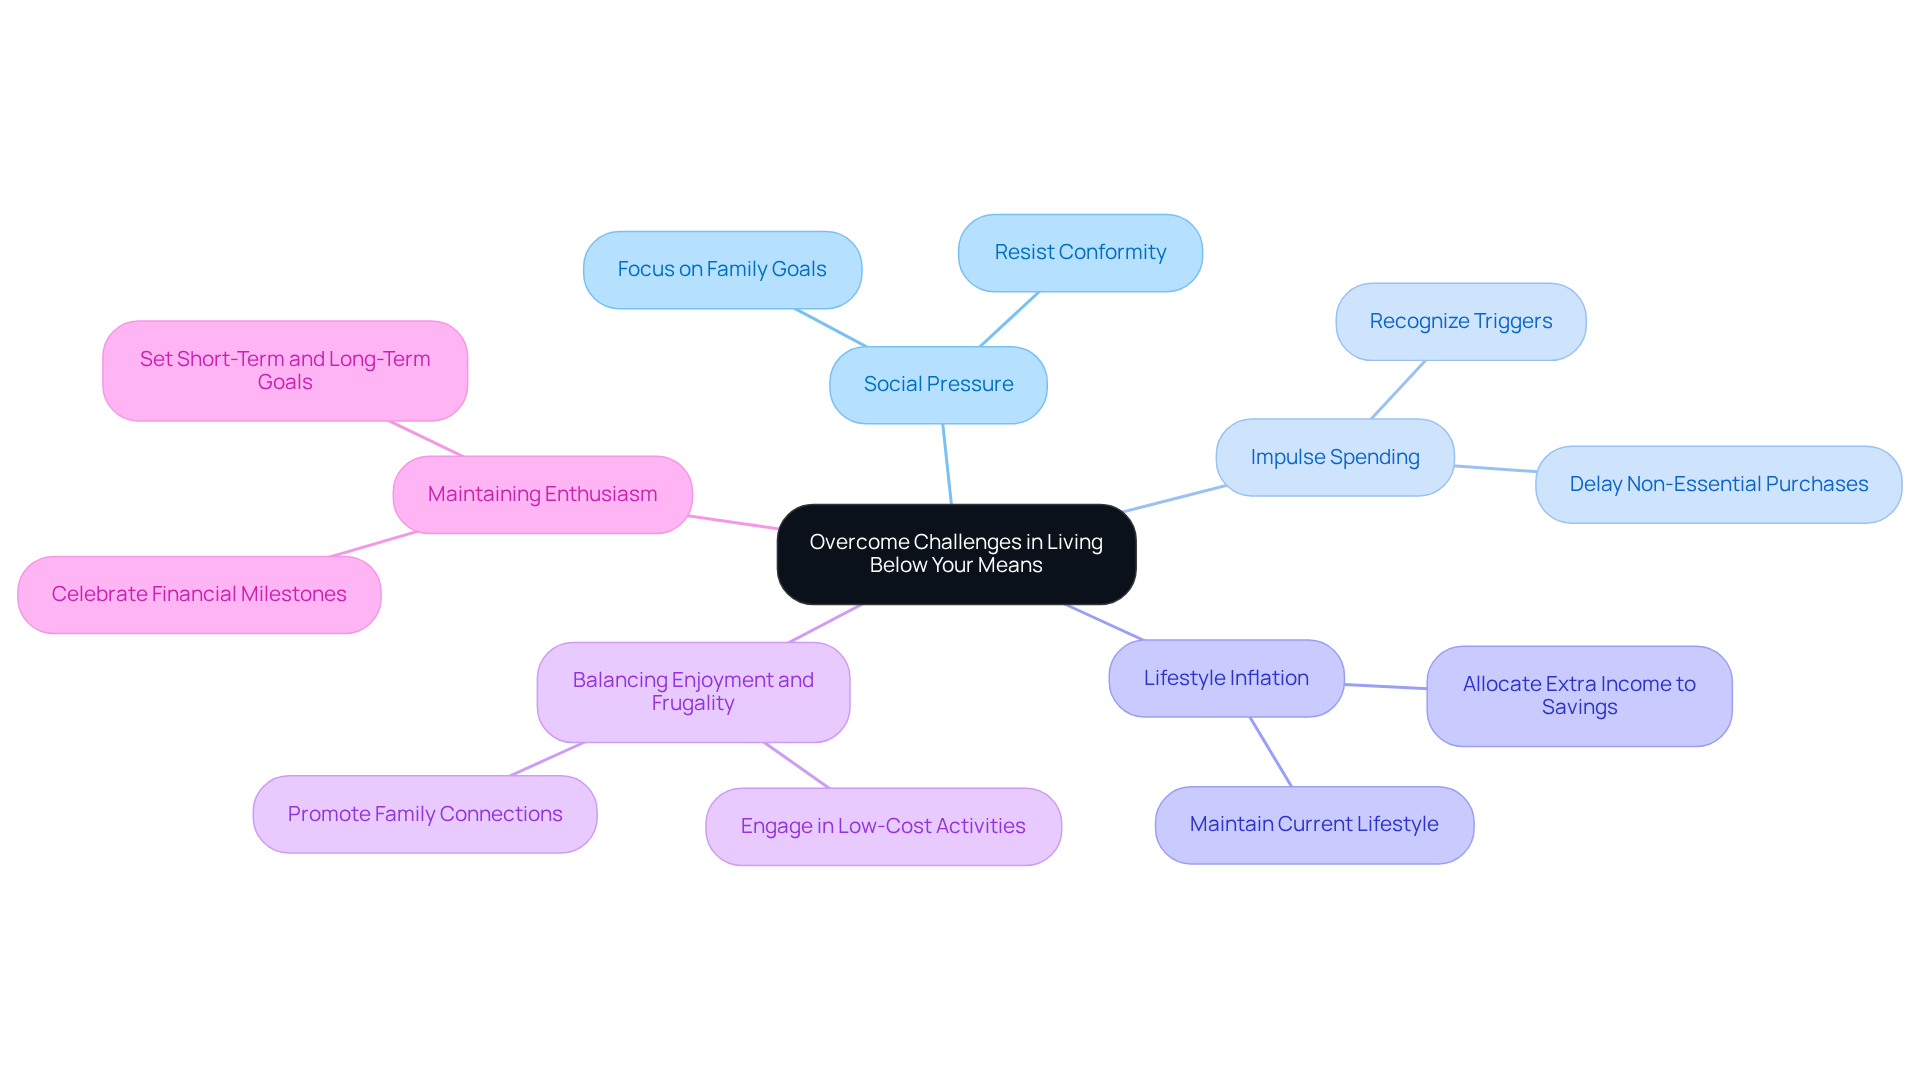
Imagine navigating the challenges of financial planning while trying to prioritize your family’s needs. While understanding how to live beneath your means is beneficial, it can come with challenges. Here’s how to overcome them:
- Social Pressure: Have you ever felt the pressure to keep up with friends or neighbors? Focus on your family’s unique goals and values, and remember that financial health is more important than appearances. Did you know that many young people often feel the urge to buy things on a whim, influenced by their friends? It’s a common challenge. Recognizing this can help you resist the urge to conform.
- Impulse Spending: Try giving yourself a little time before making those non-essential purchases. It can really help you decide if you truly need it. Statistics indicate that 54% of U.S. shoppers have spent $100 or more on impulse purchases, emphasizing the significance of conscious financial choices.
- Lifestyle Inflation: As your income increases, it’s tempting to increase your spending too. Instead, consider maintaining your current lifestyle and allocating that extra income towards savings or investments. This approach can help you avoid the common pitfall of lifestyle inflation, which can derail long-term financial stability.
- Balancing enjoyment and frugality is about knowing how to live beneath your means without sacrificing fun. Find low-cost or free activities that your loved ones enjoy, such as hiking, picnics, or community events. Participating in these activities can promote connections among relatives without straining your budget.
- Maintaining Enthusiasm: Establish short-term and long-term monetary objectives to keep your household inspired. Celebrate milestones, such as reaching a savings target or paying off debt, to reinforce positive behaviors. Imagine how much more fulfilling your family’s life could be when you focus on what truly matters, rather than what others think. Case studies reveal that families who set clear financial goals are more likely to succeed in maintaining their budget and achieving financial independence.
Conclusion
Imagine a life where financial worries take a backseat, allowing you to focus on what truly matters to your family. Living beneath your means helps your family feel secure today and tomorrow. By prioritizing essential expenses and making intentional spending choices, you can cultivate a sense of financial security that allows your family to thrive. This mindset fosters not only peace of mind but also the ability to invest in what truly matters – education, experiences, and quality time together.
Throughout this guide, we’ve shared practical strategies to help families navigate the complexities of budgeting and financial management. Many families feel overwhelmed by budgeting and financial management. From creating a family budget and automating savings to involving the entire family in financial discussions, these actionable steps can lead to significant improvements in financial well-being. Plus, the benefits of living below your means, such as reduced stress and stronger family relationships, highlight the holistic advantages of this lifestyle choice.
When you embrace living beneath your means, you’re not just making a choice for today; you’re building a legacy of financial wisdom for your children. By taking control of finances today, families can enjoy greater flexibility and freedom, allowing them to focus on what truly enriches their lives. For those seeking personalized guidance, Bright Advisers stands ready to assist in crafting a financial plan that aligns with your family’s unique goals and values. Reach out today to begin your journey toward intentional wealth management and a brighter financial future.
Frequently Asked Questions
What does it mean to live below your means?
Living below your means means consistently spending less than you earn, prioritizing essential expenses, and making thoughtful choices about discretionary spending to create a financial safety net for future needs.
Why is living below your means important for families?
It helps families save money, feel more secure, and opens doors to financial independence and peace of mind, especially for young households facing financial pressures.
How can families start living below their means?
Families can begin by tracking their spending for a month to identify areas for improvement, such as cutting unnecessary expenses or prioritizing savings.
What are some practical changes families can make to save money?
Simple changes like cutting back on dining out or planning meals can lead to significant savings over time.
How does living below your means align with personal values?
Spending intentionally to align with your values allows for both enjoyment and security, enabling families to make informed choices that support their financial goals.
Can you provide an example of how financial planning can help families?
For instance, Jay and Emma, overwhelmed with financial stress, crafted a comprehensive financial strategy with support, which included smart tax planning and personalized advice to balance their current needs with long-term dreams.
What role does Bright Advisers play in helping families with financial planning?
Bright Advisers helps families create financial plans that meet their current needs while nurturing their dreams for the future, providing support in areas like tax planning and personalized financial advice.
List of Sources
- Define Living Below Your Means
- How to Live Below Your Means Without Feeling Deprived (https://moneyfit.org/live-below-your-means)
- 8 Steps To Live Below Your Means, According to Frugal Living Expert Austin Williams (https://finance.yahoo.com/news/8-steps-live-below-means-180010243.html)
- Living Below Your Means: How to Spend Less and Live More – I Will Teach You To Be Rich (https://iwillteachyoutoberich.com/living-below-your-means)
- 40 Financial Freedom Quotes for Success | SUCCESS (https://success.com/10-meaningful-quotes-about-achieving-financial-freedom)
- The Joy of Living Within Your Means (https://becomingminimalist.com/live-within-means)
- Explore the Benefits of Living Below Your Means
- 31 Motivational Quotes to Drive Financial Success | Don Connelly & Associates (https://donconnelly.com/31-motivational-quotes-drive-financial-success)
- Nearly Half of U.S. Families Can’t Afford to ‘Thrive,’ Study Finds – The MortgagePoint (https://themortgagepoint.com/2026/03/18/about-half-of-u-s-families-fall-short-of-yearly-income-needed-to-thrive)
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- 40 quotes to help your child learn the value of money | GoHenry (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Overall (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-overall-financial-well-being.htm)
- Implement Practical Strategies to Live Below Your Means
- Why Budgeting Apps Are Gaining Popularity | Blog | Academy Bank (https://academybank.com/article/why-budgeting-apps-are-gaining-popularity-in-personal-finance)
- This Is How Much It Costs to Raise a Child in 2025 (https://money.usnews.com/money/personal-finance/articles/how-much-does-it-cost-to-raise-a-child)
- The Cost of Raising a Child (https://usda.gov/about-usda/news/blog/cost-raising-child)
- Family Budget Fact sheet (https://epi.org/resources/budget/budget-factsheets)
- How Much Does it Cost to Raise a Child? (https://northwesternmutual.com/life-and-money/how-much-does-it-cost-to-raise-a-child)
- Overcome Challenges in Living Below Your Means
- The State of Impulse Buying (Statistics & Trends 2025) – Invesp (https://invespcro.com/blog/impulse-buying)
- 55+ Impulse Buying Statistics 2026 (https://webtribunal.net/blog/impulse-buying-statistics)
- Impulse Buying Statistics (2026): Consumer Spending Habits (https://capitaloneshopping.com/research/impulse-buying-statistics)
- 150+ Impulse Buying Stats | Verified & Sourced 2026 (https://gitnux.org/impulse-buying-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading