

Key Highlights
- Business concentration risk refers to the financial vulnerability that arises when a family relies heavily on a single source of income.
- Families in Southern California often face concentration risk due to investments in local businesses or real estate.
- Key areas to assess for concentration risk include revenue sources, investment portfolios, supplier relationships, and geographic concentration.
- Diversification of income sources and investments is crucial for mitigating concentration risk and ensuring financial stability.
- Families should regularly reassess their financial situation and risk exposure to adapt to changing circumstances.
- Bright Advisers emphasises fiduciary duty, transparency, and personalised wealth management strategies to help families navigate concentration risks.
- Engaging with advisors and utilising technology can enhance monitoring and management of concentration risks.
- Educating family members about financial management and concentration risk fosters responsibility and awareness.
Introduction
Imagine the worry that comes when your family’s financial future relies on just one income source. For families in Southern California, relying on one income source – like a local business or real estate – can feel risky. Let’s explore how you can recognize and manage these risks together.
How can you and your family spot these risks and take steps to protect your future? By understanding and addressing these risks, families can build a more secure and resilient financial future together.
Define Concentration Risk in Business
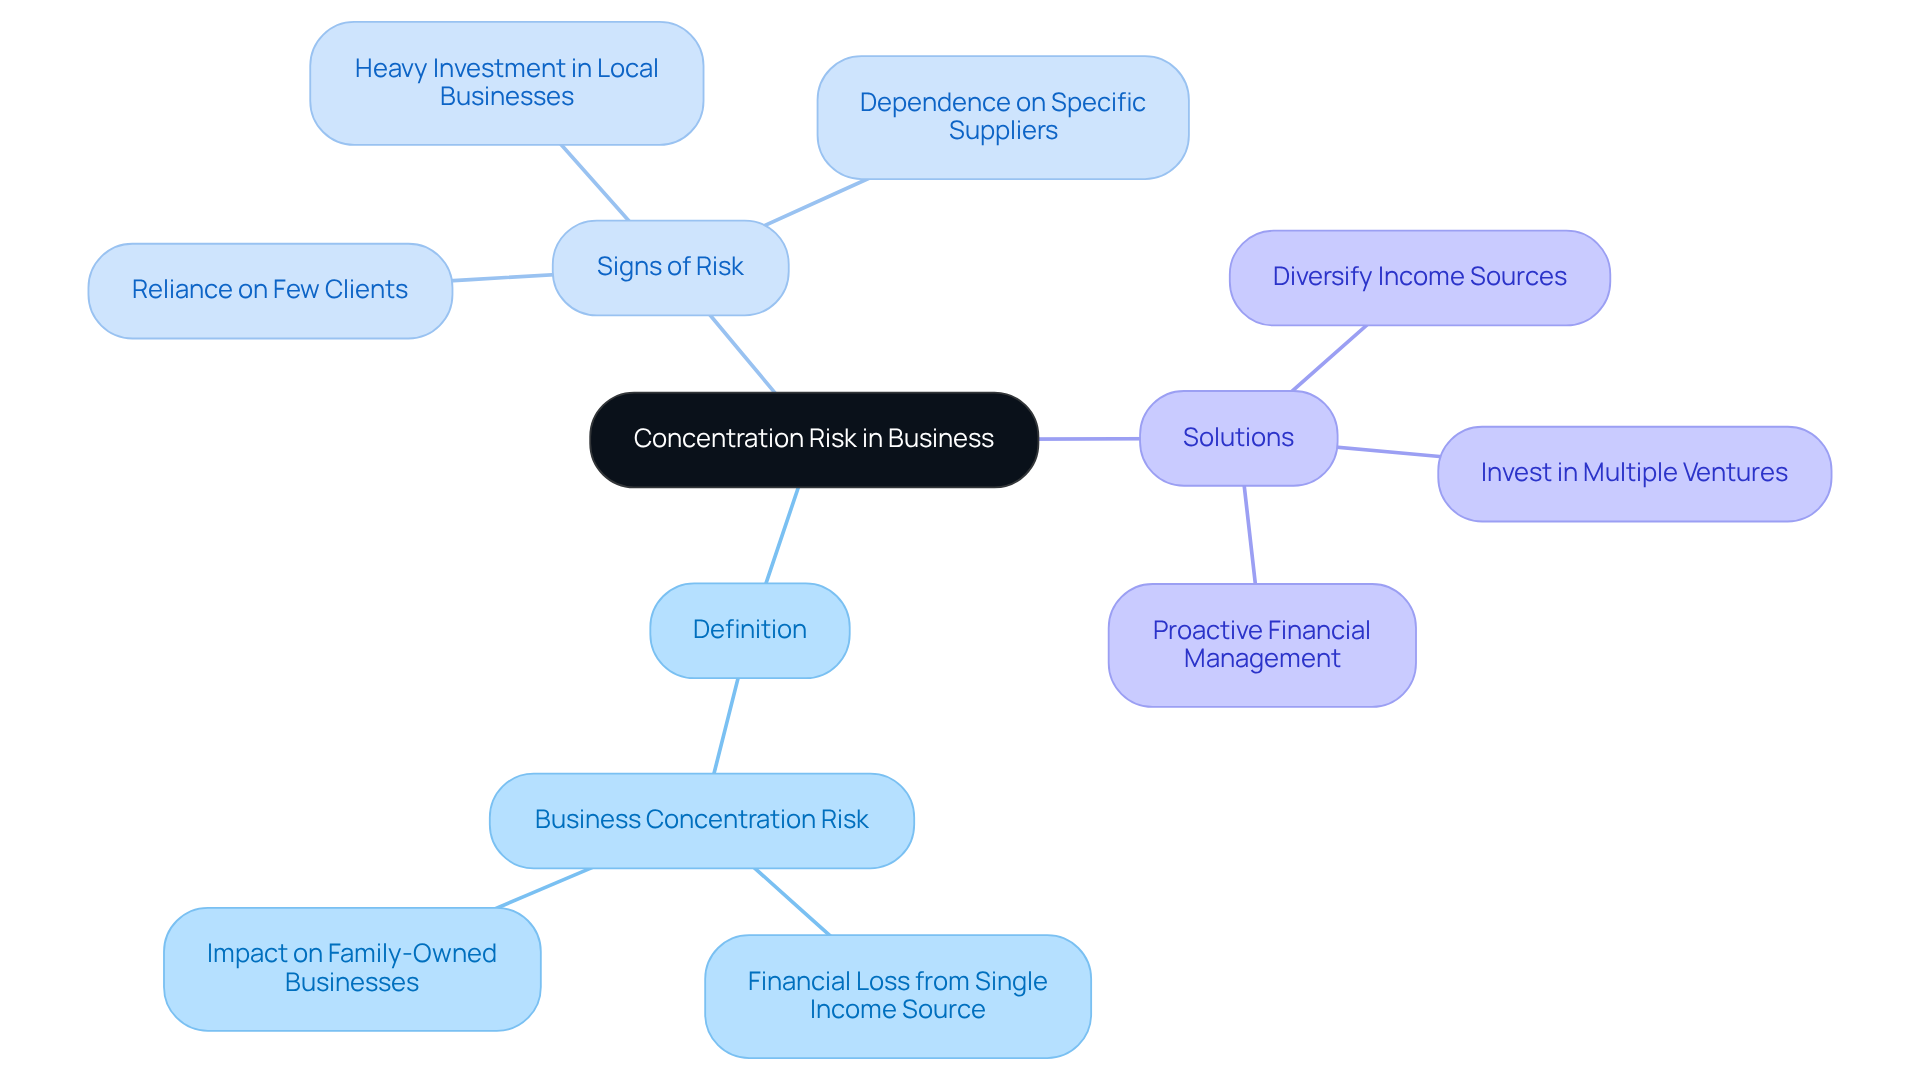
Imagine the worry that comes when your family’s financial security hinges on a single source of income. Business concentration risk indicates that if your family relies too much on one source of income, you could face financial loss. This risk can feel even more daunting when it involves businesses owned by relatives, where your family’s well-being is closely tied to their success.
In Southern California, many families face this challenge, especially those who have invested heavily in local businesses or real estate. It’s important to recognize signs of business concentration risk, such as relying too heavily on just a few clients or suppliers, to protect your family.
Taking proactive steps to diversify your income sources and investments can help shield your family from unexpected financial challenges. Imagine the peace of mind that comes from knowing your family’s future is secure, no matter what happens. Taking steps to diversify your income can be the key to safeguarding your family’s future.
Identify Areas of Concentration Risk
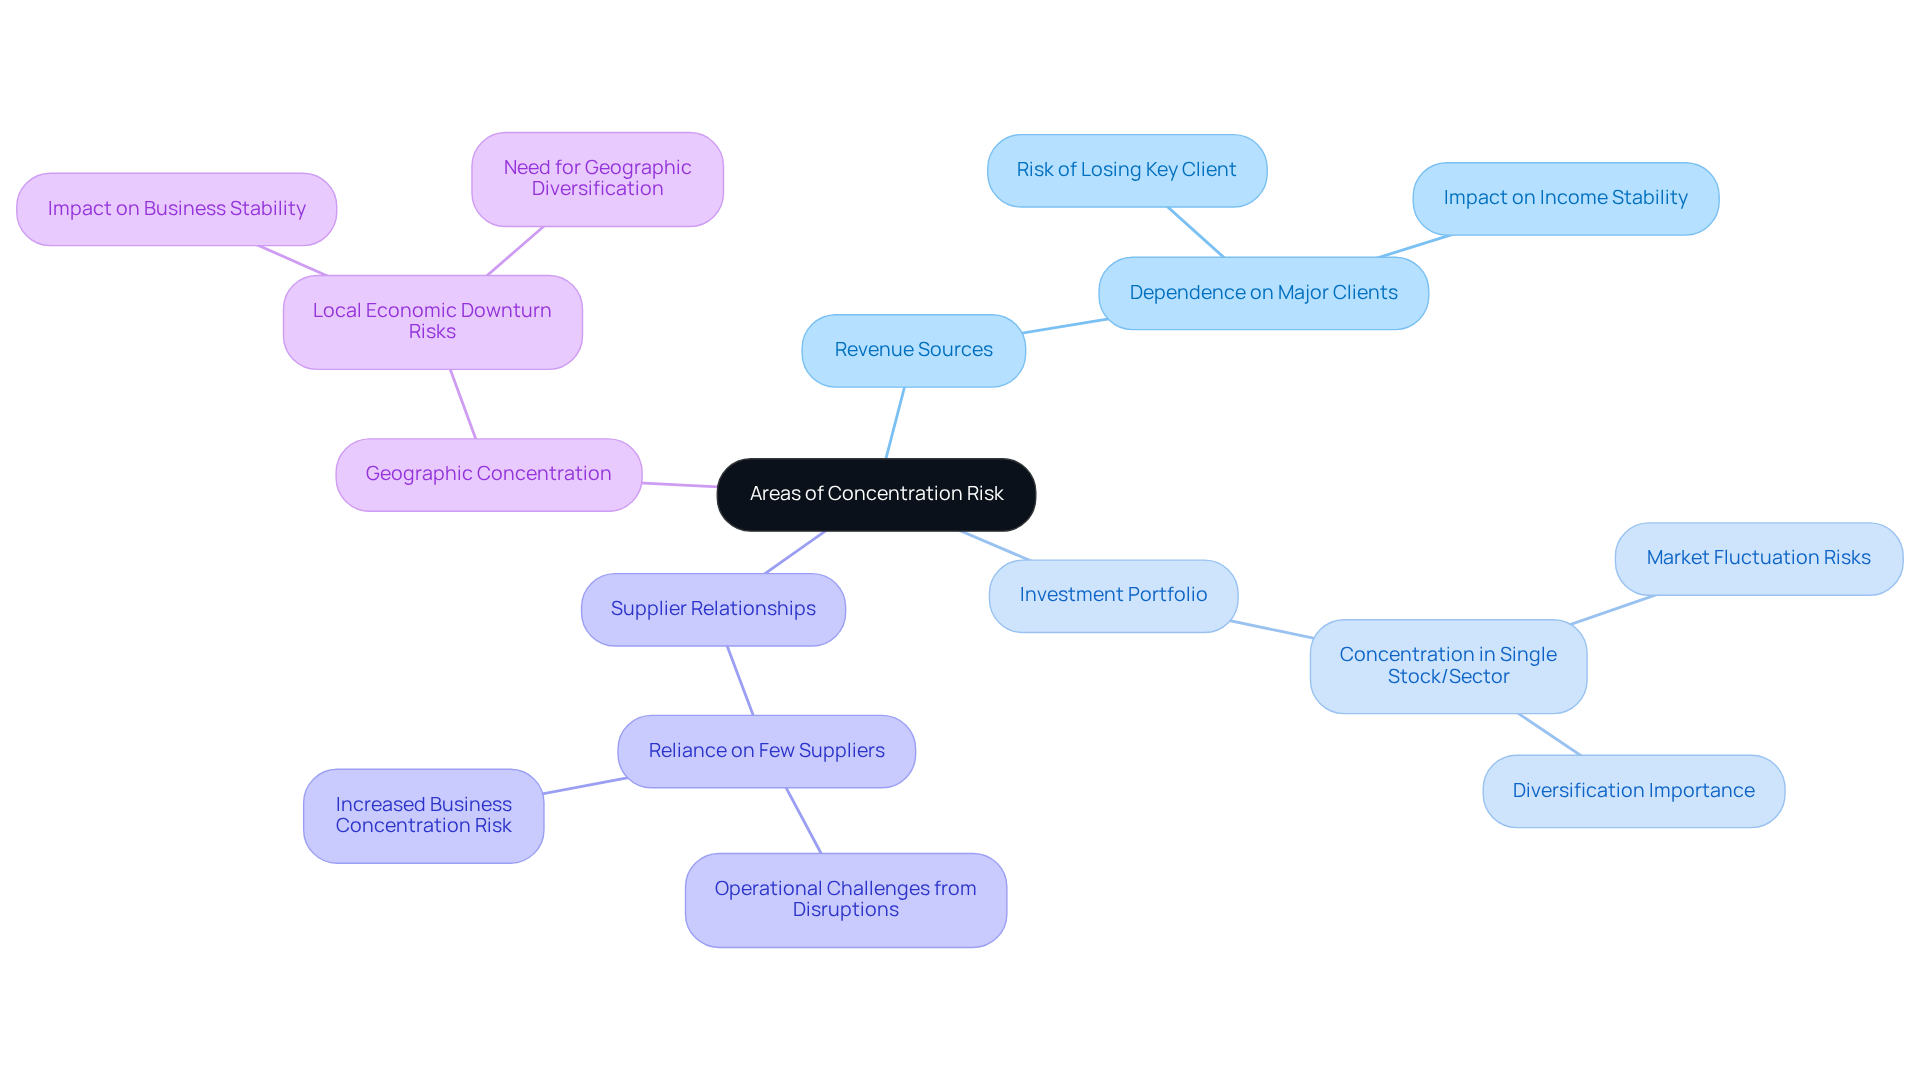
Imagine the worry that creeps in when you realize your family’s financial future hinges on a few key sources of income, highlighting the business concentration risk involved. To effectively manage concentration challenges, families must first identify where their vulnerabilities lie. Here are some key areas to assess:
-
Revenue Sources: Take a moment to think about whether a big chunk of your income relies on just one client or customer. For instance, if your company is exposed to business concentration risk by depending on a single major client for 40% of its income, this presents a considerable threat.
-
Investment Portfolio: Consider taking a closer look at your investment holdings to see how they might be affecting your family’s financial health. If a substantial part of your portfolio is invested in one stock or sector, be aware of the business concentration risk and how market fluctuations could impact your overall wealth.
-
Supplier Relationships: Think about your supply chain and how relying on just a few suppliers might impact your family’s stability. If those suppliers encounter disruptions, it could result in operational challenges and increase business concentration risk.
-
Geographic concentration can lead to business concentration risk; if your business is primarily based in one area, like Orange County, consider how a local downturn could affect your family’s financial security.
By conducting a thorough evaluation of these areas, families can gain a clearer understanding of their business concentration risk challenges and begin to formulate strategies to address them. In Southern California, where small enterprises represent a substantial part of the economy, comprehending these challenges is essential for long-term financial well-being. For instance, small enterprises in the area hire around 7.6 million Californians, emphasizing the significance of diversifying income streams to reduce uncertainties linked to economic changes. Ignoring these challenges could lead to financial instability, which affects not just your business concentration risk but also your family’s future. By understanding and addressing these vulnerabilities, you can create a more secure future for your family, ensuring peace of mind in uncertain times.
Implement Strategies to Mitigate Concentration Risk
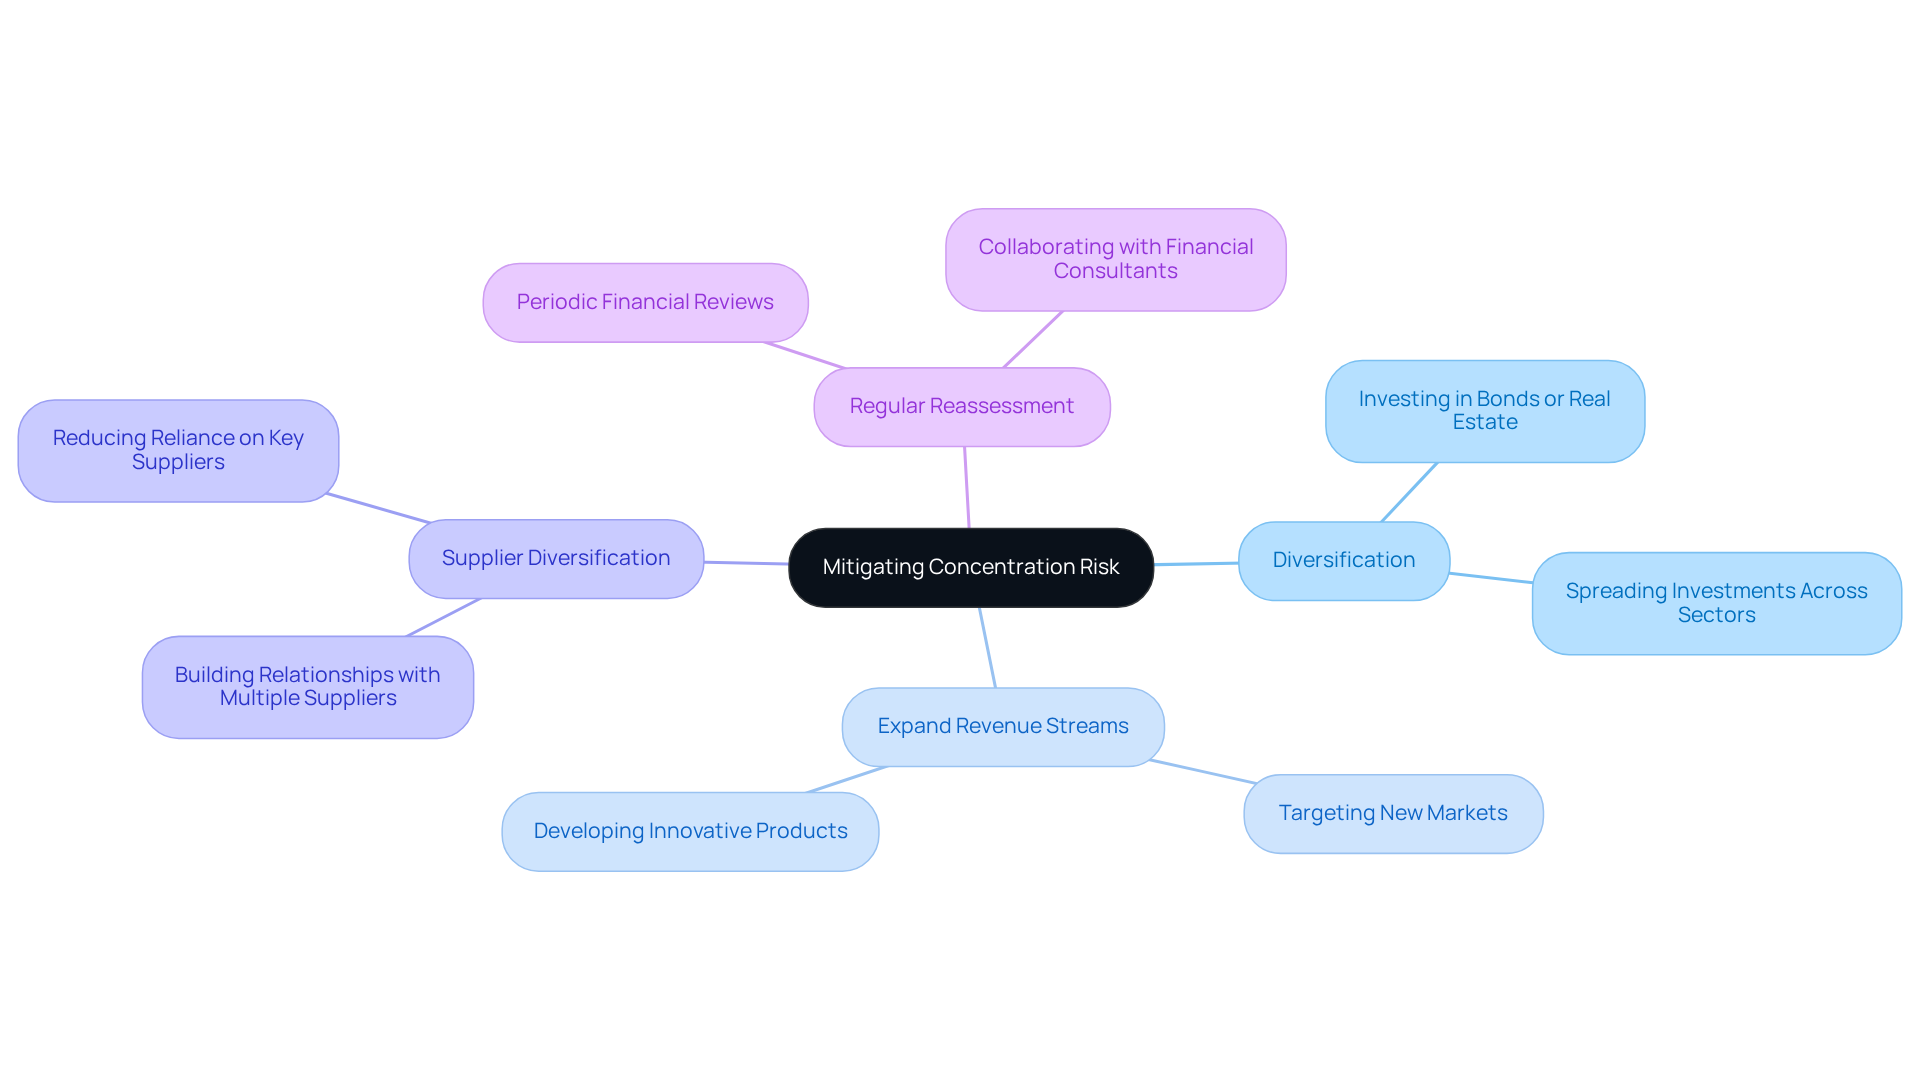
Imagine facing the uncertainty of financial risks while trying to secure your family’s future. To effectively mitigate concentration risks, families can adopt several strategic approaches:
-
Diversification: At Bright Advisers, we believe that spreading your investments is key to protecting your family’s future. By using tailored strategies, we help you create a portfolio that fits your unique needs. For instance, if your portfolio is heavily invested in technology stocks, incorporating bonds or real estate can help balance risk and enhance stability.
-
Expand Revenue Streams: If your family owns a business, diversifying your client base is essential. This might mean targeting new markets or developing innovative products, which can reduce reliance on a few key customers. Did you know that family businesses have grown from 24.2 million in 2003 to 32.4 million in 2021? This shows their resilience and the importance of diversification.
-
Supplier Diversification: Building relationships with multiple suppliers can protect you from supply chain disruptions. This way, your operations can continue smoothly, even if one supplier faces challenges.
-
Regular Reassessment: It’s not easy for families to navigate the ups and downs of the financial world. Periodically reviewing your financial situation and exposure to risks is vital. As your personal circumstances change, so should your strategies for managing business concentration risk. Collaborating with a dedicated consultant from Bright Advisers can provide valuable insights for reevaluating your portfolio and ensuring it aligns with your family’s unique financial plan.
As Pat Soldano, President of Family Enterprise USA, emphasizes, “Family businesses constitute such a large portion of ALL businesses, so how can legislators ignore them?” By actively implementing these strategies, you can ensure your family’s financial legacy endures through any challenge. Bright Advisers is here to help families make wise wealth decisions and preserve their wealth through personalized planning and transparent, all-inclusive fee structures.
Monitor and Reassess Concentration Risks
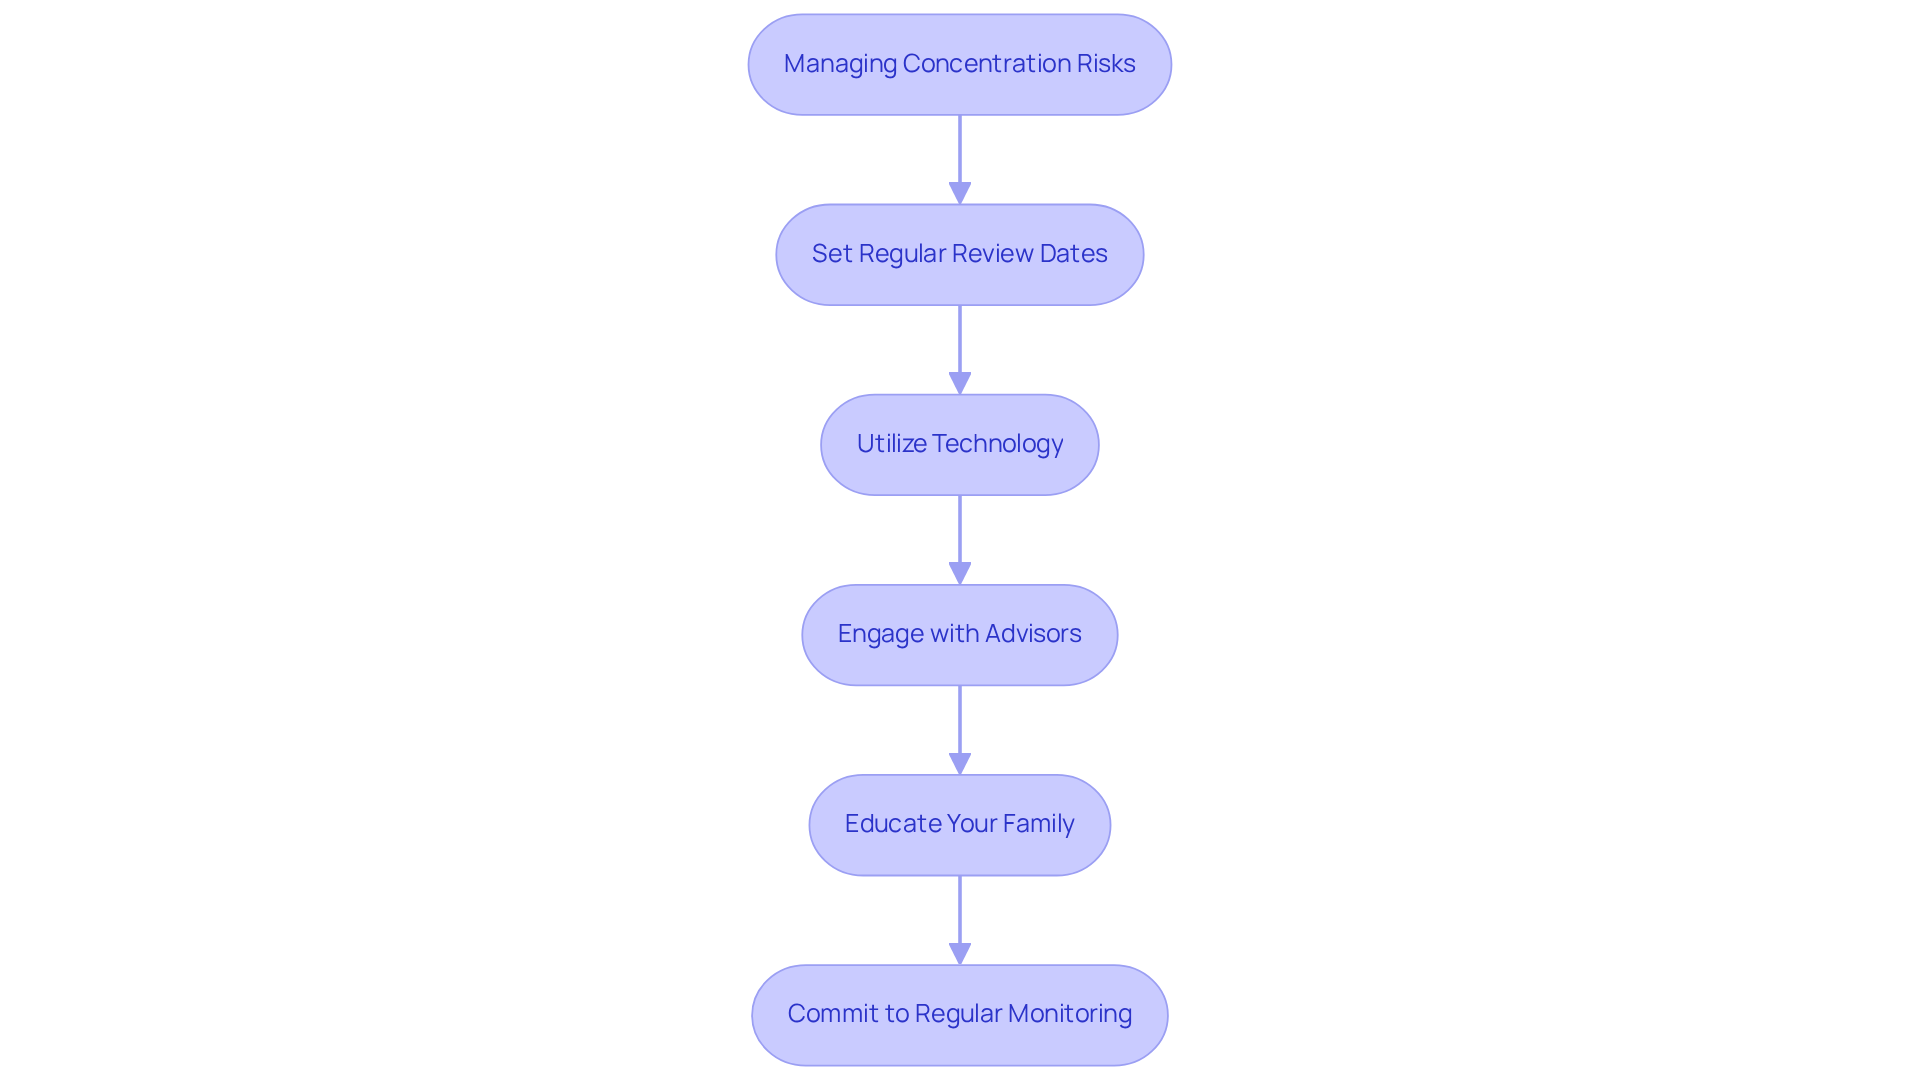
Managing business concentration risk is an ongoing journey that necessitates consistent monitoring and reassessment. Imagine facing unexpected financial challenges because you overlooked regular assessments. Families can take the following steps to effectively manage their risk exposure:
-
Set Regular Review Dates: Schedule assessments at least quarterly or biannually. This practice keeps you informed about changes in your business or investment landscape, allowing for timely adjustments.
-
Utilize Technology: Use management tools to keep an eye on your investments. Get alerts when there are big changes in your portfolio. Bright Advisers offers advanced technology that helps households track their economic well-being efficiently, featuring tools that create hyper-personalized portfolios while steering clear of costly mutual funds and ETFs.
-
Engage with Advisors: Talking regularly with advisors who get your family’s needs is really important. They can offer tailored insights and recommendations, ensuring your strategies remain aligned with your evolving needs. Bright Advisers emphasizes its fiduciary duty, ensuring no hidden fees or conflicts of interest, and offers a transparent, all-inclusive fee structure.
-
Educate Your Family: Involve your children in discussions about money management and the implications of concentration risk. Teaching them about these concepts fosters a sense of responsibility and awareness regarding business concentration risk as they grow.
Let’s consider Sarah and Tom, who faced unexpected financial challenges because they missed their annual review. After neglecting their annual evaluation, they encountered considerable economic setbacks due to market fluctuations and alterations in income. By committing to regular monitoring, families can avoid similar pitfalls and secure their financial future. Additionally, incorporating integrated tax planning and tax-loss harvesting strategies can further enhance your family’s financial resilience.
Conclusion
Imagine the worry that comes with relying on a single income source for your family’s future. Managing business concentration risk is crucial for ensuring your family’s financial stability, especially when you have deep ties to specific income sources. When families understand this risk, they can build a more secure future, protecting their wealth from unexpected challenges. The proactive measures outlined in this guide empower families to take control of their financial destinies, emphasizing the importance of diversification and strategic planning.
Key strategies discussed include:
- Identifying areas of concentration risk, such as revenue sources, investment portfolios, and supplier relationships.
- Implementing diversification.
- Expanding revenue streams.
- Regularly reassessing financial situations.
These are essential steps in mitigating these risks. Additionally, engaging with knowledgeable advisors, like those at Bright Advisers, can provide families with tailored insights and support, ensuring that your financial strategies remain aligned with your evolving needs.
Taking these steps not only protects your wealth but also brings peace of mind, knowing you’re prepared for whatever comes your way. Families are encouraged to commit to regular assessments and to educate younger generations about financial responsibility. By embracing these strategies, you’re not just securing your wealth; you’re nurturing a legacy that will support your family for generations.
Frequently Asked Questions
What is concentration risk in business?
Concentration risk in business refers to the financial risk that arises when a family relies too heavily on a single source of income, which can lead to significant financial loss if that source fails.
Why is concentration risk particularly concerning for families?
Concentration risk is especially concerning for families because their financial security may be closely tied to the success of businesses owned by relatives, making them vulnerable to financial challenges if those businesses struggle.
What are some signs of business concentration risk?
Signs of business concentration risk include relying too heavily on just a few clients or suppliers, which can jeopardize financial stability if those relationships falter.
How can families protect themselves from concentration risk?
Families can protect themselves from concentration risk by taking proactive steps to diversify their income sources and investments, which can help shield them from unexpected financial challenges.
What is the benefit of diversifying income sources?
Diversifying income sources provides peace of mind and helps ensure a family’s financial future is secure, regardless of the performance of any single income source.
List of Sources
- Define Concentration Risk in Business
- Risk-taking quotes to inspire business leaders (https://enterprisersproject.com/article/2016/10/risk-taking-quotes-inspire-business-leaders)
- 90 Warren Buffet Quotes to Inspire Your Investing Journey (https://sarwa.co/blog/warren-buffett-quotes)
- Identify Areas of Concentration Risk
- 90 Warren Buffet Quotes to Inspire Your Investing Journey (https://sarwa.co/blog/warren-buffett-quotes)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- California Small Business Statistics 2026 | Key Data (https://boostsuite.com/small-business-statistics/california)
- Assets, Debts, and Wealth in California (https://ppic.org/publication/assets-debts-and-wealth-in-california)
- How Many Small Businesses Are in California? [Dec 2023 Upd] (https://oberlo.com/statistics/how-many-small-businesses-are-in-california)
- Implement Strategies to Mitigate Concentration Risk
- Family Business Facts – Conway Center for Family Business (https://familybusinesscenter.com/resources/family-business-facts)
- 2025 US Family business survey (https://pwc.com/us/en/services/audit-assurance/private-company-services/library/family-business-survey.html)
- Family Business Facts (https://business.cornell.edu/centers/smith/resources/family-business-facts)
- Measuring the Financial Impact of Family Businesses on the US Economy (https://familybusiness.org/content/measuring-the-financial-impact-of-family-businesses-on-the-US-ec)
- Family Business Cited Stats | Family Business Alliance (https://fbagr.org/resources/cited-stats)
- Monitor and Reassess Concentration Risks
- The Importance of Regular Financial Reviews: Staying on Track – Gray Hurst Wealth Advisors (https://ghwealthadvisors.com/the-importance-of-regular-financial-reviews-staying-on-track)
- The Importance of Regular Wealth Management Check-Ins: Why You Should Review Your Financial Plan Annually – First Western Trust Bank (https://myfw.com/articles/the-importance-of-regular-wealth-management-check-ins-why-you-should-review-your-financial-plan-annually)
- The Benefits of Personal Financial Management Tools | American National Bank of Texas (https://knowledge.anbtx.com/money-management/budgeting/article/mastering-your-finances-with-personal-financial-management-tools)
- Importance of Annual Reviews (https://thepittigroup.com/blog/importance-annual-reviews)
- Stats and Graphs on the Financial Behaviors of Baby Boomers (https://mx.com/blog/baby-boomer-financial-management-stats)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading