

Key Highlights
- Naming an estate as a beneficiary can lead to delays in accessing life insurance funds due to the probate process, which may take 12 to 24 months in California.
- Proceeds from life insurance may be subject to taxes, potentially reducing the inheritance for heirs.
- Designating an estate relinquishes control over fund distribution, which may not align with the individual’s wishes.
- Regularly review and update beneficiary designations, especially after major life events, to ensure they reflect current intentions.
- Consider naming specific individuals or a trust as beneficiaries to avoid probate and ensure quicker access to funds.
- Engaging with a financial planner or estate attorney can help navigate complexities and ensure wishes are respected.
- Contingent beneficiaries should be named to prevent assets from going through probate if the primary beneficiary cannot inherit.
- Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, can assist families in creating tailored wealth management solutions.
Introduction
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even in the face of life’s uncertainties. Many parents feel overwhelmed by the complexities of life insurance and worry about their family’s financial future. Naming an estate might seem simple, but it can create unnecessary stress for families during an already difficult time.
In this guide, we’ll gently walk through the essential steps and considerations for families, highlighting potential pitfalls and sharing strategies to ensure financial support is there when you need it most. Together, we can navigate these complexities and ensure your loved ones are supported when it matters most.
Understand the Role of an Estate as a Beneficiary
Have you thought about how your choices in life insurance can impact your family when they need you the most? When you choose this option, your loved ones might face a long wait for the funds, which can add stress during an already tough time.
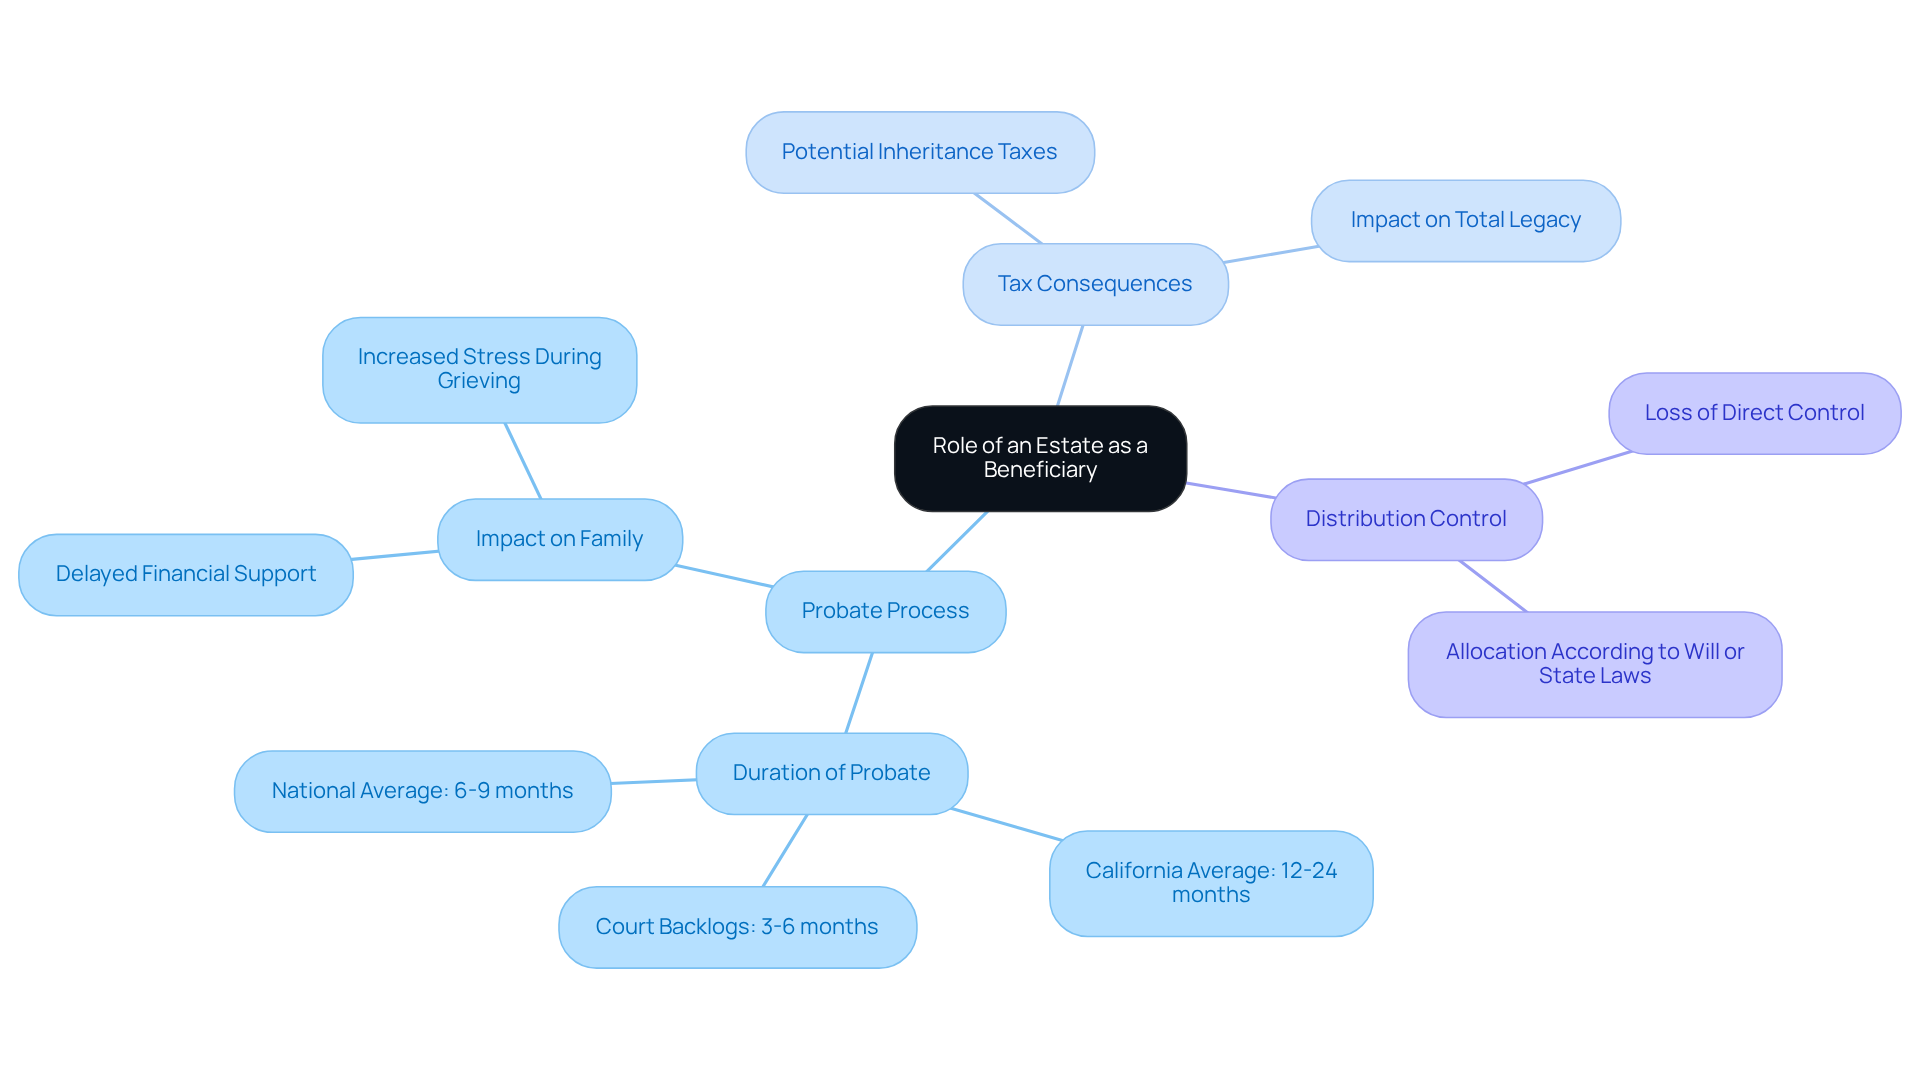
- Probate Process: Designating your assets as the recipient means the life insurance payout will go through probate, which can last between 12 to 24 months in California, frequently exceeding the national average of six to nine months. Imagine waiting months for the support you need during a tough time; it can be overwhelming for your family.
- Tax Consequences: The proceeds might be part of your taxable assets, possibly resulting in increased inheritance taxes that could reduce the total legacy for your heirs.
- Distribution Control: By naming your property, you relinquish direct control over the distribution of the funds. Instead, they will be allocated according to your will or state laws, which may not align with your intended wishes.
Example Scenario: Picture a family in Brea, California, where a parent makes this choice. Upon their passing, the life insurance payout is delayed due to the probate process, leaving the surviving spouse and children without immediate financial support during a challenging time. This highlights why it’s so important to understand your choices and look for options that can offer more immediate help to your loved ones.
Complete the Necessary Documentation for Designation
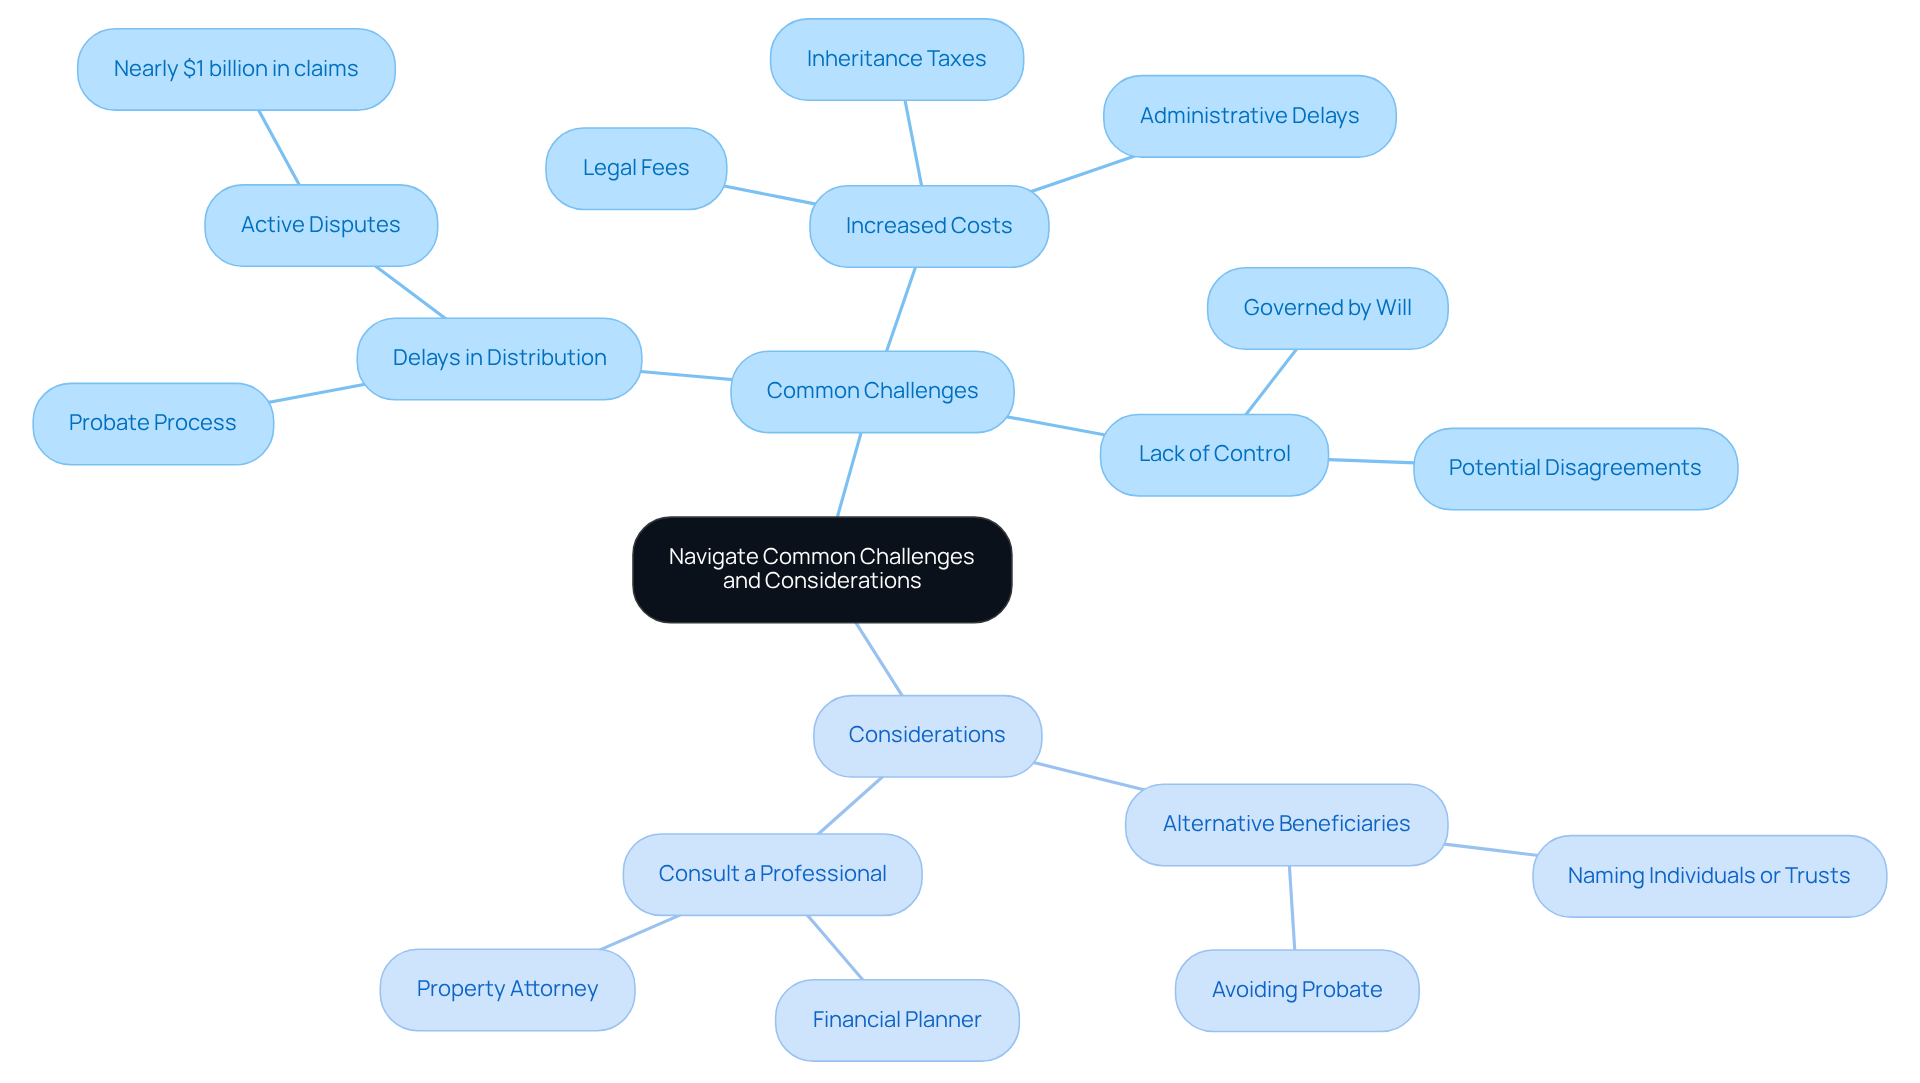
Have you ever thought about what would happen to your loved ones if something unexpected were to occur? Naming your estate as beneficiary of a life insurance policy is a crucial step in ensuring your family is taken care of. Let’s start by reaching out to your life insurance provider to get the Beneficiary Designation Form.
Once you have the form, it’s important to clearly specify that you wish to designate your property as the recipient. Make sure to include your property’s legal name as it appears in your will. You may also need to provide your full name, policy number, and any other identifying information required by the insurer.
Don’t forget to sign and date the form to validate your request. After that, send the completed form to your insurance provider, either electronically or via mail, following their instructions.
It’s a good idea to check your beneficiary designations regularly, especially after major life events, to ensure they reflect your current wishes. Imagine the stress of your loved ones facing confusion over your estate when you’re no longer there. Keeping a copy of the form you submit will be helpful for your loved ones later.
Remember, disputes may arise over claims of fraud or errors in how the assignment form was completed. It’s essential to be clear in your documentation. With 33% of Americans thinking they are underinsured, taking these steps today can bring peace of mind, knowing your family is protected and your wishes are honored.
Navigate Common Challenges and Considerations
Navigating the complexities of naming estate as beneficiary of life insurance can feel overwhelming, especially during such emotional times.
Common Challenges:
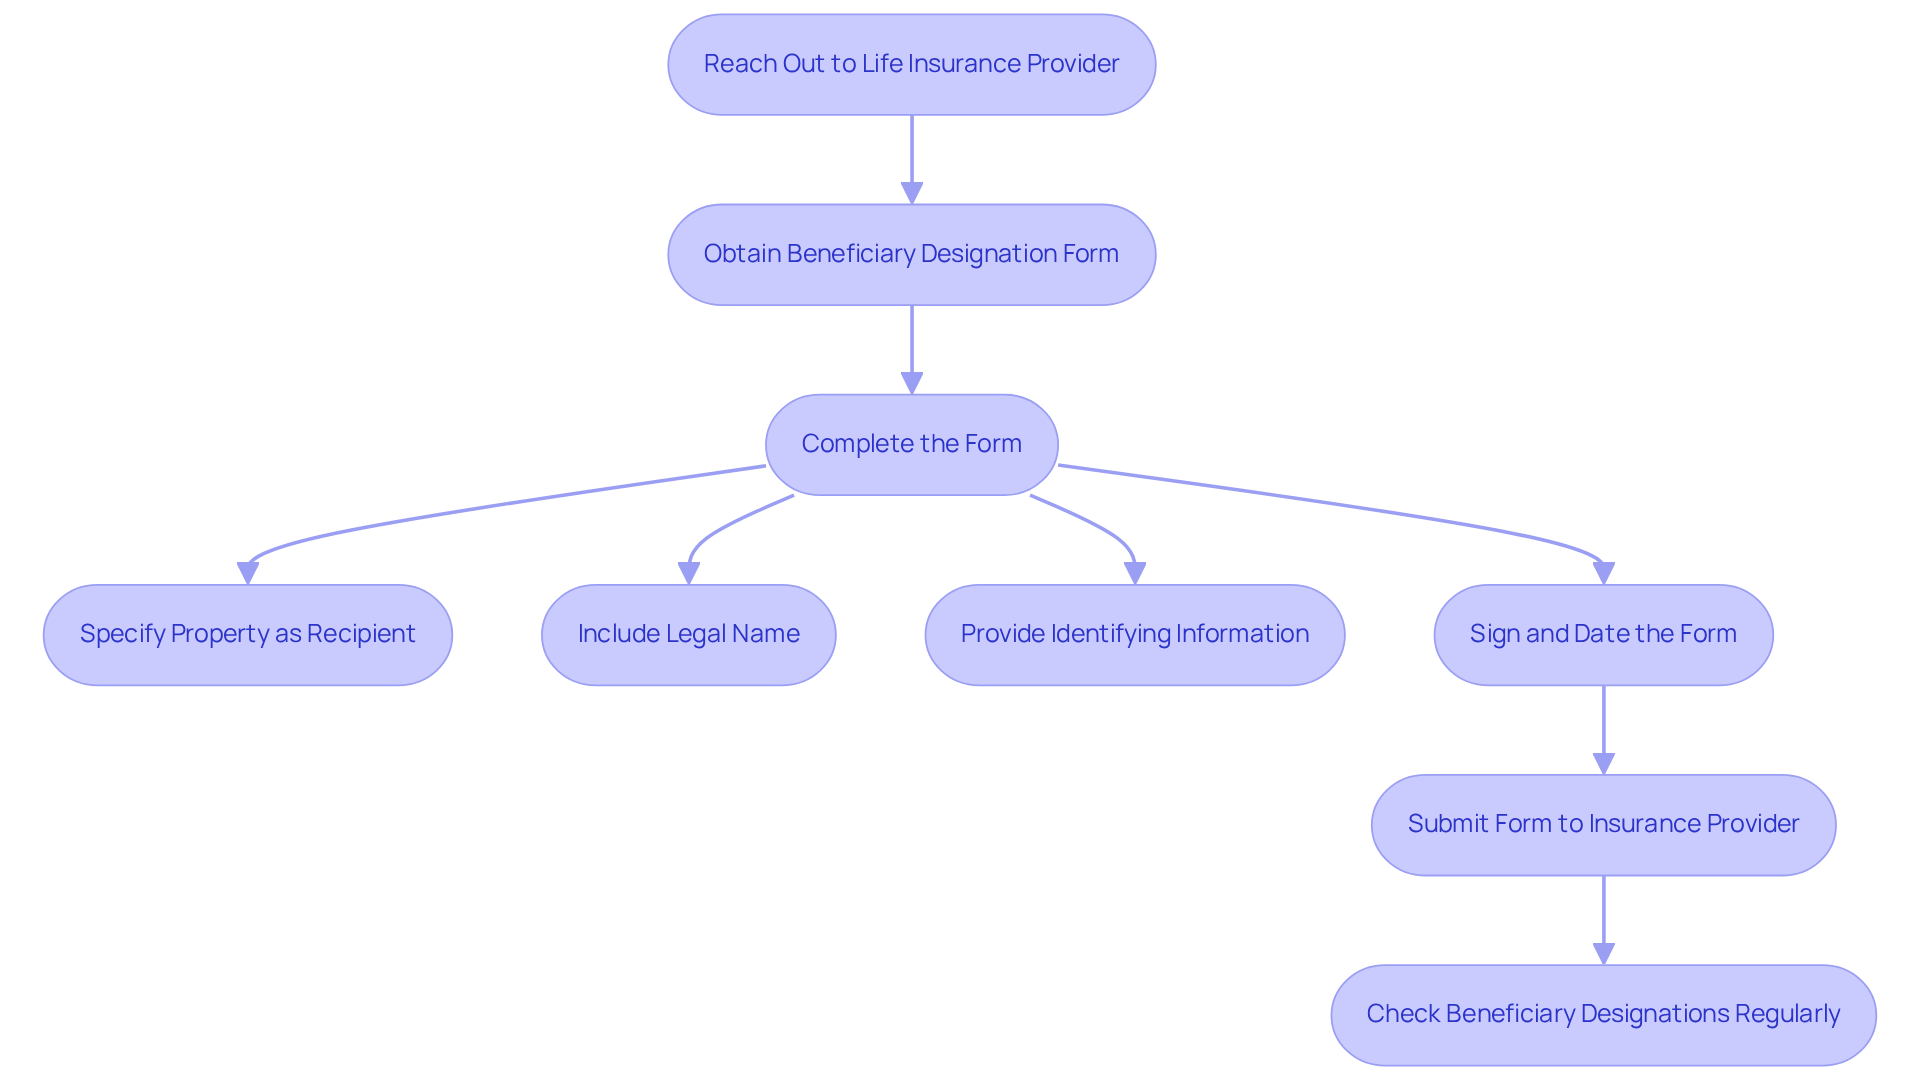
- Delays in Distribution: Navigating the probate process can be a long and challenging journey, often leaving families waiting for months or even years to access their funds. Nearly $1 billion in death-benefit claims were under active dispute at the end of the most recently reported year, illustrating the potential for delays that can add emotional strain to families already dealing with loss.
- Increased Costs: It’s important to be aware that legal fees and possible inheritance taxes might lessen what your loved ones receive, adding to the stress during an already difficult time. Administrative delays are increasingly contributing to unresolved claims, which can further complicate financial results for recipients. For instance, claims filed during the first two years of coverage consistently show higher denial rates due to contestability reviews.
- Lack of Control: Once the funds are part of your estate, their distribution is governed by your will, which may not reflect your original intentions. This could lead to unexpected challenges for your loved ones, especially if disagreements arise among them.
Considerations:
- Alternative Beneficiaries: Naming specific individuals or a trust as beneficiaries can help avoid probate, ensuring quicker access to funds. This strategy can reduce the risks related to delays and expenses tied to the probate process, offering individuals the financial stability they require during challenging times.
- Consult a Professional: Engaging with a financial planner or property attorney is crucial to discuss the best strategies tailored to your family’s unique situation. Legal advice can assist in navigating the complexities of naming an inheritance as a recipient and ensure that your wishes are respected. As noted by experts, having legal counsel can prevent insurers from imposing unreasonable demands for documentation, which can stall the claims process.
Example Scenario:
Emily and Mark, a couple in Orange County, experienced significant delays in accessing their life insurance proceeds after naming their estate as the beneficiary. They subsequently found that creating a trust might have offered prompt access to resources for their children, highlighting the significance of exploring options other than designating an inheritance directly. This experience emphasizes the necessity of proactive planning and the value of expert guidance in property management. By partnering with Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, families like Emily and Mark can navigate these complexities and create tailored wealth management solutions that empower financial security and freedom, including integrated tax planning strategies.
By taking these steps, you can ensure your family’s future is secure, allowing you to focus on what truly matters-each other.
Review and Update Your Beneficiary Designation Regularly
Have you ever thought about what would happen to your loved ones if your life insurance policy isn’t up to date? To ensure that naming estate as beneficiary of life insurance policy is appropriate, it’s important to take a moment to review and update your designations regularly.
Recommended Frequency:
- Annually: Make it a habit to review your beneficiary designations at least once a year.
- After Major Life Events: Update your designations following significant changes such as marriage, divorce, the birth of a child, or the passing of someone entitled to receive benefits.
Steps to Review:
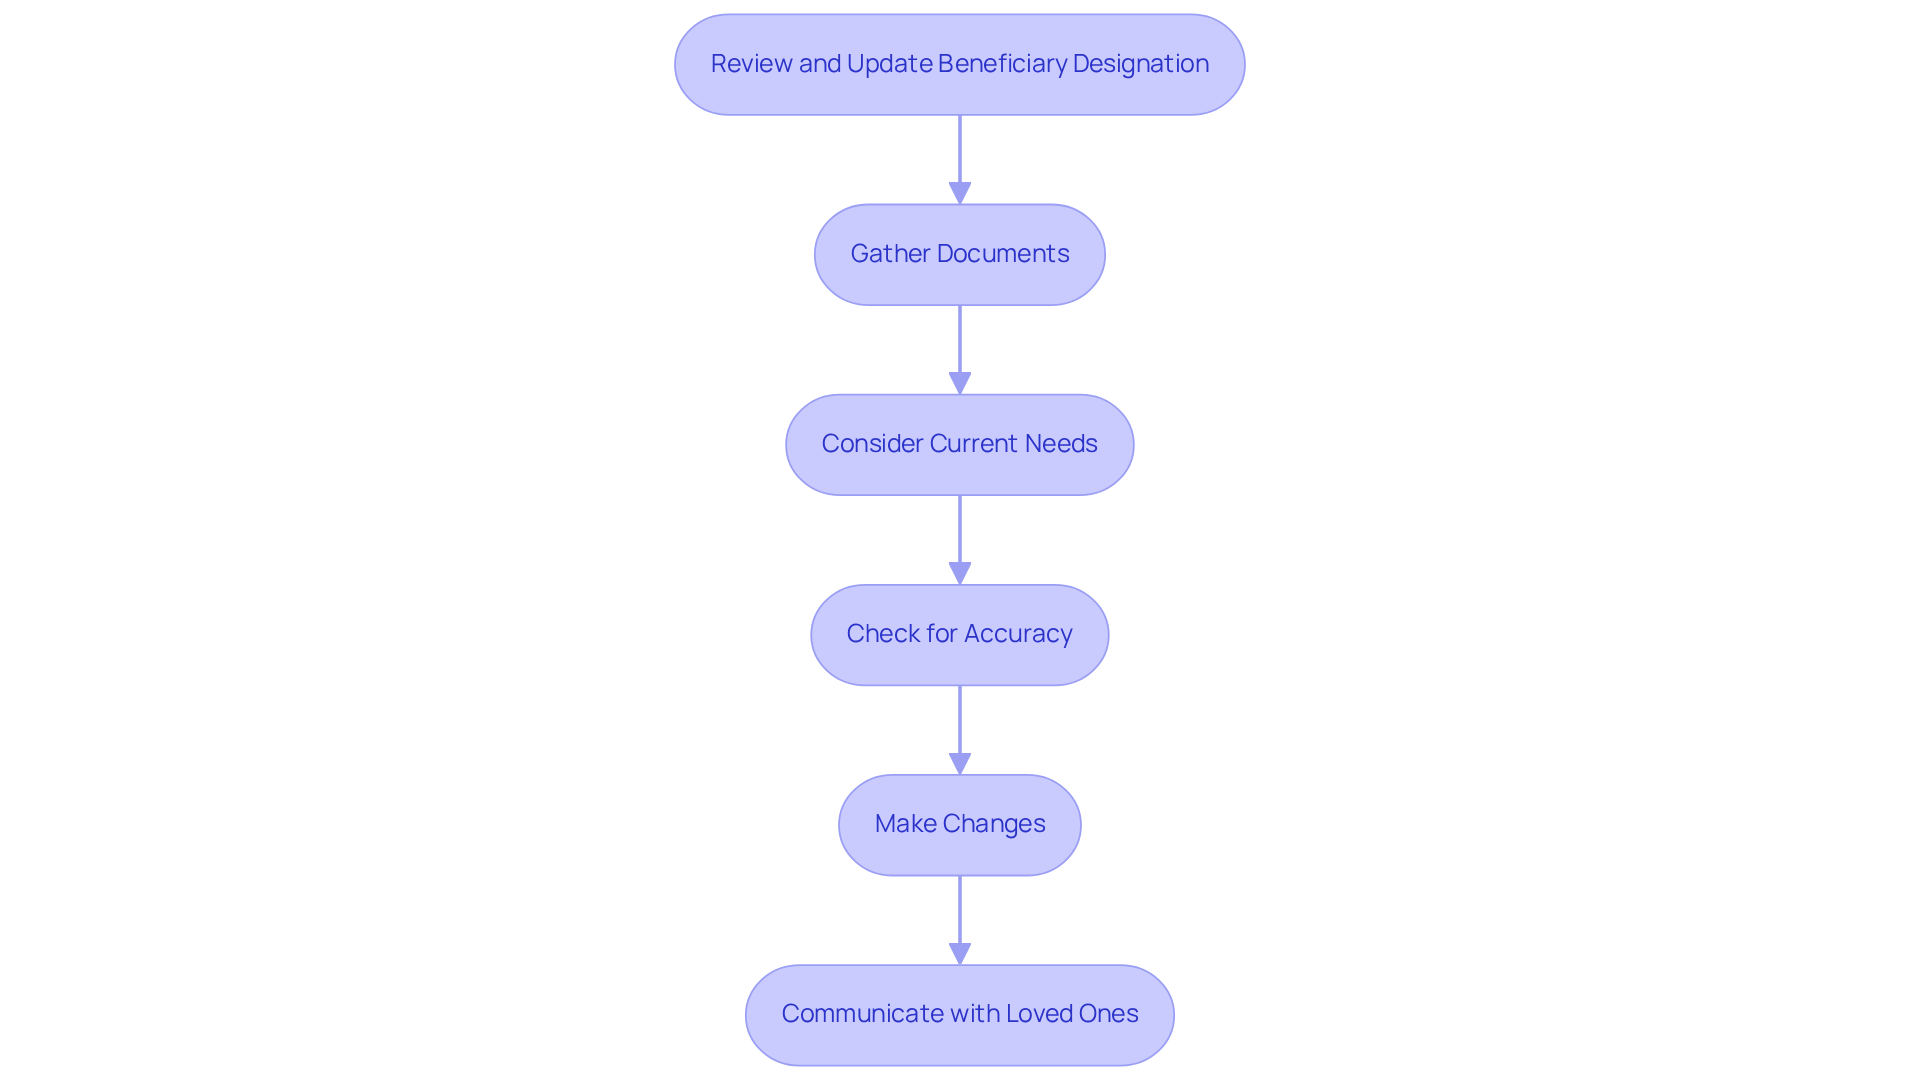
- Let’s start by gathering your life insurance policy and any important estate planning documents.
- Consider your current needs: Think about any changes in your family dynamics or financial situation that may influence your recipient choices.
- Check for accuracy: Ensure that names and Social Security numbers are correct when listing recipients to prevent future complications.
- Make necessary changes: If needed, fill out a new recipient designation form and submit it to your insurance provider.
- Communicate with your loved ones: Discuss your decisions with your relatives to ensure everyone understands your intentions.
Importance of Contingent Beneficiaries:
Naming contingent beneficiaries is crucial as it can prevent assets from going through probate if the primary beneficiary is unable to inherit. This step ensures that your wishes are honored even in unforeseen circumstances.
Example Scenario:
Allison and Brian, a family on the East Coast, realized after the birth of their second child that their previous beneficiary designations no longer reflected their current family structure. By revising their titles, they ensured that both children would be financially safeguarded. Imagine the stress of your loved ones facing legal battles over your assets because of outdated designations. Had they overlooked this update, their assets might have gone to outdated recipients, resulting in possible legal conflicts and financial instability for their relatives.
Importance of Regular Reviews:
Many families, just like yours, often forget to review their beneficiary designations, which can lead to unexpected challenges. Frequently reviewing these assignments can stop assets from going to previous recipients, like former partners, and help ensure that your desires are respected. Consulting with an estate planning professional can provide additional guidance on naming estate as beneficiary of life insurance and aligning your beneficiary designations with your overall estate plan, especially after significant life changes. Regularly reviewing your beneficiary designations can be the difference between peace of mind and unnecessary stress for your family when they need it most.
Conclusion
Imagine the weight of ensuring your family’s financial future rests on a single decision – naming an estate as a beneficiary of life insurance. It’s important to know that this choice can sometimes cause delays in getting funds when your family needs them most, and it might also bring unexpected tax issues or uncertainty about how your assets are shared. When families stay informed and take action, they can make choices that reflect their values and truly support their loved ones during tough times.
In this guide, we’ve explored important points, like:
- Making sure your paperwork is filled out correctly
- Tackling common hurdles
- Checking in on your beneficiary choices regularly
Working with professionals like financial planners or estate attorneys can offer you personalized help, making it easier to navigate the claims process and avoid any surprises.
The ultimate aim is to build a safe financial space for your family, so you can focus on what really counts – being there for one another. By taking these steps, you’re not just protecting assets; you’re nurturing your family’s future and creating a legacy of care and support. For personalized support in navigating these complexities, reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
What is the impact of choosing an estate as a beneficiary for life insurance?
Choosing an estate as a beneficiary can lead to delays in receiving funds due to the probate process, which can take 12 to 24 months in California, often longer than the national average.
How does the probate process affect life insurance payouts?
When life insurance proceeds are designated to an estate, they must go through probate, which can significantly delay the distribution of funds to beneficiaries, potentially adding stress during a difficult time.
Are there tax consequences associated with naming an estate as a beneficiary?
Yes, the proceeds from the life insurance may be considered part of the taxable assets, which could lead to increased inheritance taxes and reduce the total amount inherited by heirs.
What control do I have over the distribution of life insurance funds if I name my estate as the beneficiary?
By naming your estate, you lose direct control over how the funds are distributed. The allocation will follow your will or state laws, which may not reflect your personal wishes.
Can you provide an example of the consequences of naming an estate as a beneficiary?
For instance, in Brea, California, if a parent names their estate as the beneficiary and passes away, the life insurance payout may be delayed due to probate, leaving the surviving spouse and children without immediate financial support during a challenging time.
Why is it important to understand the choices regarding life insurance beneficiaries?
Understanding these choices is crucial because they can significantly affect the financial support available to your loved ones during difficult times, highlighting the need for options that provide more immediate assistance.
List of Sources
- Understand the Role of an Estate as a Beneficiary
- Why Is Probate Taking So Long? Expert Insights (https://theheritancelawyers.com/blog/why-is-this-probate-taking-so-long)
- What to Know About the Cost of Probate | Sheela Stark Law Group, APC (https://lawyerstark.com/blog/what-everyone-should-know-about-the-cost-of-probate)
- How Long Does Probate Take? 9 to 24 Months by State (2026) (https://catalinastructuredfunding.com/blog/how-long-does-probate-take)
- California Probate Statistics: Trends and Case Insights (https://californiacourtrecord.org/statistics-probate)
- Complete the Necessary Documentation for Designation
- Life Insurance Statistics (https://thezebra.com/resources/research/life-insurance-statistics)
- Understanding Beneficiary Designation In Estate Planning (https://westernsouthern.com/retirement/beneficiary-designation)
- Life Insurance Stats & Carrier Insights for 2026 | Empathy (https://empathy.com/blog/life-insurance-facts)
- Life Insurance Statistics, Data and Industry Trends (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Facts + Statistics: Life insurance | III (https://iii.org/fact-statistic/facts-statistics-life-insurance)
- Navigate Common Challenges and Considerations
- Probate delays surge – a 65% rise in year-long cases unveiled by Quilter FoI data analysis | Quilter Media Centre (https://media.quilter.com/search/probate-delays-surge–a-65-rise-in-year-long-cases-unveiled-by-quilter-foi-data-analysis)
- Life Insurance Claim Delays: Why Insurers Stall Payments (https://dilawgroup.com/blog/2025/09/life-insurance-claim-delays-how-insurers-stall-payments-when-families-need-them-most)
- How Long Do Beneficiaries Wait for Life Insurance Payouts? (https://lifeinsurancelawfirm.com/how-long-do-beneficiaries-wait-for-life-insurance-payouts)
- Life Insurance Claim Denial Statistics 2024-2025 (https://lifeinsuranceattorney.com/blog/2025/may/2024-2025-life-insurance-claim-denial-statistics)
- Review and Update Your Beneficiary Designation Regularly
- How often should beneficiaries be reviewed? | Urology Times (https://urologytimes.com/view/how-often-should-beneficiaries-be-reviewed)
- Don’t Let Beneficiary Designations Ruin Your Estate Plan | Repair The Roof Podcast – % (https://daytonestateplanninglaw.com/episodes/dont-let-beneficiary-designations-ruin-your-estate-plan)
- The Importance Of Regularly Reviewing Beneficiary Designations | Legacy Private Trust (https://lptrust.com/blog/regularly-reviewing-beneficiary-designations)
- The Importance of Reviewing Your Beneficiary Designations – Generations Law Group (https://generationslawgroup.com/the-importance-of-reviewing-your-beneficiary-designations)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading