

Overview
Opening a stock account for your child is a wonderful step towards fostering their financial literacy. To help you through this journey, here’s a gentle guide that outlines a step-by-step process:
- Select a brokerage that aligns with your family’s values.
- Gather the necessary information, ensuring you have everything ready for the application.
- Complete the application with care and attention.
- Fund the account. This is an exciting moment!
- Choose investment assets that resonate with your family’s goals and values.
- Monitor the account’s performance.
It’s important to educate your children about financial management along the way, nurturing their understanding from an early age.
By following these steps, you’re not just investing in stocks; you’re investing in your child’s future. Together, we can navigate this journey, ensuring that your little ones grow up with the tools they need to thrive financially. We’re here for you every step of the way!
Key Highlights:
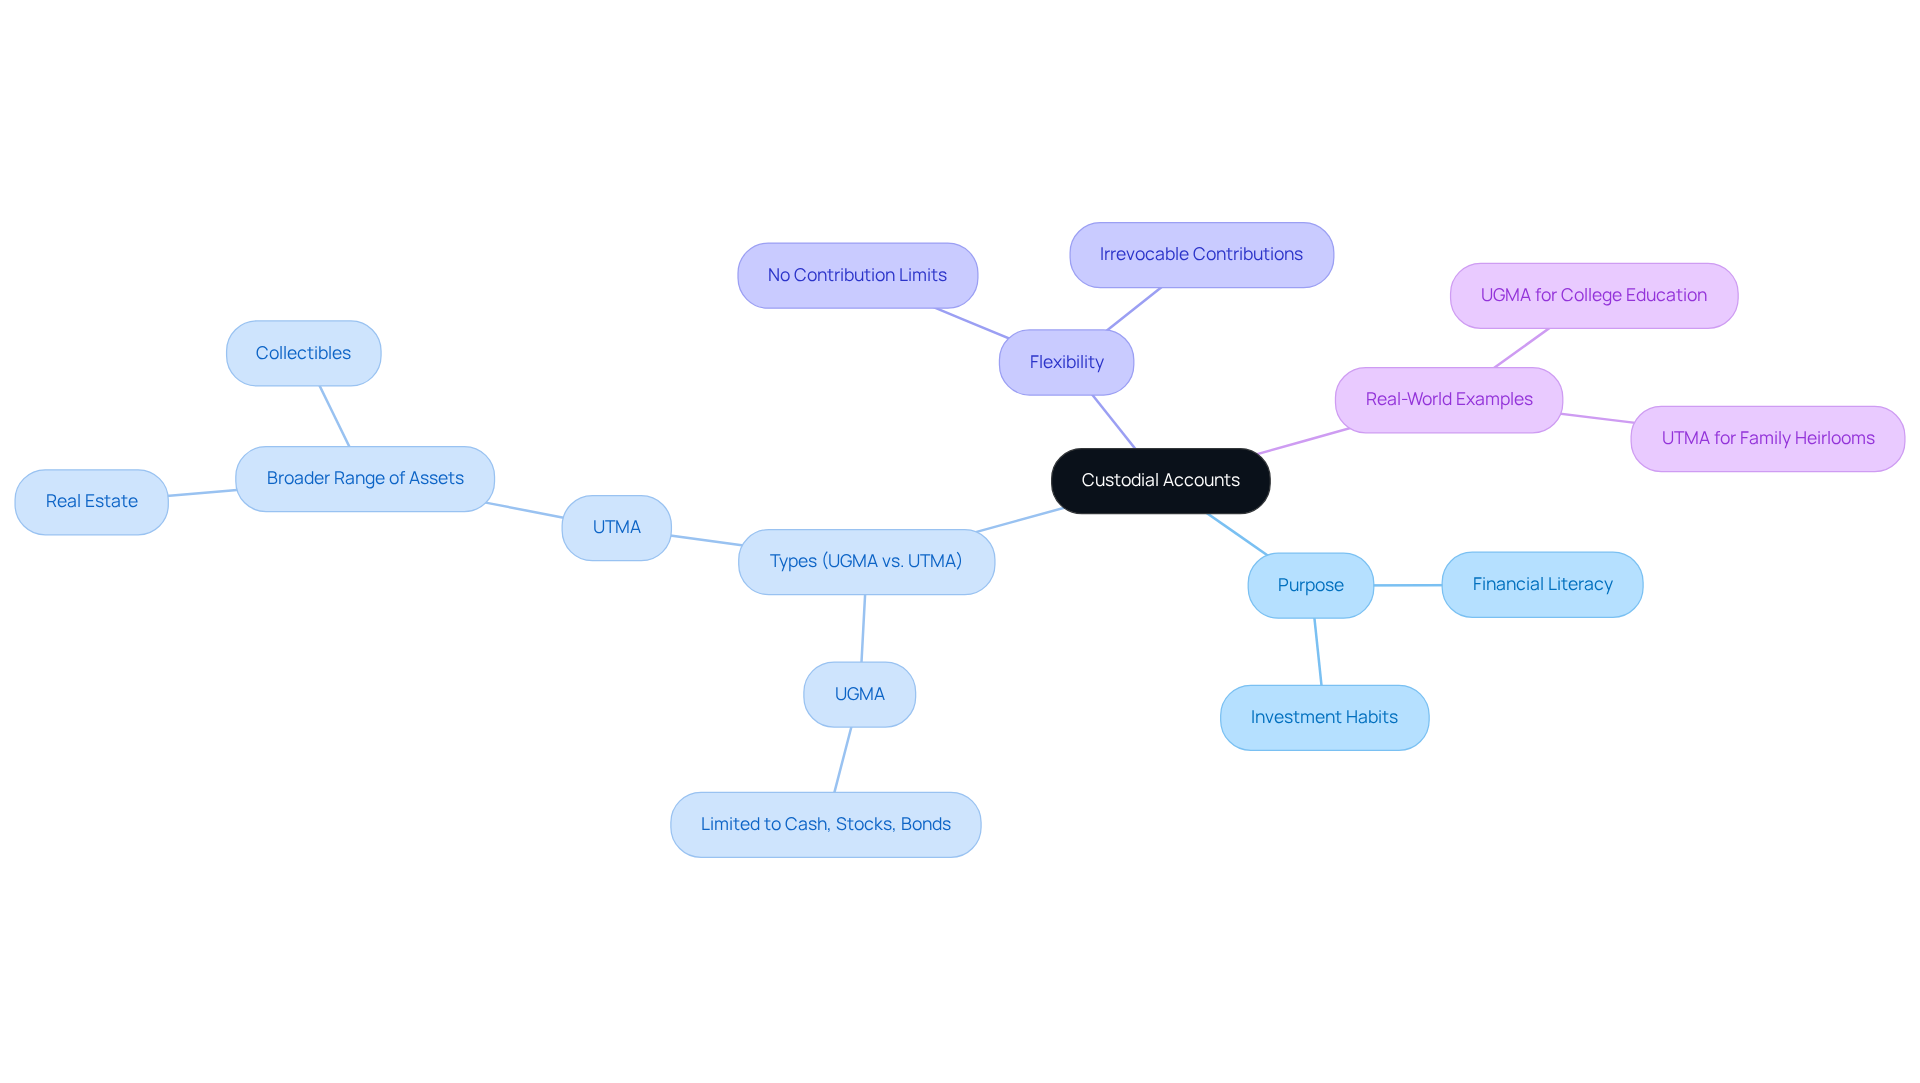
- Custodial accounts are financial arrangements set up by adults for minors, allowing the custodian to manage assets until the minor reaches adulthood.
- UGMA plans are limited to cash, stocks, and bonds, while UTMA plans allow for a wider range of assets, including real estate and collectibles.
- Bright Advisers emphasises minimising fund fees and providing personalised investment portfolios for families.
- Custodial funds help instil financial literacy in children, with no income or contribution limits, allowing for significant contributions.
- Real-world examples show families using UGMA for mutual funds and UTMA for diverse assets like heirlooms.
- Custodial assets impact financial aid eligibility, with 20% counted for aid compared to 5.64% for 529 plans.
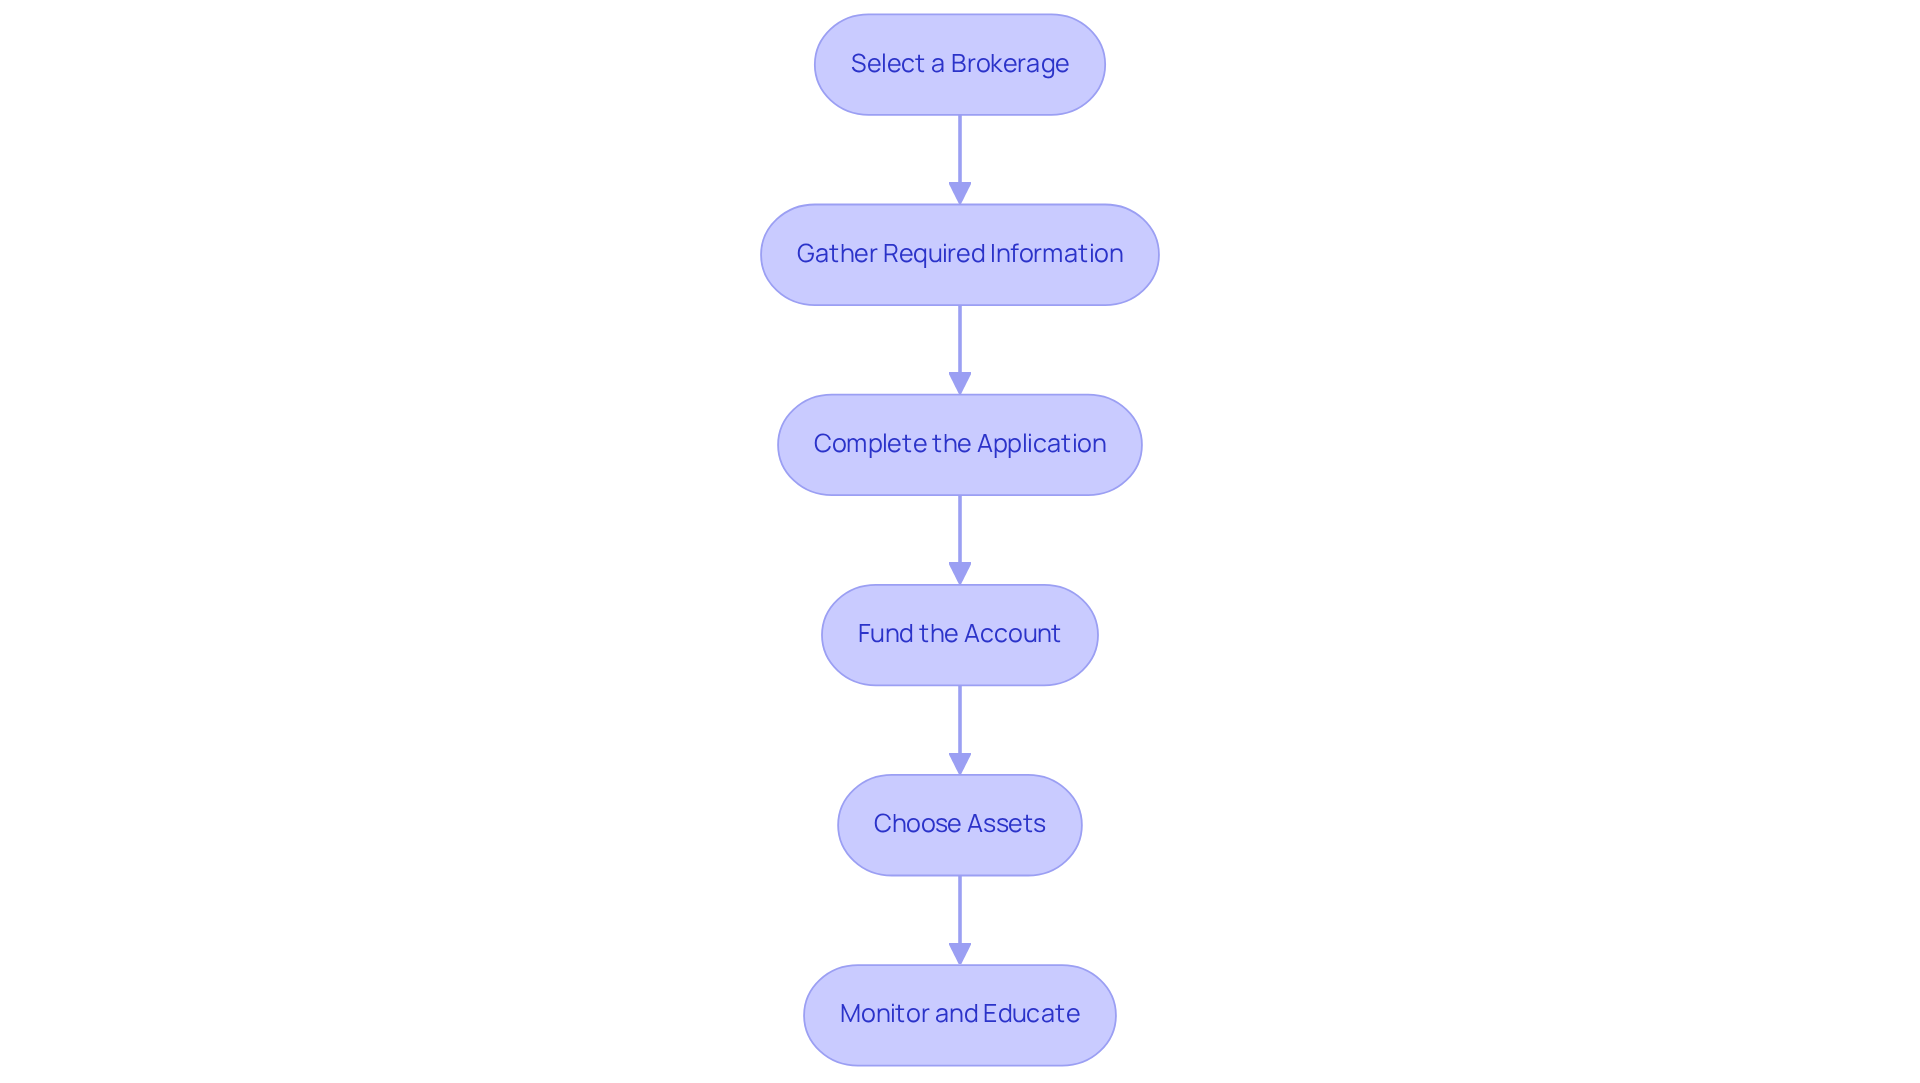
- Steps to open a kids stock account include selecting a brokerage, gathering personal information, completing the application, funding the account, choosing assets, and monitoring performance.
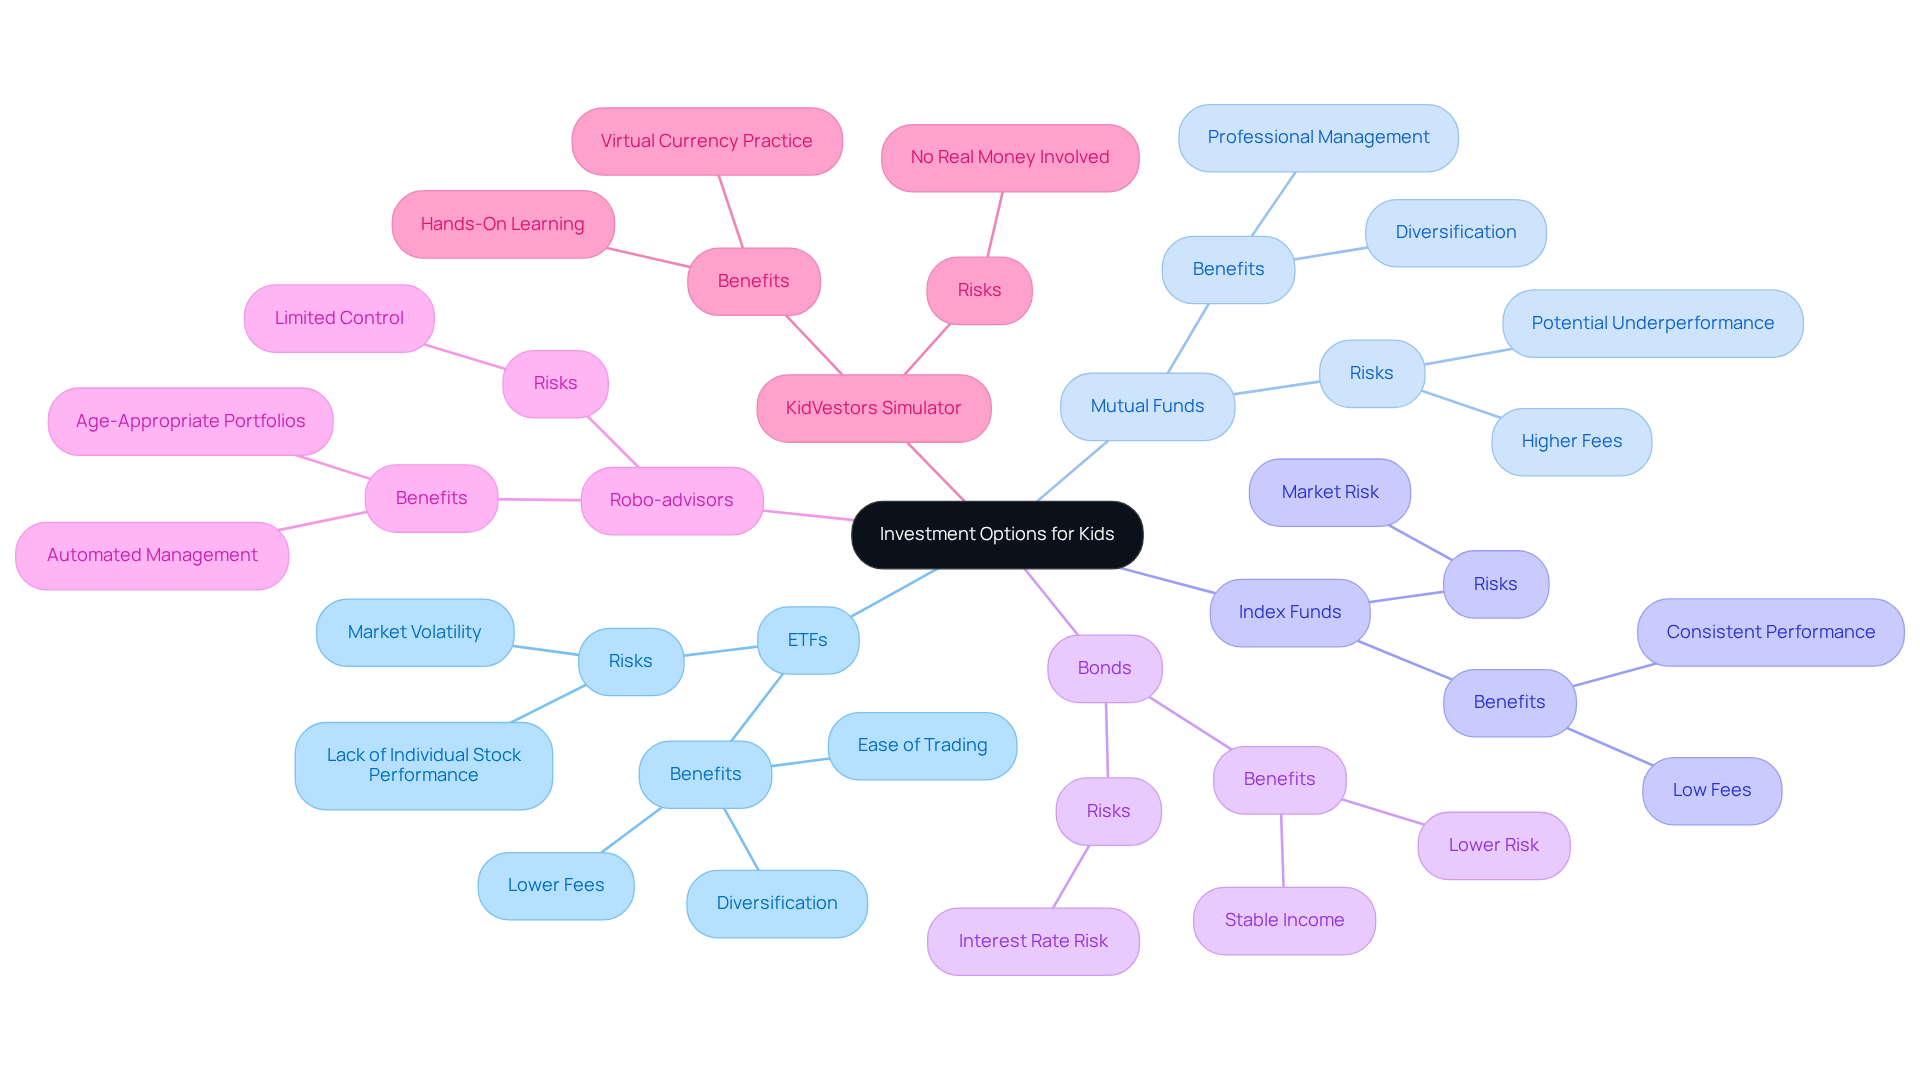
- Investment options for kids include ETFs, mutual funds, index funds, and bonds, with robo-advisors simplifying management.
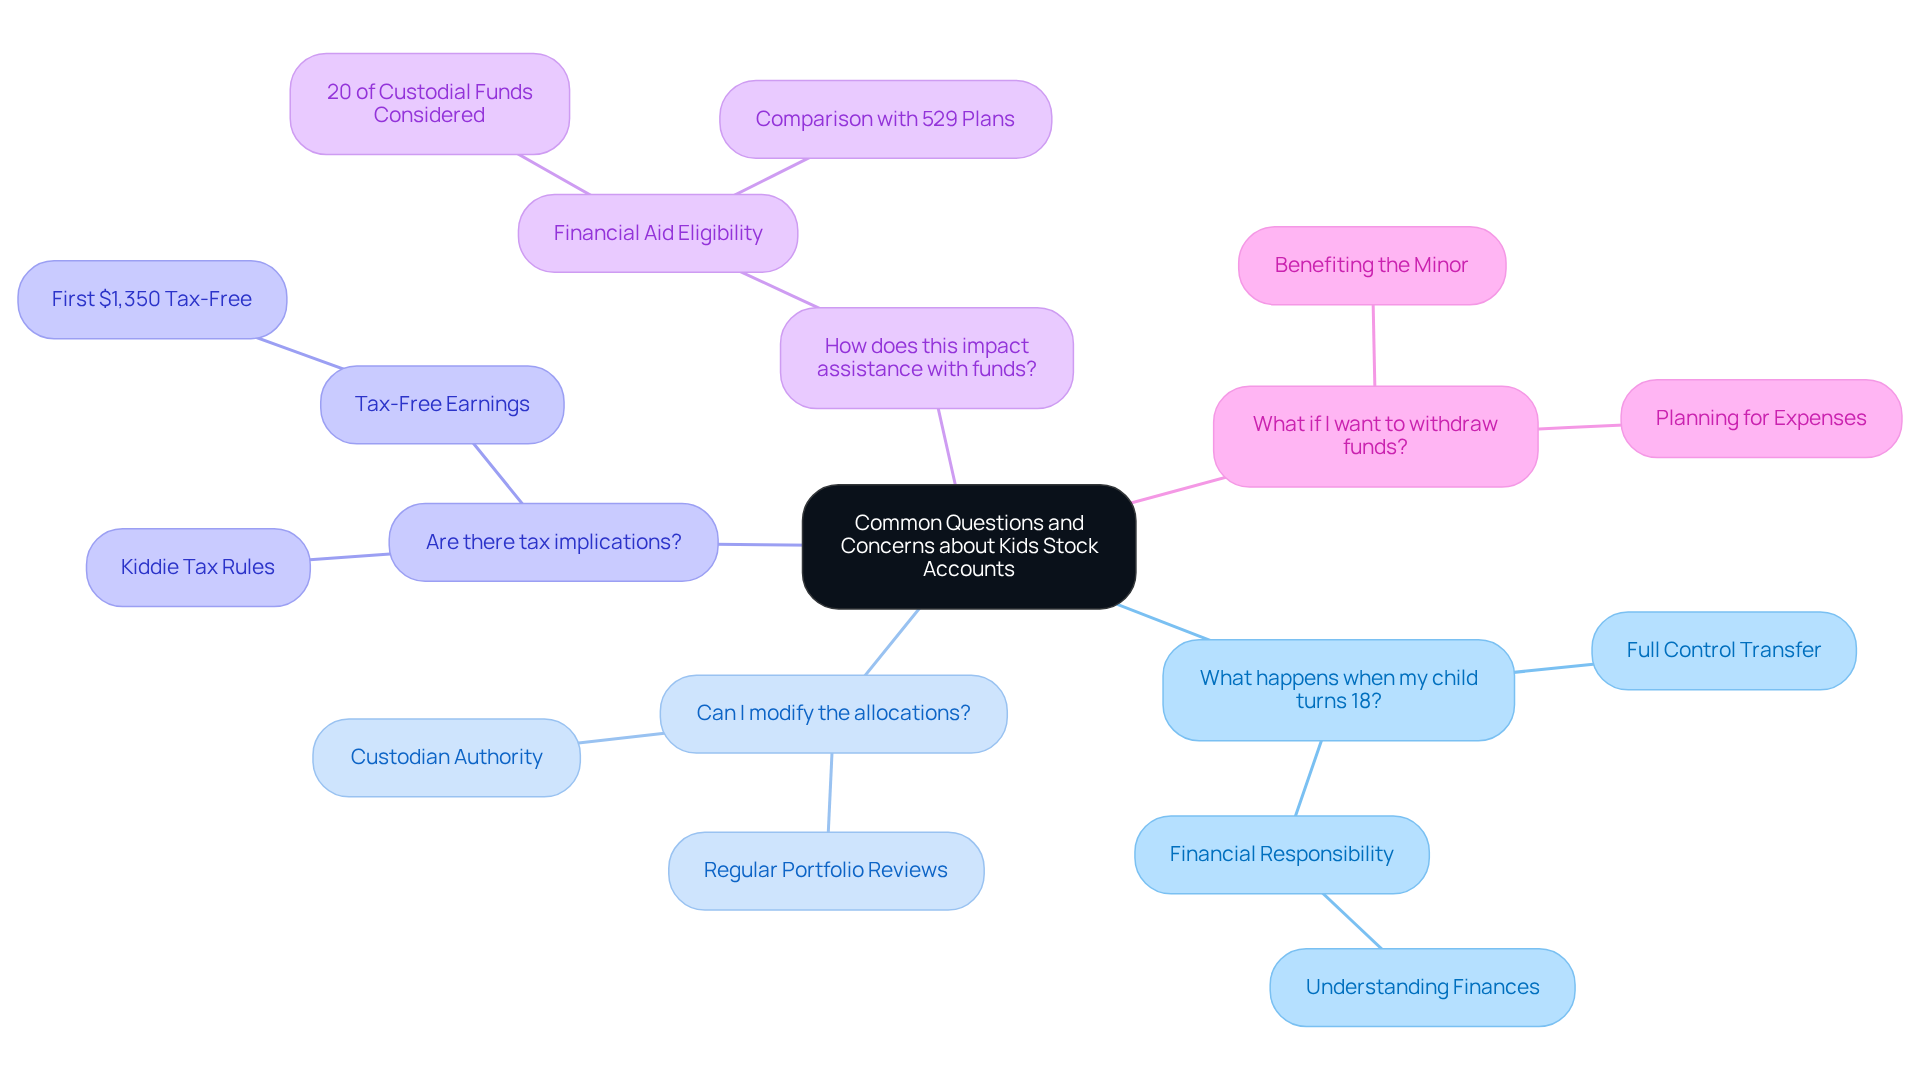
- Parents should prepare children for financial independence at age 18, review investment allocations, and understand tax implications of custodial accounts.
- Withdrawals from custodial accounts must benefit the minor, emphasising careful planning for fund usage.
Introduction
Opening a kids stock account can be a transformative step in shaping your child’s financial future. Yet, many parents feel uncertain about the process. This guide aims to demystify custodial accounts and highlight the benefits of investing early, providing your children with a solid foundation in financial literacy.
Imagine if your child could grow up understanding the value of money and investment—what a gift that would be! So, what are the key steps to successfully navigate this journey? How can you ensure that your children are well-prepared for the responsibilities of managing their own investments?
Together, we can explore these important questions and empower your family with the knowledge and tools needed for a brighter financial future.
Understand Custodial Accounts and Their Purpose
Custodial arrangements serve as valuable financial instruments set up by an adult, known as the custodian, for the benefit of a minor. These arrangements can encompass a variety of assets, including stocks, bonds, and mutual funds. The custodian oversees these funds until the minor reaches adulthood, at which point the individual gains full control over the assets. The primary purpose of custodial funds, specifically a kids stock account, is to empower parents and guardians to save and invest for their children, nurturing financial literacy and investment habits from an early age.
Understanding the distinctions between custodial arrangements, particularly UGMA (Uniform Gifts to Minors Act) and UTMA (Uniform Transfers to Minors Act), is crucial. UGMA plans are limited to assets such as cash, stocks, and bonds, while UTMA plans offer greater flexibility by allowing a broader range of assets, including real estate and collectibles. This flexibility can be particularly beneficial for families aiming to transfer wealth in diverse forms.
At Bright Advisers, we are dedicated to minimizing fund fees, making wealth management more accessible for families. Our innovative in-house technology has transformed traditional investment products, allowing for hyper-personalized portfolios tailored to the unique needs of young families. Financial consultants highlight the advantages of custodial arrangements in fostering youth literacy in money management. As Sandra Cho, a wealth manager, notes, “The benefits are that the funds possess flexibility in that there are no income or contribution limits.” This flexibility allows families to contribute freely to a kids stock account, which helps to establish a strong financial foundation for their children.
Consider real-world examples: one family might opt for a UGMA plan to invest in mutual funds for their child’s college education, while another may choose a UTMA arrangement to include a cherished family heirloom or property as part of their child’s future assets. Both options aim to instill a sense of financial responsibility in children by using a kids stock account, preparing them for adulthood and the management of their own resources. Additionally, it’s important for parents to recognize that 20% of custodial assets are counted as available for higher education financial aid, compared to only 5.64% for 529 plans. This is a significant factor to consider when planning for educational expenses. Bright Advisers also provides educational materials to assist young parents in navigating the complexities of custodial arrangements and making informed investment decisions. Together, we can navigate this journey toward securing a brighter financial future for your family.
Steps to Open a Custodial Stock Account
Opening a kids stock account can be a significant step in securing your child’s financial future. Here’s how you can navigate this journey with ease:
-
Select a Brokerage: Start by exploring brokerages that offer custodial services. Look for those with low fees, user-friendly platforms, and robust educational resources. Remember, keeping fund fees minimal is crucial for making wealth management accessible for families. Vanguard, for example, charges a $20 annual fee and boasts a low mutual fund expense ratio of 0.10%. Charles Schwab is another great option, allowing fractional share purchases for as little as $5.
-
Gather Required Information: It’s important to collect personal information for both the custodian and the minor. This includes Social Security numbers and identification documents. Having everything ready will make the process smoother.
-
Complete the Application: Next, fill out the brokerage’s application form for custodial services. Ensure that all information related to your kids stock account is accurate to avoid any delays in processing your application.
-
Fund the Account: After your application is processed, make an initial deposit to finance the fund. This can typically be done via bank transfer or check. There are no income or contribution limits for custodial funds, which means you can contribute significantly. If you have questions about these contributions, Bright Advisers can help clarify things for your family concerning the kids stock account.
-
Choose Assets: Once your fund is financed, it’s time to select assets on behalf of your child. Starting with diversified options, like index funds or ETFs, can set a solid foundation for future growth. Bright Advisers offers tailored wealth management solutions to guide families in making informed investment choices.
-
Monitor and Educate: Finally, regularly assess the performance of the account and involve your child in conversations about investing. This practice not only enhances their financial literacy but also prepares them for responsible money management in the future by utilizing a kids stock account. Keep in mind that custodial funds may impact financial aid eligibility when applying for college, so it’s wise to consider this aspect. Bright Advisers provides educational materials to empower young families on their financial journey.
Together, we can navigate this journey and ensure a brighter financial future for your family.
Explore Investment Options for Kids
When exploring investment options for a kids stock account, parents have several avenues to consider, especially with the support of Bright Advisers, which is dedicated to minimizing fund fees and improving wealth management accessibility for families.
Imagine introducing your child to the world of investing by setting up a kids stock account. Investing in a kids stock account can effectively engage children in the stock market. Companies that resonate with kids stock account, like Disney or Apple, can make the learning experience relatable and fun.
-
Consider the benefits of Exchange-Traded Funds (ETFs). ETFs provide diversification by pooling funds to invest in a variety of stocks or bonds. They typically carry lower risks compared to individual stocks, making them an excellent choice for young investors. As highlighted by financial experts, ETFs are especially advantageous for novice investors because of their cost-effectiveness and simplicity of handling.
-
Mutual Funds offer another option. Comparable to ETFs, mutual funds permit diversified allocations but are actively managed, which may lead to elevated fees. While they aim to outperform the market, they often come with additional costs that can affect overall returns.
-
Index Funds are a straightforward choice. These funds track specific indices, like the S&P 500, and are recognized for their low fees and consistent performance over time. They offer an easy way to invest in the market without the complexities of individual stock selection.
-
For a more cautious approach, consider Bonds. Bonds can offer consistent income and reduced risk compared to stocks. They are a fitting choice for parents aiming to balance their child’s financial portfolio.
Robo-advisors can simplify the process for managing a kids stock account. Automated platforms designed for minors, like a kids stock account, streamline the management of funds, enabling parents to oversee their child’s finances without needing extensive financial expertise. These services frequently encompass varied portfolios that adapt according to the age of the individual and financial objectives.
- Engage your child with the KidVestors Stock Simulator. Involving young individuals in the investment journey can be made easier with tools like the KidVestors stock simulator game, which enables them to practice purchasing stocks using virtual currency. This hands-on experience can help normalize money management and promote economic literacy.
By considering these options and utilizing the resources provided by Bright Advisers, parents can effectively educate their children about investing with a kids stock account while fostering a strong foundation for financial literacy. Together, we can navigate this journey, beginning modestly and maintaining curiosity in the investment process to foster a positive investment mindset in young individuals.
Address Common Questions and Concerns
When establishing a kids stock account as a custodial arrangement, it’s natural for parents to have numerous questions and concerns. Here are some key points to consider:
-
What happens when my child turns 18? Upon reaching 18, your child will take full control of the custodial account, allowing them to make independent financial decisions. Preparing them for this responsibility is crucial, ensuring they understand how to manage their finances effectively, particularly through a kids stock account.
-
Can I modify the allocations? As the custodian of the kids stock account, you have the authority to manage the investments until your child reaches the age of majority. Regular portfolio reviews and adjustments are essential to align with changing financial goals and market conditions.
-
Are there tax implications? Custodial accounts are subject to specific tax rules. Earnings may be taxed at your child’s rate, with the first $1,350 of unearned income being tax-free for the 2025 tax year. Consulting a tax expert can offer customized guidance based on your family’s economic circumstances.
-
How does this impact assistance with funds? Assets in custodial funds are categorized as the minor’s property, which can greatly affect aid eligibility. Federal financial aid formulas evaluate 20% of custodial funds as accessible for college expenses, in contrast to just 5.64% for 529 plans. Understanding this can help you strategize for future educational costs by utilizing a kids stock account.
-
What if I want to withdraw funds? Withdrawals from custodial accounts must solely benefit the minor. This restriction emphasizes the importance of planning how to utilize the funds effectively, ensuring they are used for expenses that support your child’s growth and development.
Together, we can navigate this journey and ensure that your child’s financial future is secure.
Conclusion
Establishing a kids stock account is a proactive step toward securing your child’s financial future. It allows you, as parents, to instill valuable investment habits from an early age. By understanding custodial accounts and their purpose, your family can make informed decisions that will benefit your children in the long run.
Imagine if you could guide your child toward financial literacy and responsibility. The article outlines essential steps for opening a custodial stock account:
- Selecting a brokerage
- Gathering necessary information
- Completing the application
- Funding the account
- Choosing appropriate assets
- Monitoring the investments
It’s also important to engage your children in discussions about money management. This not only enhances their financial literacy but also prepares them for responsible decision-making as they transition into adulthood.
Ultimately, the journey of opening a kids stock account is not just about investing money; it’s about fostering a mindset that values financial education and responsibility. We encourage you to explore various investment options, utilize available resources, and remain proactive in your children’s financial education. Together, we can cultivate a generation that is well-equipped to navigate the complexities of personal finance and investment, ensuring a brighter financial future for your family.
Frequently Asked Questions
What is a custodial account?
A custodial account is a financial arrangement set up by an adult, known as the custodian, for the benefit of a minor. The custodian manages the account until the minor reaches adulthood, at which point the minor gains full control over the assets.
What types of assets can be included in custodial accounts?
Custodial accounts can encompass various assets, including stocks, bonds, mutual funds, real estate, and collectibles, depending on the type of custodial arrangement.
What are the differences between UGMA and UTMA custodial accounts?
UGMA (Uniform Gifts to Minors Act) accounts are limited to specific assets such as cash, stocks, and bonds. In contrast, UTMA (Uniform Transfers to Minors Act) accounts allow for a broader range of assets, including real estate and collectibles.
What is the primary purpose of a kids stock account?
The primary purpose of a kids stock account is to empower parents and guardians to save and invest for their children, fostering financial literacy and investment habits from an early age.
How do custodial accounts help with financial literacy for children?
Custodial accounts help instill a sense of financial responsibility in children by allowing them to manage and understand their own resources as they grow, preparing them for adulthood.
What are the financial aid implications of custodial assets?
It’s important for parents to note that 20% of custodial assets are counted as available for higher education financial aid, compared to only 5.64% for 529 plans, which can significantly impact educational expense planning.
How does Bright Advisers support families with custodial accounts?
Bright Advisers minimizes fund fees and utilizes innovative in-house technology to create hyper-personalized portfolios for families. They also provide educational materials to help young parents navigate custodial arrangements and make informed investment decisions.
List of Sources
- Understand Custodial Accounts and Their Purpose
- Best Custodial Accounts In 2025: What To Know Before You Invest (https://businessinsider.com/personal-finance/investing/best-custodial-accounts)
- UTMA & UGMA Custodial Accounts: Overview, Benefits – NerdWallet (https://nerdwallet.com/article/investing/utma-ugma)
- What are the pros and cons of custodial accounts for minors? – Cordasco & Company (https://cspcpa.com/2023/10/11/what-are-the-pros-and-cons-of-custodial-accounts-for-minors)
- Child Support Statistics in the United States (https://aecf.org/blog/child-support-statistics)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- Steps to Open a Custodial Stock Account
- Financial Education Quotes (https://financialeducatorscouncil.org/financial-education-quotes)
- 25 quotes that show why education is important (https://canva.com/learn/25-quotes-show-education-important)
- 10 Great Investing Quotes to Consider (https://smartasset.com/investing/top-10-investing-quotes-of-all-time)
- 50 Great Quotes Illustrate the Power of Education (https://ecpi.edu/blog/50-great-quotes-illustrate-the-power-of-education)
- How Much Does It Cost to Open a Custodial Account? (https://investopedia.com/how-much-does-it-cost-to-open-a-custodial-account-7506692)
- Explore Investment Options for Kids
- ETFs vs Stocks : What’s Better For Your Kid’s Portfolio? (https://kidvestors.co/post/etfs-vs-stocks)
- ETFs vs. Mutual Funds: Which Is Better for Young Investors? (https://investopedia.com/articles/investing/021916/etfs-vs-mutual-funds-which-better-young-investors.asp)
- Wisdom of Great Investors – Quotes | Davis ETFs (https://davisetfs.com/investor_education/quotes)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Investing for Kids: 7 Investment Account Options – NerdWallet (https://nerdwallet.com/article/investing/set-kids-brokerage-account)
- Address Common Questions and Concerns
- Are Custodial Accounts a Good Option for Parents Saving for College? (https://savingforcollege.com/article/are-custodial-accounts-a-good-option-for-parents-saving-for-college)
- What To Think About When Your Child Reaches Age 18 (https://lenoxadvisors.com/insights/what-to-think-about-when-your-child-reaches-age-18)
- Custodial Accounts: What You Should Know | Bankrate (https://bankrate.com/investing/custodial-account)
- Saving for College: Custodial Accounts (https://schwab.com/learn/story/saving-college-custodial-accounts)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading