

Key Highlights
- Incentive Stock Options (ISOs) allow employees to purchase company shares at a set price, providing a potential investment opportunity for families.
- Eligibility for ISOs is limited to employees; consultants and board members do not qualify.
- The exercise price for ISOs must be at least equal to the fair market value on the grant date.
- To benefit from tax advantages, shares must be held for at least one year after exercising and two years after the grant date.
- Exercising ISOs typically does not trigger immediate income tax, but the difference between the exercise price and stock value can affect Alternative Minimum Tax (AMT) calculations.
- For 2026, AMT exemptions are $90,100 for singles and $140,200 for married couples, with phaseouts starting at $500,000 for singles and $1,000,000 for couples.
- Strategies to minimise ISO taxes include exercising options in low-income years, monitoring market conditions, and planning for future income changes.
- Tax-loss harvesting can offset gains from ISOs, potentially saving families significant amounts on taxes.
- Consulting tax professionals can provide personalised strategies and insights into AMT implications, ensuring families make informed decisions regarding their ISOs.
- Bright Advisers offers guidance to help families navigate the complexities of ISOs and enhance their wealth accumulation potential.
Introduction
Imagine feeling overwhelmed by the complexities of Incentive Stock Options (ISOs) while trying to secure your family’s financial future.
Together, we’ll explore a gentle, step-by-step approach to navigating ISOs, uncovering strategies that can help your family save significantly.
What if the tax landscape changes unexpectedly? Let’s ensure your family is ready for those surprises, so you can feel secure in your financial journey.
Understand Incentive Stock Options (ISOs)
Imagine having the chance to secure your family’s financial future through employee stock options, but feeling lost in the details. Incentive Stock Options (ISOs) give you a chance to buy shares in your company at a set price, which can be a great way to invest in your family’s future.
Here’s what you need to know:
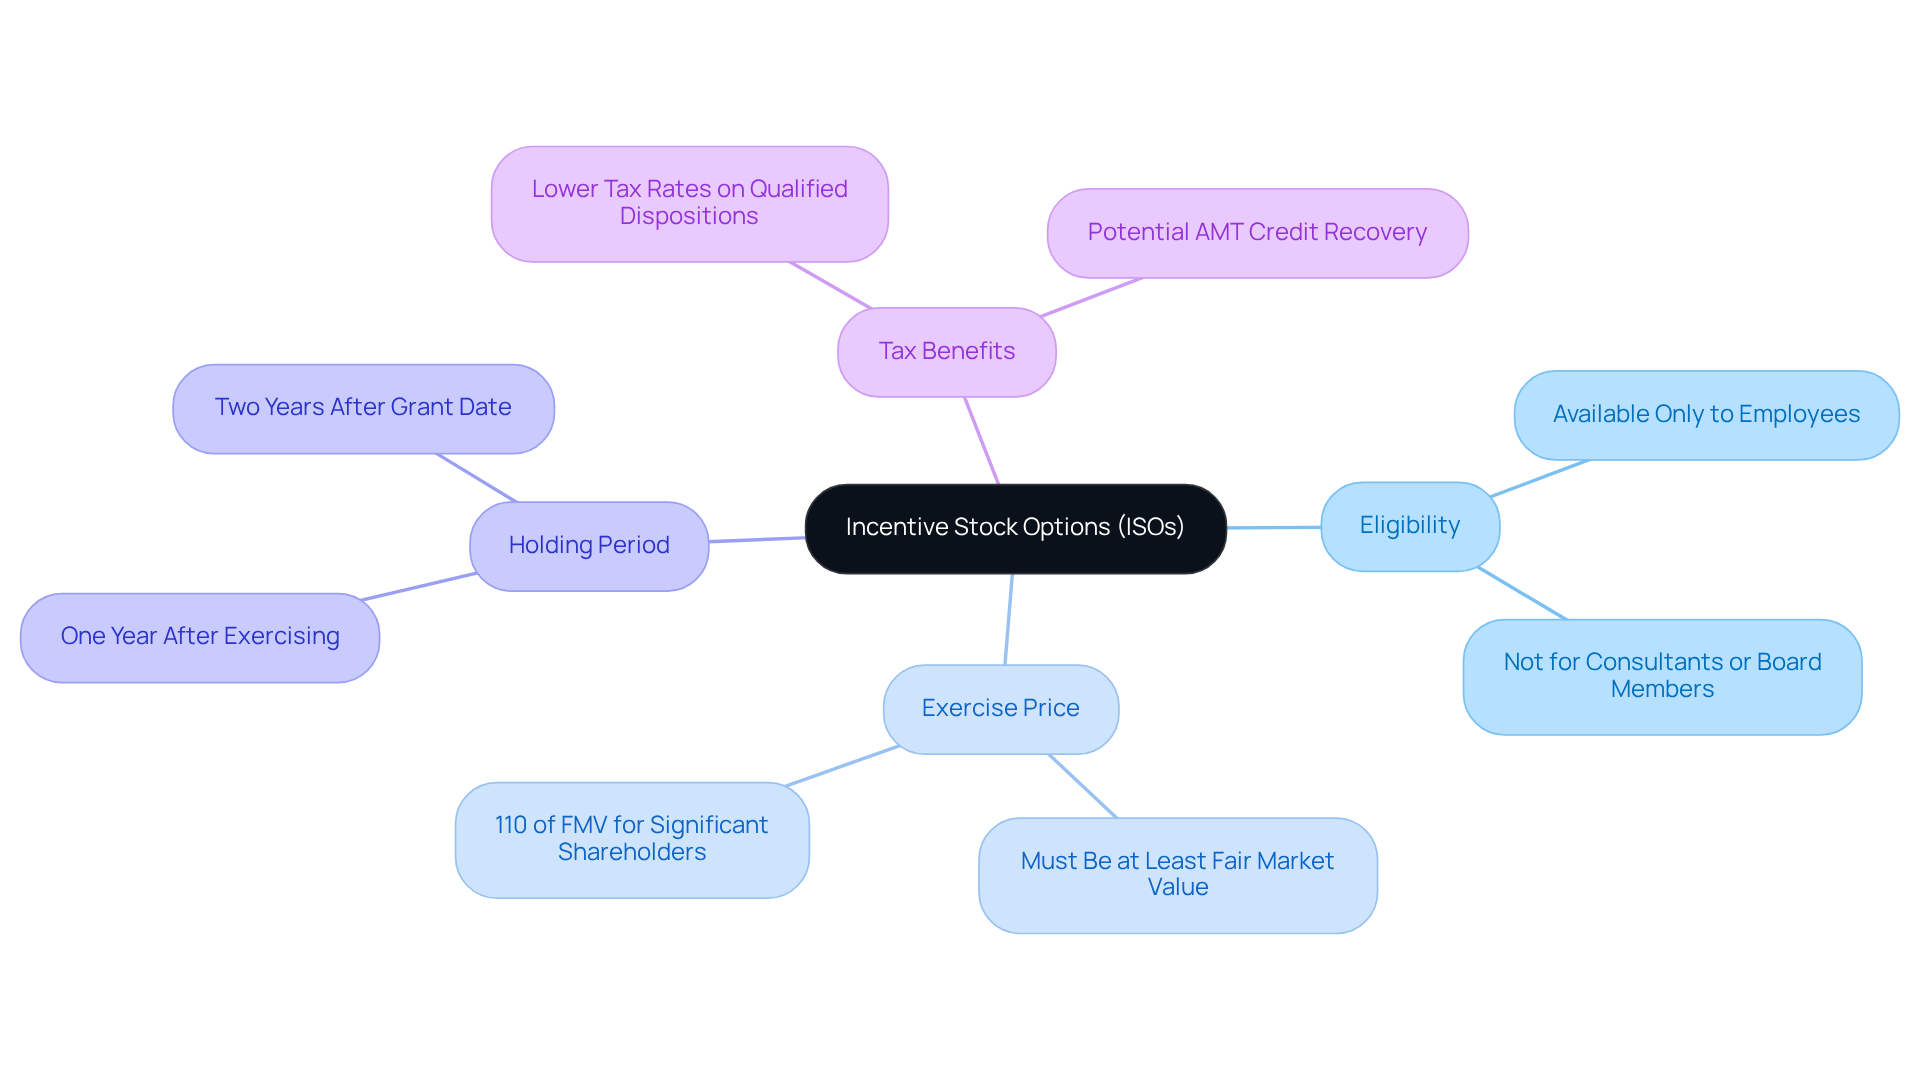
- Eligibility: ISOs are available only to employees, not consultants or board members.
- Exercise Price: The price you pay for the shares must be at least equal to their fair market value on the grant date.
- Holding Period: To enjoy the tax benefits, you’ll need to hold the shares for at least one year after exercising the options and two years after the grant date.
- Tax Benefits: When you hold onto those shares for the right amount of time, any profits you make could be taxed at a lower rate, which is a win for your family’s finances.
Navigating the world of employee stock options can feel overwhelming, particularly when trying to understand how to reduce taxes on incentive stock options. Grasping these basics will assist you in navigating the tax consequences and strategies related to how to reduce taxes on incentive stock options effectively. Understanding these options can empower you to make informed decisions that benefit your family’s financial well-being.
Explore Tax Implications and AMT for ISOs
Navigating the world of Incentive Stock Options can feel daunting, especially when learning how to reduce taxes on incentive stock options. Let’s explore some key points that can help you understand this better:
-
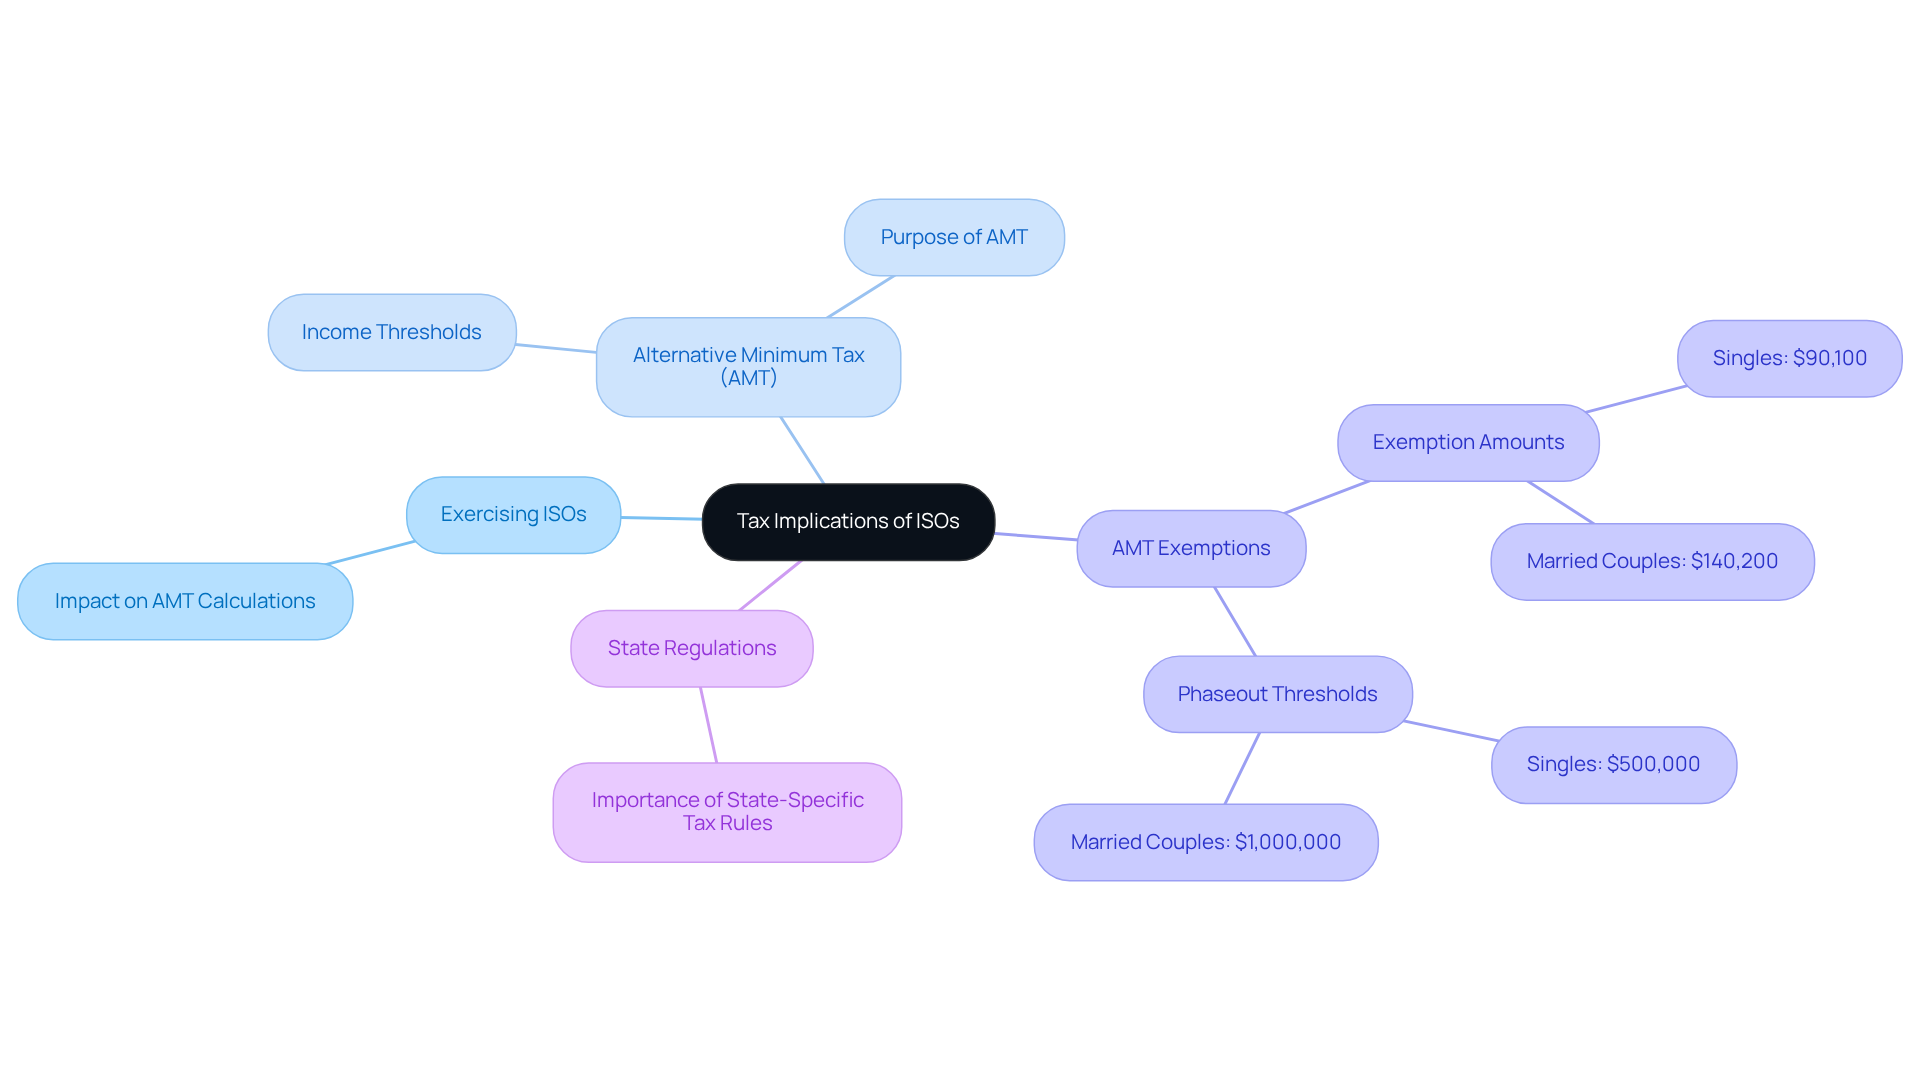
Typically, exercising your incentive stock options won’t trigger regular income tax right away. But, it’s important to know that the difference between what you pay and the stock’s value at exercise can affect your AMT calculations.
-
The Alternative Minimum Tax (AMT) is designed to ensure that those with higher incomes contribute a fair share. If your income from AMT goes beyond a certain threshold, you might find yourself facing AMT due to your stock options.
-
For 2026, the AMT exemption is $90,100 for singles and $140,200 for married couples, but keep in mind that phaseouts start at $500,000 for singles and $1,000,000 for couples.
-
If you do end up facing AMT from your stock options, understanding how to reduce taxes on incentive stock options could help you qualify for an AMT credit in the future. This credit can ease your tax burden when you sell the stock later, helping you manage your finances more effectively.
-
Remember, some states might have their own tax rules for Incentive Stock Options, so it’s wise to check those out. Taking a moment to review your state’s tax regulations can really help you plan better for your family’s future.
By grasping these tax implications, you can take steps to protect your family from unexpected financial surprises.
Implement Strategies to Minimize ISO Taxes
Imagine feeling confident about your financial future while understanding how to reduce taxes on incentive stock options.
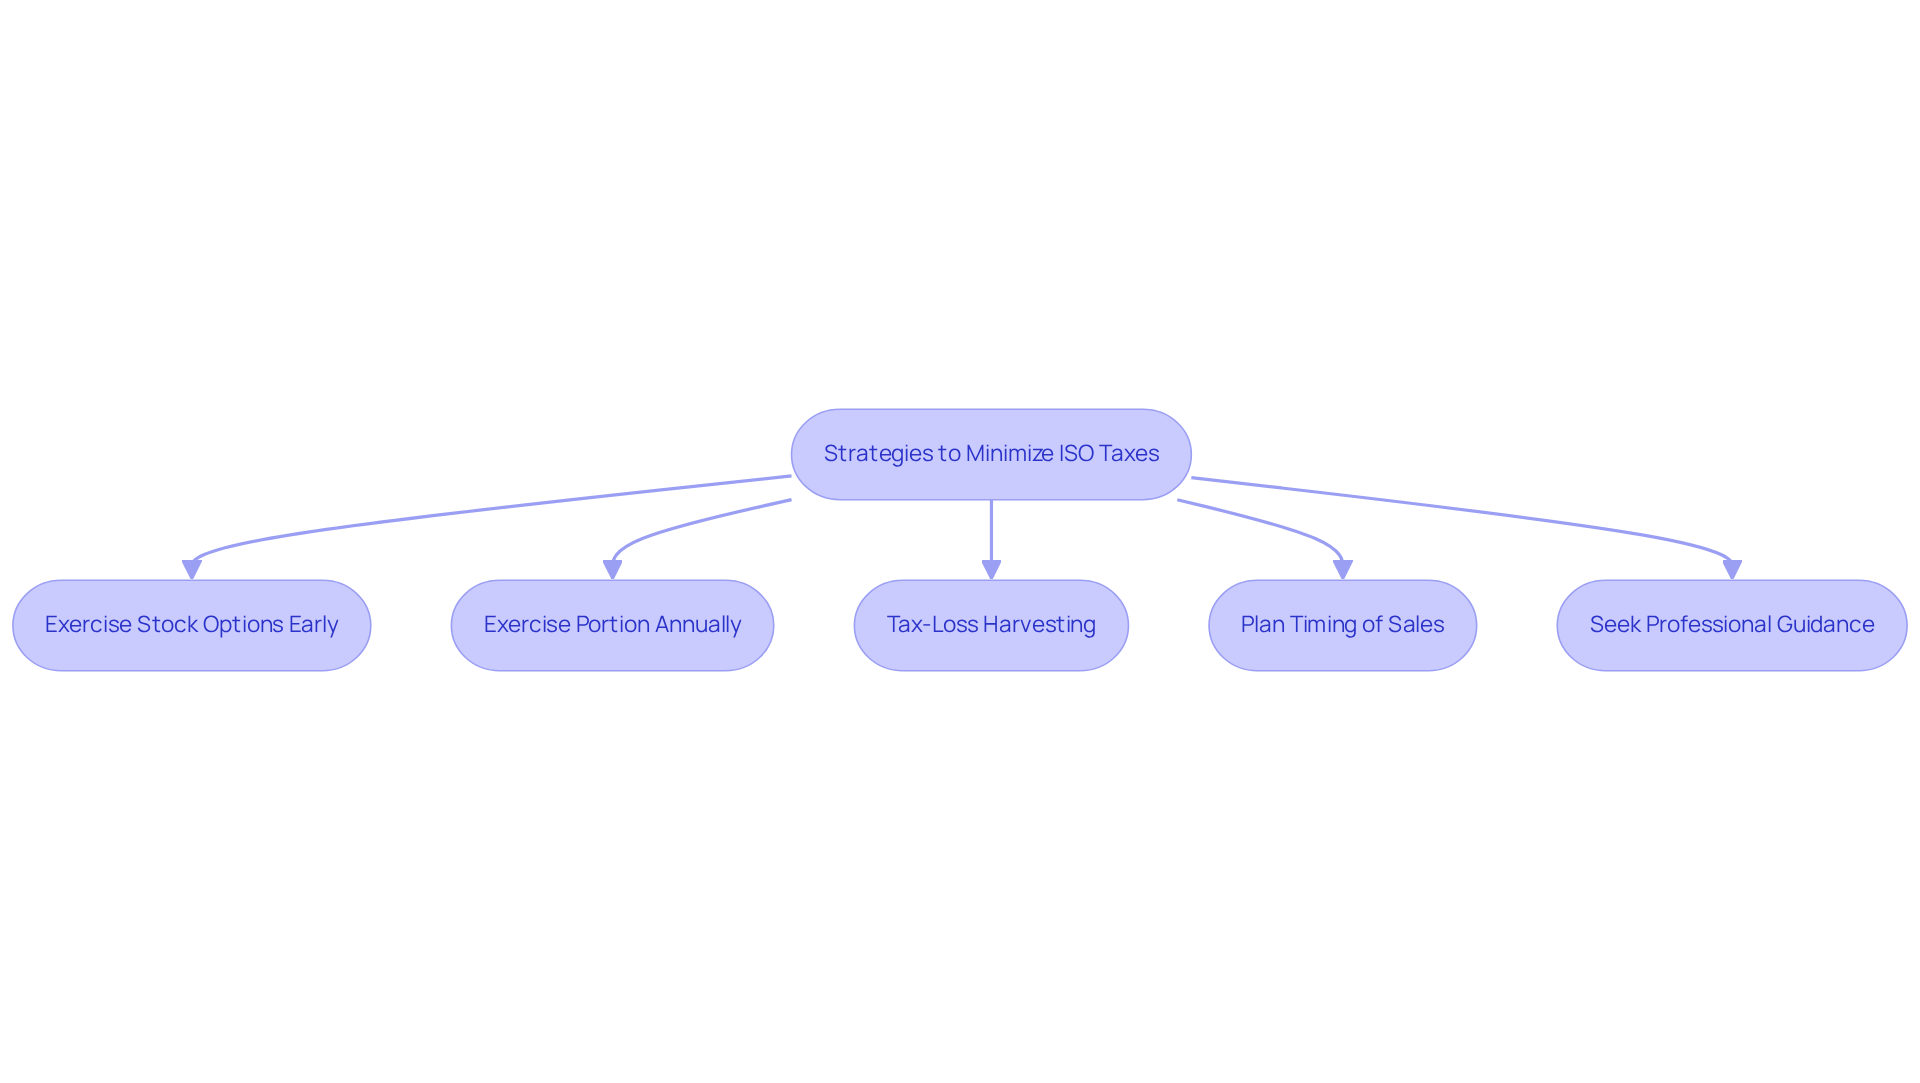
Exercising your stock options early in the year can be a smart move, especially if you expect a significant increase in stock value. Holding onto your shares for a while can help you qualify for long-term capital gains treatment, which usually means lower taxes.
To manage your exposure to the Alternative Minimum Tax (AMT), consider exercising only a portion of your incentive stock options each year. This way, you can stay below the AMT threshold and reduce your overall tax liability.
If you have other investments that aren’t performing well, selling them at a loss can offset gains from your incentive stock options. For instance, if you recognize a capital gain of $25,000 from your ISOs, selling another investment at a loss can lower your taxable income, potentially saving you thousands. Experts suggest that tax-loss harvesting can save families like yours an estimated $8,050 on taxes by offsetting capital gains with capital losses.
Carefully planning the timing of your stock sales is also crucial. If you can, wait until you meet the holding period requirements to benefit from lower capital gains tax rates. This can significantly lighten your tax burden when you eventually sell your shares. Just remember the wash-sale rule, which disallows losses if you repurchase substantially identical securities within 30 days of selling at a loss.
With these strategies, you can understand how to reduce taxes on incentive stock options and feel more secure about your financial future. For families like yours, seeking professional assistance from Bright Advisers can provide the guidance needed to navigate these complexities and enhance your wealth accumulation potential. Together, we can navigate this journey.
Optimize Timing for Exercising and Selling ISOs
Imagine facing the challenge of exercising your Incentive Stock Options while juggling family priorities and financial responsibilities. Timing is essential, and here are some strategies to help you optimize your timing:
-
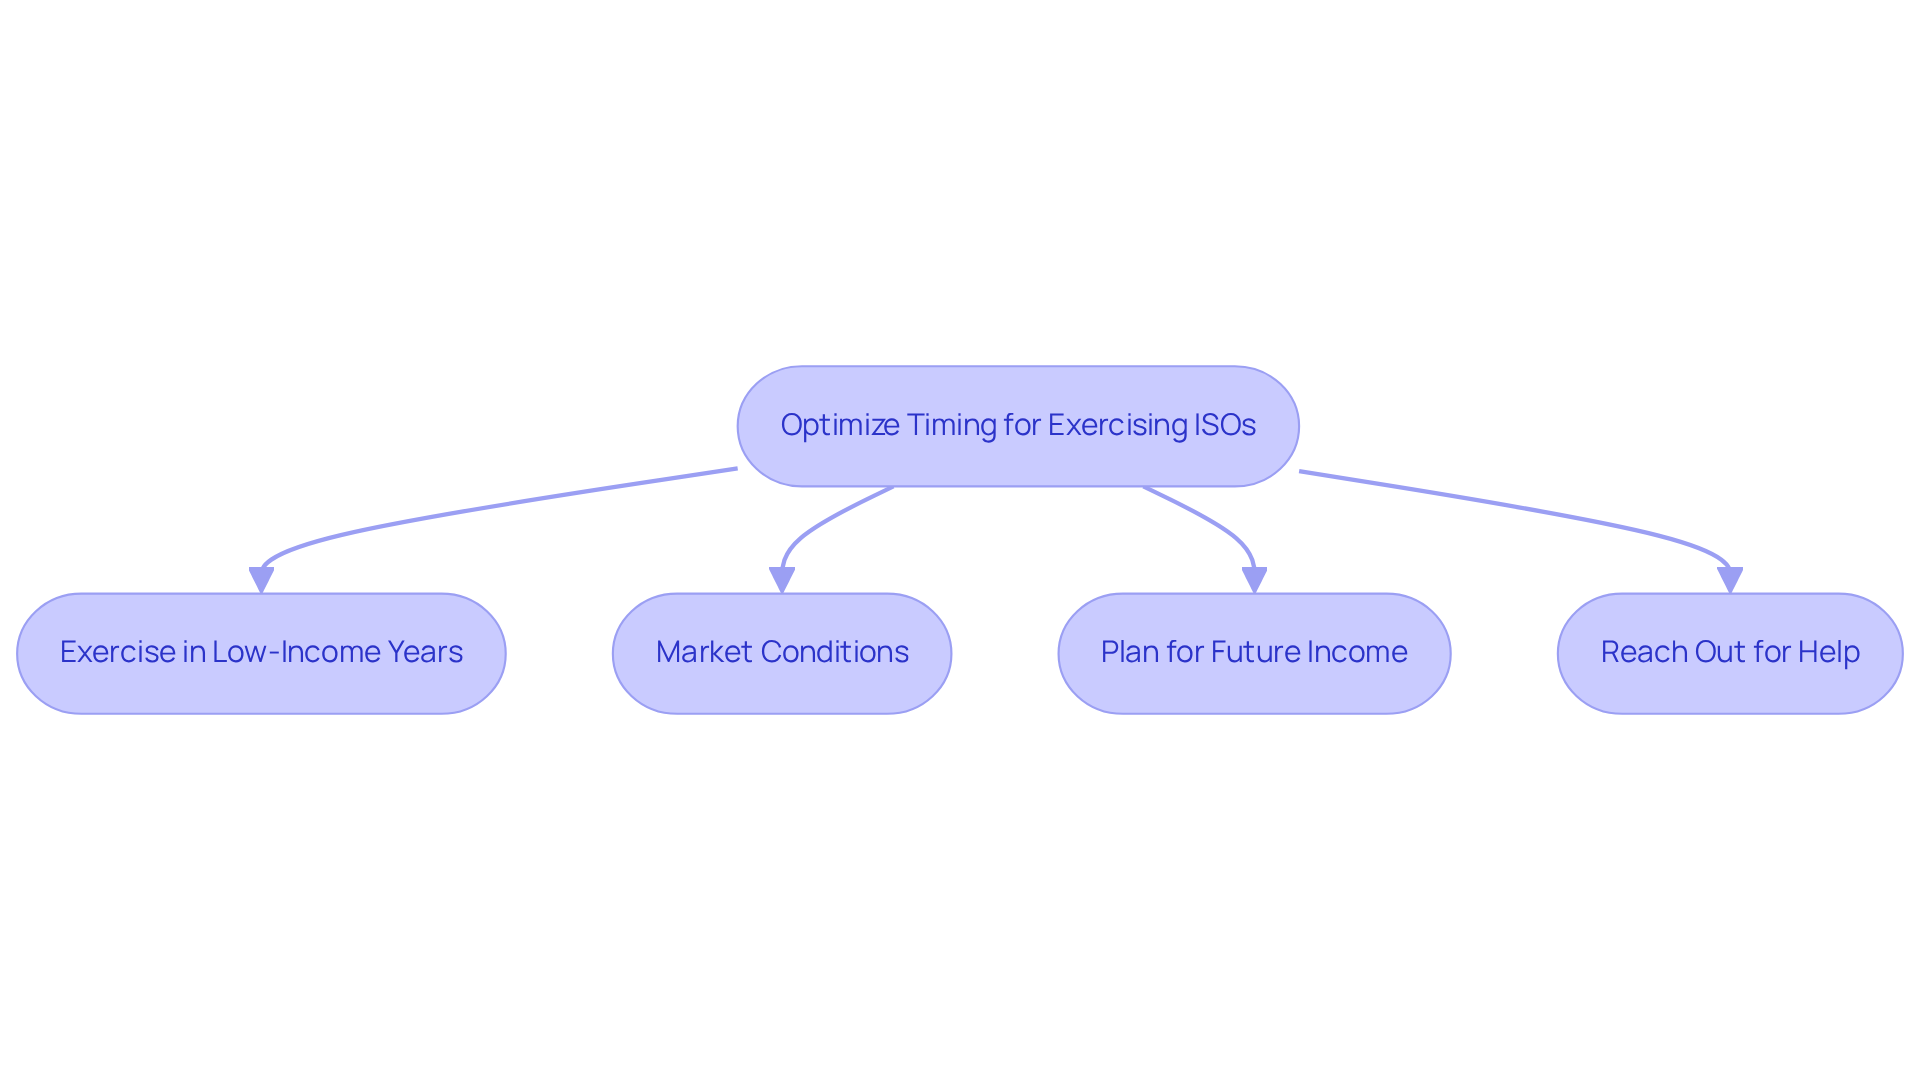
Exercise in Low-Income Years: If you think you’ll have a lower income this year, it might be a good idea to exercise your ISOs now. This can help reduce your exposure to the Alternative Minimum Tax (AMT), which represented nearly 73% of the total cost to exercise options in 2021. Exercising in a low-income year can teach you how to reduce taxes on incentive stock options and significantly lower your tax liability.
-
Market Conditions: Keep an eye on market conditions. If the share price looks good, it might be the right time to exercise and sell, especially if you’ve met the required holding period of one year after purchase and two years after the grant date. For example, if you exercise your option at $20 and sell at $85 after meeting these requirements, you’ll benefit from long-term capital gains treatment, avoiding immediate tax implications on the sale.
-
Plan for Future Income: Think about your future income projections. If you expect a significant rise in earnings, it may be wise to exercise your options before that increase to avoid higher financial obligations. Exercising stock options in a year when your income is lower can illustrate how to reduce taxes on incentive stock options, given that taxes accounted for 73% of the total cost to exercise stock options in 2021.
-
Reach Out for Help: Don’t hesitate to reach out to a tax expert who can help you navigate these waters. They can provide personalized insights based on your financial situation, ensuring you make informed decisions.
By taking the right steps now, you can secure a brighter financial future for your family.
Consult Professionals for Tailored Tax Advice
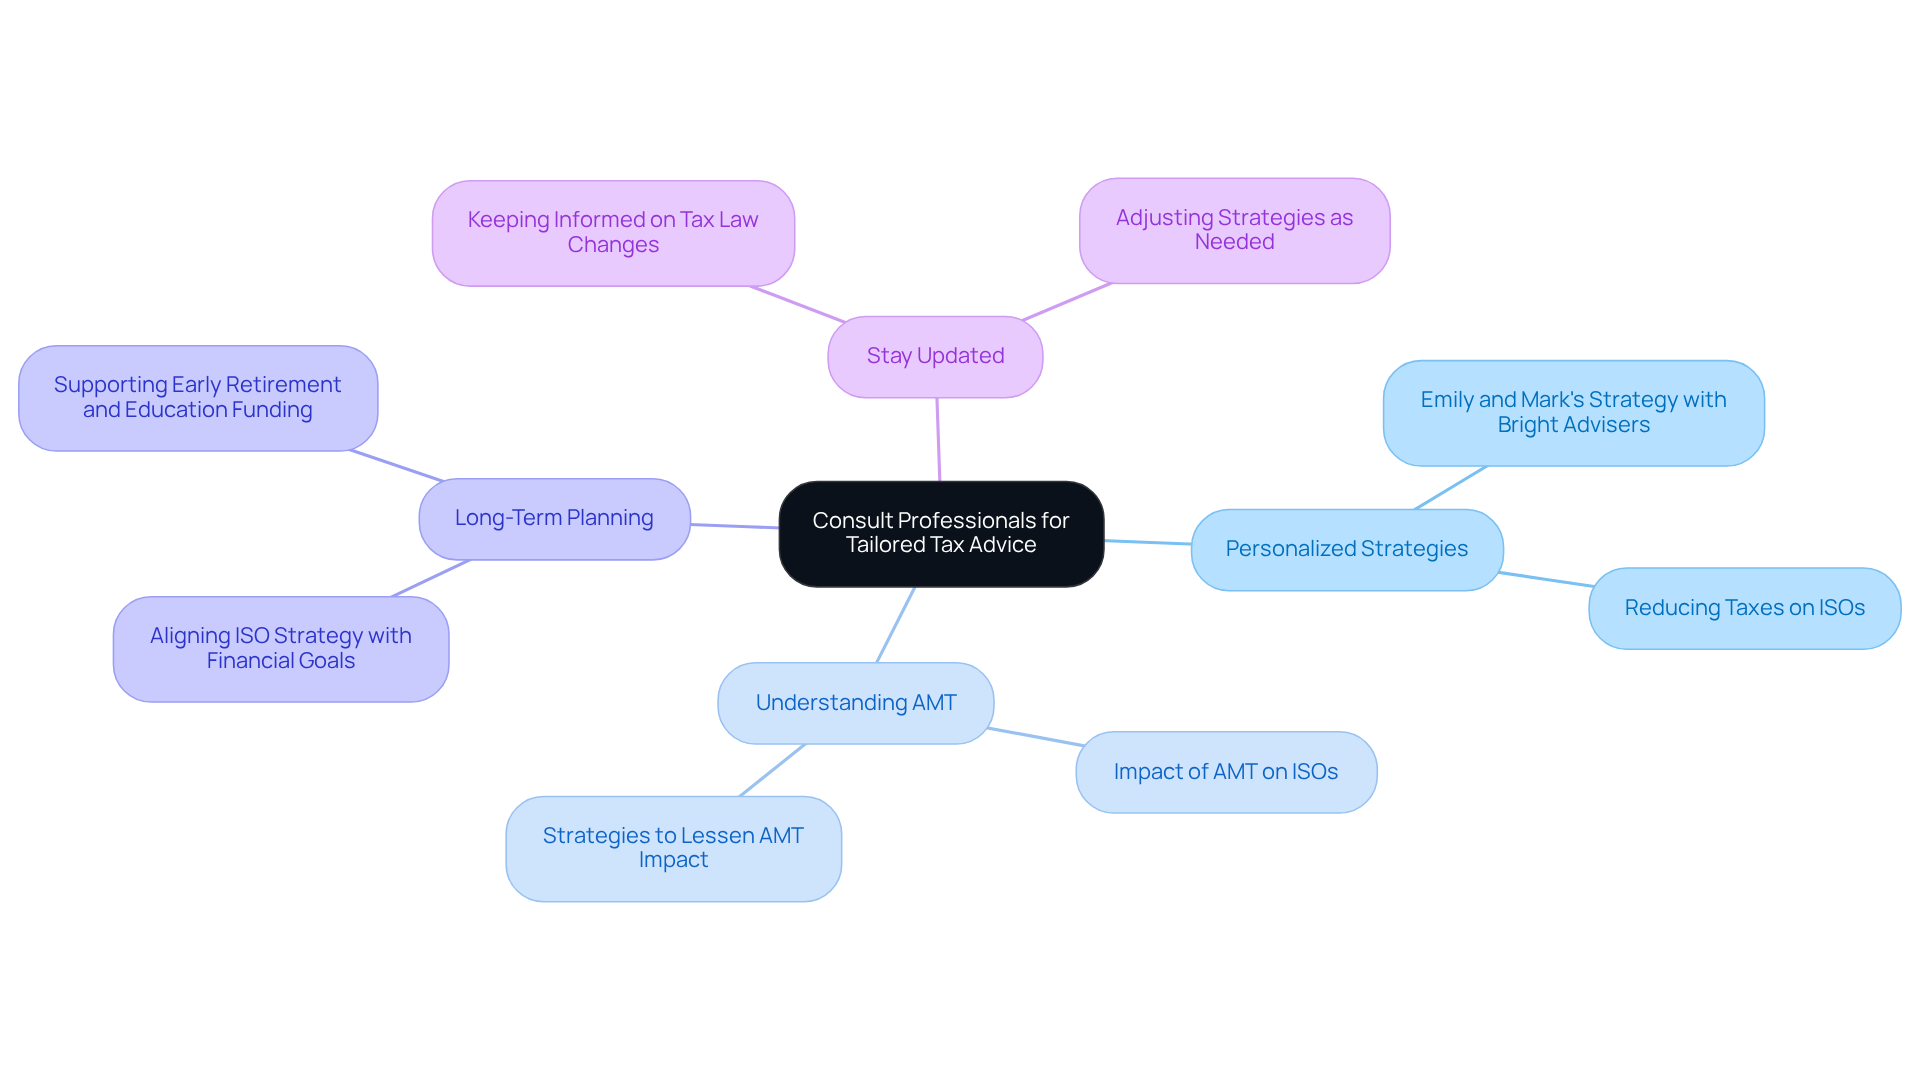
Imagine feeling overwhelmed by the tax implications of your Incentive Stock Options, just like Emily and Mark did. Navigating these complexities can be daunting, which is why seeking professional advice is so important for families striving for financial freedom. Here are some key reasons to consult a tax professional:
-
Tax professionals can create personalized strategies that show you how to reduce taxes on incentive stock options, tailored to your unique financial situation. For instance, Emily and Mark worked closely with Bright Advisers to develop a strategy that fit their specific needs, allowing them to manage their stock options with confidence.
-
Understanding AMT: Professionals offer valuable insights into how the Alternative Minimum Tax (AMT) affects your situation, guiding you on strategies to lessen its impact. Bright Advisers helped Emily and Mark grasp their AMT exposure, empowering them to make informed choices about their stock options.
-
Long-Term Planning: Partnering with a financial advisor ensures that your ISO strategy aligns with your broader financial goals, creating a cohesive approach to wealth management. Emily and Mark’s collaboration with Bright Advisers led to a comprehensive financial plan that supported their dreams of early retirement and funding their children’s education.
-
Stay Updated: Tax laws can change, and professionals stay informed about the latest regulations, ensuring compliance and the ability to seize new opportunities. Bright Advisers kept Emily and Mark in the loop about relevant tax changes, enabling them to adjust their strategies as needed.
Did you know that many families, like yours, turn to professionals for help with incentive stock options? You’re not alone in this journey. As Daniel Zajac, Managing Partner of the Zajac Group, wisely notes, ‘Understanding how to reduce taxes on incentive stock options is essential because they can greatly affect a client’s wealth and tax bill, particularly when the Alternative Minimum Tax (AMT) is involved.’ By consulting with professionals like Bright Advisers, families can transform confusion into confidence, paving the way for a brighter financial future.
Conclusion
Imagine feeling confident about your family’s financial future, knowing how to navigate the complexities of Incentive Stock Options (ISOs). When families understand ISOs – like who qualifies and how to exercise them – they can make choices that truly benefit their financial well-being. The tax benefits of ISOs can really change a family’s financial situation, so it’s important to approach these options with care.
Some helpful strategies include:
- Knowing when to exercise ISOs
- Being aware of the Alternative Minimum Tax (AMT)
- Using tax-loss harvesting to balance gains
These strategies can help families lower their tax bills and improve their financial situation. Talking to professionals like Bright Advisers can give families personalized advice that fits their unique financial needs, helping them navigate ISOs with confidence.
By understanding and managing the tax implications of ISOs, families can build a more secure financial future. We encourage families to seek guidance to navigate these challenges, ensuring they make the most of their stock options and protect their wealth for the future.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of employee stock option that allows employees to buy shares in their company at a set price, which can be a beneficial investment for their family’s financial future.
Who is eligible for ISOs?
ISOs are available only to employees of the company, not to consultants or board members.
What is the exercise price for ISOs?
The exercise price for ISOs must be at least equal to the fair market value of the shares on the grant date.
What are the holding period requirements for ISOs to receive tax benefits?
To enjoy tax benefits, you must hold the shares for at least one year after exercising the options and two years after the grant date.
What are the tax benefits of holding ISOs?
If you hold the shares for the required time, any profits made could be taxed at a lower rate, which can positively impact your family’s finances.
How does exercising ISOs affect regular income tax and AMT?
Exercising ISOs typically does not trigger regular income tax immediately, but the difference between the exercise price and the stock’s value at exercise can affect your Alternative Minimum Tax (AMT) calculations.
What is the Alternative Minimum Tax (AMT)?
The AMT is designed to ensure that individuals with higher incomes pay a fair share of taxes. If your AMT income exceeds certain thresholds, you may be subject to AMT due to your stock options.
What are the AMT exemption amounts for 2026?
For 2026, the AMT exemption is $90,100 for singles and $140,200 for married couples, with phaseouts starting at $500,000 for singles and $1,000,000 for couples.
How can understanding ISOs help with AMT credits?
If you face AMT due to your stock options, understanding how to reduce taxes on ISOs could help you qualify for an AMT credit in the future, which can reduce your tax burden when you sell the stock later.
Should I consider state tax rules for ISOs?
Yes, some states have their own tax rules for Incentive Stock Options, so it is advisable to review your state’s tax regulations to better plan for your family’s financial future.
List of Sources
- Understand Incentive Stock Options (ISOs)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Explore Tax Implications and AMT for ISOs
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- ISO Taxes: How AMT and AMT Credits Work + Avoiding AMT on ISO Exercises | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/tax-isos-amt-credits)
- AMT Exemption Amounts | Tax Notes (https://taxnotes.com/research/federal/reference-tables/amt-exemption-amounts/2zf7h)
- Mastering ISO and AMT Implications (https://trayecto.io/blog/mastering-isos-and-amt)
- Understanding the Alternative Minimum Tax | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/alternative-minimum-tax)
- Implement Strategies to Minimize ISO Taxes
- Tax-Loss Harvesting Strategies: How They Work (https://am.gs.com/en-us/advisors/campaign/tax-loss-harvesting-strategies-how-they-work)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- How to Cut Your Tax Bill with Tax-Loss Harvesting (https://schwab.com/learn/story/how-to-cut-your-tax-bill-with-tax-loss-harvesting)
- Continuous tax-loss harvesting yields more potential for tax benefits (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/continuous-tax-loss-harvesting-yields-more-potential-for-tax-savings)
- The economics of tax-loss harvesting (https://thetaxadviser.com/issues/2023/sep/the-economics-of-tax-loss-harvesting)
- Optimize Timing for Exercising and Selling ISOs
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- 6 Reasons to Exercise Your Incentive Stock Options When the Price Is Down (https://zajacgrp.com/insights/6-reasons-to-exercise-your-incentive-stock-options-even-when-the-price-is-down)
- What to Do with Stock Options: When to Exercise & Tax Planning Strategies (https://aspiriant.com/fathom/stock-options-exercise-tax-planning)
- 2021 State of Stock Options Report — Secfi (https://secfi.com/learn/2021-state-of-stock-options)
- Exercising Options (https://insight.kellogg.northwestern.edu/article/exercising_options)
- Consult Professionals for Tailored Tax Advice
- Incentive Stock Options Tax Planning Opportunities – GHJ (https://ghjadvisors.com/ghj-insights/incentive-stock-options-tax-planning-opportunities-and-pitfalls)
- Tax Planning Strategies for Incentive Stock Options (ISOs) (https://cbh.com/insights/articles/tax-planning-strategies-for-incentive-stock-options-isos)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- How Your Income May Influence a Qualified Sale of Incentive Stock Options (ISOs) – Zajac Group (https://zajacgrp.com/insights/how-your-income-may-influence-a-qualified-sale-of-incentive-stock-options-isos)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading