

Key Highlights
- A liquidity event occurs when a company’s equity becomes available for sale, impacting stock holdings and tax obligations.
- Types of liquidity events include IPOs, mergers, and acquisitions, each affecting stock differently.
- Stocks from liquidity events are taxed as regular income, with employers typically withholding 22% for federal taxes on RSUs up to $1 million.
- Capital gains tax applies to profits from stocks sold after vesting, with lower rates for shares held over a year.
- High-tax states like California and New York can significantly increase tax liabilities after liquidity events.
- Immediate tax strategies include adjusting withholding, selling holdings to cover taxes, tax-loss harvesting, and charitable contributions.
- Long-term tax management strategies involve diversification, retirement account contributions, regular tax reviews, and estate planning.
- Utilising tax planning software, engaging with fiduciary financial advisors like Bright Advisers, and accessing educational resources can enhance tax planning efforts.
Introduction
Imagine facing a sudden financial change and feeling overwhelmed by the tax implications that come with it. Understanding the financial landscape after a liquidity event can be daunting, especially for families navigating the complexities of stock options and restricted stock units (RSUs). Many families feel anxious about the financial decisions they face after a liquidity event.
With the potential for significant tax implications looming, it becomes crucial to explore effective strategies for reducing tax burdens following vesting. Together, we can explore effective strategies to manage taxes on liquidity, empowering your family to safeguard your financial future.
How can families feel prepared and confident in the face of unexpected tax bills, and what proactive measures can they take to optimize their financial outcomes? With the right strategies, families can feel confident and secure in their financial decisions.
Understand Liquidity Events and Their Tax Implications
Imagine a moment when your hard work pays off, but it comes with unexpected financial challenges. A liquidity event occurs when your company’s equity becomes available for sale, often through an IPO, acquisition, or merger. For families with stock options or restricted stock units (RSUs), learning how to reduce taxes on liquidity after vesting can help avoid significant tax consequences. Here’s what you need to know:
-
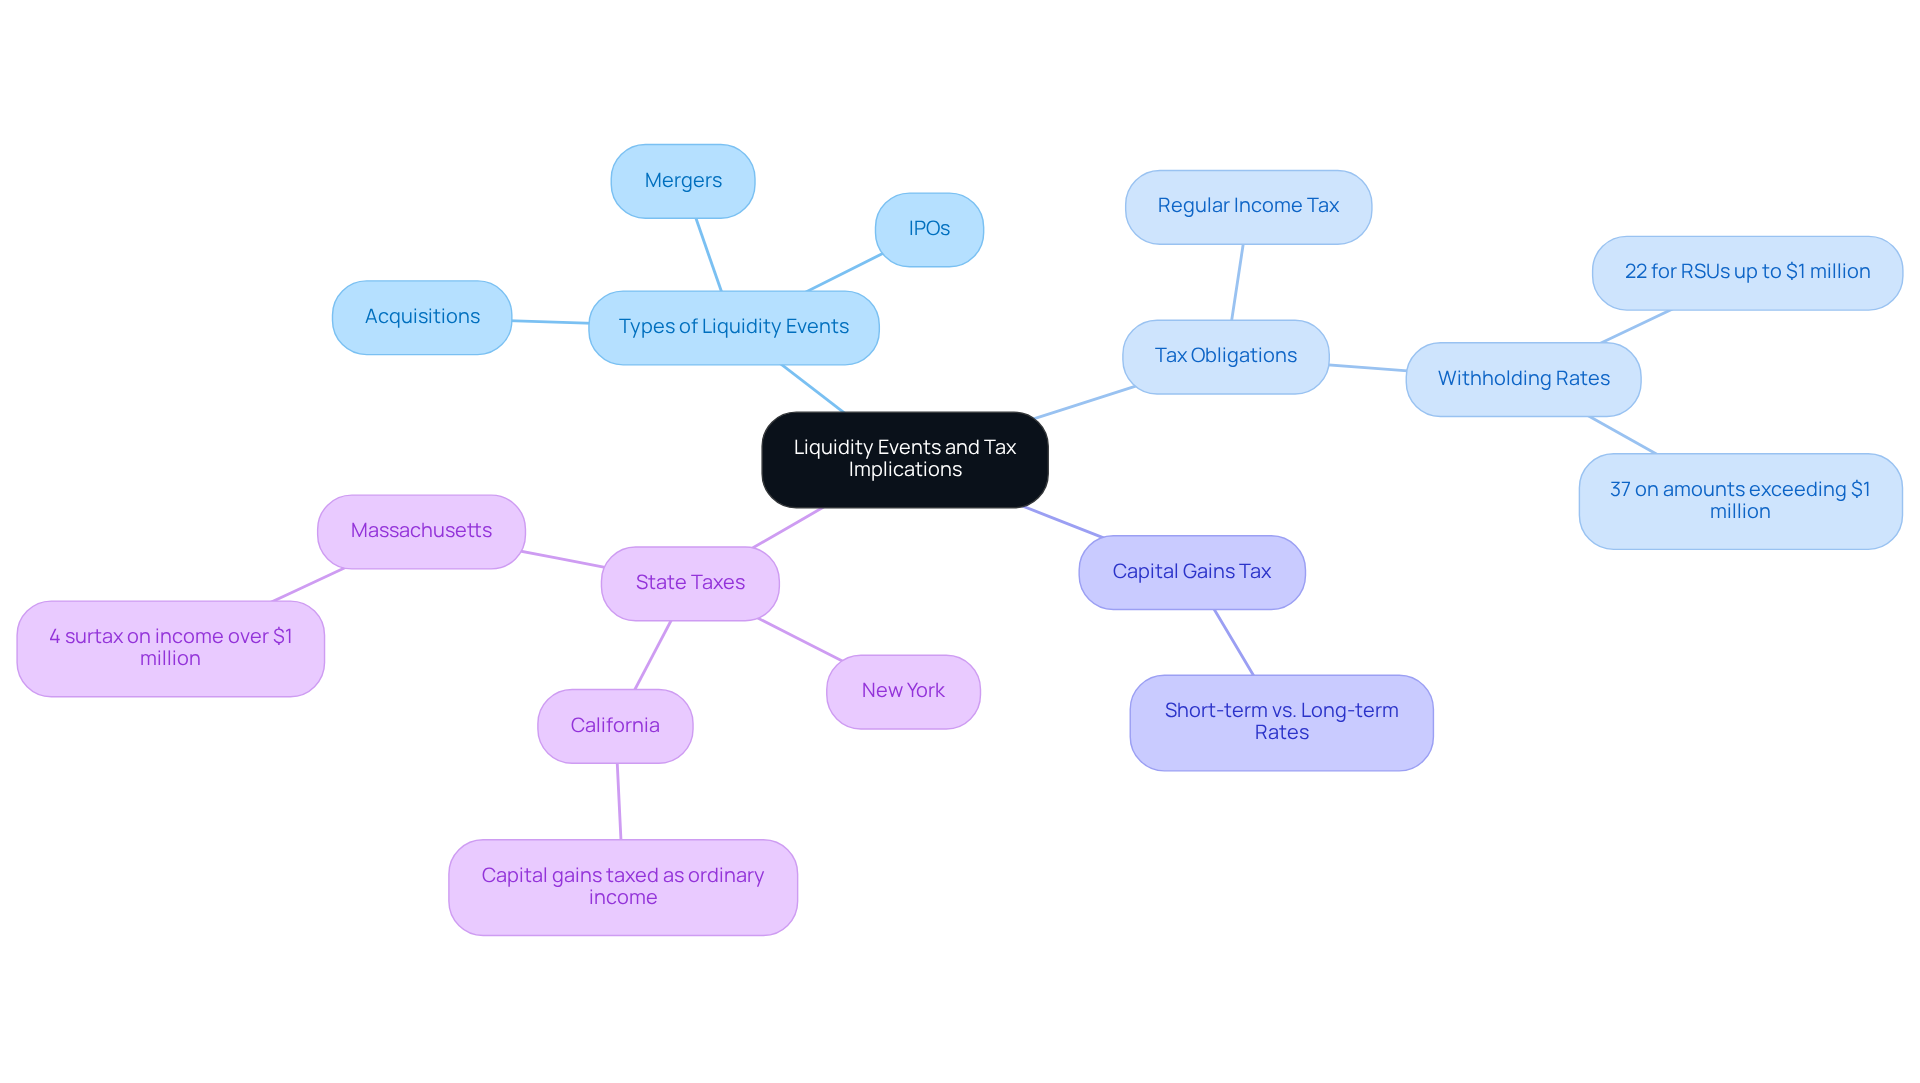
Types of Liquidity Events: Familiarize yourself with various liquidity events, including IPOs, mergers, and acquisitions, as each can impact your stock holdings differently. Common examples include selling a business or receiving a large inheritance.
-
When your stocks become available, it’s important to understand how to reduce taxes on liquidity after vesting, as they’ll be taxed as regular income, which can feel like a heavy burden at first. This can lead to a significant tax obligation, especially if you possess a large quantity of stocks. Employers typically withhold 22% for federal income taxes on RSUs up to $1 million in supplemental income, but understanding how to reduce taxes on liquidity after vesting is essential as this may not cover your total tax liability.
-
Capital Gains Tax: If you hold onto your stocks after they vest, any profit made when you sell them later will be subject to capital gains tax. The rate depends on how long you hold the shares before selling; shares held for over a year may qualify for lower long-term capital gains rates.
-
State Taxes: Be aware of how to reduce taxes on liquidity after vesting, particularly if you live in high-tax states like California or New York, where tax rates can significantly impact your overall tax liability. For instance, Massachusetts recently added a 4% surtax on income over $1 million, which can catch many business owners off guard after a liquidity event.
Without proper planning, you might find your family’s financial goals slipping away. By grasping these key points, you can feel more confident in preparing for the financial impact of liquidity events, ensuring your family’s future is secure. Engaging with financial professionals at Bright Advisers can provide valuable insights into managing newfound wealth through comprehensive financial management strategies, including budgeting, asset tracking, tax planning, retirement income strategies, and education funding. Handled together, this helps families navigate the complexities of tax implications effectively while preserving wealth across generations.
Implement Immediate Tax Strategies After Vesting
Imagine facing a tax bill that could impact your family’s financial stability – it’s a reality many parents encounter after their equity vests. Once your equity vests, it’s crucial to act swiftly to understand how to reduce taxes on liquidity after vesting. Here are some immediate strategies:
-
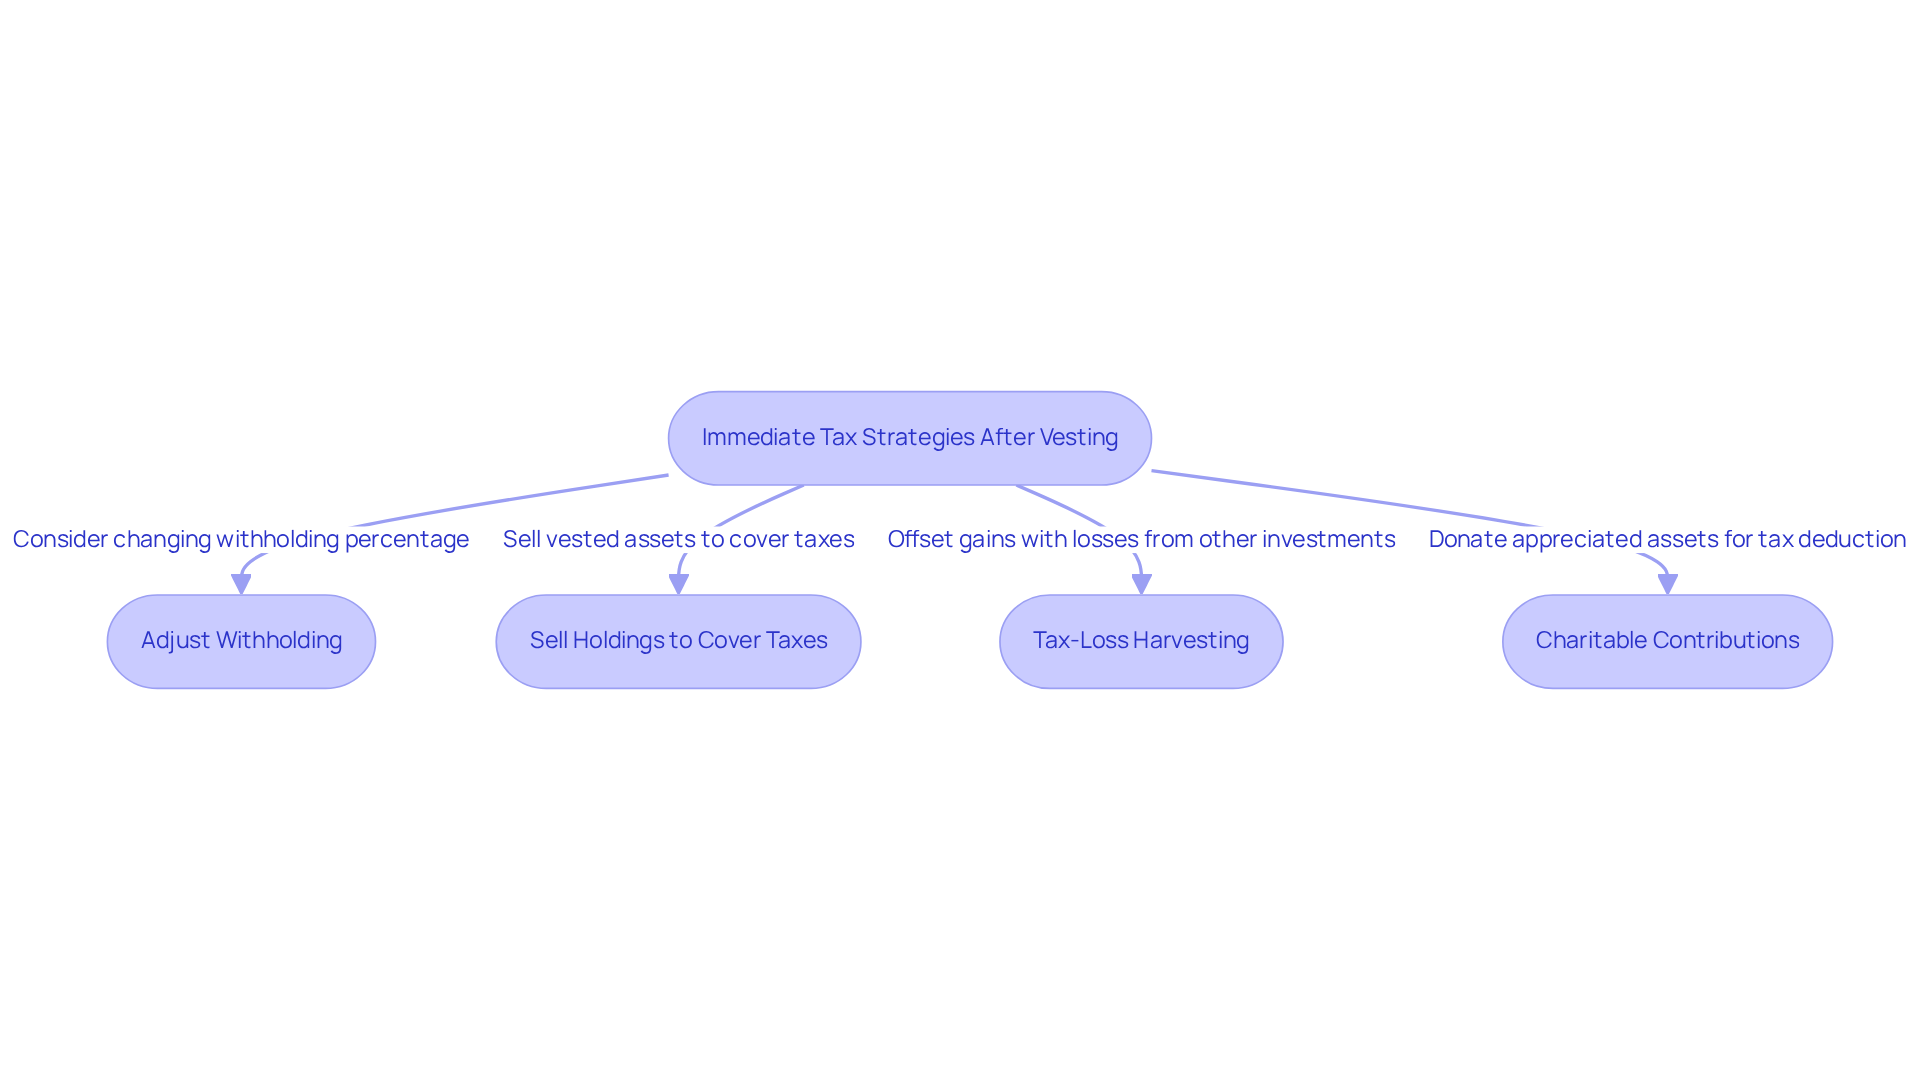
Adjust Withholding: If your employer allows it, think about changing your tax withholding percentage to cover the tax obligation from the vested units. The default withholding rate is usually 22%, but you might need to increase it based on your total income, especially if you expect to be in a higher tax bracket.
-
Sell Holdings to Cover Taxes: Selling a few of your vested assets can help cover those tax bills without putting extra strain on your budget. This method, known as sell-to-cover, is often automatic and simplifies tax payment for employees.
-
Tax-Loss Harvesting: If you have other investments that aren’t performing well, consider selling them to offset gains from your vested assets. This approach can help lower your overall tax obligation by balancing gains with losses.
-
Charitable Contributions: If you’re inclined to give, donating appreciated assets to charity can provide a tax deduction while avoiding capital gains tax on the appreciated value. This not only supports a good cause but also helps manage your tax exposure.
It’s easy to feel overwhelmed by tax obligations when all you want is to care for your family. Taking action right after your equity vests can help your family learn how to reduce taxes on liquidity after vesting and keep more of what you’ve earned. For instance, Sarah, who sold 42 shares at $352.44 each to cover $14,654.82 in taxes due, illustrates the importance of timely action in tax planning. If you wait too long, you might face surprise tax bills that could put a strain on your family’s budget. Understanding the implications of RSUs and their tax treatment can help you avoid unexpected tax bills, especially if your income might push you into a higher tax bracket. Taking these steps can help ensure your family’s financial future remains secure, allowing you to focus on what truly matters – your loved ones.
Establish Long-Term Tax Management Strategies
Imagine navigating the complexities of tax planning after a big financial change – it’s a challenge many families face. To ensure ongoing tax efficiency after a liquidity event, families can explore strategies on how to reduce taxes on liquidity after vesting that not only ease the burden but also align with their values.
-
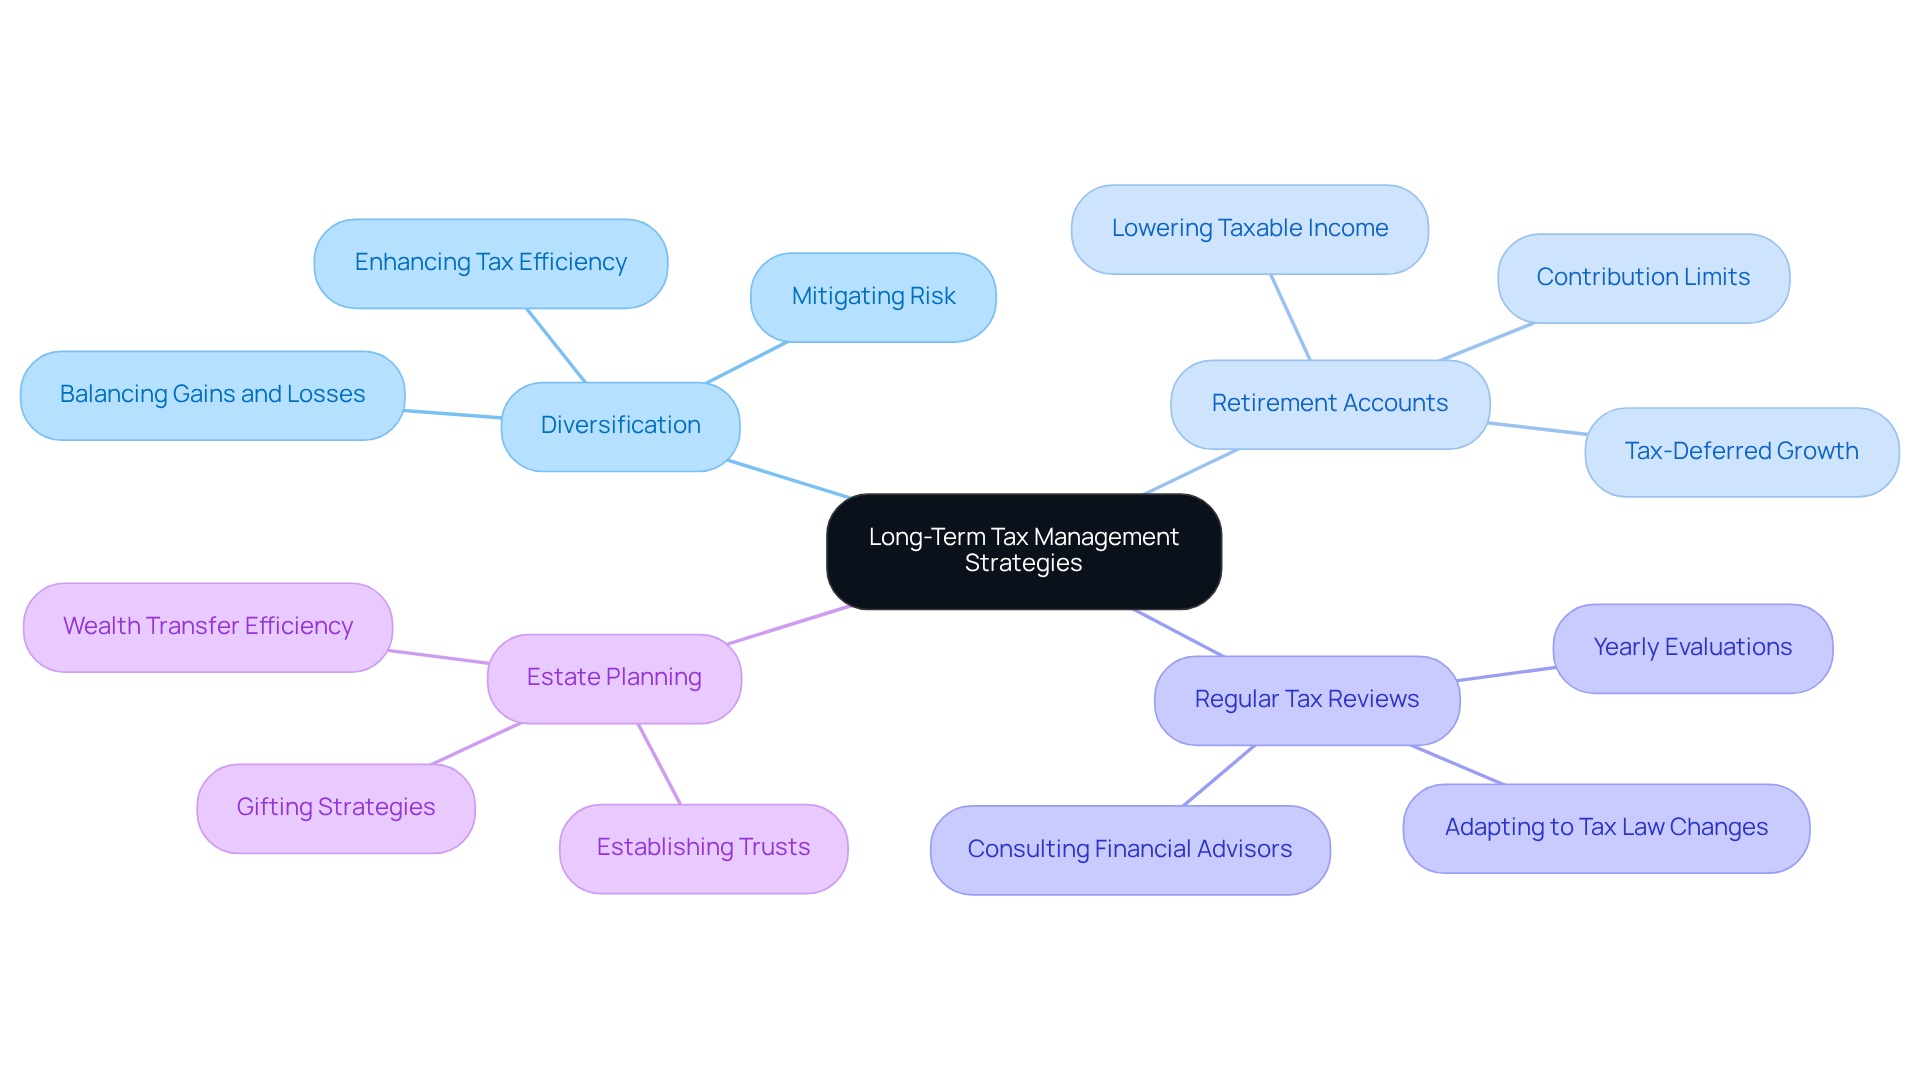
Diversification: Maintaining a diversified investment portfolio can help balance gains and losses across various asset classes. This approach not only mitigates risk but also enhances tax efficiency, reducing the overall tax burden.
-
Retirement Accounts: Think about how contributing to accounts like IRAs and 401(k)s can help your family save for the future while reducing your tax burden. These accounts allow for tax-deferred growth, which can significantly lower taxable income over time.
-
Regular Tax Reviews: It’s important to arrange yearly tax evaluations with a financial advisor. This way, you can assess your tax circumstances and modify your approaches as needed. Staying informed about changes in tax laws and personal circumstances is crucial for effective planning.
-
Estate Planning: Consider how thoughtful estate planning can help your family pass on wealth more easily. This may involve establishing trusts or employing gifting methods that align with your household’s financial objectives.
By implementing these long-term plans, households can develop a strong tax management approach that aligns with their financial goals and prepares them for upcoming liquidity events, particularly focusing on how to reduce taxes on liquidity after vesting. For example, utilizing tax-loss harvesting can enable households to offset gains with losses, potentially lowering their overall tax liability. Moreover, integrating philanthropic giving approaches can offer prompt tax advantages while aiding causes significant to the household.
With the right strategies in place, you can turn tax planning into a pathway for your family’s future success.
Access Tools and Resources for Effective Tax Planning
Navigating tax planning can feel overwhelming, especially when you’re juggling family responsibilities and financial goals. To support your tax planning efforts, consider utilizing the following tools and resources:
-
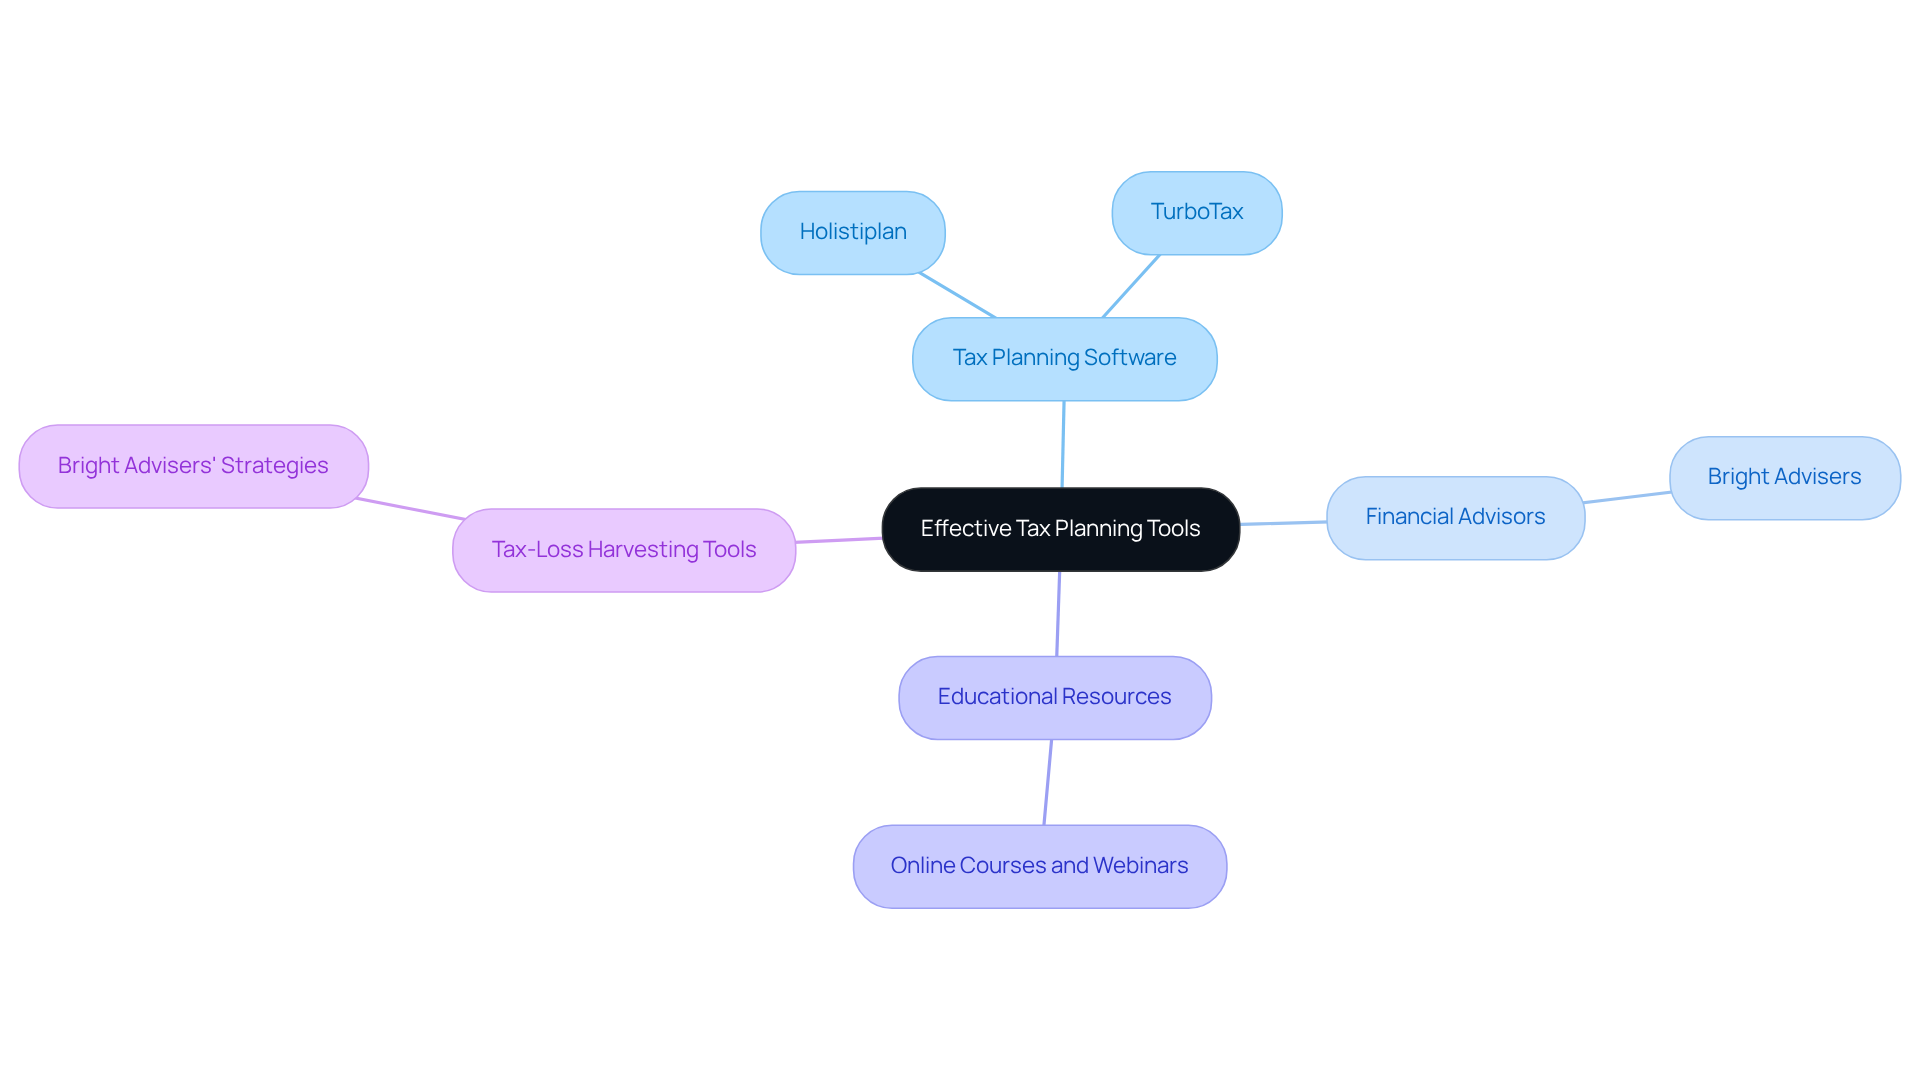
Tax Planning Software: Imagine having a platform like Holistiplan or TurboTax at your fingertips. These tools simplify the process of calculating taxes owed and identifying potential deductions. Holistiplan is known for its efficiency, helping advisors process financial data quickly and accurately.
-
Financial Advisors: It’s important to engage with a fiduciary financial advisor who specializes in tax planning. Bright Advisers has helped families like Emily and Mark achieve financial independence by crafting personalized plans tailored to their unique situations. Their thorough assessment of income, expenses, assets, and liabilities led to a clear understanding of financial goals, allowing them to make work optional.
-
Educational Resources: Explore online courses or webinars focused on tax planning for households. Websites like Bright Advisers offer valuable insights that can boost your financial literacy, empowering you to make informed decisions.
-
Tax-Loss Harvesting Tools: Consider platforms that provide tax-loss harvesting services. Bright Advisers uses these strategies to help families manage their investments effectively, reducing tax liabilities while enhancing portfolio performance.
With these helpful tools and resources, you can feel more confident in your tax planning and be ready for whatever comes next, just like Emily and Mark did with Bright Advisers by their side.
Conclusion
Imagine navigating the complexities of taxes after a liquidity event with confidence and clarity. Understanding how to effectively manage taxes is crucial for families looking to secure their financial future. Many families feel overwhelmed by the complexities of tax obligations after a liquidity event. But with the right strategies, they can navigate these challenges with confidence. This proactive approach not only helps in minimizing tax liabilities but also ensures that families retain more of their hard-earned wealth.
Key strategies to consider include:
- Adjusting tax withholdings
- Utilizing sell-to-cover options
- Engaging in tax-loss harvesting
Additionally, long-term planning through:
- Diversification
- Retirement accounts
- Regular tax reviews
can significantly enhance tax efficiency. Families are encouraged to leverage tools and resources, such as tax planning software and the expertise of fiduciary advisors like Bright Advisers, to streamline their financial management processes.
It’s clear that effective tax planning is essential for families. By taking informed actions and seeking professional guidance, families can transform potential tax burdens into opportunities for growth and stability. By embracing these strategies, families can focus on creating lasting memories while building a secure future for their children.
Frequently Asked Questions
What is a liquidity event?
A liquidity event occurs when a company’s equity becomes available for sale, often through an IPO, acquisition, or merger. It can also include selling a business or receiving a large inheritance.
How are stock options and restricted stock units (RSUs) taxed during a liquidity event?
When stocks become available after vesting, they are taxed as regular income. Employers typically withhold 22% for federal income taxes on RSUs up to $1 million in supplemental income, but this may not cover the total tax liability.
What is capital gains tax and how does it apply to liquidity events?
Capital gains tax is applied to any profit made when selling stocks after they vest. The tax rate depends on how long the shares are held; shares held for over a year may qualify for lower long-term capital gains rates.
How do state taxes affect liquidity events?
State taxes can significantly impact overall tax liability, especially in high-tax states like California or New York. For example, Massachusetts has a 4% surtax on income over $1 million, which can surprise many business owners after a liquidity event.
Why is it important to plan for taxes after a liquidity event?
Without proper planning, families may face significant tax obligations that could jeopardize their financial goals. Understanding tax implications helps ensure that families can manage their newfound wealth effectively.
How can Bright Advisers assist families in managing the financial impact of liquidity events?
Bright Advisers provides valuable insights into managing newfound wealth through comprehensive financial management strategies, including budgeting, asset tracking, tax planning, retirement income strategies, and education funding, ensuring families navigate tax complexities effectively while preserving wealth across generations.
List of Sources
- Understand Liquidity Events and Their Tax Implications
- Tax Planning for Liquidity Events: Avoid Costly Cash Mistakes (https://kahnlitwin.com/blogs/tax-blog/whats-the-real-cost-of-holding-cash-tax-planning-for-liquidity-events)
- Liquidity Events and Sunsetting TCJA Provisions (https://cohnreznick.com/insights/liquidity-events-and-the-upcoming-sunsetting-of-relevant-tcja-provisions)
- What is an RSU? How They Work, Benefits, & Taxes (https://carta.com/learn/equity/rsu)
- Navigating Liquidity Events: Key Insights for IPOs, M&As and Buyouts (https://aspiriant.com/fathom/guide-to-major-financial-events)
- Restricted Stock Units: Taxes, Vesting and Key RSU Facts | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/restricted-stock-units)
- Implement Immediate Tax Strategies After Vesting
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- RSUs Vesting: Should You Sell or Hold? Tax Tips and Planning Strategies – Apollon Financial (https://apollonfinancial.com/rsu-vesting-sell-or-hold-tax-tips-merck)
- Why Rising Stock Prices Can Lead to RSU Underwithholding (https://brightonjones.com/blog/rsu-underwithholding)
- Sell-to-Cover Restricted Stock Units (RSUs): Your Withholding Options (https://summitry.com/blog/rsu-sell-to-cover-strategy)
- 2025 Update: Tech Company Stock Pay Accounts for One-Quarter of Withholding Growth So Far in 2025-26 [EconTax Blog] (https://lao.ca.gov/LAOEconTax/Article/Detail/843)
- Establish Long-Term Tax Management Strategies
- Tax Planning Strategies to Grow and Protect Family Wealth – BCR Wealth Strategies (https://bcrwealth.com/tax-planning/tax-planning-strategies-to-grow-and-protect-family-wealth)
- Tax Diversification and Tax Efficient Investing | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/tax-diversification.html)
- Navigating Liquidity Events: Tax‑Efficient Strategies for Thoughtful Wealth Planning | PeakSpan Master Classes (https://peakspancapital.com/resources/master-classes/navigating-liquidity-events-tax-efficient-strategies-for-thoughtful-wealth-planning)
- Tax-Efficient Investing in 2025: Strategies for Minimizing Tax Implications — Cornerstone Wealth Group (https://cwgadvisors.com/blog/tax-efficient-investing-strategies-for-minimizing-tax-implications)
- Five Strategies for Tax-Efficient Investing Diversification – First Western Trust Bank (https://myfw.com/articles/five-strategies-for-tax-efficient-investing-diversification)
- Access Tools and Resources for Effective Tax Planning
- Best Tax Planning Software for Financial Advisors (2026 Comparison) (https://incomelaboratory.com/tax-planning-software-advisors-2026)
- The best tax software of 2026 (https://cnbc.com/select/best-tax-software)
- A Financial Advisor’s Role in Tax Planning (https://savantwealth.com/savant-views-news/article/a-financial-advisors-role-in-tax-planning)
- Holistiplan | Award-Winning Software for Tax Planning, Estate, and Insurance. (https://holistiplan.com)
- How to Evaluate Tax Planning Software: A Criteria-Driven Guide for Financial Advisors (https://wealth.com/resources/articles/how-to-evaluate-tax-planning-software-a-criteria-driven-guide-for-financial-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading