

Key Highlights
- An Employee Stock Purchase Plan (ESPP) allows employees to buy company shares at a discount, fostering ownership and investment in their future.
- Discounts on shares typically range from 5% to 15%, with 85% of companies offering a 15% discount.
- Eligibility for ESPPs generally includes full-time employees, with technology and finance sectors having the highest participation rates.
- Enrolment occurs during specific periods, and educational programmes are crucial to inform employees about the benefits of ESPPs.
- Tax implications include ordinary income from discounts and capital gains taxes based on the holding period of the stocks.
- Form 3922 is essential for reporting ESPP transactions accurately, detailing the purchase and discount received.
- Common reporting issues include missing ESPP income on W-2 forms, incorrect cost basis, and disqualifying dispositions, which can lead to higher tax liabilities.
- Consulting a tax professional is advisable for personalised guidance on ESPP taxation and reporting.
Introduction
Imagine feeling empowered to make the most of your Employee Stock Purchase Plan, turning confusion into confidence for your family’s financial future. These plans offer a unique opportunity to invest in a company at a discounted rate, but they also come with specific tax implications that can significantly impact your overall earnings.
But many families feel lost when it comes to understanding the intricacies of their Employee Stock Purchase Plans. How can you navigate the complexities of tax reporting while maximizing the benefits of your ESPP? Together, we can navigate this journey, helping you confidently manage your investments and avoid common pitfalls.
Understand Employee Stock Purchase Plans (ESPP)
Imagine a way to invest in your family’s future while feeling secure in your financial choices. An Employee Stock Purchase Program (ESPP) offers just that, allowing you to buy shares of your company at a reduced cost through payroll deductions. This initiative not only fosters employee ownership but also encourages you to invest in your own future.
Let’s explore some key benefits that can make a real difference for your family:
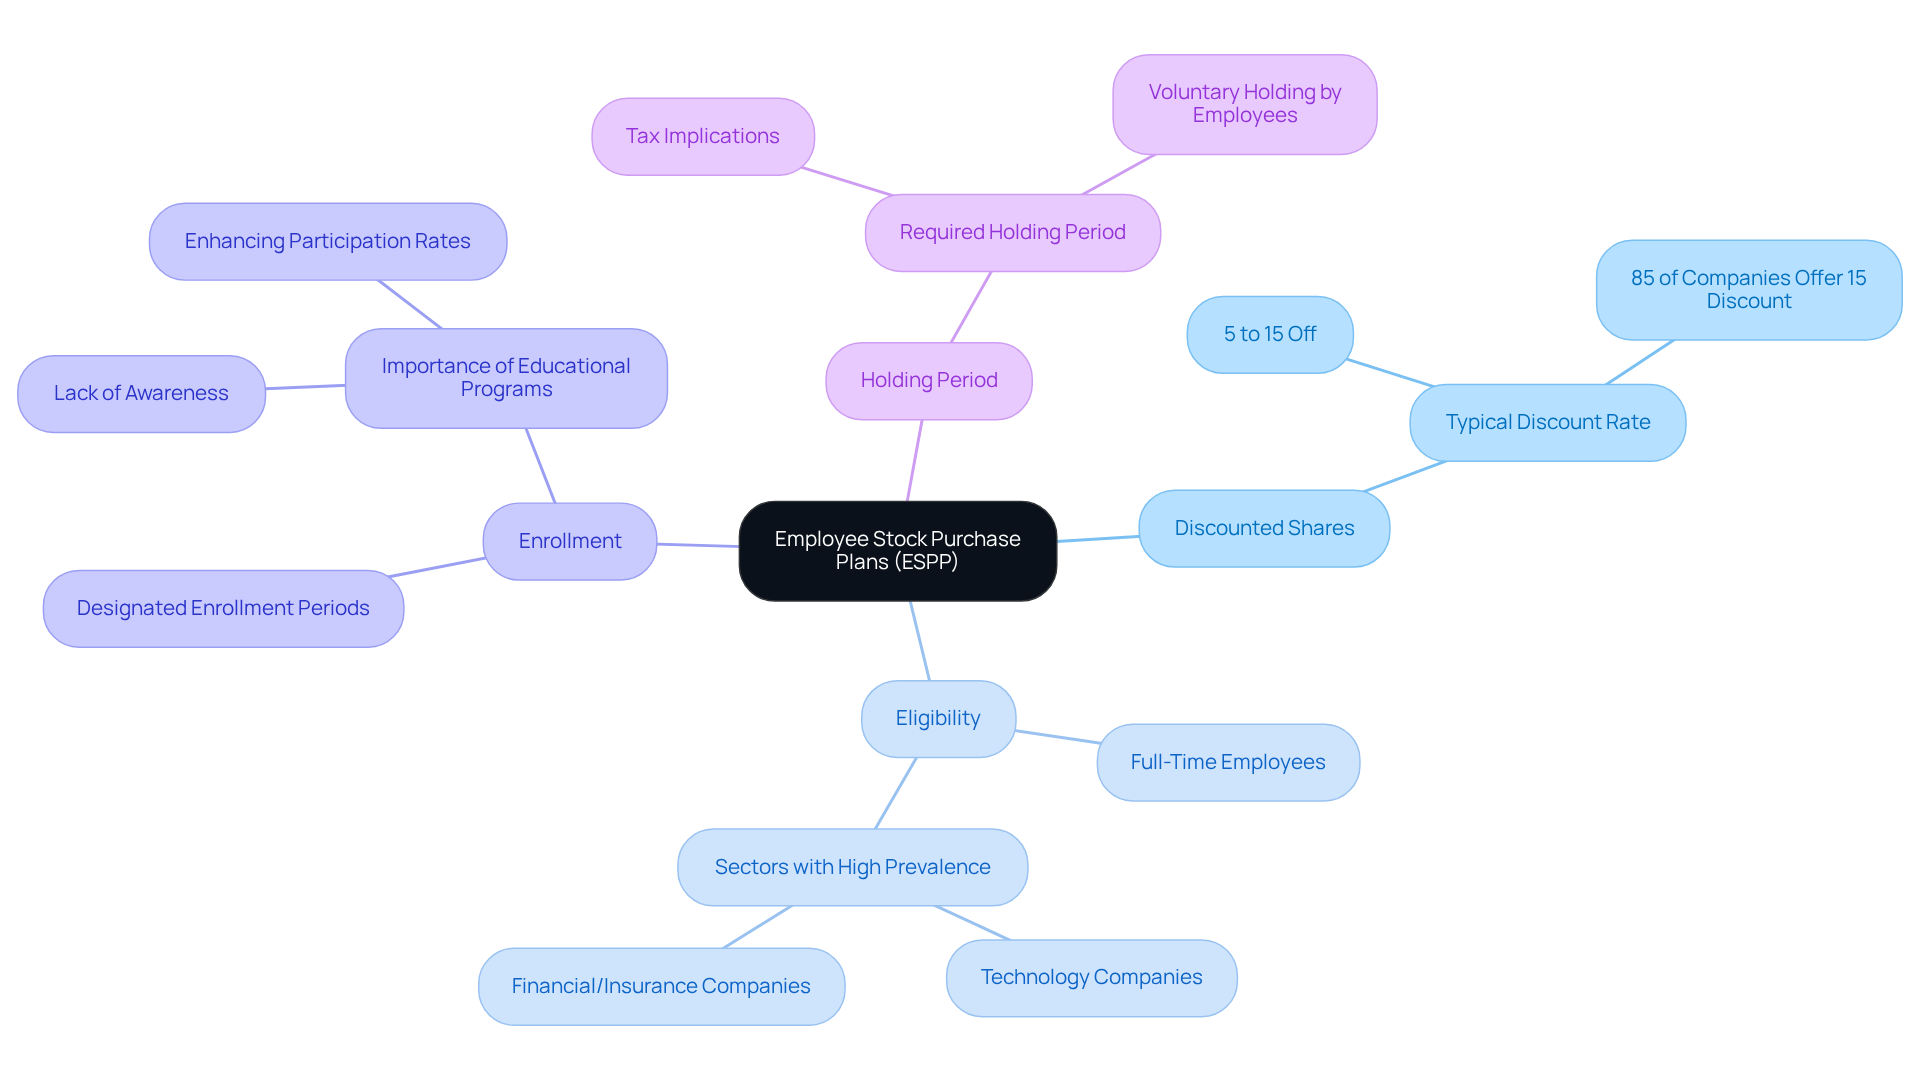
- Discounted Shares: You can purchase shares at a price lower than the market value, often between 5% to 15% off. Recent data shows that 85% of companies with qualified ESPPs offer a 15% discount, which is a significant increase from previous years.
- Eligibility: Most companies extend these plans to full-time employees, although eligibility criteria may vary. Notably, technology and financial sectors exhibit the highest prevalence of ESPPs, reflecting their importance for families.
- Enrollment: You typically enroll during designated periods and can choose the percentage of your salary to contribute. A robust educational program is essential to ensure you understand the benefits of participation, as many families miss out due to a lack of awareness.
- Holding Period: Depending on the plan, there may be a required holding period before selling the stocks, which can influence tax implications. This shows that many families trust these investments, holding onto their shares for a year or more, which can be a comforting choice for your financial future.
Understanding these components is crucial for accurately declaring any earnings from your ESPP reported on W2 on your tax return, especially for families looking to enhance their financial strategies. For example, Jay and Emma, a couple aiming to alleviate financial stress while preparing for their children’s schooling and their retirement, could gain greatly from joining an employee stock purchase plan. Furthermore, a 15% discount and lookback feature can yield an almost guaranteed return of 17.6% or more over a short period, making ESPPs an attractive option for young families.
By embracing these opportunities, you can pave the way for a brighter future for your family, filled with possibilities and peace of mind.
Identify Tax Implications of ESPP Shares
Imagine the relief of knowing exactly how your Employee Stock Purchase Plan (ESPP) can benefit your family’s financial future. When participating in an ESPP, understanding the tax implications is essential for making informed decisions that support your family’s goals.
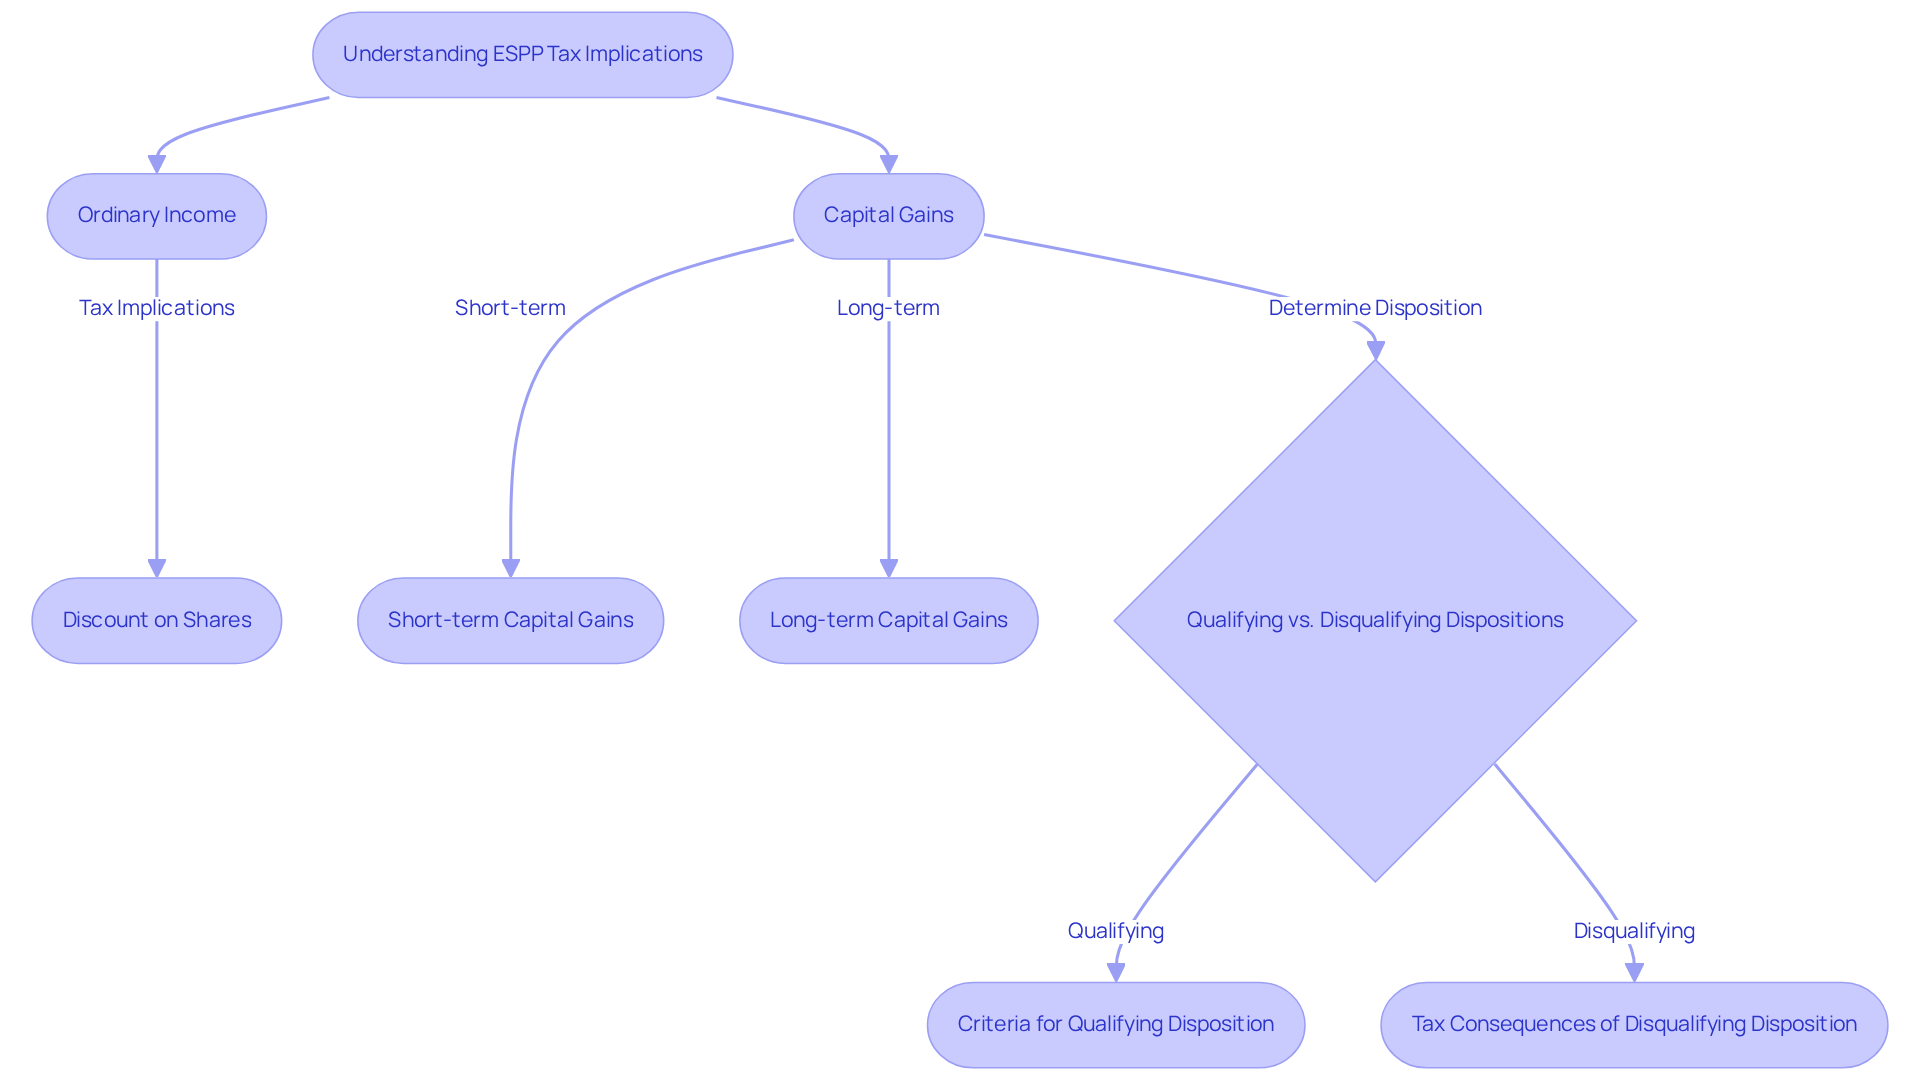
First, let’s talk about ordinary income. The discount you receive on shares purchased through an ESPP is classified as ordinary income and is considered as espp reported on w2. This amount is subject to federal income tax and FICA taxes, which can impact your overall tax liability. Navigating tax implications can feel overwhelming, especially when you’re trying to secure your family’s future.
Next, consider capital gains. When you sell your ESPP stocks, any profit exceeding the purchase price is subject to capital gains tax. The rate depends on how long you’ve owned the stocks before selling. Short-term capital gains are taxed at standard rates, while long-term capital gains enjoy reduced rates if you meet the holding period criteria. By grasping these concepts, you can make informed decisions that protect your family’s financial well-being.
Your employer will provide Form 3922 after you acquire stocks, detailing your ESPP transactions. This form is essential for accurate earnings reporting and tax preparation. It’s important to understand how these tax implications can shape your family’s financial journey.
Lastly, be aware of the difference between qualifying and disqualifying dispositions. If you sell stocks after meeting certain holding period criteria – at least one year after acquisition and two years after the offering date – you may qualify for advantageous long-term capital gains tax rates. Conversely, failing to meet these criteria results in a disqualifying disposition, leading to higher tax rates on the gains. For instance, if you sell your stocks within one year of acquisition, the profit will be taxed as regular earnings instead of at the reduced long-term capital gains rate.
With the right knowledge, you can turn potential tax challenges into opportunities for your family’s growth and security. Understanding these tax implications is vital for effective financial planning and can help you avoid unexpected liabilities during tax season. Employees who hold their shares for the qualifying period can significantly reduce their tax burden, as evidenced by case studies showing substantial tax savings through strategic timing of sales.
Report ESPP Income on Your W2 Form
Imagine the relief of knowing that your income from the employee stock purchase plan, or ESPP reported on W-2, is reported correctly, easing your tax season worries.
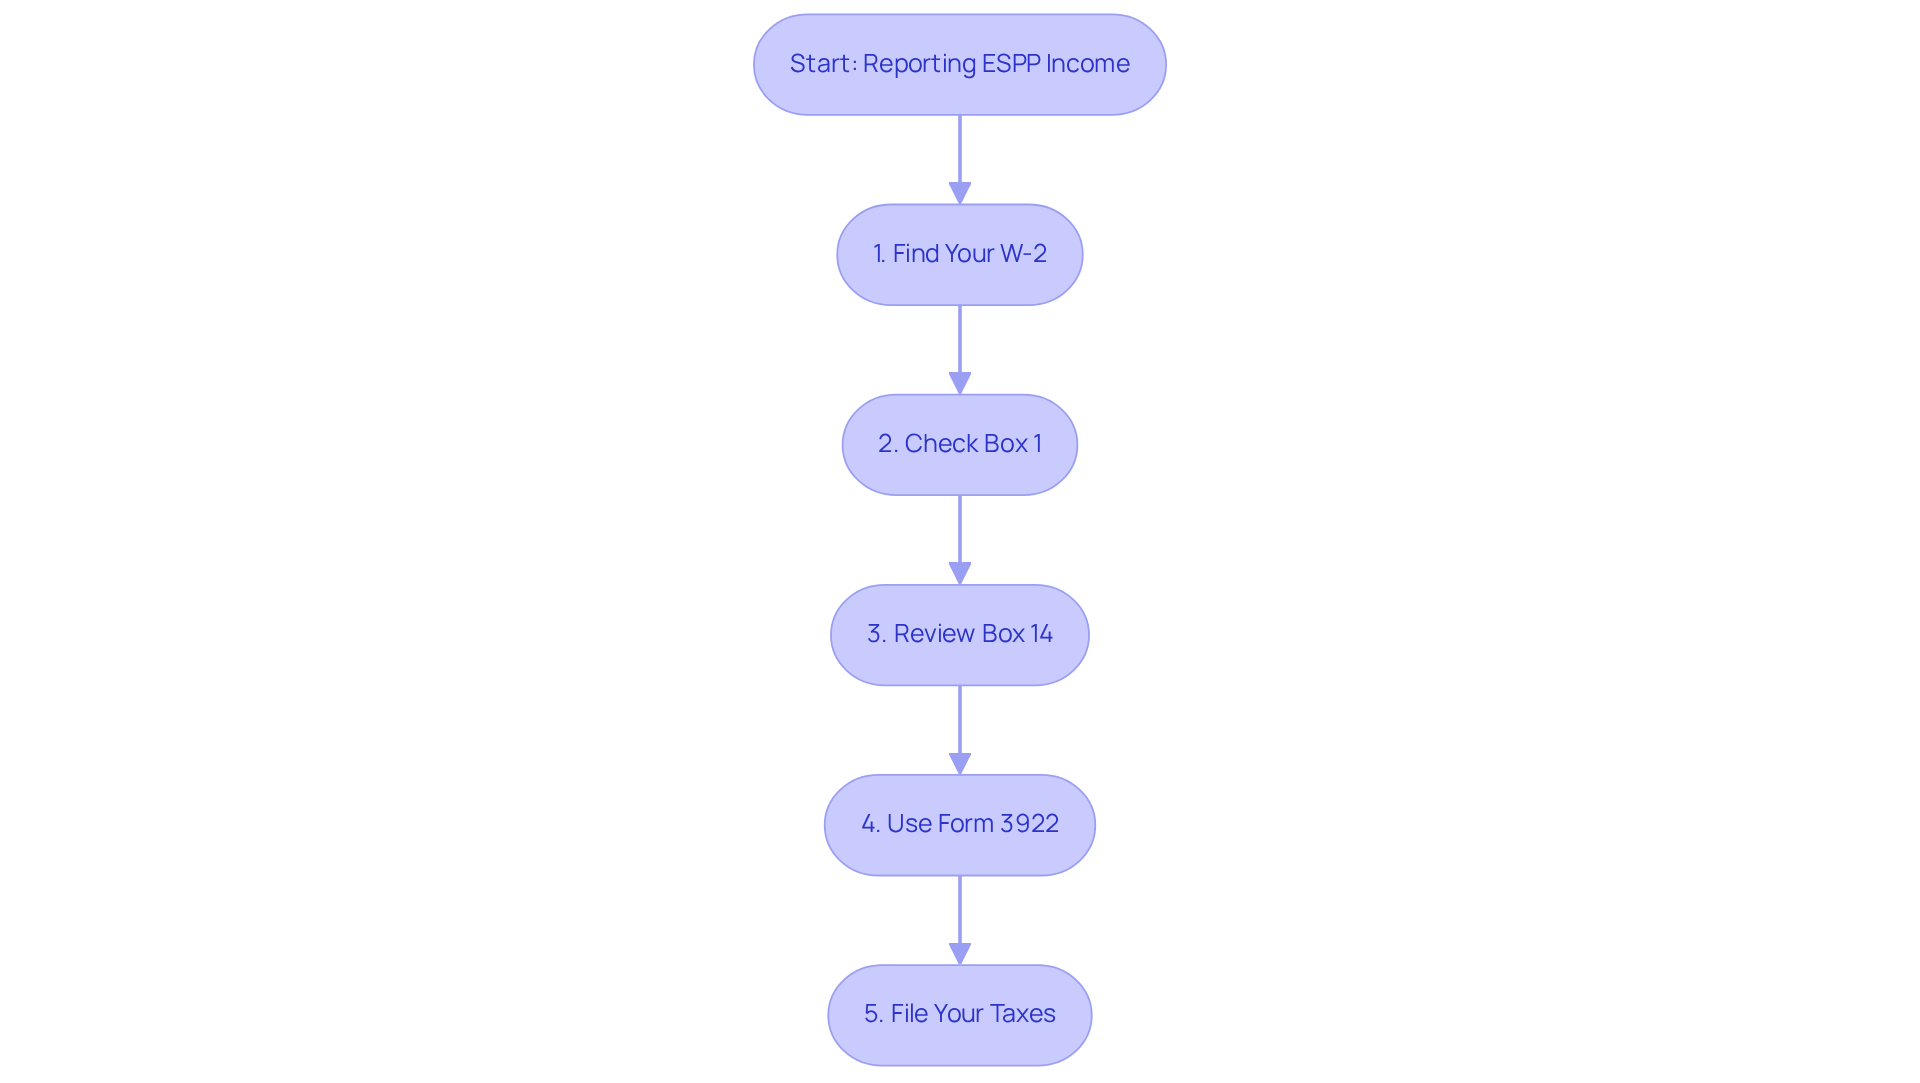
To accurately report your ESPP income on your W-2 form, follow these essential steps:
- Find Your W-2: Your employer will provide a W-2 form outlining your total earnings, including any employee stock purchase plan revenue.
- Check Box 1: The regular earnings from your employee stock purchase plan shares, which are ESPP reported on W-2, will be shown in Box 1 of your W-2. This figure represents your total taxable earnings for the year.
- Review Box 14: Some employers may also include ESPP earnings in Box 14, labeled as ‘ESPP’. While this information is supplementary and may not be required for your tax return, it can be useful for your records.
- Use Form 3922: If you sold stocks, consult Form 3922 for specifics on the stocks purchased and the discount received. This form is crucial for determining your cost basis for capital gains reporting.
- File Your Taxes: Let’s make sure the earnings on your W-2 match your tax return, so you can feel confident about your filing. If you have extra earnings from selling employee stock purchase plan shares, report it on Schedule D and Form 8949.
Following these steps helps you ensure that your employee stock purchase plan income is accurately reported, specifically as ESPP reported on W-2. This way, you can avoid mistakes that might lead to tax issues. Common reporting mistakes, such as overlooking Form 3922 or miscalculating the cost basis, can result in double taxation or missed deductions, making careful attention to detail essential.
According to Barbara Baksa, Executive Director of NASPP, “Employees will not participate if they don’t understand the plan or, worse, don’t know about it.” This emphasizes the significance of being knowledgeable about your employee stock purchase plan and its tax consequences. Additionally, filing by March 31 can help you save on state taxes, further emphasizing the need for timely and accurate reporting.
Taking these steps not only protects your finances but also ensures peace of mind for your family’s future.
Troubleshoot Common Reporting Issues
Imagine the stress of tax season when you realize your employee stock purchase plan earnings are missing or misreported. Here’s how to troubleshoot these issues effectively:
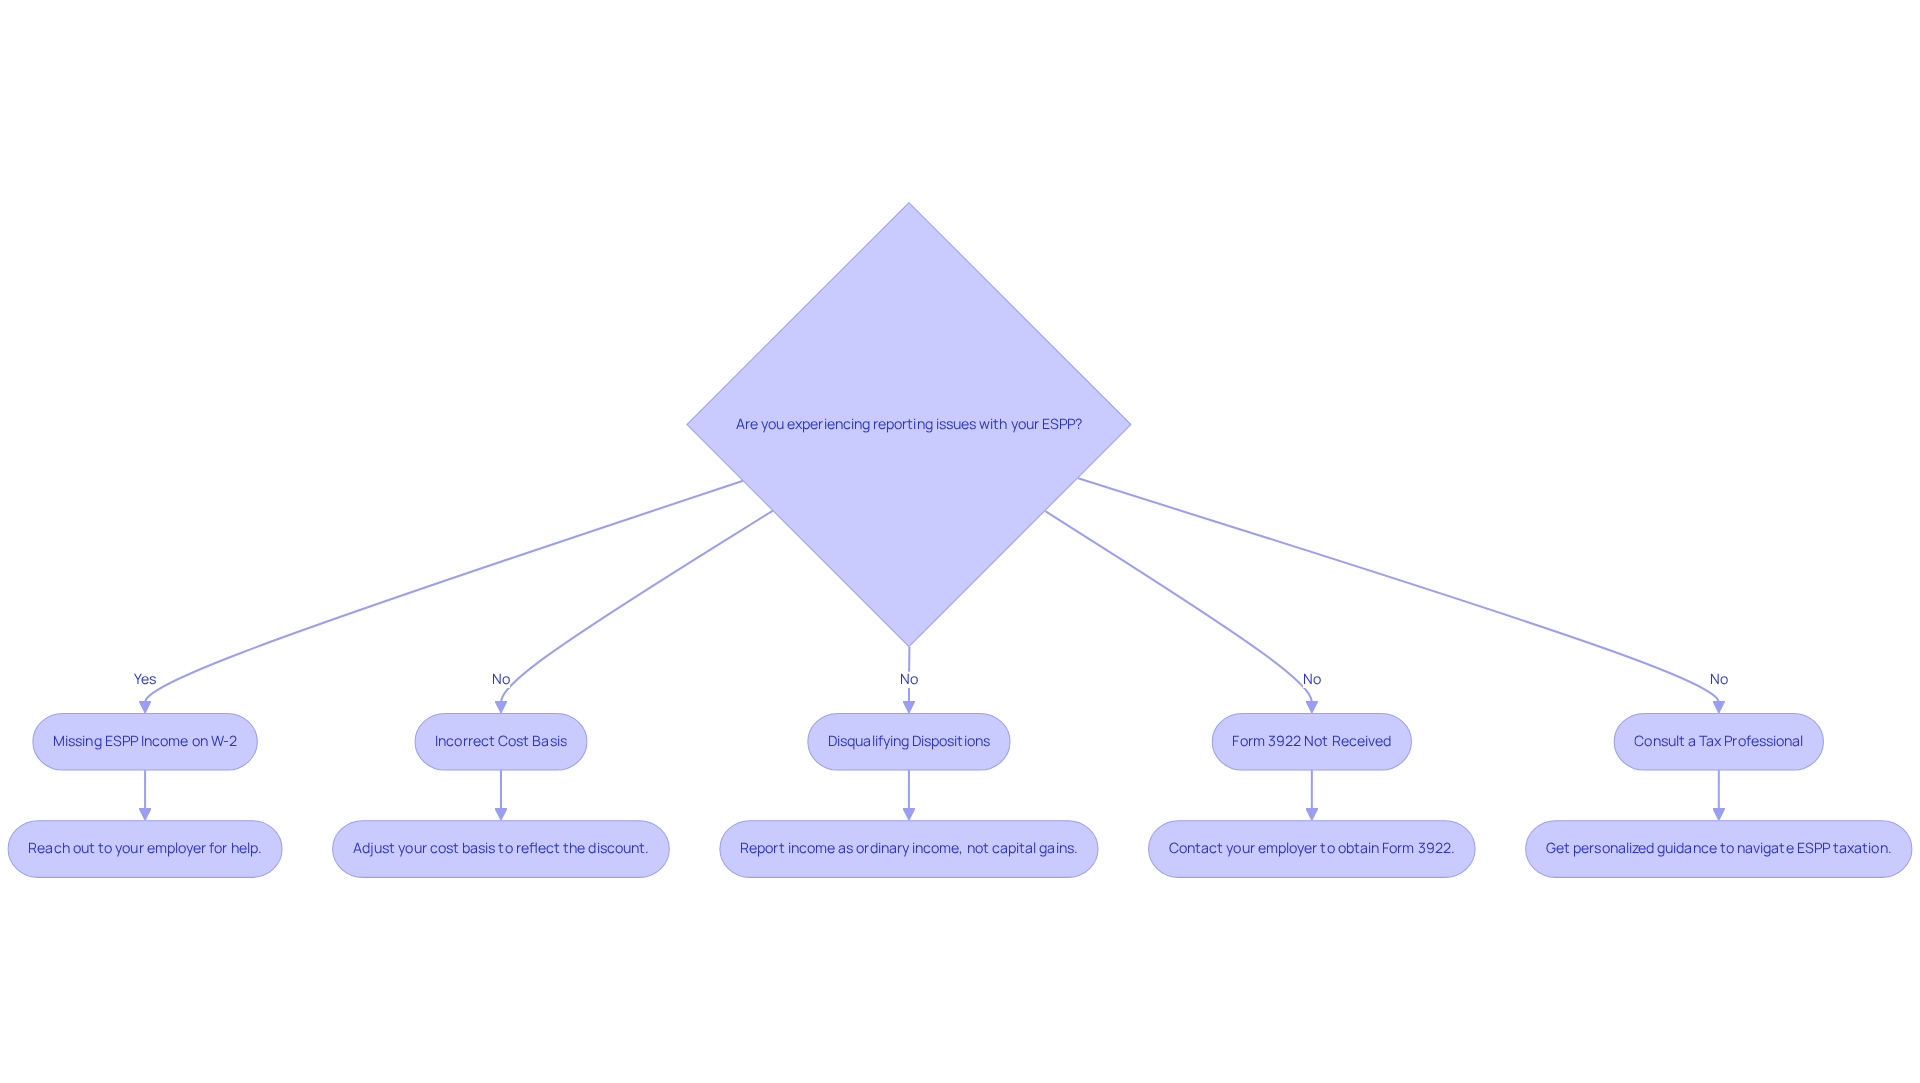
- Missing ESPP Income on W-2: If you notice your ESPP income is missing from your W-2, don’t hesitate to reach out to your employer for help. You may need to report the discount as ordinary income on your tax return and adjust your cost basis to avoid double taxation. Misreporting can lead to unexpected tax bills, adding stress to your family budget.
- Incorrect Cost Basis: If your broker gives you an incorrect cost basis on your 1099-B, you’ll need to make some adjustments. Make sure your cost basis reflects the discount from the employee stock purchase plan to accurately calculate your gains or losses. For example, in a disqualifying disposition, the short-term capital gain could be significant, like $2,490, if not reported correctly.
- Disqualifying Dispositions: If you sell your stocks before meeting the holding period, remember to report that income as ordinary income, not capital gains. This distinction is crucial for accurate tax reporting, as it can affect your overall tax liability.
- Form 3922 Not Received: If you haven’t received Form 3922 yet, reach out to your employer right away. This form is essential for accurately reporting your employee stock purchase plan transactions, which are espp reported on w2, and ensuring compliance with IRS regulations. Keep this form until you dispose of the shares for accurate reporting.
- Consult a Tax Professional: If you’re feeling unsure about your reporting, it might be a good idea to talk to a tax professional. Their expertise can provide personalized guidance and help you navigate the intricacies of ESPP taxation, ensuring you avoid costly errors.
By recognizing these common issues and knowing how to address them, you can approach tax season with confidence, knowing you’re not alone in this journey.
Conclusion
Imagine the peace of mind that comes from understanding how to report your Employee Stock Purchase Plan (ESPP) on your W-2. By grasping the intricacies of ESPPs, families can make informed decisions that contribute to their financial well-being and future security.
We’ve walked through the key components of ESPPs together, from their benefits to the tax implications and how to report your ESPP income on your W-2. Recognizing the ordinary income generated by discounts and navigating the complexities of capital gains are crucial steps in effective financial planning. Tax season can be overwhelming, especially when it comes to reporting your ESPP correctly, but troubleshooting common reporting issues can help prevent unnecessary stress, allowing families to focus on what truly matters.
When you take charge of your ESPP reporting, you’re not just protecting your finances; you’re also paving the way for a brighter future for your family. Embracing these strategies can lead to a more secure and prosperous future, allowing families to thrive and invest in their children’s dreams. For personalized guidance tailored to your unique situation, consider reaching out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
What is an Employee Stock Purchase Plan (ESPP)?
An Employee Stock Purchase Plan (ESPP) allows employees to buy shares of their company at a reduced cost through payroll deductions, fostering employee ownership and encouraging personal investment in their financial future.
What are the main benefits of participating in an ESPP?
The main benefits include purchasing shares at a discounted price (often 5% to 15% off), eligibility for full-time employees, the ability to choose the percentage of salary to contribute, and potential long-term financial security through stock ownership.
Who is eligible to participate in an ESPP?
Most companies offer ESPPs to full-time employees, although eligibility criteria may vary. The technology and financial sectors tend to have the highest prevalence of these plans.
How do I enroll in an ESPP?
Enrollment typically occurs during designated periods, and employees can select the percentage of their salary to contribute. It is important to participate in educational programs to fully understand the benefits of the plan.
Is there a holding period for stocks purchased through an ESPP?
Yes, many ESPPs require a holding period before selling the stocks, which can affect tax implications. This encourages families to hold onto their shares for a year or more, contributing to financial stability.
How can ESPPs impact my tax return?
Understanding the components of an ESPP is crucial for accurately declaring any earnings reported on your W2 on your tax return, especially for families looking to enhance their financial strategies.
What kind of returns can I expect from an ESPP?
With a 15% discount and lookback feature, ESPPs can yield an almost guaranteed return of 17.6% or more over a short period, making them an attractive option for young families.
How can participating in an ESPP benefit my family’s financial future?
By participating in an ESPP, families can invest in their future, potentially alleviate financial stress, and prepare for significant expenses such as children’s education and retirement.
List of Sources
- Understand Employee Stock Purchase Plans (ESPP)
- NASPP | Why Your Qualified ESPP Should Offer a 15% Discount (https://naspp.com/blog/why-15-percent-for-espp)
- Employee Stock Purchase Plan (ESPPs) Trends (https://stockopter.com/employee-stock-purchase-plan-espps-trends)
- Money Left on the Table: An Analysis of Participation in Employee Stock Purchase Plans (https://academic.oup.com/rfs/article/27/12/3658/1574801?login=true)
- Employee Stock Purchase Programs: 2026 Guide to ESPP Risks & Benefits (https://advisorfinder.com/blog-posts/employee-stock-purchase-programs-risks-benefits-2025)
- How Much Should I Contribute to My Company’s ESPP? (https://wiserinvestor.com/how-much-should-i-contribute-to-my-companys-espp)
- Identify Tax Implications of ESPP Shares
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/amp/L8NgMFpFX)
- Employee stock purchase plan – ESPP (https://jpmorganworkplacesolutions.com/insights/employee-stock-purchase-plan-espp)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/blog/espp-tax-rules-what-you-need-to-know)
- ESPP double tax: How to avoid getting taxed twice on shares (https://taxesforexpats.com/articles/investments/how-to-avoid-getting-double-taxed-on-espp-employee-stock-purchase-plan.html)
- ESPP Tax Calculator (https://nerdwallet.com/investing/calculators/espp-tax)
- Report ESPP Income on Your W2 Form
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/L8NgMFpFX)
- 6 Big Tax-Return Errors To Avoid With Employee Stock Purchase Plans (https://forbes.com/sites/brucebrumberg/2021/03/23/6-big-tax-return-errors-to-avoid-with-employee-stock-purchase-plans)
- Qualifying Dispositions of ESPP Stock (https://computershare.com/us/insights/employee-share-plans/qualifying-dispositions-of-espp-stock)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- ESPP double tax: How to avoid getting taxed twice on shares (https://taxesforexpats.com/articles/investments/how-to-avoid-getting-double-taxed-on-espp-employee-stock-purchase-plan.html)
- Troubleshoot Common Reporting Issues
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/L8NgMFpFX)
- 6 Big Tax-Return Errors To Avoid With Employee Stock Purchase Plans (https://forbes.com/sites/brucebrumberg/2021/03/23/6-big-tax-return-errors-to-avoid-with-employee-stock-purchase-plans)
- ESPP mistakes you need to avoid (https://jpmorganworkplacesolutions.com/insights/espp-mistakes-you-need-to-avoid)
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)
- ESPP double tax: How to avoid getting taxed twice on shares (https://taxesforexpats.com/articles/investments/how-to-avoid-getting-double-taxed-on-espp-employee-stock-purchase-plan.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading