

Key Highlights
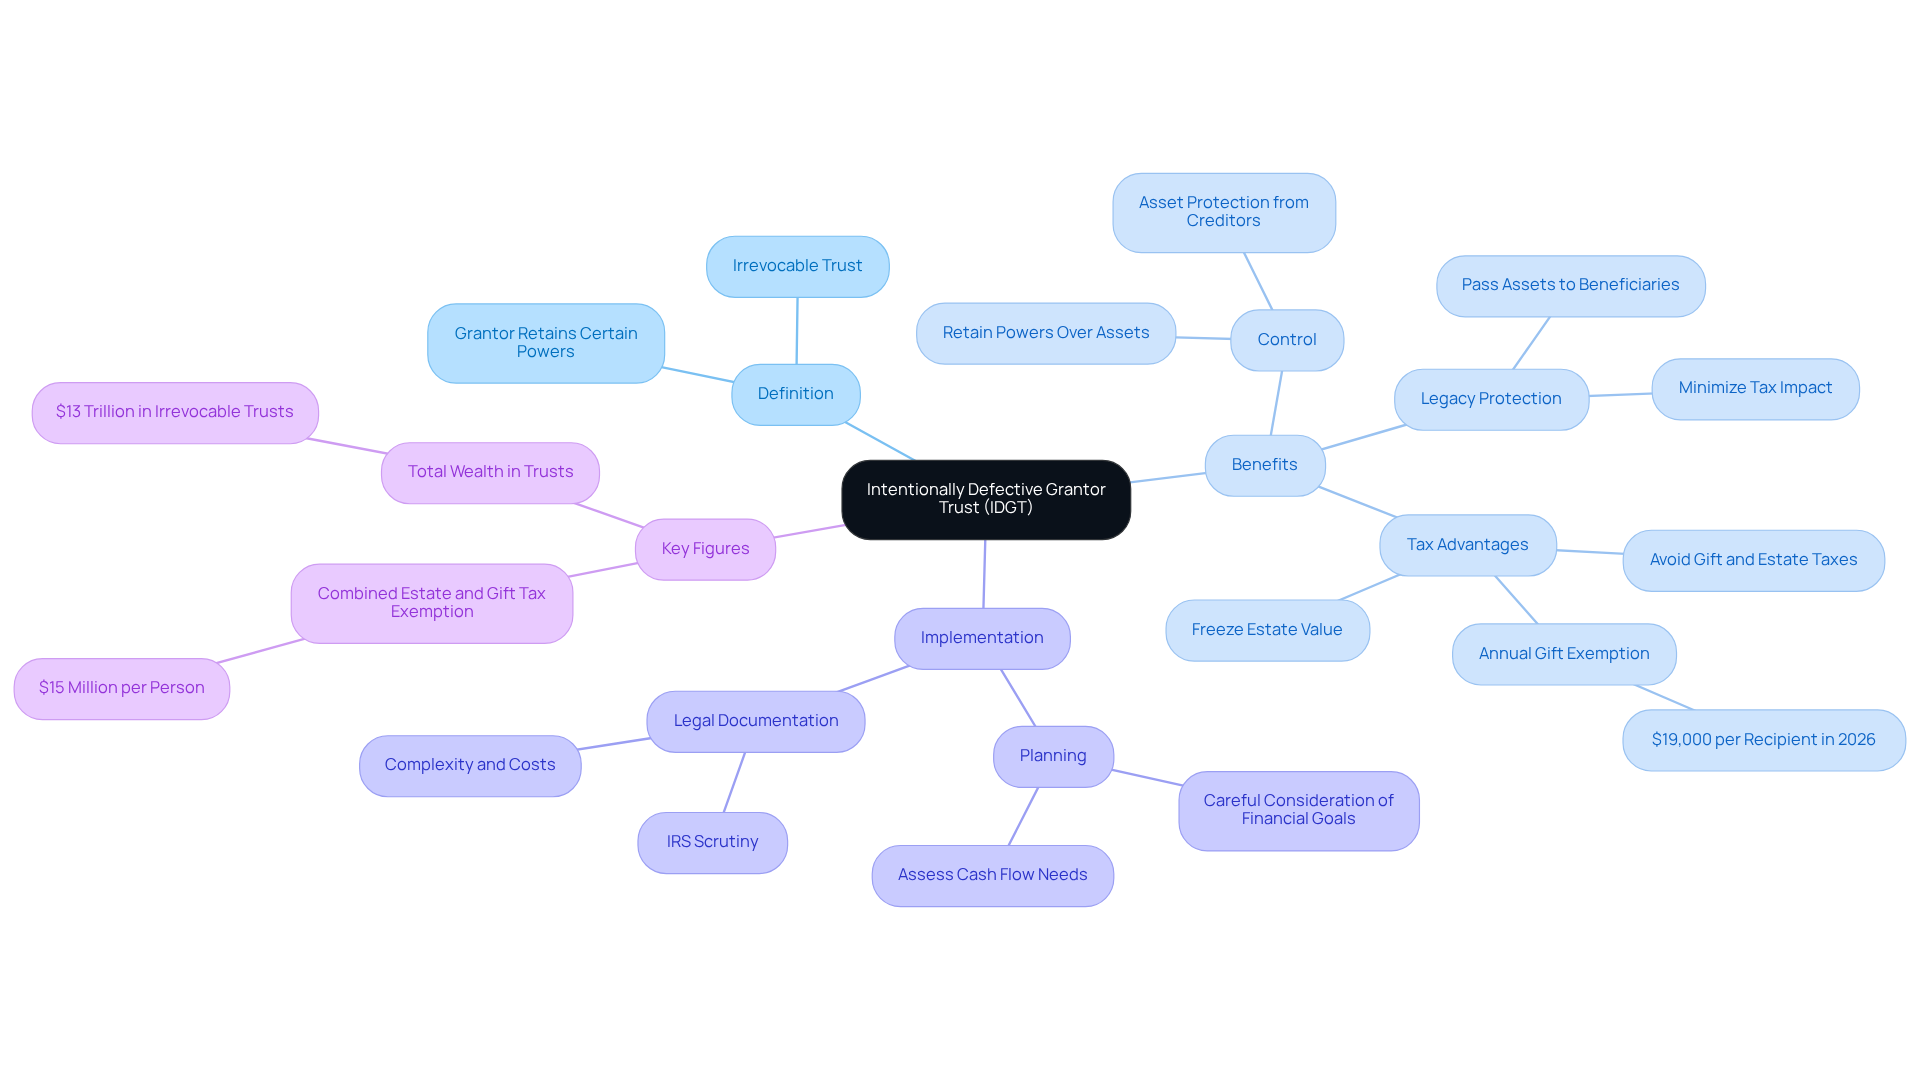
- An intentionally defective grantor trust (IDGT) allows families to maintain control over assets while securing tax advantages.
- Transferring appreciating properties into an IDGT can freeze estate value, allowing future appreciation to pass to beneficiaries without gift or estate taxes.
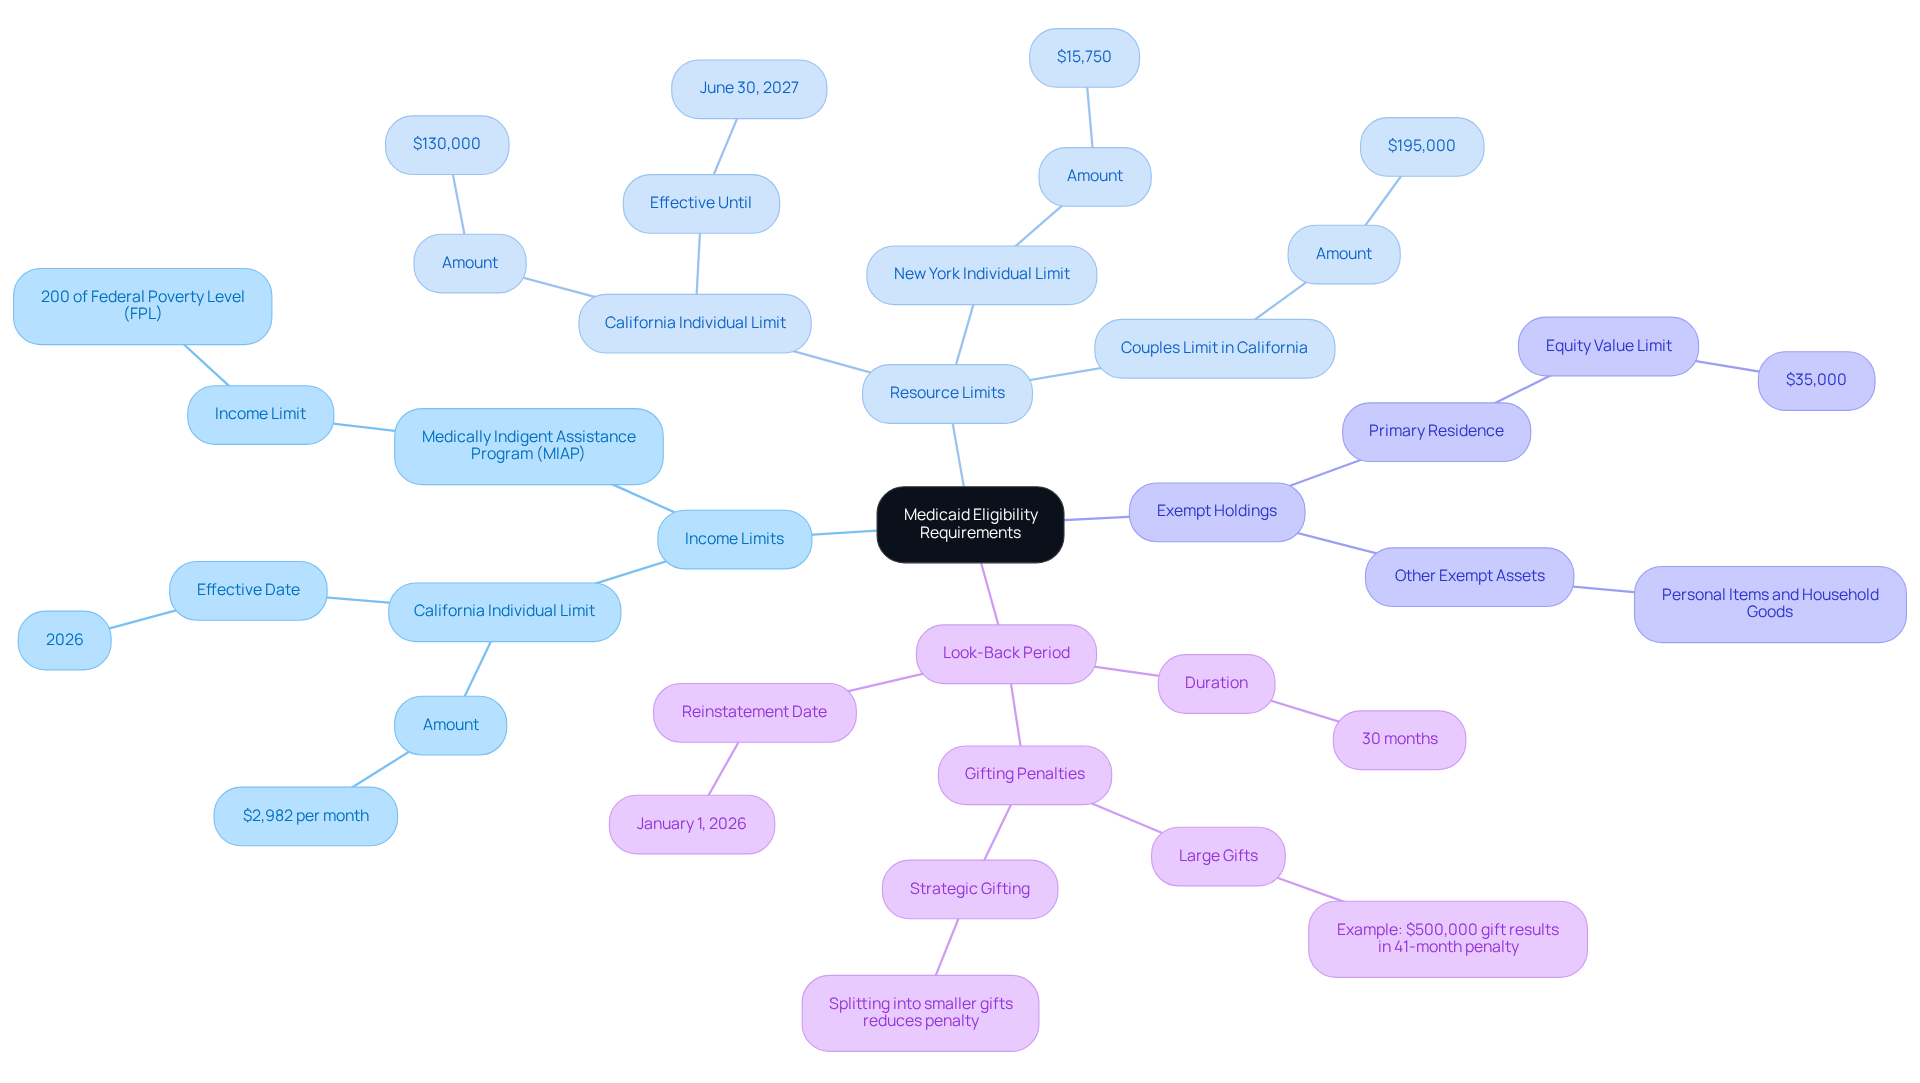
- Key Medicaid eligibility requirements include income limits (e.g., $2,982/month in California) and resource limits (e.g., $130,000 for individuals in California).
- Certain properties, like primary residences, may be exempt from Medicaid resource limits, but specific guidelines apply.
- The 30-month look-back period for Medicaid eligibility requires careful asset transfer planning to avoid penalties.
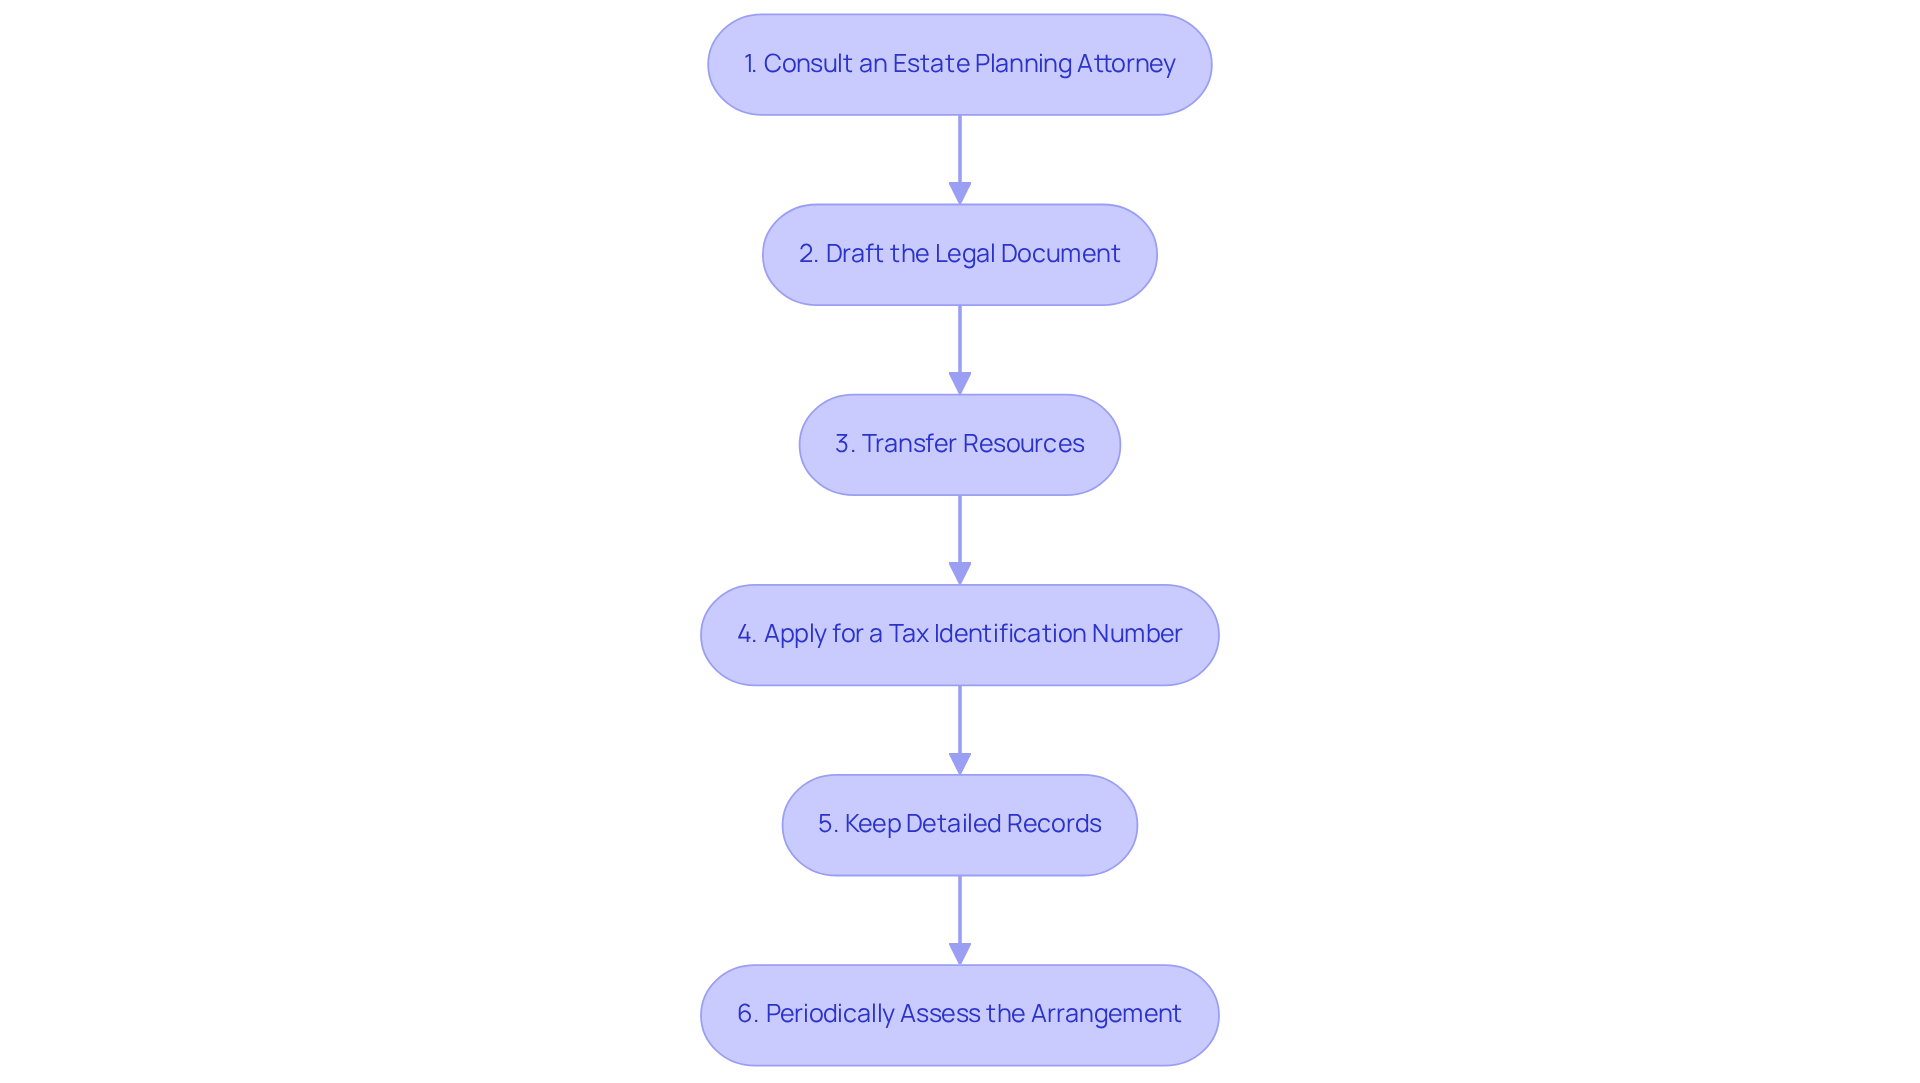
- Setting up an IDGT involves steps such as consulting an estate planning attorney, drafting legal documents, transferring assets, and applying for a Tax Identification Number (TIN).
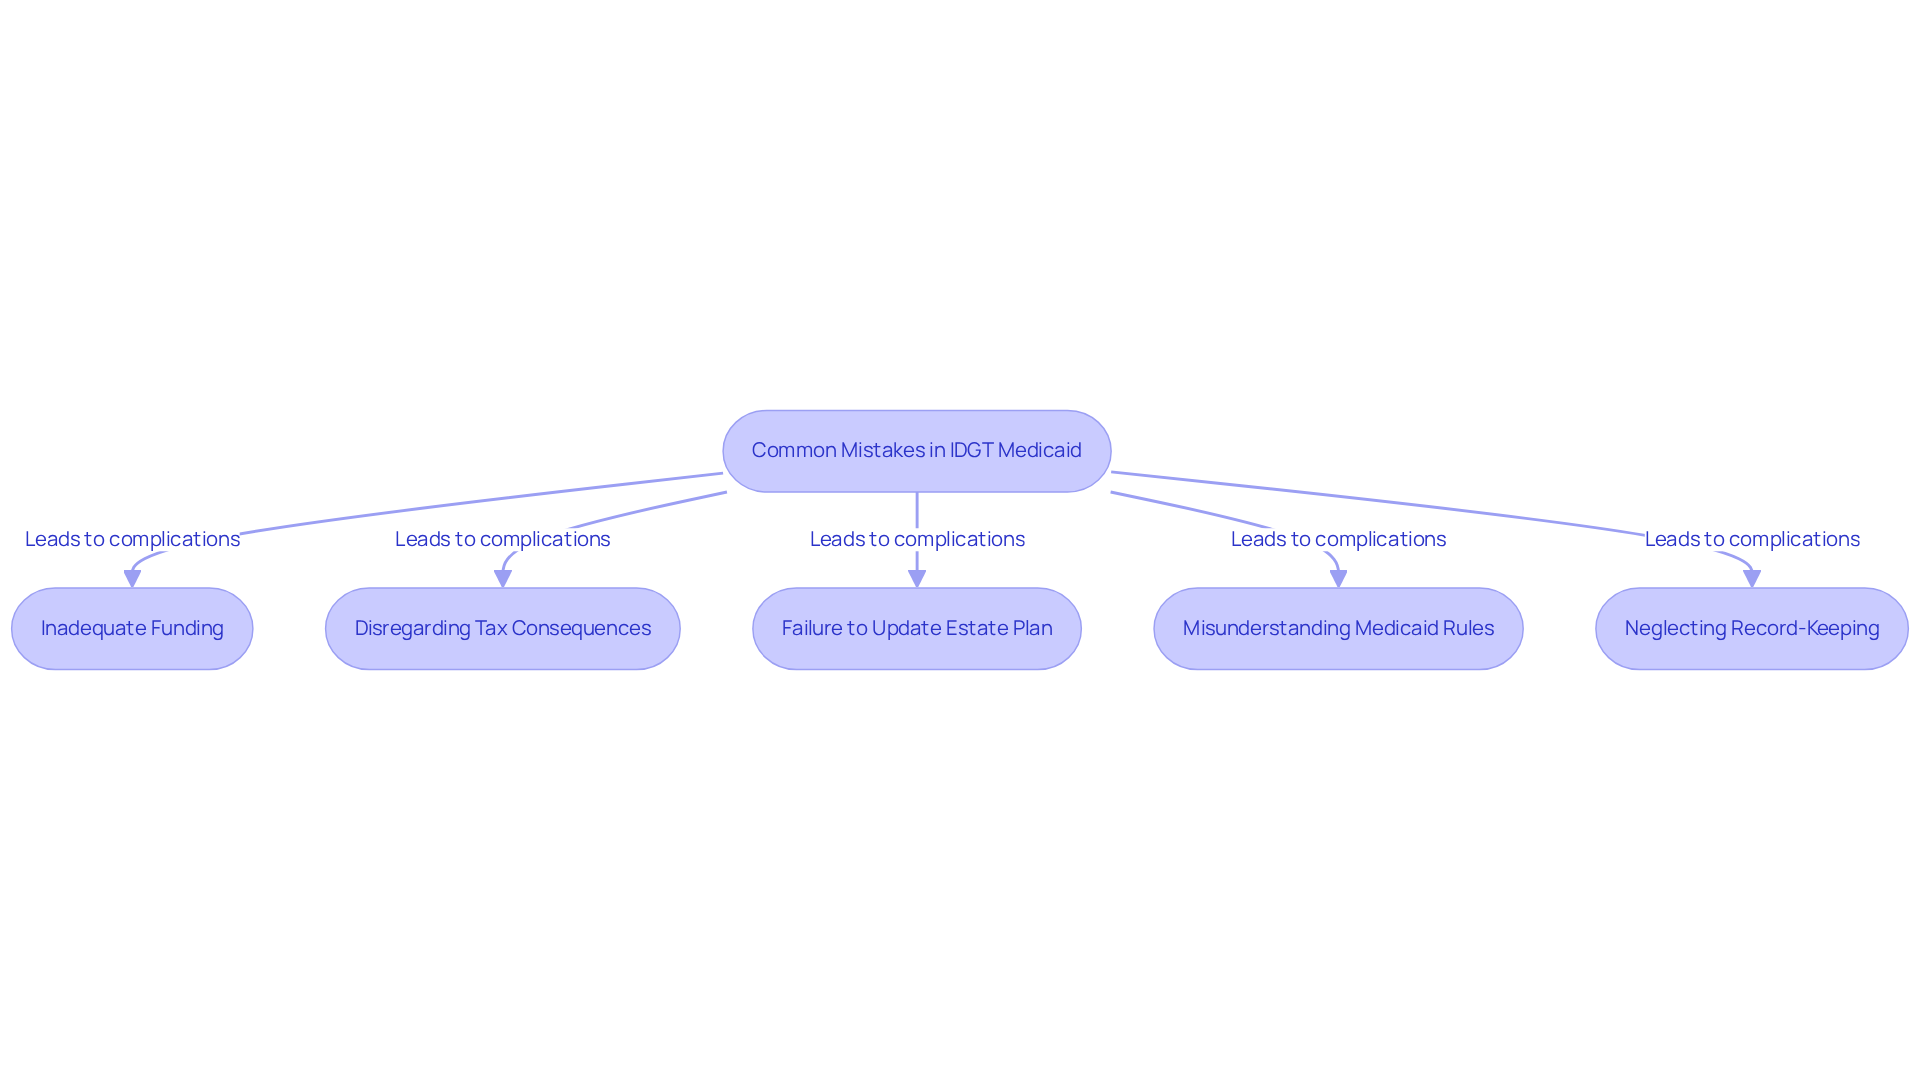
- Common mistakes in managing IDGTs include inadequate funding, misunderstanding tax consequences, failing to update estate plans, and neglecting record-keeping.
- Regular reviews and updates of the estate plan are essential to adapt to changing family needs and ensure compliance with laws.
Introduction
Imagine feeling overwhelmed by the thought of securing your family’s financial future while ensuring Medicaid eligibility. Navigating the complexities of estate planning can be challenging, but an intentionally defective grantor trust (IDGT) can be a helpful tool, giving families control over their assets while also providing valuable tax benefits. But setting up this trust can feel challenging, and it’s easy to worry about making mistakes that could affect the benefits it offers.
So, how can your family set up an IDGT to protect your wealth and navigate the complexities of Medicaid eligibility? In this guide, we’ll walk you through the steps to set up an IDGT, pointing out key requirements and common pitfalls to help your family protect your legacy with confidence.
Understand the Basics of an Intentionally Defective Grantor Trust
Imagine feeling secure about your family’s financial future while navigating the complexities of wealth management. An intentionally defective grantor trust Medicaid is a financial tool that allows you to keep control while also securing your family’s future. This arrangement enables you to maintain certain powers over the assets while enjoying significant tax advantages.
For families like yours, who may have valuable assets, utilizing an intentionally defective grantor trust Medicaid can be a game-changer in protecting your legacy. By transferring appreciating properties into the trust, you can effectively freeze the value of your estate at the time of transfer. This means that any future appreciation can pass to your beneficiaries without incurring gift or estate taxes, providing you with peace of mind.
It’s important to understand that implementing an intentionally defective grantor trust Medicaid requires careful planning and legal documentation. However, the benefits can be substantial. For instance, the annual gift exemption is set at $19,000 for each recipient in 2026, and the combined estate and gift tax exemption currently stands at $15 million per person. These figures highlight how IDGTs can be powerful tools for families looking to manage their wealth effectively across generations.
By grasping these key concepts, you’re taking the first step toward a secure future for your family, and we’re here to help you every step of the way.
Identify Key Requirements for Medicaid Eligibility
Navigating the maze of Medicaid eligibility can feel overwhelming for families, but understanding the key requirements can make a world of difference.
-
Income Limits: In California, the income limit for an individual is about $2,982 per month as of 2026, which is set at 300% of the current SSI Federal Benefit Rate (FBR). This threshold is crucial for determining eligibility.
-
Resource Limits: Many states set limits on how much families can have in resources, which can feel restrictive. For example, in New York, a person must have resources below $15,750 to qualify for Medicaid. In California, the limit for individuals is set at $130,000 through June 30, 2027, while couples have a threshold of $195,000.
-
Exempt Holdings: Certain properties, like a primary residence, may be excluded from these limits. However, specific guidelines apply, and understanding which resources qualify as exempt is crucial for effective planning. For instance, the equity value of a primary residence must not exceed $35,000.
-
Look-Back Period: Medicaid has a 30-month look-back period during which any transfer of property may be scrutinized. This rule will be reinstated starting January 1, 2026. Transferring assets into an intentionally defective grantor trust Medicaid can be a strategic move, but it must be executed carefully to avoid penalties. For example, a gift of $500,000 can result in a 41-month penalty for Medi-Cal eligibility, while splitting it into ten $50,000 gifts can reduce the penalty to just 4 months. Additionally, California’s penalties for gifting run concurrently, allowing for strategic gifting to minimize total penalties.
Without a clear understanding, families might miss out on essential support that could ease their financial burden. With the right knowledge and support, families can secure the assistance they need to thrive.
Establish the Trust: Step-by-Step Setup Process
Imagine feeling secure about your family’s future while navigating the complexities of estate planning. Setting up an Intentionally Defective Grantor Trust (IDGT) involves several essential steps that families should follow to ensure compliance and effectiveness:
-
Consider reaching out to a caring estate planning attorney who can guide you through this process. This is crucial for ensuring compliance with state laws and regulations, as well as for receiving tailored advice.
-
Collaborate with your attorney to draft the legal document. This document must clearly detail the conditions of the arrangement, including the powers held by the grantor, the recipients, and the management of the resources.
-
Transfer resources into the fund. This may include cash, real estate, or other investments. It’s essential to confirm that these resources are correctly titled in the name of the entity to prevent issues later.
-
Apply for a Tax Identification Number (TIN) for the entity, as this will be necessary for tax reporting purposes.
-
Keep detailed records of all transactions related to the fund, including asset transfers and income generated. This documentation is essential for tax purposes and for maintaining Medicaid eligibility.
-
Periodically assess the arrangement with your attorney to ensure it continues to meet your household’s needs and complies with any changes in laws or regulations.
Following these steps helps families create an intentionally defective grantor trust Medicaid that aligns with their estate planning and Medicaid needs. For example, a case study demonstrates how a household employed an intentionally defective grantor trust Medicaid to safeguard their assets while ensuring they remained eligible for Medicaid benefits, showcasing the effectiveness of this vehicle in practical situations. Additionally, statistics show that proper estate planning can significantly reduce probate costs, which can reach 5% or more of an estate’s total value, emphasizing the importance of setting up a trust correctly. It’s important to understand that without proper guidance, families risk losing valuable assets or missing out on essential benefits. Taking these steps not only protects your family’s assets but also ensures peace of mind for the future.
Navigate Challenges and Avoid Common Mistakes
Navigating the complexities of an intentionally defective grantor trust Medicaid can feel overwhelming for families, but understanding common pitfalls can make all the difference.
-
Inadequate Funding: It’s easy to overlook funding your IDGT fully, but doing so is crucial for reaping its benefits. Make sure to move all your assigned assets into the trust; it’s a vital step for your family’s financial well-being.
-
Disregarding Tax Consequences: While the IDGT offers tax benefits, remember that you’ll still be responsible for income taxes on its earnings. Imagine facing unexpected tax bills that strain your family budget. Planning ahead can help you avoid this stress.
-
Failure to Update the Estate Plan: Major life events, like welcoming a new child or changes in your financial situation, mean it’s time to revisit your estate plan. Consulting with an estate planning lawyer every few years is essential to ensure your plan reflects your family’s evolving needs. As Virginia Hammerle, a board-certified attorney, wisely notes, ‘Many local residents believe that establishing an estate plan is a one-time task, but the process involves ongoing review, legal knowledge, and thoughtful decisions about family needs.’
-
Misunderstanding Medicaid Rules: Families often misinterpret Medicaid regulations regarding asset transfers. Understanding the look-back period and its implications for eligibility is vital. Consulting with a professional can clarify these complex rules, as failing to do so can lead to significant financial consequences.
-
Neglecting Record-Keeping: Keeping organized documentation of all transactions related to the fund is critical. Proper record-keeping supports Medicaid eligibility and ensures accurate tax reporting. Overlooking this aspect can lead to disputes and complications in managing relationships.
By proactively addressing these challenges, you can enhance the effectiveness of your intentionally defective grantor trust Medicaid. Taking these steps not only protects your family’s future but also fosters a sense of security and togetherness in your financial journey. Regular reviews and updates, along with clear communication about family dynamics, can significantly mitigate the risks associated with trust management.
Conclusion
Imagine feeling secure about your family’s financial future while navigating the complexities of Medicaid regulations. Establishing an intentionally defective grantor trust (IDGT) for Medicaid can be a pivotal step in securing that future. This tool helps families keep control of their assets while also offering tax benefits that help preserve wealth for future generations. When families understand how IDGTs work and their impact on Medicaid eligibility, they can approach estate planning with more confidence.
Throughout this guide, we’ve highlighted key aspects of setting up an IDGT, including:
- The essential requirements for Medicaid eligibility
- The step-by-step process for establishing the trust
- Common pitfalls to avoid
From understanding income and resource limits to ensuring proper documentation and funding, each element plays a crucial role in the successful management of an IDGT. We encourage families to seek professional guidance to navigate these complexities effectively, ensuring compliance with state laws and maximizing the benefits of this financial strategy.
Setting up an intentionally defective grantor trust is about more than just protecting assets; it’s about creating a safe and nurturing space for your loved ones. By taking proactive steps and remaining informed about the evolving landscape of Medicaid regulations, families can safeguard their legacies and ensure that their loved ones are well-prepared for the future. Engaging with a fiduciary advisor, like Bright Advisers, can provide the necessary support to make informed decisions and achieve peace of mind in wealth management. By taking these steps, you can create a lasting legacy that your family will cherish for generations to come.
Frequently Asked Questions
What is an intentionally defective grantor trust (IDGT)?
An intentionally defective grantor trust is a financial tool that allows you to maintain control over certain assets while enjoying significant tax advantages, particularly in the context of wealth management.
How does an IDGT benefit families with valuable assets?
By transferring appreciating properties into the trust, families can freeze the value of their estate at the time of transfer. This allows any future appreciation to pass to beneficiaries without incurring gift or estate taxes.
What are the tax exemptions associated with IDGTs?
The annual gift exemption is set at $19,000 for each recipient in 2026, and the combined estate and gift tax exemption currently stands at $15 million per person.
What is required to implement an IDGT?
Implementing an intentionally defective grantor trust requires careful planning and legal documentation to ensure compliance and effectiveness.
How can IDGTs help in securing a family’s financial future?
IDGTs provide a way to manage wealth effectively across generations, allowing families to protect their legacy while navigating the complexities of wealth management.
List of Sources
- Understand the Basics of an Intentionally Defective Grantor Trust
- Understanding the Uses, Benefits, and Drawbacks of an Intentionally Defective Grantor Trust (IDGT) – GSRM (https://gsrm.com/understanding-the-uses-benefits-and-drawbacks-of-an-intentionally-defective-grantor-trust-idgt)
- Grantor Trusts & IDGTs: Estate Planning & Tax Considerations (https://commercetrustcompany.com/research-and-insights/articles/understanding-intentionally-defective-grantor-trusts)
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- Irrevocable Trusts – A Complete Guide (https://deskera.com/blog/irrevocable-trusts)
- Identify Key Requirements for Medicaid Eligibility
- 2025 Medicaid Eligibility Income Chart by State + Calculator – Jarvis Law Office (https://jarvisfirm.com/2025-medicaid-eligibility-income-chart-by-state)
- Asset Limit Frequently Asked Questions | DHCS (https://dhcs.ca.gov/medi-cal/help/asset-limit-frequently-asked-questions)
- Medi-Cal Changes in 2026: Plan Before It’s Too Late (https://cunninghamlegal.com/medi-cal-changes-in-2026-plan-before-its-too-late)
- Program Eligibility and Income Limits | SCDHHS (https://scdhhs.gov/members/program-eligibility-and-income-limits)
- Establish the Trust: Step-by-Step Setup Process
- What Is the Average Cost for Estate Planning in California? (https://amity-law.com/blog/what-is-the-average-cost-for-estate-planning-in-california)
- How Much Does an Estate Planning Attorney Cost in 2026? | Neptune Blog (https://meetneptune.com/blog/estate-planning-attorney-cost)
- How Much Does an Estate Planning Lawyer Cost in San Diego? – Skaja, Daniels & Luu, LLP (https://sdlegal.law/2025/10/17/how-much-does-an-estate-planning-lawyer-cost-in-san-diego)
- How Much Does Estate Planning Cost? (https://legalshield.com/blog/how-much-does-estate-planning-cost)
- Estate Planning Costs: What to Expect (https://ncoa.org/article/how-much-does-estate-planning-cost-understanding-legal-fees-and-expenses)
- Navigate Challenges and Avoid Common Mistakes
- 4 Common Trust Mistakes (https://schwab.com/learn/story/4-common-trust-mistakes)
- 5 Common Trust Mistakes to Avoid | Hammerle Morris Law Firm (https://hammerle.com/blog/five-common-trust-mistakes-to-avoid)
- Common Mistakes When Setting Up Trusts | Estate Law Partners, LLC (https://estatelawpartners.com/blog/2025/november/common-mistakes-when-setting-up-trusts)
- Common Living Trust Mistakes That Can Lead to Probate (https://rudolphlegal.com/common-mistakes-people-make-when-creating-a-living-trust)
- 7 Common Mistakes People Make When Creating a Trust. (https://unsworthlaplante.com/7-common-mistakes-people-make-when-creating-a-trust)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading