

Overview
Are you wondering if you have a high deductible health plan (HDHP)? It’s essential to check if your deductible meets the IRS-defined thresholds: at least $1,650 for individuals or $3,300 for families. Additionally, ensure that your out-of-pocket maximum does not exceed $8,300 for individuals or $16,600 for families in 2025.
Understanding your health plan can feel overwhelming, but don’t worry; you’re not alone. Start by reviewing your coverage documents, or consider reaching out to your provider for clarification. Your HR department can also be a valuable resource in confirming your plan type.
It’s important to grasp both the benefits and potential costs associated with HDHPs. This knowledge is crucial for effective financial planning, especially when it comes to your family’s future. Remember, we’re here for you, and together, we can navigate this journey to ensure your family’s health and financial well-being.
Key Highlights:
- High-deductible health plans (HDHPs) offer lower monthly premiums but require higher out-of-pocket deductibles.
- For 2025, an HDHP is defined by a deductible of at least $1,650 for individuals and $3,300 for families.
- The out-of-pocket maximum for HDHPs is capped at $8,300 for individuals and $16,600 for families in 2025.
- HDHPs often cover preventive care services at no cost, encouraging regular health cheque-ups.
- Health Savings Accounts (HSAs) can be paired with HDHPs, allowing tax-free savings for medical expenses.
- To verify if you have an HDHP, review coverage documents, contact your provider, cheque online resources, or consult your HR department.
- While HDHPs can lower monthly costs, they may lead to higher out-of-pocket expenses, requiring careful financial planning.
Introduction
Navigating the complexities of health insurance can feel overwhelming, especially for families trying to balance quality care with financial concerns. High-deductible health plans (HDHPs) might seem like a promising choice, offering lower monthly premiums, but they also require a deeper understanding of how they work and what they mean for your family’s healthcare costs.
Imagine if you could easily determine whether your plan qualifies as an HDHP and what that means for your financial health. This guide will illuminate the essential steps to identify a high-deductible health plan, empowering you to make informed decisions that align with your family’s needs and financial well-being.
Together, we can navigate this journey.
Define High-Deductible Health Plans (HDHPs)
Navigating health coverage can feel overwhelming, especially for young parents trying to balance costs and care. Considering a high-deductible health plan (HDHP) can be beneficial, especially if you understand how to tell if you have a high deductible health plan. This type of coverage offers lower monthly premiums, which can ease some financial burdens, but it does come with higher deductibles compared to traditional plans.
Imagine if you could save money each month while still protecting your family’s health. To understand how to tell if you have a high deductible health plan (HDHP), refer to IRS guidelines for 2025, which define an HDHP as having a deductible of at least $1,650 for individual coverage and $3,300 for family coverage. This means that before your insurance kicks in to help with medical expenses, you would need to cover these costs out-of-pocket up to that deductible amount.
But don’t worry; you’re not alone in this journey. Many HDHPs come with Health Savings Accounts (HSAs), which allow you to save money tax-free for medical expenses. This can be a wonderful way to prepare for unexpected healthcare needs while also managing your family’s budget.
Together, we can navigate these options and find a plan that works for you. Remember, we’re here for you every step of the way as you make decisions that prioritize your family’s health and financial well-being.

Identify Criteria for High-Deductible Health Plans
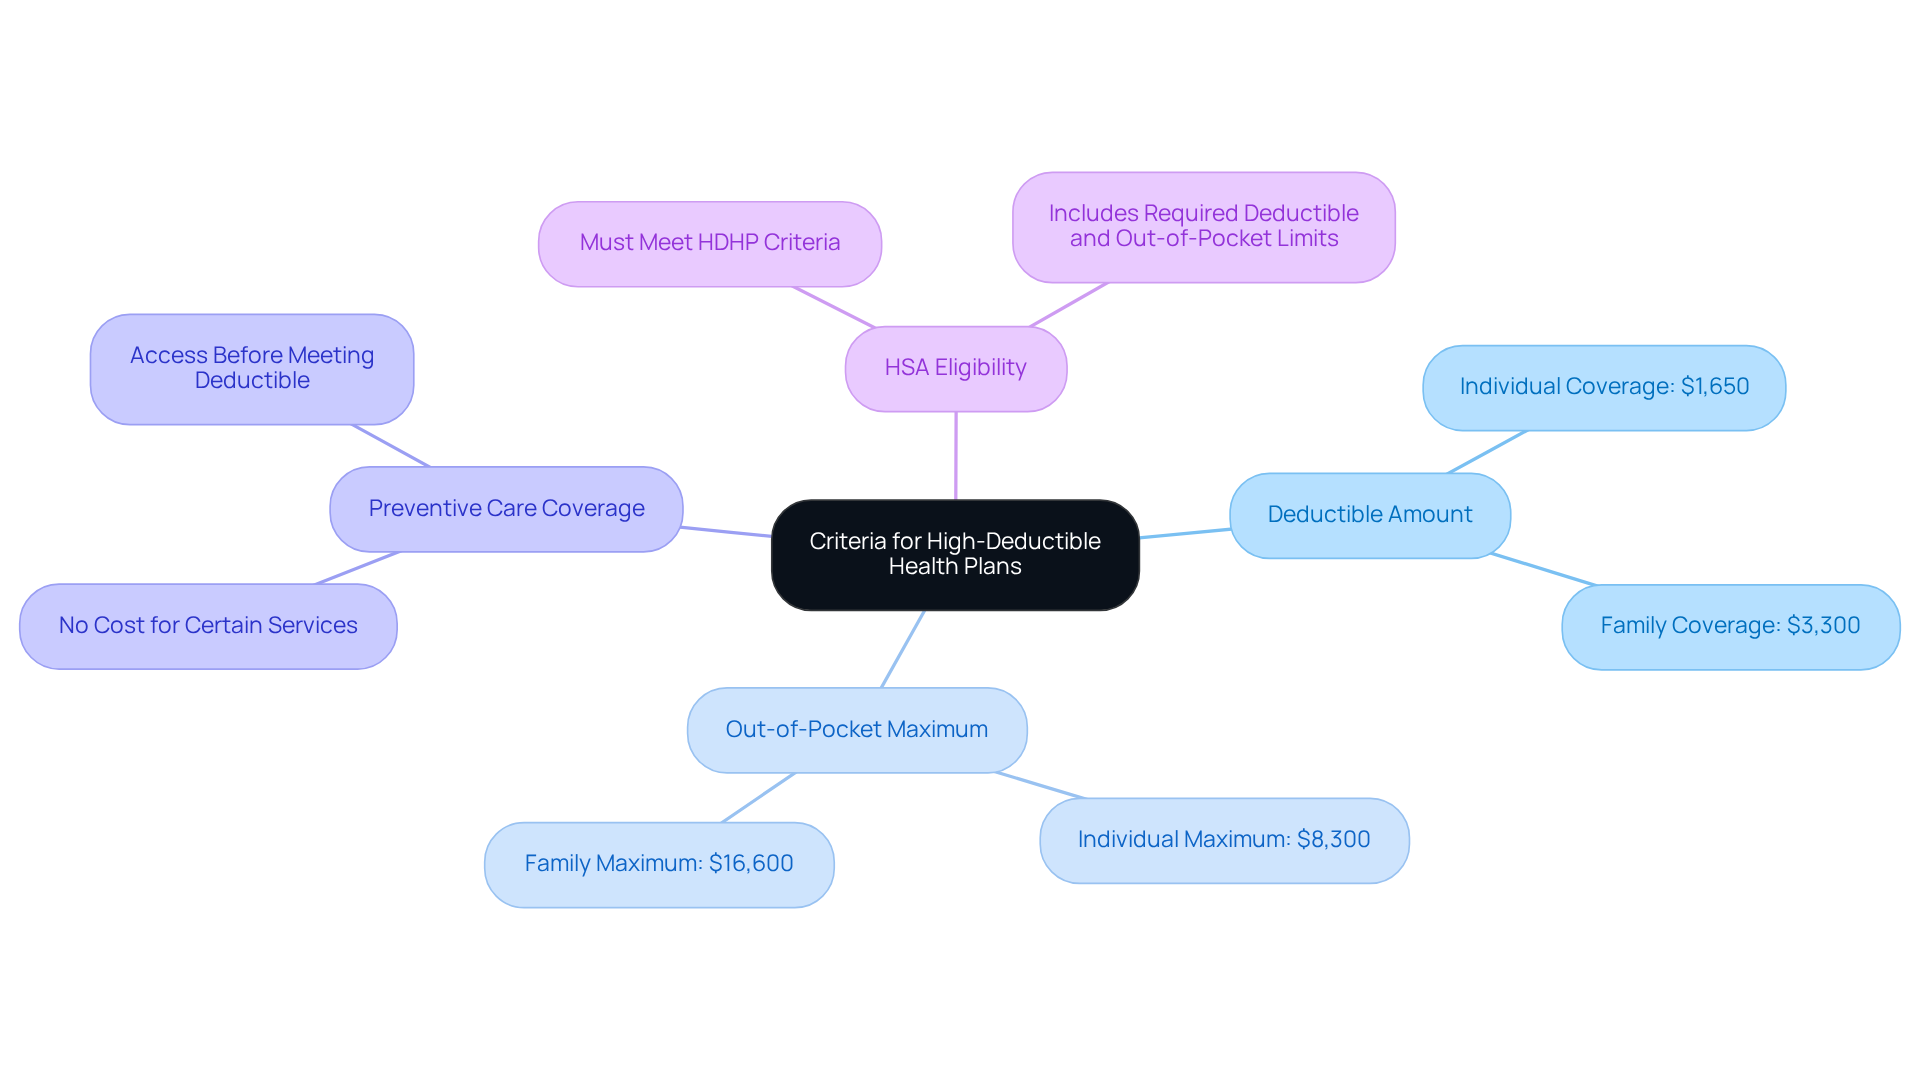
Determining how to tell if you have a high deductible health plan (HDHP) can feel overwhelming, but we’re here to help you navigate this journey. Let’s explore the key criteria together:
- Deductible Amount: For 2025, your plan should have a deductible of at least $1,650 for individual coverage and $3,300 for family coverage. This is an important step in understanding your plan’s structure.
- Out-of-Pocket Maximum: It’s crucial to know that the out-of-pocket maximum for HDHPs cannot exceed $8,300 for individuals and $16,600 for families in 2025. Keeping these limits in mind can help you plan better for your family’s needs.
- Preventive Care Coverage: One of the benefits of HDHPs is that they often cover certain preventive services at no cost, even before you’ve met your deductible. Imagine knowing that your family can access essential health services without worrying about extra costs. Check if your plan includes these valuable services.
- HSA Eligibility: If your health plan is HSA-qualified, it must meet the HDHP criteria. This means it should have the required deductible and out-of-pocket maximum limits. Understanding this can empower you to make informed decisions for your family’s financial health.
By considering these criteria, you can better assess how to tell if you have a high deductible health plan and ensure it aligns with your family’s priorities. Remember, we’re here for you every step of the way.
Verify Your Health Plan Type
To confirm whether you have a high-deductible health plan, let’s walk through some simple steps together:
- Review Your Coverage Documents: Begin by looking at your health coverage policy documents or summary of benefits. These important papers usually outline how to tell if you have a high deductible health plan by detailing the deductible and out-of-pocket maximum amounts, which gives you a clearer picture of your plan.
- Contact Your Provider: If you find the documents a bit confusing, don’t hesitate to reach out to your provider’s customer service. They are there to help you, so ask them directly how to tell if you have a high deductible health plan that meets the current IRS criteria.
- Check Online Resources: Many providers offer helpful digital tools or FAQs that can assist you in identifying your coverage type. Take a moment to visit your provider’s website for additional information that can make this process easier.
- Consult Your HR Department: If your medical coverage comes through your employer, your HR department is a great resource. They can clarify how to tell if you have a high deductible health plan and provide you with the necessary details.
Remember, we’re here for you as you navigate these important decisions for your family’s health and financial well-being. Together, we can make this journey smoother.

Understand the Implications of Having an HDHP
Navigating a high-deductible health plan (HDHP) can feel overwhelming, but knowing how to tell if you have a high deductible health plan can empower your family’s financial journey.
- Lower Premiums: One of the key advantages of HDHPs is their lower monthly premiums. This can free up funds for other important financial goals, like saving for your children’s education. For families like Allison and Brian, understanding how to tell if you have a high deductible health plan means having more resources available for thoughtful financial planning.
- Higher Out-of-Pocket Costs: However, it’s essential to be aware that you will need to cover more out-of-pocket costs before your insurance starts to help. This can pose a financial strain, particularly when learning how to tell if you have a high deductible health plan and unexpected medical expenses arise. Allison and Brian learned how to tell if you have a high deductible health plan by recognizing the importance of preparing for these costs through effective tax planning, including setting aside funds in a Health Savings Account (HSA).
- Health Savings Account (HSA) Benefits: If your HDHP qualifies for an HSA, you can contribute pre-tax dollars, which can be used for qualified medical expenses. This not only provides tax advantages but was also a key strategy for Allison and Brian, helping them optimize their tax situation while managing healthcare costs.
- Preventive Care: Many HDHPs cover preventive services at no charge, encouraging families to prioritize wellness check-ups and screenings. This proactive approach can lead to long-term savings and improved health outcomes for your loved ones.
- Financial Planning Considerations: As you consider an HDHP, it’s essential to understand how to tell if you have a high deductible health plan by reflecting on your family’s healthcare needs and financial situation. It may not be the best fit for those with chronic health issues or high medical expenses. Allison and Brian’s experience with Bright Advisers underscores the importance of integrating healthcare decisions with overall financial planning, ensuring that families are well-prepared for both expected and unexpected healthcare costs.
Remember, we’re here for you. Together, we can navigate this journey and find the best solutions for your family’s future.

Conclusion
Navigating the complexities of health insurance can feel overwhelming, especially when it comes to understanding high-deductible health plans (HDHPs). It’s important to recognize the characteristics and criteria that define an HDHP, as this knowledge is vital for families striving to balance healthcare costs with financial stability. By familiarizing yourself with the IRS guidelines for deductibles and out-of-pocket maximums, you can make informed decisions about your health coverage.
When identifying an HDHP, consider key factors such as:
- Deductible amounts
- Out-of-pocket limits
- Eligibility for Health Savings Accounts (HSAs)
Preventive care coverage is another significant benefit that enhances the value of an HDHP, allowing families to access essential health services without incurring additional costs. By reviewing policy documents, reaching out to providers, and consulting with HR departments, you can confidently determine your health plan type.
Ultimately, understanding how to identify and assess a high-deductible health plan empowers families to make strategic financial decisions. As you weigh the advantages and disadvantages of HDHPs, it’s essential to consider your unique healthcare needs and financial situation. Taking proactive steps to explore options, such as HSAs and preventive care, can lead to better health outcomes and financial security. Embracing this knowledge allows families to navigate their healthcare journey with confidence and clarity. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is a high-deductible health plan (HDHP)?
A high-deductible health plan (HDHP) is a type of health coverage that offers lower monthly premiums but comes with higher deductibles compared to traditional plans.
How can I determine if I have an HDHP?
You can determine if you have an HDHP by checking if your plan meets the IRS guidelines for 2025, which define an HDHP as having a deductible of at least $1,650 for individual coverage and $3,300 for family coverage.
What are the financial implications of having an HDHP?
While HDHPs have lower monthly premiums, they require you to pay higher out-of-pocket costs before your insurance begins to cover medical expenses, as you must meet the deductible first.
Are there any benefits associated with HDHPs?
Many HDHPs come with Health Savings Accounts (HSAs), which allow you to save money tax-free for medical expenses, helping you prepare for unexpected healthcare needs while managing your budget.
Who can benefit from choosing an HDHP?
Young parents and individuals looking to balance costs and care may find HDHPs beneficial, as they can save money on monthly premiums while still protecting their family’s health.
List of Sources

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin