

Overview
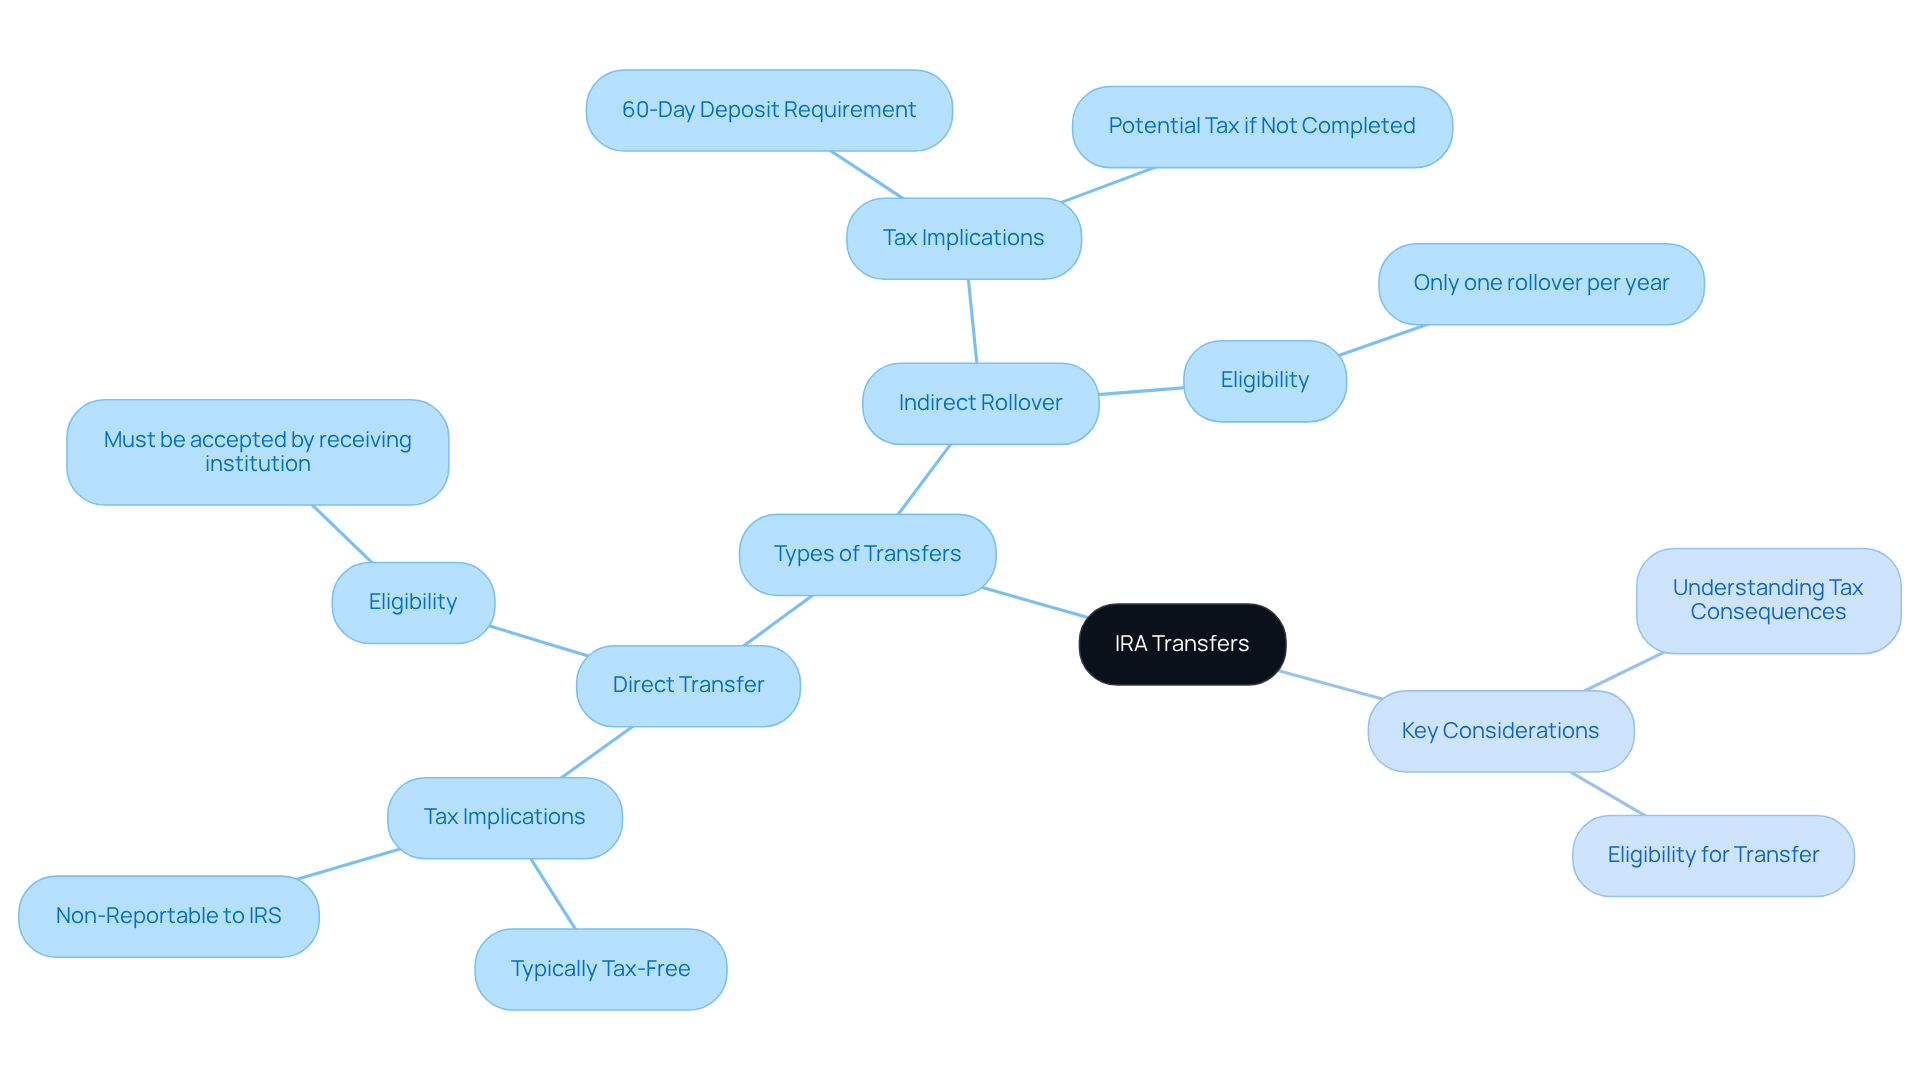
Transferring your IRA to another bank can feel overwhelming, but understanding the process can ease your worries. There are two main types of transfers:
- Direct transfers, which are tax-free
- Indirect rollovers, which require a 60-day deposit to avoid taxes
It’s essential to follow specific steps, like selecting a new provider and submitting transfer requests, to ensure everything goes smoothly.
Imagine if you could navigate this journey with confidence. The article outlines these processes clearly, addressing common challenges such as processing delays and tax implications. By providing a comprehensive guide, we aim to empower you with the knowledge needed for effective retirement planning.
Remember, you’re not alone in this. We’re here for you, ready to support you through each step of the transfer process. Together, we can ensure that your financial future aligns with your family’s values and aspirations.
Key Highlights:
- Types of IRA transfers include Direct Transfers (tax-free, no IRS reporting) and Indirect Rollovers (60-day deposit requirement to avoid taxes).
- Understanding tax implications is crucial; direct transfers are generally tax-free, while indirect rollovers can incur taxes if not completed timely.
- Ensure the receiving institution accepts the type of IRA you want to transfer to avoid complications.
- Steps to initiate an IRA transfer include choosing a new provider, opening an account, contacting the current provider, completing forms, submitting transfer requests, and monitoring the process.
- Common challenges include delays in processing, incomplete forms, transfer fees, tax implications, and ensuring account type compatibility.
- Post-transfer management tips include reviewing investment options, setting up automatic contributions, regularly monitoring performance, staying informed about fees, and educating oneself on retirement planning.
Introduction
Navigating the world of Individual Retirement Accounts (IRAs) can feel overwhelming, especially when you’re considering a transfer to a new bank. It’s important to understand the intricacies of this process, as it plays a vital role in ensuring your family’s financial stability and growth. This article offers a compassionate, step-by-step guide designed to empower you to seamlessly transfer your IRA. We’ll highlight essential concepts, potential challenges, and effective solutions that can help you along the way.
Imagine if you encounter unexpected delays or tax implications during the transfer process. It’s important to understand these details, as they can significantly impact your financial future. Together, we can explore strategies that safeguard your retirement savings while maximizing their benefits. Remember, we’re here for you on this journey, providing the support you need to navigate these important decisions for your family.
Understand IRA Transfers: Key Concepts and Types
Before you embark on the journey of how to transfer IRA to another bank, it’s important to grasp some key concepts that can make this process smoother for you and your family.
Types of IRA Transfers: Let’s explore the two main types of transfers you might encounter:
- Direct Transfer: Picture this as a seamless handoff, where funds move directly from one IRA to another without you ever taking possession. This method is typically tax-free and doesn’t require you to report anything to the IRS, allowing you to focus on what matters most.
- Indirect Rollover: In this scenario, you receive the funds and have 60 days to deposit them into a new IRA. It’s crucial to act within this timeframe to avoid any tax implications. Remember, you can only do one indirect rollover per year, so plan accordingly.
Tax Consequences: Understanding the tax implications of each transfer type is vital. Direct transfers are generally tax-free, providing peace of mind, while indirect rollovers can lead to taxes if not completed on time. It’s essential to be aware of these details to protect your family’s financial future.
Eligibility: Not all IRAs are eligible for transfer. Make sure the receiving institution accepts the type of IRA you wish to move, ensuring a smooth transition.
By familiarizing yourself with these concepts, you’ll be better prepared to understand how to transfer IRA to another bank effectively. Remember, we’re here for you, ready to support you every step of the way as you navigate this important financial decision for your family.
Initiate the Transfer: Steps to Start Your IRA Move
To start your journey toward a new IRA, let’s take it step by step together:
-
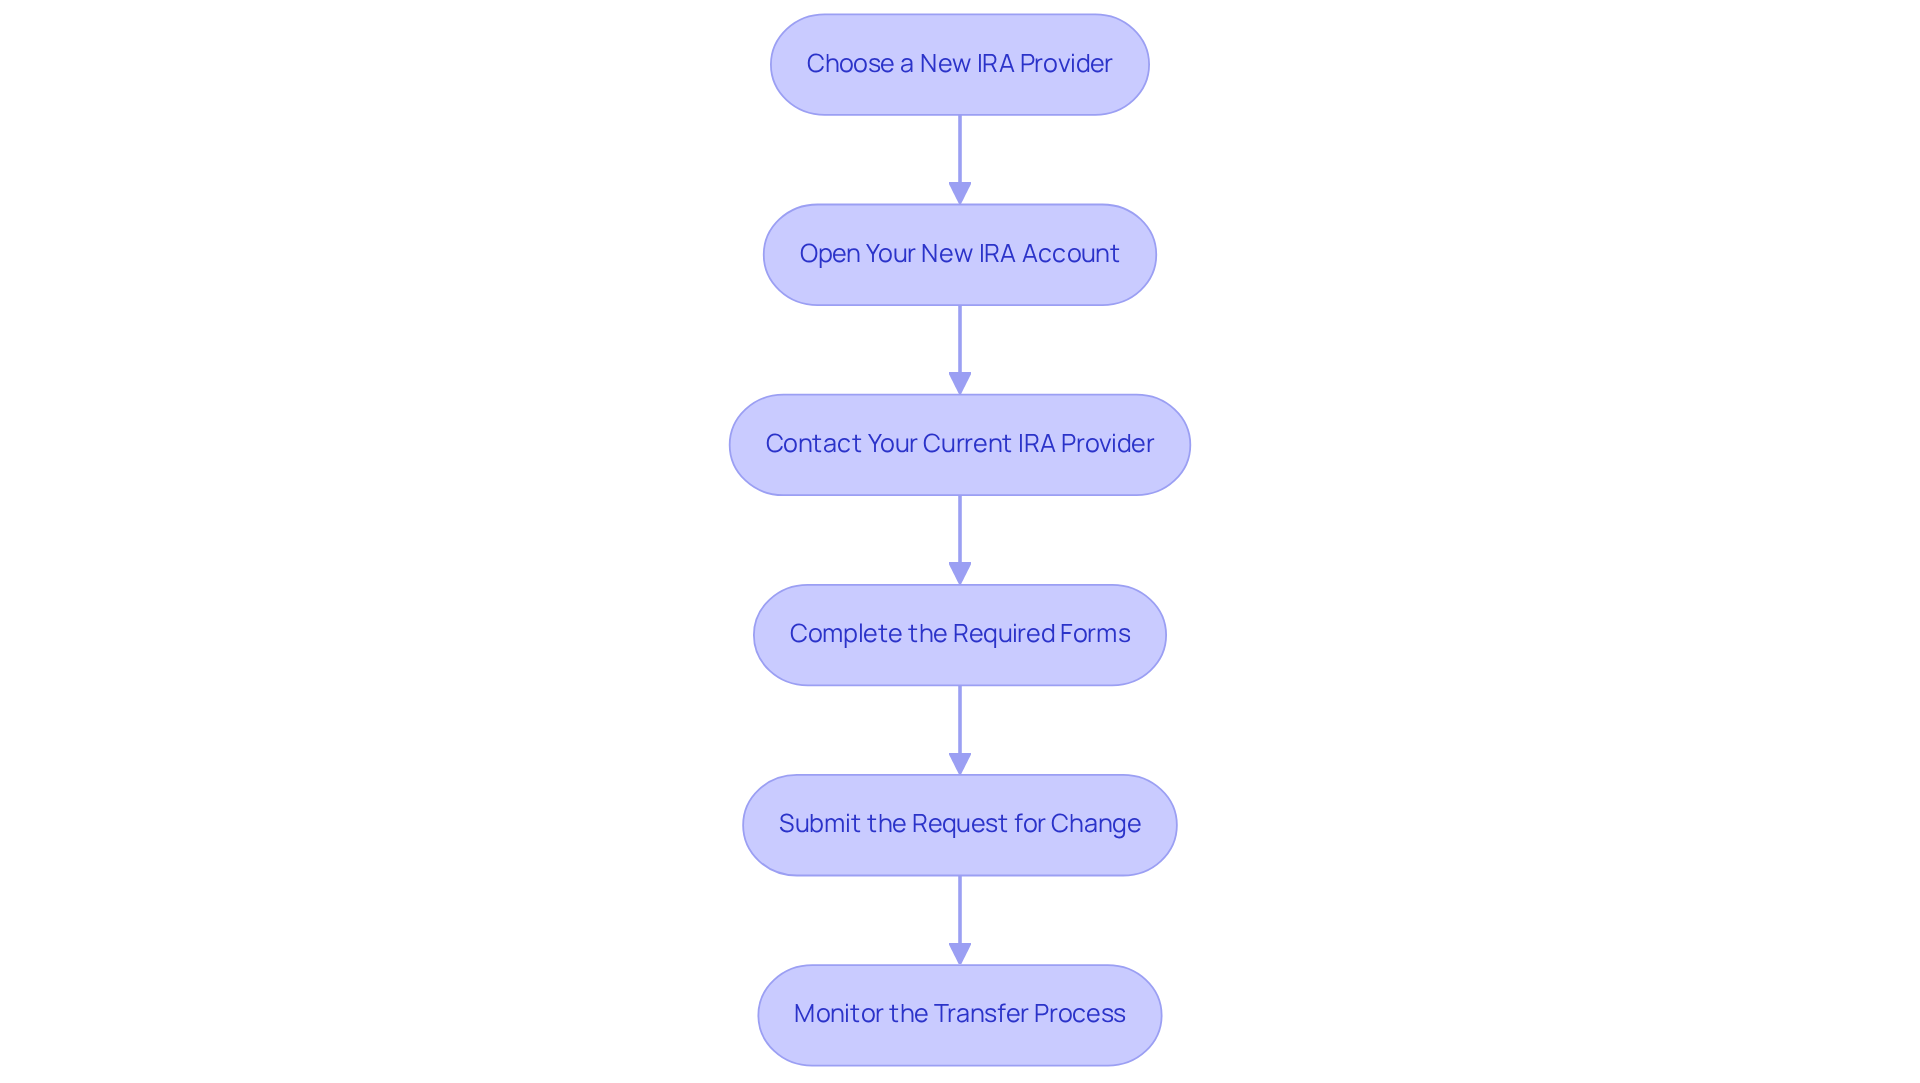
Choose a New IRA Provider: Begin by exploring options that resonate with your financial goals. Look for institutions that offer the type of IRA you wish to transfer to. Consider factors like fees, investment choices, and customer support. Remember, as Dayana Yochim, a previous expert on retirement and investing, reminds us, making informed choices is crucial for your financial future.
-
Open Your New IRA Account: If you haven’t already set up an IRA at your new institution, you’ll need to open one. This can often be done online and typically requires some personal information and identification.
-
Contact Your Current IRA Provider: Reach out to the financial institution currently holding your IRA. Let them know about your plan to transfer your account and inquire about any specific forms or procedures they might need from you.
-
Complete the Required Forms: Fill out the request forms provided by your new IRA provider. Be prepared to share details about your current IRA, including account numbers and the amount you wish to transfer.
-
Submit the Request for Change: Once you’ve completed the forms, send them to your new IRA provider. They will coordinate with your current provider to facilitate the transfer. Don’t forget to keep copies of all documents for your records.
-
Monitor the Transfer Process: Keep an eye on the status of your transfer, as it may take several weeks to complete. Stay in touch with both institutions to ensure everything is moving along smoothly.
As you navigate this process, consider that statistics show the average total participant contribution rate in early 2025 was 14.3%, while the average annual employee 401(k) contribution in 2024 was 7.7%. Additionally, individuals aged 50 and older can contribute up to $31,000 in 2025. By following these steps and keeping these statistics in mind, you can understand how to transfer IRA to another bank seamlessly. Together, we can navigate this journey toward a secure financial future for your family.
Navigate Challenges: Common Issues and Solutions in IRA Transfers
Understanding how to transfer IRA to another bank can feel overwhelming, but you’re not alone. Let’s explore some common challenges together and find effective solutions to help you navigate this process with confidence:
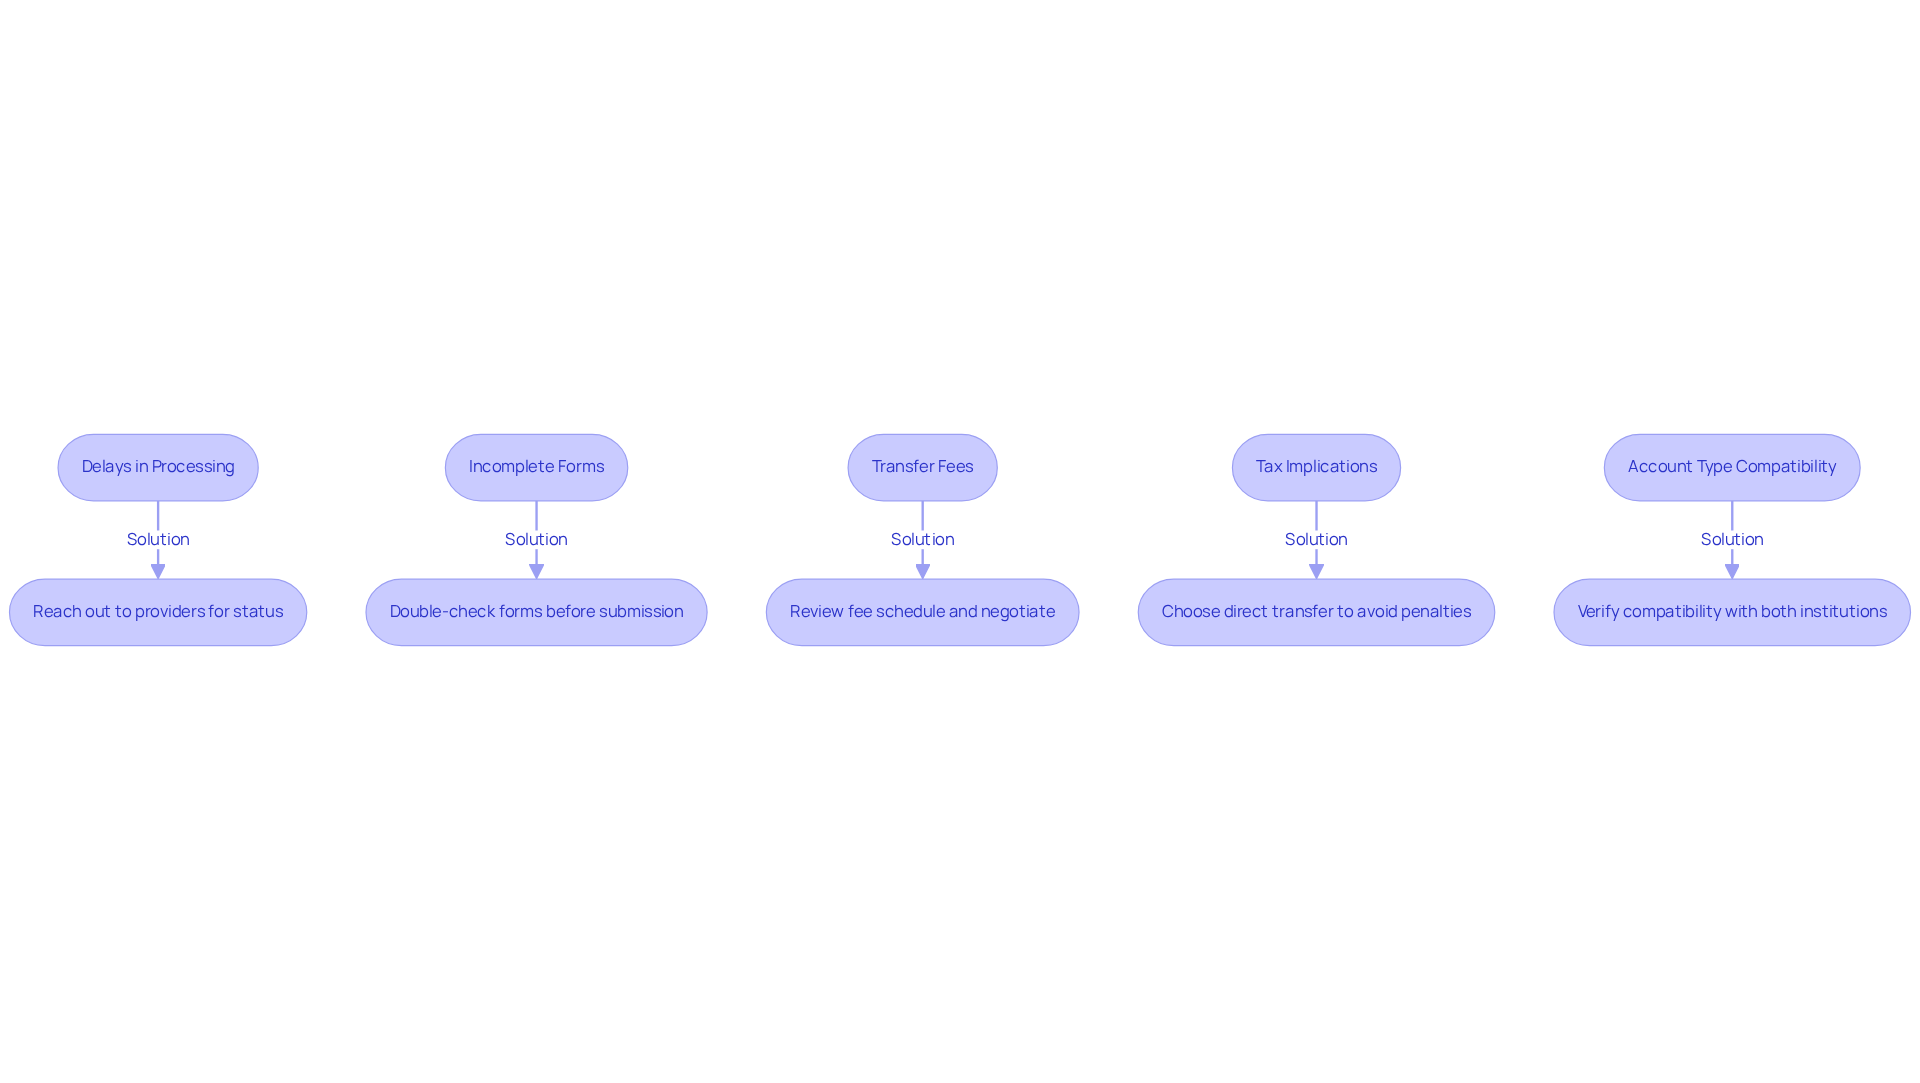
Imagine facing Delays in Processing. Transfers often take longer than expected, and it can be frustrating. If you find yourself waiting, reach out to both your existing and new IRA providers to check on the status of your transfer. Statistics show that respondents typically wait an average of two months for successful rollovers. Being proactive can make a big difference. Remember, a $100,000 rollover check with an eight-week delay could mean losing up to $76,000 in returns. It’s crucial to stay informed.
Next, let’s talk about Incomplete Forms. It’s essential to ensure that all forms are thoroughly completed and accurate. Missing information can lead to processing delays, and many IRA submission forms are sent incomplete. Before submitting, double-check your forms to avoid unnecessary setbacks. You might find it comforting to know that 80% of respondents were unable to complete a rollover unassisted, highlighting how complex this process can be.
Now, consider Transfer Fees. Some financial institutions may impose fees for transferring your IRA, which can impact your investment. Take a moment to review your current provider’s fee schedule. If fees are a concern, don’t hesitate to explore options for negotiation or seek out providers that offer no transaction fees. This can significantly affect your overall investment.
Be mindful of Tax Implications as well. It’s easy to accidentally execute an indirect rollover instead of a direct transfer, which can lead to tax penalties. Choosing a direct transaction whenever possible can help mitigate this risk. For instance, a $100,000 rollover check with even a two-week absence from the market could result in a loss of over $37,000 in potential returns over thirty years. The IRS does allow waivers of the 60-day rule under certain circumstances, which can provide relief if you miss the deadline.
Lastly, ensure Account Type Compatibility. Confirm that the type of IRA you are transferring is compatible with the new account. For example, transferring a Roth IRA to a traditional IRA is not permitted. It’s wise to verify compatibility with both institutions before proceeding to avoid complications.
By understanding these obstacles and their solutions, you can learn how to transfer IRA to another bank more efficiently, ensuring a brighter economic future for your family. Plus, the new self-certification process introduced by the IRS can help individuals who make innocent or accidental rollover mistakes, providing a pathway to rectify issues without incurring penalties. Remember, together, we can navigate this journey.
Manage Your New IRA: Post-Transfer Steps for Success
After completing your IRA transfer, it’s essential to manage your new account thoughtfully for long-term financial success. Here are some key steps to consider:
-
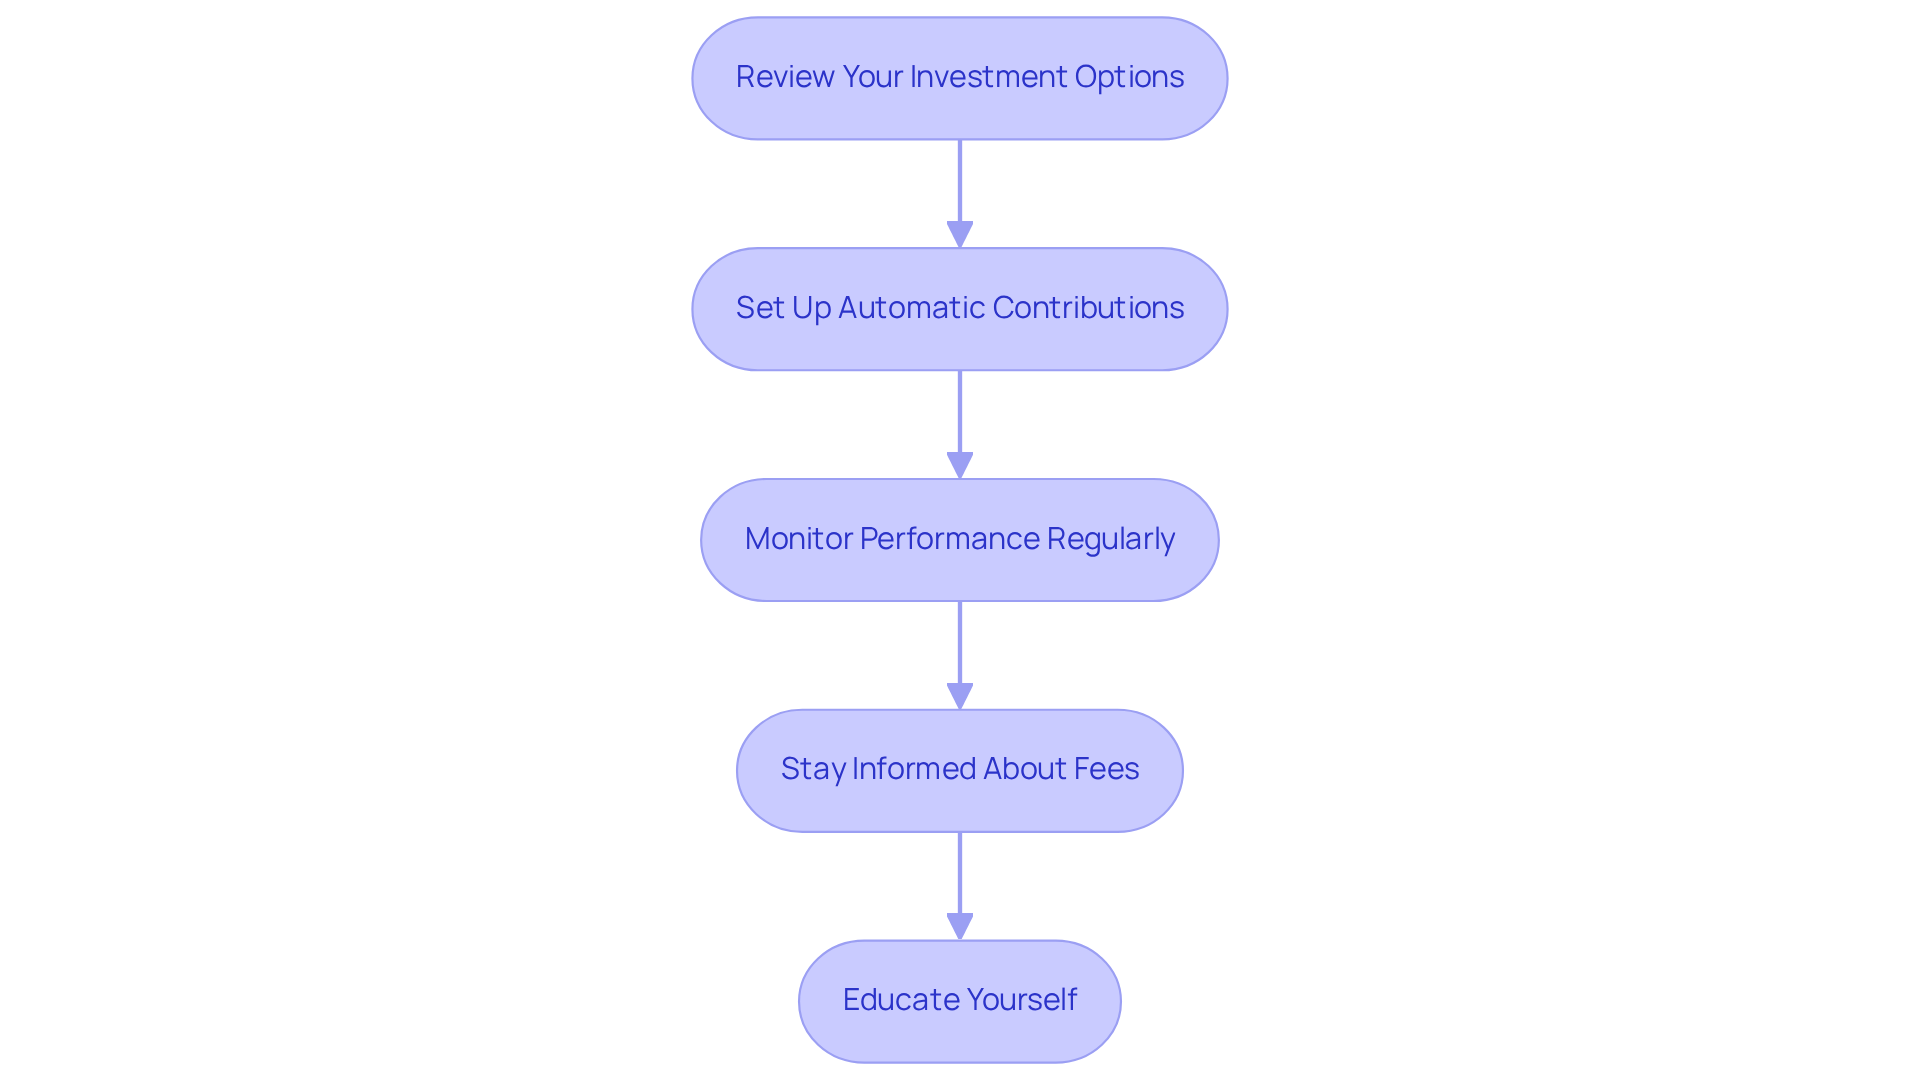
Review Your Investment Options: Take a moment to familiarize yourself with the investment choices available in your new IRA. Understanding your risk tolerance and financial goals can help you make informed decisions. Imagine the possibilities with larger 401(k) plans that offer a diverse range of options—this can truly benefit your investment strategy.
-
Set Up Automatic Contributions: Establishing automatic contributions to your IRA can significantly boost your retirement savings. Did you know that the average total participant contribution rate for retirement accounts was 14.3% in early 2025? This highlights the power of consistent contributions. Starting with a percentage of your income, like 10% to 15%, can help you build a solid foundation over time.
-
Monitor Performance Regularly: It’s important to frequently assess your IRA’s performance to ensure your investments align with your financial objectives. The average annual return for 401(k) accounts was 8.0% from 2020 to 2024, showcasing the potential for growth when managed wisely. Imagine the peace of mind that comes from knowing your investments are on track!
-
Stay Informed About Fees: Be vigilant about any fees associated with your new IRA. Understanding these costs is crucial to avoid unnecessary expenses that could diminish your returns. Many experts recommend comparing fees across different providers to find the most cost-effective options. Remember, every little bit counts toward your financial future.
-
Educate Yourself: Continuously seek knowledge about retirement planning and investment strategies. Utilize resources from your new IRA provider and consider reaching out to a planner for personalized advice. Knowledge is a powerful tool in making informed investment decisions, and we’re here to support you on this journey.
By actively managing your new IRA, you can maximize its potential and ensure it effectively contributes to your long-term financial security. Together, we can navigate this journey for a brighter future for you and your family.
Conclusion
Transferring an IRA to another bank is a significant financial decision, one that can greatly impact your future savings and investments. It’s essential to understand the intricacies of this process, including the different types of transfers and potential tax implications, to ensure a smooth transition for you and your family. By taking informed steps—like choosing the right provider and managing the transfer effectively—you can safeguard your financial future.
Throughout this guide, we’ve highlighted key concepts, from differentiating between direct and indirect transfers to addressing common challenges such as processing delays and incomplete forms. It’s crucial to maintain proactive communication with financial institutions and to monitor the transfer process closely. Additionally, managing your new IRA post-transfer—through regular performance reviews, automatic contributions, and ongoing education—will help maximize your investment potential.
Ultimately, the journey of transferring an IRA is not just about moving funds; it’s about taking control of your financial destiny. Imagine if you could navigate this process with confidence, ensuring that your retirement savings are positioned for growth and stability. By applying the insights and strategies we’ve discussed, you can make informed decisions that lead to a more secure financial future for you and your family. Remember, taking action today can make all the difference tomorrow. We’re here for you, ready to assist you on this important journey.
Frequently Asked Questions
What are the main types of IRA transfers?
The two main types of IRA transfers are Direct Transfers and Indirect Rollovers. A Direct Transfer involves funds moving directly from one IRA to another without you taking possession, while an Indirect Rollover means you receive the funds and must deposit them into a new IRA within 60 days.
What is a Direct Transfer?
A Direct Transfer is a seamless handoff where funds move directly from one IRA to another without you ever taking possession of the funds. This method is typically tax-free and does not require reporting to the IRS.
What is an Indirect Rollover?
An Indirect Rollover is when you receive the funds from your IRA and have 60 days to deposit them into a new IRA. It is important to complete this within the timeframe to avoid tax implications.
What are the tax consequences of IRA transfers?
Direct Transfers are generally tax-free, while Indirect Rollovers can lead to taxes if the funds are not deposited into a new IRA within 60 days. Understanding these implications is crucial for protecting your financial future.
Are all IRAs eligible for transfer?
No, not all IRAs are eligible for transfer. It is important to ensure that the receiving institution accepts the type of IRA you wish to move to facilitate a smooth transition.
Why is it important to understand IRA transfer concepts?
Familiarizing yourself with IRA transfer concepts helps you navigate the process effectively, ensuring you make informed decisions that protect your family’s financial future.
List of Sources
- Understand IRA Transfers: Key Concepts and Types
- Rollovers vs. Transfers: Moving IRA Funds – Equity Trust (https://trustetc.com/blog/transfer-rollover-changing-custodians)
- What is an IRA Rollover: Types, Rules, and Benefits | TIAA (https://tiaa.org/public/retire/financial-products/iras/rollovers)
- Annual IRA Rollovers of More than $1 Trillion by 2030, Study Says (https://asppa-net.org/news/2025/7/annual-ira-rollovers-of-more-than-$1-trillion-by-2030-study-says)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- Rollovers of retirement plan and IRA distributions | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/rollovers-of-retirement-plan-and-ira-distributions)
- Initiate the Transfer: Steps to Start Your IRA Move
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- Navigate Challenges: Common Issues and Solutions in IRA Transfers
- 401(k) Rollover Delays: Costly Mistakes to Avoid (https://401kspecialistmag.com/401k-rollover-delays-could-cost-nearly-76k-in-lost-savings)
- Did You Miss the 60-Day Deadline for Your IRA Rollover? – Wright Ford Young & Co. (https://cpa-wfy.com/did-you-miss-the-60-day-deadline-for-your-ira-rollover)
- IRS Eases Rules To Fix IRA 60-Day Rollover Mistakes (https://kitces.com/blog/rev-proc-2016-47-self-certification-of-late-60-day-rollover-contribution-hardship-waiver)
- 10 IRA Rollover Mistakes to Avoid (https://jlsmithgroup.com/blog/10-ira-rollover-mistakes-to-avoid)
- Missed the 60-Day Rollover Deadline? Here’s How to Fix It (https://richmondbrothers.com/missed-the-60-day-ira-rollover-deadline-heres-how-to-fix-it)
- Manage Your New IRA: Post-Transfer Steps for Success
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Dividend.com (https://dividend.com/dividend-education/41-inspiring-and-intelligent-investing-quotes)
- 2025 IRA Contribution And Income Limits: What Retirement Savers Need To Know | Bankrate (https://bankrate.com/retirement/401k-ira-contribution-and-income-limits)
- 10 Great Investing Quotes to Consider (https://smartasset.com/investing/top-10-investing-quotes-of-all-time)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading