

Key Highlights
- Concentrated stock positions can pose significant risks to a family’s financial stability, with over 40% of companies in the Russell 3000 experiencing steep price drops since 1980.
- Emotional attachment to company shares can cloud judgement, making it essential to limit any single investment to no more than 10% of the total portfolio.
- Families should assess their exposure to concentrated equity and define clear financial goals before unwinding large stock positions.
- Gradual selling, tax-loss harvesting, and using exchange funds are effective strategies for unwinding concentrated positions while managing tax implications.
- Understanding capital gains tax and timing sales can significantly impact financial outcomes during the unwinding process.
- Consulting with a financial advisor, such as those at Bright Advisers, can provide valuable insights and help families navigate the complexities of concentrated investments.
Introduction
What if your family’s dreams hinge on a single investment? Concentrated stock positions can offer significant rewards, but they also pose substantial risks that can jeopardize long-term stability. Together, let’s navigate effective strategies for unwinding large positions in concentrated company stock, helping families understand the complexities of:
- Diversification
- Tax implications
- Risk management
How can we honor our emotional attachments while ensuring a secure financial future for our families?
Understand Concentrated Stock Positions and Their Risks
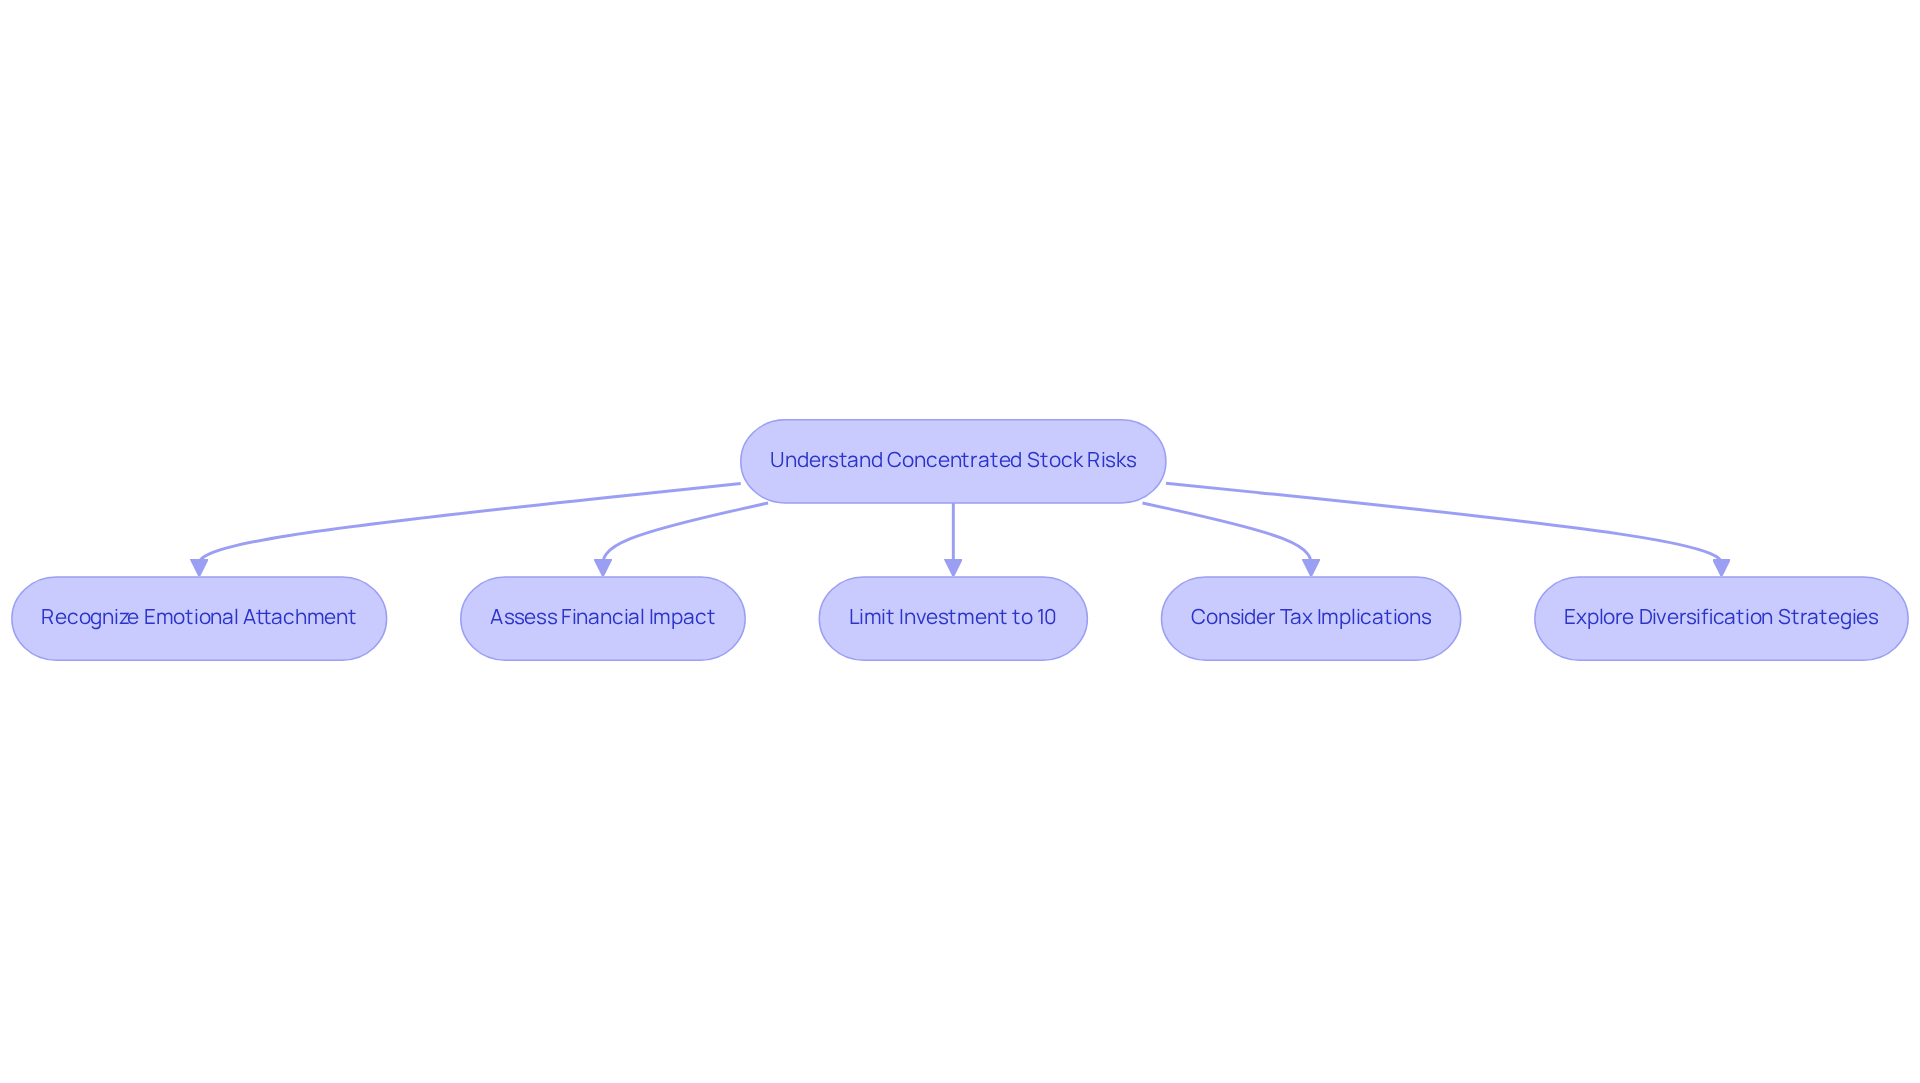
Imagine feeling the weight of your family’s future resting on a single investment; it can be both a blessing and a burden. When you put a big chunk of your wealth into one company’s shares, it can feel like a safe bet, especially if it’s tied to your job or a long-term plan. Sure, this can lead to big gains, but it also comes with some serious risks that can shake your financial foundation.
A single share can swing wildly in price, putting your family’s financial peace at risk. Did you know that more than 40% of companies in the Russell 3000 have faced steep price drops since 1980? It shows just how risky it can be to rely too much on one investment.
It’s easy to get attached to your company’s shares, but that emotional bond can cloud your judgment when it’s time to sell or diversify. That emotional pull can lead to tough choices, especially when the market takes a downturn. Putting too much into one investment can leave your portfolio vulnerable, which isn’t what you want for your family’s future. It’s wise to keep any one investment to no more than 10% of your total portfolio to protect your family’s financial health.
Concentrated investments can make your portfolio more volatile; in fact, 85% of stocks in the Russell 1000 have dropped more than the index itself since 2014. If you sell a big chunk of your investment, you might face hefty taxes, which can make it hard to let go. For example, if you have a $10 million investment with no cost basis, you could owe around $2.38 million in taxes, which is a lot to consider. Understanding these risks is the first step in creating a plan on how to unwind a large position concentrated company stock and manage your investments gradually.
Take Allison and Brian, for instance; they faced these challenges head-on and found support through Bright Advisers. With smart tax planning, they not only secured their kids’ education but also found a way to retire earlier than they thought possible. Using strategies like planned giving can help lower the risks of concentrated investments while also providing tax advantages. Recognizing and tackling these risks is crucial for families who want to protect their financial future while managing the challenges of concentrated investments.
Assess Your Exposure and Define Your Financial Goals
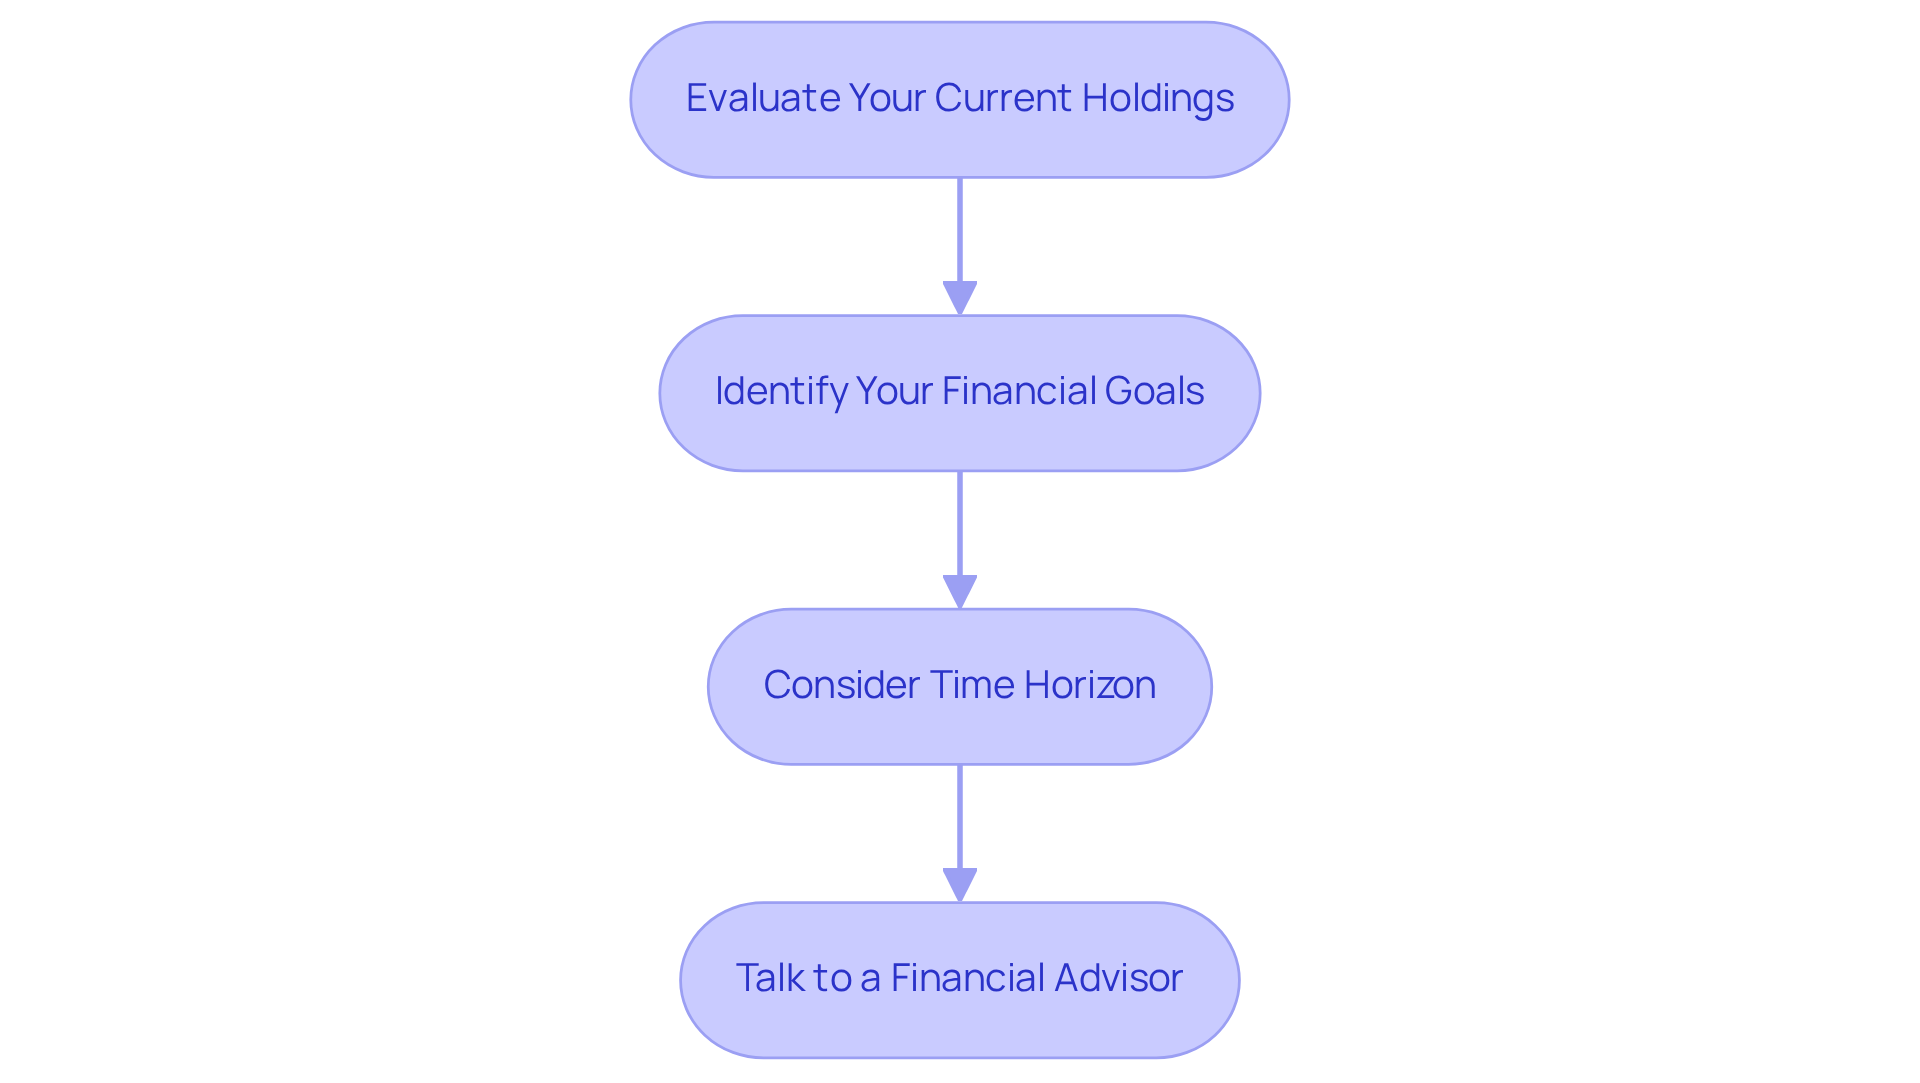
Imagine the weight of having your family’s financial future resting on a single investment. Before understanding how to unwind a large position concentrated company stock, it’s crucial to evaluate your exposure and clarify your financial objectives. Here are some gentle steps to guide you:
- Evaluate Your Current Holdings: Take a moment to see how much of your total wealth is tied up in concentrated equity. Understanding this can help you grasp your level of exposure and its potential impact on your family’s financial health.
- Identify Your Financial Goals: Think about what you hope to achieve by unwinding your investment. Are you looking to diversify, reduce risk, or generate liquidity for other needs? Clearly defining your goals will help you understand how to unwind a large position concentrated company stock.
- Consider Time Horizon: Reflect on your investment time horizon. If you need access to funds soon, your strategy may differ from someone with a longer time frame.
- Talk to a Financial Advisor: Engaging with a financial advisor can really help you feel more at ease. They can provide valuable insights into your situation and help you develop a plan that aligns with your family’s financial goals.
Sometimes, concentrated equity comes from your job or a merger, but it can be risky for your family’s future. Historical failures of companies like Lehman Brothers and Enron remind us of the dangers of holding too much wealth in a single stock. Financial advisors often suggest keeping single-stock allocations to no more than 10% of your portfolio value to help reduce these risks. Plus, capital gains taxes can reach up to 37%, making diversification a smart choice for many families.
When you take the time to understand your investments and set clear goals, you can build a stronger, more secure future for your family. Taking these steps can help you feel more secure and confident in your family’s financial journey.
Explore Strategies for Unwinding Concentrated Positions
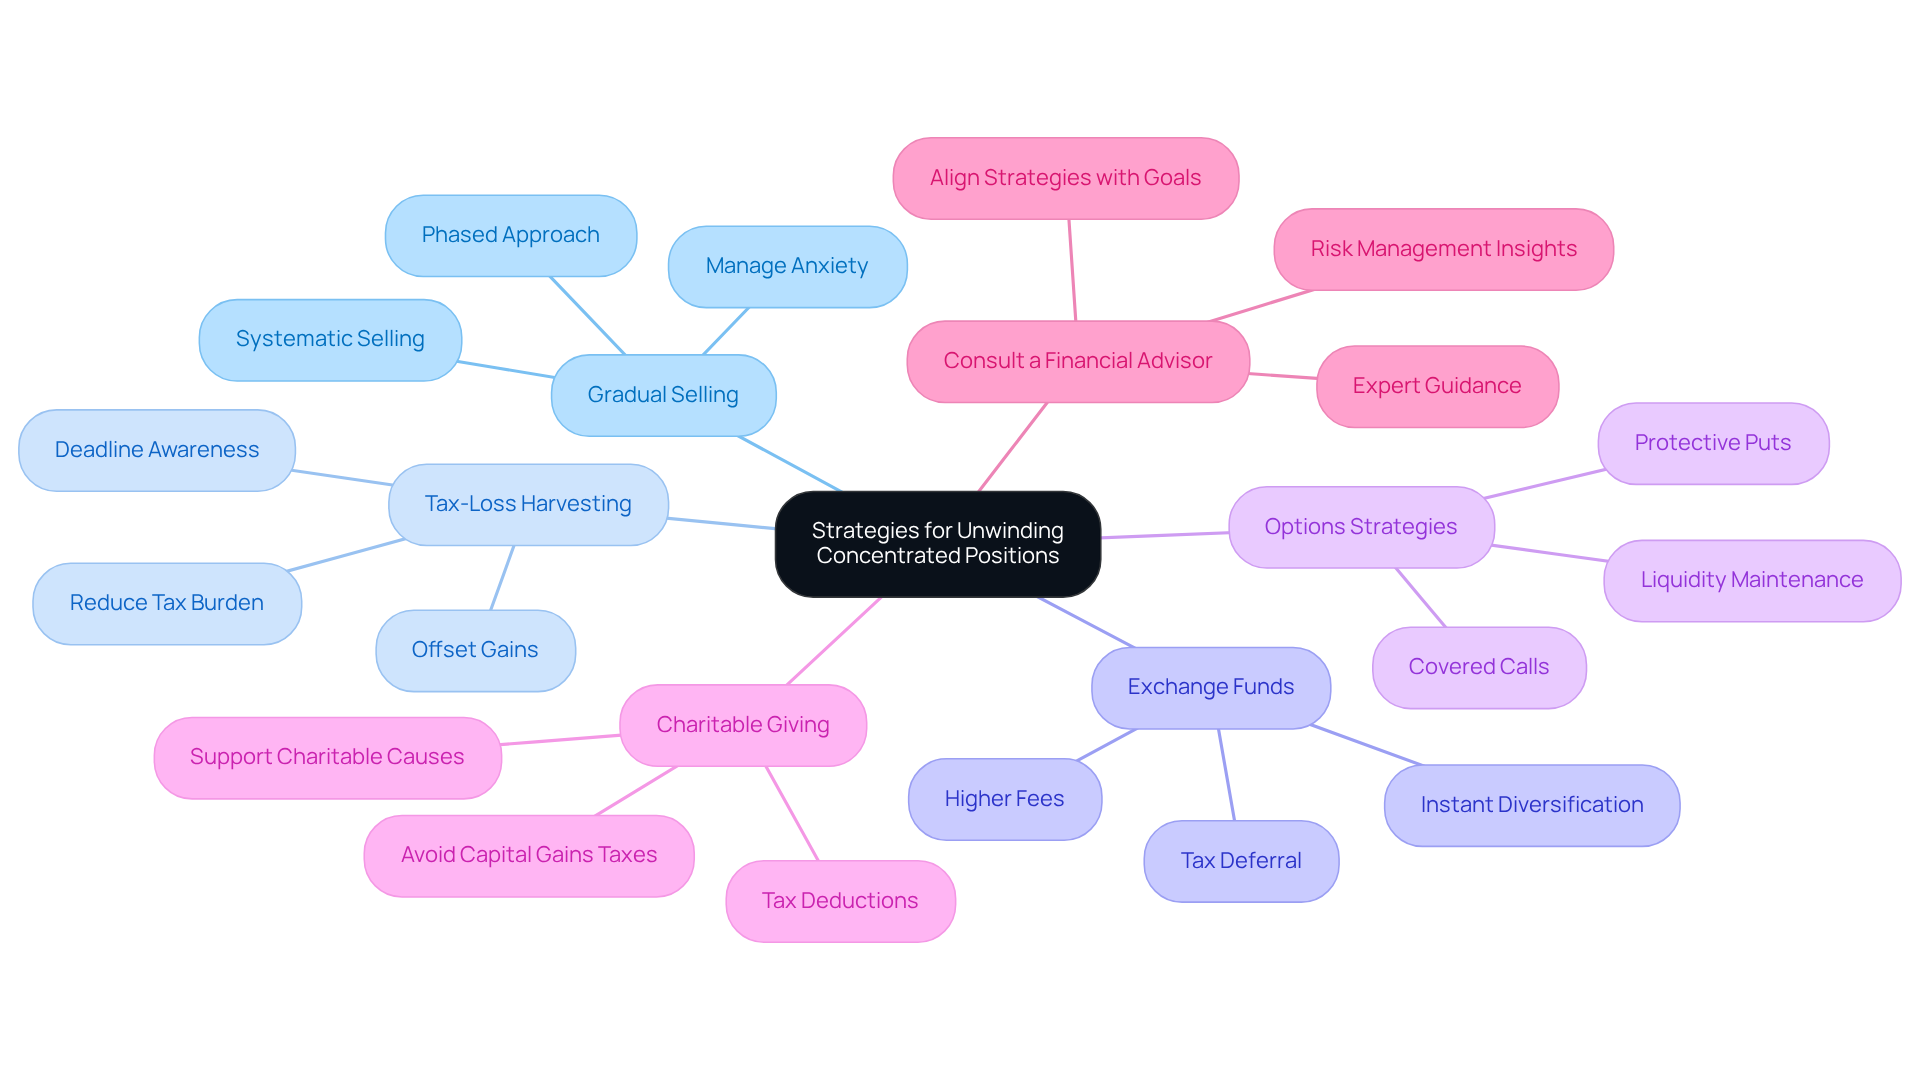
Imagine feeling overwhelmed by the thought of dismantling your investment strategy without a clear plan. Here are several gentle strategies to consider:
-
Gradual Selling: Instead of selling all at once, think about a phased approach. Gradually selling portions of your shares over time can help ease the stress of large transactions while understanding how to unwind a large position concentrated company stock. Research shows that many families face the risk of losing a significant portion of their investments, so this strategy can help you manage that anxiety.
-
Tax-Loss Harvesting: If you have other investments that have lost value, consider selling them to offset gains from your concentrated stock sale. This can help lighten your overall tax burden. For instance, if you recognize a $30,000 loss on one investment, it can counterbalance profits from another, potentially saving you a good amount in taxes. Bright Advisers integrates advanced tax planning strategies to help families navigate these complexities effectively.
-
Exchange Funds: These allow you to swap your focused stock for shares in a diversified fund, deferring taxes while achieving diversification. This approach is particularly beneficial for those with high tax rates and minimal liquidity needs, as it provides instant diversification without immediate tax consequences. A case study on using exchange funds for diversification illustrates how families can achieve this without incurring immediate tax liabilities.
-
Options strategies, such as covered calls or protective puts, can provide income or downside protection while learning how to unwind a large position concentrated company stock. These strategies can help manage risk and maintain liquidity, facilitating a smoother transition away from focused holdings. Bright Advisers employs innovative strategies to enhance portfolio performance during this process.
-
Charitable Giving: Donating appreciated assets to charity can provide a tax deduction while allowing you to diversify your holdings without incurring capital gains taxes. This approach not only supports charitable objectives but also assists in managing focused investments effectively.
-
Consult a Financial Advisor: Working with a financial advisor can help you navigate these strategies effectively, ensuring that your approach aligns with your financial goals and risk tolerance. Advisors at Bright Advisers can offer insights into the best practices for managing focused equity holdings and assist you in implementing a strategy that fits your unique circumstances.
Taking these steps today can safeguard your family’s financial future and bring peace of mind. Remember, proactive management is essential to protect your family’s well-being. We’re here for you, ready to support you on this journey.
Manage Tax Implications During the Unwinding Process
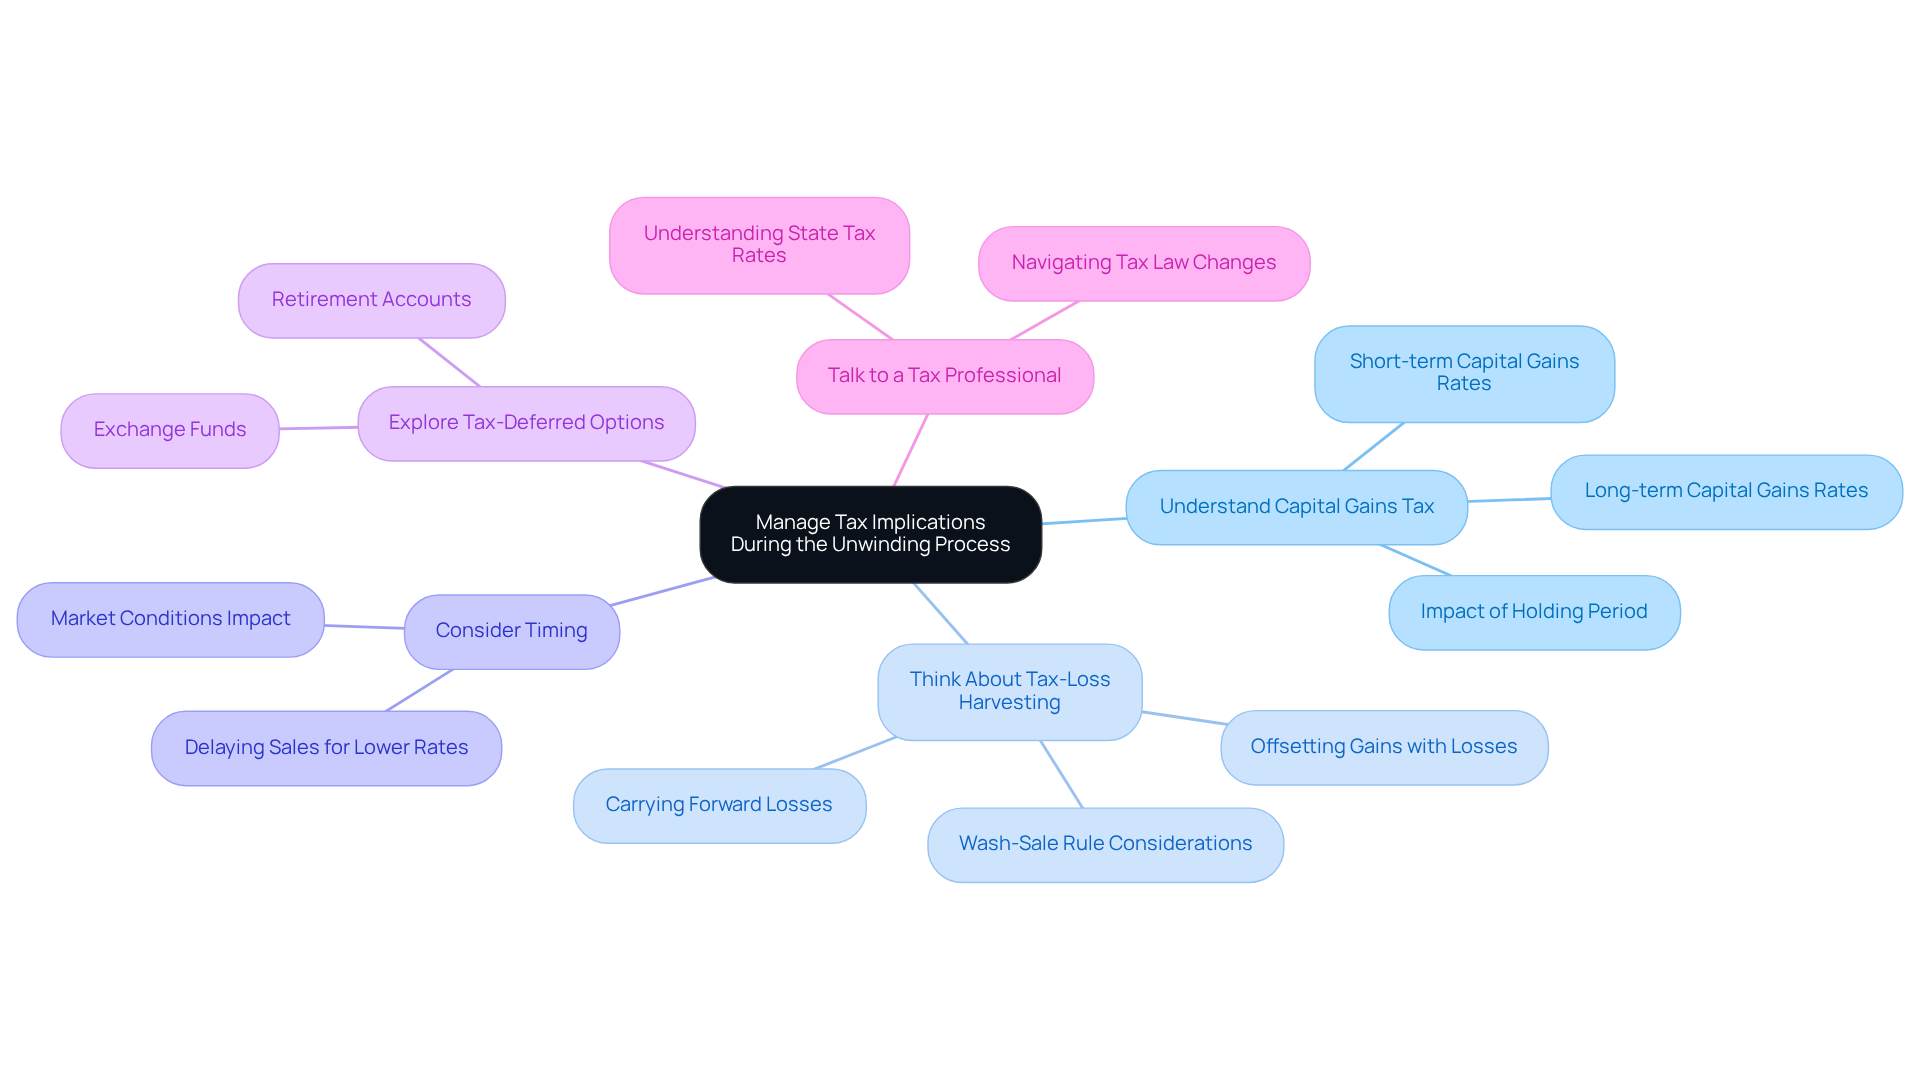
Imagine facing the complexities of taxes while trying to secure your family’s financial future. Tax consequences can significantly influence your financial results when considering how to unwind a large position concentrated in company stock. Here are some key considerations to help you navigate this journey:
-
Understand Capital Gains Tax: If you sell stock that has increased in value, you might face capital gains tax. For 2026, long-term capital gains tax rates are 15% for single filers with taxable income up to $49,450 and 20% for those over $545,500. It’s important to familiarize yourself with how these rates apply to your situation.
-
Think About Tax-Loss Harvesting: Offsetting gains with losses from other investments can help ease your tax burden. This strategy is particularly effective in volatile markets, allowing families like yours to manage their tax responsibilities more effectively.
-
Consider Timing: The timing of your sales can impact your tax situation. If you anticipate a decrease in income in the following year, delaying sales may allow you to benefit from lower tax rates.
-
Explore Tax-Deferred Options: Strategies such as exchange funds or certain retirement accounts can allow you to defer taxes while diversifying your holdings. This is crucial for long-term financial planning and securing your family’s future.
-
Talk to a Tax Professional: Engaging with a tax advisor can help you feel more confident about your tax situation and guide you through the complexities. This is especially important given the varying state tax rates and potential changes in tax laws.
With the right support, you can turn these challenges into opportunities for your family’s growth and security.
Conclusion
Imagine feeling secure about your family’s financial future, even when faced with concentrated company stock. You might feel uncertain about the risks that come with concentrated investments, but it’s important to know how to manage them to help your family feel secure. When you take a caring approach, you can help protect your family from potential losses and enhance your overall financial stability.
Let’s talk about some important steps to consider when looking at your investments. Evaluating your current holdings and defining your financial goals can make a big difference. These strategies can really help your family manage your investments better, whether it’s through gradual selling, tax-loss harvesting, or charitable giving. Each of these methods offers unique benefits that can help you navigate the complexities of concentrated stock positions while managing tax implications effectively.
Talking to a financial advisor can really help you find the right path for your family. They can provide tailored guidance to ensure that your unwinding process aligns with your individual financial objectives. Taking charge of your investments is key to keeping your family’s wealth safe. When you take steps to diversify, you’re helping your family feel more secure.
Using these strategies can give your family peace of mind, protecting against market volatility and fostering confidence in achieving long-term financial goals. If you’re ready to take the next step, consulting with a financial advisor can be a pivotal moment in this journey.
Frequently Asked Questions
What is a concentrated stock position?
A concentrated stock position occurs when a significant portion of an individual’s wealth is invested in a single company’s shares, often tied to their job or long-term plans.
What are the risks associated with concentrated stock positions?
Concentrated stock positions can lead to significant financial risks, including price volatility, emotional attachment that clouds judgment, and potential tax implications when selling a large investment.
How common are steep price drops in concentrated stock positions?
More than 40% of companies in the Russell 3000 have experienced steep price drops since 1980, highlighting the risks of relying heavily on one investment.
What is a recommended strategy for managing concentrated stock positions?
It is advisable to limit any single investment to no more than 10% of your total portfolio to protect your family’s financial health.
How can concentrated investments affect portfolio volatility?
Concentrated investments can increase portfolio volatility; for instance, 85% of stocks in the Russell 1000 have dropped more than the index itself since 2014.
What tax implications should be considered when selling a concentrated stock position?
Selling a large portion of a concentrated stock position can result in hefty taxes. For example, a $10 million investment with no cost basis could incur around $2.38 million in taxes.
How can families manage the risks of concentrated investments?
Families can manage these risks through smart tax planning and strategies like planned giving, which can lower risks while providing tax advantages.
Can you provide an example of how families have successfully navigated concentrated stock positions?
Allison and Brian faced challenges with their concentrated stock position but found support through Bright Advisers. With effective tax planning, they secured their children’s education and were able to retire earlier than expected.
List of Sources
- Understand Concentrated Stock Positions and Their Risks
- Concentrated stock positions: High rewards, higher risks – What to know before betting big on one stock (https://russellinvestments.com/content/ri/us/en/insights/russell-research/2025/02/concentrated-stock-positions-high-rewards-higher-risks–what-to-.html)
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- Turn concentrated stock risk into potential tax-savings reward (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/concentrated-stock-risk)
- How to Reduce Risk & Diversify Concentrated Stock Positions (https://privatebank.bankofamerica.com/articles/concentrated-stock-positions.html)
- Concentrated Investing Quotes by Allen C. Benello (https://goodreads.com/work/quotes/50147795-concentrated-investing-strategies-of-the-world-s-greatest-concentrated)
- Assess Your Exposure and Define Your Financial Goals
- Turn concentrated stock risk into potential tax-savings reward (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/concentrated-stock-risk)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Concentrated Stock Position Calculator | Parametric Portfolio Associates (https://parametricportfolio.com/tools/concentrated-stock-position-calculator)
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- Explore Strategies for Unwinding Concentrated Positions
- Tax-Efficient Ways to Diversify Concentrated Stock Positions (https://financialplanningassociation.org/learning/publications/journal/OCT24-tax-efficient-ways-diversify-concentrated-stock-positions-OPEN)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- What is Tax-Loss Harvesting? Rules & Examples | New York Life (https://newyorklife.com/articles/what-is-tax-loss-harvesting)
- Tax-Loss Harvesting Strategies: How They Work (https://am.gs.com/en-us/advisors/campaign/tax-loss-harvesting-strategies-how-they-work)
- Manage Tax Implications During the Unwinding Process
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- What Is Capital Gains Tax? 2026 Rates Explained (https://nw.bank/blog-detail/blog/2026/05/05/what-is-capital-gains-tax–2026-rates-explained)
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading