

Key Highlights:
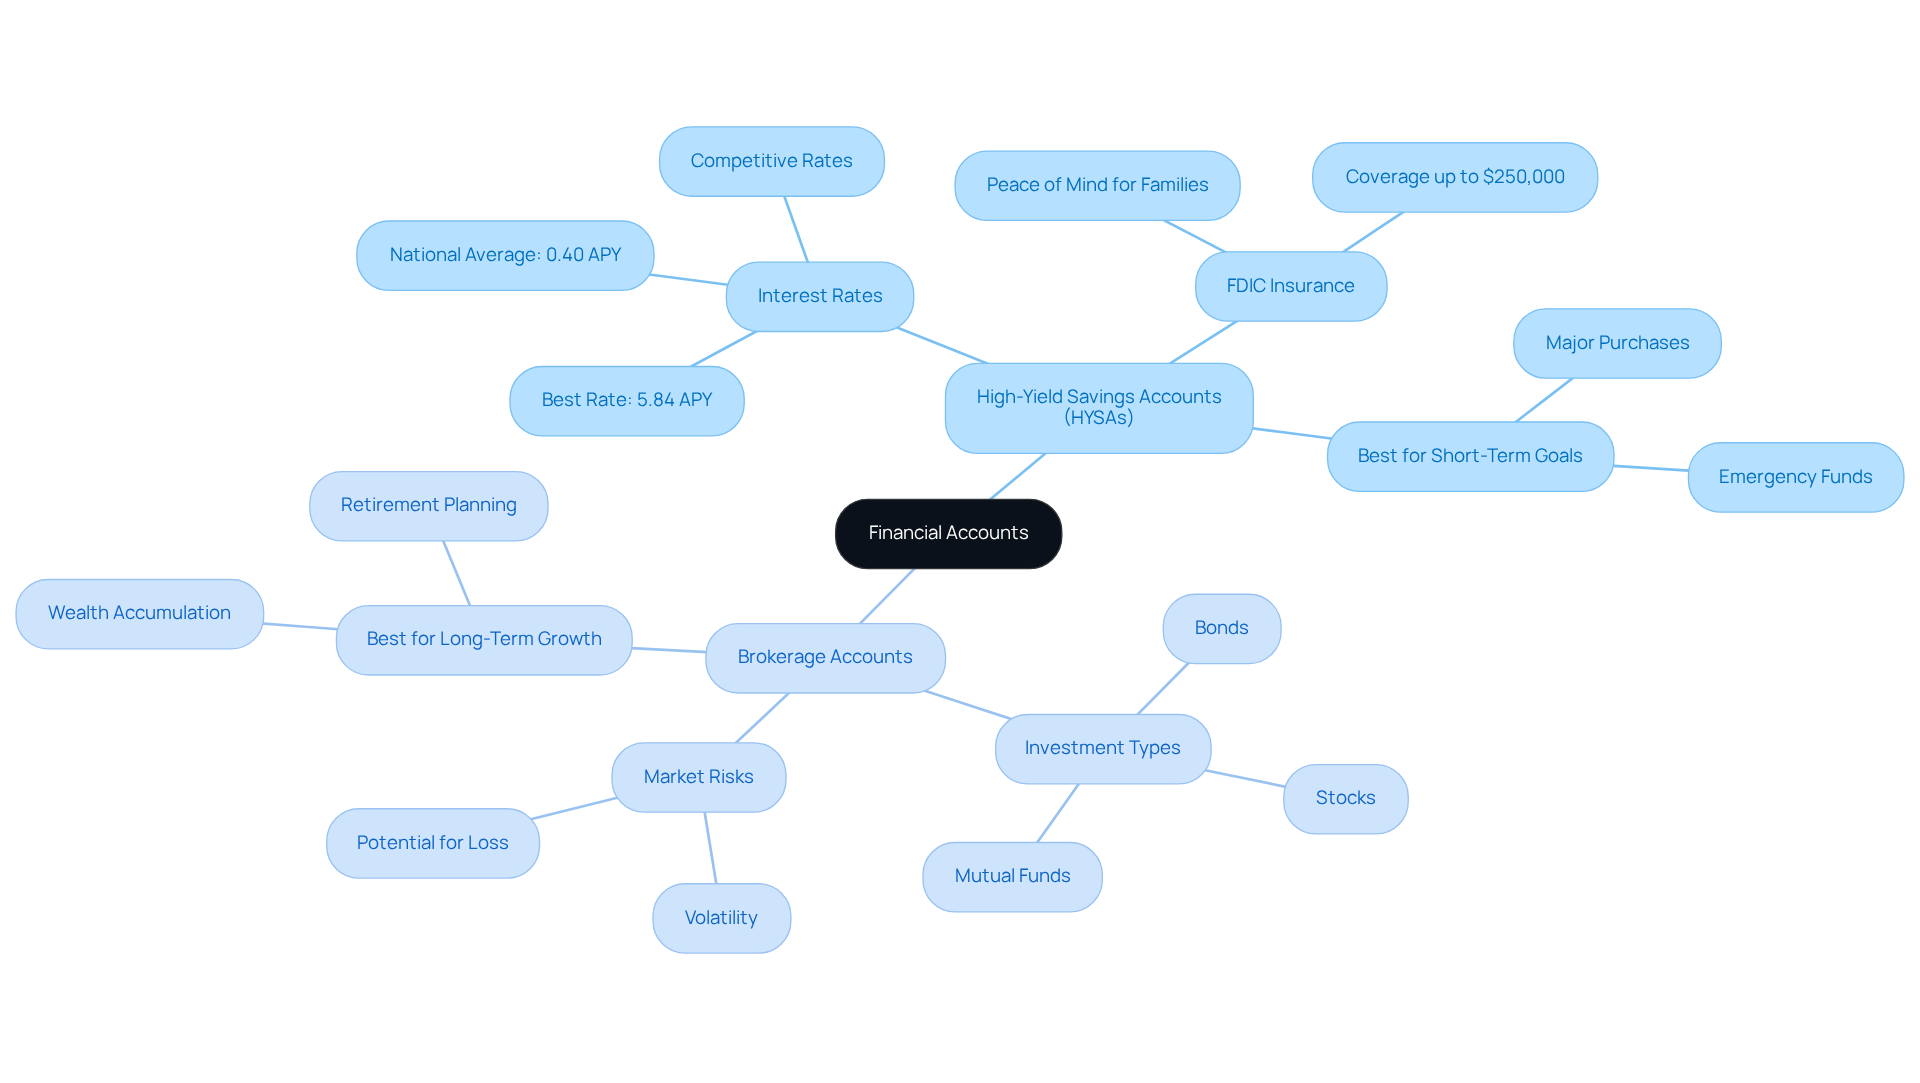
- High-Yield Savings Accounts (HYSAs) offer interest rates up to 5.84% APY, significantly higher than the national average of 0.40%.
- HYSAs are FDIC-insured, protecting deposits up to $250,000, which provides security for families.
- Brokerage accounts allow investments in stocks, bonds, and mutual funds, potentially leading to higher returns but with increased risks due to market volatility.
- HYSAs are ideal for short-term savings goals, such as emergency funds, while brokerage accounts are suited for long-term wealth growth.
- Financial advisors recommend understanding both account types to align financial decisions with family goals.
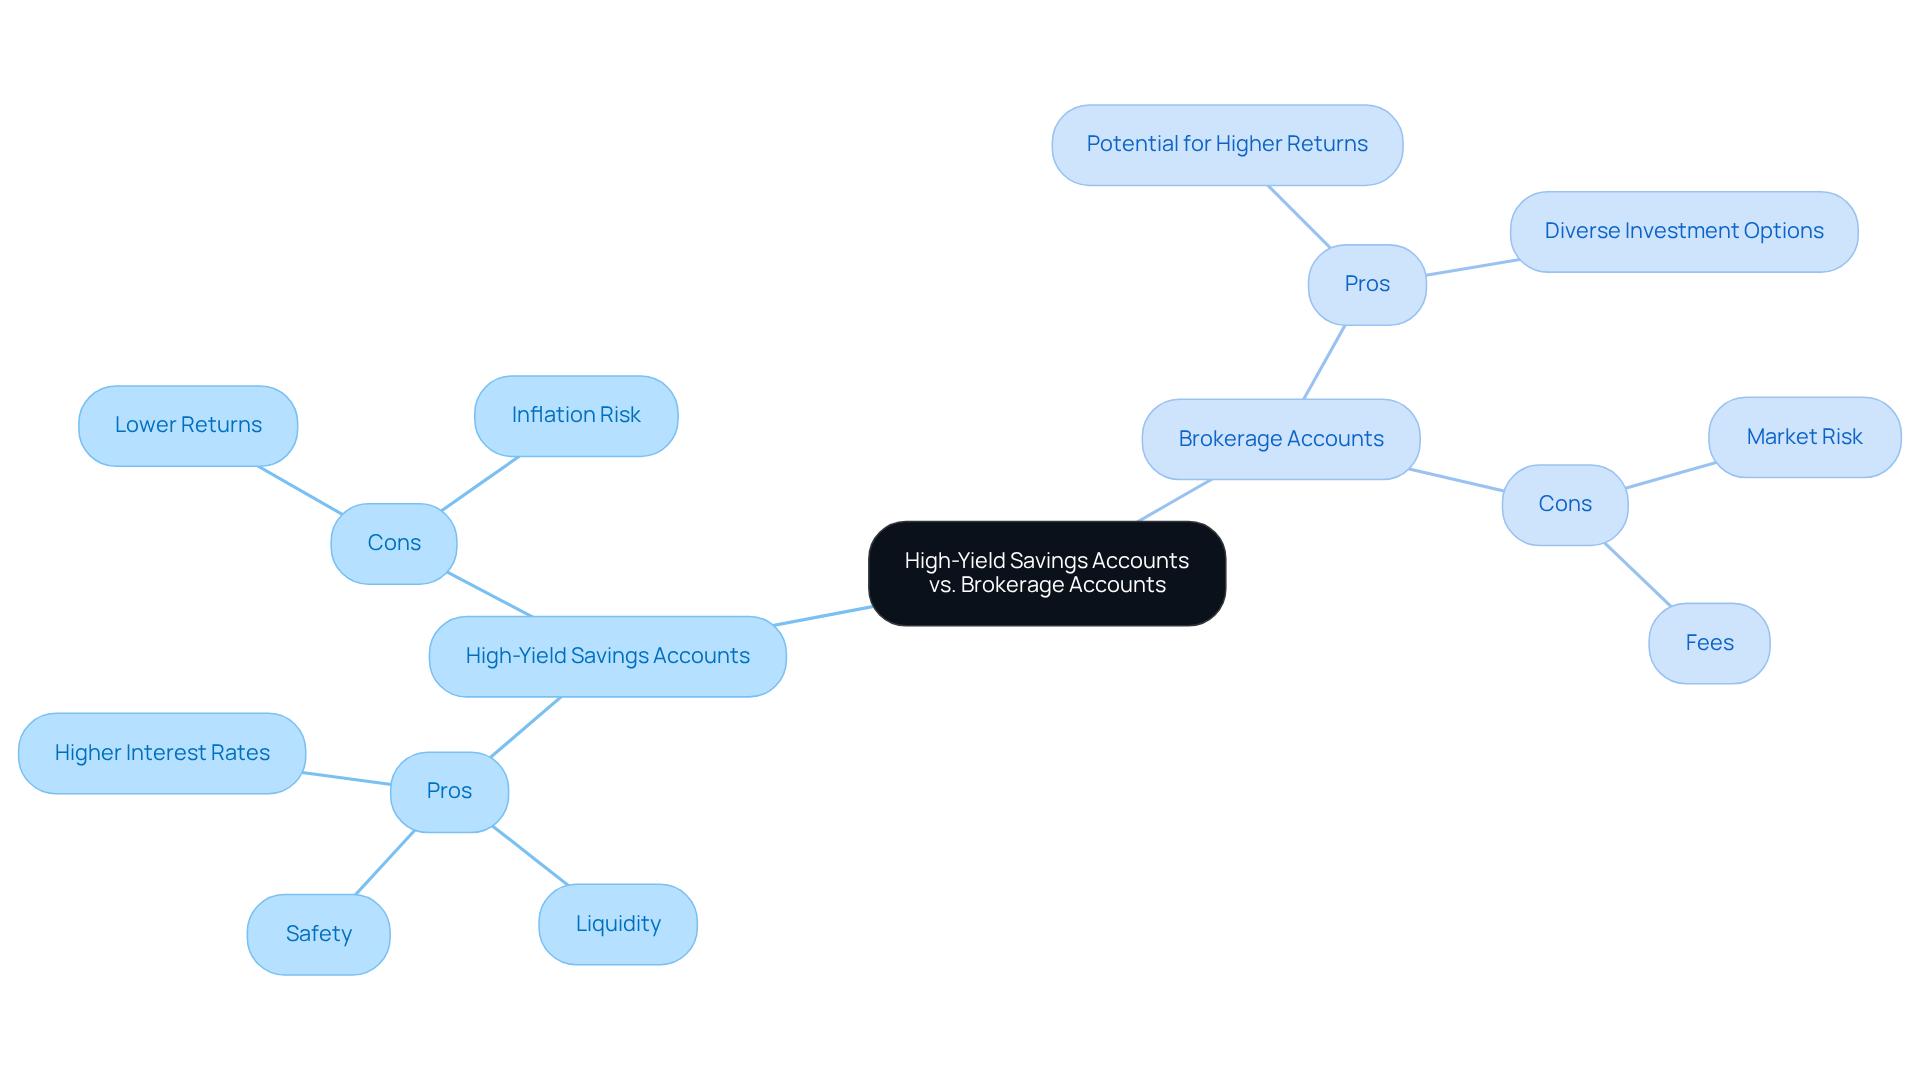
- Pros of HYSAs include safety, liquidity, and higher interest rates, while cons include lower returns and inflation risk.
- Brokerage accounts offer potential for higher returns and diverse investment options, but come with market risks and possible fees.
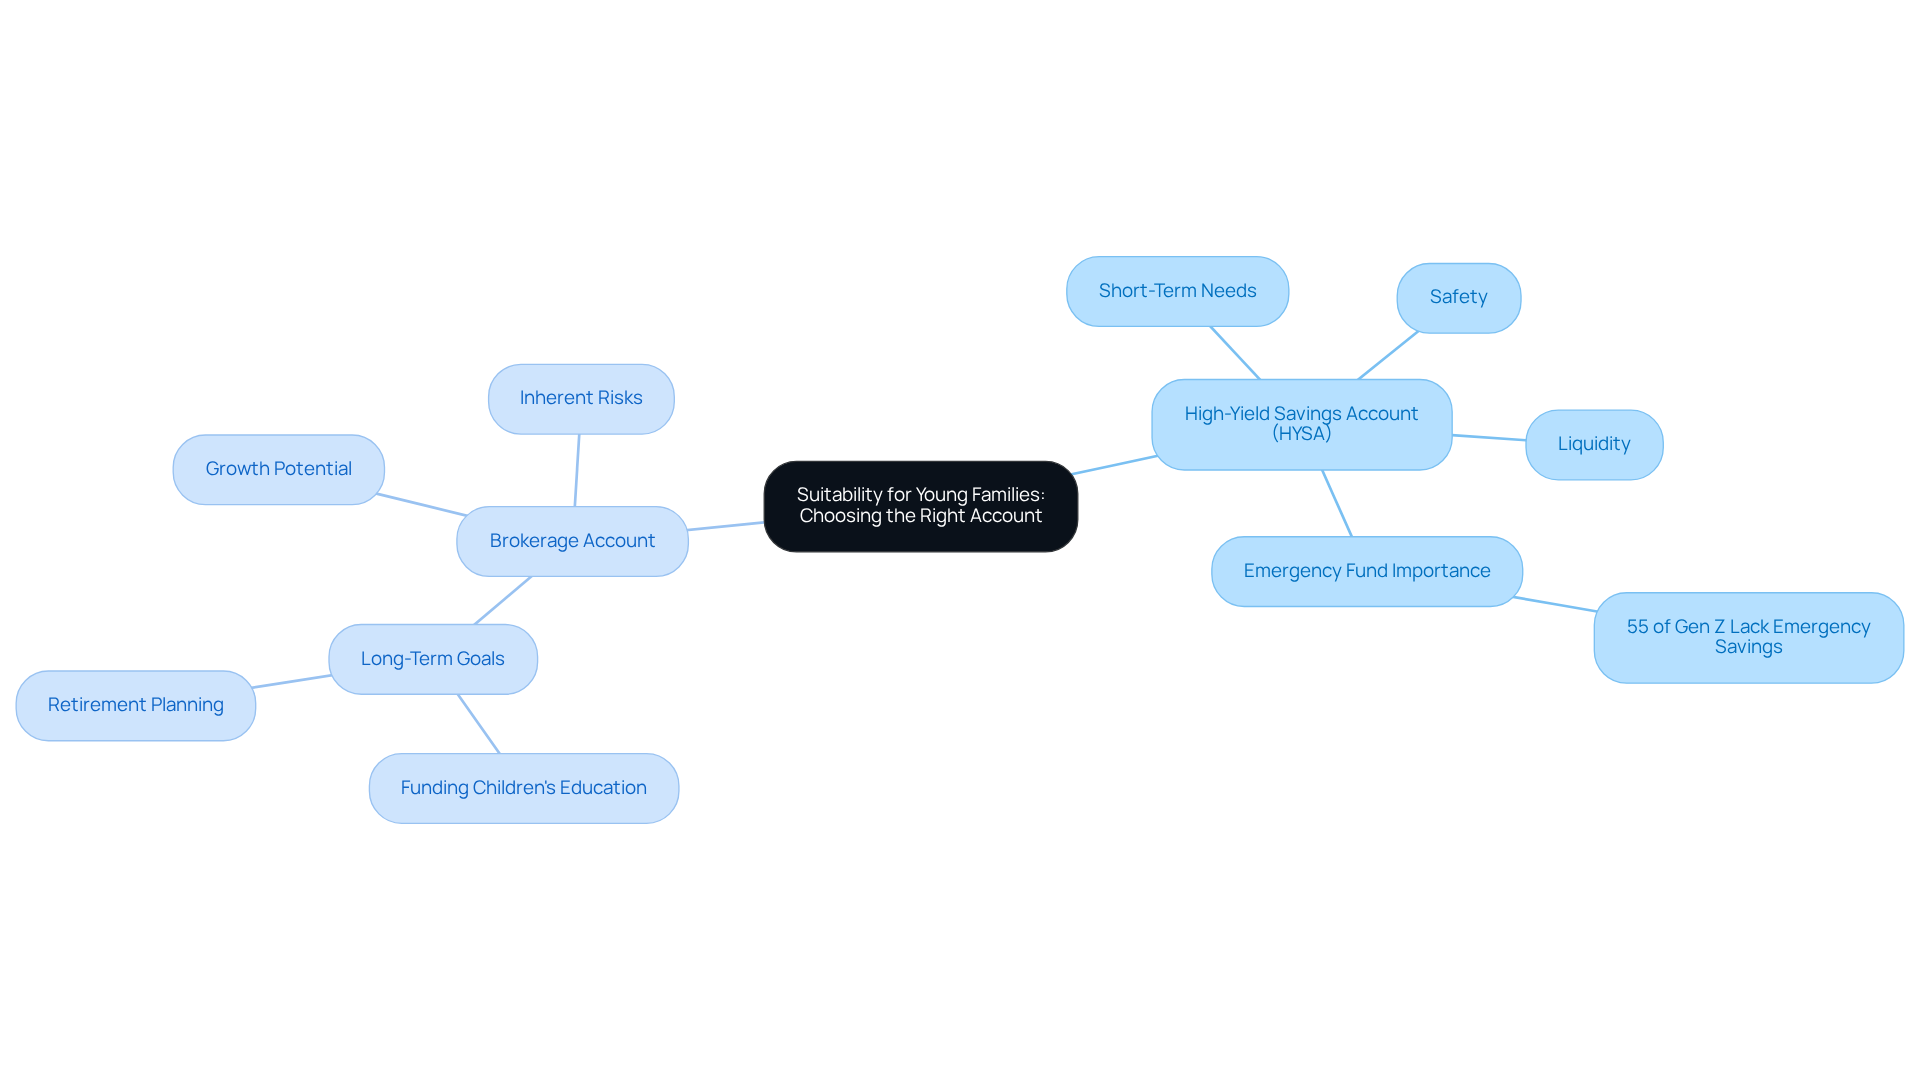
- For young families, HYSAs can provide a secure foundation, while brokerage accounts may support long-term aspirations like education funding or retirement.
Introduction
Navigating the financial landscape can feel overwhelming for young families. When it comes to choosing between high-yield savings accounts (HYSAs) and brokerage accounts, the decision can weigh heavily. Each option has its own set of advantages and risks, making it crucial for families to understand how these accounts align with their financial goals.
Imagine if the security and stability of a HYSA could provide the peace of mind you need for short-term savings. Or perhaps the growth potential of a brokerage account offers the long-term benefits your family aspires to. This article will explore the critical differences between these two financial tools, helping you make informed decisions that best suit your unique circumstances.
We’re here for you as you navigate this journey, ensuring that your family’s financial future is secure and bright.
Understanding High-Yield Savings Accounts and Brokerage Accounts
High-Yield Savings Plans (HYSAs) have gained popularity in 2025, offering interest rates that are significantly higher than traditional savings options. This makes them an appealing choice for families eager to grow their savings with minimal risk. Right now, the best high-yield accounts boast rates as high as 5.84% APY, a remarkable contrast to the national average of just 0.40%. Plus, these accounts are typically FDIC-insured, safeguarding deposits up to $250,000. This added layer of security can bring peace of mind to families concerned about their financial future.
On the other hand, brokerage services serve as investment platforms where individuals can buy and sell a variety of securities, including stocks, bonds, and mutual funds. While these investments might offer the potential for , they also come with increased risks due to market volatility. The value of investments can fluctuate significantly, which may not align with the financial stability many families seek.
Understanding the differences between high-yield savings options and HYSAs vs brokerage account services is essential for families as they navigate their financial planning. HYSAs can be particularly beneficial for short-term savings goals, like building an emergency fund or saving for major purchases. In contrast, brokerage services might be better suited for long-term investment strategies aimed at wealth growth.
Financial advisors emphasize the importance of grasping these account types. As one expert wisely noted, “Understanding your options is crucial for making informed decisions that align with your financial goals.” This insight underscores the need for families to carefully evaluate their financial situations, weighing the security of high-yield savings against the growth potential of a HYSAs vs brokerage account. By doing so, families can create a balanced approach to managing their finances, ensuring they prioritize both security and growth.
Imagine if you could confidently navigate your financial journey, knowing you have the right tools at your disposal. We’re here for you, ready to support you in making informed choices that resonate with your family’s values and aspirations. Together, we can explore the best options for your financial future.
Key Differences Between HYSAs and Brokerage Accounts
Navigating the world of finances can feel overwhelming, especially for young parents. It’s essential to understand the differences in HYSA vs brokerage account, as they serve distinct purposes and come with varying levels of risk and liquidity. High-yield savings accounts (HYSAs) are a dependable choice for short-term deposits and emergency funds. They typically offer consistent interest rates and easy access to your money. For example, as of June 2025, some HYSAs boast annual percentage yields (APYs) as high as 5.00%, far exceeding the average 0.42% found in traditional savings accounts. Plus, these funds are insured up to $250,000, providing peace of mind for families prioritizing safety and financial security.
On the other hand, HYSA vs brokerage account shows that brokerage accounts are designed for long-term wealth growth through investments in assets like stocks and bonds. While they can offer higher returns, they also come with increased risks, such as market fluctuations and potential losses. It’s crucial for families to carefully consider their financial goals. Are you looking for the security and liquidity of high-yield savings accounts, or do you want to explore the risks associated with HYSA vs brokerage account for potentially greater rewards?
Wealth management experts, like those at Bright Advisers, often recommend a balanced approach. Imagine if you could combine the accessibility of HYSAs with the growth potential of a HYSA vs brokerage account. This strategy allows families to build an emergency fund while also investing for future milestones, such as retirement or funding a child’s education. Bright Advisers is here to help you navigate these choices with customized financial planning strategies, ensuring you understand the risks associated with each option.
Ultimately, making that align with your family’s unique circumstances is vital. Together, we can navigate this journey, benefiting from Bright Advisers’ commitment to minimal fund fees and personalized support. Remember, you’re not alone in this; we’re here for you every step of the way.

Pros and Cons of High-Yield Savings Accounts vs. Brokerage Accounts
High-Yield Savings Accounts (HYSAs)
Pros:
- Safety: HYSAs are FDIC-insured, which means your deposits are protected up to $250,000. This safety net can bring peace of mind, especially for families.
- Liquidity: You can access your funds easily without penalties, making HYSAs a great option for emergencies. Imagine having that financial cushion when unexpected expenses arise.
- Higher Interest Rates: Compared to traditional savings accounts, HYSAs typically offer better interest rates, helping your savings grow faster. Who wouldn’t want their hard-earned money to work a little harder for them?
Cons:
- Lower Returns: While HYSAs are safer, they usually provide lower returns than investments in a brokerage account. It’s essential to weigh your options based on your family’s financial goals.
- Inflation Risk: The interest you earn might not keep up with inflation, which could affect your purchasing power over time. It’s important to consider how this might impact your family’s future.
Brokerage Accounts
Pros:
- Potential for Higher Returns: Investing in stocks and other securities can lead to significant returns over time. This could be a way to build a brighter future for your family.
- Diverse Investment Options: Brokerage accounts offer a wide range of investment choices, including ETFs, mutual funds, and individual stocks. This variety allows you to tailor your investments to fit your family’s needs and values.
Cons:
- Market Risk: Investments can lose value, and there’s no guarantee of returns. It’s crucial to understand this risk as you plan for your family’s financial future.
- Fees: Brokerage services may come with trading fees, management fees, and other costs that can eat into your profits. Families should carefully consider these factors when deciding between a HYSA vs brokerage account.
As you navigate these options, remember that we’re here for you. Together, we can explore the best to support your family’s dreams.
Suitability for Young Families: Choosing the Right Account
When managing your family’s finances, deciding between a and a brokerage account, often referred to as HYSA vs brokerage account, can feel overwhelming. Imagine if you could secure your family’s future while also planning for long-term goals. For young households, it’s essential to assess both short-term needs and long-term aspirations.
If you’re focused on building an emergency fund or saving for immediate goals, a HYSA often emerges as the best option. Its safety and liquidity provide peace of mind, especially when studies reveal that 55% of Gen Z lack enough emergency savings to cover three months of expenses. This highlights just how crucial HYSAs can be for families striving to create a secure financial foundation.
At Bright Advisers, we understand the importance of low fund fees, making wealth management more accessible for families like yours. This means you can direct more of your hard-earned resources toward achieving your financial objectives.
On the flip side, if your sights are set on long-term growth-perhaps funding your children’s education or planning for retirement-you might find that a HYSA vs brokerage account comparison shows the latter serves you better, even with its inherent risks. Currently, many high-yield savings options offer up to 4.3% APY, making them an attractive choice for families prioritizing security.
Ultimately, your decision should reflect your unique financial situation, risk tolerance, and investment timeline. And remember, a hybrid strategy that combines both a HYSA vs brokerage account can be a wonderful way to balance the safety of a HYSA with the growth potential of a brokerage account. Together, we can navigate this journey and find the best path for your family’s financial future.
Conclusion
Choosing the right financial account is so important for young families. It directly affects how well they can save and invest for the future. High-yield savings accounts (HYSAs) offer a safe, FDIC-insured option that helps families grow their savings with minimal risk. This makes them perfect for short-term goals and emergency funds. On the other hand, brokerage accounts can provide higher returns through investments in stocks and bonds, but they also come with increased risks and market ups and downs. Understanding these differences empowers families to make informed decisions that truly align with their financial dreams.
In this article, we’ve explored the pros and cons of each account type. HYSAs shine with their safety, liquidity, and competitive interest rates, while brokerage accounts open the door to diverse investment options and the potential for significant long-term growth. Families need to think about their unique financial situations, considering factors like risk tolerance and investment timelines, to figure out which account fits best with their goals.
Ultimately, the journey toward financial security for young families is about finding a careful balance between safety and growth. A hybrid approach that combines both HYSAs and brokerage accounts can offer the best of both worlds. This way, families can secure their immediate needs while also planning for future milestones. By taking the time to assess these options and seeking personalized financial guidance, families can confidently pave the way toward a prosperous financial future. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What are High-Yield Savings Accounts (HYSAs)?
High-Yield Savings Accounts (HYSAs) are savings accounts that offer significantly higher interest rates compared to traditional savings options, with rates currently reaching as high as 5.84% APY.
Why are HYSAs appealing to families?
HYSAs are appealing to families because they provide a way to grow savings with minimal risk, are typically FDIC-insured up to $250,000, and offer much higher interest rates than the national average of 0.40%.
What is a brokerage account?
A brokerage account is an investment platform that allows individuals to buy and sell various securities, such as stocks, bonds, and mutual funds.
What are the risks associated with brokerage accounts?
Brokerage accounts come with increased risks due to market volatility, as the value of investments can fluctuate significantly, which may not align with the financial stability many families seek.
When should families consider using HYSAs?
Families should consider using HYSAs for short-term savings goals, such as building an emergency fund or saving for major purchases.
What is the ideal use for brokerage accounts?
Brokerage accounts are better suited for long-term investment strategies aimed at wealth growth.
Why is it important to understand the differences between HYSAs and brokerage accounts?
Understanding the differences is crucial for families to make informed decisions that align with their financial goals, balancing the security of high-yield savings with the growth potential of investments.
How can families create a balanced approach to managing their finances?
Families can create a balanced approach by carefully evaluating their financial situations and weighing the security of HYSAs against the growth potential of brokerage accounts, ensuring they prioritize both security and growth.
List of Sources
- Understanding High-Yield Savings Accounts and Brokerage Accounts
- High-Yield Savings Account Rates Today: December 8, 2025 – Rates Are Steady (https://forbes.com/advisor/banking/savings/savings-account-rates-today-12-08-25)
- Best high-yield savings account rates on Dec. 3, 2025: Earn up to 5.00% APY | Fortune (https://fortune.com/article/best-savings-account-rates-12-3-2025)
- Best High-Yield Savings Accounts for December 2025: Up to 4.51% (https://wsj.com/buyside/personal-finance/banking/best-high-yield-savings-account?gaa_at=eafs&gaa_n=AWEtsqfdosKd1cmUqQv9l5HB0bytEgIYCRCQ7Ir9nl3VsXY_WwDQGL68oVDz&gaa_ts=69376eb1&gaa_sig=73bNGWGSfqcOOz6xbg1NKt2stms5LjNhmTUHe7p112SeP0xC5ABd4ETRC_D8BTMLbQ_TI8Hn7zw6js475l9SaQ%3D%3D)
- Best High-Yield Savings Account Rates for November 2025: Earn 5.00% APY While You Still Can (https://investopedia.com/high-yield-savings-accounts-4770633)
- Best High-Yield Savings Accounts Of November 2025 – Up to 4.20% | Bankrate (https://bankrate.com/banking/savings/best-high-yield-interests-savings-accounts)
- Key Differences Between HYSAs and Brokerage Accounts
- What Are the Pros and Cons of High-Yield Savings Accounts? | Leader Bank (https://leaderbank.com/blog/what-are-pros-and-cons-high-yield-savings-accounts)
- 82% of Americans don’t use this kind of savings account that earns over 5% a year — here’s how much money you may be missing out on (https://cnbc.com/select/americans-not-using-high-yield-savings-accounts)
- Are High-Yield Savings Accounts Safe? (https://experian.com/blogs/ask-experian/are-high-yield-savings-accounts-safe)
- Choosing Between High Yield Savings and Investing (https://smartasset.com/investing/high-yield-savings-account-vs-investing)
- Pros and cons of a high-yield savings account (https://cnbc.com/select/pros-and-cons-high-yield-savings-accounts)
- Pros and Cons of High-Yield Savings Accounts vs. Brokerage Accounts
- Average Savings Account Interest Rate For November 2025 | Bankrate (https://bankrate.com/banking/savings/average-savings-interest-rates)
- Best High-Yield Savings Accounts of December 2025: Up to 5.00% – NerdWallet (https://nerdwallet.com/banking/best/high-yield-online-savings-accounts)
- Best High-Yield Savings Accounts – November 2025 | US News Money (https://usnews.com/banking/high-yield-savings-accounts)
- What’s a good high-yield savings account interest rate after the Fed cut rates? (https://cbsnews.com/news/whats-good-high-yield-savings-account-interest-rate-october-2025-fed-cut-rates)
- Best High-Yield Savings Account Rates for November 2025: Earn 5.00% APY While You Still Can (https://investopedia.com/high-yield-savings-accounts-4770633)
- Suitability for Young Families: Choosing the Right Account
- New 2025 savings and wealth stats show who’s getting ahead (https://finance.yahoo.com/personal-finance/banking/article/savings-and-wealth-statistics-215214936.html)
- US Families Juggle Financial Support Across Generations | PLANADVISER (https://planadviser.com/us-families-juggle-financial-support-across-generations)
- The State of Personal Finance in America Q3 2025 (https://ramseysolutions.com/budgeting/state-of-personal-finance?srsltid=AfmBOorHHrcD50p9J54nM6gyIzG5AjwWSB5S8nFJnFoKi7HrQa9MD67M)
- U.S. Net Worth by Age: What the Data Shows [Updated for 2025] (https://harness.co/articles/wealth-benchmarks-net-worth-america)
- Confronted with Higher Living Costs, 72% of Young Adults Take Action to Improve their Financial Health, finds BofA Better Money Habits Study (https://newsroom.bankofamerica.com/content/newsroom/press-releases/2025/07/confronted-with-higher-living-costs–72–of-young-adults-take-ac.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading