

Key Highlights
- Incentive Stock Options (ISOs) offer favourable tax treatment if specific holding requirements are met, potentially leading to lower capital gains tax rates.
- Exercising ISOs may trigger Alternative Minimum Tax (AMT) based on the difference between market value and strike price.
- Non-Qualified Stock Options (NSOs) can be granted to a wider range of individuals and are taxed as ordinary income upon exercise, leading to higher immediate tax burdens.
- Families can adopt various exercise strategies for ISOs, including holding shares for appreciation, early activity to start the holding period, or a cashless approach.
- For NSOs, families may choose to exercise and sell immediately for cash or hold shares for potential appreciation, with staggered exercises to manage tax liabilities.
- Understanding tax implications is crucial; ISOs may incur AMT, while NSOs are taxed as ordinary income at exercise, which can lead to unexpected financial burdens.
- ISOs are suitable for families seeking long-term investment opportunities, while NSOs offer flexibility and immediate cash access, appealing to those with lower risk appetites.
- Bright Advisers emphasises the importance of personalised planning to help families navigate stock options and align their financial goals.
Introduction
Imagine feeling overwhelmed by the complexities of employee stock options, unsure of how they fit into your family’s financial future. Navigating Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can be challenging, especially when considering their long-term financial implications. It’s important to understand how these options can impact your family’s financial journey, as each presents unique advantages and challenges. Families must weigh potential tax benefits against immediate cash needs.
How can you effectively choose between ISOs and NSOs to align with your financial goals while minimizing tax burdens? Together, we’ll explore key strategies and tax implications that can help your family make informed decisions for a secure financial future.
Define Incentive Stock Options and Non-Qualified Stock Options
Navigating the world of employee stock options can feel overwhelming, especially when it comes to making the best choices for your family’s future.
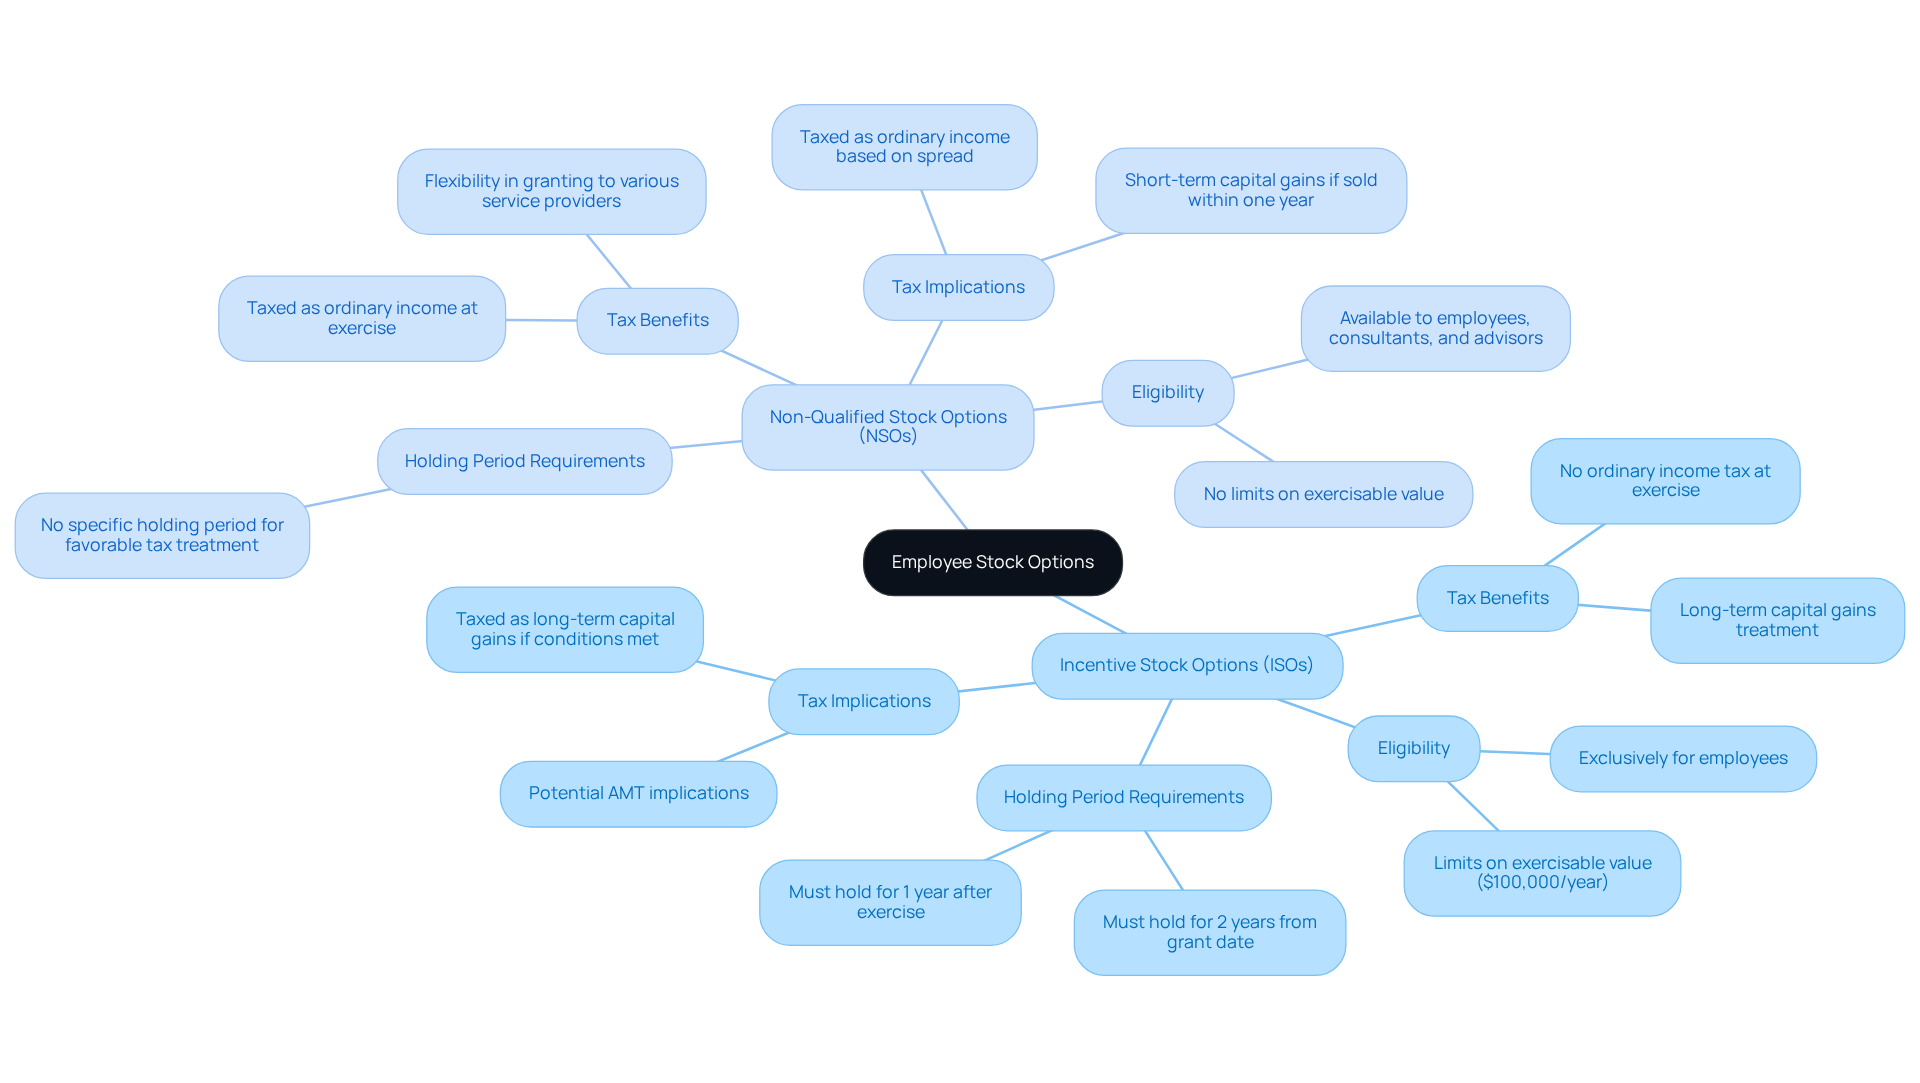
Imagine being offered Incentive Stock Options (ISOs) as part of your job – these special options can offer you some great tax benefits! ISOs are granted exclusively to employees and can provide favorable tax treatment under the Internal Revenue Code. To qualify, the option must meet specific criteria, like having a purchase price set at or above the fair market value at the time of grant. Plus, if you hold the shares for at least one year after exercising the option and two years from the grant date, you could benefit from lower capital gains tax rates. This potential for favorable tax treatment is a significant advantage, as it can lead to lower overall tax burdens if the conditions are met. However, it’s important to understand that exercising ISOs may trigger alternative minimum tax (AMT) implications based on the difference between the market value at the point of acquisition and the strike price.
On the flip side, Non-Qualified Stock Options can be given to many people, including employees and even consultants, making them a bit more flexible. When you exercise these options, the difference between the exercise price and the fair market value of the stock is taxed as ordinary income, which can lead to a higher tax burden at that time. Unlike ISOs, non-qualified stock options don’t have the same holding period requirements for favorable tax treatment, making them simpler but less tax-efficient.
It’s important to understand the differences in incentive stock options vs non-qualified stock options exercise strategy, as they can help your family make informed financial decisions that align with your goals. For example, if you acquire 200 shares of NSOs at a $10 strike price when the market value is $15, the $1,000 profit is taxed as ordinary income. In contrast, if you exercise ISOs under similar conditions and meet the holding requirements, you may qualify for long-term capital gains treatment, significantly reducing your tax liability.
Case studies illustrate these differences:
- Jay and Emma, a couple seeking to reduce financial anxiety, worked with Bright Advisers to create a comprehensive financial strategy that included optimizing their tax situation and leveraging innovative investment strategies.
- Emily and Mark, another couple aiming for financial freedom, benefited from understanding how their equity compensation could impact their overall financial plan.
- Meanwhile, Allison and Brian, high-income earners, realized the importance of tax planning to maximize their financial potential.
With the right knowledge and support, you can confidently steer your family toward a brighter financial future.
Compare Exercise Strategies for ISOs and NSOs
Navigating stock options can feel overwhelming for families, especially when considering the financial future of your loved ones. When it comes to exercising stock options, households can explore various strategies as part of the incentive stock options vs non qualified stock options exercise strategy.
Exercise Strategies for ISOs:
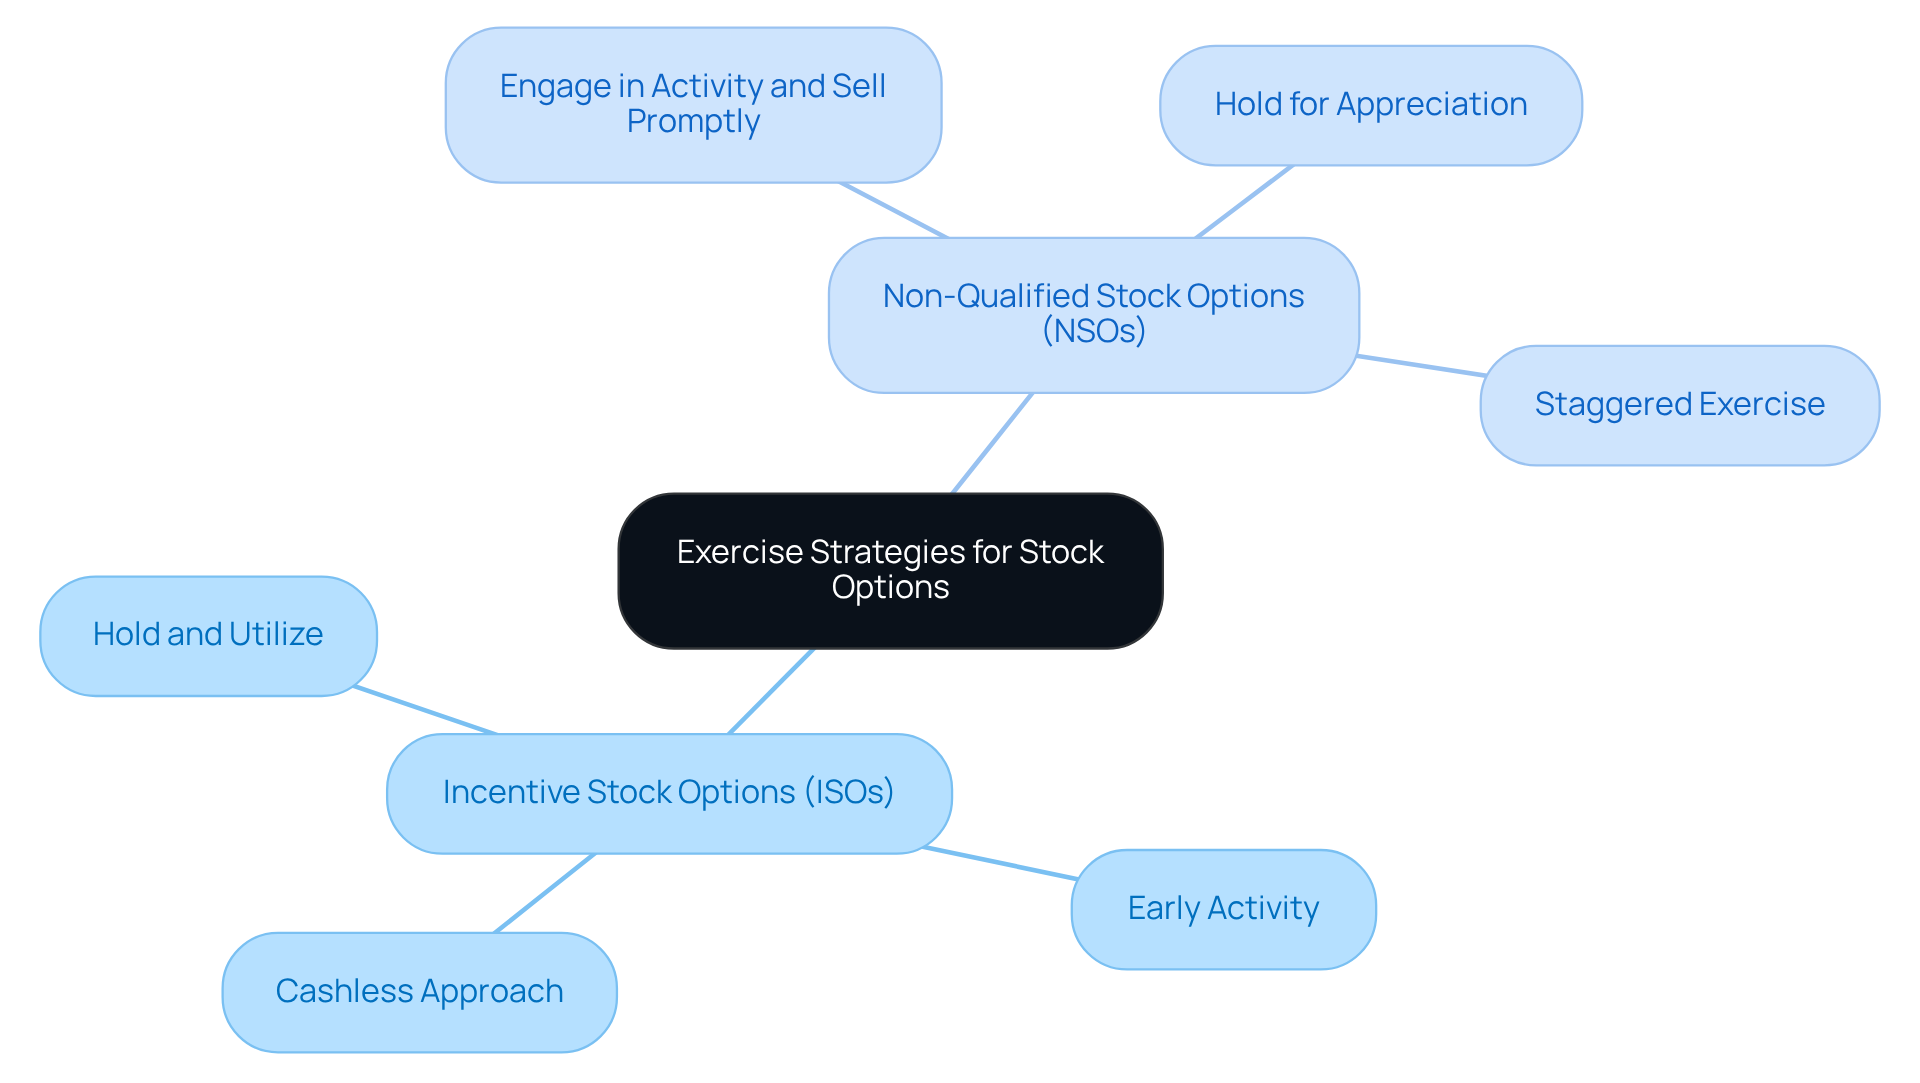
- Hold and Utilize: Families may choose to hold onto their ISOs until they’re ready to use them. This can be a smart move if they expect the stock price to rise significantly. However, it’s important to be aware that this strategy might expose them to the Alternative Minimum Tax (AMT) if the stock appreciates too much before selling.
- Early Activity: Engaging in early activity allows families to acquire shares before they vest. This can be beneficial for tax reasons, as it starts the holding period for long-term capital gains sooner. By doing this, families can potentially avoid higher tax obligations down the road.
- Cashless Approach: This strategy involves using the options and quickly selling enough shares to cover the acquisition cost and taxes. It’s a way for families to avoid upfront cash expenses. As mentioned by Secfi, “A cashless method can be a convenient way to utilize stock options without paying cash upfront, especially if your company has already gone public or reached another liquidity event.”
Exercise Strategies for NSOs:
- Engage in Activity and Sell Promptly: Families can exercise their stock options and sell the shares right away to realize gains and cover taxes. While this approach gives you quick access to cash, it might not be the best way to grow your family’s future. Let’s explore other options together.
- Alternatively, families can exercise their stock options and hold onto the shares for potential appreciation. It’s important to think about how taxes will affect your family, as you’ll face ordinary income tax when you realize those gains. We’re here to help you navigate this together.
- Staggered Exercise: Families may choose to exercise their stock options in stages over several years. This can help manage tax liabilities effectively and avoid a large tax hit in a single year. Consulting with a tax professional is crucial, as highlighted by Darrow Wealth Management: “We will collaborate with your tax professional for a final review of the strategies we develop together.”
By understanding the incentive stock options vs non qualified stock options exercise strategy, you can make informed decisions that align with your family’s financial goals and tax situations. By taking the time to understand these strategies, you can pave the way for a more secure financial future for your family, knowing that support is available every step of the way.
Analyze Tax Implications of Exercising ISOs vs. NSOs
Many families feel overwhelmed by the complexities of tax implications when exercising stock options.
Tax Implications for ISOs:
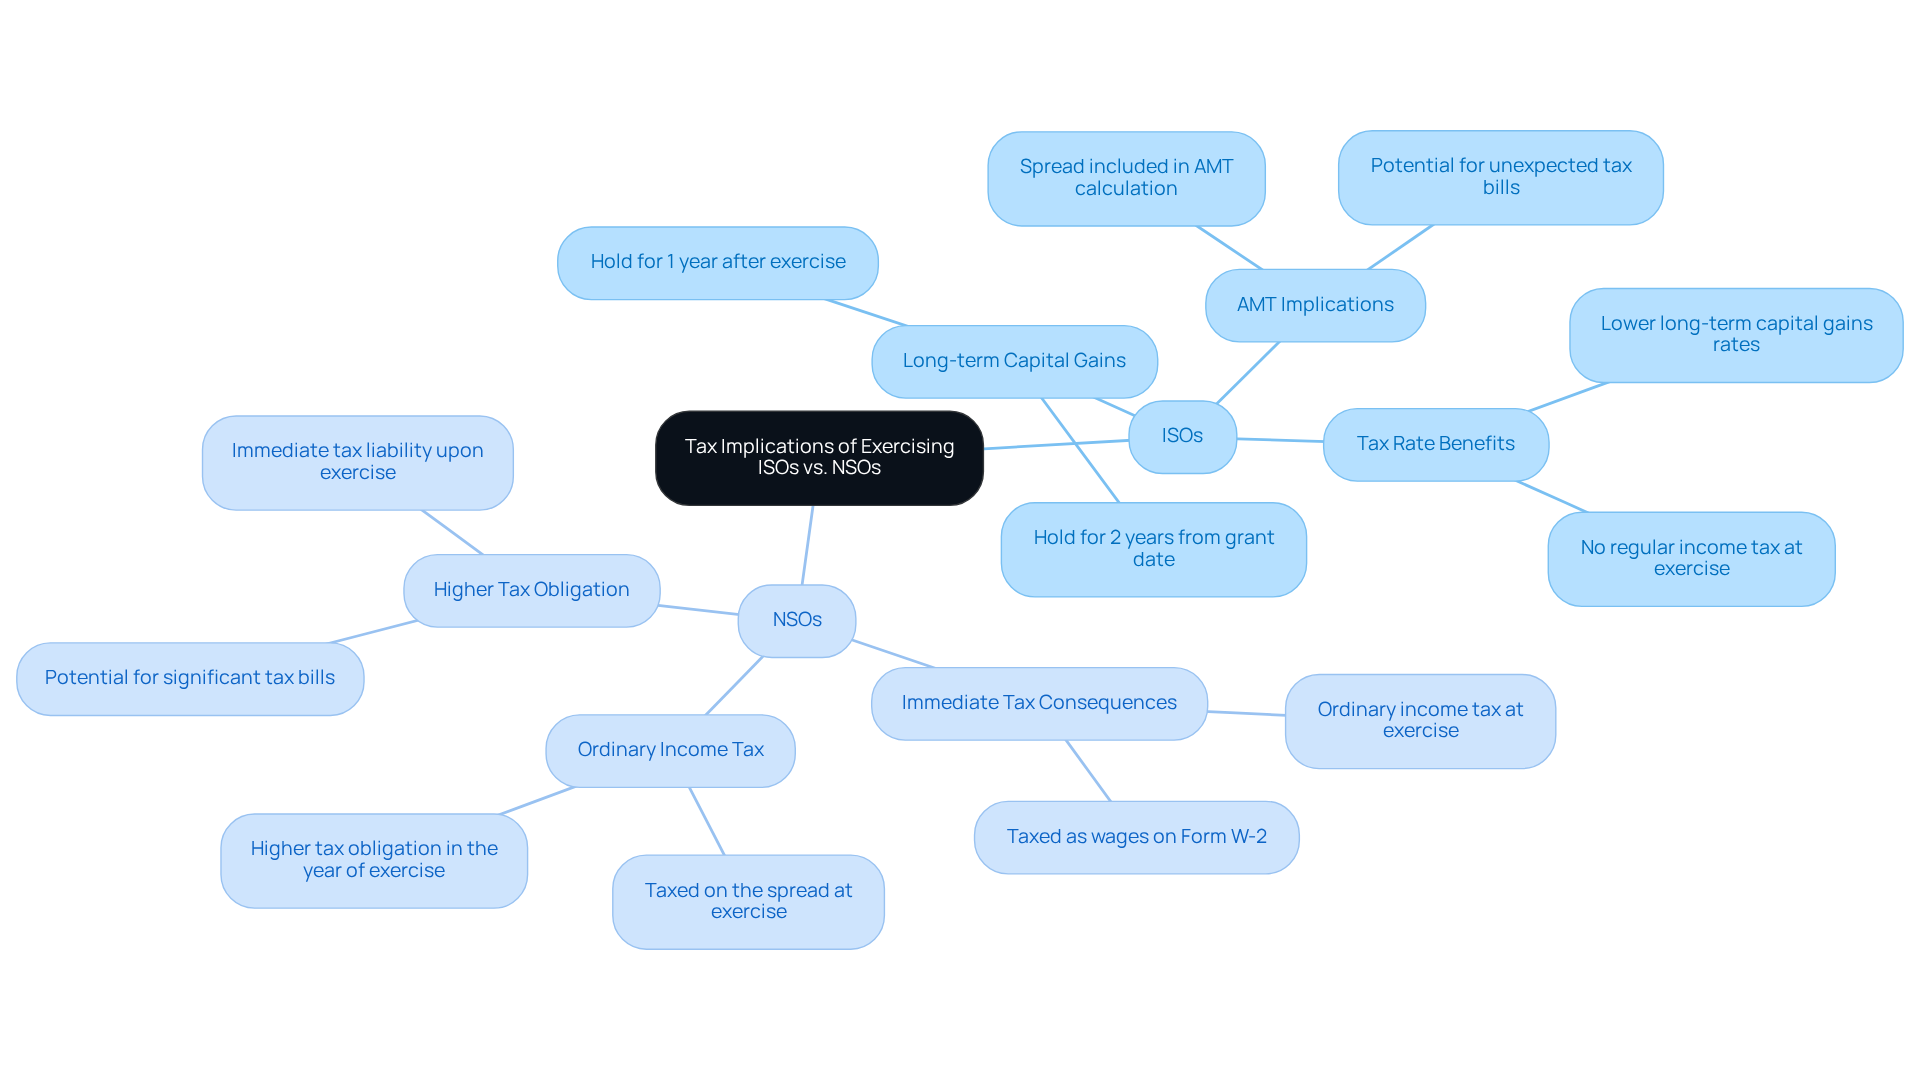
But here’s the catch: the difference between what you pay for the stock and its current value could trigger the Alternative Minimum Tax (AMT). For example, if you exercise ISOs at a price of $10 when the shares are valued at $30, that $20 difference is factored into the AMT calculation. If you want to benefit from lower long-term capital gains rates, it’s important to hold onto your shares for at least a year after you acquire them and two years from when they were granted. This usually leads to a lower tax rate compared to standard income tax rates.
Tax Implications for NSOs:
In contrast, exercising NSOs brings immediate tax consequences. The difference between the option price and the fair market value of the stock at the moment of exercise is considered ordinary income and is subject to federal income tax, Social Security tax, and Medicare tax. For instance, if you exercise 100 vested NSOs at a grant price of $1 when the current value is $3, you’ll incur ordinary income tax on a $200 gain at the time of exercise. This can lead to a significantly higher tax obligation in the year you realize the gain, especially if the stock has increased substantially.
Understanding these tax implications is essential for families as they develop their incentive stock options vs non qualified stock options exercise strategy. Without proper planning, families might face unexpected financial burdens that could impact their future. A survey revealed that over 25% of employees received unexpectedly high tax bills after exercising or selling shares, highlighting the importance of informed decision-making in this area. Together, we can navigate these challenges and secure a brighter financial future for your family.
Evaluate Suitability of ISOs and NSOs for Financial Goals
When evaluating the incentive stock options vs non qualified stock options exercise strategy, it’s important for families to reflect on their financial dreams, comfort with risk, and the tax implications that come with each choice. At Bright Advisers, we’ve walked alongside families like Emily and Mark, helping them find their way through these important decisions and work towards financial freedom with personalized planning and care.
Suitability of ISOs:
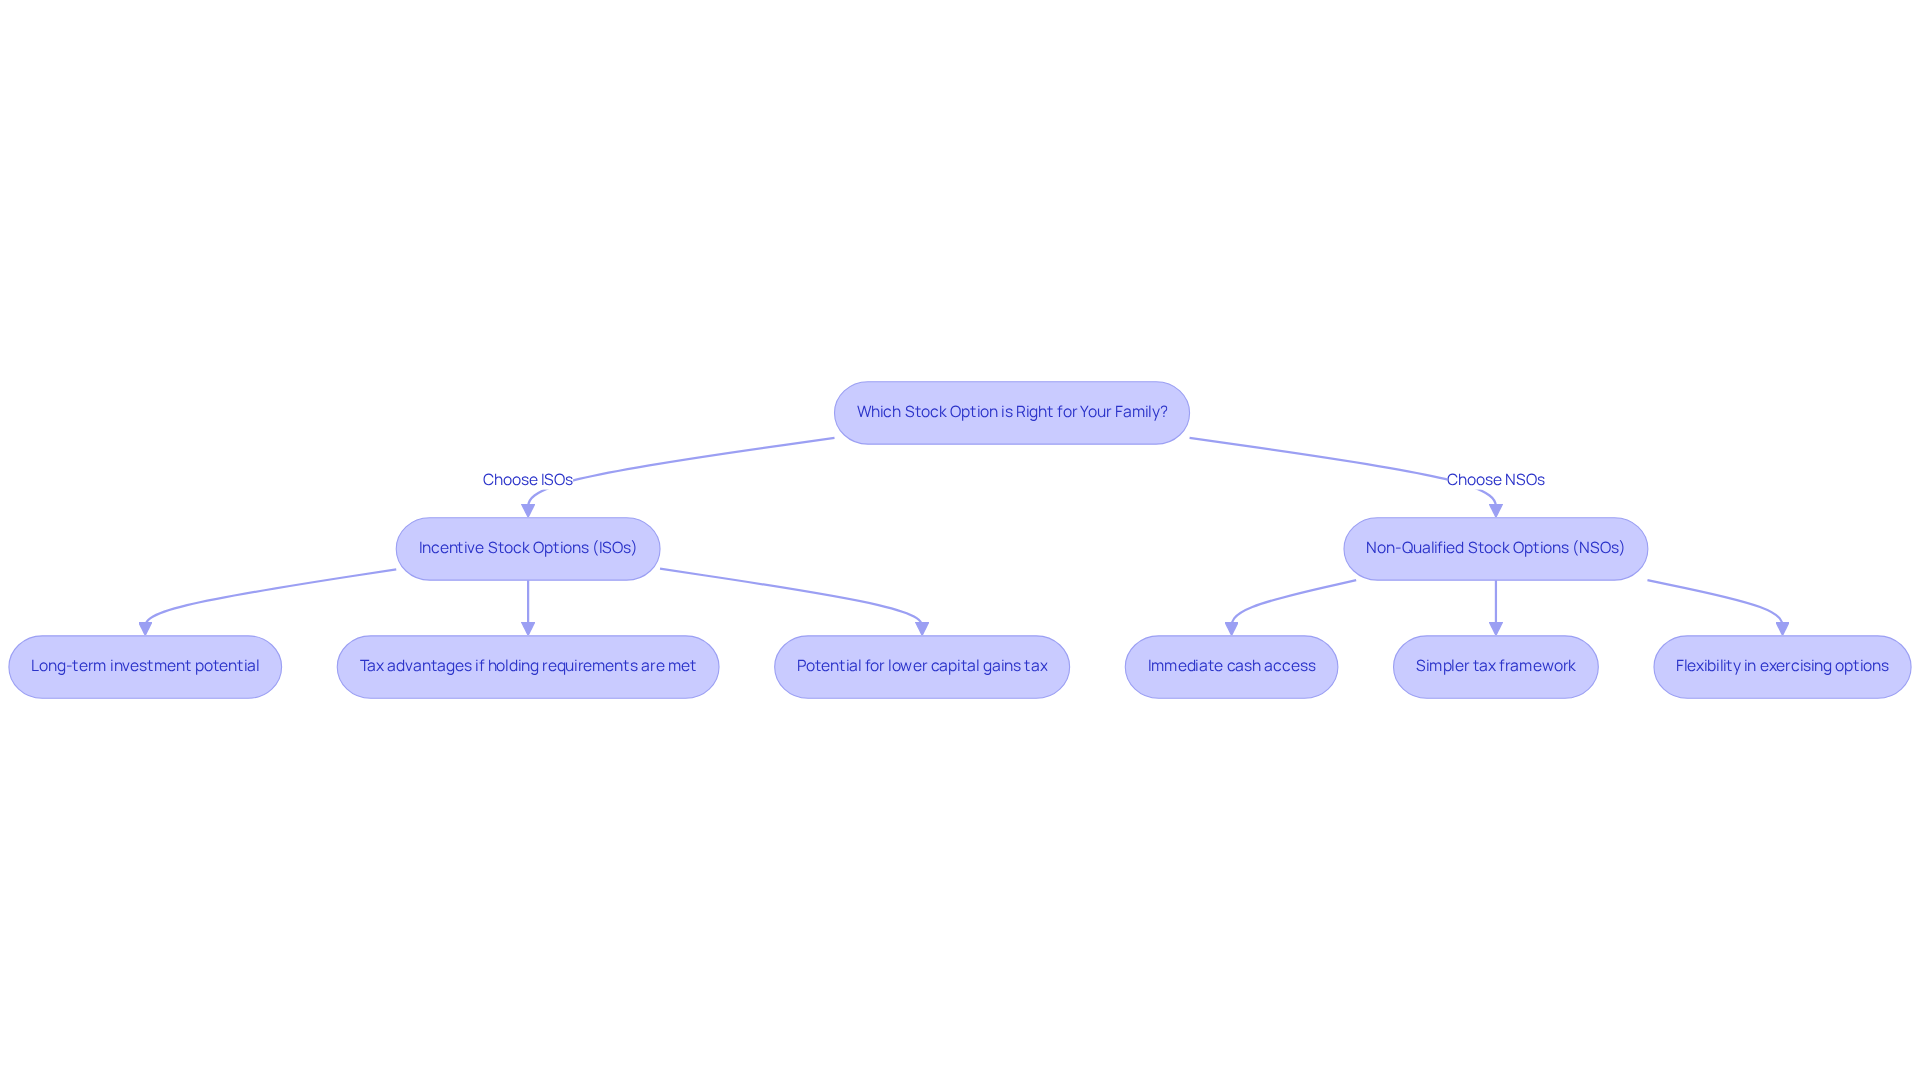
- ISOs are often a great fit for families looking for long-term investment opportunities. They can yield significant returns if the company’s stock performs well over time, making them appealing for those willing to hold shares for the required periods to benefit from favorable tax treatment. Families anticipating a lower tax bracket in the future may find ISOs advantageous due to the capital gains tax treatment, which can be more favorable than ordinary income tax rates. Bright Advisers employs strategies such as tax-loss harvesting to enhance the benefits of ISOs for households.
Suitability of NSOs:
- NSOs may be better suited for families who value flexibility and immediate access to cash. Since stock options can be exercised and sold immediately, households can swiftly realize profits, which is advantageous for short-term financial requirements. Moreover, households with a lower risk appetite might favor non-qualified stock options, as they provide a simple tax framework without the intricacies of the Alternative Minimum Tax (AMT) linked to incentive stock options. Bright Advisers also highlights clear fee structures, ensuring households comprehend the expenses associated with exercising non-qualified stock options.
Choosing between incentive stock options vs non qualified stock options exercise strategy is a personal journey that should reflect your family’s unique financial situation and goals. By carefully evaluating these factors, you can make informed decisions that support your long-term financial strategies. With the right guidance, you can confidently navigate these choices and secure a brighter financial future for your family. Please note that past performance does not guarantee future results, and all investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Navigating the world of stock options can feel overwhelming for families, but understanding the differences between Incentive Stock Options (ISOs) and Non-Qualified Stock Options (NSOs) can make a significant difference. Each type of stock option has its own unique advantages and challenges, especially when it comes to tax implications and exercise strategies.
Imagine if you could make informed decisions that align with your family’s long-term goals. By grasping these distinctions, you can empower your family to make choices that truly reflect your values and aspirations.
The article highlights key strategies for exercising both ISOs and NSOs, emphasizing the importance of understanding tax implications and personal financial situations. Families can choose to hold ISOs for potential long-term gains or exercise NSOs for immediate cash flow, each with its own set of tax consequences. Real-life examples illustrate how families like Jay and Emma, and Emily and Mark, have successfully navigated these options with the guidance of Bright Advisers, showcasing the value of personalized financial planning.
The choice between ISOs and NSOs is deeply personal, reflecting your family’s unique financial landscape and dreams. If you’re feeling uncertain about your options, we’re here for you. Reach out for a personalized Tax & Wealth Assessment that can help you navigate this journey together. Taking the time to understand your options today can pave the way for a more secure and fulfilling future for your family.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are special stock options granted exclusively to employees that can offer favorable tax treatment under the Internal Revenue Code, provided certain criteria are met.
What are the tax benefits of ISOs?
ISOs can lead to lower capital gains tax rates if the shares are held for at least one year after exercising the option and two years from the grant date. However, exercising ISOs may trigger alternative minimum tax (AMT) implications.
What are Non-Qualified Stock Options (NSOs)?
Non-Qualified Stock Options (NSOs) can be granted to a wider range of individuals, including employees and consultants. They are simpler than ISOs but do not offer the same tax advantages.
How are NSOs taxed?
When NSOs are exercised, the difference between the exercise price and the fair market value of the stock is taxed as ordinary income, which can result in a higher tax burden at that time.
What is the difference in tax treatment between ISOs and NSOs?
ISOs may qualify for long-term capital gains treatment if holding requirements are met, potentially reducing tax liability, while NSOs are taxed as ordinary income upon exercise.
Can you provide an example of how ISOs and NSOs are taxed?
If you acquire 200 shares of NSOs at a $10 strike price when the market value is $15, the $1,000 profit is taxed as ordinary income. In contrast, if you exercise ISOs under similar conditions and meet the holding requirements, you may qualify for long-term capital gains treatment.
How can understanding stock options benefit families?
Understanding the differences between ISOs and NSOs can help families make informed financial decisions that align with their goals, potentially optimizing their tax situations and overall financial strategies.
What role does Bright Advisers play in financial planning related to stock options?
Bright Advisers helps families create comprehensive financial strategies that include optimizing tax situations and leveraging investment strategies related to equity compensation.
List of Sources
- Define Incentive Stock Options and Non-Qualified Stock Options
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- ISOs vs. NSOs: Equity Tax Strategies | Dark Horse CPAs (https://darkhorse.cpa/blog/incentive-stock-options-vs-nonqualified-stock-options)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Incentive Stock Options vs. Non Qualified Stock Options (https://zajacgrp.com/insights/comparing-incentive-stock-options-and-non-qualified-stock-options)
- Stock Options: NQSOs and ISOs (https://schwab.com/learn/story/stock-options-nqsos-and-isos-guide)
- Compare Exercise Strategies for ISOs and NSOs
- Cashless exercise options: How to exercise stock options without paying cash upfront — Secfi (https://secfi.com/learn/cashless-exercise-stock-options)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- Cashless Exercise of Stock Options (https://carta.com/learn/equity/stock-options/exercising/cashless-exercise)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Should You Exercise Your Incentive Stock Options? A Practical Decision-Making Guide – True Wealth Design (https://truewealthdesign.com/incentive-stock-options)
- Analyze Tax Implications of Exercising ISOs vs. NSOs
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Equity Compensation: Incentive Stock Options and Non-Qualified Stock Options – Rubin Rudman (https://rubinrudman.com/article/equity-compensation-incentive-stock-options-and-non-qualified-stock-options)
- ISO vs NSO: The Tax Implications (https://brightonjones.com/blog/iso-vs-nso)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- Evaluate Suitability of ISOs and NSOs for Financial Goals
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- ISO vs NSO: Key Differences, Explained (https://cakeequity.com/guides/iso-vs-nso)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- ISO vs NSO: Decoding Stock Options in a Nutshell — Brooklyn Fi (https://brooklynfi.com/blog/iso-vs-nso-decoding-stock-options)
- Incentive Stock Options: How ISOs Work vs NSOs – NerdWallet (https://nerdwallet.com/investing/learn/isos)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading